Explore CoreMacro
CoreMacro | Europe
Europe-focused research - including in-depth country reports. Typically published twice a month.
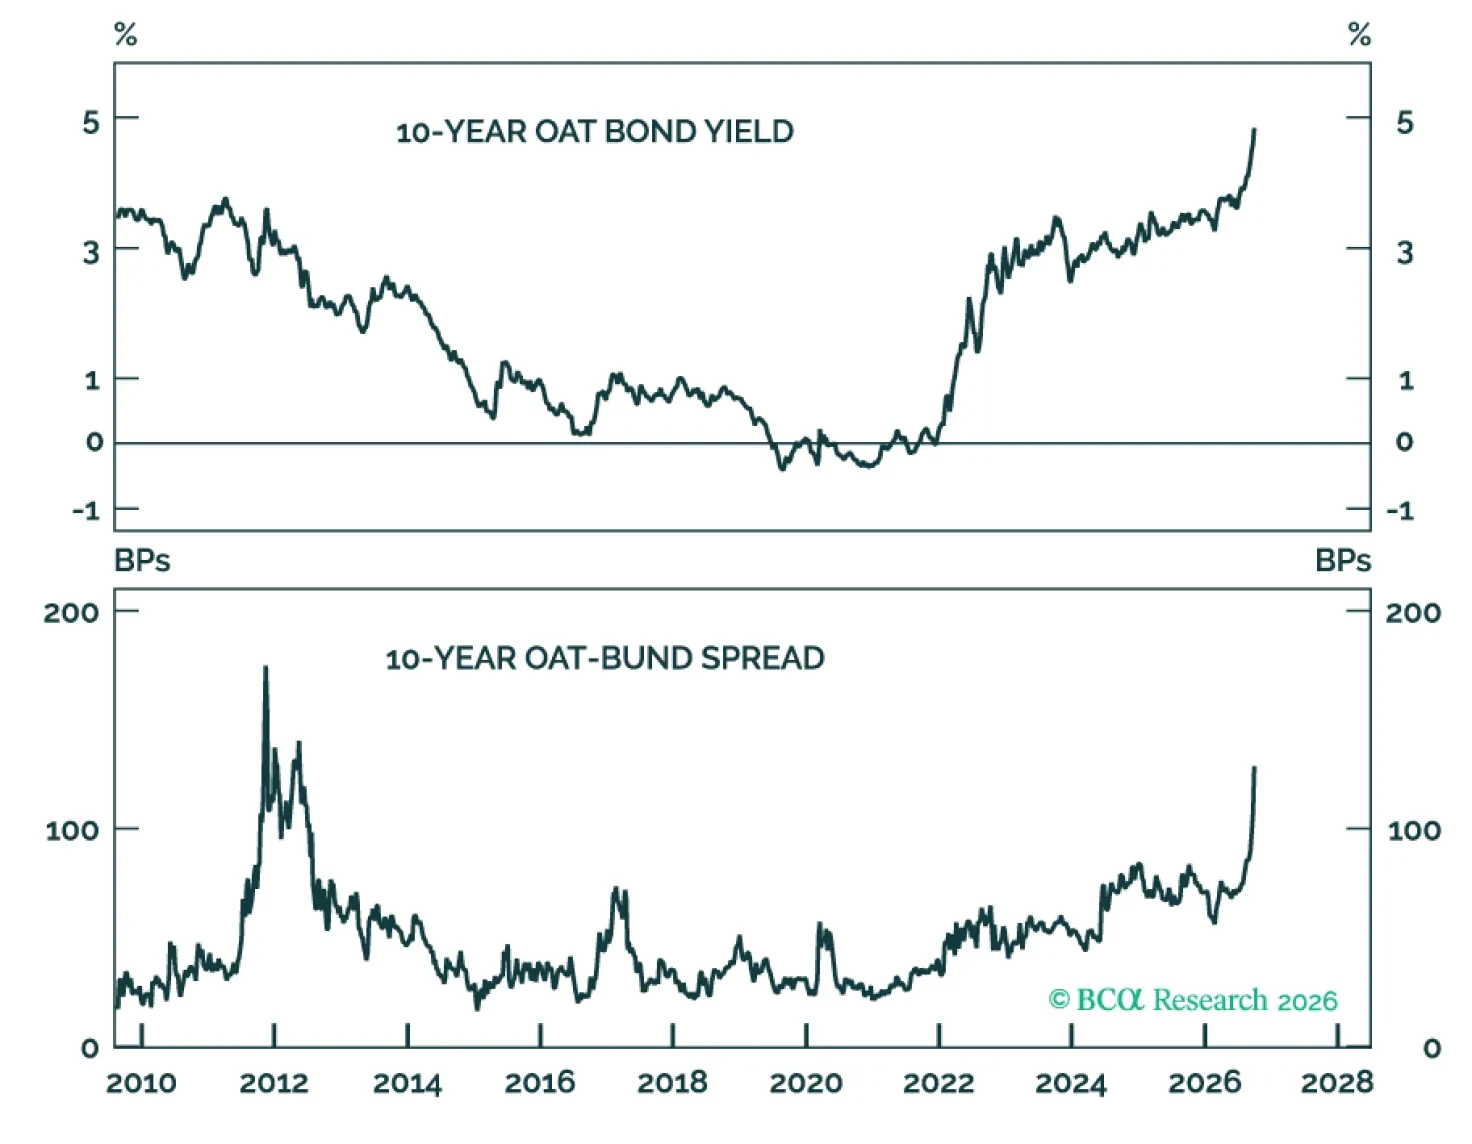
Forced selling may be approaching a pause, but France’s fiscal and political adjustment has barely begun. Maintain an underweight in OATs and use relief rallies to reduce exposure. Contained contagion is reassuring for Europe; it is not a buy signal for France.
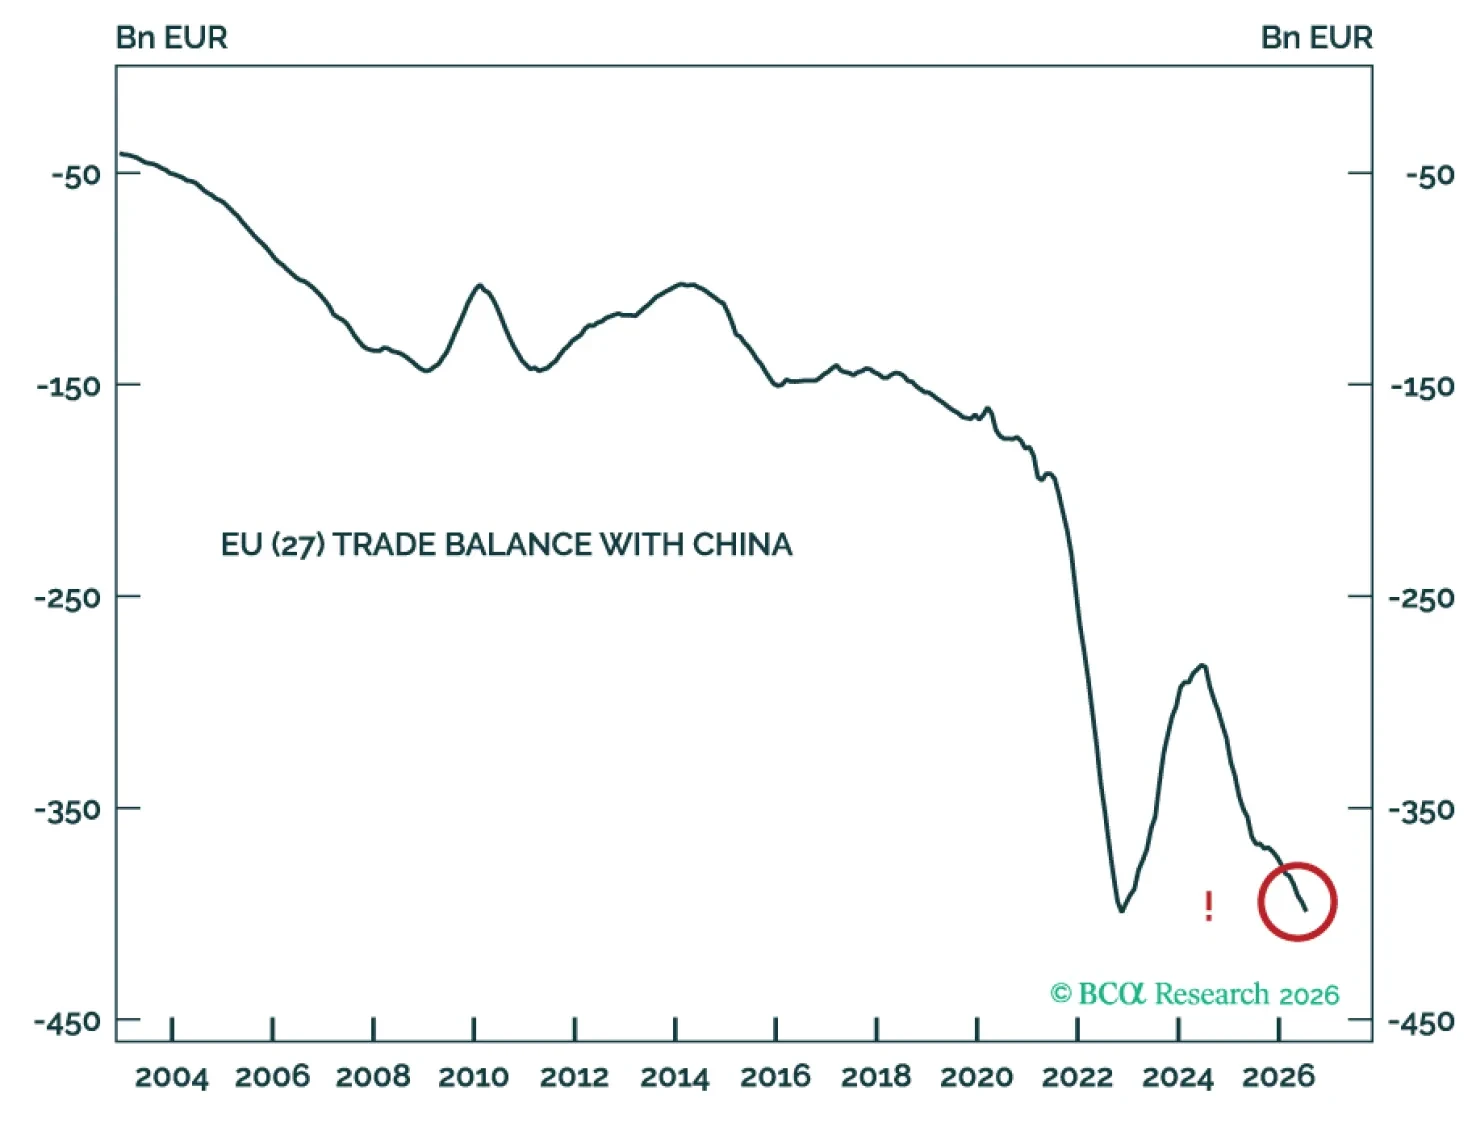
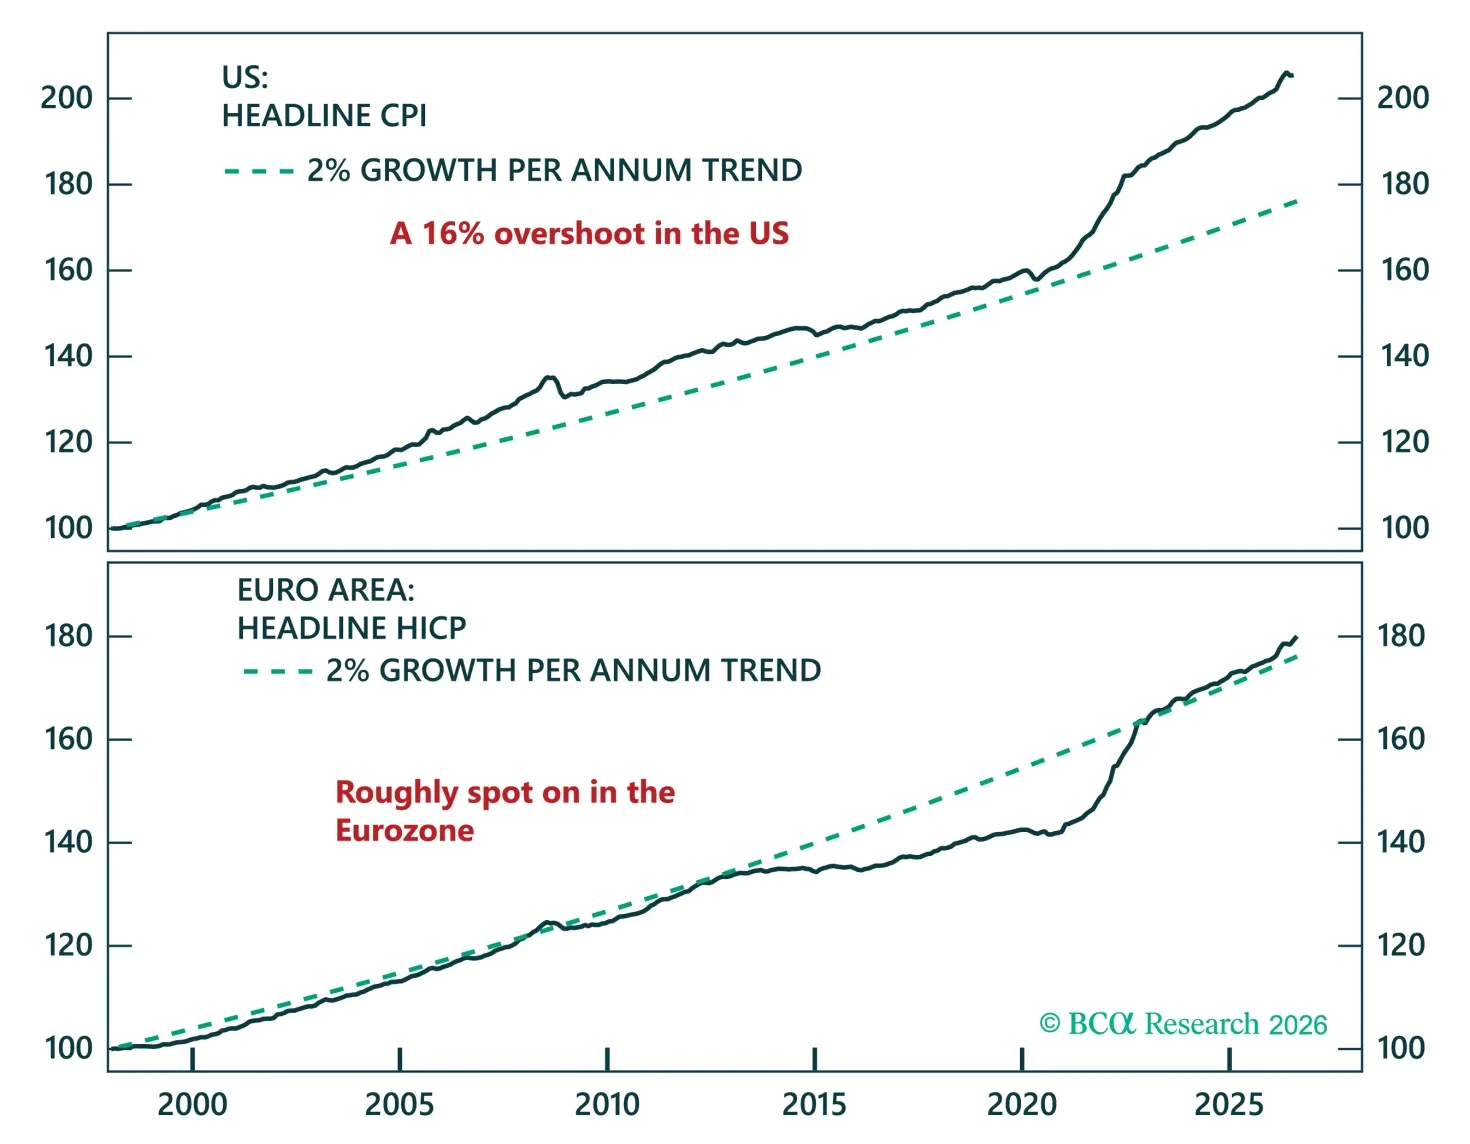
The ECB is winning, and almost nobody's pricing it in. A flatter Phillips curve, a shrinking term premium, a euro built to shrug off France, credibility is the trade.
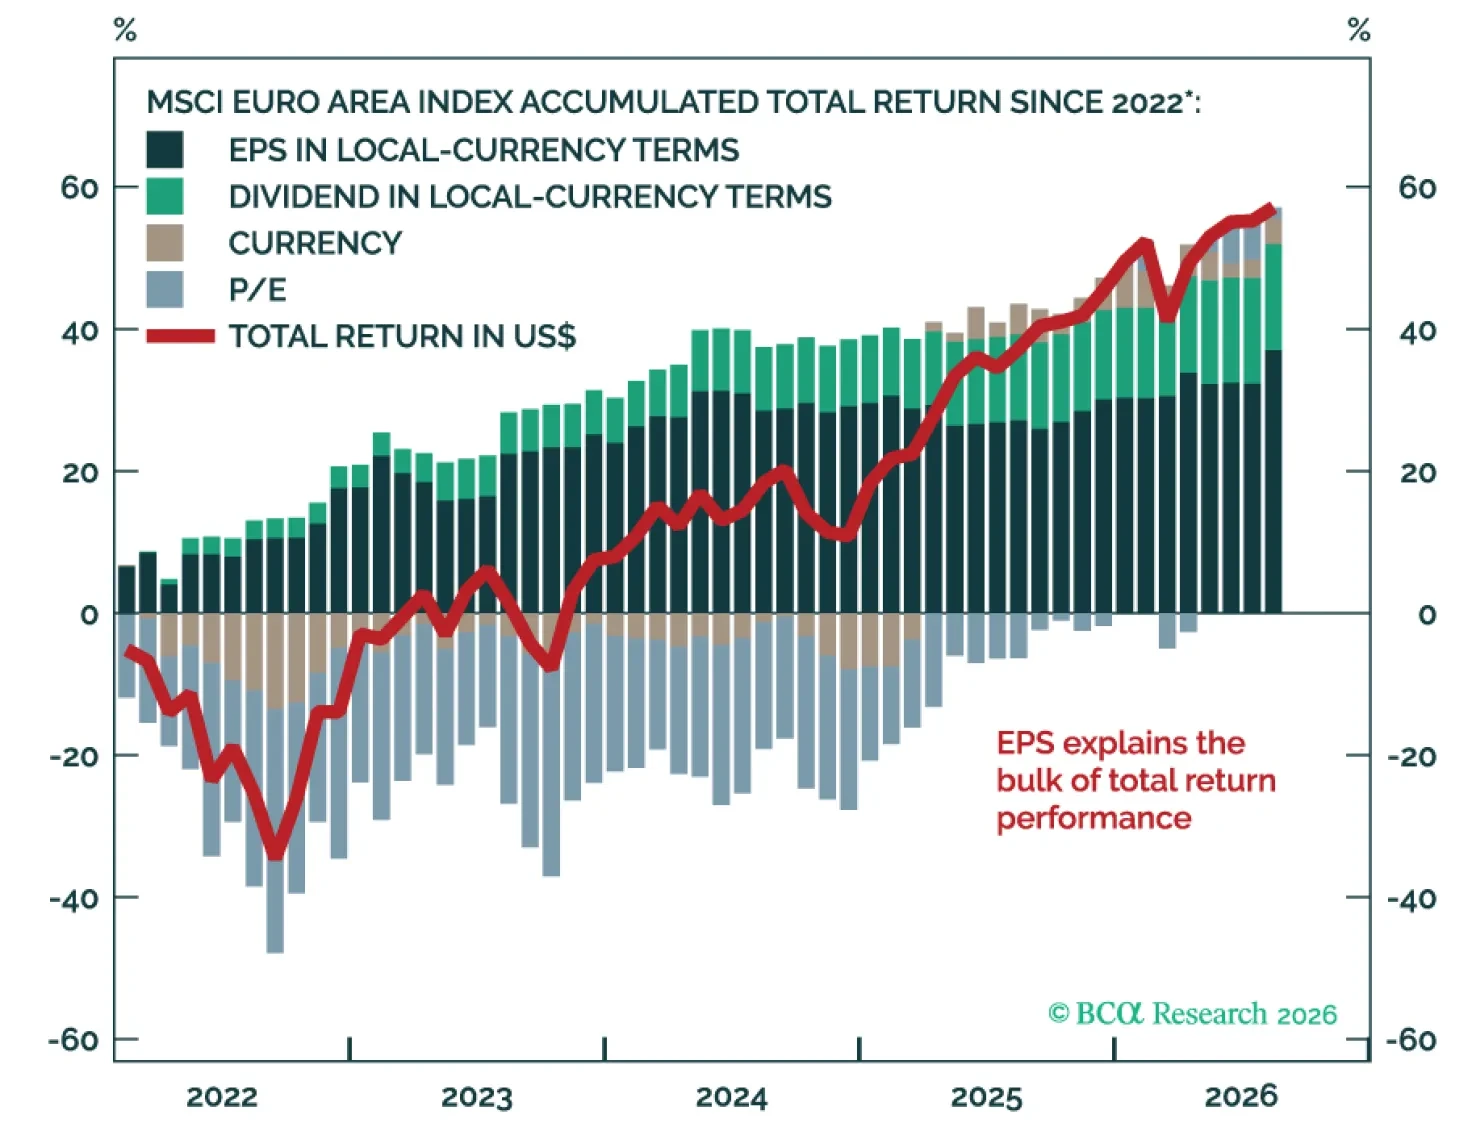
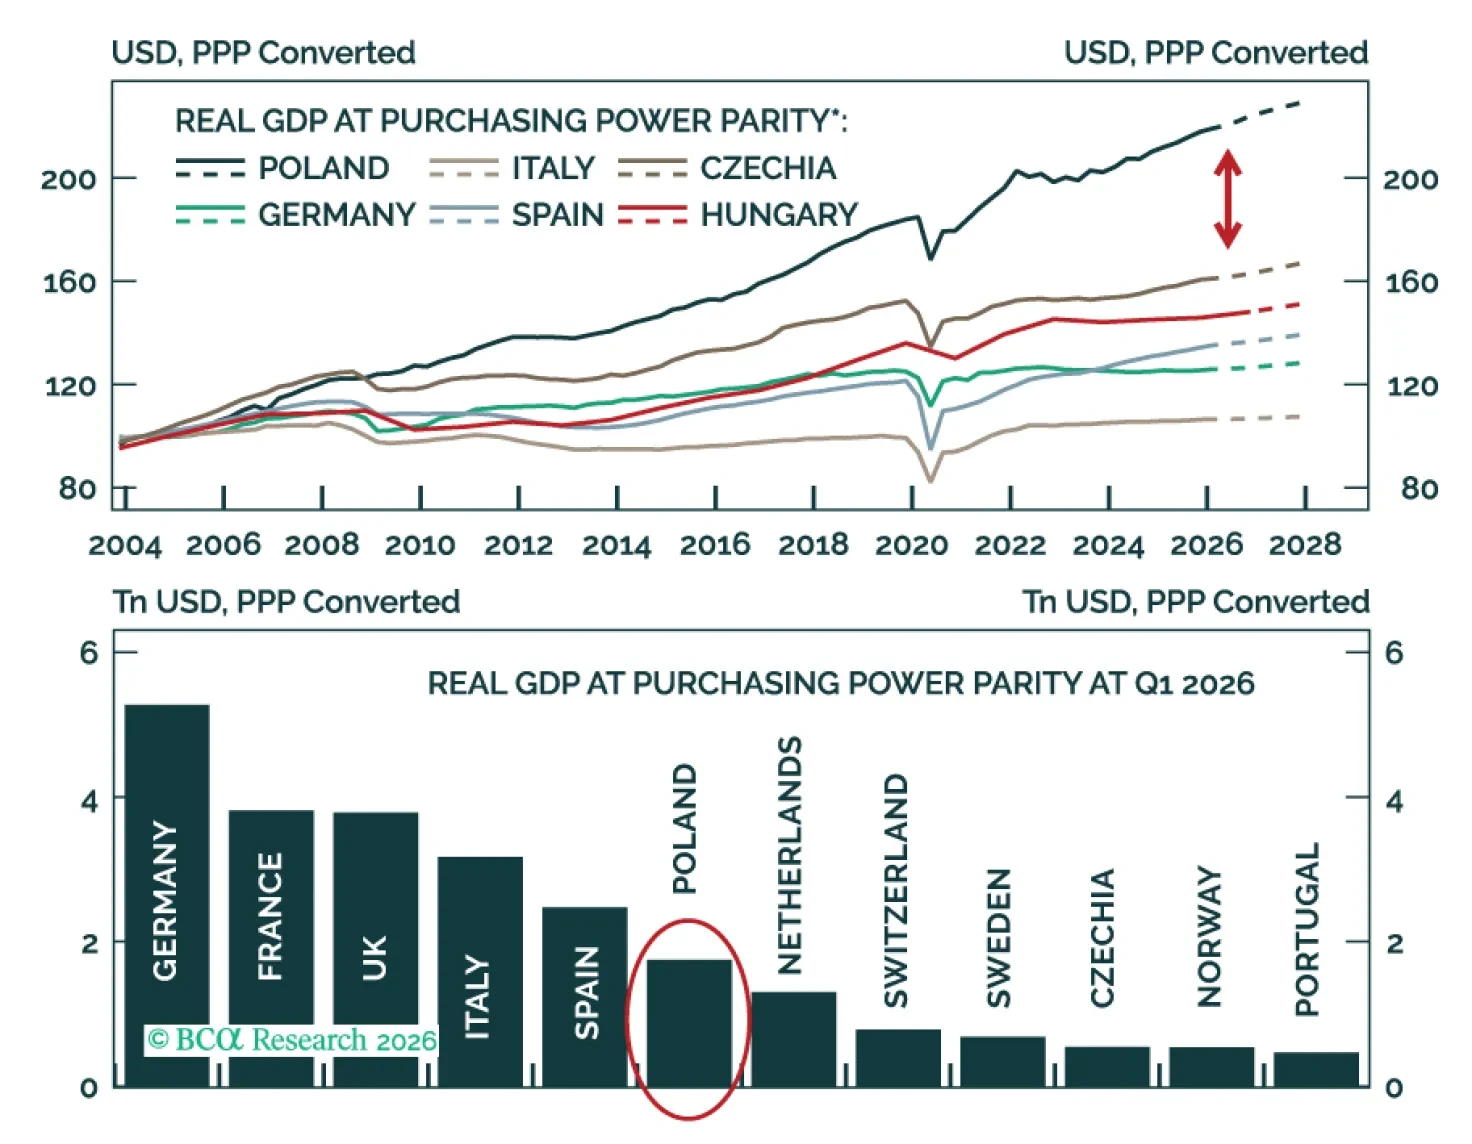
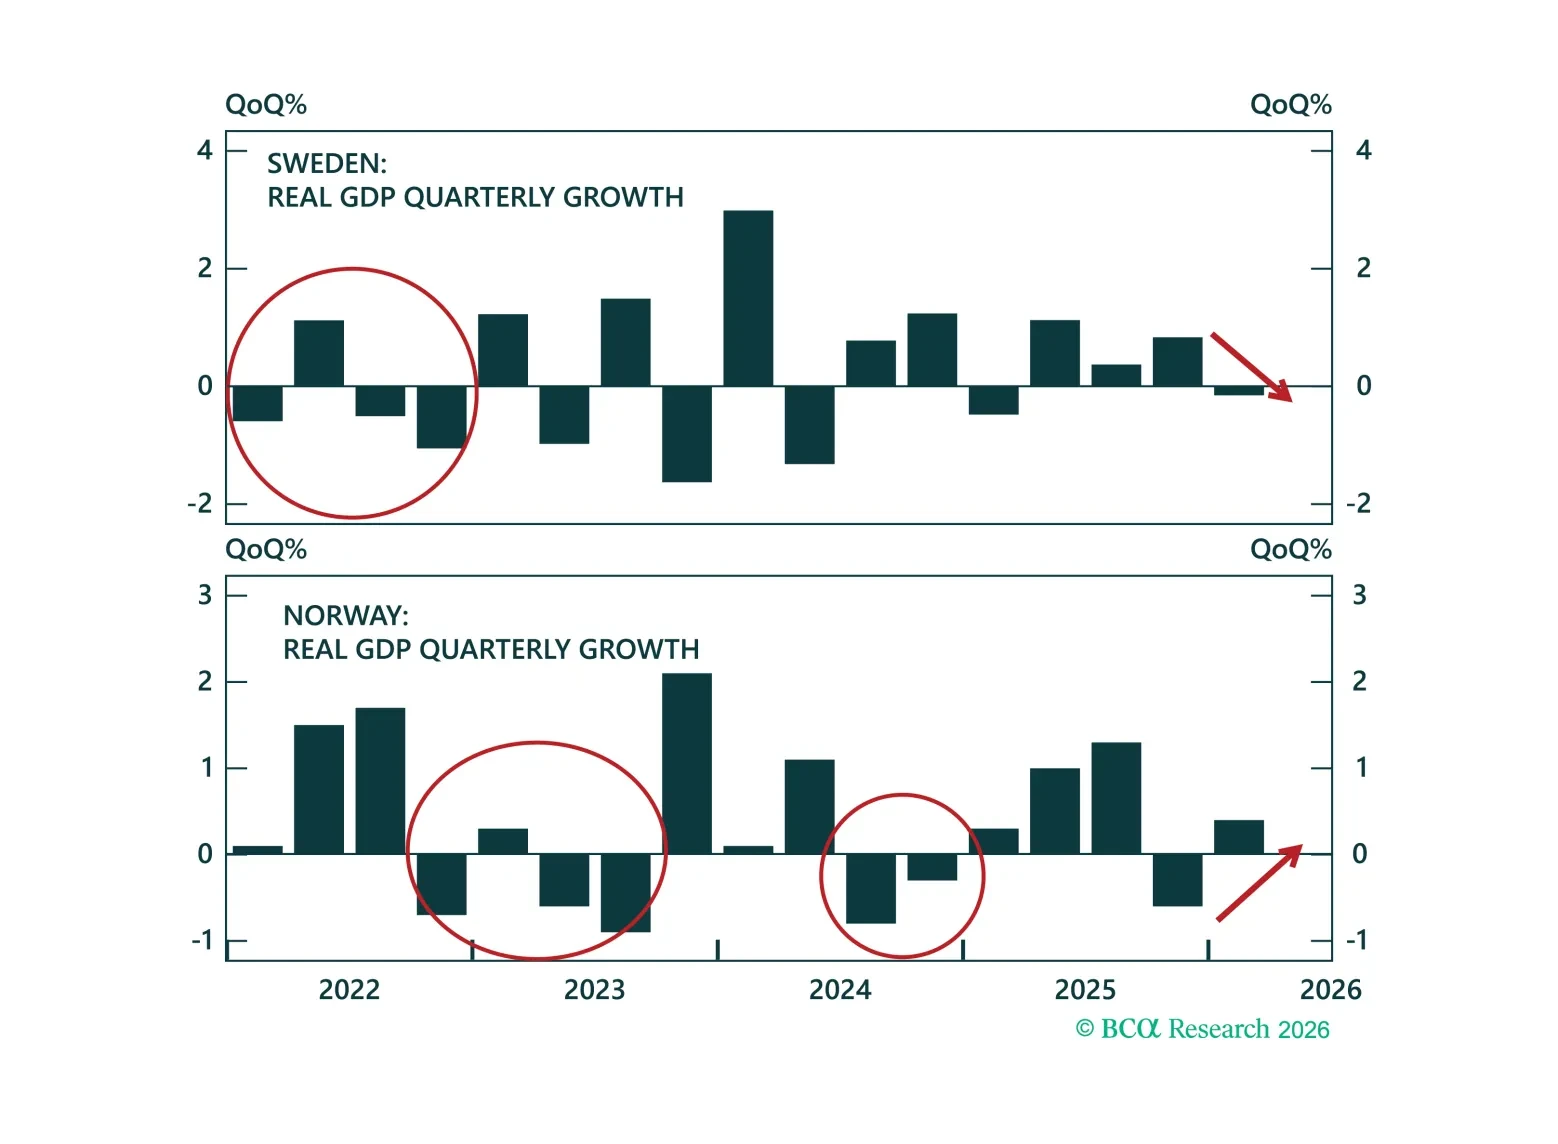
The war in Iran and the energy shock are driving a reversal of Nordic fortunes: Sweden’s recovery is faltering just as Norway receives a welcome energy windfall. Favor Norwegian over Swedish equities and buy NOK/SEK. In rates, fade aggressive Riksbank hike expectations and downgrade Norwegian government bonds to neutral.
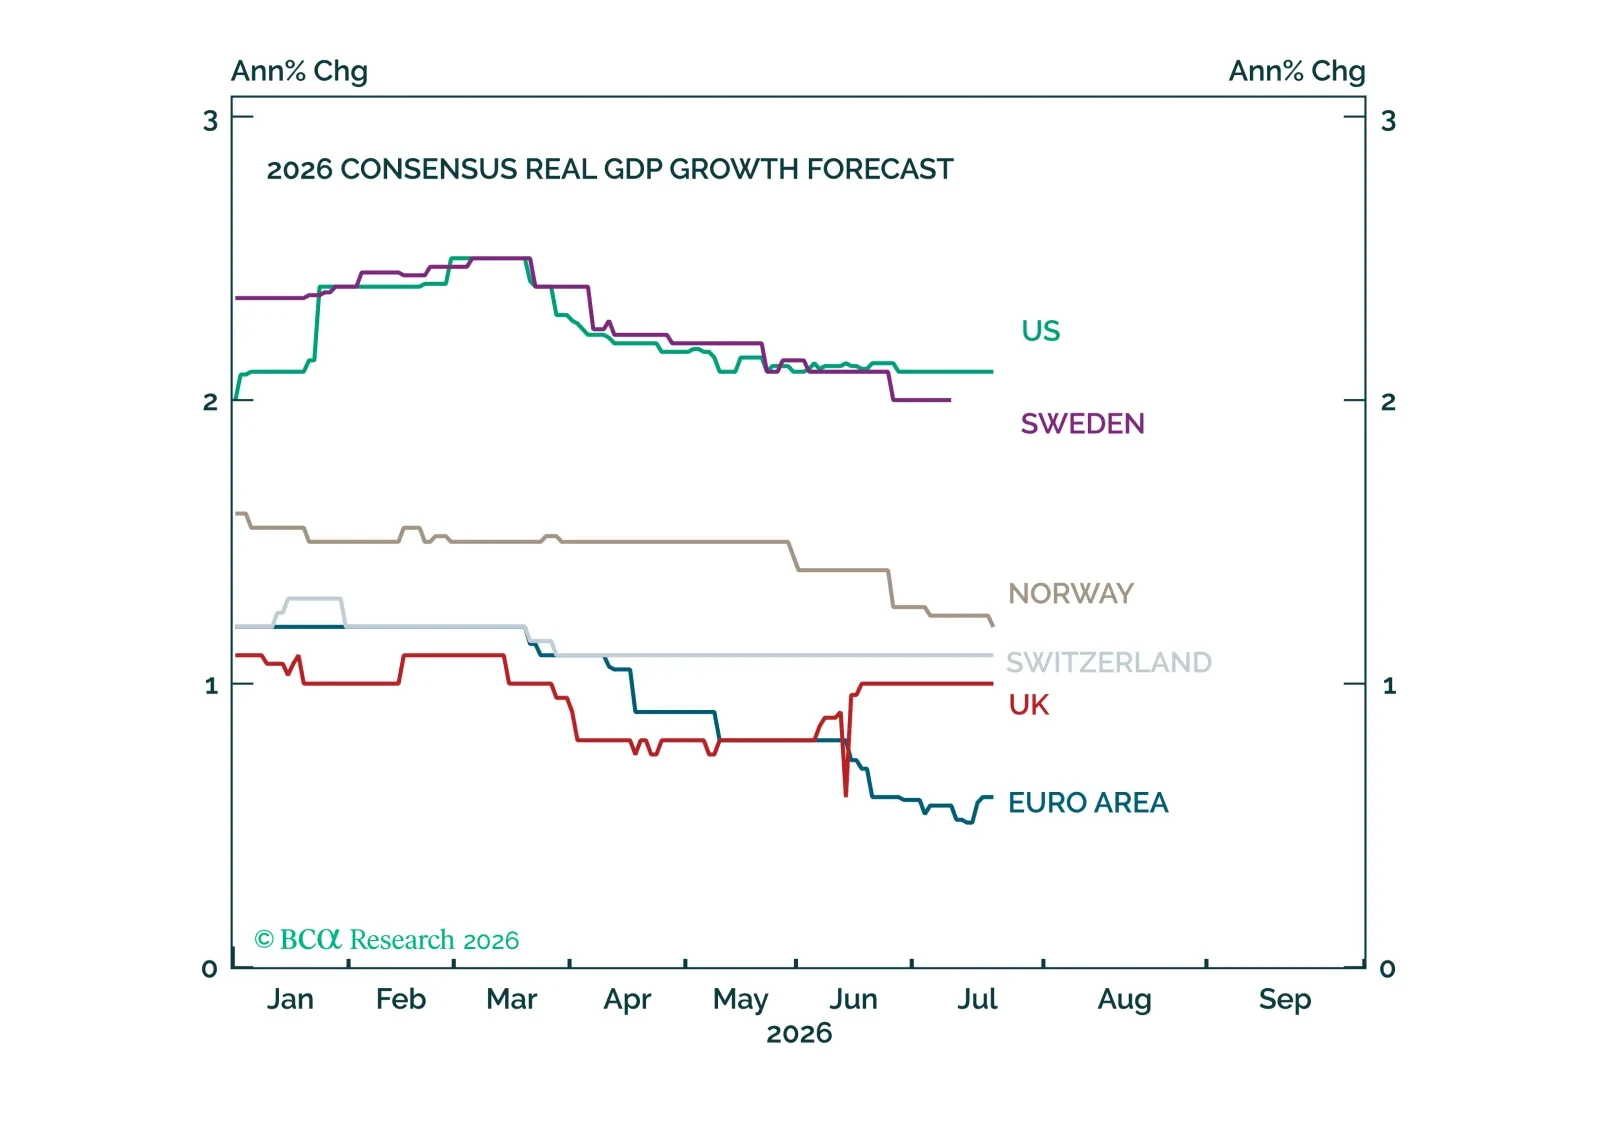
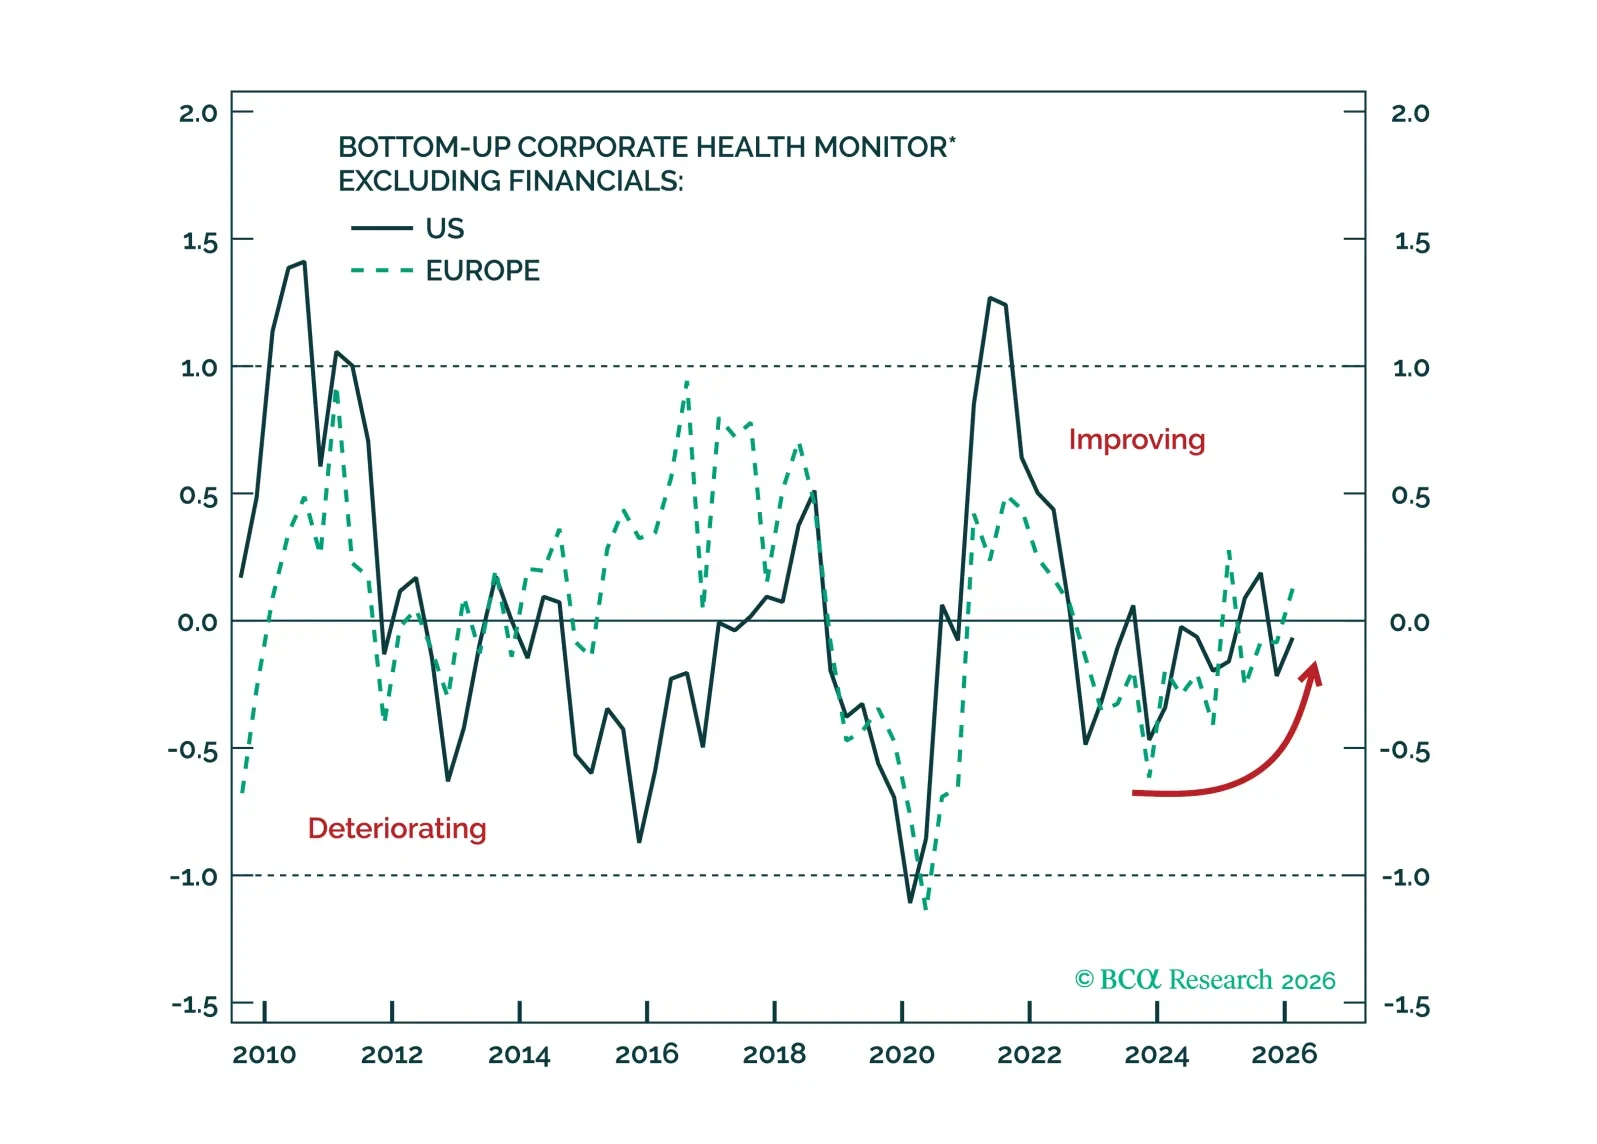
Europe faces a difficult macro backdrop, but whether it slips into recession remains finely balanced. We present two perspectives before translating them into investment implications.
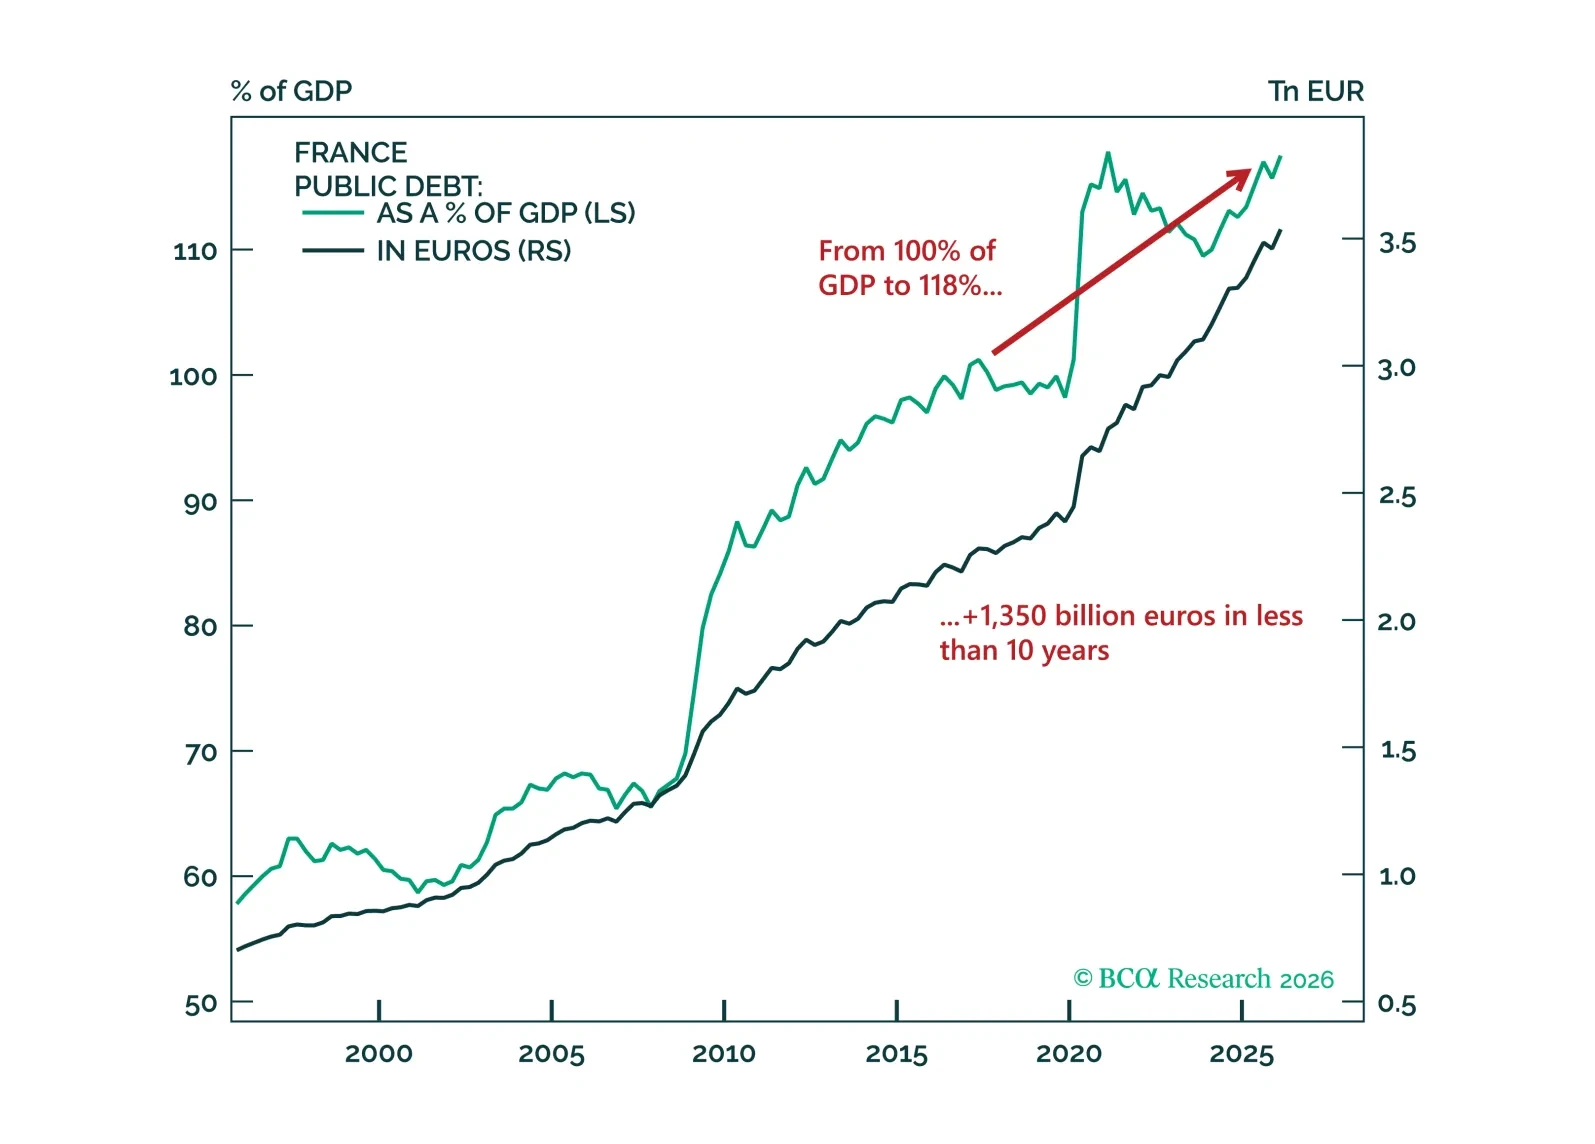
We wish all our French clients Bonne Fête Nationale! The rest of the world knows the holiday by its other name, Bastille Day. It is fitting, therefore, that we publish today GeoMacro Beta report on the coming political earthquake in France.
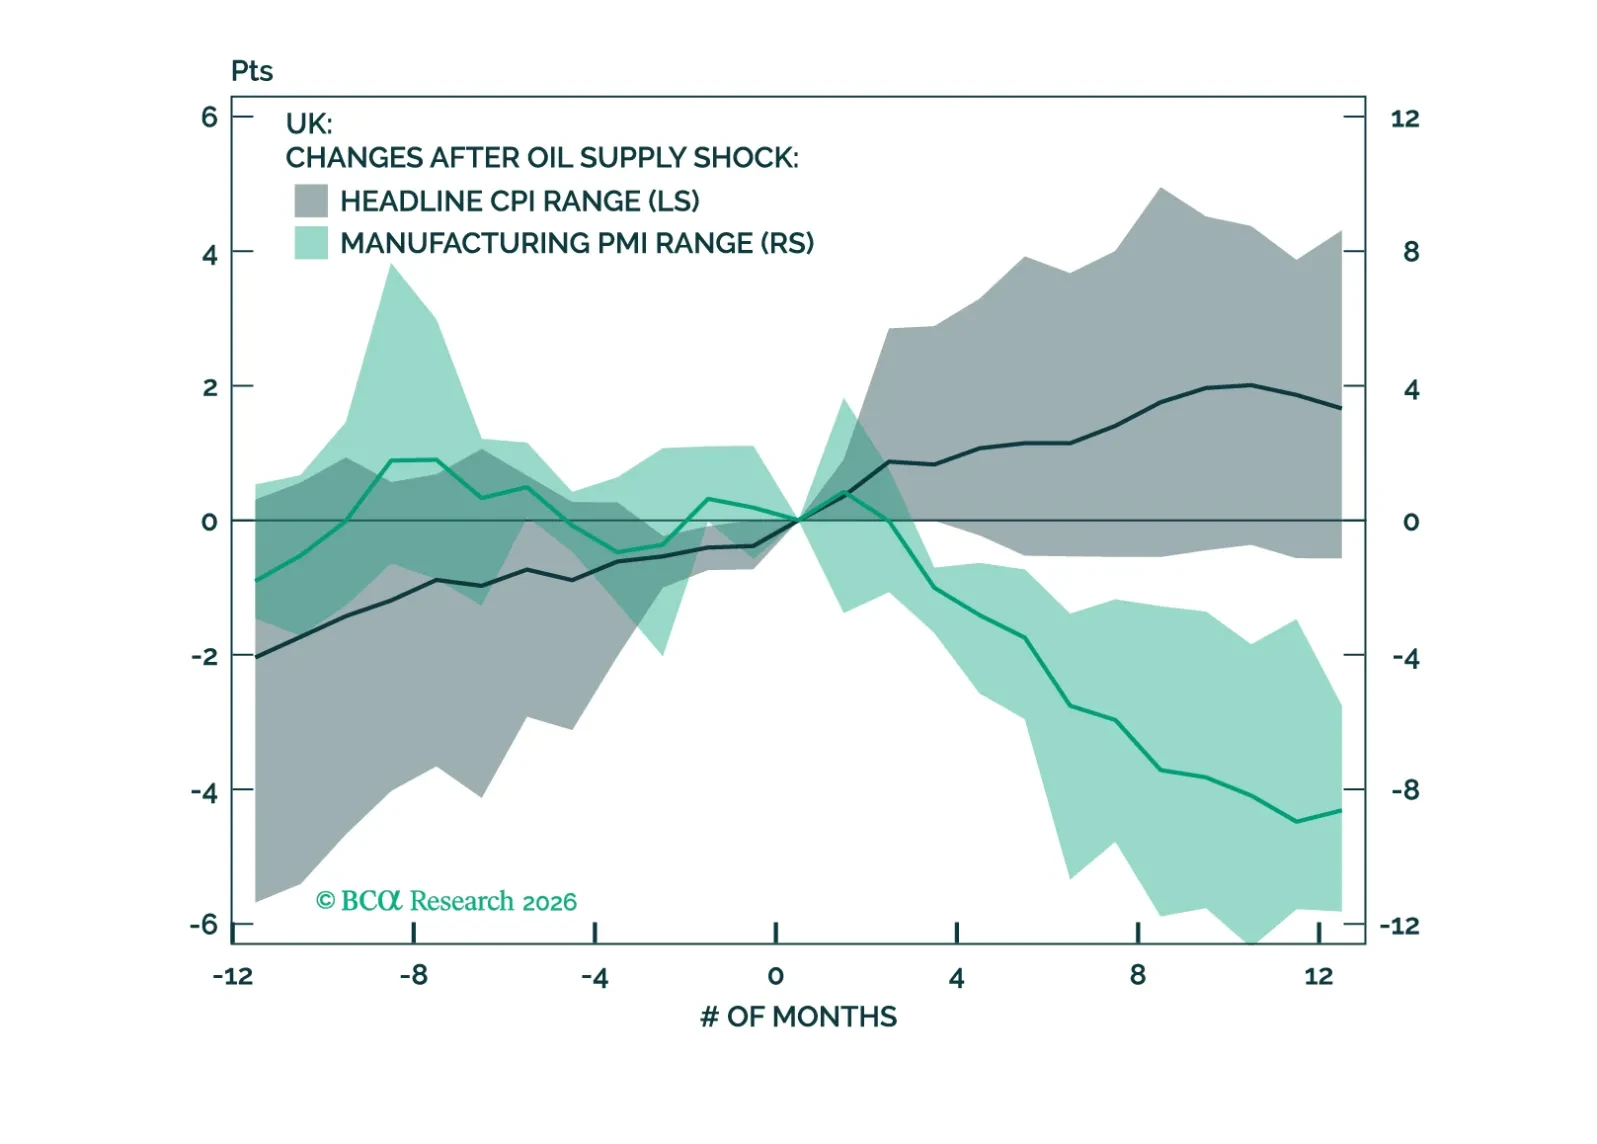
The UK economy is becoming increasingly fragile, but the investment outlook is improving. Slower growth and a more dovish BoE will support gilts, while UK equities will likely benefit from a favorable sector mix and a weaker pound.