Skip to main content
Explore CoreMacro

CoreMacro | Thematic Reports

Deep-dive special reports, exploring the investment themes that will shape markets over the medium-to-long term.  Typically published twice a month.
Special Report In 2026, against the backdrop of plunging birth rates around the world, investors were focused on AI bottlenecks. Little did they know that the biggest bottleneck to artificial intelligence was, ironically, human intelligence. Progress in overcoming this bottleneck set geopolitics ablaze and ushered in an economic boom that dwarfed anything that came before it. It also paved the way for speciation, unprecedented social strife, and ultimately, the demise of the human race. This is the story of World War E.
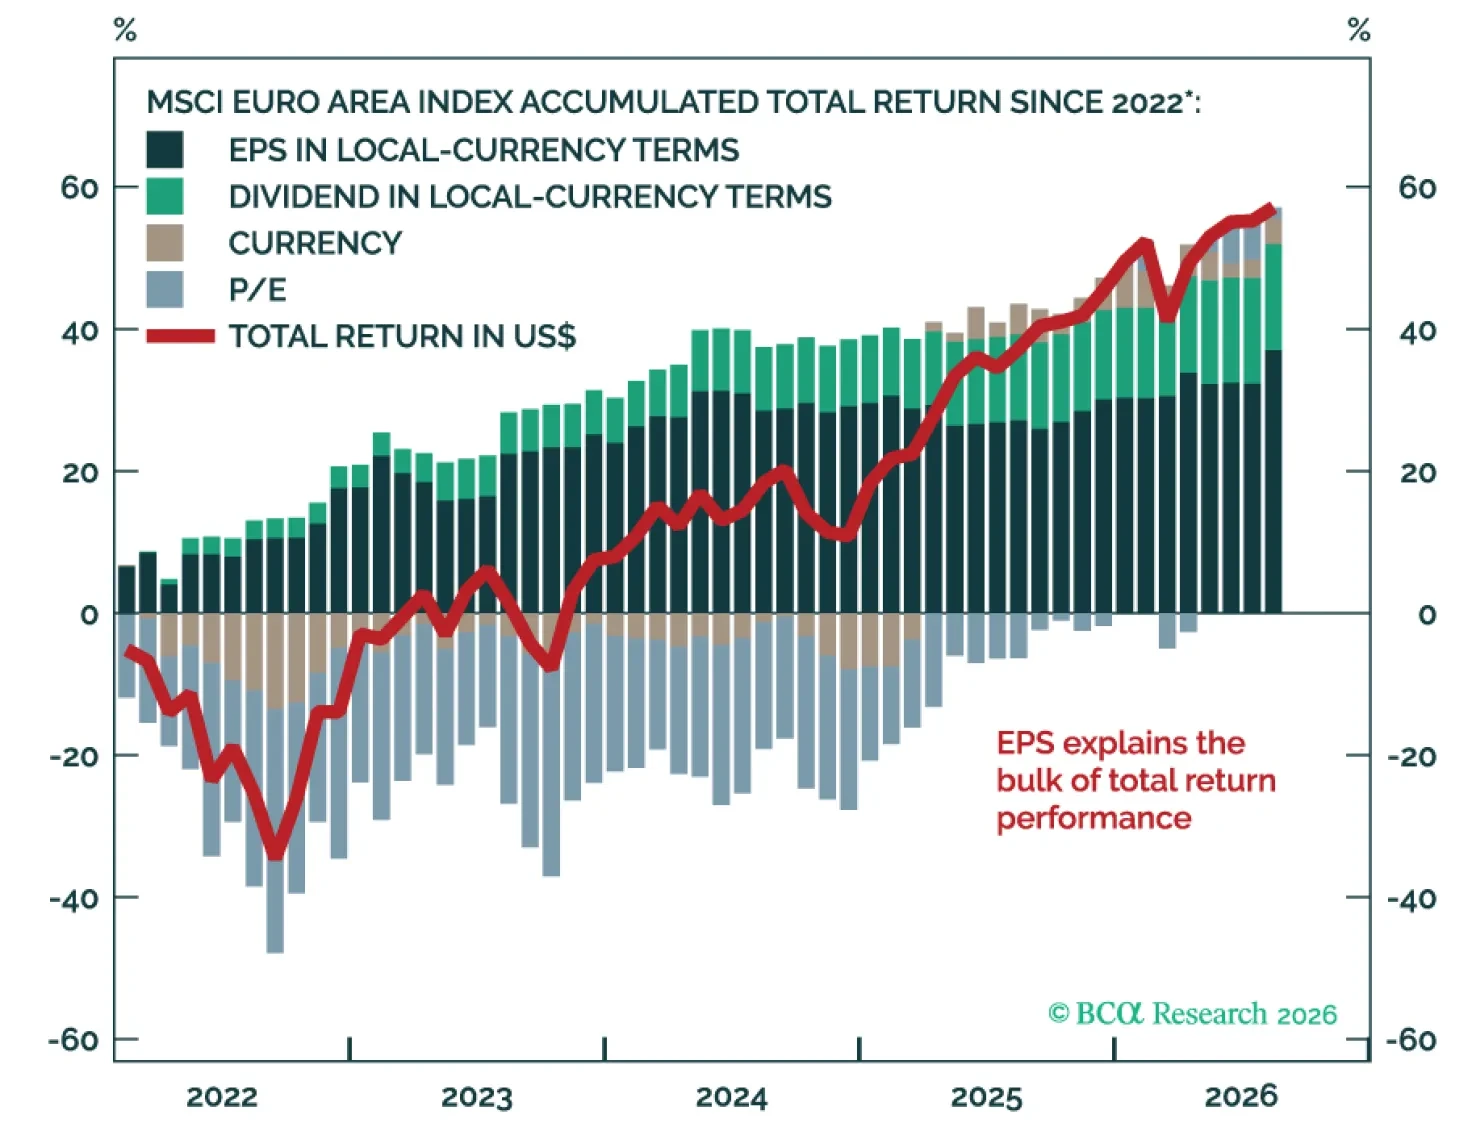
Special Report Europe’s earnings recovery is increasingly difficult to dismiss. Margins, ROE, ROIC, and capital efficiency have all improved, while banks have re-emerged as an earnings engine. Cyclical conditions remain supportive, and the structural picture continues to improve: higher investment, improving productivity, and EU reforms could give the recovery staying power.
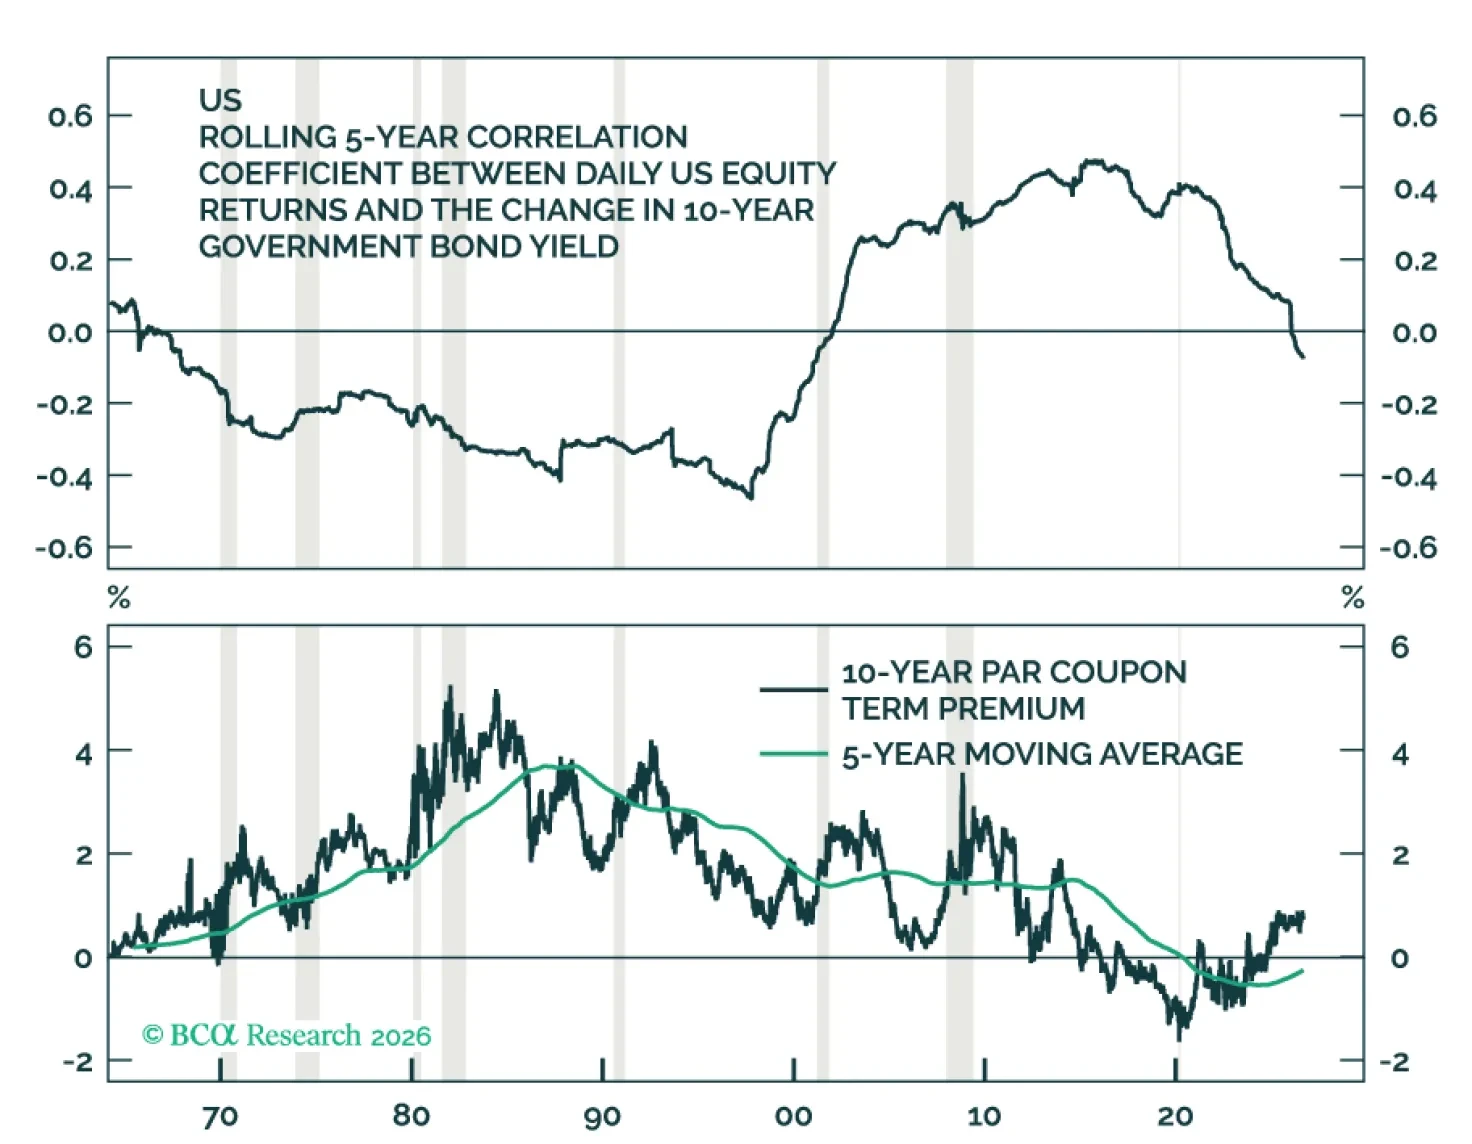
Special Report We propose a unified framework for predicting the direction of short-term interest rates and long-term bond yields that brings together three approaches: 1) the saving-investment approach; 2) the Taylor rule approach; and 3) the portfolio balance approach. Our analysis suggests that bond yields in the US and many other countries have increased mainly because of a higher neutral interest rate and a larger term premium. Given the risk of a further rise in inflation expectations, investors should overweight inflation-linked bonds.
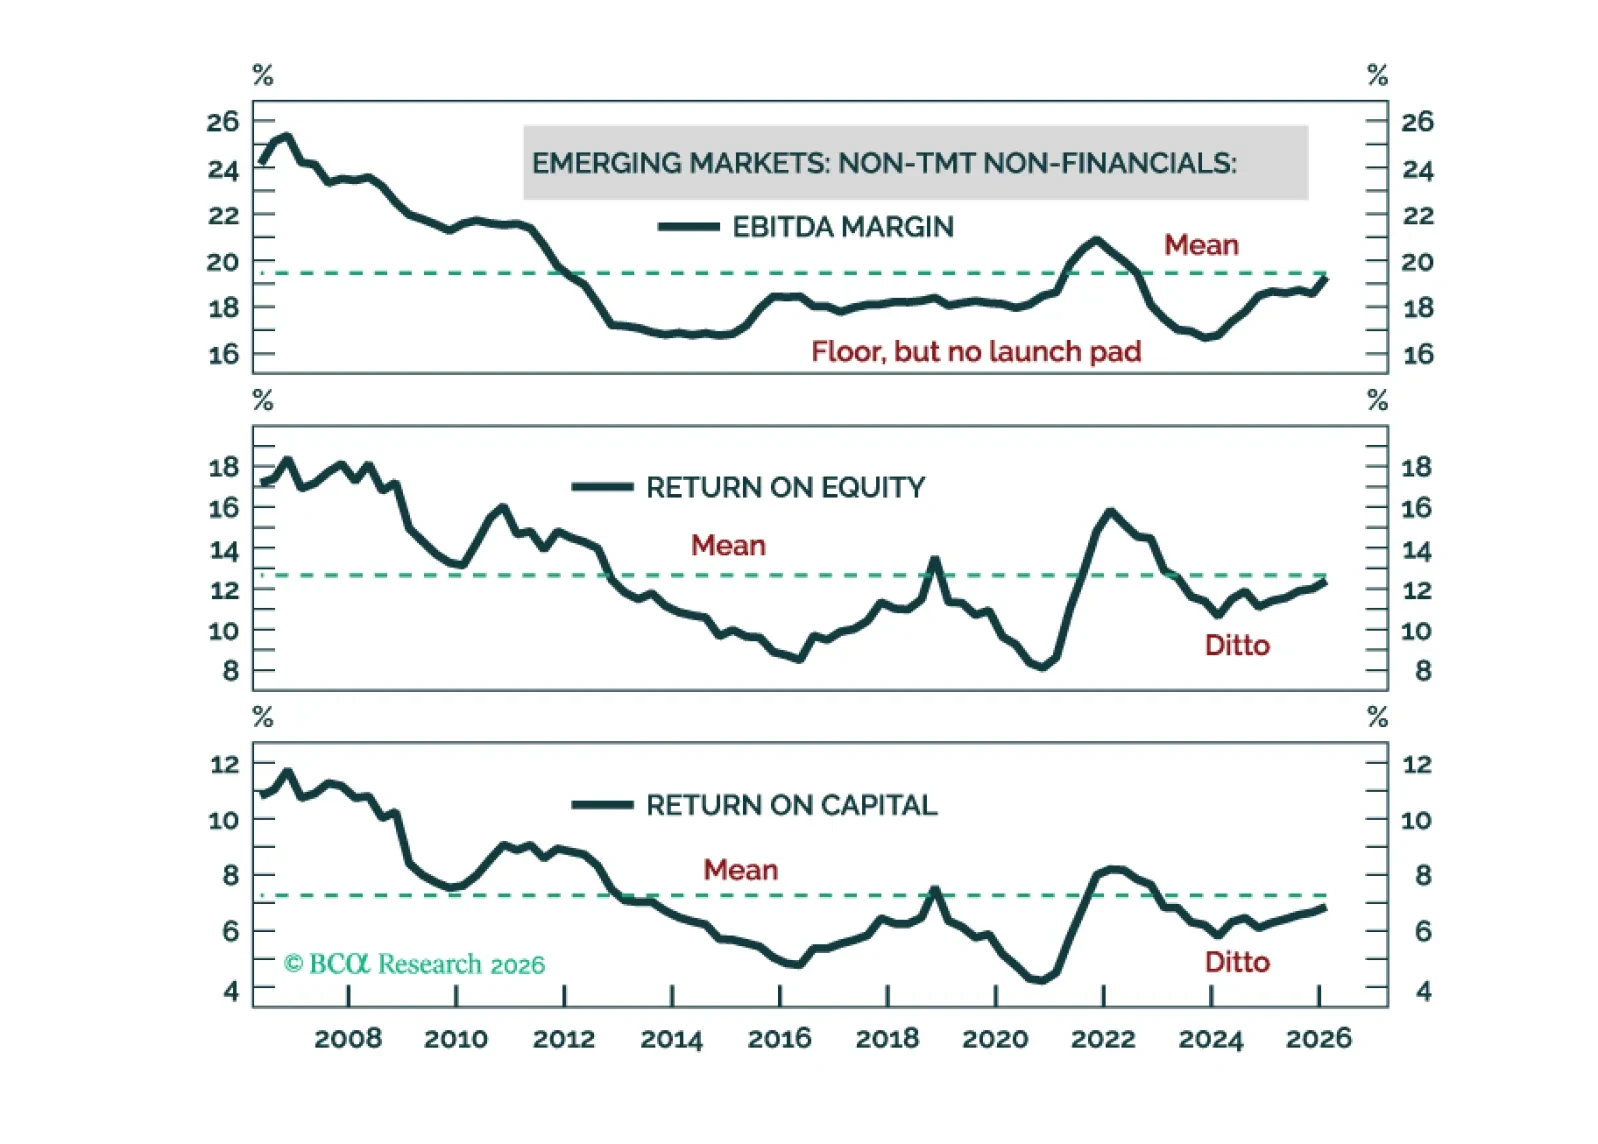
Special Report Outside semiconductor stocks, EM/China profitability has been well below both their US peers and the levels that prevailed during the EM structural bull market in the 2000s. Over a 3- to 5-year horizon, EM/China relative equity performance versus global will be range-bound.
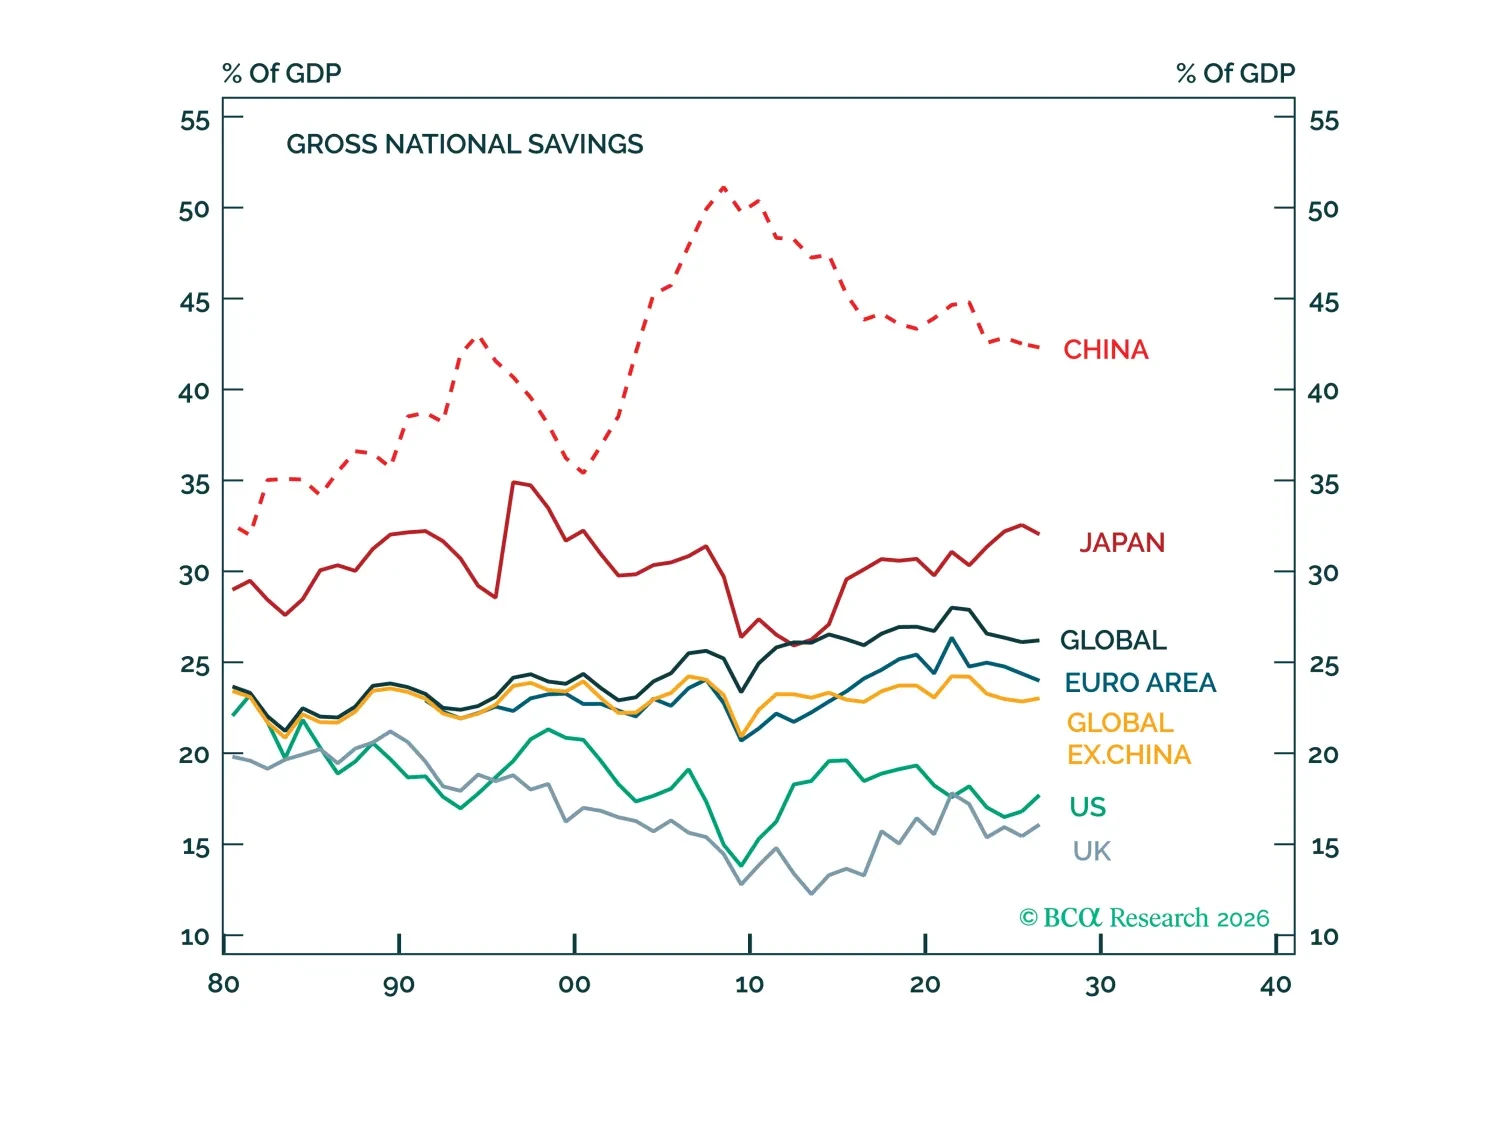
Special Report China does not produce too much. It spends too little. The only viable way for China to reduce investment without raising unemployment is by lowering national savings. Doing so is likely to be politically challenging, however. This suggests that China will suffer from subpar growth and deflationary pressures for the foreseeable future.
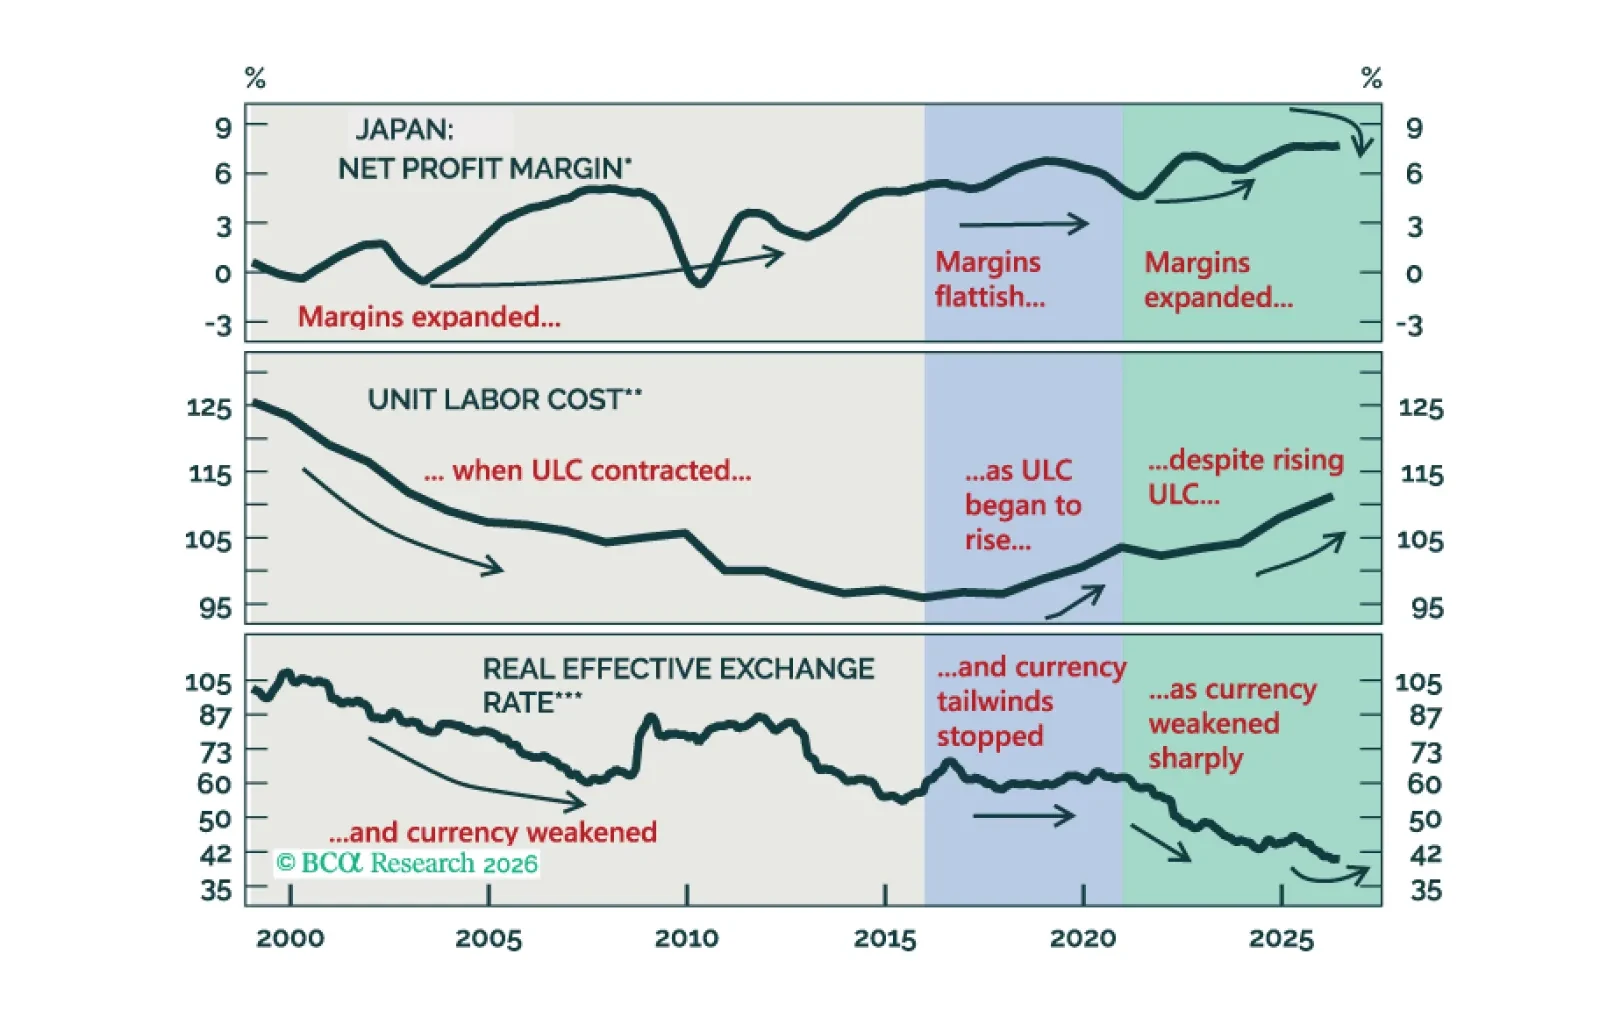
Special Report Over the past 10 years, Japan’s profit margin expansion has been driven neither by advances in labor productivity nor by operational efficiency gains, but by massive currency devaluation and lower depreciation charges. Going forward, higher wages and unit labor costs, as well as currency appreciation, will become major headwinds to margins.
Special Report News flash: Young urban professionals are not gasping under the weight of an impossible rent burden. Investors should not be led astray by lightly examined popular narratives.
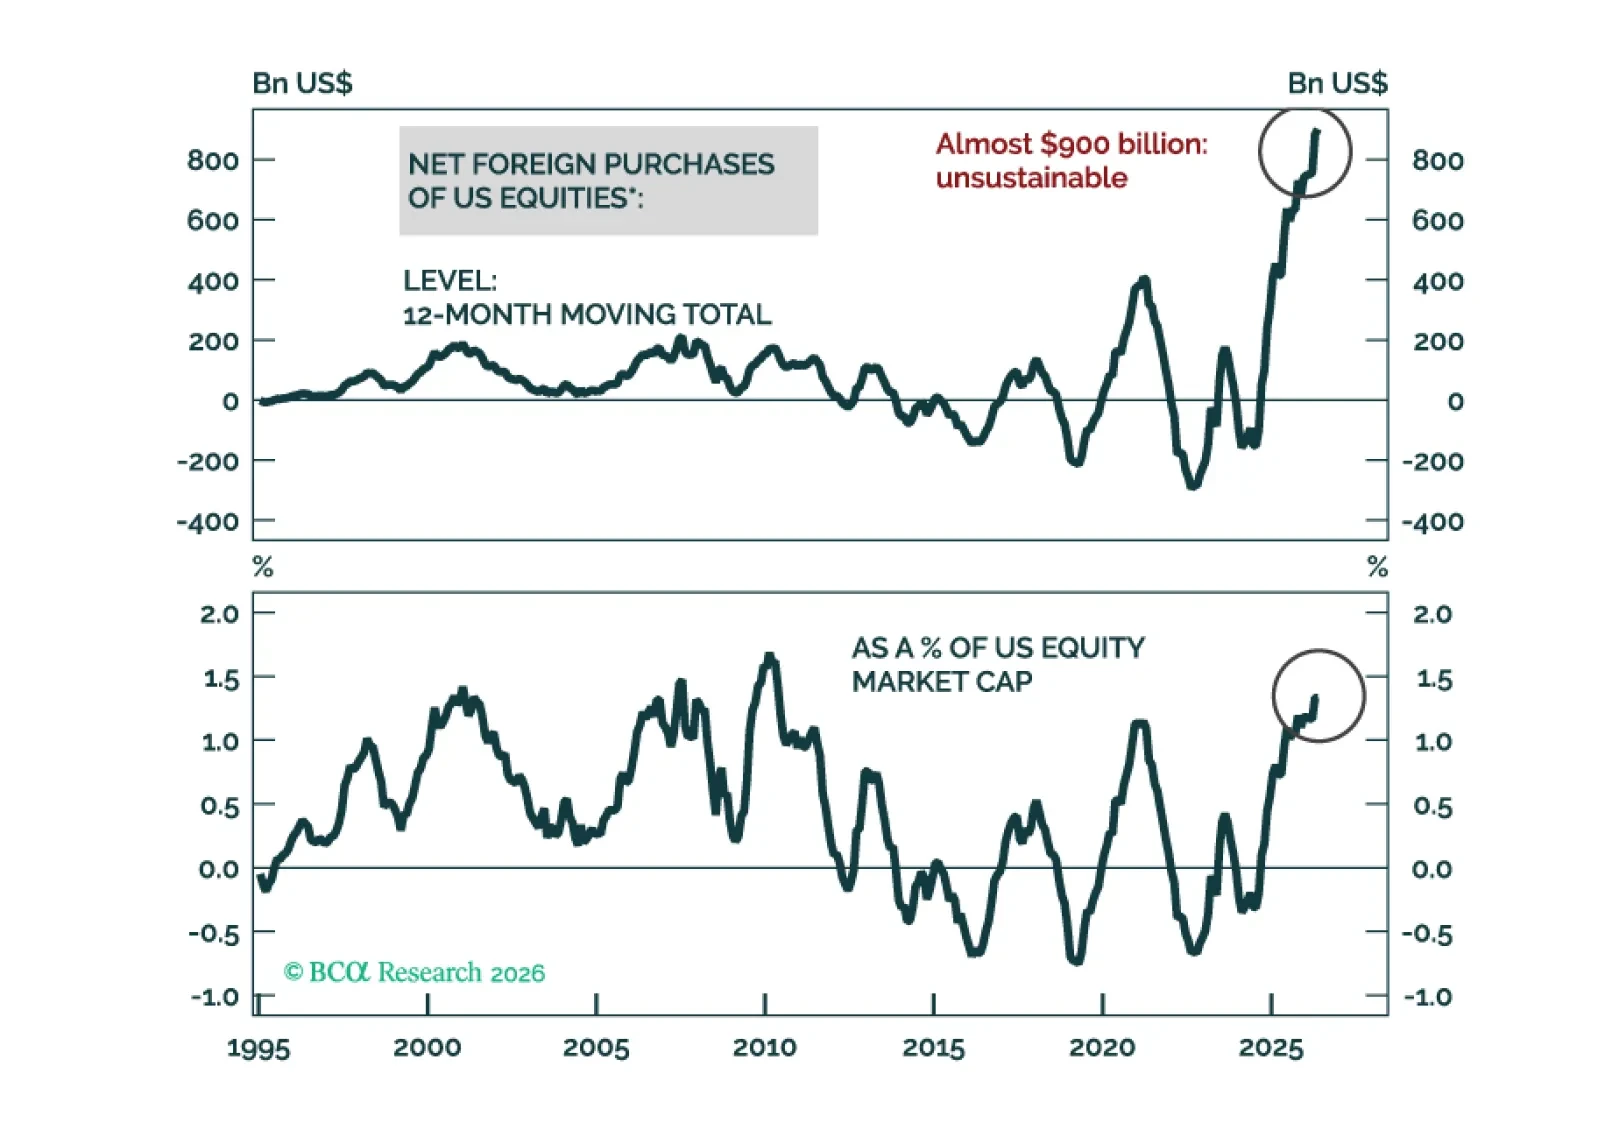
Special Report The US dollar will become a pro-cyclical currency going forward. This regime shift would upend financial market correlations, and most investment portfolios are not positioned for it. A great deal of money is made or lost during regime changes - and one is coming soon. That is why our message remains loud and clear: Get Out of the Dollar (G.O.D.).
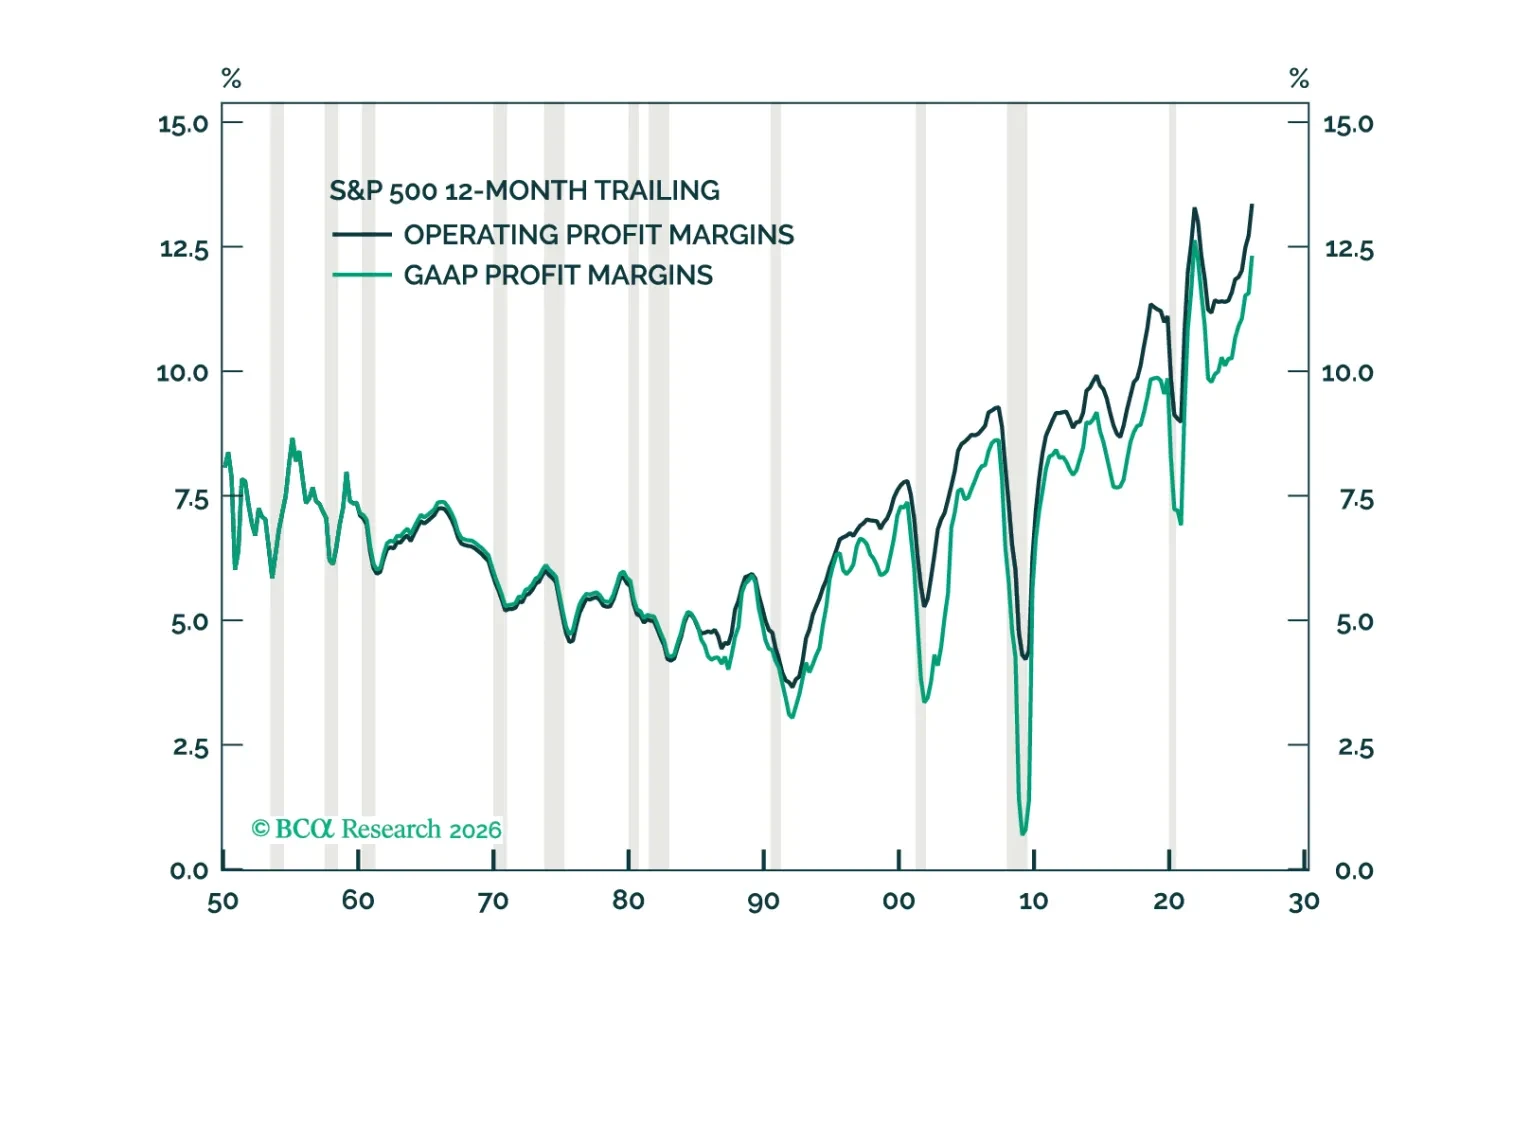
Special Report The Goldilocks environment for US profit margins should start to sour next year. Contrary to conventional wisdom, AI could end up eroding margins for both producers and consumers of artificial intelligence.
Special Report The magnitude of US tech/AI capital spending already rivals past bubble thresholds, threatening hyperscalers’ future returns on capital. There are echoes of previous market tops. Our preferred overlay strategy for equity portfolios remains long semiconductor producers / short hyperscalers.