Commodities
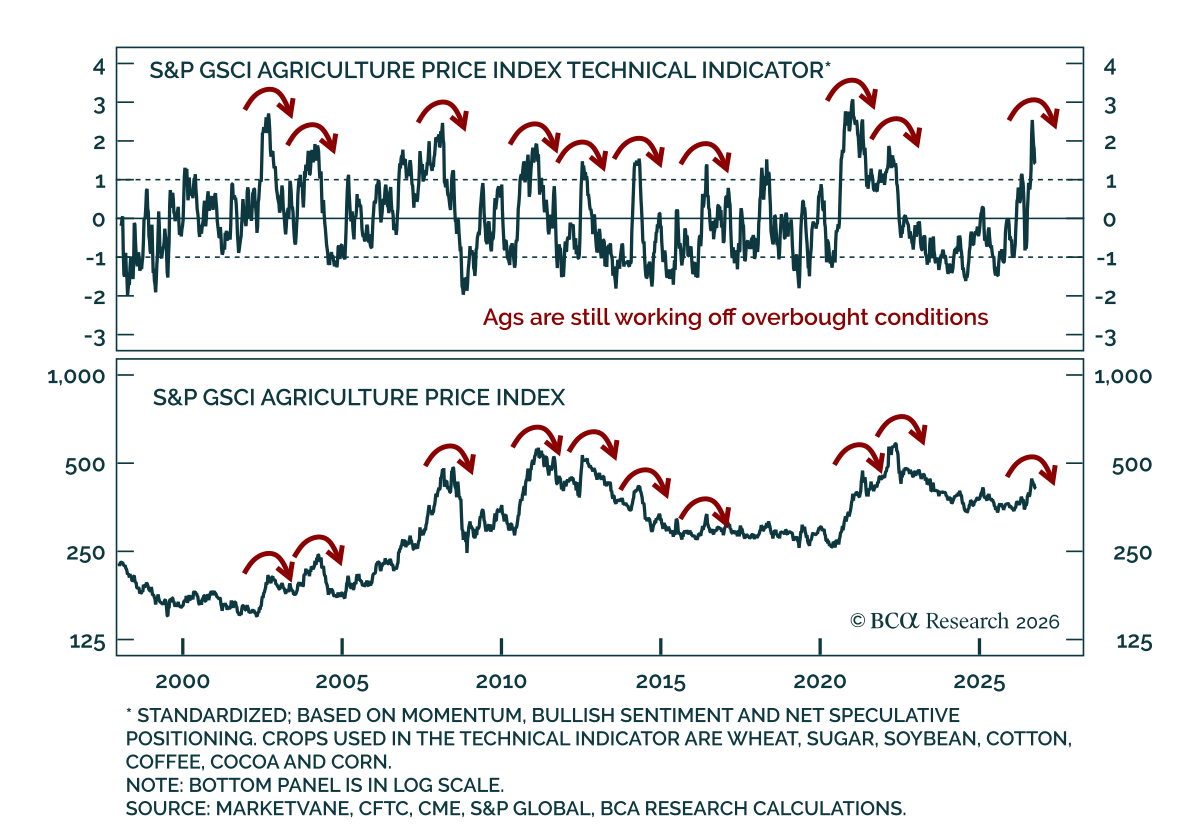
Our Commodity strategists argue the recent selloff in agricultural commodities is a correction rather than a top, which should create a buying opportunity next year. Ags have corrected meaningfully and broadly over the past two months, following an explosive…
Ags have tumbled from overbought highs, and further near-term weakness is likely. But a “super” El Niño and an ongoing energy shock are setting the stage for the next rally.
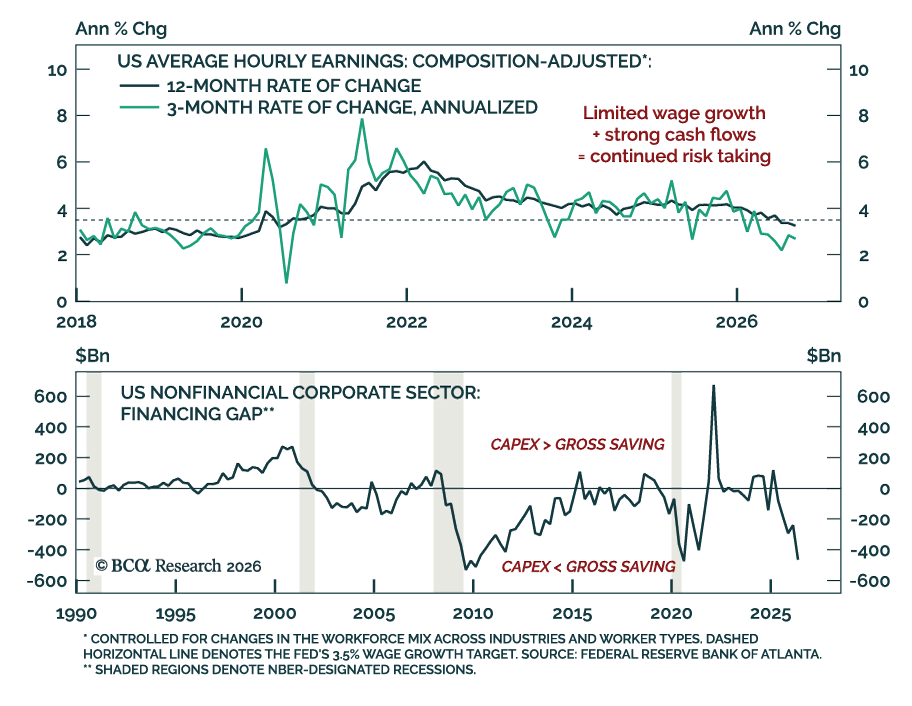
Our FICC strategists recommend staying long risk, holding neutral duration, and fading volatility spikes over the next six to nine months. While worries keep piling up, spanning politics, wars, higher yields, and doubts about AI, our colleagues argue the one…
Politics, wars, a global tightening cycle, doubts over AI capex: the wall of worry keeps rising. But the spark that would topple risk assets is missing. Our Q4 FICC outlook explains why to stay long risk, and where the danger lies.
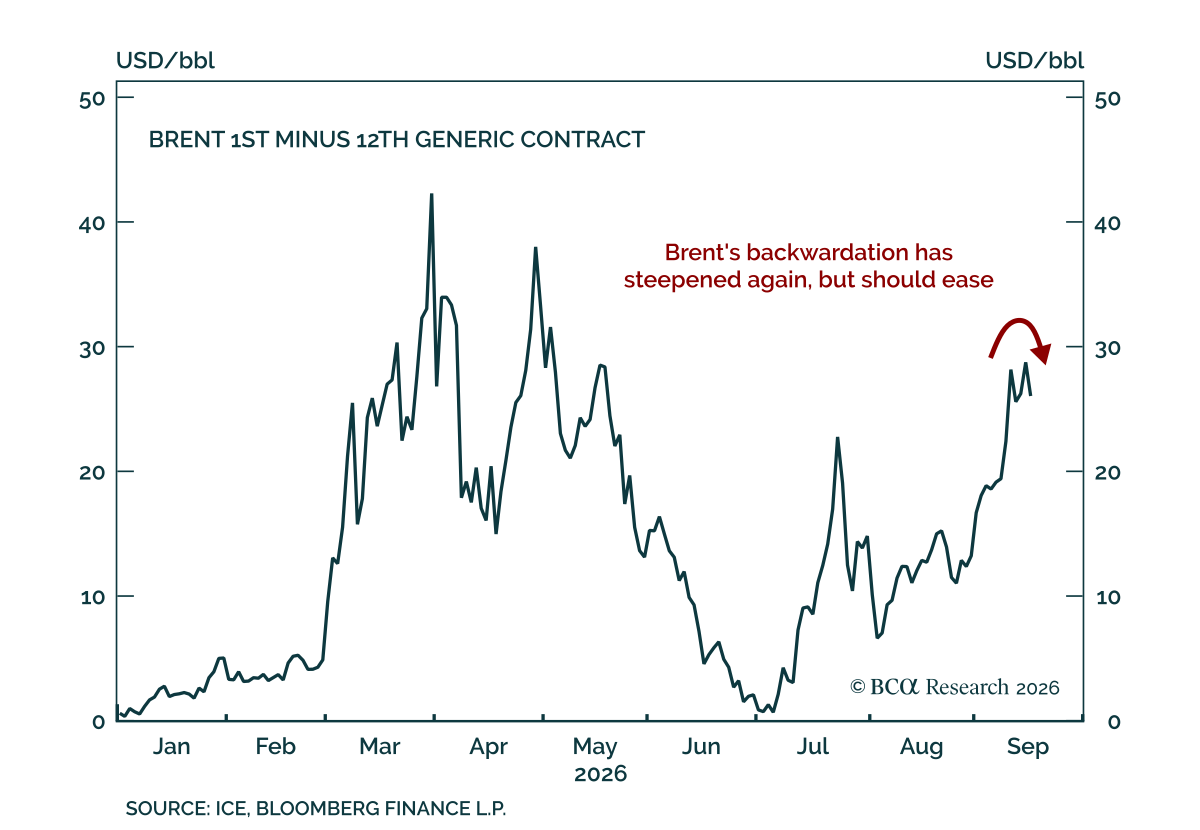
Our Commodity strategists expect rising dark transits through the Strait of Hormuz to keep cushioning the blow to global crude supplies. Middle Eastern seaborne exports have continued to climb through September despite the latest escalation in hostilities, a…
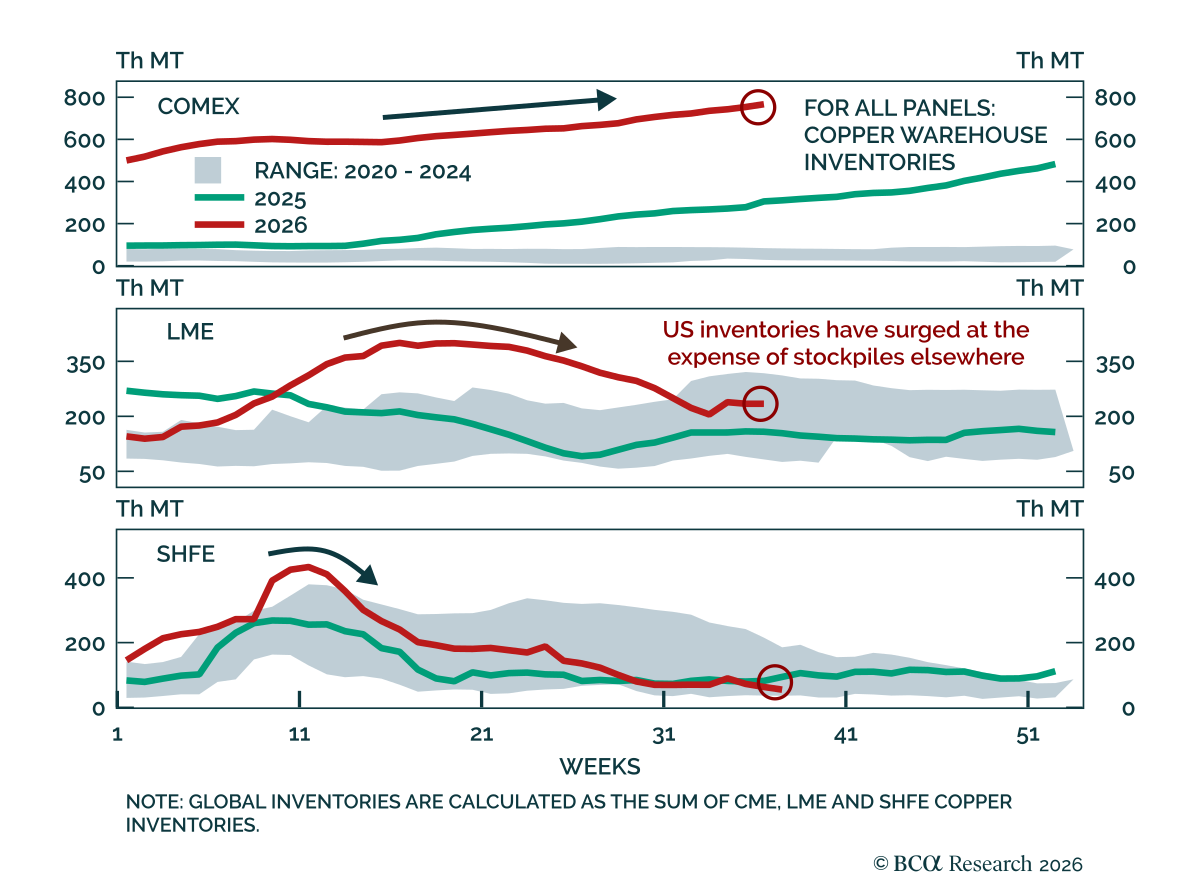
Our FICC strategists see copper's rally as hostage to US tariff uncertainty. The prospect of a levy on refined copper imports has dislocated global inventories and lifted prices. US exchange stockpiles now stand at 15 times their 2020-2024 average and account…
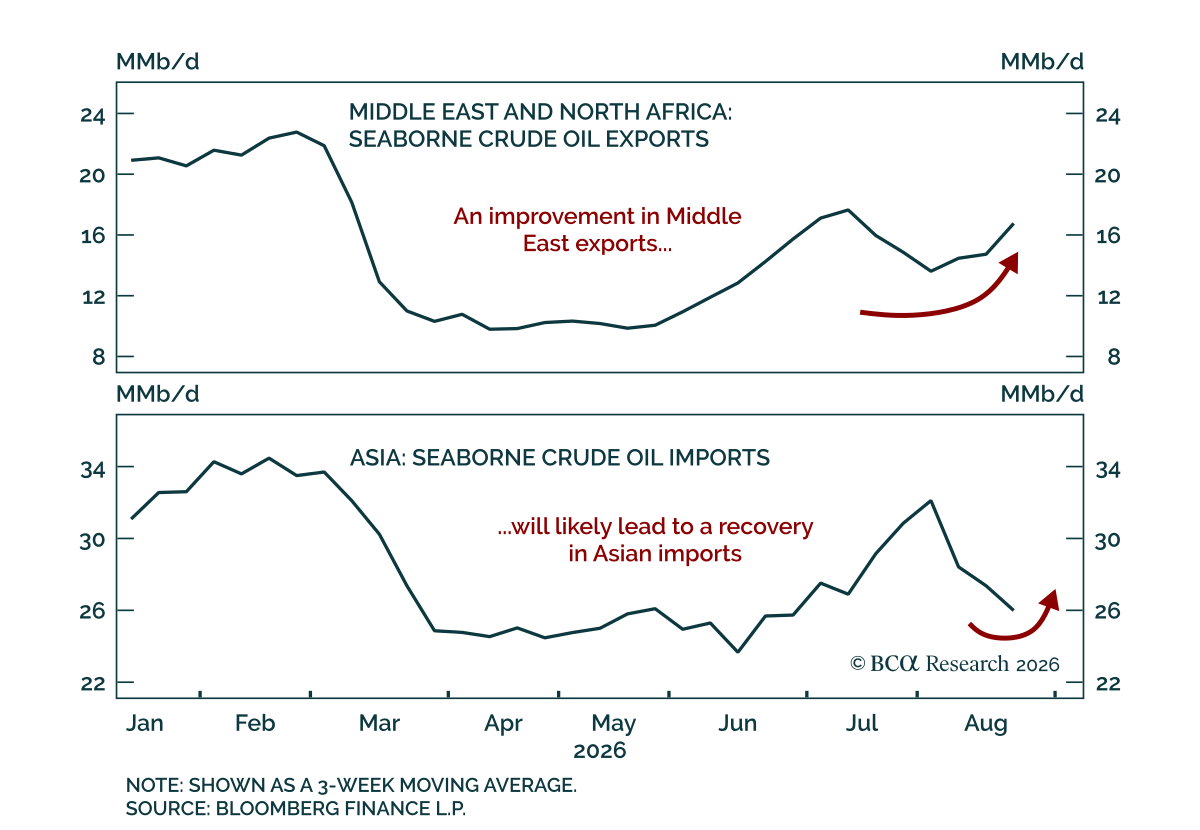
Our Commodity strategists judge that crack spreads are near their peak; the next big move will be to the downside. The record premium of refined product prices over crude reflects a bifurcated oil market, in which the pain from the supply disruption sits at…

El Niño signals are strengthening, but the setup points to soybean underperformance versus the broader agriculture complex. Agriculture is generally less exposed to swings in the business cycle than energy and industrial metals, with prices driven more by…
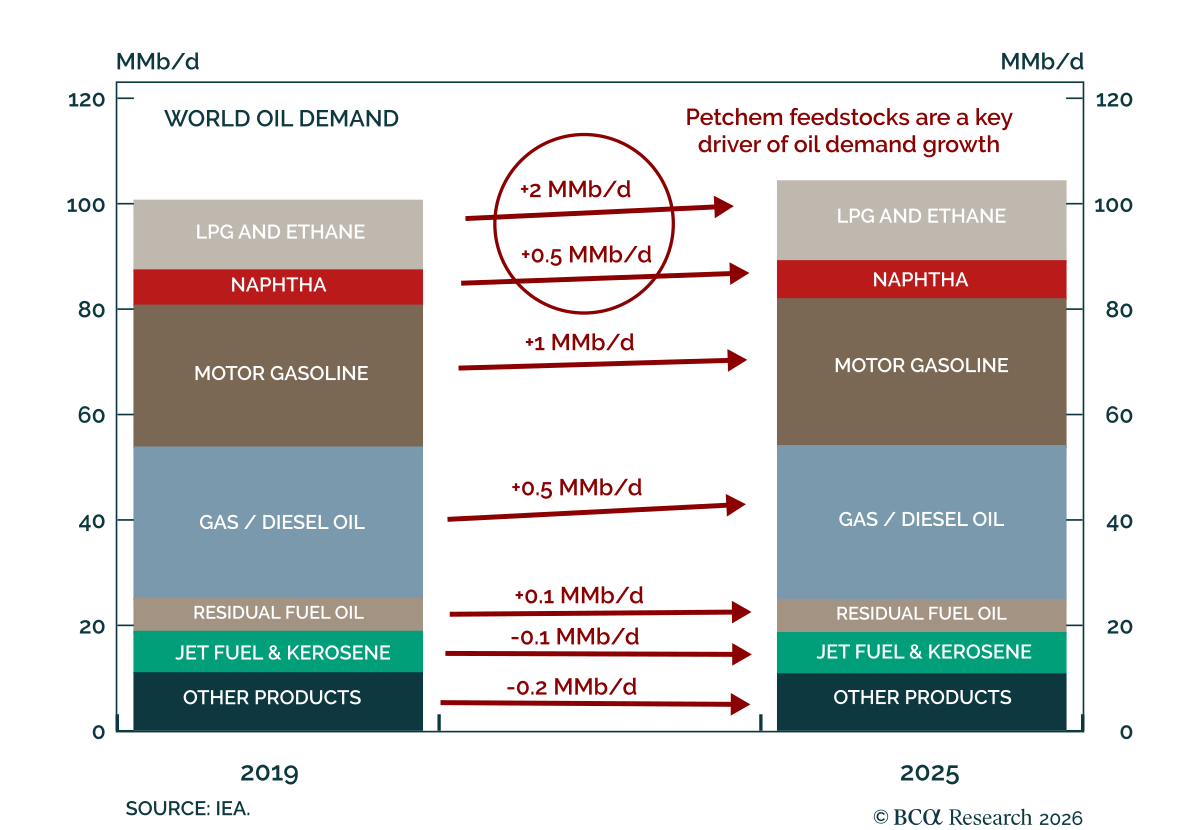
Our Commodity strategists see China's pivot to coal-derived petrochemical feedstock as a long-term tailwind for Chinese coal prices, and a structural headwind for global oil demand growth. Petrochemicals account for most of the net increase in oil demand in…
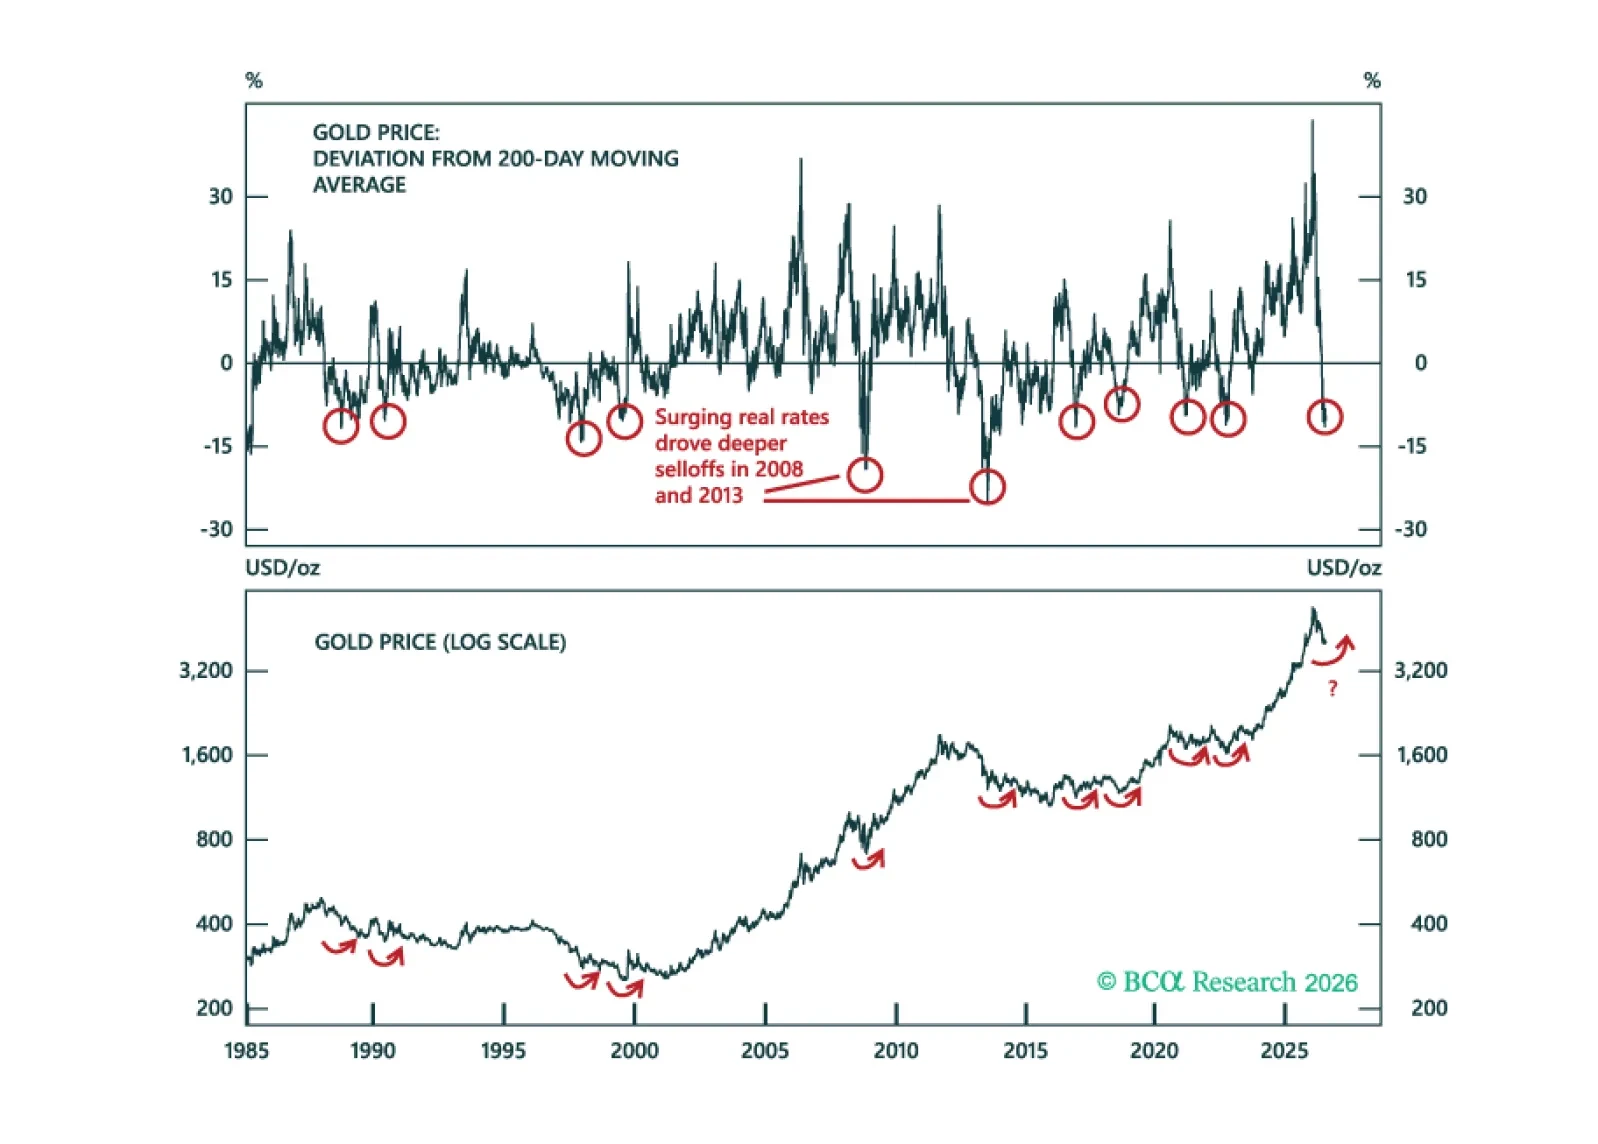
In this Special Report we argue that the worst of gold's downturn is likely behind us. Real rates and the dollar — which have reasserted themselves as gold's primary drivers — are set to shift from headwinds to tailwinds for the metal.