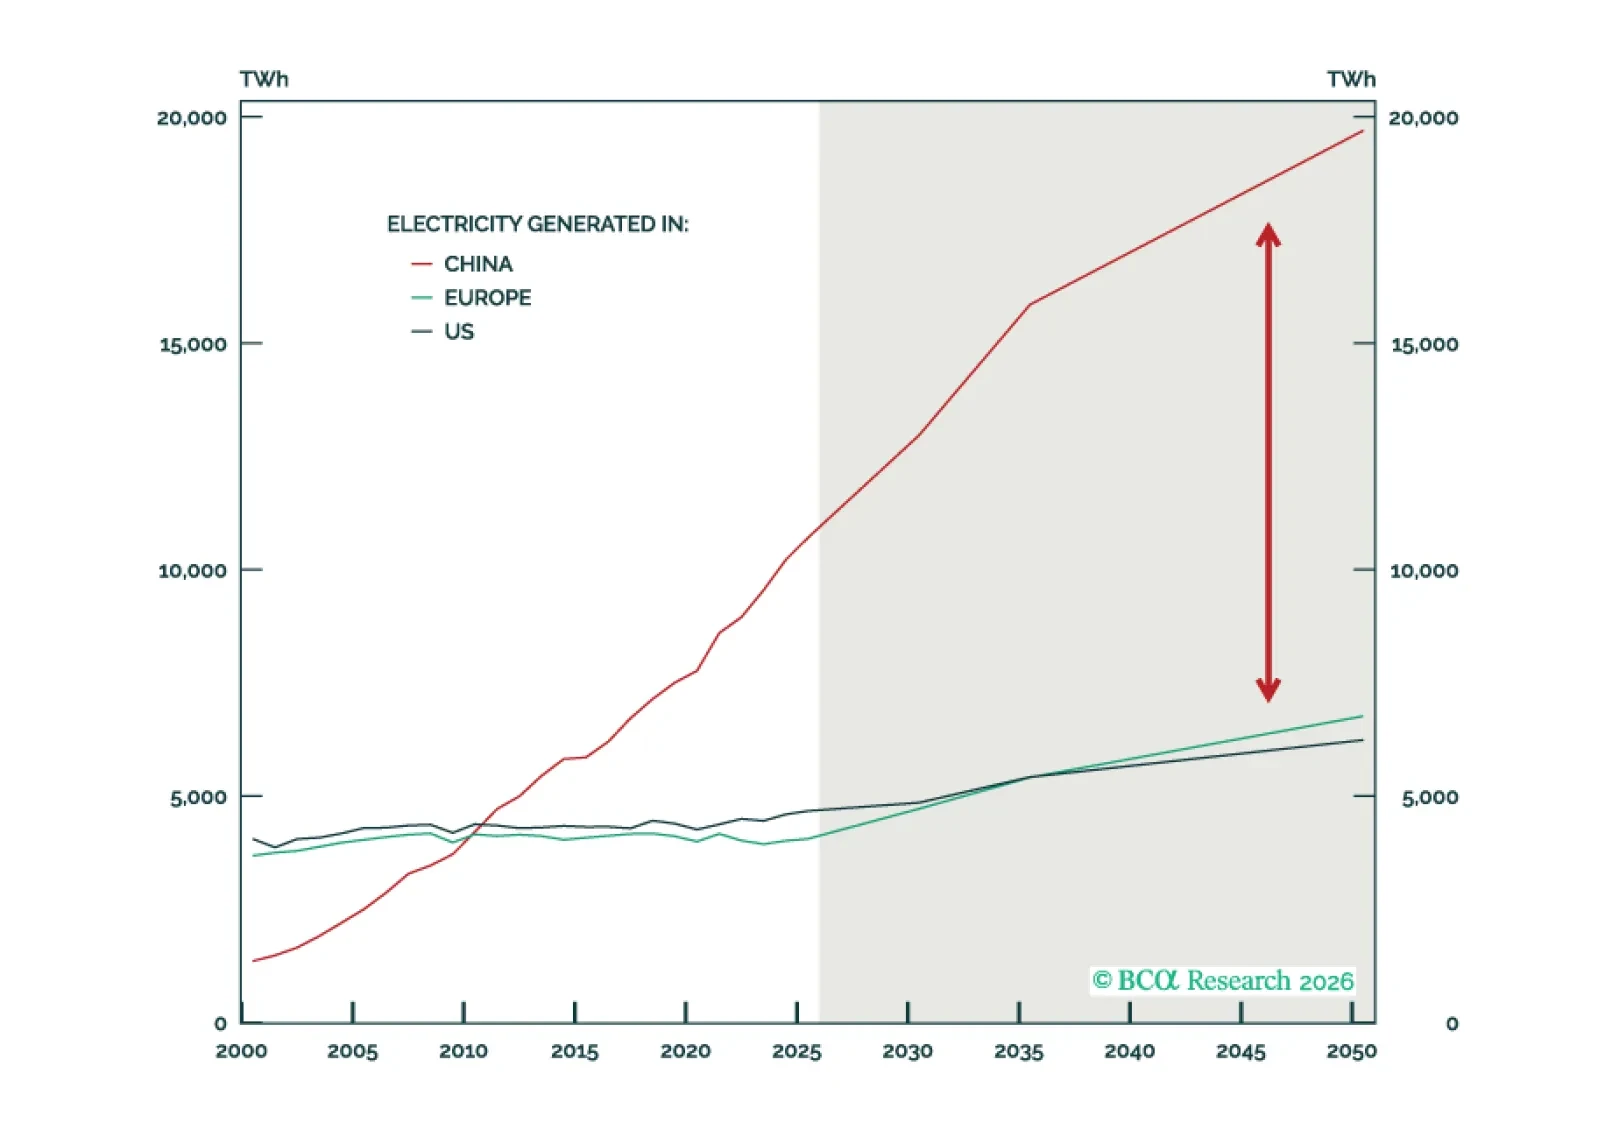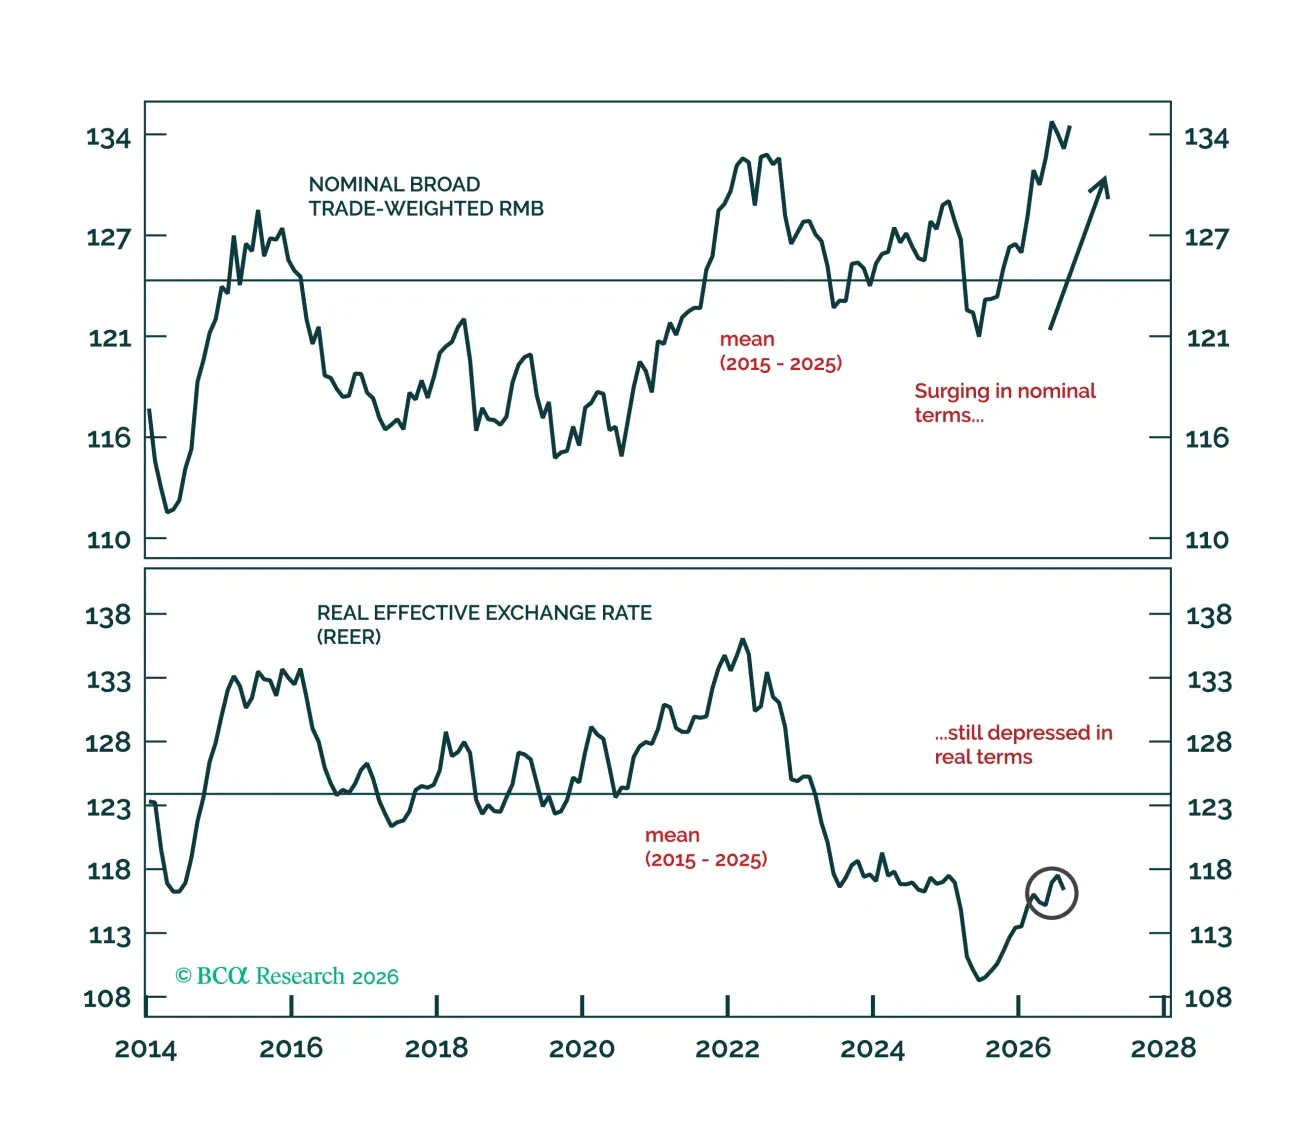
China's policy stance is gradually becoming more supportive of households, but a decisive reflationary pivot has yet to materialize. In the meantime, we favor large state-owned banks and onshore utilities as defensive plays.
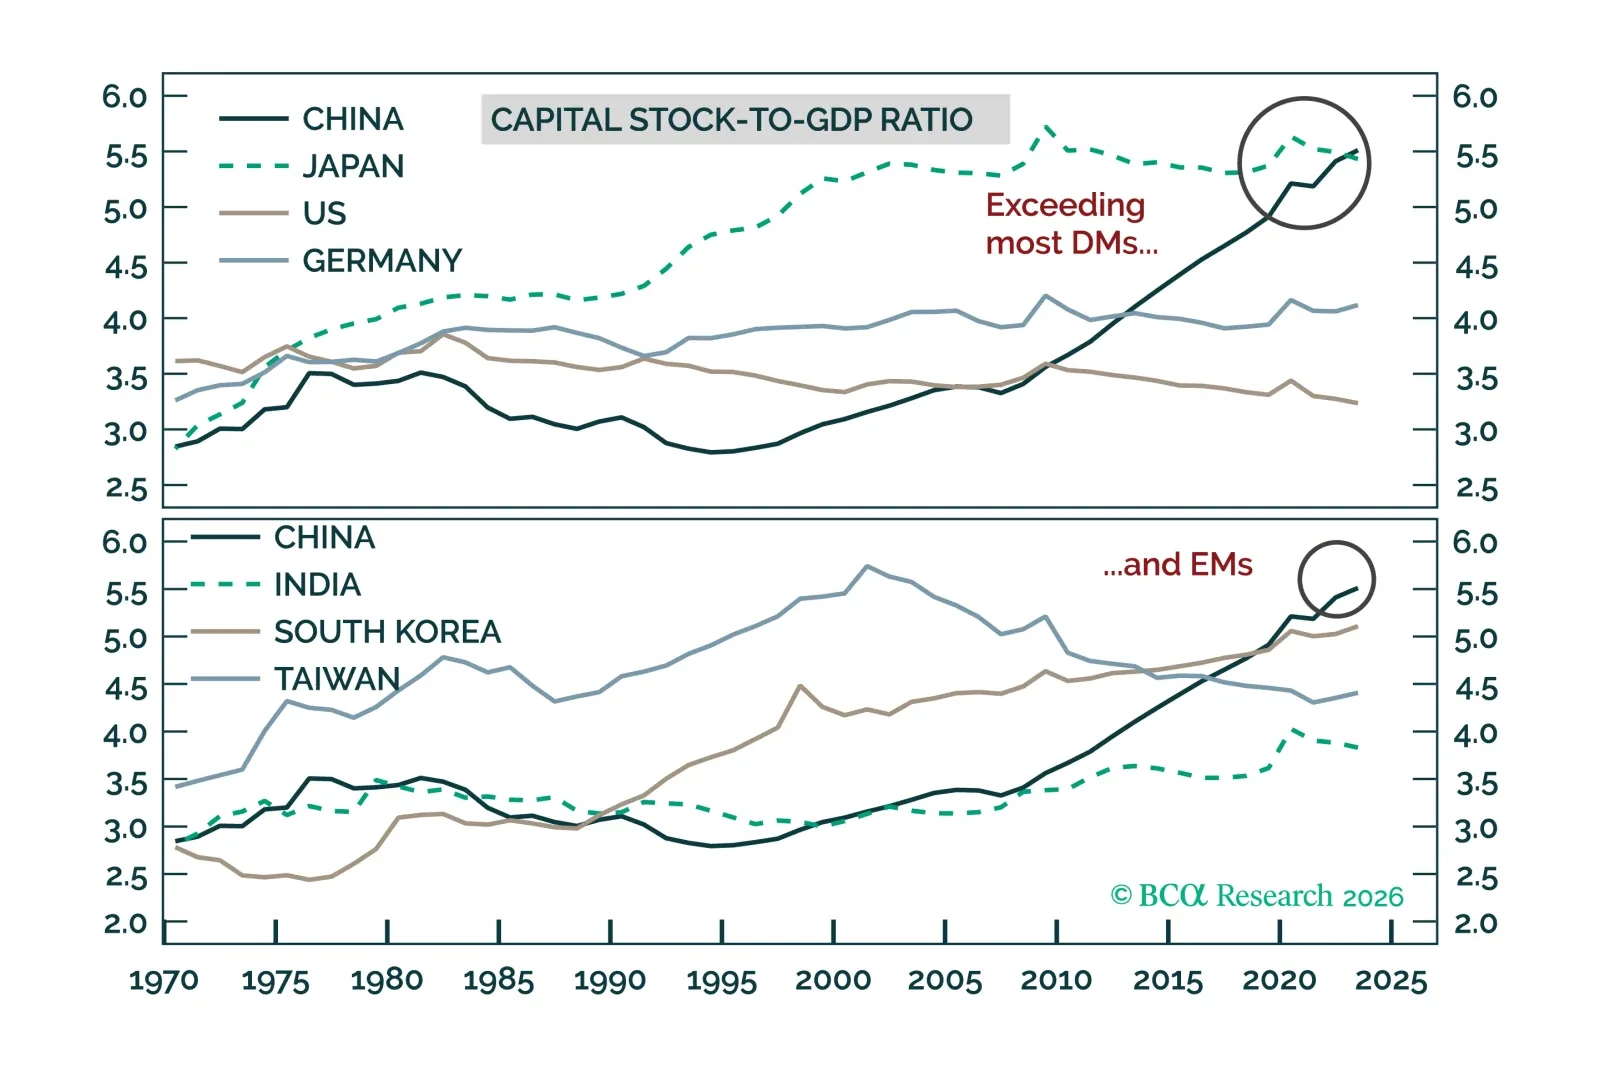
China’s investment has hit cyclical and structural limits. Mounting economic pressures will likely push Beijing toward a more aggressive, consumer-focused reflationary stance over the next one to two years.
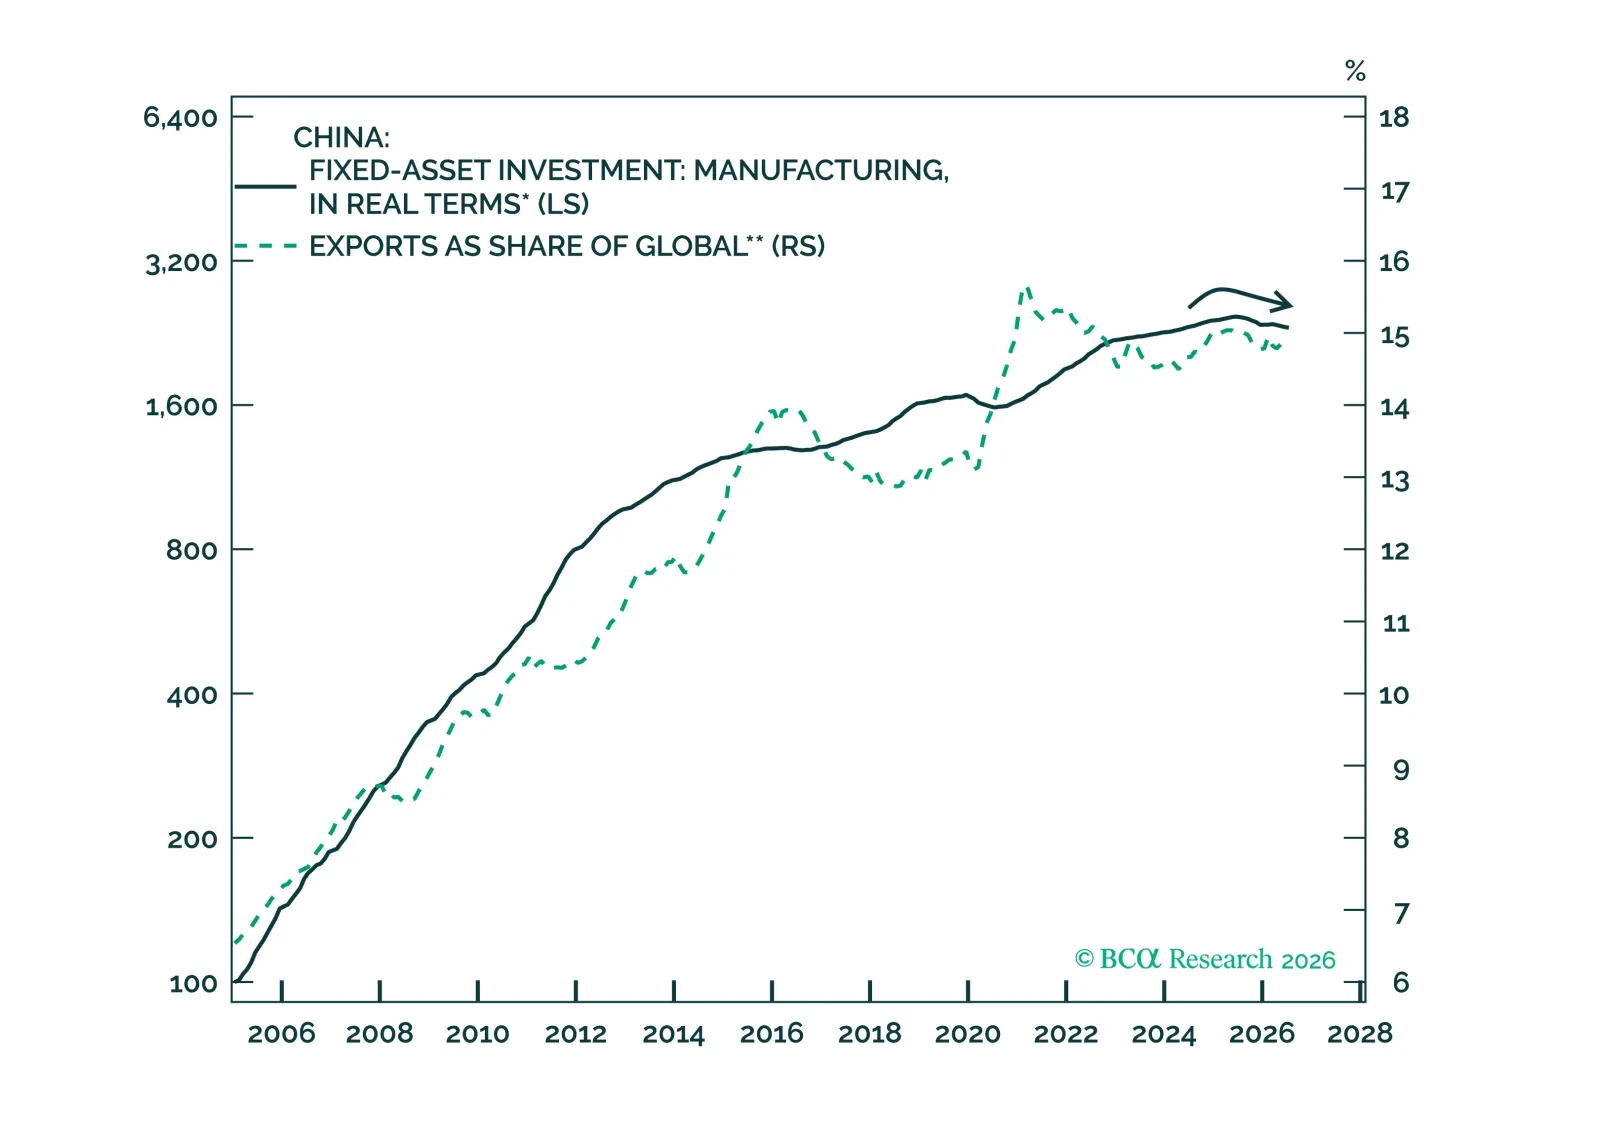
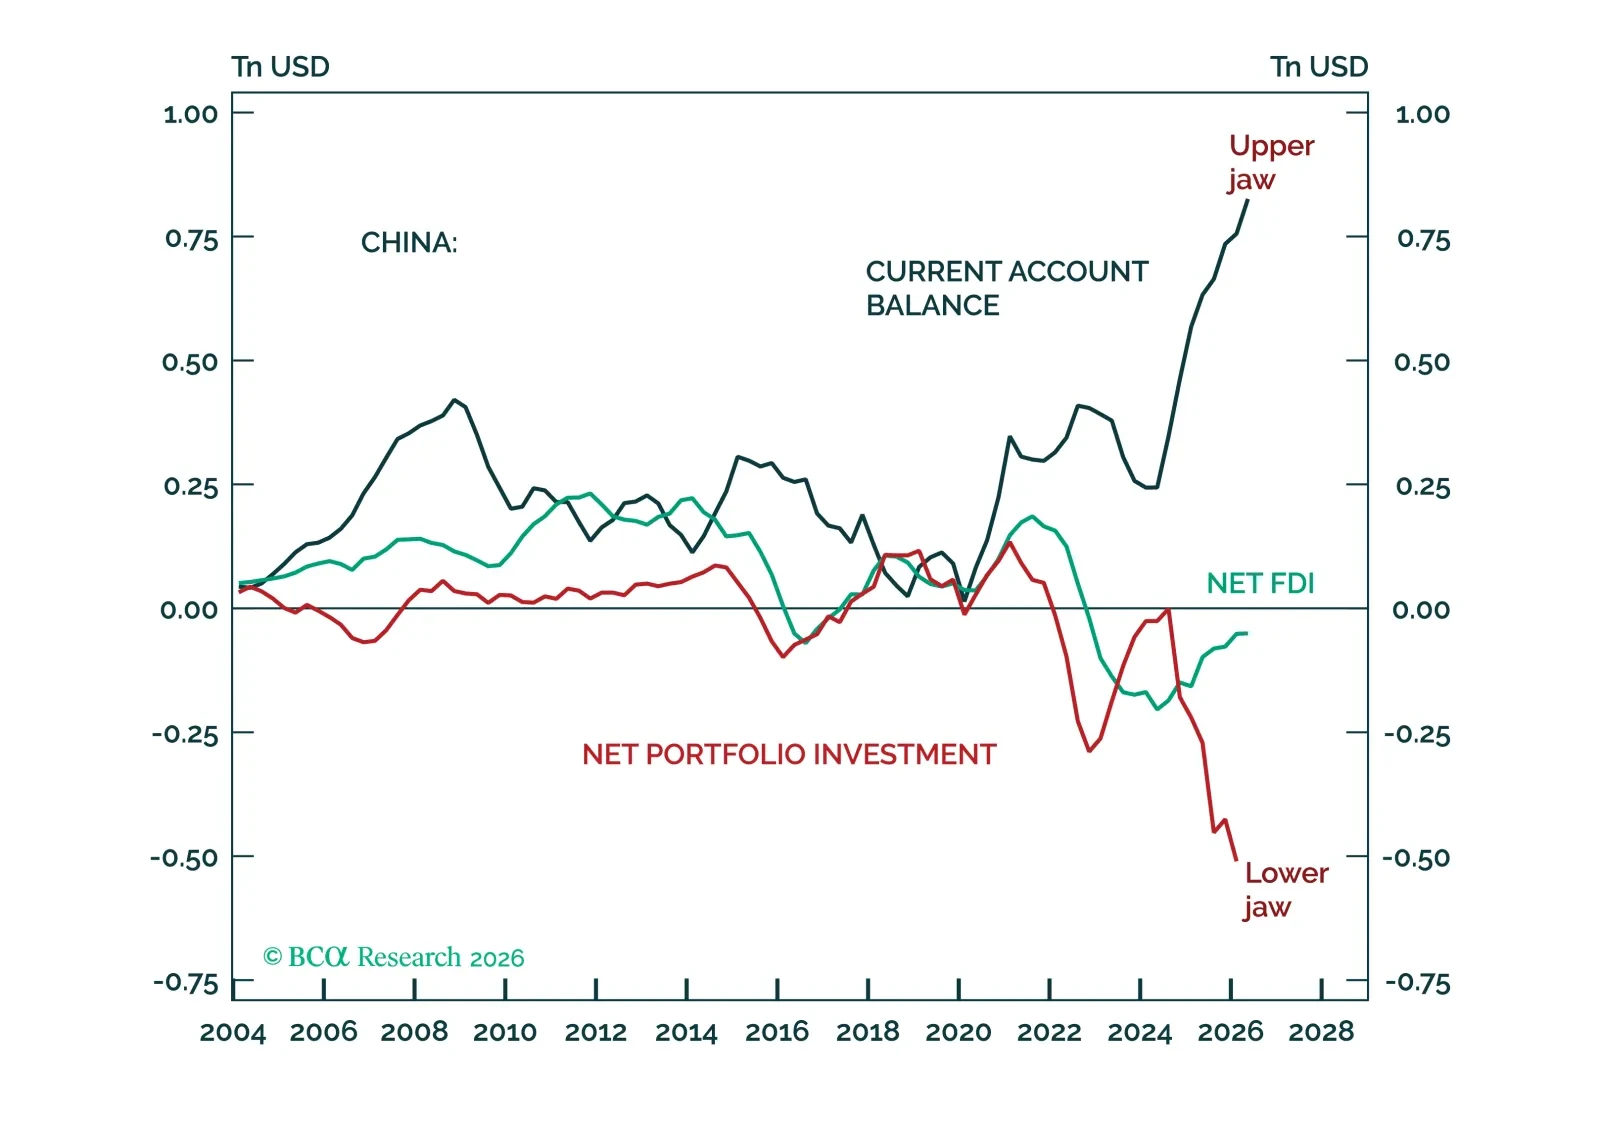
In this report, we highlight notable developments on both sides of China’s BoP: a widening external surplus on the current account side, and shifts in how that surplus is recycled abroad through BoP financial account.
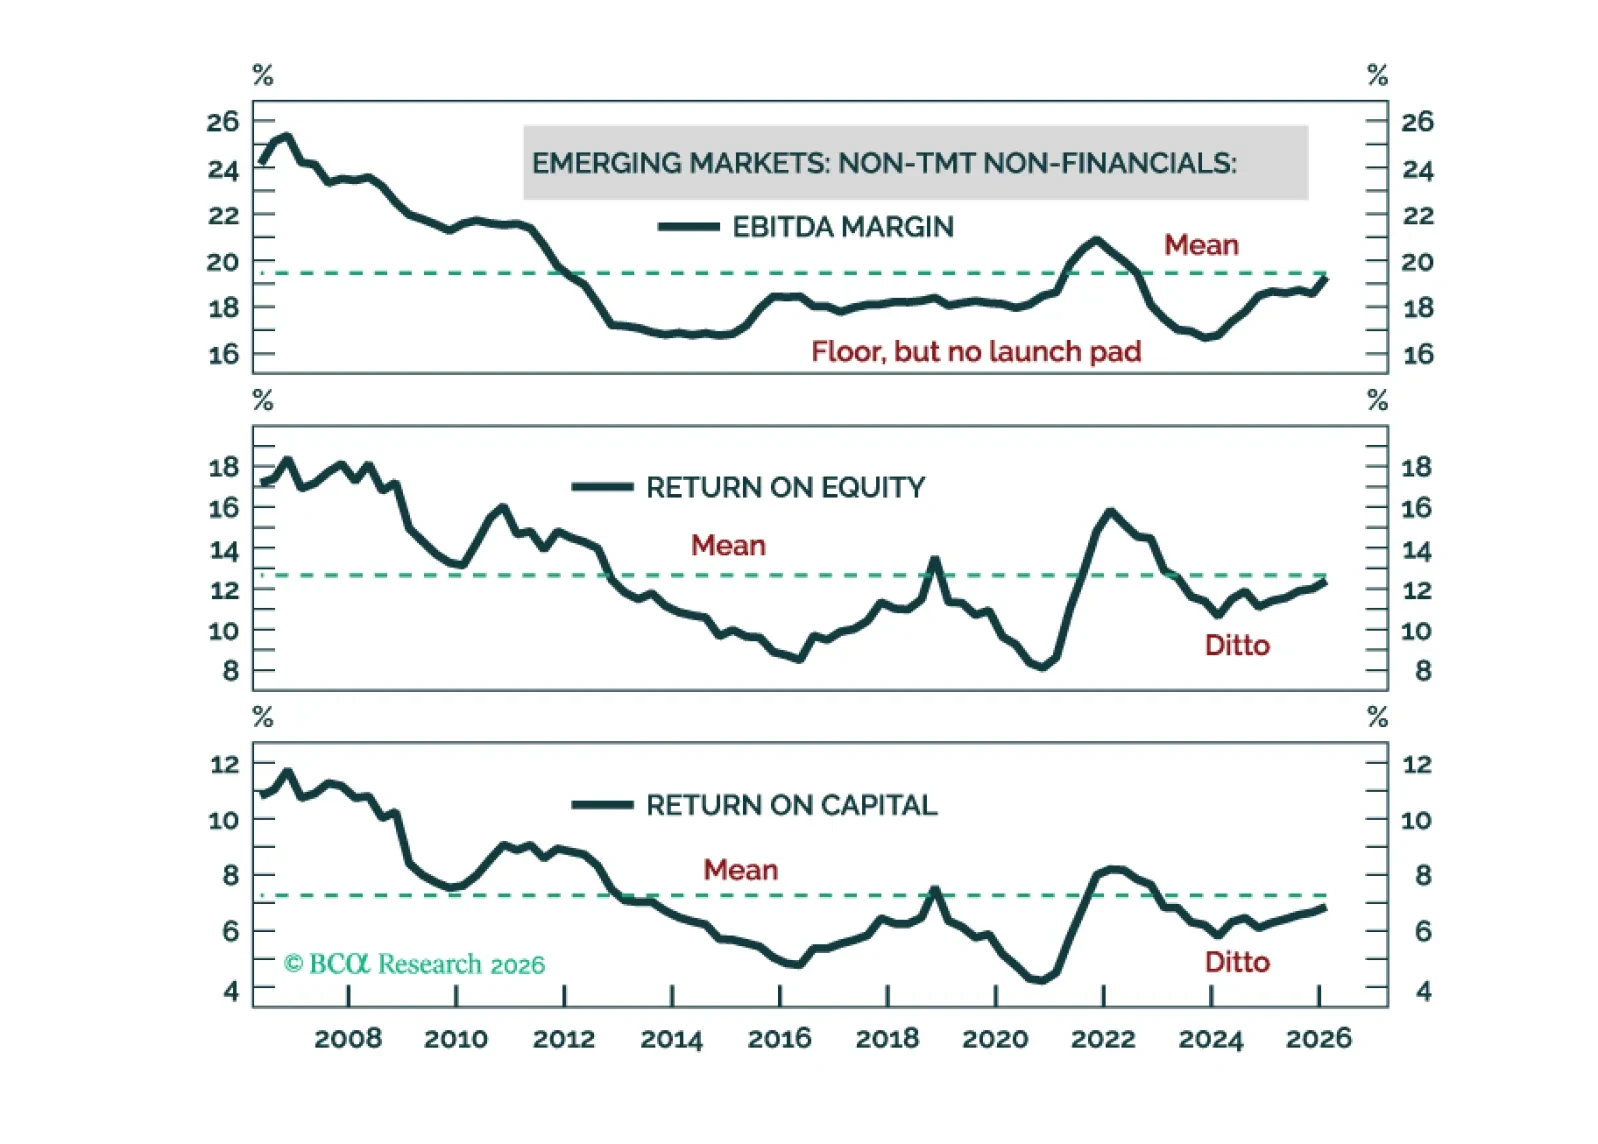
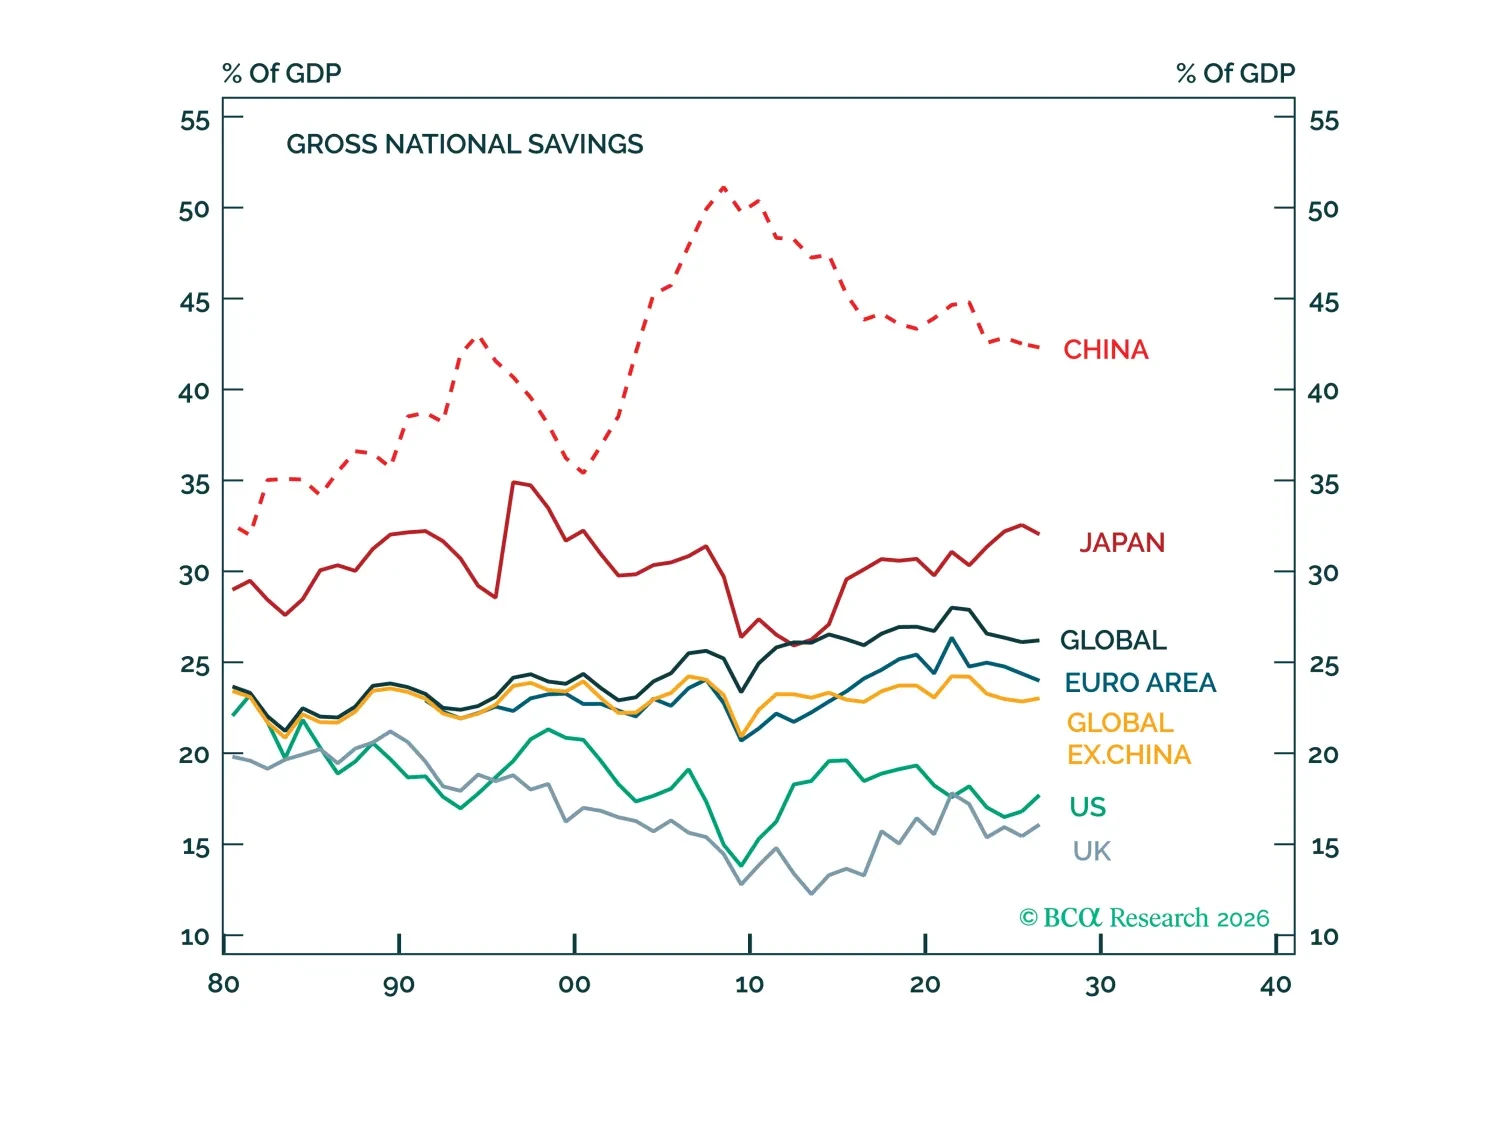
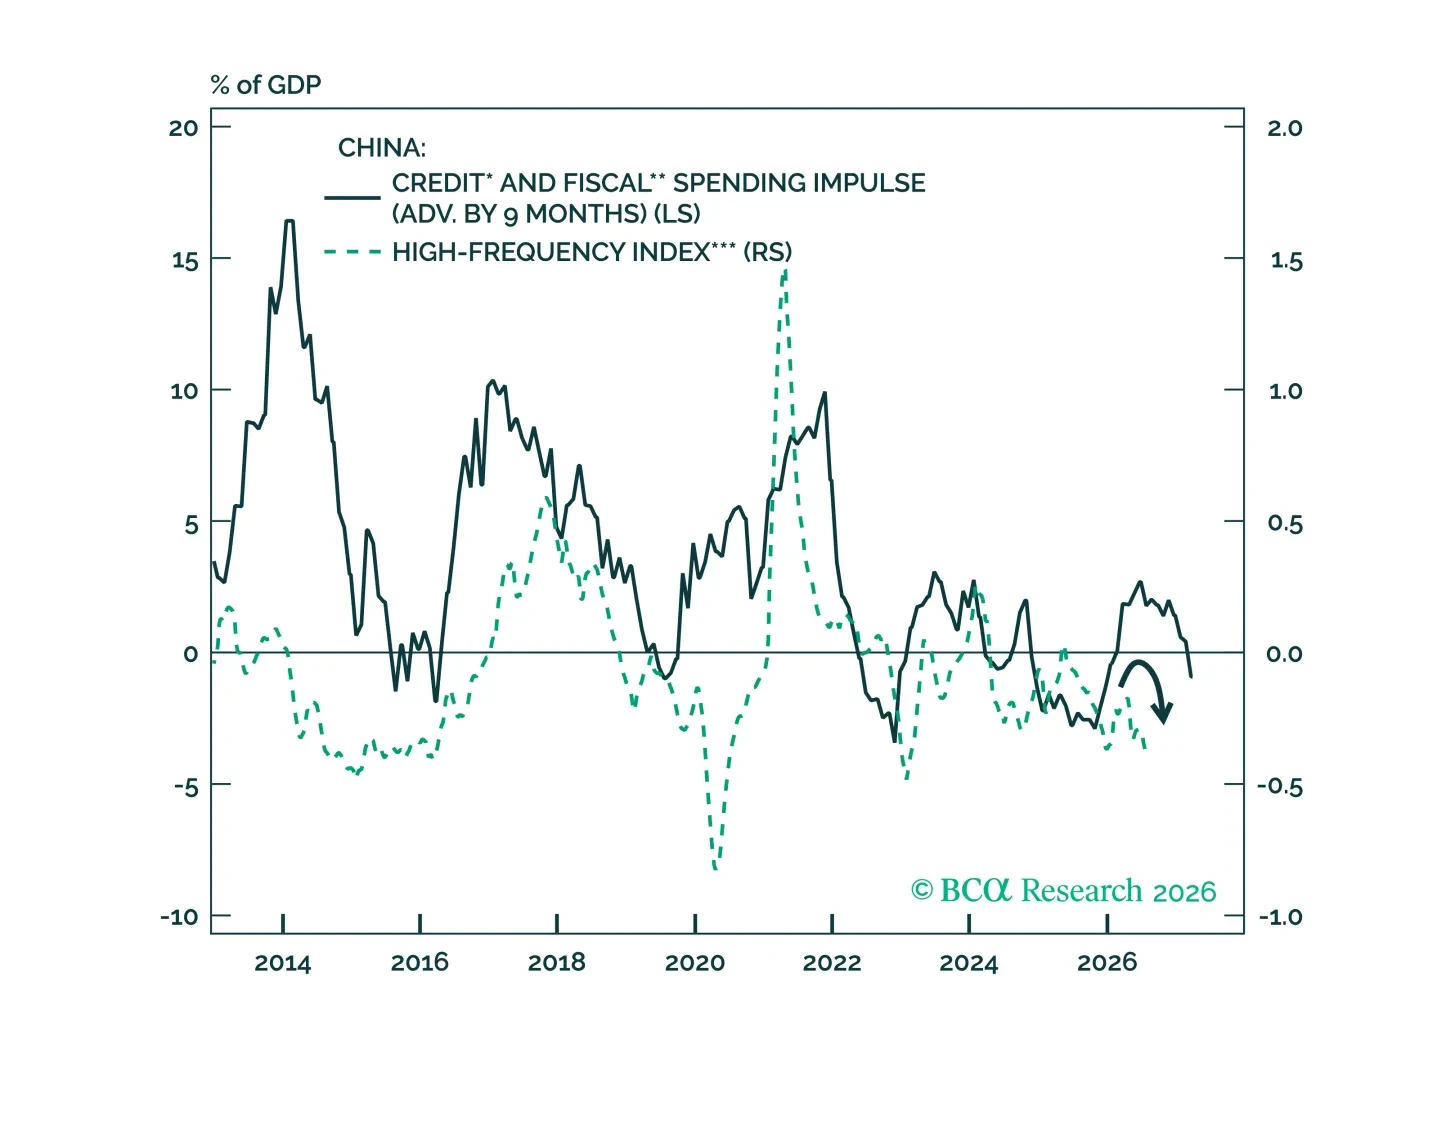
China's economy is slowing, but policymakers are unlikely to launch broad-based stimulus in H2. Meanwhile, the emergence of China's "Kimi moment" underscores Beijing's commitment to technological upgrading and the country's rapidly advancing AI capabilities.
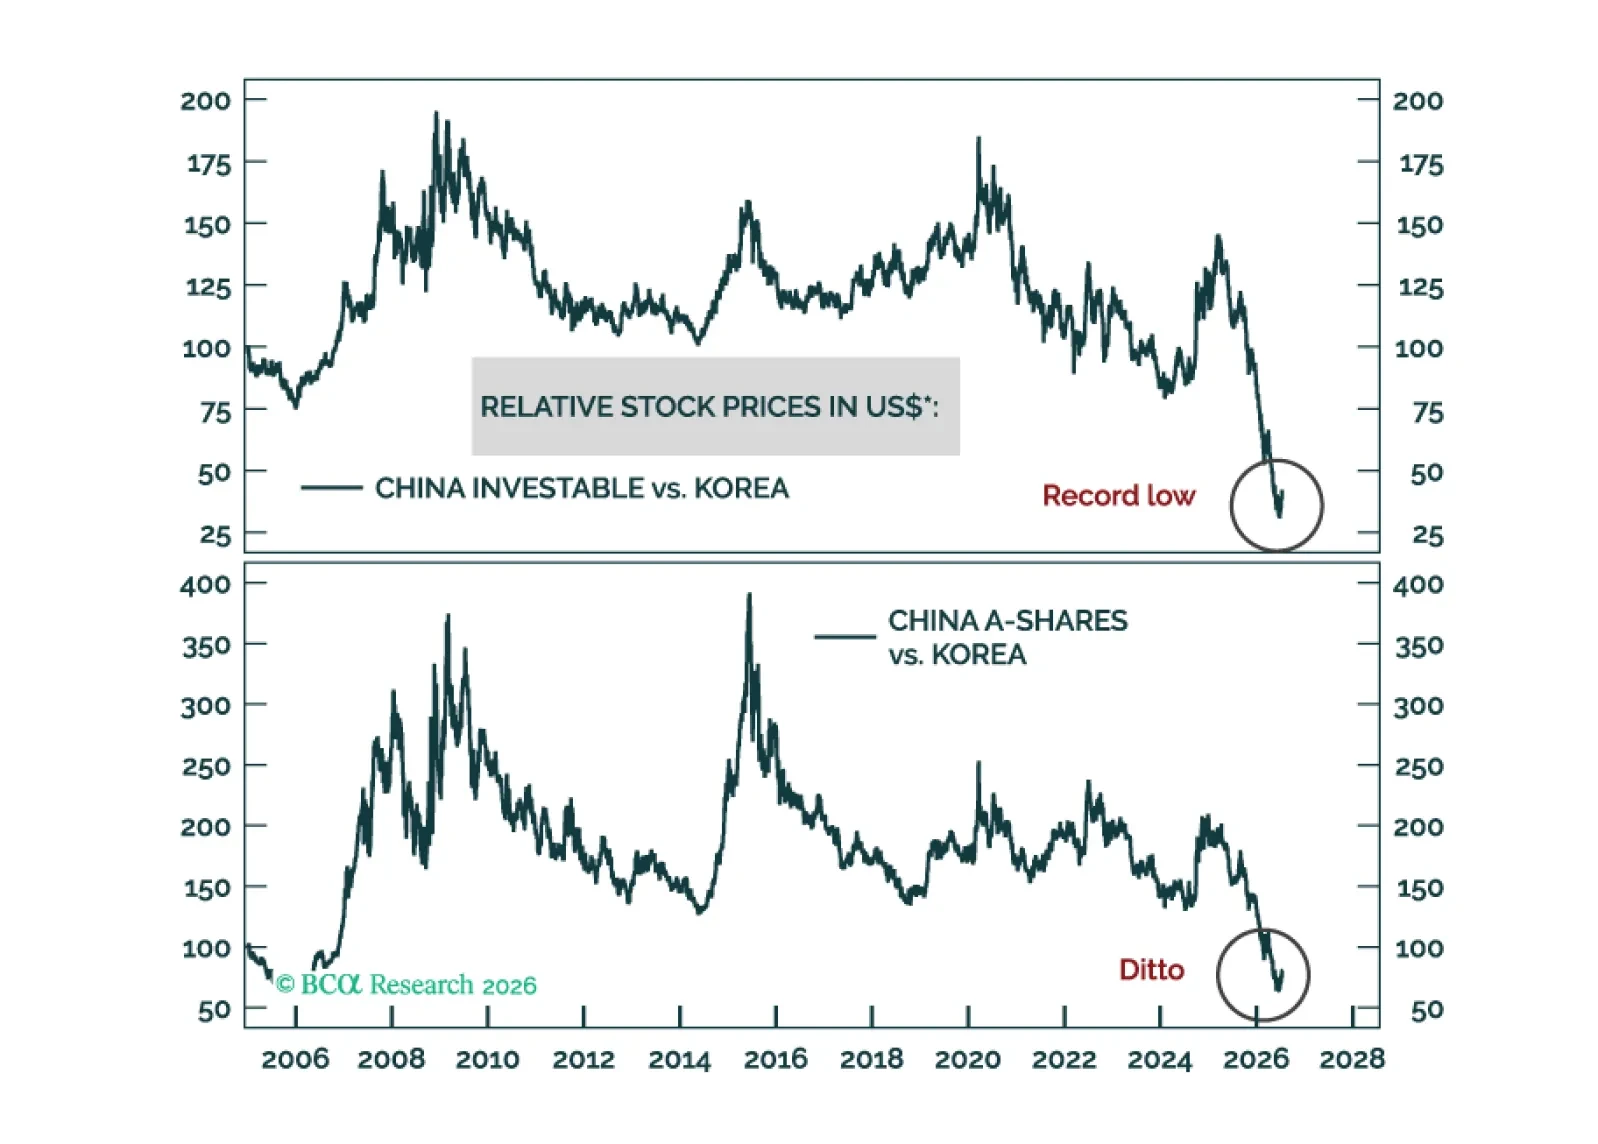
As a short-term (0-3 months) trade, go long an equal-weighted basket of Chinese Investable and A-shares / short the KOSPI. This is a bet on mean reversion. We do not recommend that medium- and long-term investors implement this strategy.
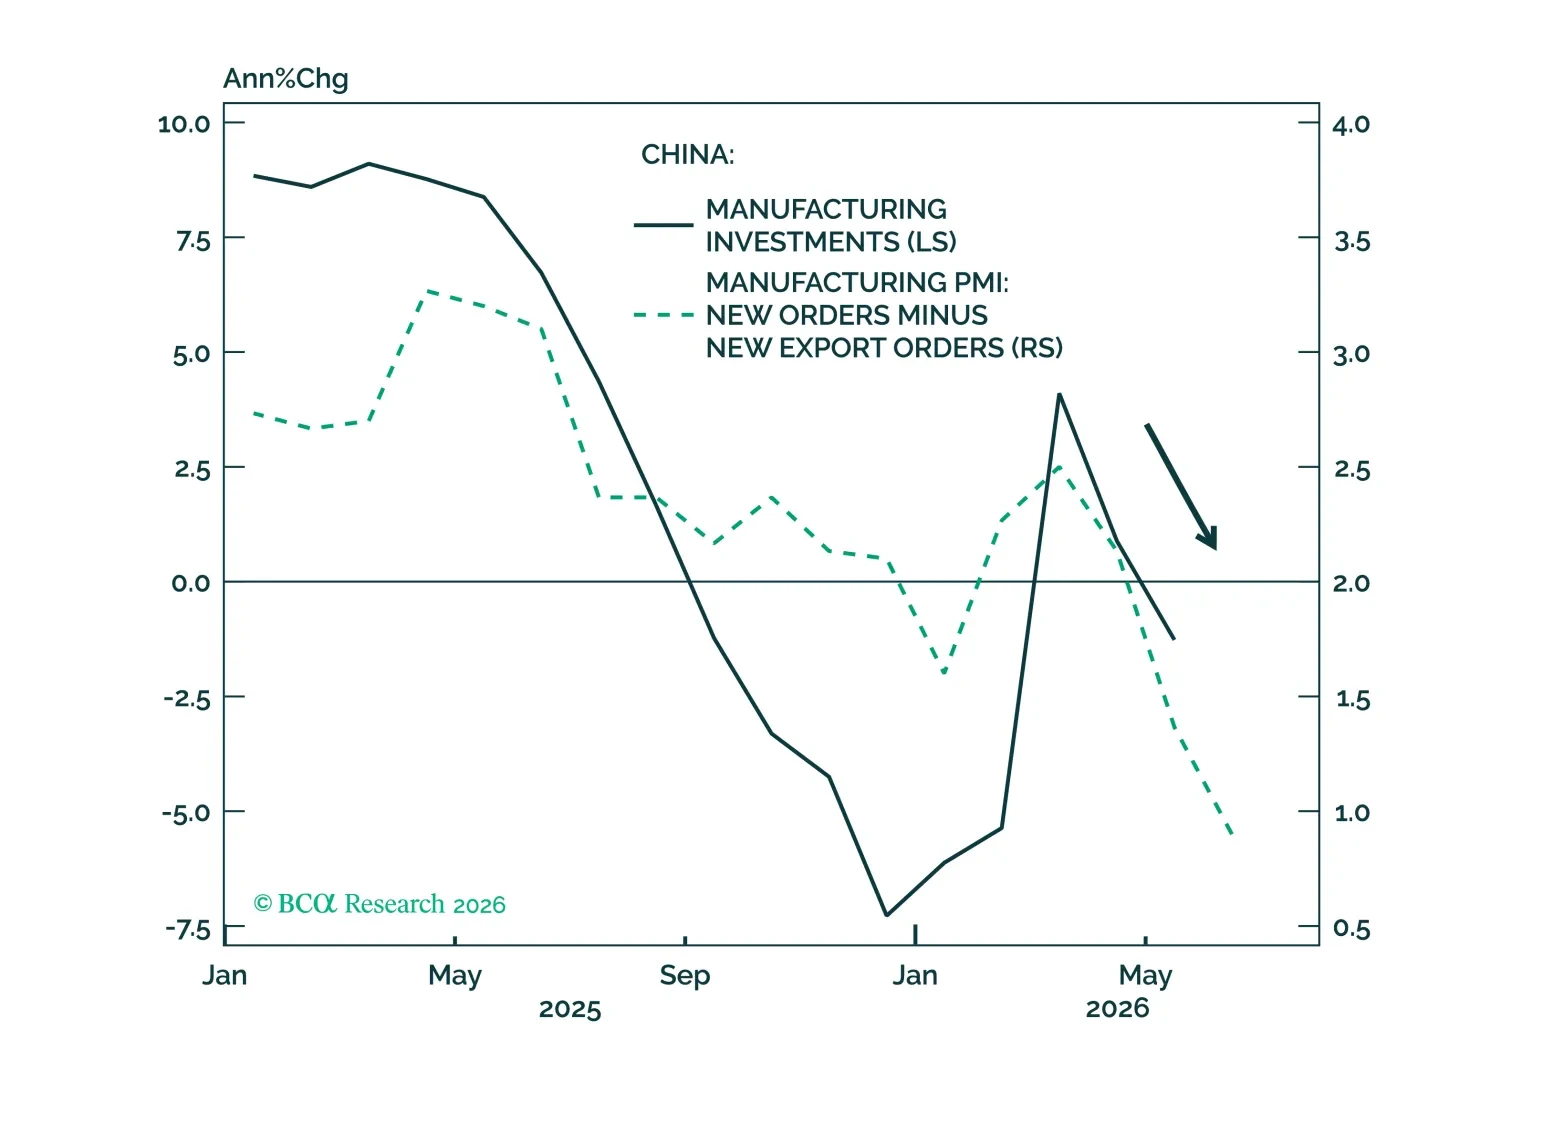
The rebound in China's producer prices and profits this year owes more to external demand than to meaningful progress under Beijing's anti-involution campaign.