 CoreMacro
Find out more
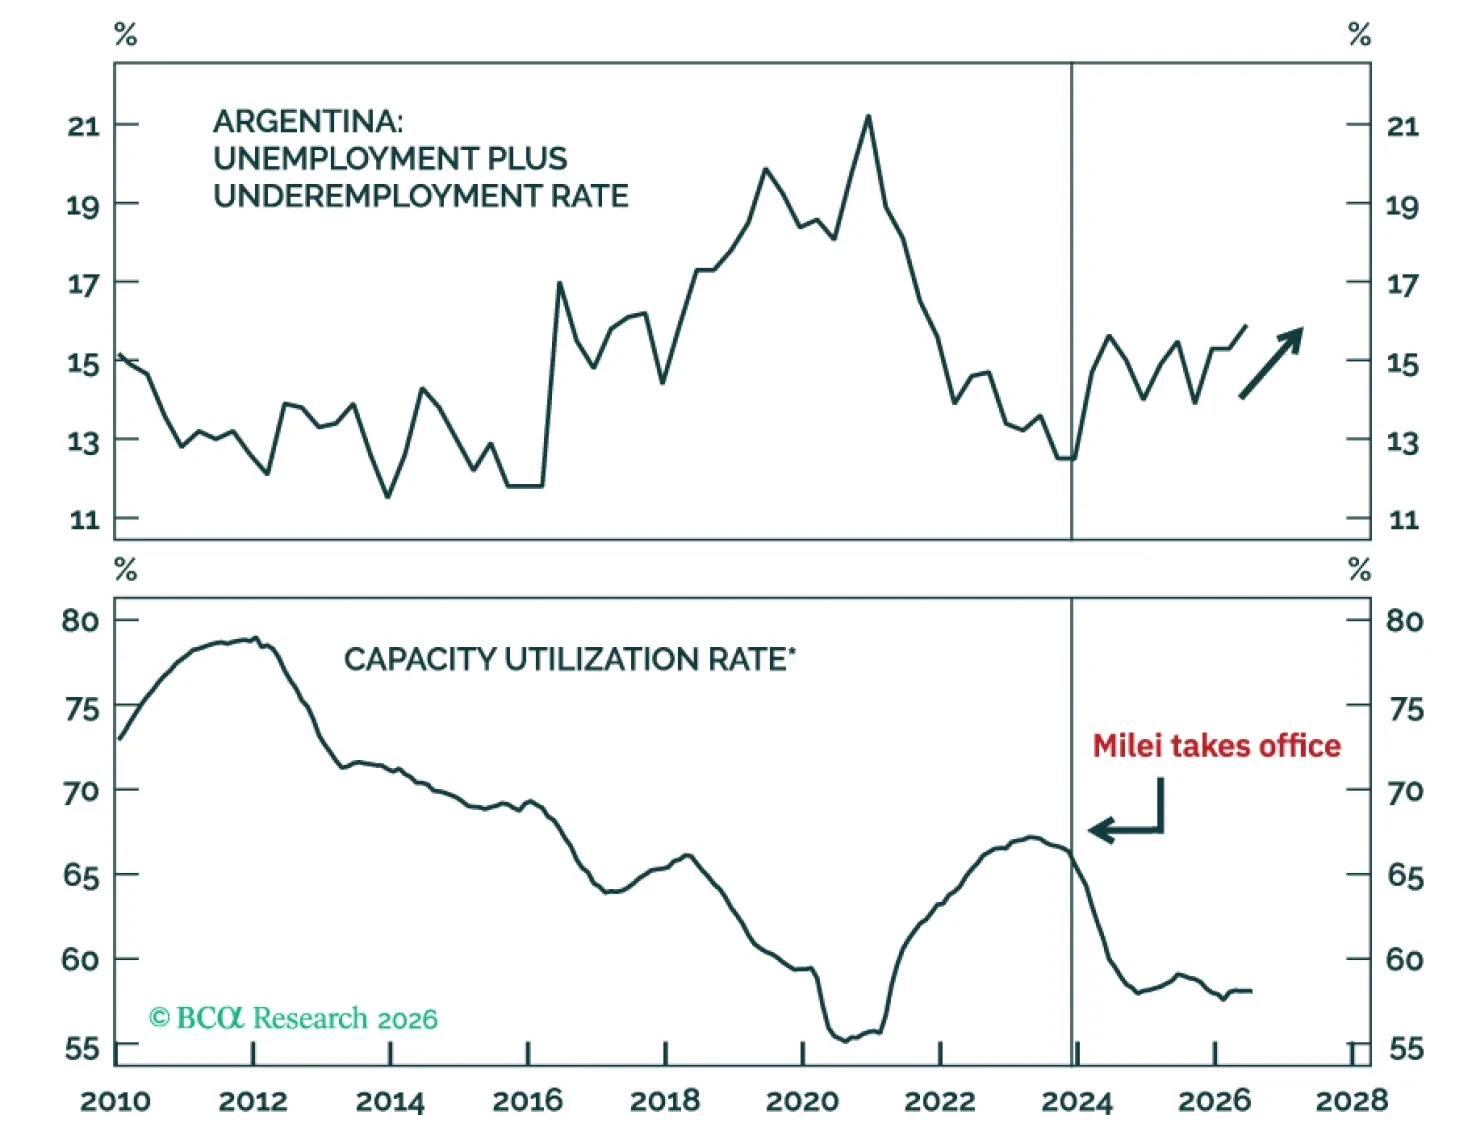
If President Milei does not ease policy immediately to contain the disinflationary squeeze, he is likely to lose next year's election. This means neoliberal structural reforms will suffer a setback in subsequent years. Close long positions in Argentine assets.
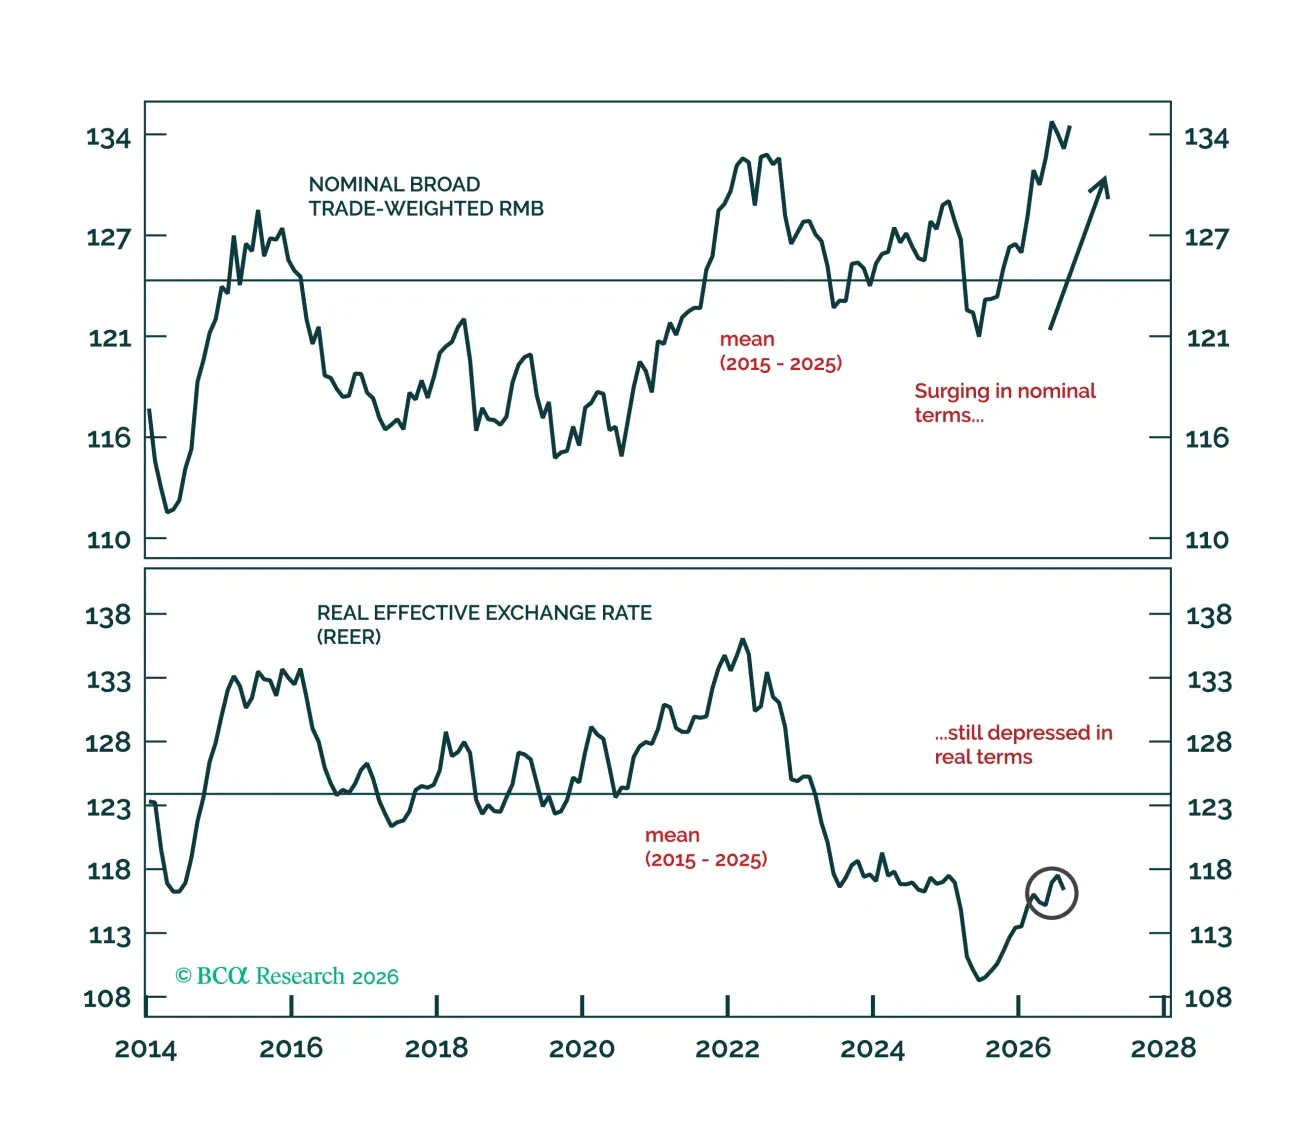
China's policy stance is gradually becoming more supportive of households, but a decisive reflationary pivot has yet to materialize. In the meantime, we favor large state-owned banks and onshore utilities as defensive plays.
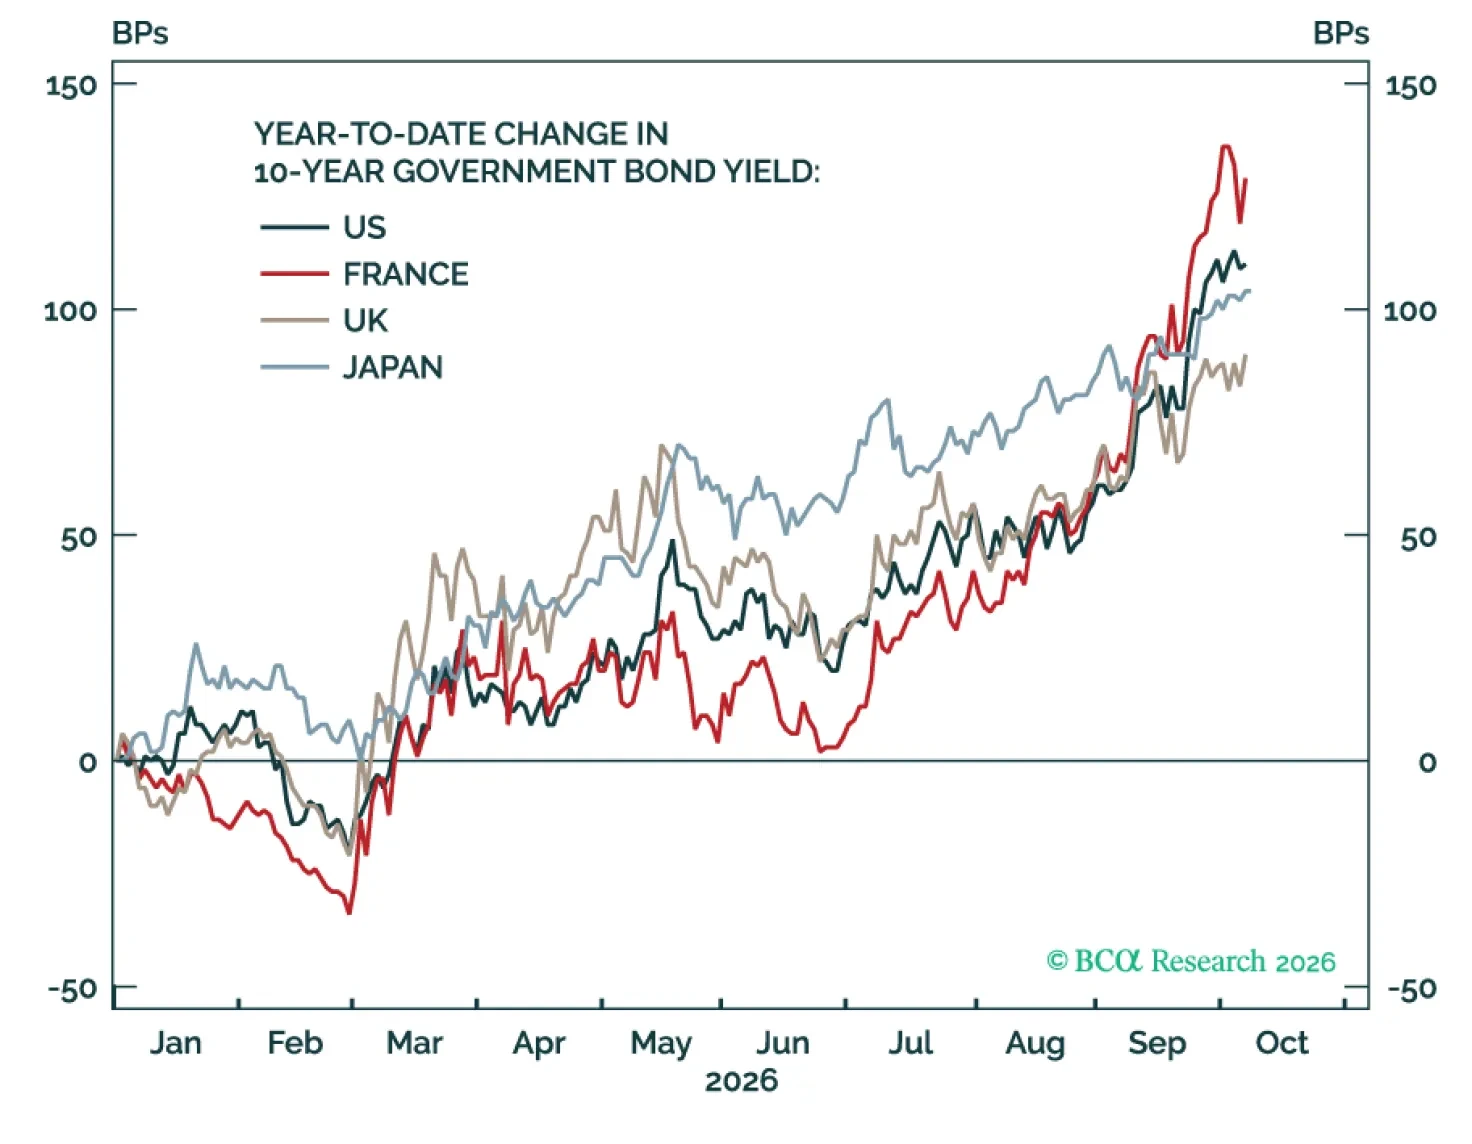
The global bond selloff is not over, but opportunities are emerging. US Treasuries and French OATs remain vulnerable to further selling, while other European government bonds look increasingly attractive. Investors should favor German Bunds and peripheral bonds, particularly on a currency-hedged basis.
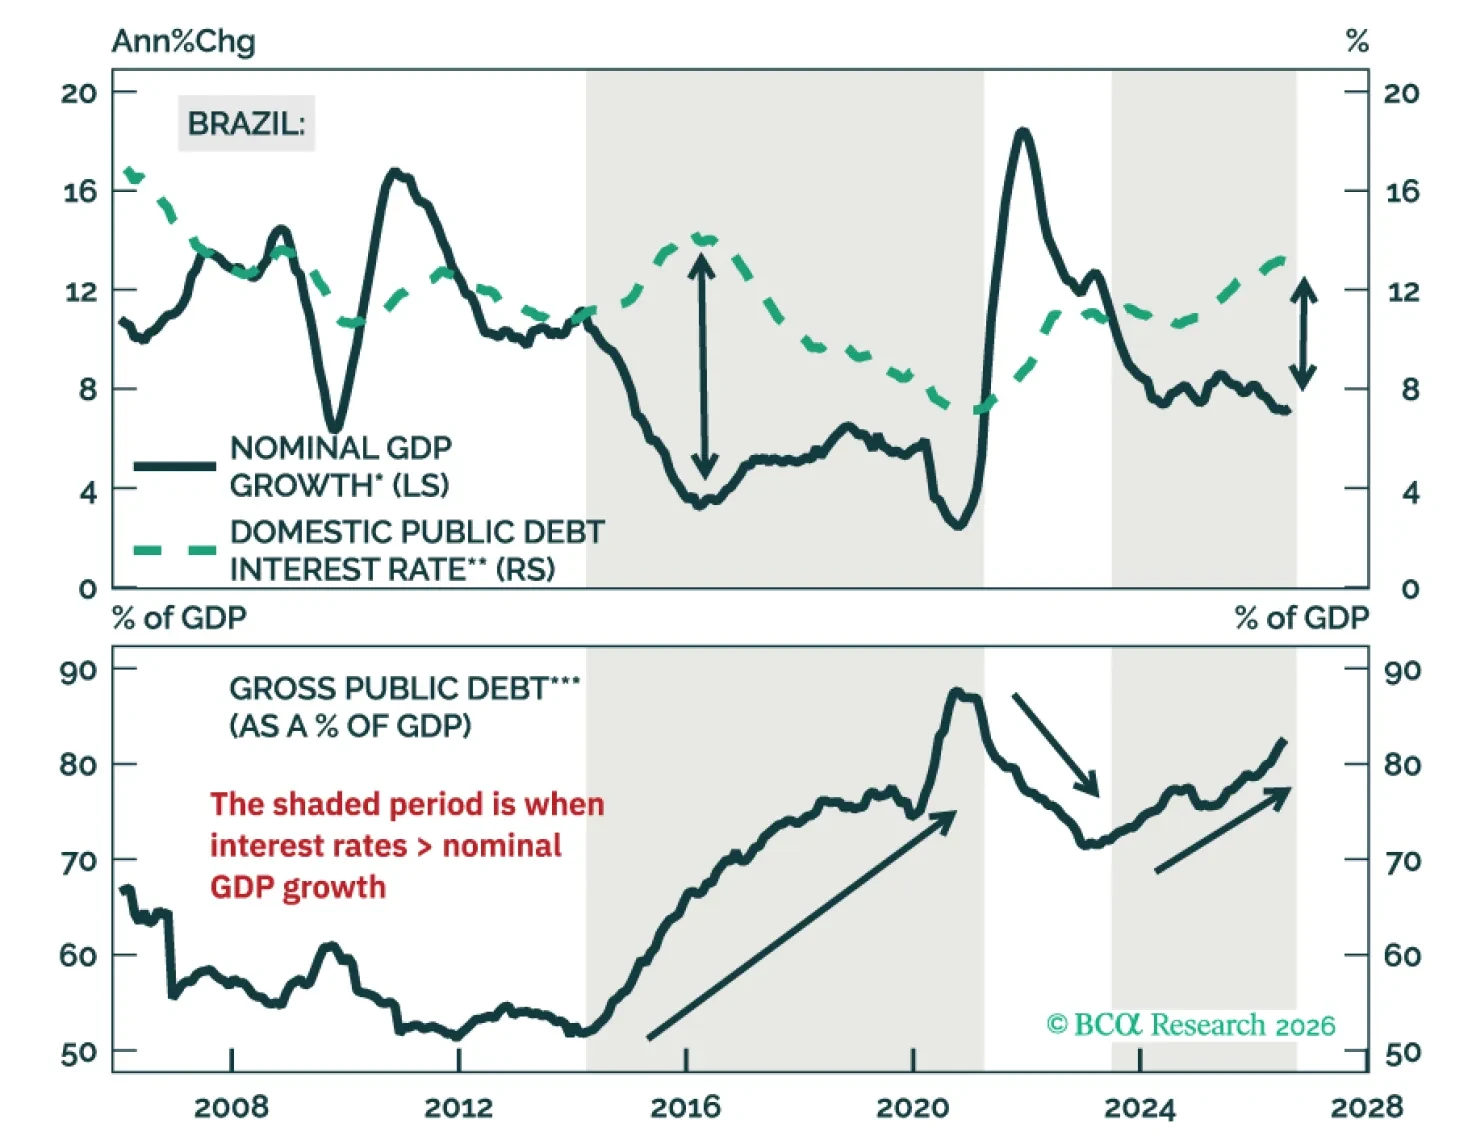
The most bullish development for Brazil from the weekend’s elections was not the higher odds of a right-wing presidency, but the likely president’s (Flávio Bolsonaro) stronghold in Congress. Upgrade Brazilian fixed-income markets to overweight and equities to neutral within their respective EM portfolios.
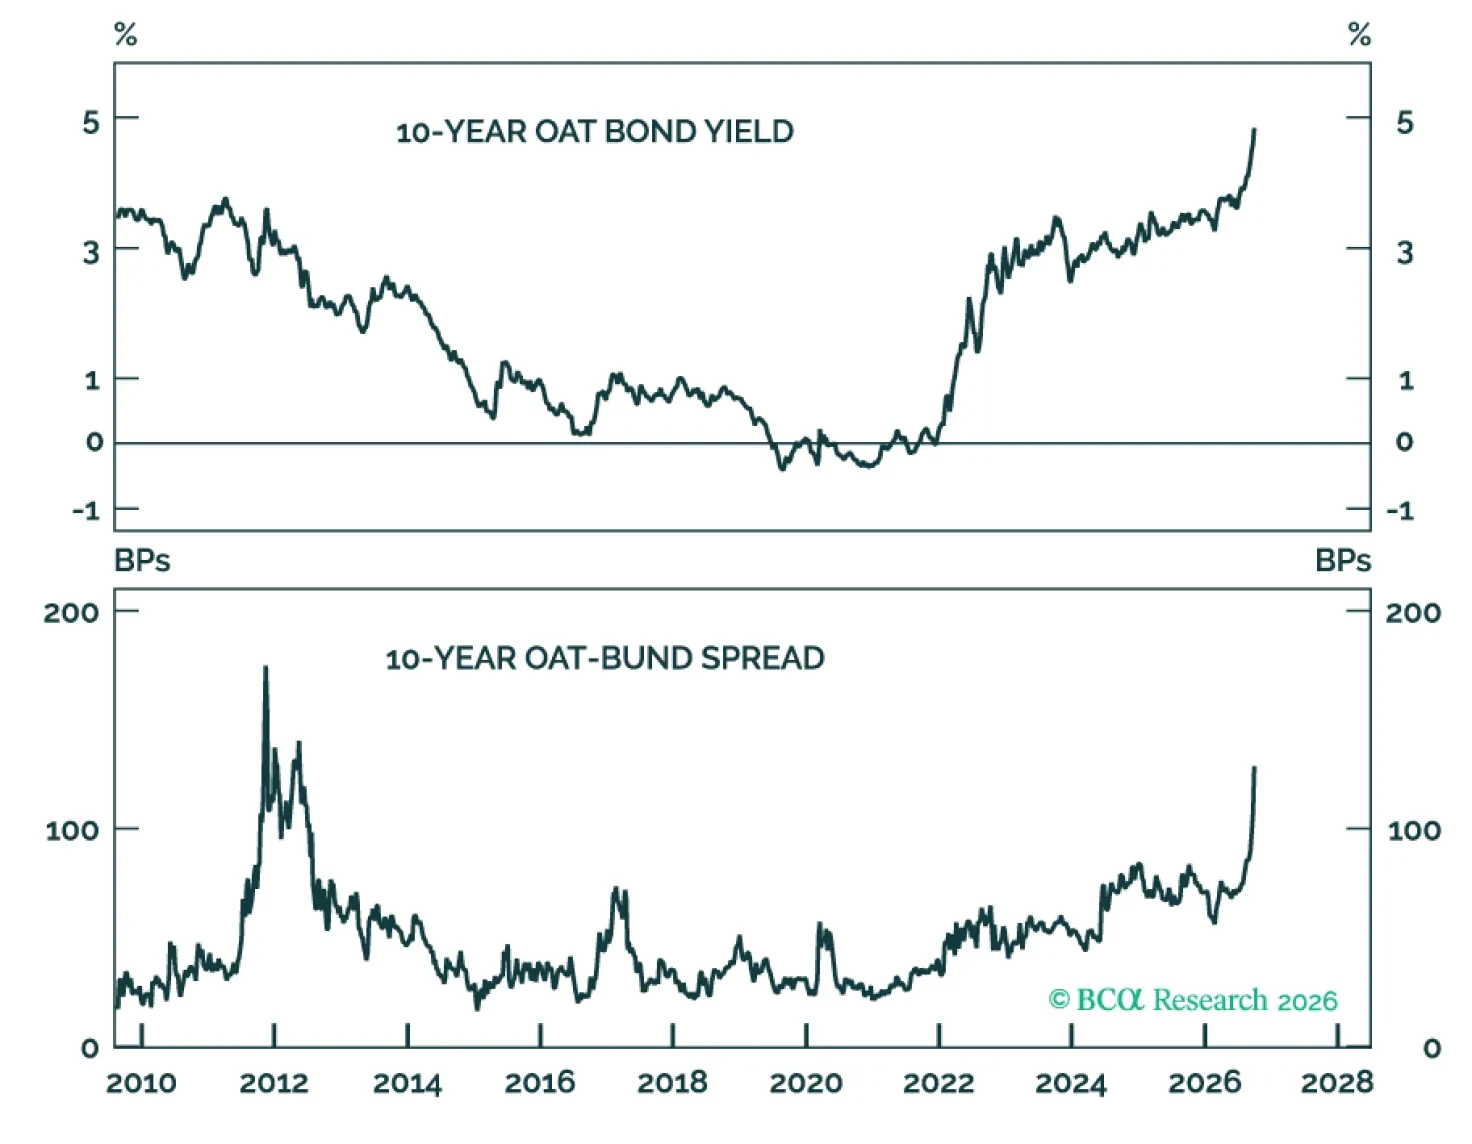
Forced selling may be approaching a pause, but France’s fiscal and political adjustment has barely begun. Maintain an underweight in OATs and use relief rallies to reduce exposure. Contained contagion is reassuring for Europe; it is not a buy signal for France.
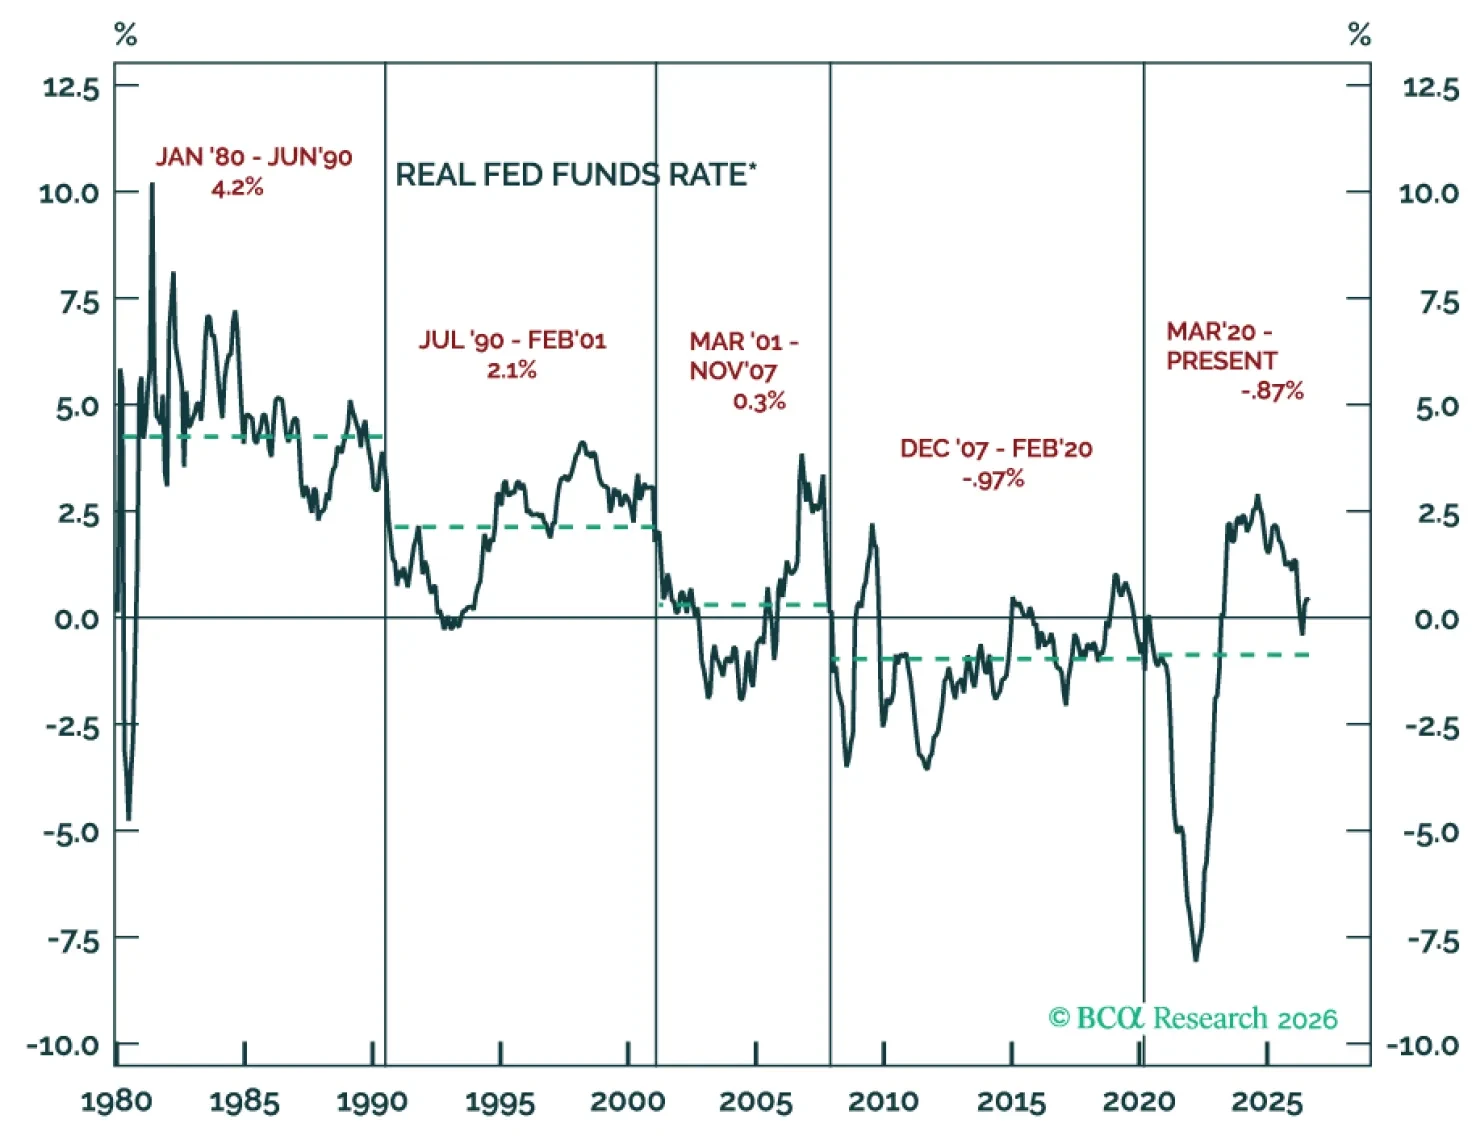
Rising rates don’t halt bull markets but real yields exceeding the economy’s potential long-run growth rate could. That relative level could lead to a stock-bond collision if it persisted long enough to slow the economy.
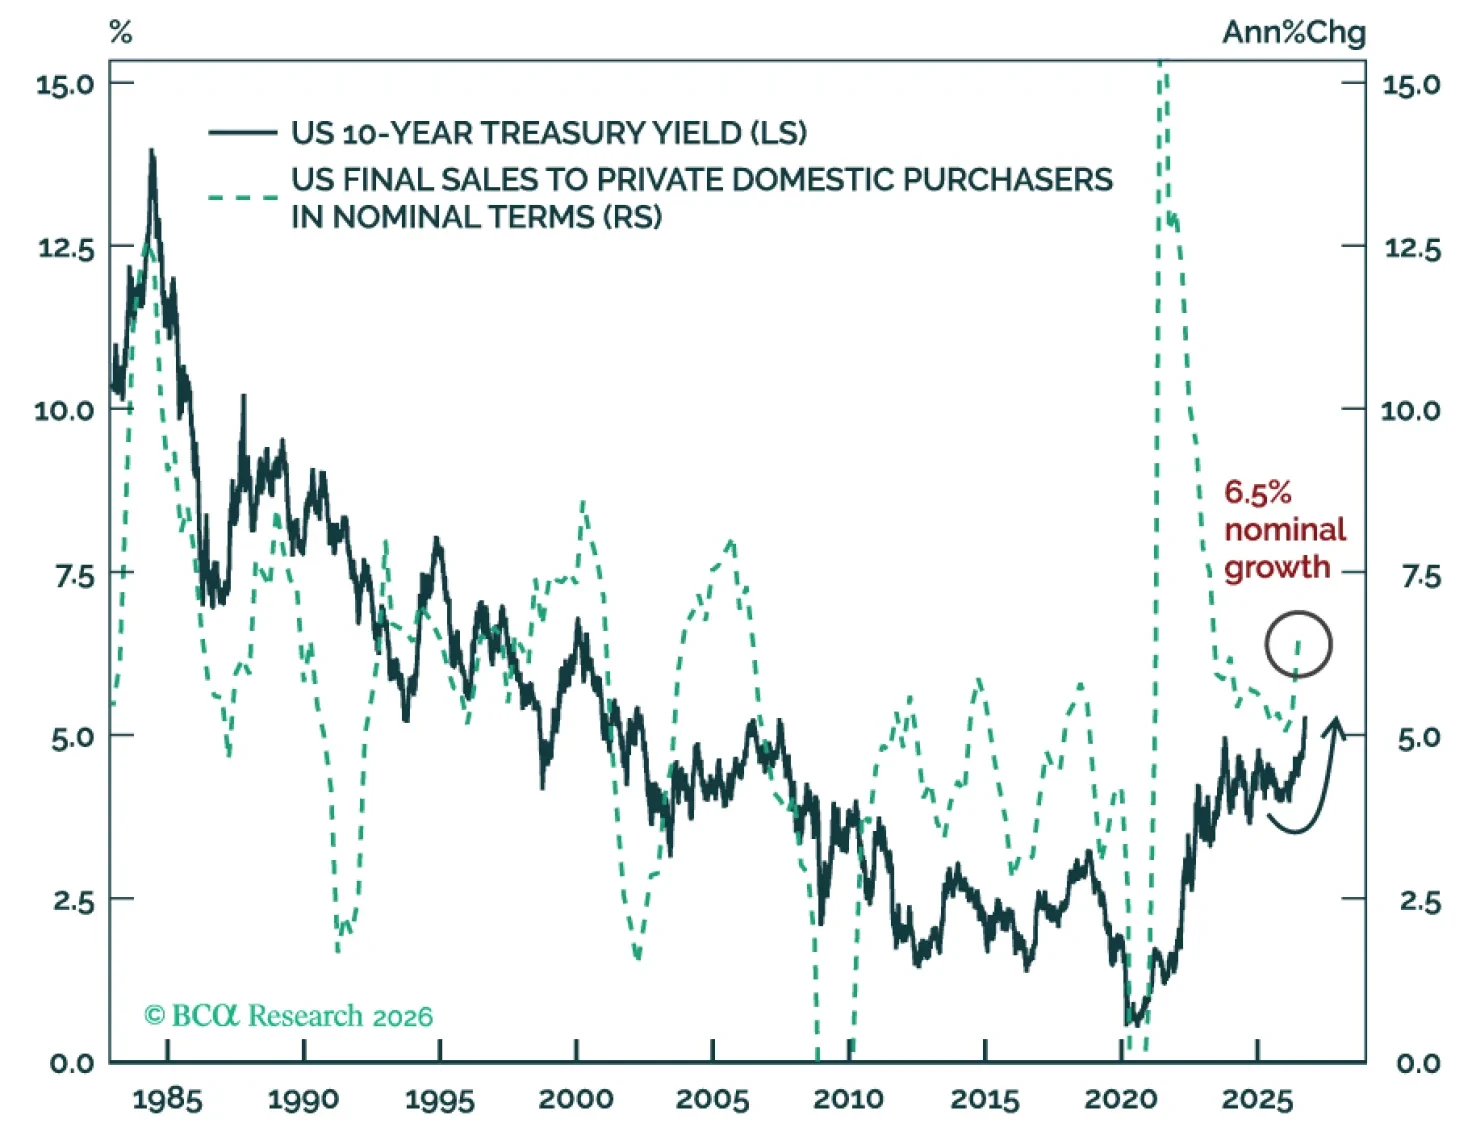
US bonds will likely continue selling off until tighter financial conditions – most plausibly a double-digit decline in the S&P 500 – cool nominal growth. Higher discount rates will threaten US equity valuations before earnings weaken. AI stocks will peak well ahead of AI capex. Remain downbeat on EM stocks.
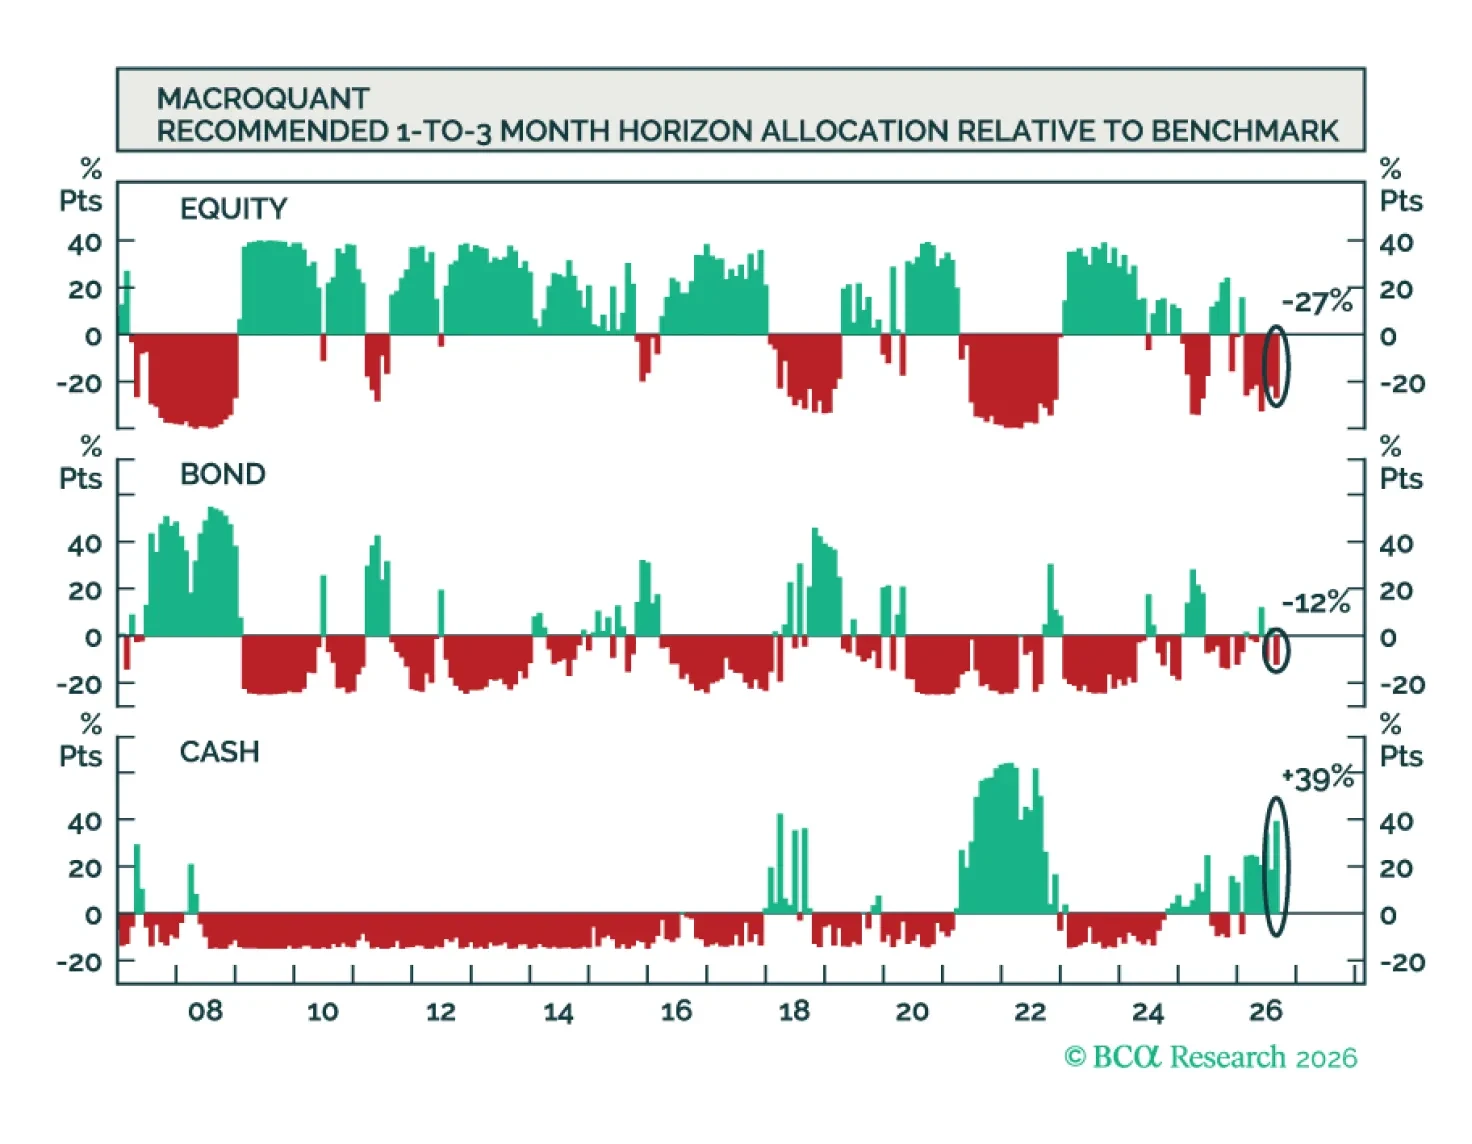
MacroQuant recommends an underweight to equities and bonds, counterbalanced by a significant overweight to cash. The model is very bullish on the US dollar, slightly negative on gold and copper, and positive on oil.
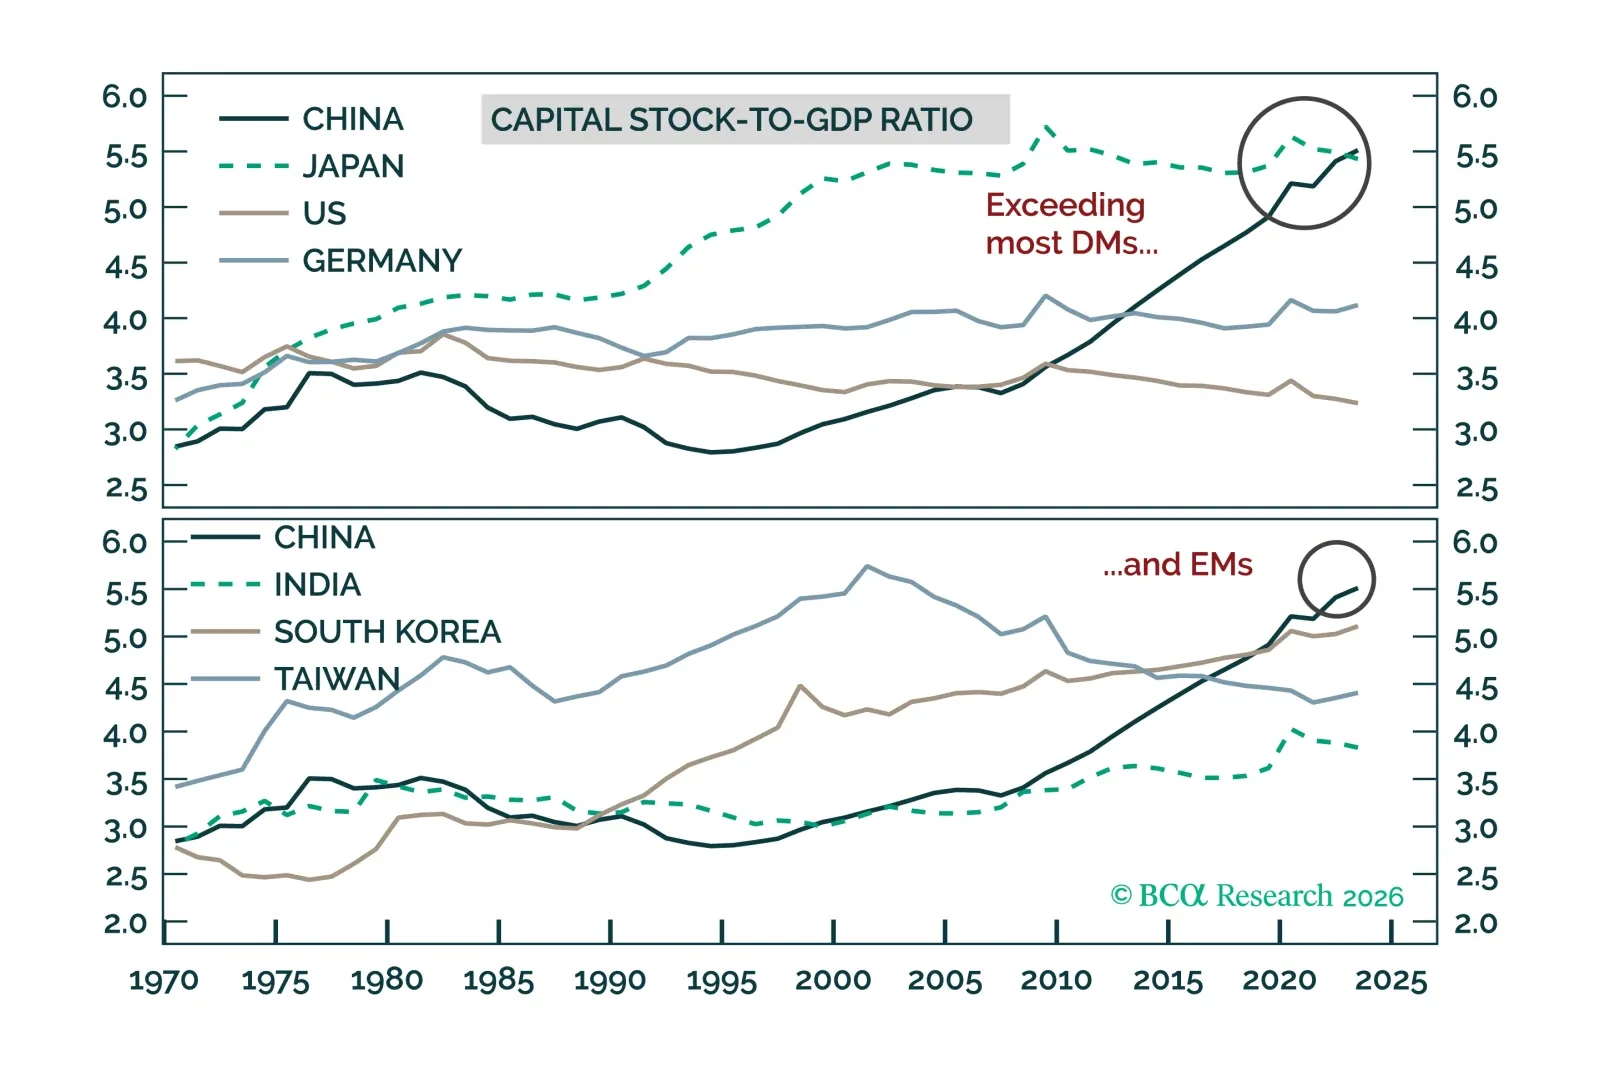
China’s investment has hit cyclical and structural limits. Mounting economic pressures will likely push Beijing toward a more aggressive, consumer-focused reflationary stance over the next one to two years.