Skip to main content

Europe

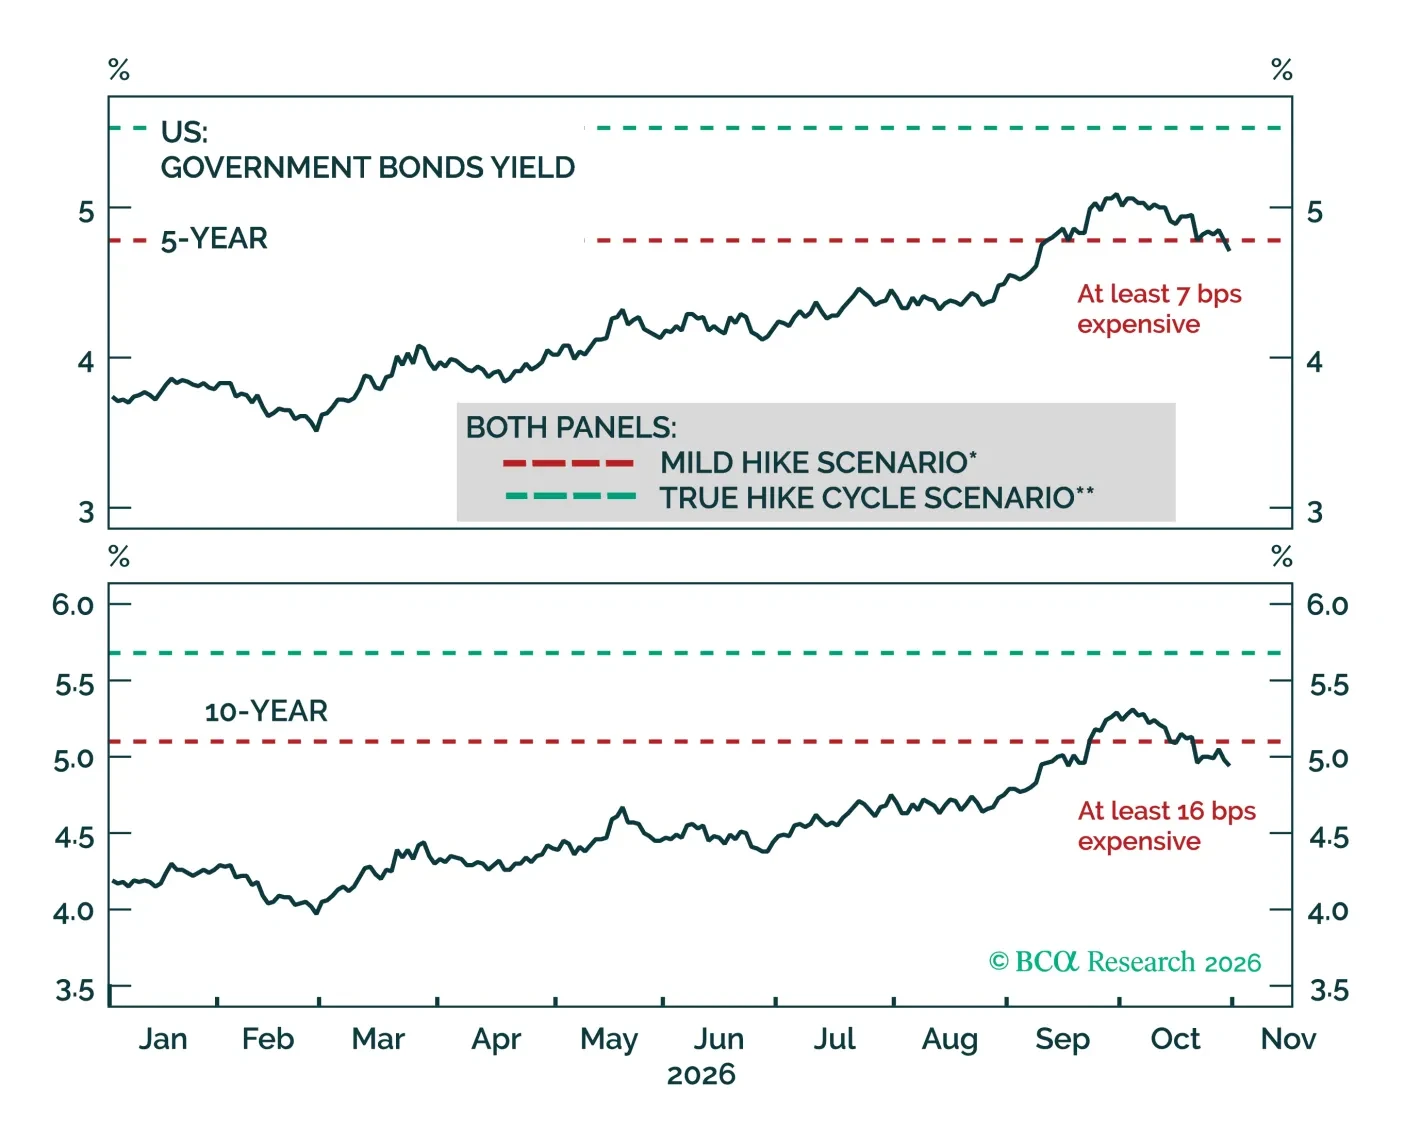
US Treasury yields have fallen below our fair value estimate as investors rotated out of AI equities and into fixed income. We lay out why near-term inflation risks argue for a rebound, and the tactical trades we initiate to position for it.
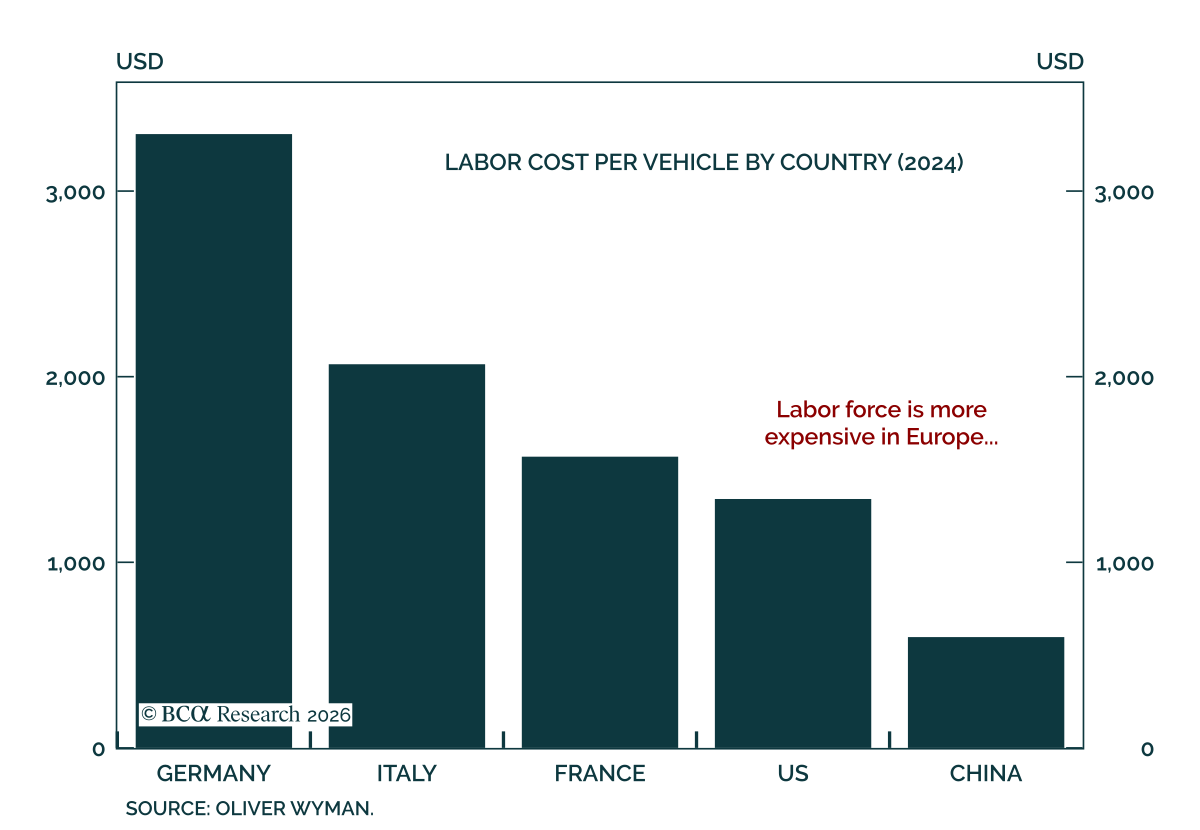
An aggressive underweight stance toward European automakers is no longer warranted. Euro area auto stocks have dropped roughly 25% this year alone. The reasons behind the structural downtrend are well-known: inefficient supply chains, higher production costs,…
BCA’s geopolitical strategists argue that investors should be structurally overweight European versus US financial assets. On the political front, investors should recognize that Euroscepticism is “dead” as a risk. The importance of European integration has…

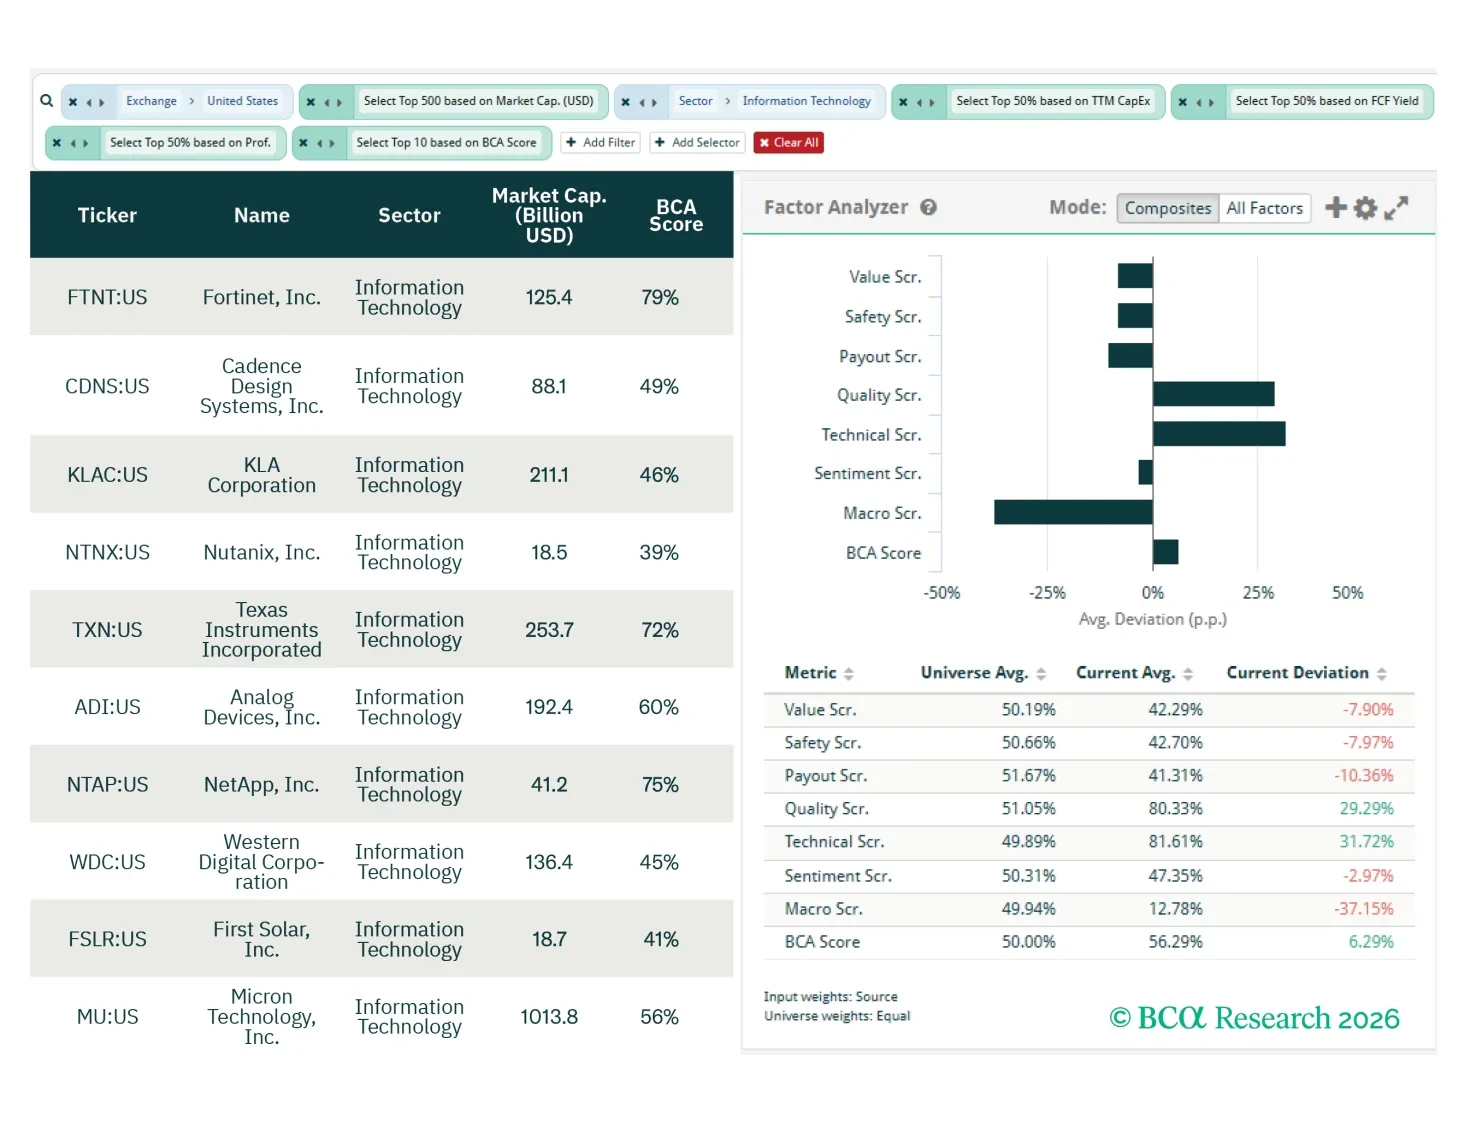
In this screener report, we explore opportunities in high-quality Tech, European integration winners, and selective US cyclicals in Industrials and Materials.
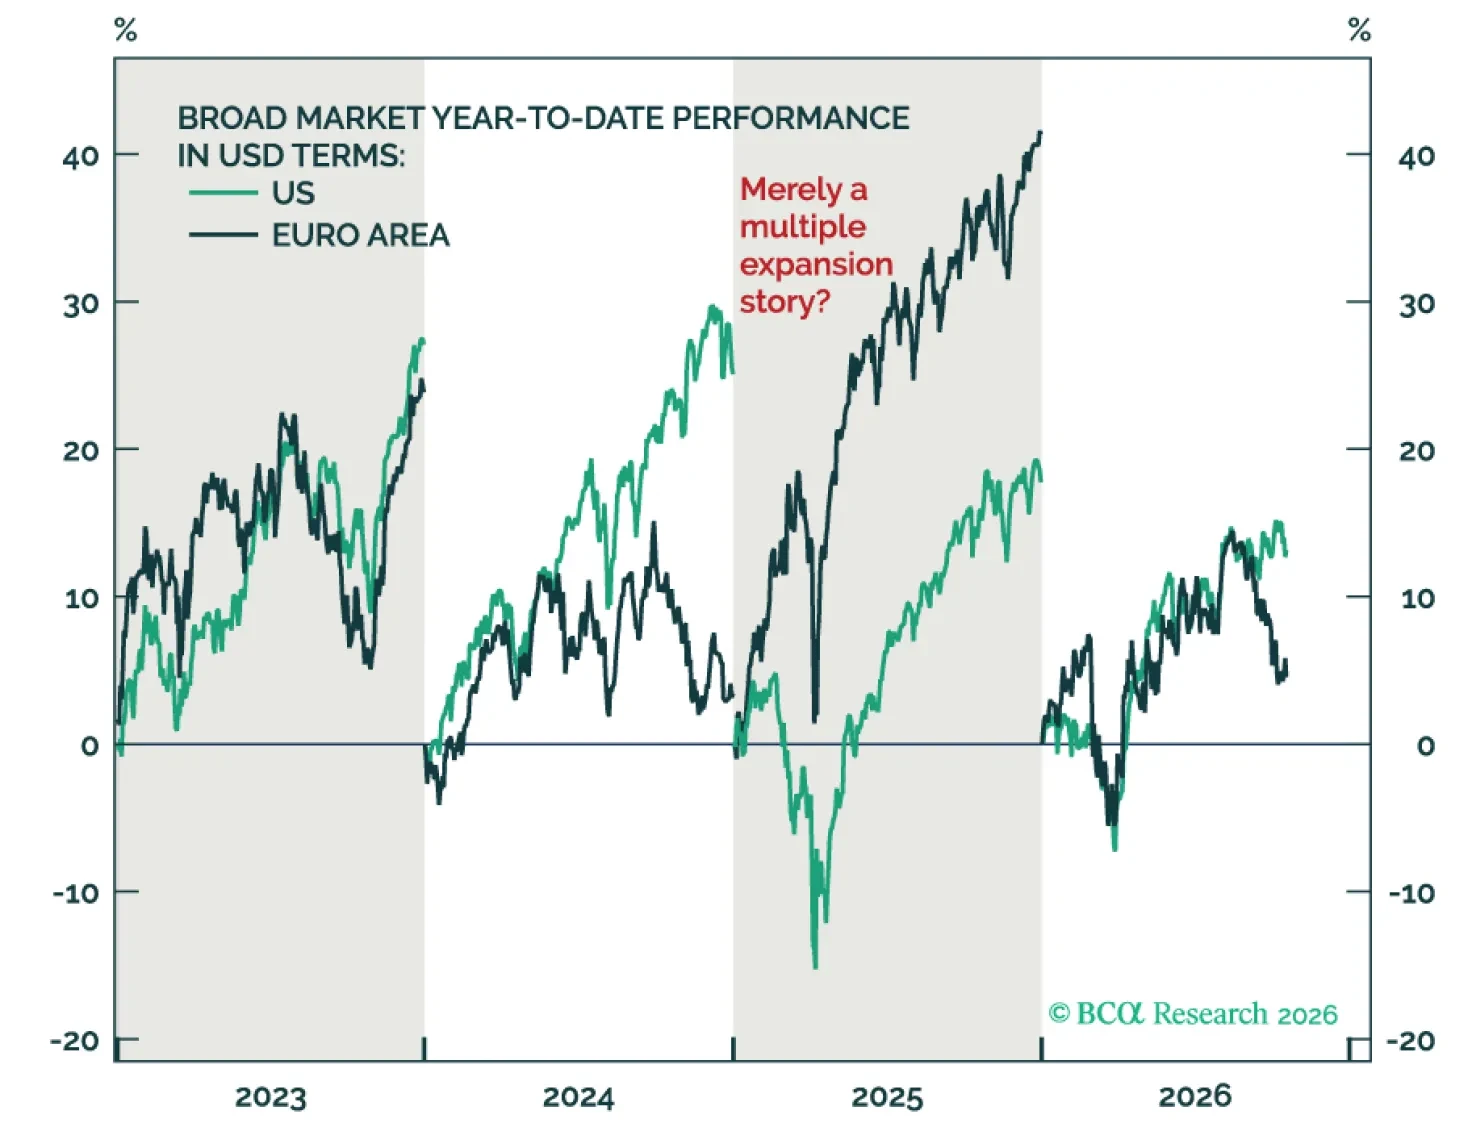
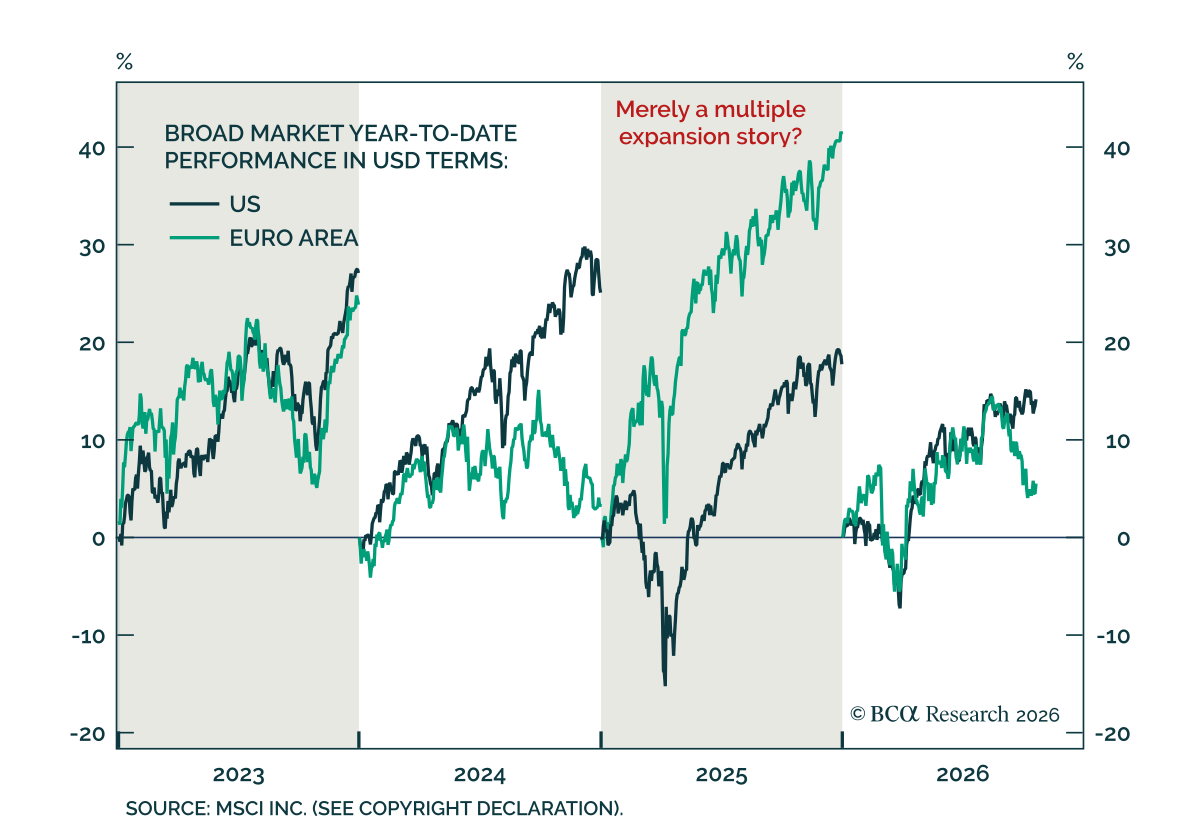
Europe has 99 problems, but the paucity of bearish views about the Old Continent is not one of them! And yet, somewhat shockingly, European assets have outperformed US assets over the past two years. Sure, markets make mistakes. But the macro graveyards are littered with investors who thought they were smarter than the markets. In this report, we suggest that Europe is on a cusp of significant structural reforms that will unlock value in its services sector. And that while many of the challenges are real, they’re either well understood or priced in. 
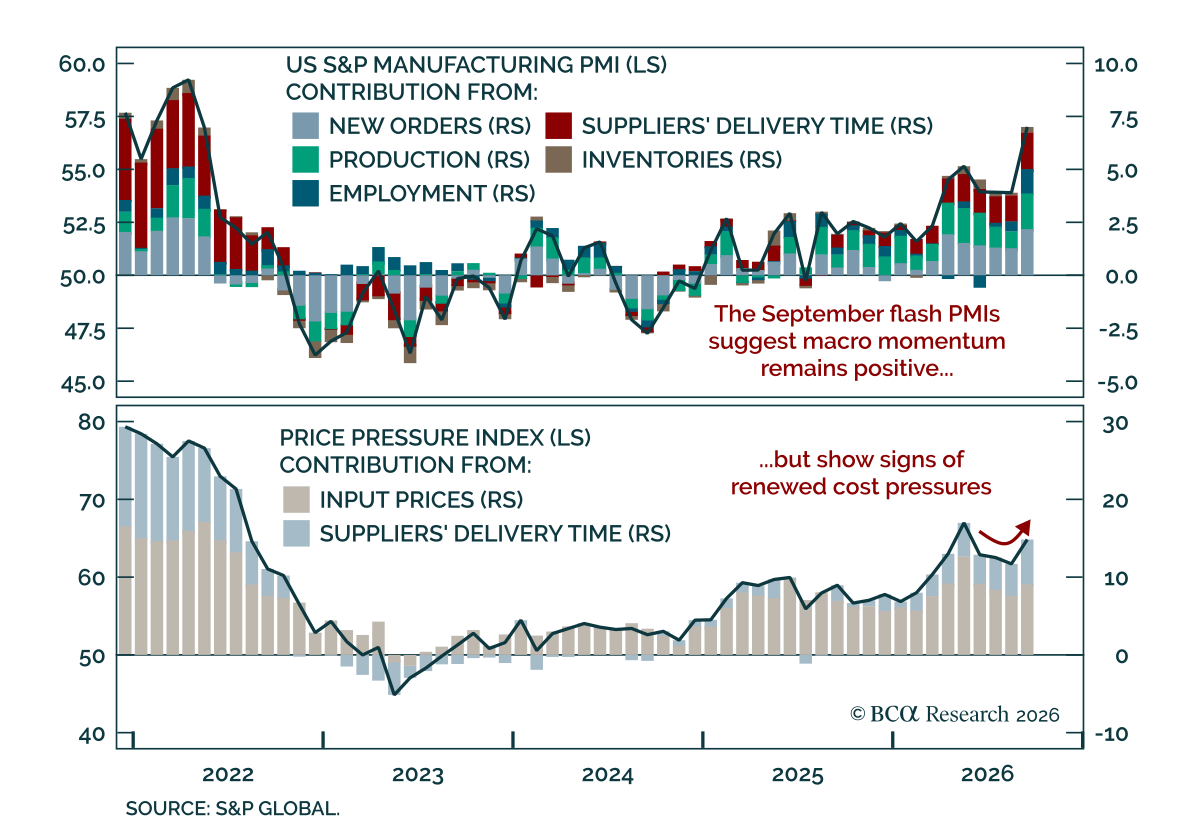
September's flash PMIs show the US economy remains resilient to persistently high energy prices and higher rates. The composite index rose to 58.4 from 56, its highest level since 2021. Manufacturing and services both came in well above consensus.…
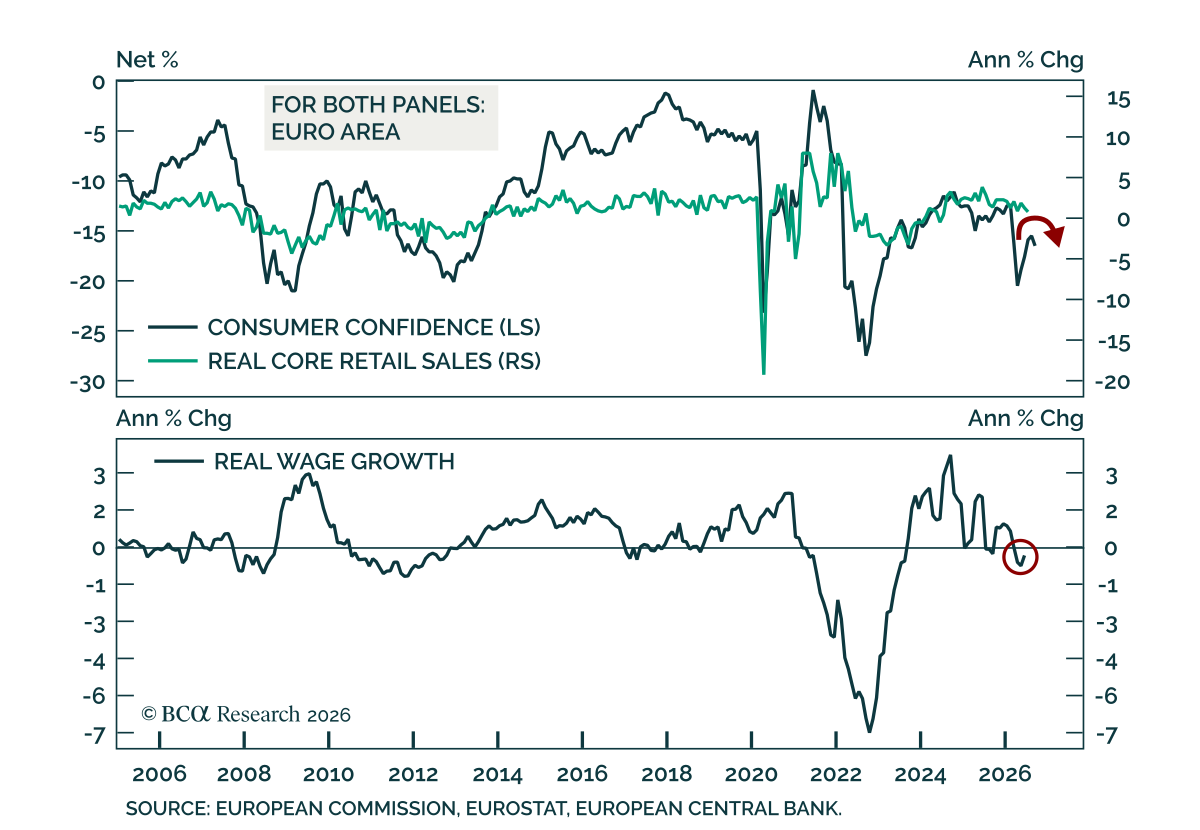
Falling Euro Area consumer confidence and greater energy exposure favor US over European equities near-term. Euro Area consumer confidence fell in September, ending a four-month upswing. The European Commission's flash index dropped 1 percentage point (p.p.)…
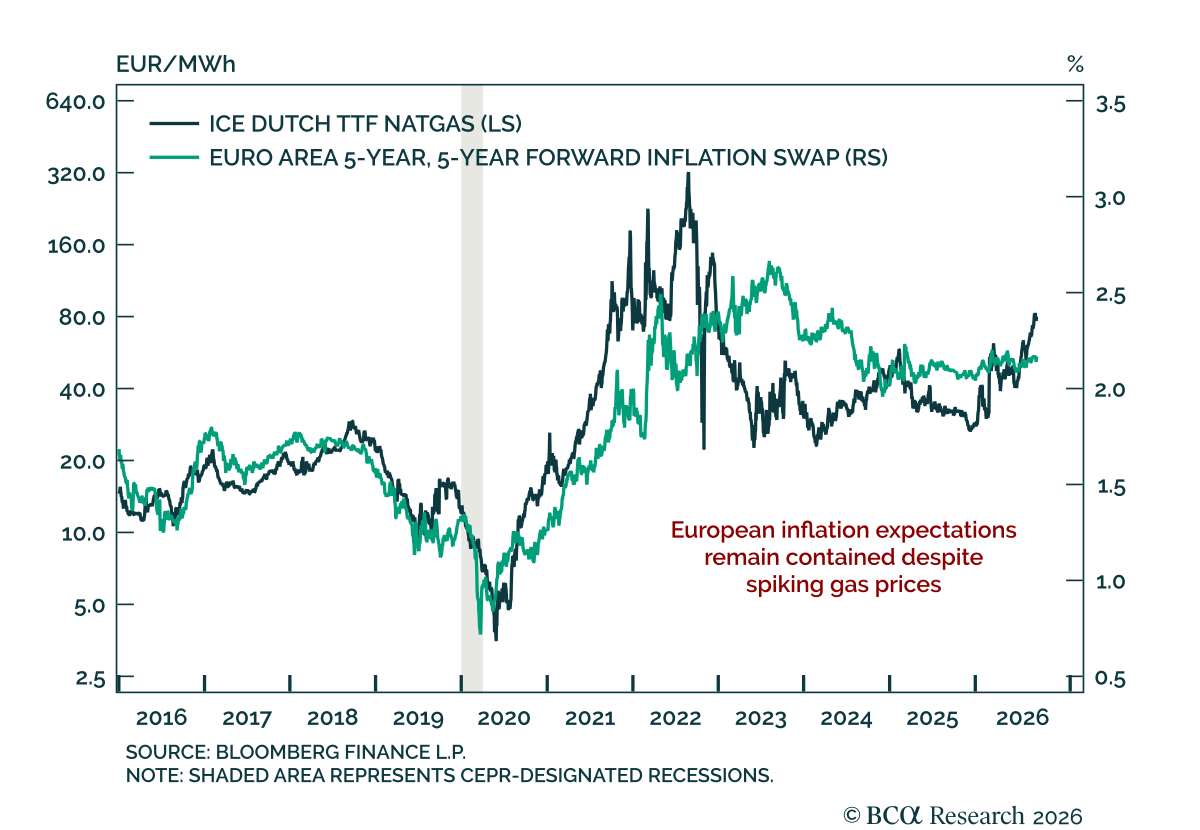
European natural gas prices have surged above recent highs, but the absence of a corresponding rise in longer-term inflation expectations argues against the ECB hiking deeply into restrictive territory. ICE Dutch TTF prices, the European benchmark, have moved…
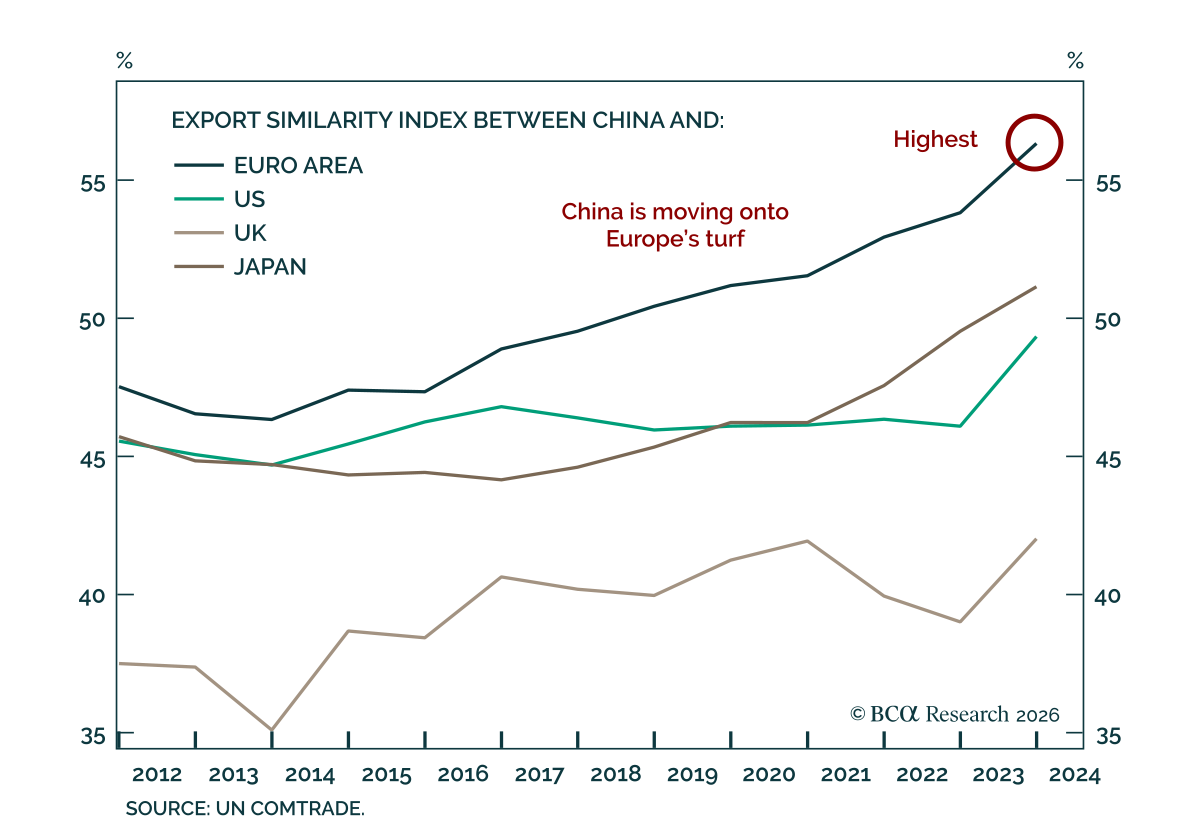
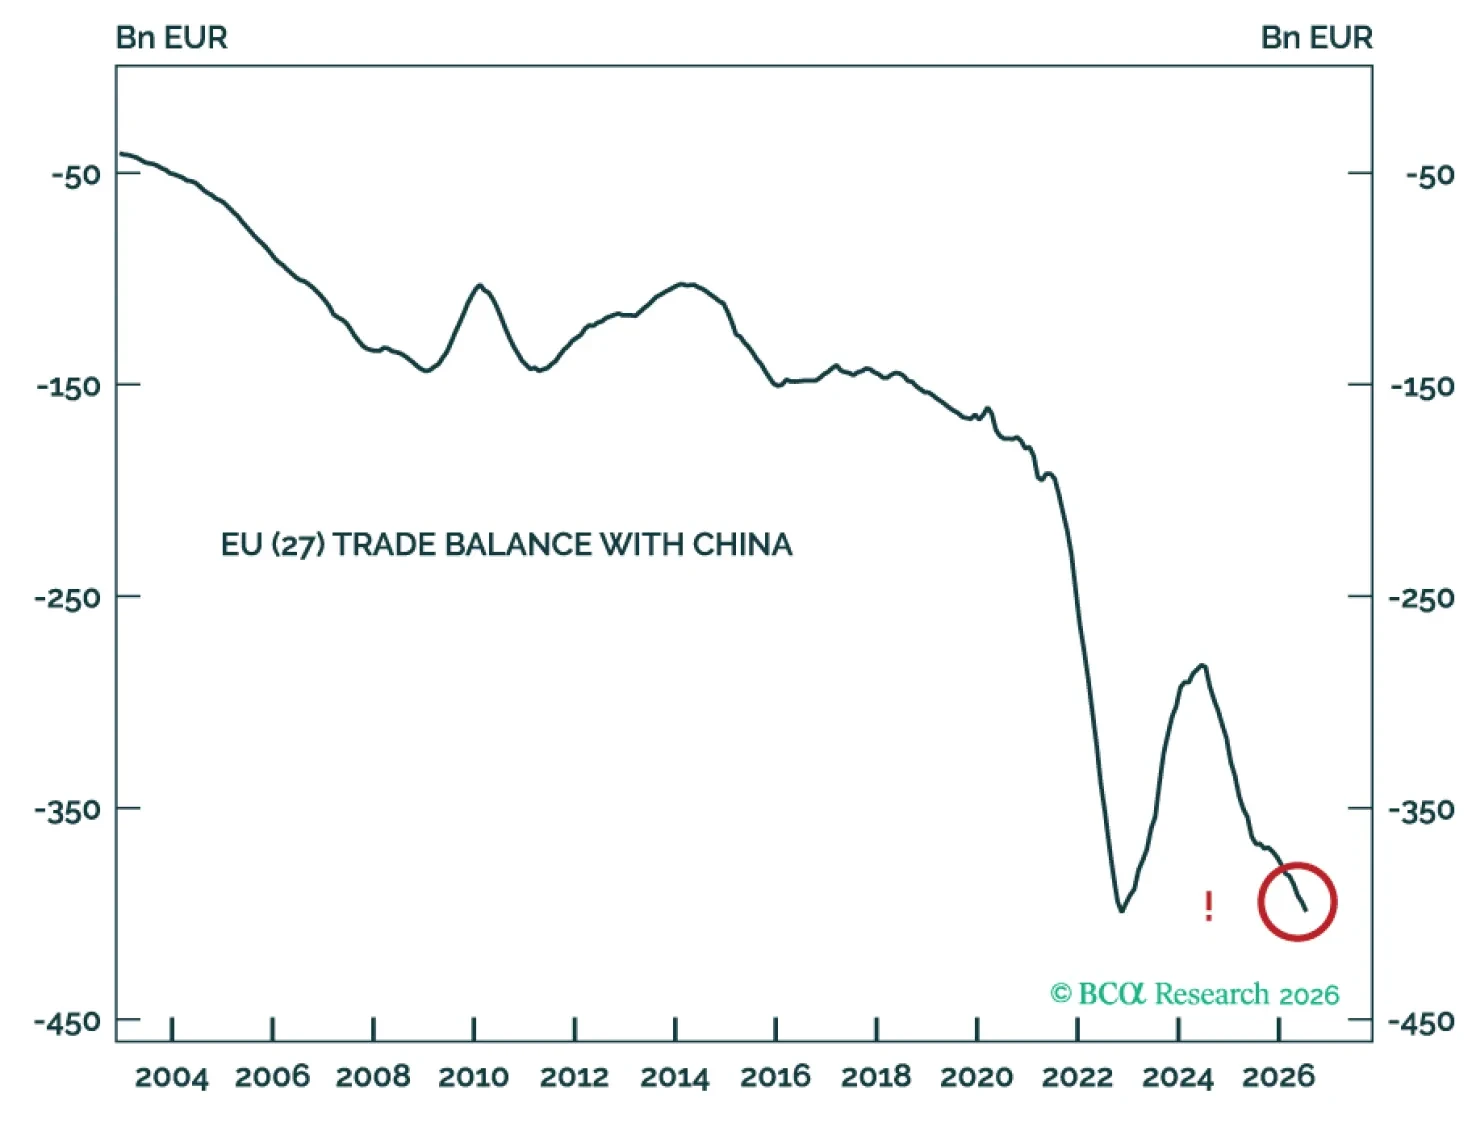
China’s rise up the industrial value chain is creating a structural challenge for Europe. Our Chart Of The Week comes from Jeremie Peloso, Chief European Strategist. China shock 1.0 largely benefited Europe. China supplied cheap labor and low value added…
Special Report

China shock 2.0 threatens Europe’s industrial core, but it is also forcing a long-overdue response. China stands to lose more than the EU from the coming confrontation. Beijing cannot afford to alienate Europe while its domestic demand remains weak. Europe, meanwhile, can turn protectionism into a stronger fiscal multiplier and an industrial revival.