Economy
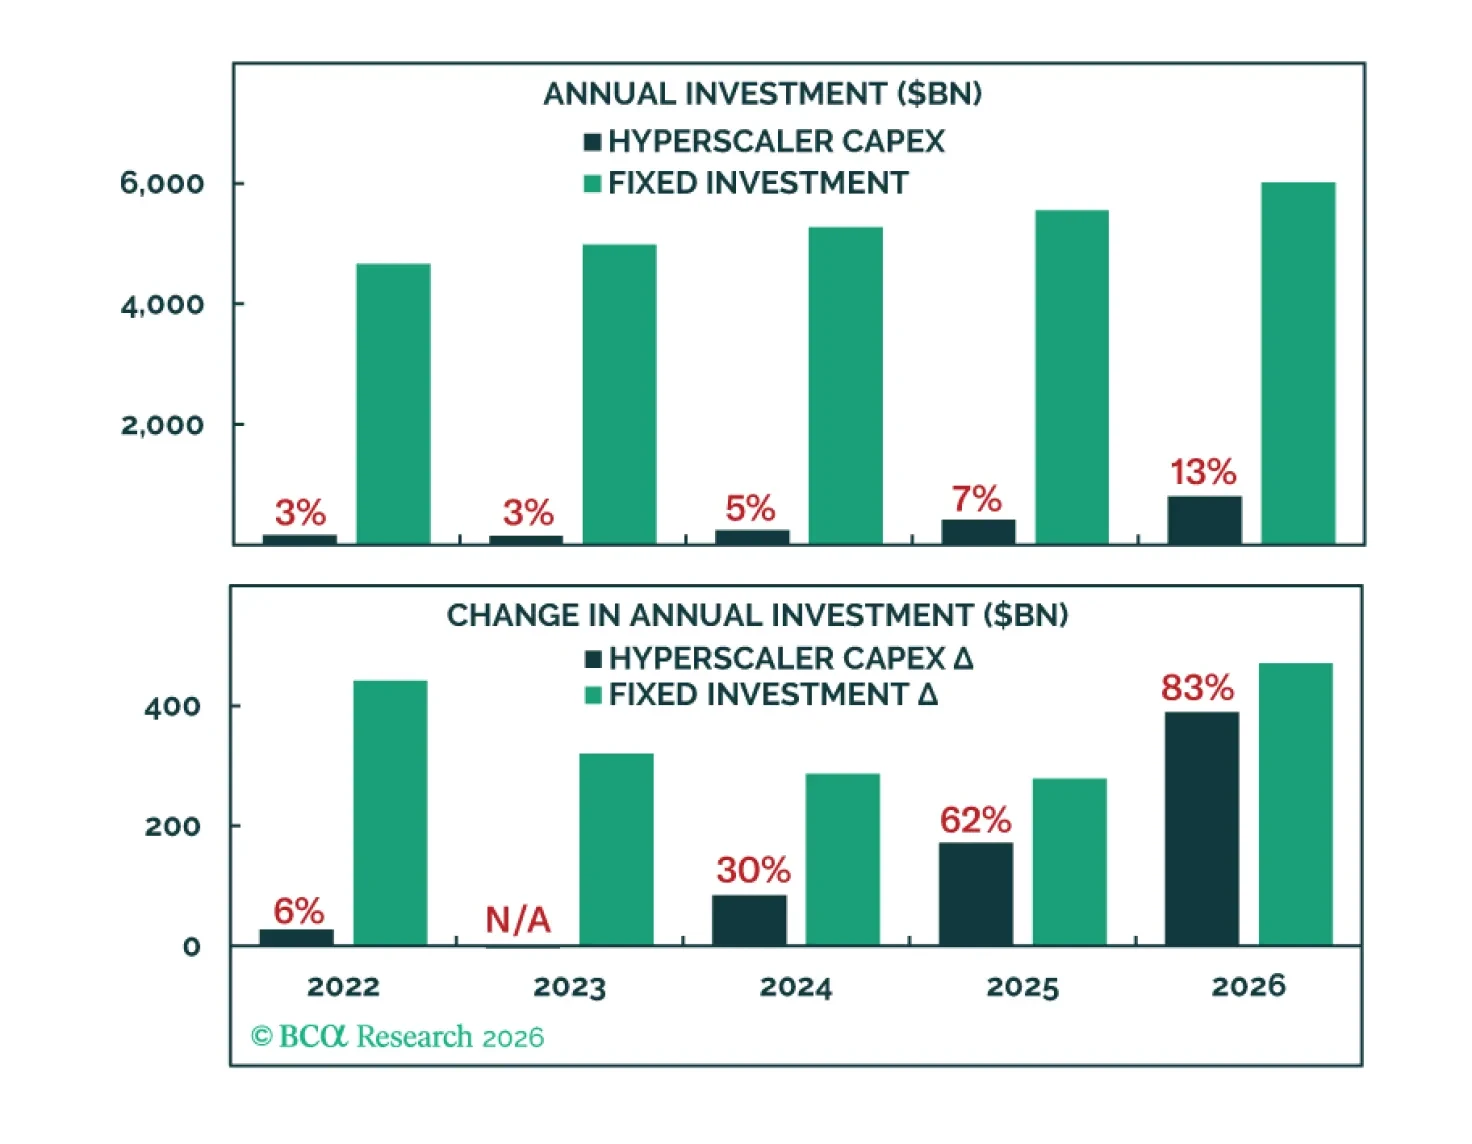
Data centers have swallowed aggregate US investment to such an extent that even a modest hyperscaler capex pullback could sink the expansion and bull market.
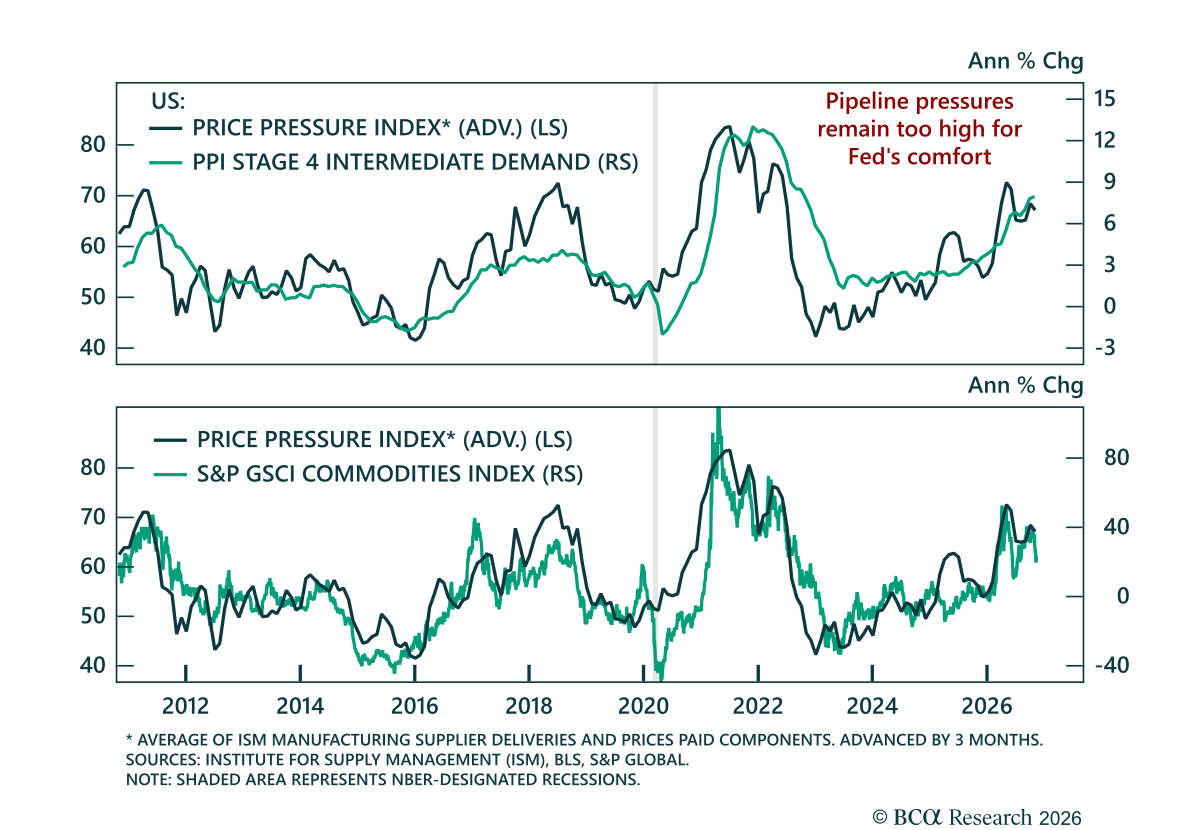
The October PPI tempers bets on a 50bps move in December, but its details give the Fed little comfort that the inflation trend has changed. Headline PPI rose 0.3% m/m (6.5% y/y), marginally below consensus, slowing from 1.4% in September as energy prices…
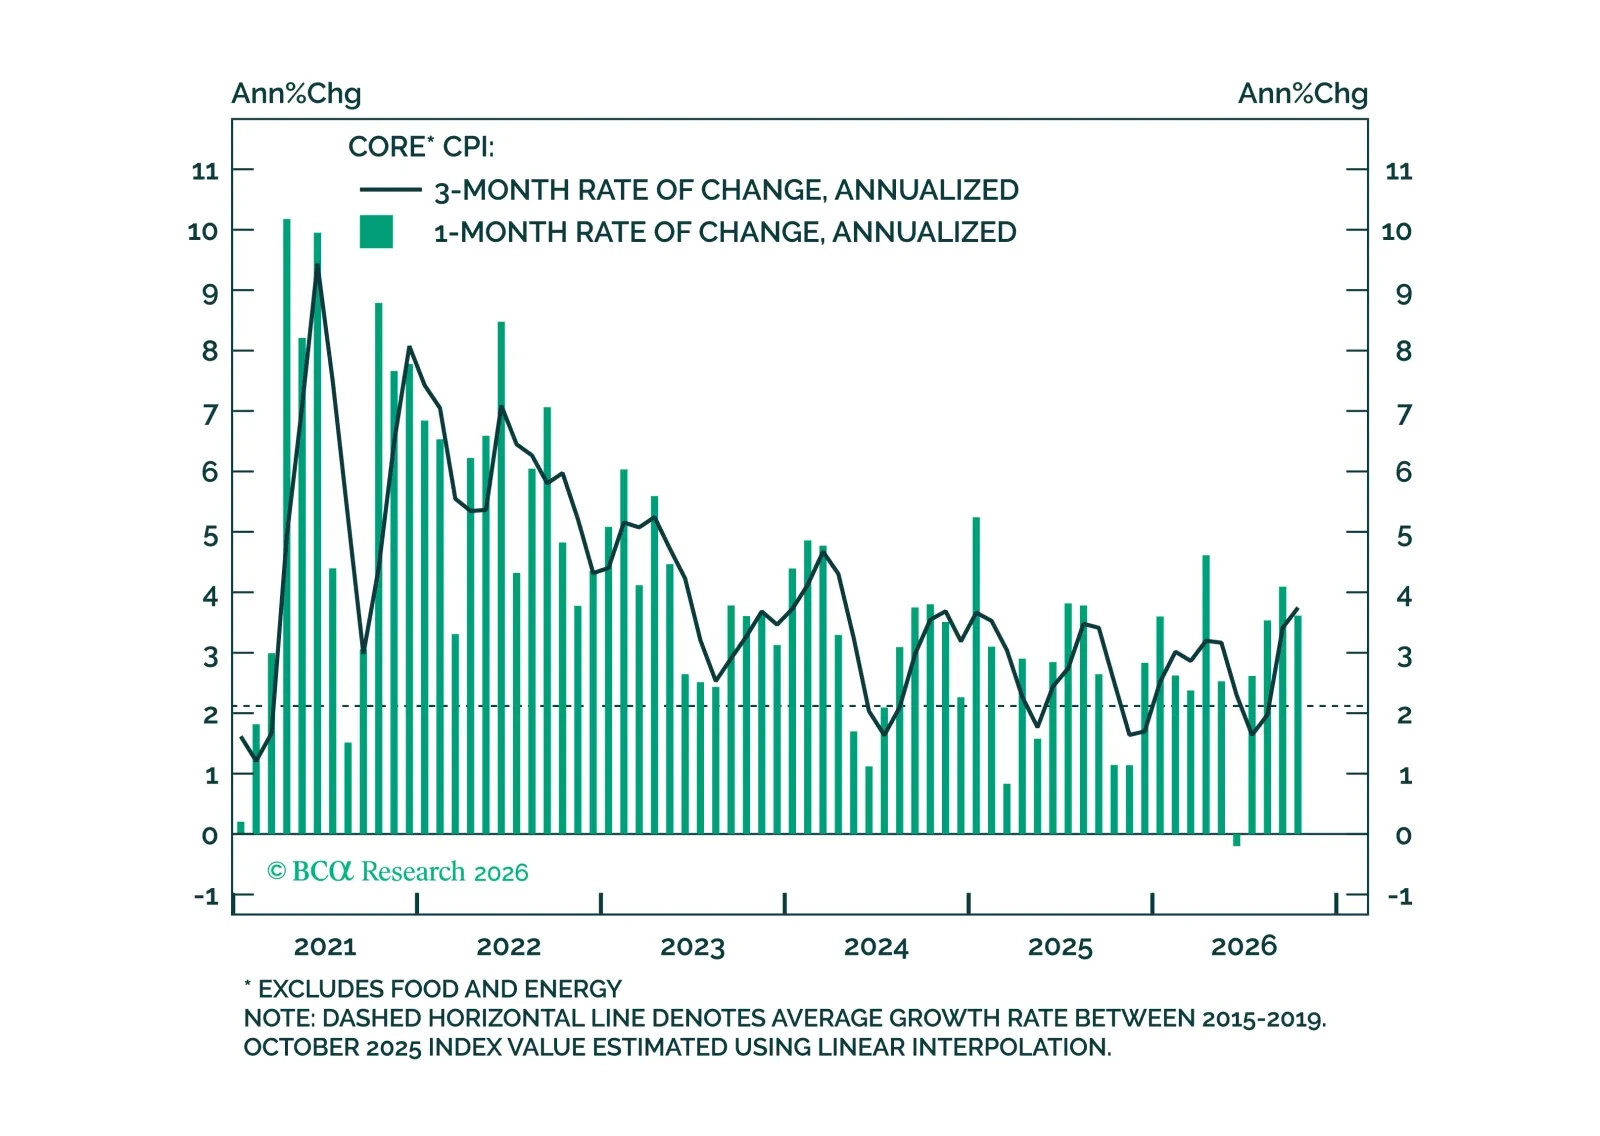
The US economy is not overheating, but shocks related to tariffs, energy and computer chips are keeping core inflation above target. These shocks will eventually fade, but likely not in the next few months.
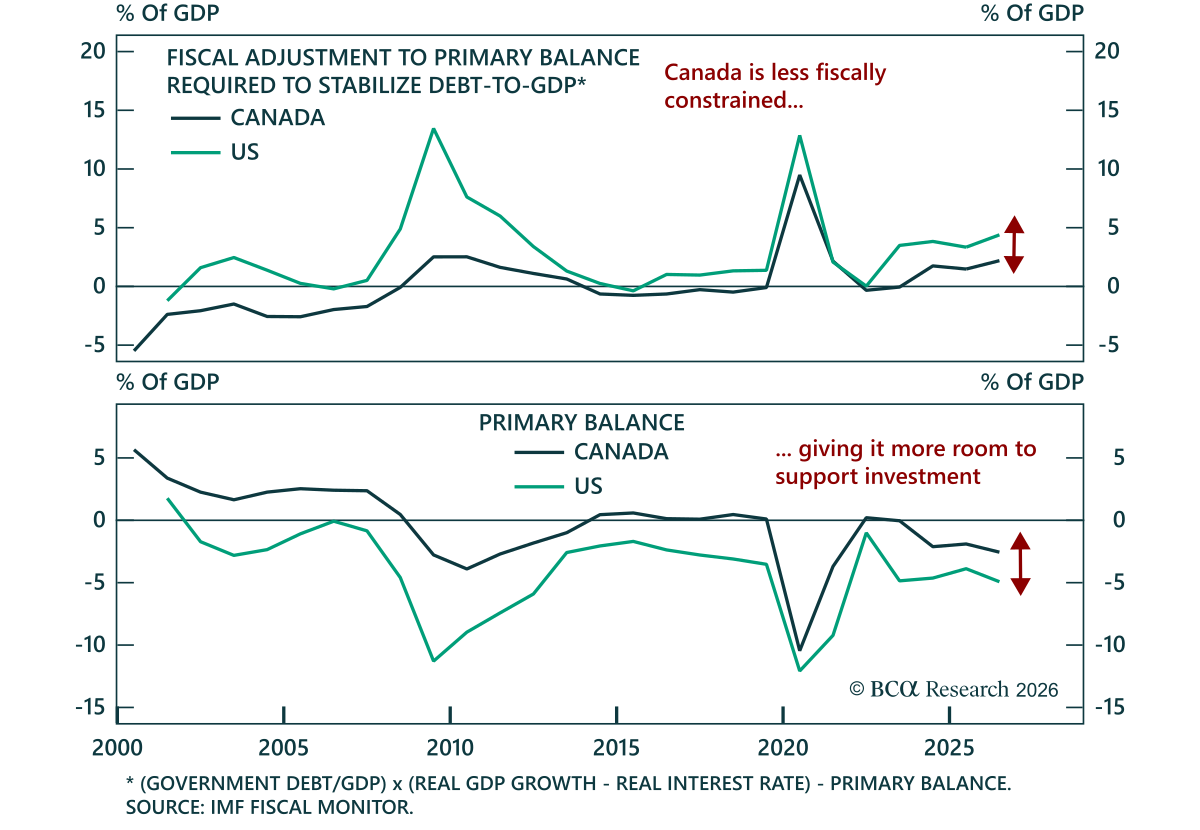
Canada’s budget reinforces the case for an investment-led recovery despite near-term housing weakness. The deficit is projected at 1.8% of GDP both this year and next, but Canada remains less fiscally constrained than the US. Its general-government net debt…
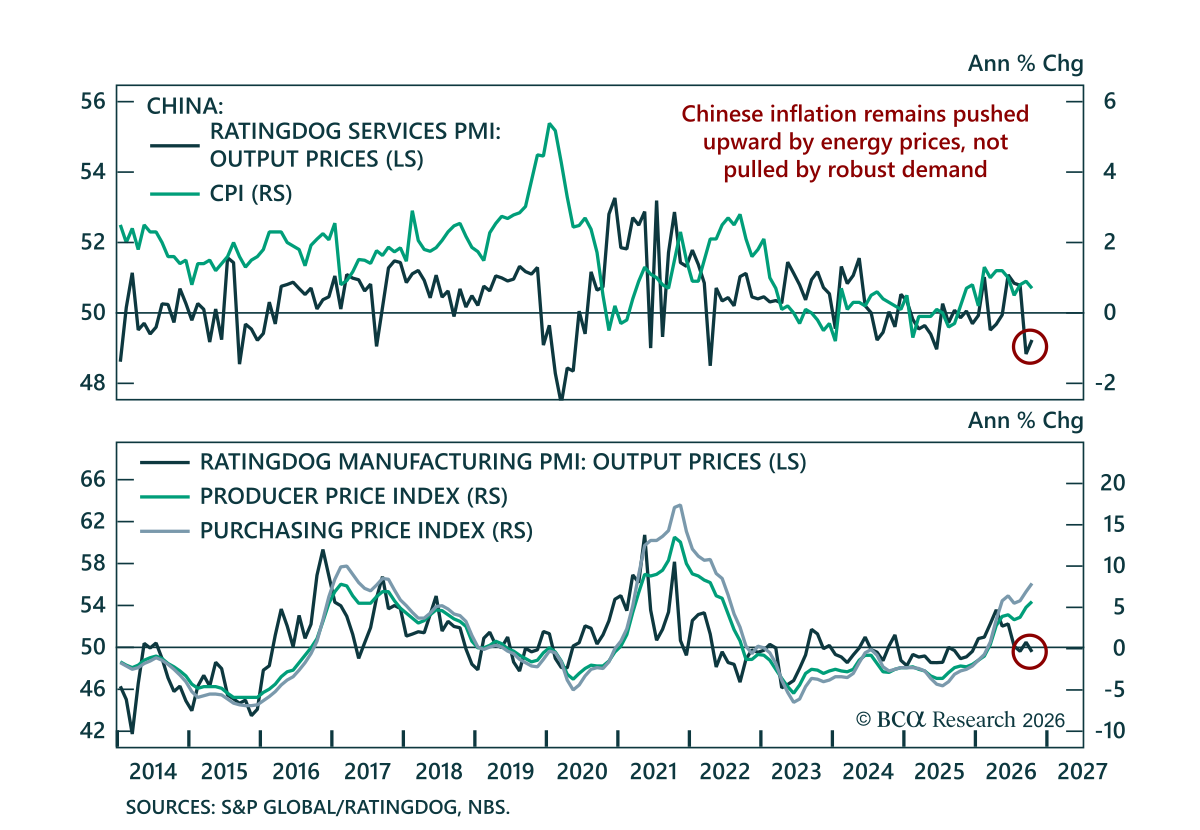
October inflation data complicate the outlook for Chinese corporate margins while continuing to buffer export competitiveness. Headline CPI slowed to 0.7% y/y from 0.9% in September, with deflation in food prices outweighing higher energy costs, while core…
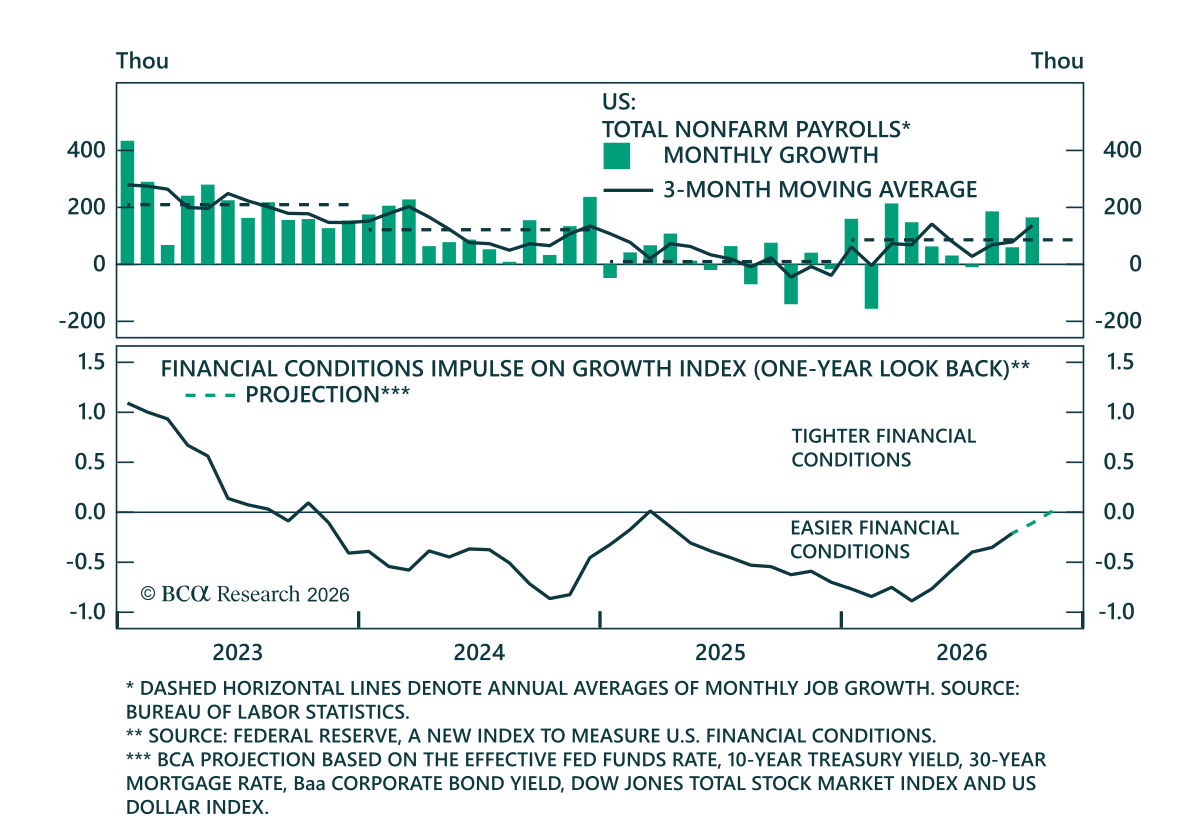
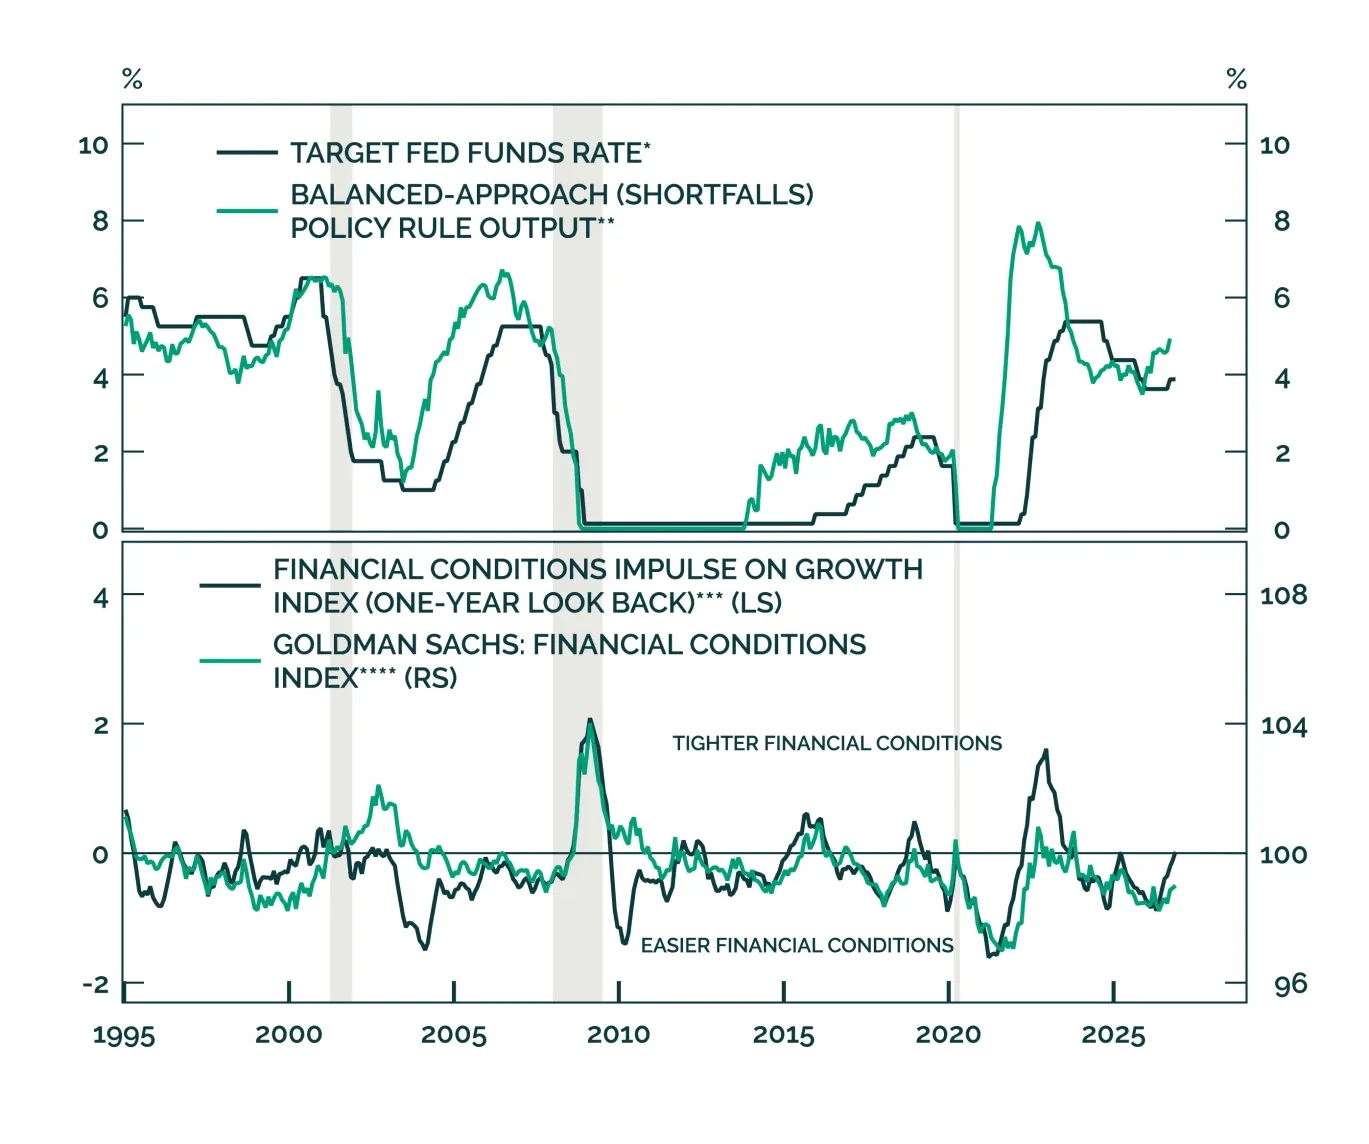
October’s strong labor market report reinforces a December rate hike as the most likely outcome, even as the Fed weighs growth against tighter financial conditions. Nonfarm payrolls rose 165k, well above the consensus estimate of 59k. The unemployment rate…
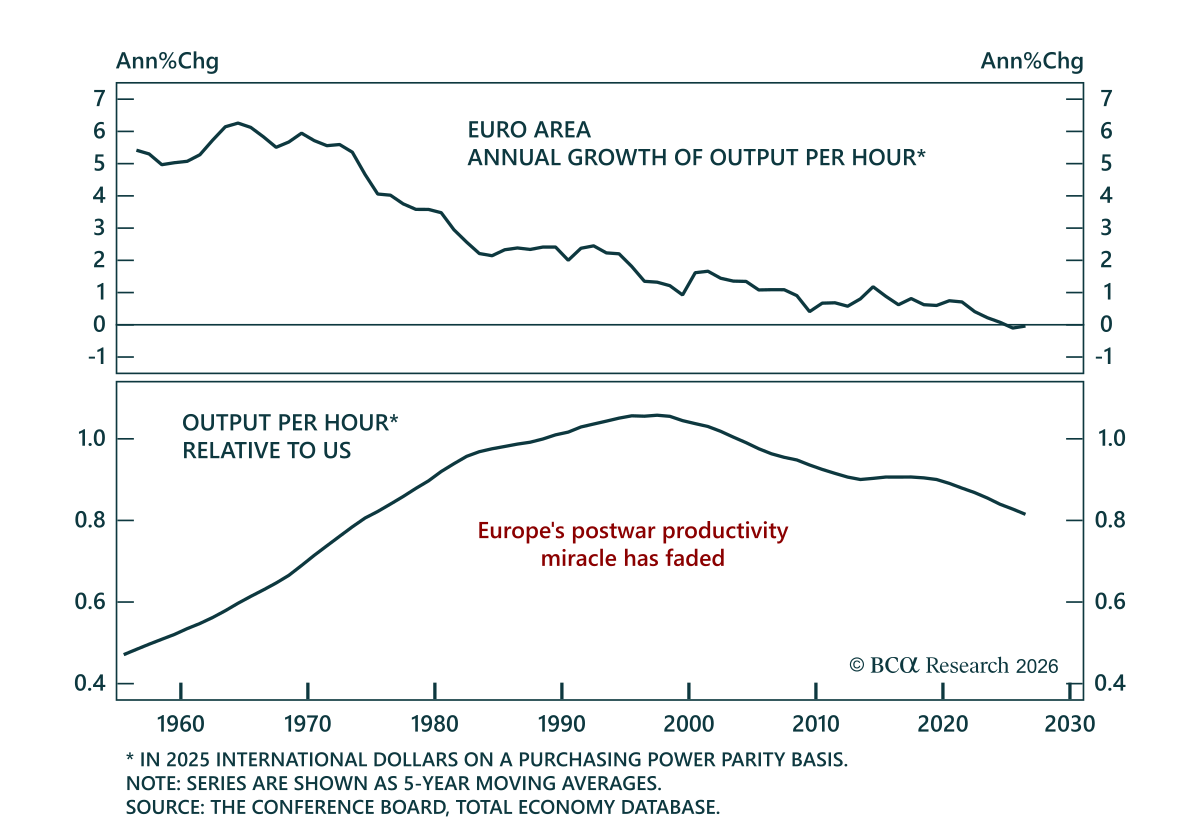
Peter Berezin, our Chief Economist, recommends selling European assets on any rallies. Peter argues repairing Europe’s deep structural problems may require dismantling much of the welfare state, which is unlikely to happen before a major crisis. Lower oil…
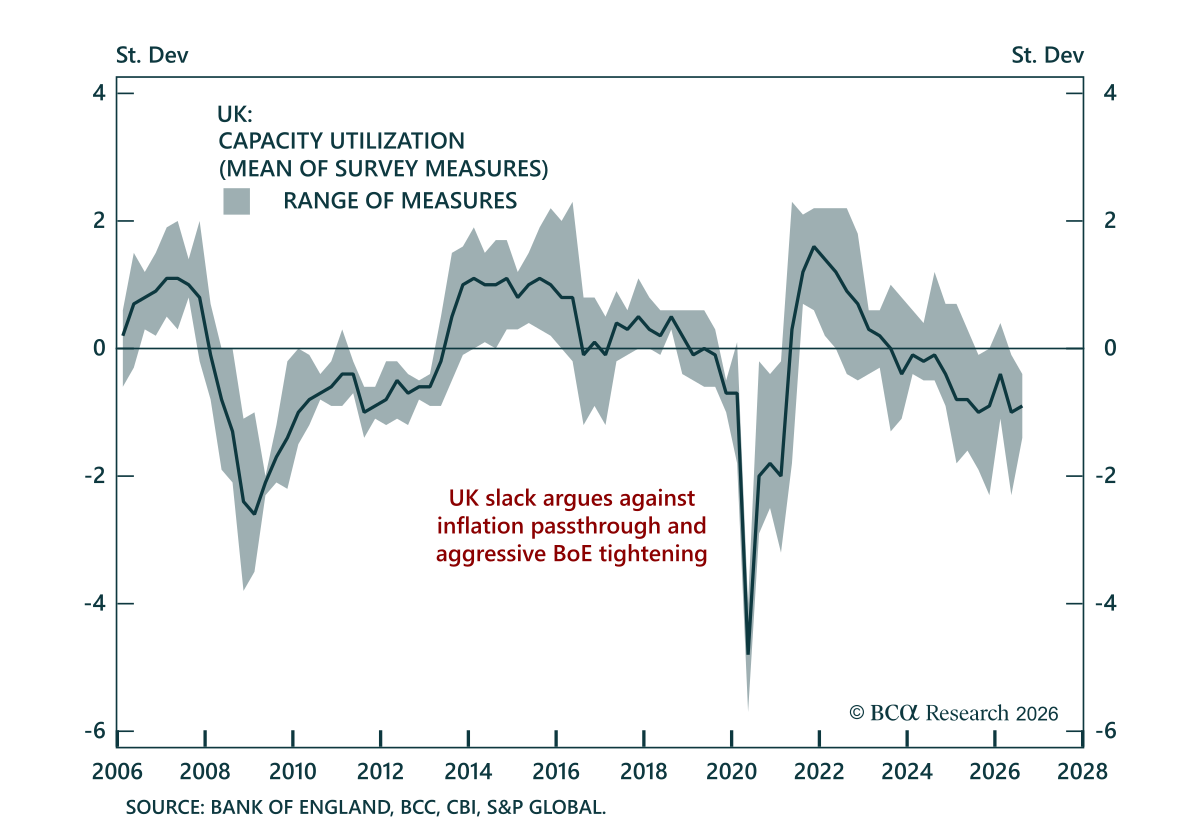
The Bank of England’s 25bps hike to 4% adds to hawkish near terms pricing but creates room for downside surprises in rates later next year. The move was expected, but the unanimous vote to increase rates, with one member favoring a 50bps hike, contrasted with…
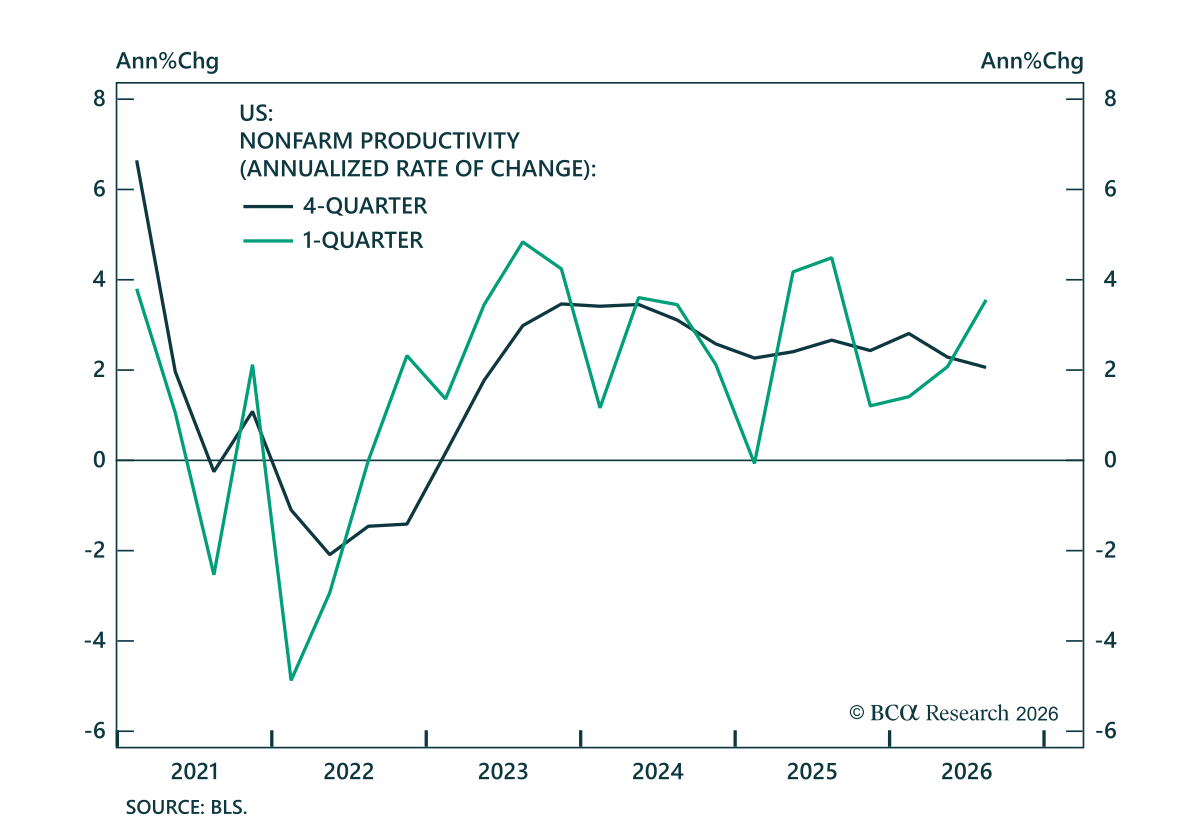
Strong Q3 US productivity reflects the demand-side impact of the AI capex boom, not supply-side gains from ex-tech AI adoption. Preliminary Q3 US nonfarm productivity came in surprisingly strong, growing at a 3.6% annualized q/q rate versus expectations of…