 FICC
| Bonds
Bond market analysis on where to position across government bonds, credit, and inflation-linked debt.
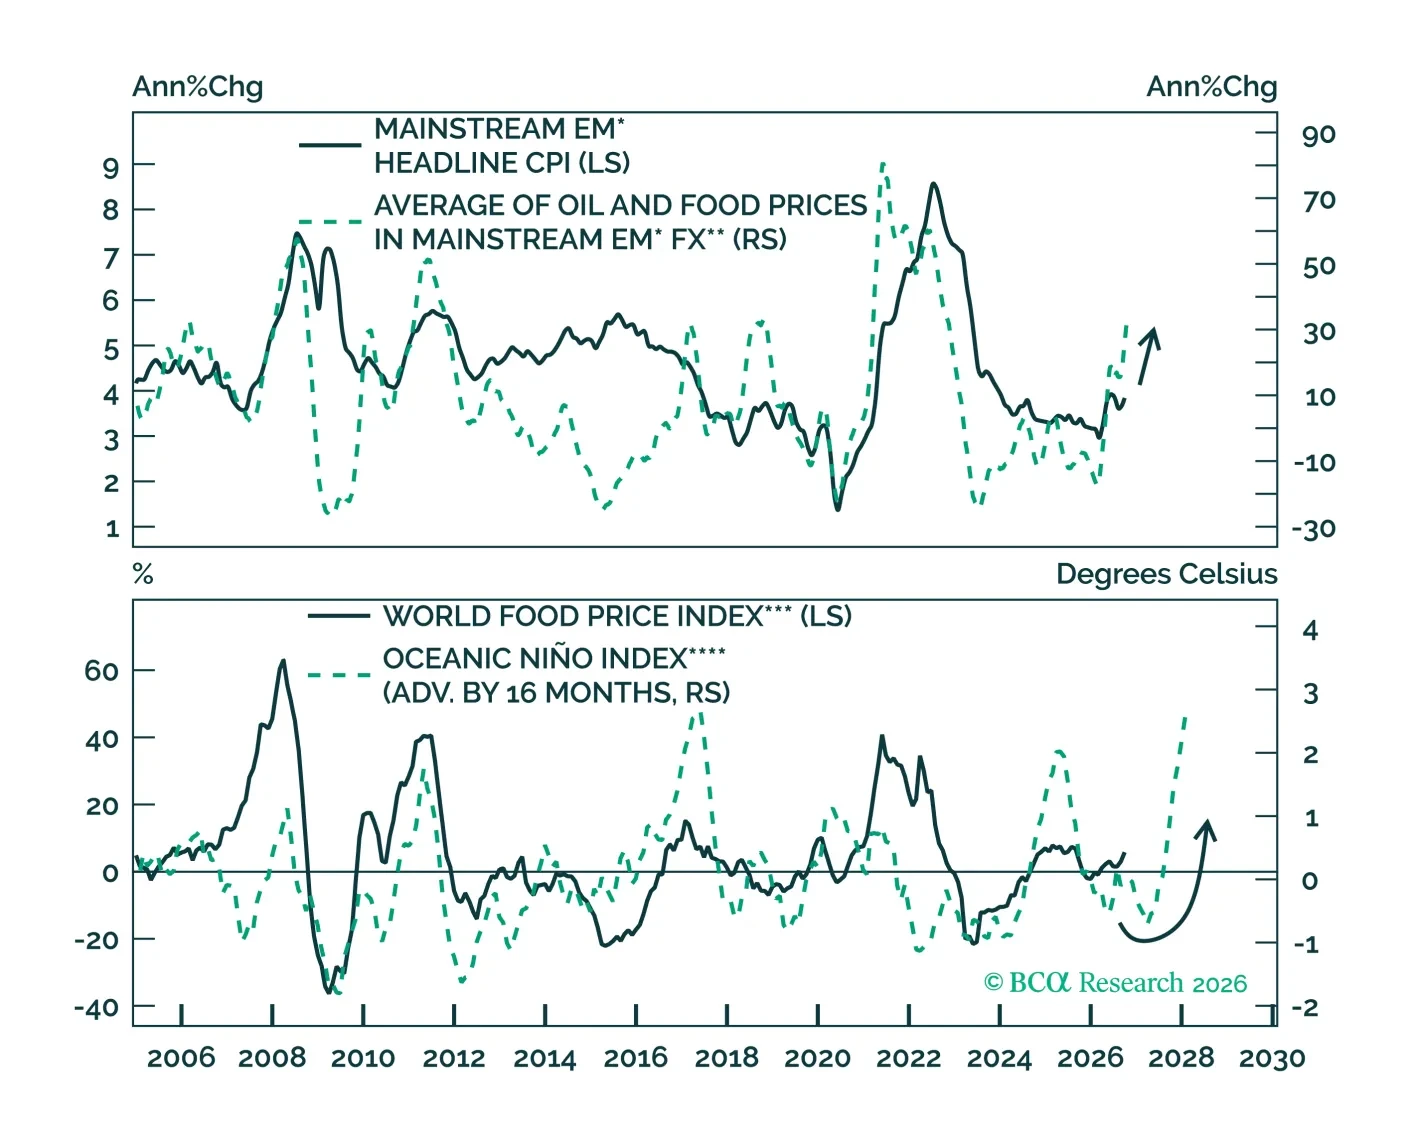
EM local bonds face near-term turbulence from rising inflation, global risk aversion, and currency weakness. Use the sell-off to build exposure: medium- and longer-term fundamentals remain favorable.
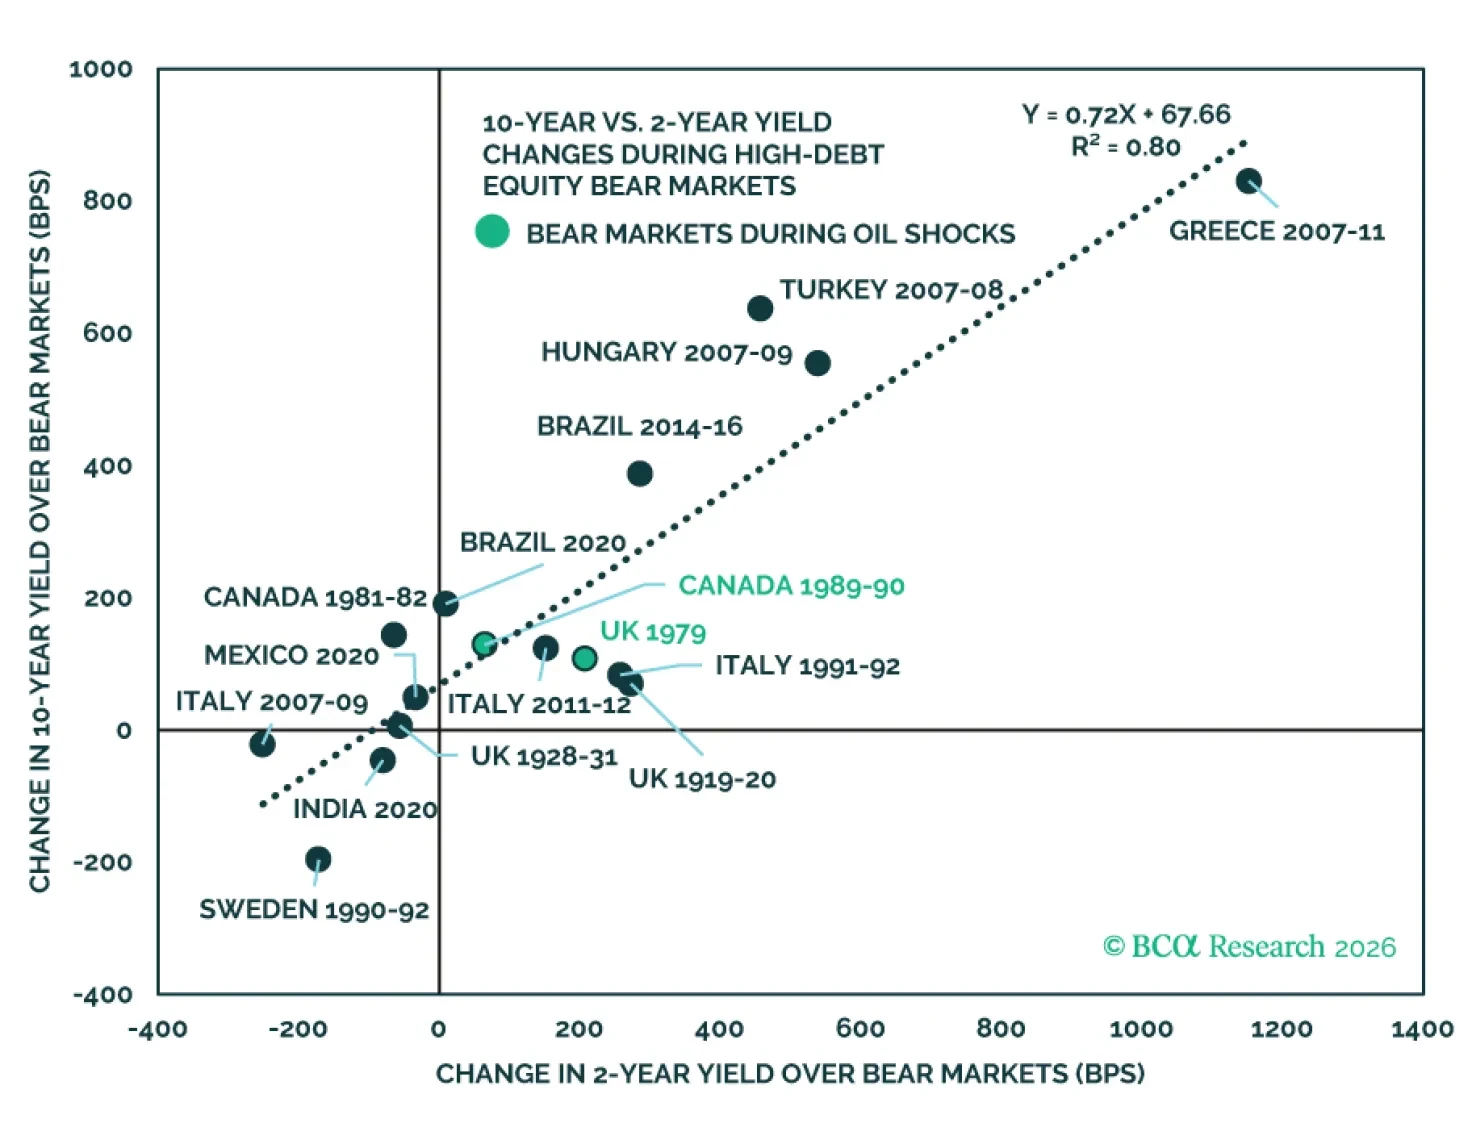
History suggests central bank policy determines how bonds behave in recessions, even for high-debt countries. The Fed should be able to cut into a slowdown, making Treasurys an effective equity hedge… for USD-based investors. Foreign investors will see currency depreciation erase their gains.
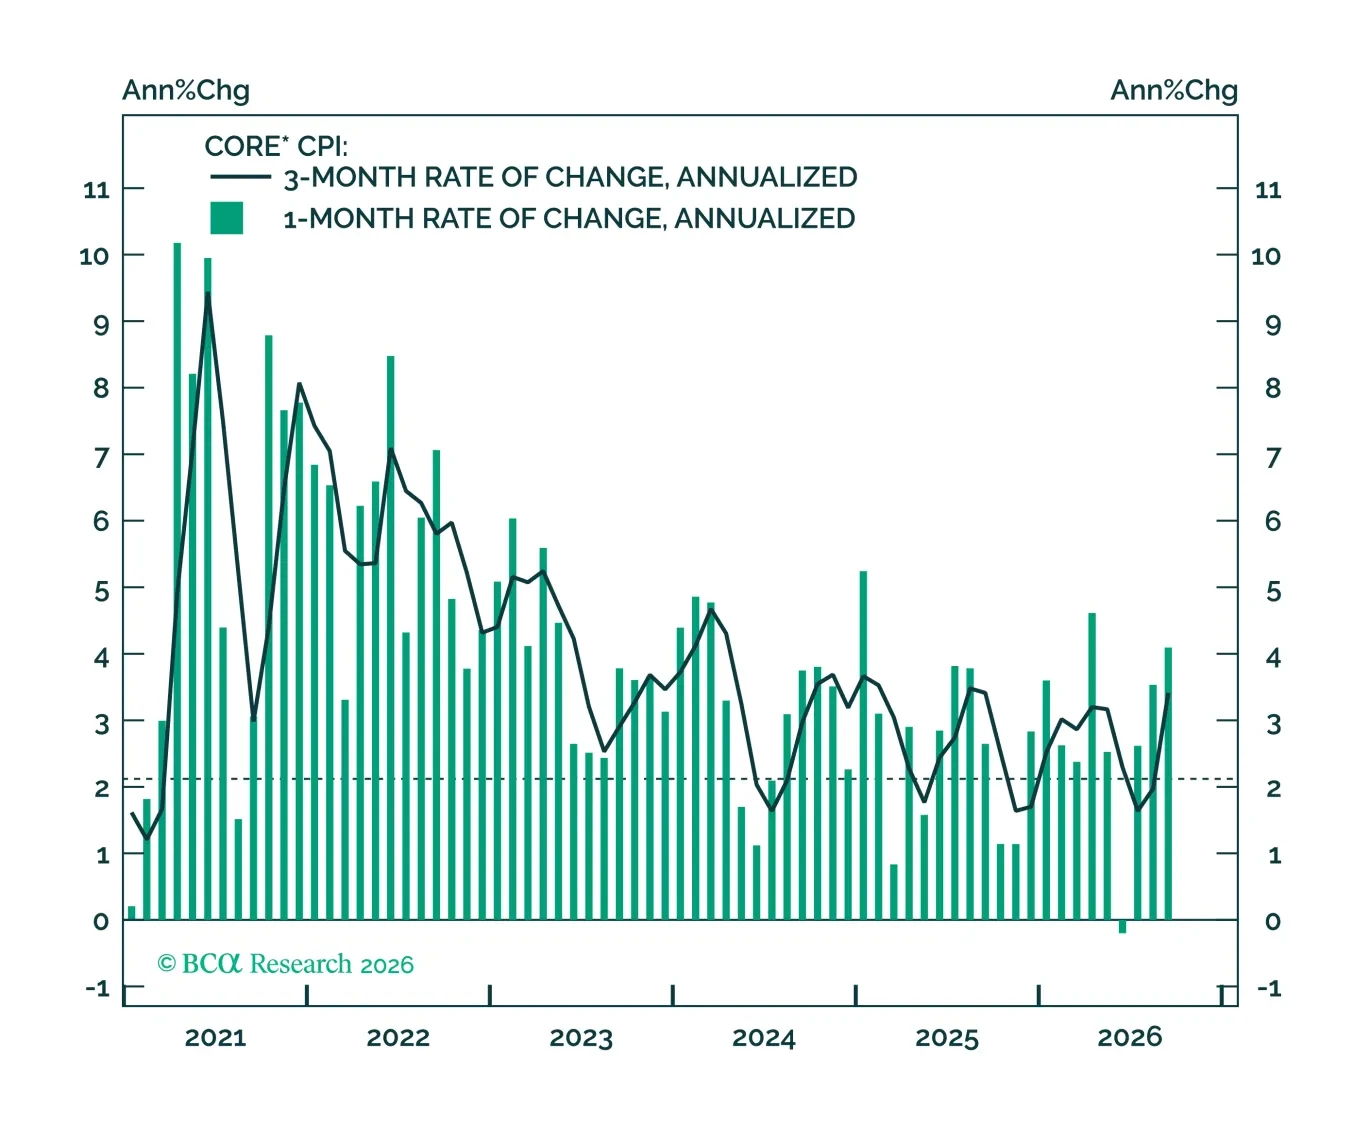
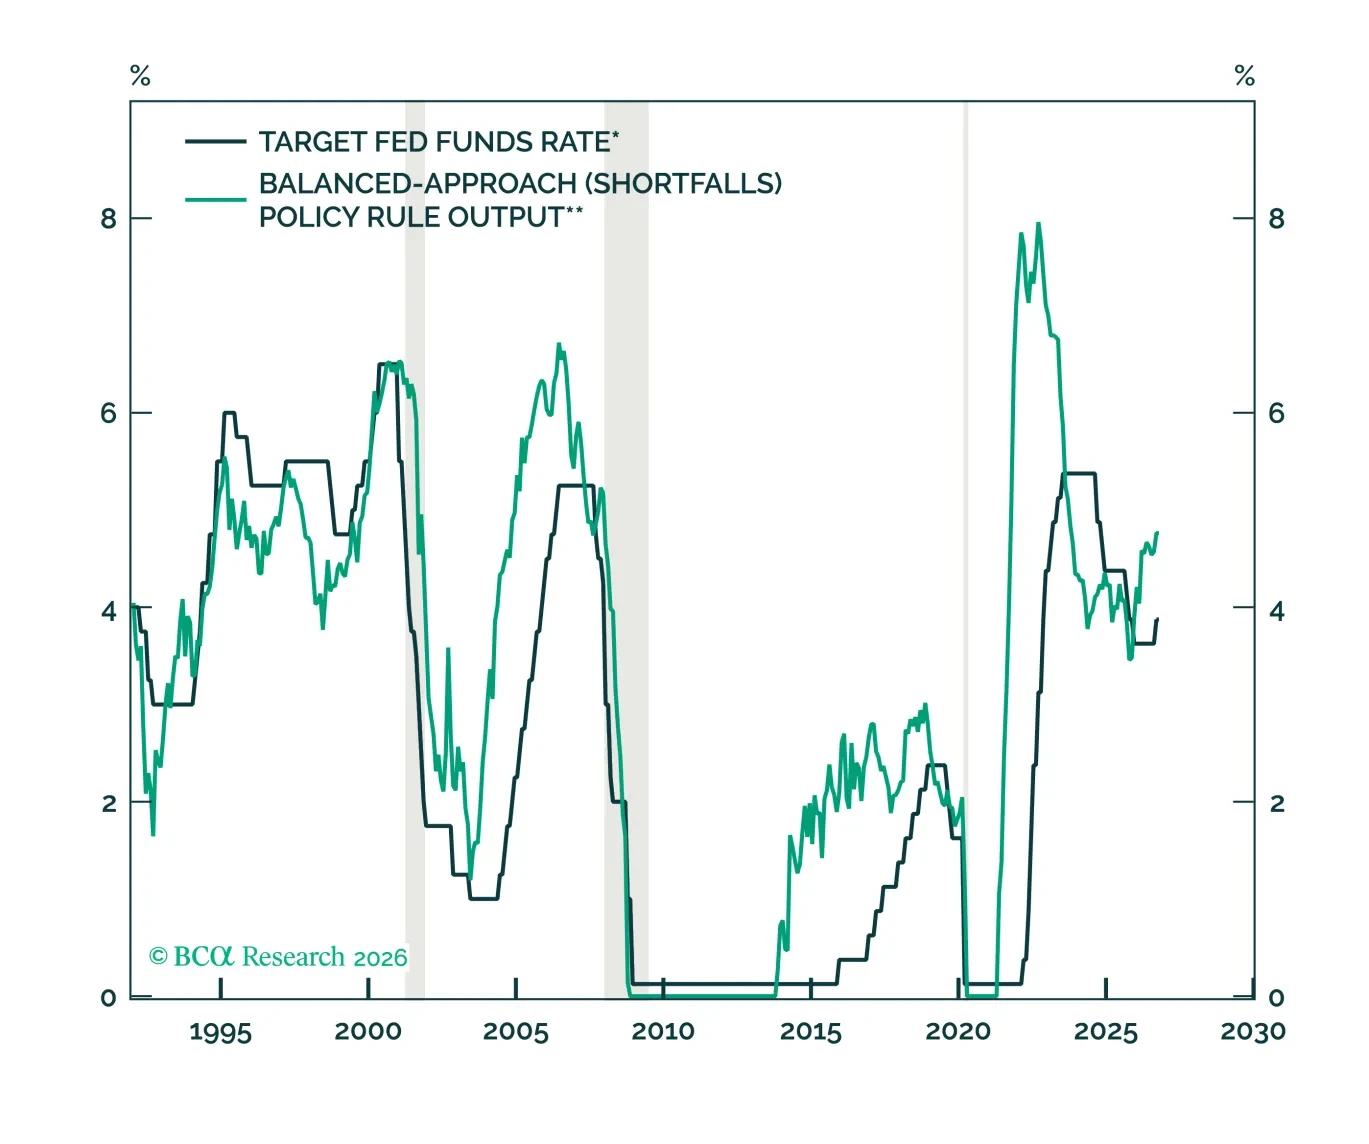
US inflation came in hot for the second consecutive month in September, though probably not hot enough for the Fed to move its next rate hike up to the October meeting.
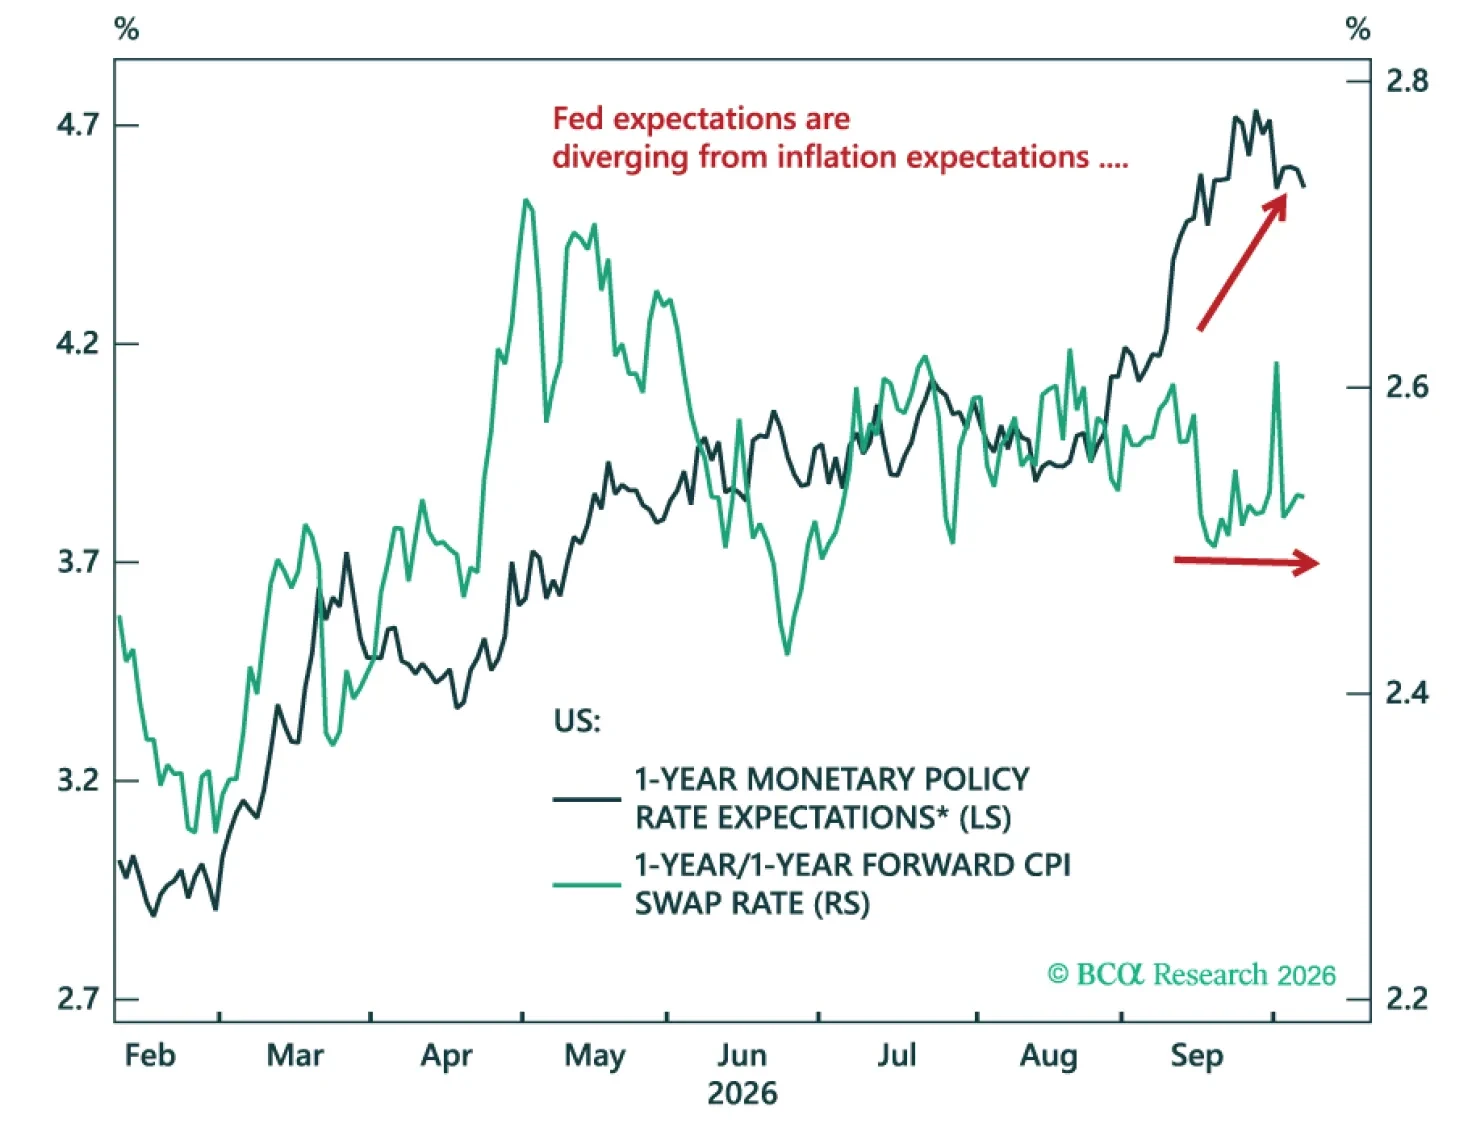
We review our Model Bond Portfolio performance for Q3 and look ahead as energy prices continue to drive fixed income markets. Balanced labor markets point to a mild tightening cycle, creating opportunities in government bonds and credit, while inflation-linked bonds continue offering protection against persistent energy risks.
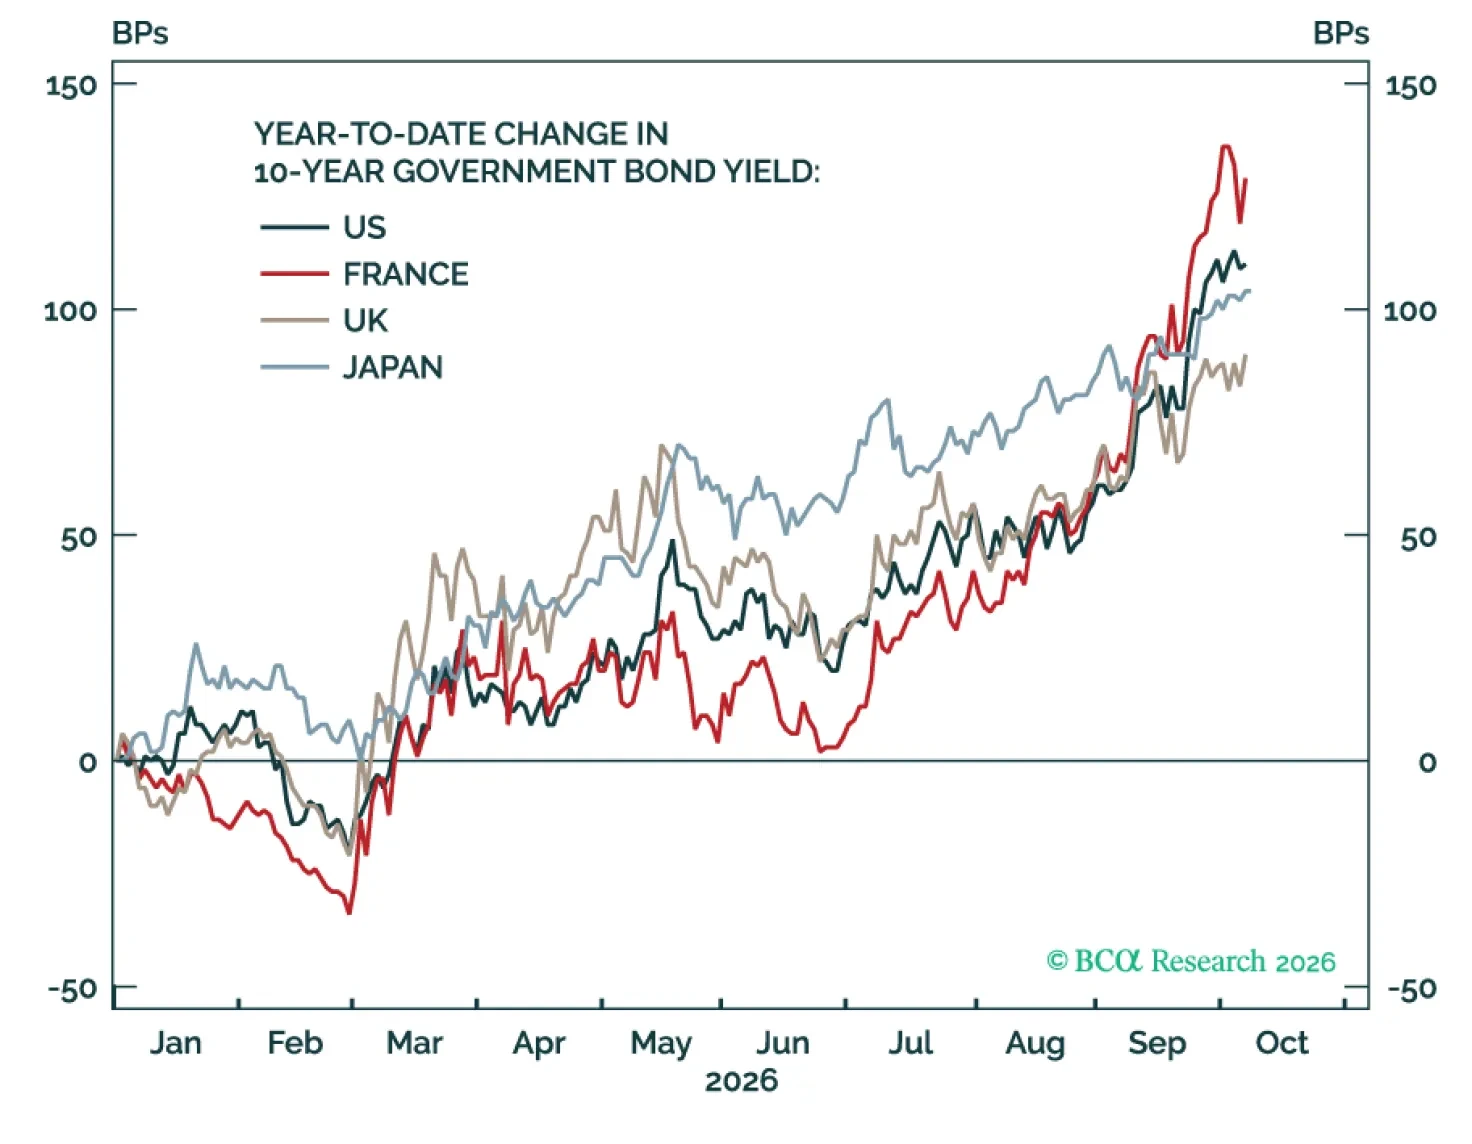
The global bond selloff is not over, but opportunities are emerging. US Treasuries and French OATs remain vulnerable to further selling, while other European government bonds look increasingly attractive. Investors should favor German Bunds and peripheral bonds, particularly on a currency-hedged basis.
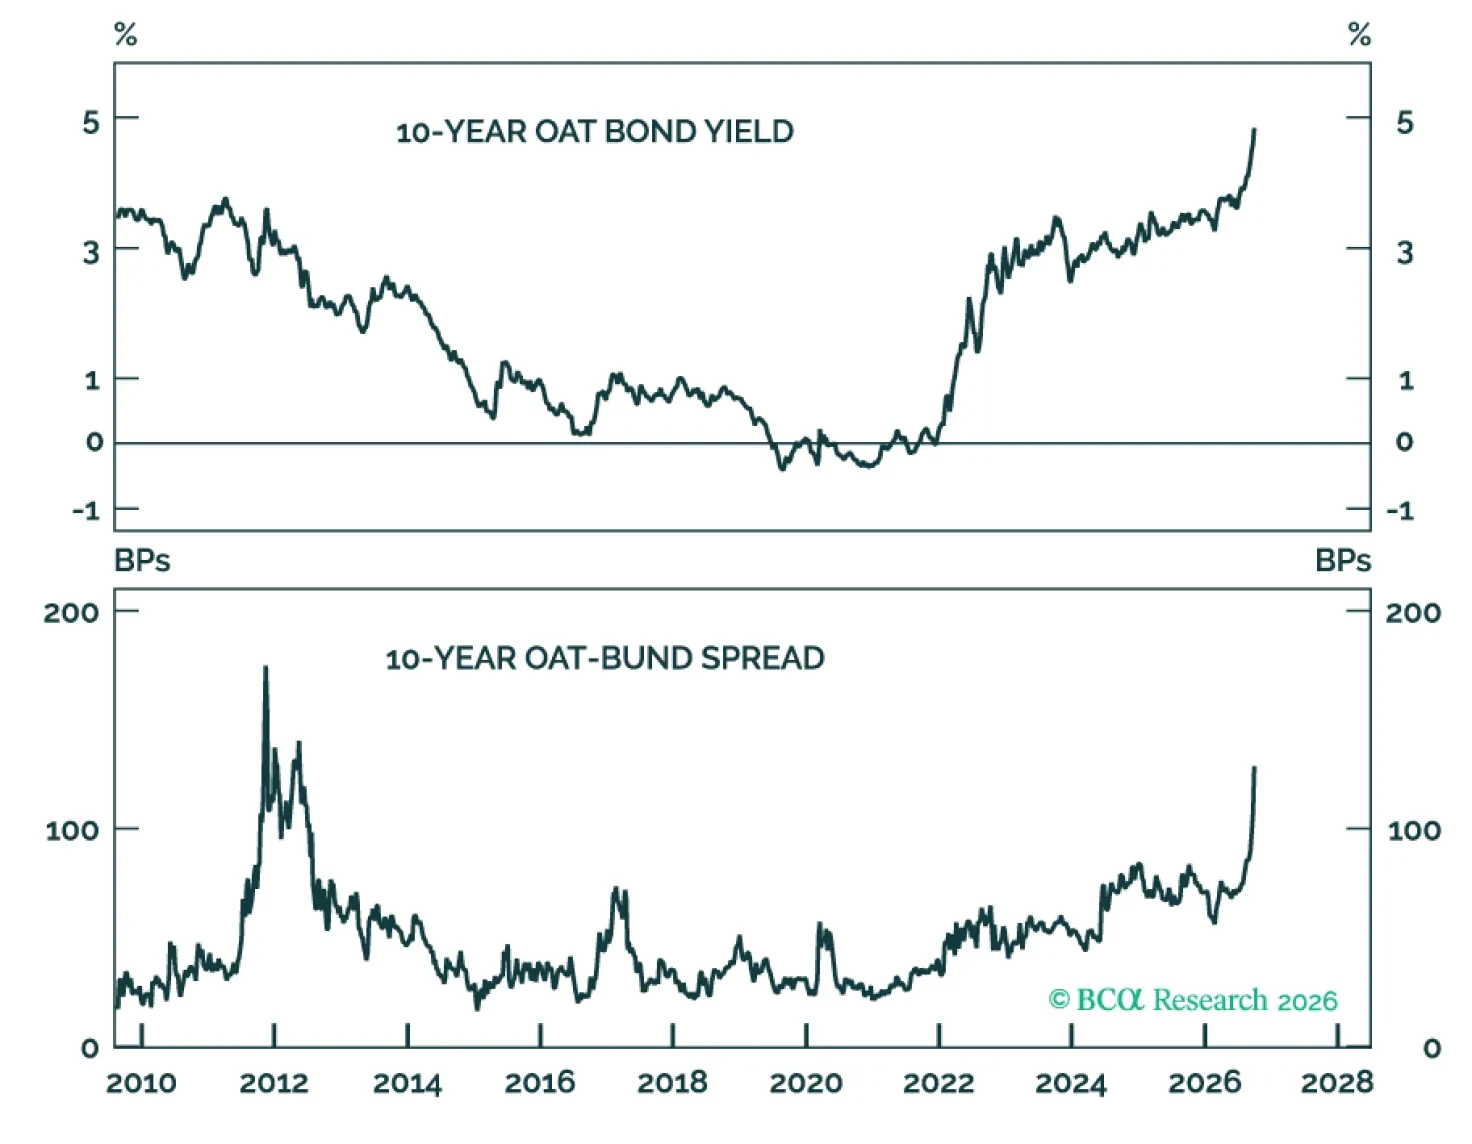
Forced selling may be approaching a pause, but France’s fiscal and political adjustment has barely begun. Maintain an underweight in OATs and use relief rallies to reduce exposure. Contained contagion is reassuring for Europe; it is not a buy signal for France.
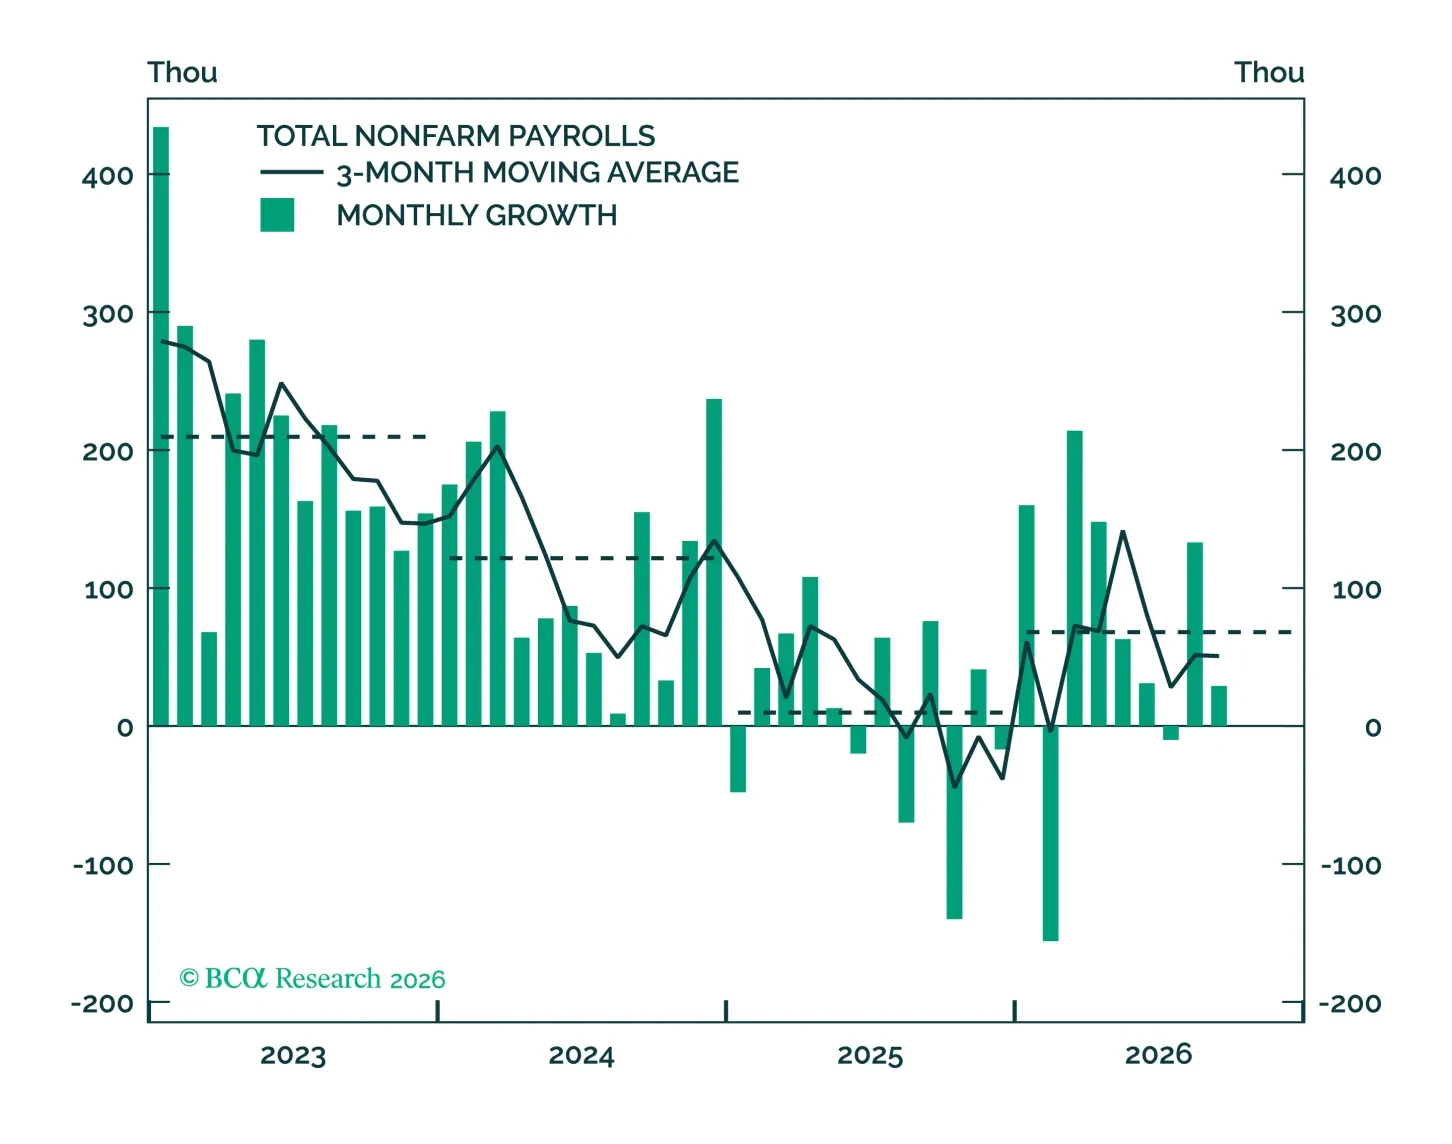
This morning’s jobs report serves to underscore that the labor market is not a source of inflationary pressure and therefore of second-order importance when it comes to the Fed’s near-term decision making.
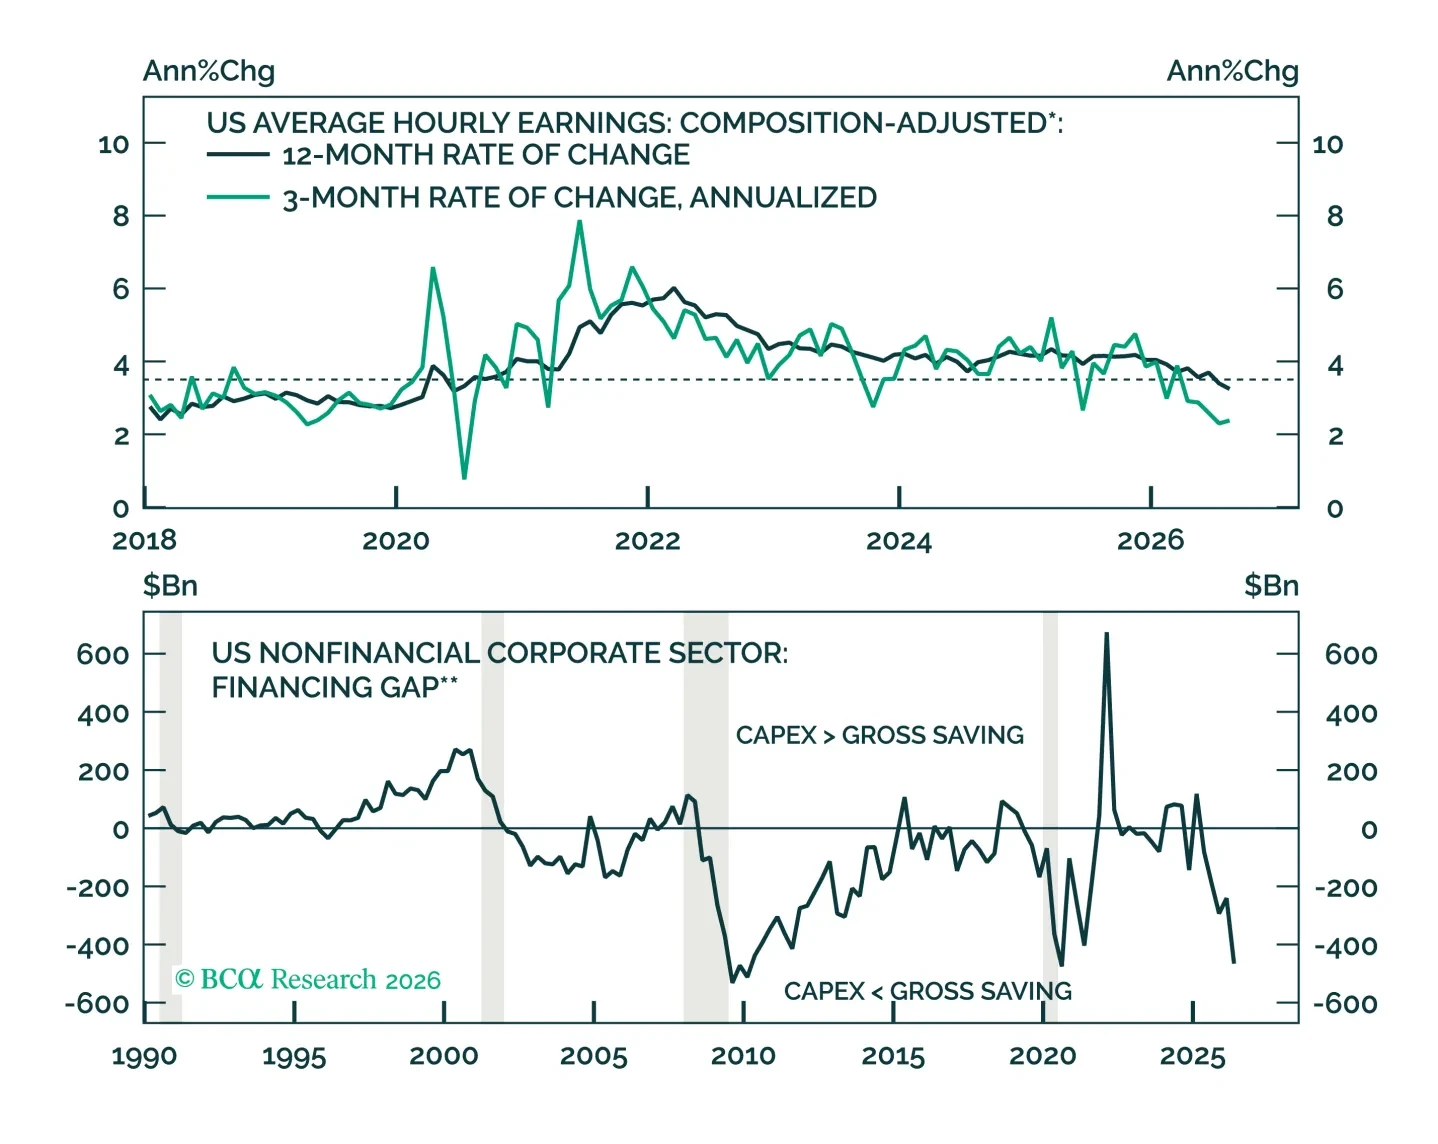
Politics, wars, a global tightening cycle, doubts over AI capex: the wall of worry keeps rising. But the spark that would topple risk assets is missing. Our Q4 FICC outlook explains why to stay long risk, and where the danger lies.
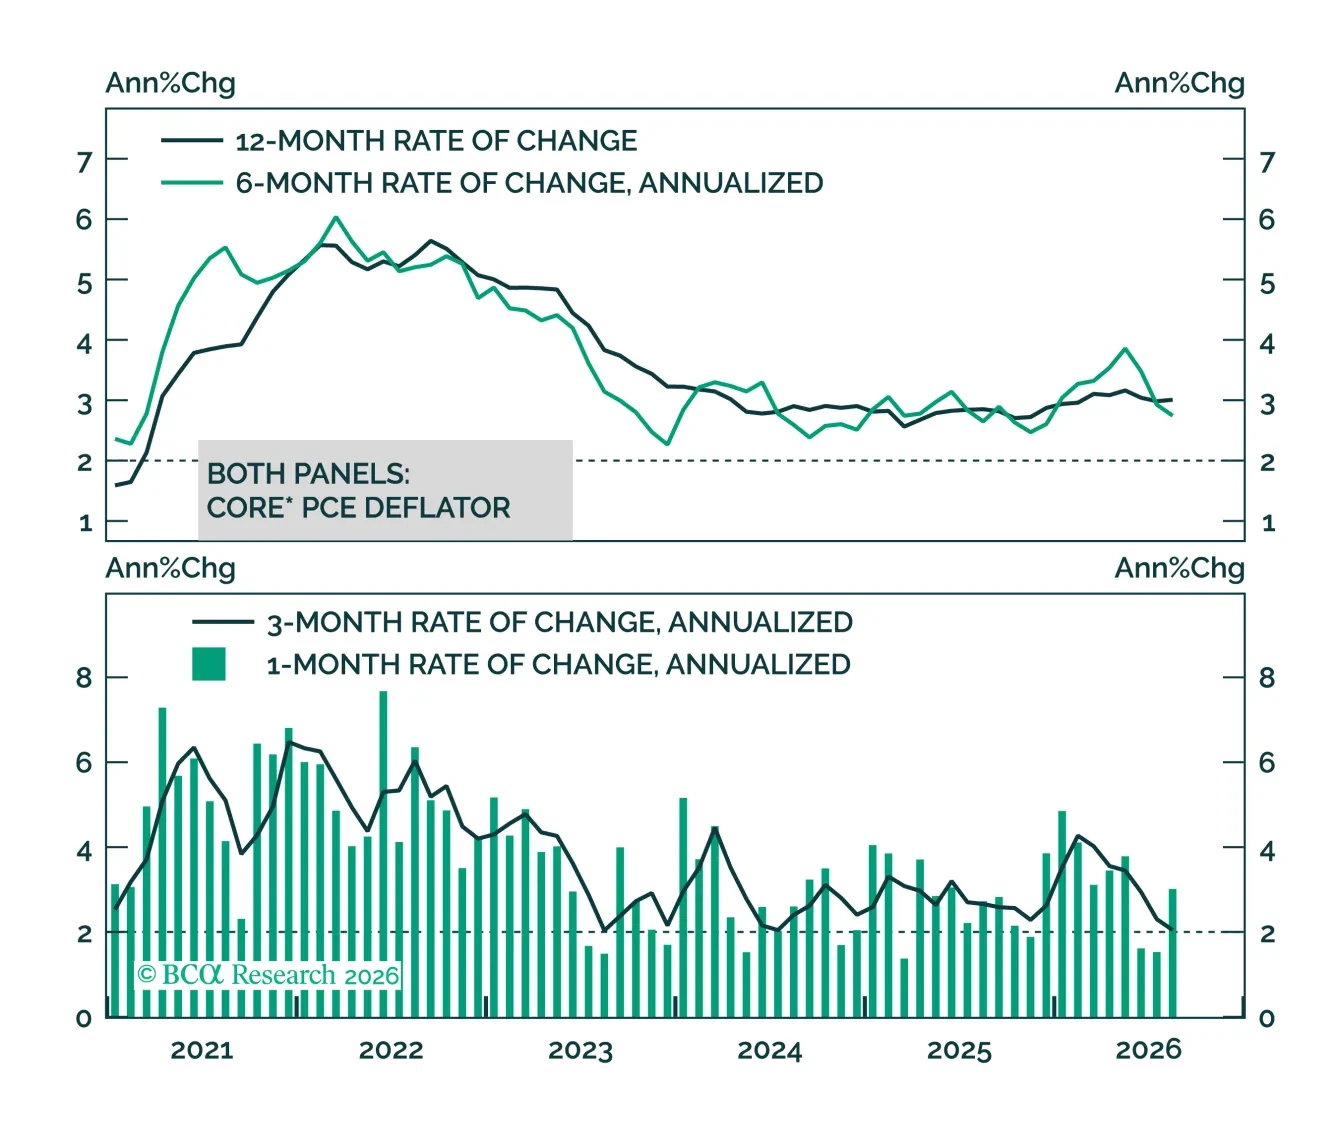
Core US inflation is still running above target. But this morning’s data revisions reveal that the gap is not nearly as large as it appeared yesterday.