 FICC
| Currencies
Near-term trades and longer-term views on every major developed and emerging market currency.
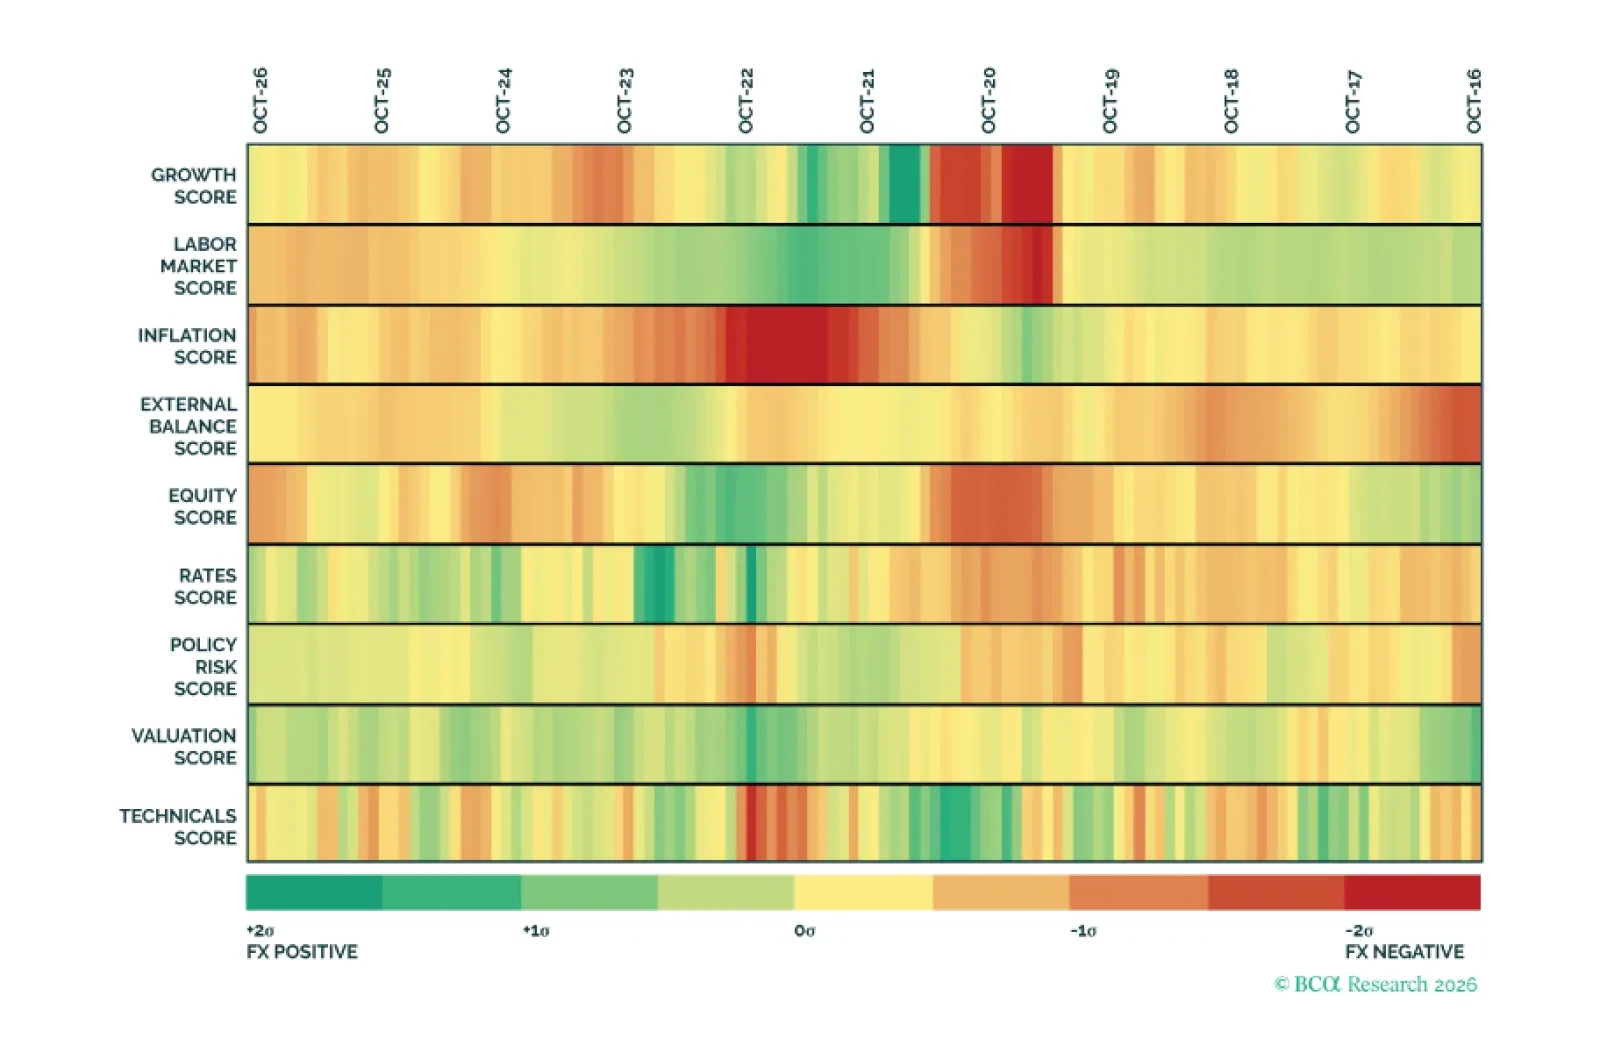
GBP offers attractive carry today, but the market’s aggressive rate hike pricing is likely to turn into a headwind within 12 months. Our latest Currency Chartpack examines the valuation, growth, rate, and policy drivers of the pound, showing why the long-term outlook is less rosy than near-term data implies.
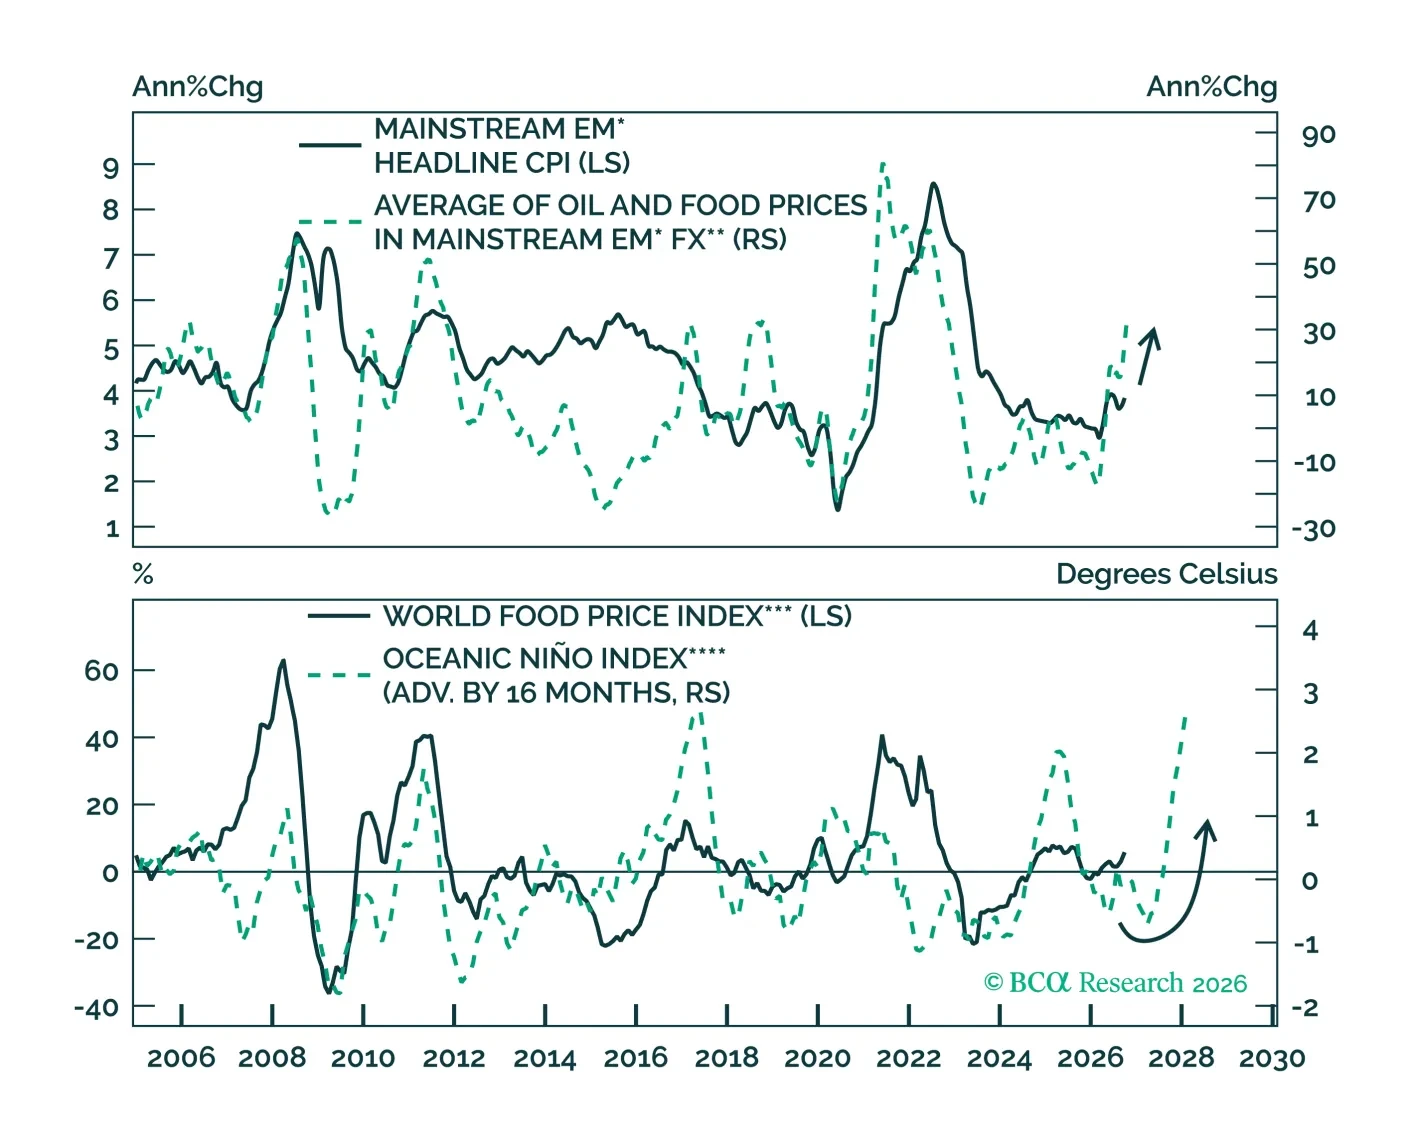
EM local bonds face near-term turbulence from rising inflation, global risk aversion, and currency weakness. Use the sell-off to build exposure: medium- and longer-term fundamentals remain favorable.
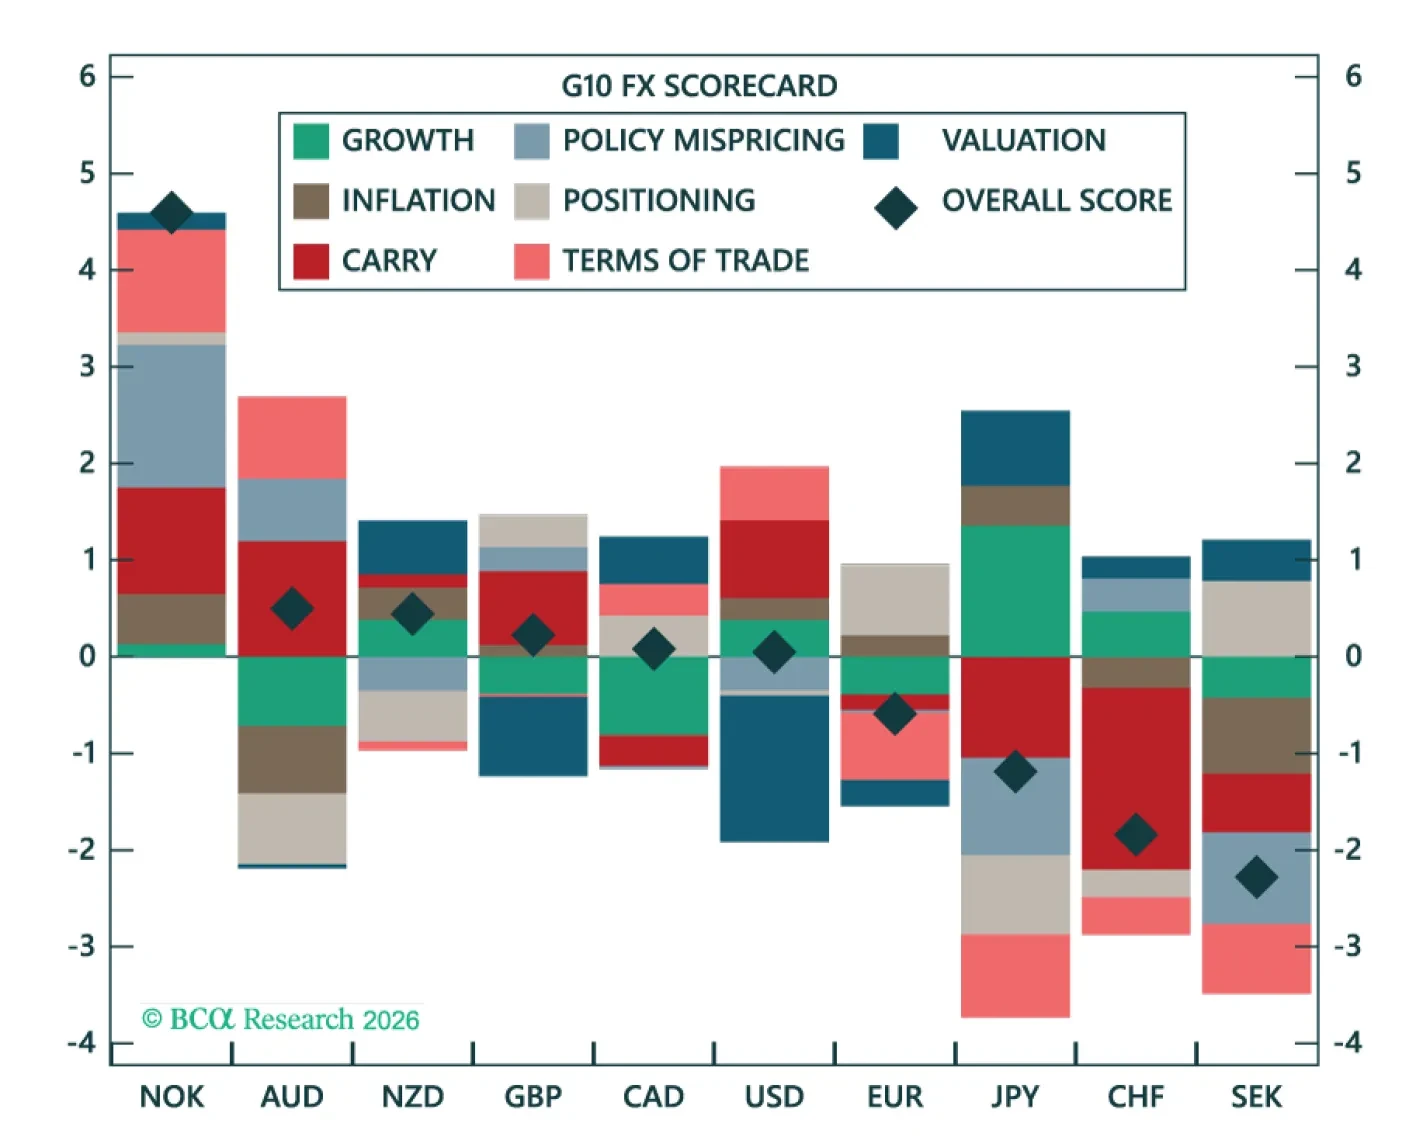
Our G10 FX cyclical scorecard still favors high-carry currencies over low yielders, suggesting patience should continue to pay. We break down the factors driving each currency and highlight the most appealing relative-value opportunities.
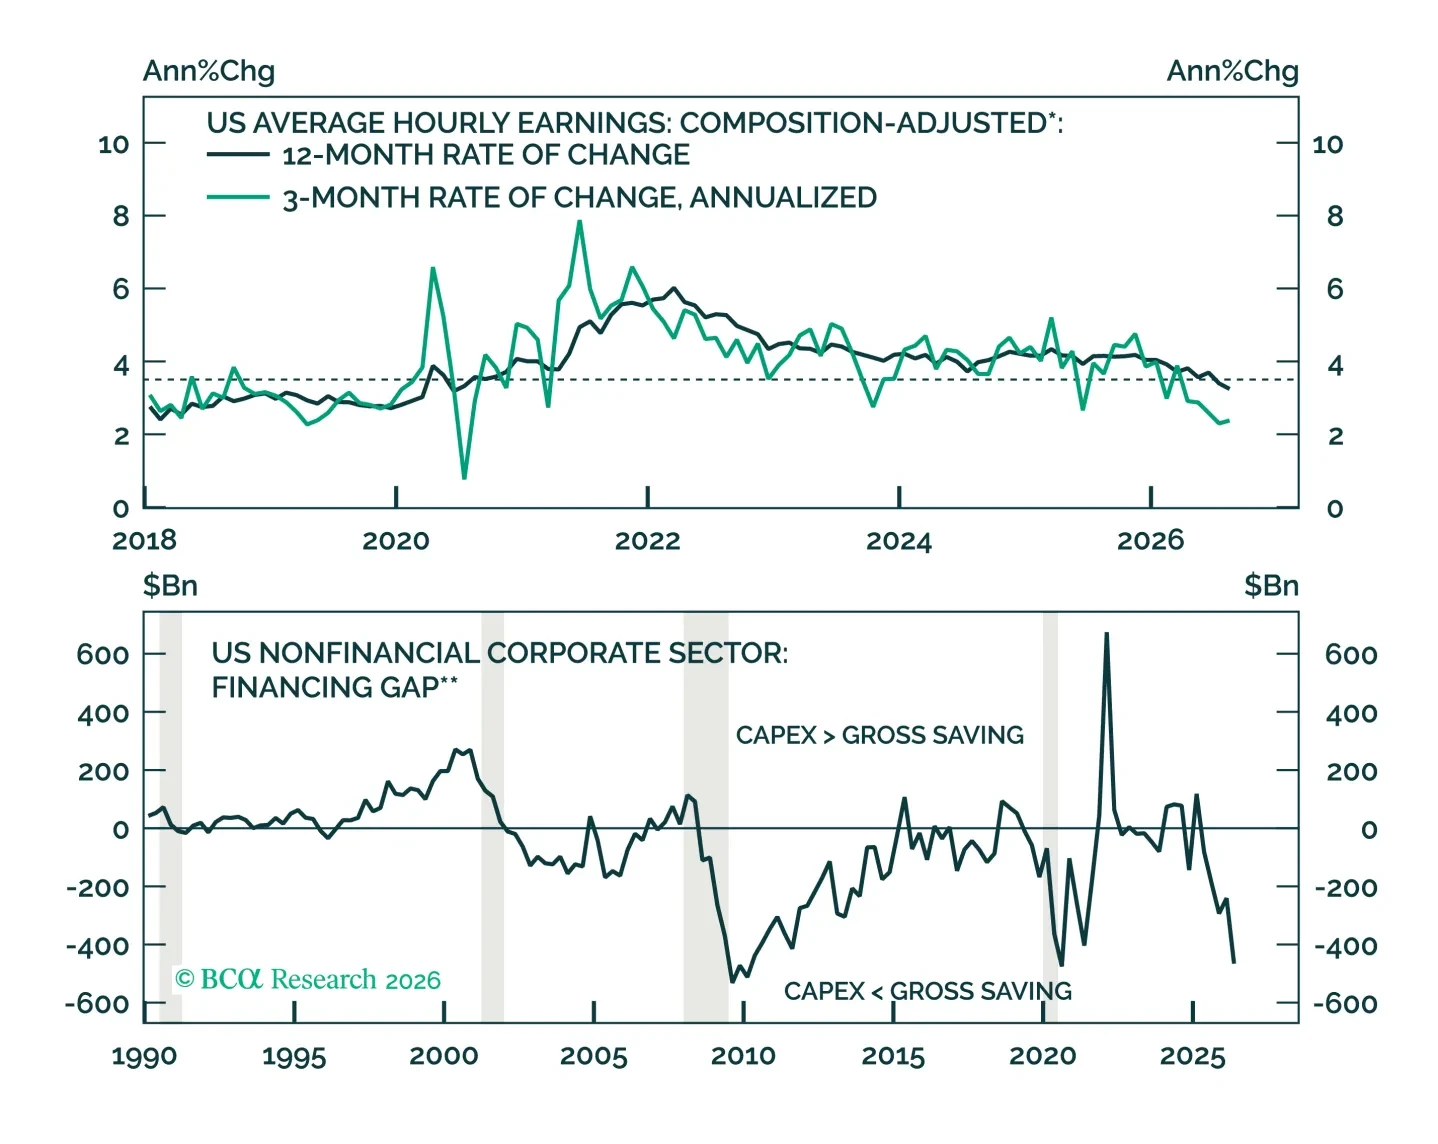
Politics, wars, a global tightening cycle, doubts over AI capex: the wall of worry keeps rising. But the spark that would topple risk assets is missing. Our Q4 FICC outlook explains why to stay long risk, and where the danger lies.
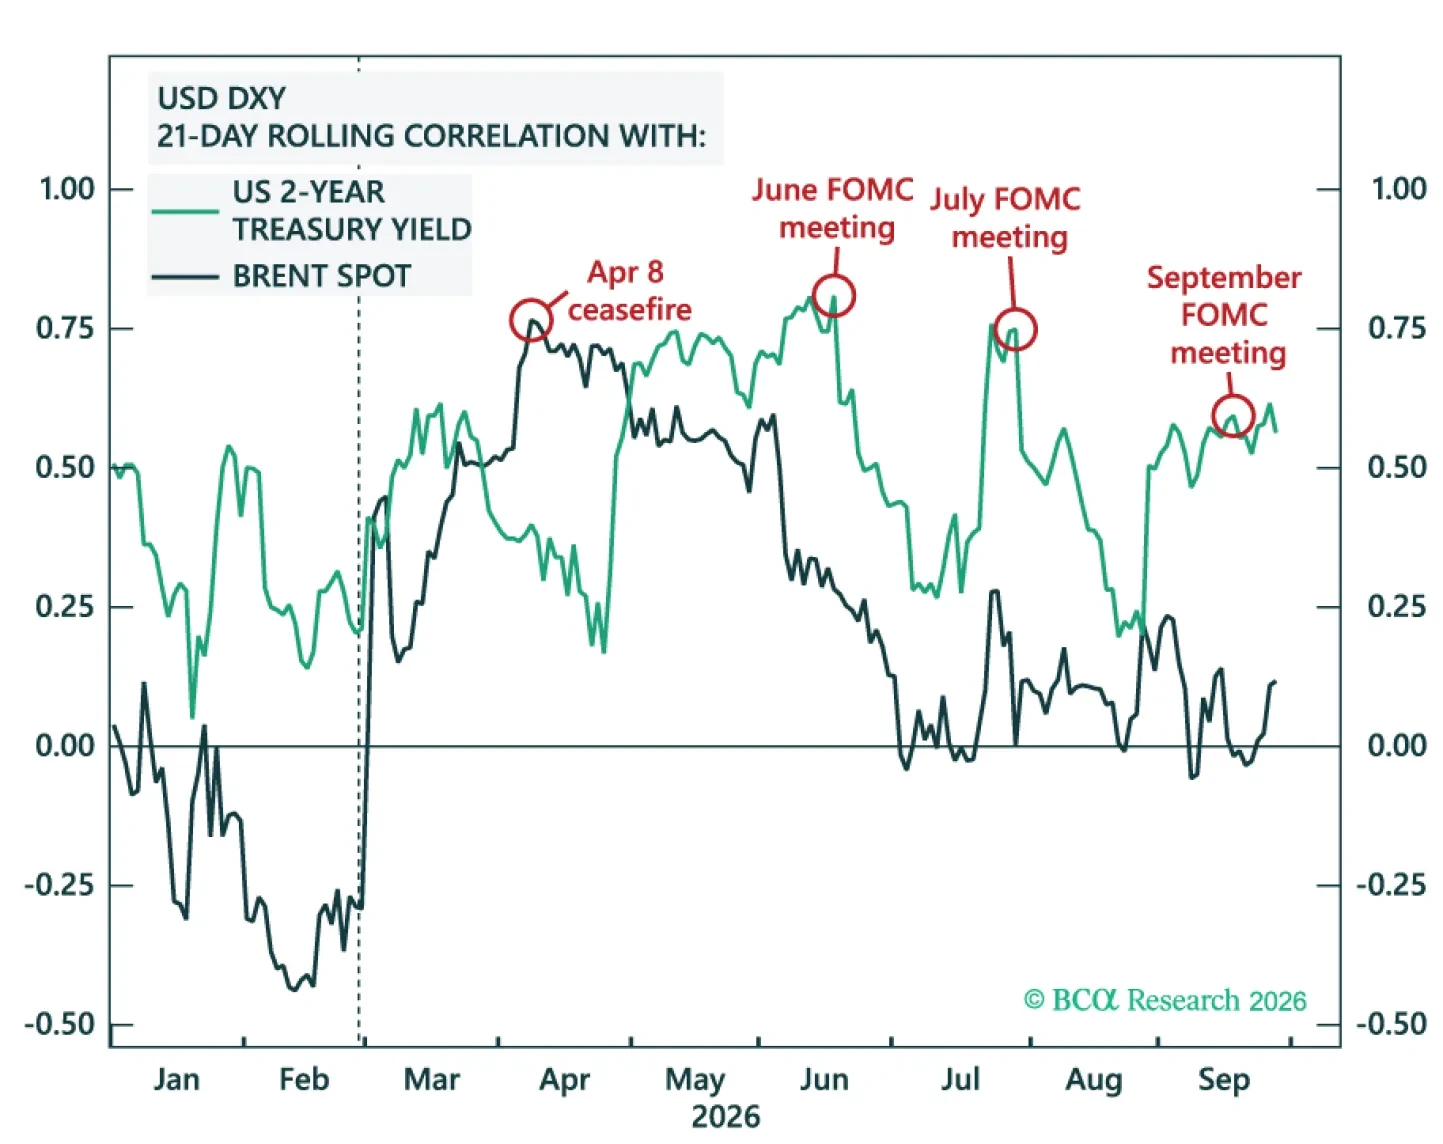
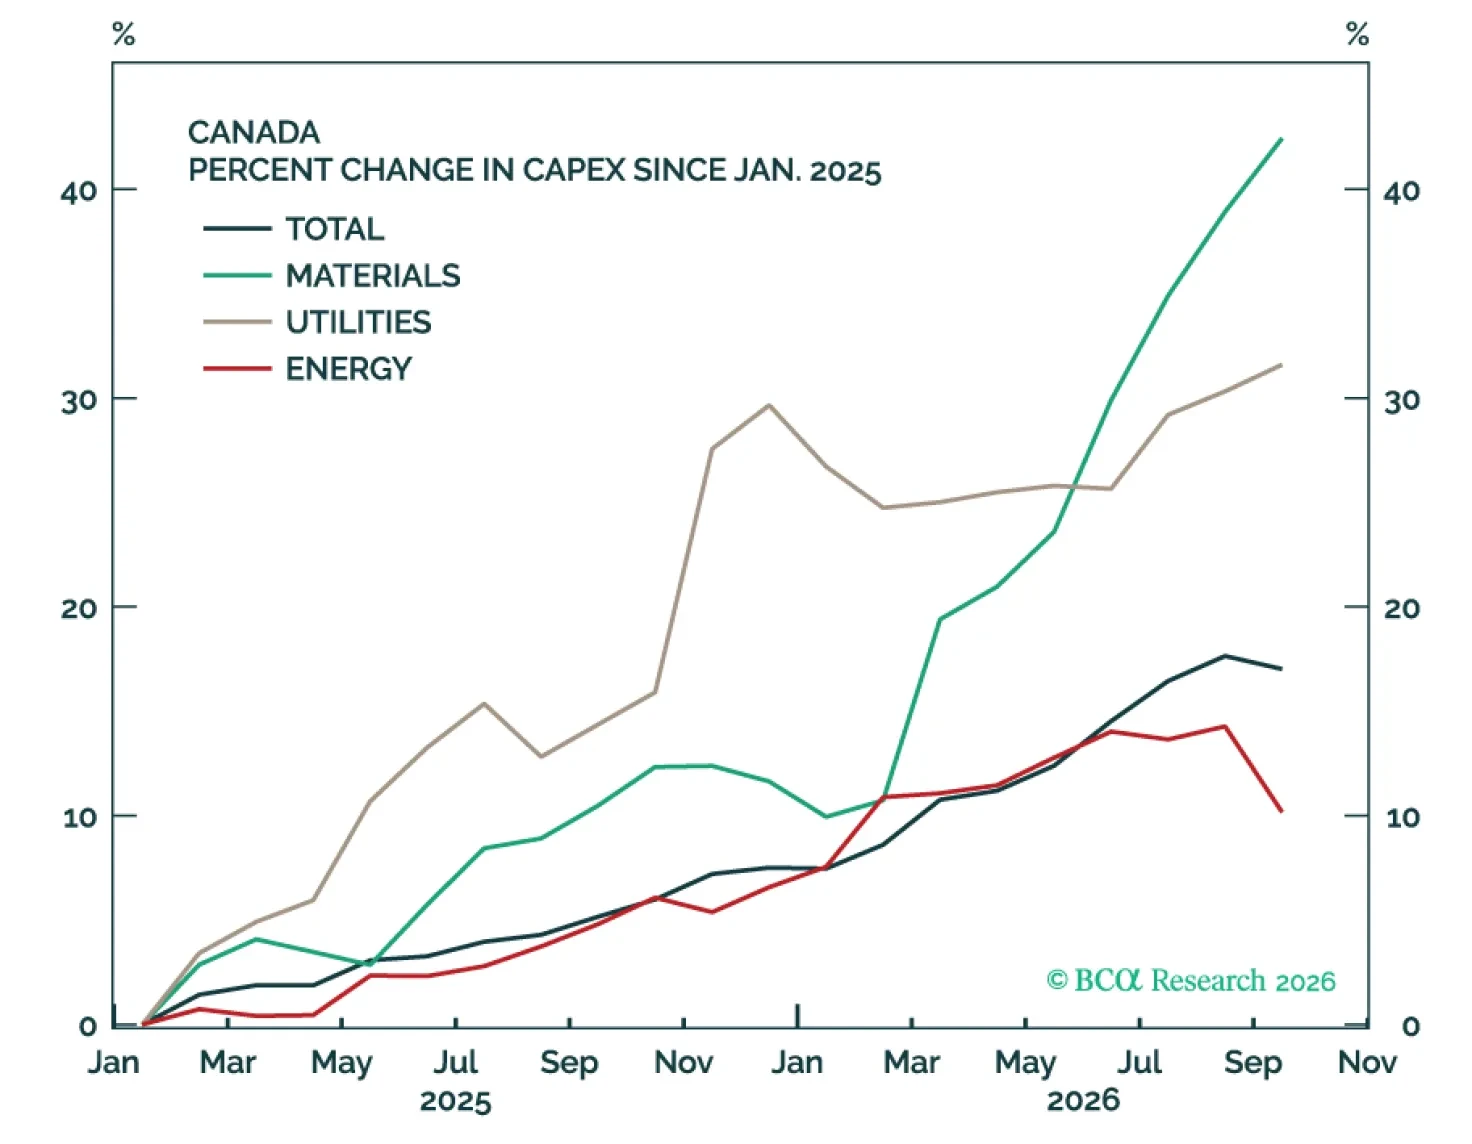
Global capex is driving the strongest industrial cycle since 2021. The US is best positioned to capture the gains and to weather near-term risks, supporting widening real-rate differentials and favoring continued upside in the dollar in the coming months.
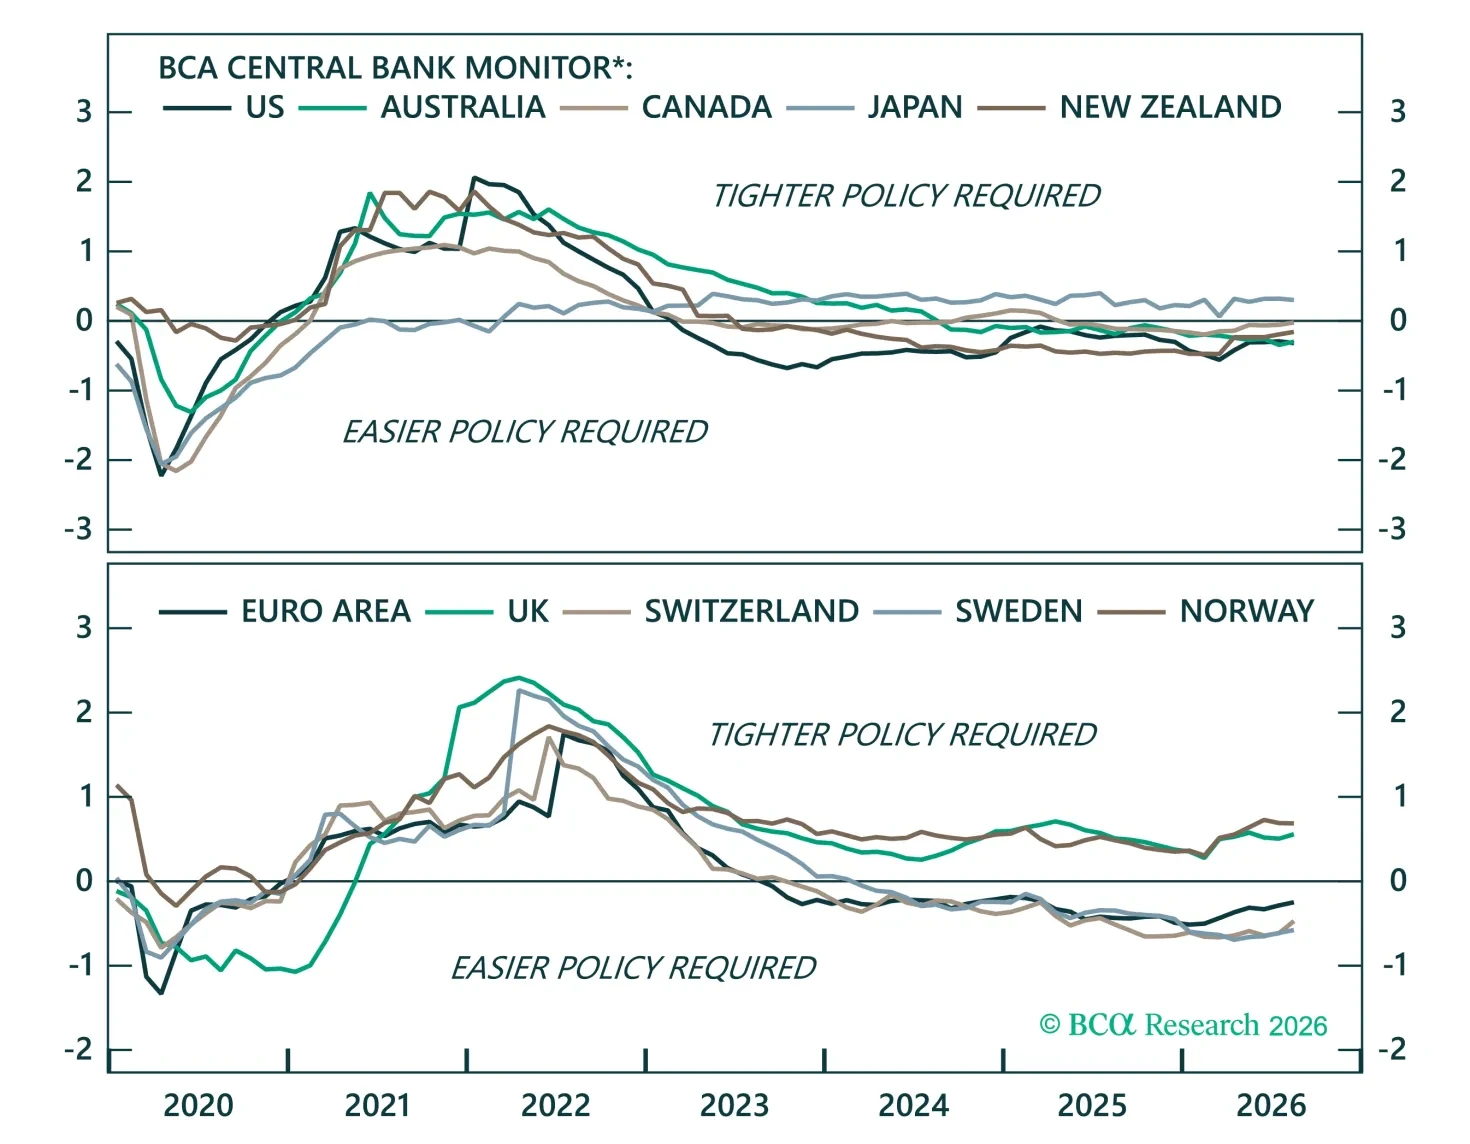
Central banks have begun a mild tightening cycle as elevated energy prices raise concerns about second-round inflation effects. We use BCA’s Central Bank Monitors to test whether hawkish market pricing is justified and identify tactical opportunities across global bond and currency markets.
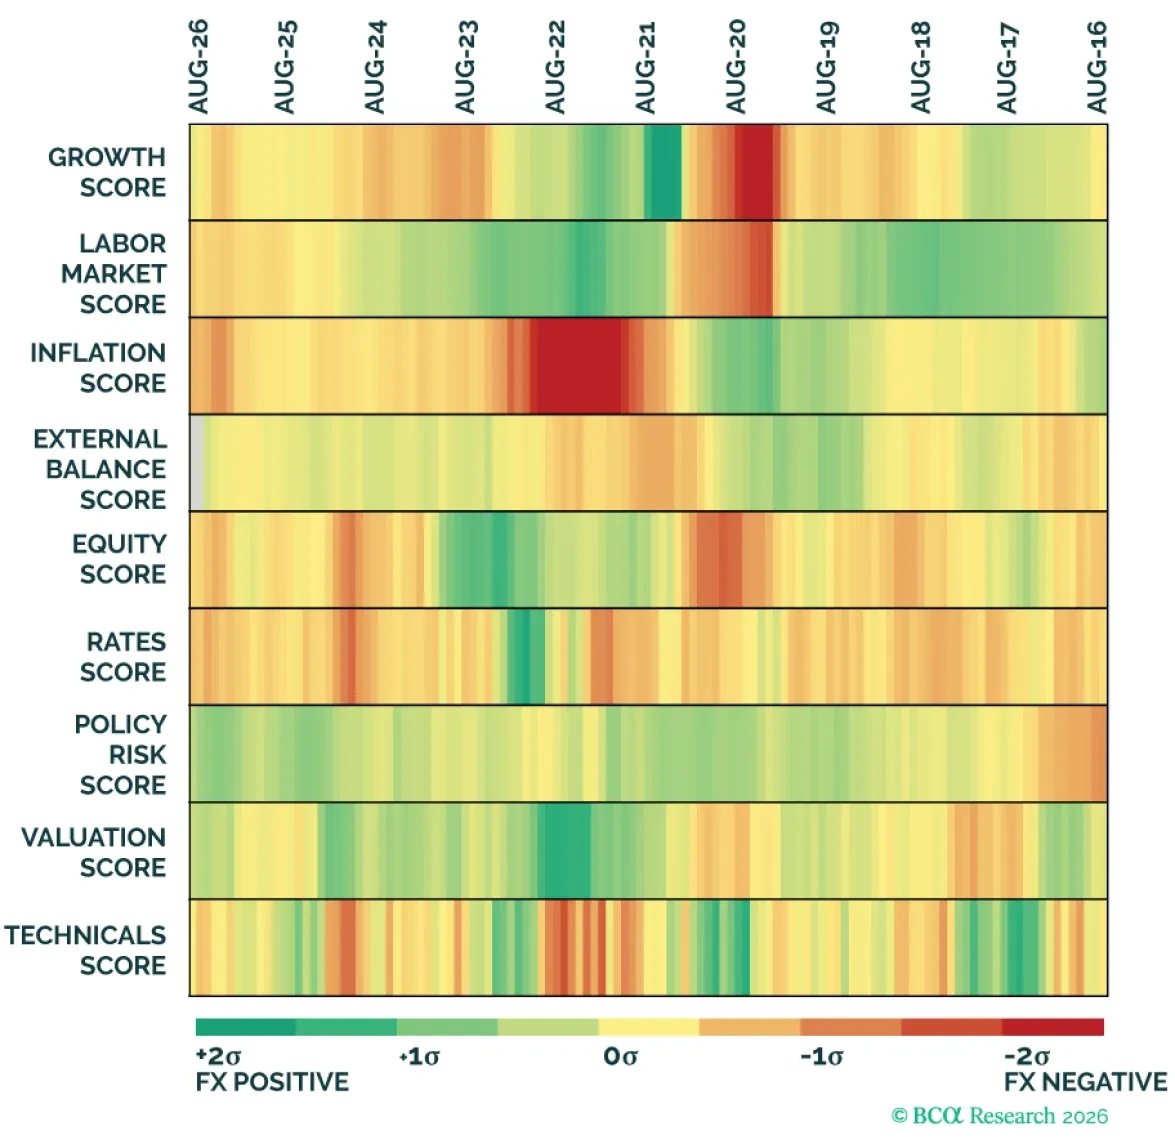
Foreign exchange markets are shaped by a wide range of macro influences. The sheer breadth of relevant information makes systematically assessing where a currency stands at any point in time a challenging analytical task. We introduce an FX scorecard that condenses the full range of data into nine thematic scores, providing a clear visual snapshot of a currency's position and how it's evolving.
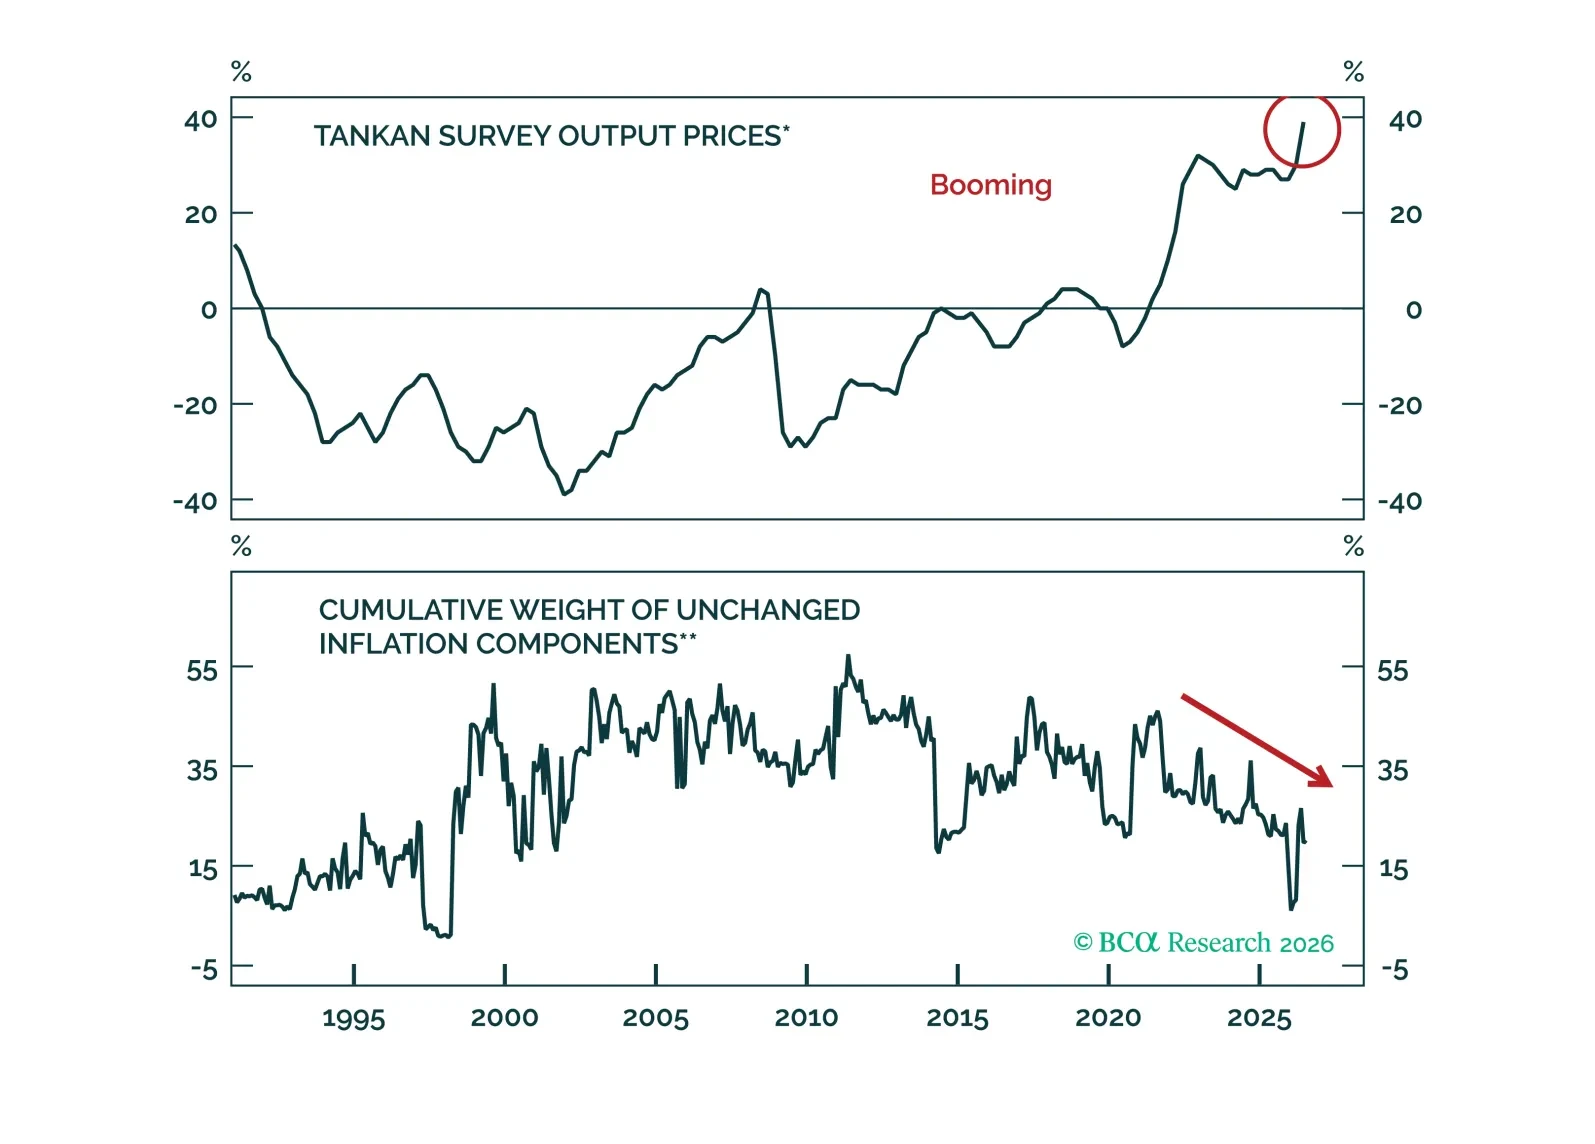
The yen's next leg isn't a fiscal story, it's an inflation one, and the BoJ is about to admit it. We lay out why a September pivot sends USD/JPY toward 99, and why global risk assets won't pay the price.
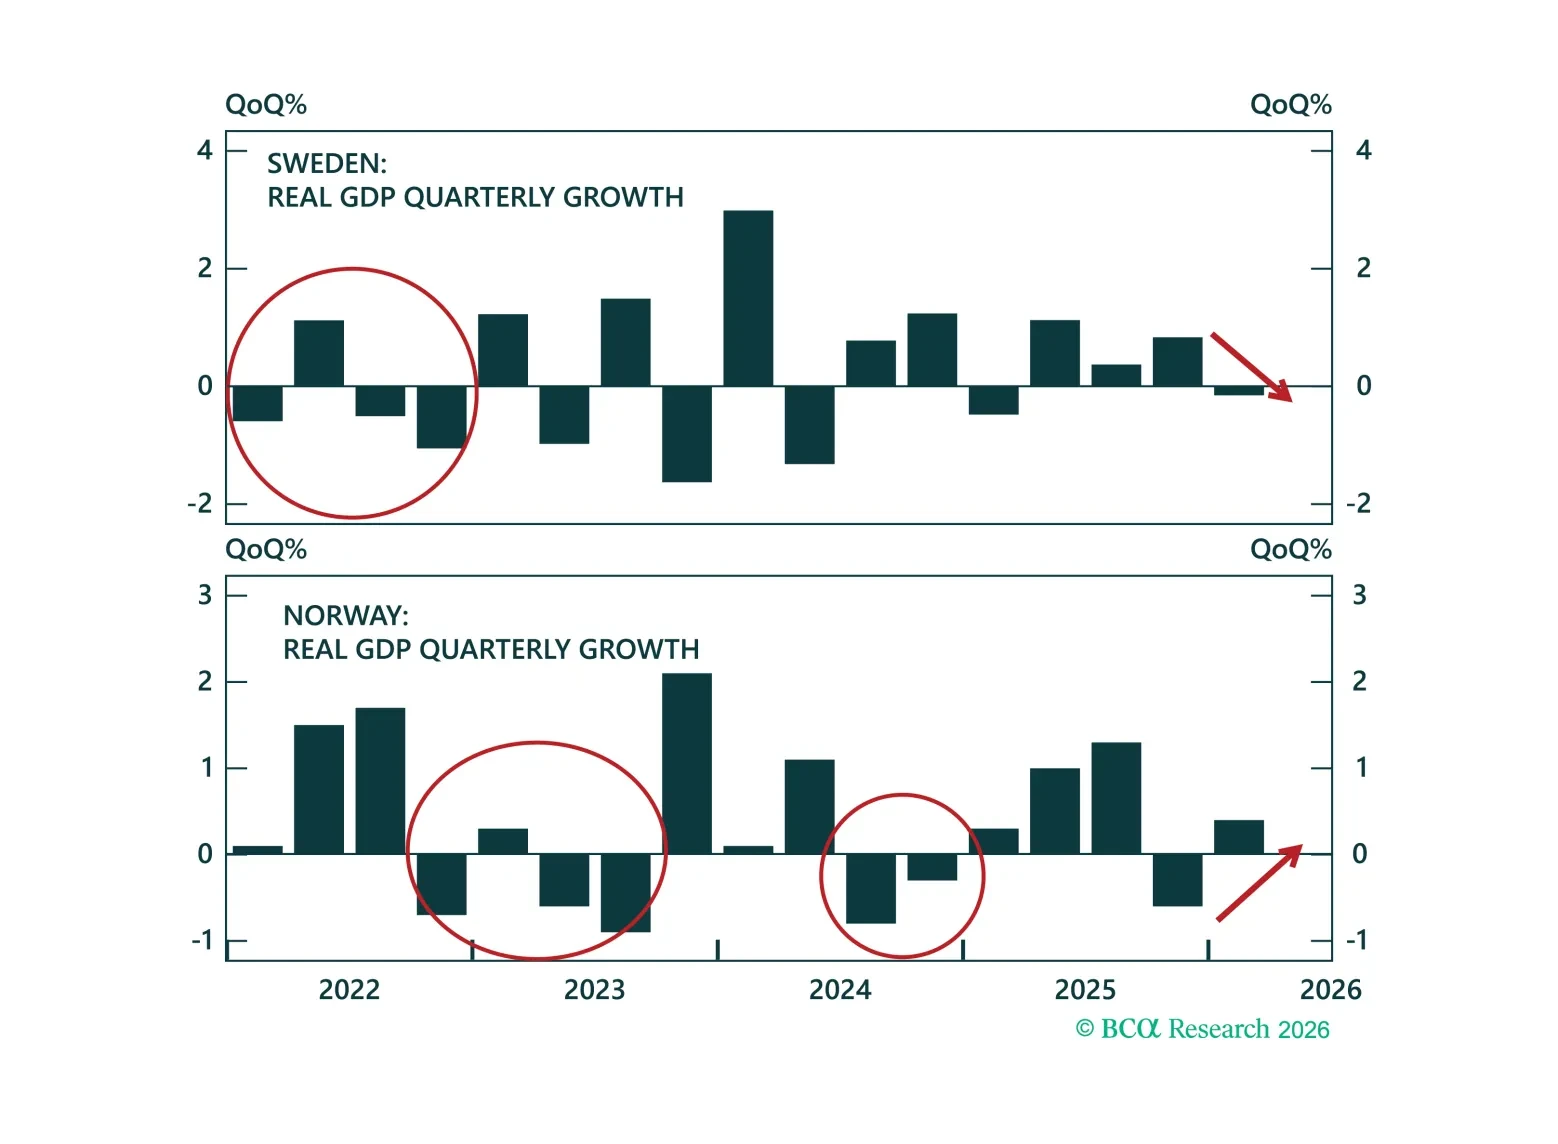
The war in Iran and the energy shock are driving a reversal of Nordic fortunes: Sweden’s recovery is faltering just as Norway receives a welcome energy windfall. Favor Norwegian over Swedish equities and buy NOK/SEK. In rates, fade aggressive Riksbank hike expectations and downgrade Norwegian government bonds to neutral.