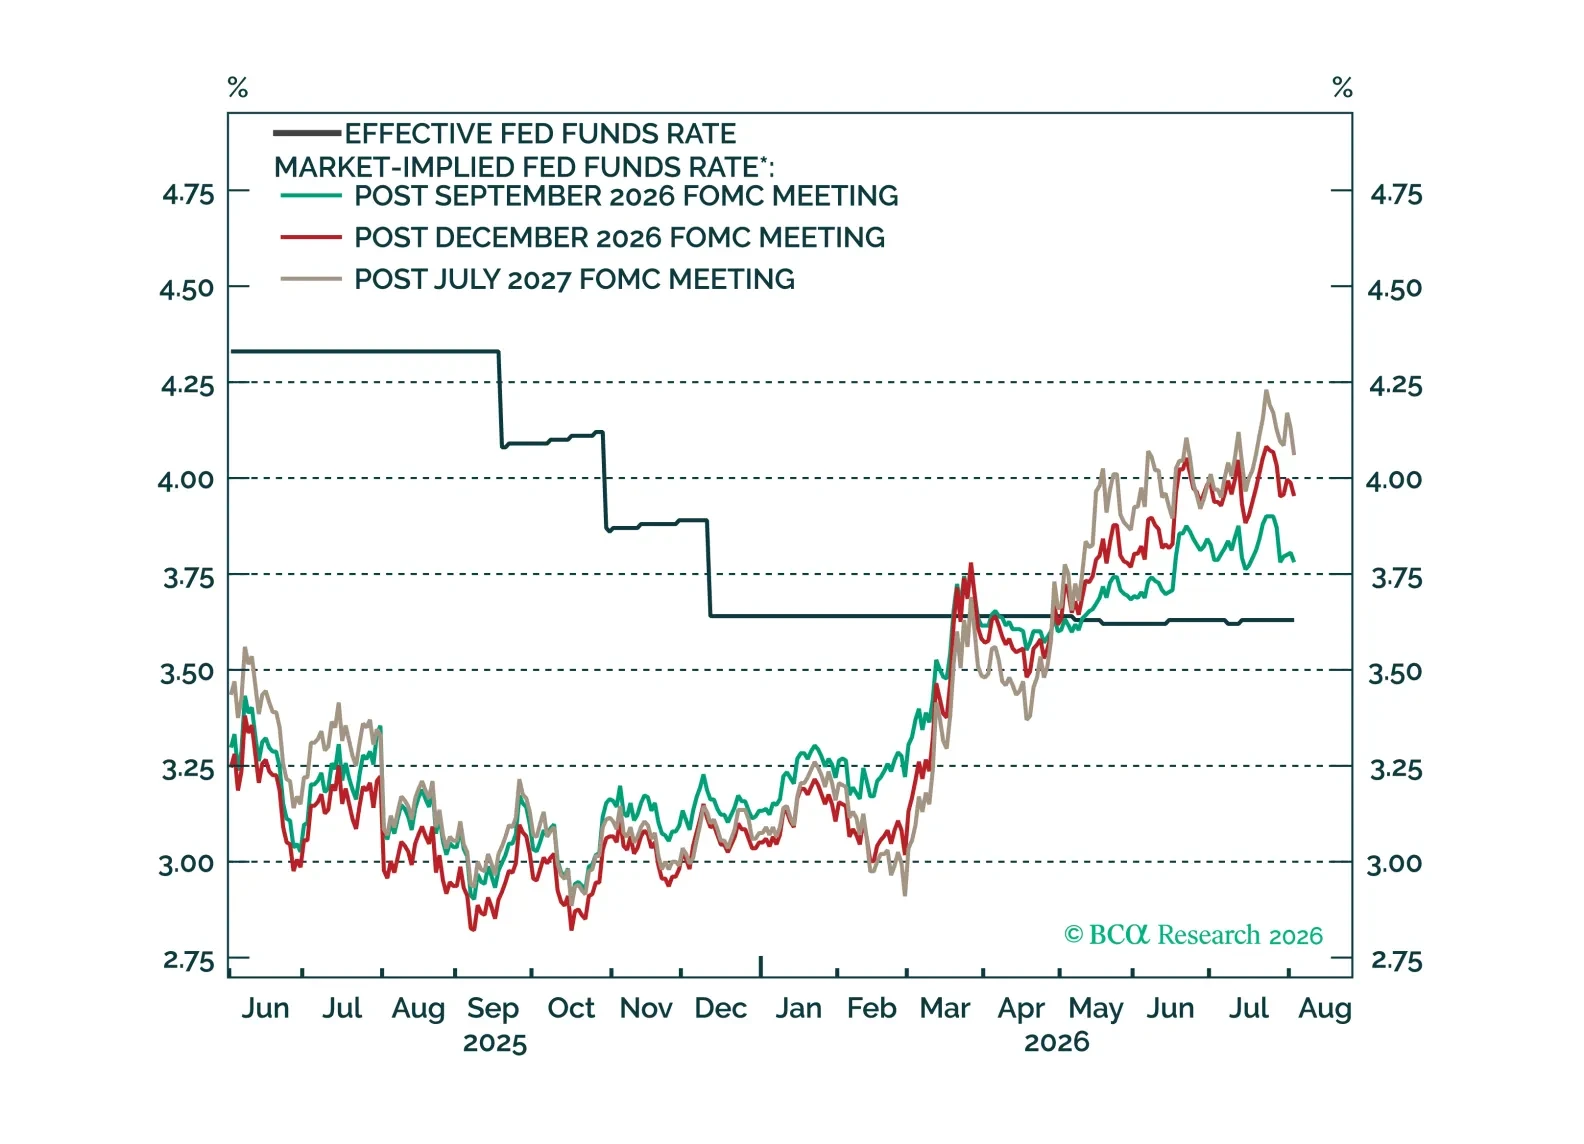
Inflation/Deflation
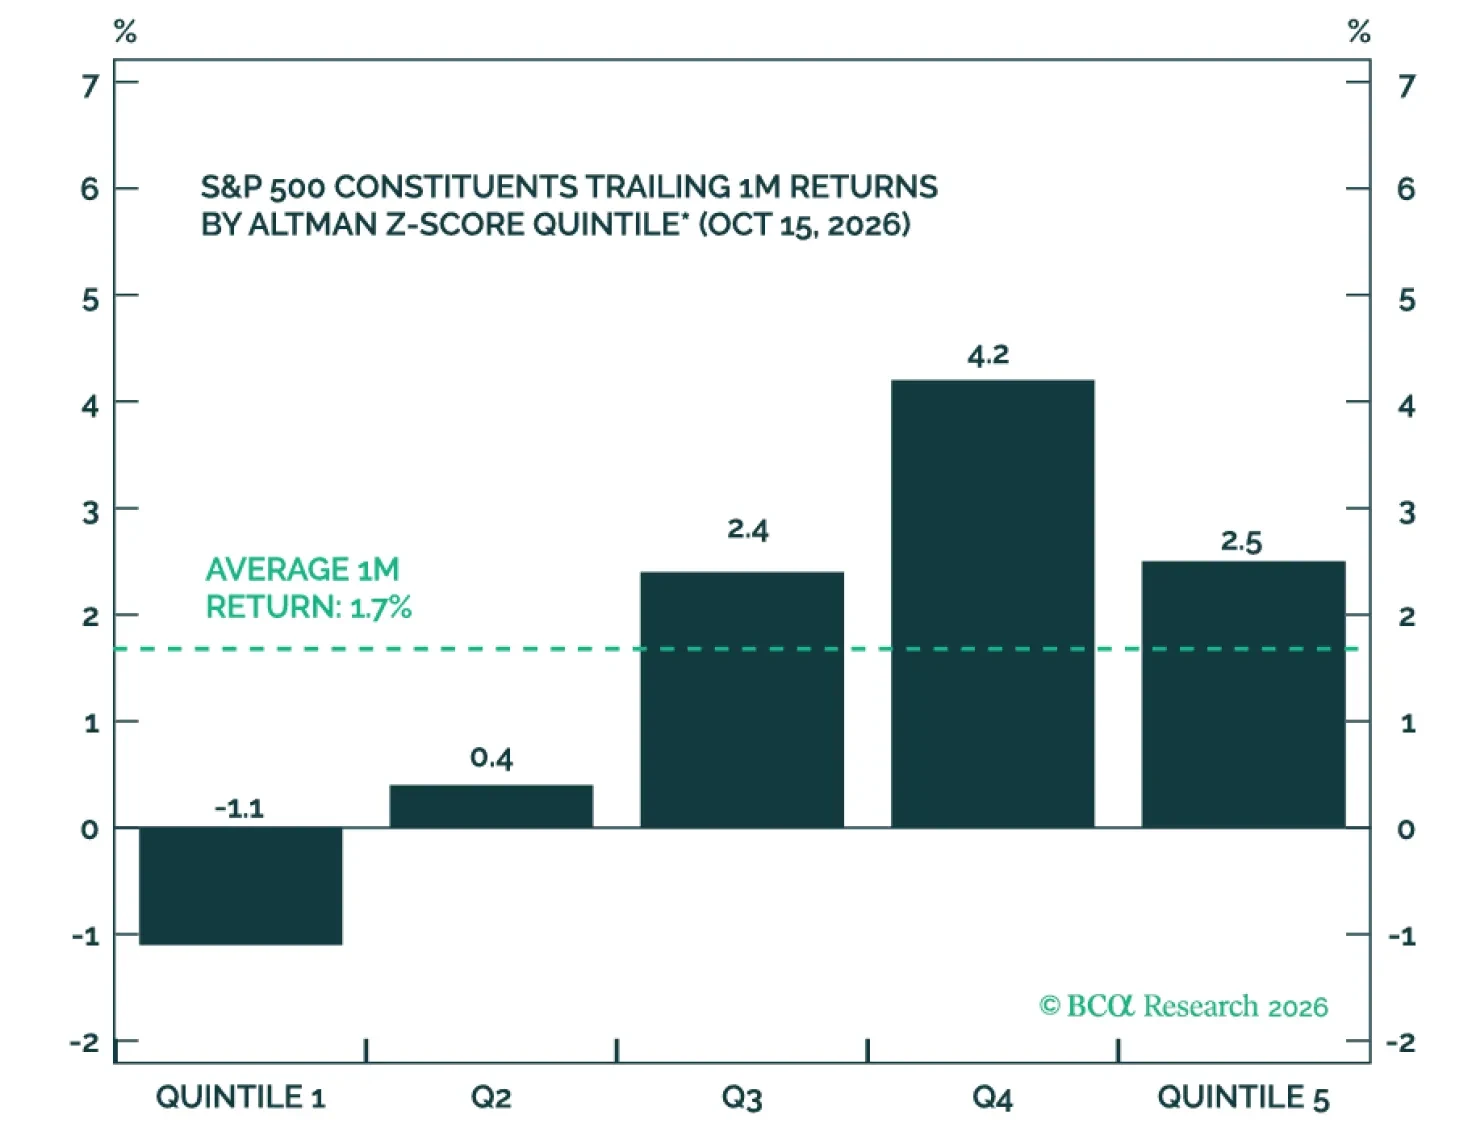
Credit spreads have widened as bond risks intensified, pressuring weak-balance-sheet companies. But the stress is narrow and valuations have already compressed, so equity risks look manageable. Rather than de-risk, we would lean into quality: large over small caps, quality capex, and defensible Tech margins, and look to Q3 earnings for confirmation.
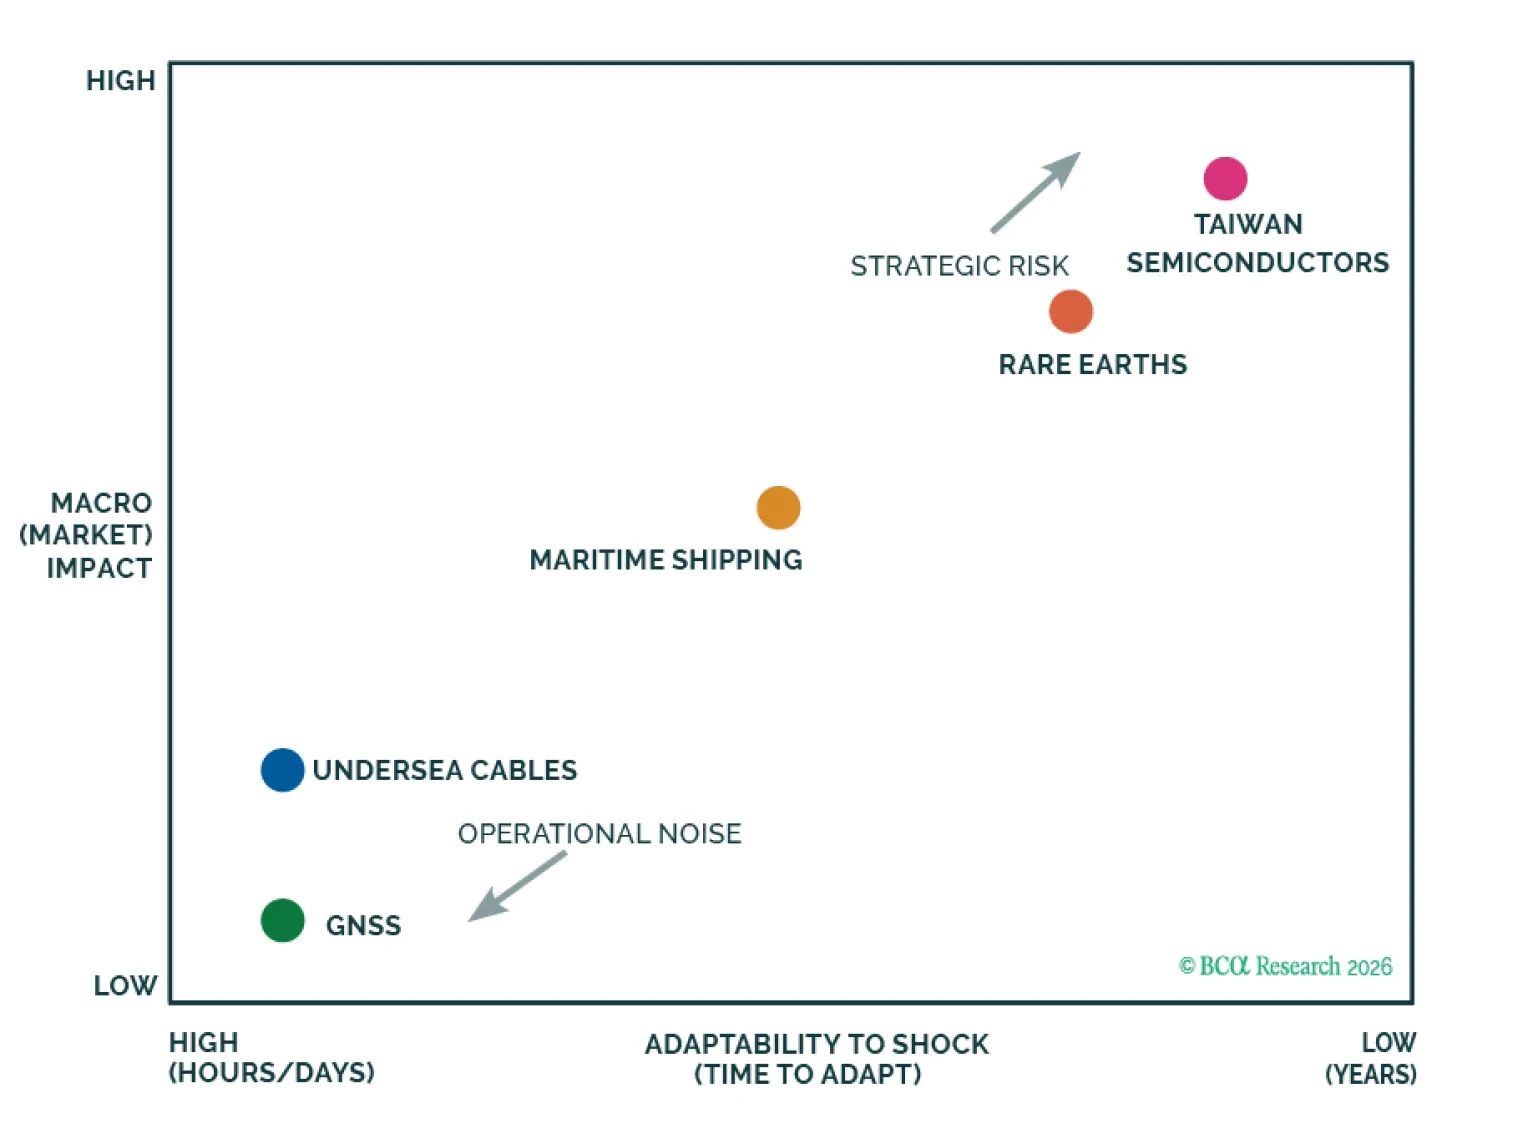
Not all chokepoints are equally dangerous. How we adapt to a shock is often underappreciated. Besides the ongoing Hormuz shock, investors should pay attention to Taiwanese chip production and Chinese rare earth minerals.
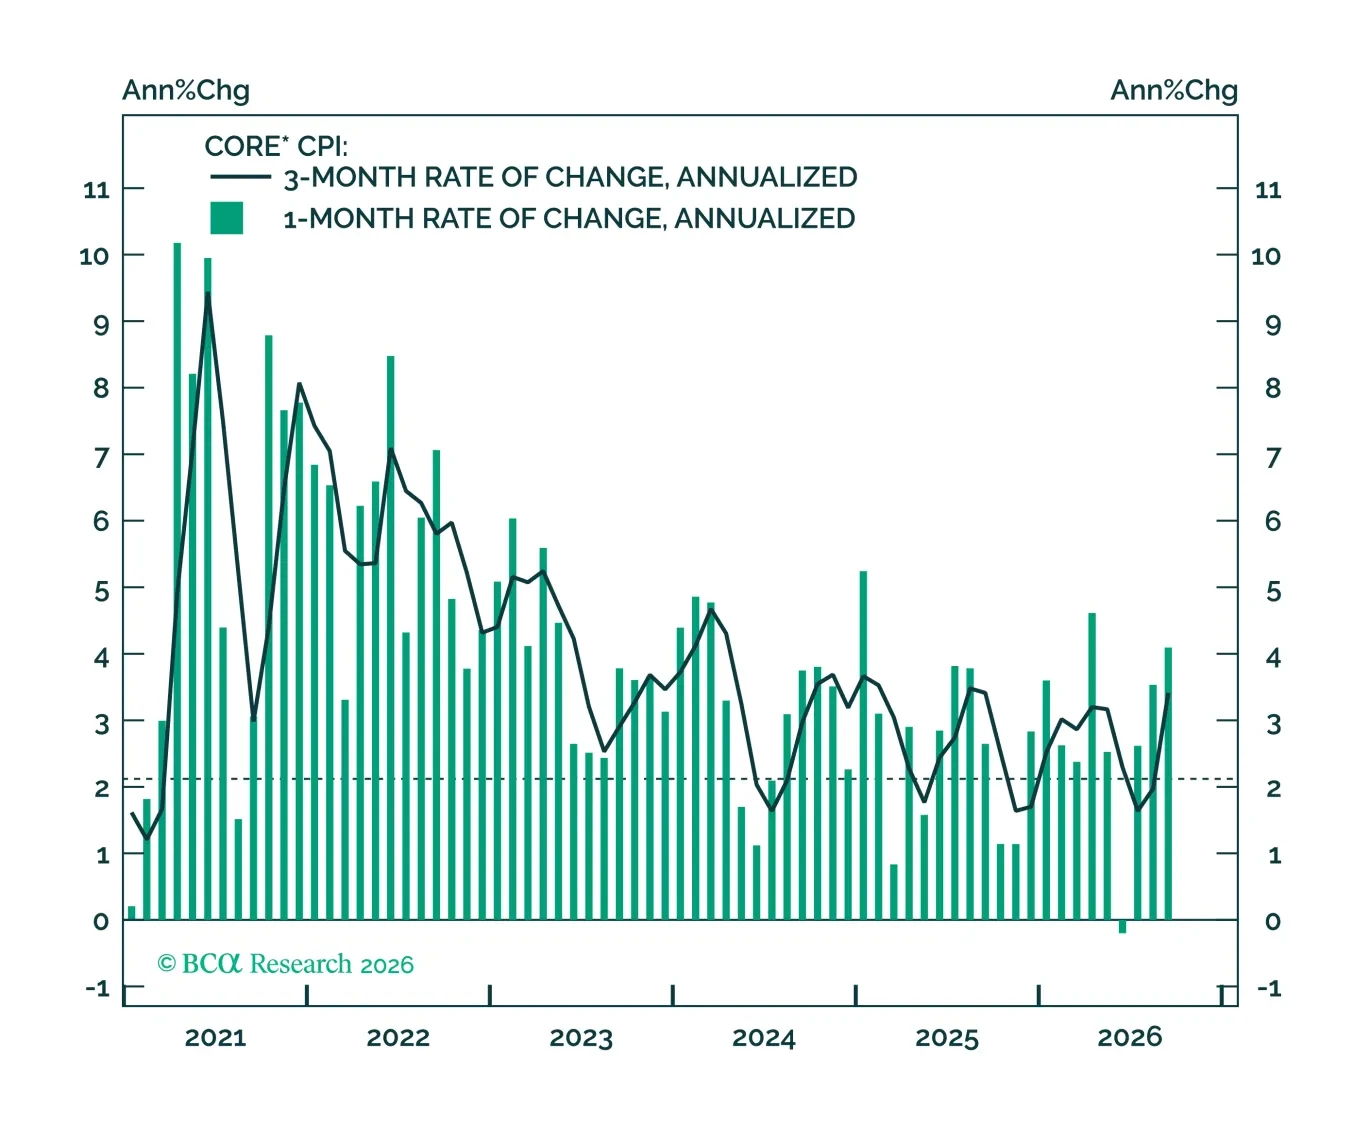
US inflation came in hot for the second consecutive month in September, though probably not hot enough for the Fed to move its next rate hike up to the October meeting.
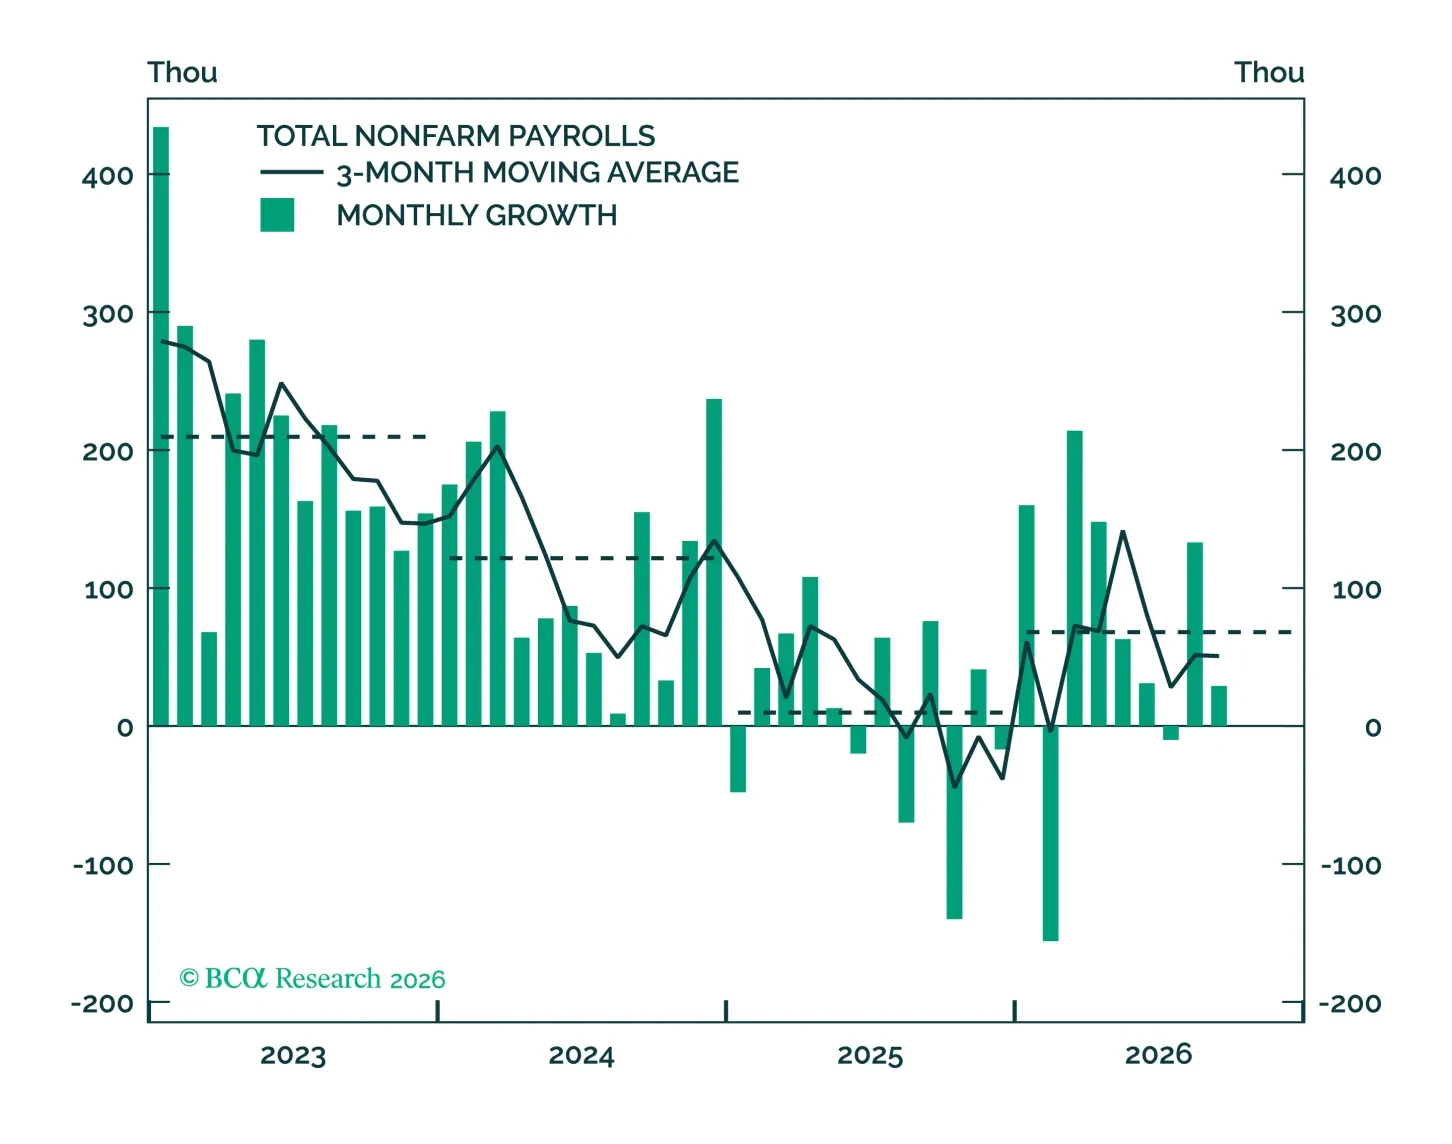
This morning’s jobs report serves to underscore that the labor market is not a source of inflationary pressure and therefore of second-order importance when it comes to the Fed’s near-term decision making.
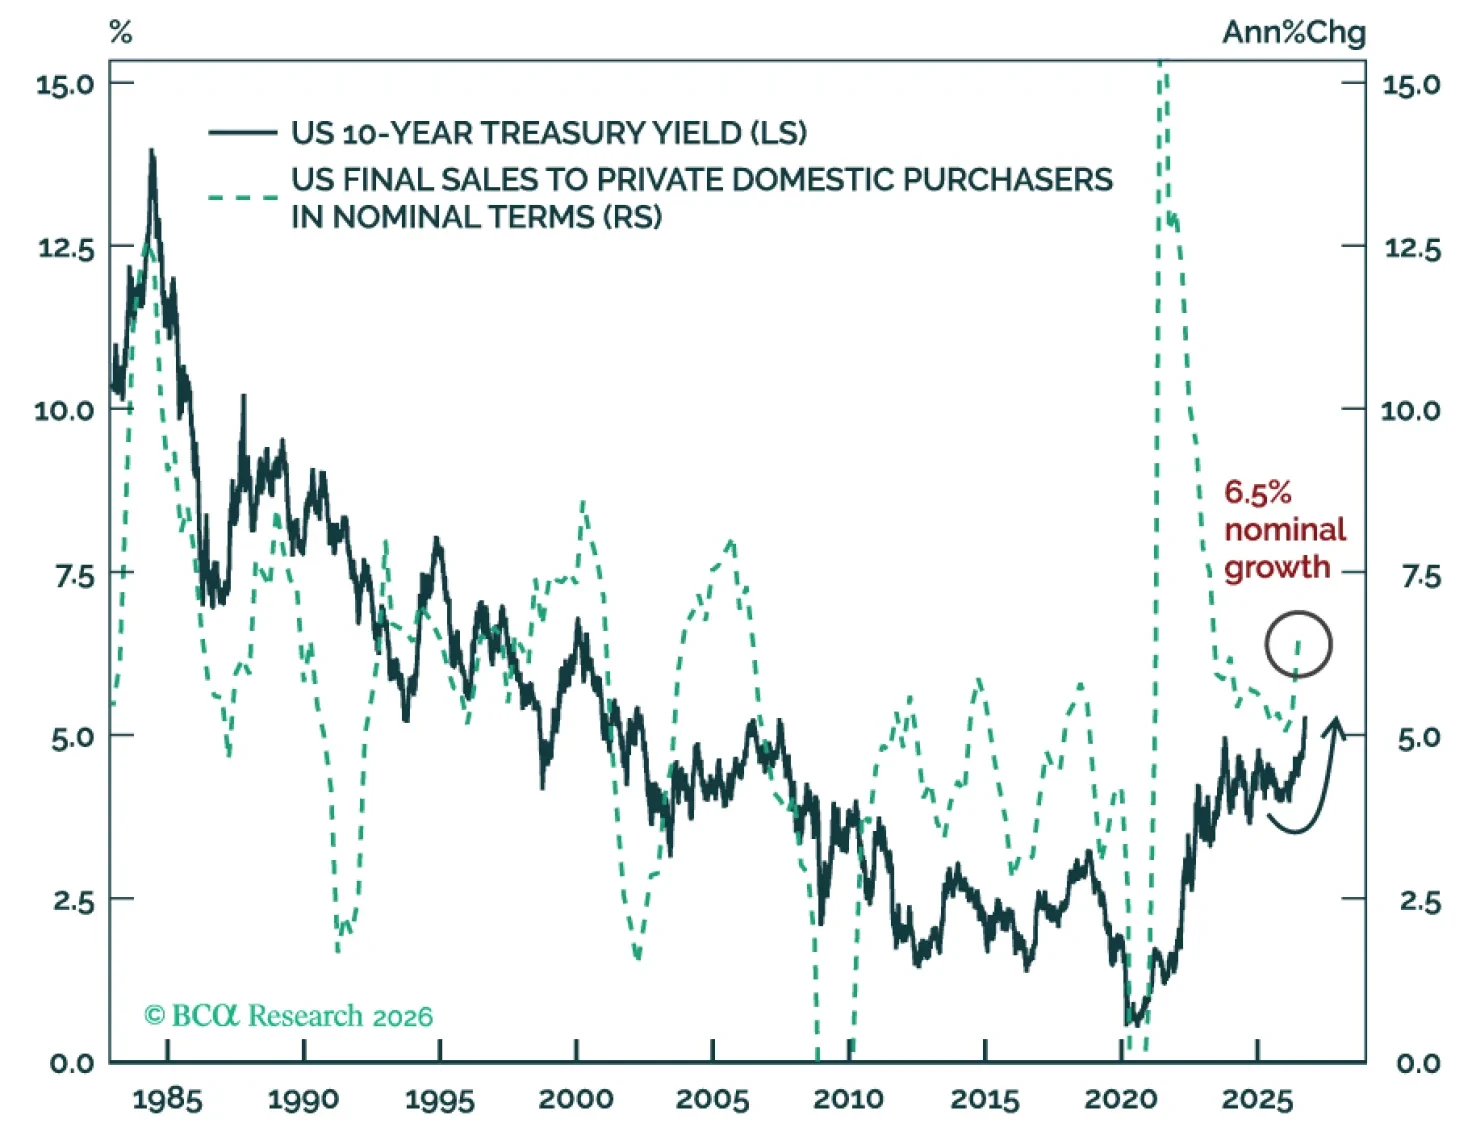
US bonds will likely continue selling off until tighter financial conditions – most plausibly a double-digit decline in the S&P 500 – cool nominal growth. Higher discount rates will threaten US equity valuations before earnings weaken. AI stocks will peak well ahead of AI capex. Remain downbeat on EM stocks.
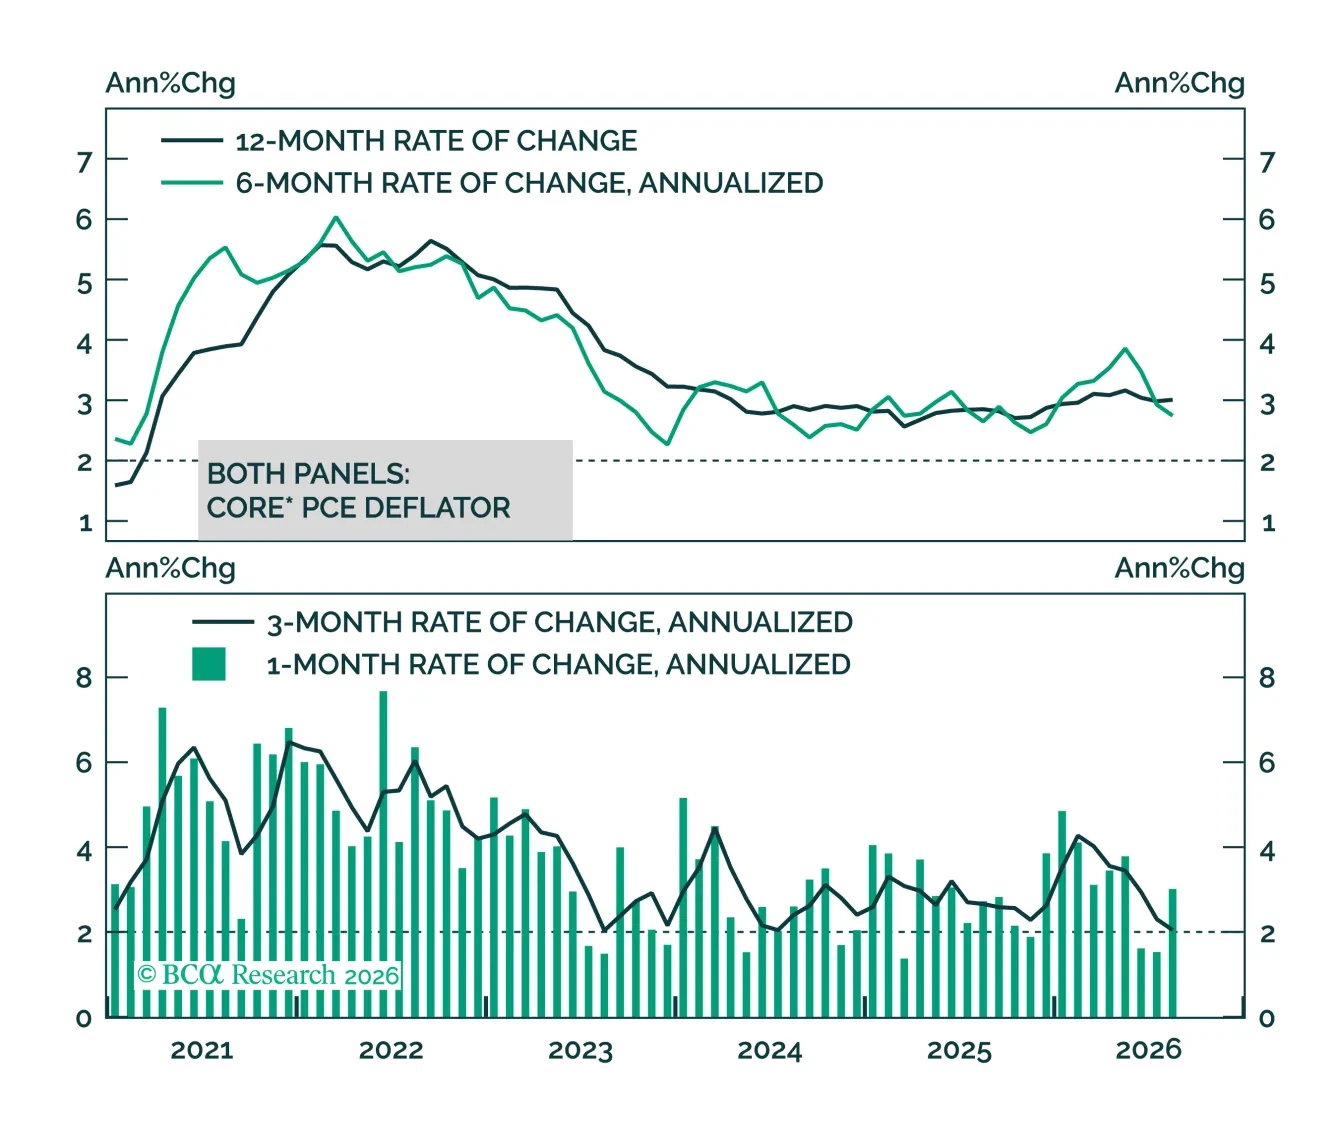
Core US inflation is still running above target. But this morning’s data revisions reveal that the gap is not nearly as large as it appeared yesterday.
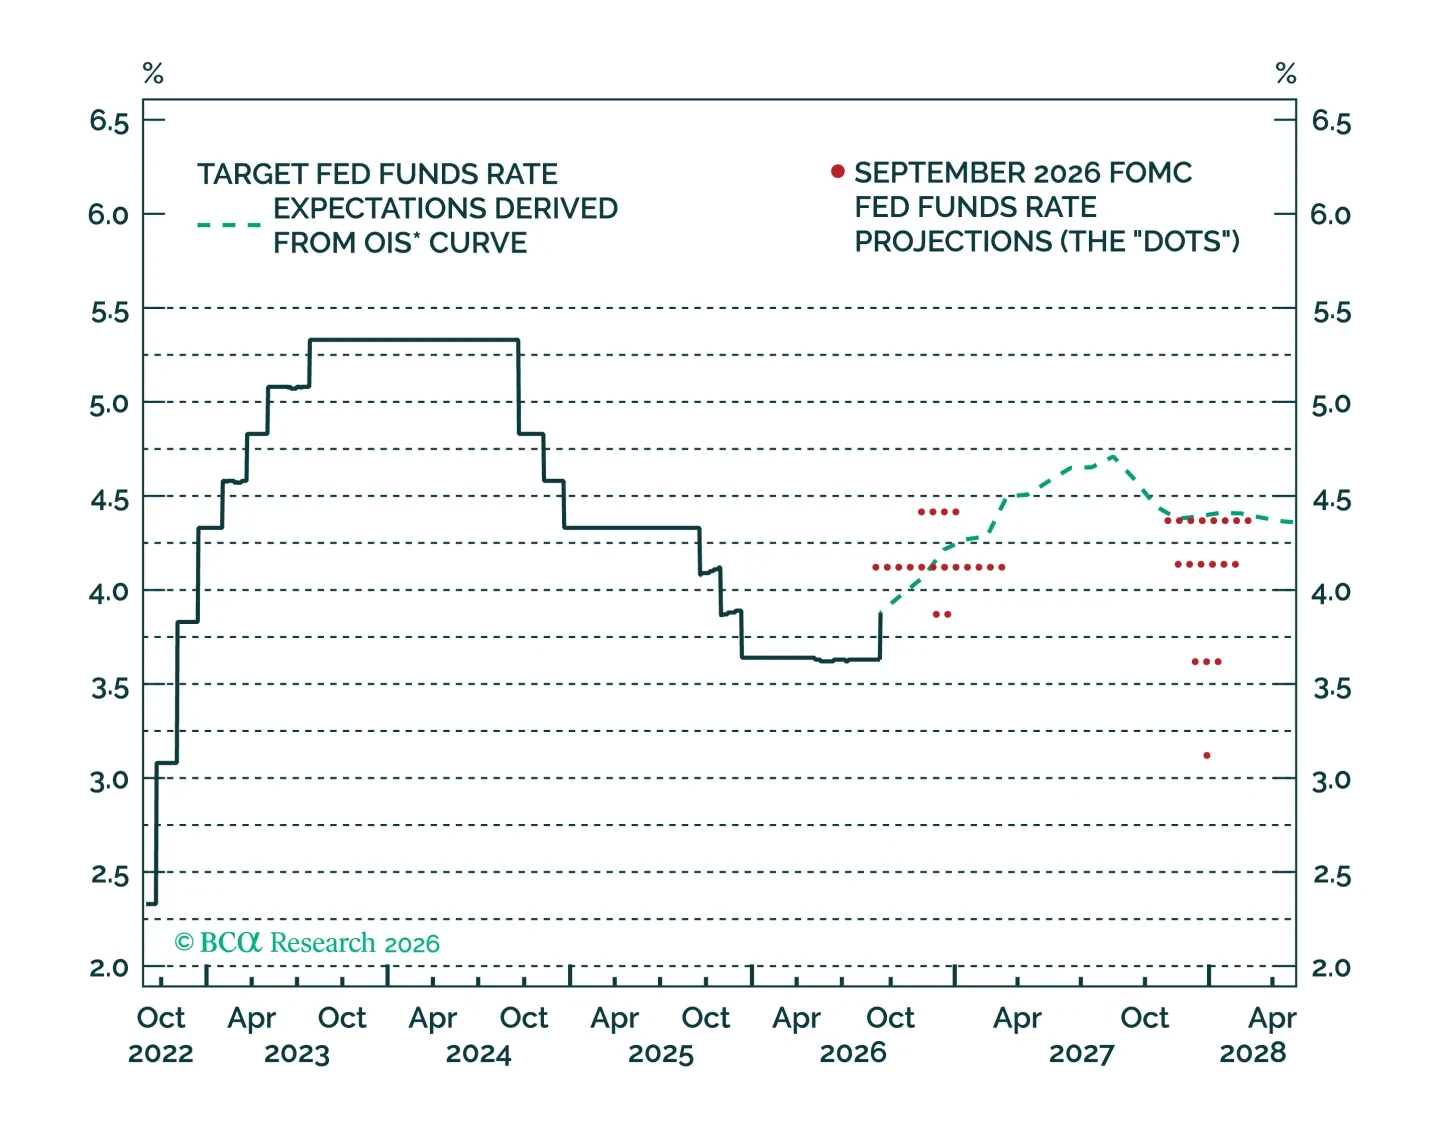
The Fed is unanimous in expecting a mild tightening cycle of no more than 75 bps, but that outcome is contingent on a rapid drop in core inflation in 2027.
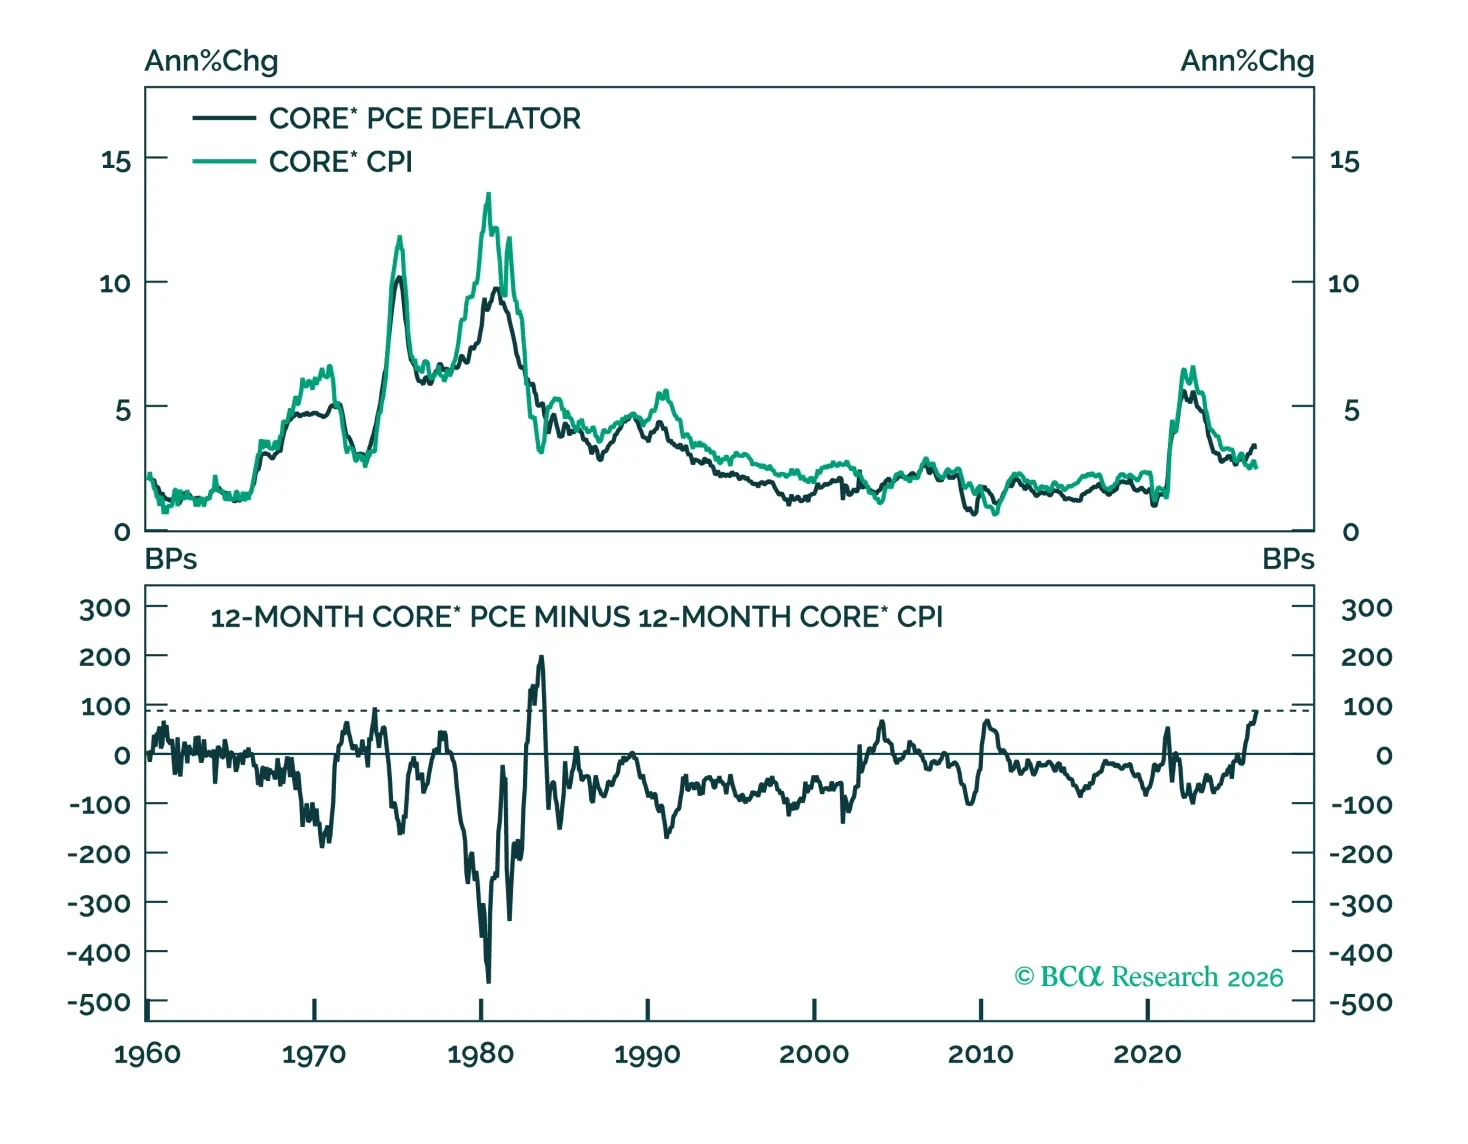
The PCE/CPI gap is an increasingly important factor driving the near-term outlook for Fed policy. We discuss the drivers of that gap and conclude that it’s likely to narrow in the coming months.
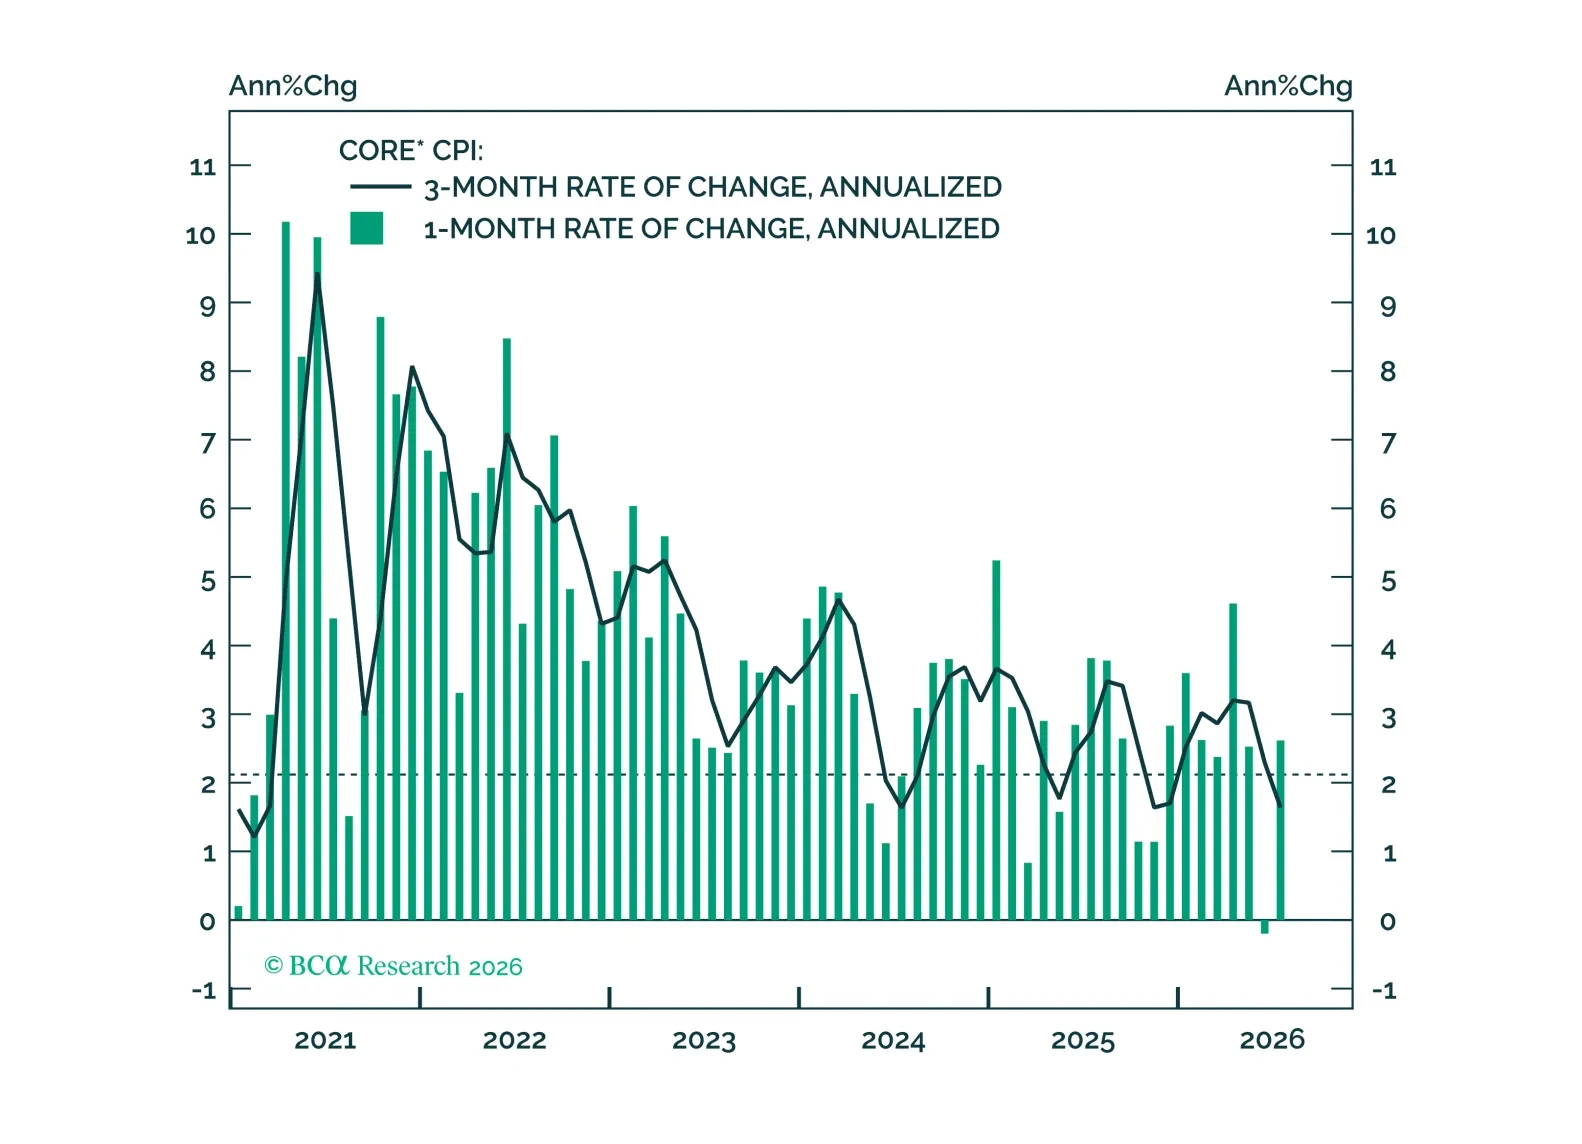
July’s CPI reading was low enough to keep the Fed on hold for now, but near-term upside inflation risks remain.