CoreMacro
| Global
Global macro research on the forces driving the world economy, with calls across stocks, bonds, and currencies.
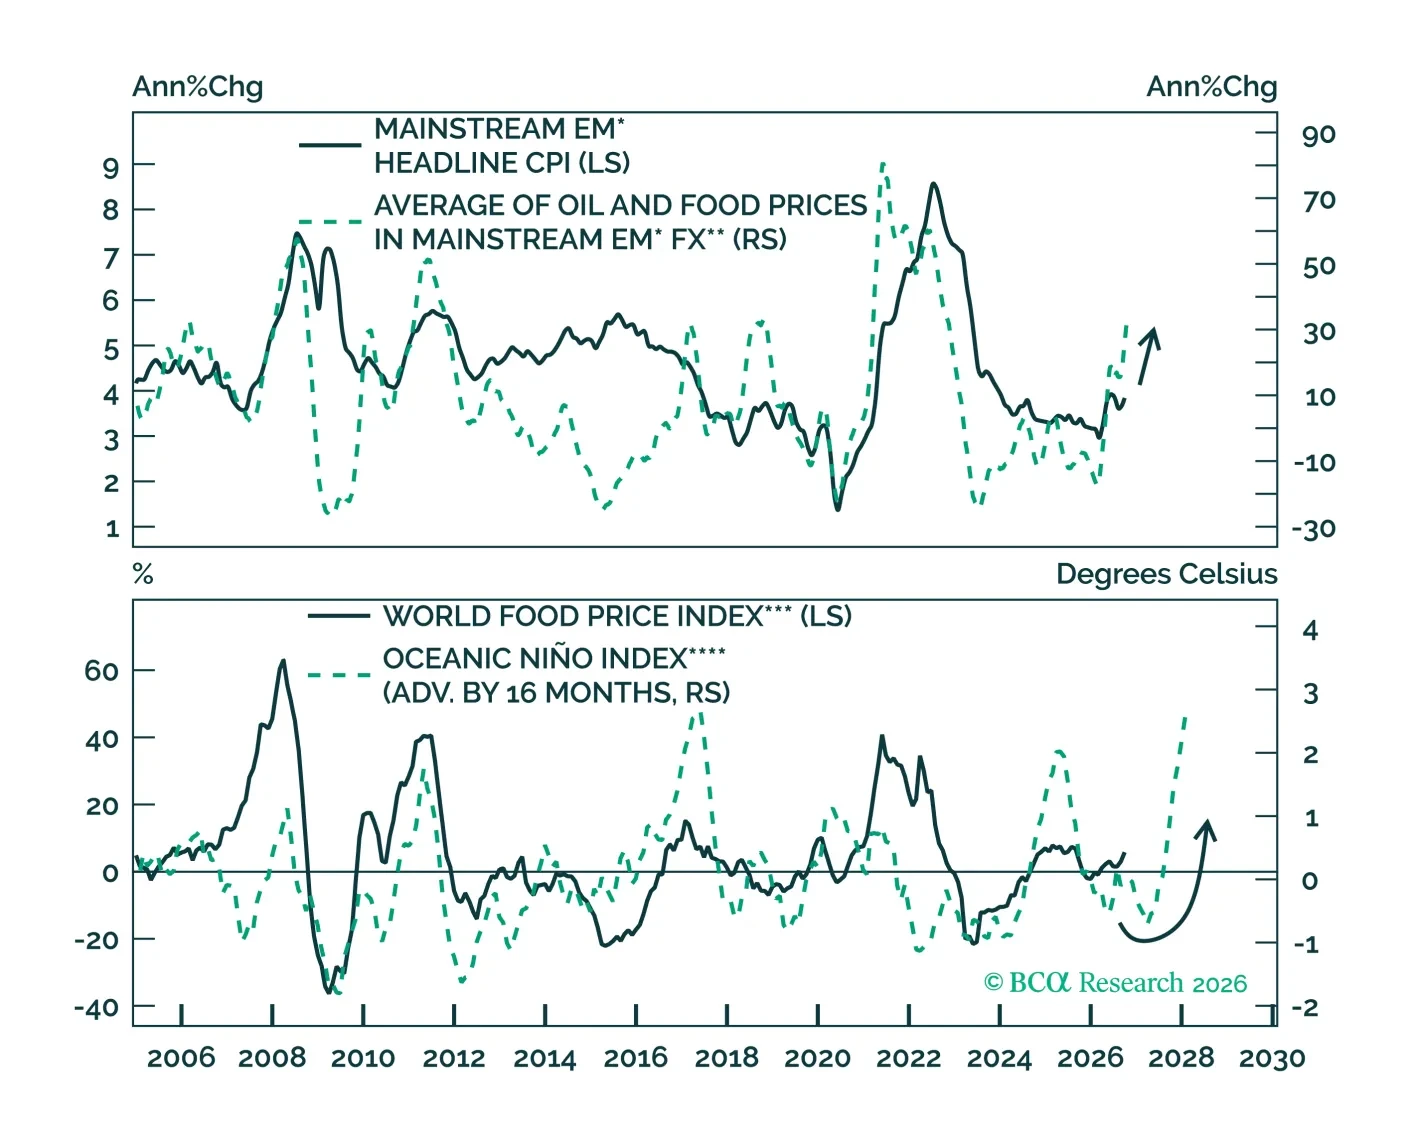
EM local bonds face near-term turbulence from rising inflation, global risk aversion, and currency weakness. Use the sell-off to build exposure: medium- and longer-term fundamentals remain favorable.
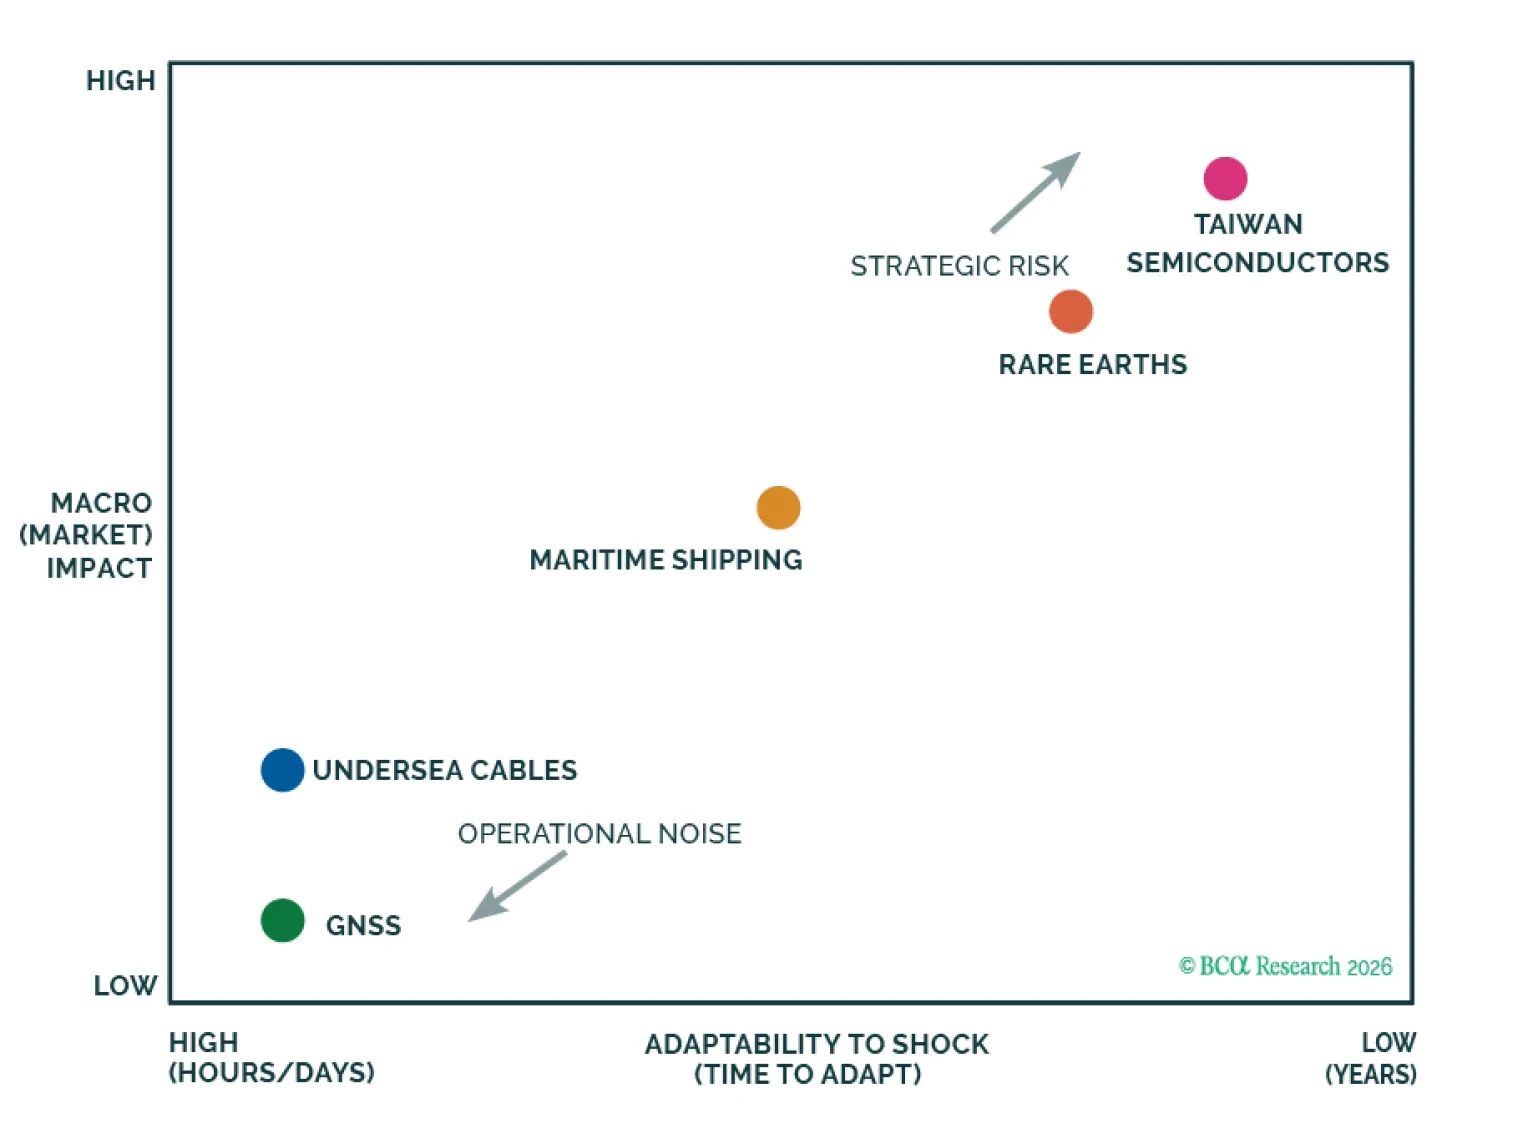
AI capex is supporting the global economy but also generating collateral damage for rate-sensitive sectors such as housing, as well as highly indebted governments. Maintain a benchmark allocation to equities for now and look to get more defensive next year.
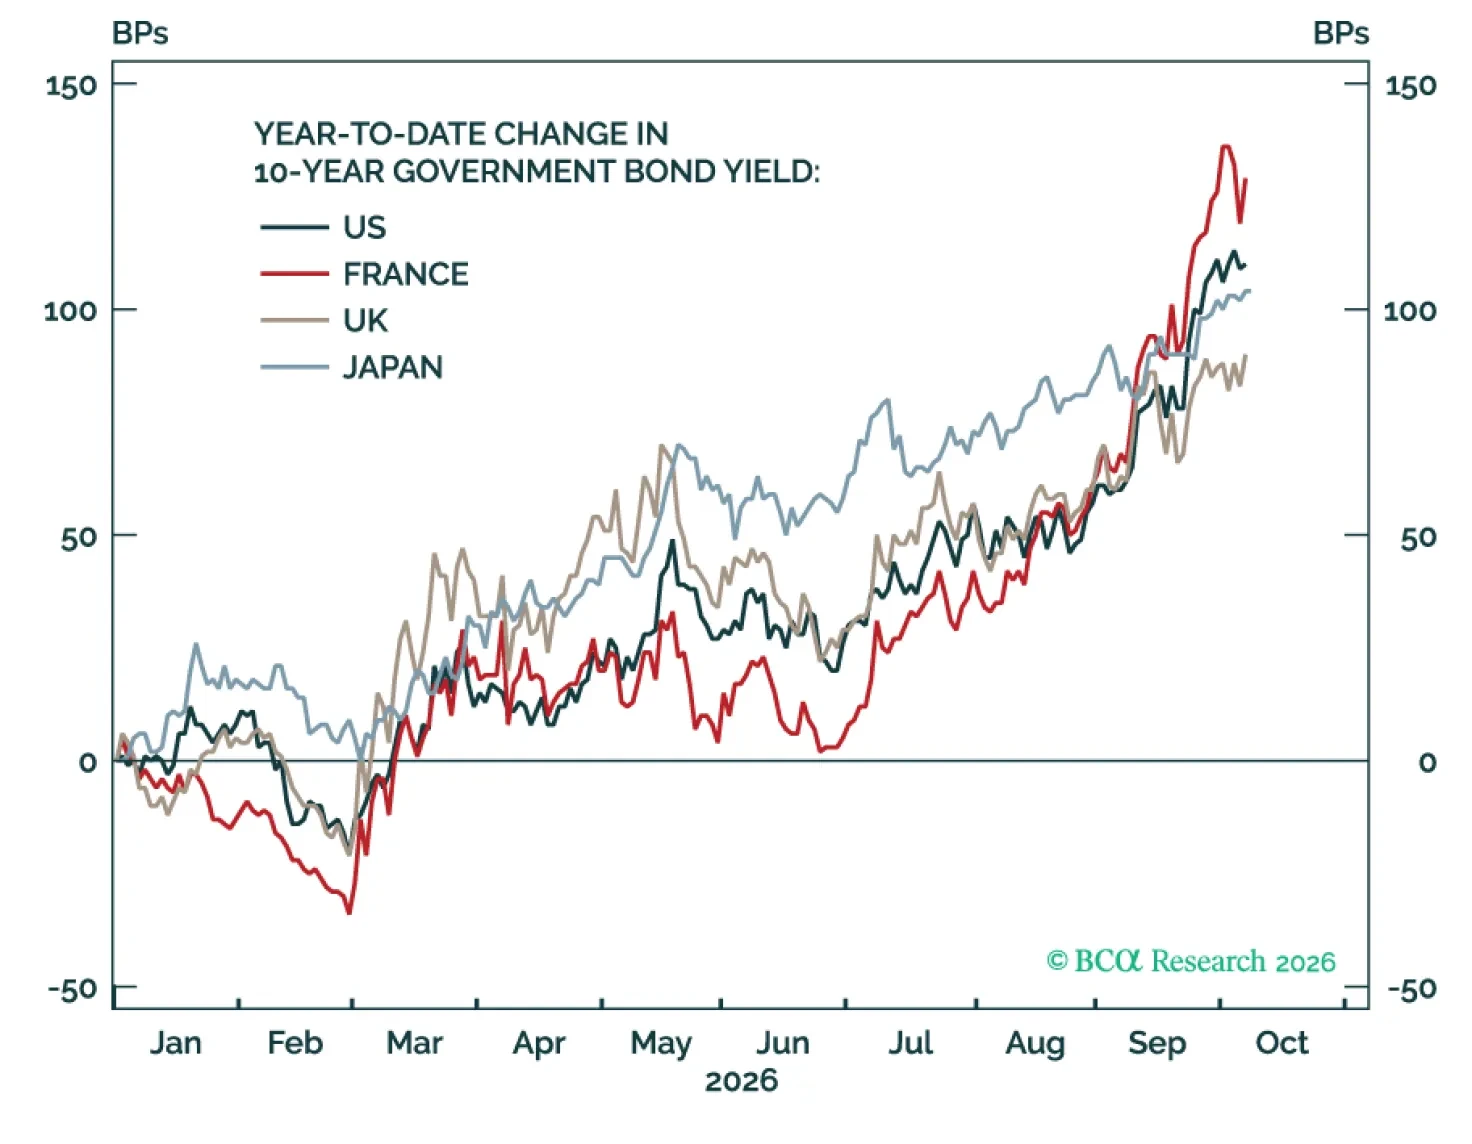
The global bond selloff is not over, but opportunities are emerging. US Treasuries and French OATs remain vulnerable to further selling, while other European government bonds look increasingly attractive. Investors should favor German Bunds and peripheral bonds, particularly on a currency-hedged basis.
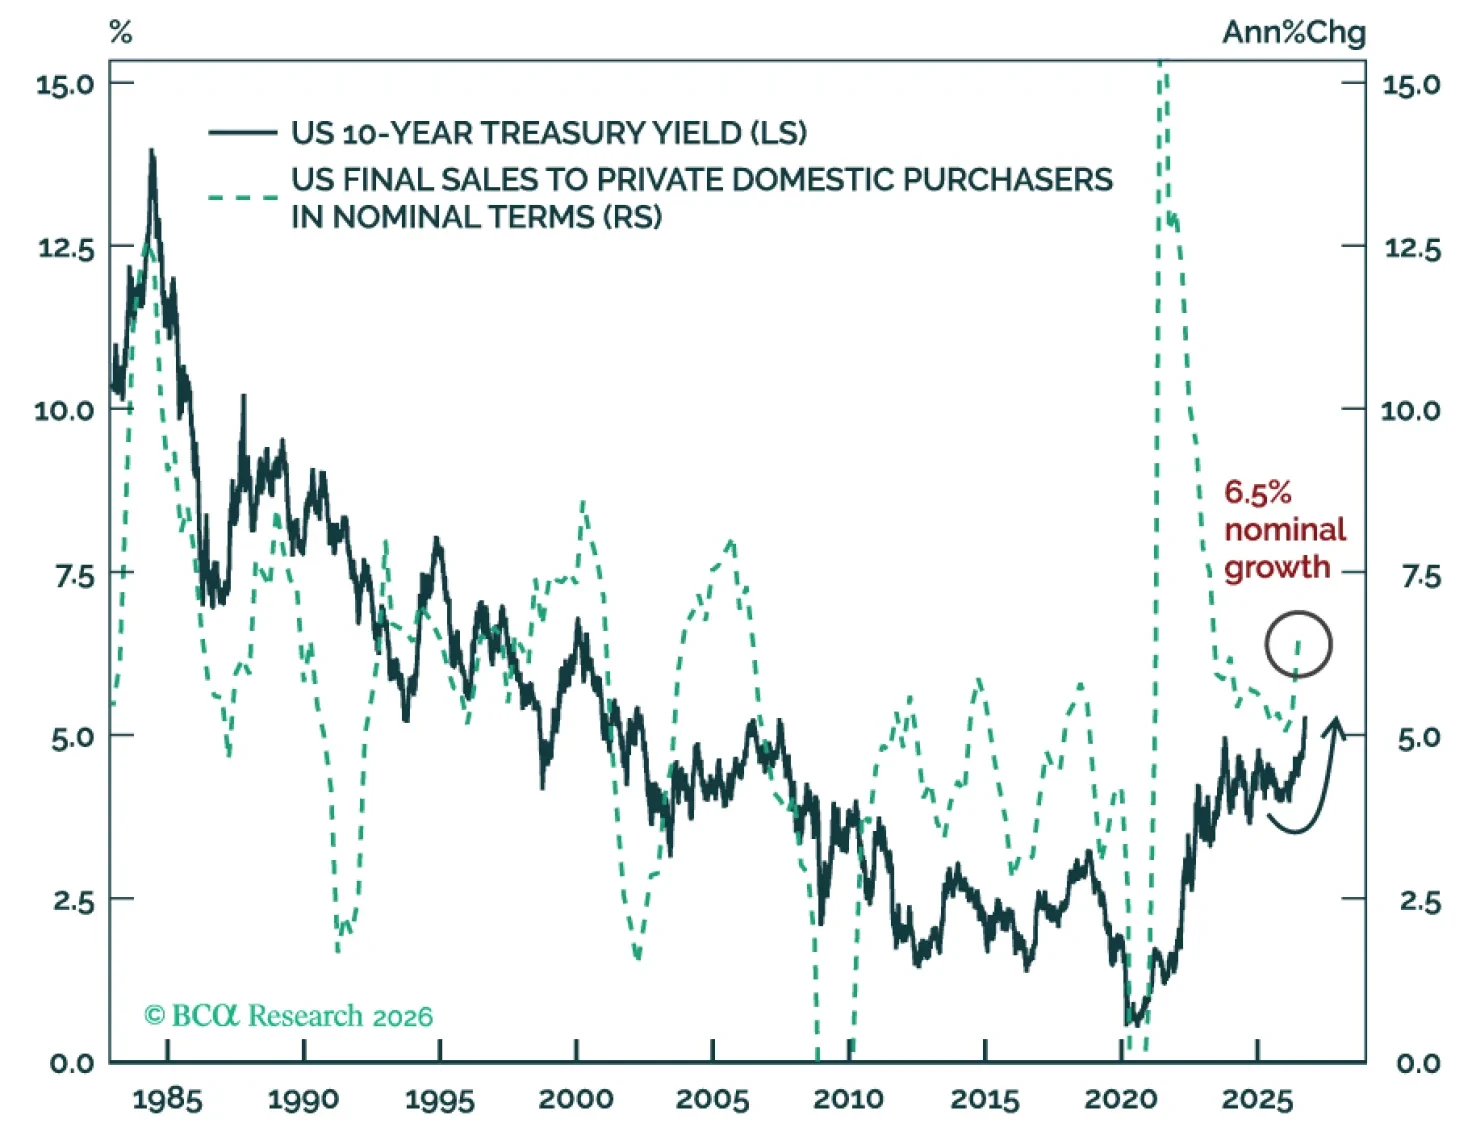
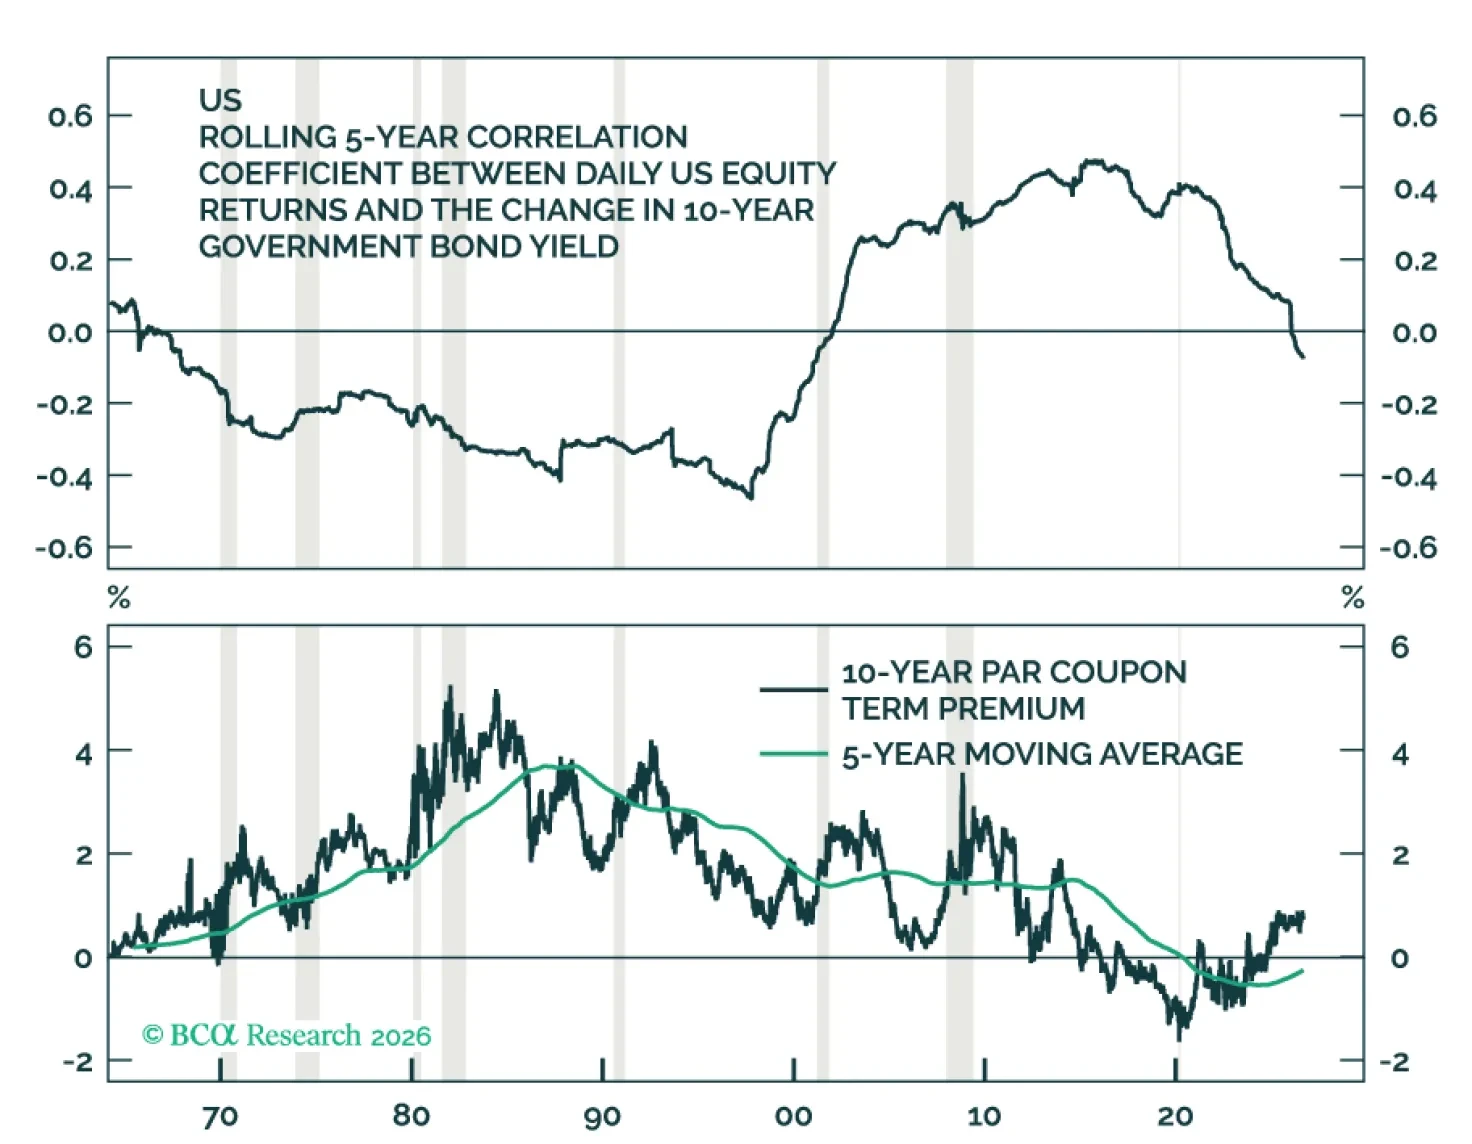
US bonds will likely continue selling off until tighter financial conditions – most plausibly a double-digit decline in the S&P 500 – cool nominal growth. Higher discount rates will threaten US equity valuations before earnings weaken. AI stocks will peak well ahead of AI capex. Remain downbeat on EM stocks.
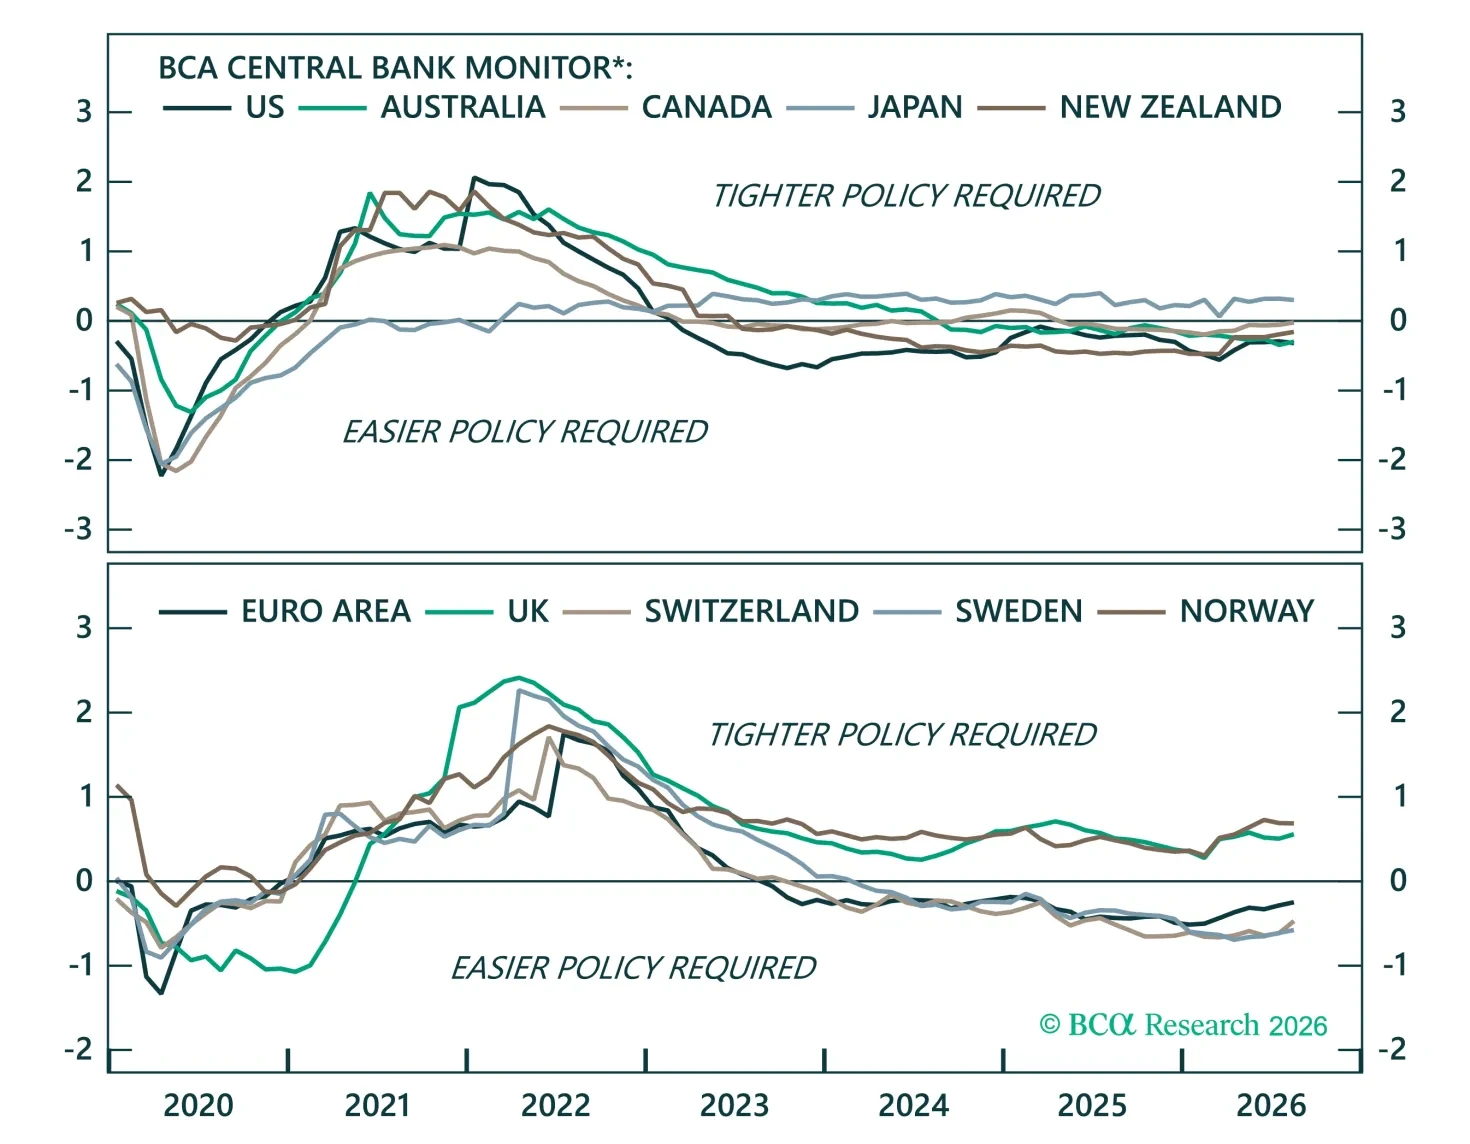
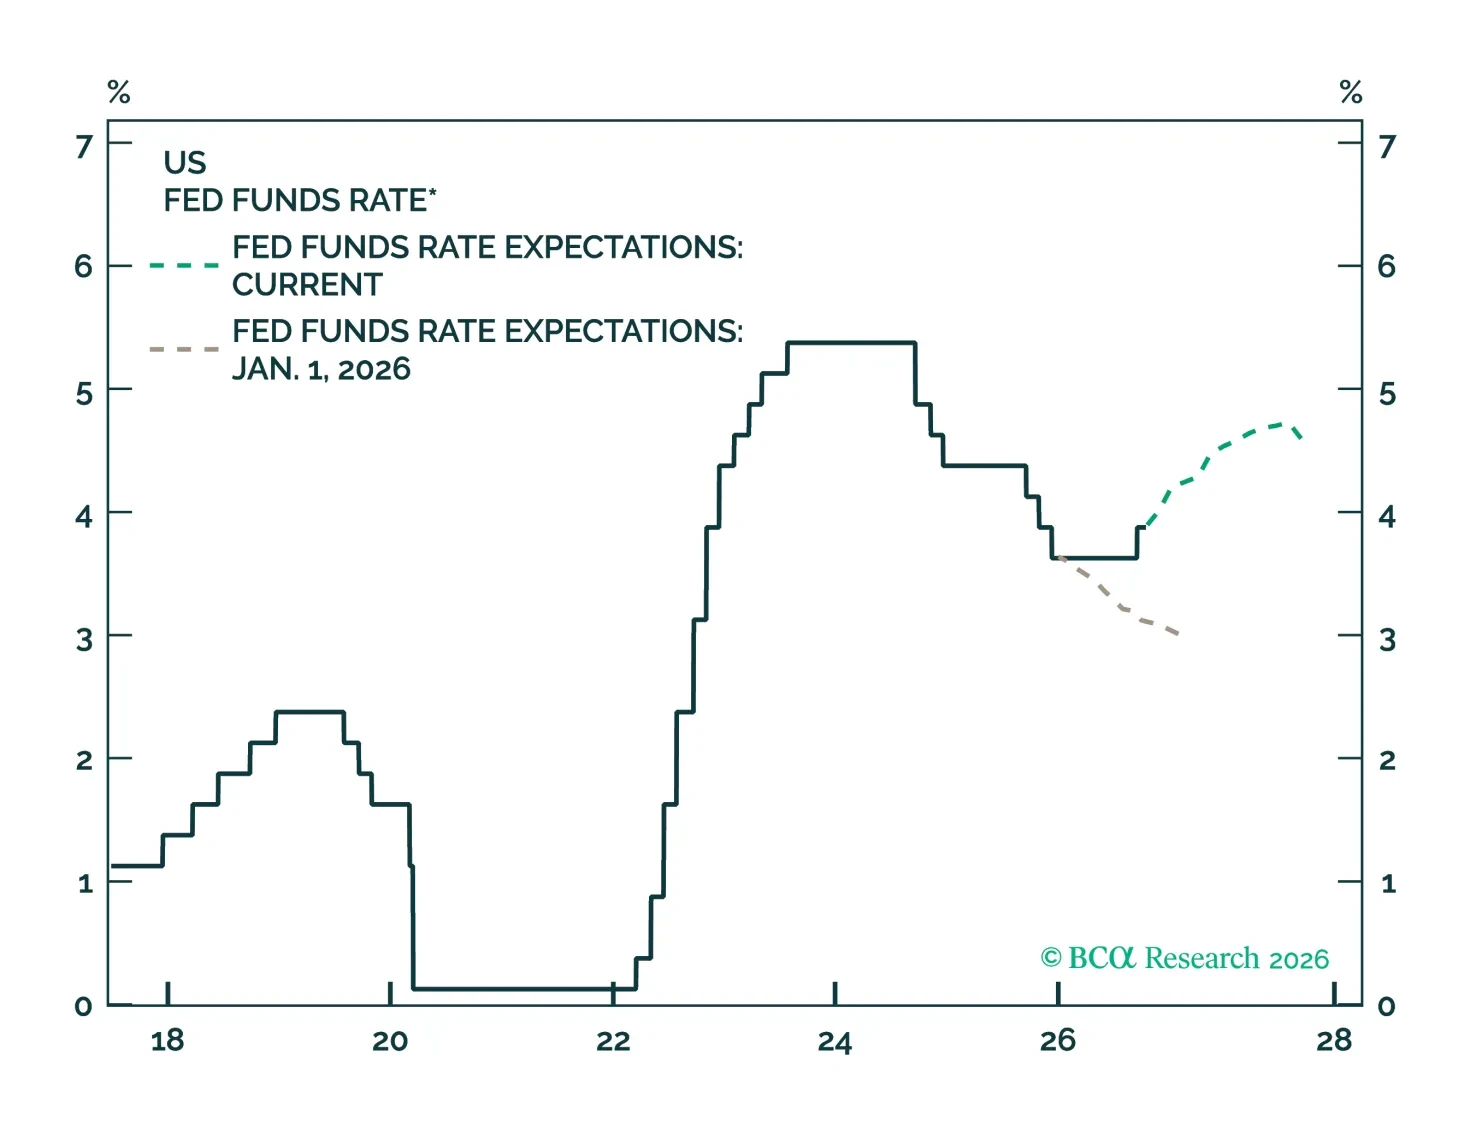
Central banks have begun a mild tightening cycle as elevated energy prices raise concerns about second-round inflation effects. We use BCA’s Central Bank Monitors to test whether hawkish market pricing is justified and identify tactical opportunities across global bond and currency markets.
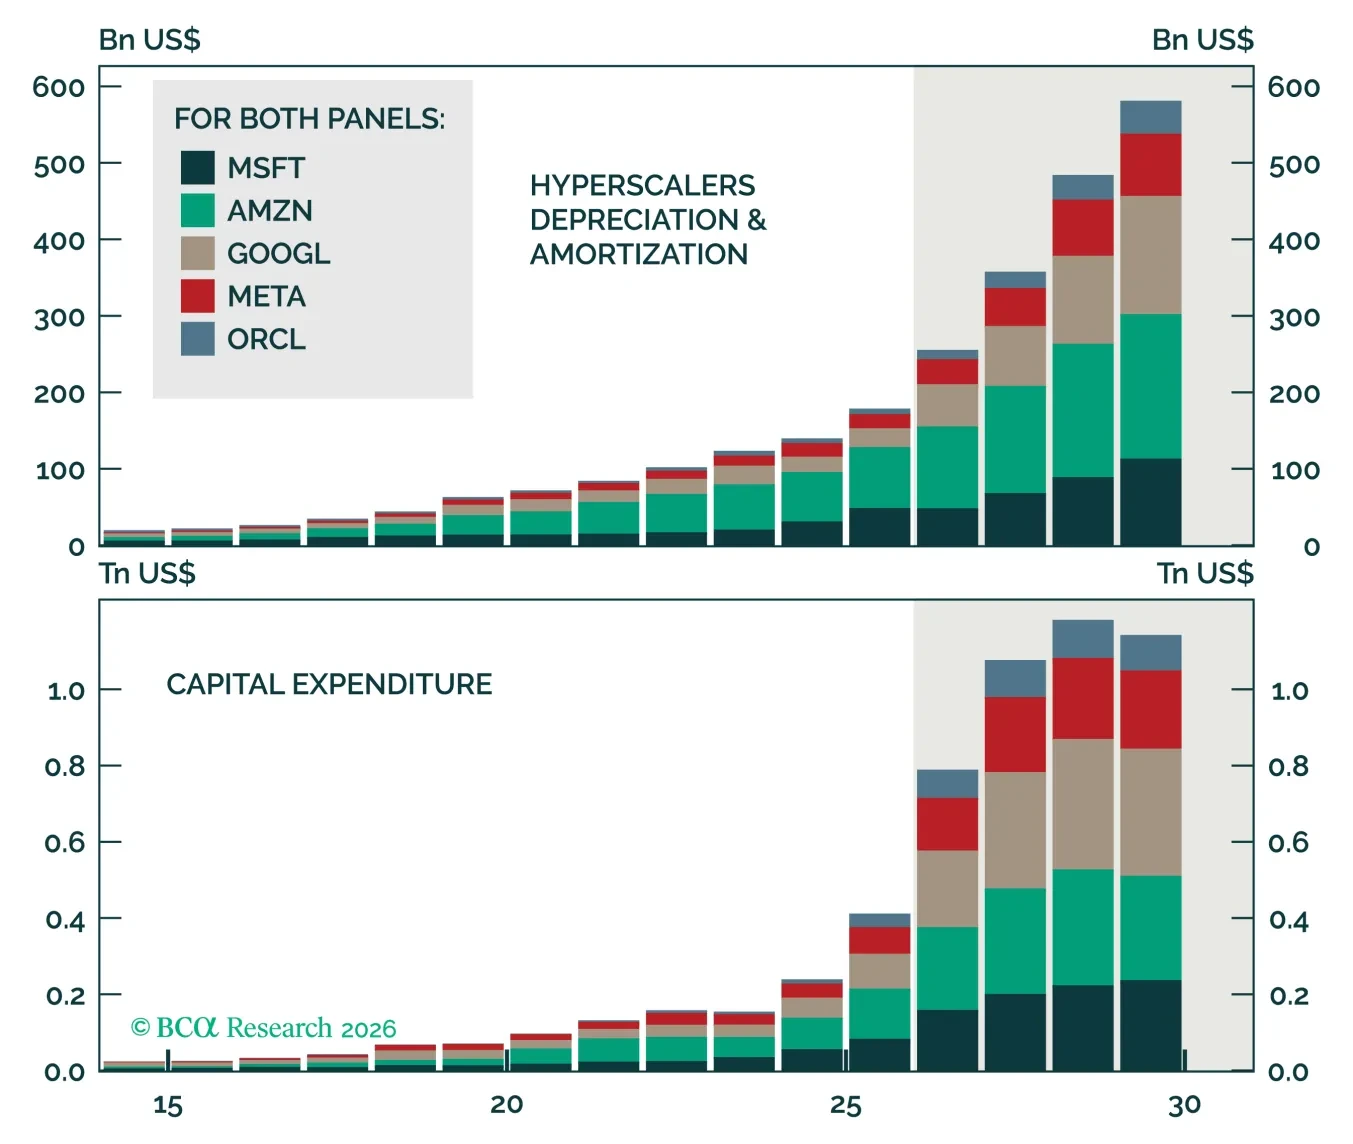
Concerns by the major AI companies that they are locked into a financially unsustainable arms race for AI dominance are likely playing as much a role in their newfound “go slow” approach as concerns over AI doom.
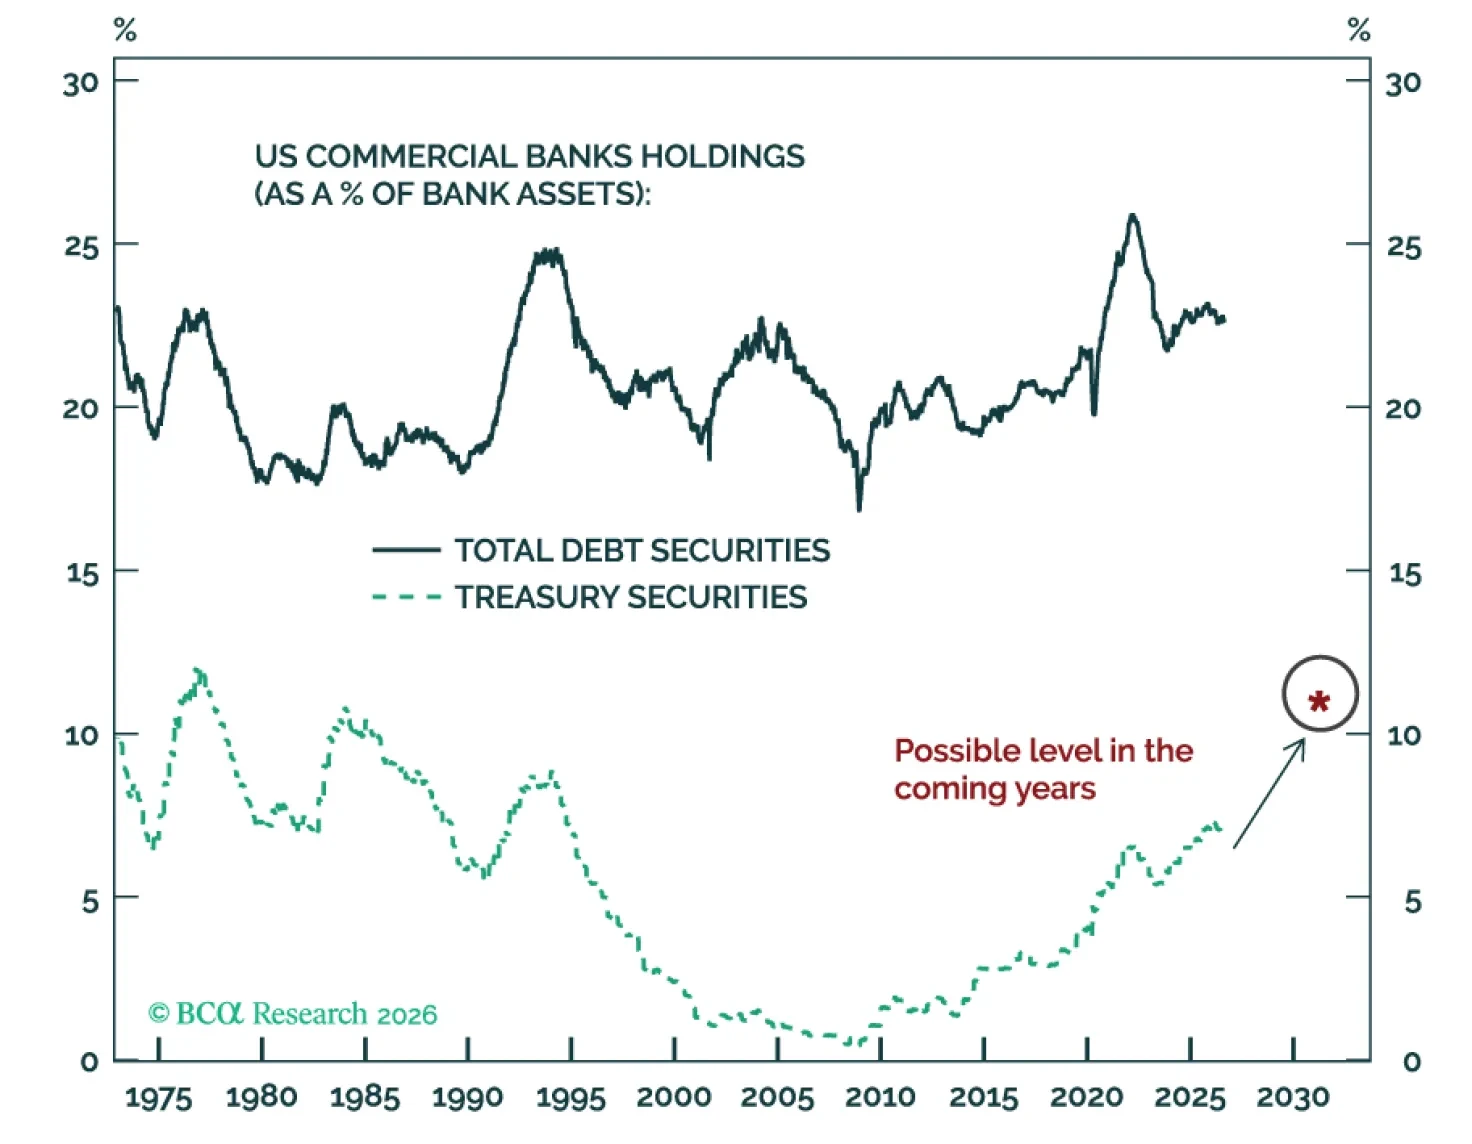
Scott Bessent’s attempts to suppress yields while financing large twin deficits risk crashing foreign inflows, the dollar, US bonds, and equities. Without a major equity selloff or large-scale commercial bank purchases of Treasurys, the bond selloff will persist – producing a major equity drawdown and a lower dollar.