 Explore CoreMacro
CoreMacro | Emerging Markets
Emerging Markets research - including in-depth country reports. Typically published four times a month.
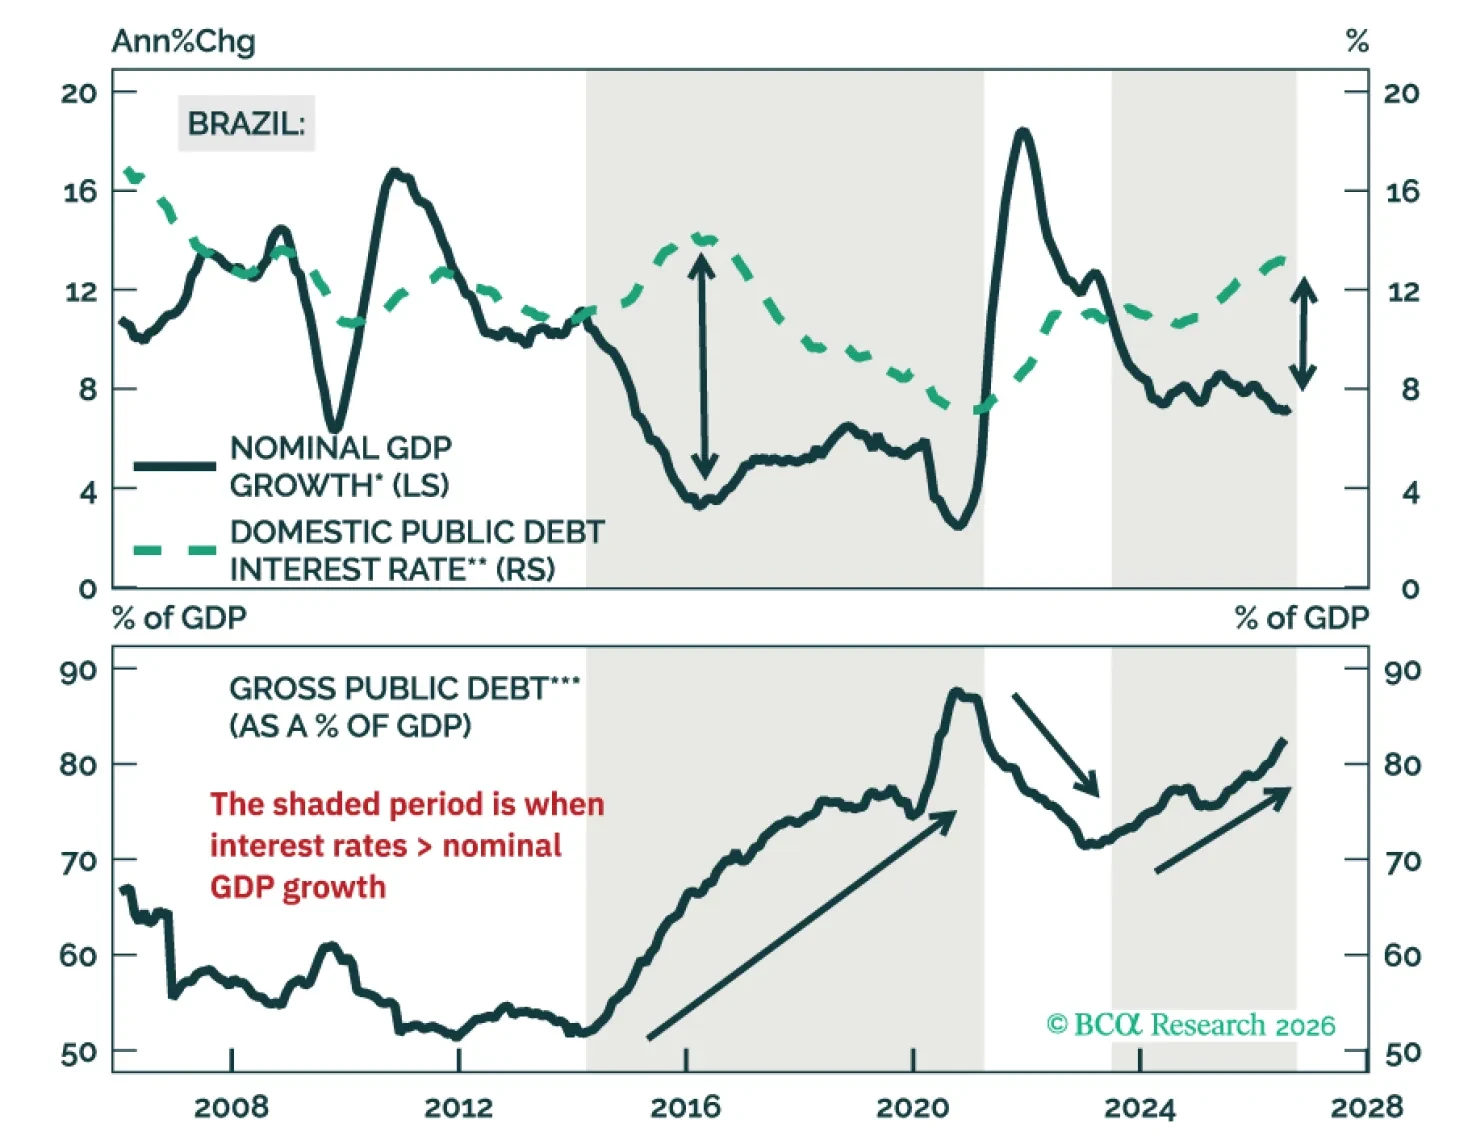
The most bullish development for Brazil from the weekend’s elections was not the higher odds of a right-wing presidency, but the likely president’s (Flávio Bolsonaro) stronghold in Congress. Upgrade Brazilian fixed-income markets to overweight and equities to neutral within their respective EM portfolios.
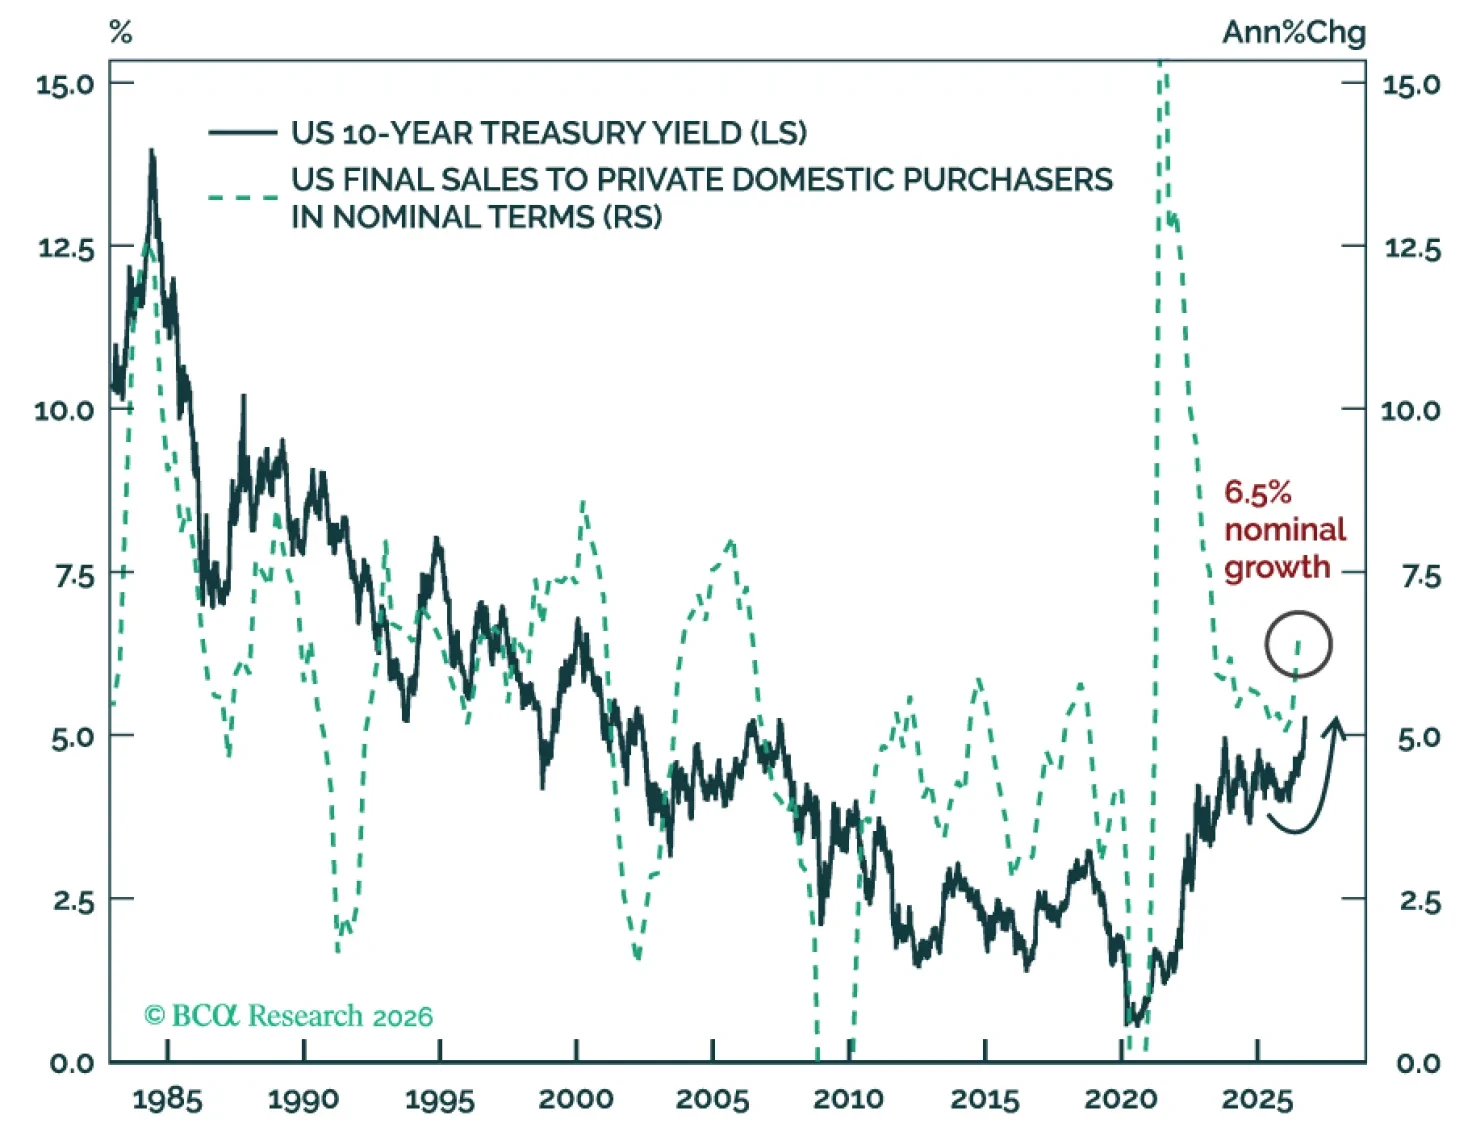
US bonds will likely continue selling off until tighter financial conditions – most plausibly a double-digit decline in the S&P 500 – cool nominal growth. Higher discount rates will threaten US equity valuations before earnings weaken. AI stocks will peak well ahead of AI capex. Remain downbeat on EM stocks.
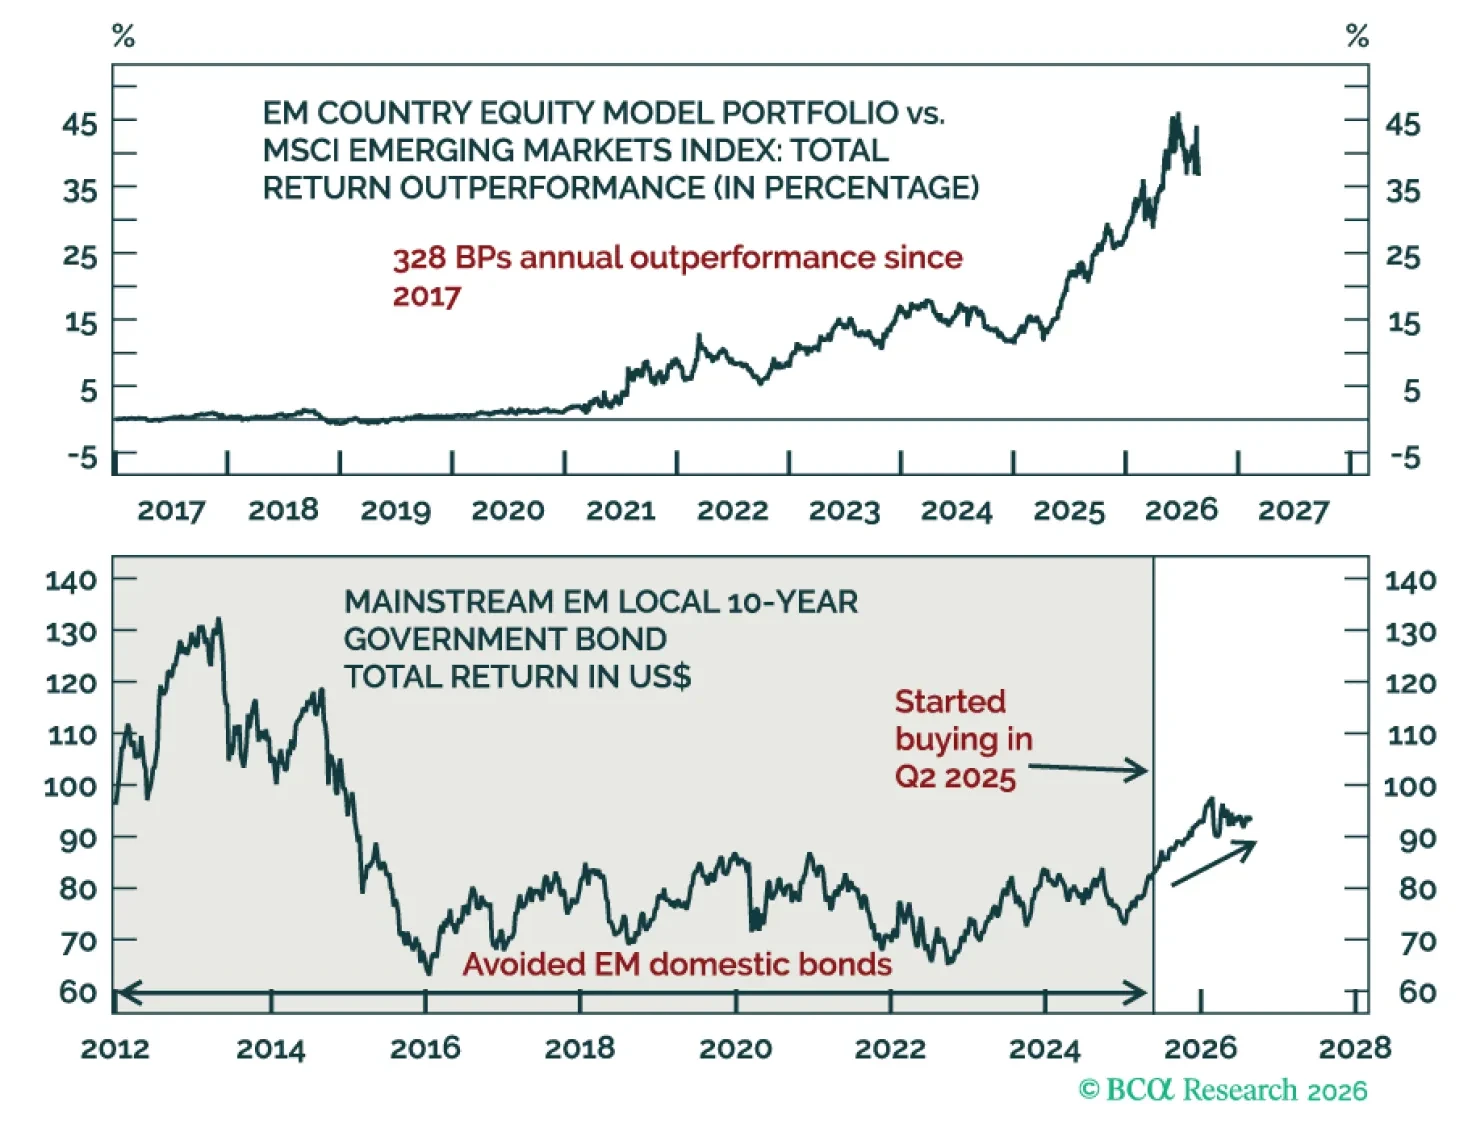
We review the track record of our broader investment strategy and individual calls. We also use this opportunity to close several positions that have become stale.
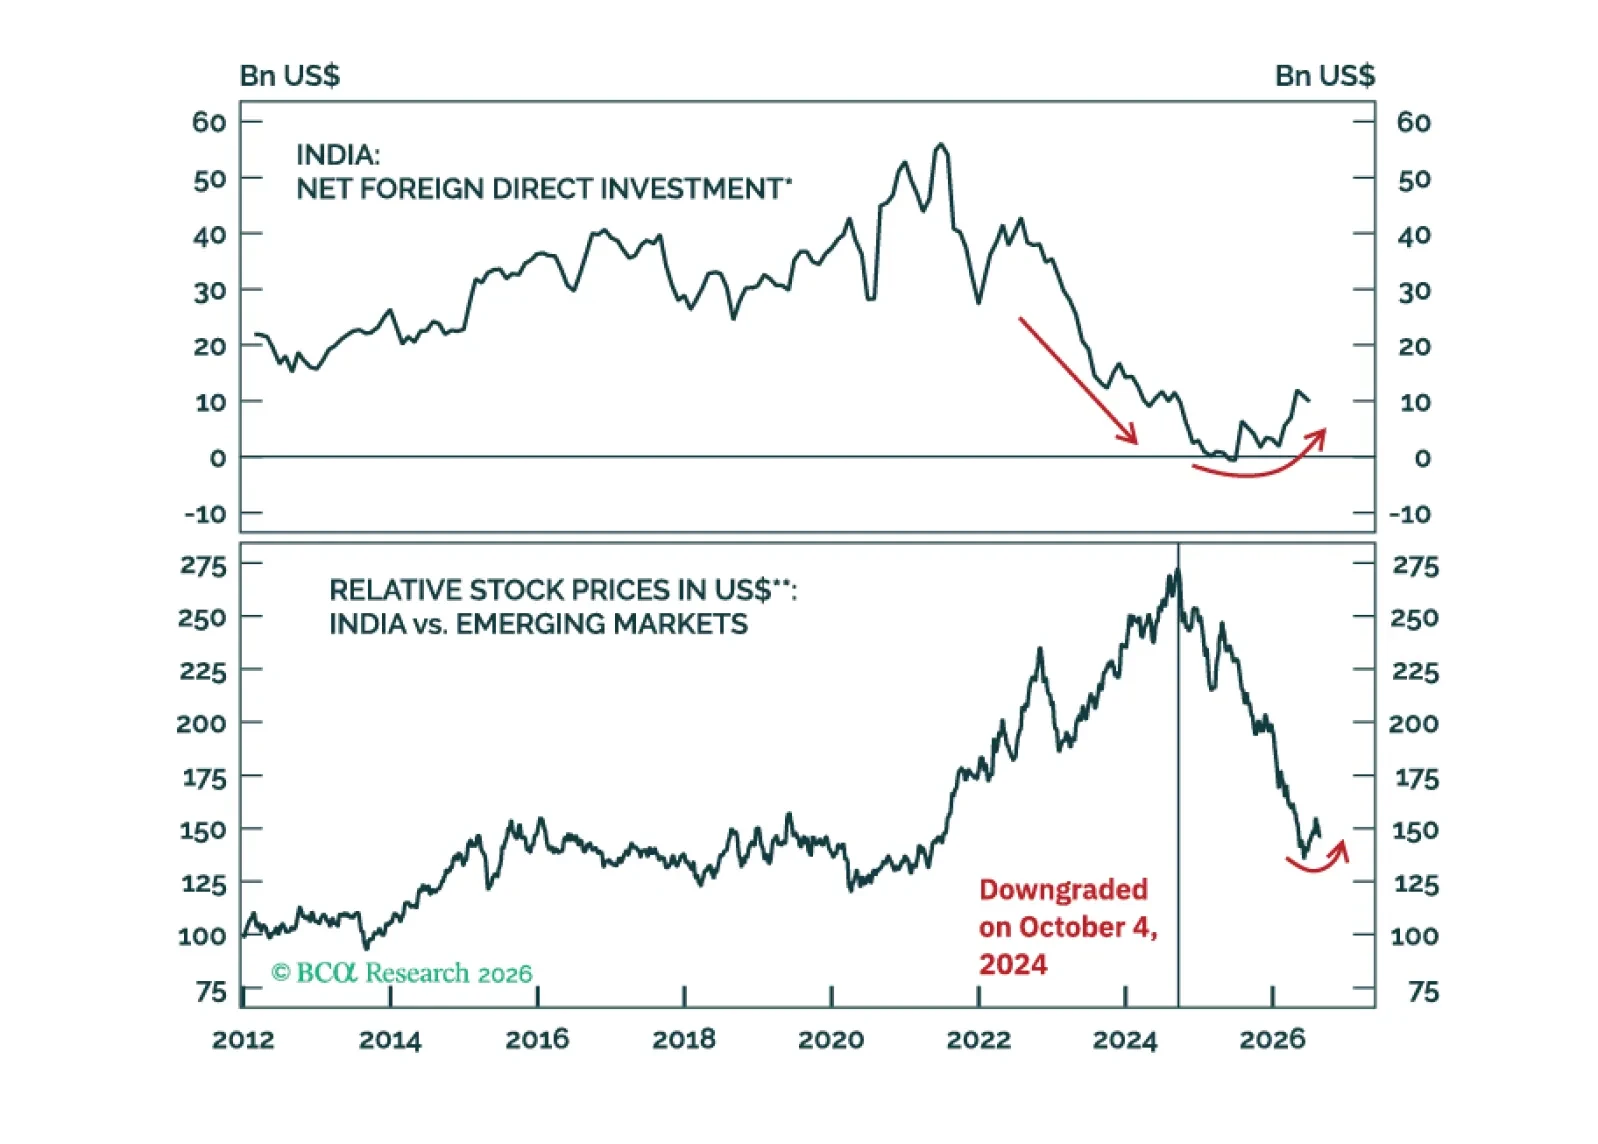
BCA's CoreMacro and Portfolio Construction teams combine two distinct but intersecting lenses to revisit a once heralded opportunity: India. We upgrade India across both public and private markets, but the conviction is not the same everywhere.
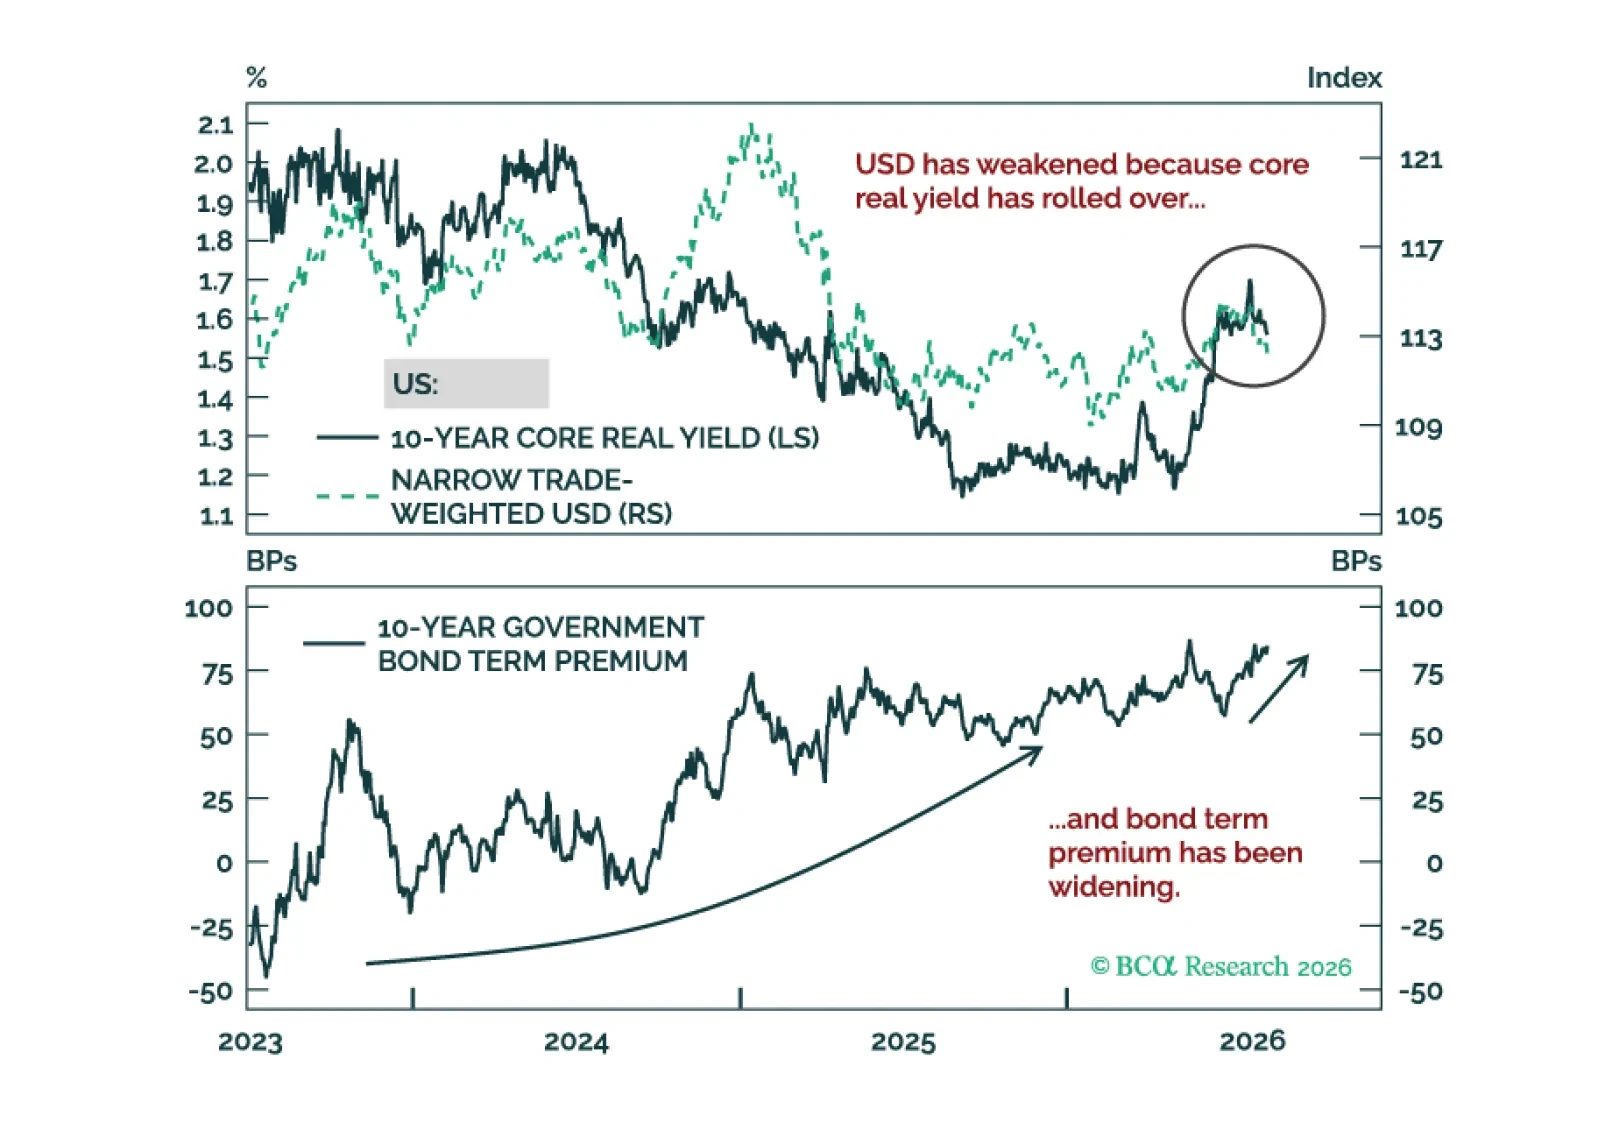
If bond yields rise due to widening bond term premiums or escalating inflation expectations, Bessenomics is unlikely to avert a stock-bond collision. Buy back gold mining stocks.
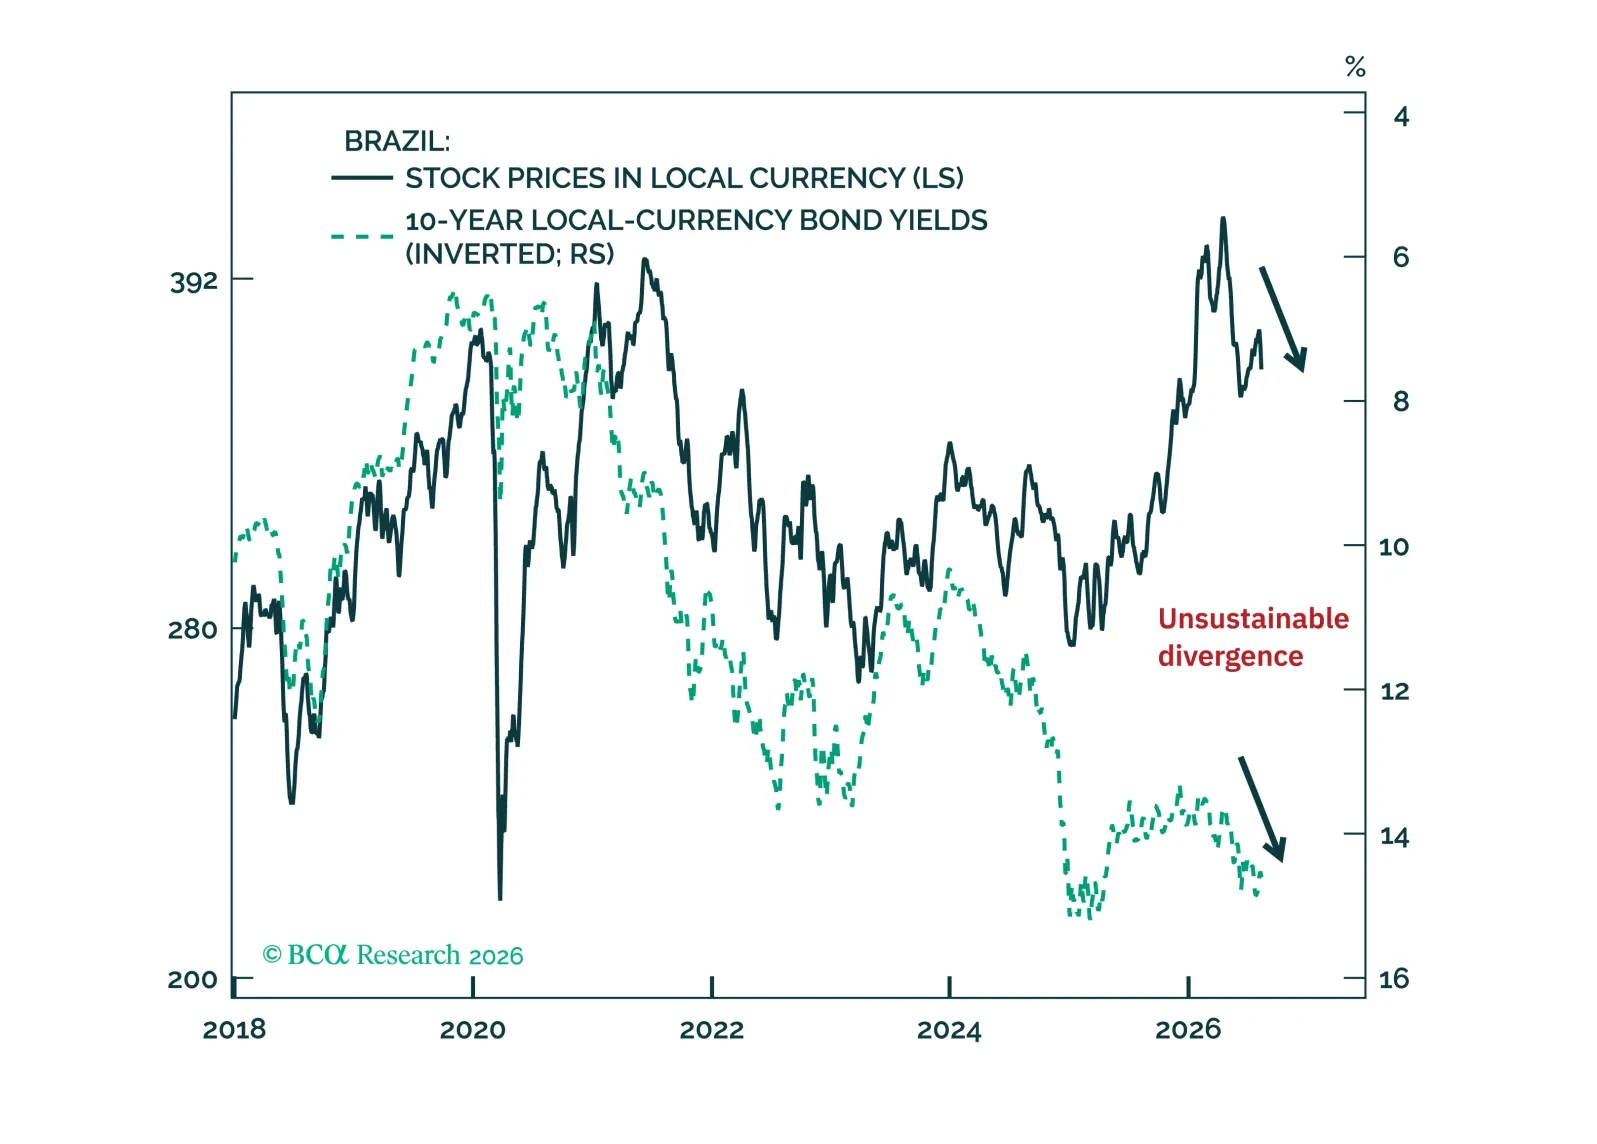
We are downgrading Brazilian equities from neutral to underweight and maintaining our underweights in Brazil's domestic bonds and sovereign credit within their respective EM portfolios. Go long Brazilian 5-year CDS as a short-term trade.
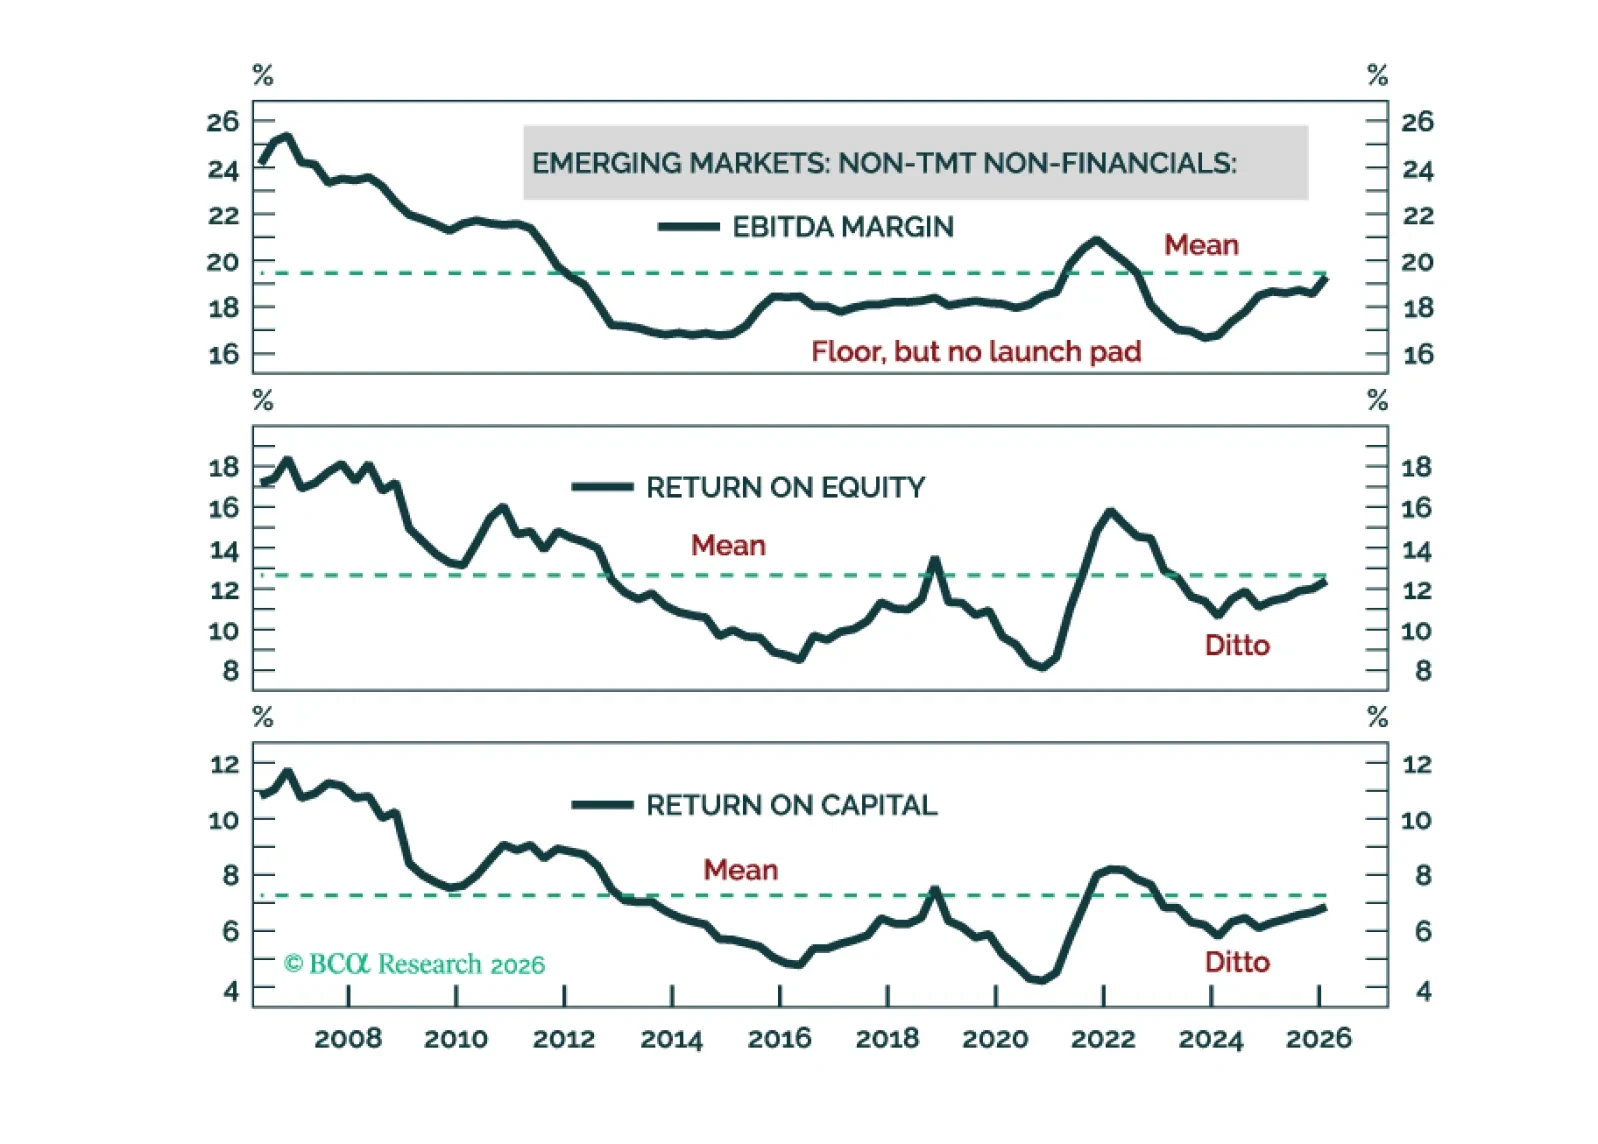
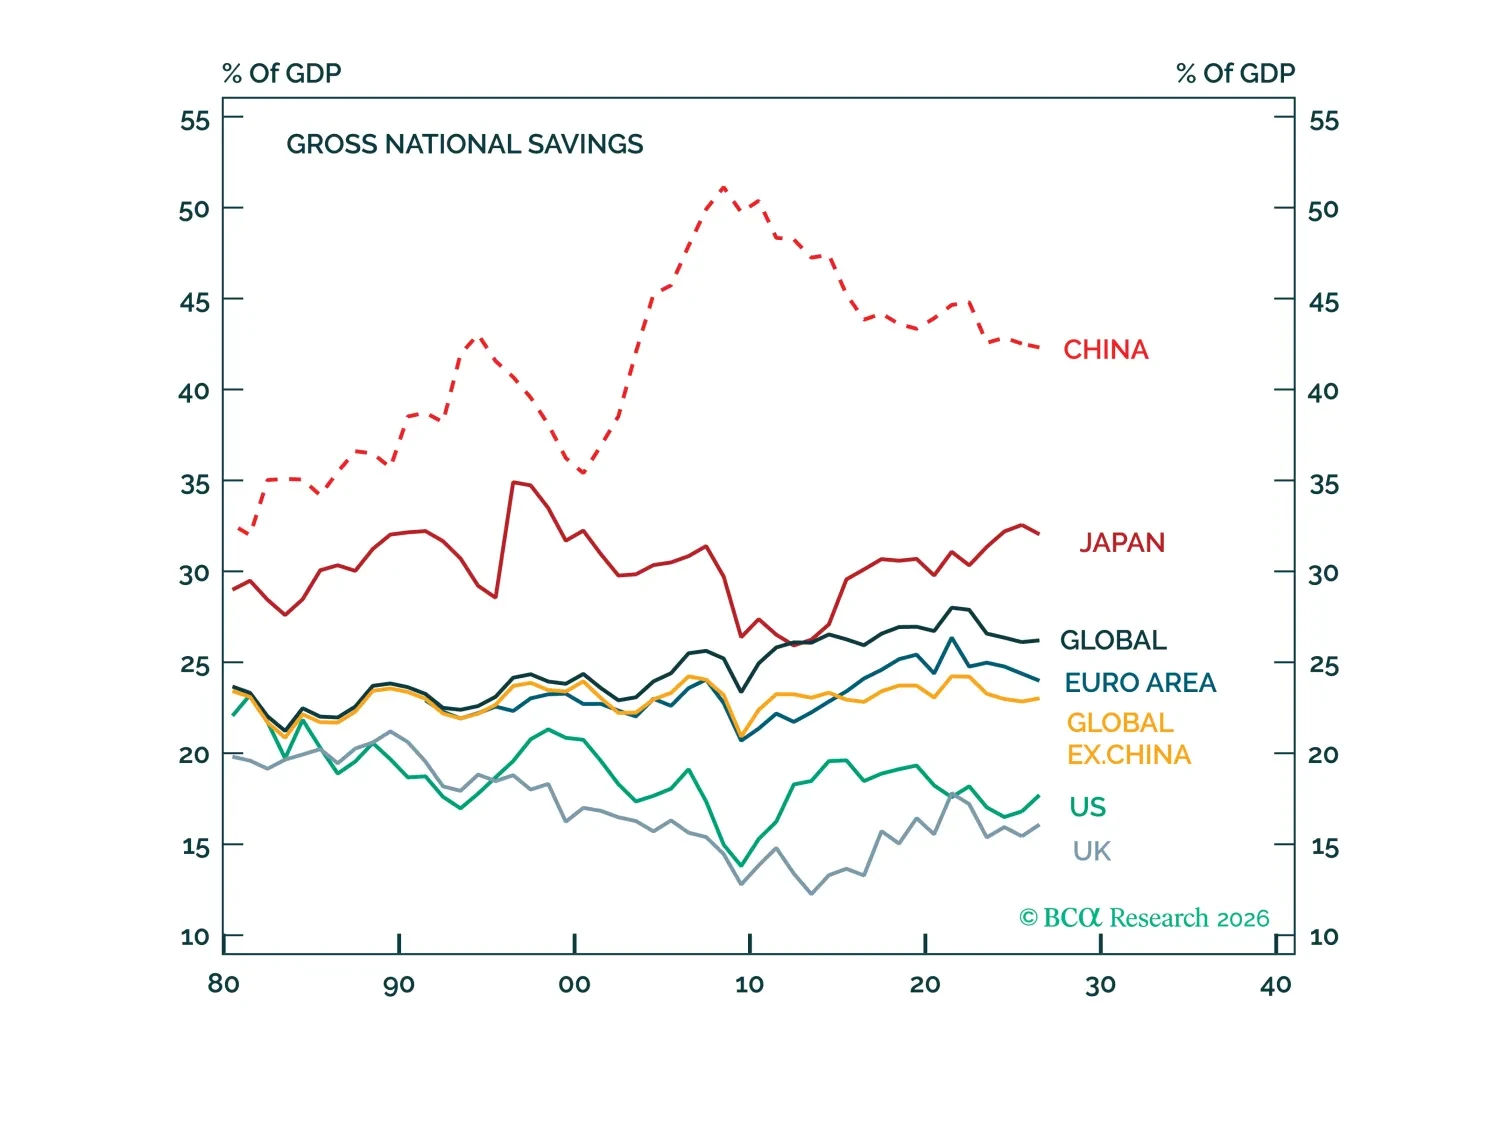
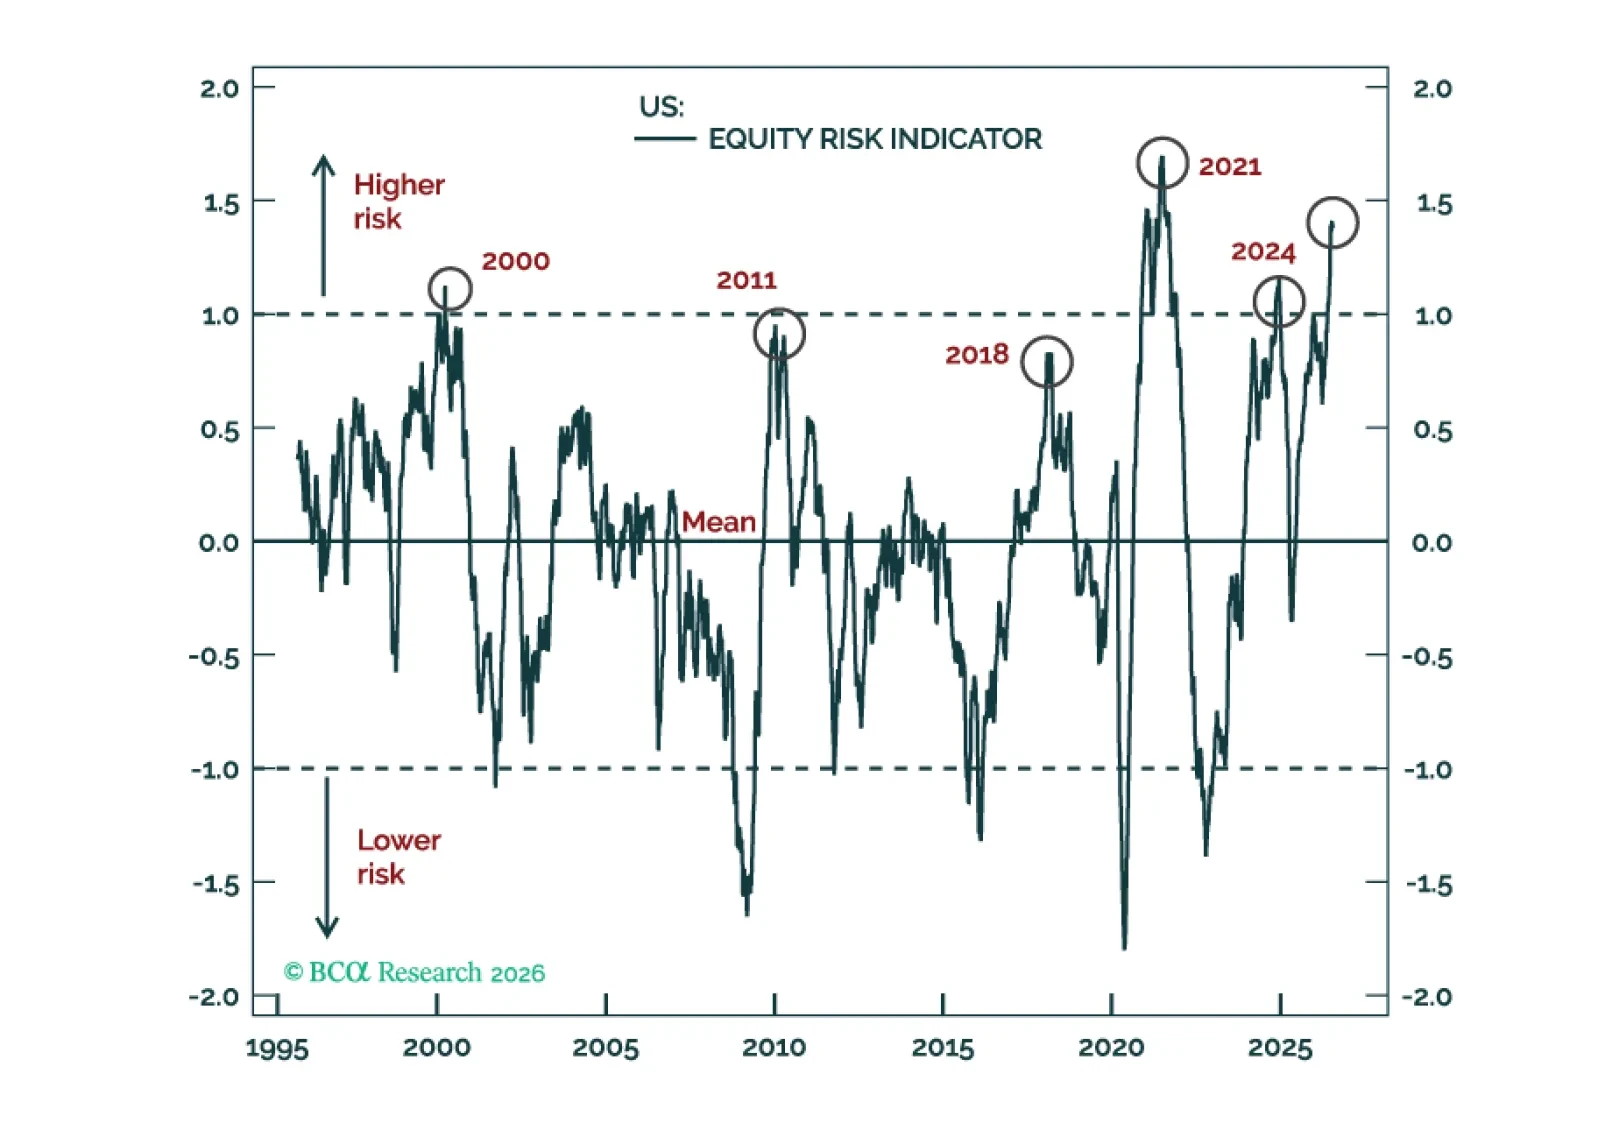
Global equities have reached extremes on multiple measures, none of which are reliable timing tools. But imbalances in economics and investing can build for far longer than rational analysis would predict - and usually unravel much faster than investors expect.
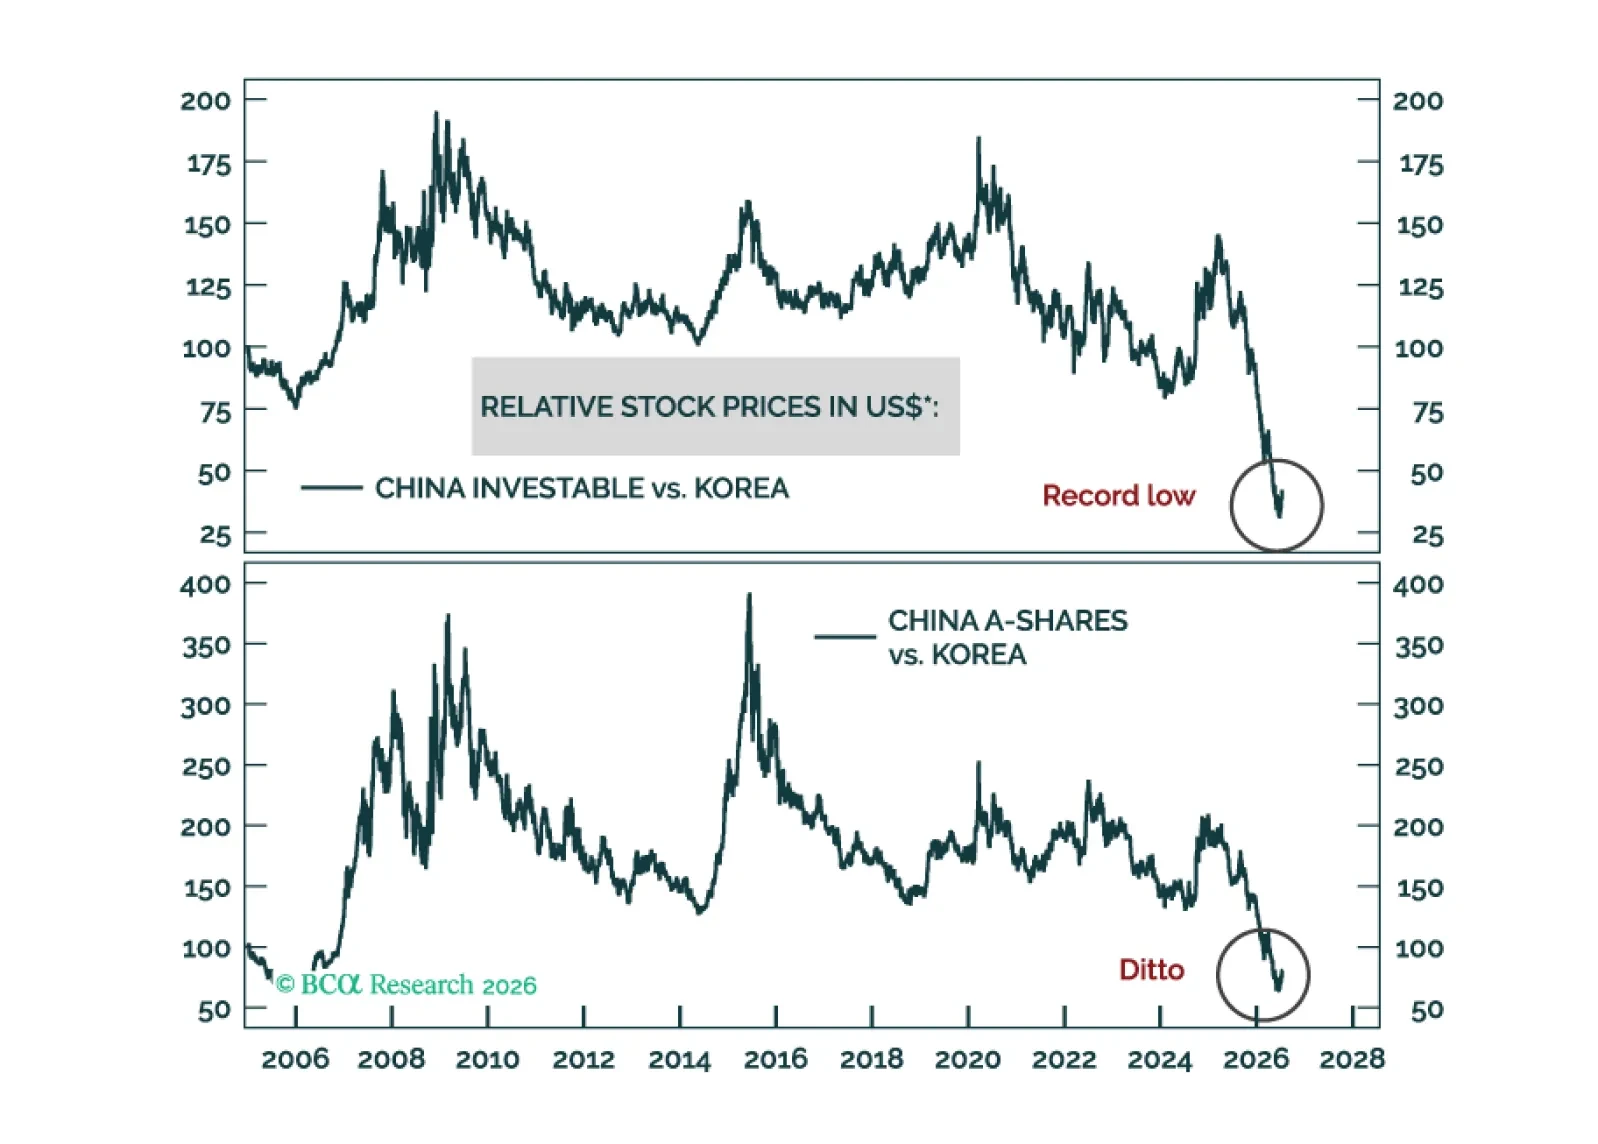
As a short-term (0-3 months) trade, go long an equal-weighted basket of Chinese Investable and A-shares / short the KOSPI. This is a bet on mean reversion. We do not recommend that medium- and long-term investors implement this strategy.