Max Malakhveitchouk
Research Associate
-
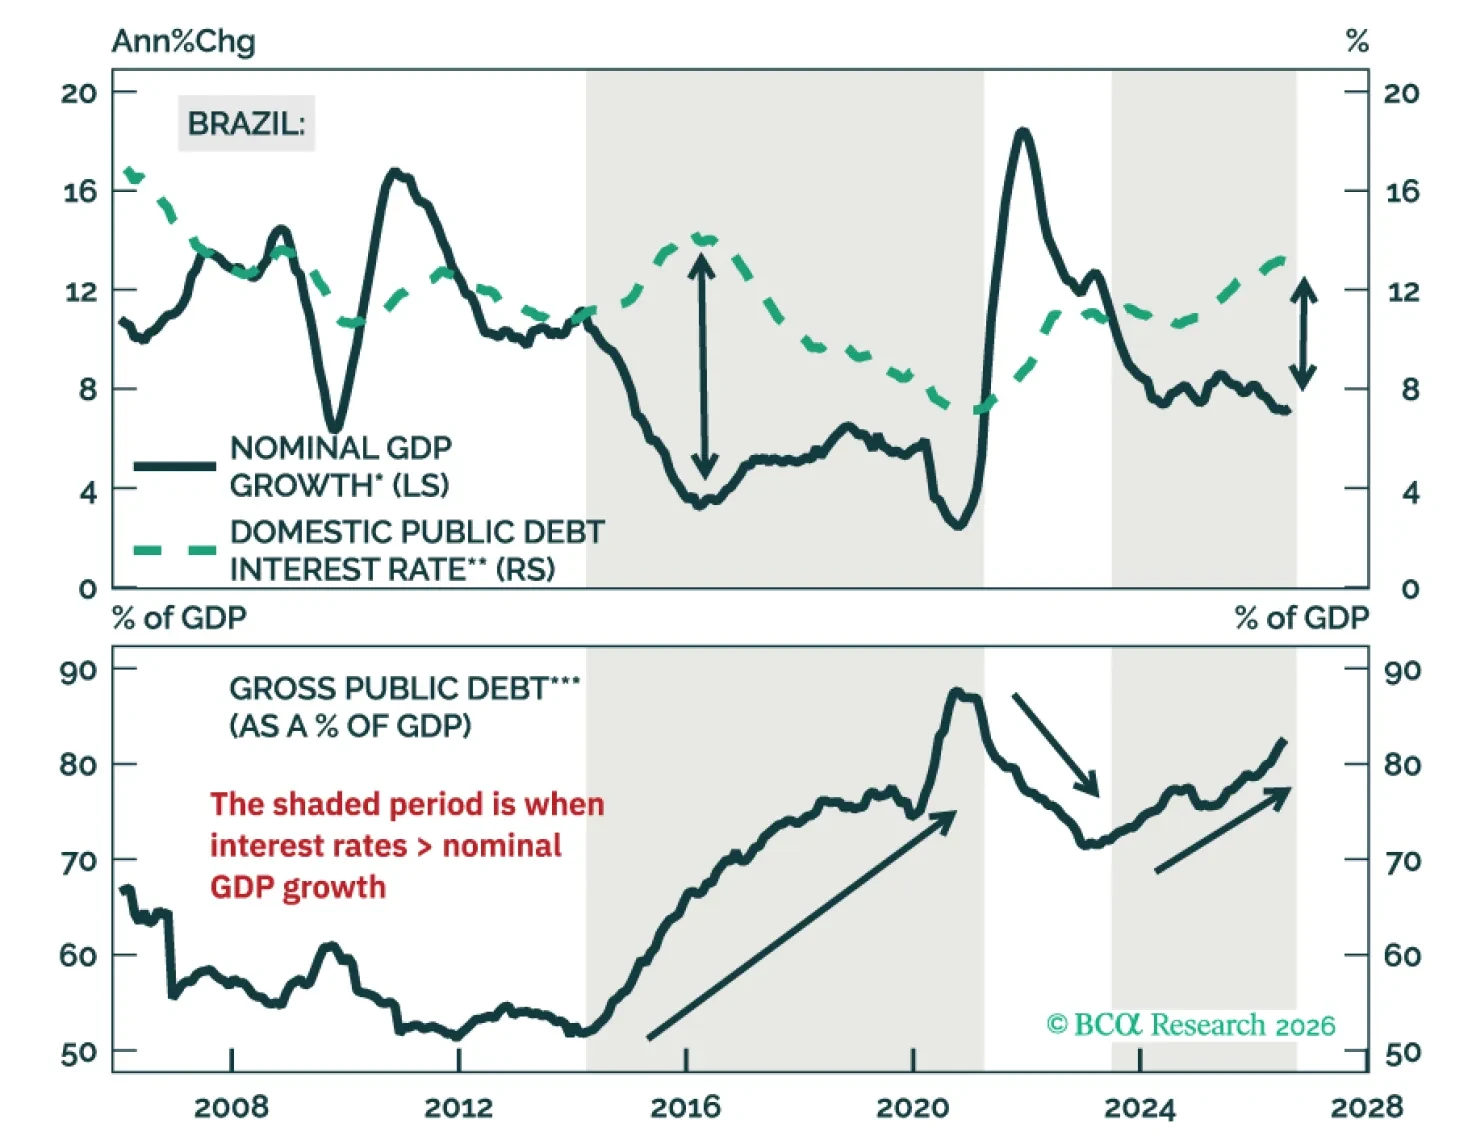
Brazil: Political Ambitions Will Meet Economic Reality
The most bullish development for Brazil from the weekend’s elections was not the higher odds of a right-wing presidency, but the likely president’s (Flávio Bolsonaro) stronghold in Congress. Upgrade Brazilian fixed-income markets to overweight and equities to neutral within their respective EM portfolios.
-
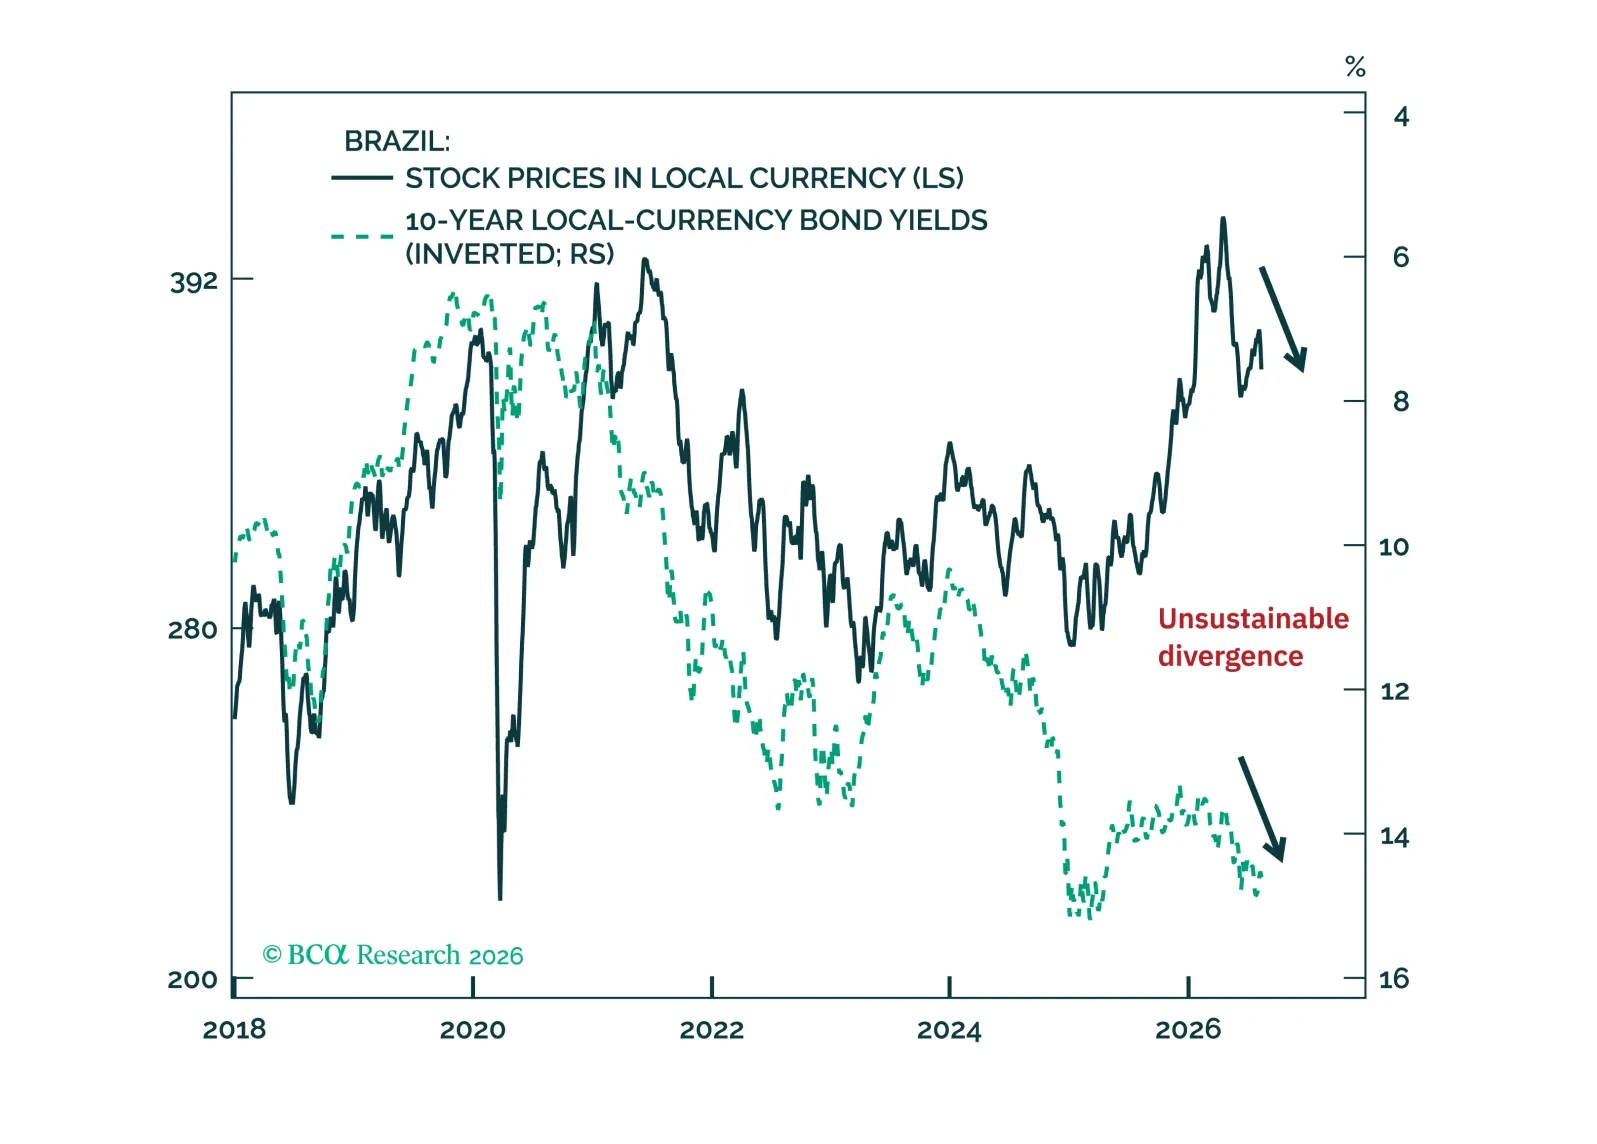
Brazil: Off Course
We are downgrading Brazilian equities from neutral to underweight and maintaining our underweights in Brazil's domestic bonds and sovereign credit within their respective EM portfolios. Go long Brazilian 5-year CDS as a short-term trade.
-
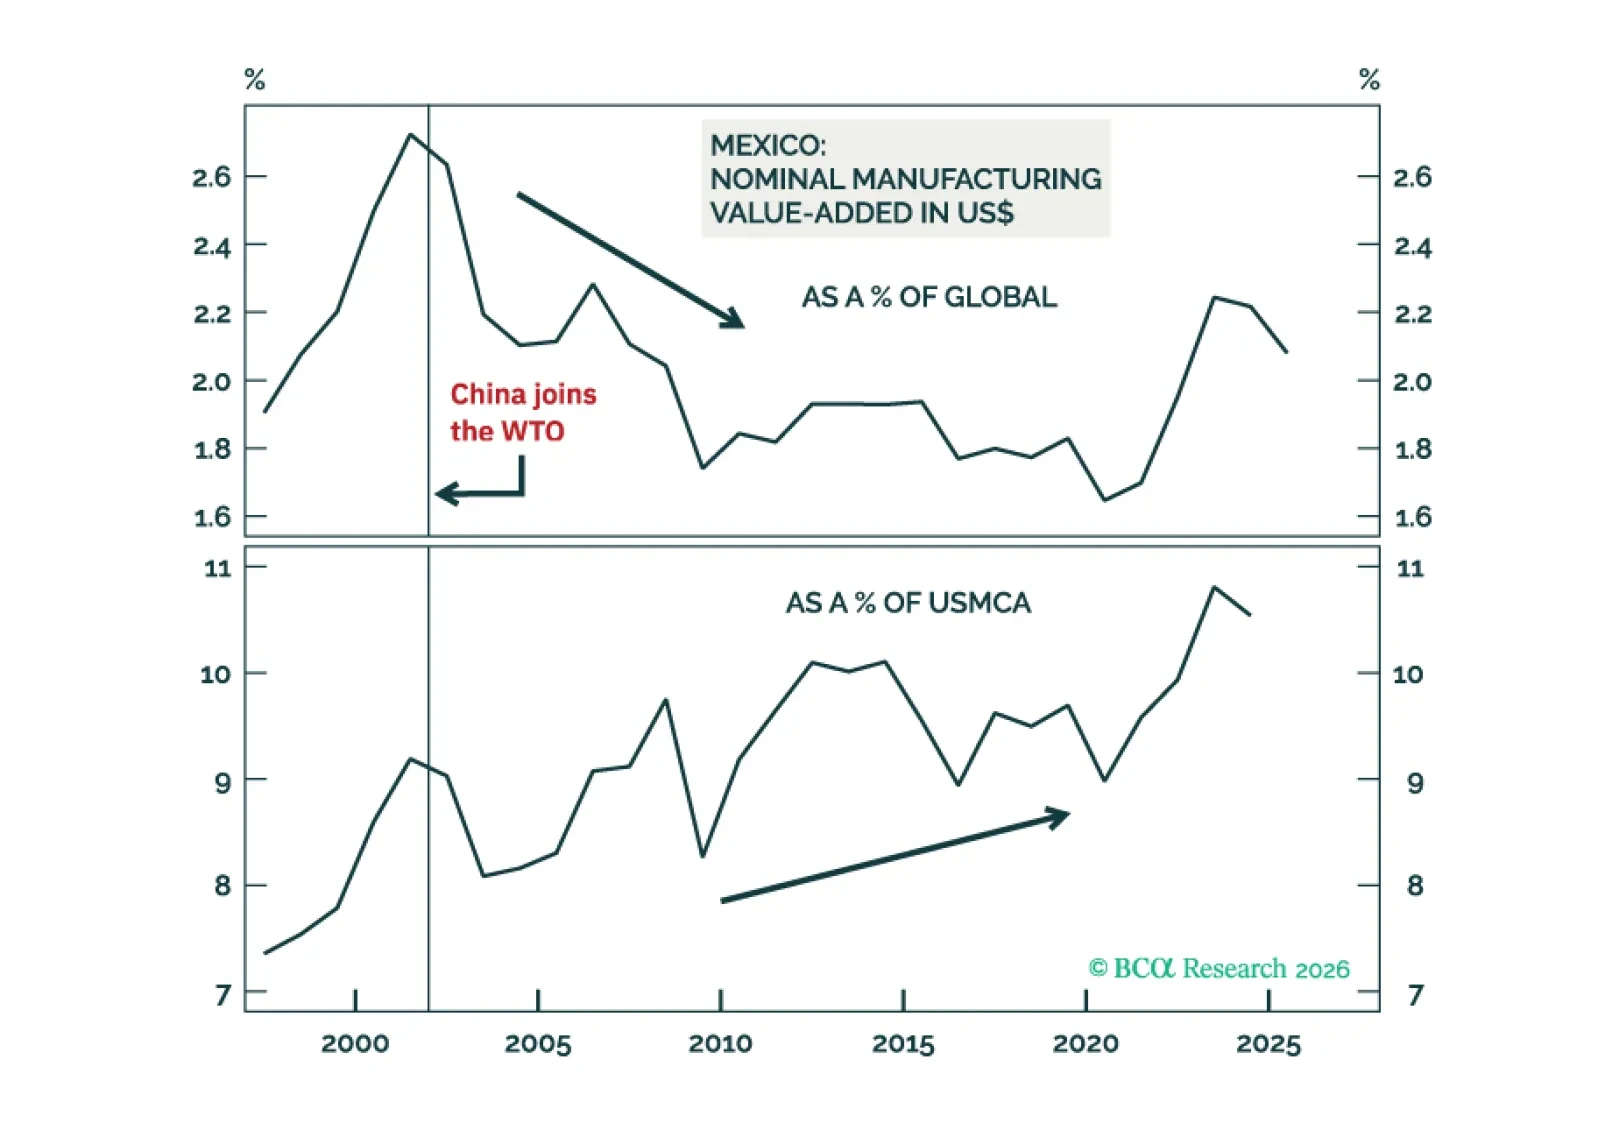
Mexico: An Export Boom Without A Productivity Lift
We continue to overweight Mexican stocks, local bonds, sovereign credit, and currency within their respective EM portfolios. Also, stay long Mexican equities / short the S&P500.
-
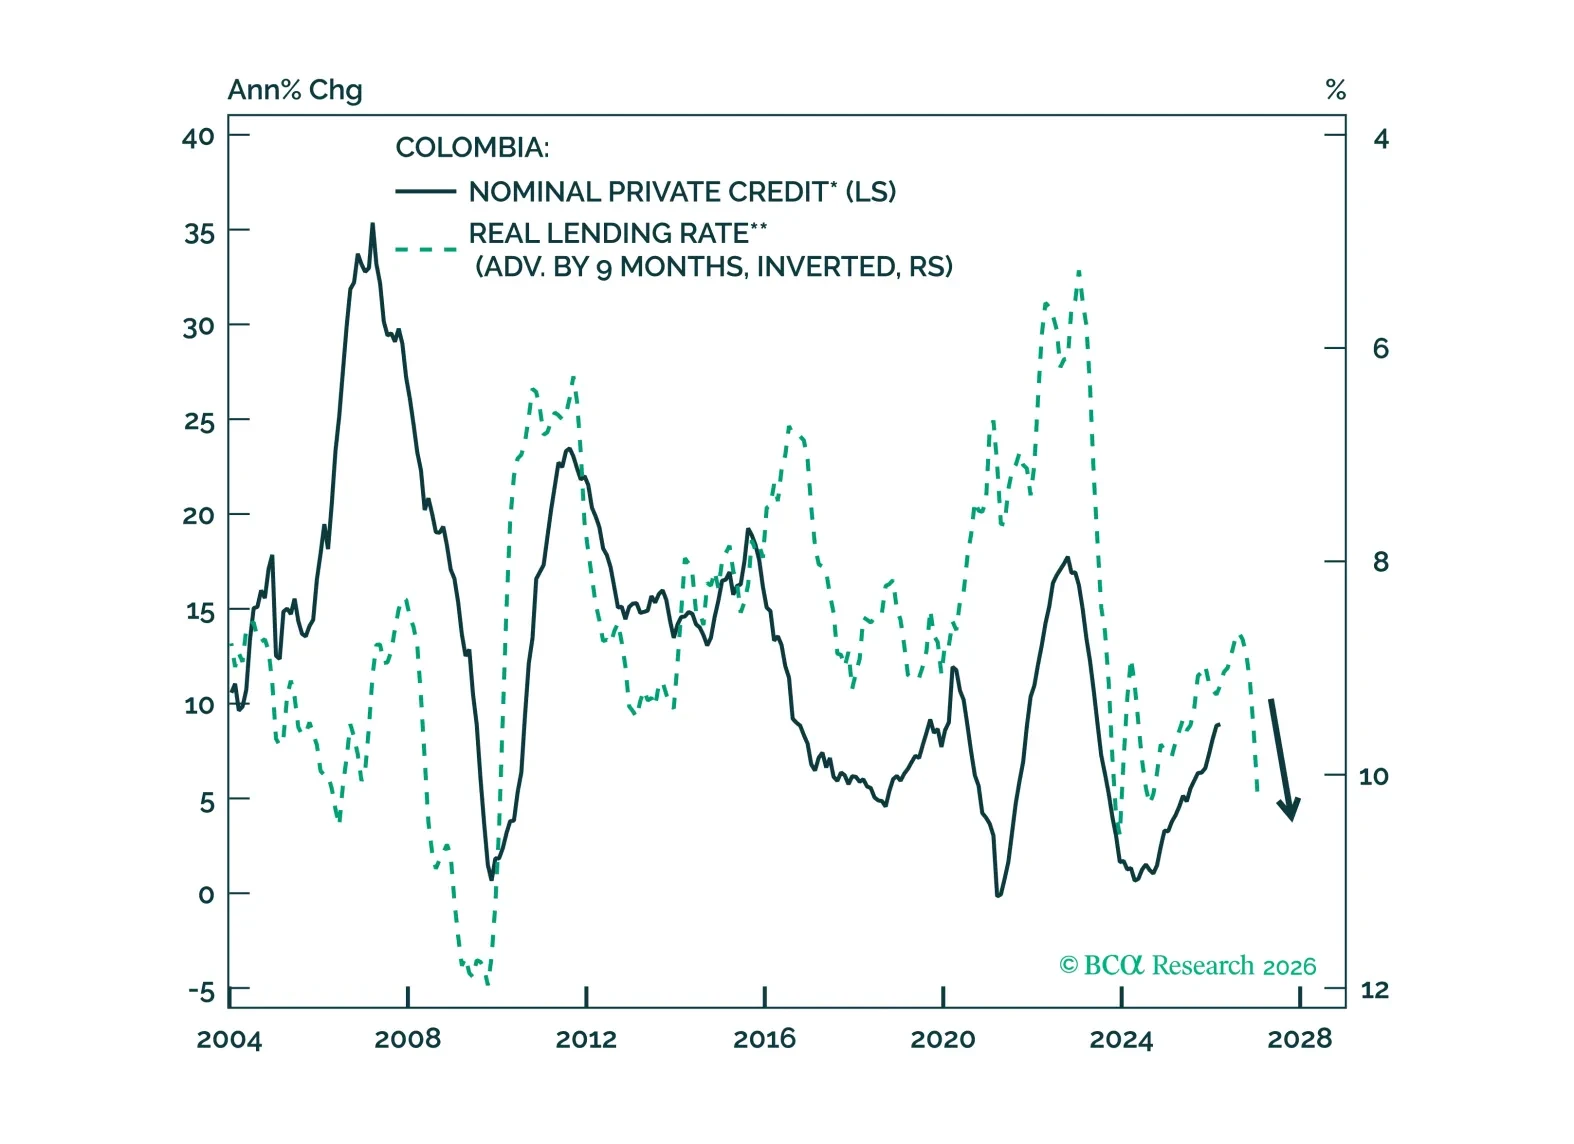
Colombia: The Rally Is Borrowed
The rally in Colombia’s financial markets has a short shelf life. The election will bring a right-wing government, but it cannot fix inflation, fiscal arithmetic, or balance-of-payments vulnerabilities. Use the near-term rally to downgrade Colombian fixed income and equities.
-
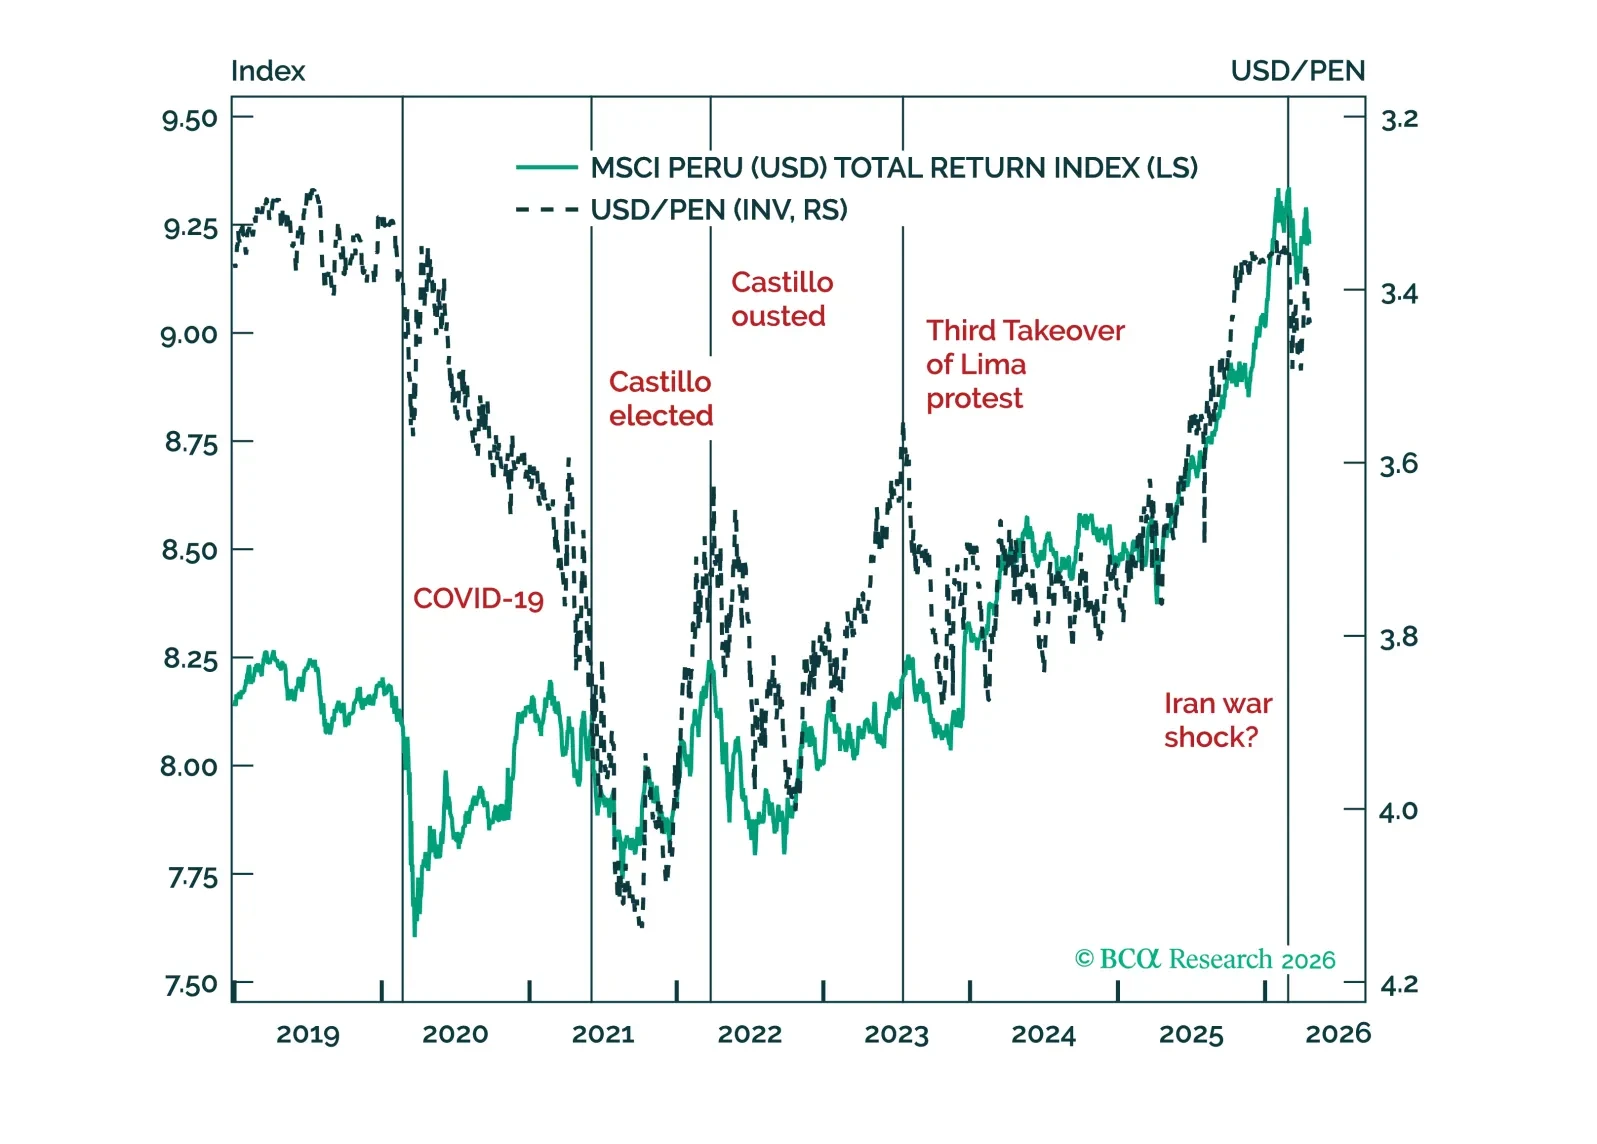
Peru: Election Boosts Markets
Peru is well established to elect a pro-market government in the June 7 run-off, with institutional constraints limiting left-tail policy risks. We will go long Peruvian assets when Hormuz volatility subsides.
-
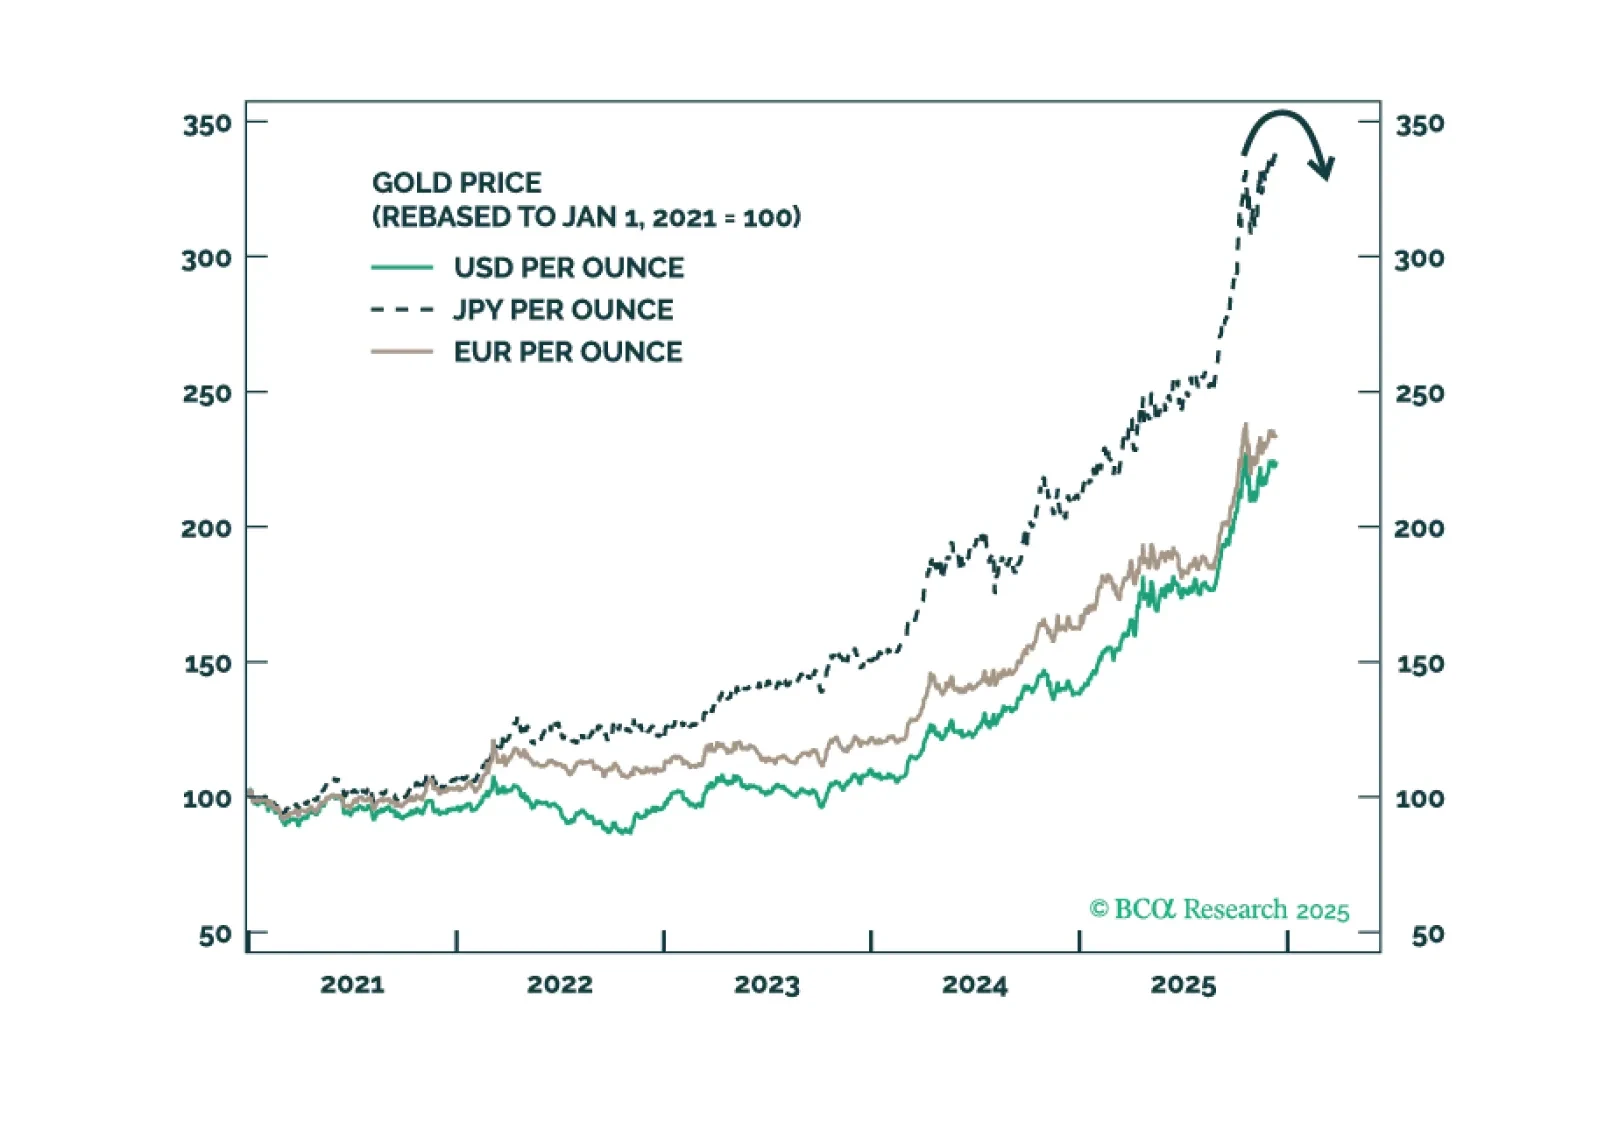
A Short Geopolitical Outlook For 2026
2026 will see geopolitical risk move sideways globally as the US pursues a ceasefire in the proxy war with Russia and a tariff truce with China ahead of midterm elections that will produce gridlock.
-
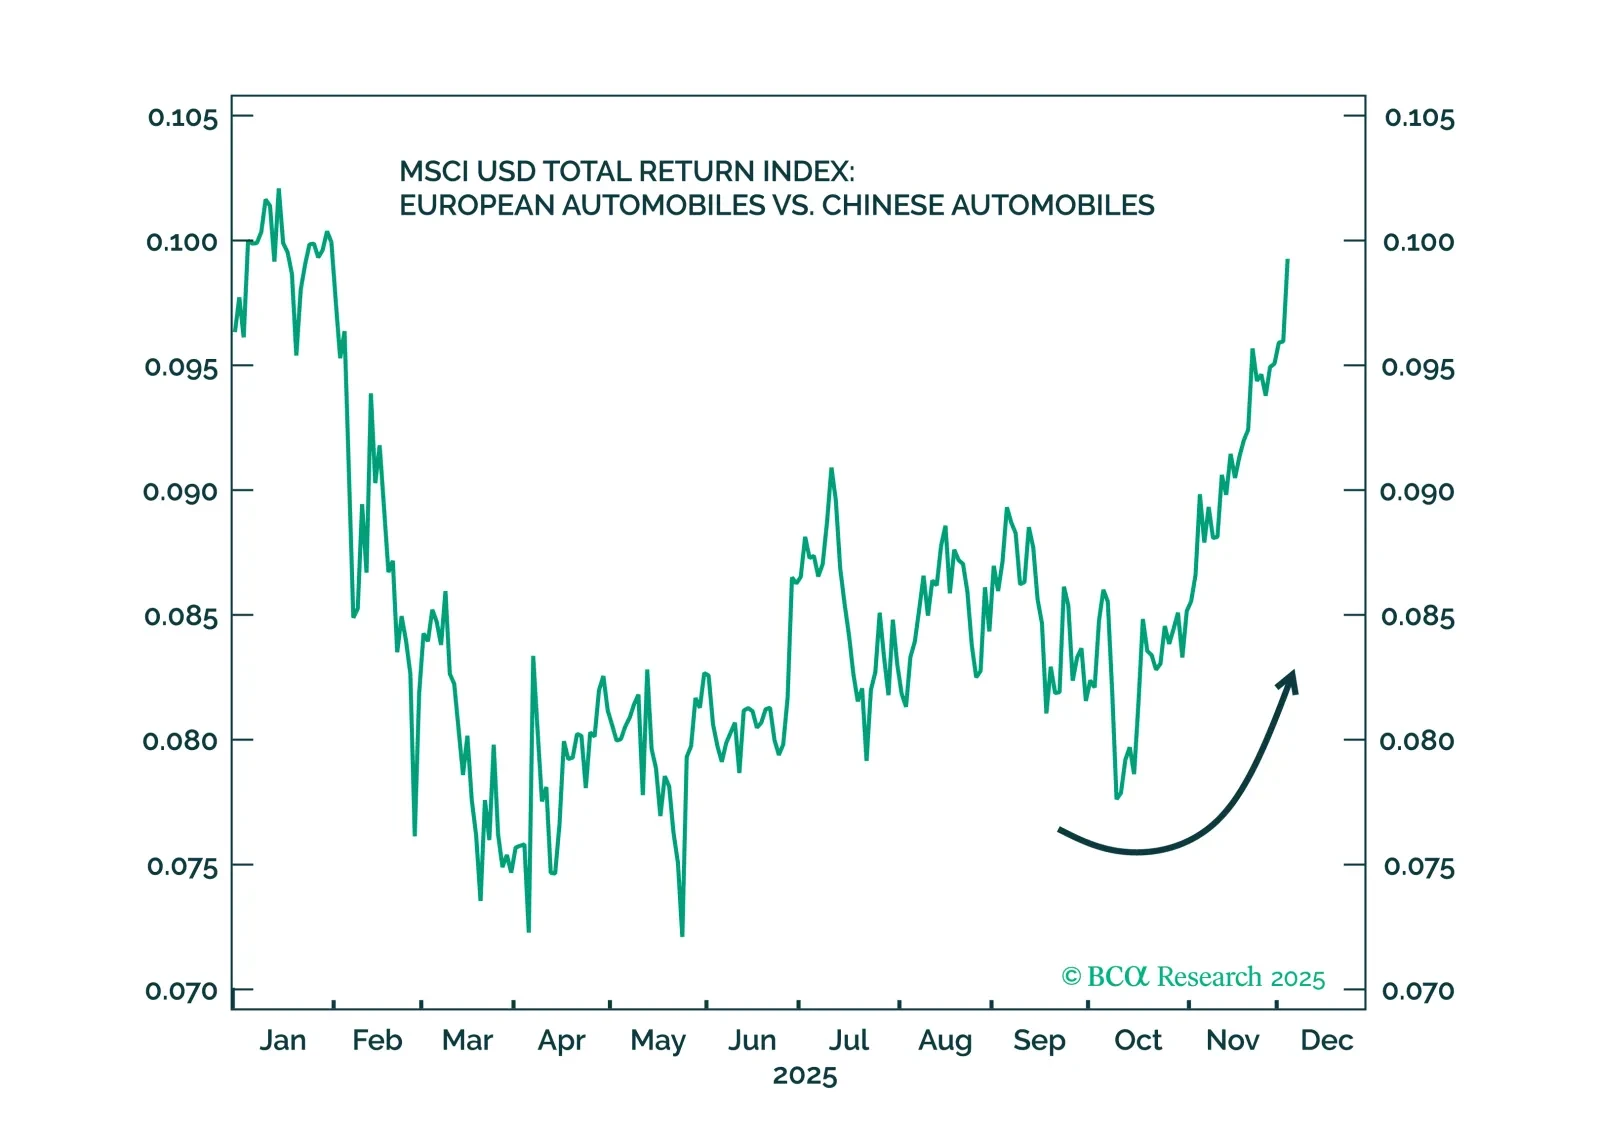
Our Best And Worst Calls Of 2025
We got Trump's tariff shock and backtracking correct and predicted Israel's attack on Iran. But we missed the China rally — and there is still no Ukraine ceasefire.
-
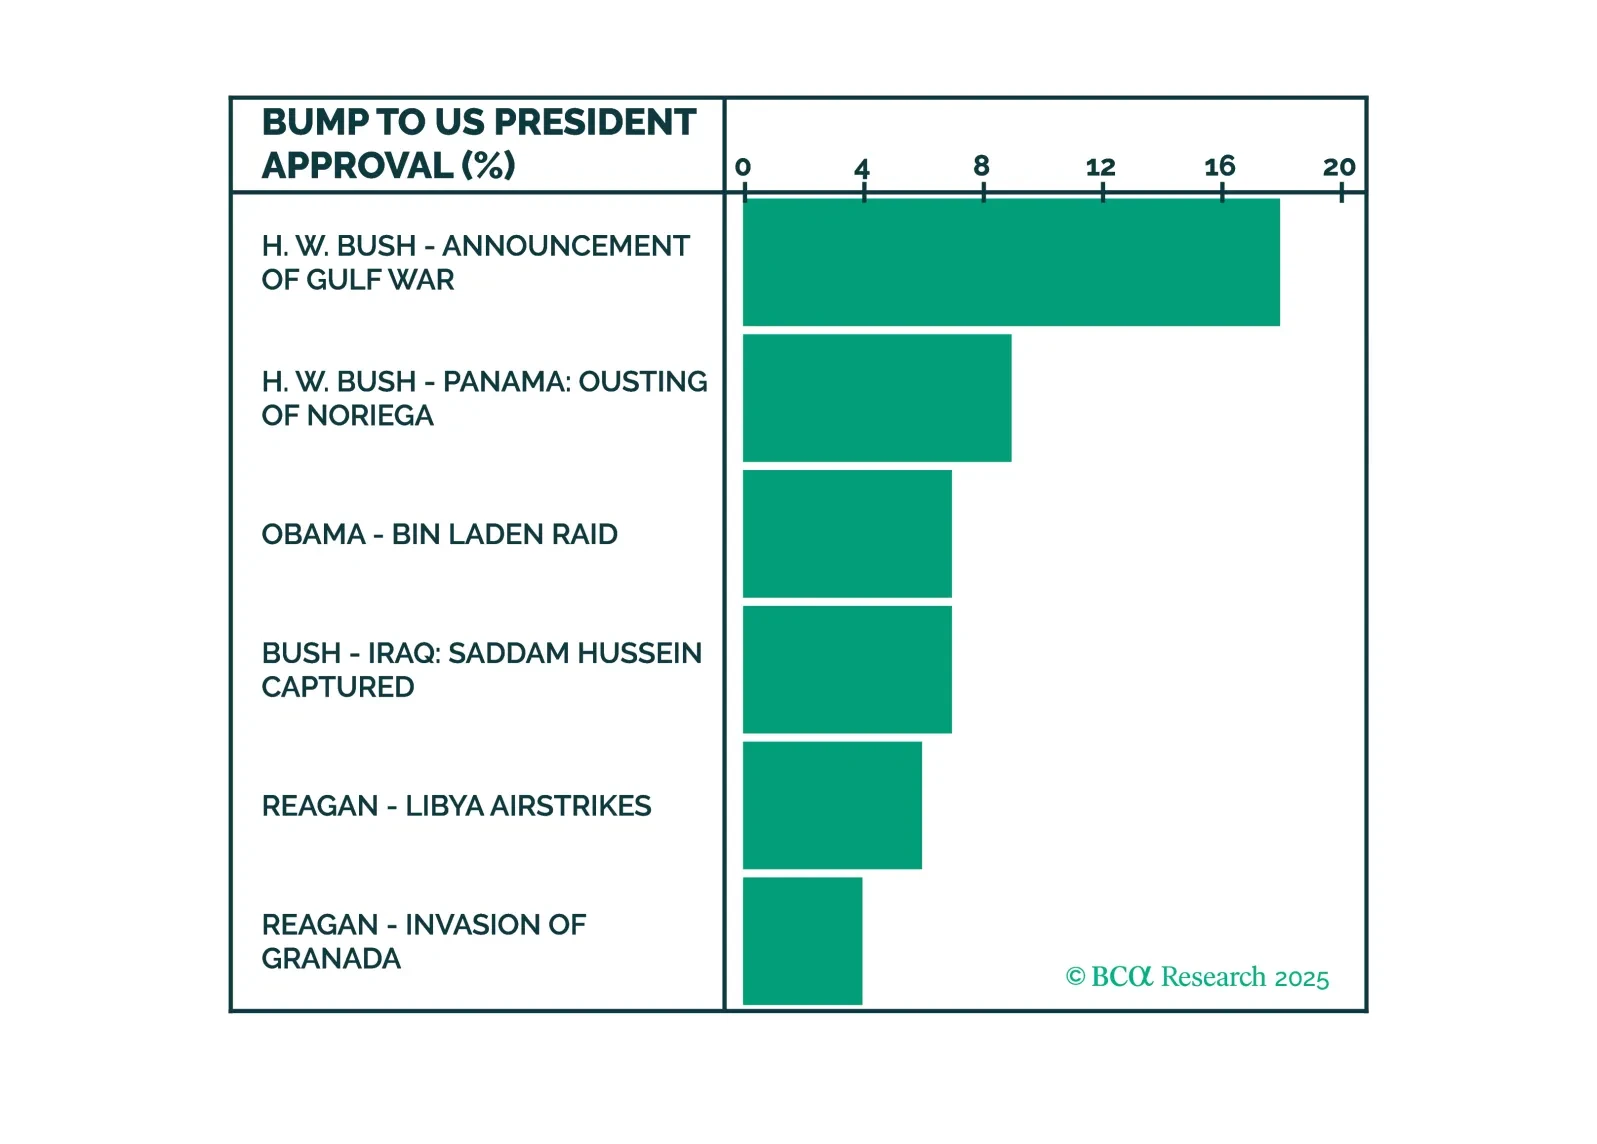
Maduro’s Last Barrel
US intervention will likely force out Maduro from Venezuela and reopen the economy. This could increase Venezuelan crude production in the long run, a modestly bearish outcome for oil markets over cyclical and structural horizons.
-
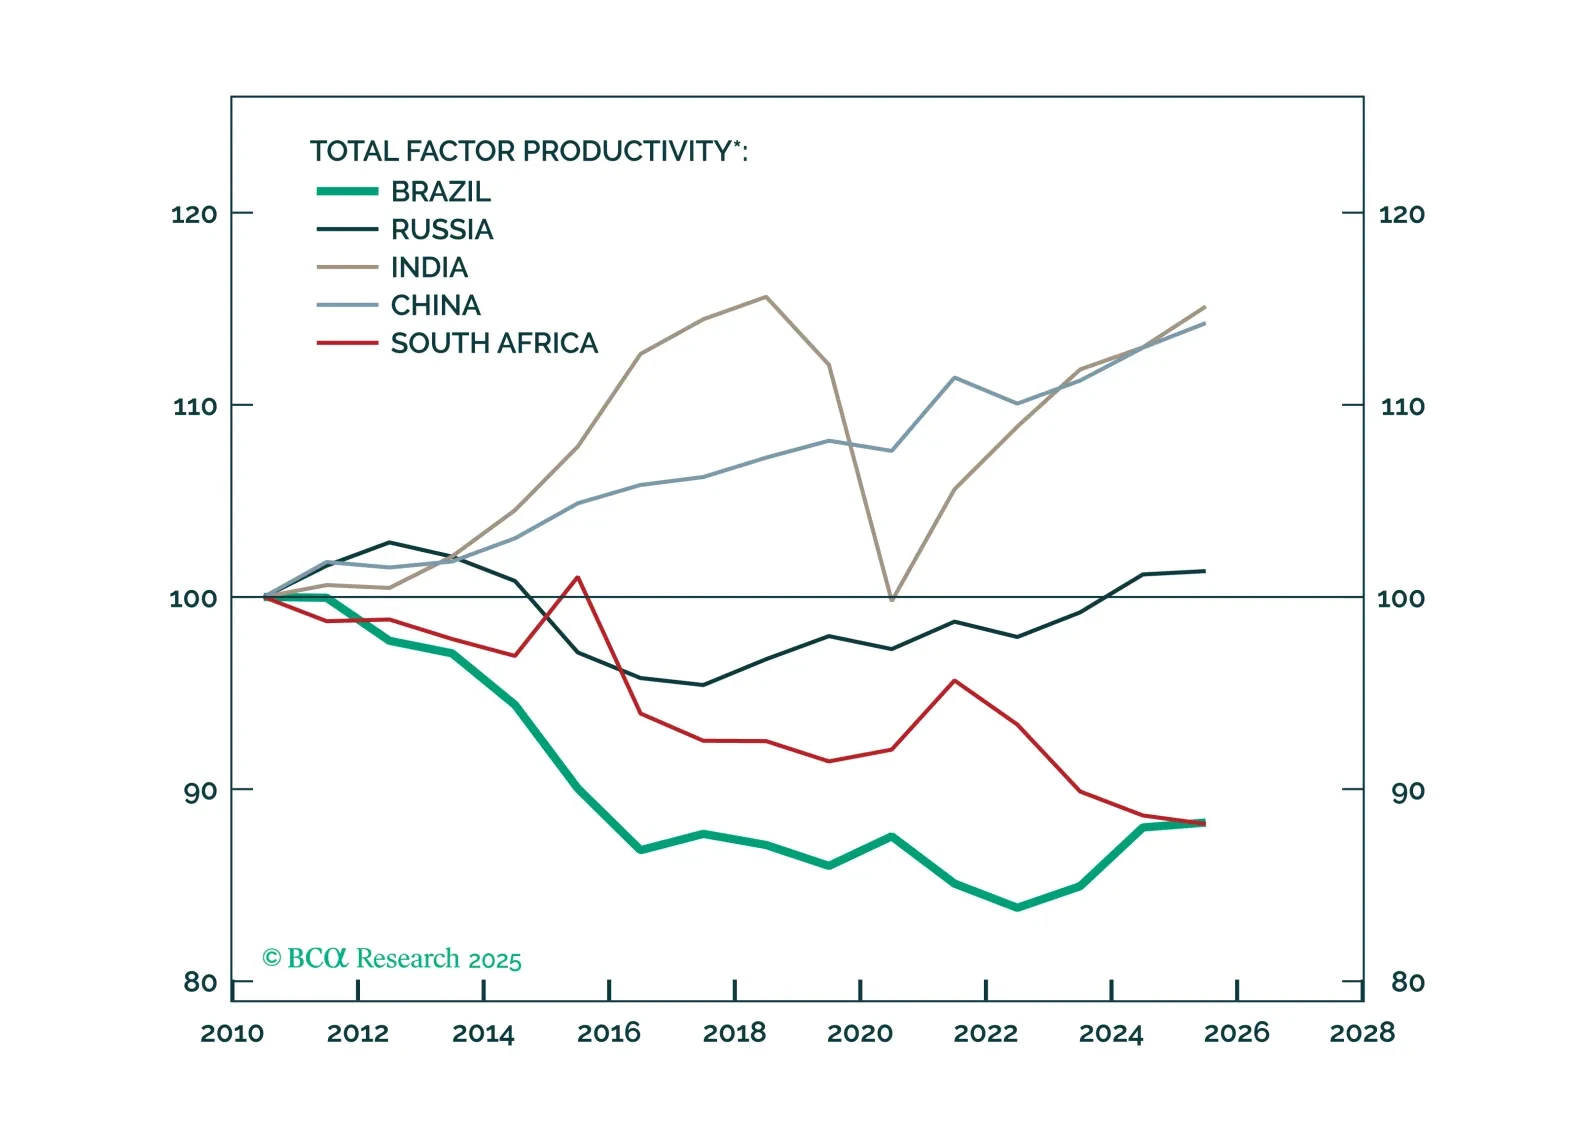
Brazil: Opportunity Meets Reality
Brazil’s bleak macro outlook persists – rising debt, weak productivity, and political inertia. With 2026 elections looming, genuine reform seems unlikely, though Argentina’s bold turnaround could pressure Brasília to rethink its cycle of governability over growth.
-
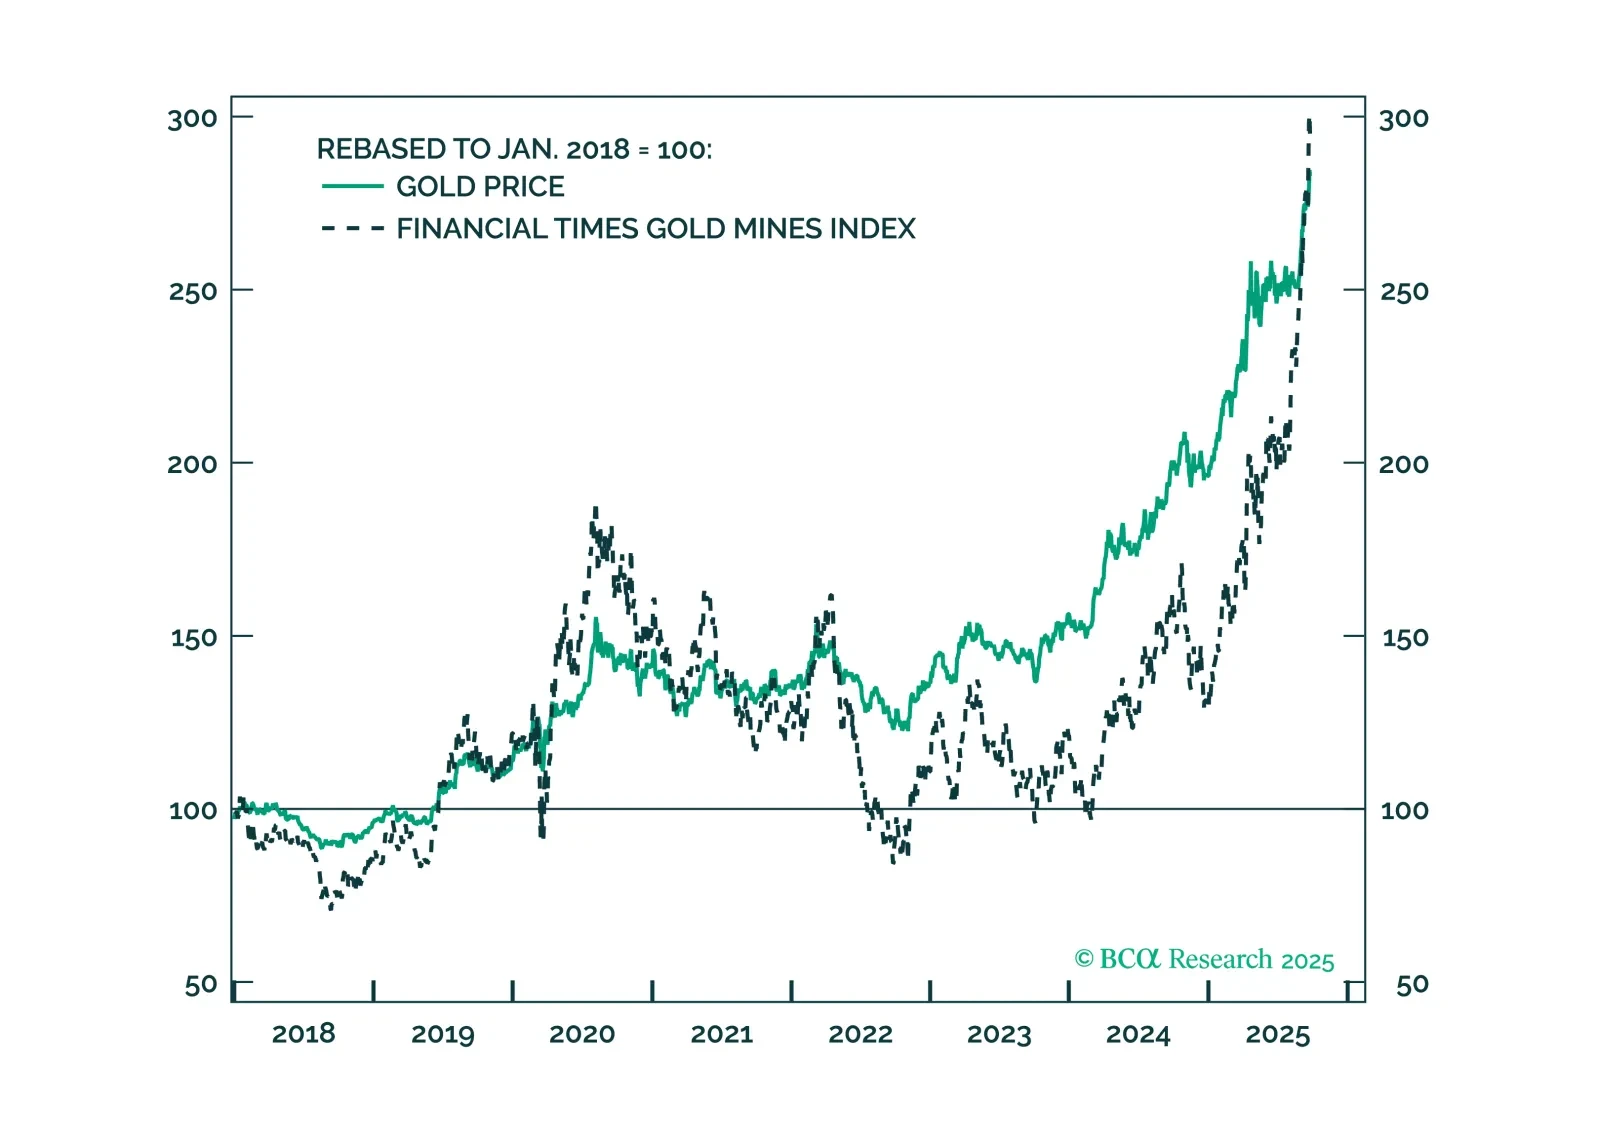
Geopolitics And US Politics, Q4
Rising Russia-NATO risks, tactical oil/gold trades, tougher sanctions on Russia (maybe China), China stimulus with ~5% growth target, and US checks on Trump’s ambitions will define Q4.