Policy
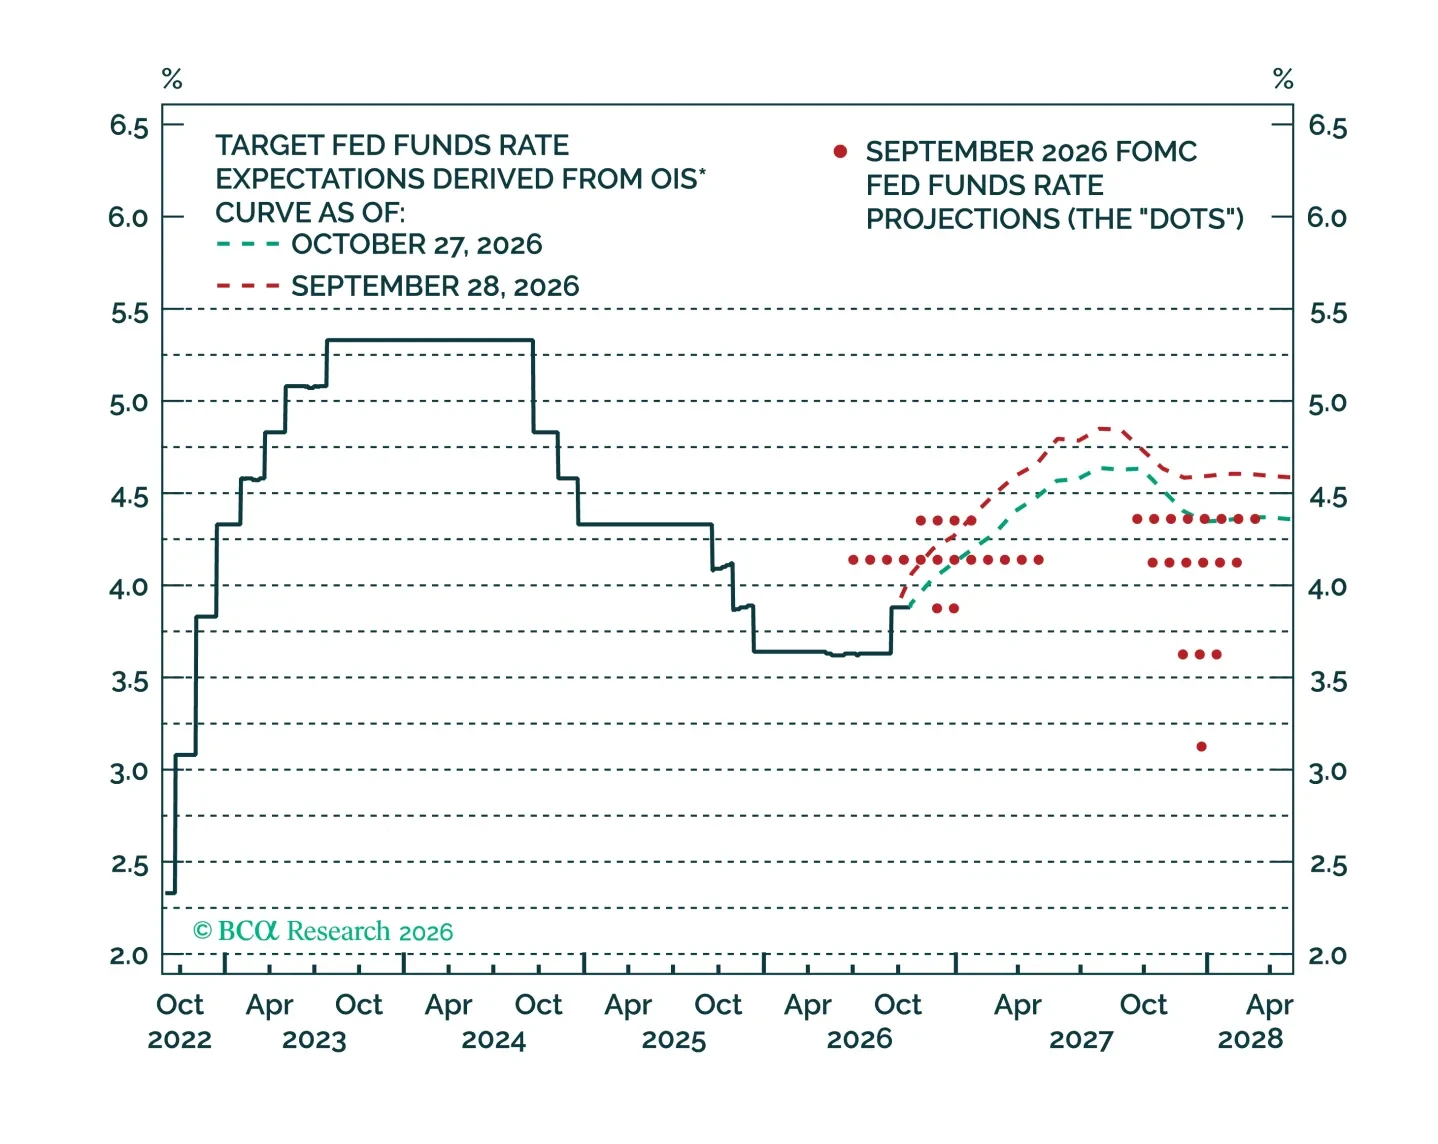
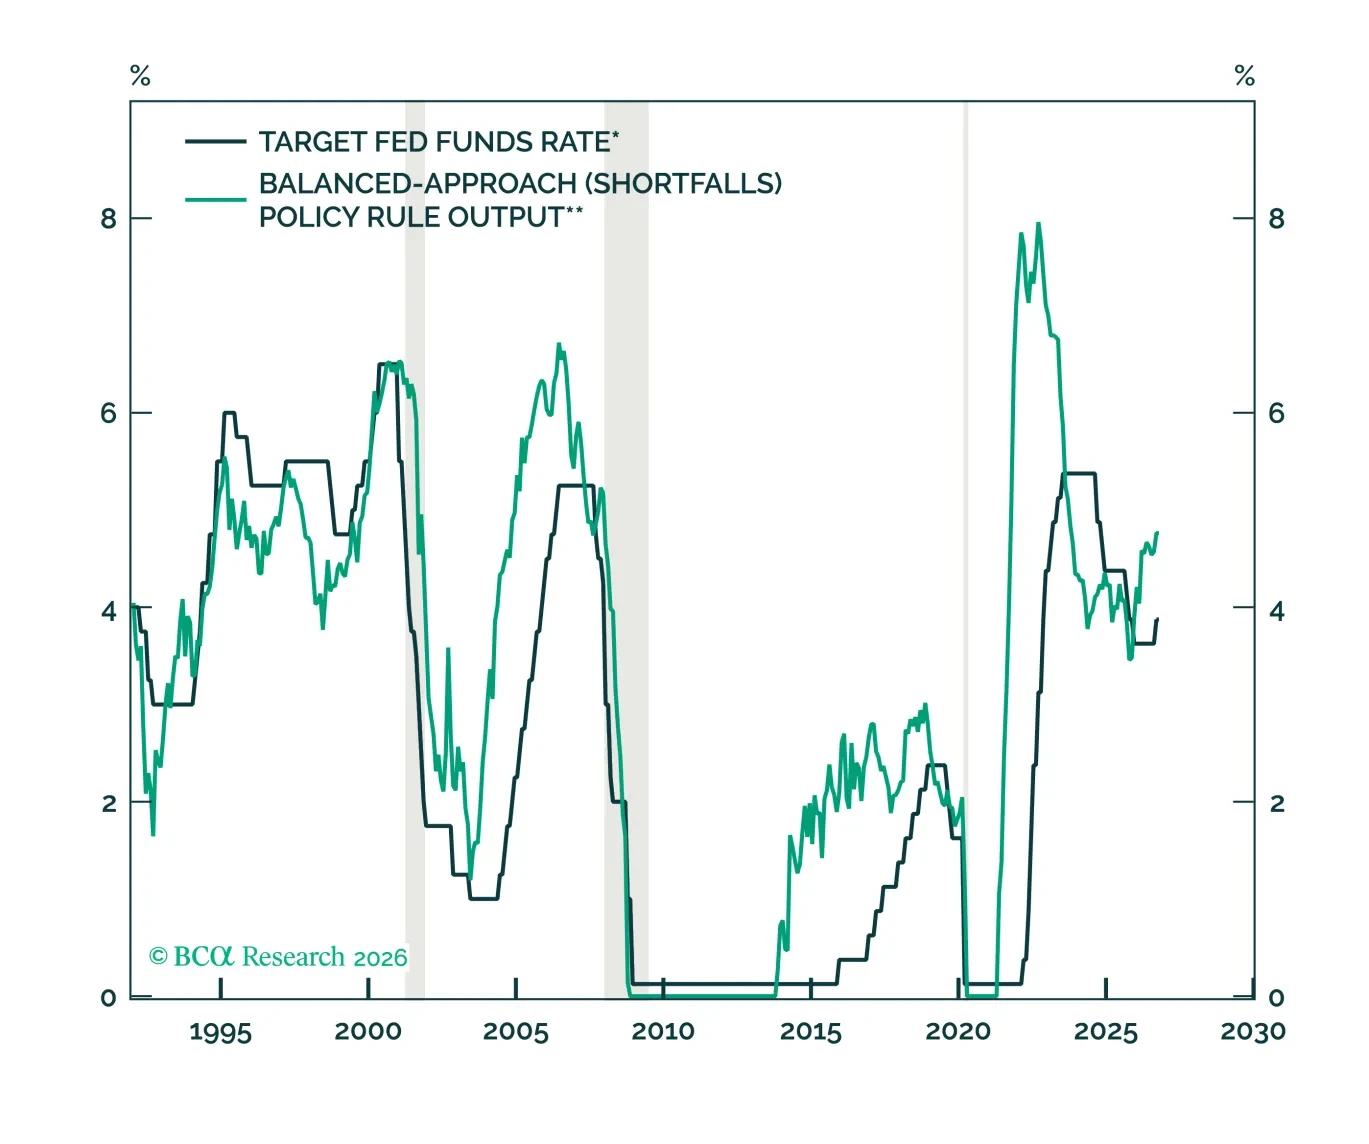
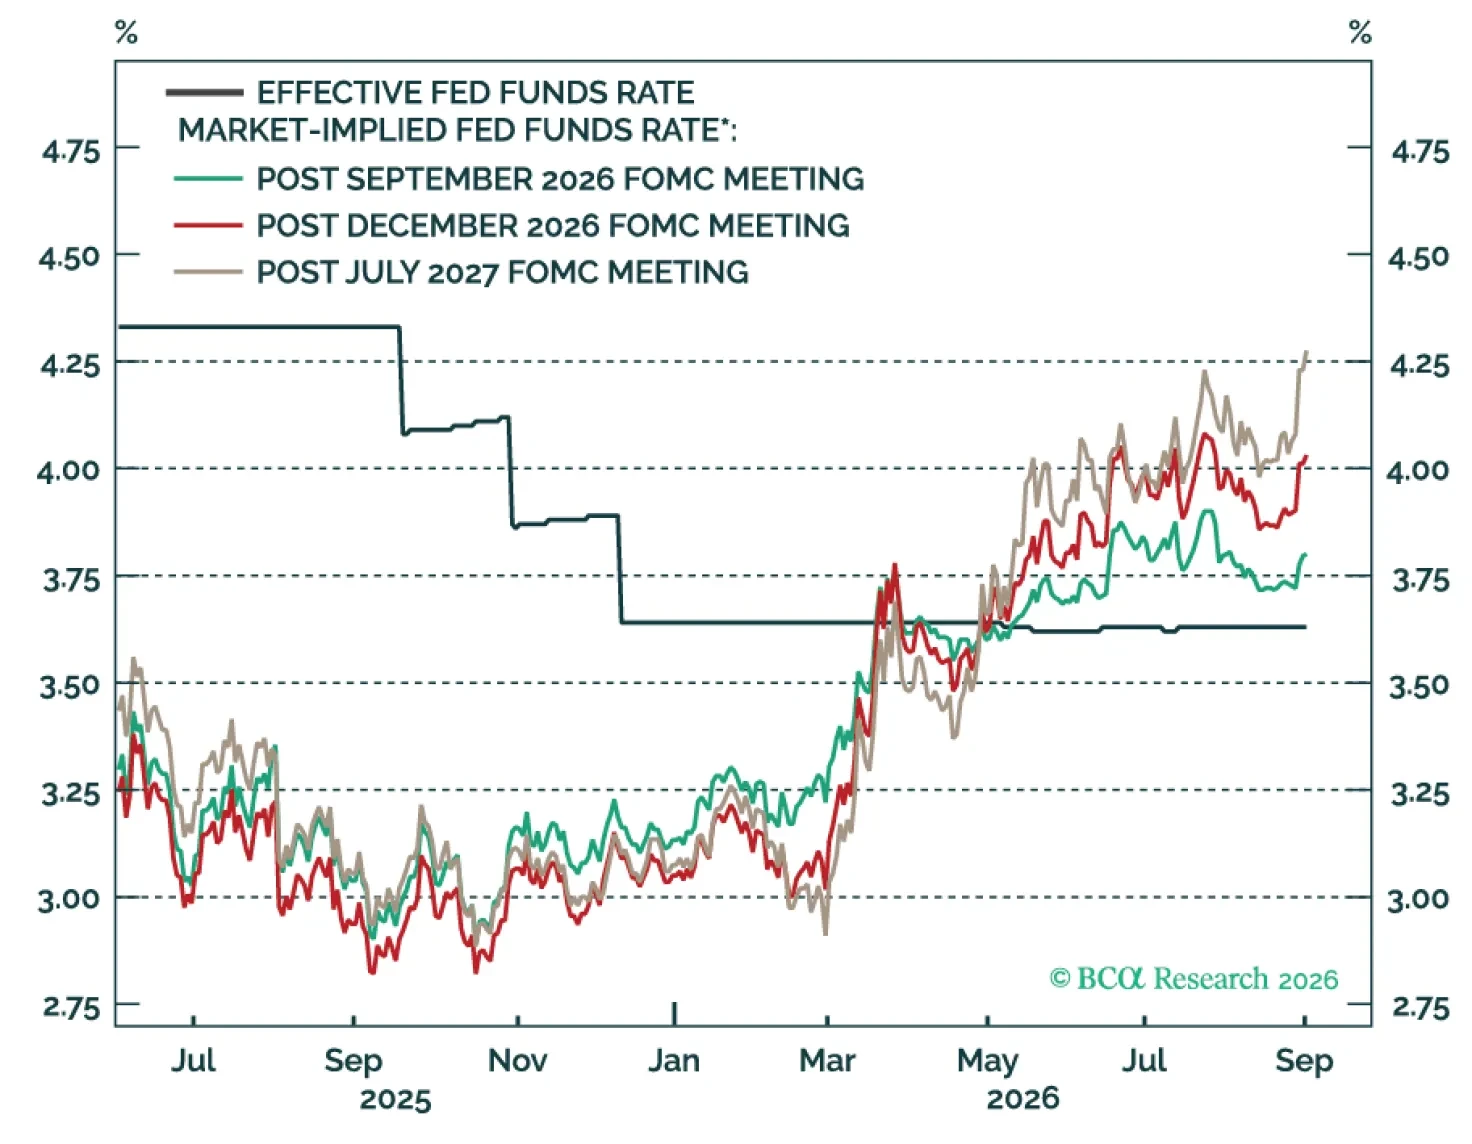
The Fed will hike rates at a pace of 25 bps per quarter until either falling inflation or tighter financial conditions cause it to stop.
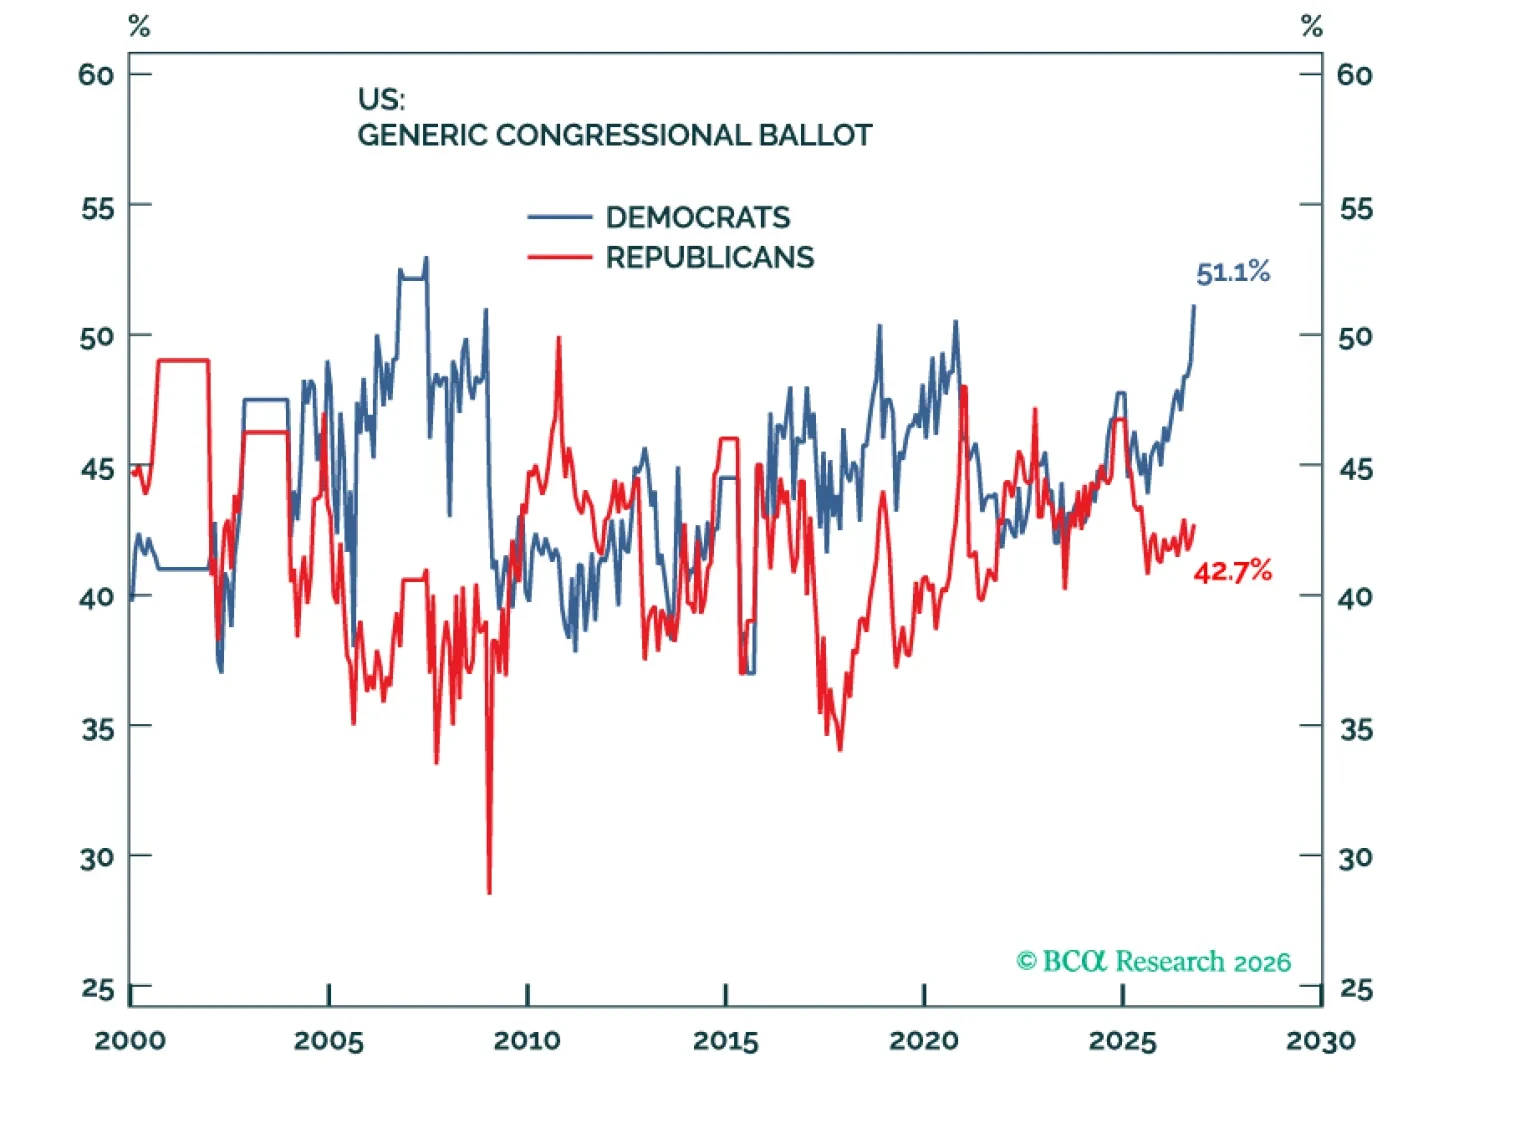
Democrats will win both houses in the midterm, but beyond near-term volatility, none of the outcomes pose a major market risk. The vote is more important as a signal of an anti-business turn in US policy in coming years, which markets could start to price in late 2027 or early 2028.
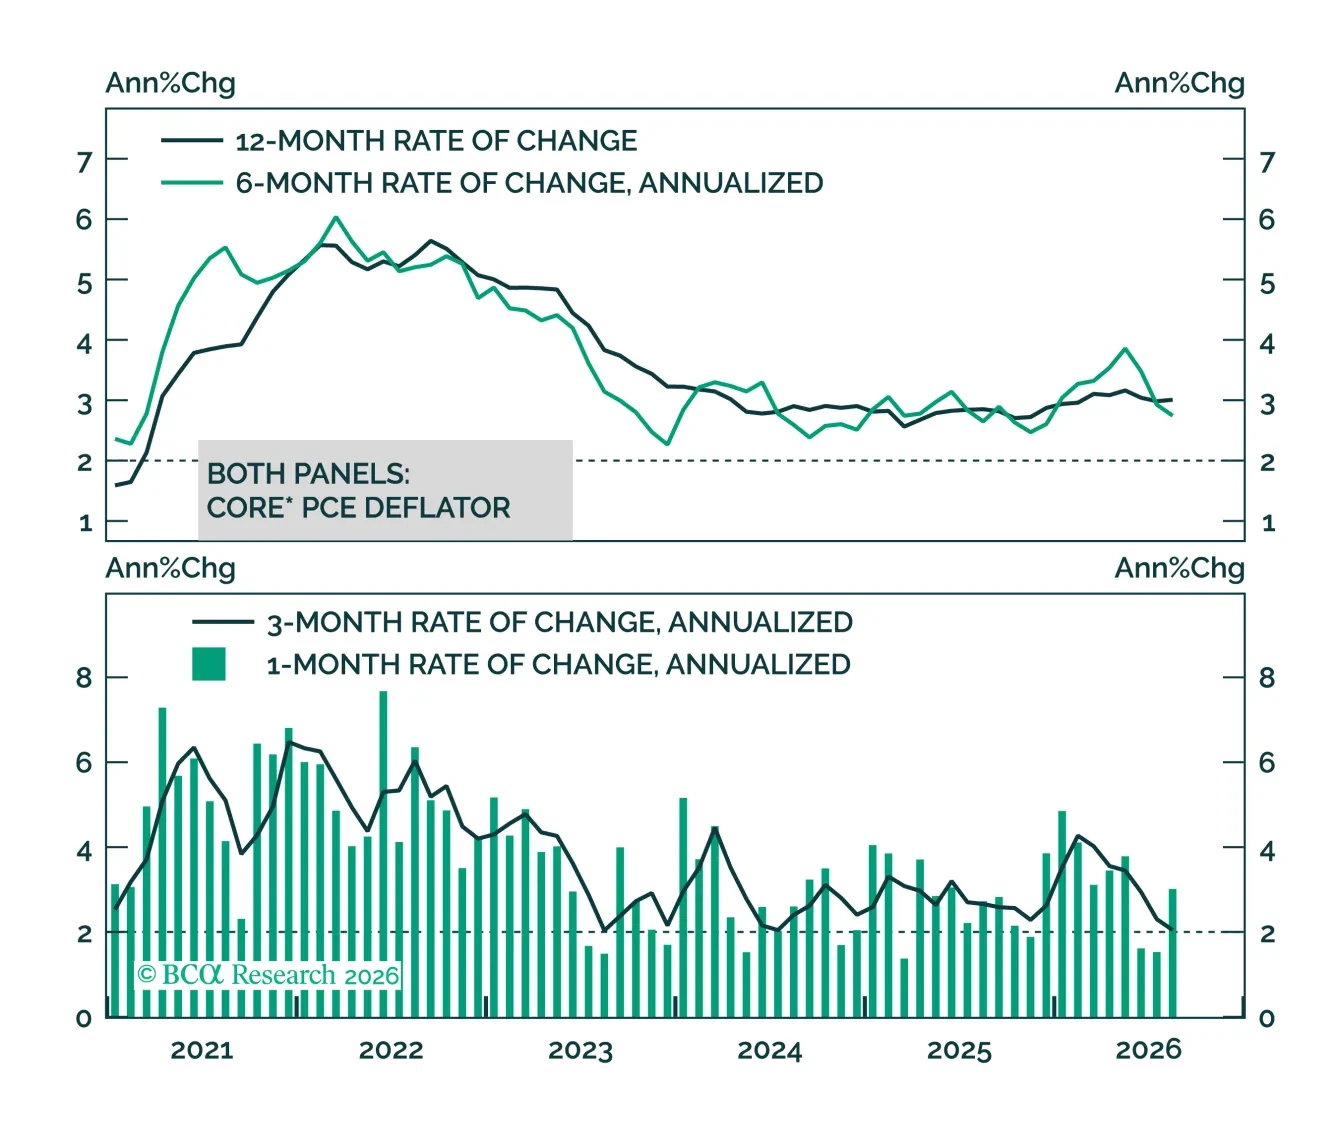
Core US inflation is still running above target. But this morning’s data revisions reveal that the gap is not nearly as large as it appeared yesterday.
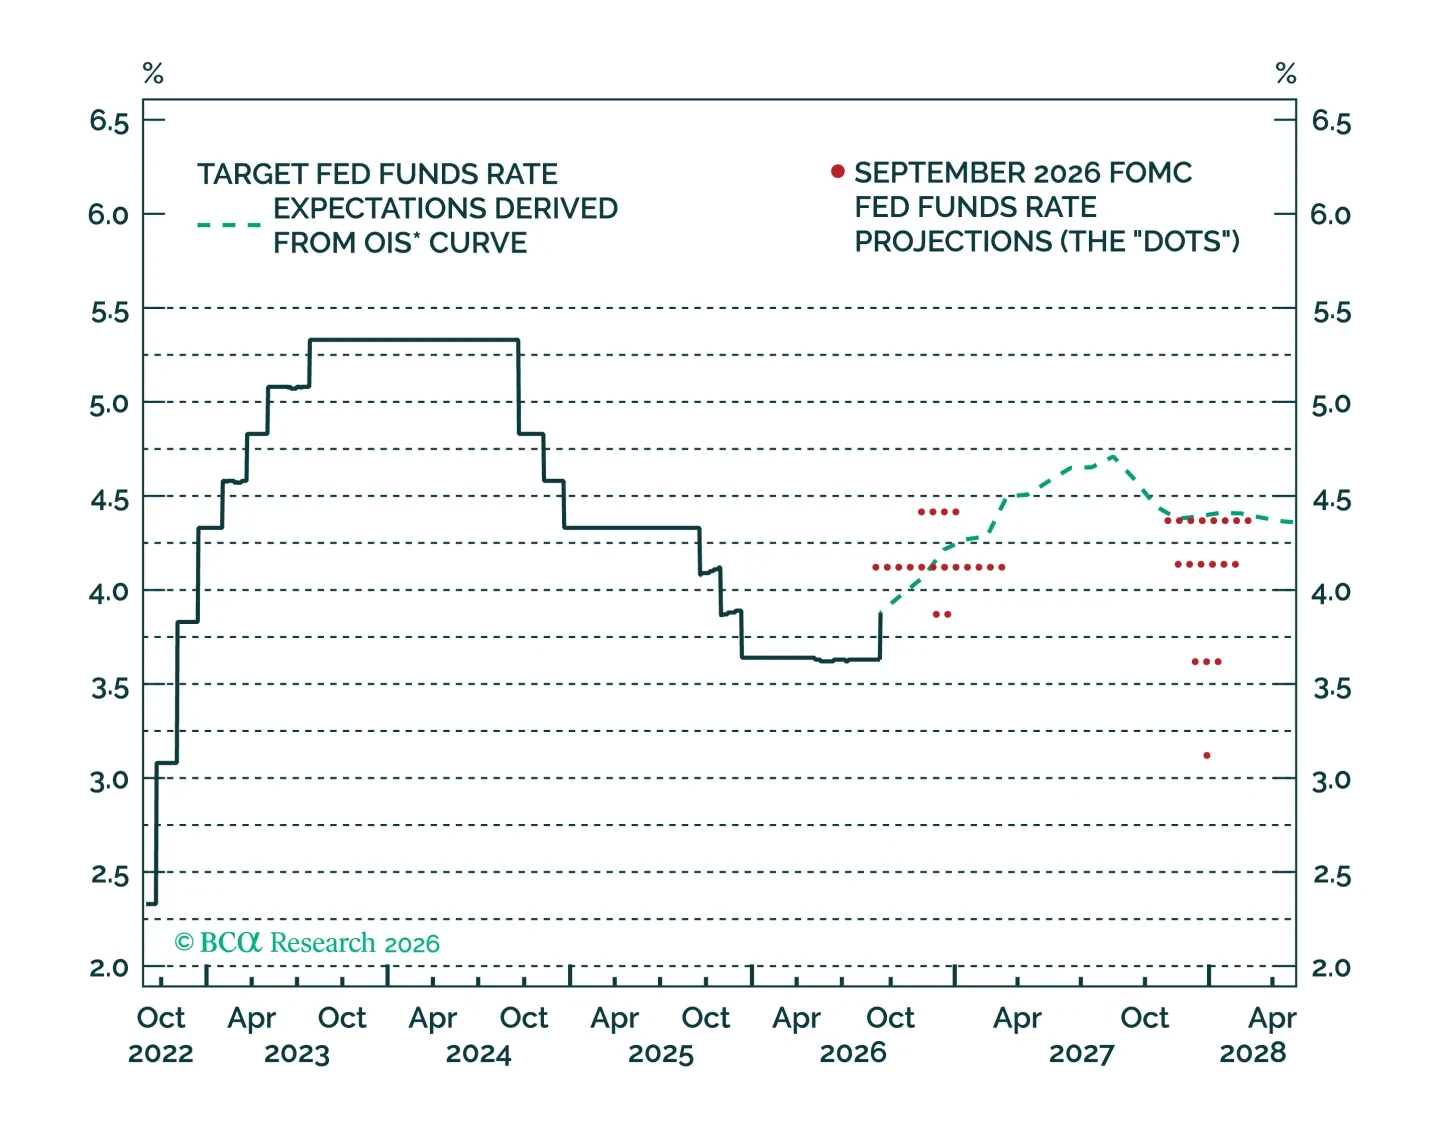
The Fed is unanimous in expecting a mild tightening cycle of no more than 75 bps, but that outcome is contingent on a rapid drop in core inflation in 2027.

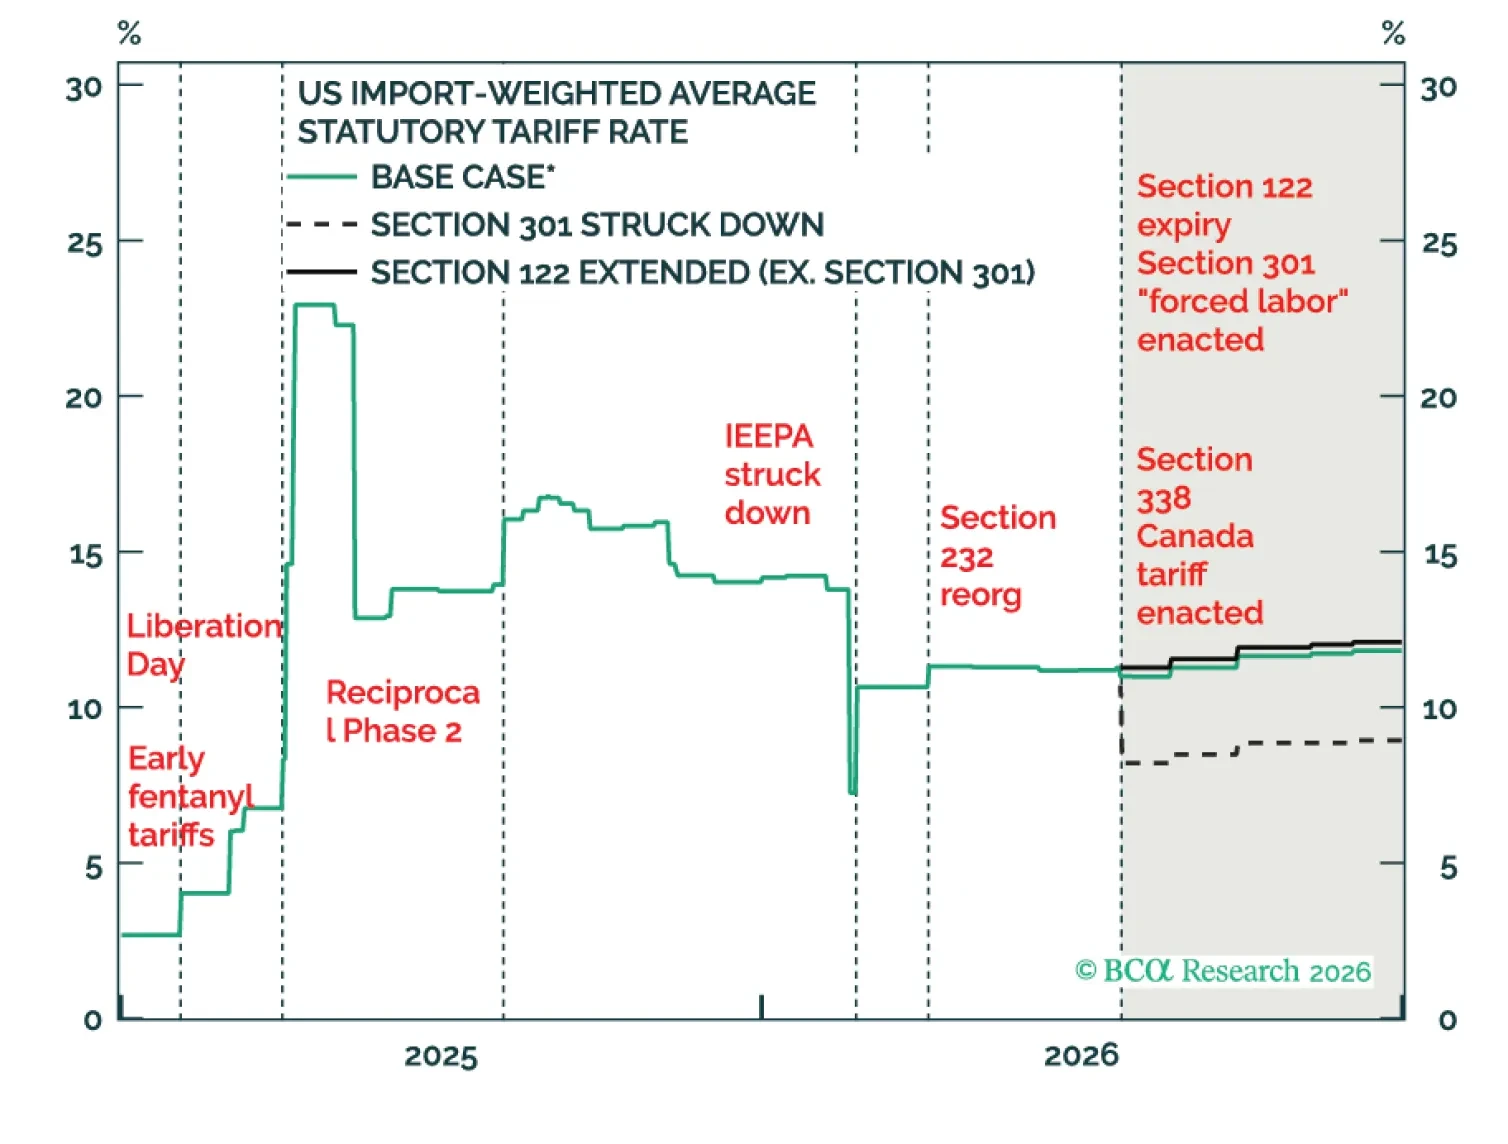
President Trump is raising tariffs again, now through 2027 – and more countries will retaliate this time. While markets can climb over “Liberation Day 2.0,” investors should be wary of today's aggressive policies engendering drastic policy change in 2028.
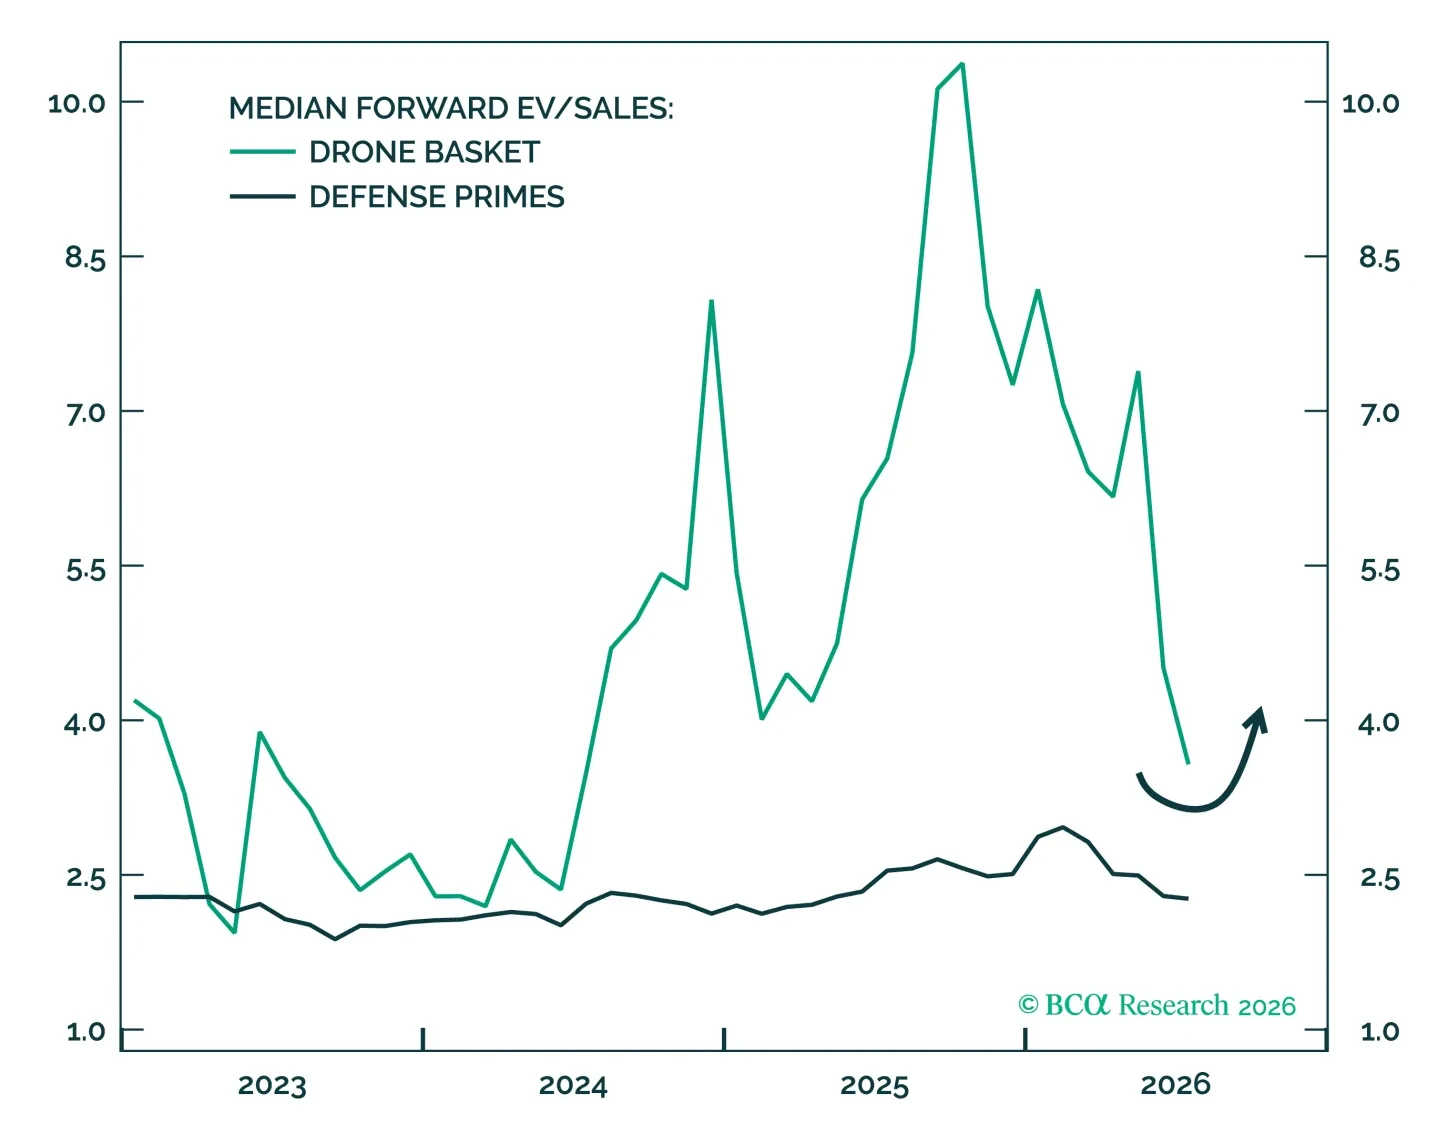
US aerospace and defense stocks still have a structural tailwind from geopolitics, but face rising cyclical challenges from macro and market fundamentals, as well as eventual Iran and Ukraine ceasefires and political change in the United States.
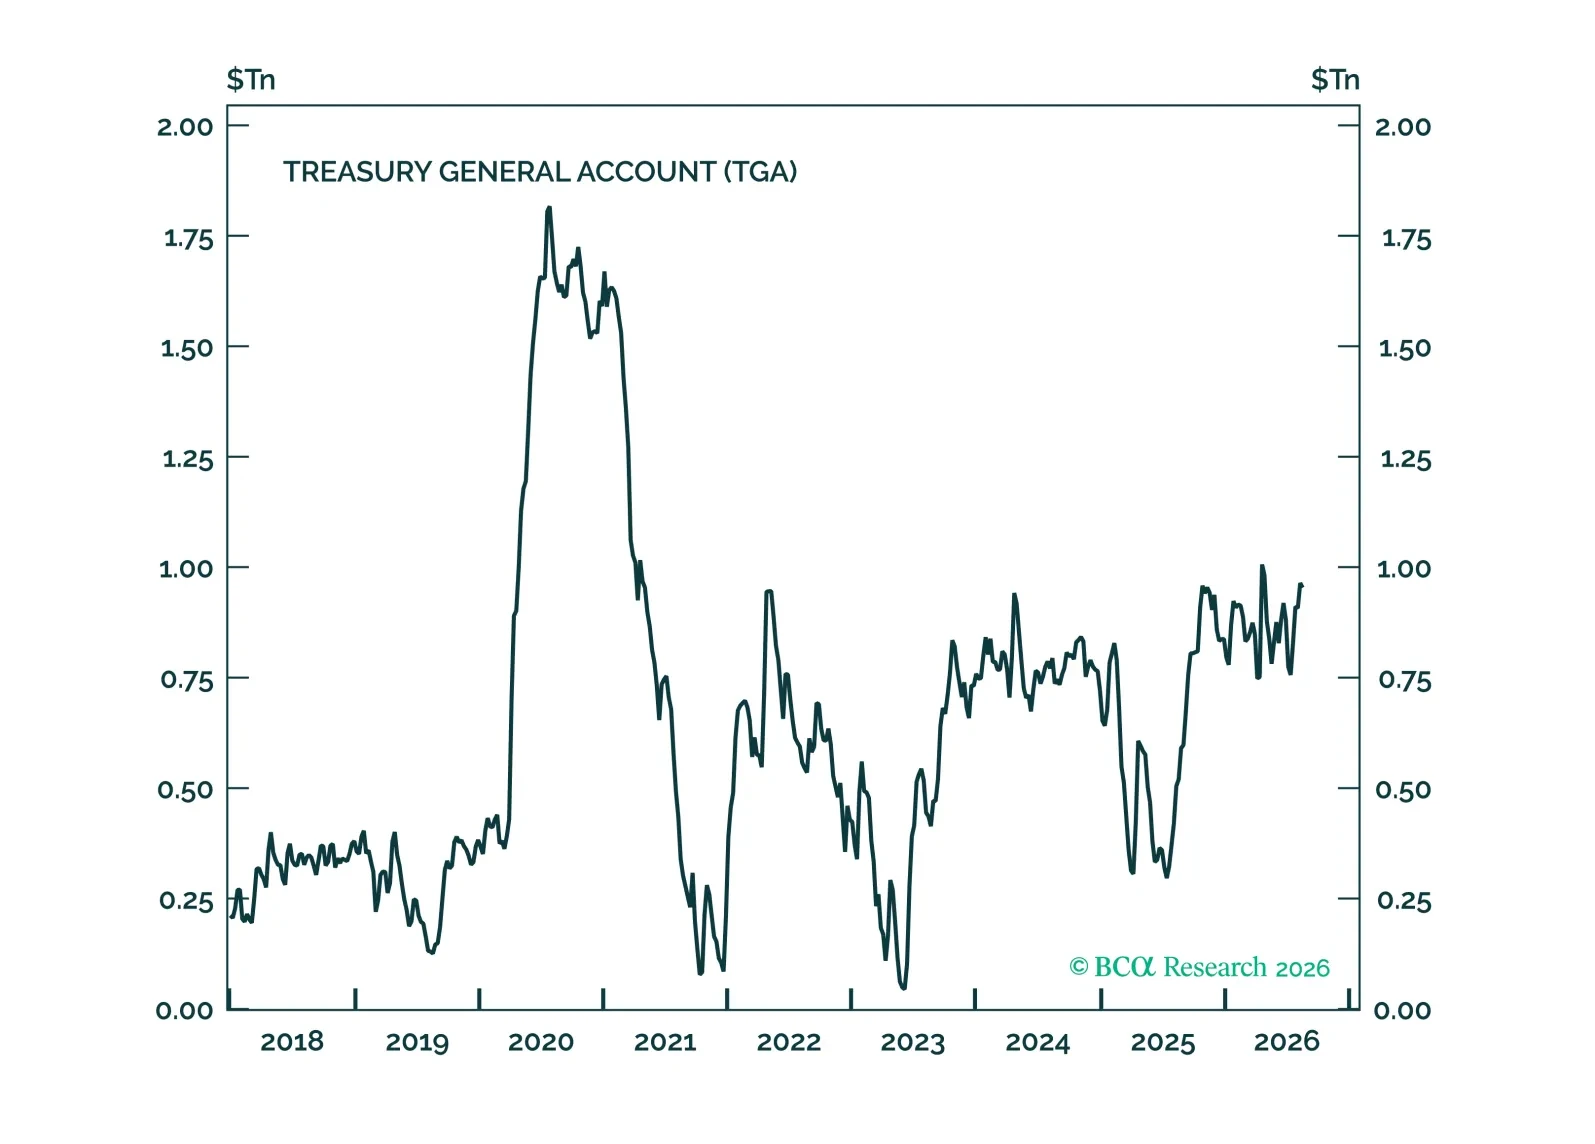
The US Treasury department’s attempts at yield suppression are doomed to fail unless the Federal Reserve gets involved.