 Explore CoreMacro
CoreMacro | Emerging Markets
Emerging Markets research - including in-depth country reports. Typically published four times a month.
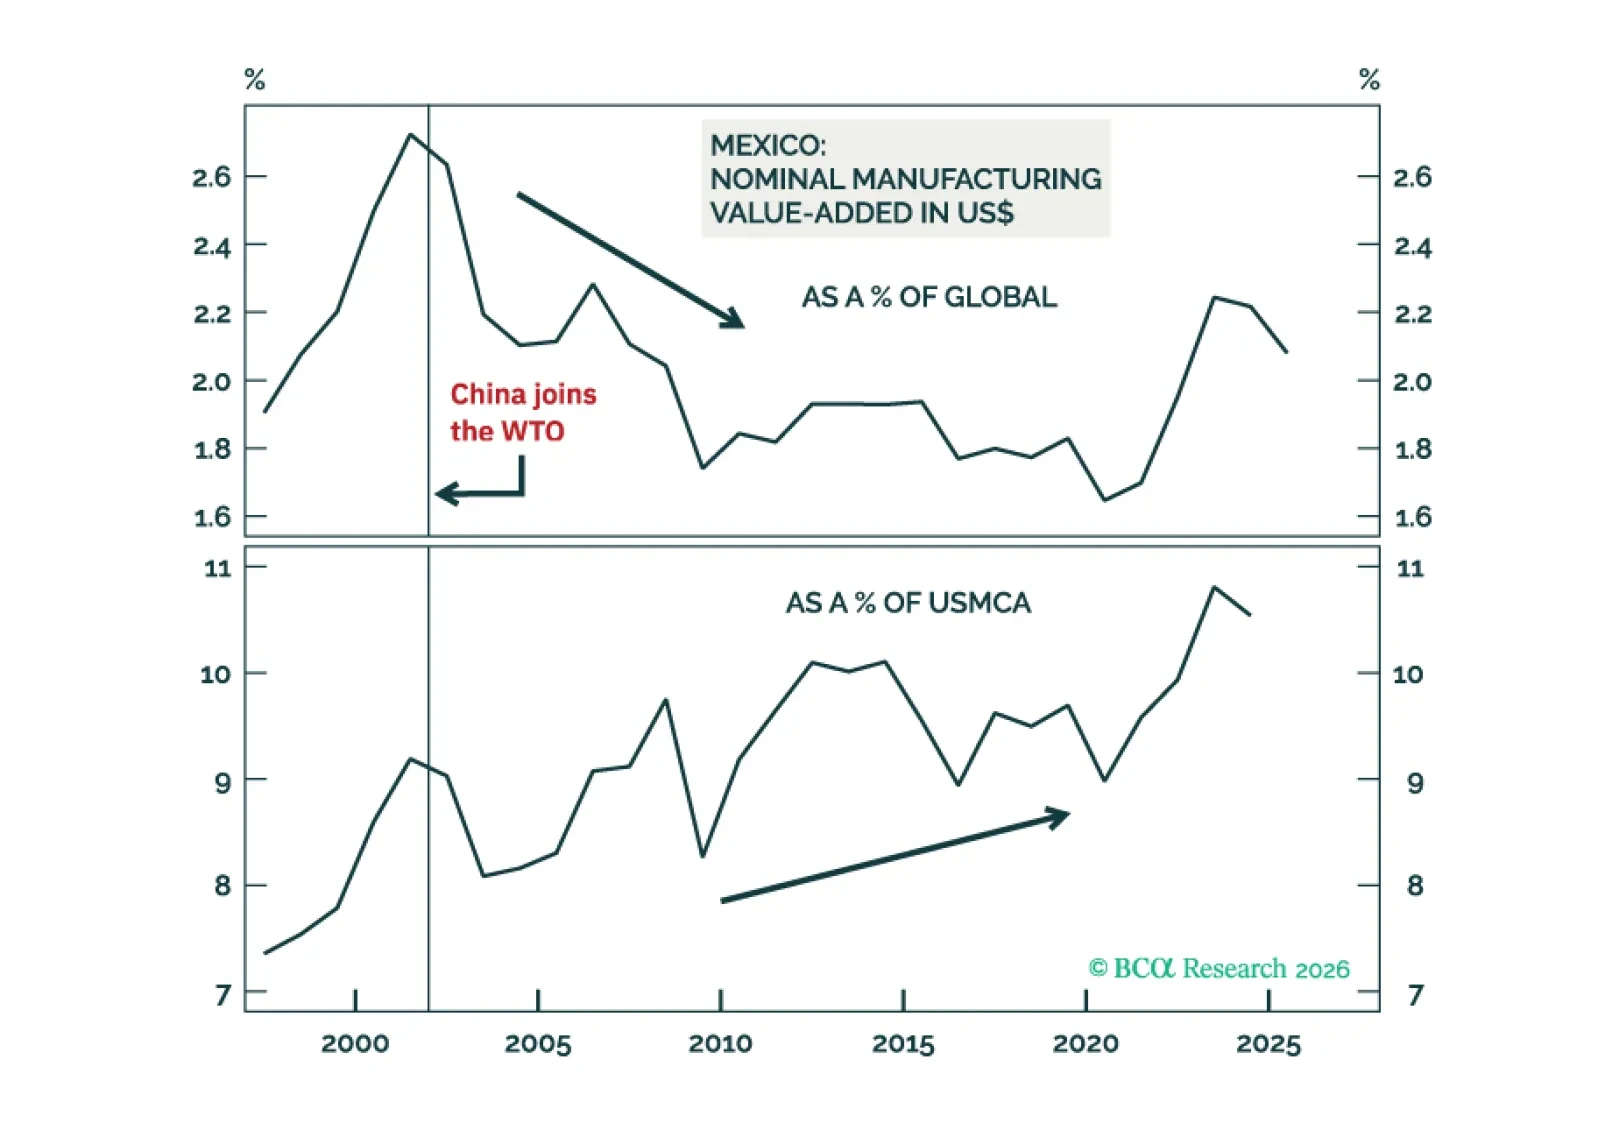
We continue to overweight Mexican stocks, local bonds, sovereign credit, and currency within their respective EM portfolios. Also, stay long Mexican equities / short the S&P500.
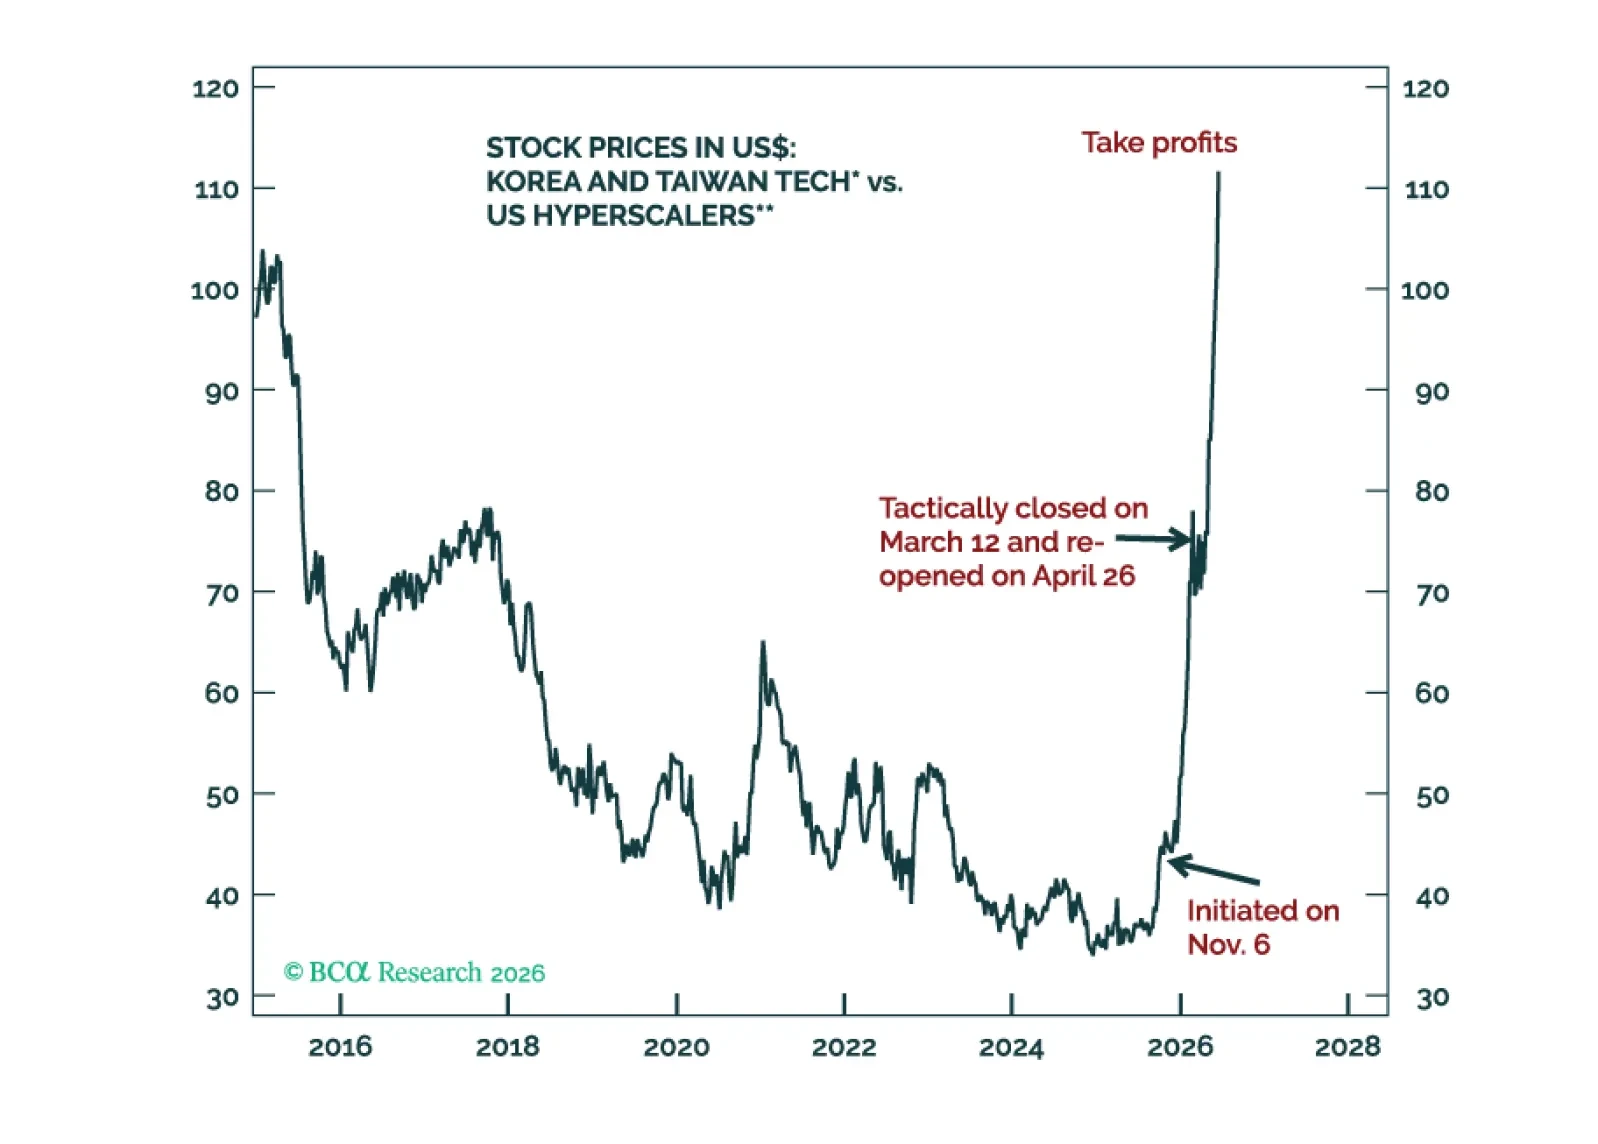
Korea’s recent equity market tantrum is a warning signal for global risk assets. We are booking profits on the long Asian semiconductor stocks / short US hyperscalers trade and downgrading Korea from overweight to neutral in an EM equity portfolio.
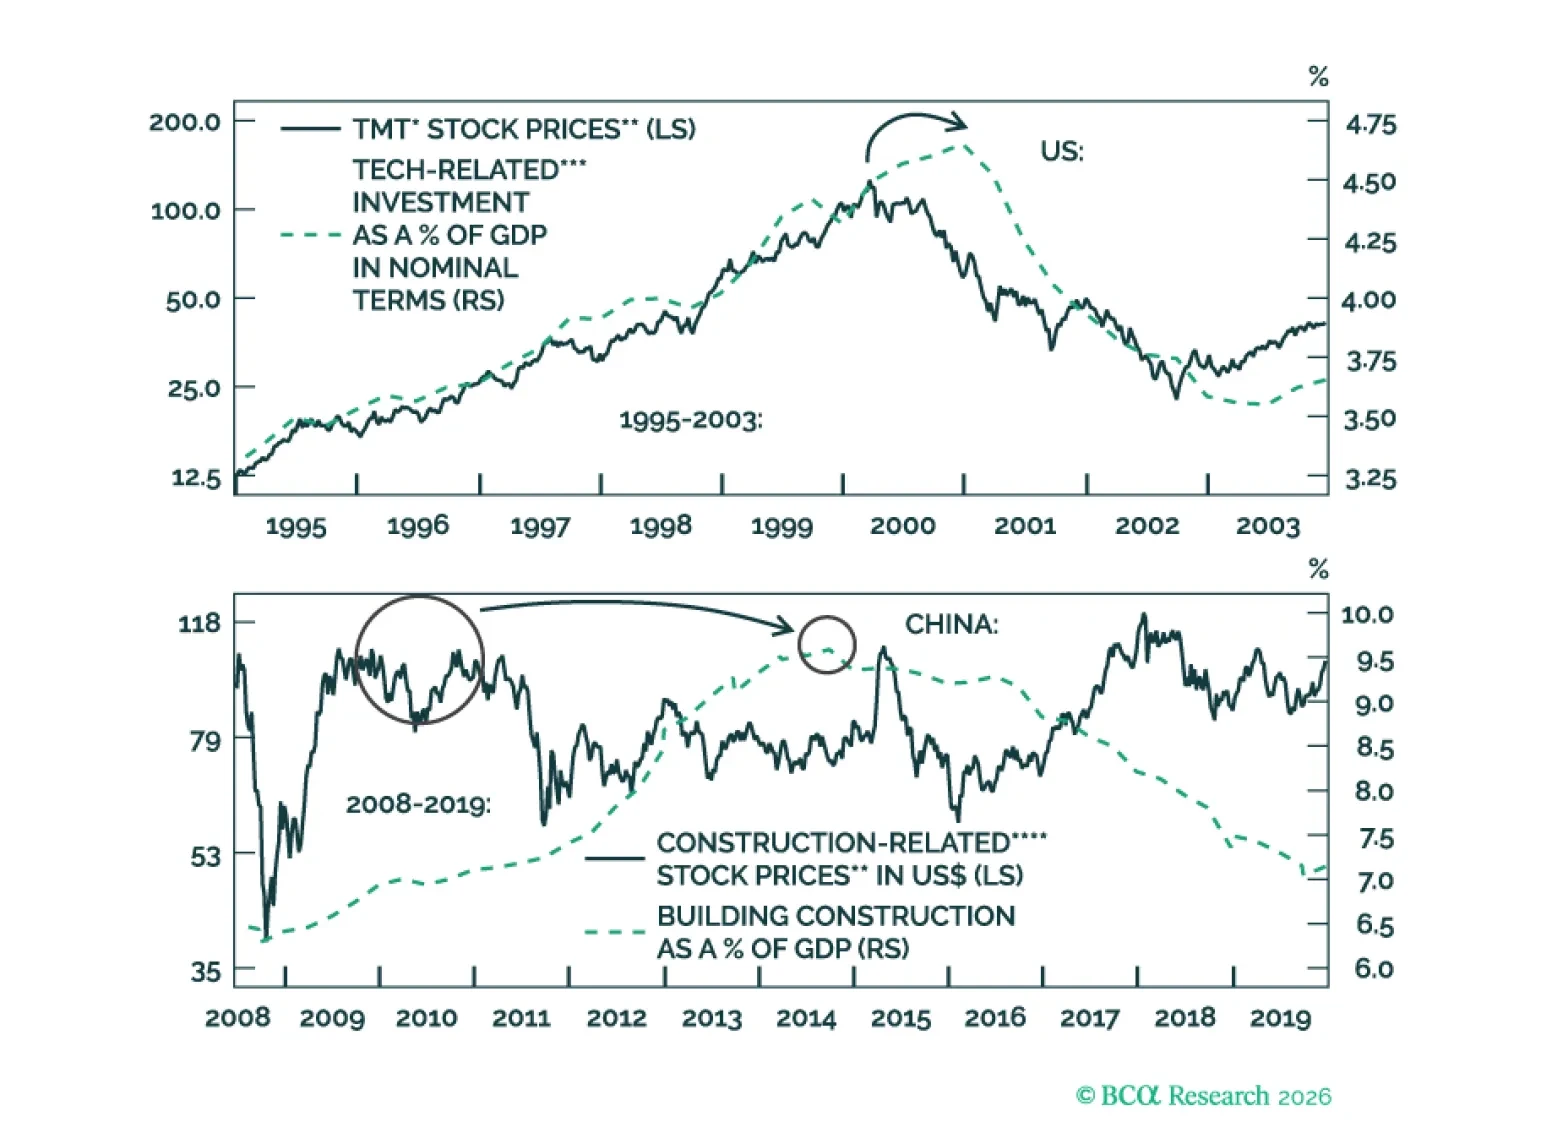
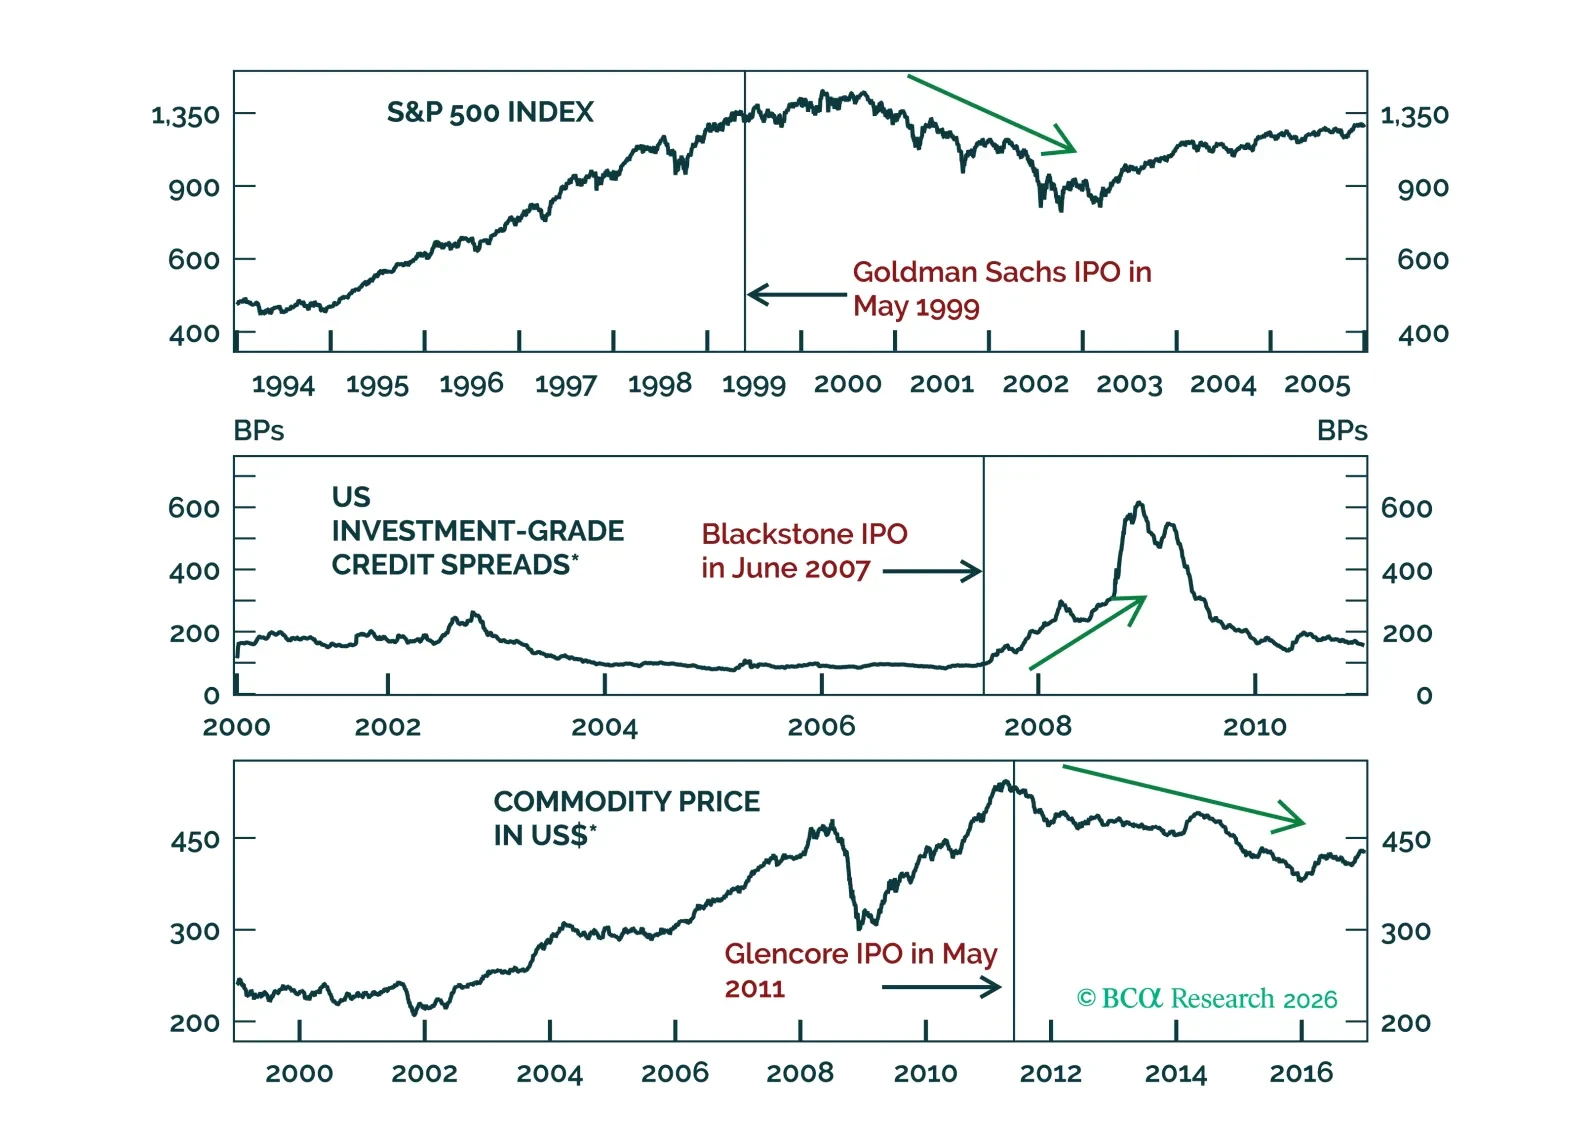
AI is transformative, yet tech stocks may not produce positive returns. Market cycles have not disappeared. Greed and fear will still produce large share price fluctuations. Meanwhile, US inflation is the key near-term risk. Global non-tech capex aspirations also look overstated.
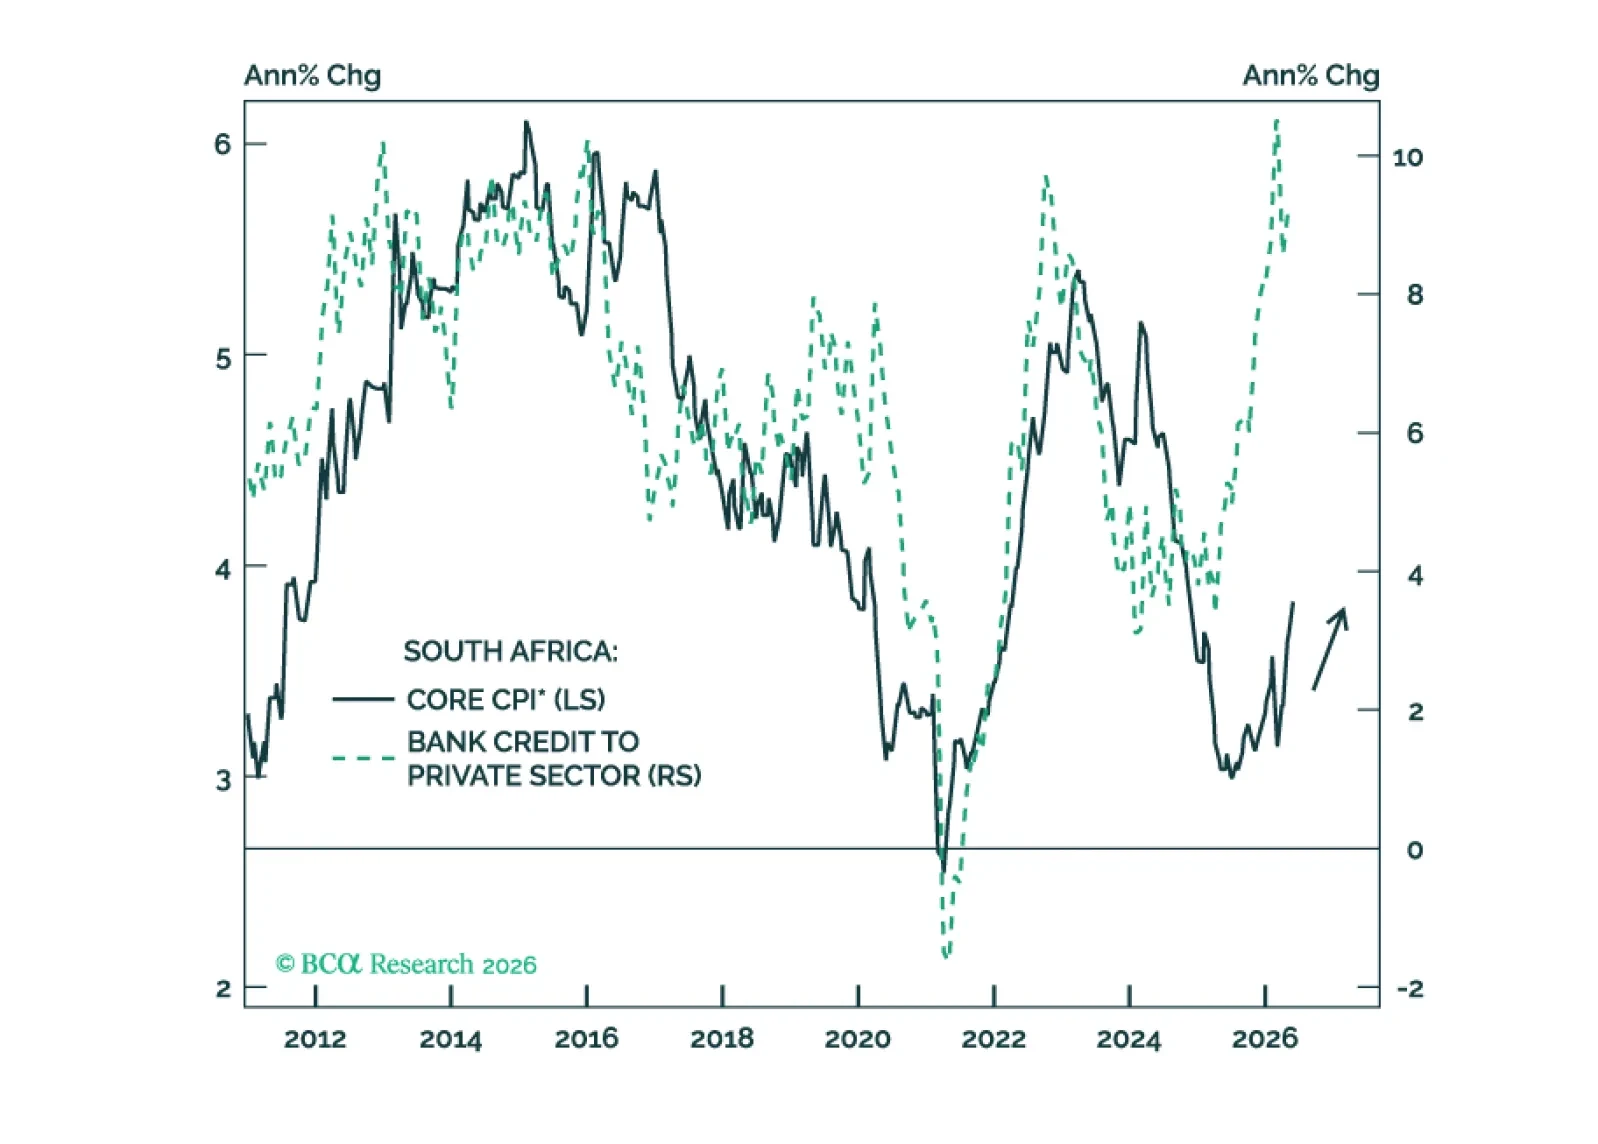
South Africa’s ambitious reform agenda will take time to bear fruit. Meanwhile, the country faces a stagflationary squeeze as inflation rises while growth slows. South African stocks, bonds, and currency are all vulnerable.
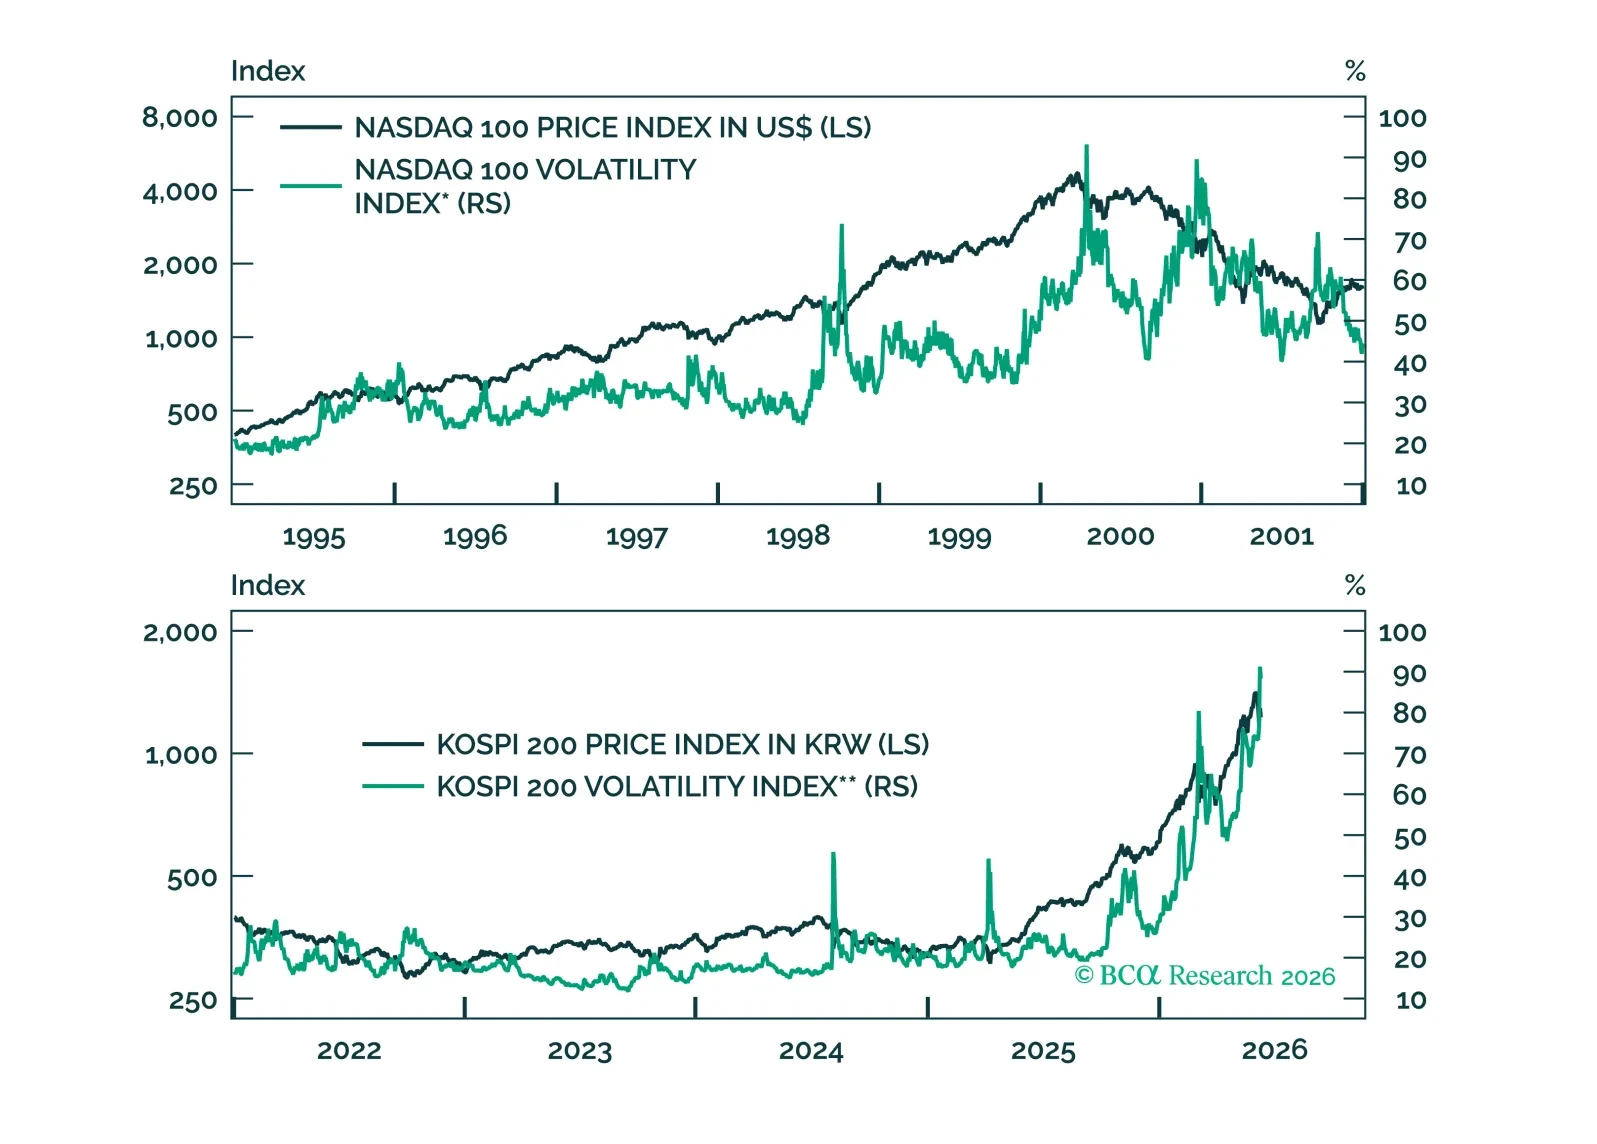
Rising volatility in Korean markets captures a late-cycle surge in which euphoria and drawdown risk are rising together. While KOSPI momentum remains intact, the bigger opportunity may be emerging in the increasingly mispriced KRW, which could rally meaningfully as portfolio flow headwinds fade.
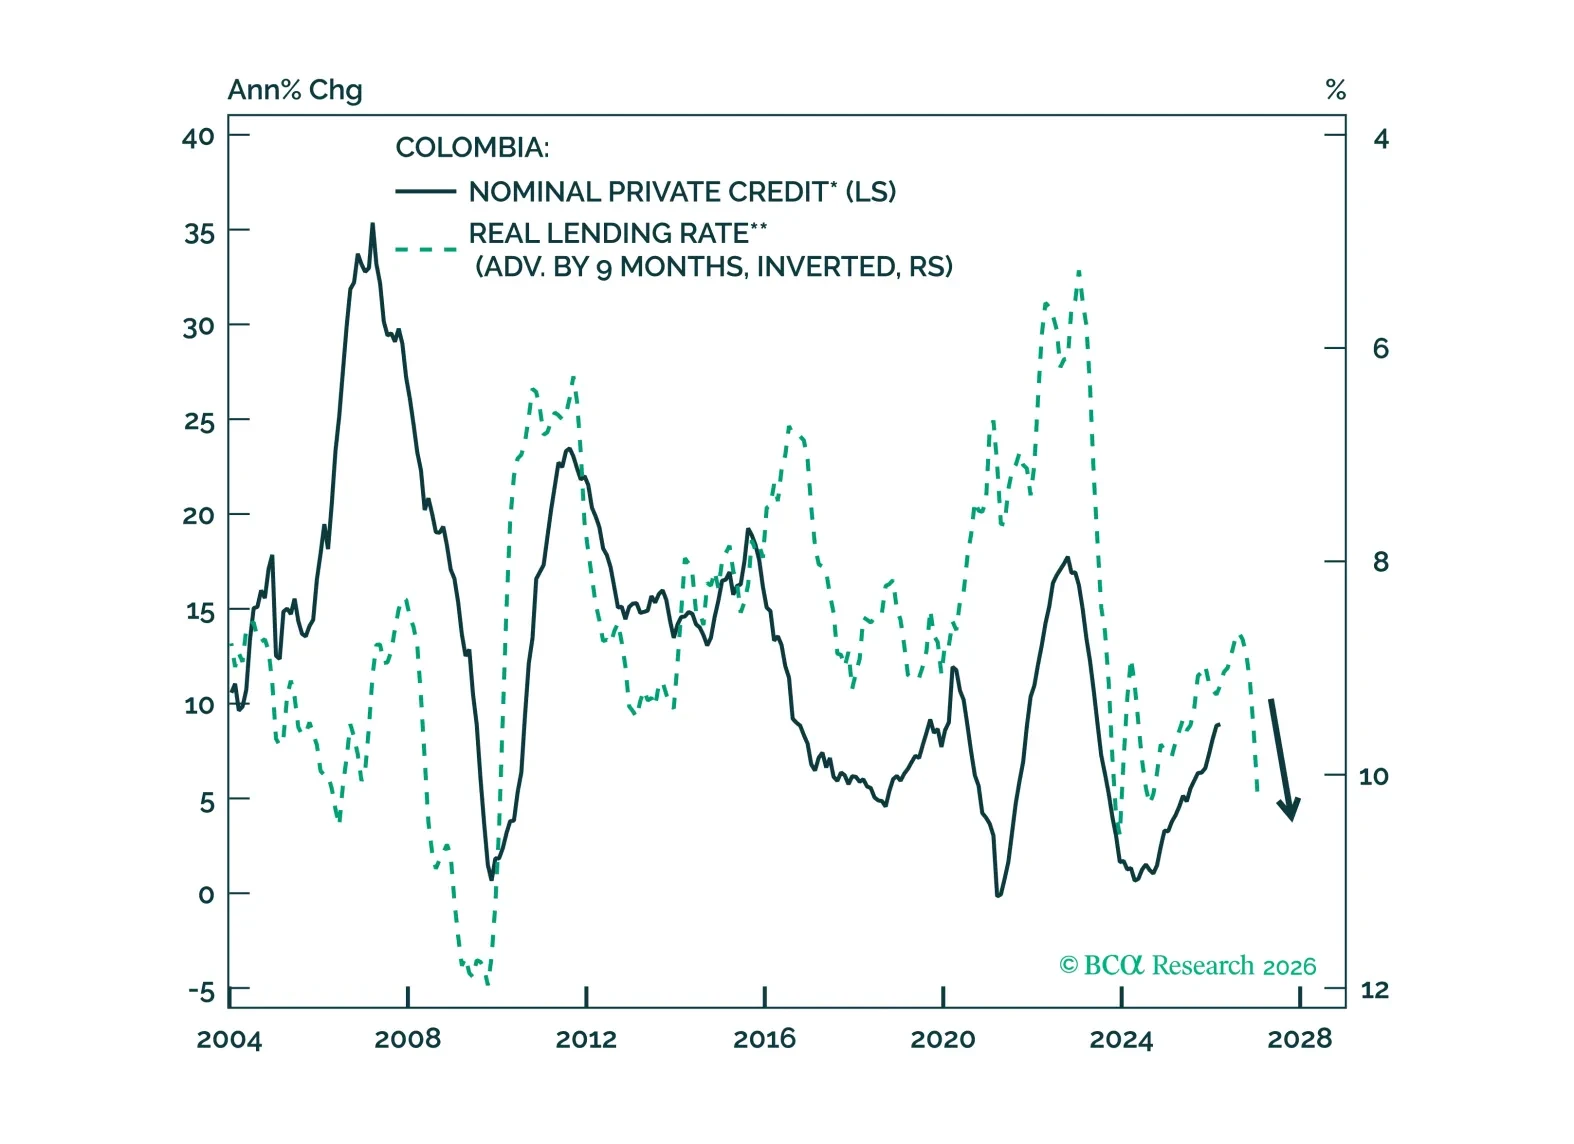
The rally in Colombia’s financial markets has a short shelf life. The election will bring a right-wing government, but it cannot fix inflation, fiscal arithmetic, or balance-of-payments vulnerabilities. Use the near-term rally to downgrade Colombian fixed income and equities.
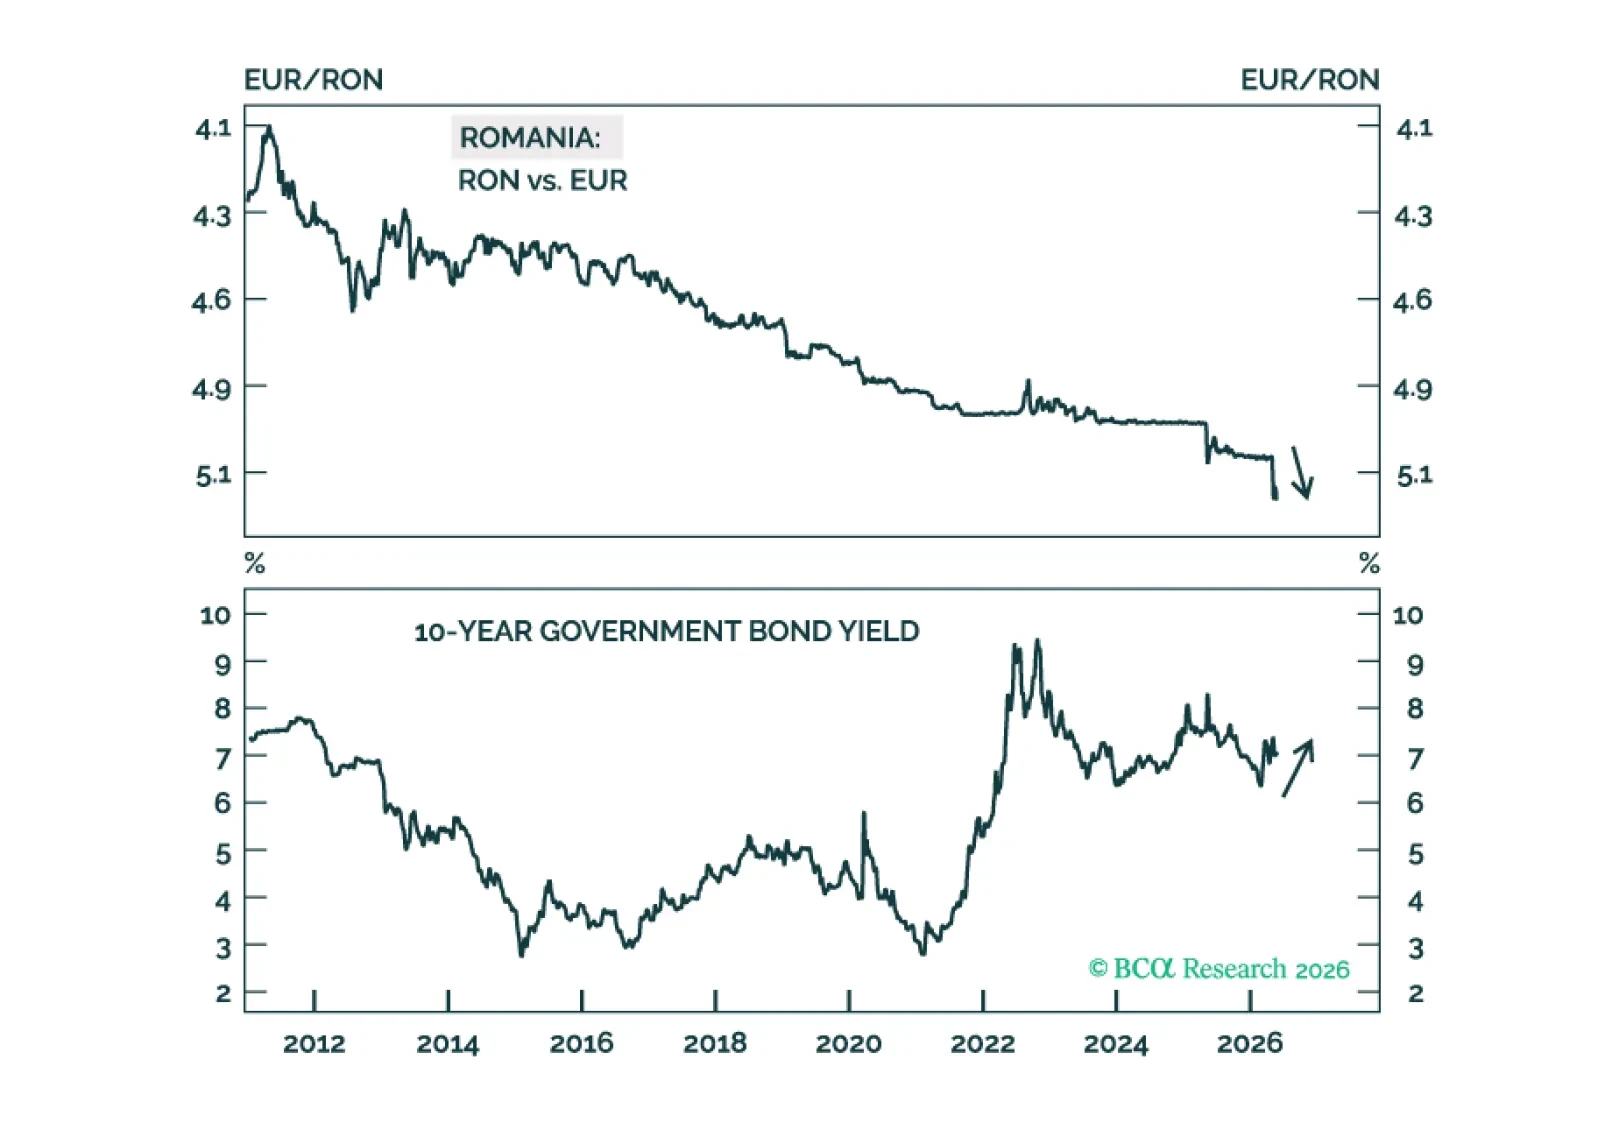
In Romania, large fiscal and current account deficits, high inflation, negative real rates, an overvalued exchange rate, and deteriorating growth point to budding currency devaluation. Investors should short the Romanian currency versus the euro and underweight Romanian local bonds, equities, and sovereign credit.
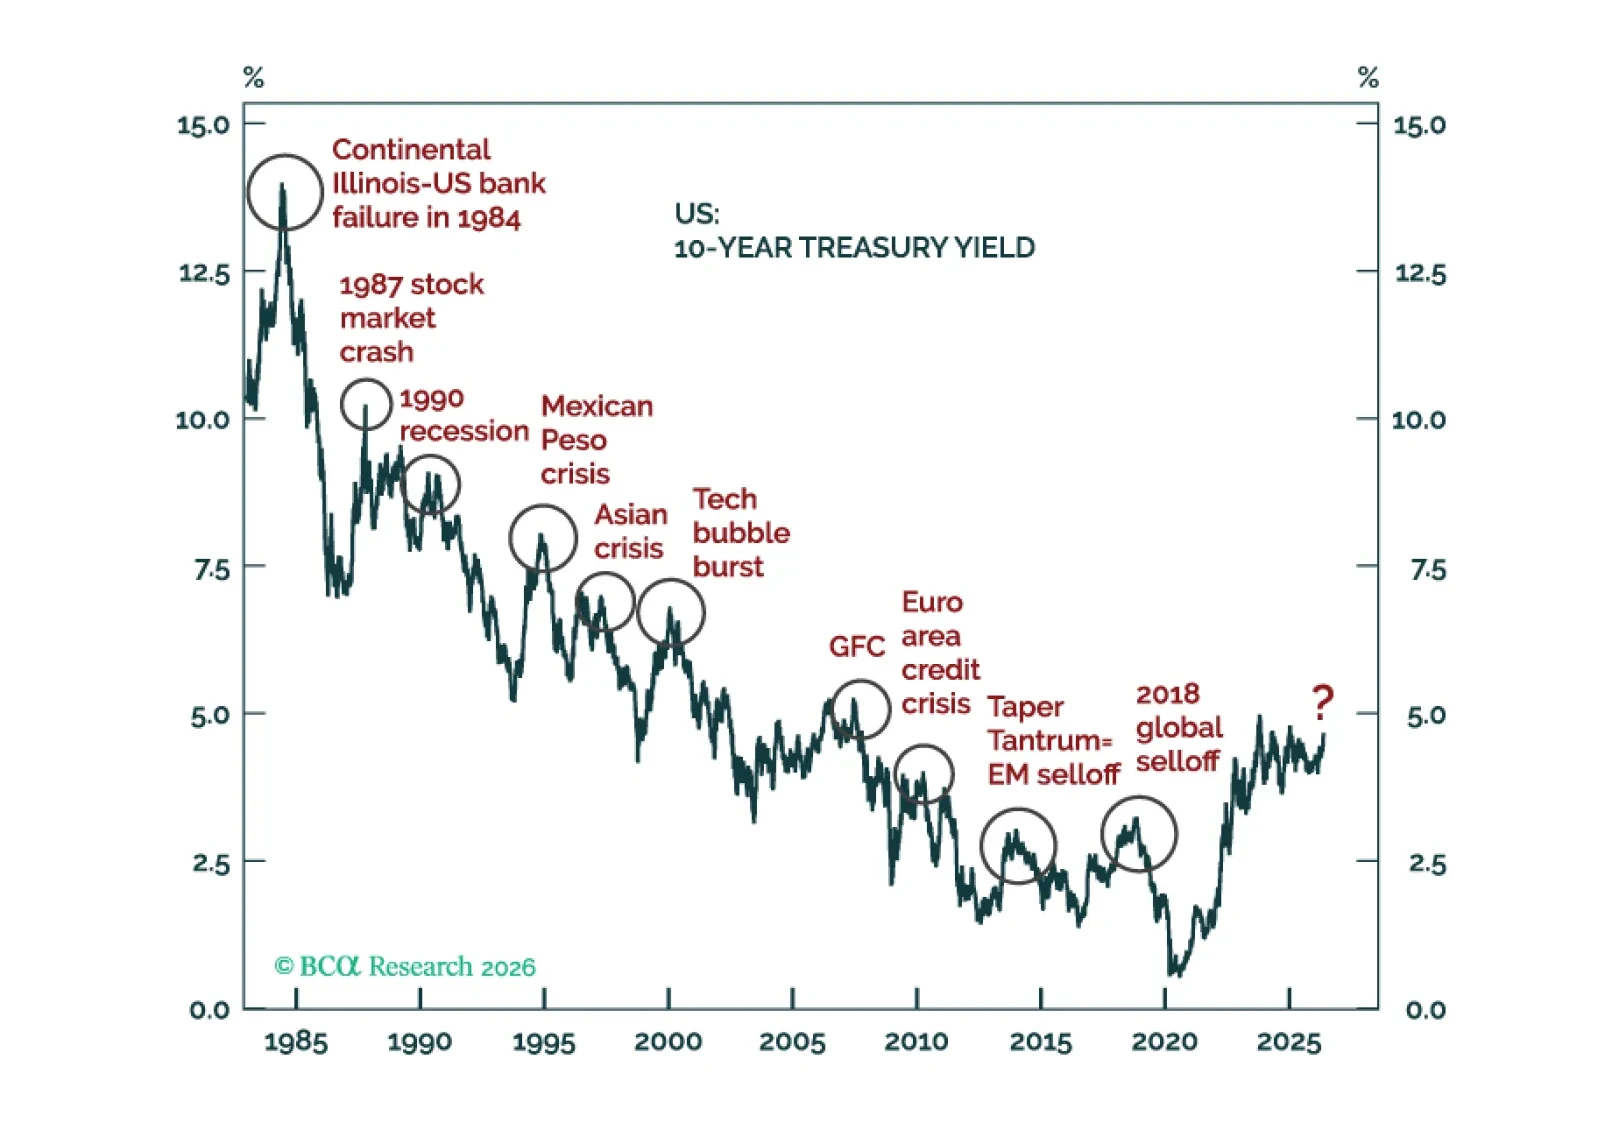
US stocks and bonds are on a collision course. Only a meaningful equity selloff is likely to pull bond yields considerably lower. Global equity risk-reward looks poor. The dollar will stay firm near term, but its medium- and long-term outlook remains bearish.
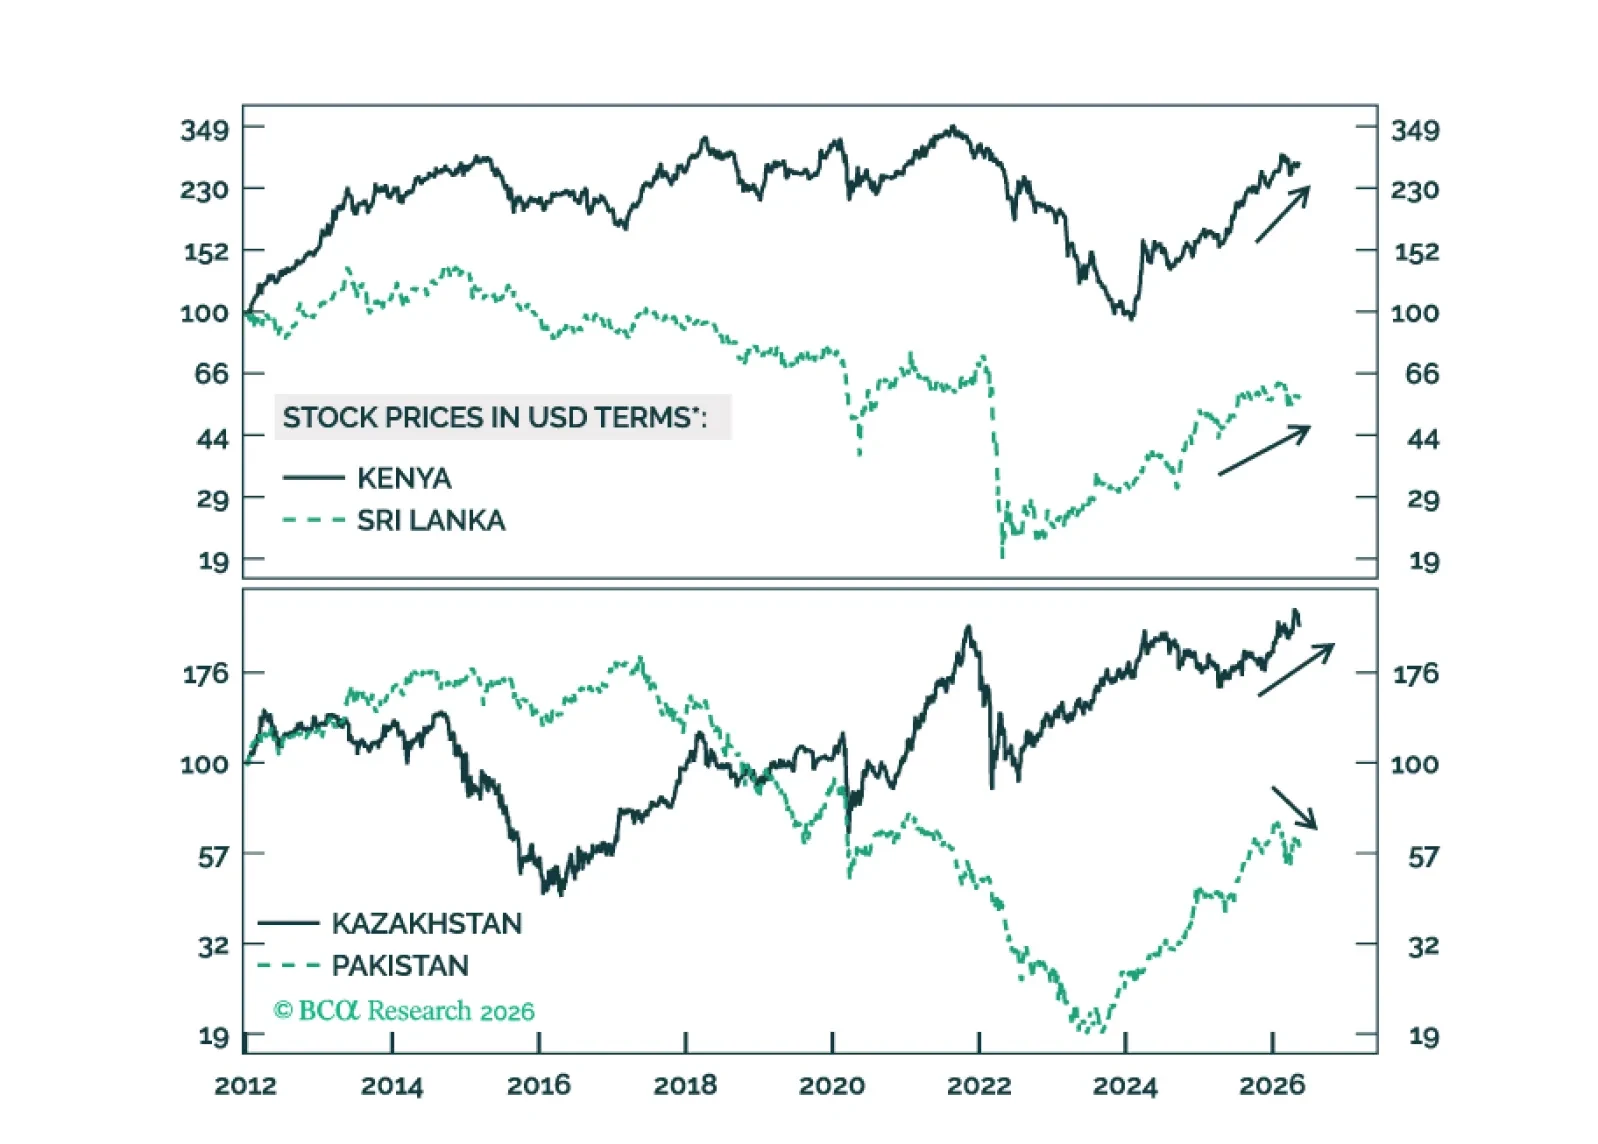
The divergence across frontier markets is likely to widen. Kenya, Kazakhstan, and Sri Lanka are well placed to outperform, while Pakistan is vulnerable. We offer several trade ideas to capture this divergence.