 Explore CoreMacro
CoreMacro | Emerging Markets
Emerging Markets research - including in-depth country reports. Typically published four times a month.
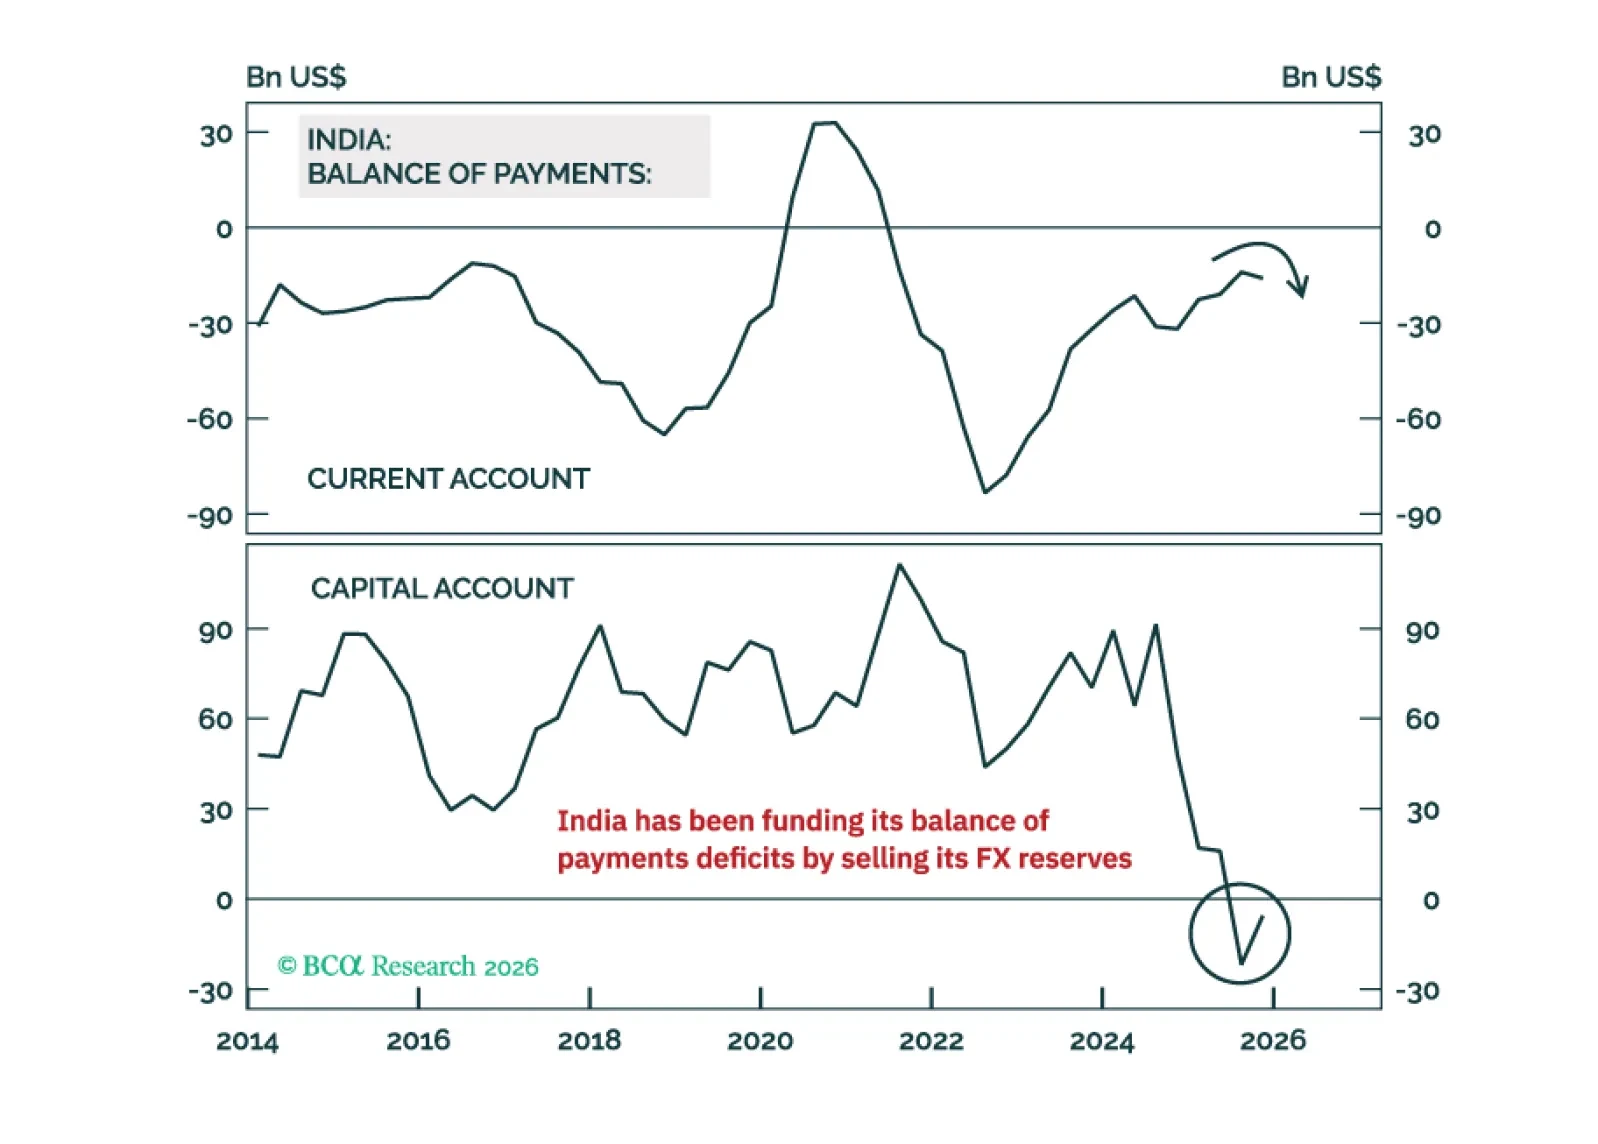
India is probably the most vulnerable among the G-20 economies should the Strait of Hormuz not reopen fully by the end of this month. Growth will slow, while inflation will rise materially. Investors should brace for further weakness in the currency and stock prices.
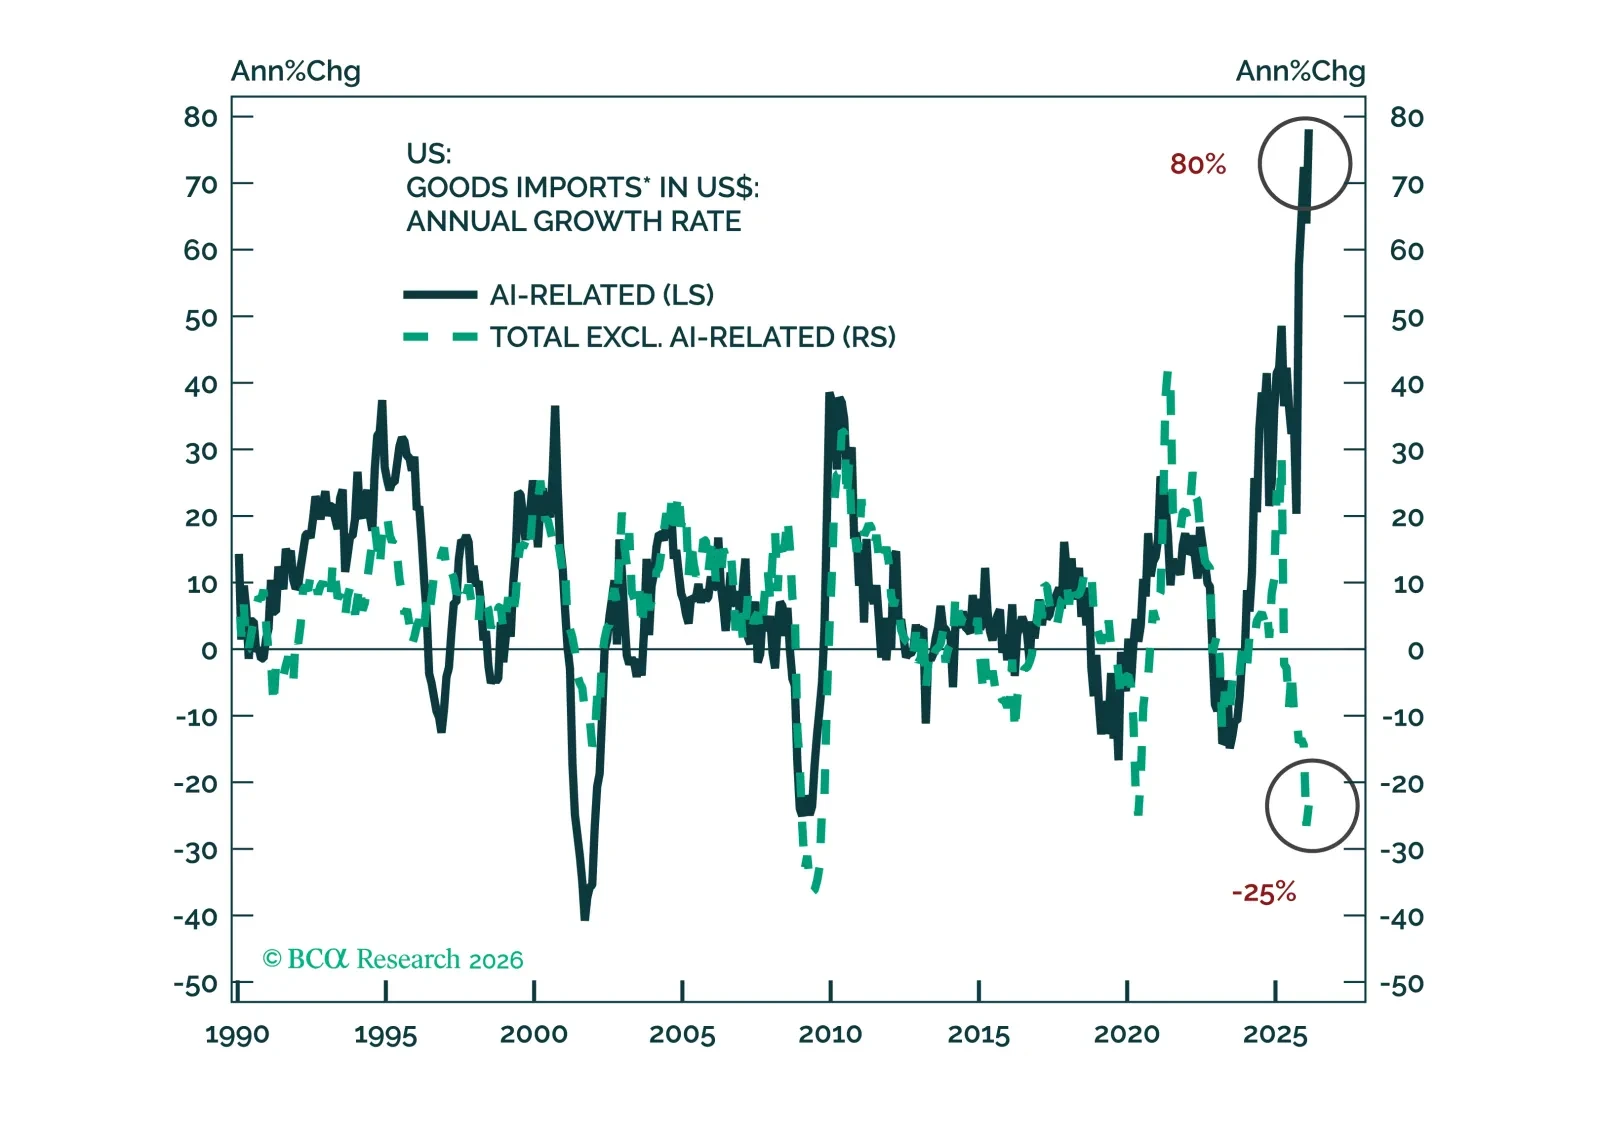
Global trade has held up despite US non-AI import volumes contracting by 25% over the past 12 months. The strength in global trade has concentrated in two areas: (1) imports of AI-related hardware and (2) developing countries’ imports, especially from China. Will these continue?
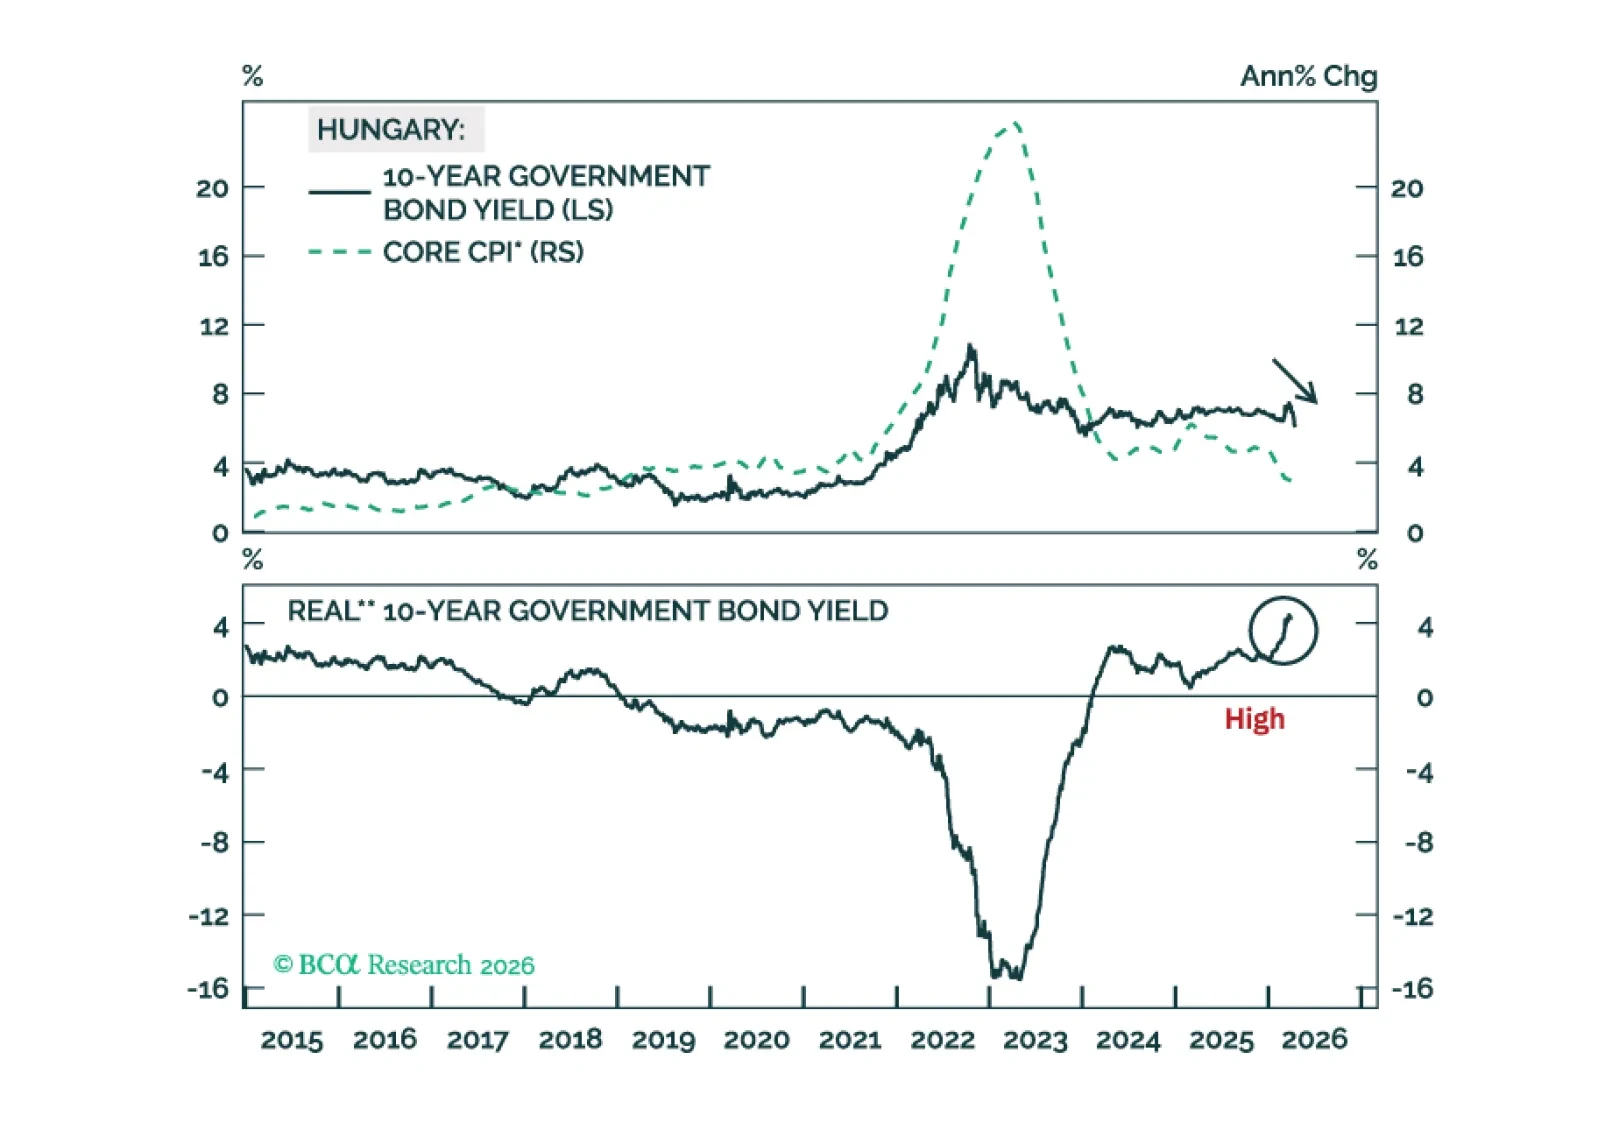
Hungary’s growth outlook has improved as the election of a new government will likely unlock significant EU funds for the country. Currency traders should go long the Hungarian forint / short US dollar.
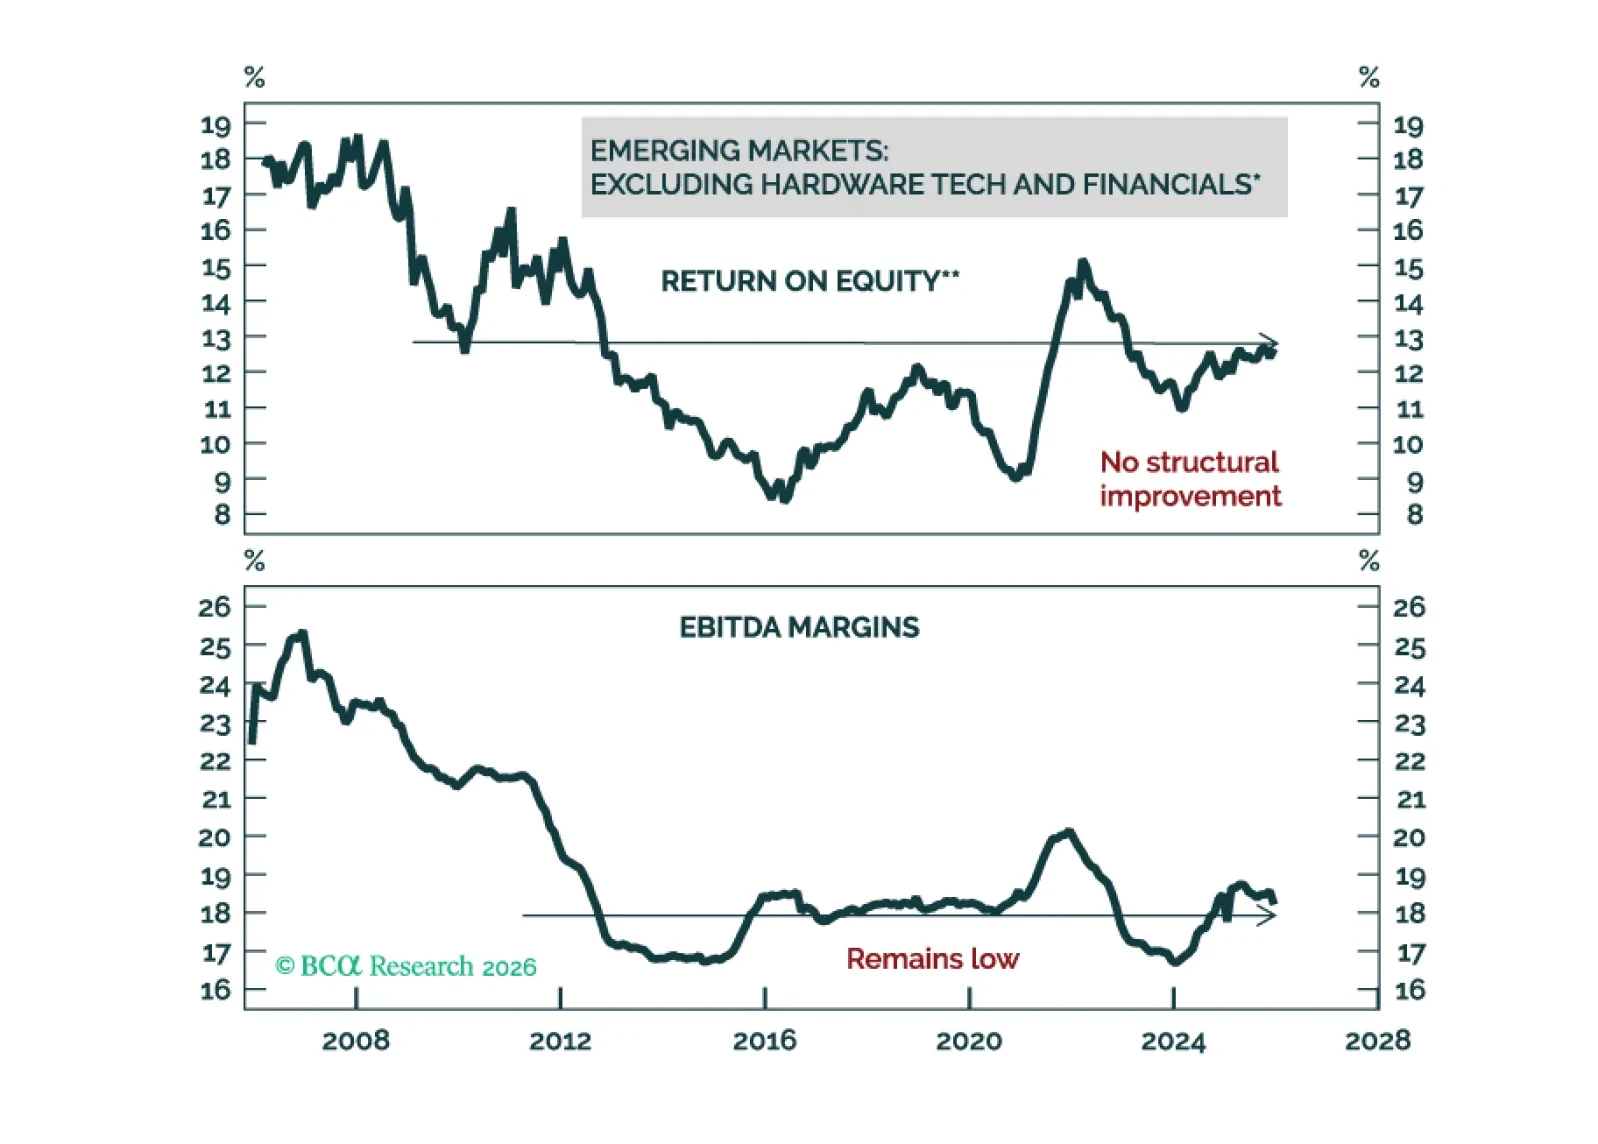
Outside Asian semiconductor producers, EM corporate earnings and profitability have seen little improvement. Despite the ceasefire in the Middle East, the medium-term outlook for EM stocks is still unattractive.
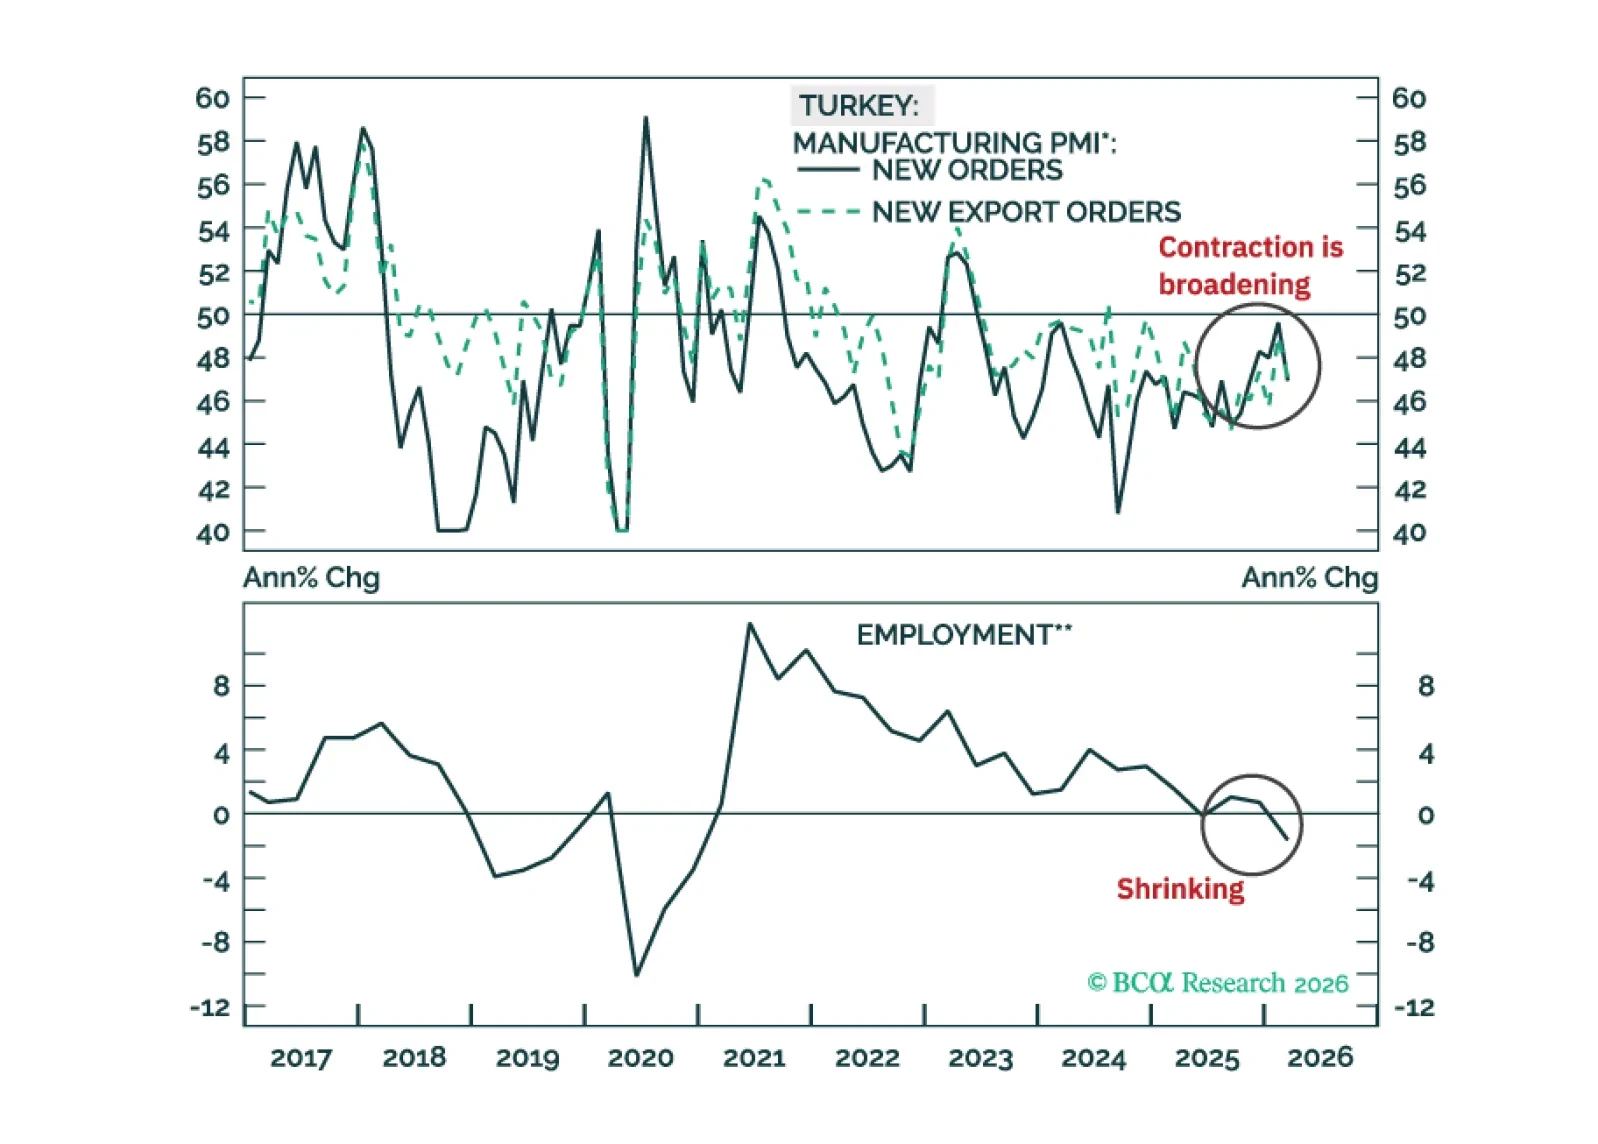
The Turkish financial markets will struggle in the very near term, but beyond that, the cyclical disinflation process will resume. Fixed-income investors should put Turkish 2-year local currencybonds on a ‘buy’ watch list.
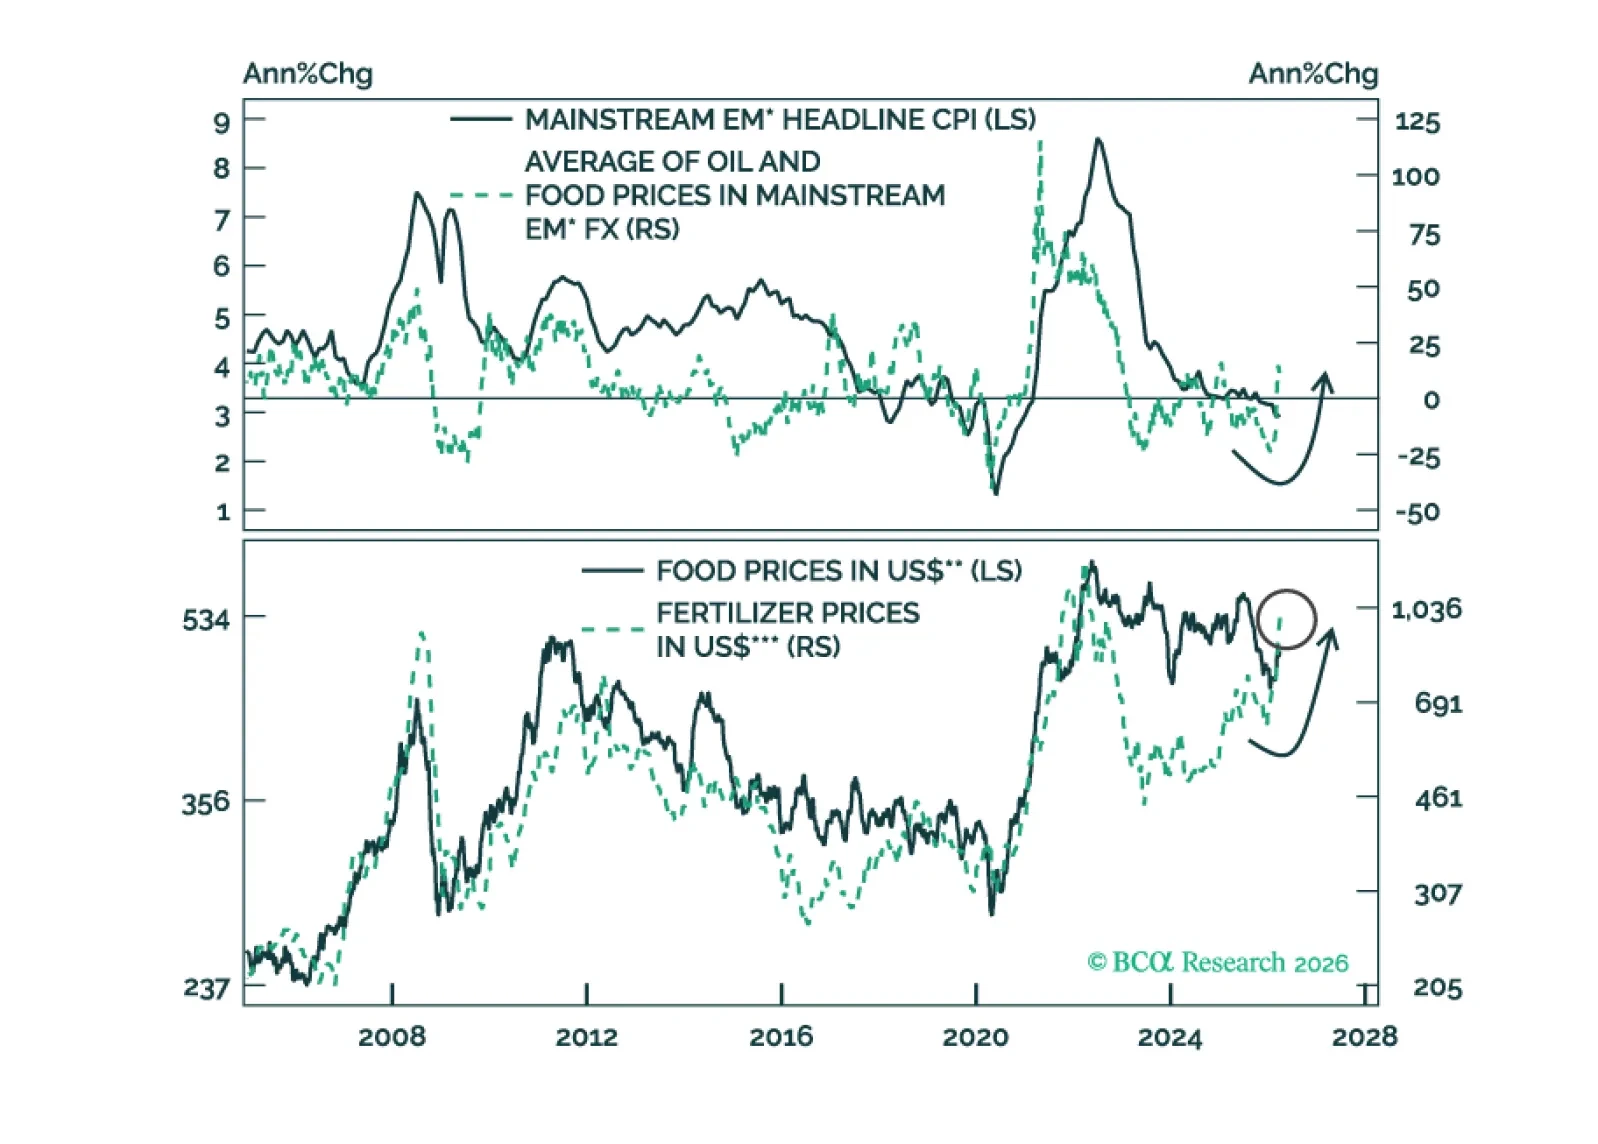
The global risk-off phase will persist. It is too early to buy local-currency bonds in Mainstream EM, but it is not too late to sell EM sovereign and corporate credit (USD bonds).
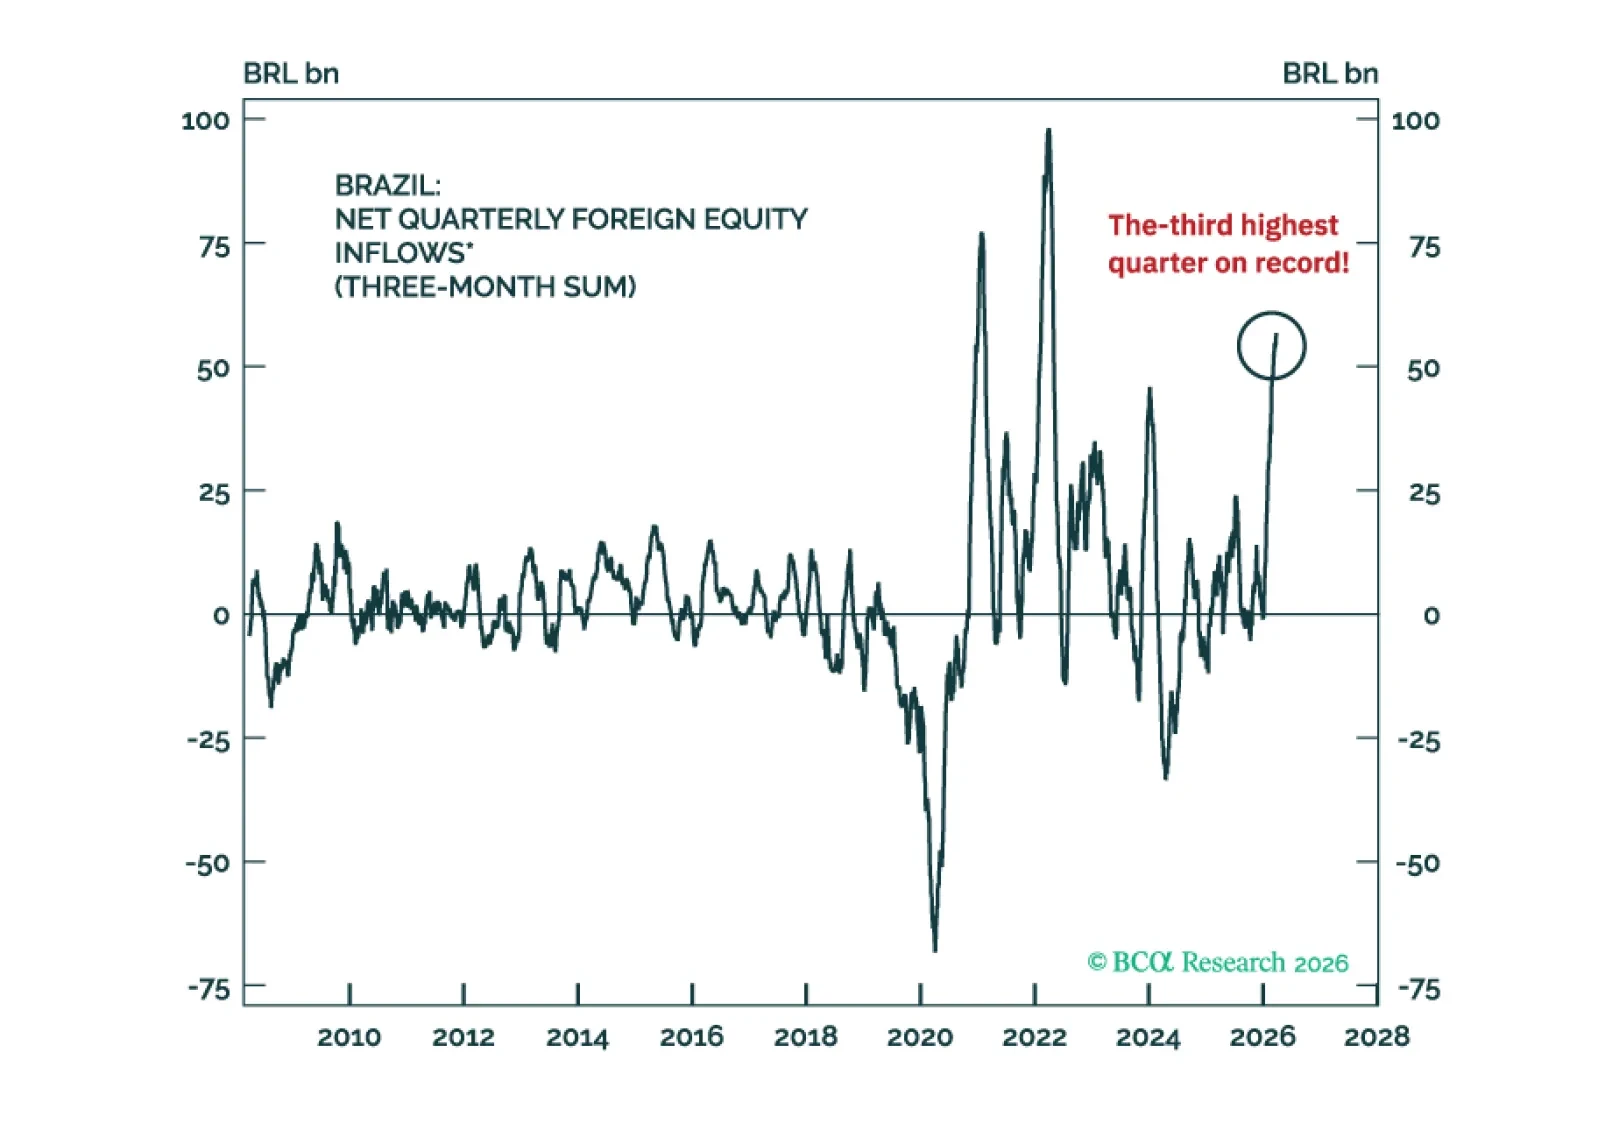
Overstretched foreign inflows into Brazilian markets will reverse, while soaring oil prices will not benefit Brazil in the near term. Avoid the country’s risk assets and the BRL, and stay underweight Brazilian equities and fixed income relative to EM. We also recommend paying 10-year Brazilian swap rates.
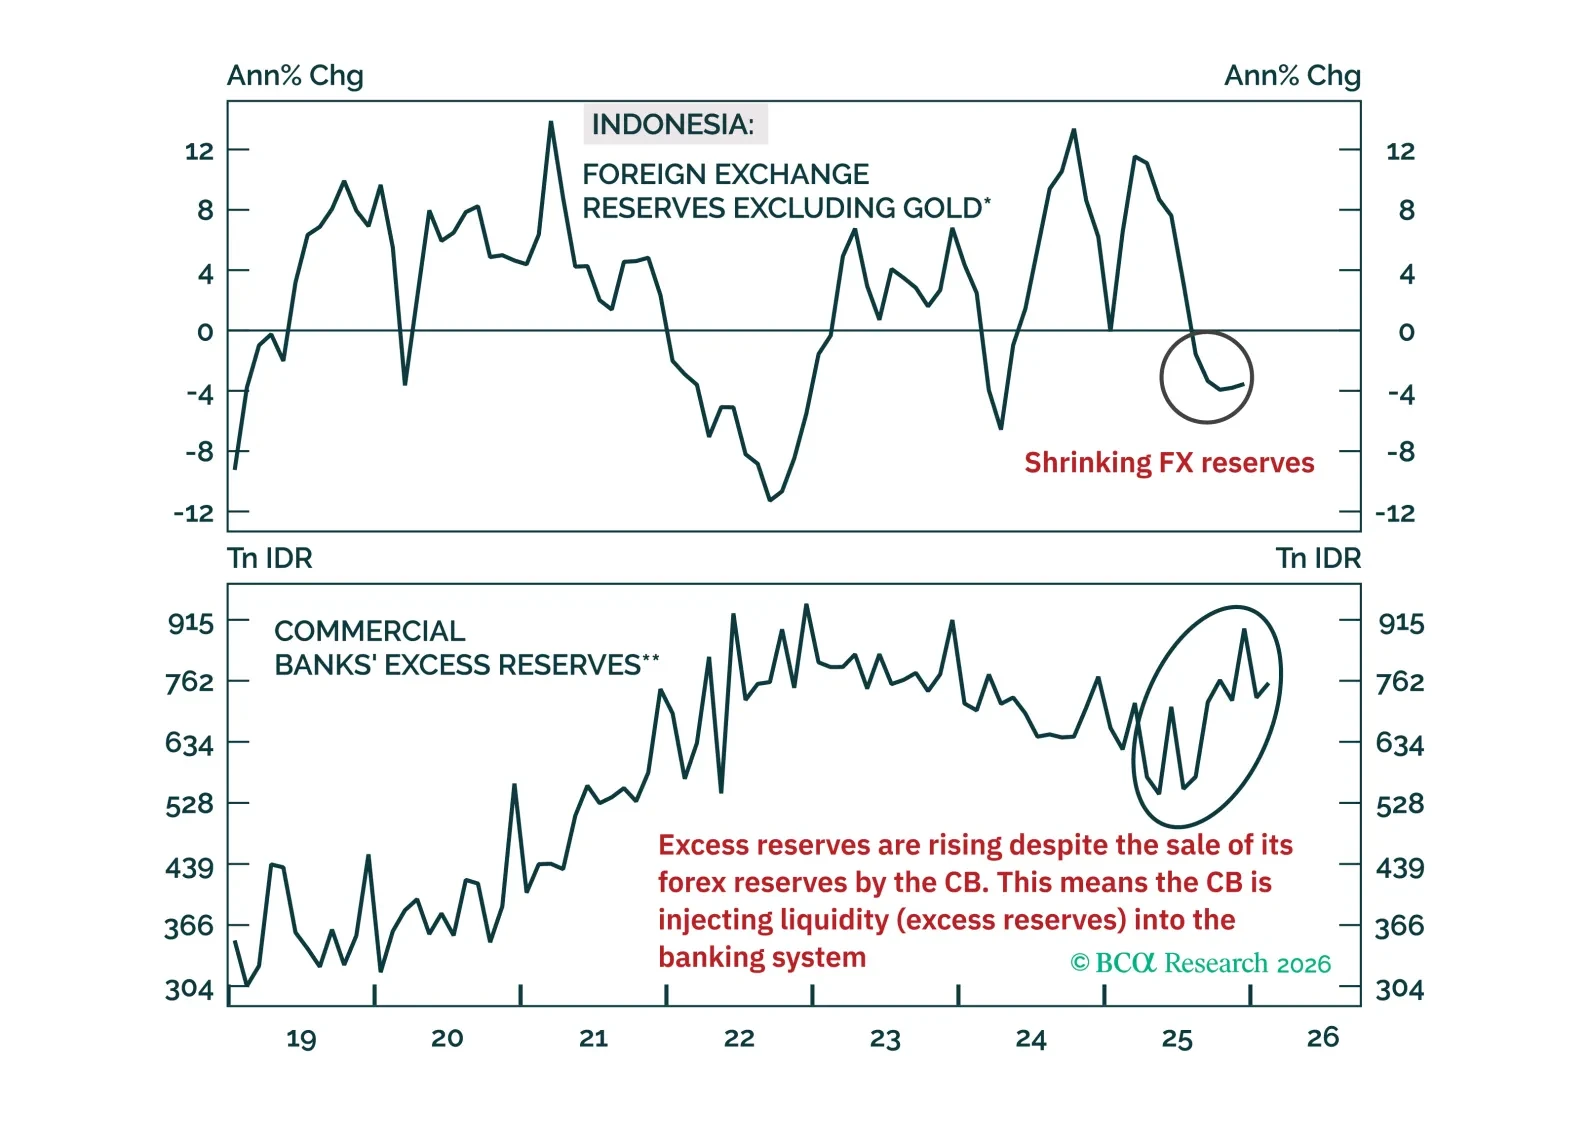
Indonesian rupiah will continue to plunge, and its local-currency bond yields will rise materially. Investors should short domestic bonds, currency unhedged.
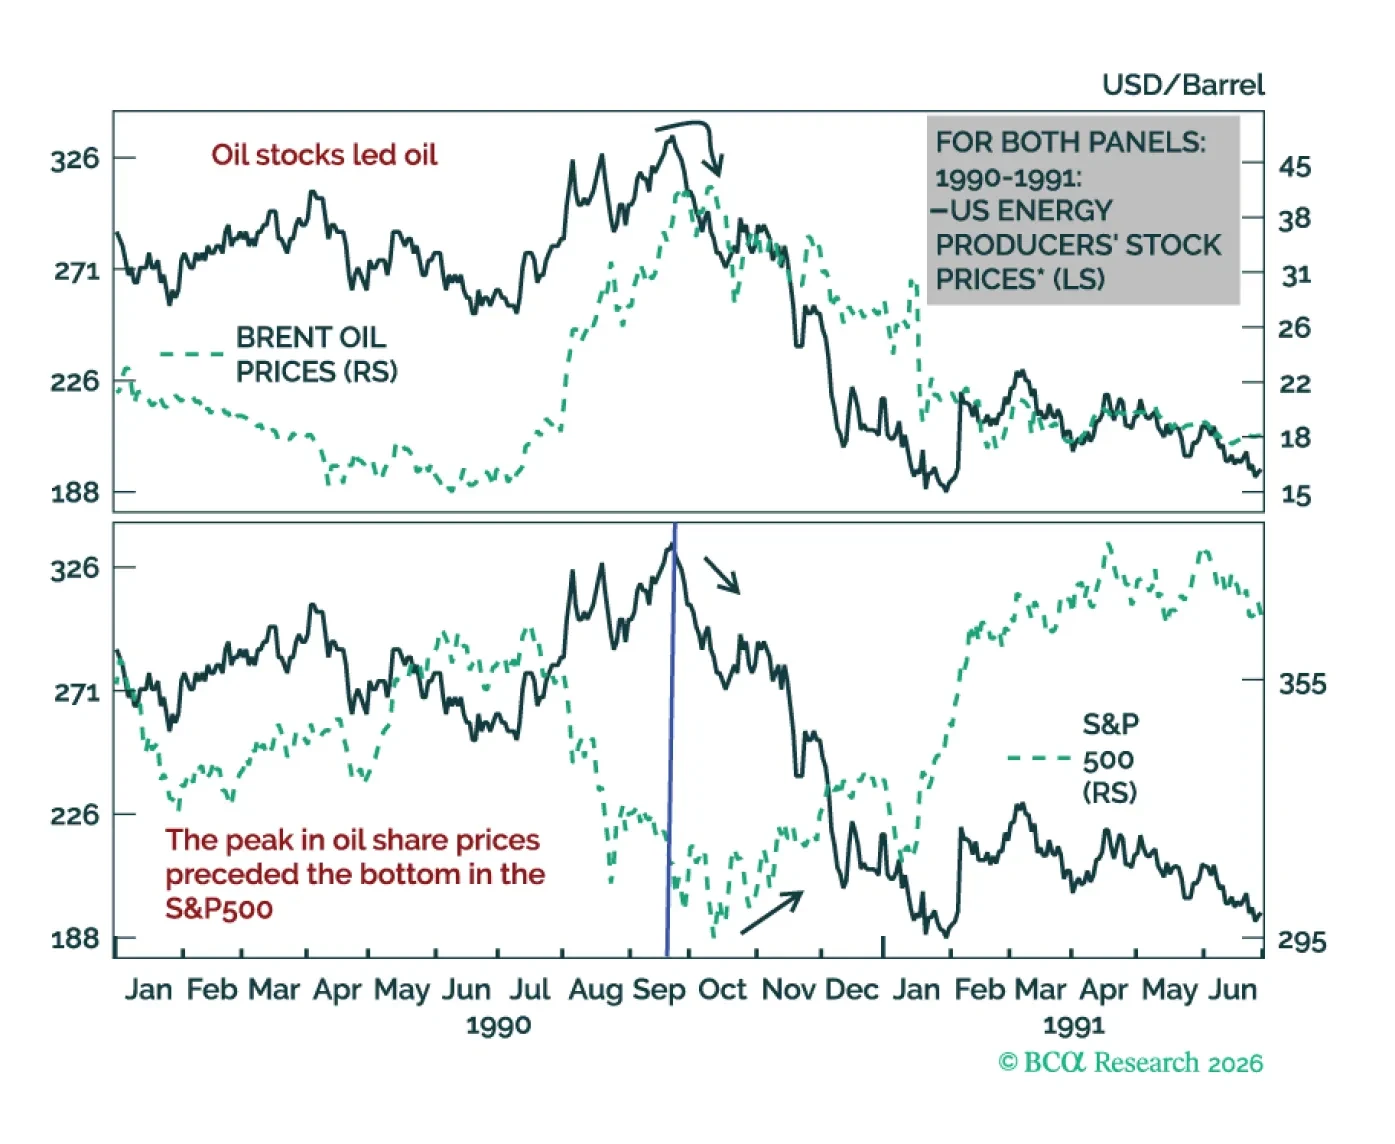
Oil prices will likely rise in the near term, irrespective of developments in the Strait of Hormuz. Given that global share prices have become correlated with crude prices, global stocks will continue selling off. Go short the EM equity index and take profits on our open trades that have benefited from the global risk-on environment.