Oil
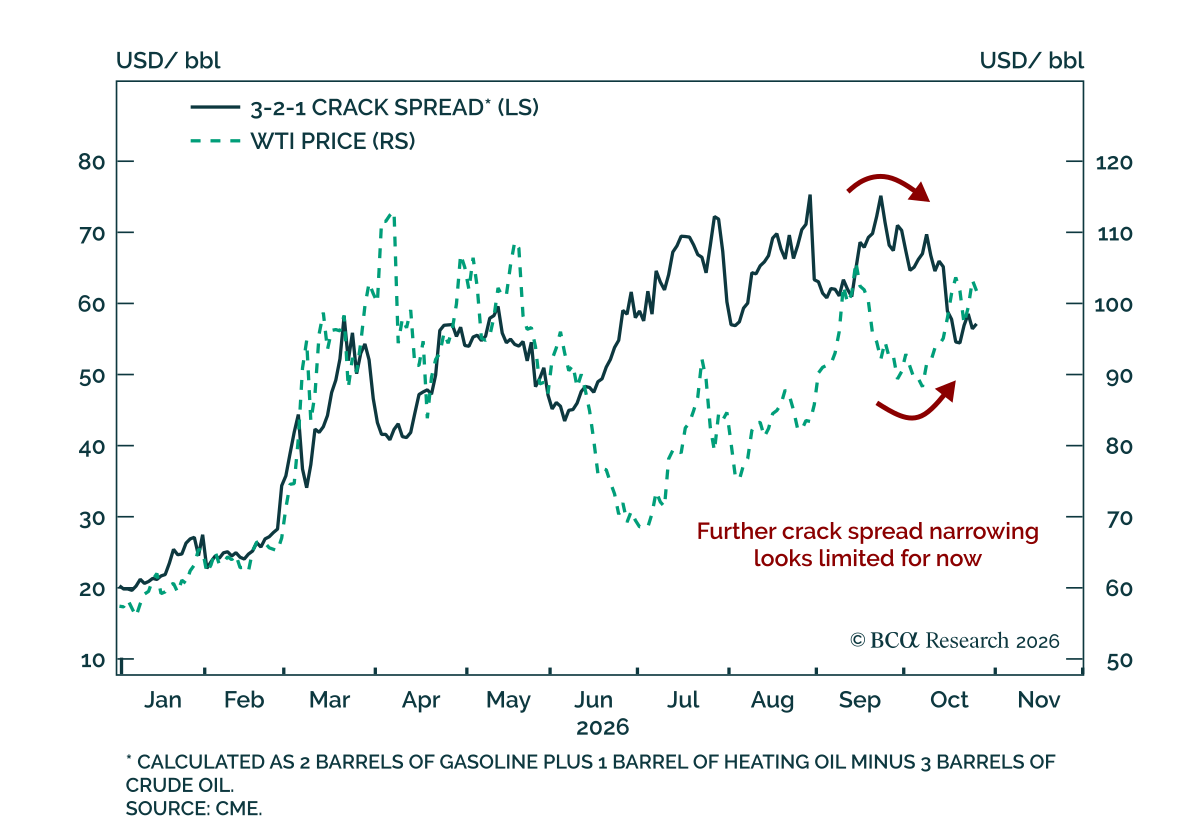
Crude has led the latest rally, leaving refined product prices behind and crack spreads narrower. We explain why the spread compression is unlikely to continue and why product prices will follow crude.
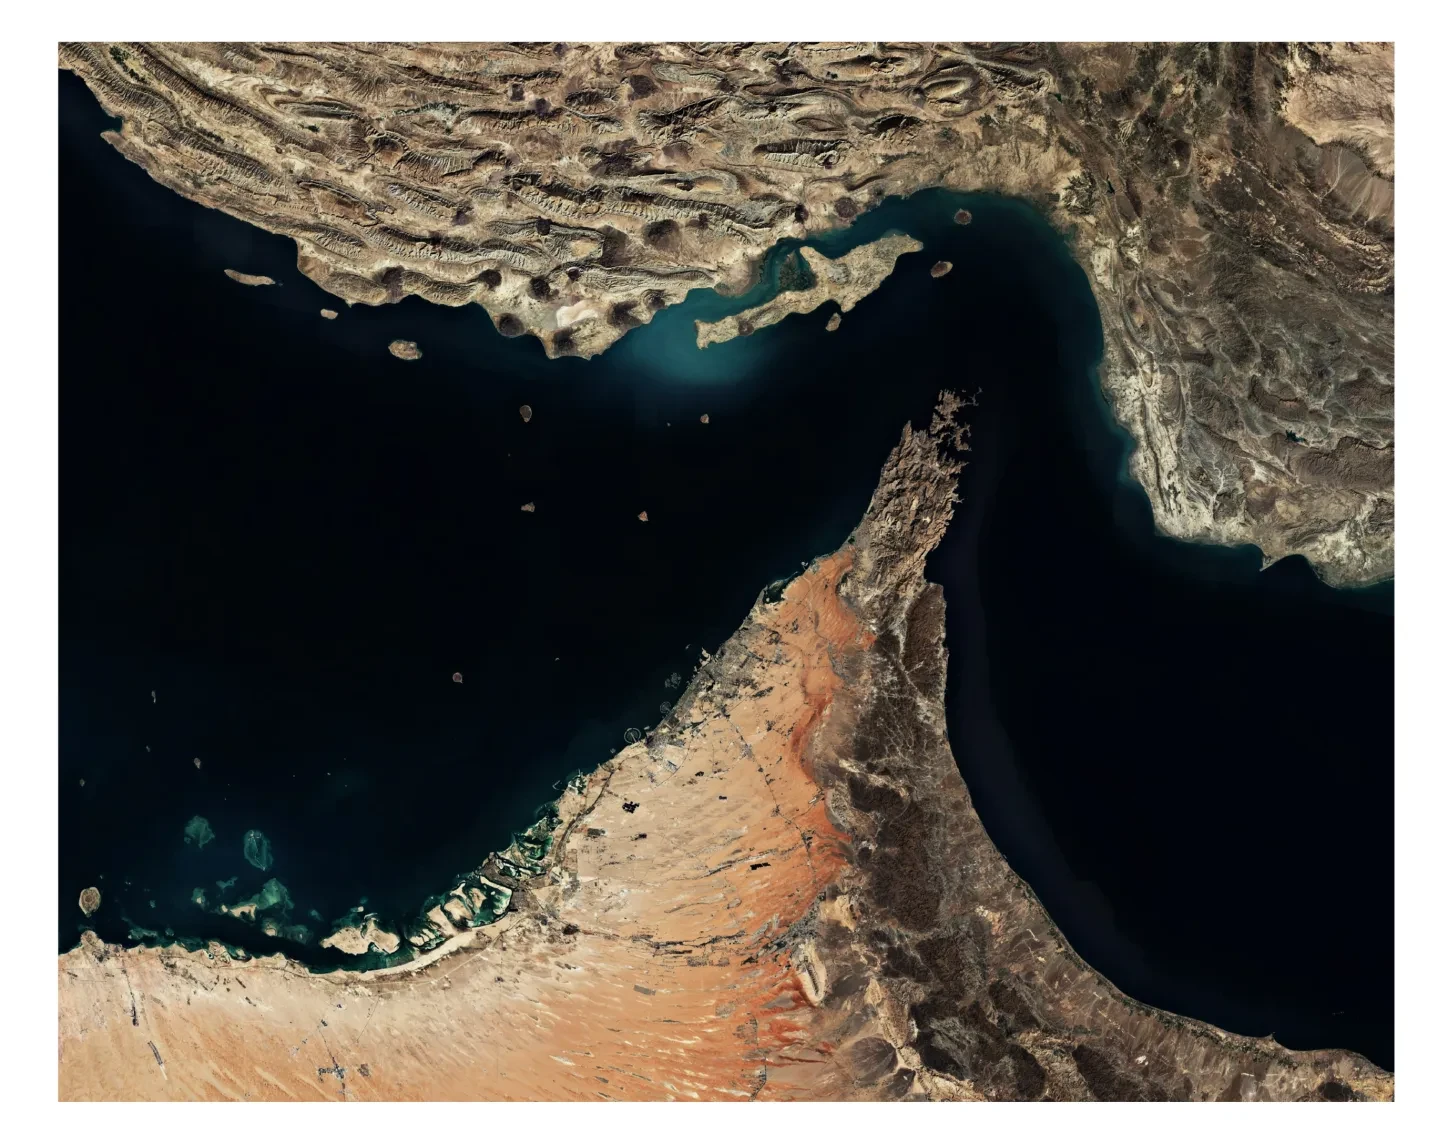
Iran is effectively trying to create an “October surprise,” an adage that refers to a pre-election crisis that alters the trajectory of polling and the eventual outcome. It is likely to be successful, with oil prices likely to face upward momentum from here. The intention would be to ensure that oil prices do not see any significant decline from now until November 3.
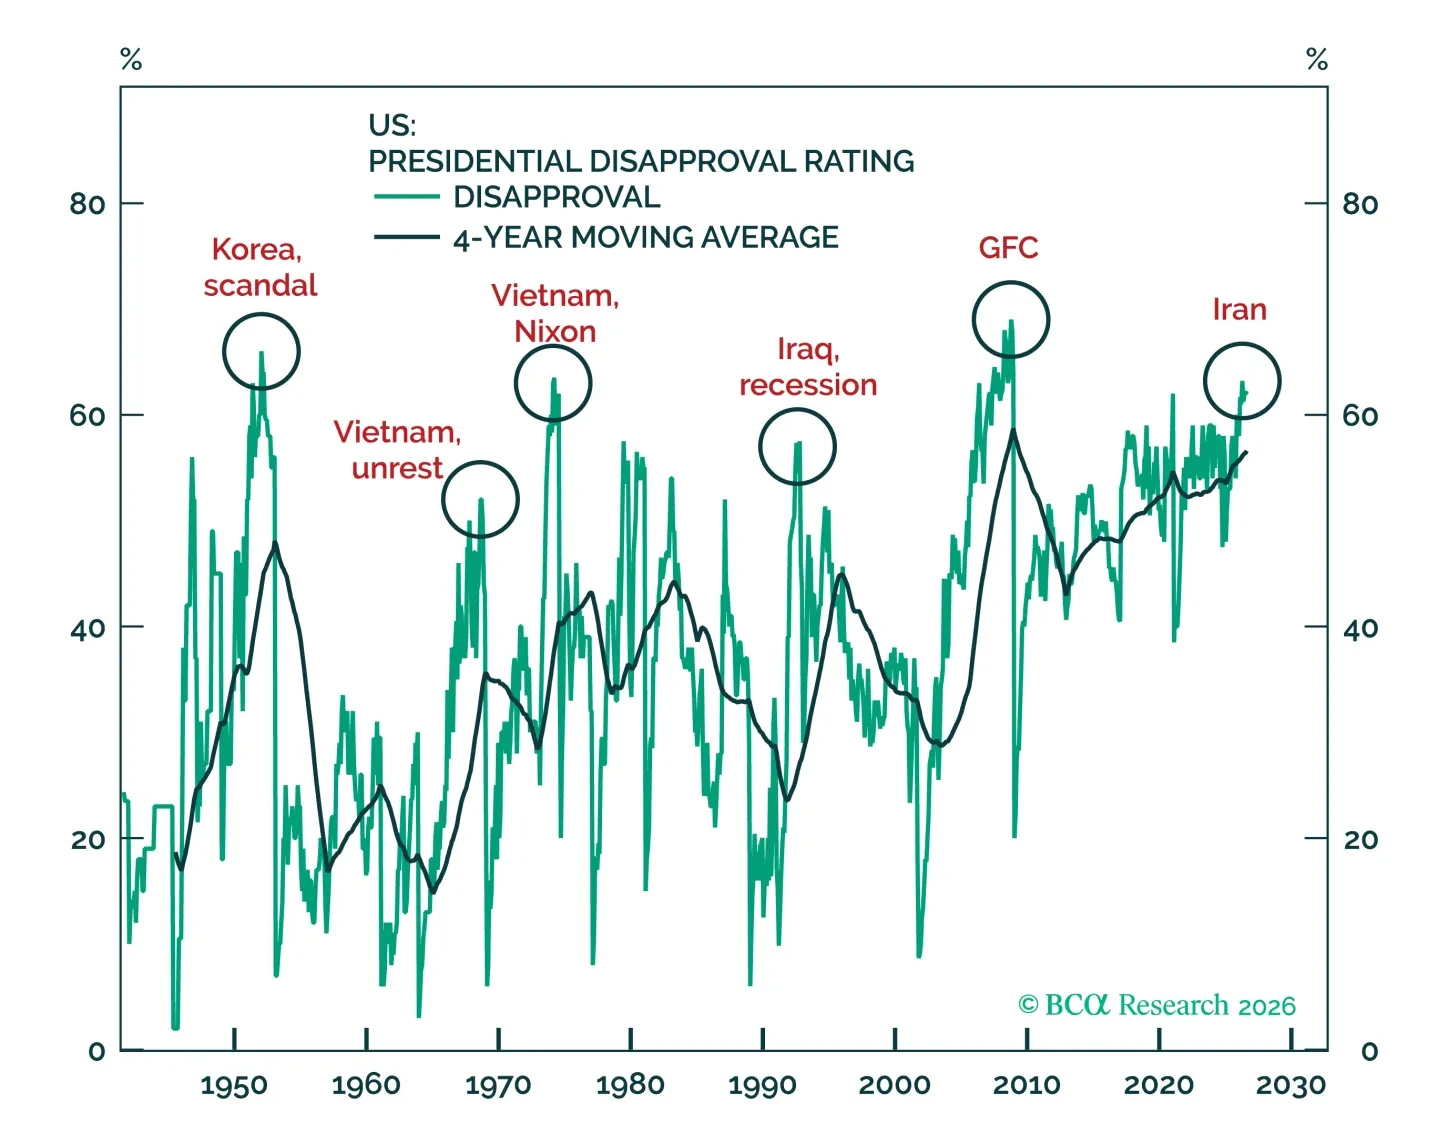
The big risk for the markets remains a flare up in the Middle East conflict. The Fed appears to be targeting geopolitics as much as inflation fundamentals. By the logic of transitive properties, therefore, more war means more hikes. That’s negative. So why are we not bearish on equities and bonds? Because President Trump holds his own faith in his hands. With his unfavourability near all-time highs (Chart of the Month), the conflict in Iran is at its end. Our worry? A Democratic Party sweep that surprises in its intensity and thus forces markets to start pricing in a leftward tilt in 2028.
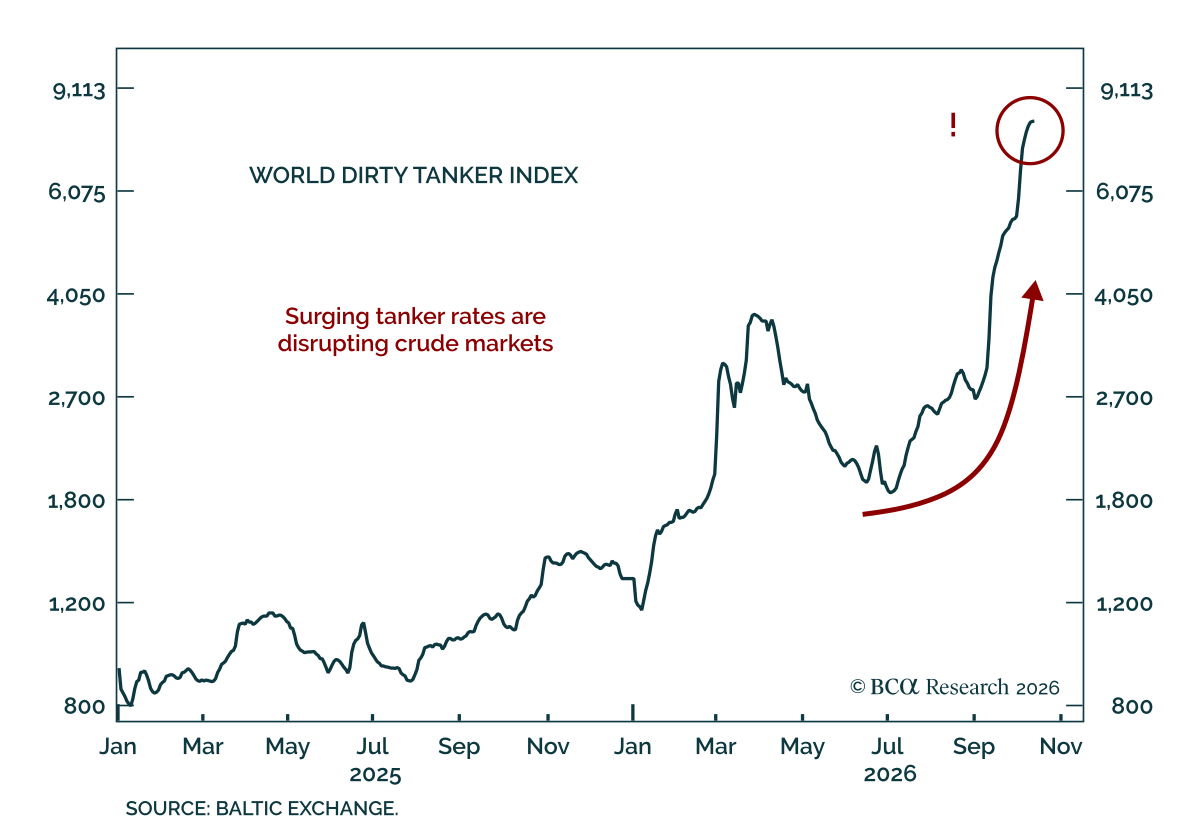
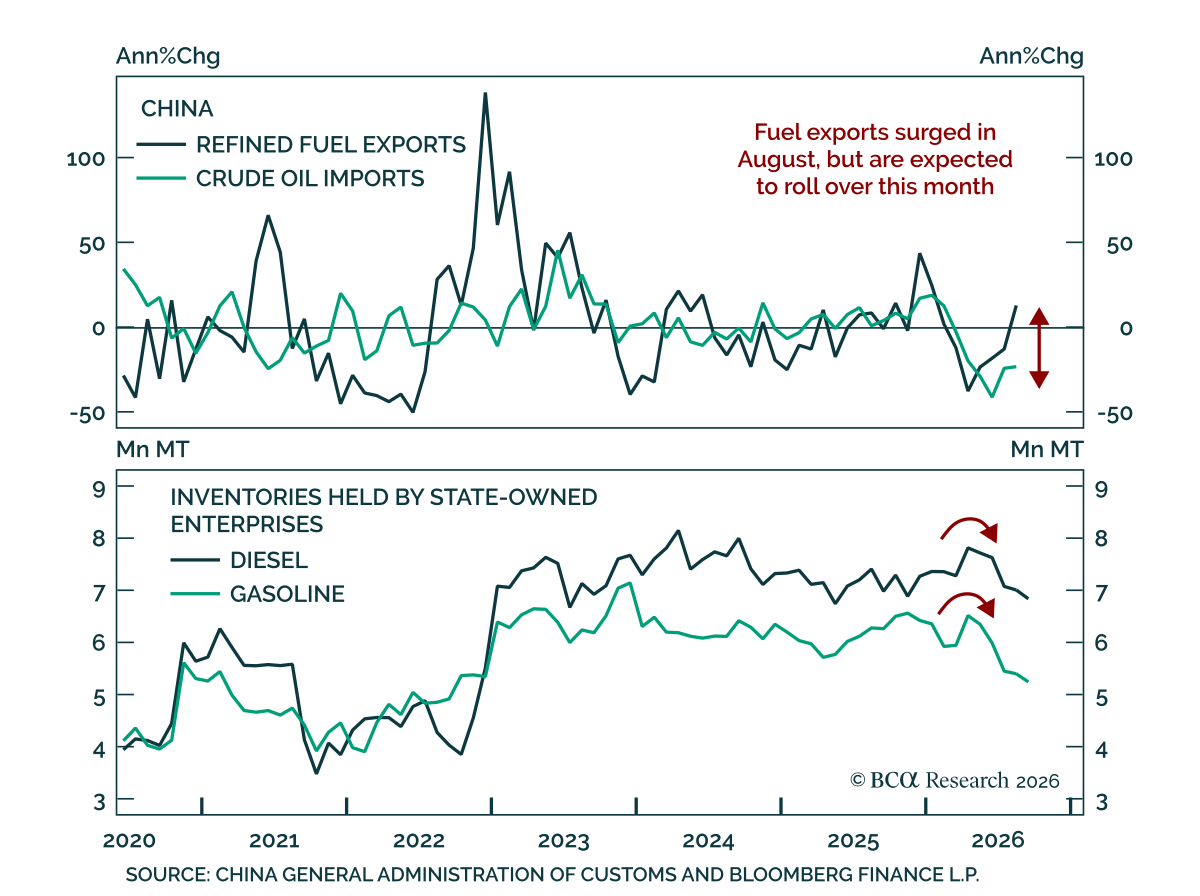
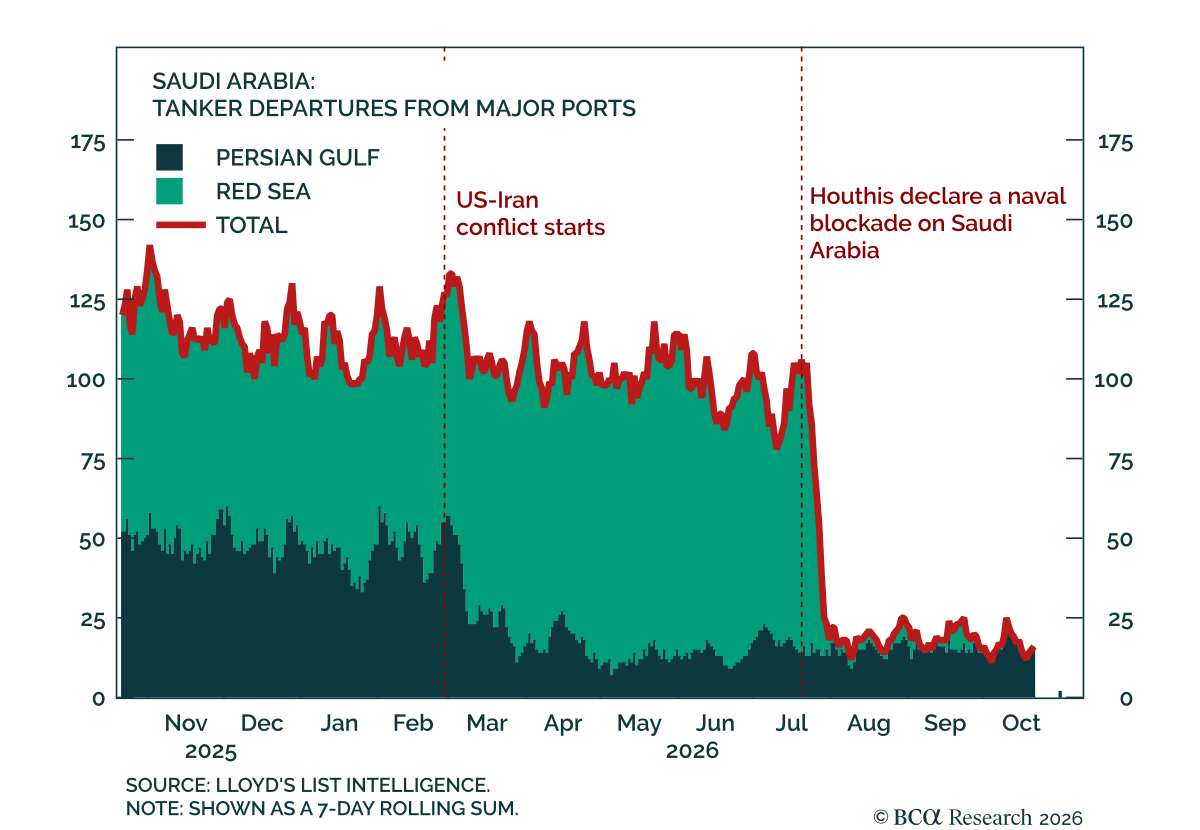
Markets woke up to twin Houthi attacks on October 12. On October 9, the Yemen-based, Iran-allied, militant group attacked the King Khalid International Airport with a missile, killing 12 civilians and injuring over 300. Following that attack, President Trump suggested that the US “may” join Saudi Arabia’s fight against the Houthis. On October 11, the airport was struck again, with Saudi Arabia vowing to respond.
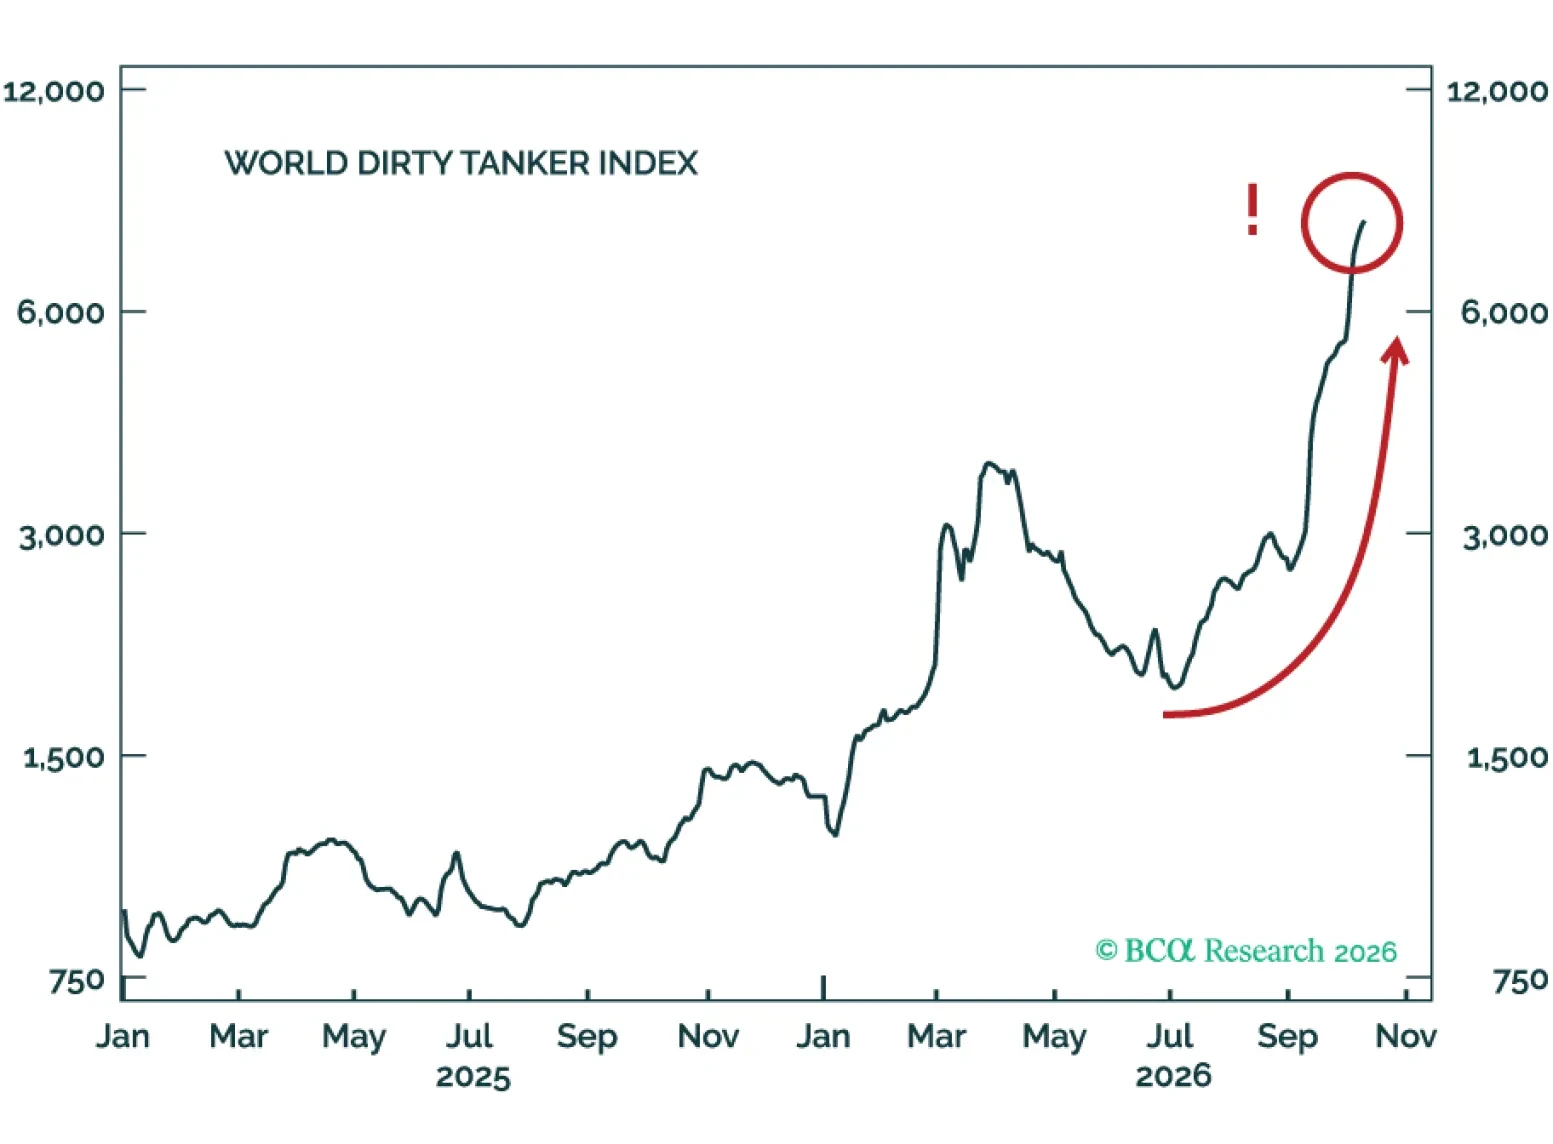
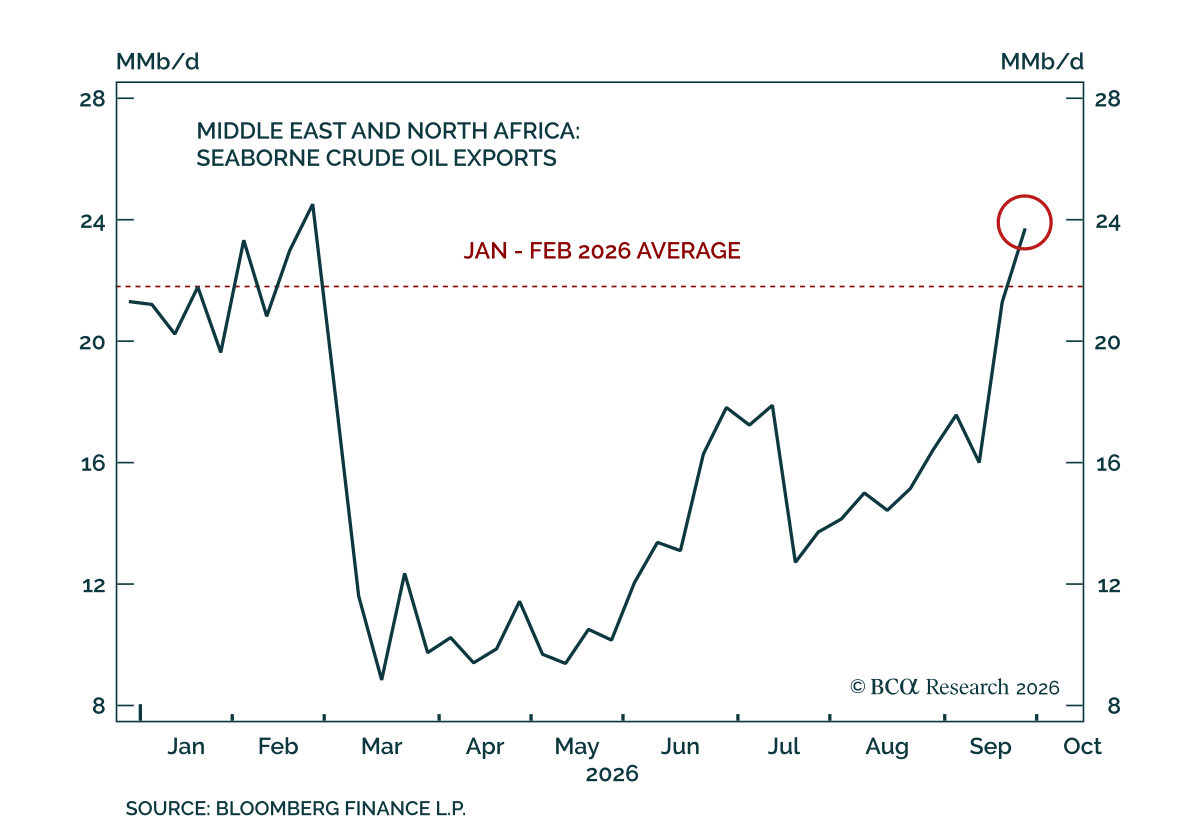
Middle Eastern crude exports are back at pre-war levels, yet Brent remains above $100/bbl. We explain why more barrels haven’t meant lower prices, and why policymakers have no clean fix. Even if Putin follows through on his reported agreement to release Russian diesel supplies into global markets, it is unlikely to meaningfully ease the fuel's supply disruption over the near term.