 CoreMacro
BCA’s flagship global macro and investment strategy platform, helping investors anticipate regime shifts, connect signals across regions and asset classes, and navigate the world’s most difficult macro questions.
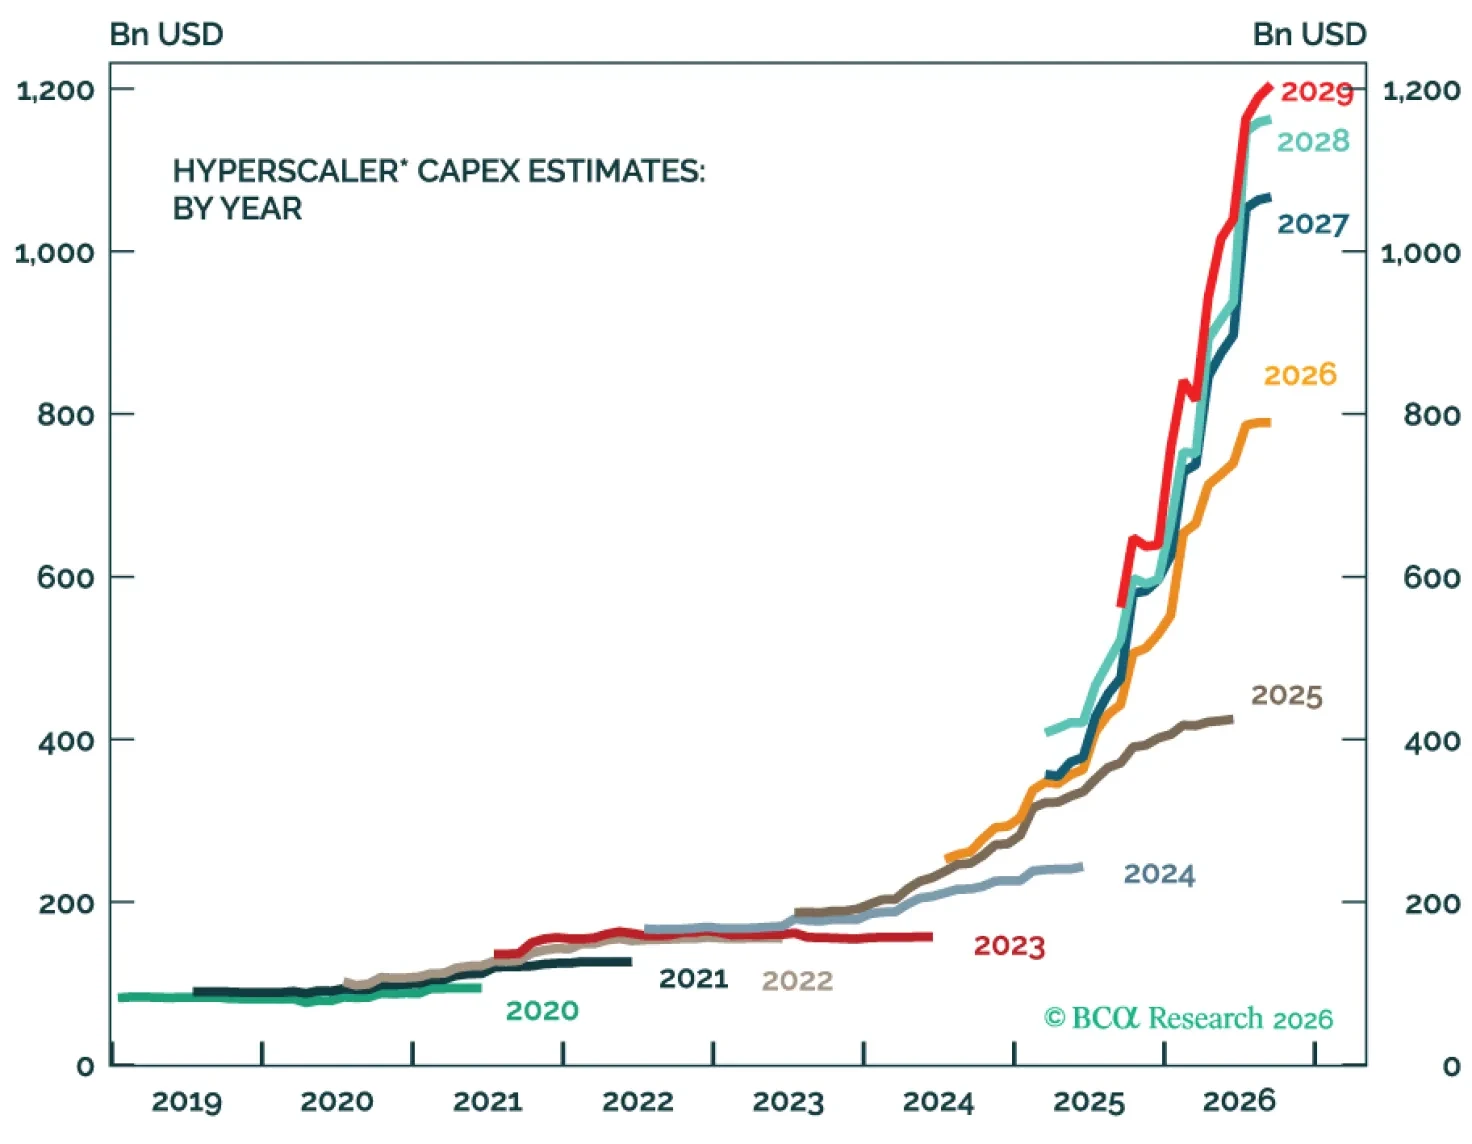
Today's report examines several of the most interesting ideas we've heard over two weeks of meetings and calls with investors.
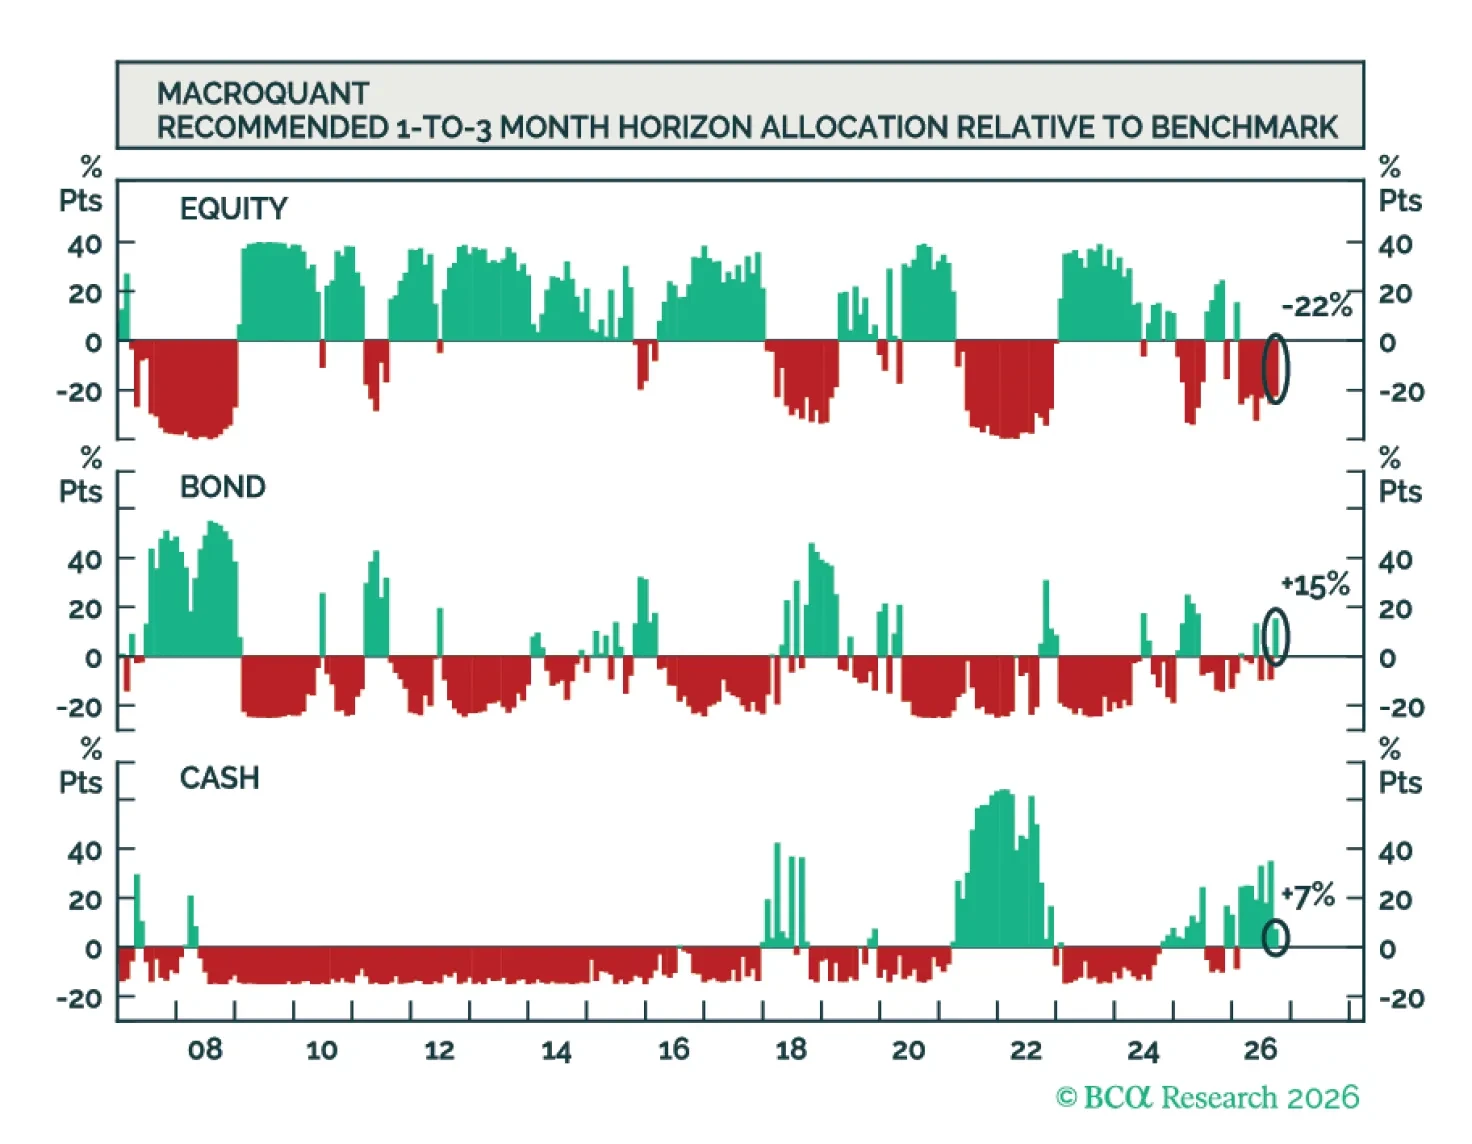
MacroQuant recommends a slight underweight to equities and an overweight to bonds and cash. The model is bullish on the US dollar, negative on gold, very negative on copper, and neutral on oil.
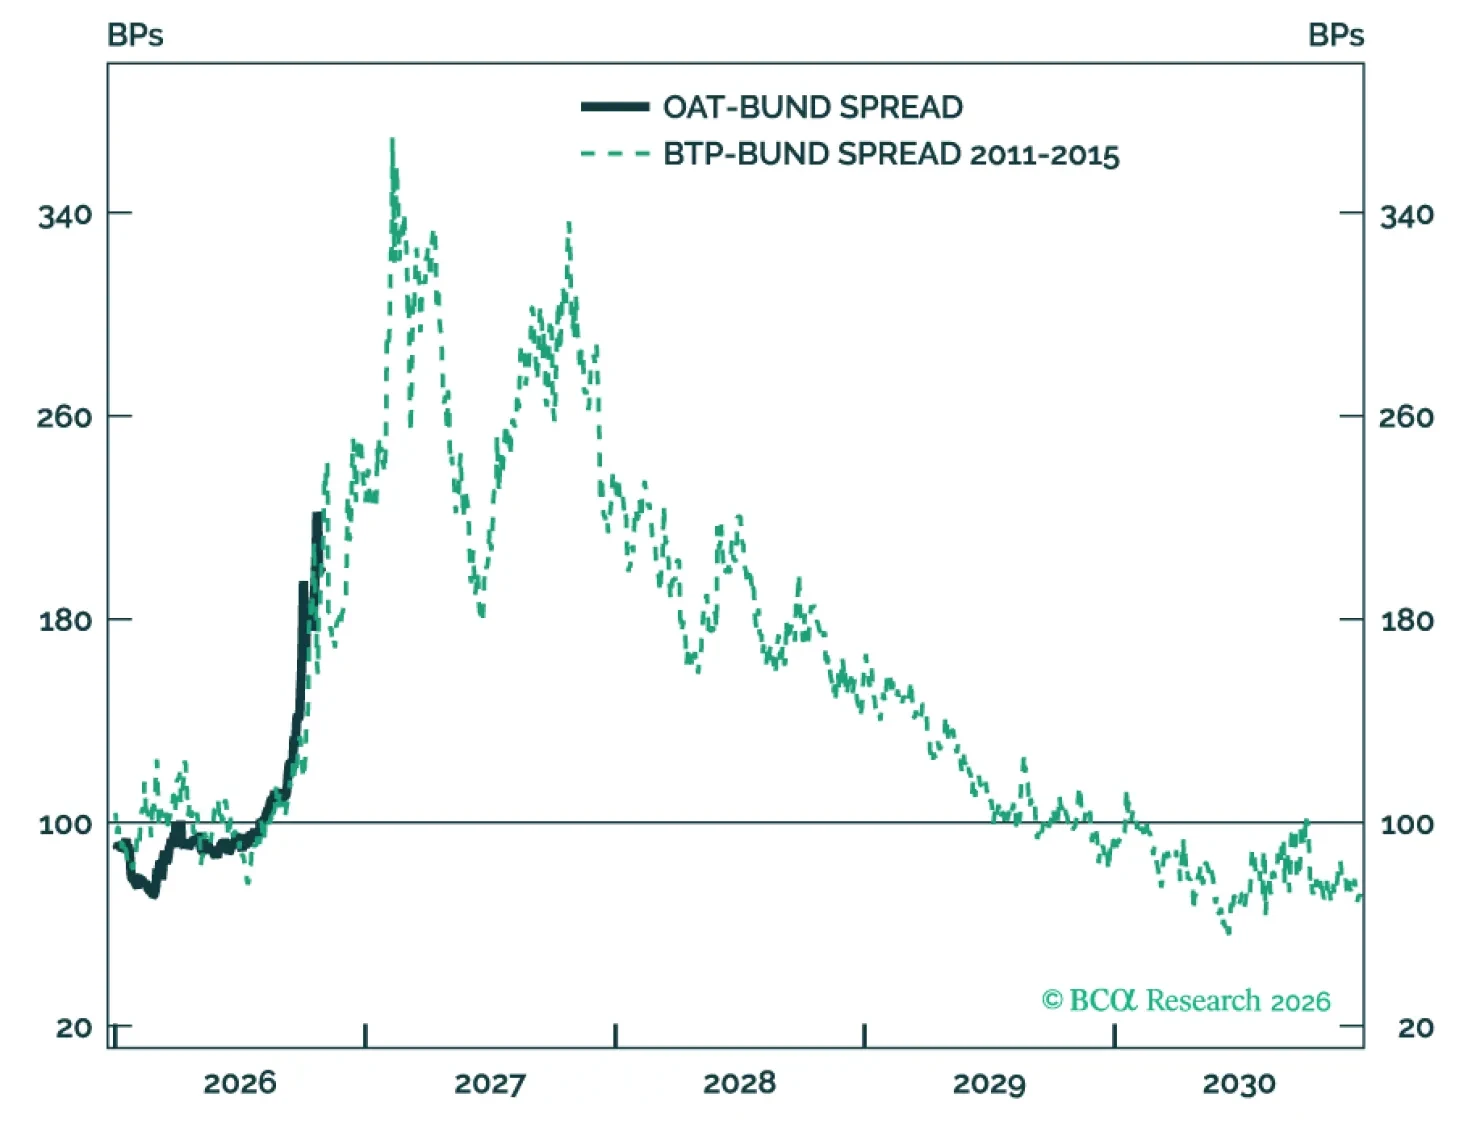
France’s fiscal mess is far from over, but the bond vigilantes may have gotten ahead of themselves. We book profits on short OATs, eyeing another opportunity in early 2027 as election risks resurface. Meanwhile, French equities are too cheap to ignore. We tactically buy on depressed valuations.
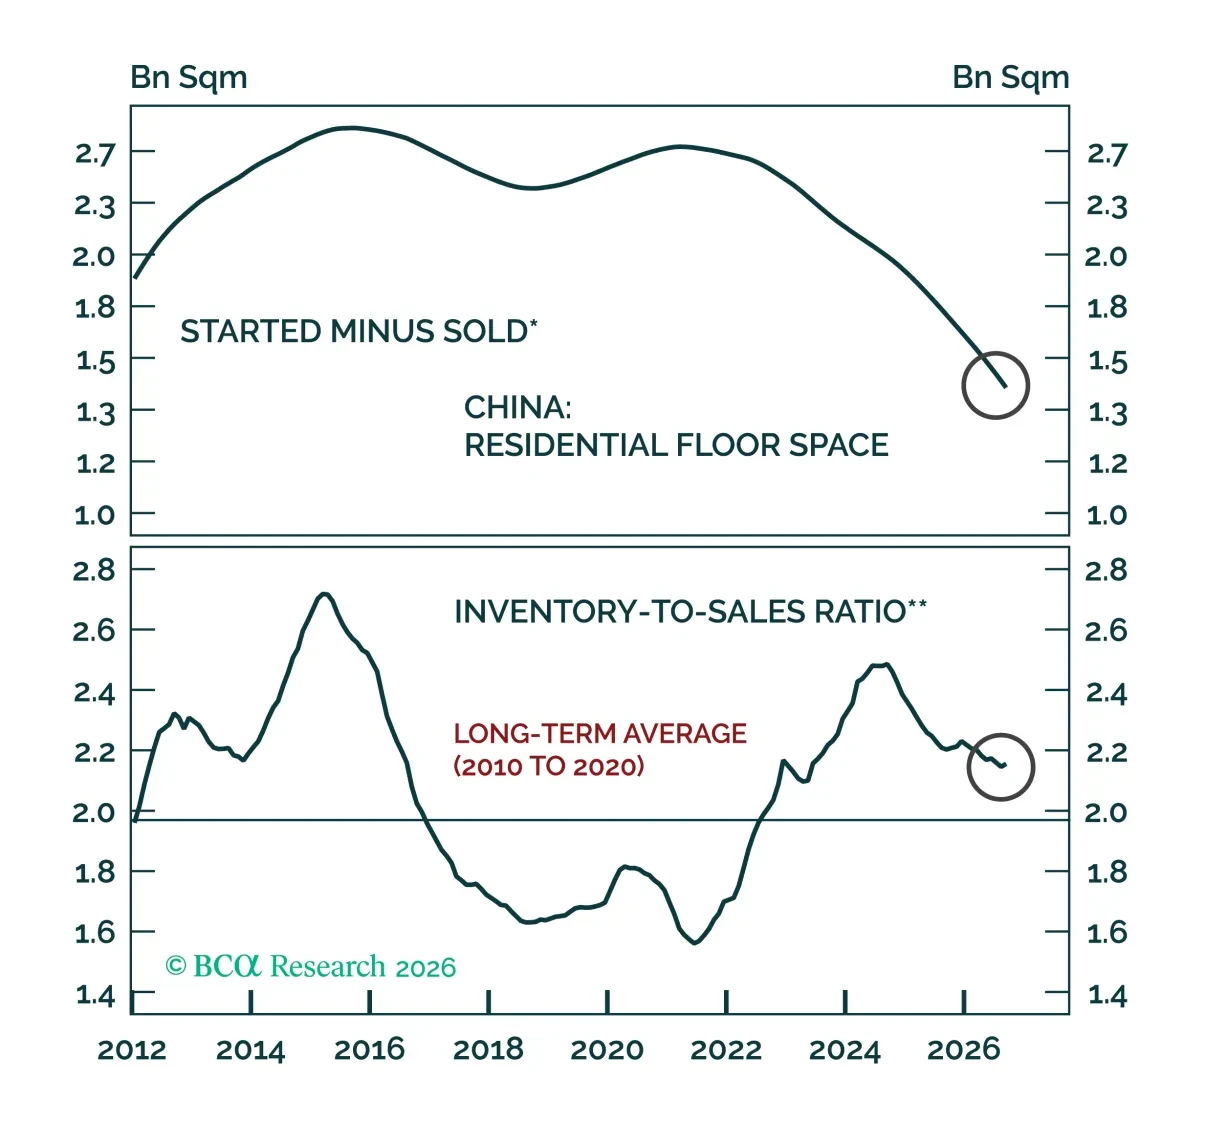
After a sharp five-year correction, China's top-tier housing markets will likely bottom out late next year. The rest of the country, however, will keep struggling with oversupply.
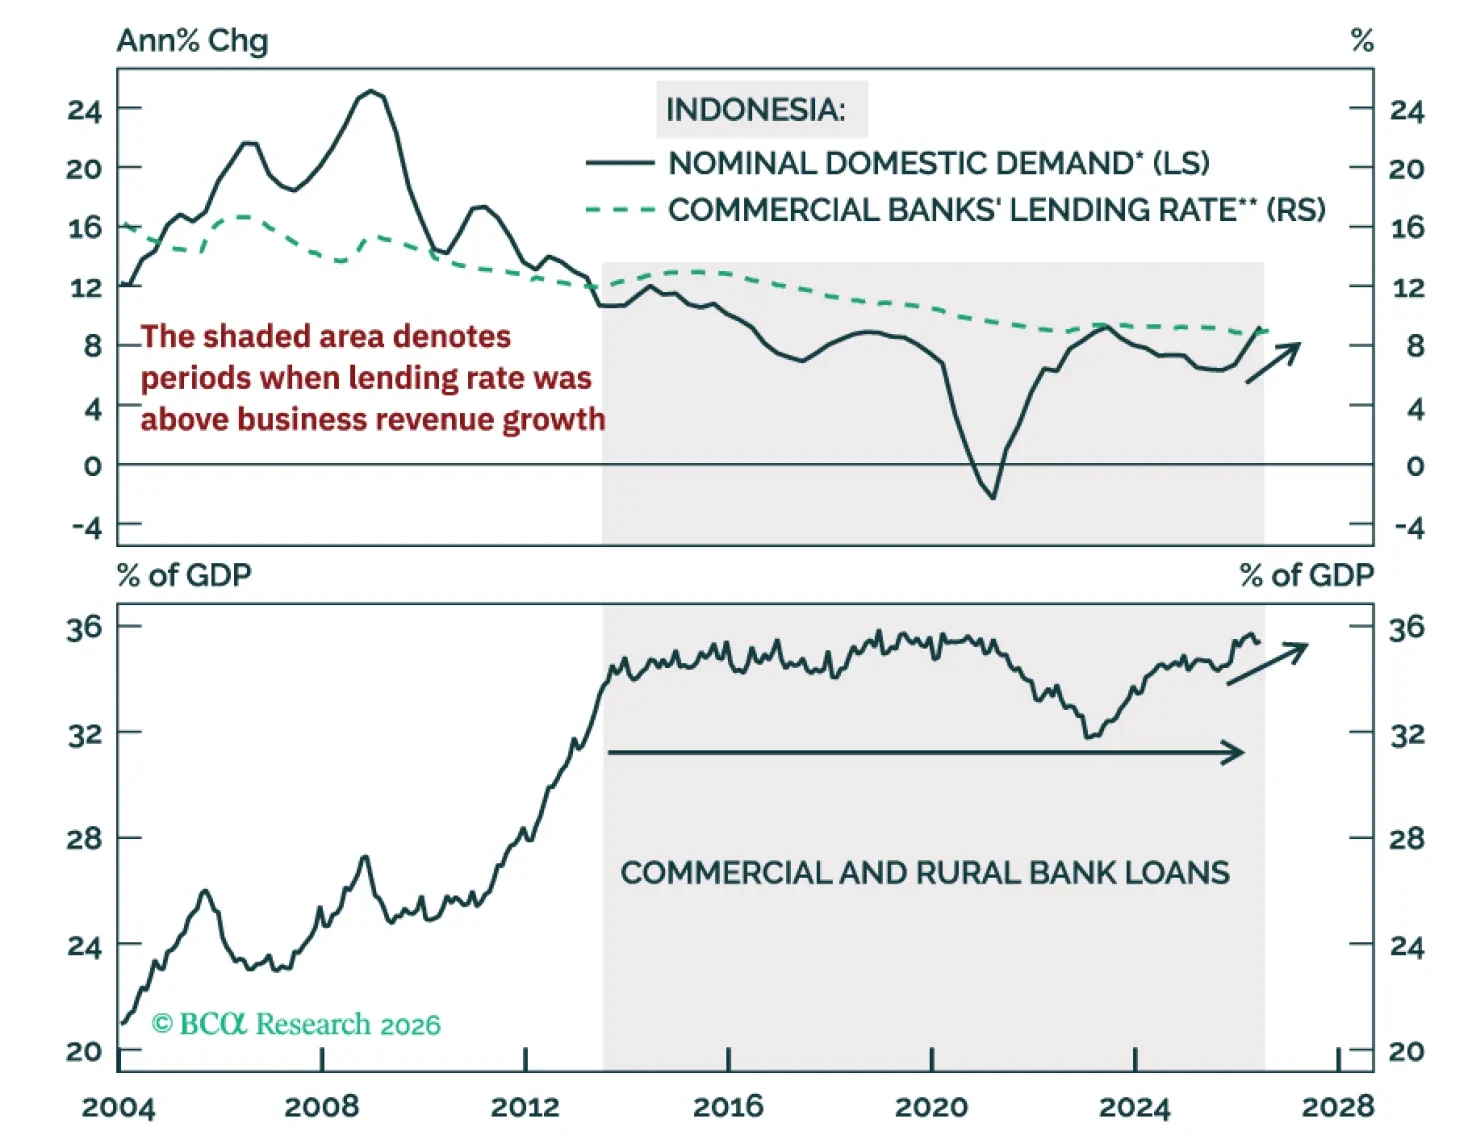
Given that the economy’s productive capacity is limited, government stimulus will lift nominal growth but do little to increase real output growth. The upshot will be rising inflation and wider twin deficits. This is bearish for the currency, bonds, and stocks.
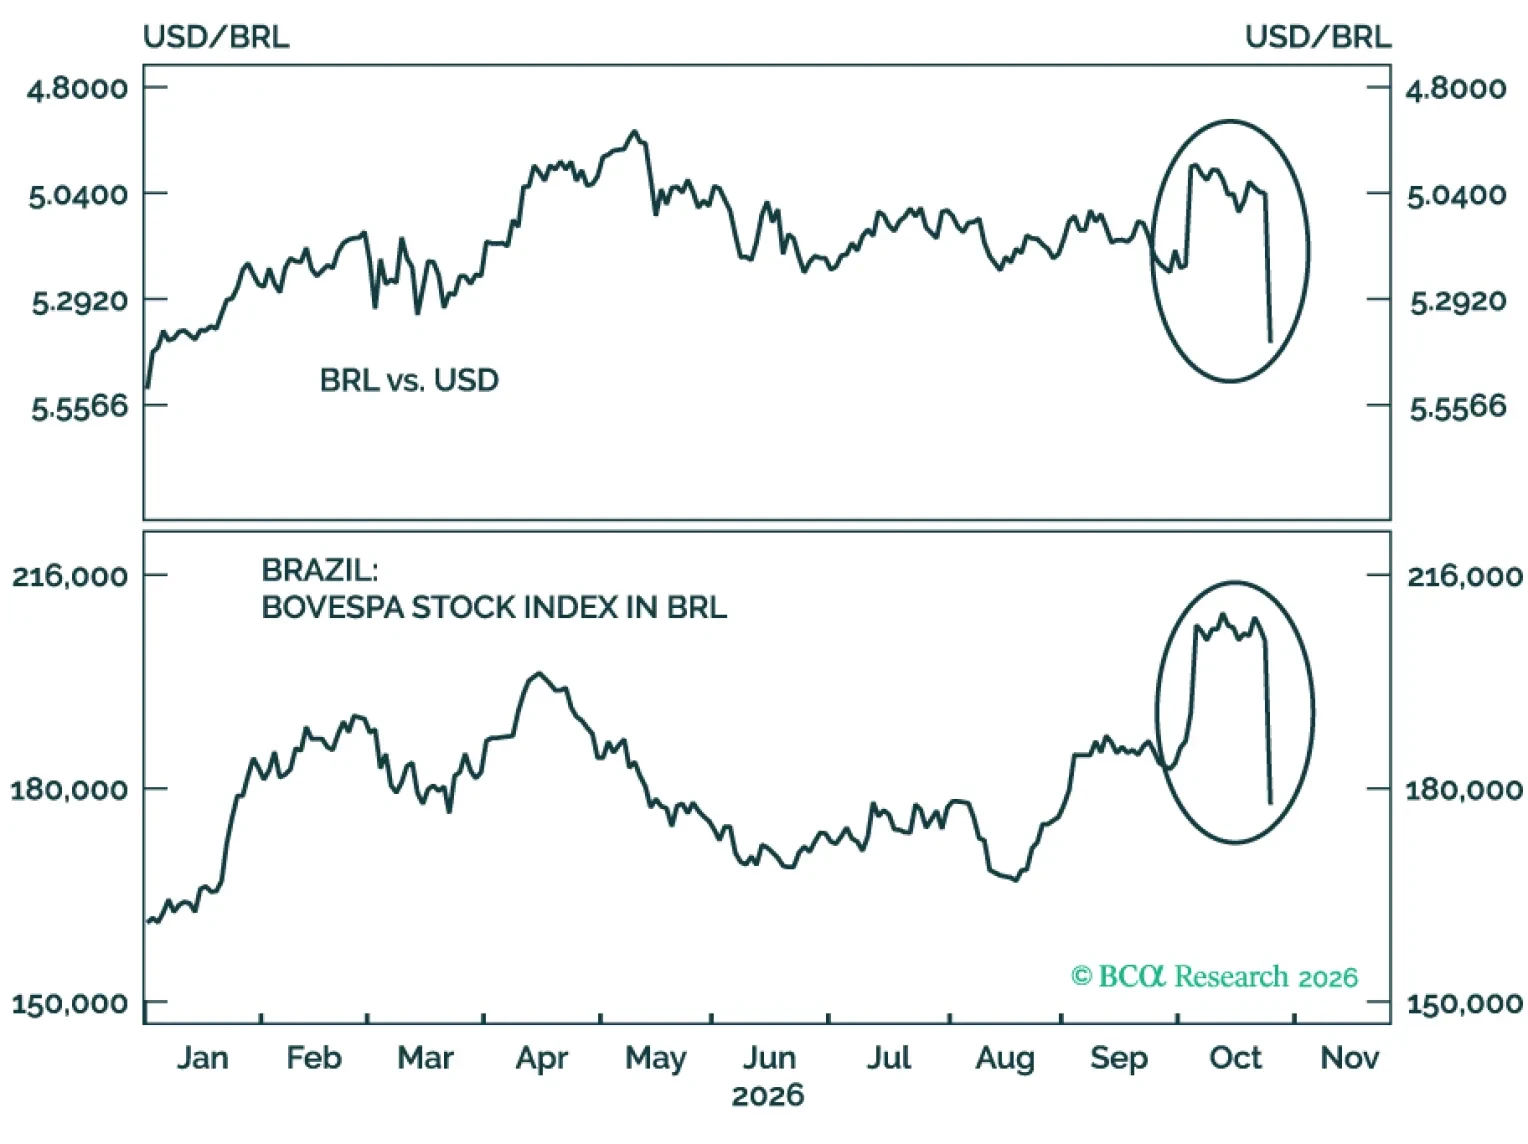
Brazil’s elections have turned into a game of roulette for investors. Bulls and bears were each wrong-footed between the first and second rounds of elections. We are downgrading Brazilian equities, local bonds, and sovereign credit to underweight within their respective EM portfolios.
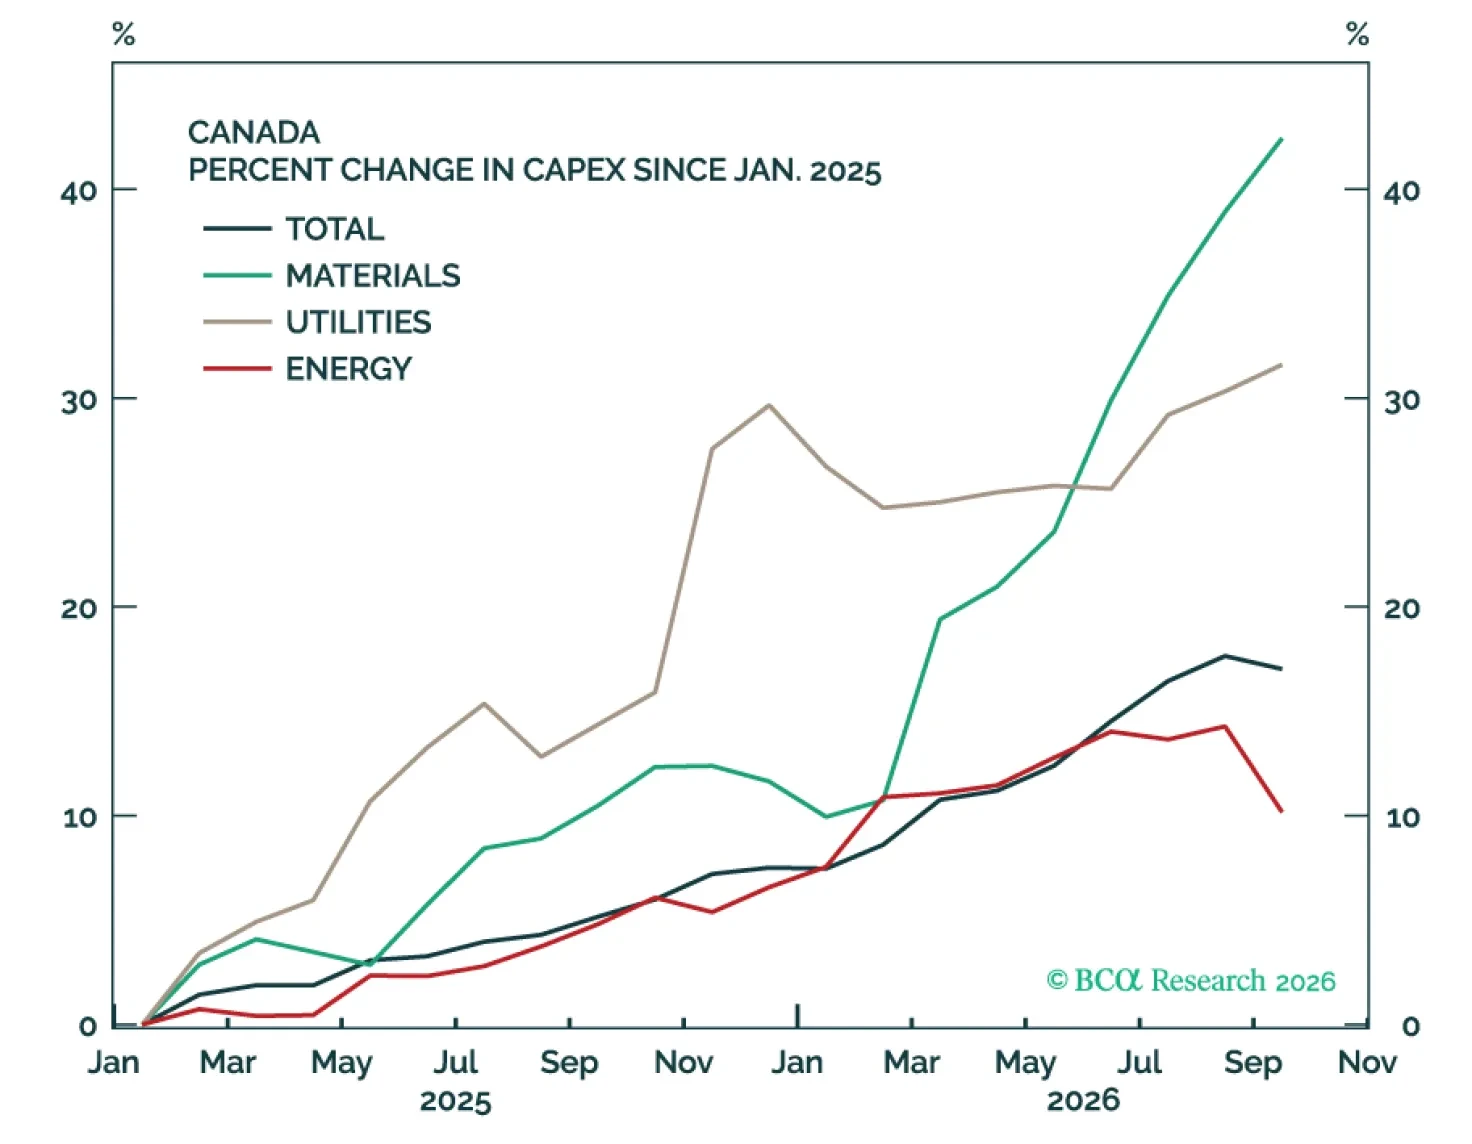
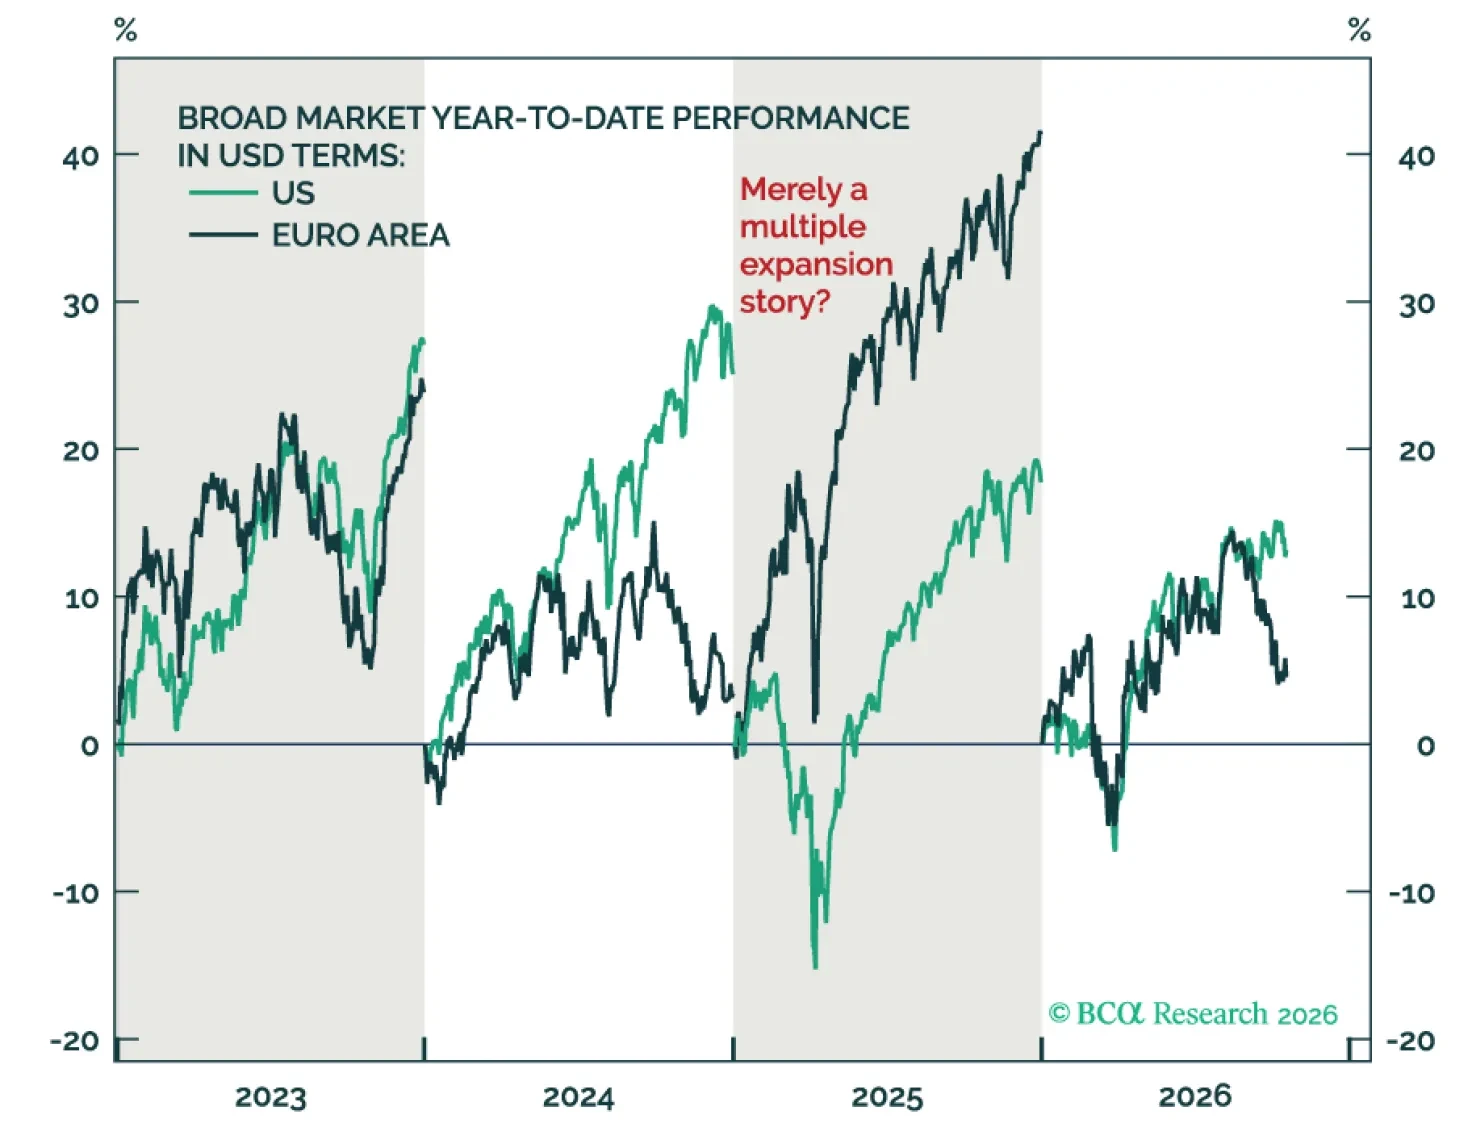
Europe has 99 problems, but the paucity of bearish views about the Old Continent is not one of them! And yet, somewhat shockingly, European assets have outperformed US assets over the past two years. Sure, markets make mistakes. But the macro graveyards are littered with investors who thought they were smarter than the markets. In this report, we suggest that Europe is on a cusp of significant structural reforms that will unlock value in its services sector. And that while many of the challenges are real, they’re either well understood or priced in.
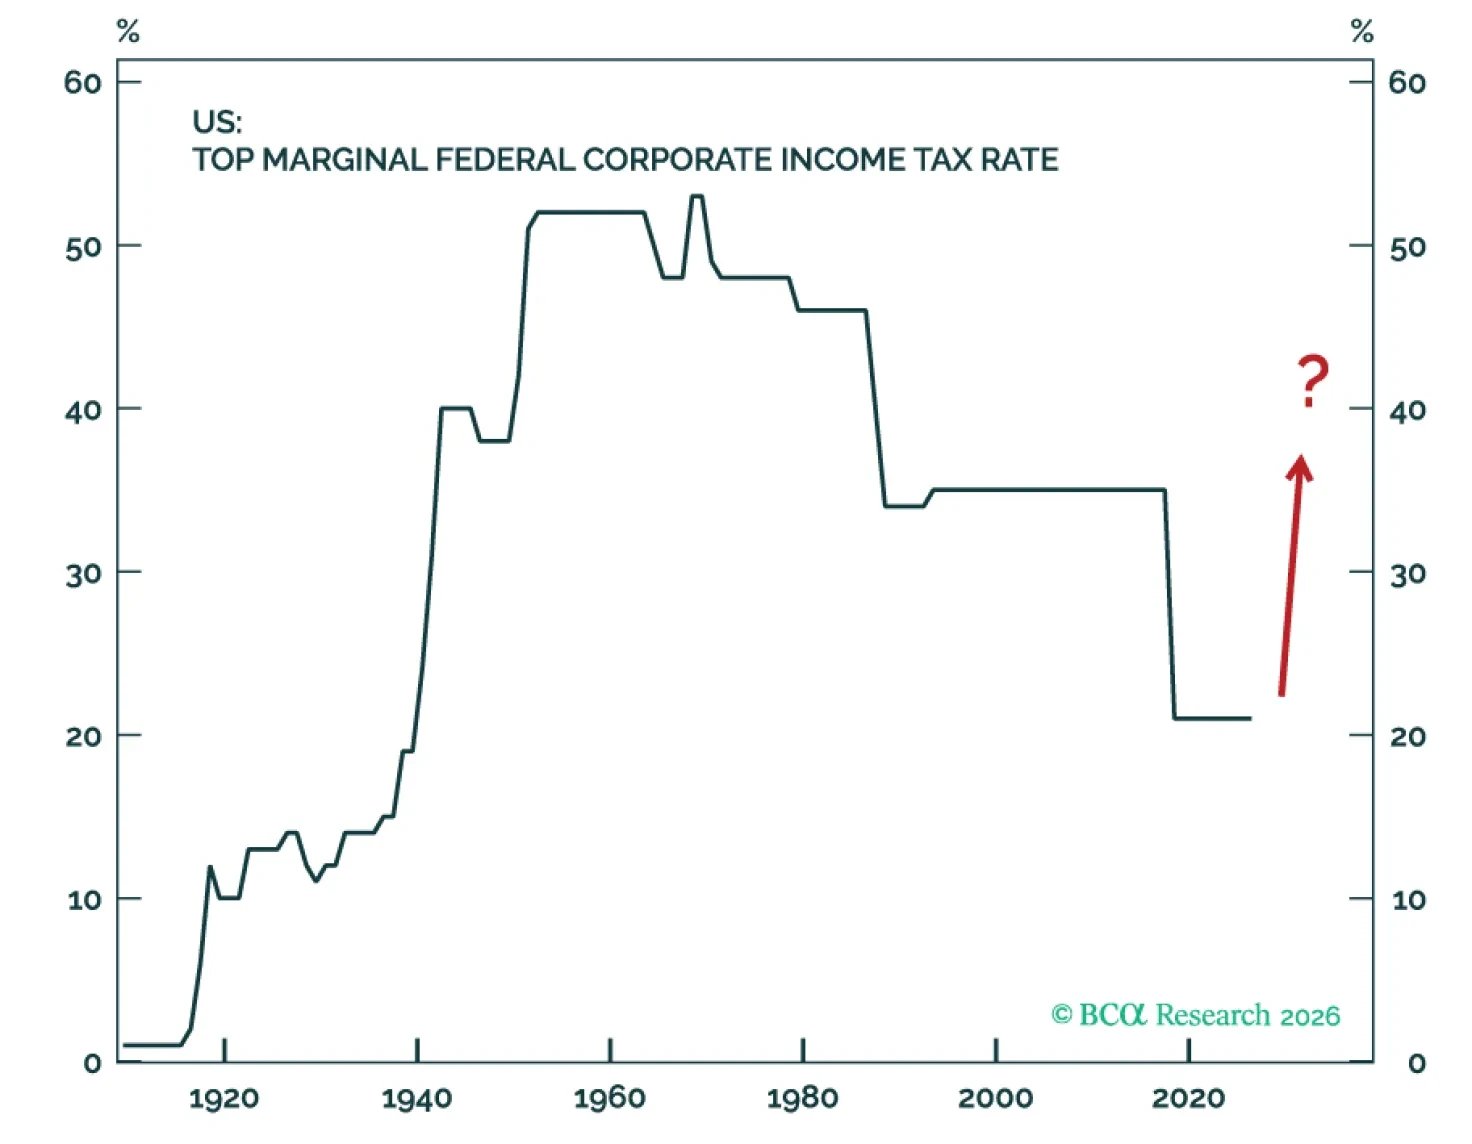
We highlight several potential inflections in well-established structural factors, pointing out ways that markets might respond differently this time to economic data and policy actions.
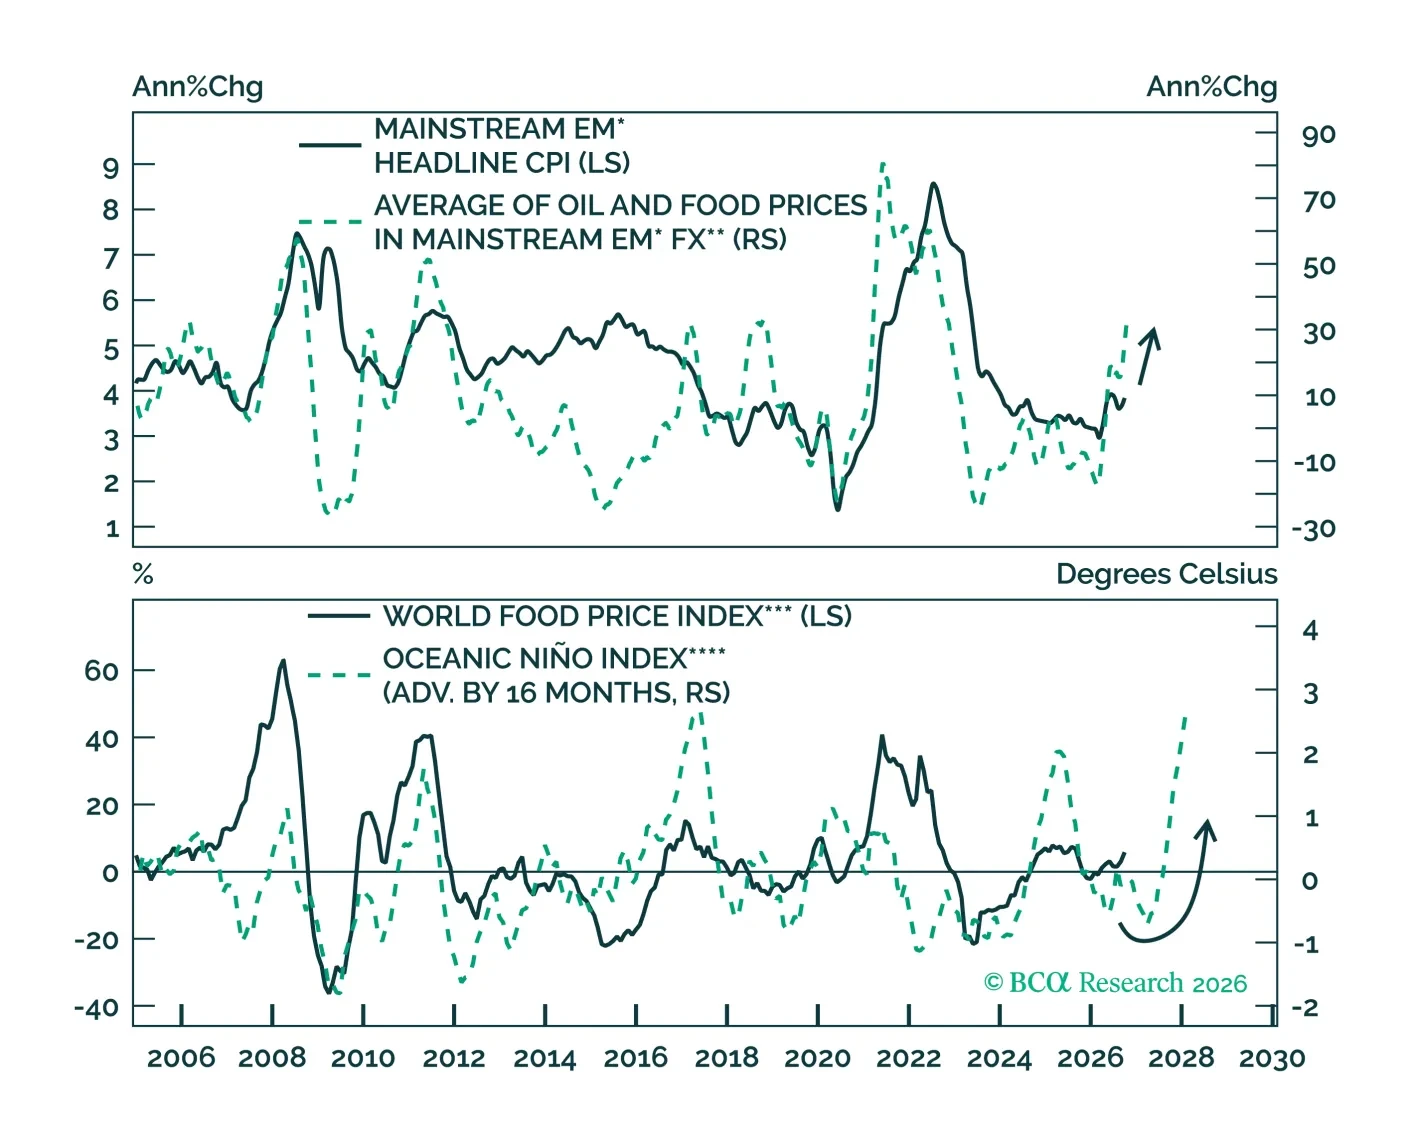
EM local bonds face near-term turbulence from rising inflation, global risk aversion, and currency weakness. Use the sell-off to build exposure: medium- and longer-term fundamentals remain favorable.