Corporate
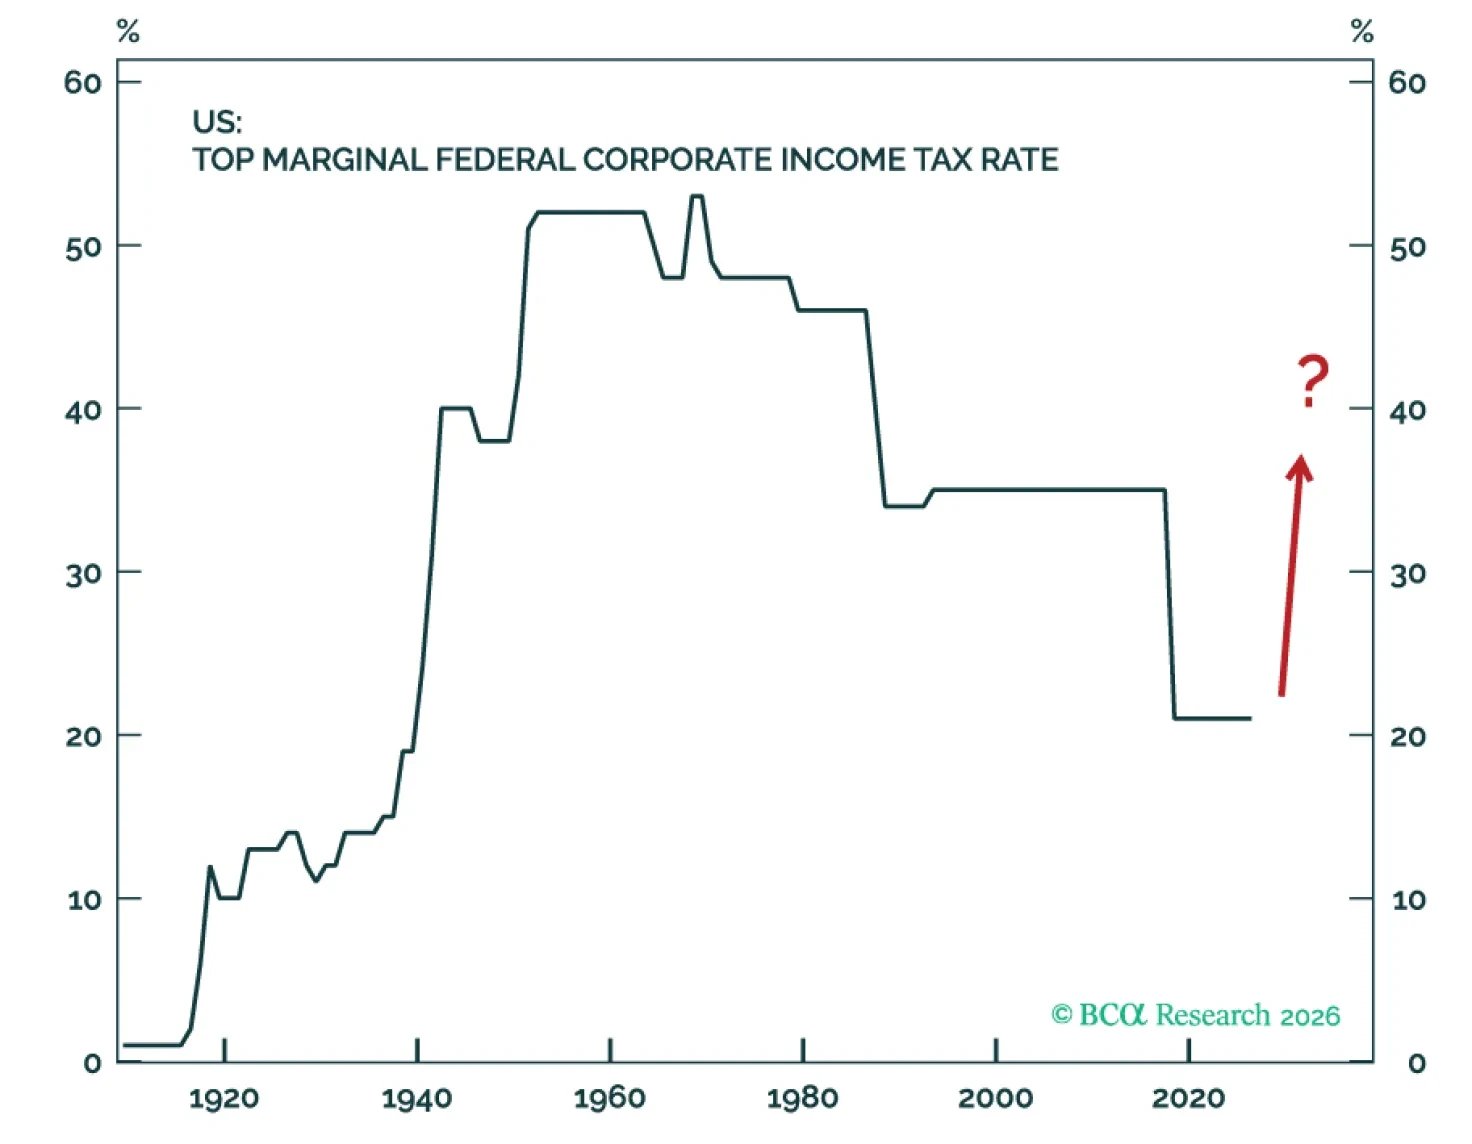
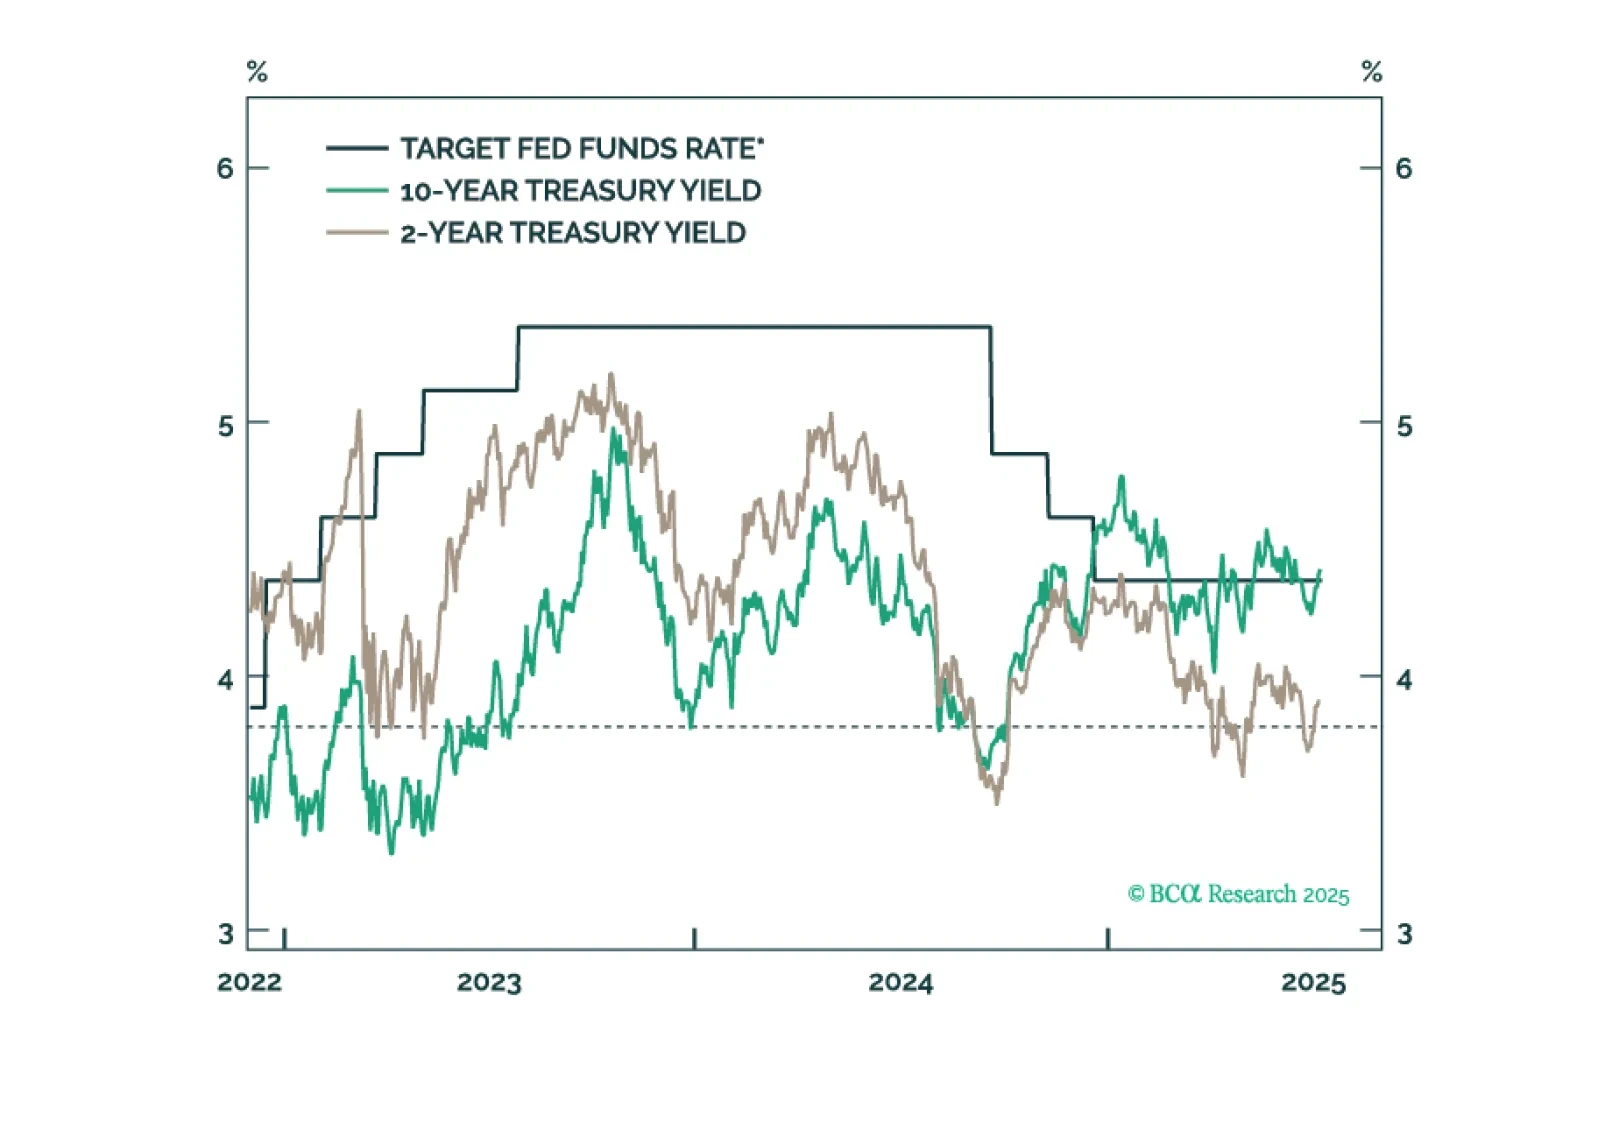
We highlight several potential inflections in well-established structural factors, pointing out ways that markets might respond differently this time to economic data and policy actions.
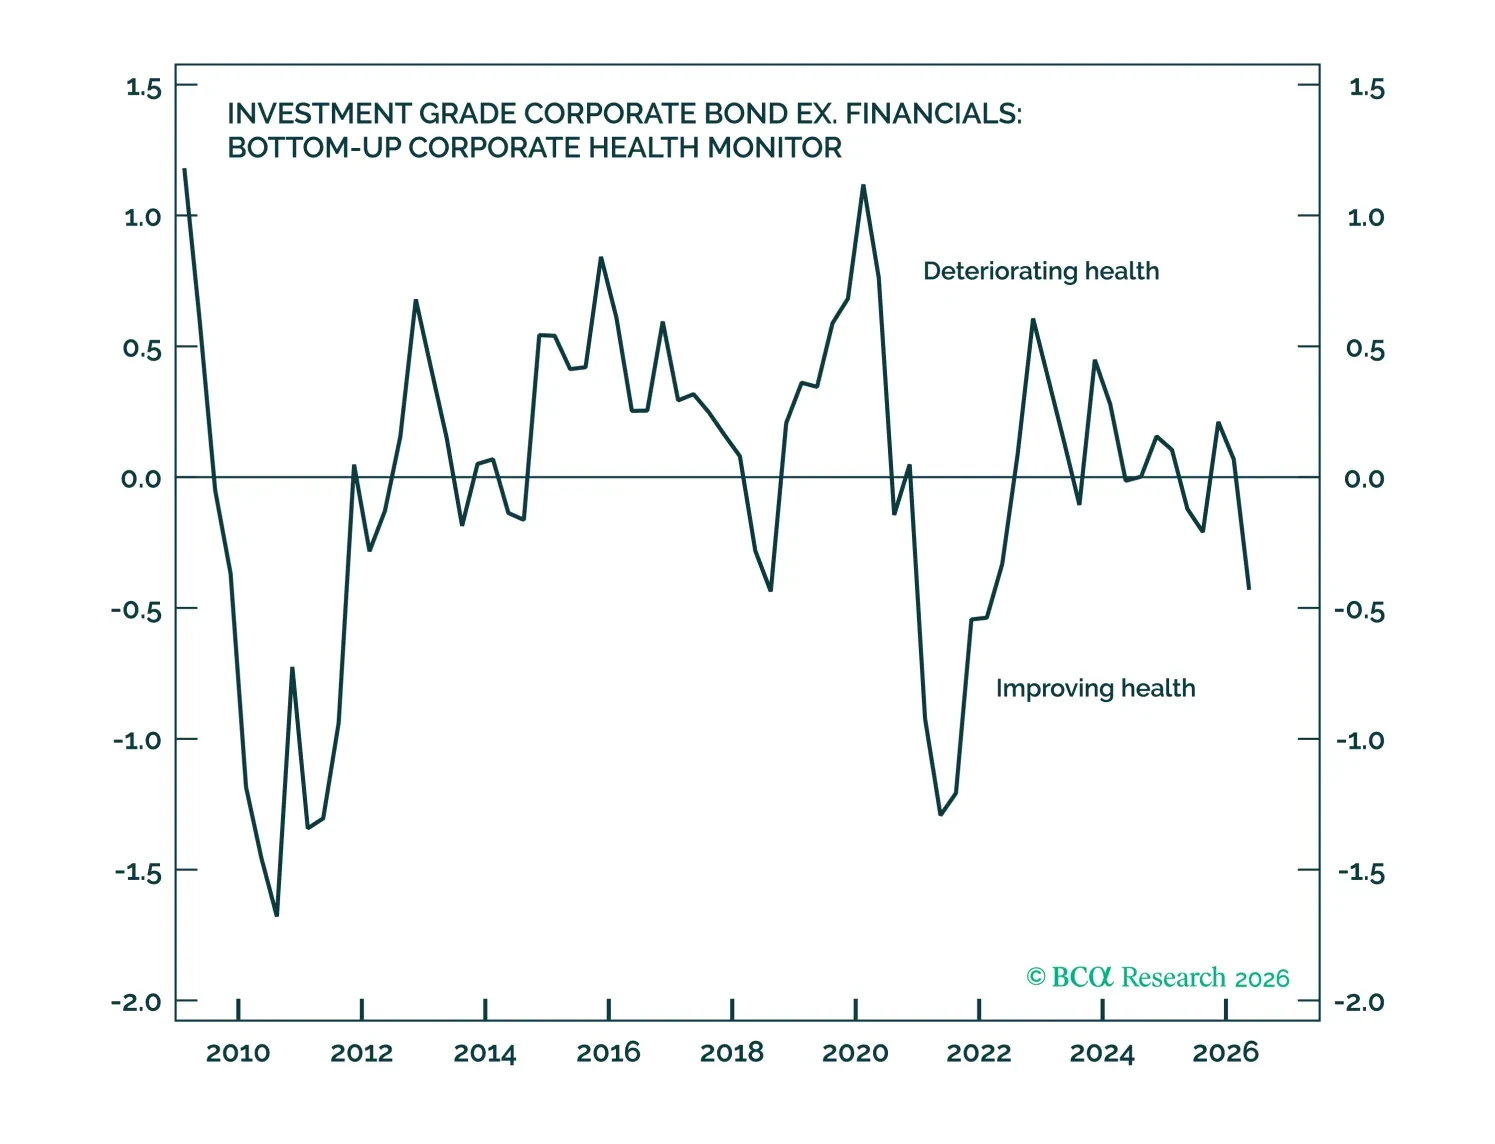
US corporate balance sheet health looks strong overall, and credit metrics aren’t showing any significant negative impact from the AI issuance boom.
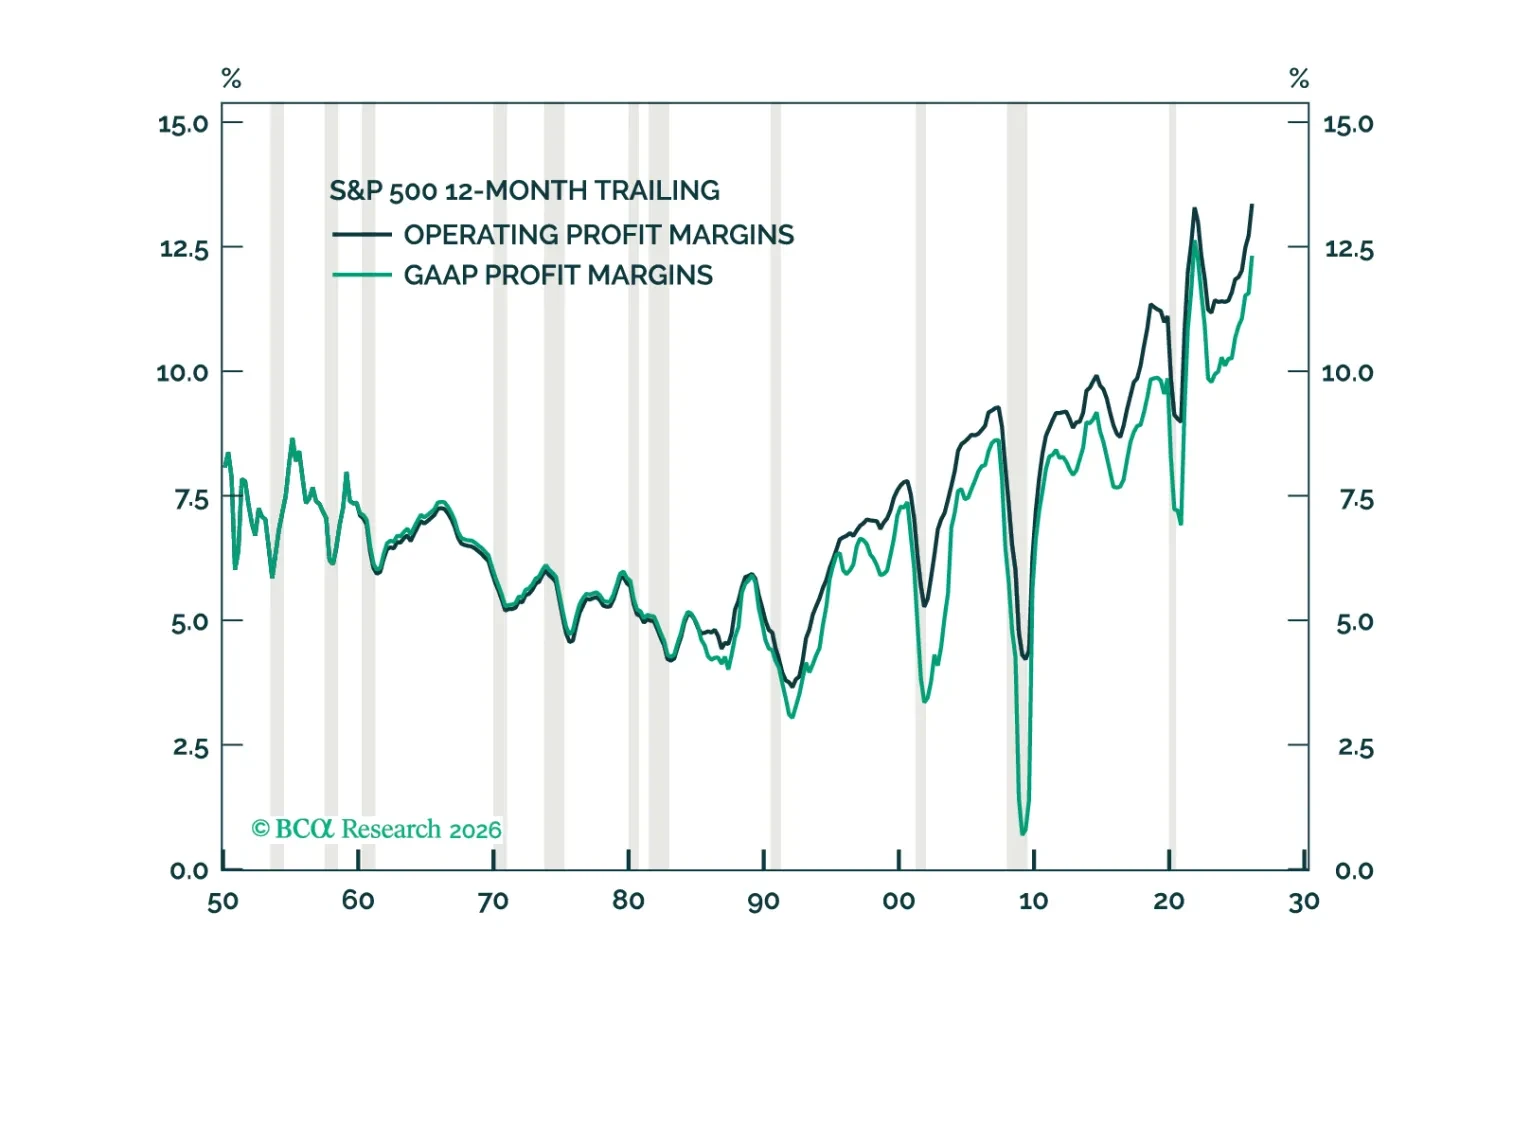
The Goldilocks environment for US profit margins should start to sour next year. Contrary to conventional wisdom, AI could end up eroding margins for both producers and consumers of artificial intelligence.
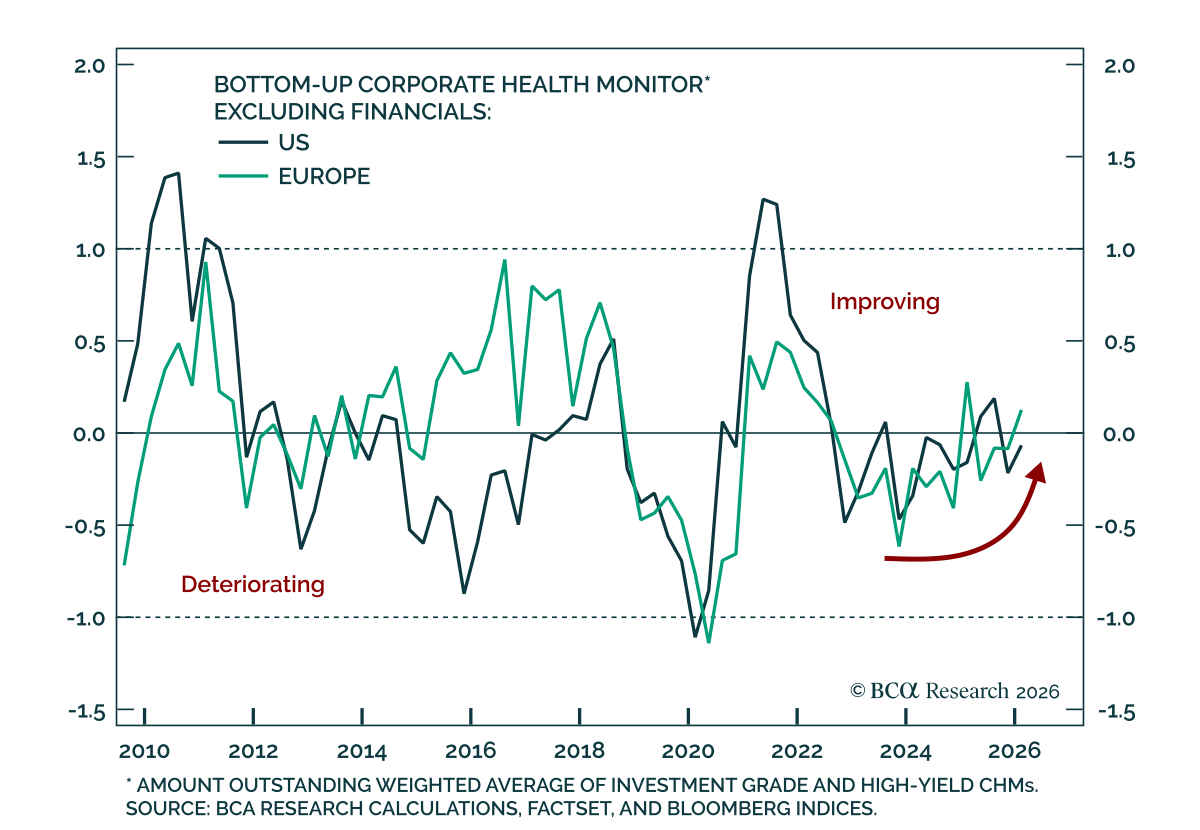
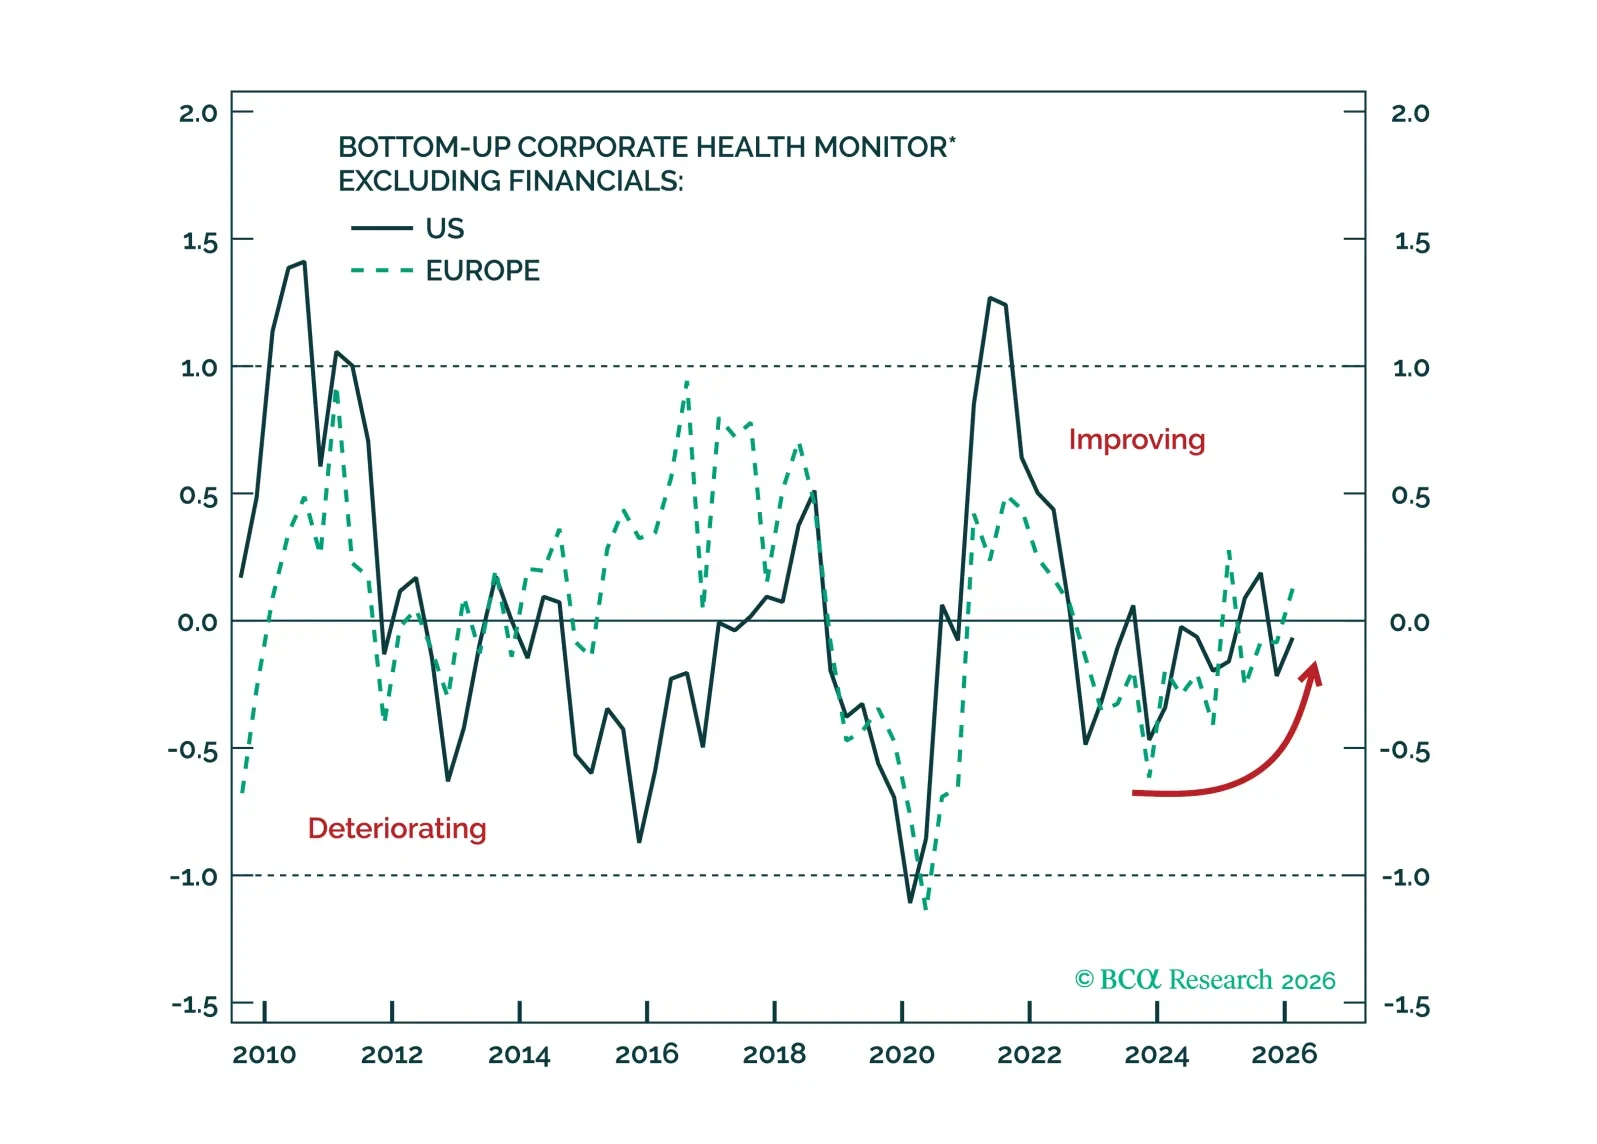
Corporate health remains supportive of tight credit spreads in both the US and Europe, but a growing divide is emerging beneath the surface. Investment-grade issuers continue to strengthen, while lower-rated borrowers face mounting pressures. Credit markets are pricing resilience, leaving investors vulnerable should corporate fundamentals begin to deteriorate.
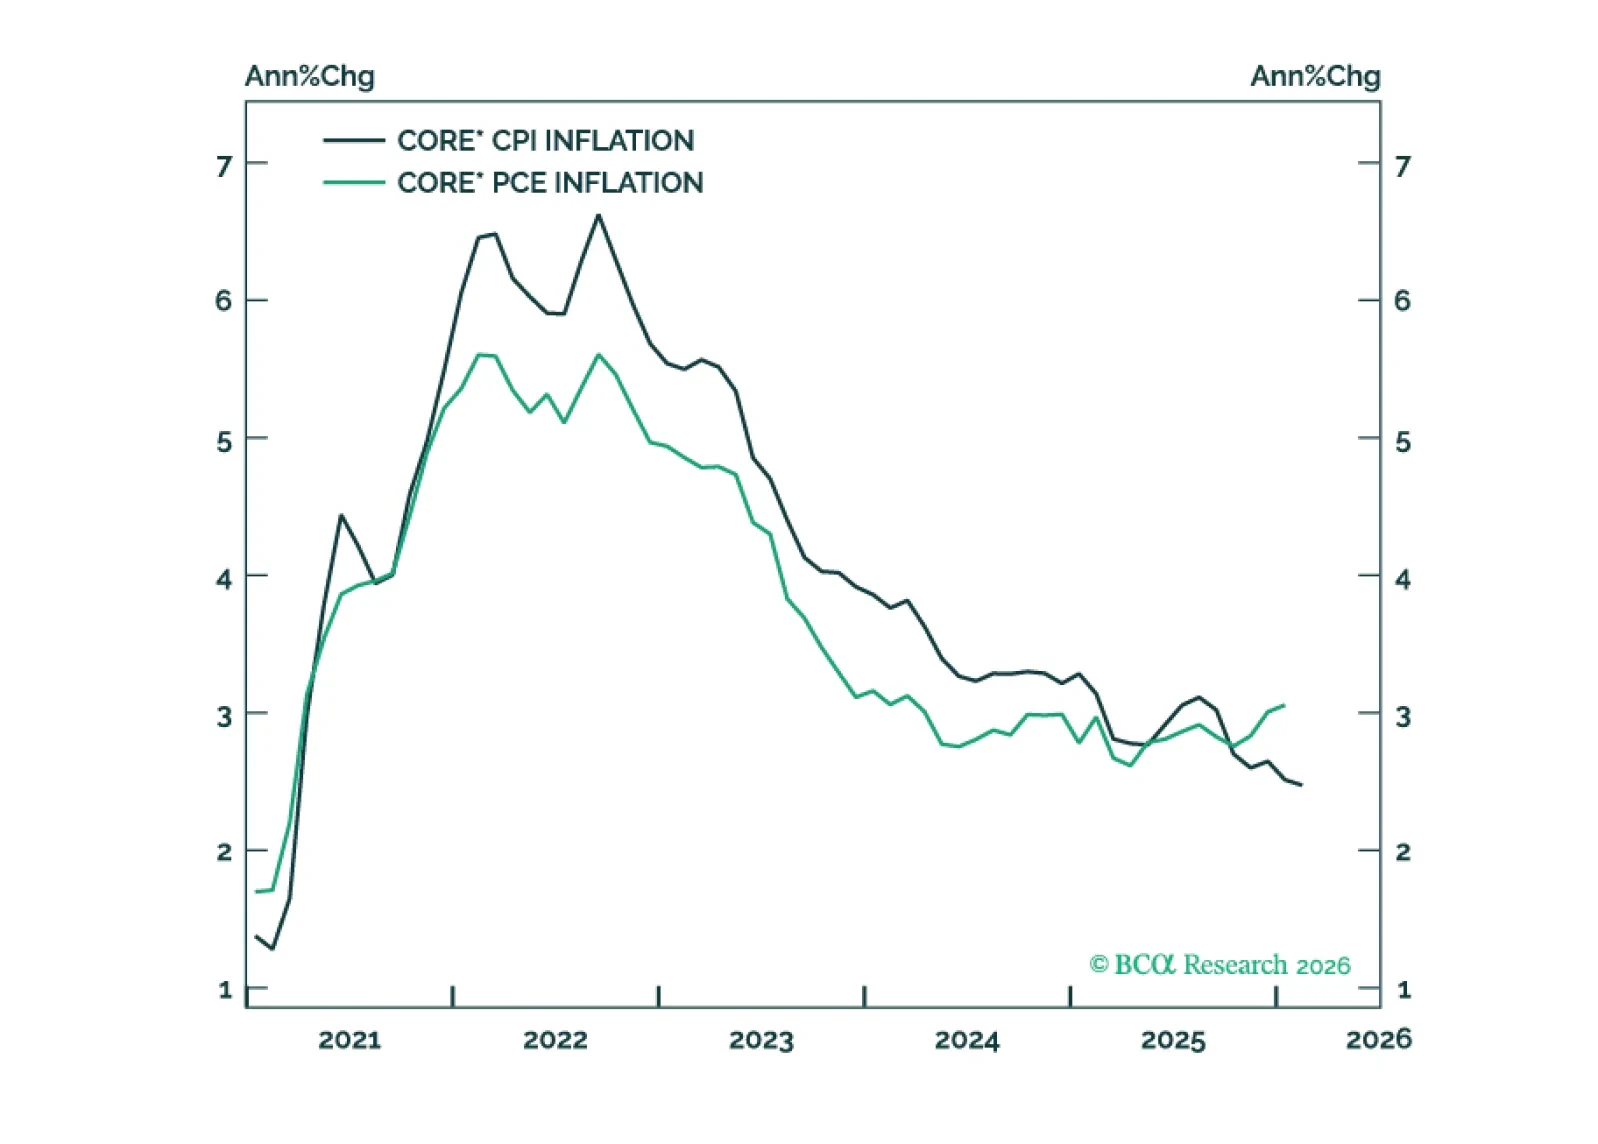
The gap between PCE and CPI inflation will narrow within the next few months, mostly driven by core PCE inflation converging toward its trimmed mean.
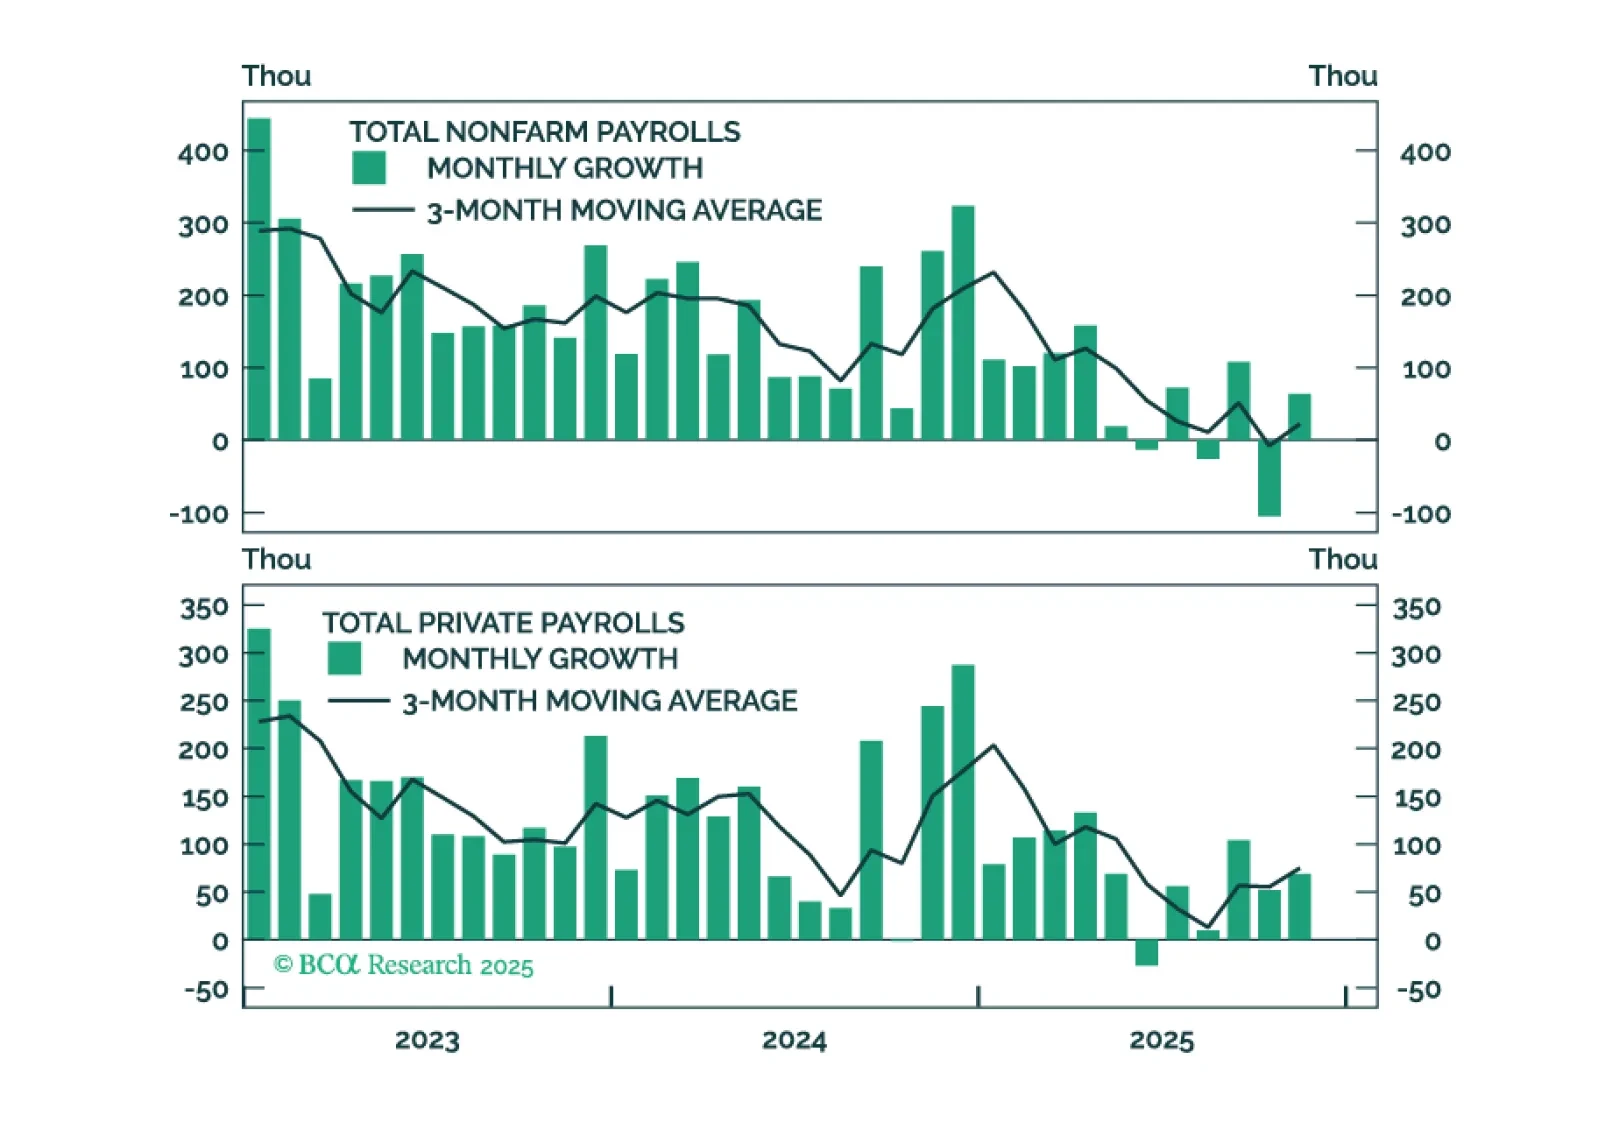
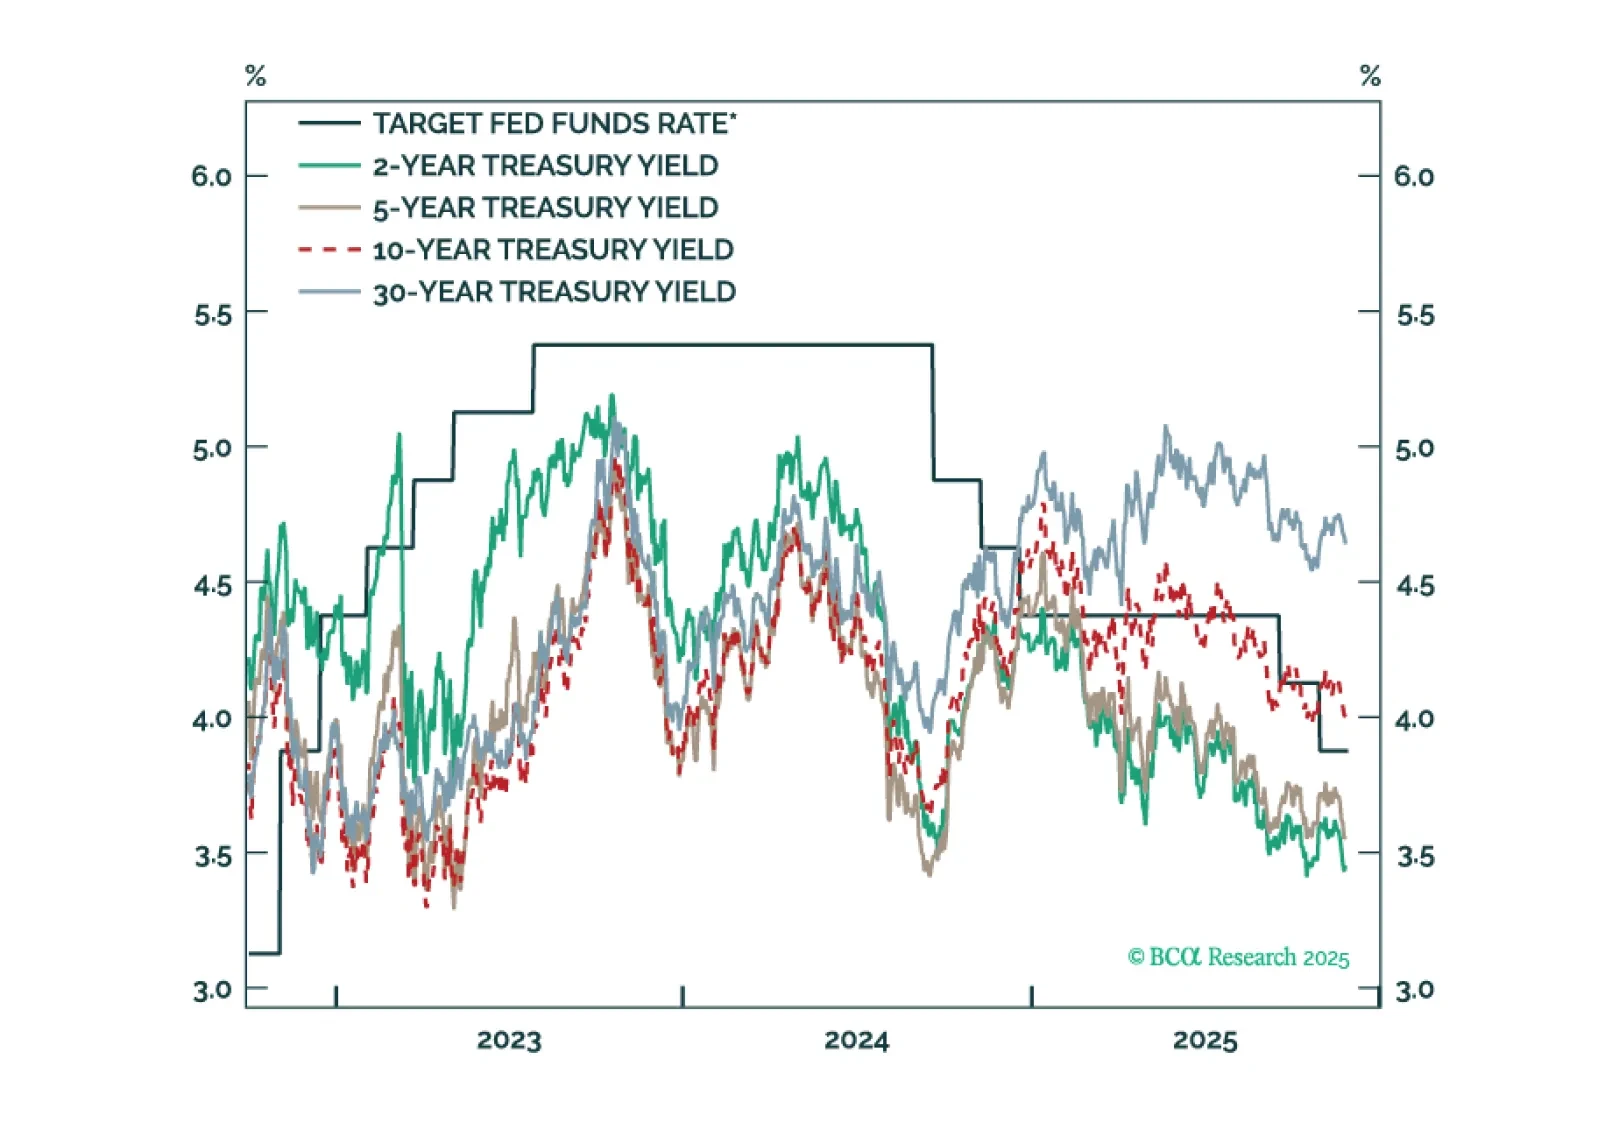
Employment Data Point To Dovish Policy Surprises In 2026
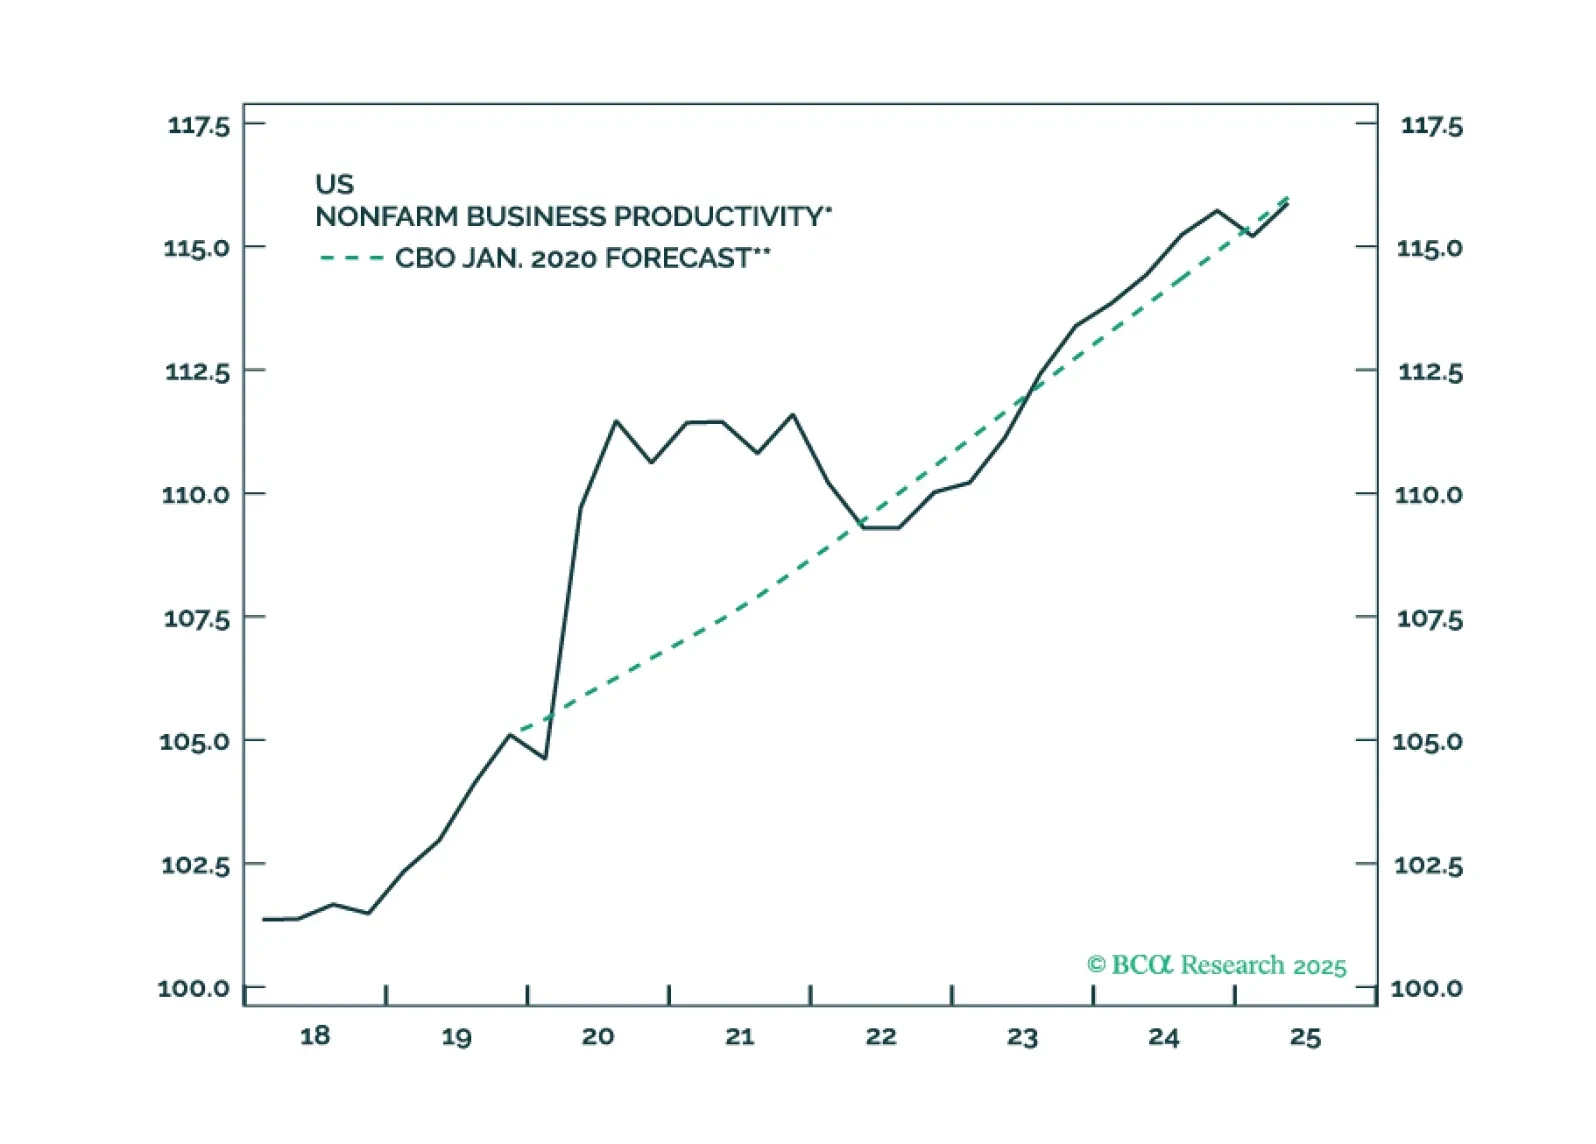
The AI boom has had less of an impact on the economy than widely believed. This may eventually change, but the risk is that investors grow impatient before it does.