 CoreMacro
BCA’s flagship global macro and investment strategy platform, helping investors anticipate regime shifts, connect signals across regions and asset classes, and navigate the world’s most difficult macro questions.
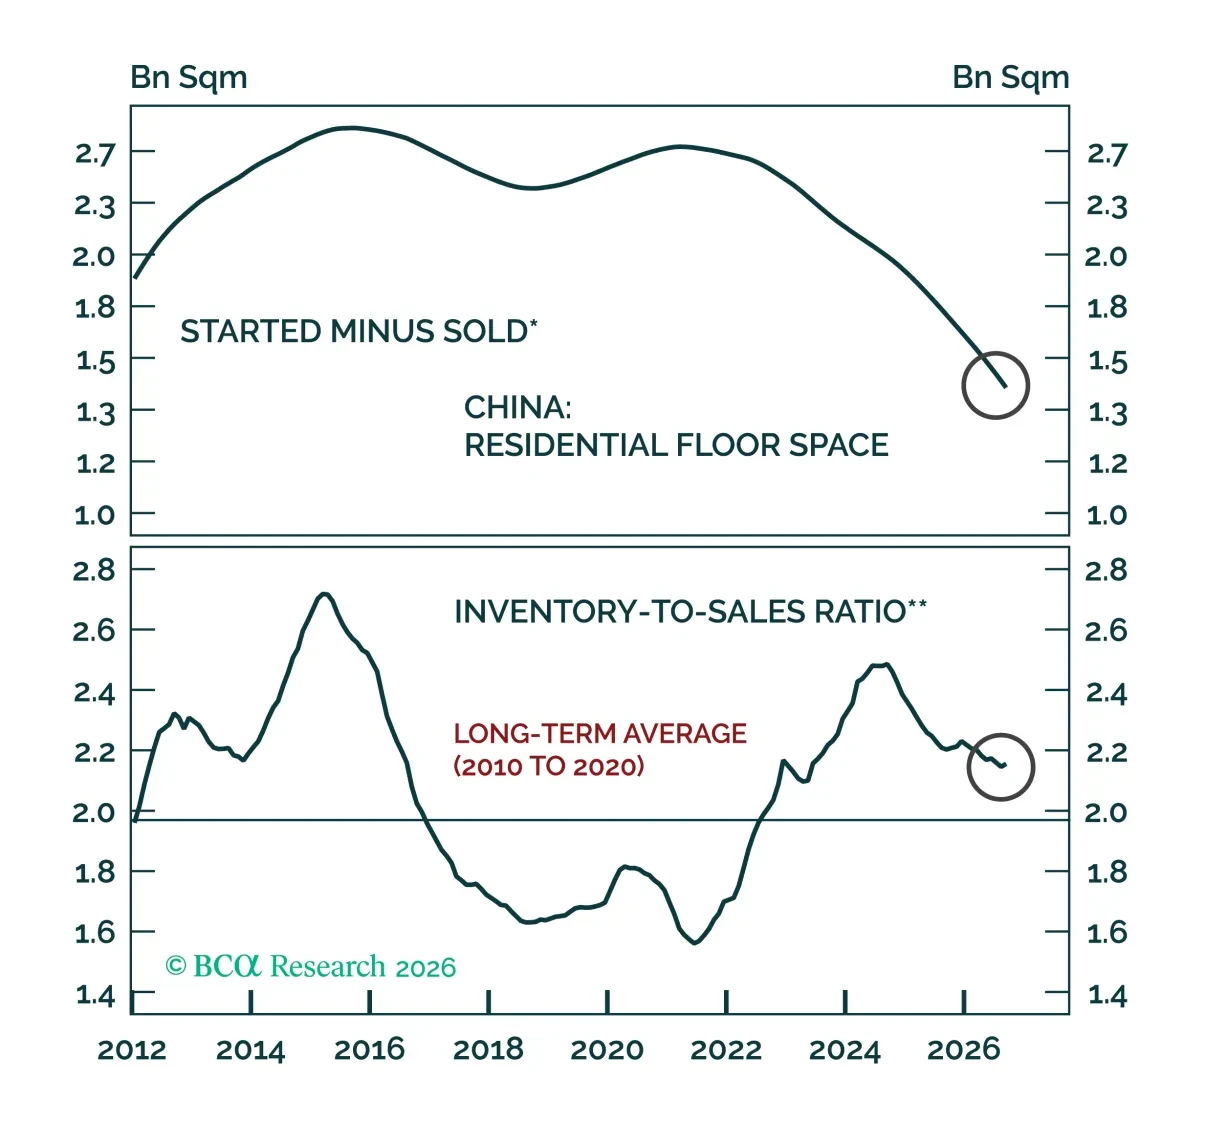
After a sharp five-year correction, China's top-tier housing markets will likely bottom out late next year. The rest of the country, however, will keep struggling with oversupply.
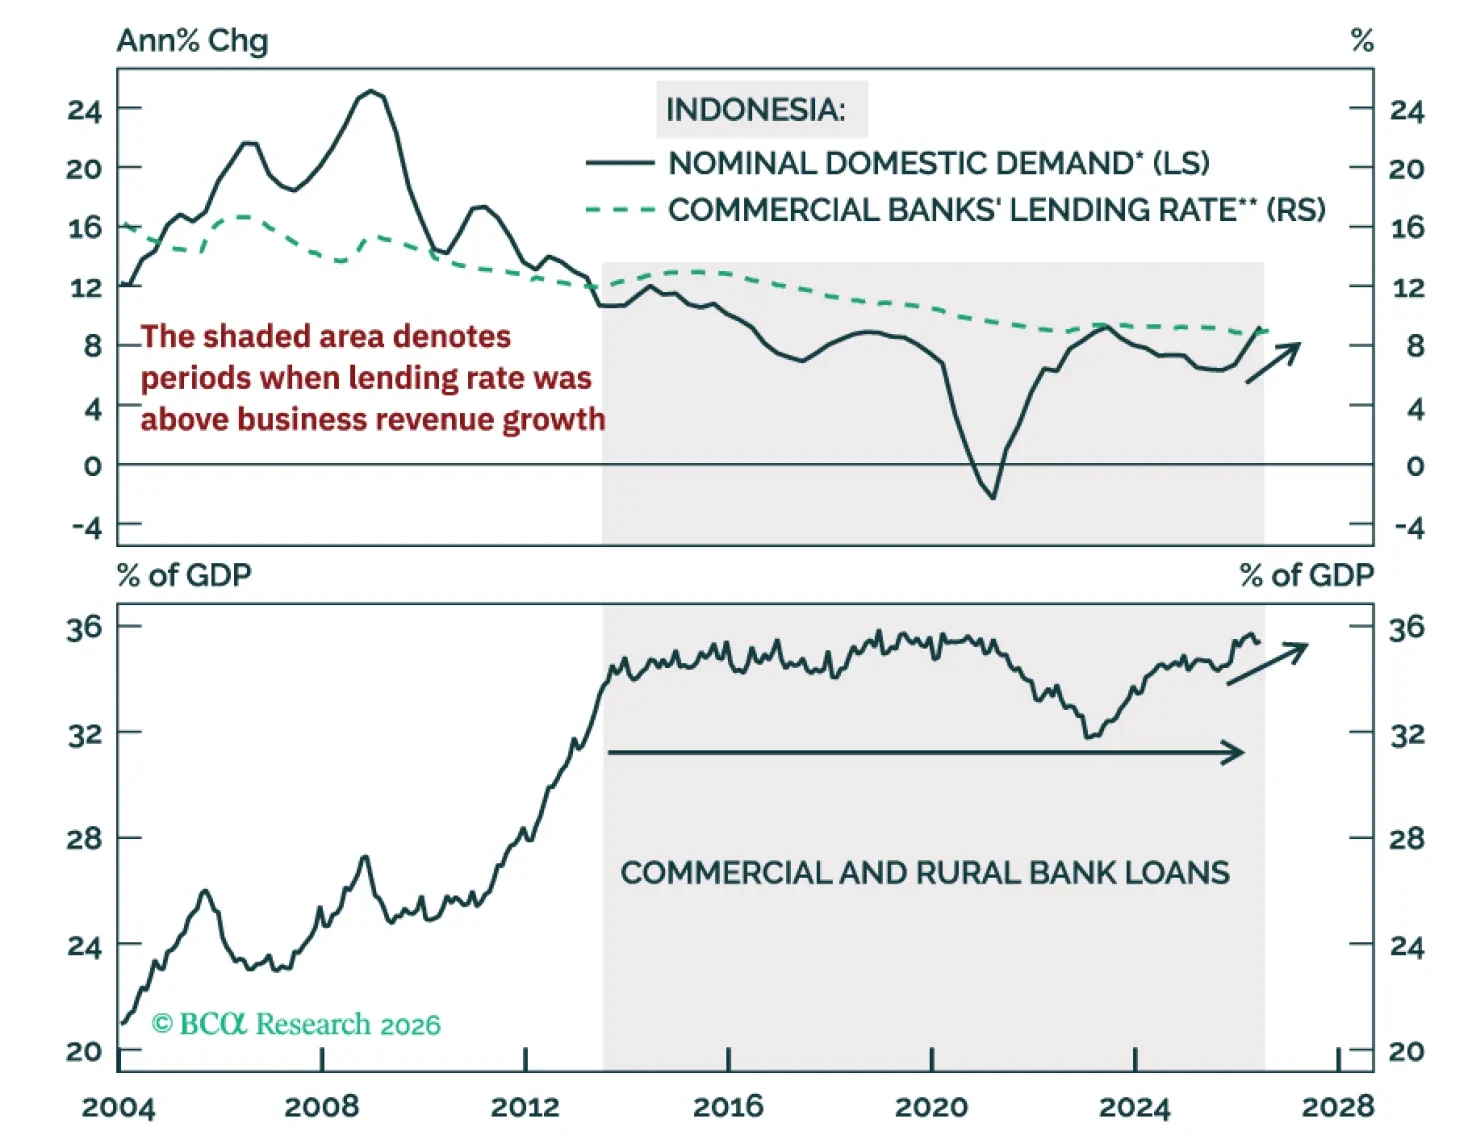
Given that the economy’s productive capacity is limited, government stimulus will lift nominal growth but do little to increase real output growth. The upshot will be rising inflation and wider twin deficits. This is bearish for the currency, bonds, and stocks.
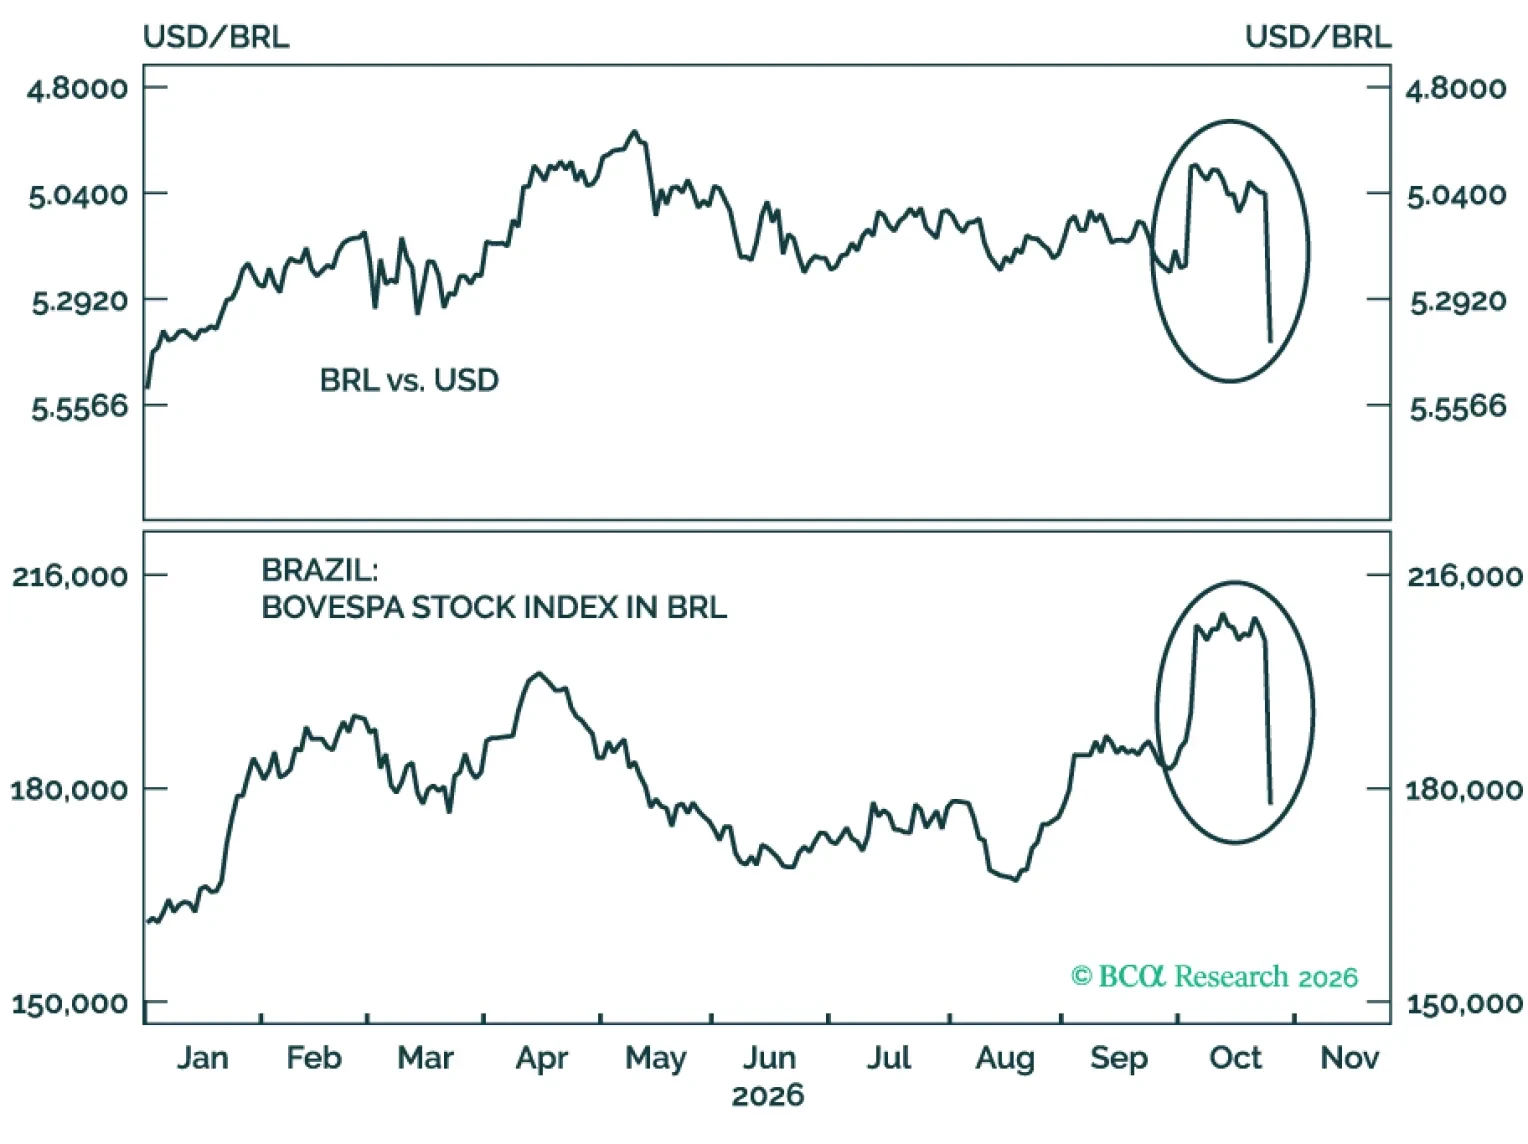
Brazil’s elections have turned into a game of roulette for investors. Bulls and bears were each wrong-footed between the first and second rounds of elections. We are downgrading Brazilian equities, local bonds, and sovereign credit to underweight within their respective EM portfolios.
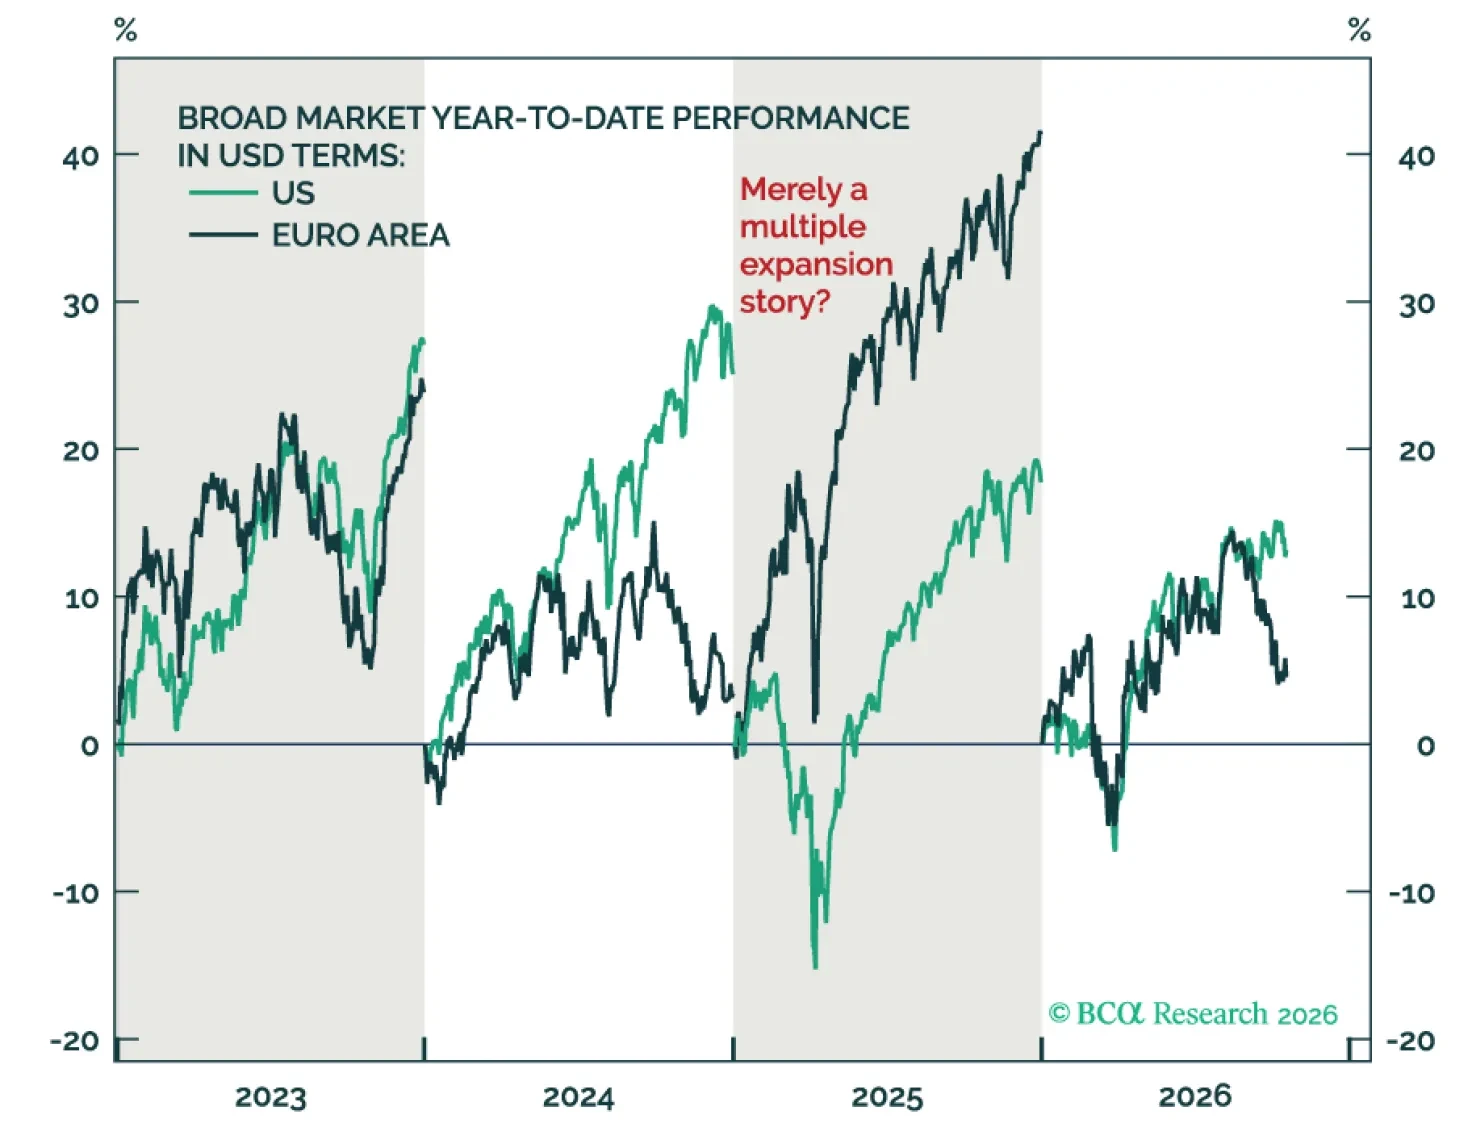
Europe has 99 problems, but the paucity of bearish views about the Old Continent is not one of them! And yet, somewhat shockingly, European assets have outperformed US assets over the past two years. Sure, markets make mistakes. But the macro graveyards are littered with investors who thought they were smarter than the markets. In this report, we suggest that Europe is on a cusp of significant structural reforms that will unlock value in its services sector. And that while many of the challenges are real, they’re either well understood or priced in.
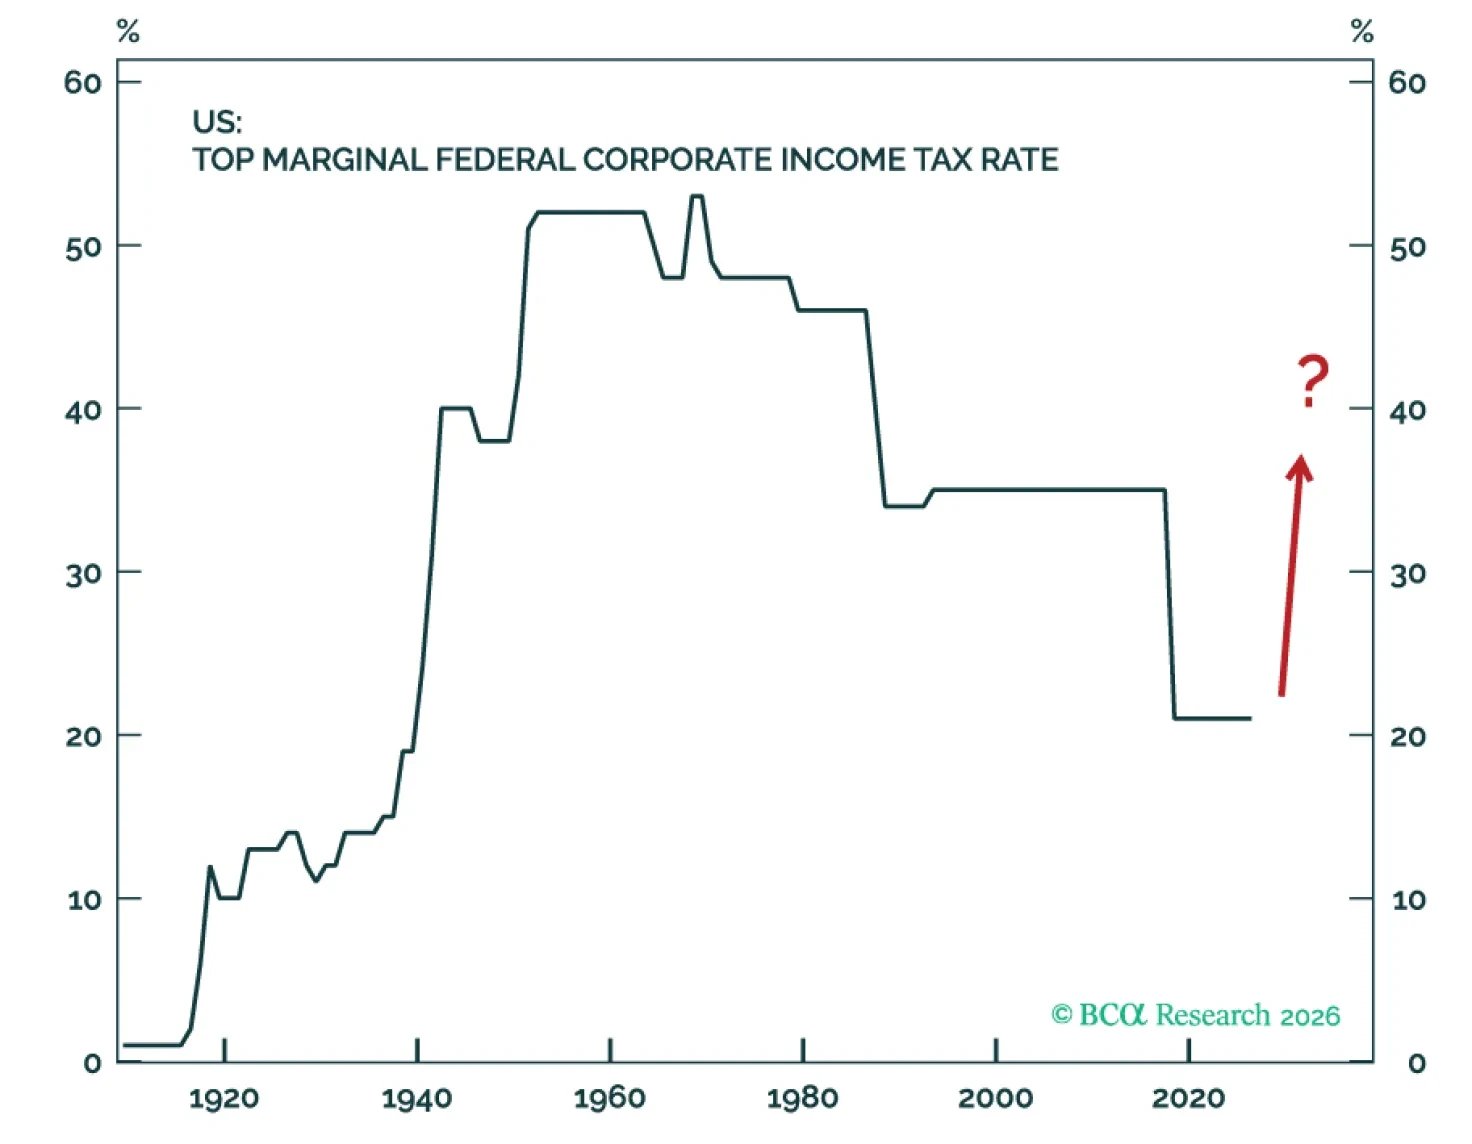
We highlight several potential inflections in well-established structural factors, pointing out ways that markets might respond differently this time to economic data and policy actions.
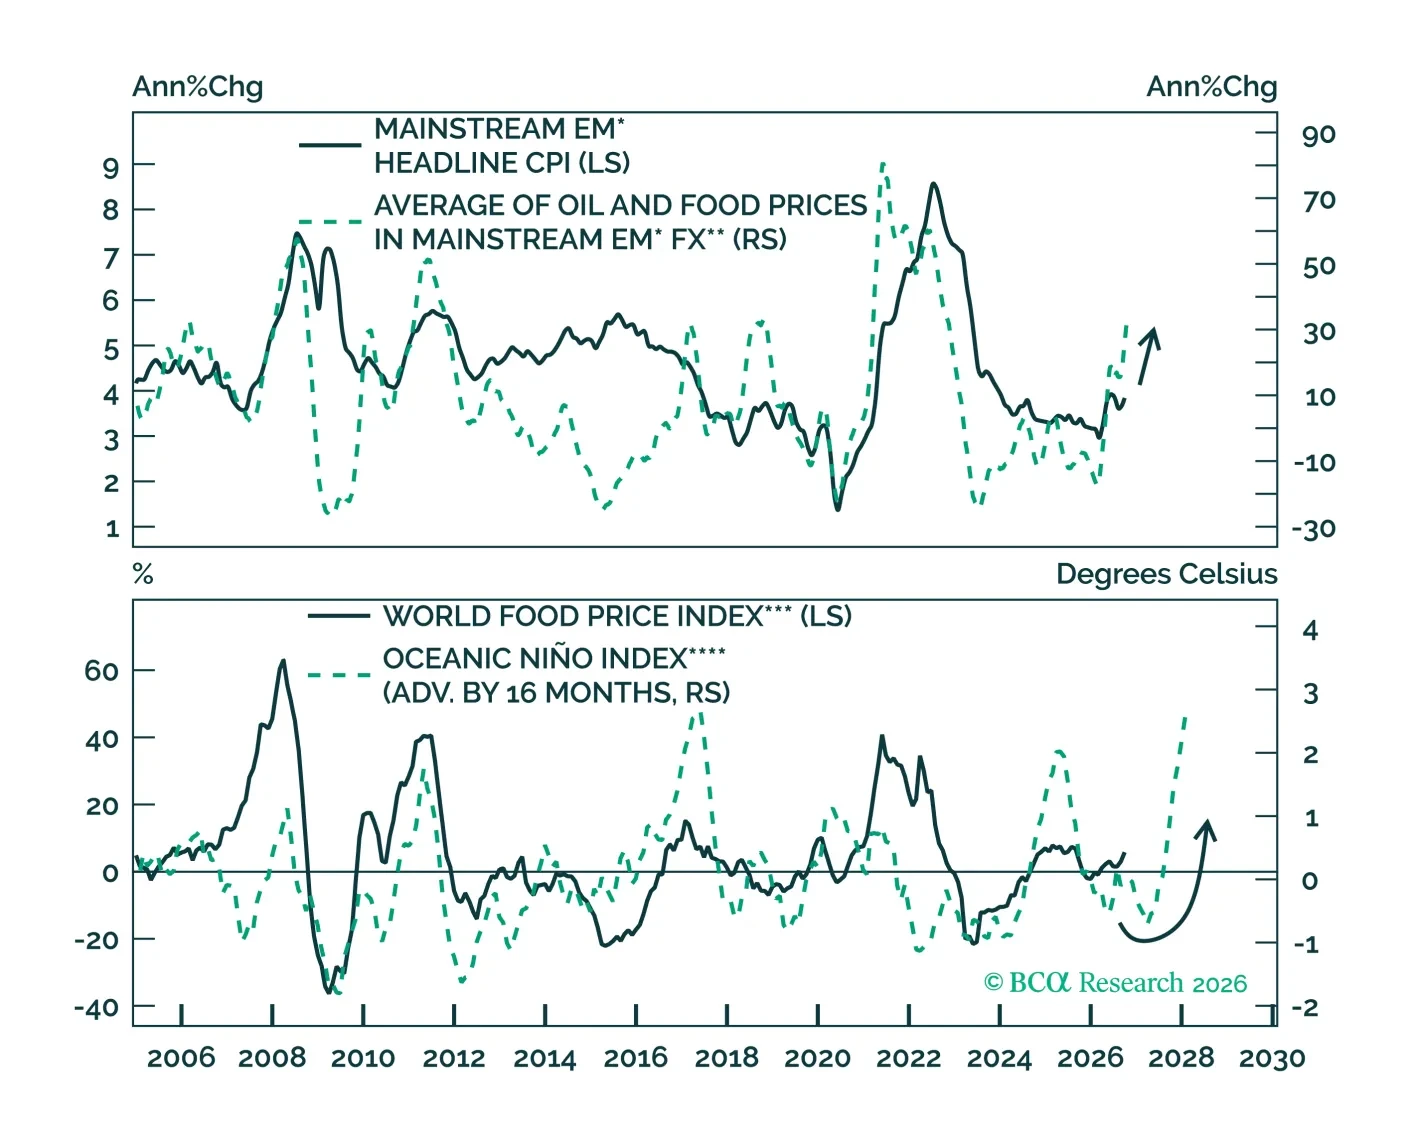
EM local bonds face near-term turbulence from rising inflation, global risk aversion, and currency weakness. Use the sell-off to build exposure: medium- and longer-term fundamentals remain favorable.
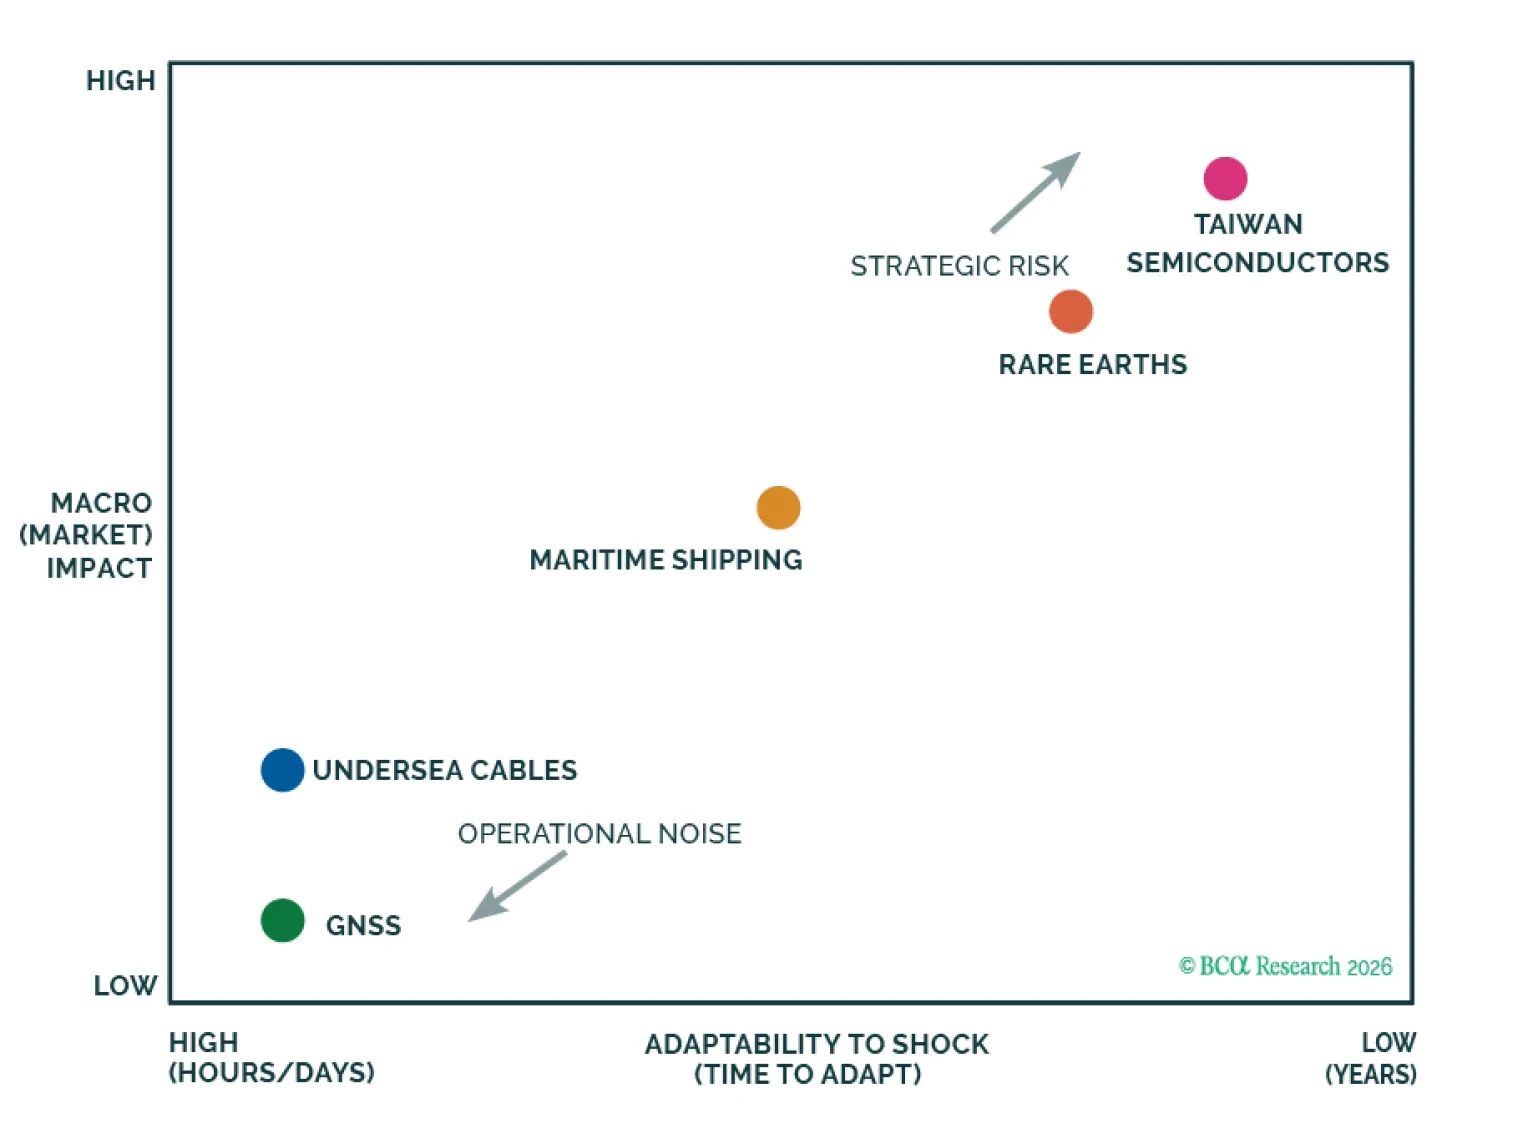
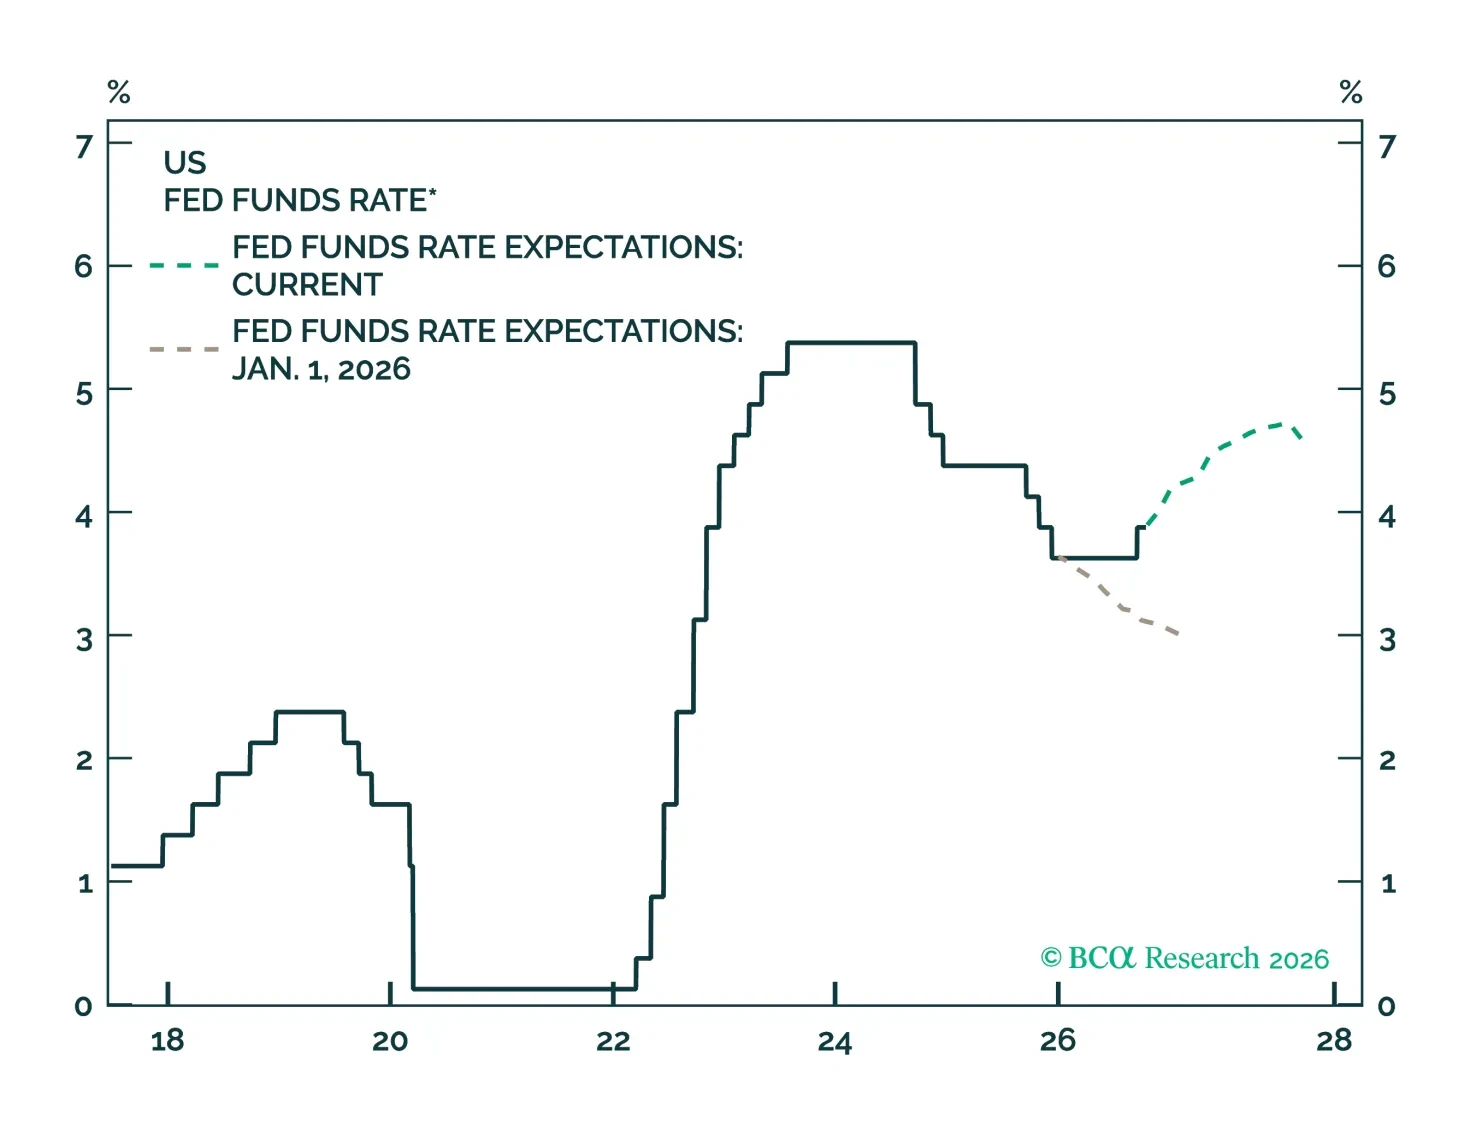
AI capex is supporting the global economy but also generating collateral damage for rate-sensitive sectors such as housing, as well as highly indebted governments. Maintain a benchmark allocation to equities for now and look to get more defensive next year.
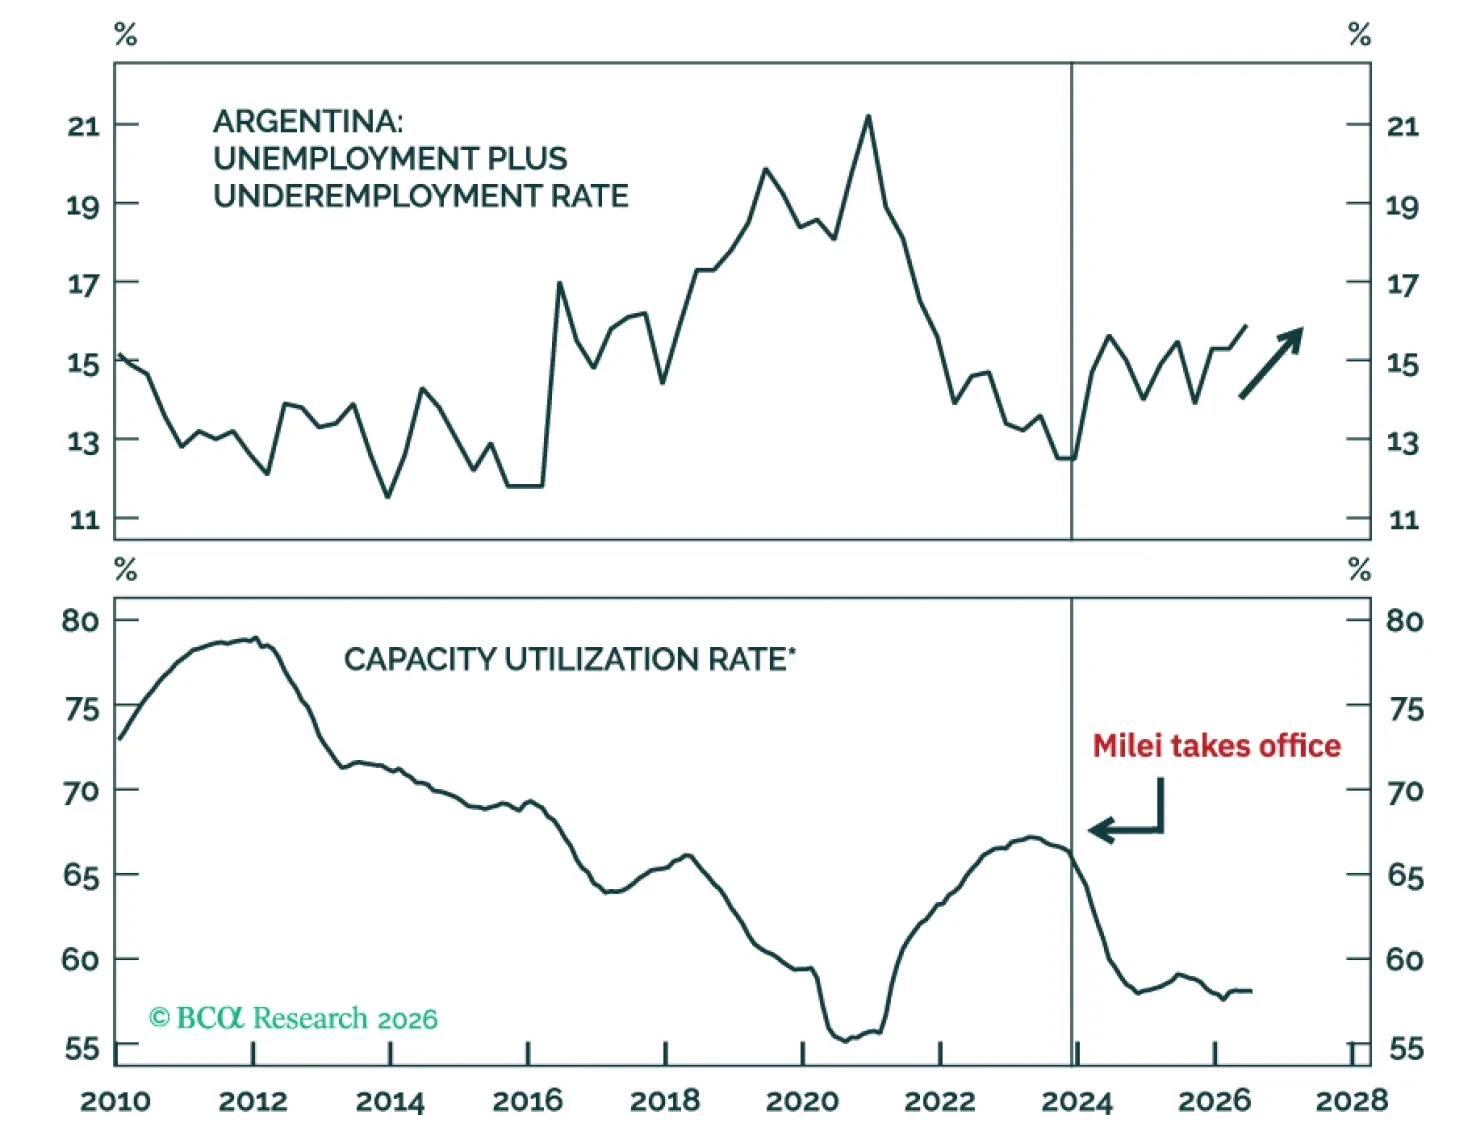
If President Milei does not ease policy immediately to contain the disinflationary squeeze, he is likely to lose next year's election. This means neoliberal structural reforms will suffer a setback in subsequent years. Close long positions in Argentine assets.