 CoreMacro
| Europe
Country-by-country analysis of Europe’s economy, policy, and politics, pinpointing opportunities across the region.
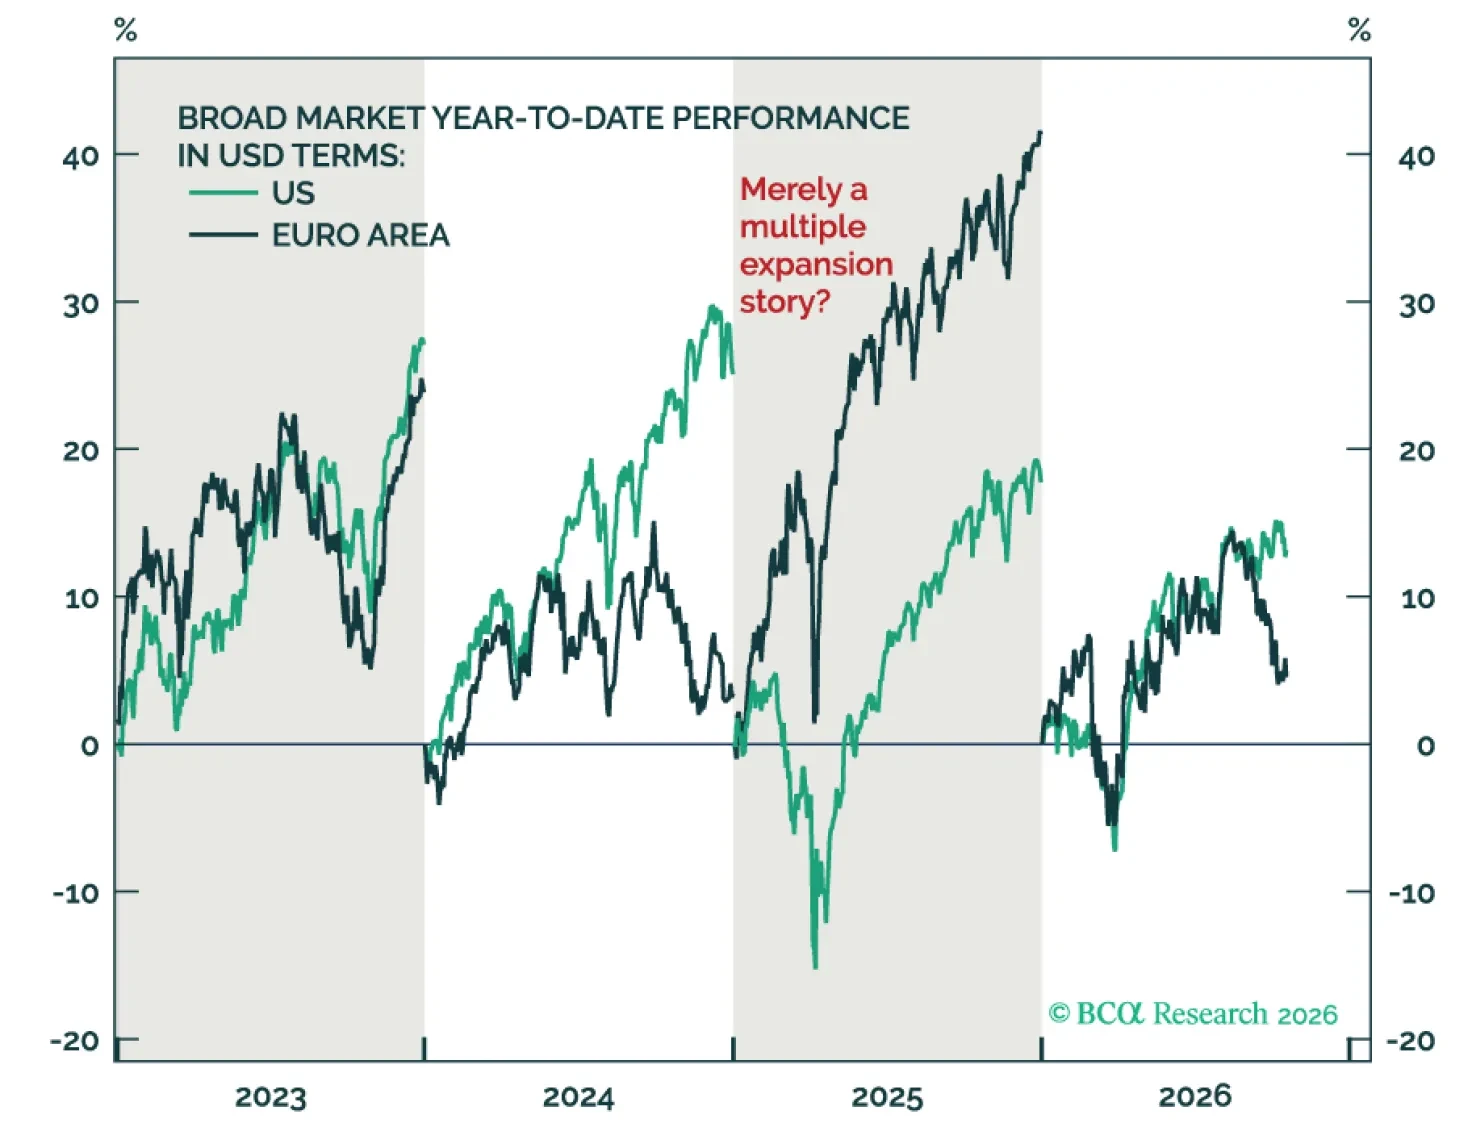
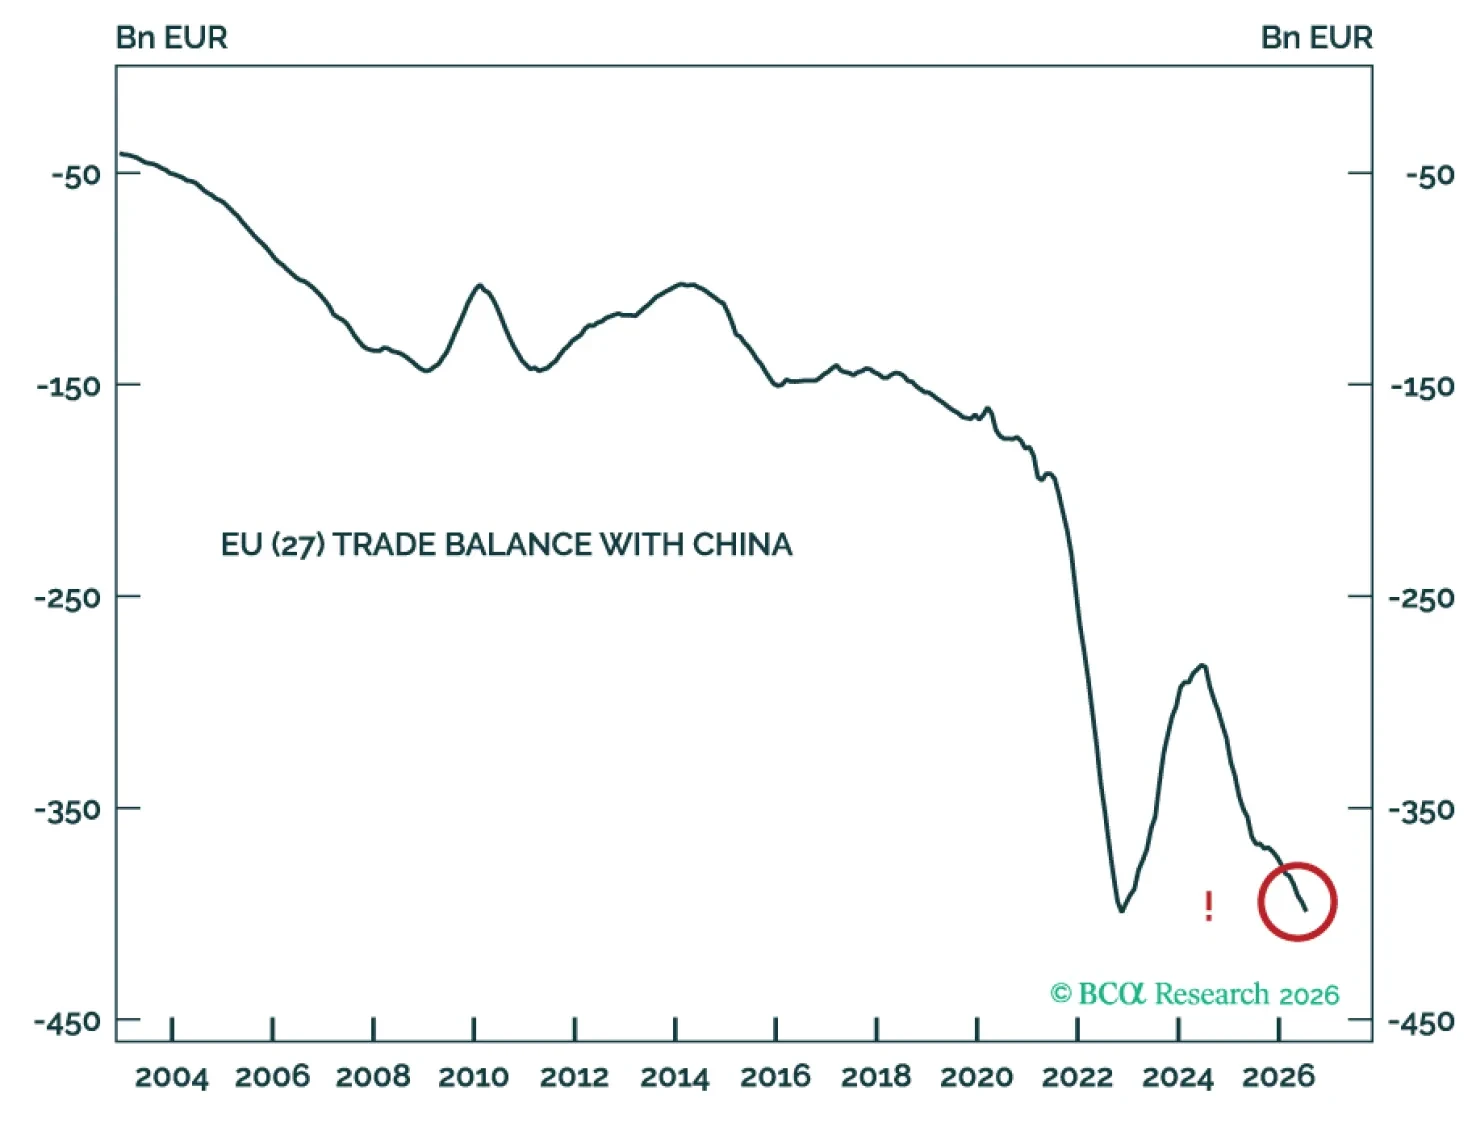
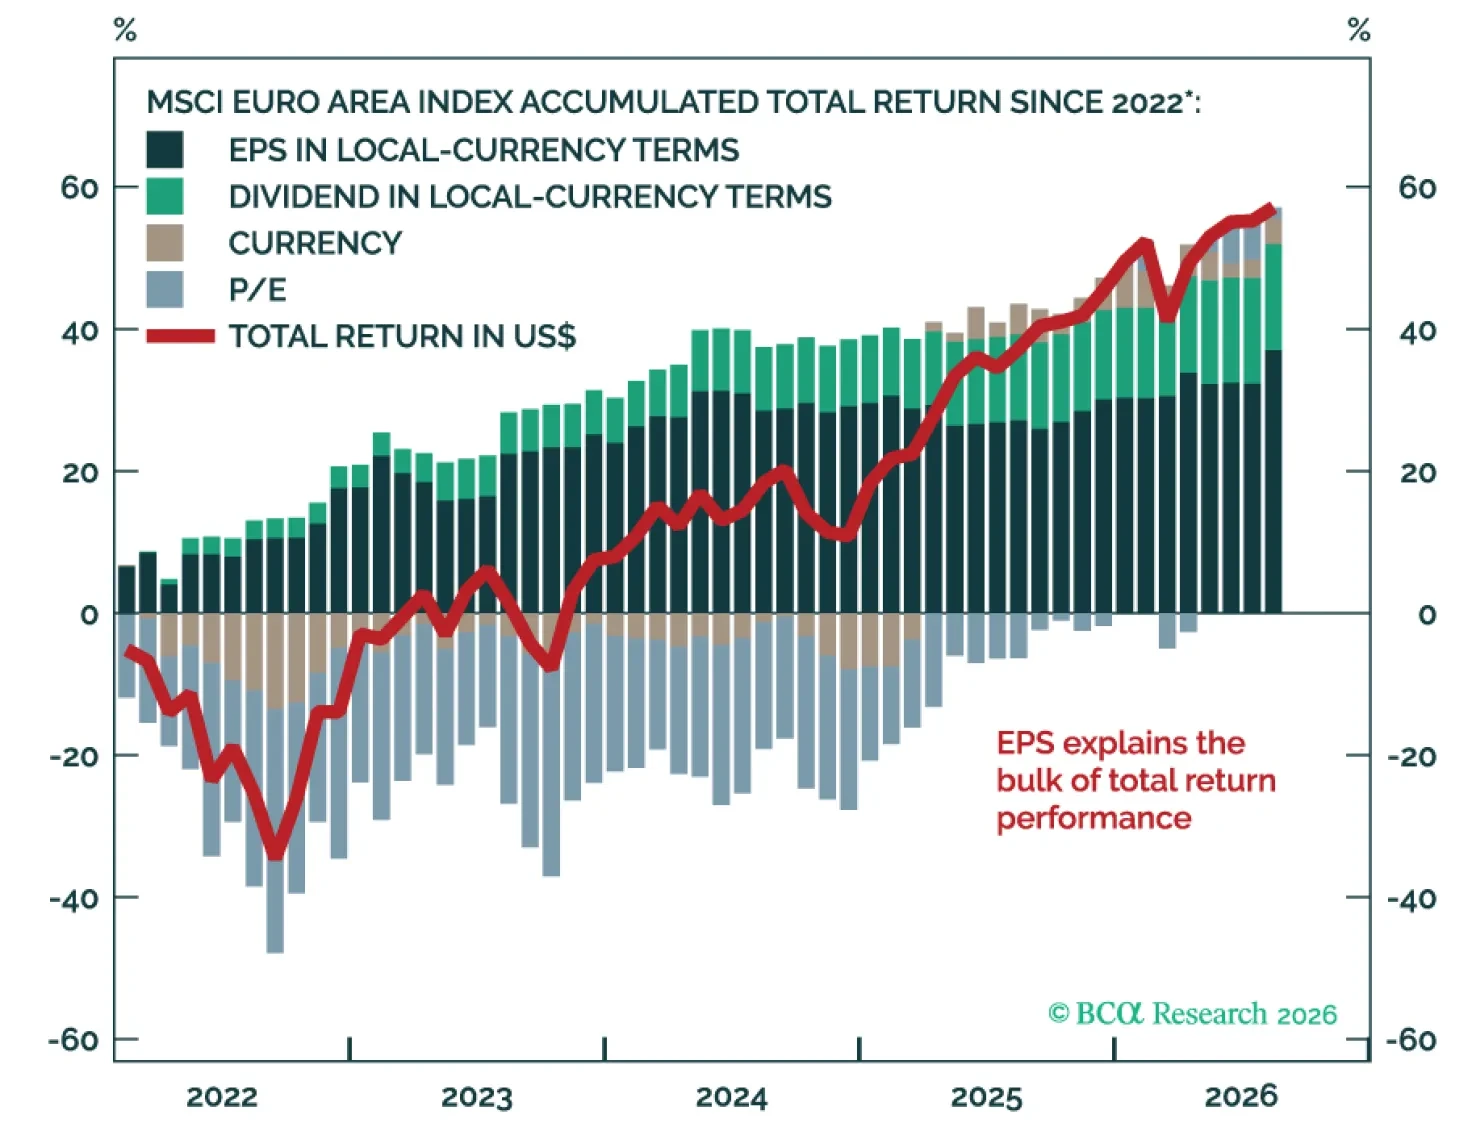
Europe has 99 problems, but the paucity of bearish views about the Old Continent is not one of them! And yet, somewhat shockingly, European assets have outperformed US assets over the past two years. Sure, markets make mistakes. But the macro graveyards are littered with investors who thought they were smarter than the markets. In this report, we suggest that Europe is on a cusp of significant structural reforms that will unlock value in its services sector. And that while many of the challenges are real, they’re either well understood or priced in.
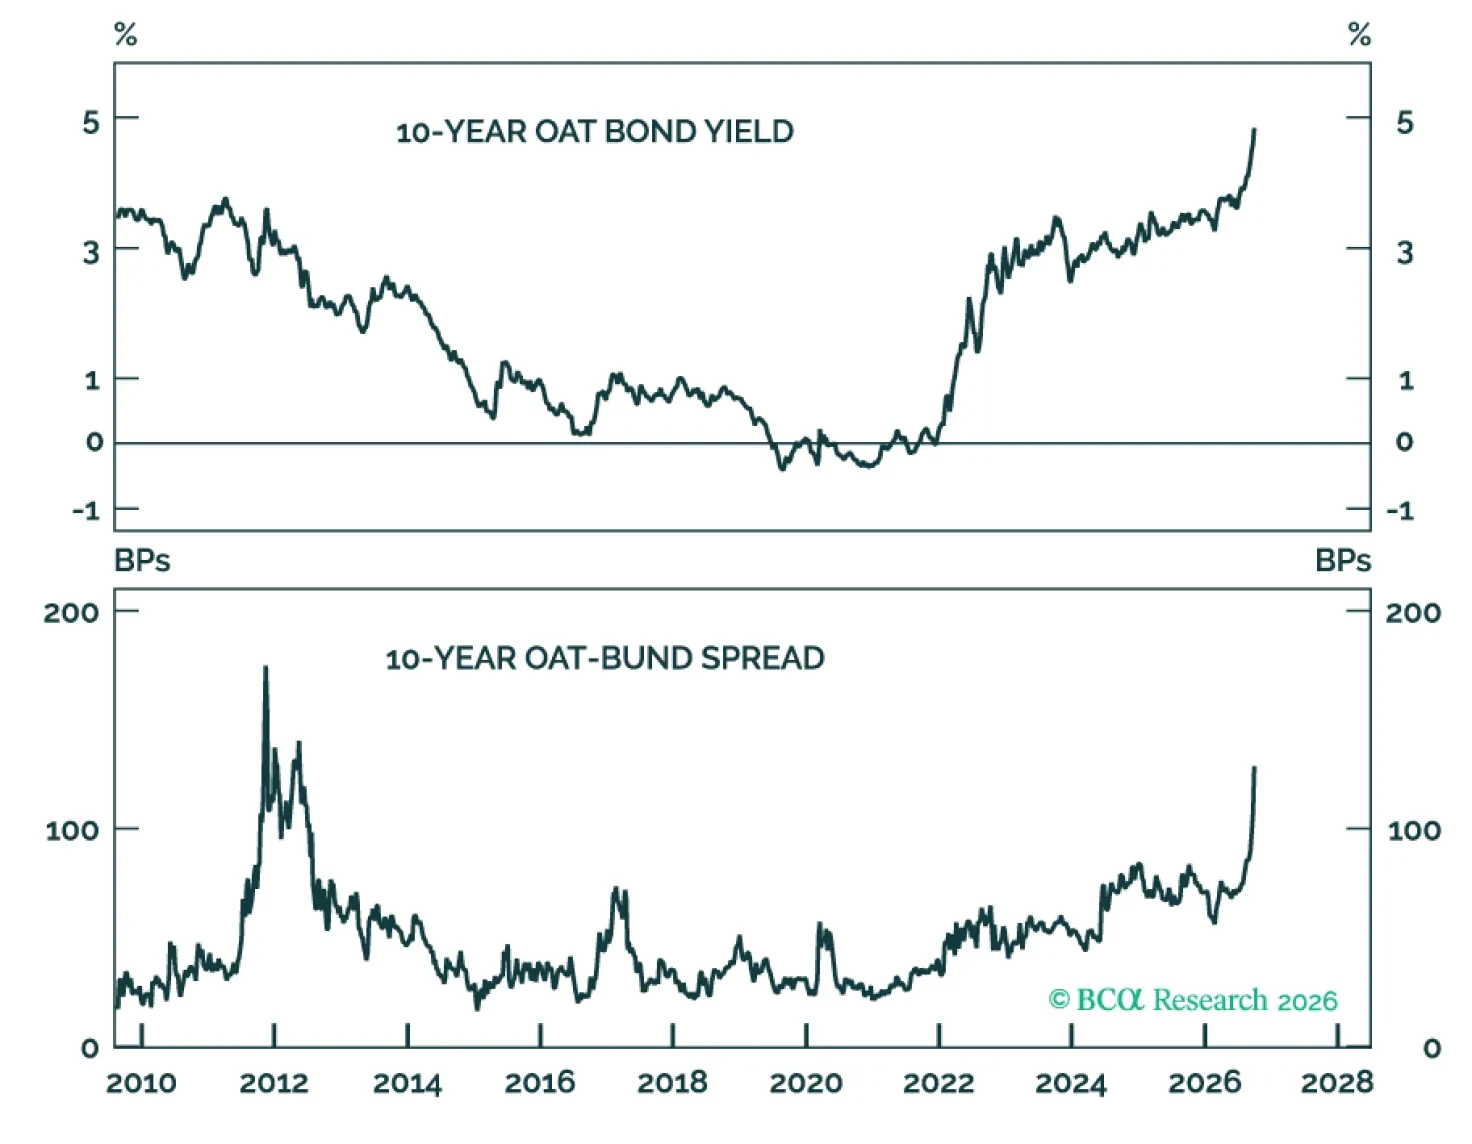
Forced selling may be approaching a pause, but France’s fiscal and political adjustment has barely begun. Maintain an underweight in OATs and use relief rallies to reduce exposure. Contained contagion is reassuring for Europe; it is not a buy signal for France.
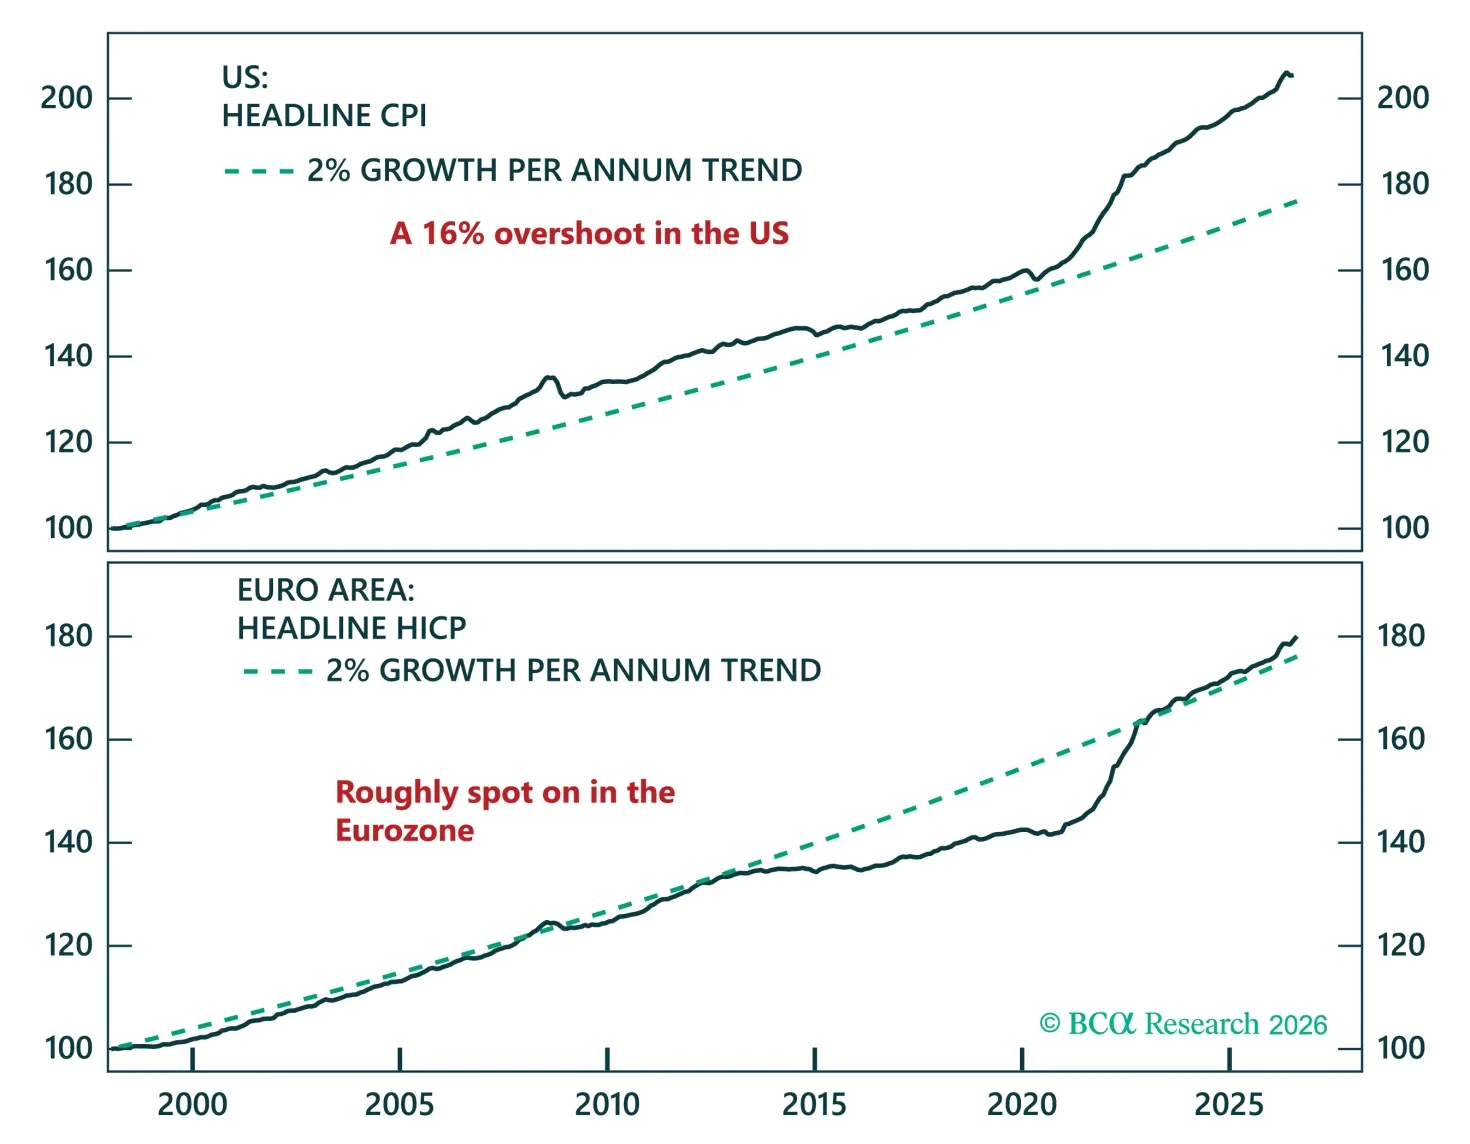
The ECB is winning, and almost nobody's pricing it in. A flatter Phillips curve, a shrinking term premium, a euro built to shrug off France, credibility is the trade.
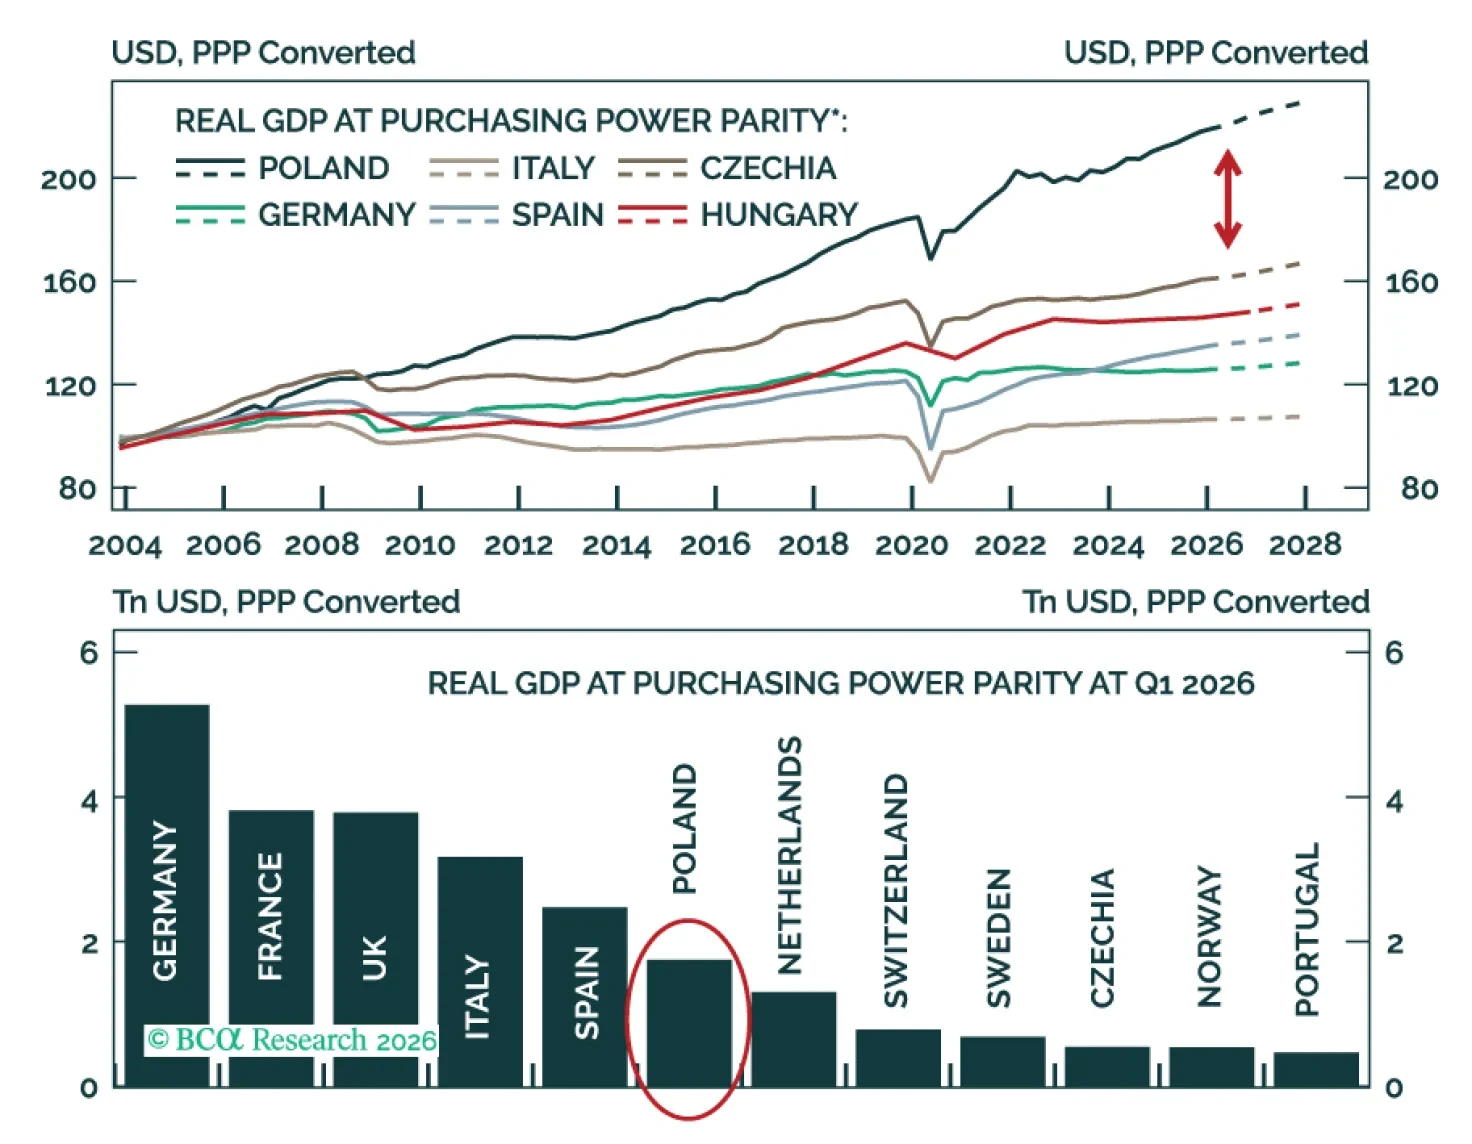
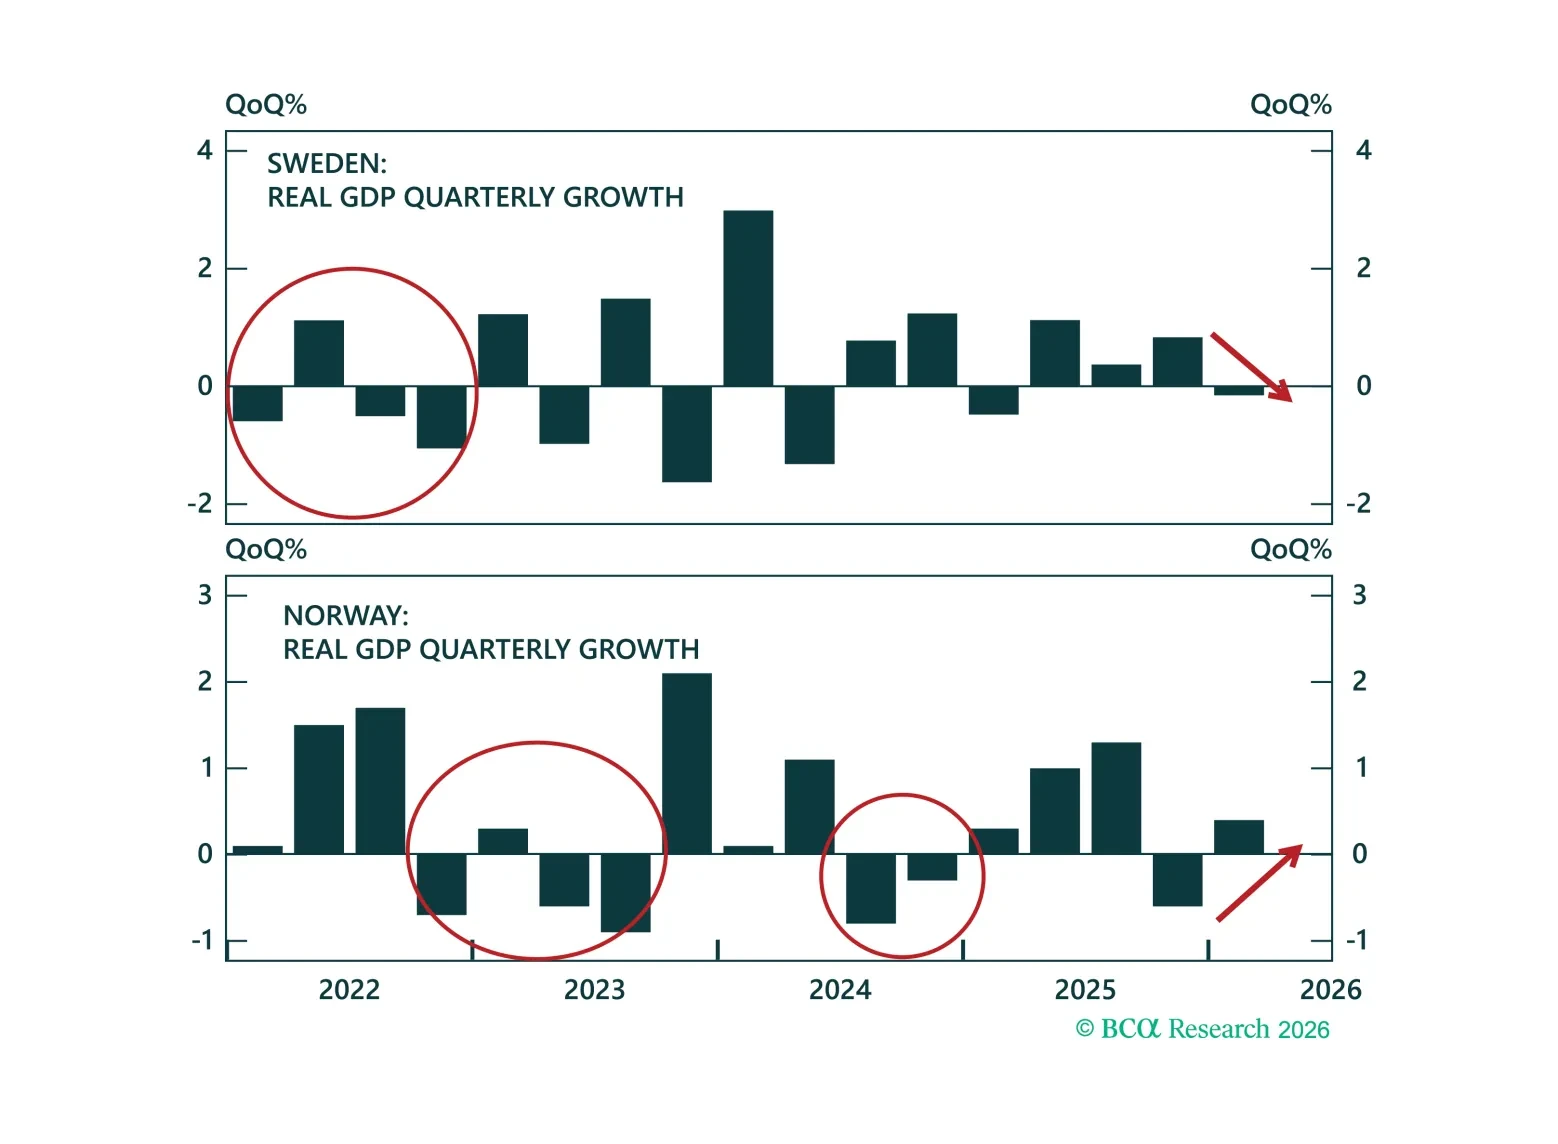
The war in Iran and the energy shock are driving a reversal of Nordic fortunes: Sweden’s recovery is faltering just as Norway receives a welcome energy windfall. Favor Norwegian over Swedish equities and buy NOK/SEK. In rates, fade aggressive Riksbank hike expectations and downgrade Norwegian government bonds to neutral.
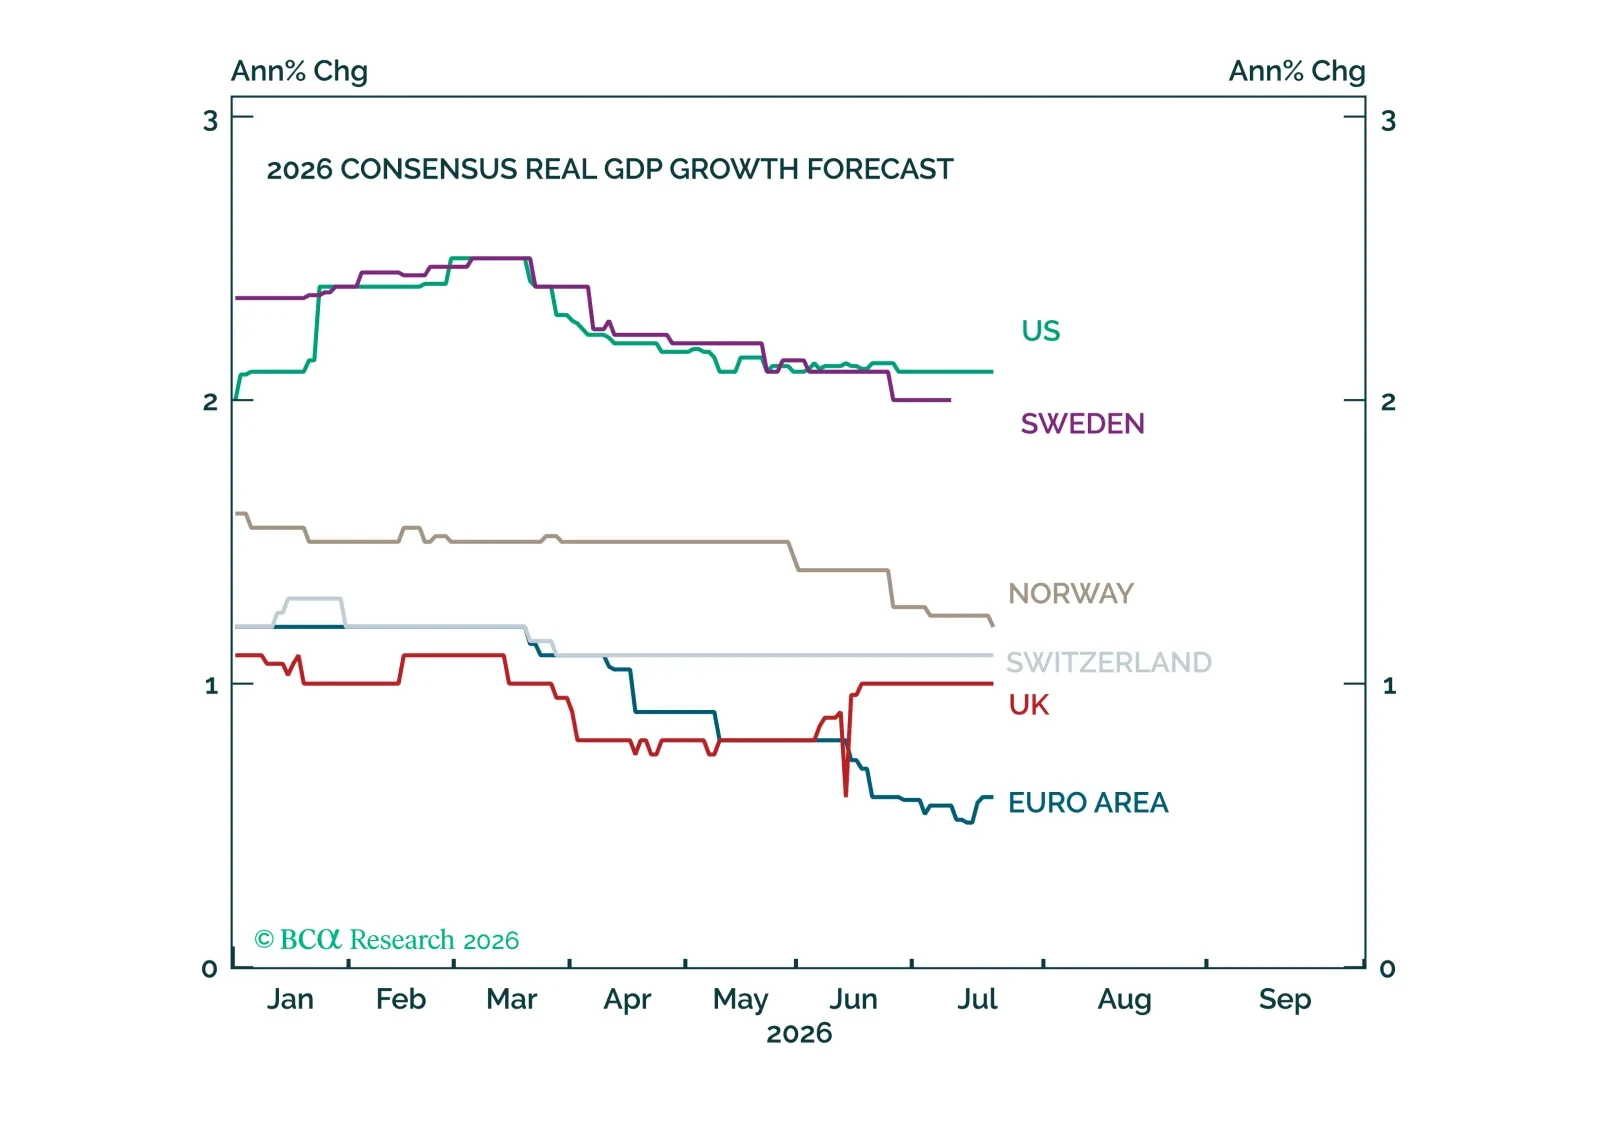
Europe faces a difficult macro backdrop, but whether it slips into recession remains finely balanced. We present two perspectives before translating them into investment implications.
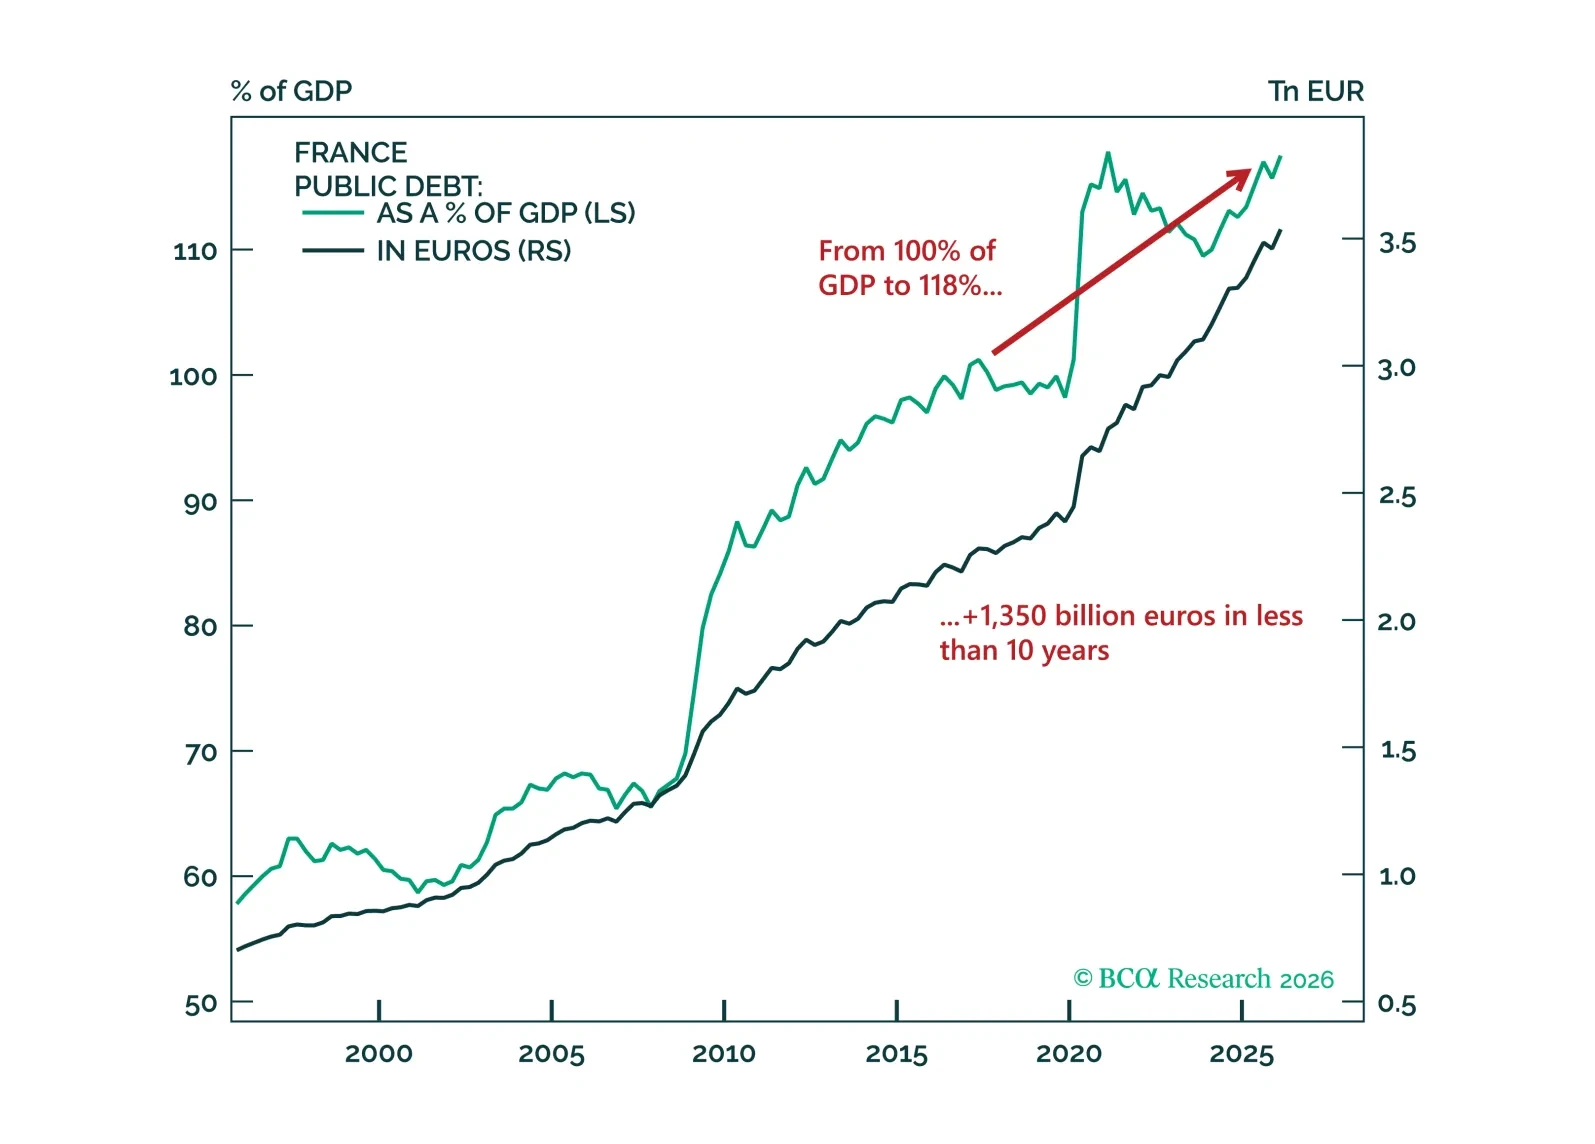
We wish all our French clients Bonne Fête Nationale! The rest of the world knows the holiday by its other name, Bastille Day. It is fitting, therefore, that we publish today GeoMacro Beta report on the coming political earthquake in France.
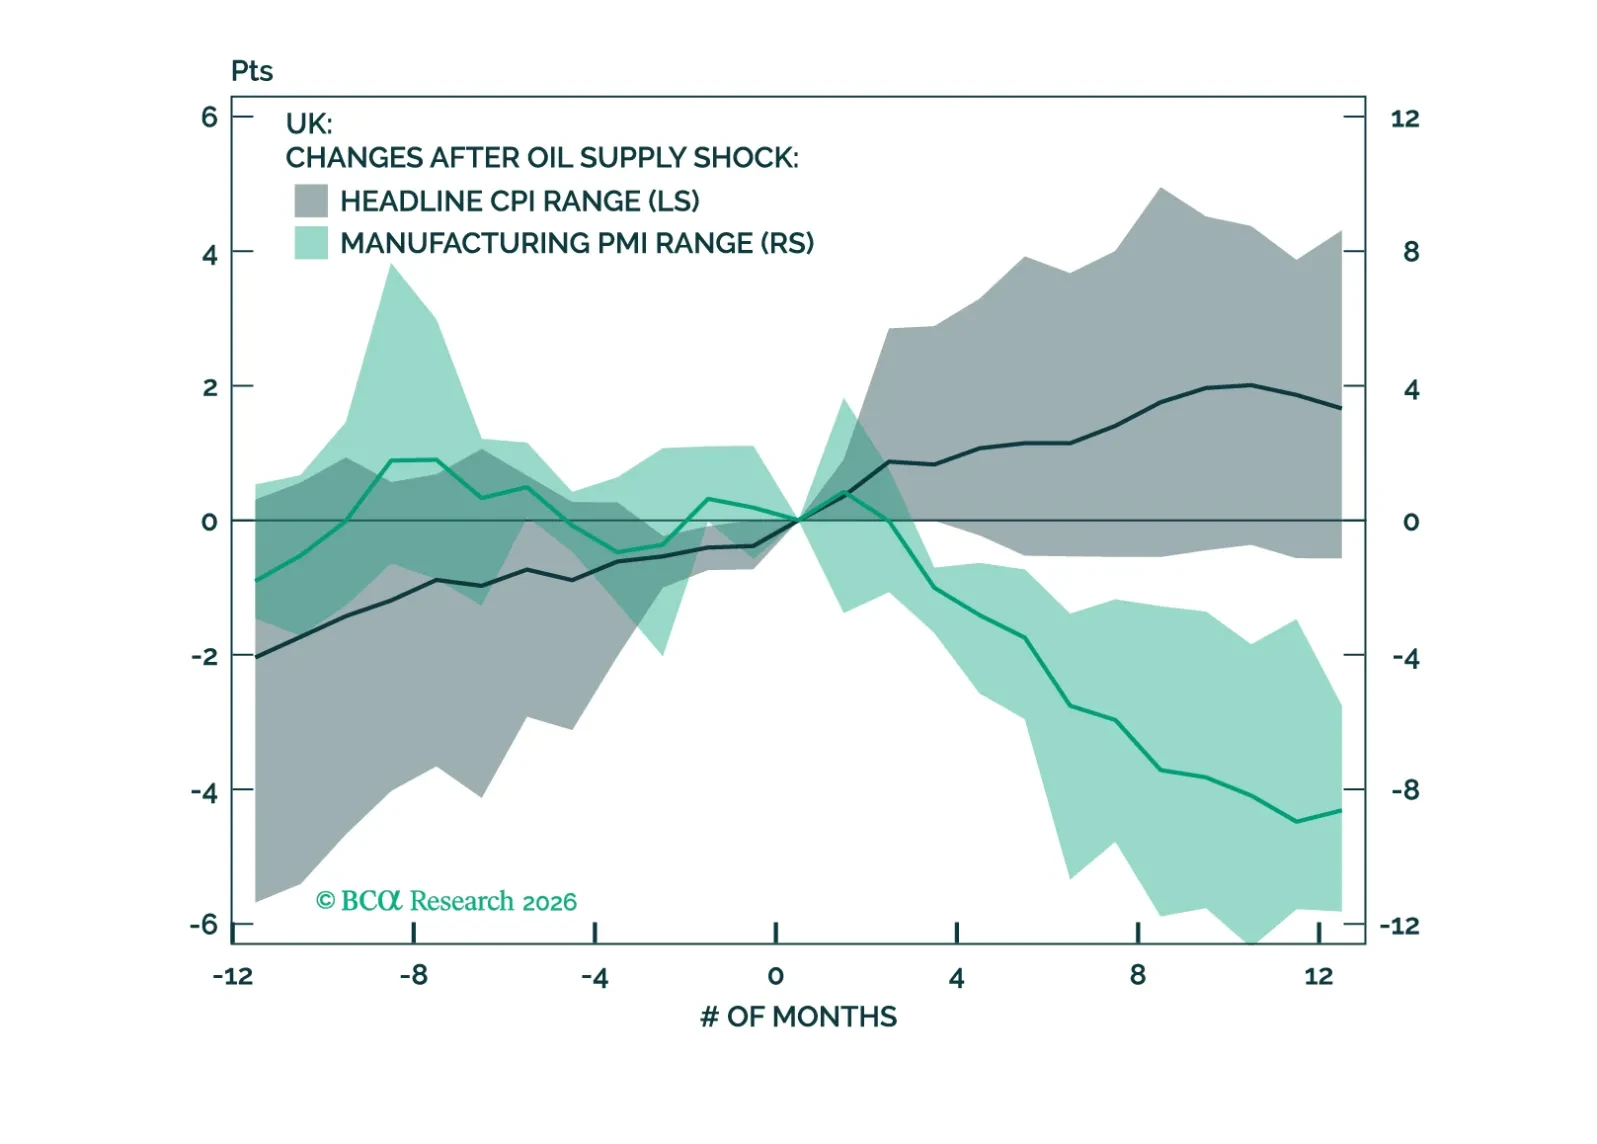
The UK economy is becoming increasingly fragile, but the investment outlook is improving. Slower growth and a more dovish BoE will support gilts, while UK equities will likely benefit from a favorable sector mix and a weaker pound.