 CoreMacro
Find out more
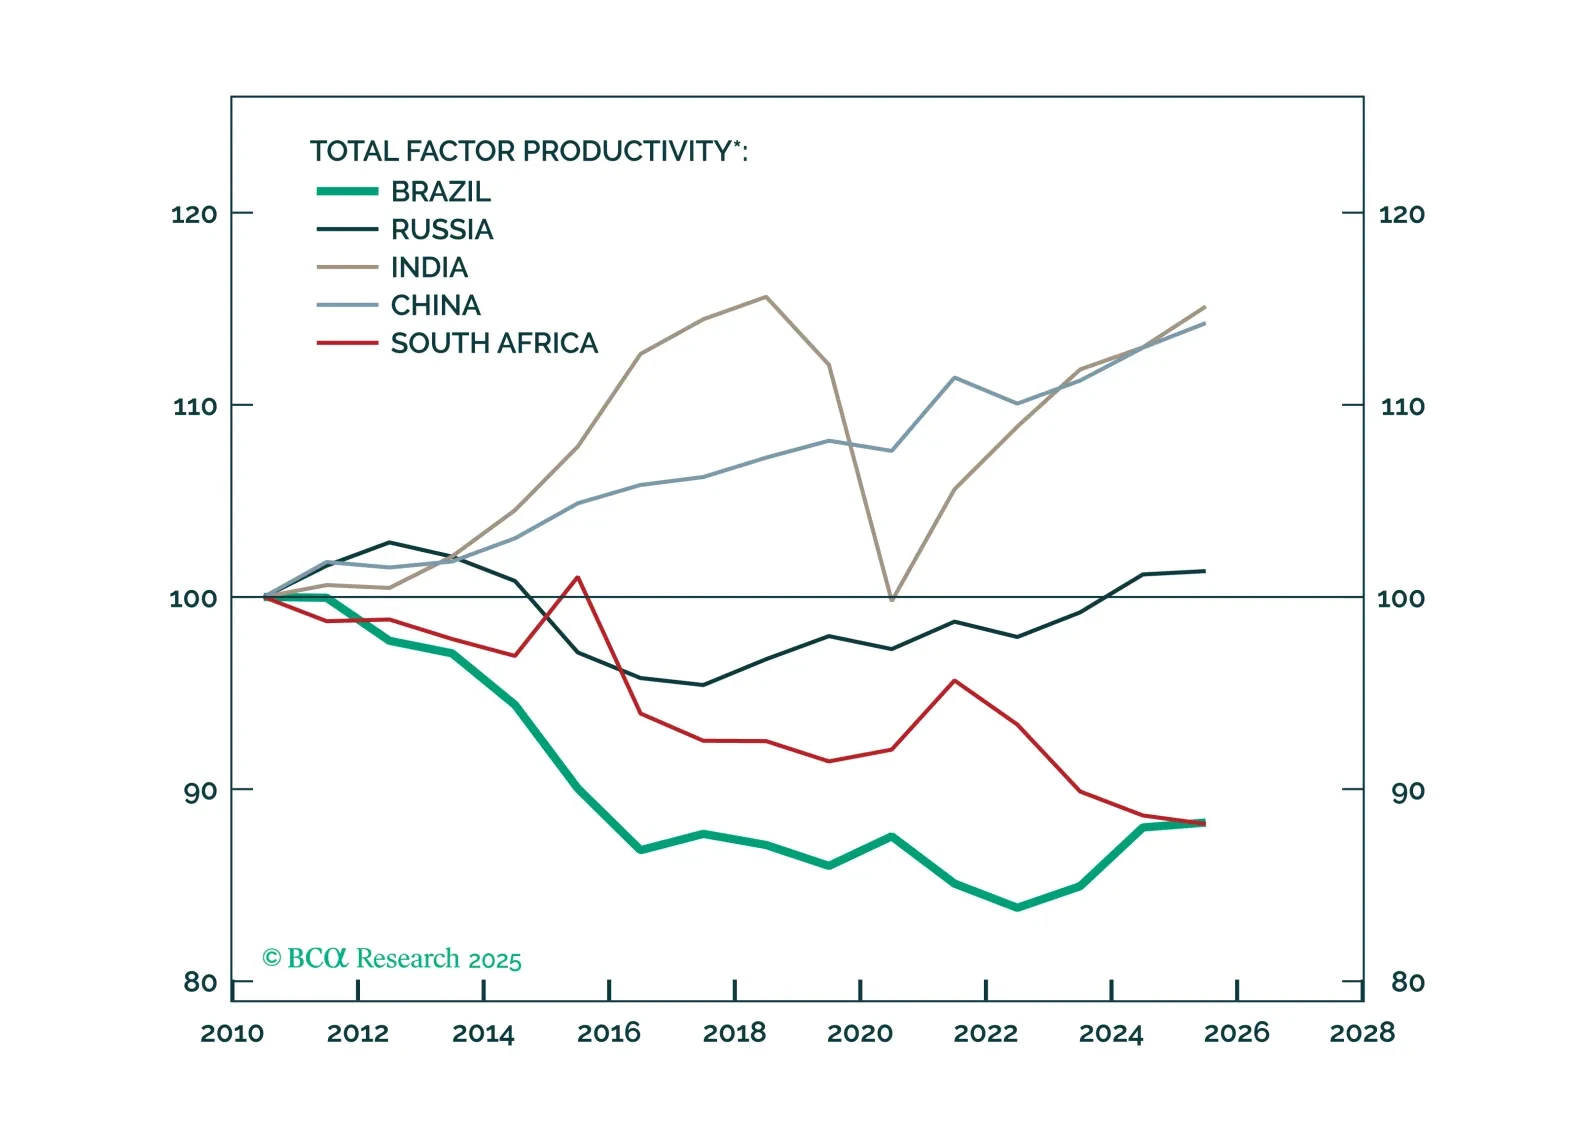
Brazil’s bleak macro outlook persists – rising debt, weak productivity, and political inertia. With 2026 elections looming, genuine reform seems unlikely, though Argentina’s bold turnaround could pressure Brasília to rethink its cycle of governability over growth.
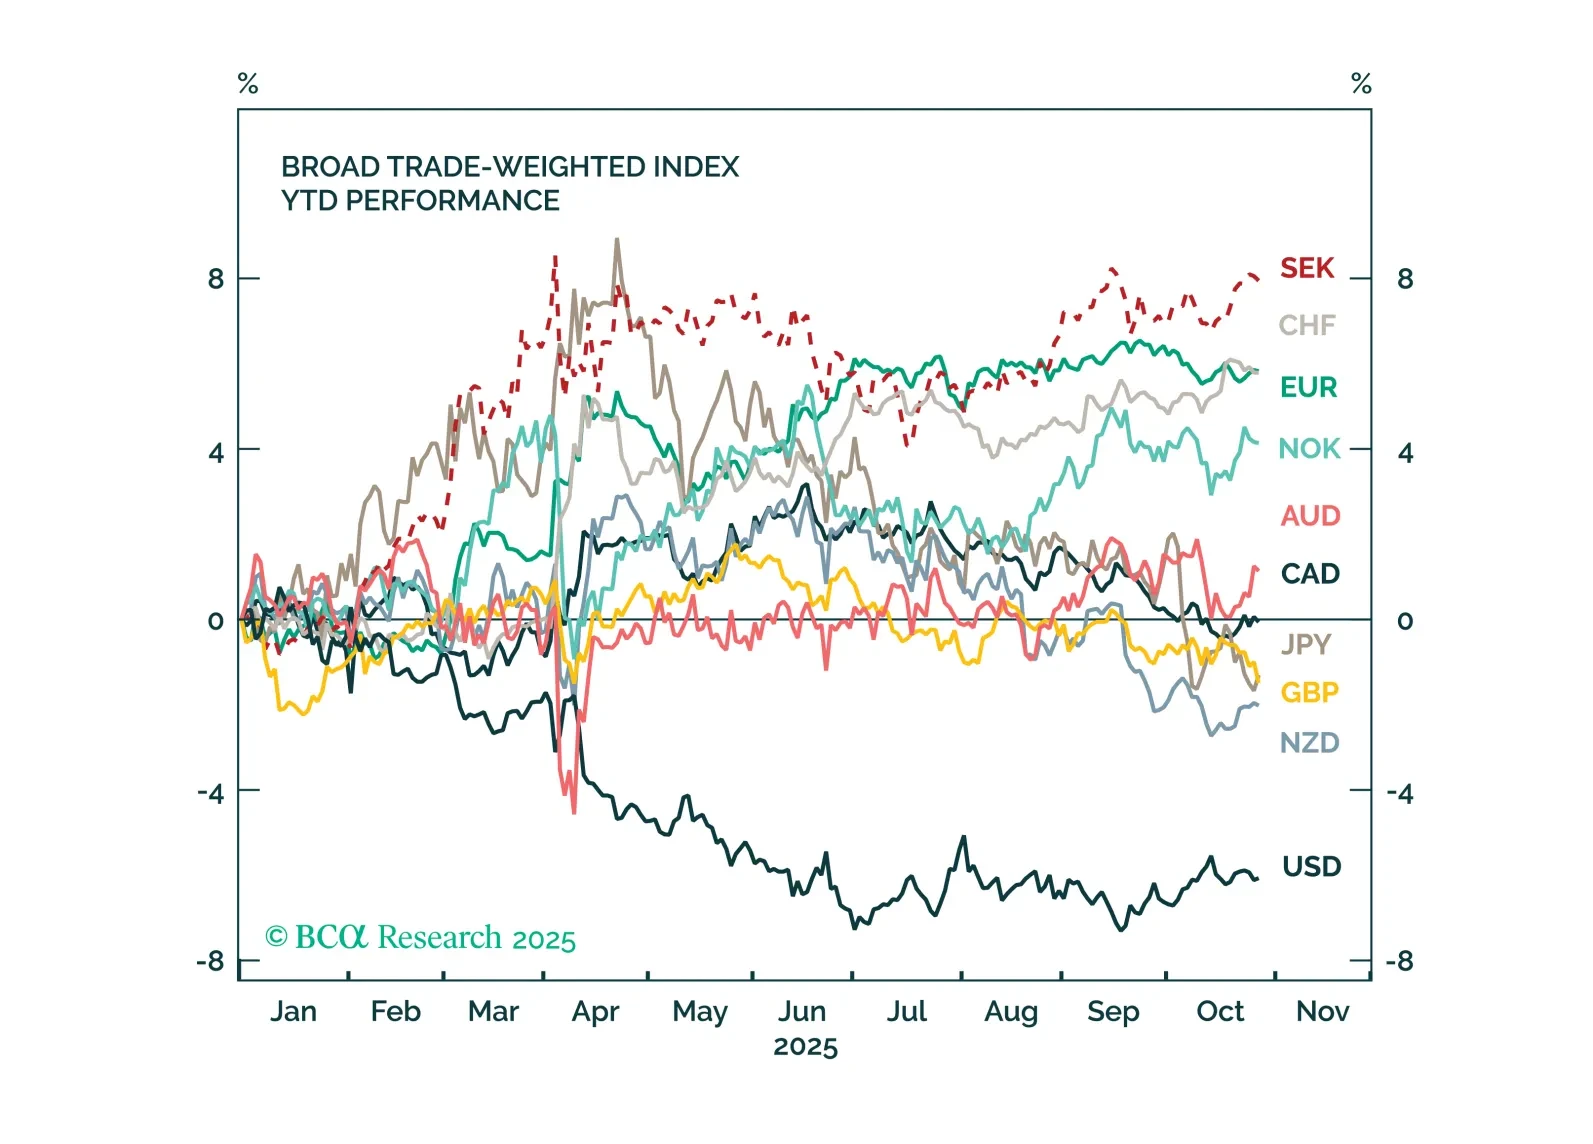
Markets are increasingly pricing an end to the global easing cycle, with many central banks expected to remain on hold. But uncertainty remains high, and policy surprises are likely going into 2026. This Strategy Report breaks down the current drivers behind G10 central bank policies, and how to position for the next moves across FX and fixed income.
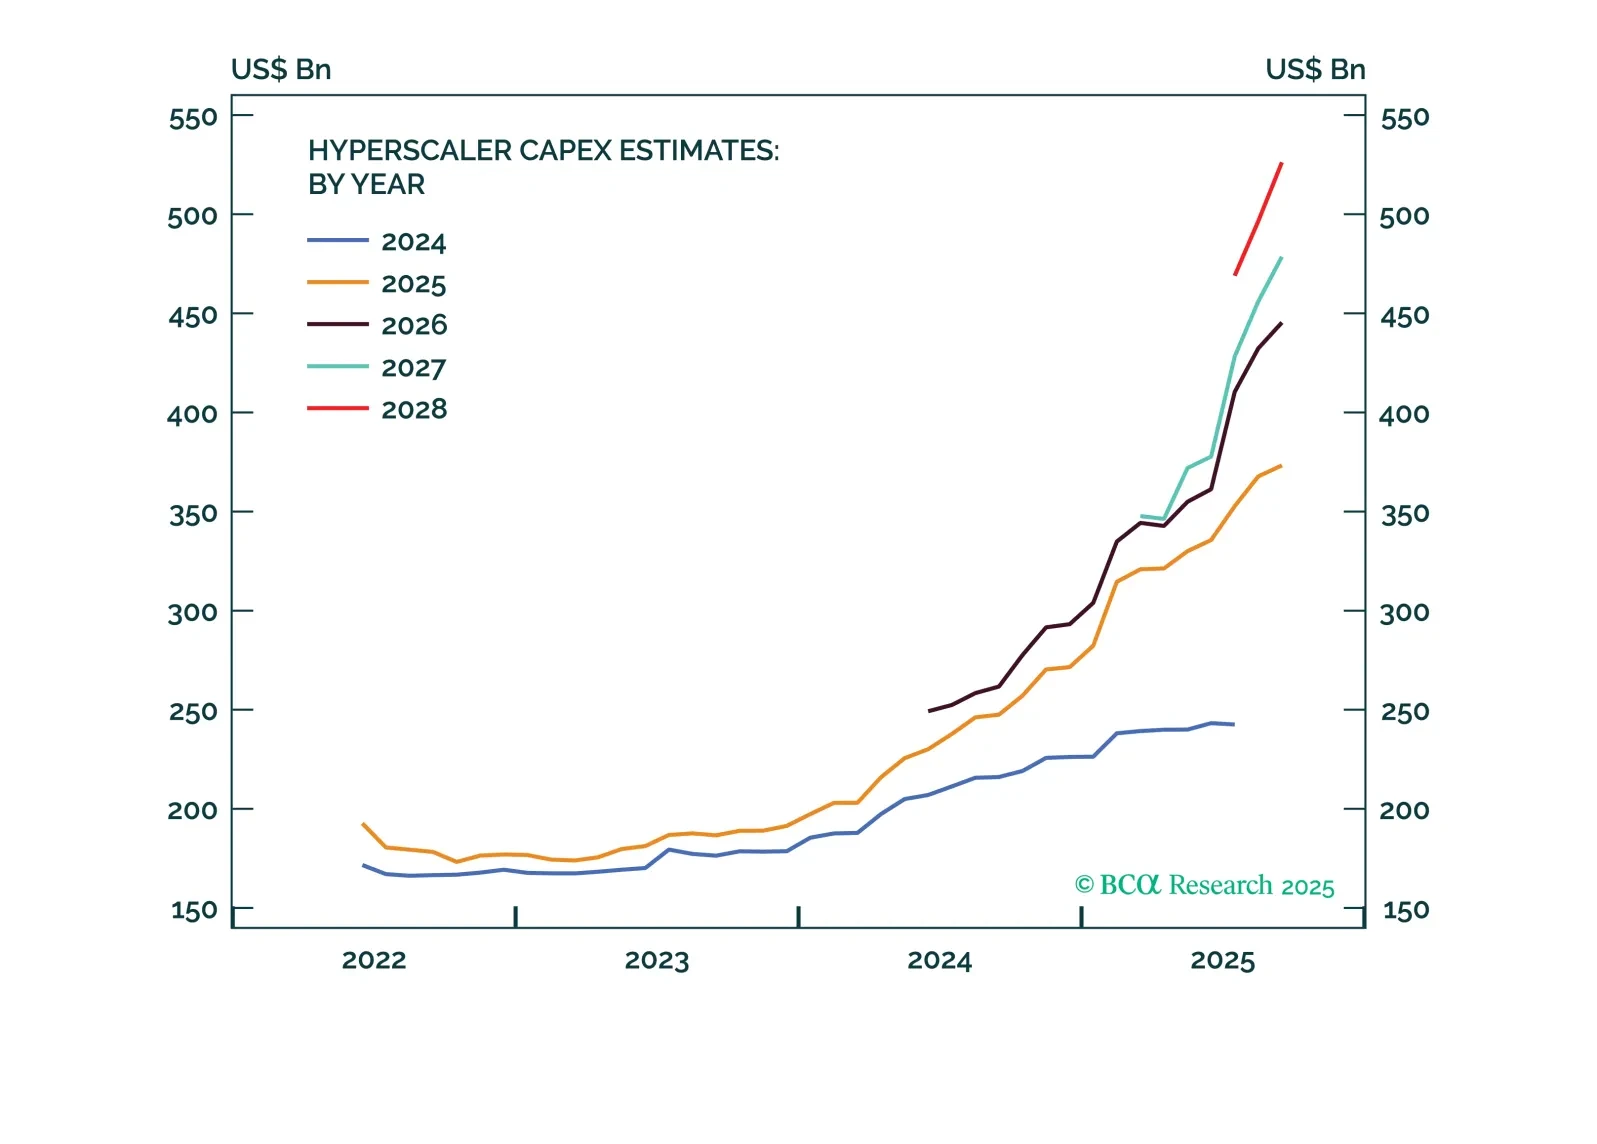
Fresh off a month of boning up on all things AI, we walk through a high-level Q&A discussing AI capex and how much the AI investing boom is really contributing to US growth.
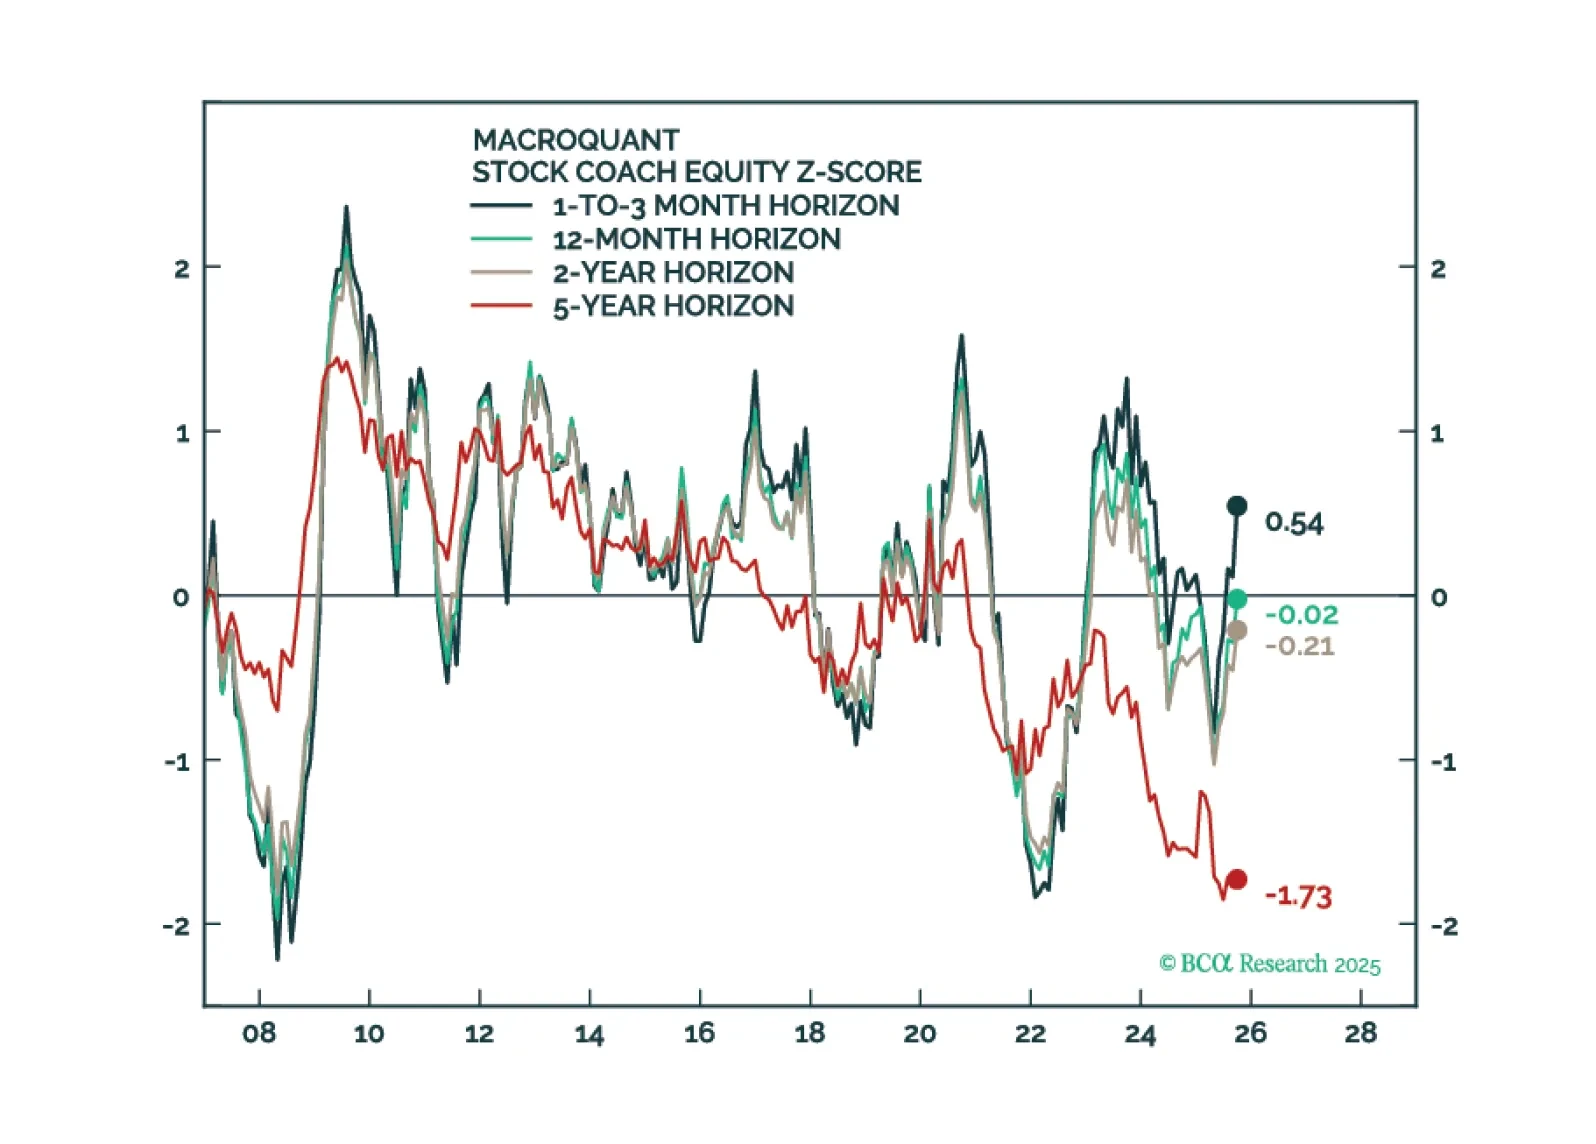
MacroQuant is tactically overweight equities, favors an above-benchmark duration stance in fixed-income portfolios, remains bearish on the US dollar, and is bullish on gold and copper.

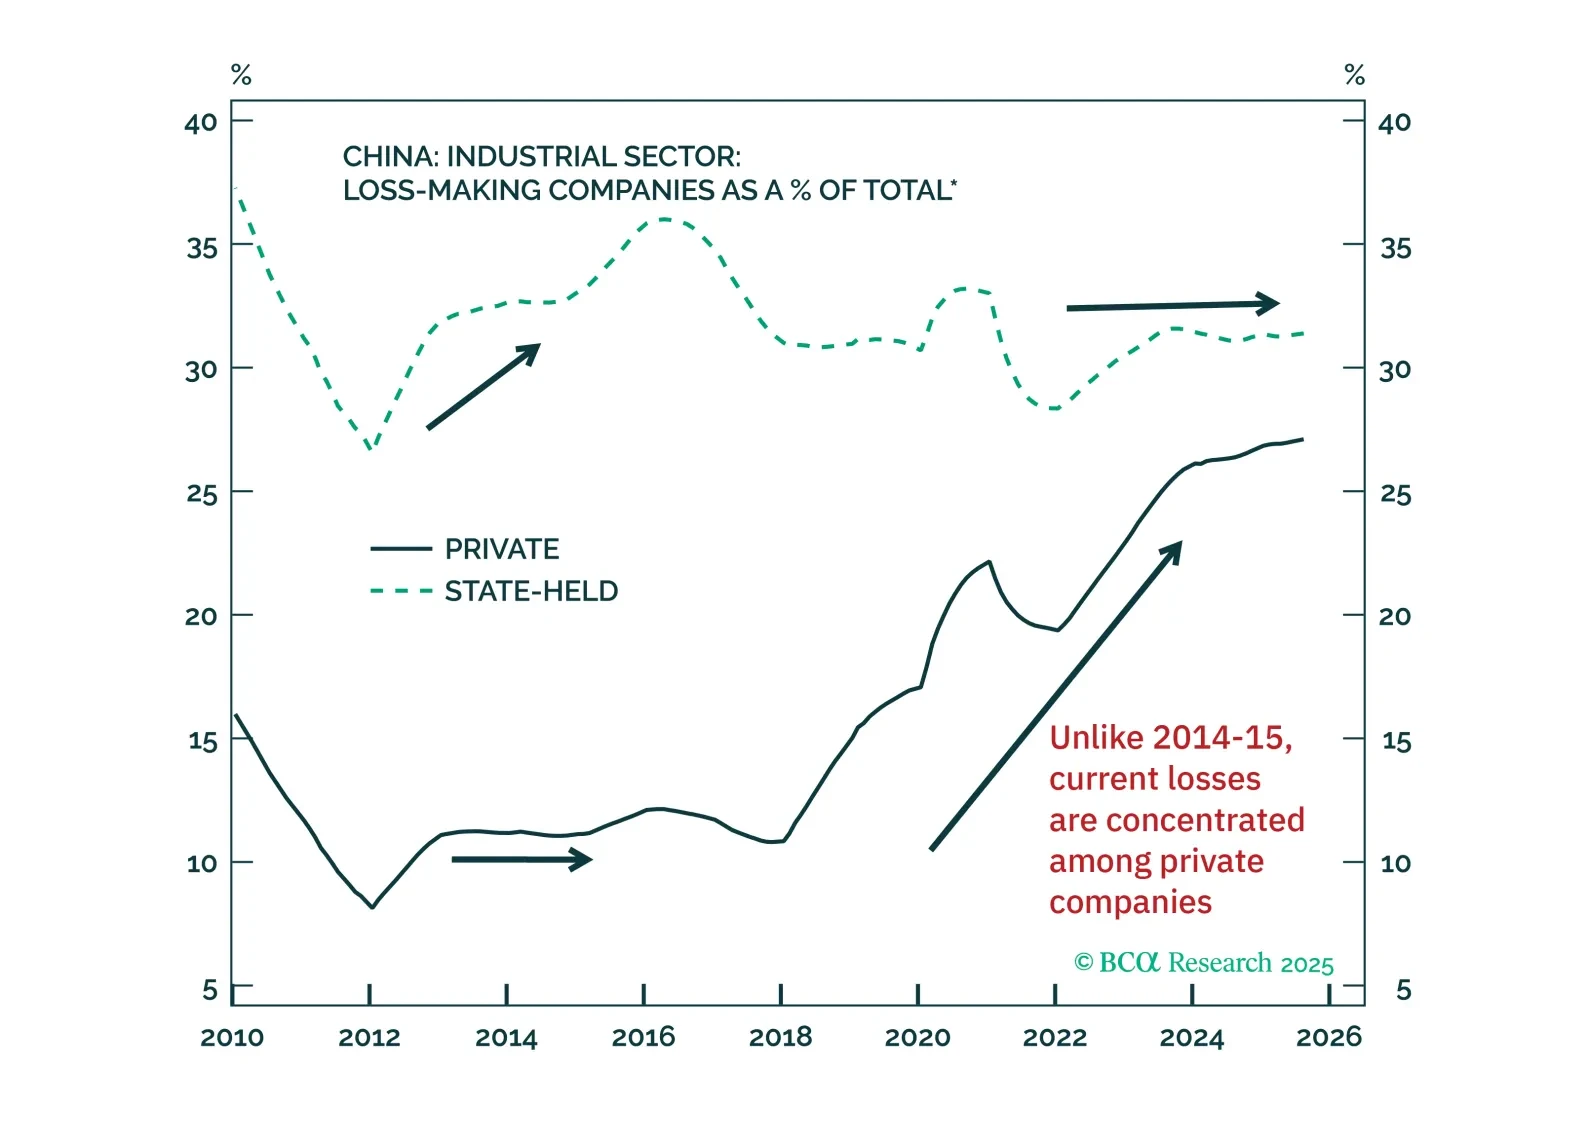
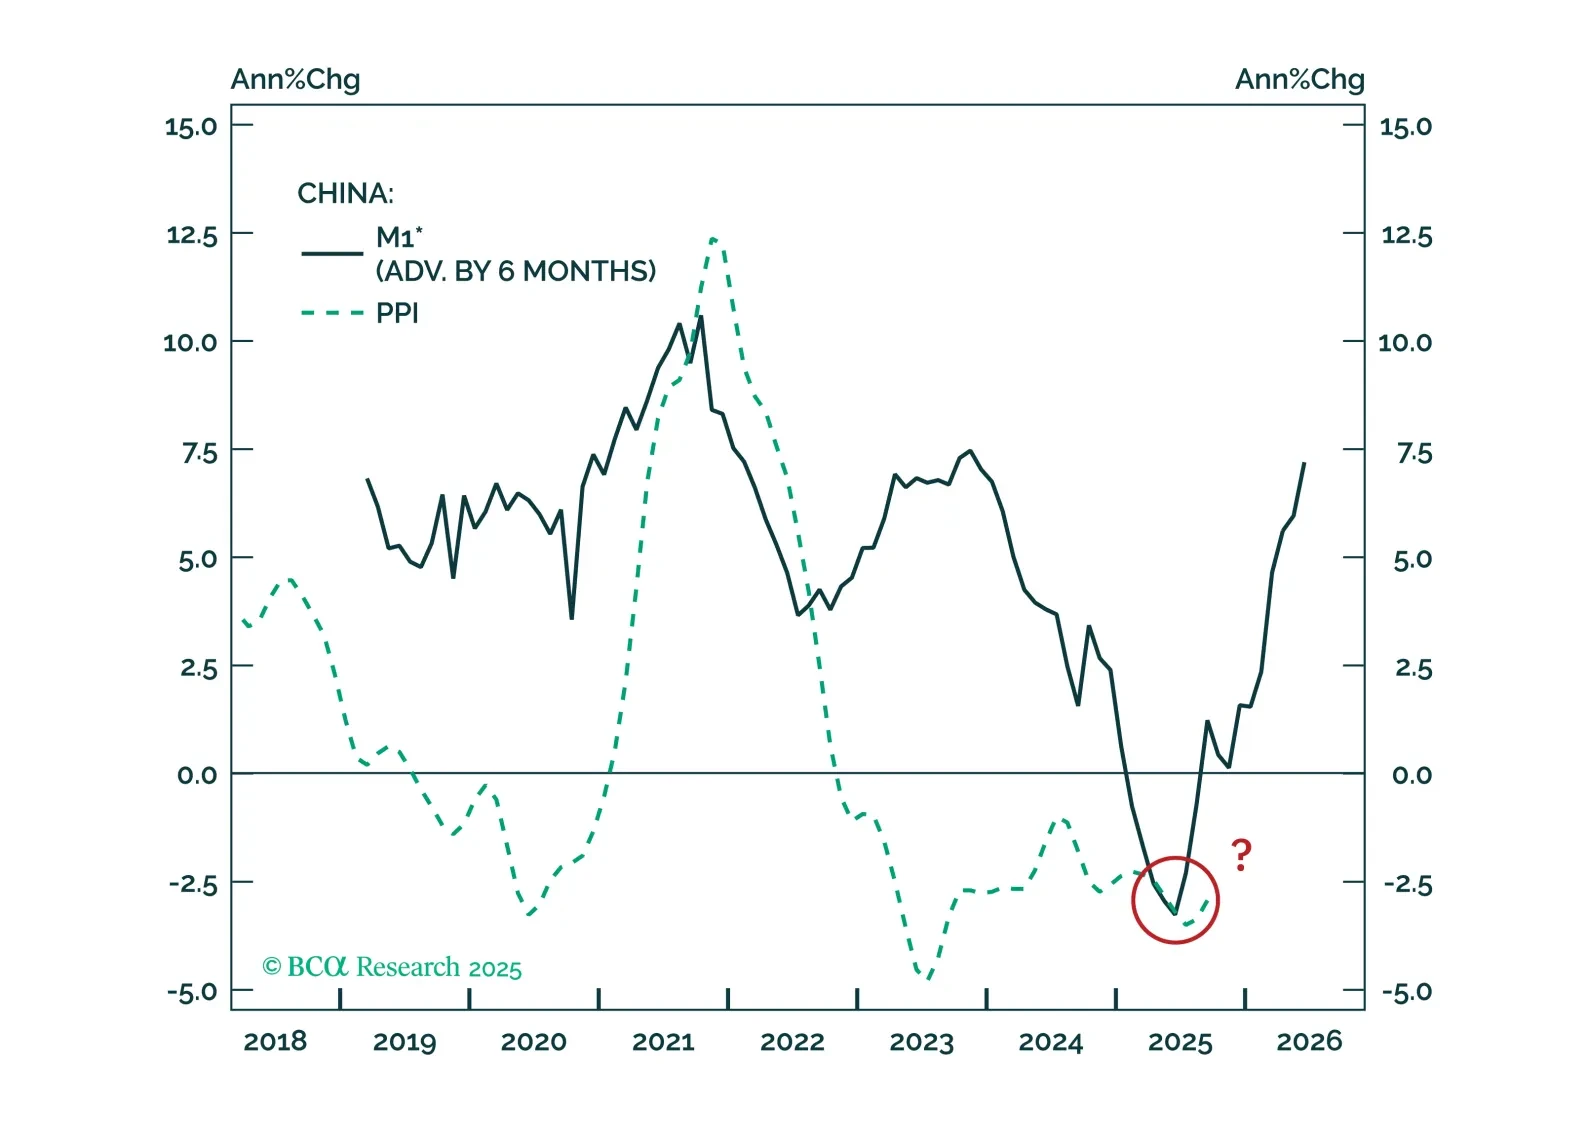
This month’s China High-Frequency Indicator (HFI) Chartbook decodes the conflicting messages in recent economic data, highlights key signals from our HFI, and explains what they mean for China’s economy and markets.
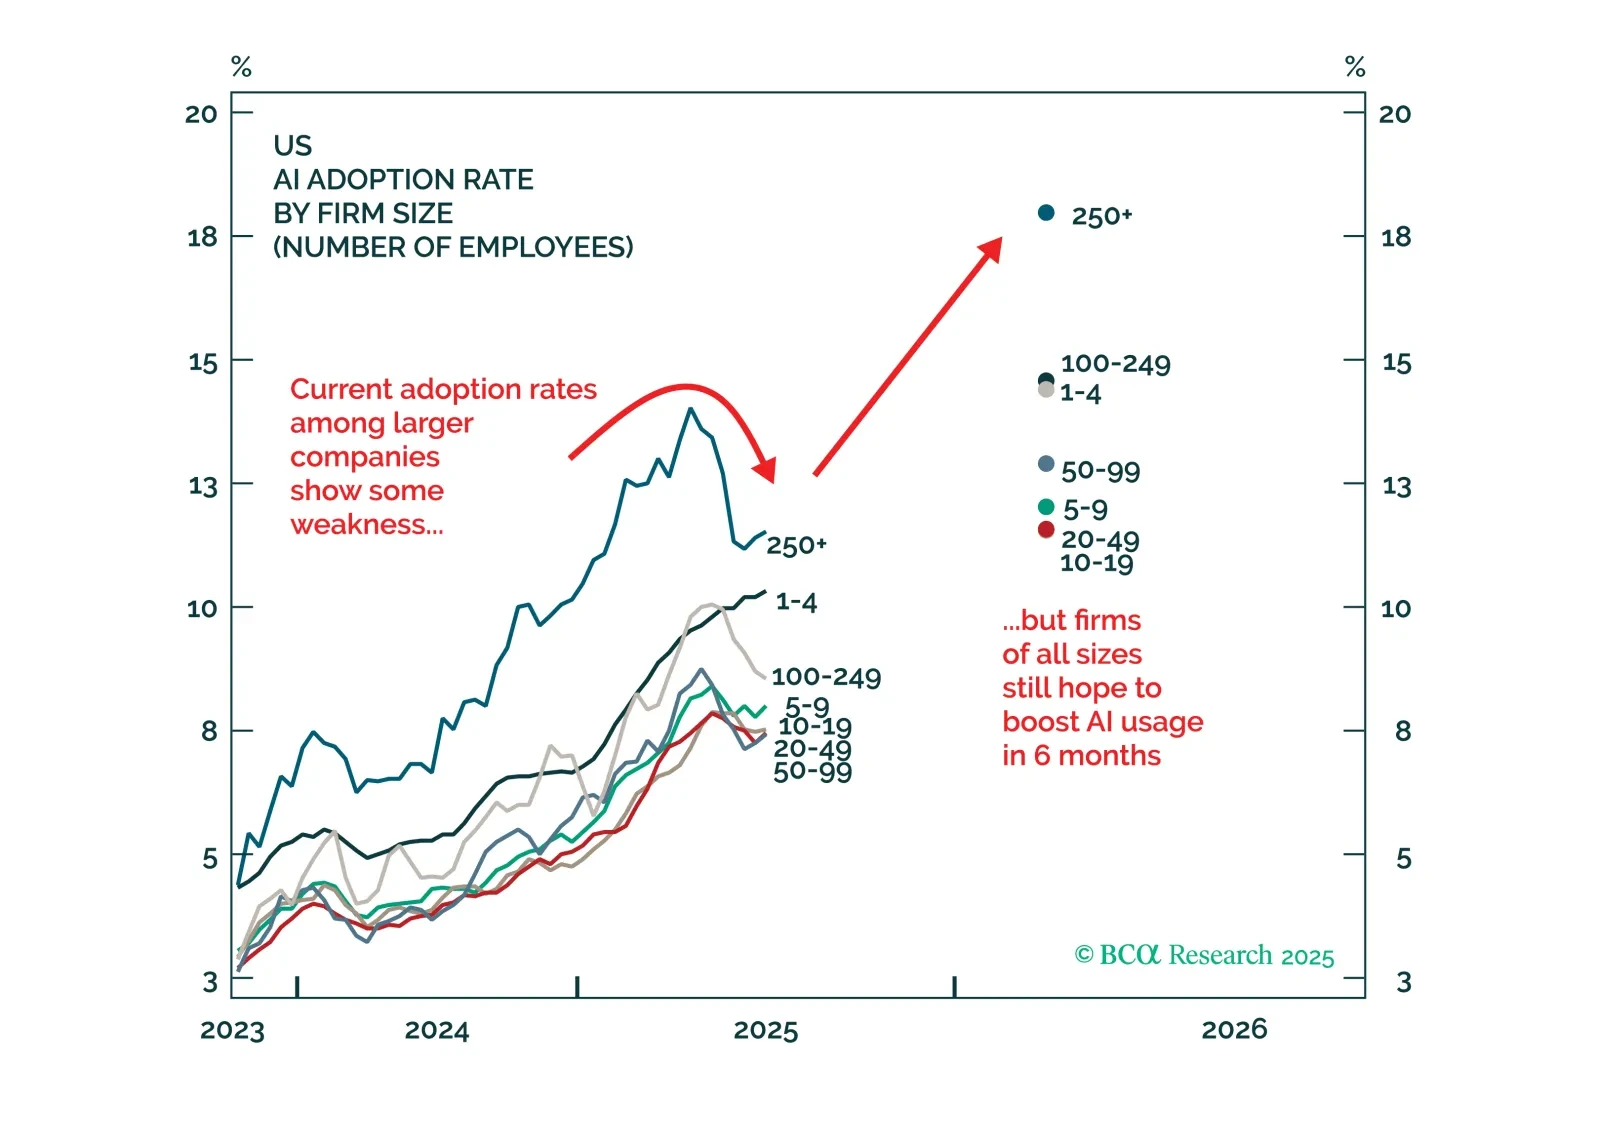
The rush to build AI infrastructure is based on a false premise: that there are significant advantages to being the first to come to market.

President Javier Milei’s electoral win has massively outperformed expectations. Meaningful legislative support and renewed market confidence will revitalize his liberalizing economic program. Our recommendation not to sell Argentine assets following the post-Buenos Aires election carnage has been validated.
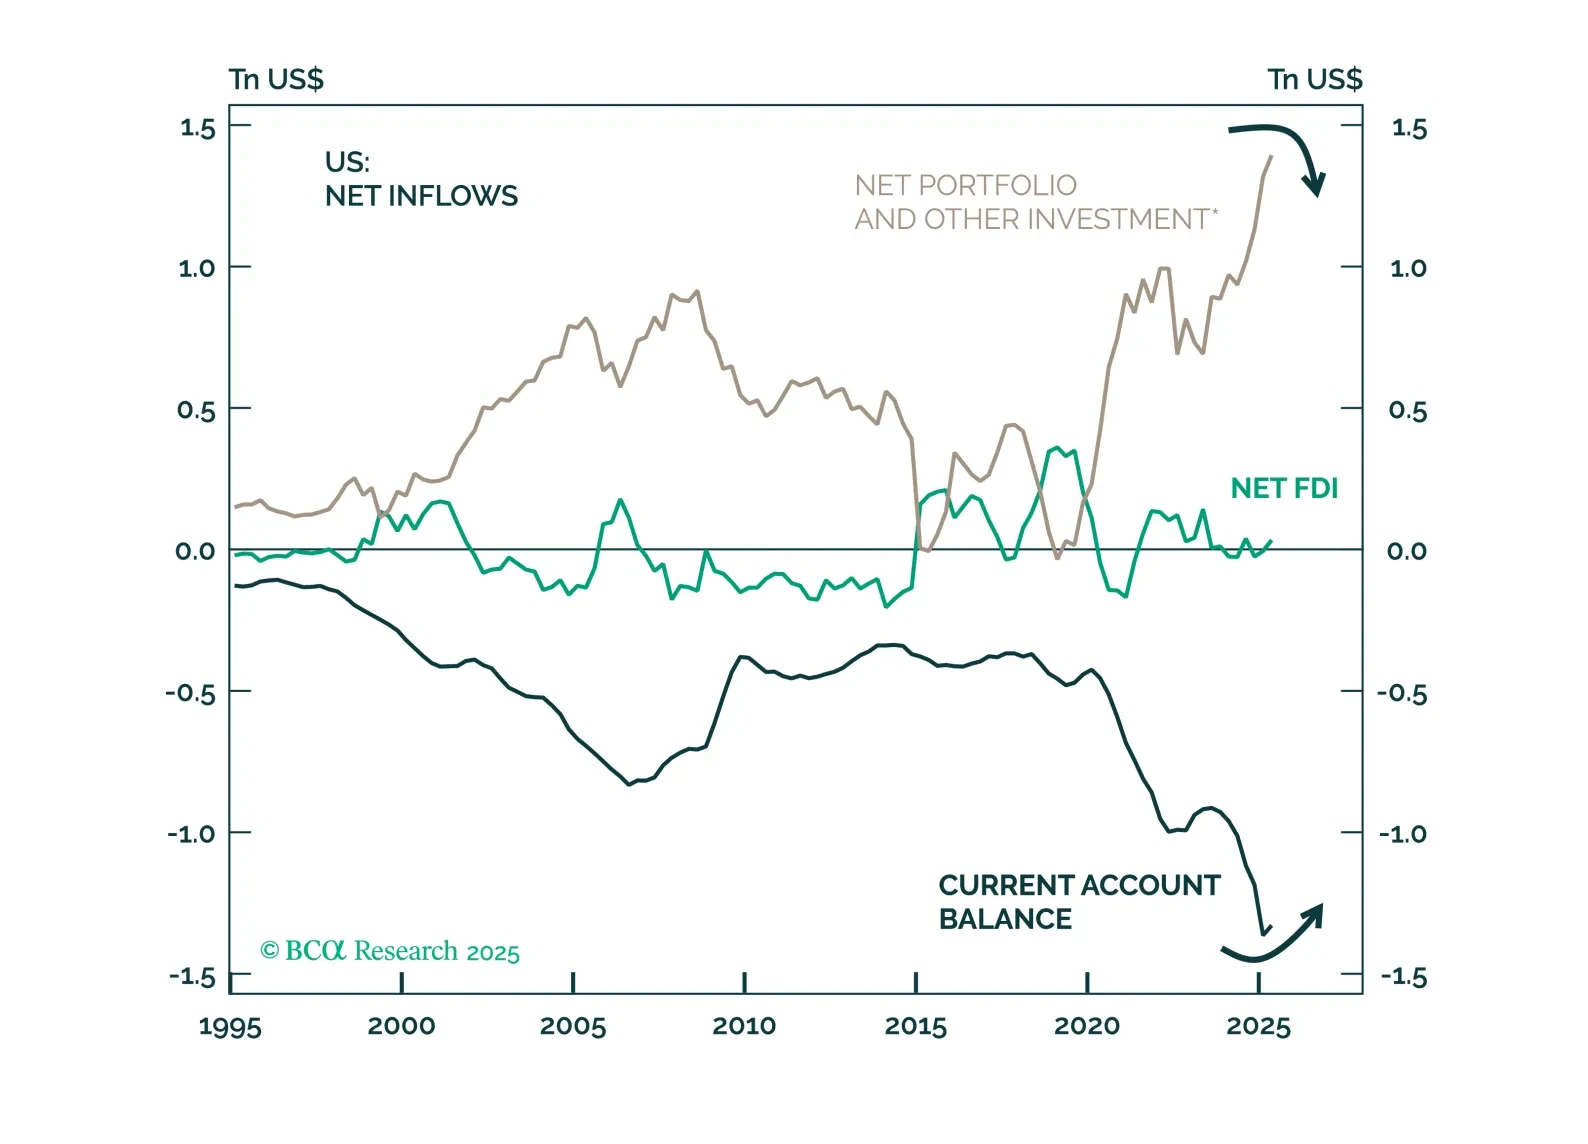
In this week’s note, we share the main implications for European investors from what was discussed at the BCA Conference in New York and provide a short list of the questions most frequently asked by investors we met recently in Lisbon, Madrid, and Barcelona.