 CoreMacro
Find out more
We still believe a recession looms, but it has yet to rear its ugly head. We continue to recommend investors position defensively, but we will change tack if clear signs of a recession don’t emerge soon.
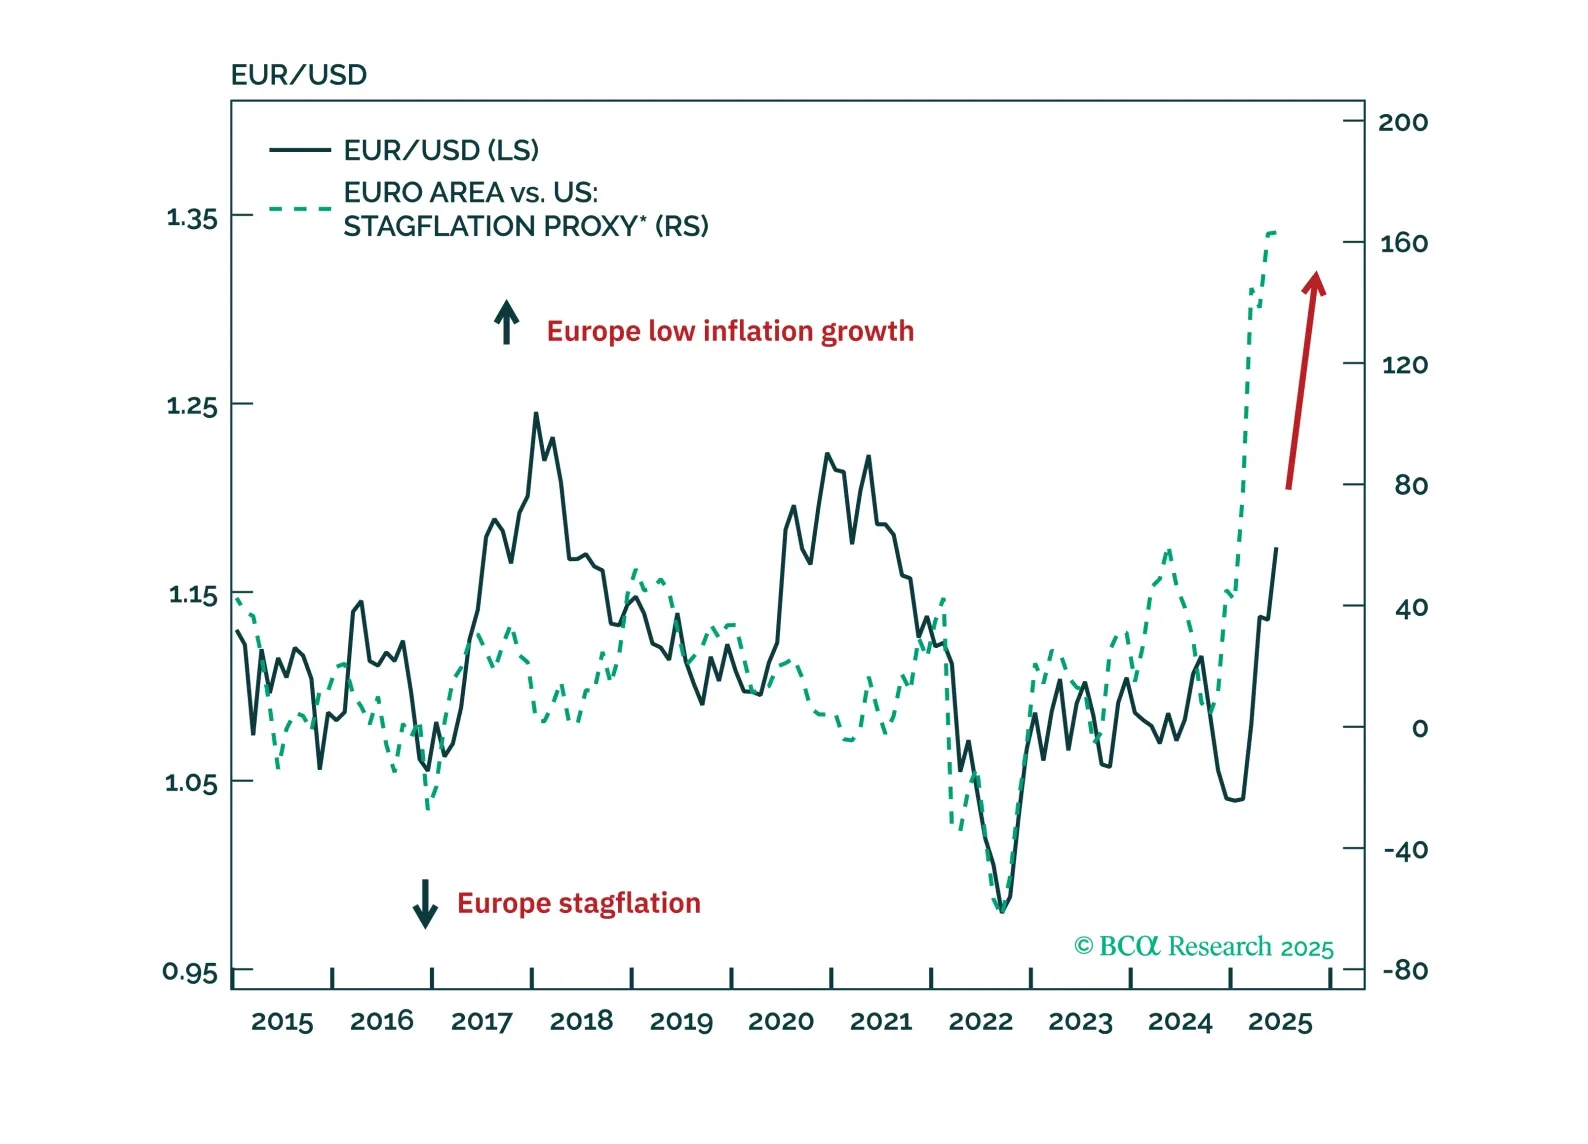
EUR/USD is in a multi-year bull market. A short-term pause is likely, but the longer-term trend remains higher toward 1.25, and eventually 1.40.
We will abandon our recession call if US economic data show clear signs of stabilization over the summer months. For now, that has not happened. Maintain a modest underweight to stocks but look to get more defensive if MacroQuant’s equity z-score falls below -1.
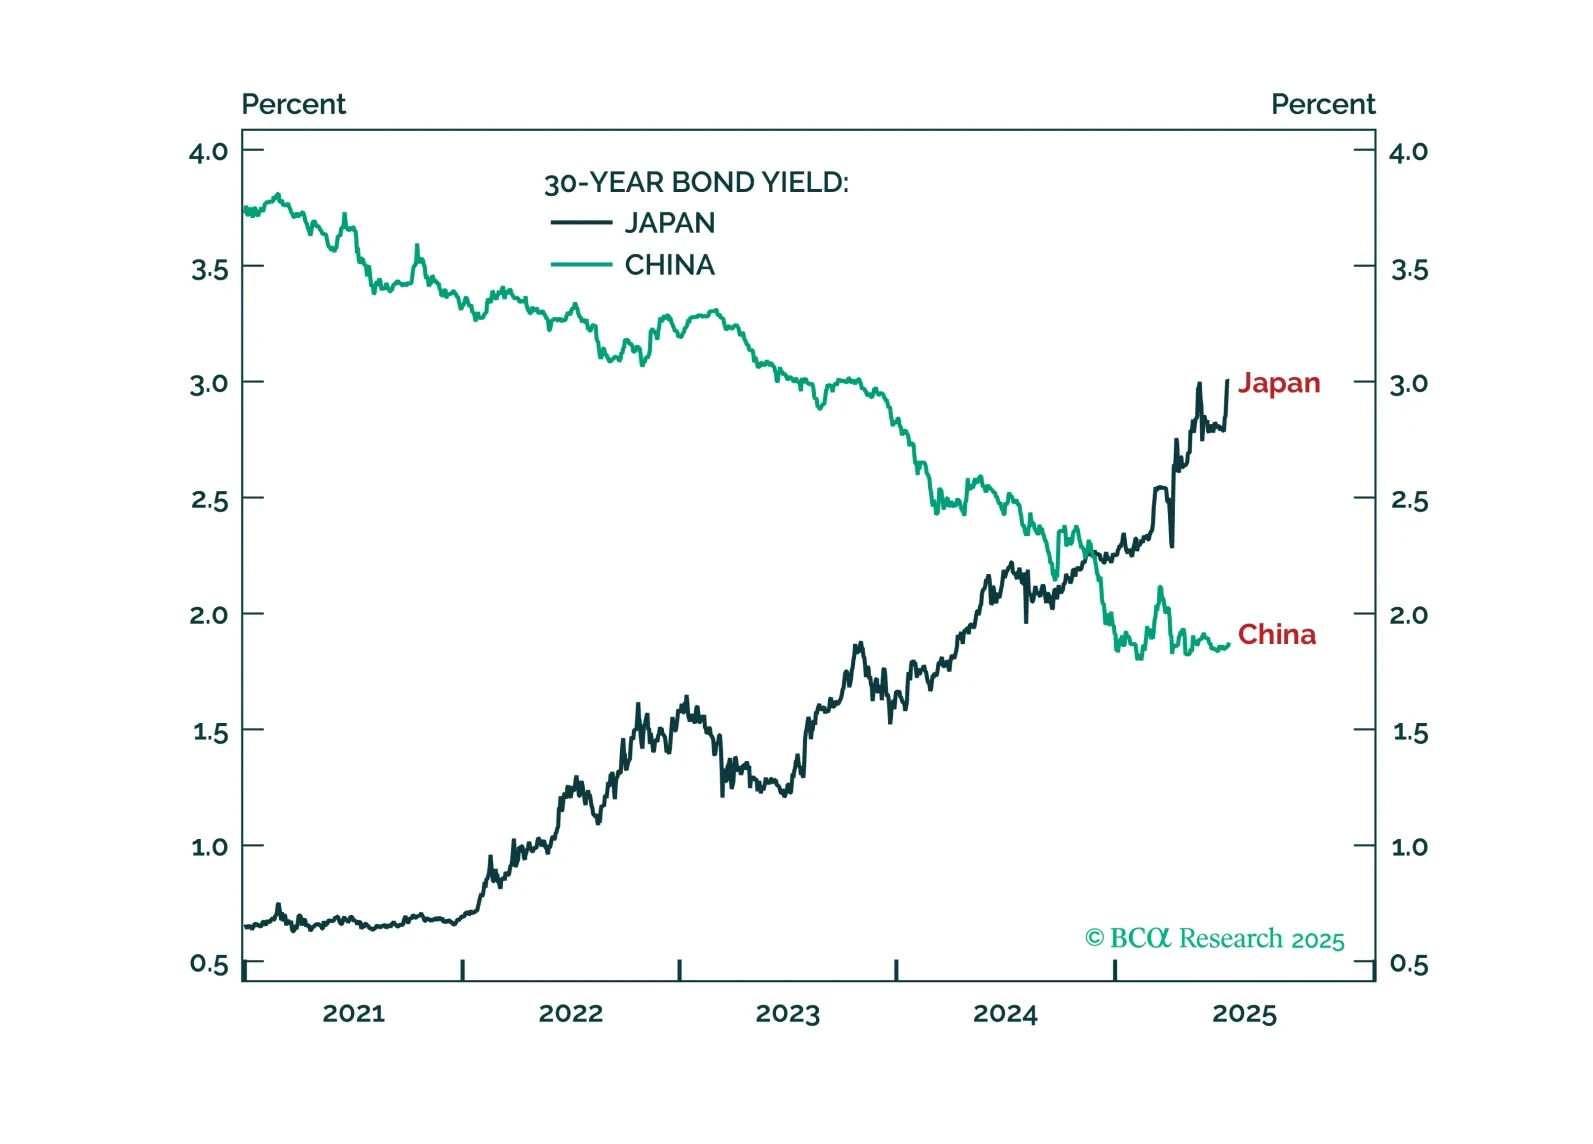
Upward pressure on Japan’s real bond yield justifies overweighting the yen and underweighting overvalued tech. Plus: two new tactical trades are long JPY/EUR and short platinum.
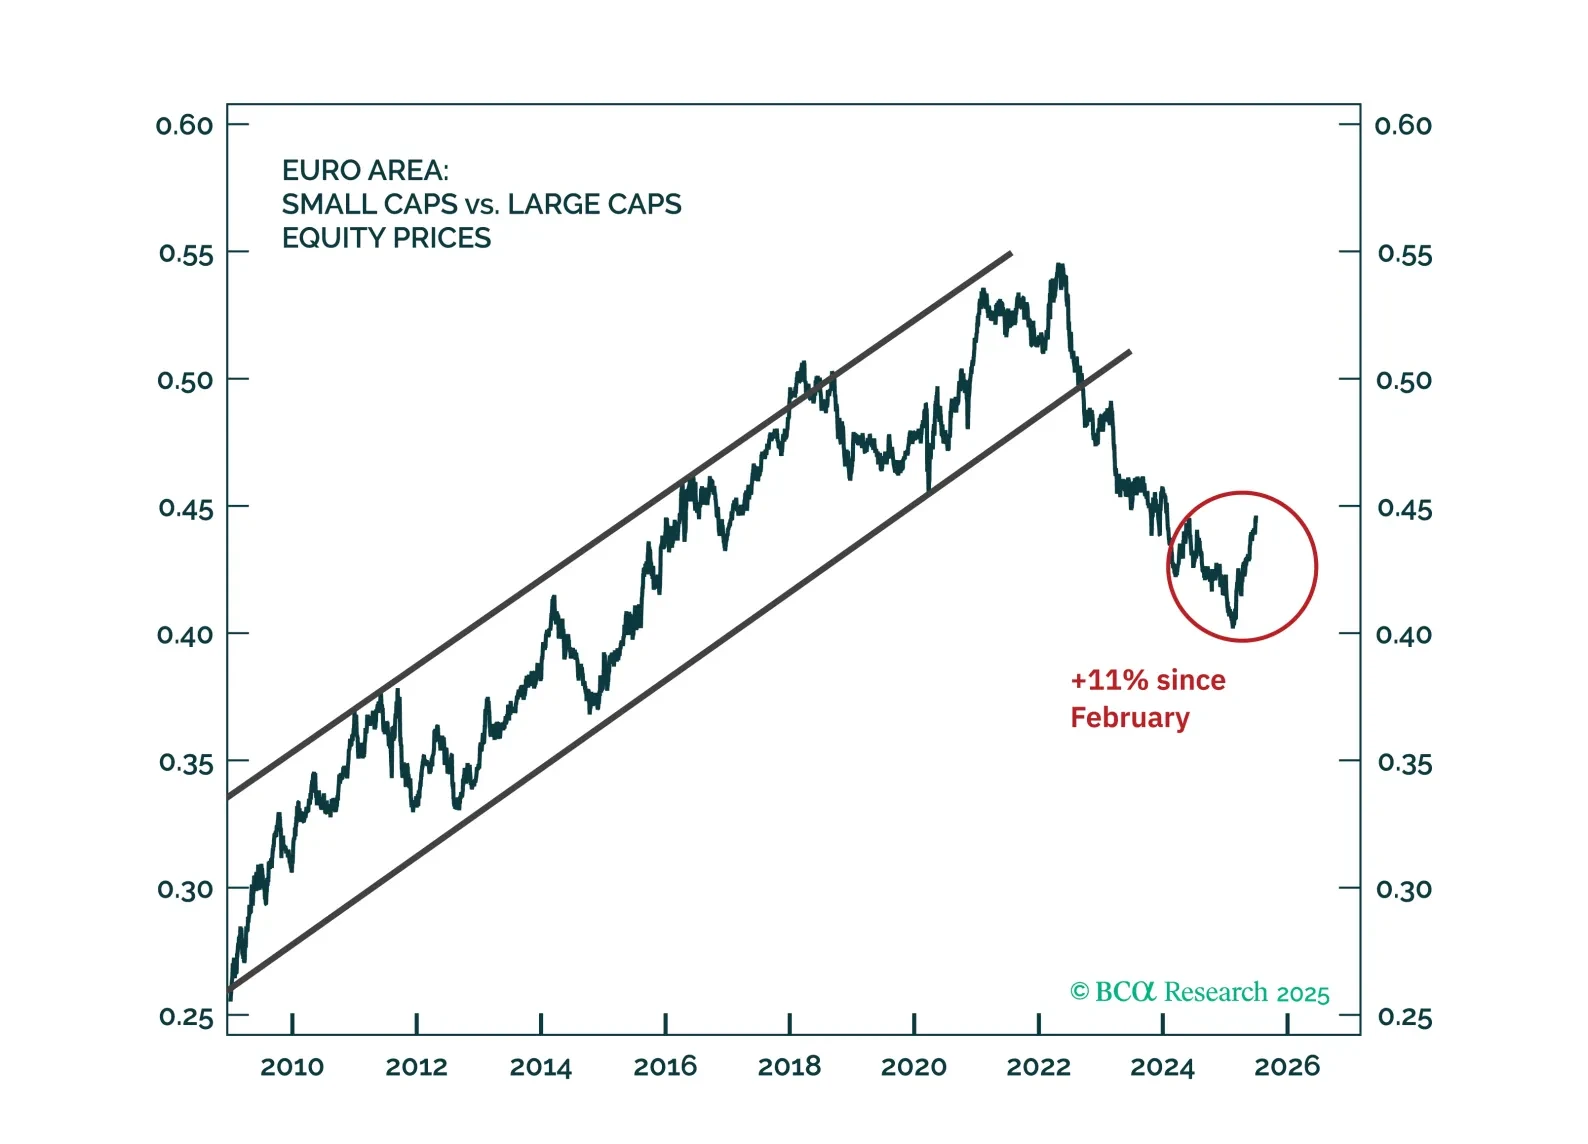
We upgrade European small caps to maximum overweight and double down on our existing recommendation to go long European small caps relative to US ones.
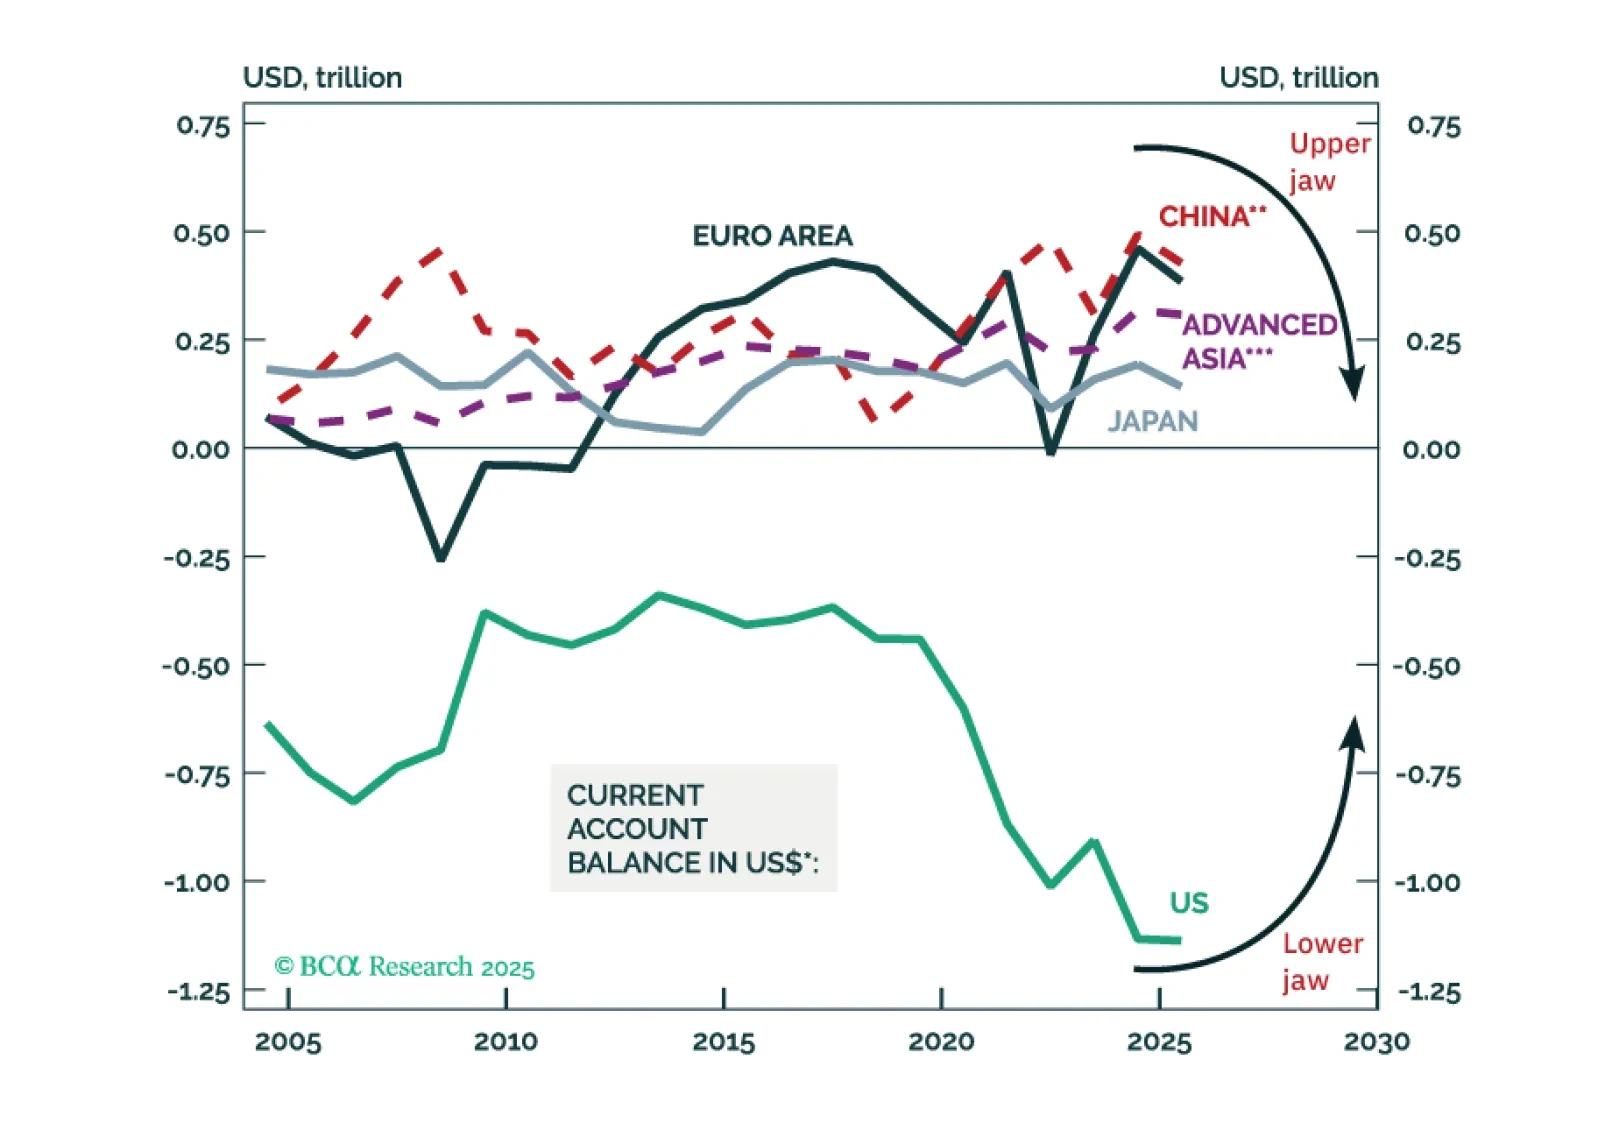
Alligator Bite #1: As US net portfolio inflows decline (the alligator's upper jaw closes), its current account deficit must narrow (the lower jaw will also shut). Alligator Bite #2: As the US current account deficit shrinks (the lower jaw closes), current account surpluses in the rest of the world will narrow (the upper jaw will come down).
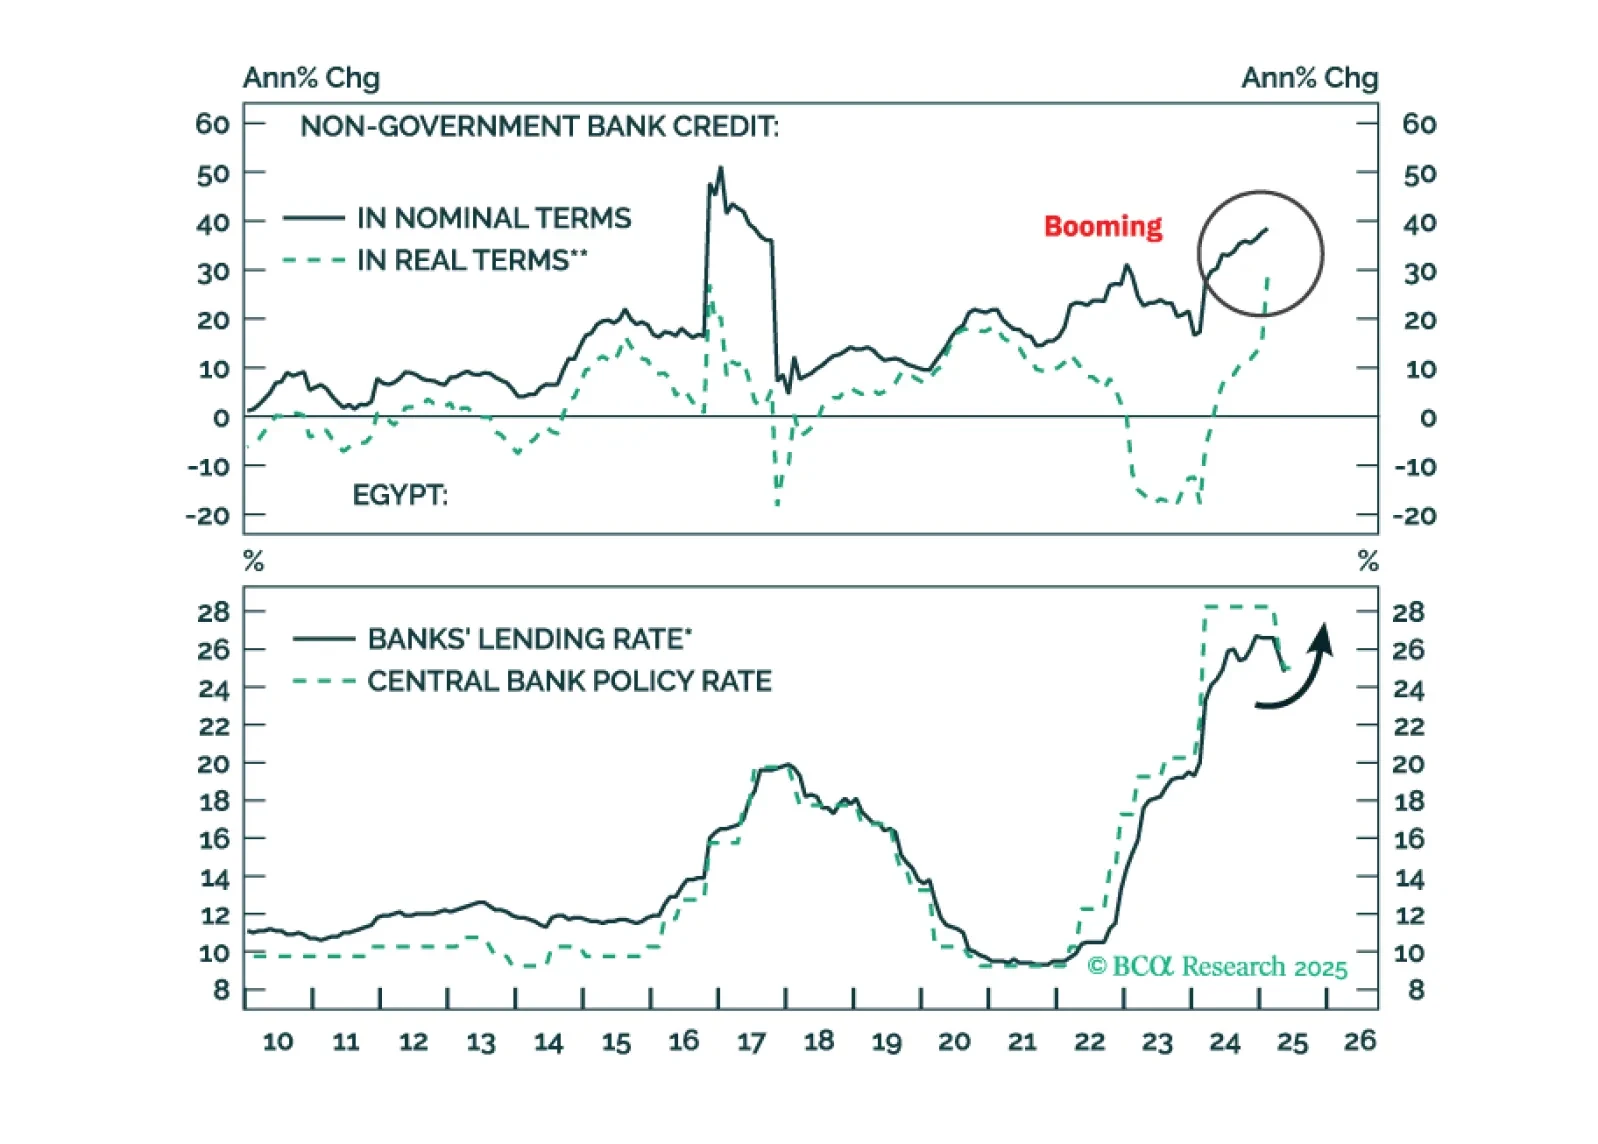
Downward pressure on the pound will rise in the coming months. Inflation will go up, so will bond yields. It’s time to book profits on Egyptian domestic bonds.
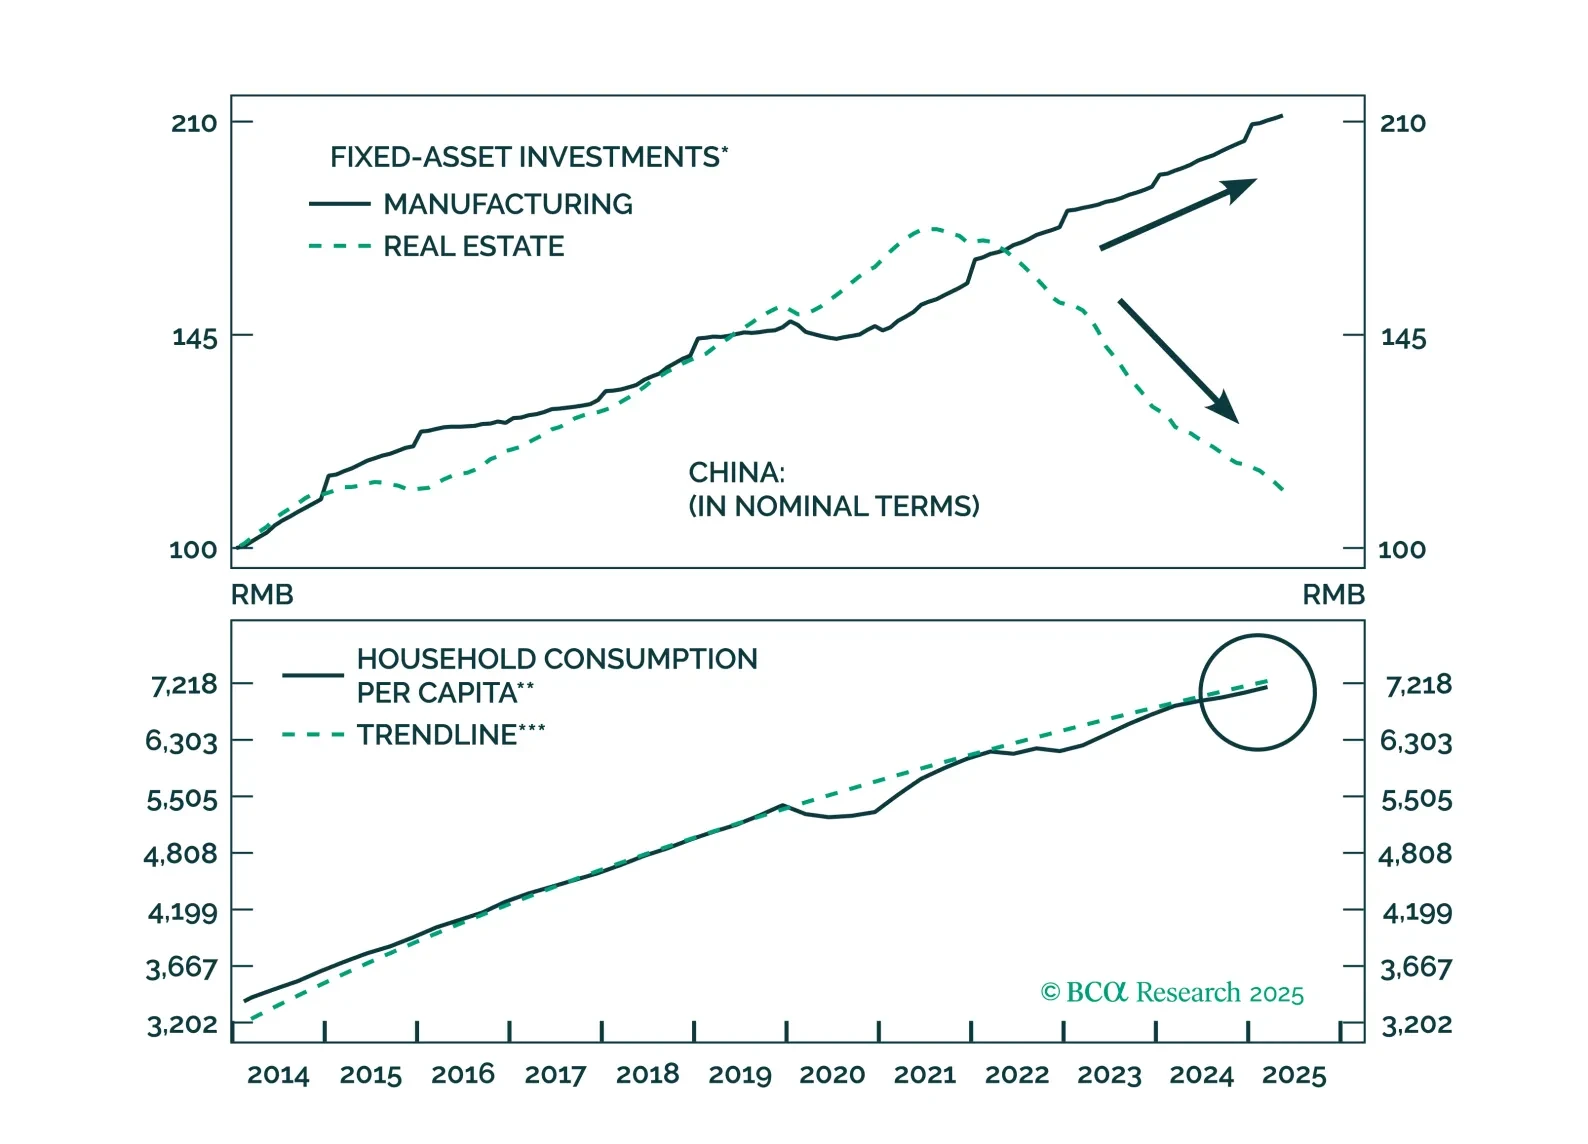
This report analyzes China’s persistent deflation, which is rooted in supply-side forces. Consumption support will be slow and incremental, keeping deflationary pressures elevated for the next 6–12 months.
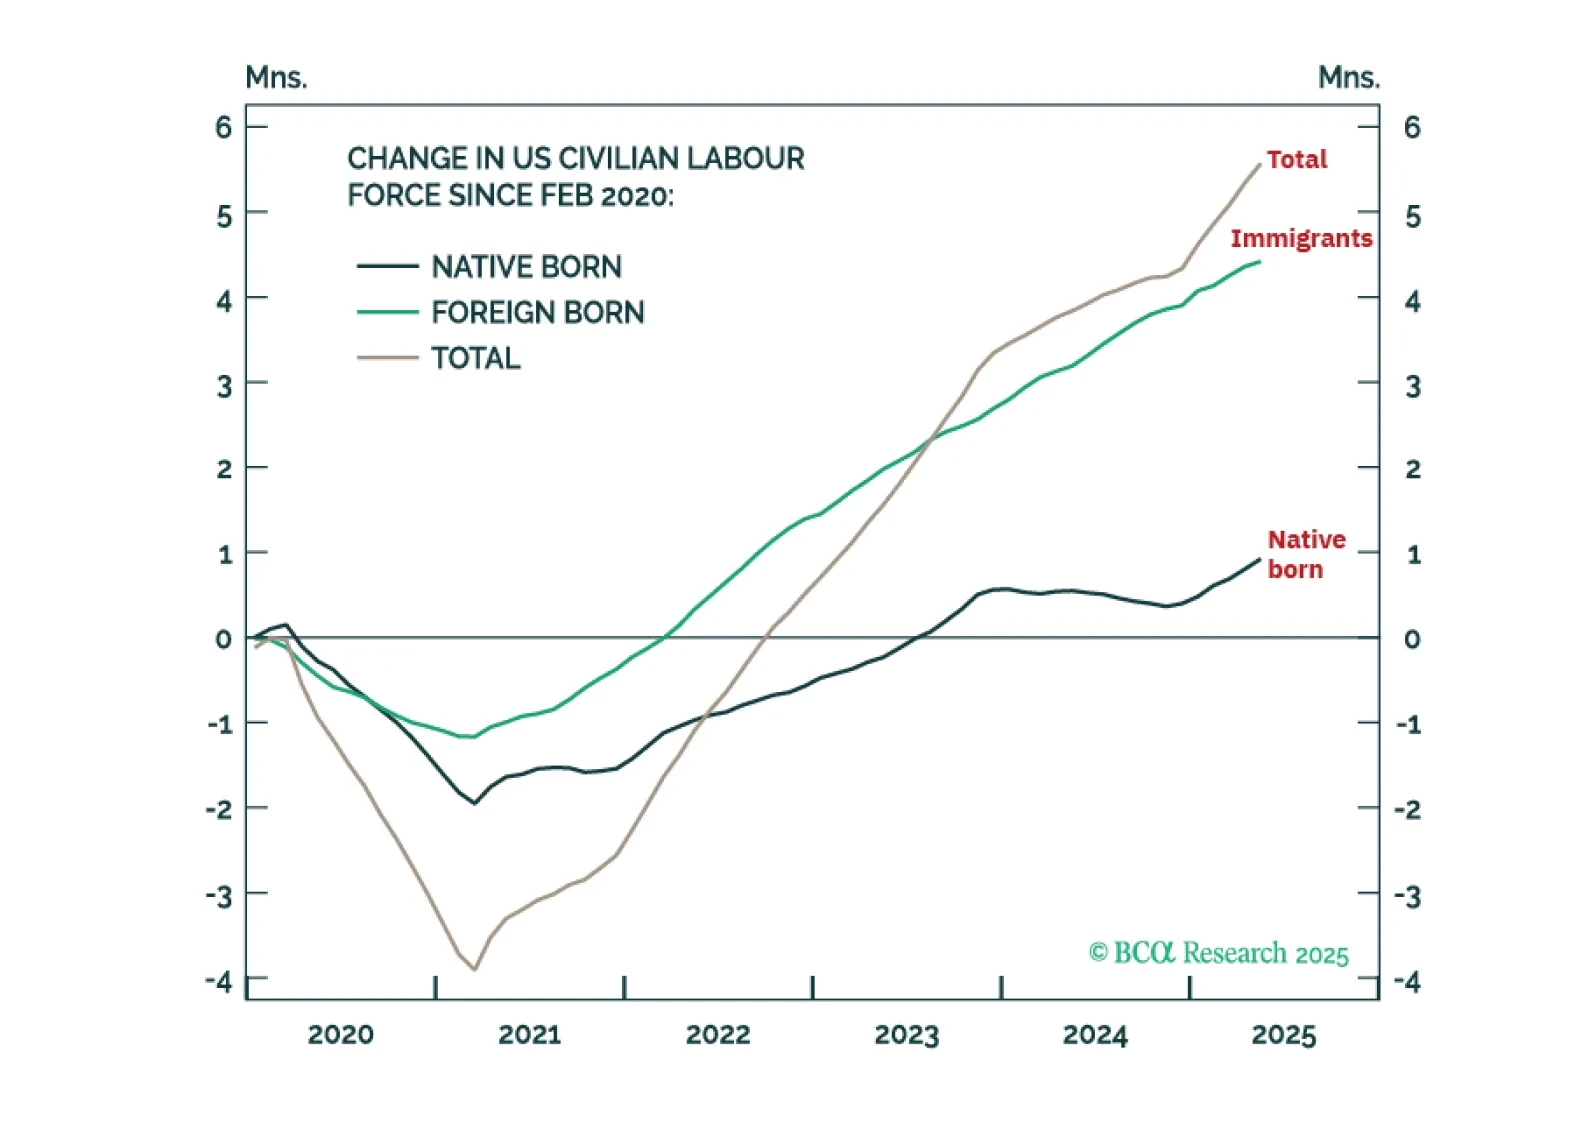
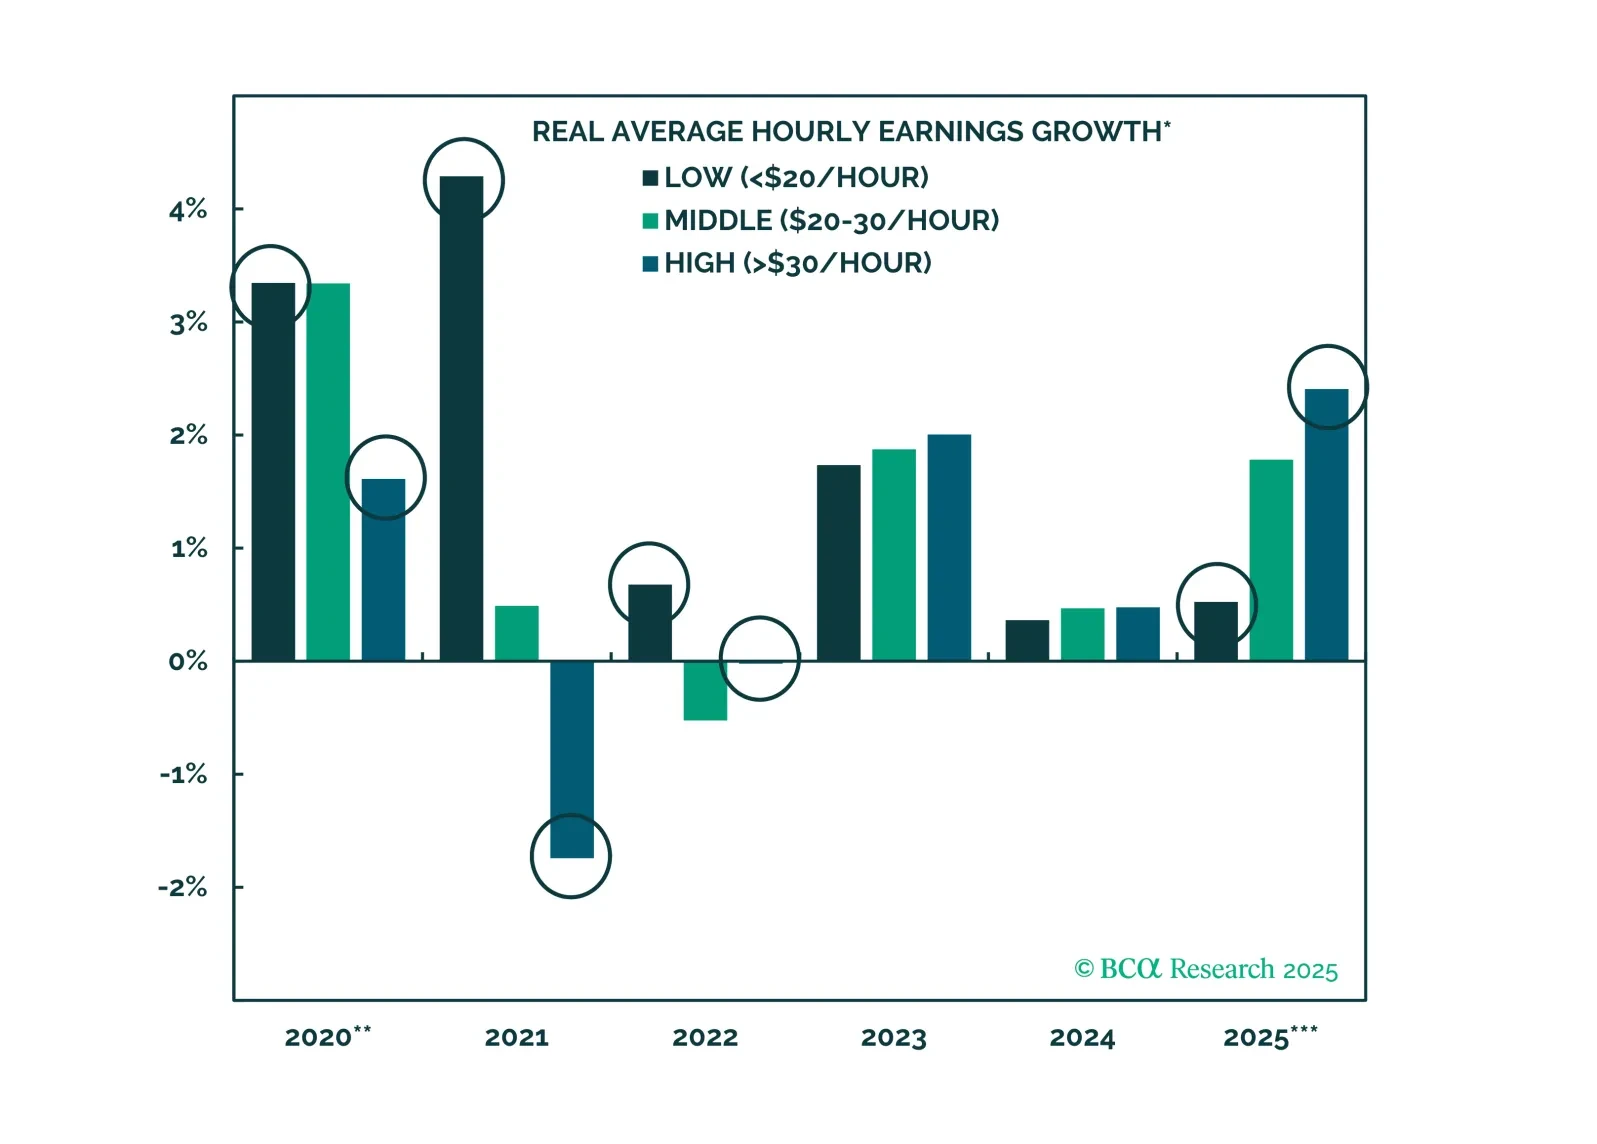
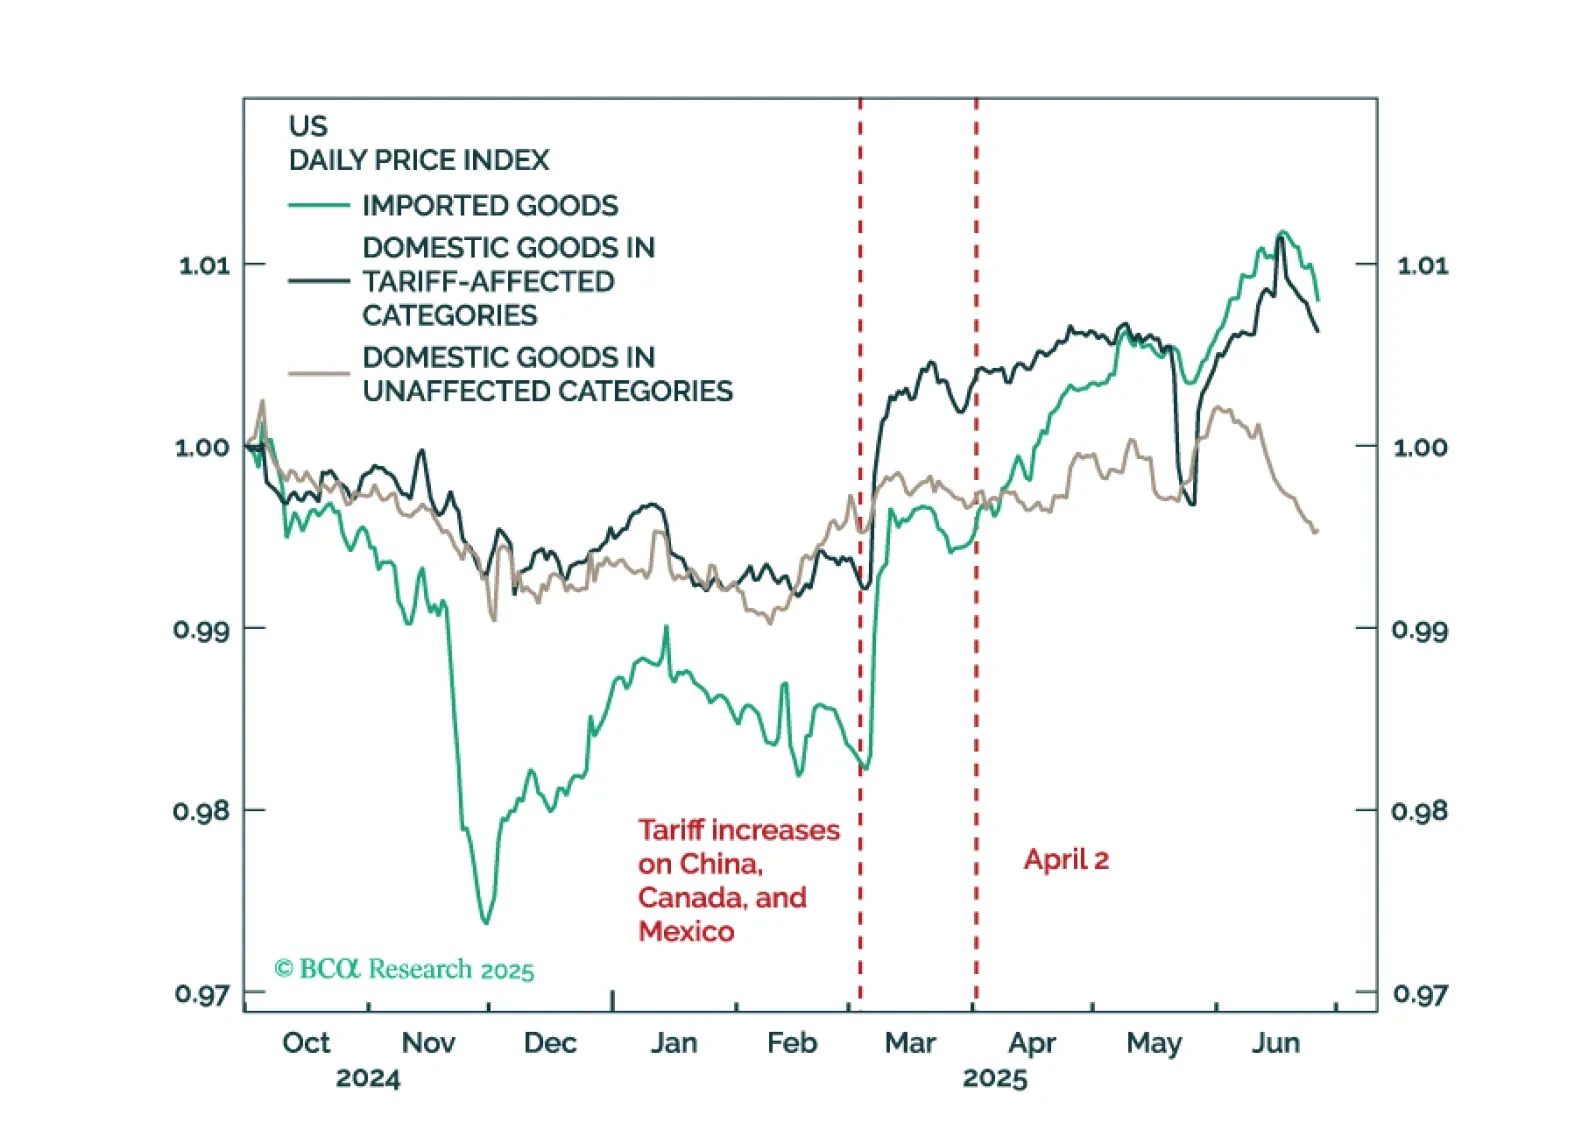
Trump’s immigration policies are protecting the US economy from a sharp rise in unemployment but steering it into a ‘mini stagflation’. Plus: a new tactical trade is to underweight global technology (IXN).