 CoreMacro
BCA’s flagship global macro and investment strategy platform, helping investors anticipate regime shifts, connect signals across regions and asset classes, and navigate the world’s most difficult macro questions.
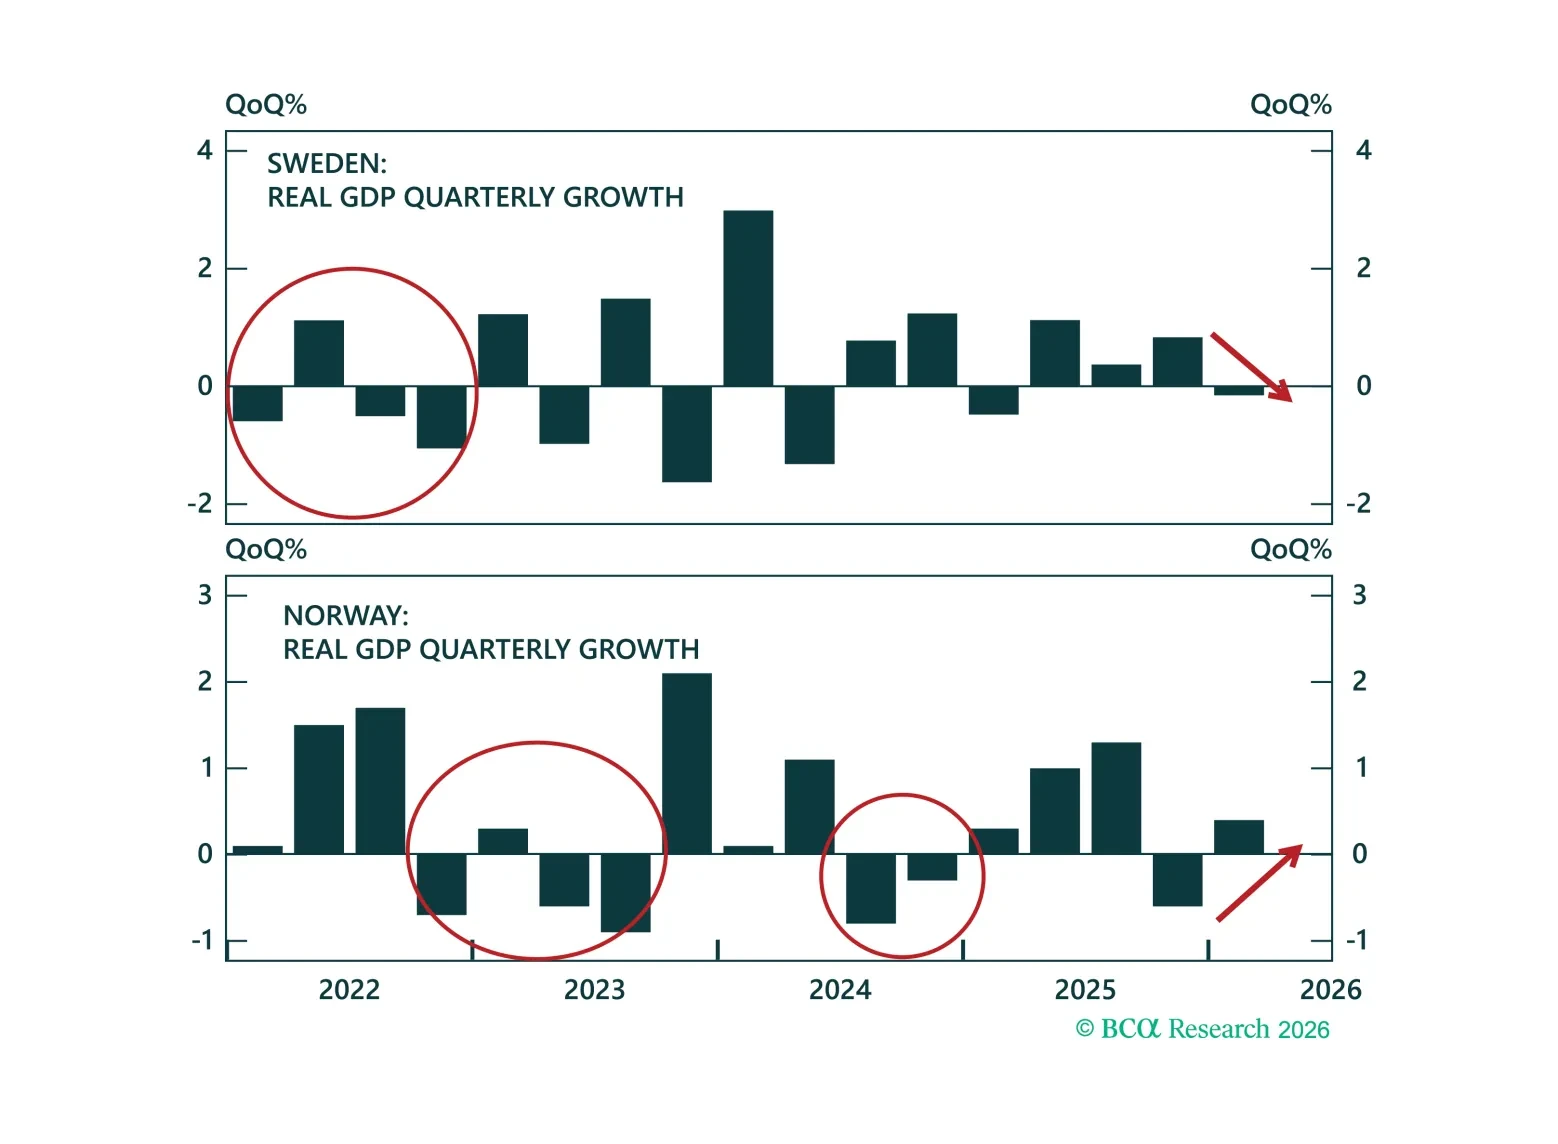
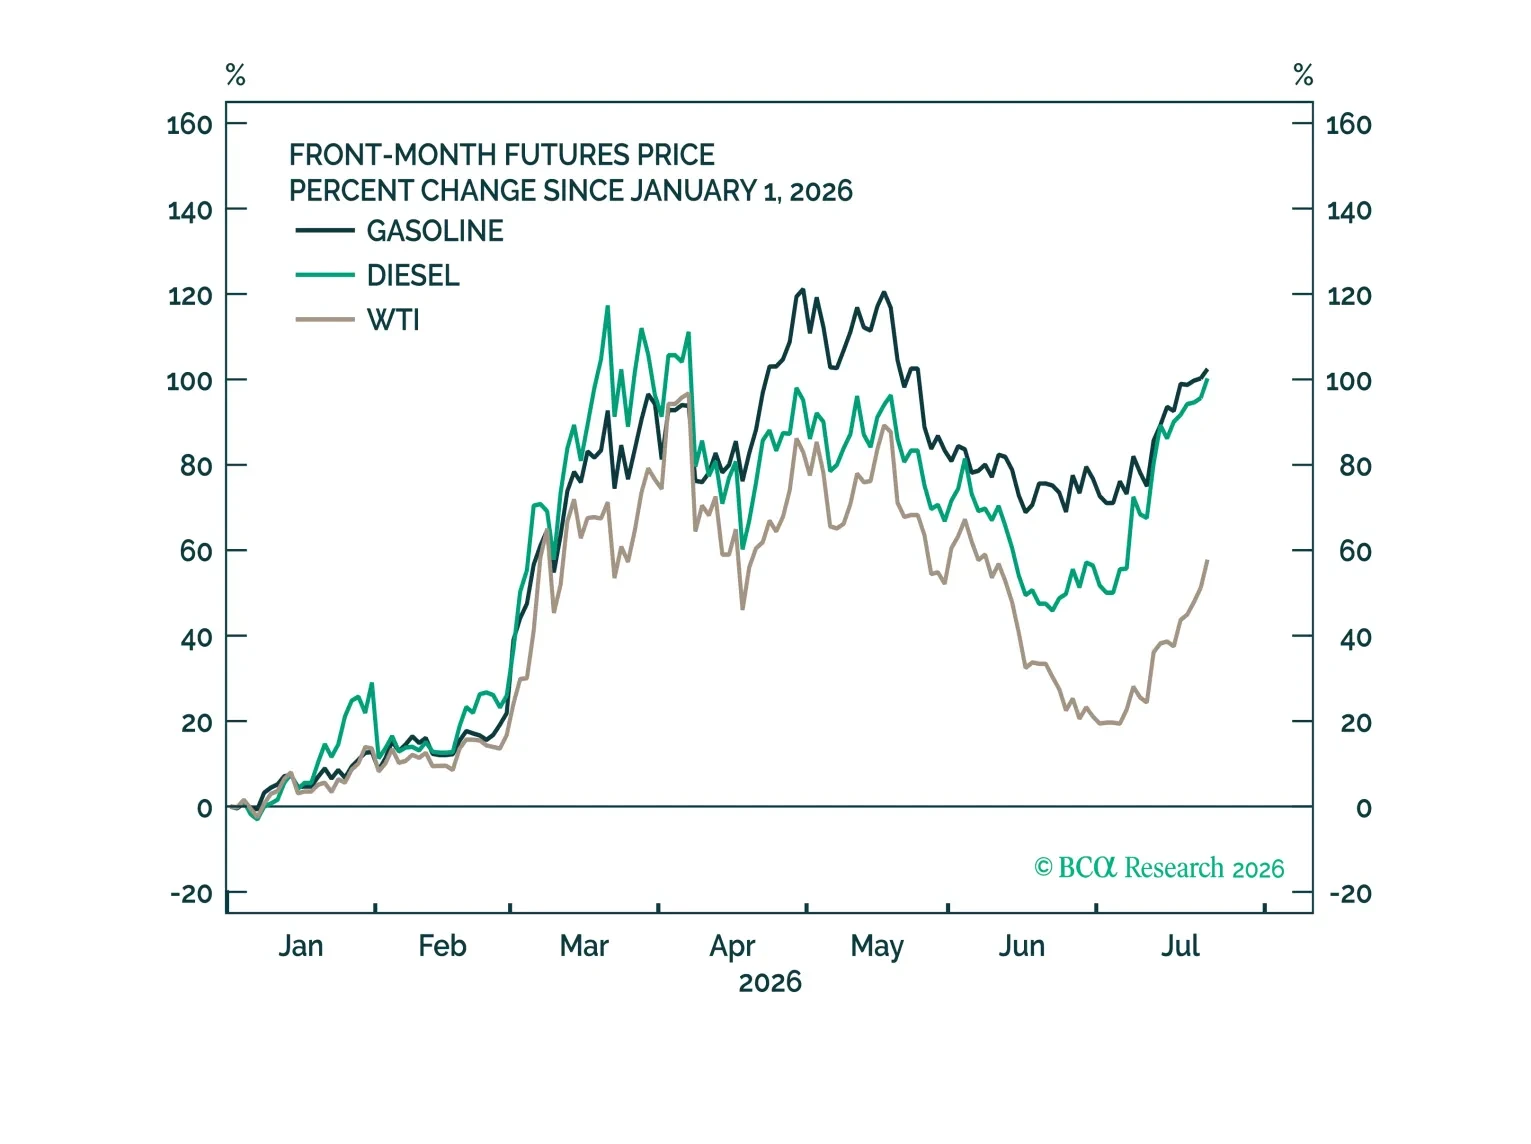
The war in Iran and the energy shock are driving a reversal of Nordic fortunes: Sweden’s recovery is faltering just as Norway receives a welcome energy windfall. Favor Norwegian over Swedish equities and buy NOK/SEK. In rates, fade aggressive Riksbank hike expectations and downgrade Norwegian government bonds to neutral.
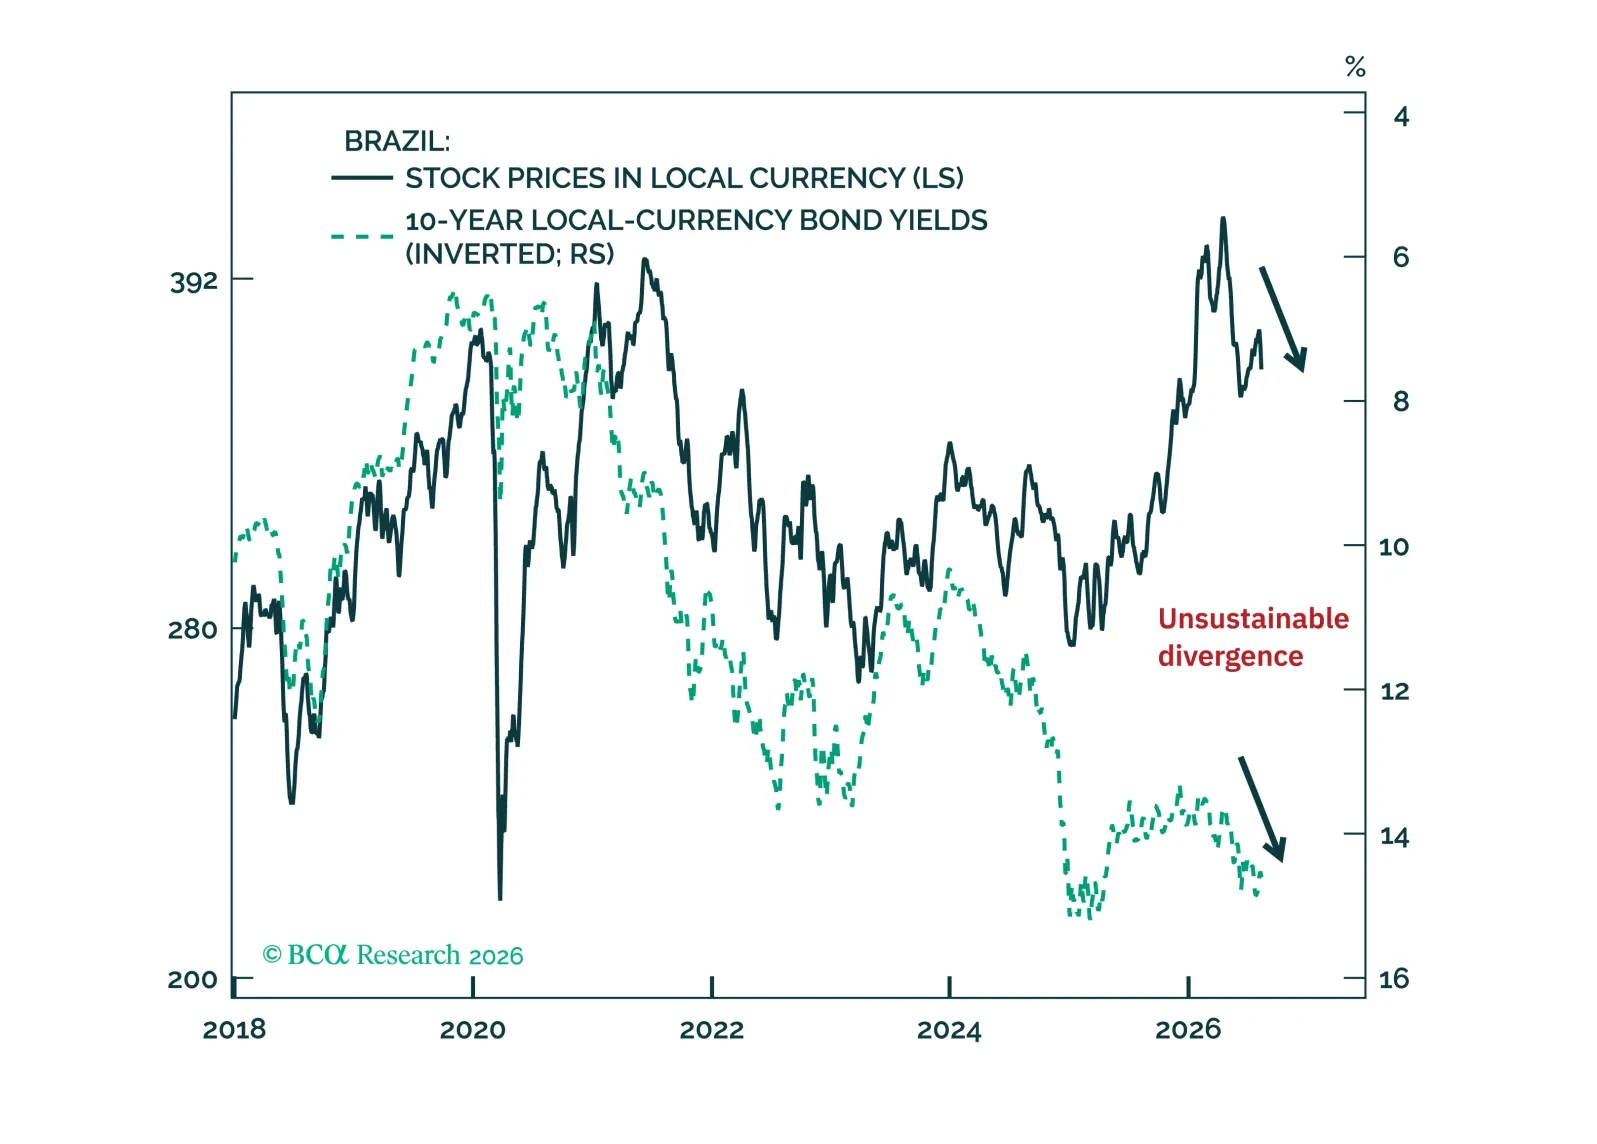
We are downgrading Brazilian equities from neutral to underweight and maintaining our underweights in Brazil's domestic bonds and sovereign credit within their respective EM portfolios. Go long Brazilian 5-year CDS as a short-term trade.
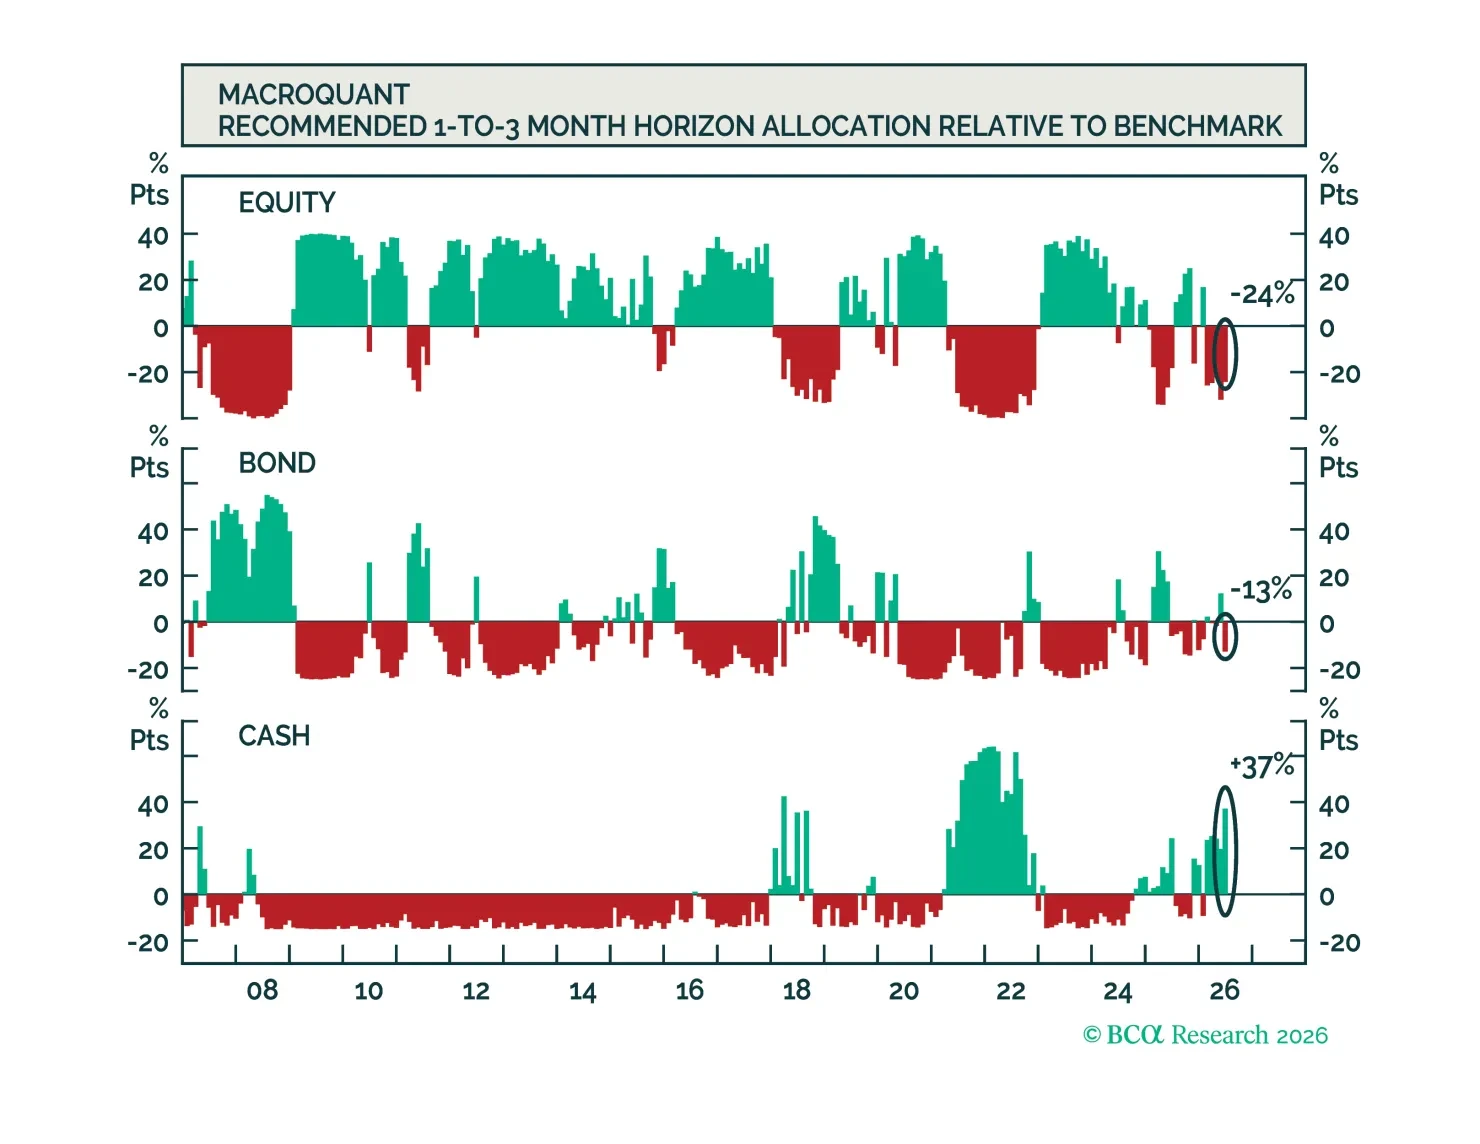
MacroQuant recommends a slight underweight position in equities, and favors a below-benchmark duration stance in fixed-income portfolios. The model is very positive on the US dollar, neutral on gold, constructive on copper, and very bullish on oil.
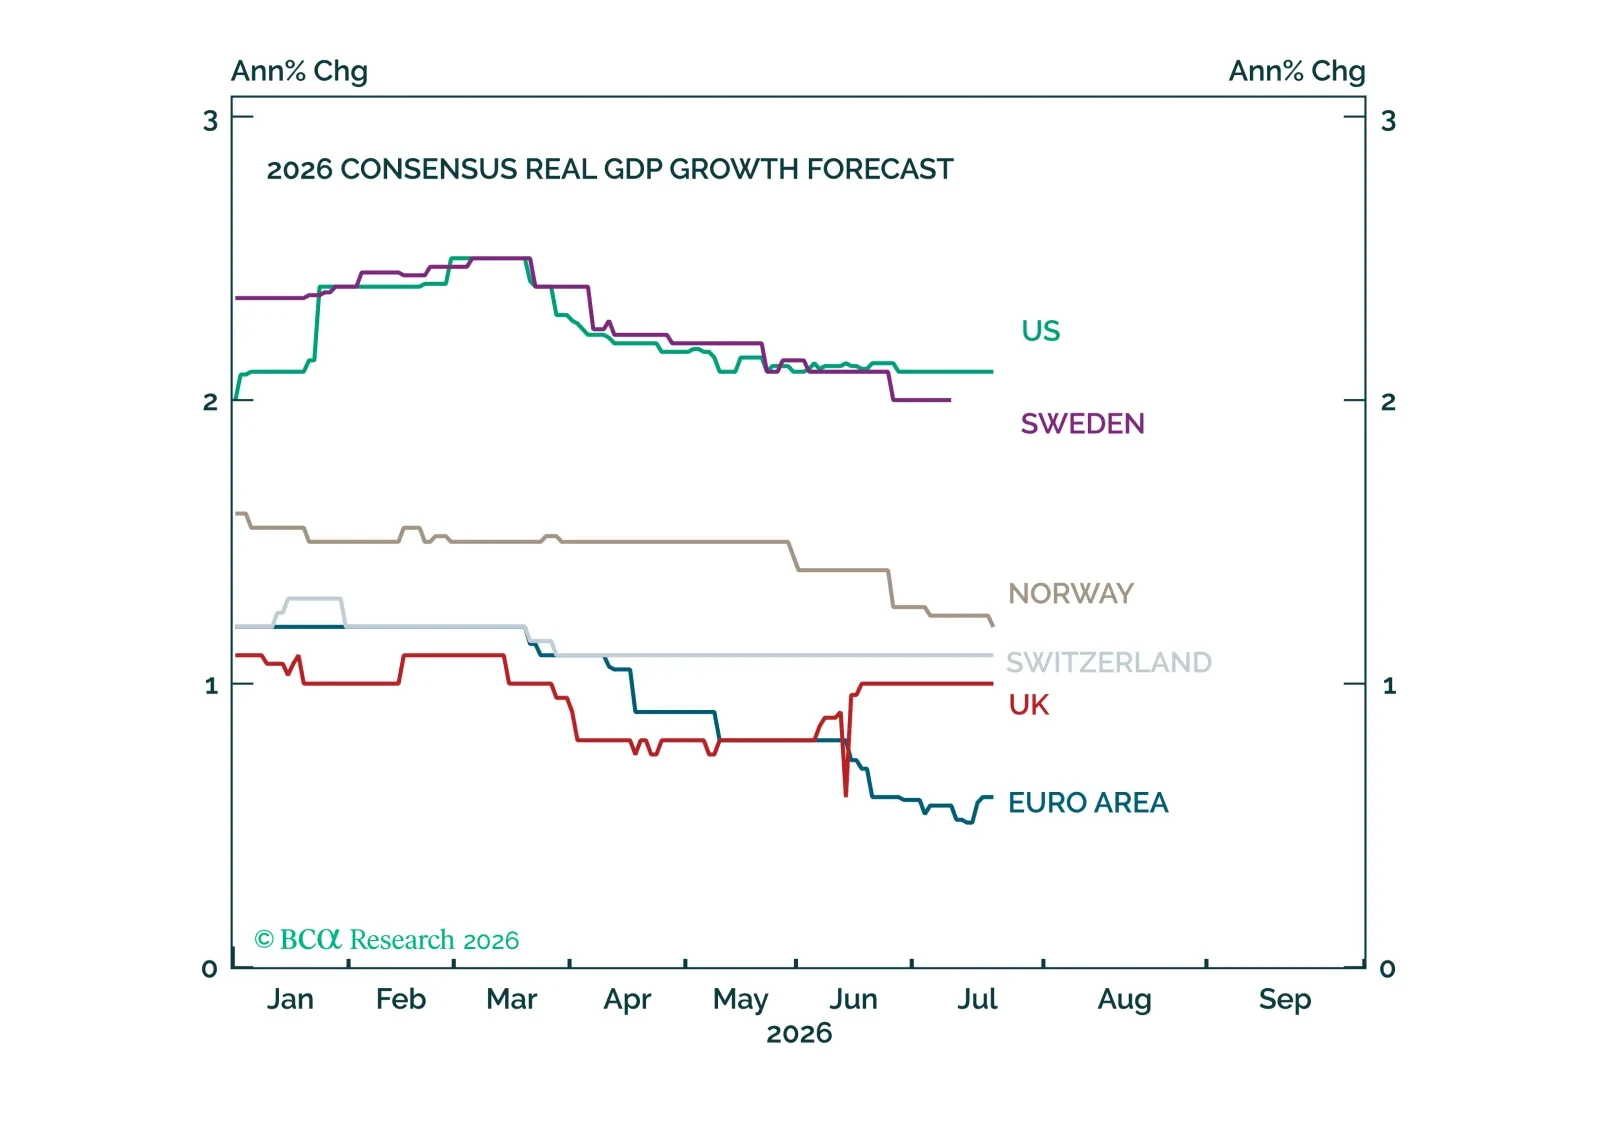
Europe faces a difficult macro backdrop, but whether it slips into recession remains finely balanced. We present two perspectives before translating them into investment implications.
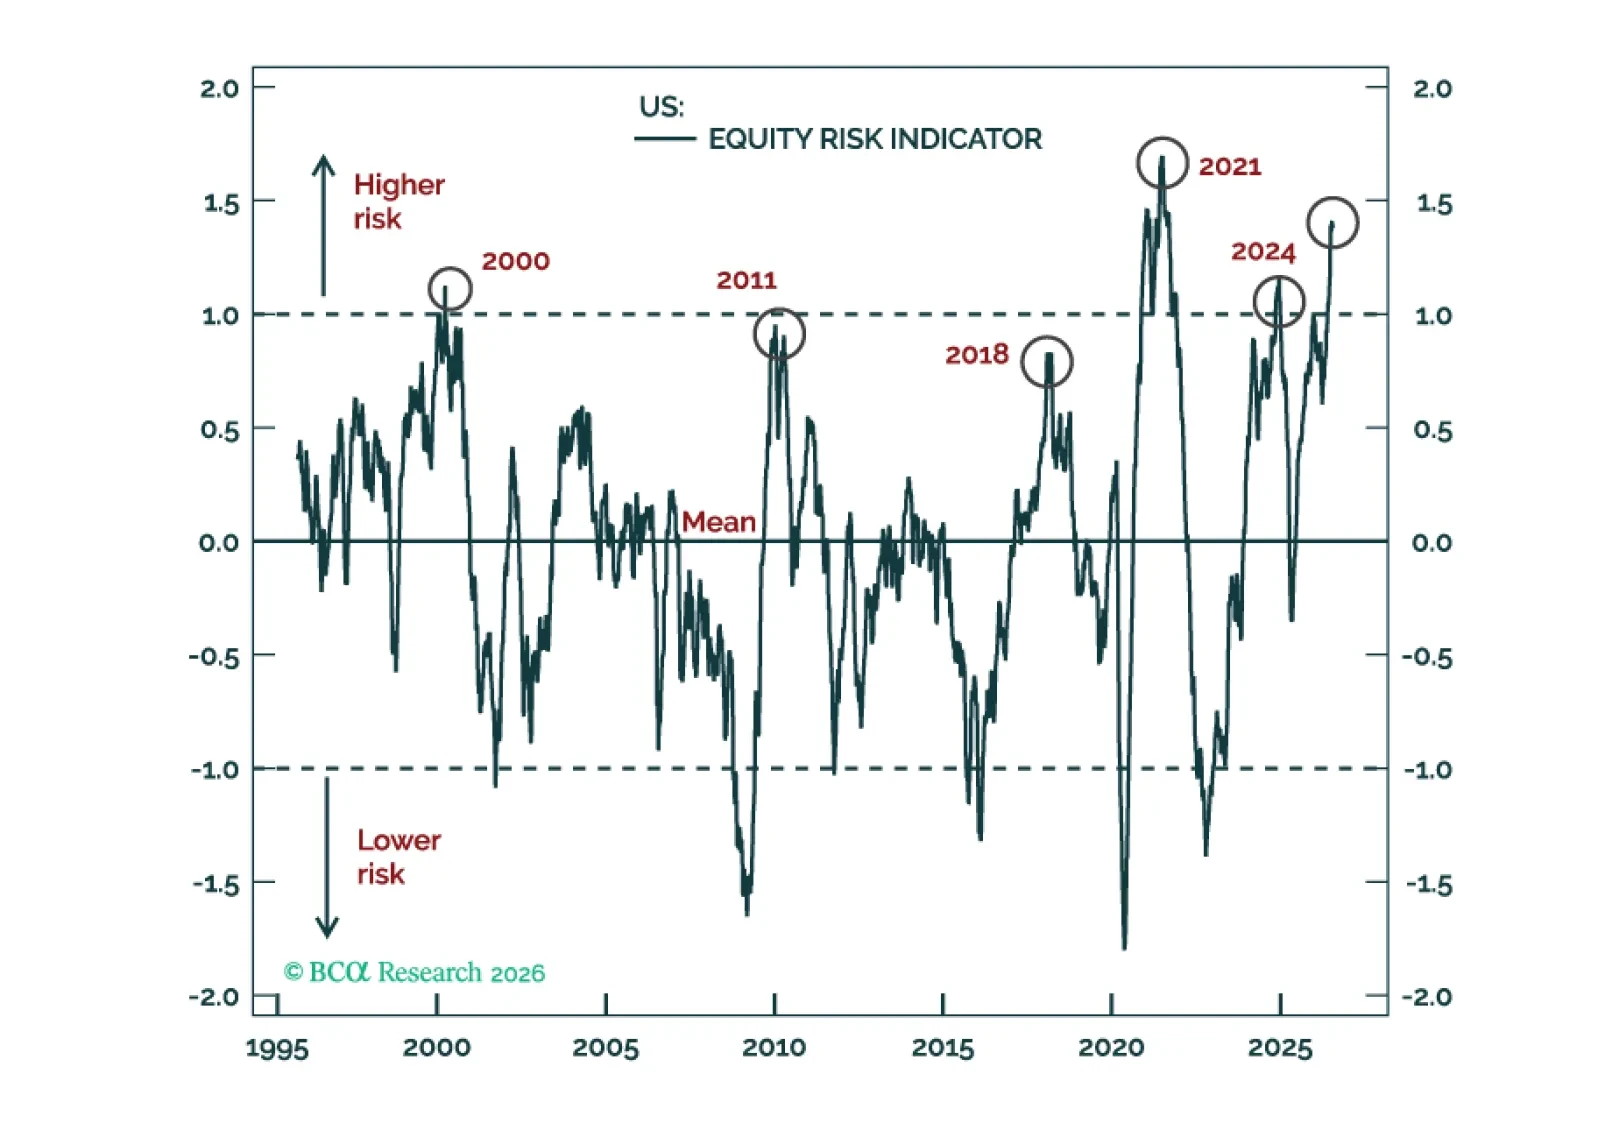
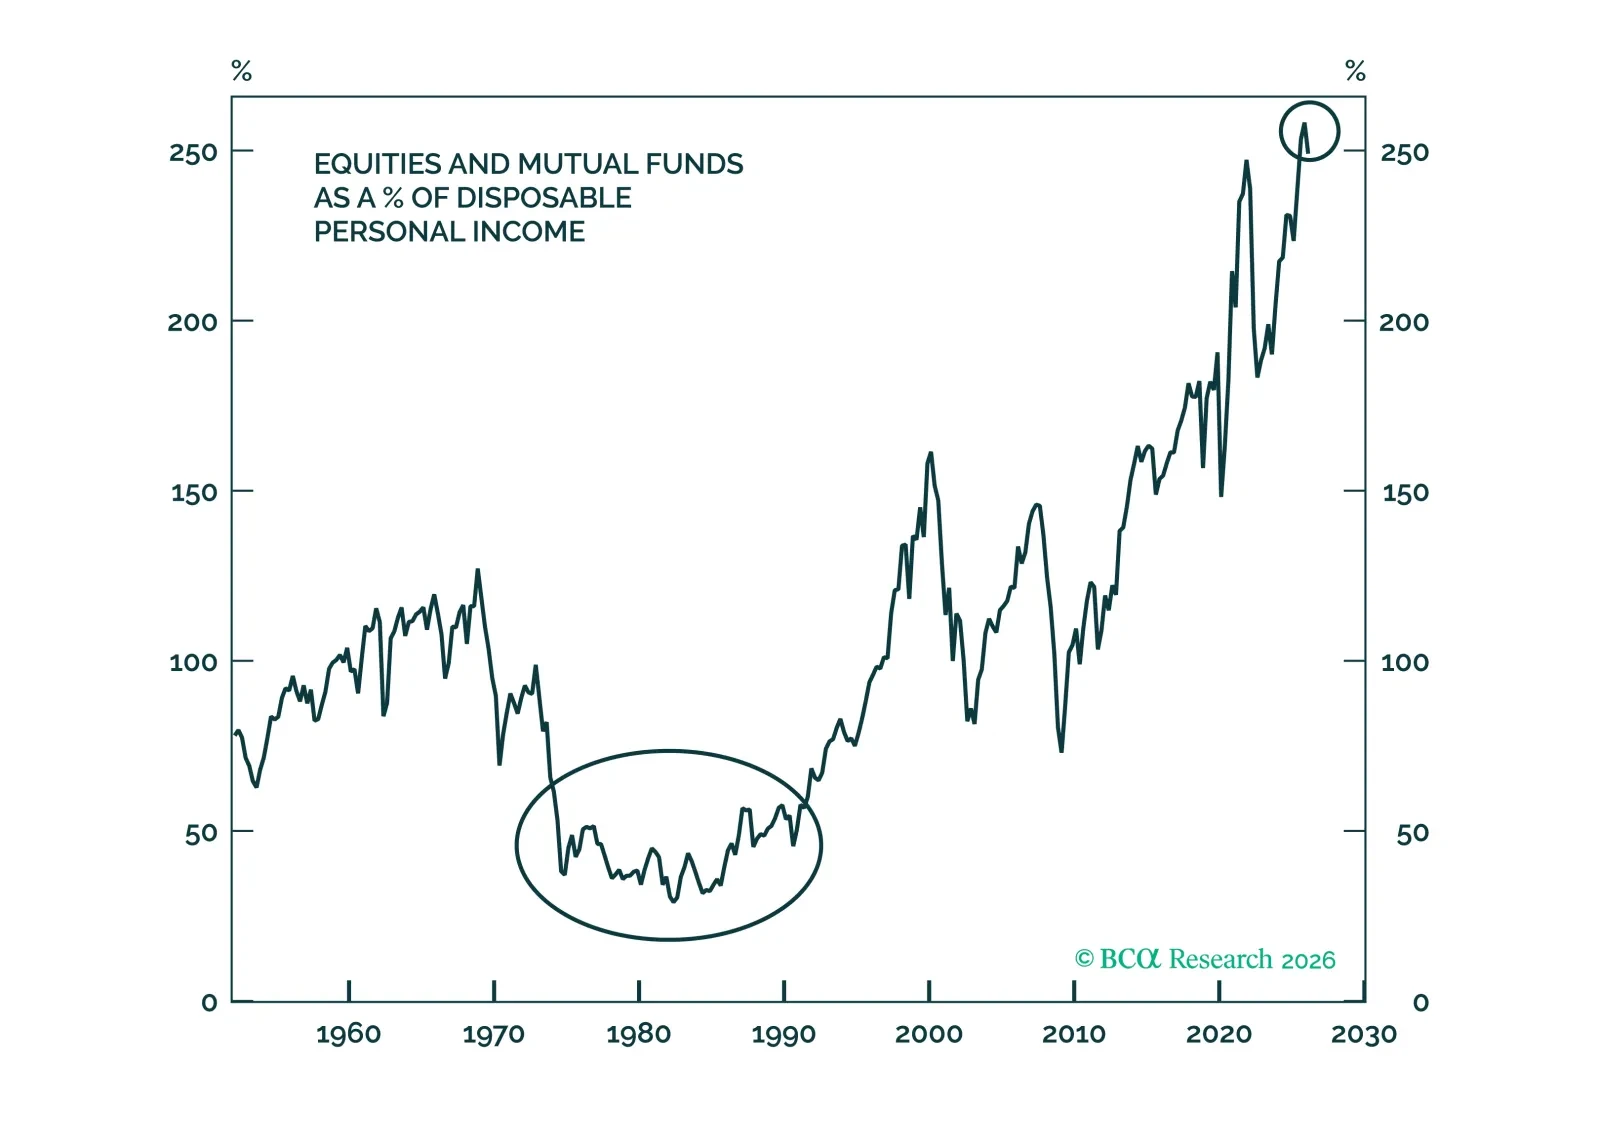
Global equities have reached extremes on multiple measures, none of which are reliable timing tools. But imbalances in economics and investing can build for far longer than rational analysis would predict - and usually unravel much faster than investors expect.
As long as the AI boom keeps booming, all other investment considerations will remain on the back burner. However, if the AI trade fizzles, this would expose deep-seated problems within the global economy, which could very well lead to an economic downturn as early as next year.