 CoreMacro
BCA’s flagship global macro and investment strategy platform, helping investors anticipate regime shifts, connect signals across regions and asset classes, and navigate the world’s most difficult macro questions.
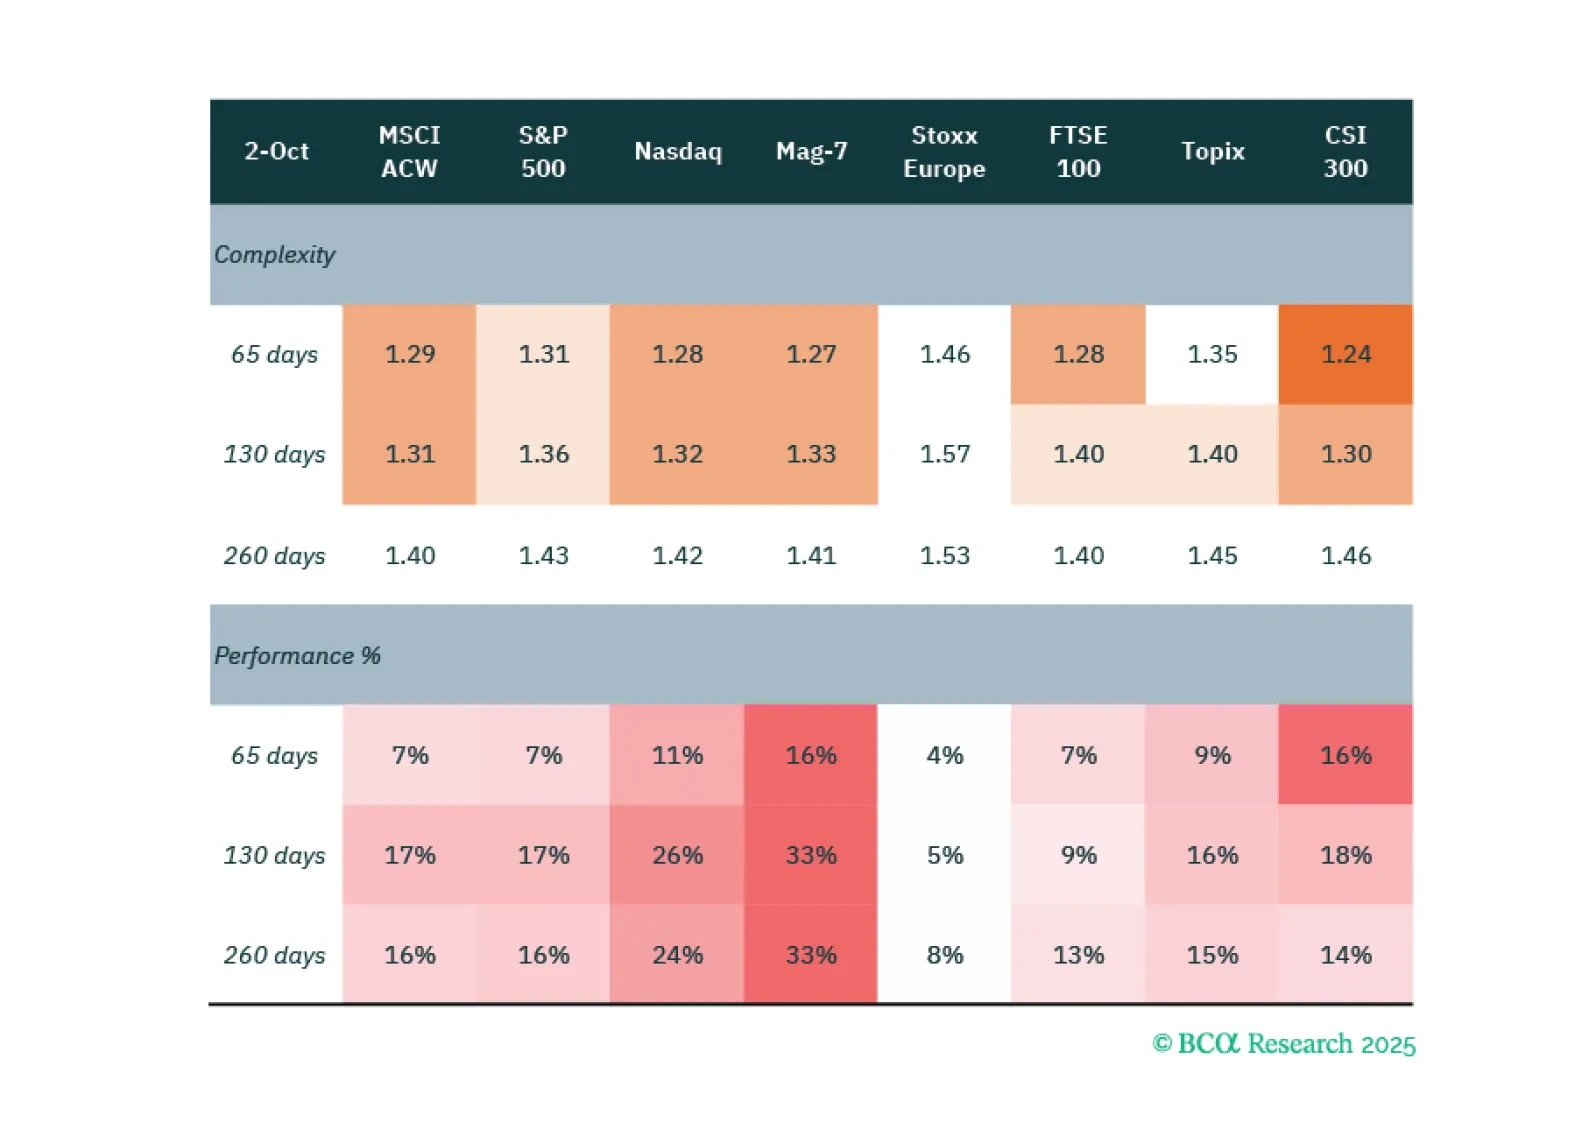
A short guide on how best to use and interpret our real-time fractal heatmap for asset allocation.
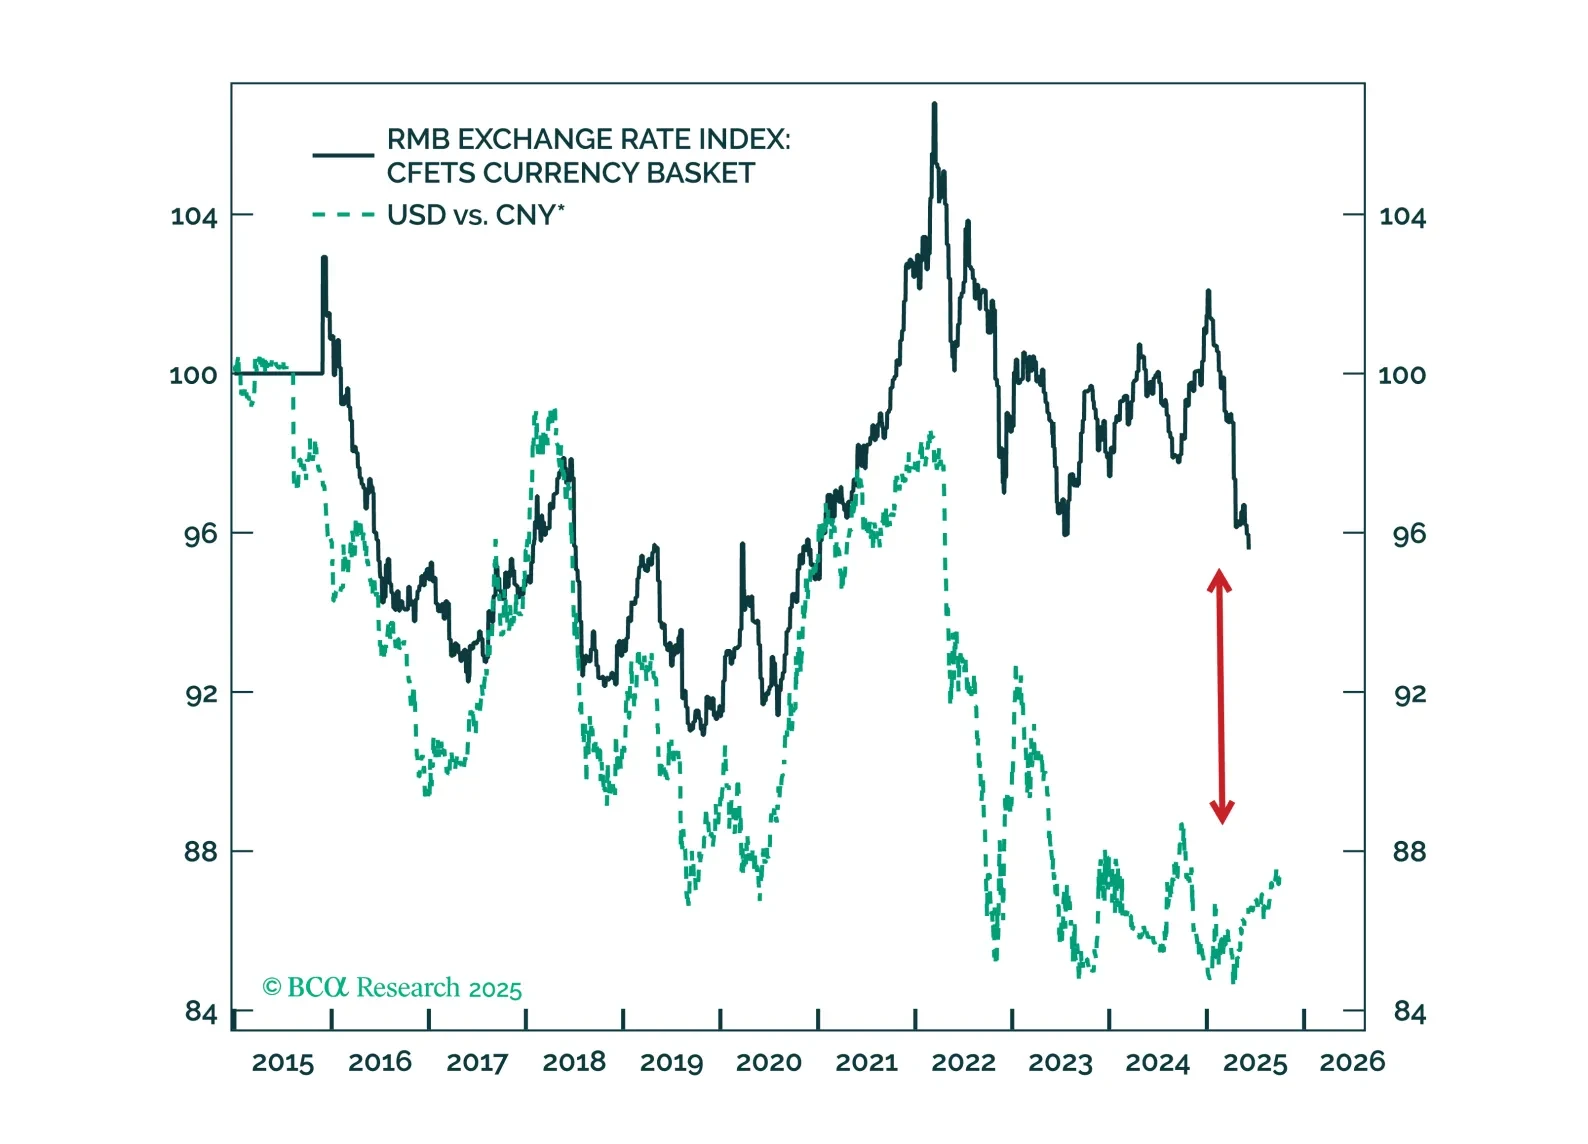
The CNY/USD has room to appreciate both cyclically and structurally, while nominal yields on China’s long-duration government bonds are set to fall. This combination supports Chinese equities.
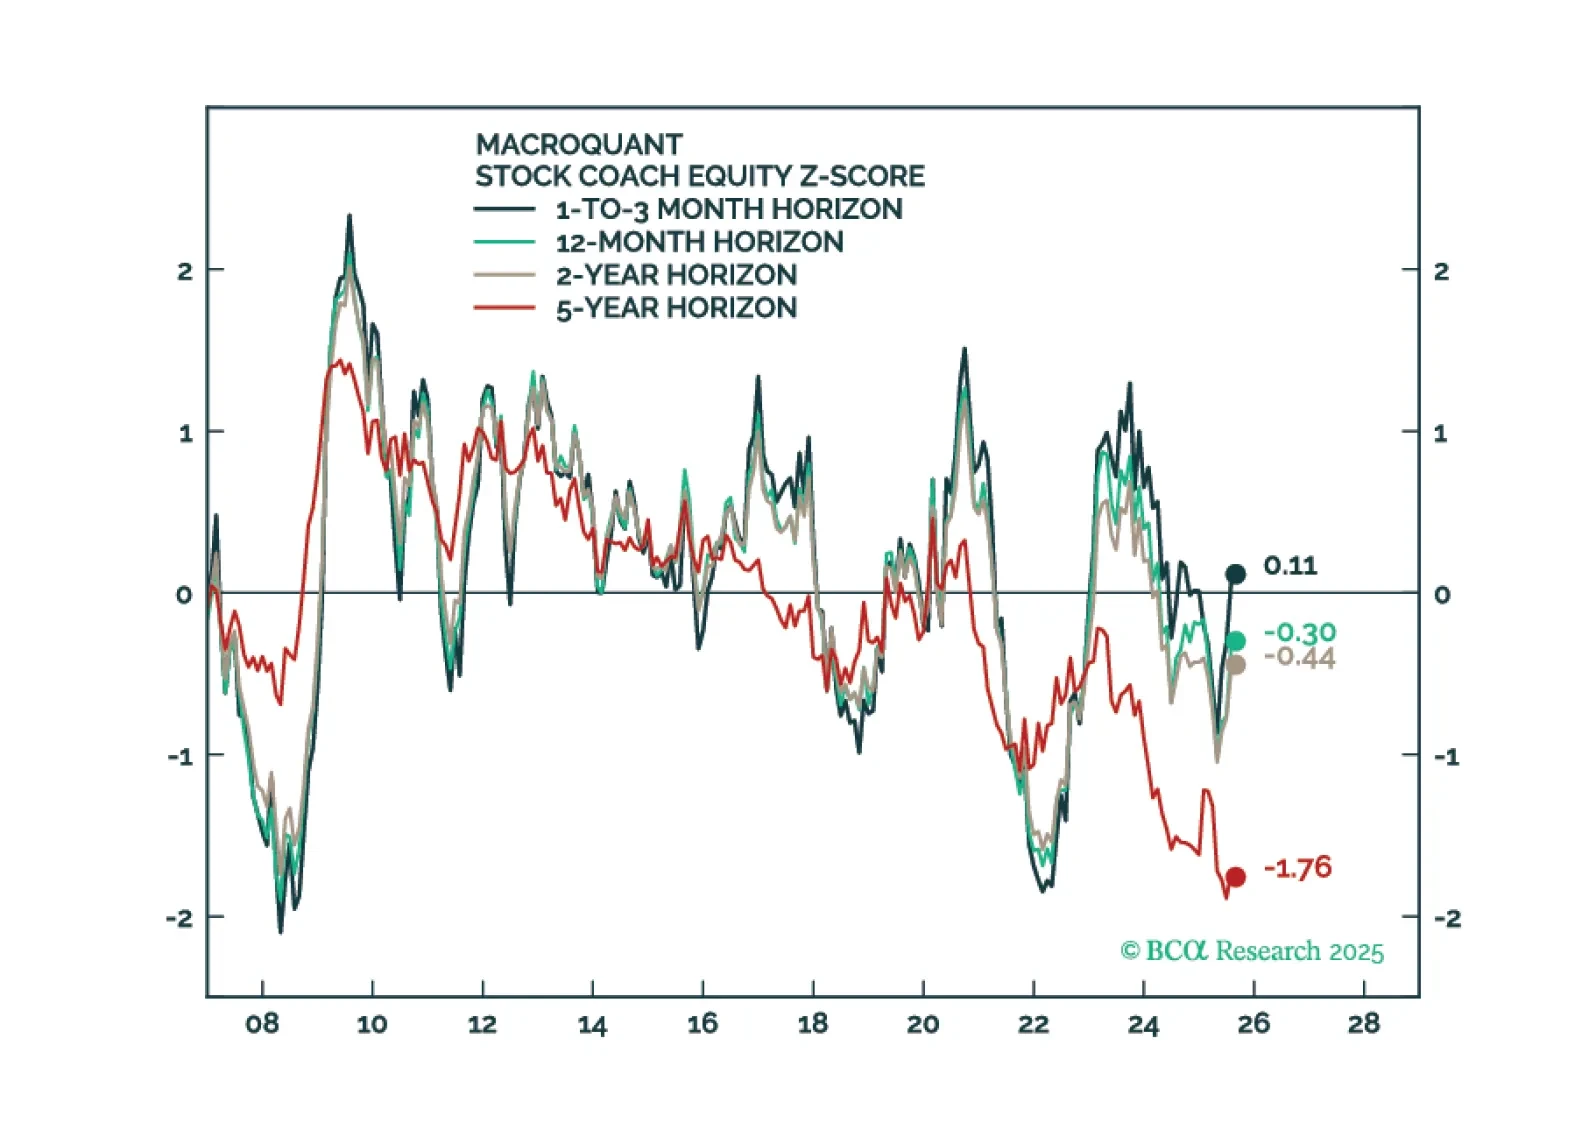
MacroQuant is neutral-to-slightly positive on stocks on a tactical 1-to-3 month horizon but sees downside risks over a longer-term horizon. Its favorite equity sectors are communication services and IT. Regionally, it prefers EM and US equities. The model is bullish on duration. It remains bearish on the US dollar. It is upbeat on gold and copper but is slightly negative on oil.
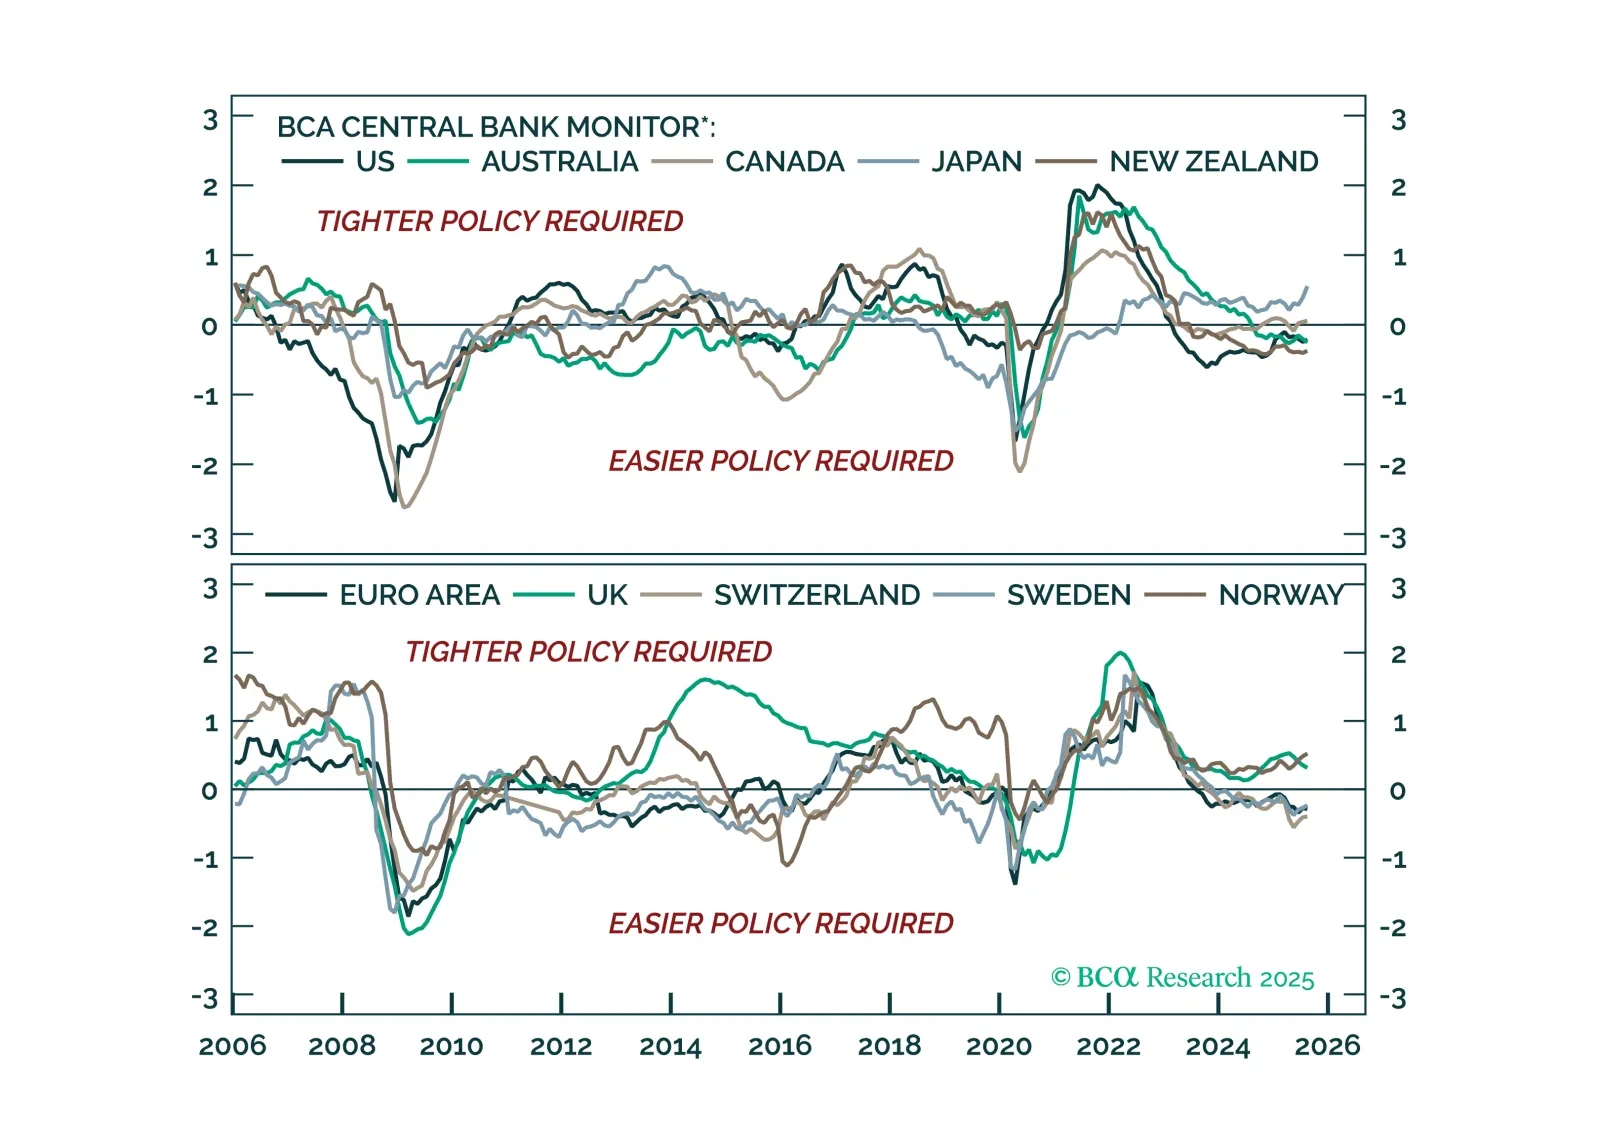
Monetary policy divergences are re-emerging. We rely on BCA’s Central Bank Monitor to assess the current policy stance of major central banks, and highlight the tactical opportunities across bond markets and currencies.
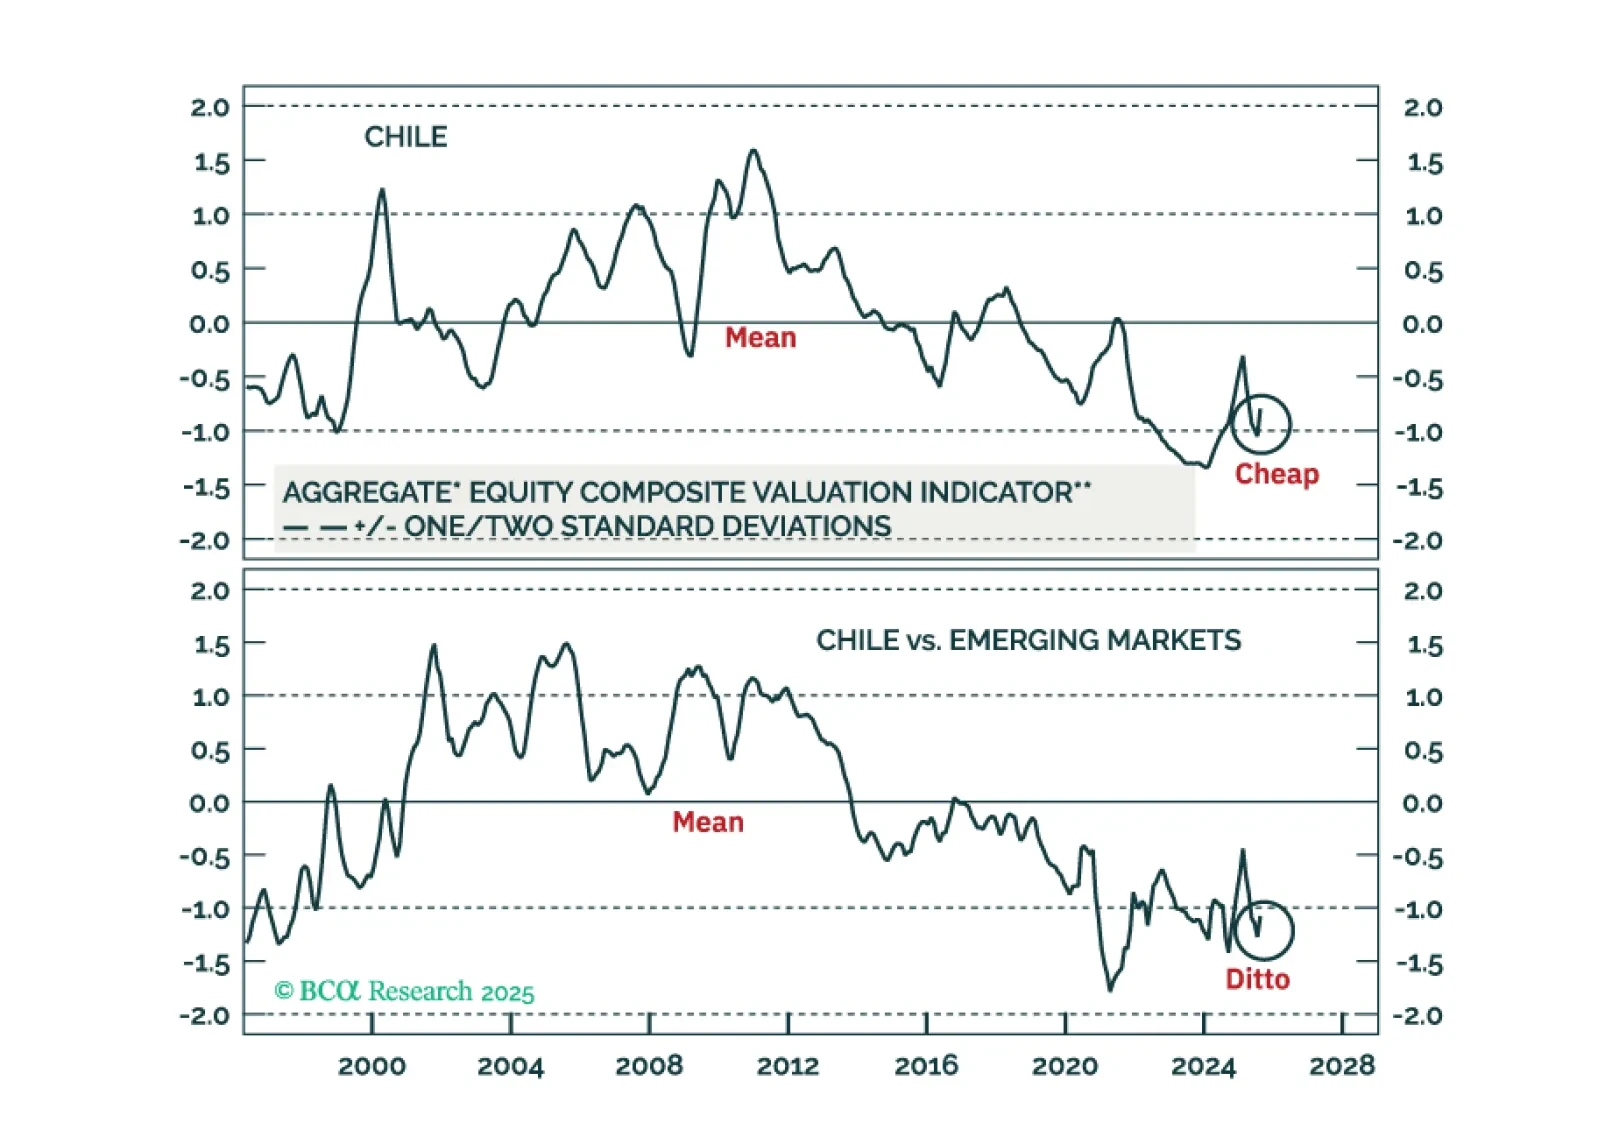
Chilean equities are undergoing a structural re-rating. A political swing back to a pro-business administration, a benign macro backdrop, and a resilient exchange rate will drive Chilean markets’ outperformance versus EM peers.
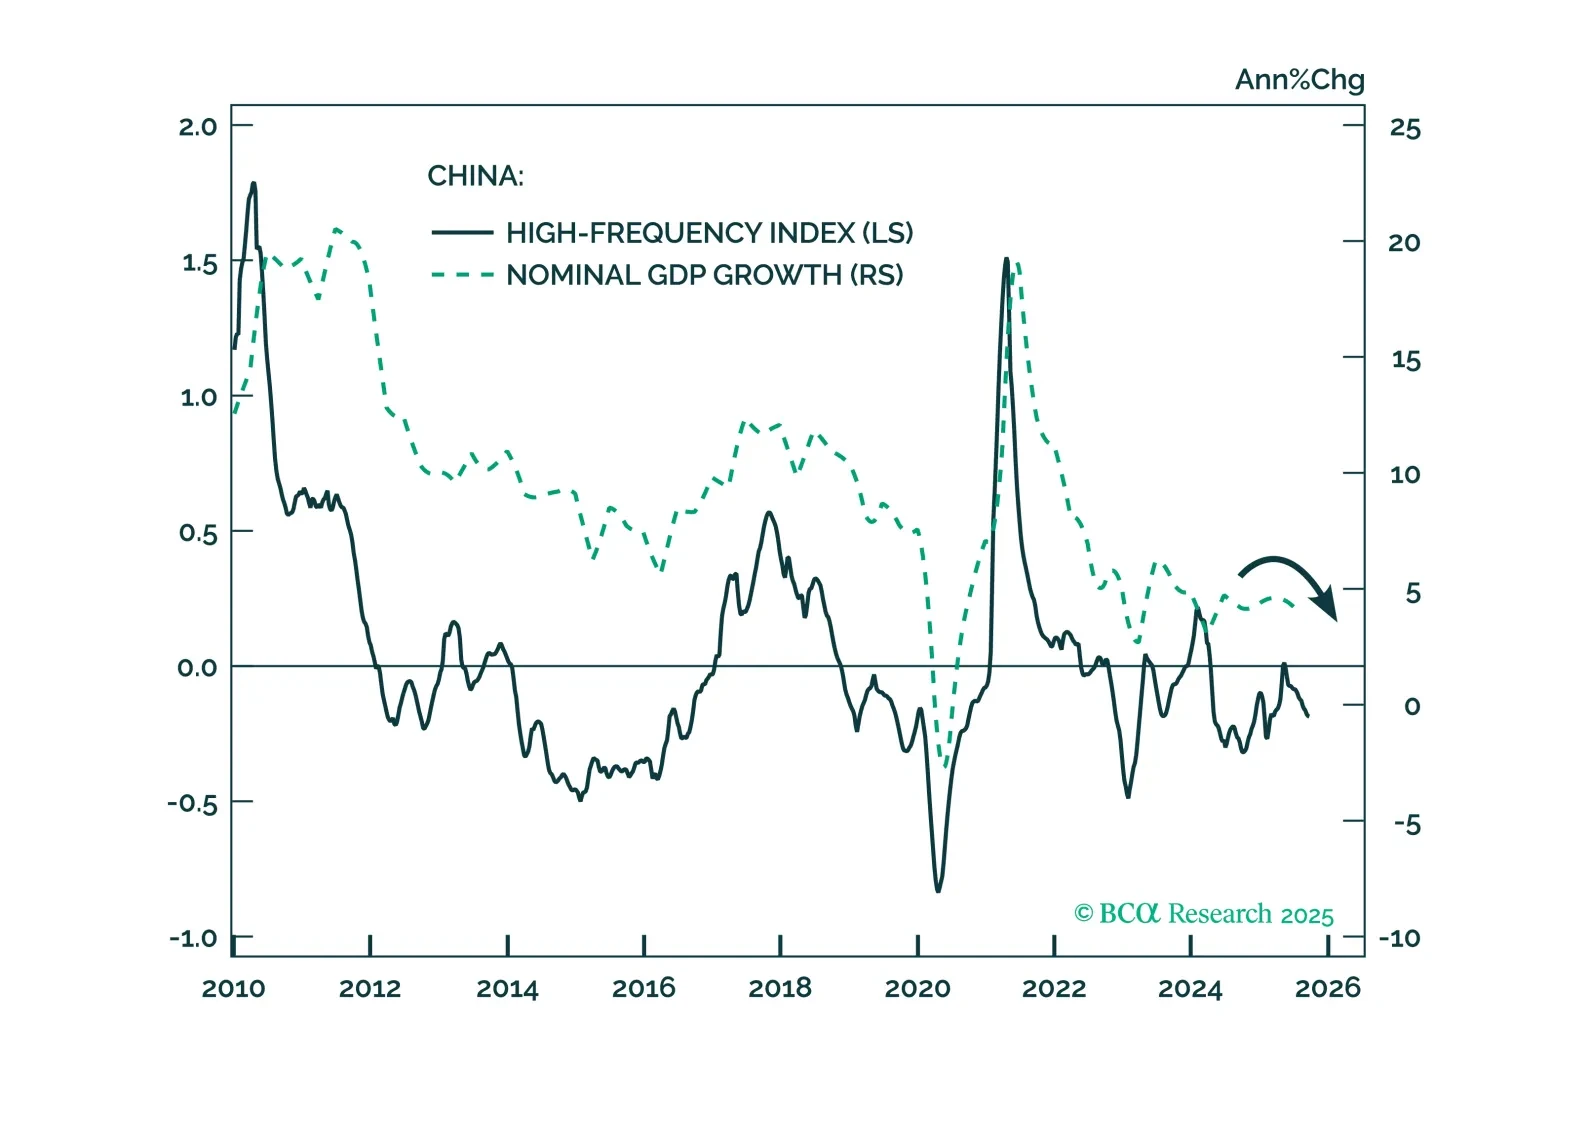
Our high-frequency indicators show China’s growth momentum weakening further in September, increasing the likelihood of new stimulus in the weeks ahead. We remain tactically cautious on Chinese equities, but strategically constructive on offshore Chinese shares.
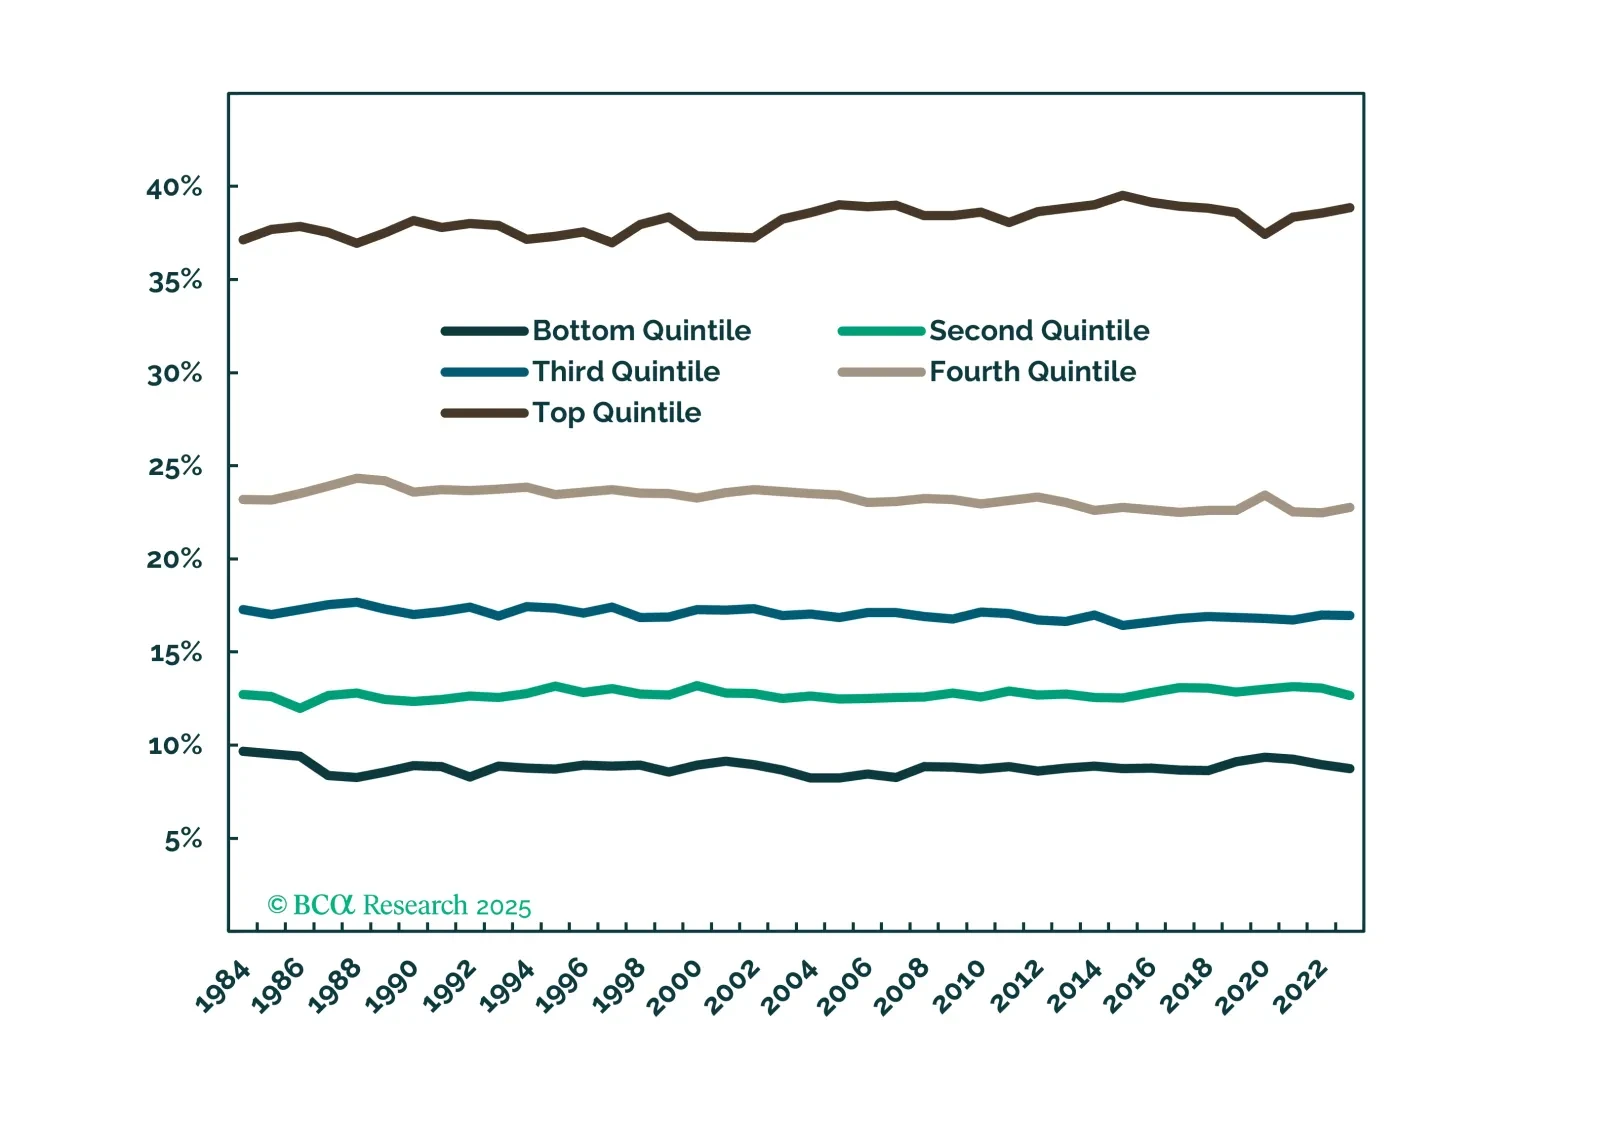
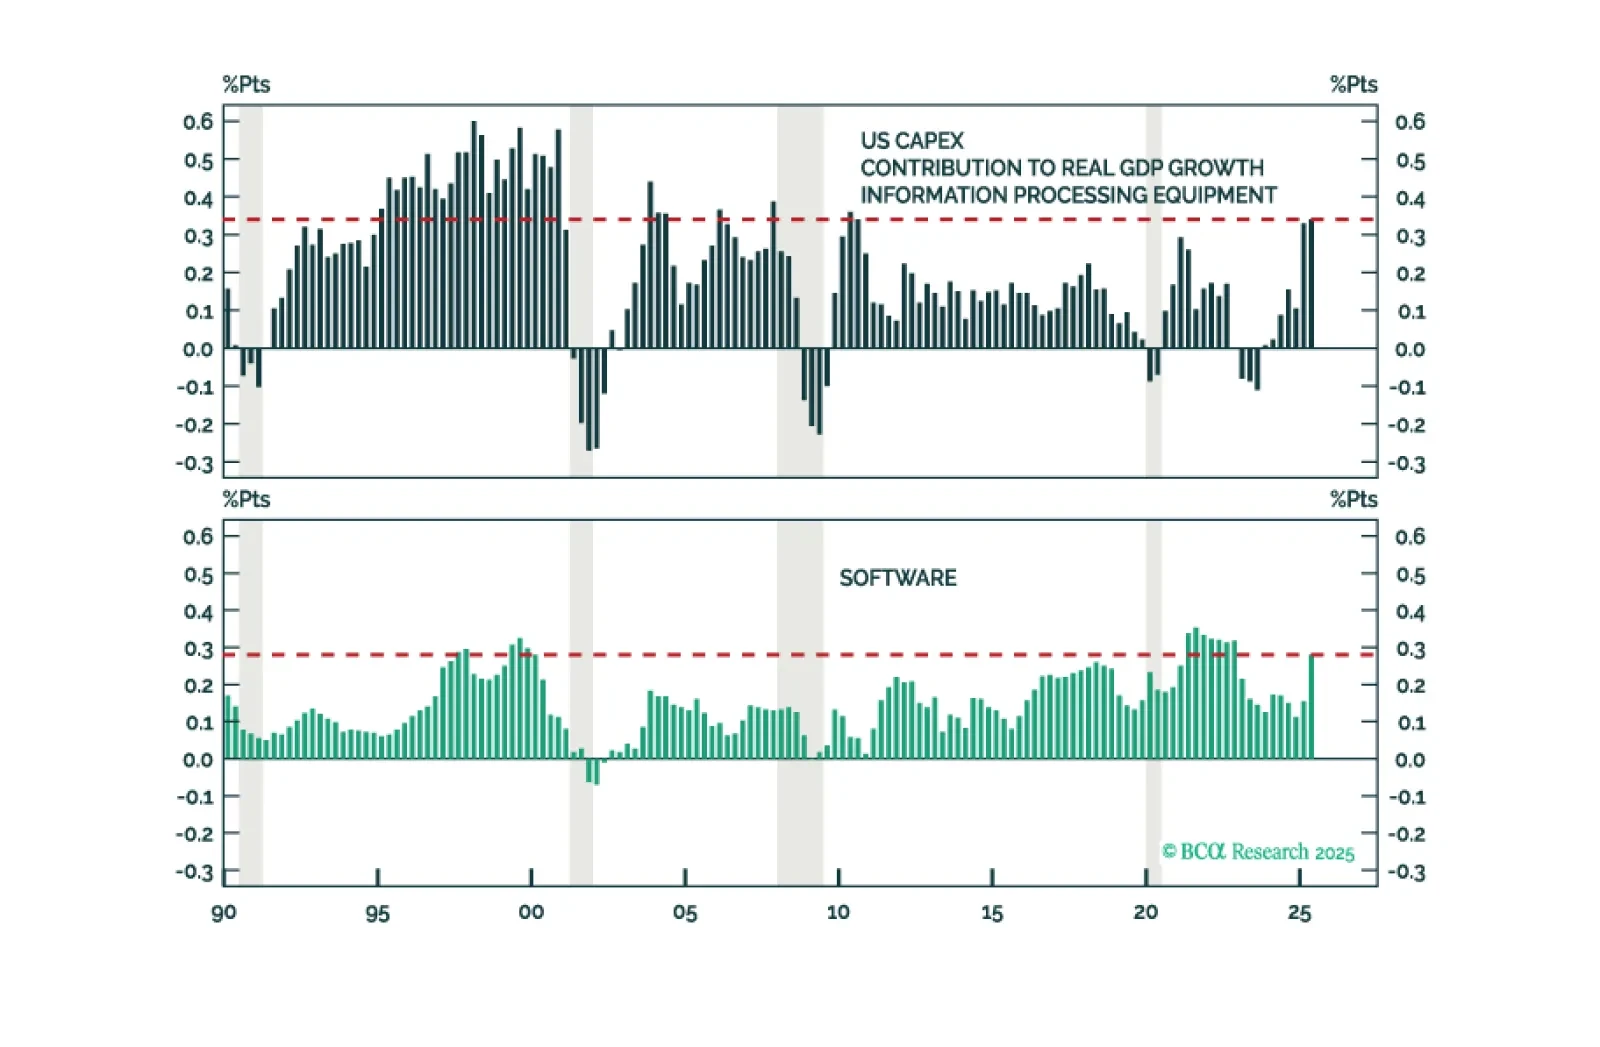
While it is not yet time to bet against risk assets, we push back on the increasingly popular ideas that the wealthiest households and/or AI-related capex can keep the expansion going despite the wobbling labor market.
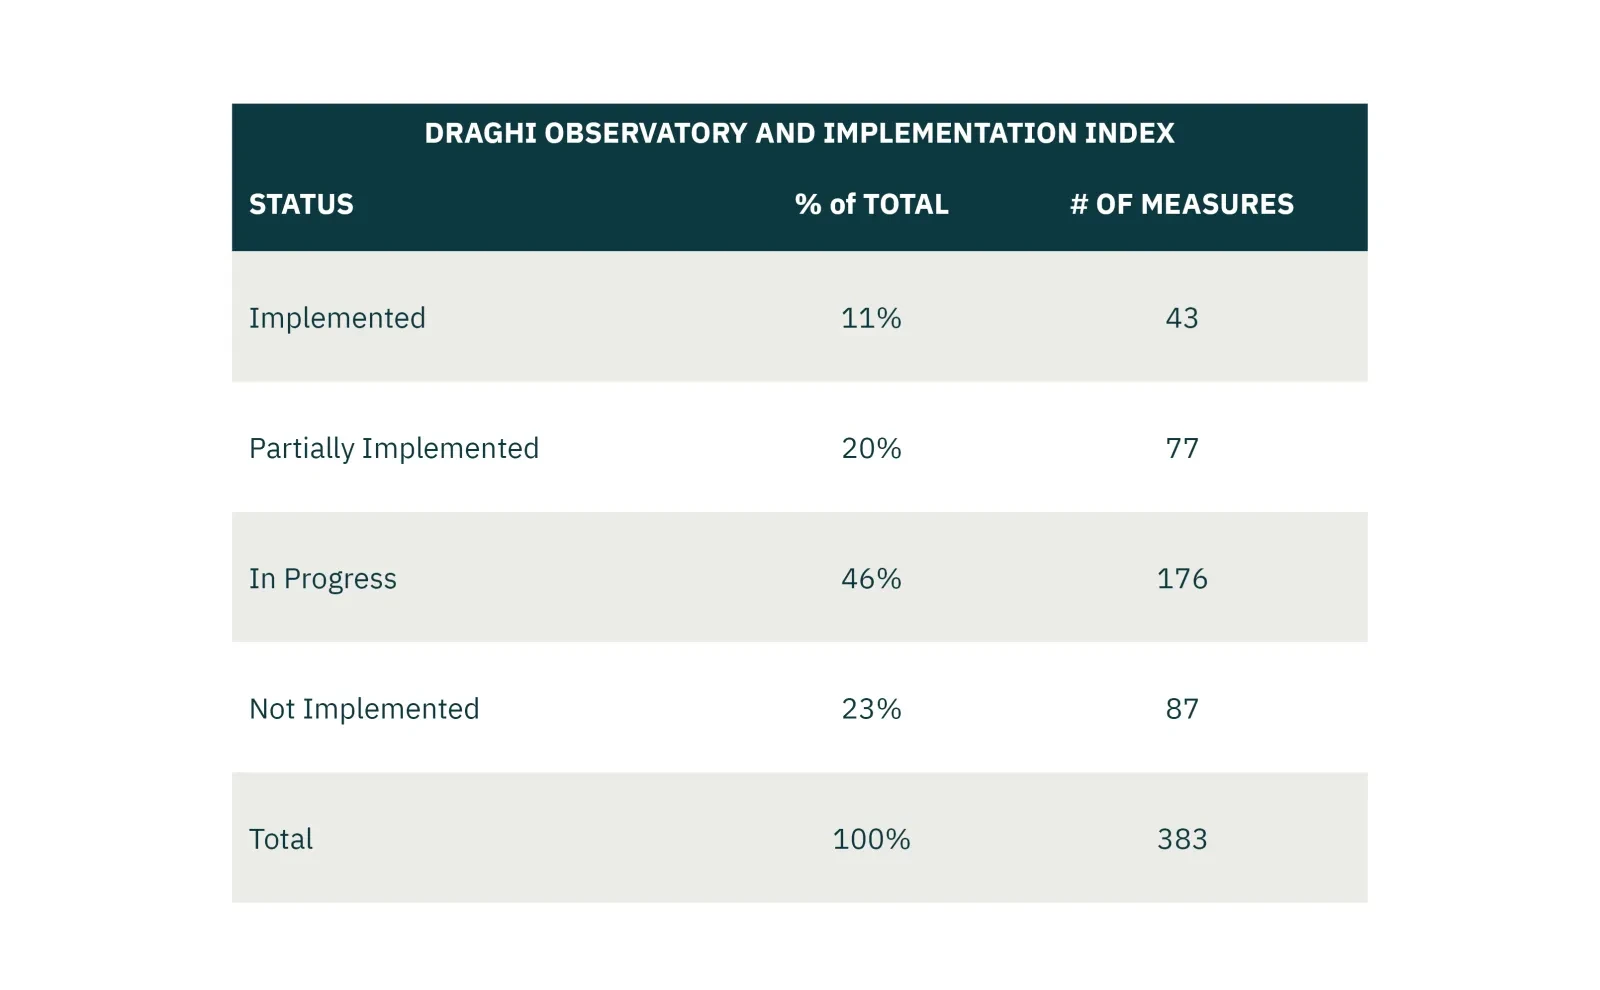
One year in, the EU is progressing slowly in implementing Mario Draghi's recommendations to restore Europe’s competitiveness. The lack of progress is due more to the various pushbacks from European capitals and the lack of proper funding than a lack of ambition. Our overall assessment remains positive, given the EU is adopting many of the priorities from Draghi’s report.
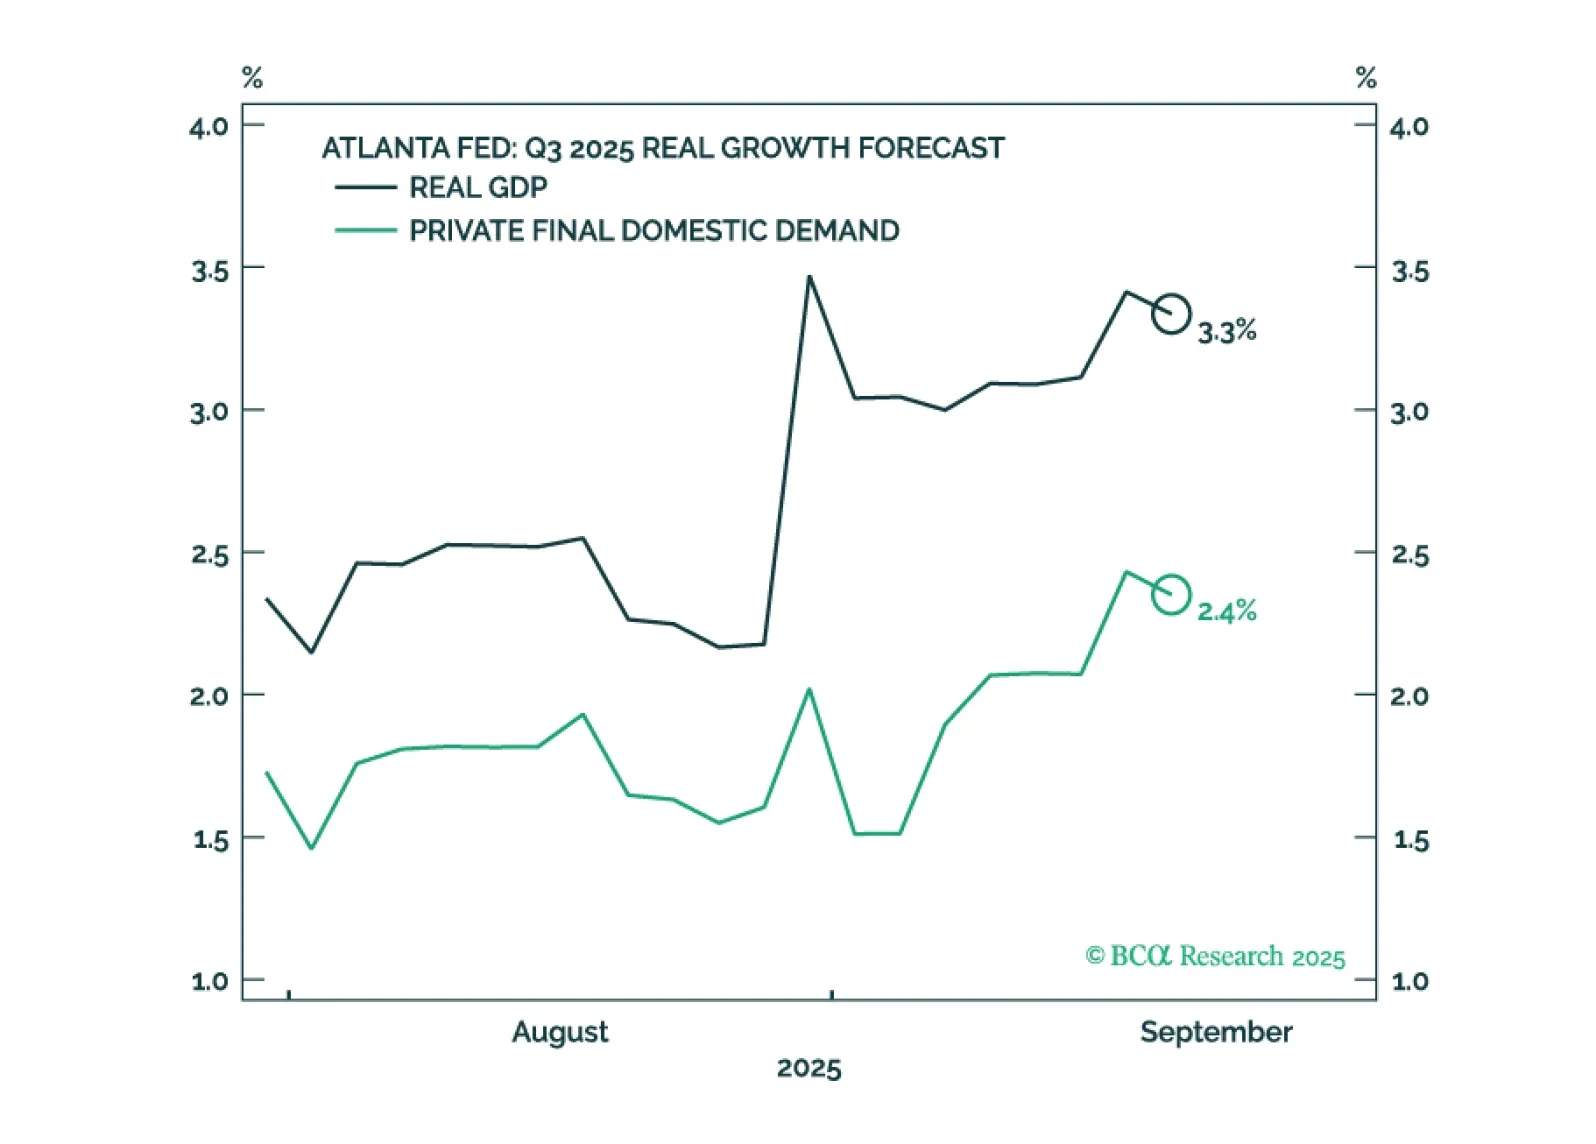
US GDP growth appears to have accelerated even as employment growth has faltered. We will make a final decision in early October when we publish our next Strategy Outlook, but most likely, we will cut our 12-month US recession probability to 40%-to-50% from 60% and turn tactically neutral on stocks, while still retaining a modest equity underweight over a 12-month horizon.