 CoreMacro
BCA’s flagship global macro and investment strategy platform, helping investors anticipate regime shifts, connect signals across regions and asset classes, and navigate the world’s most difficult macro questions.
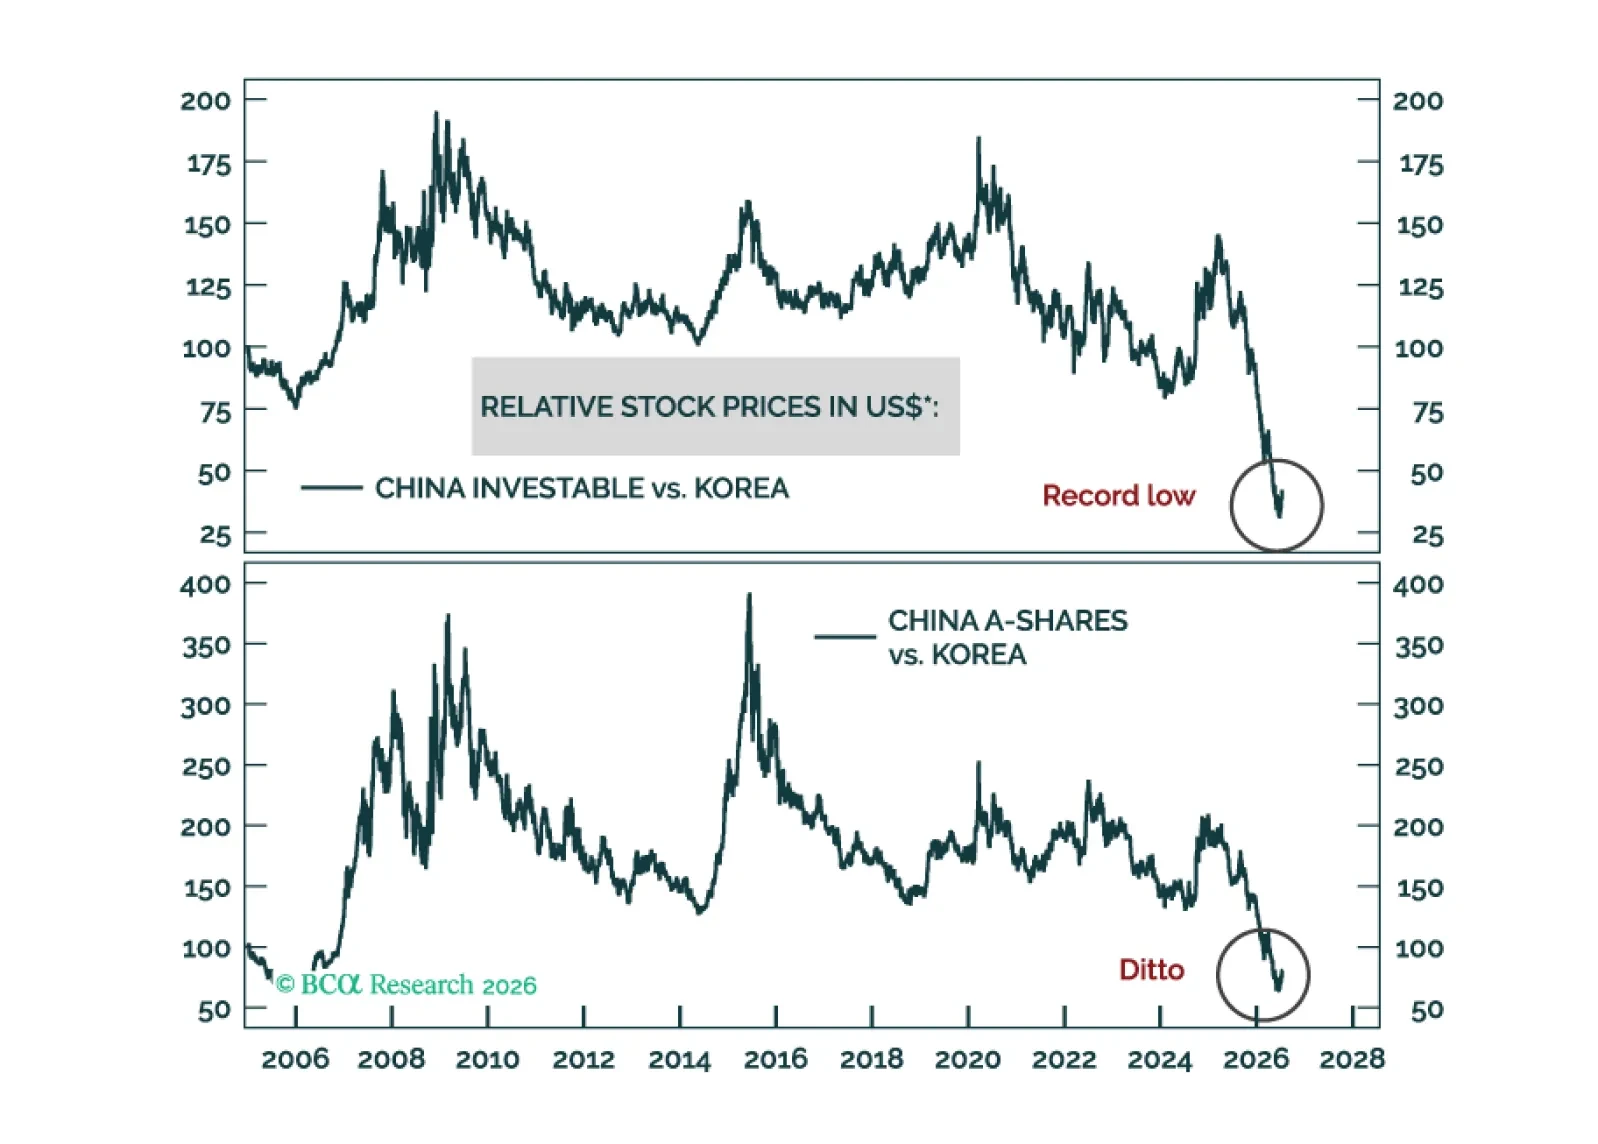
As a short-term (0-3 months) trade, go long an equal-weighted basket of Chinese Investable and A-shares / short the KOSPI. This is a bet on mean reversion. We do not recommend that medium- and long-term investors implement this strategy.
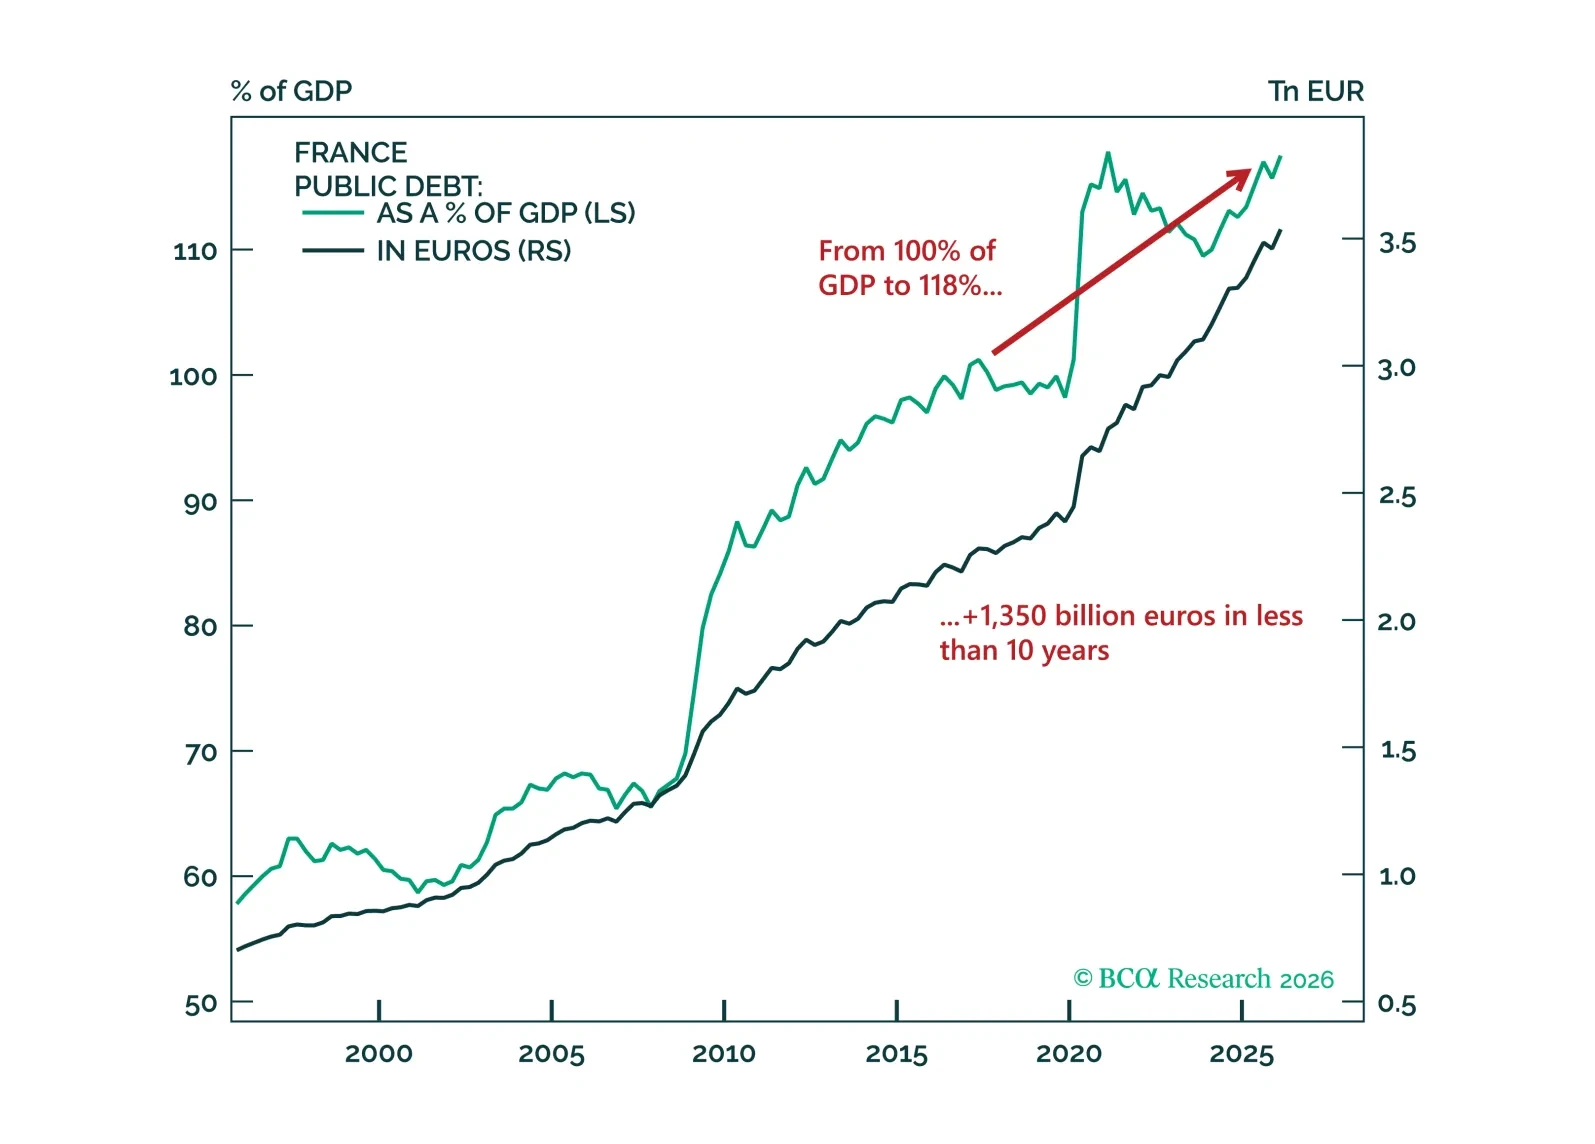
We wish all our French clients Bonne Fête Nationale! The rest of the world knows the holiday by its other name, Bastille Day. It is fitting, therefore, that we publish today GeoMacro Beta report on the coming political earthquake in France.
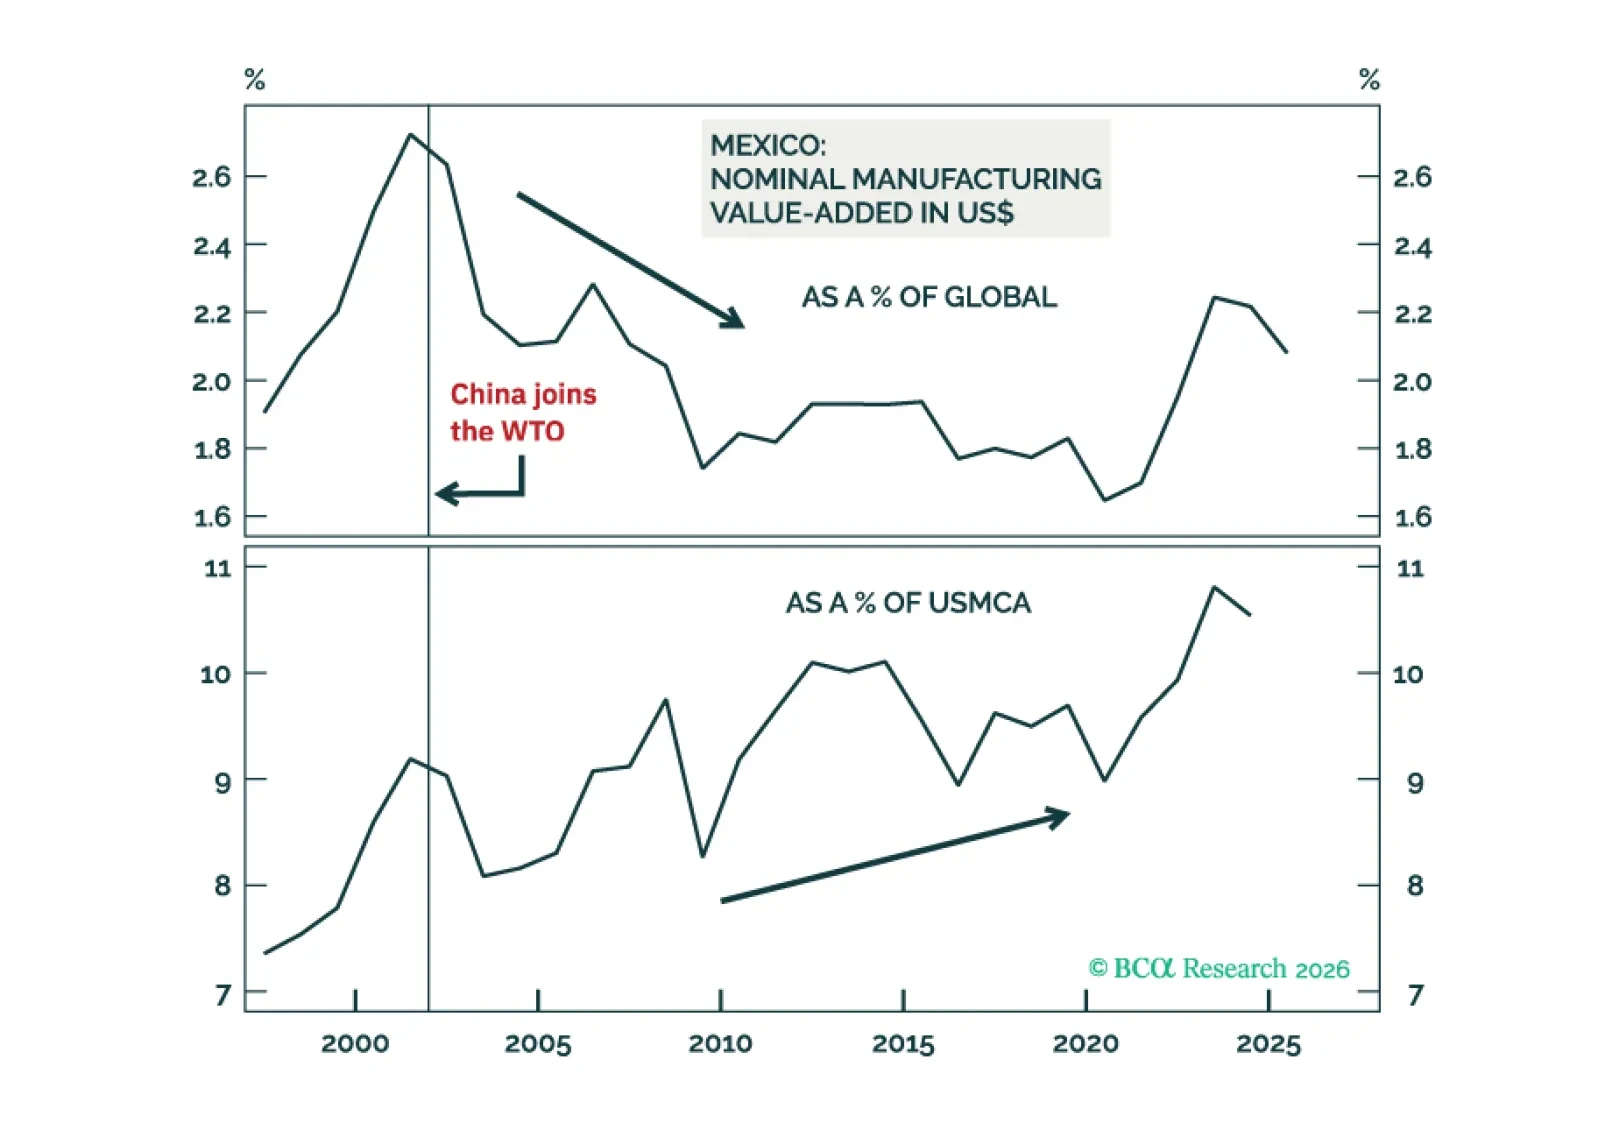
We continue to overweight Mexican stocks, local bonds, sovereign credit, and currency within their respective EM portfolios. Also, stay long Mexican equities / short the S&P500.
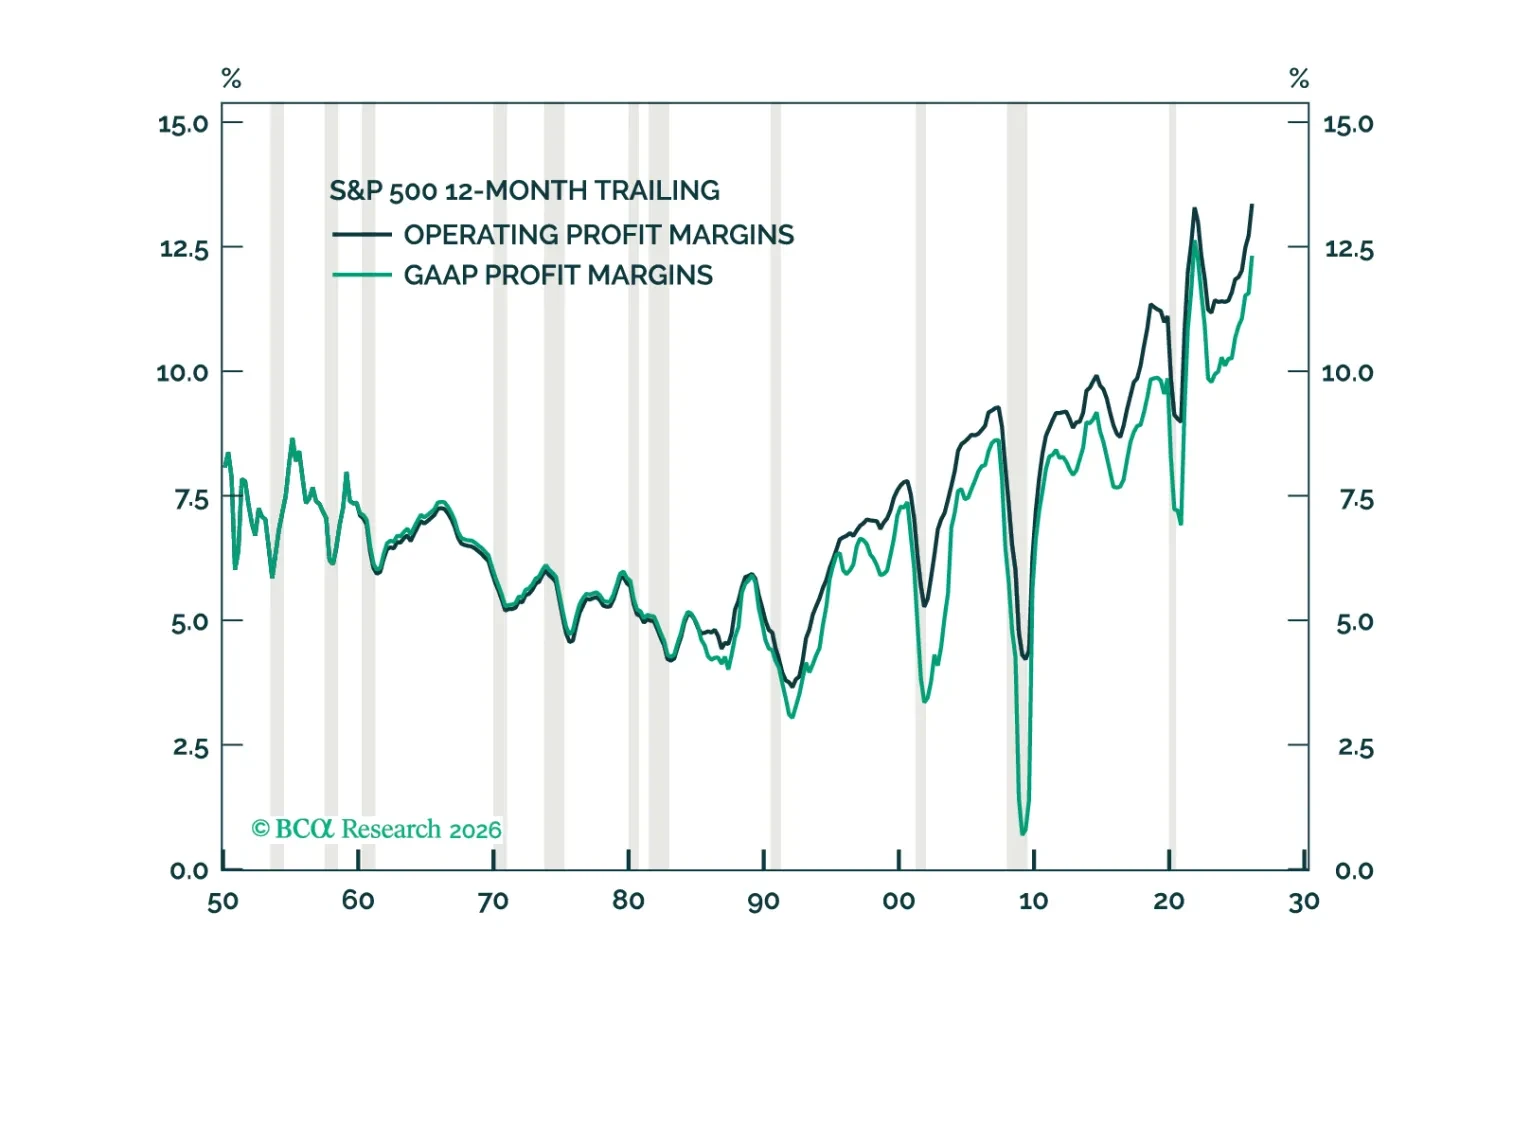
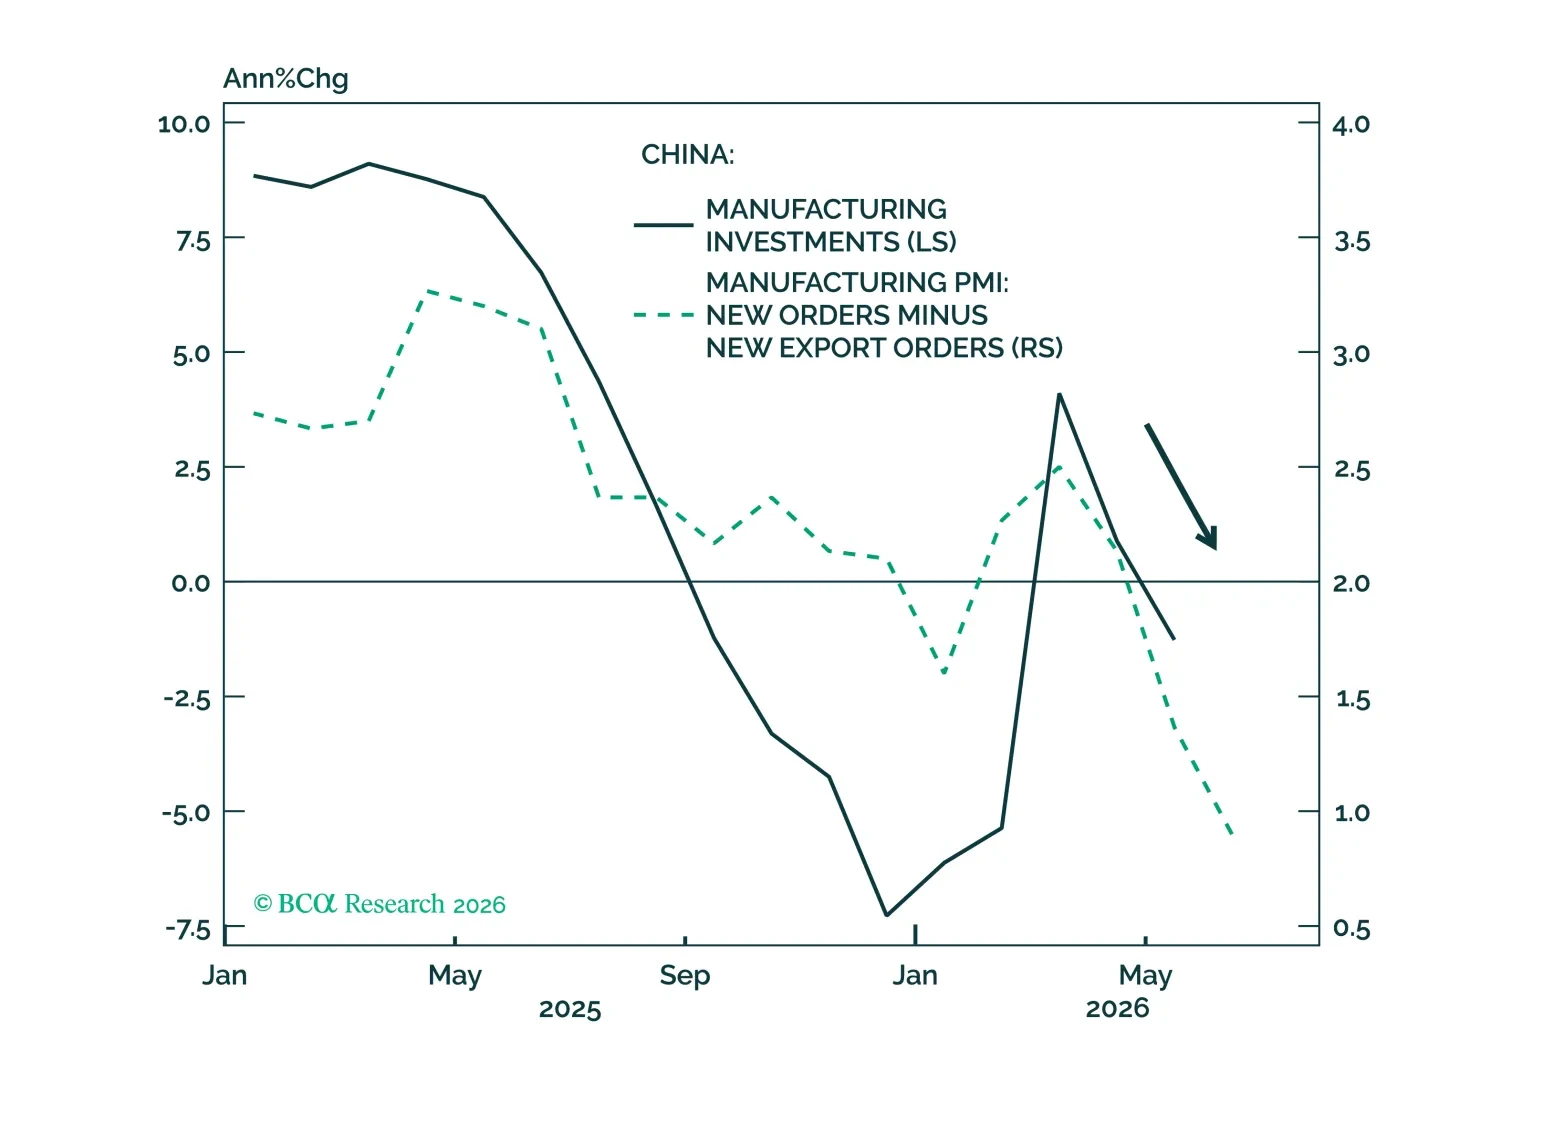
The rebound in China's producer prices and profits this year owes more to external demand than to meaningful progress under Beijing's anti-involution campaign.
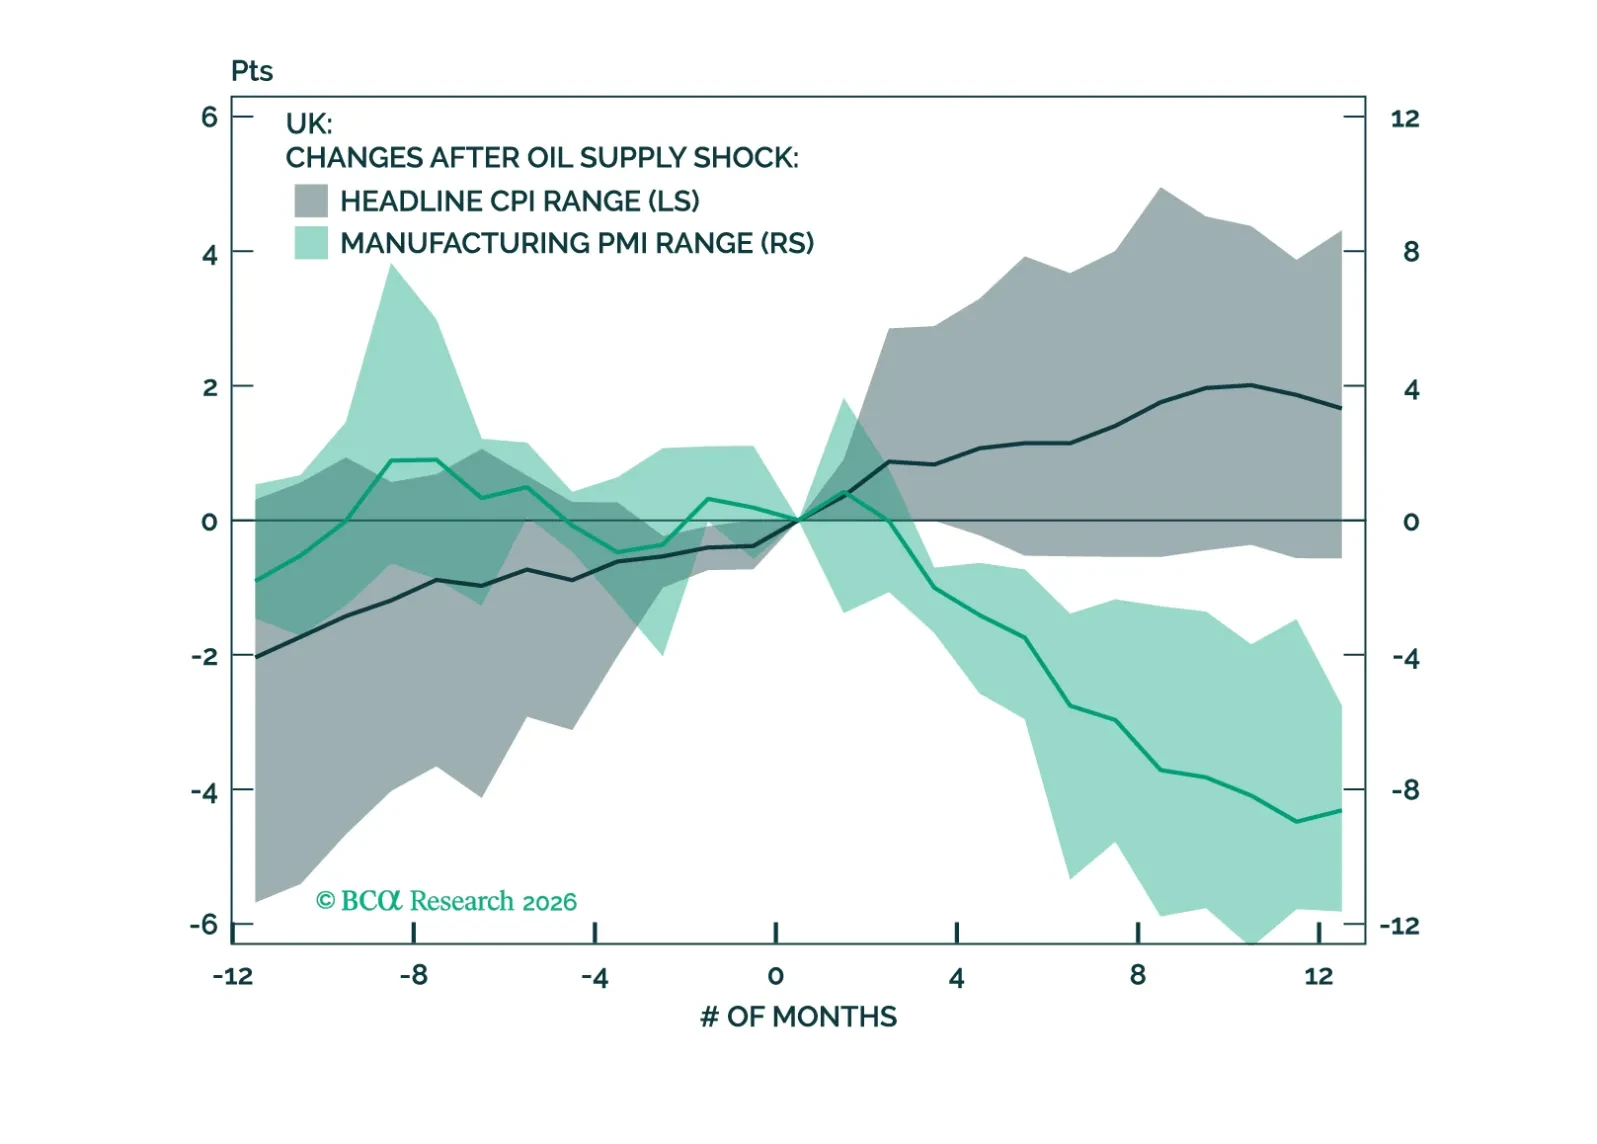
The UK economy is becoming increasingly fragile, but the investment outlook is improving. Slower growth and a more dovish BoE will support gilts, while UK equities will likely benefit from a favorable sector mix and a weaker pound.
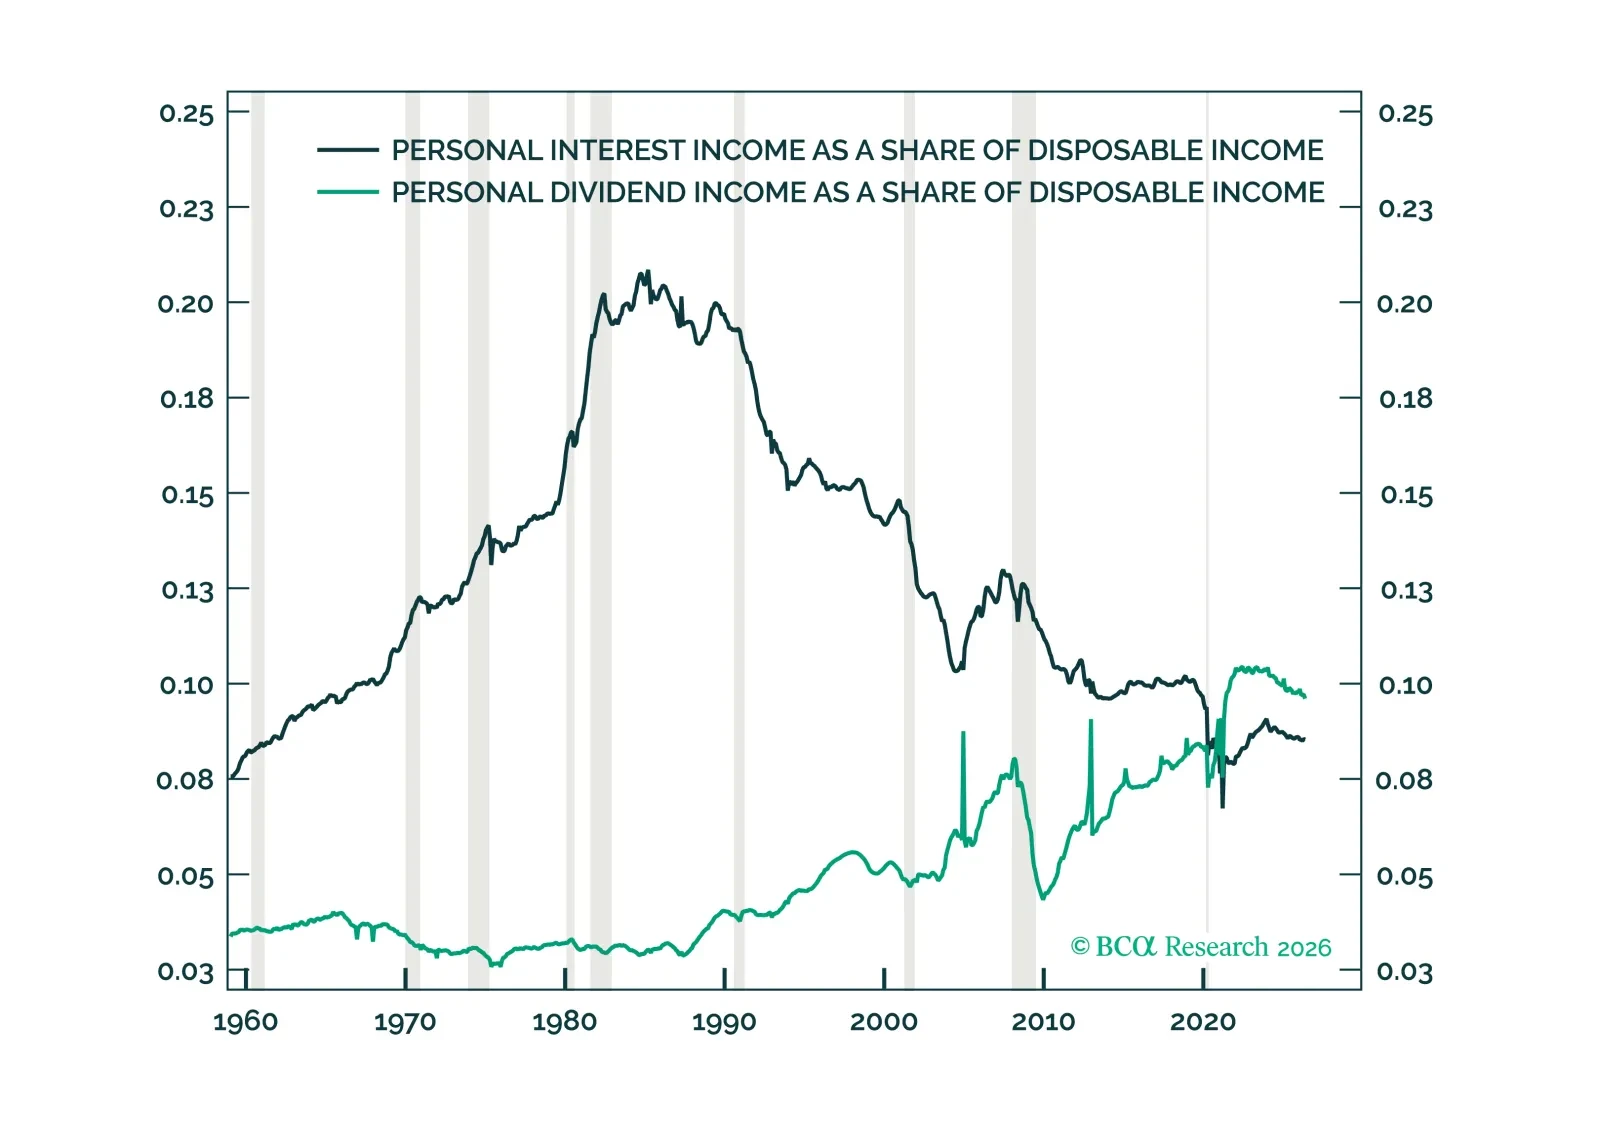
We are increasingly being asked if higher for longer interest rates could help spur consumption by boosting interest income. This report examines household income and balance sheet data to see if they might.
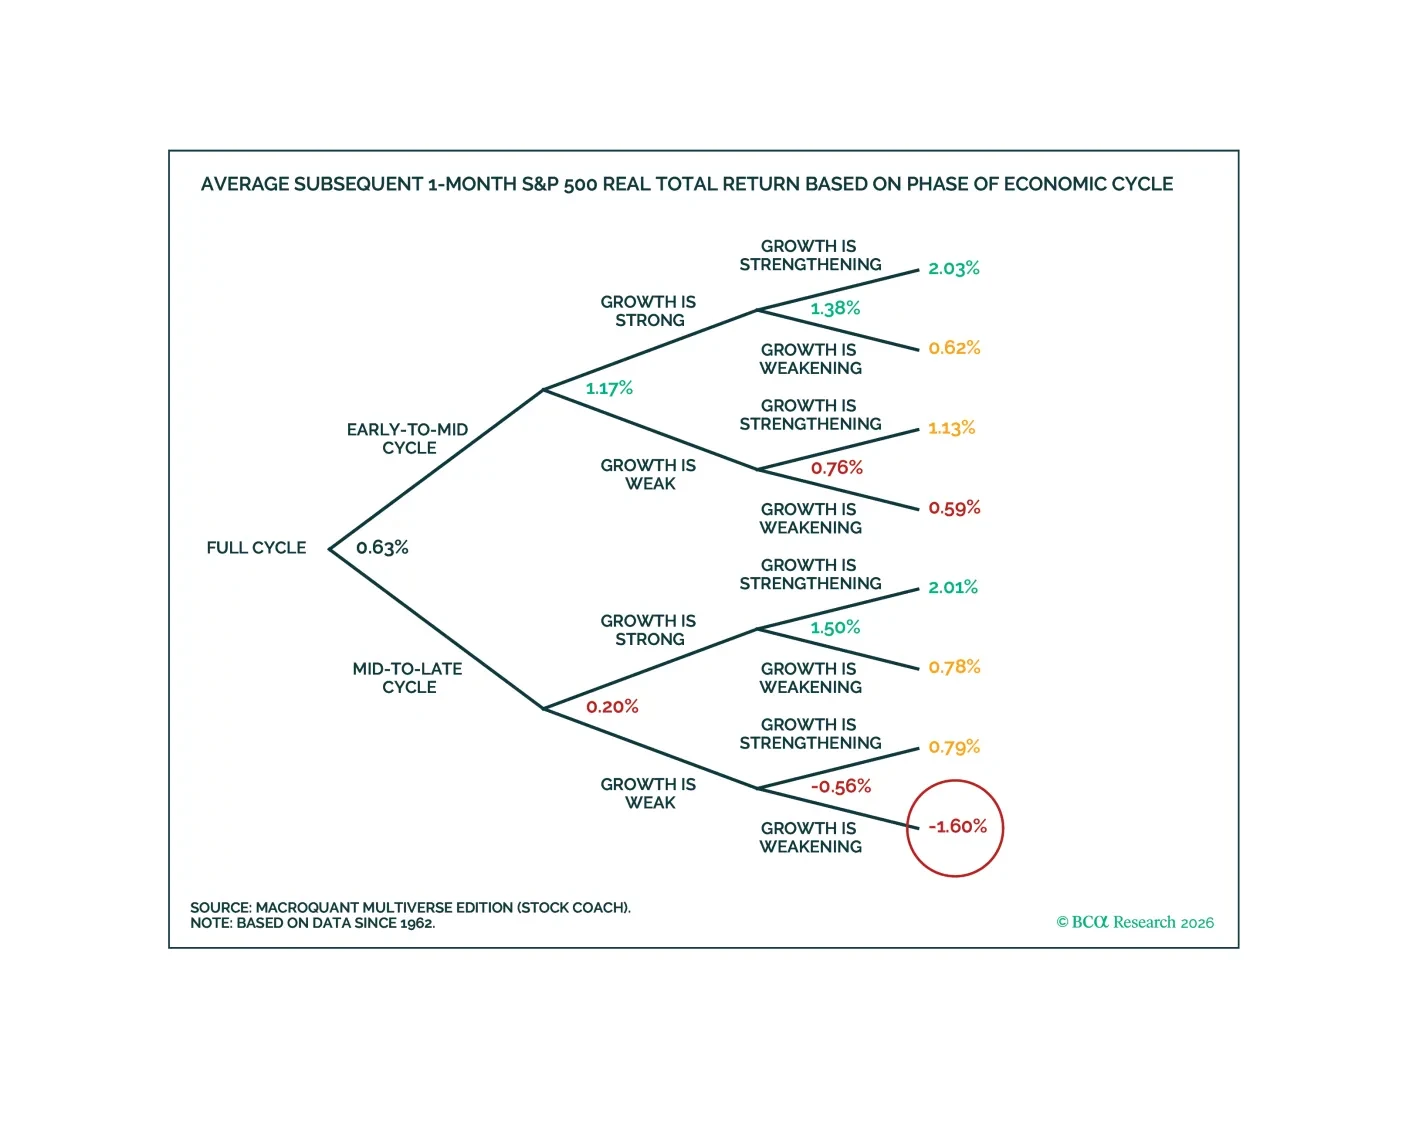
MacroQuant recommends underweighting equities and adopting a benchmark duration stance in fixed-income portfolios. The model is very positive on the US dollar, bearish on gold, neutral on copper, and bullish on oil.