 CoreMacro
BCA’s flagship global macro and investment strategy platform, helping investors anticipate regime shifts, connect signals across regions and asset classes, and navigate the world’s most difficult macro questions.
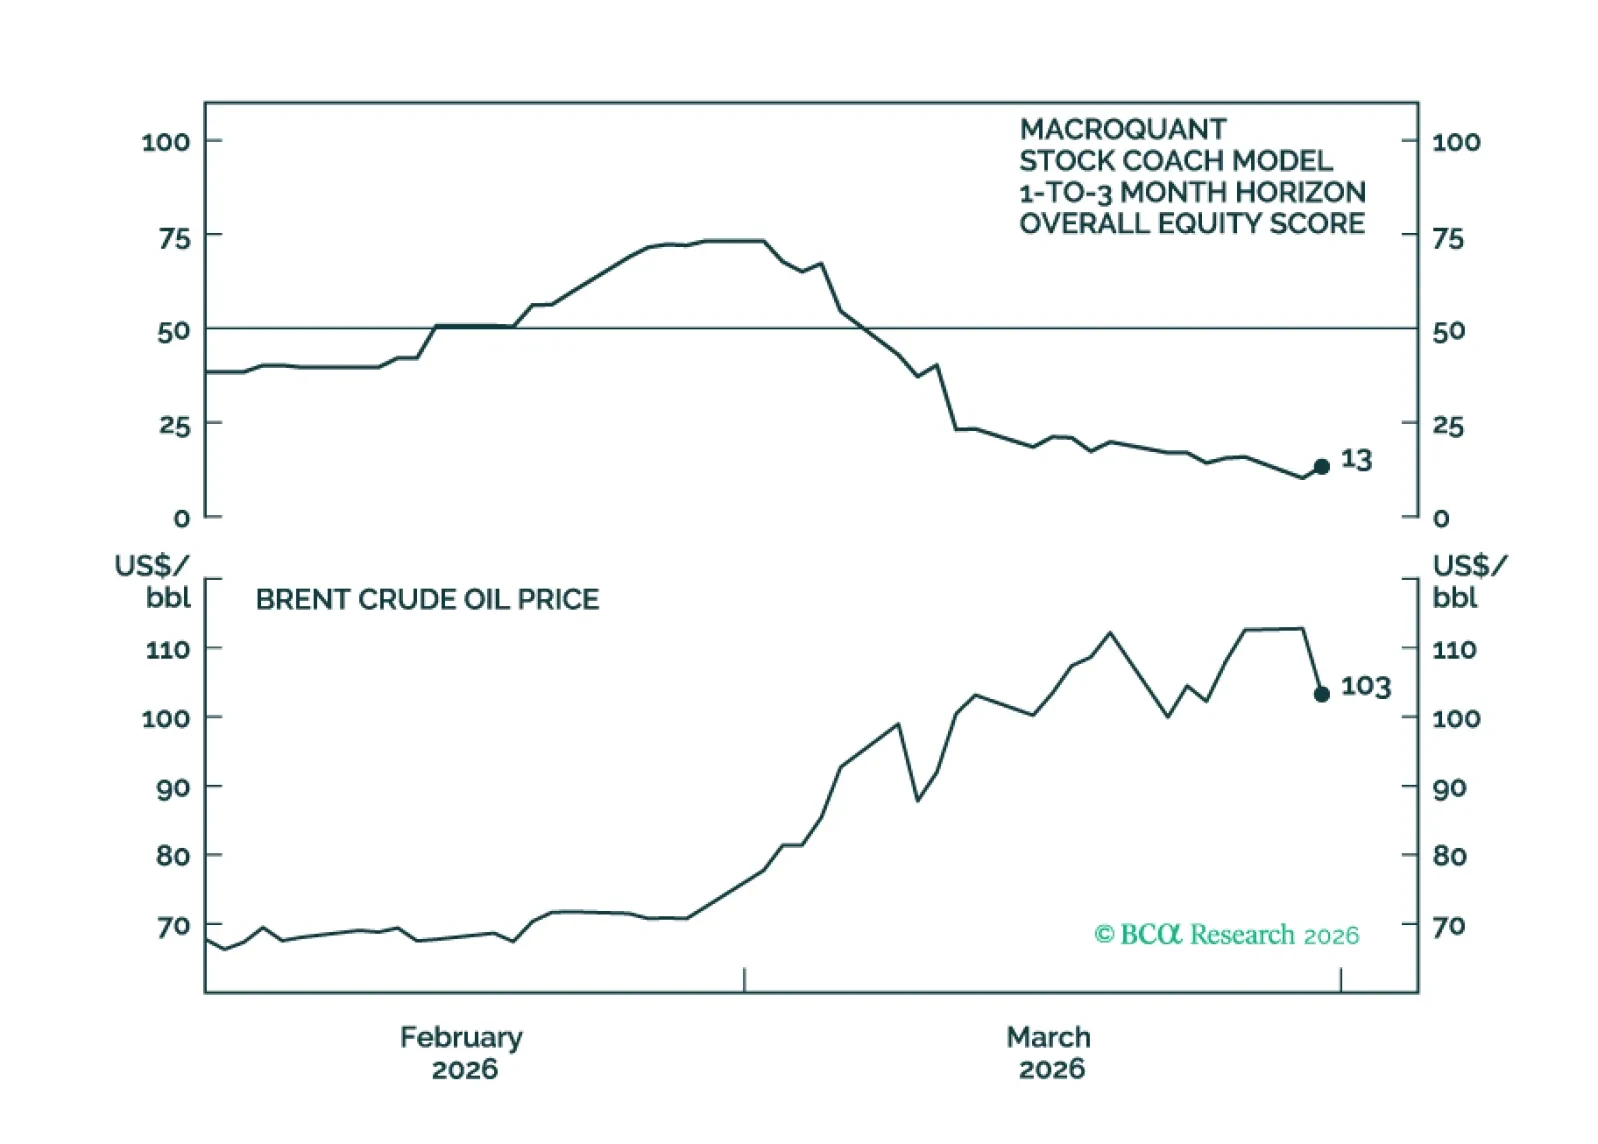
MacroQuant recommends a strong underweight position in equities, favors a below-benchmark duration stance in fixed-income portfolios, has become neutral-to-slightly positive on the US dollar, has downgraded gold to neutral and copper to a strong underweight, and is bullish on oil.
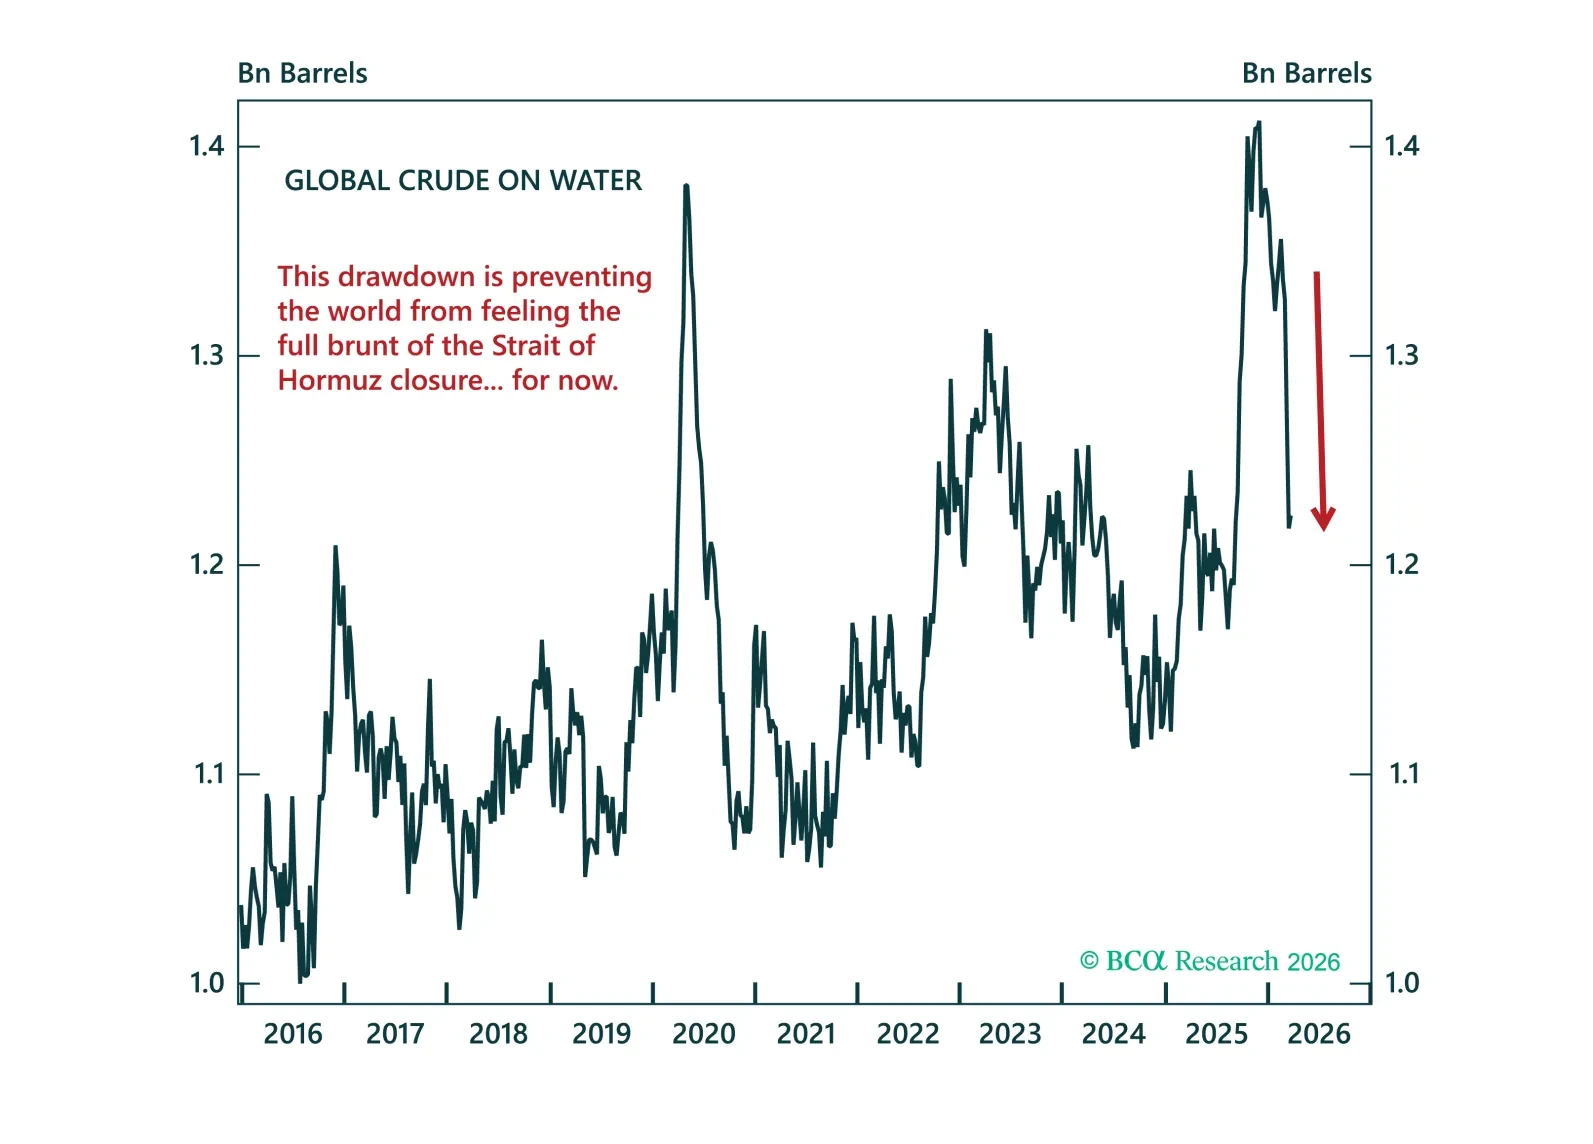
We are pleased to introduce our new Quarterly Investment Outlook, a joint publication bringing together the European Investment Strategy (EIS), Global Fixed Income Strategy (GFIS), and Foreign Exchange Strategy teams. The main takeaway of the current edition is that investors should not add risk. Markets are still focused on inflation, but the binding constraint is growth: if the energy shock persists into mid-April, a rapid shift toward recession pricing will follow.
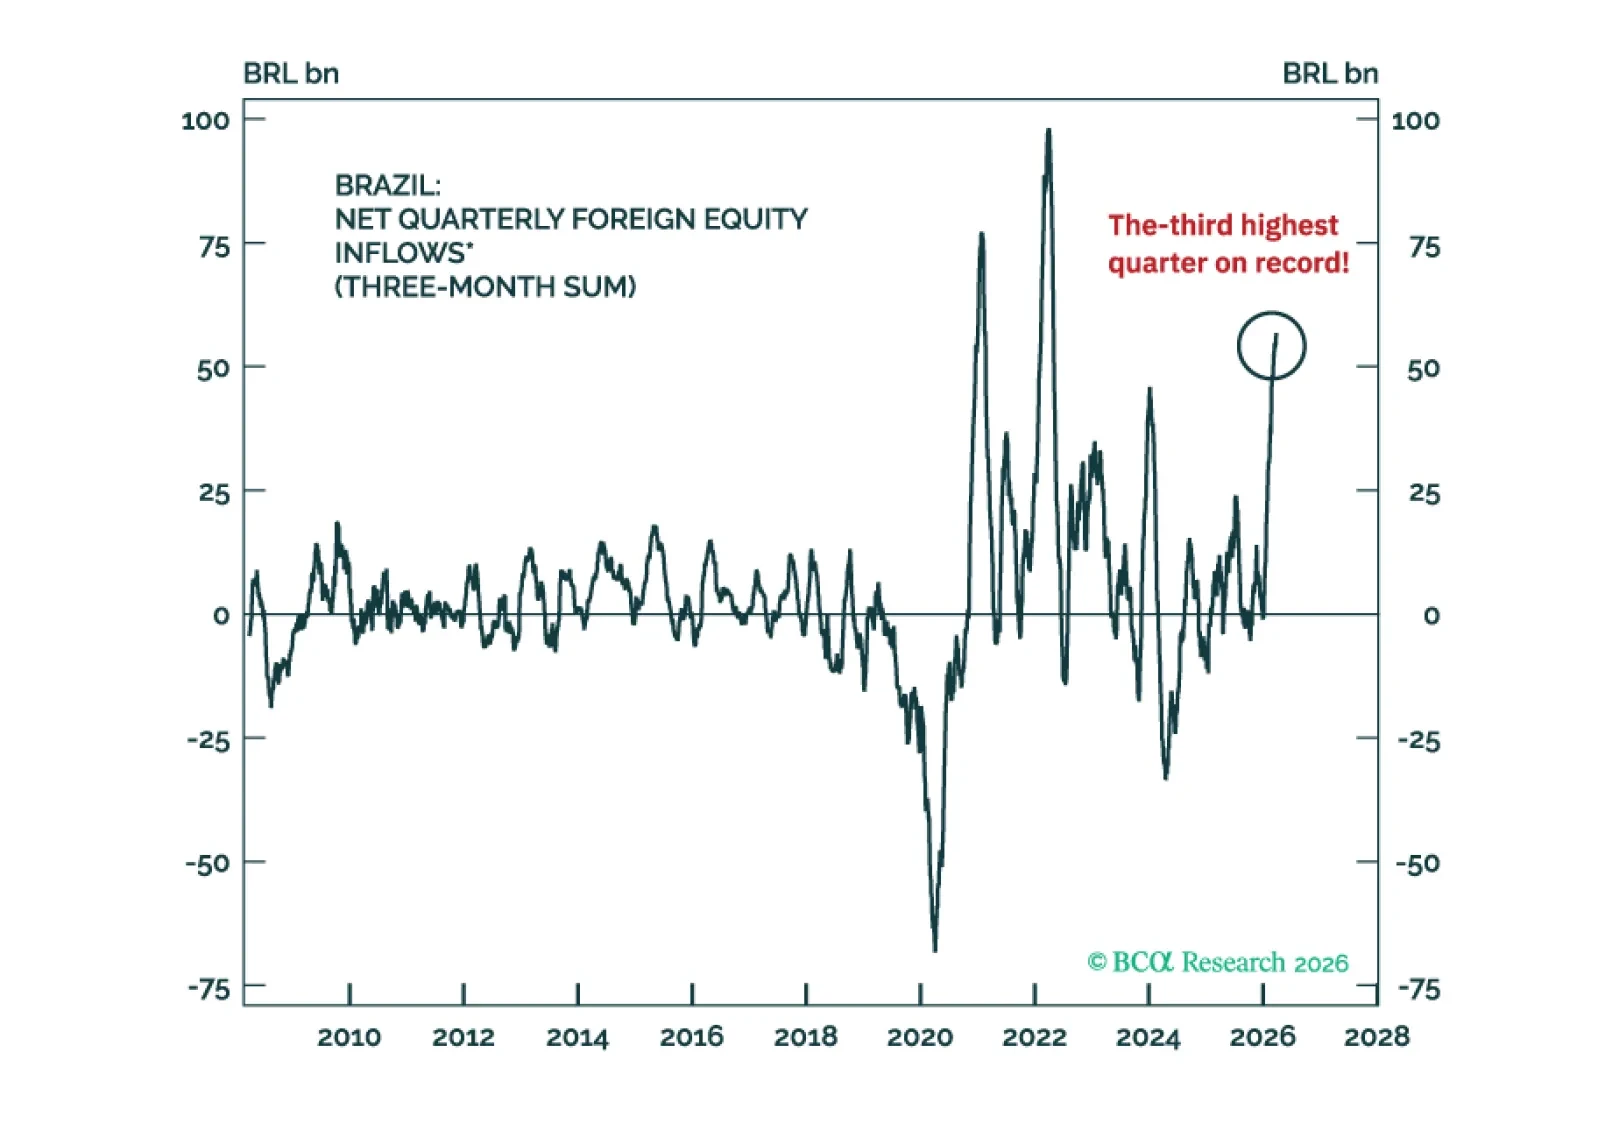
Overstretched foreign inflows into Brazilian markets will reverse, while soaring oil prices will not benefit Brazil in the near term. Avoid the country’s risk assets and the BRL, and stay underweight Brazilian equities and fixed income relative to EM. We also recommend paying 10-year Brazilian swap rates.

One month into the Iranian conflict, we take stock of how markets have moved so far and how some of the big open questions might influence them going forward. A long opportunity may be developing at the long end of the Treasury curve.
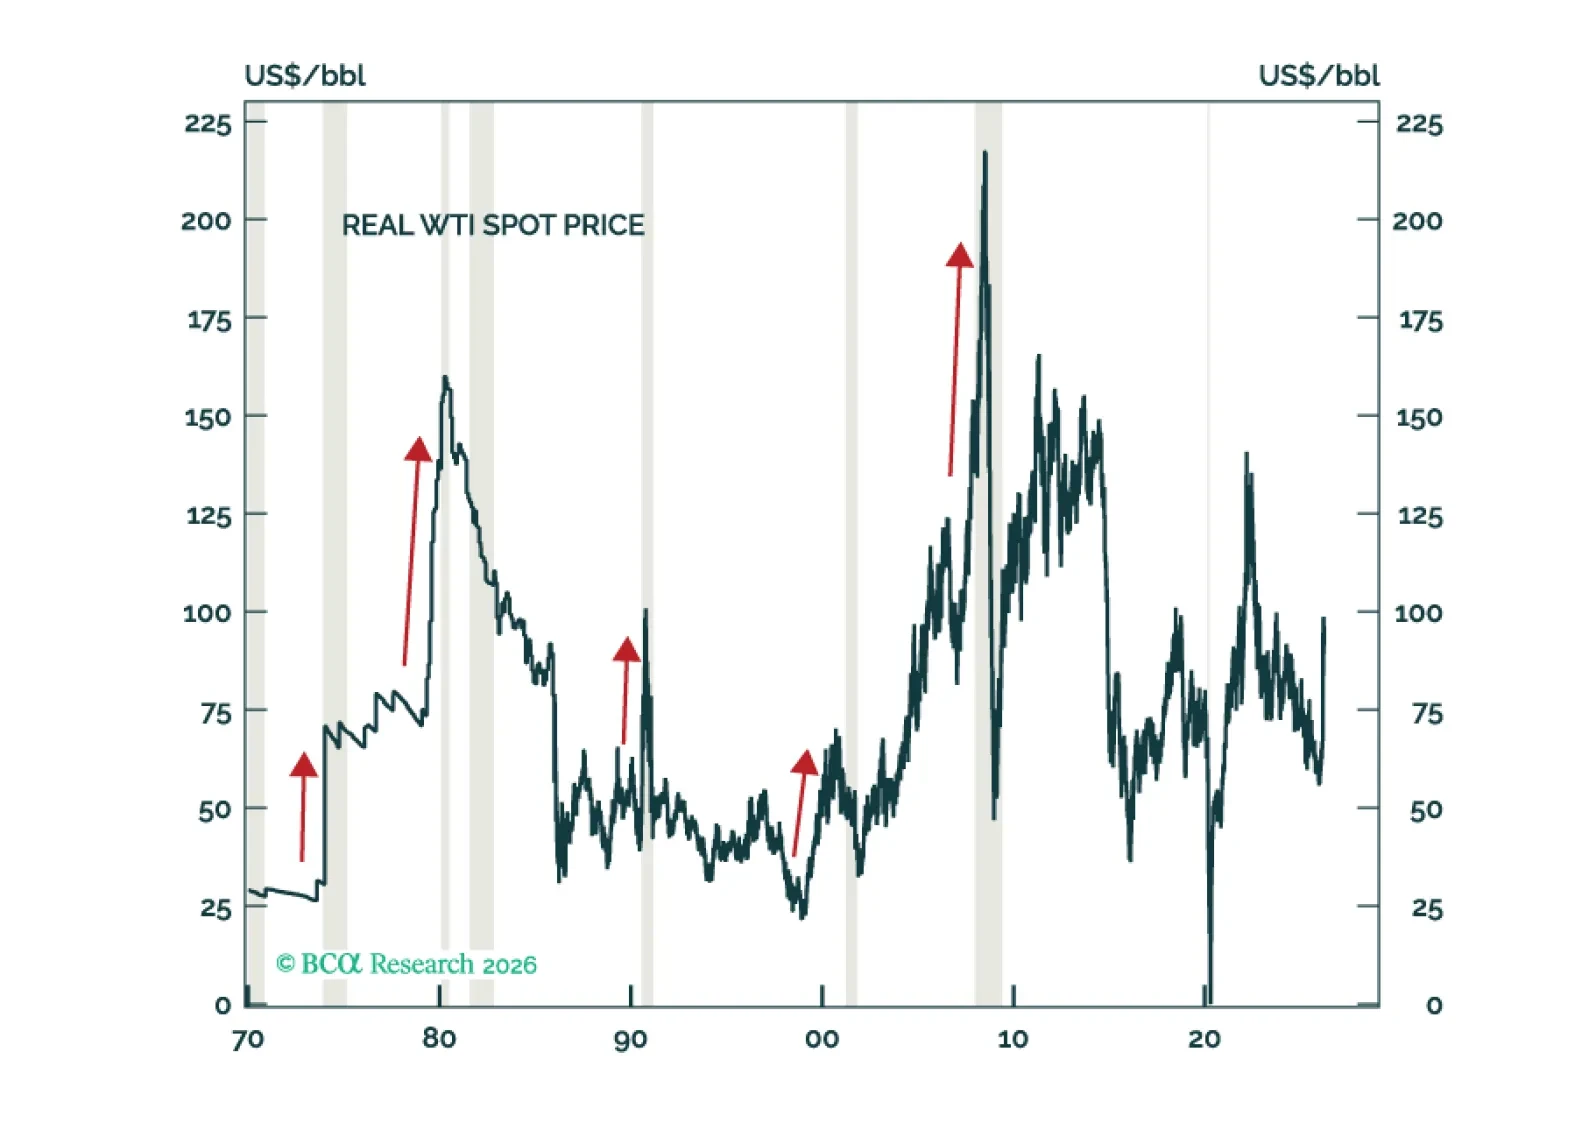
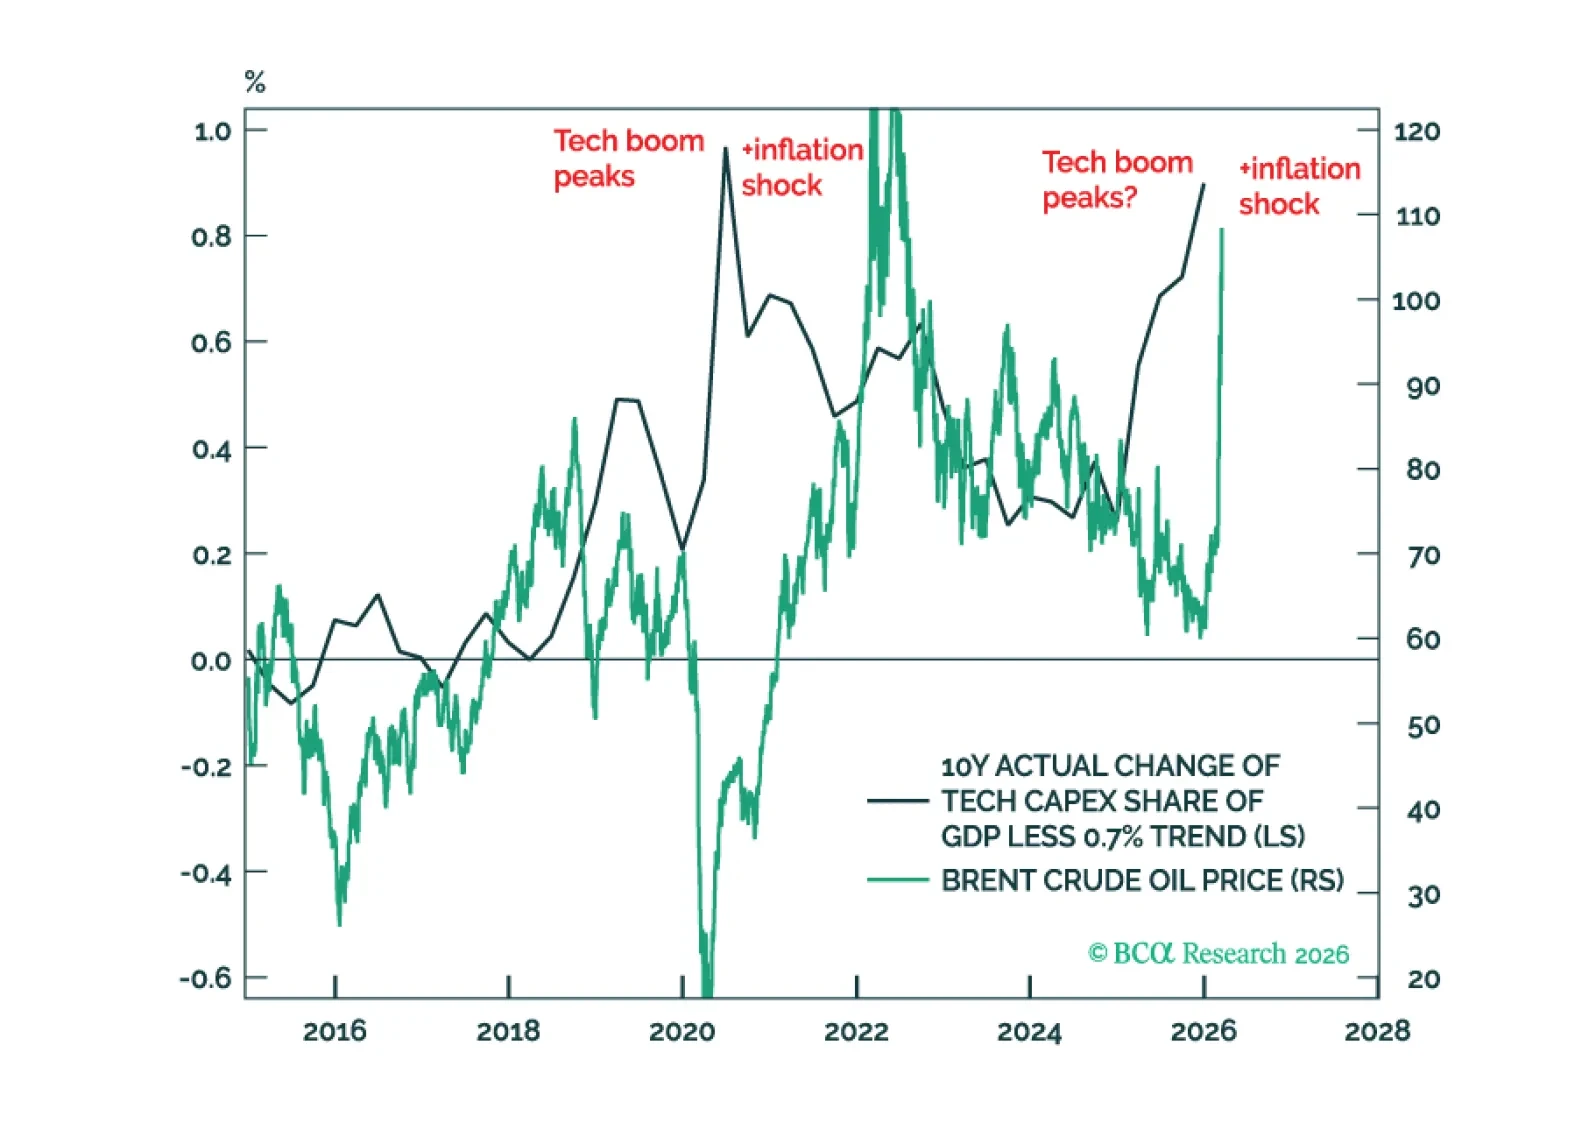
The current macro environment is a toxic brew of many of the same vulnerabilities that haunted the global economy in the lead-up to past recessions: Rising oil prices, an unsustainable tech capex boom, elevated equity valuations, excessively high homes prices, and brewing stresses in private credit and other parts of the financial system. While global equities look increasingly oversold in the very near term, they will still finish the year below current levels.
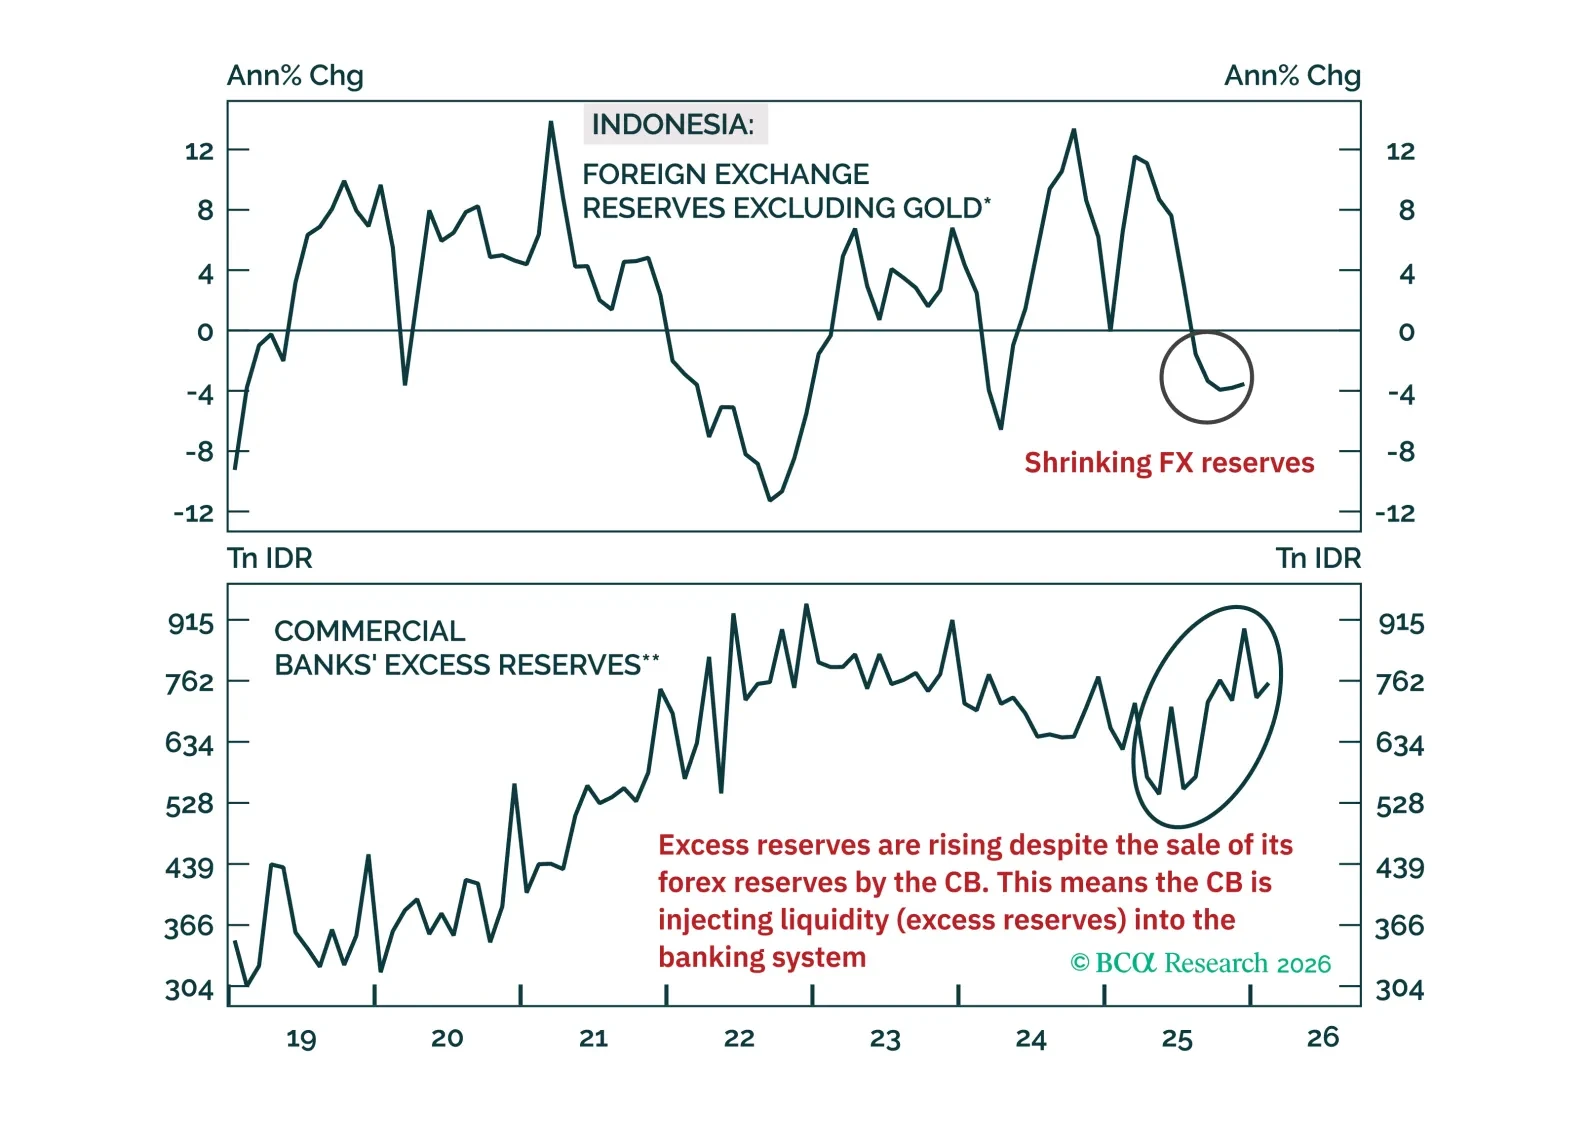
Indonesian rupiah will continue to plunge, and its local-currency bond yields will rise materially. Investors should short domestic bonds, currency unhedged.
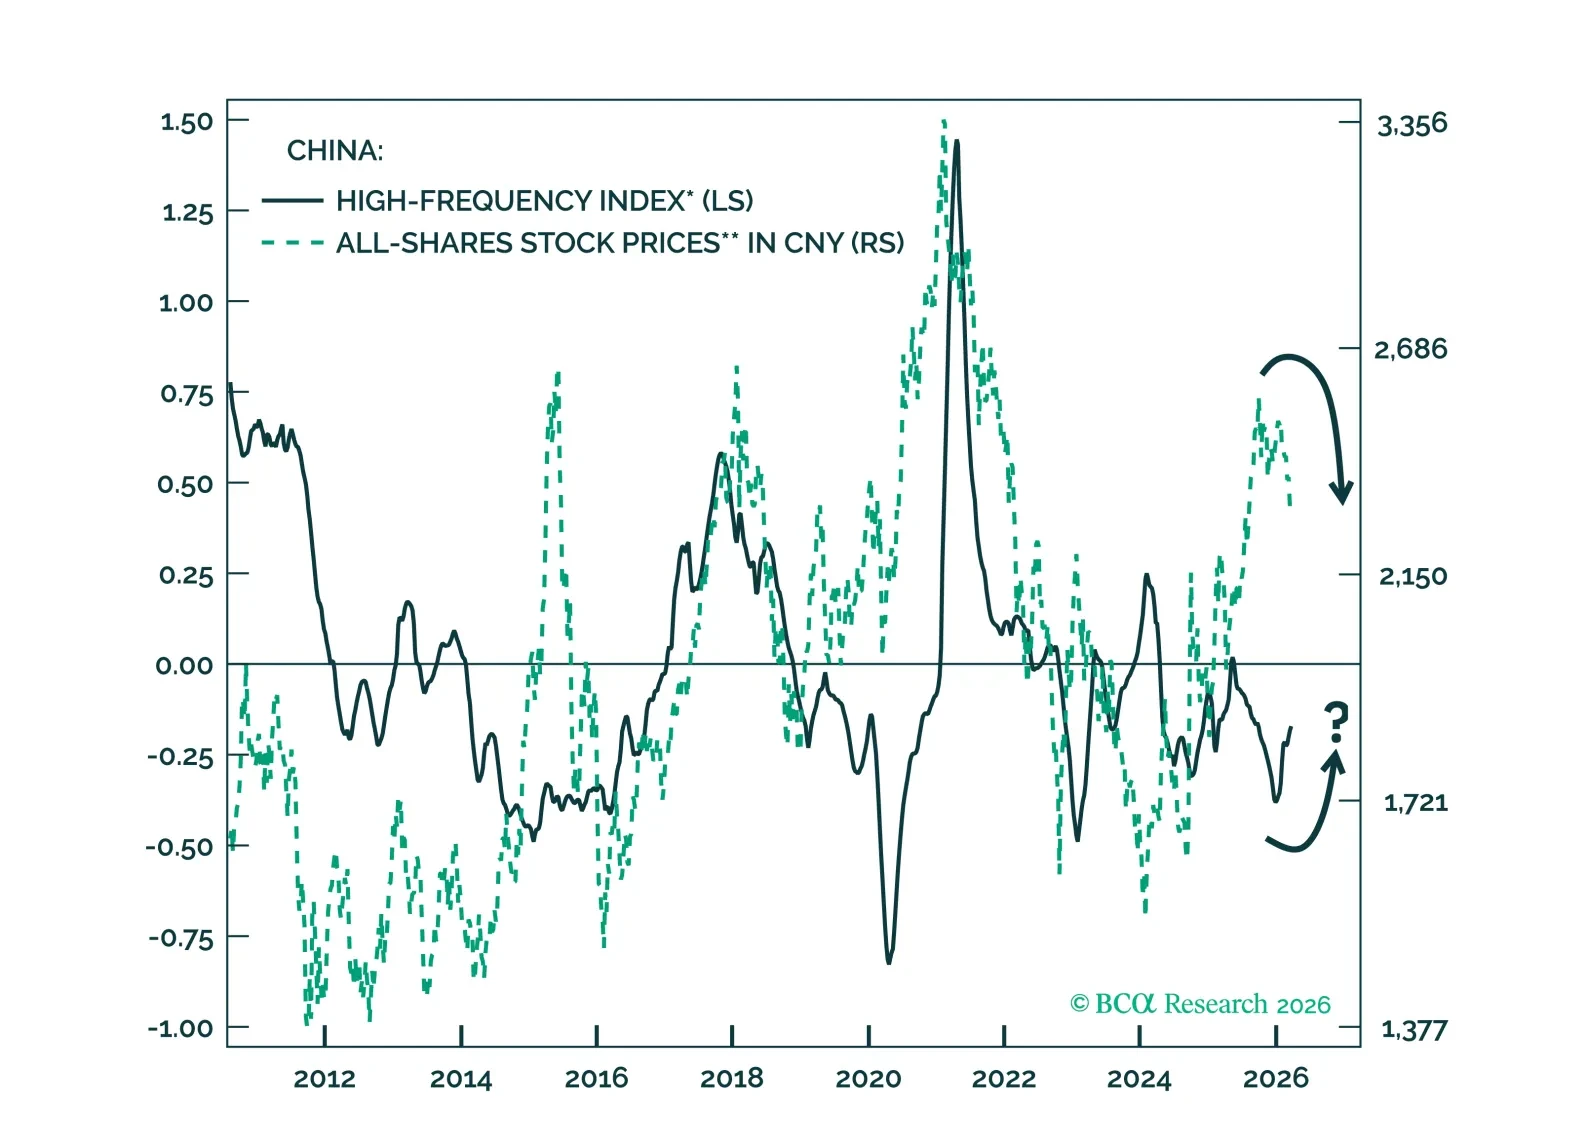
Chinese stock prices are converging with economic growth after a 2025 rally. While the country can endure a short-term oil price shock, it remains susceptible to extended supply disruptions and a global slowdown.
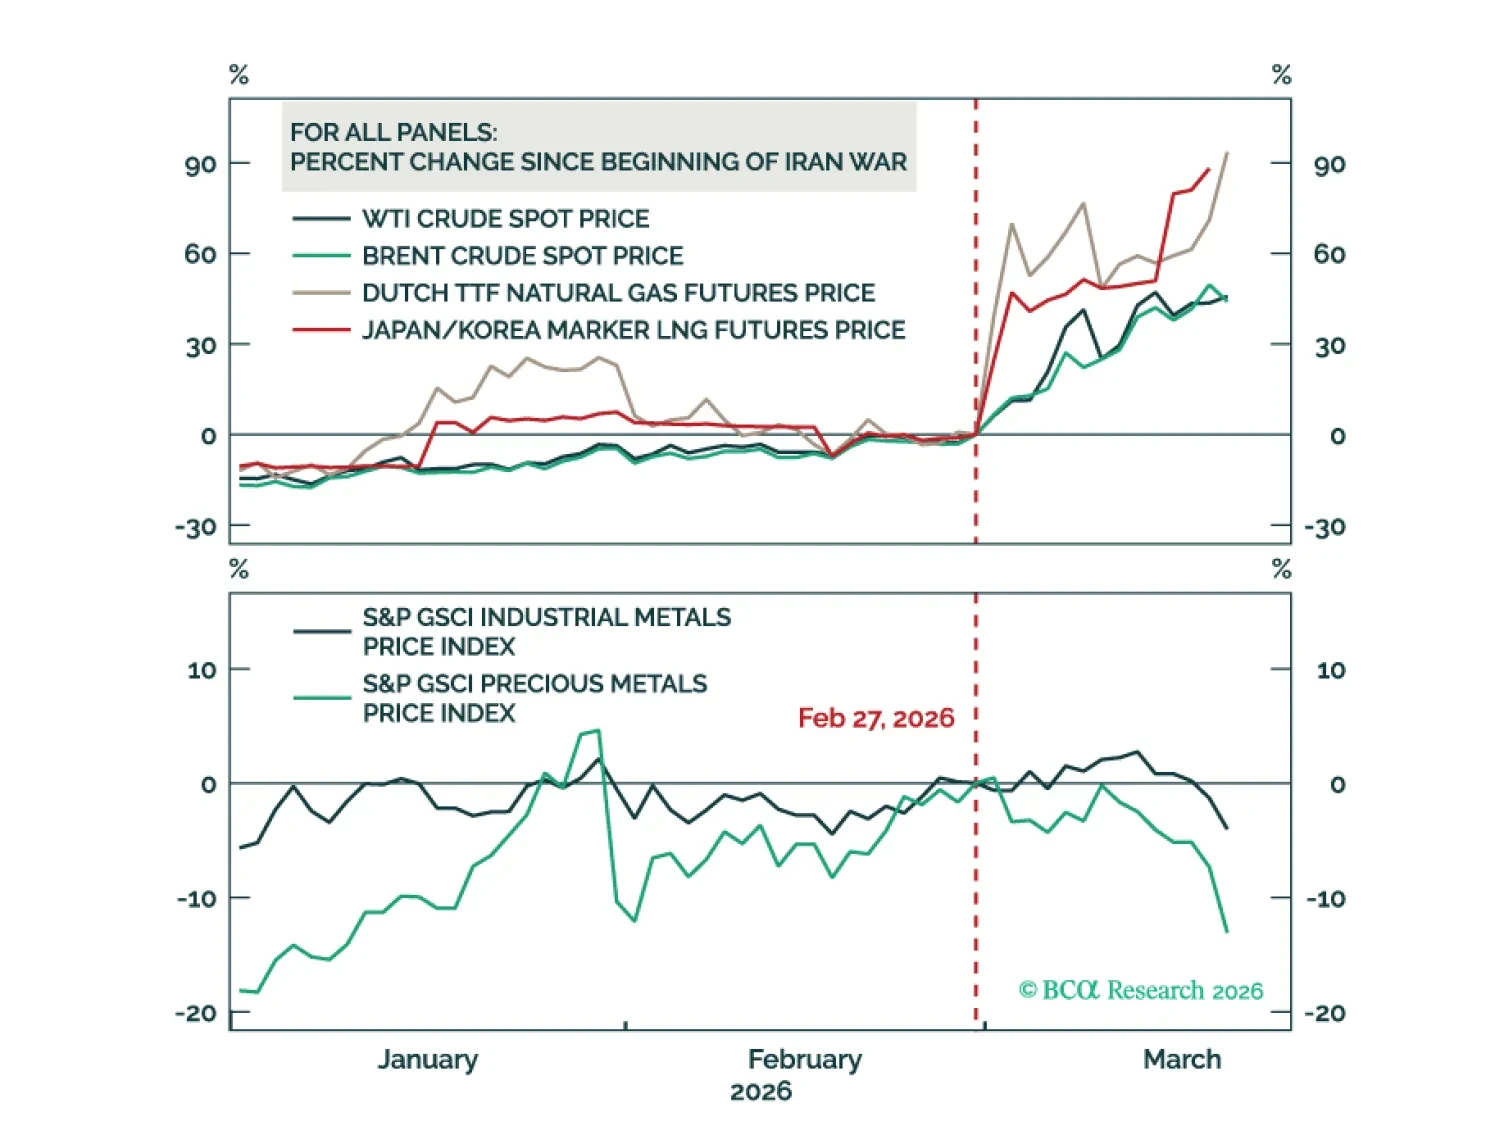
Higher oil prices threaten the global economy, warranting an underweight stance on equities. Over the long haul, industrial metals will fare better than crude.
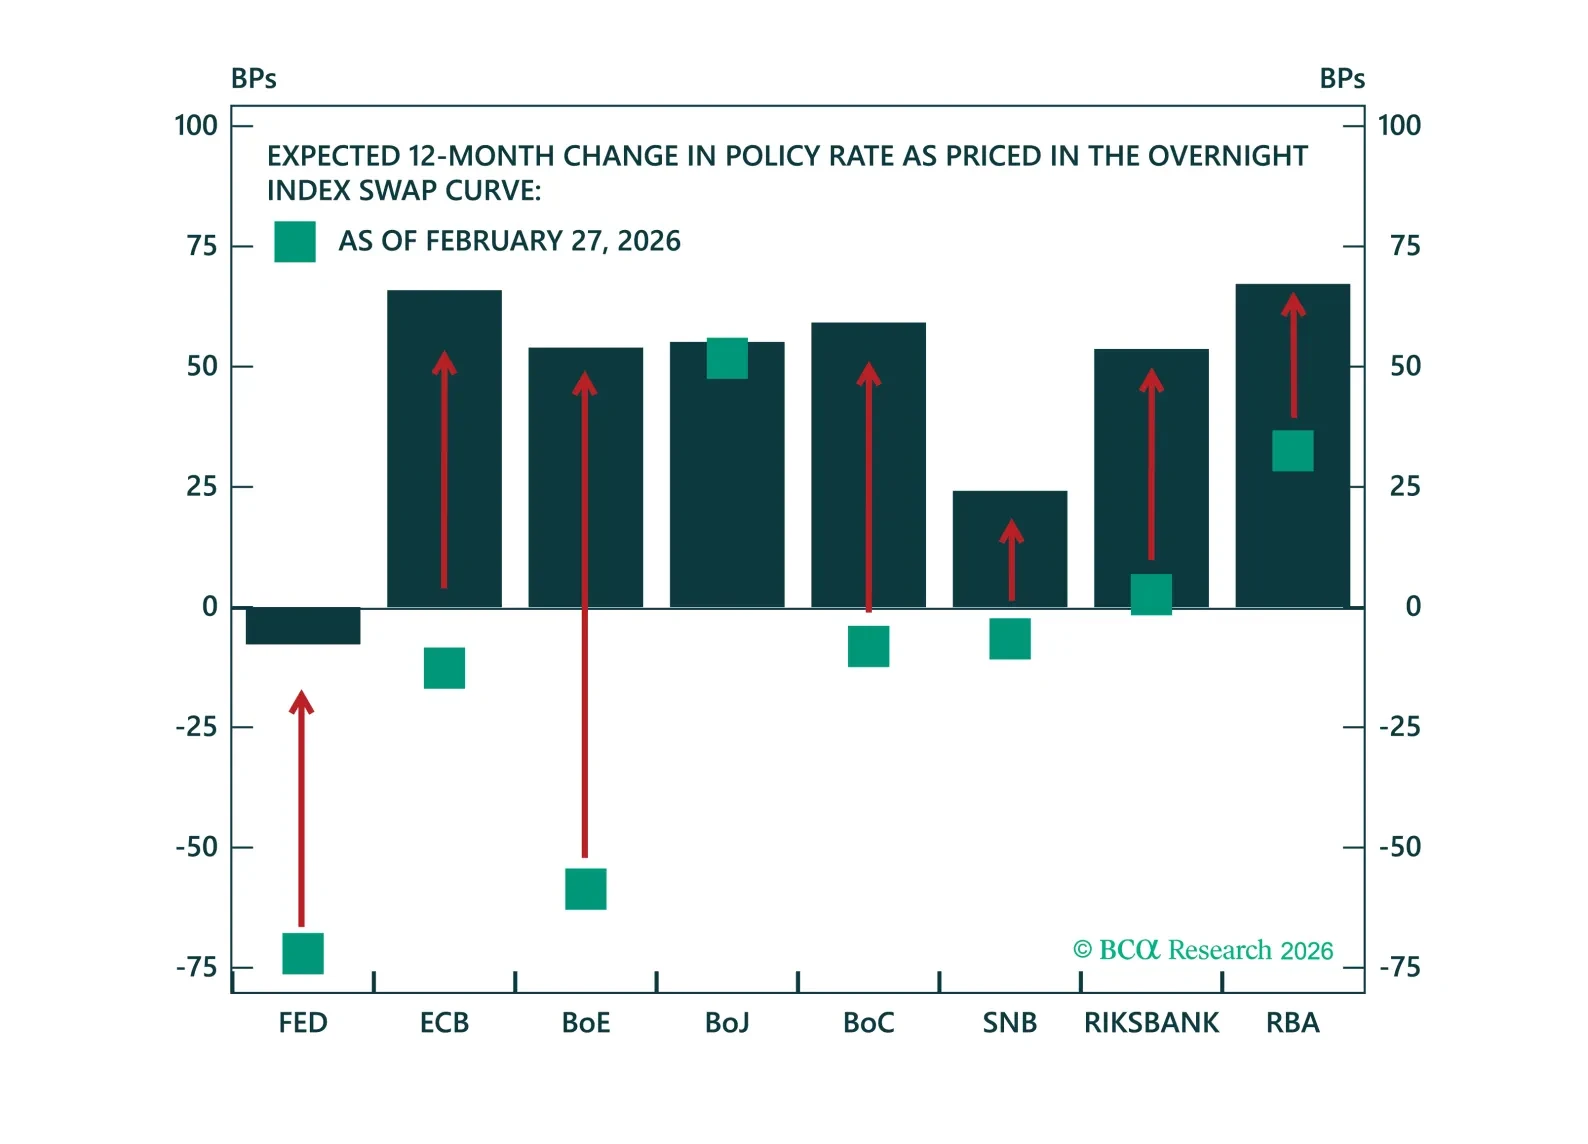
We discuss the takeaways from this week’s central bank meetings amidst the unfolding energy price shock.
Forced to choose between growth and inflation, the Fed will save growth and the stock market rather than the 2 percent inflation target and the bond market.