 CoreMacro
BCA’s flagship global macro and investment strategy platform, helping investors anticipate regime shifts, connect signals across regions and asset classes, and navigate the world’s most difficult macro questions.
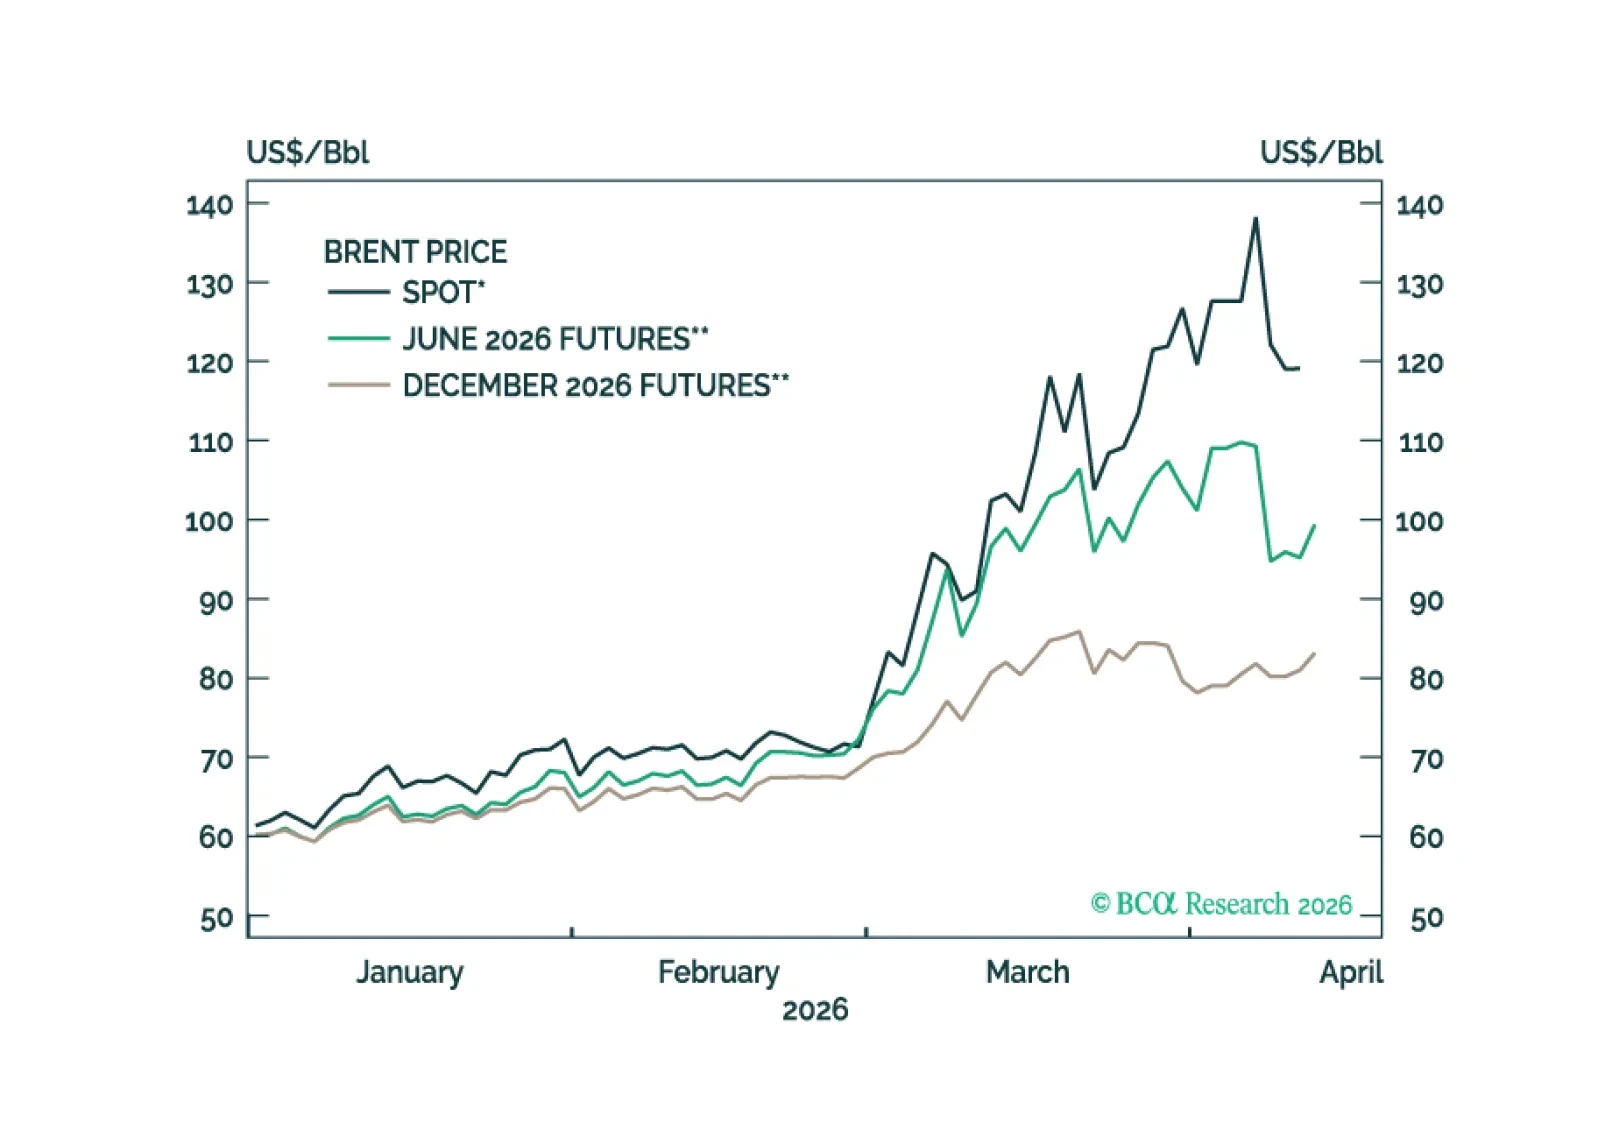
The main reason the oil shock has not caused stocks to crash is that investors do not expect the shock to last very long.
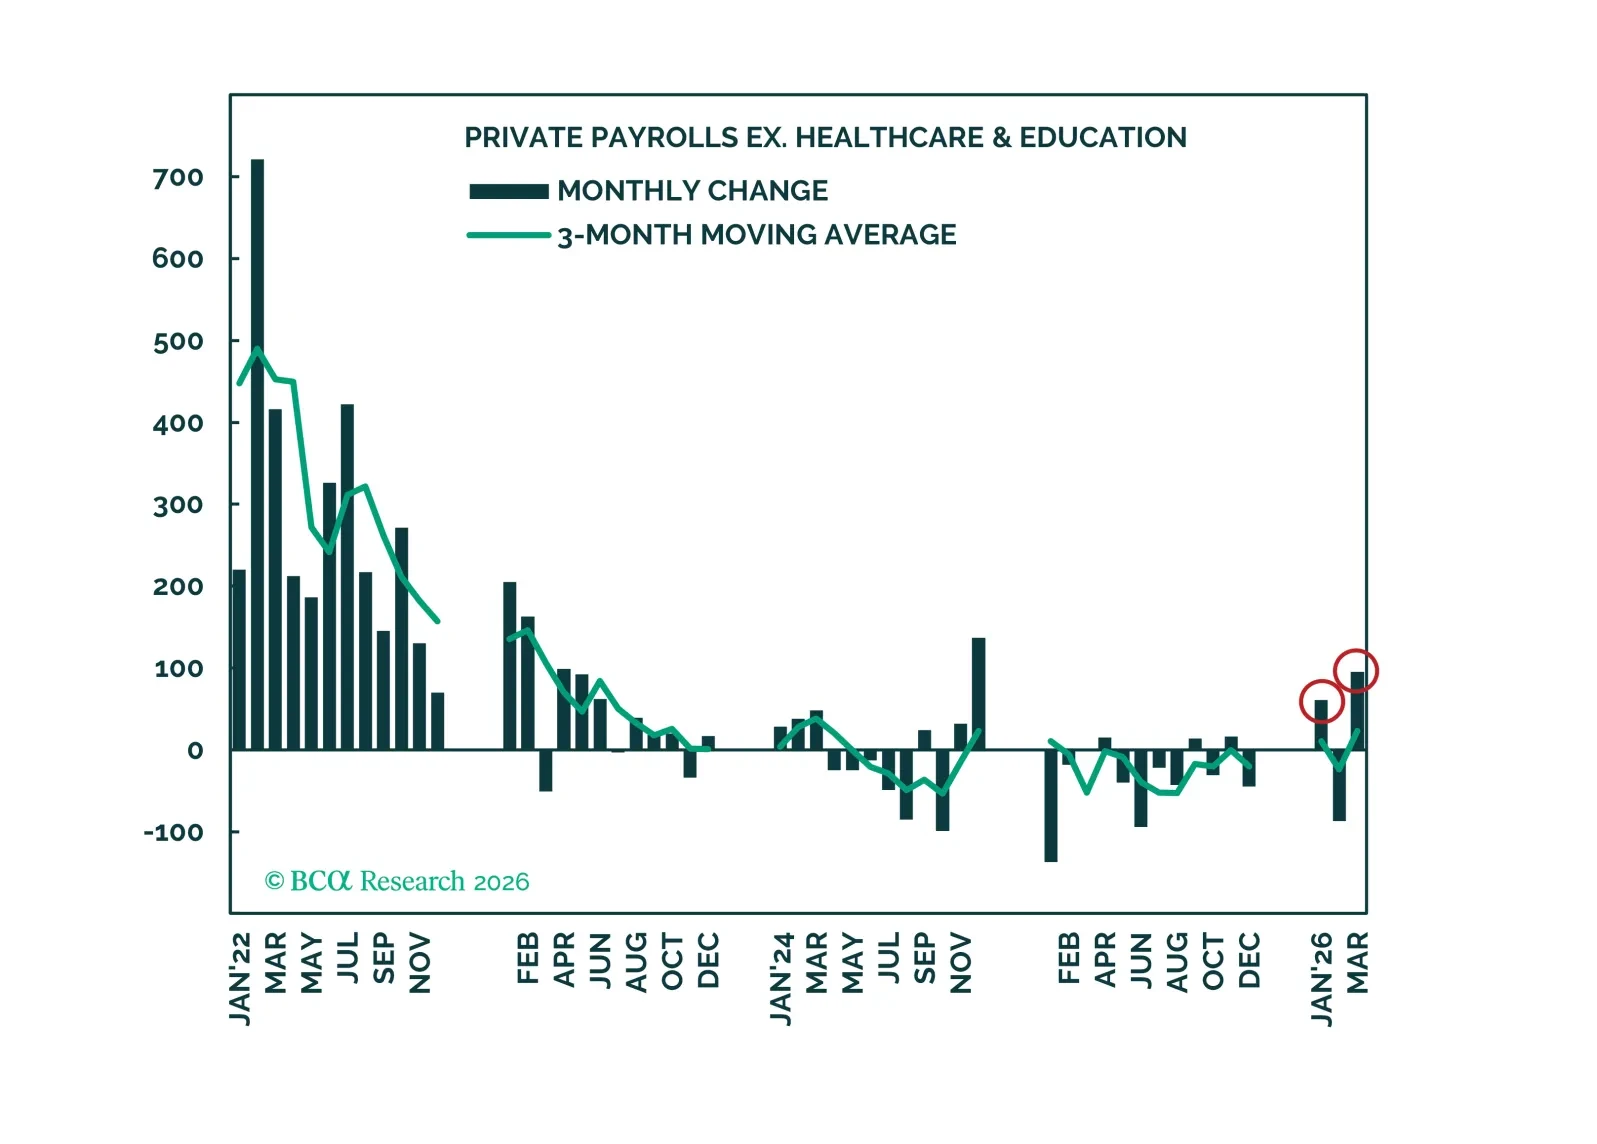
The labor market showed signs of reviving in the first three months of this year, but it is yet to be determined how consumers will react to the energy supply shock. We reiterate our benchmark asset allocation recommendations, but are skeptical that S&P 500 earnings growth will meet outsized expectations over the rest of 2026.
The relief rally in stocks can continue a while longer. However, much can still go wrong. As such, we are retaining a 12-month underweight to stocks but are moving to neutral on a short-term tactical horizon.
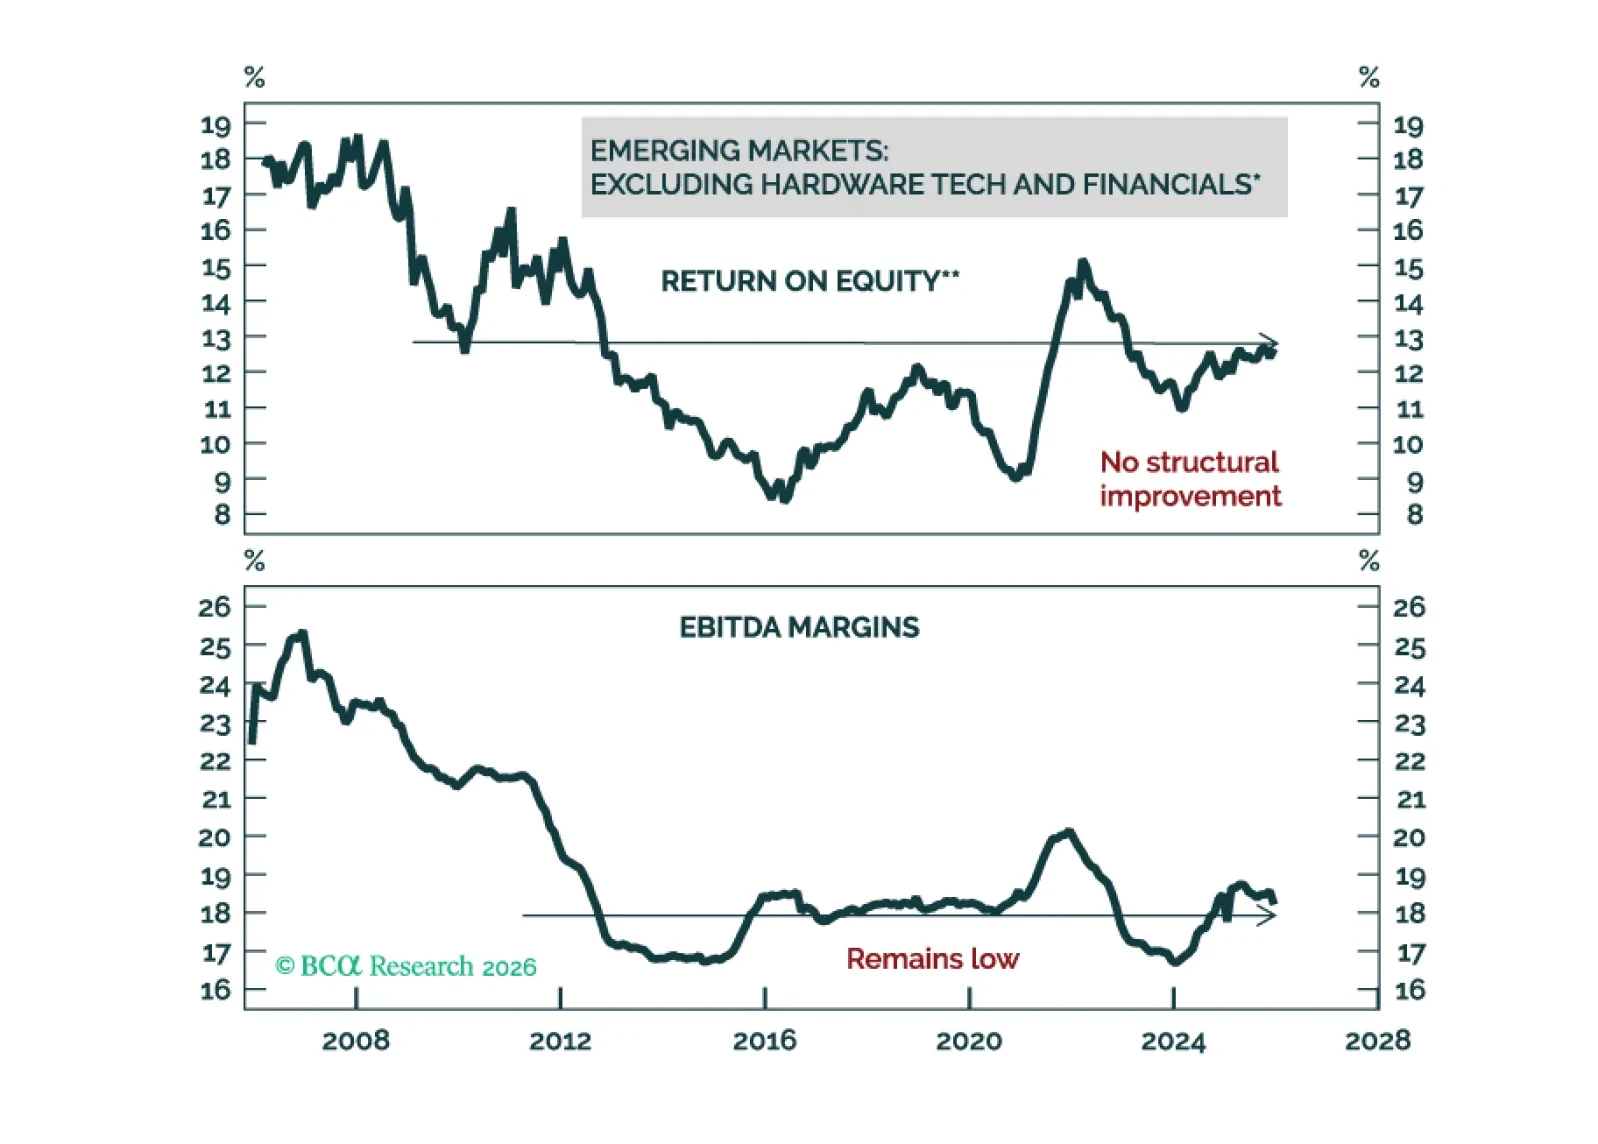
Outside Asian semiconductor producers, EM corporate earnings and profitability have seen little improvement. Despite the ceasefire in the Middle East, the medium-term outlook for EM stocks is still unattractive.
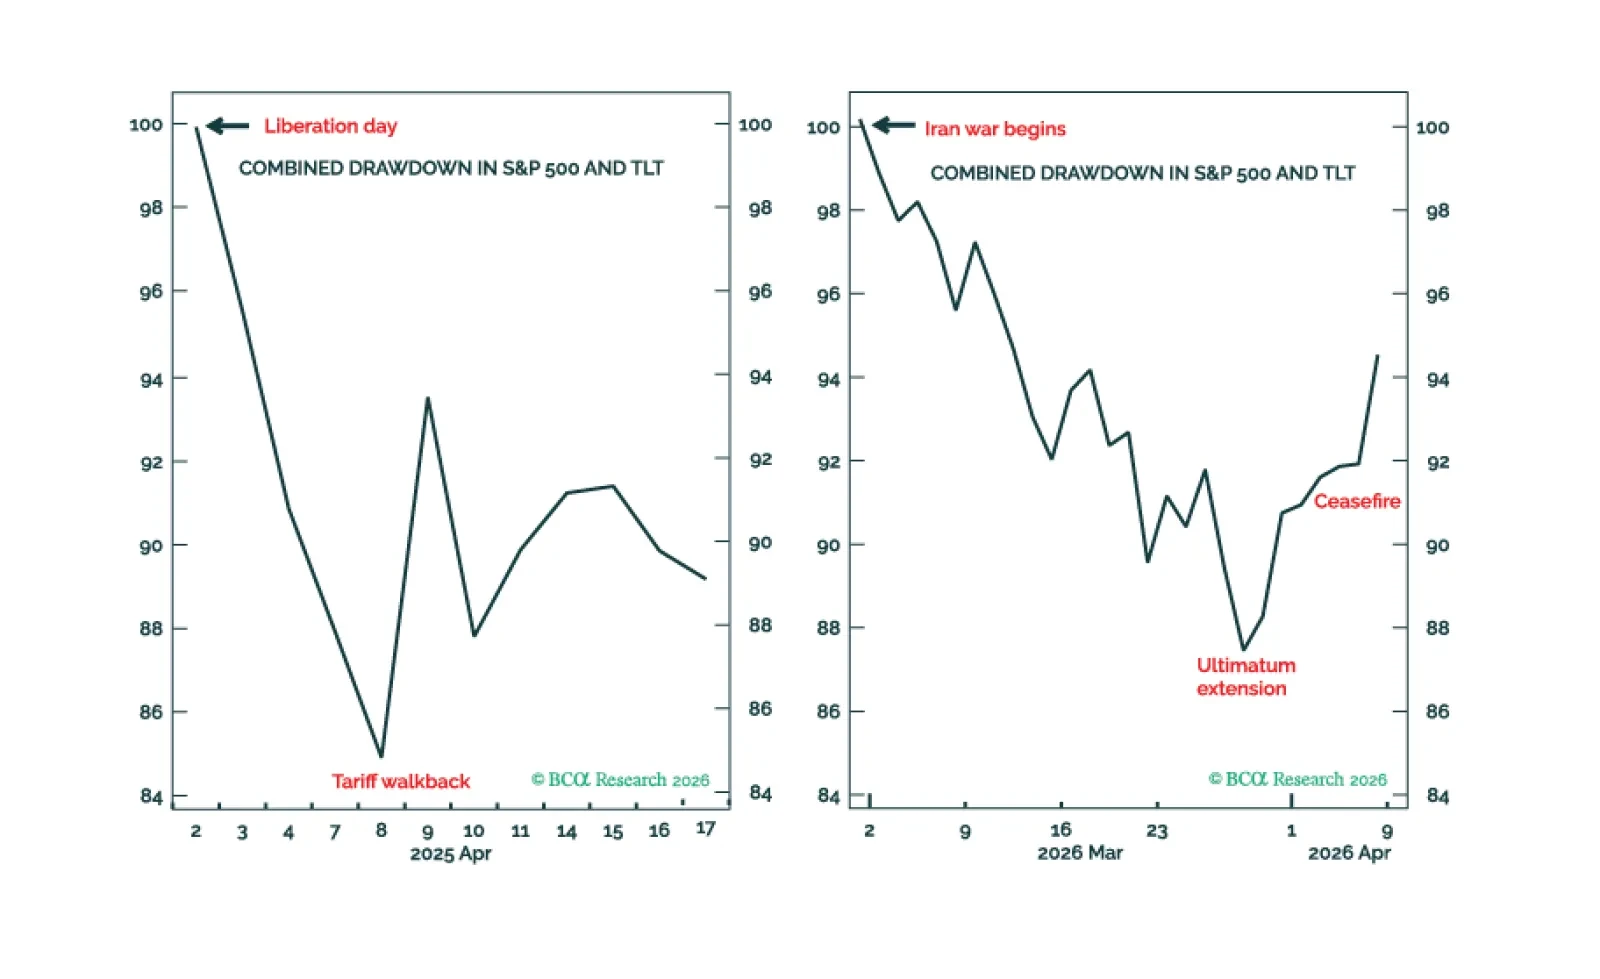
Trump’s breaking point is encapsulated by the combined drawdown in stocks plus bonds reaching 12-15 percent. On this basis, we describe how to ‘trade Trump’. Plus, we highlight three positions that should do well independent of Trump’s actions, including a new trade.
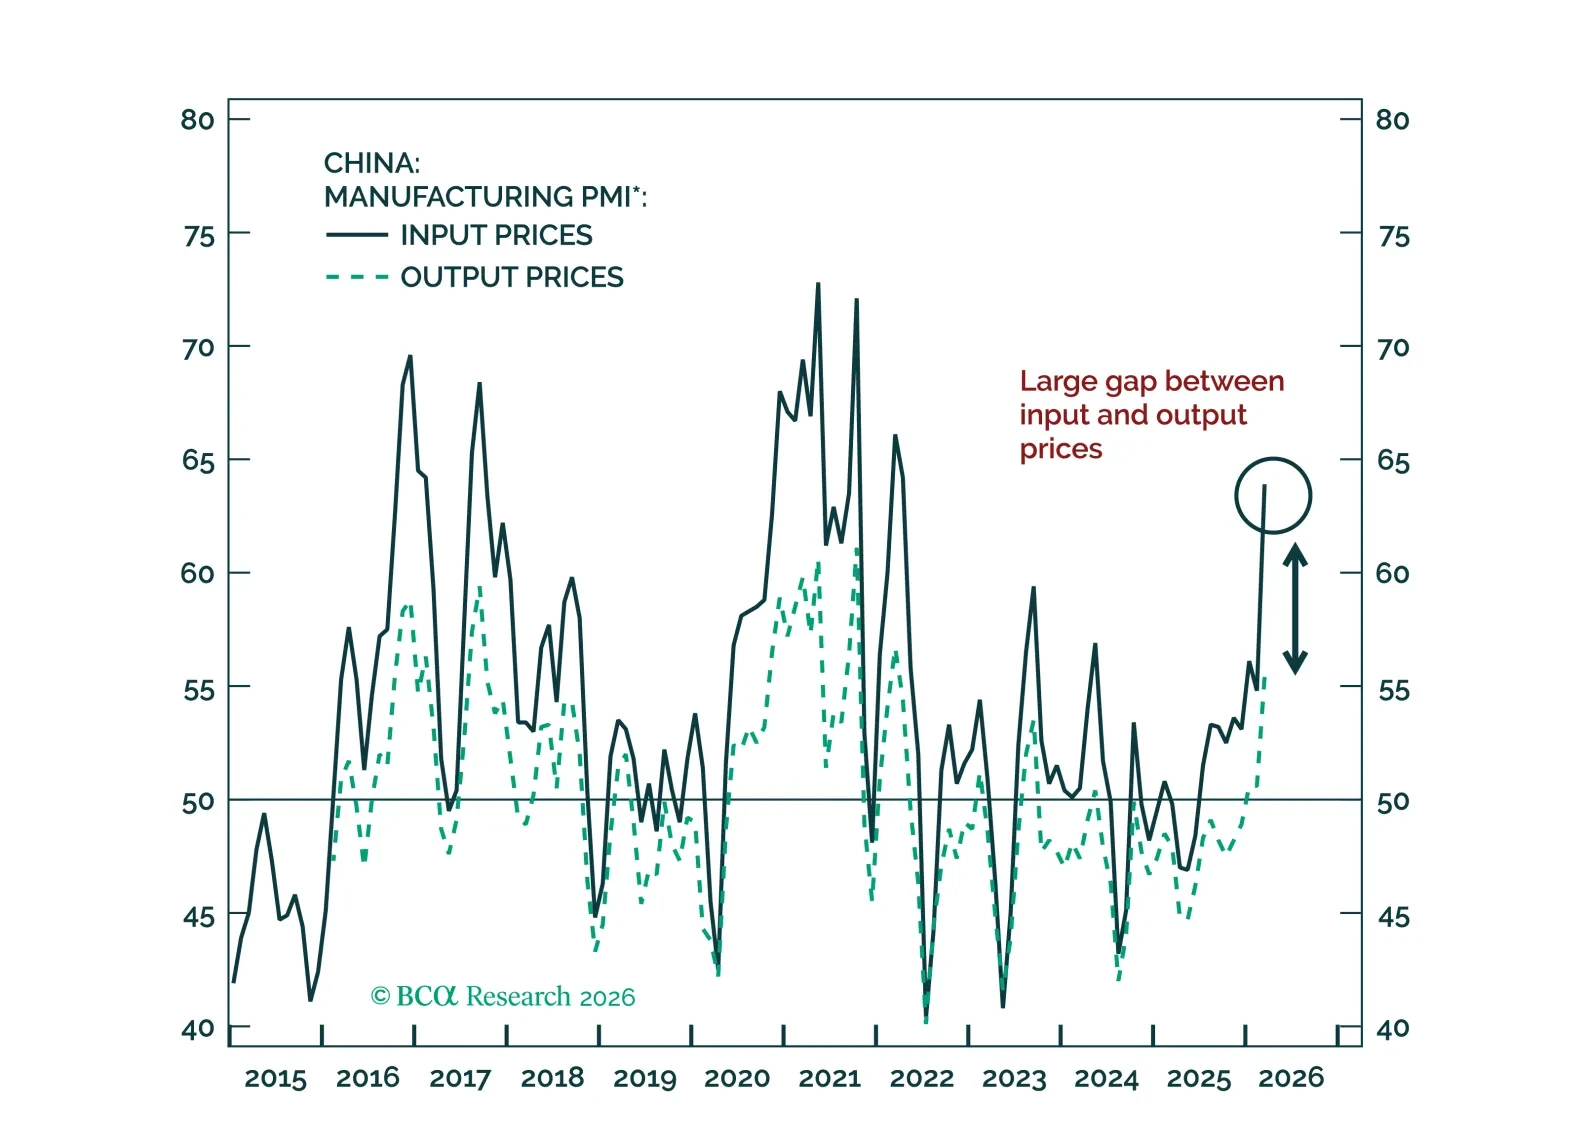
The ceasefire announced on Tuesday may signal peak intensity in the Middle East crisis, but sustained energy price pressures will continue to challenge Chinese corporate profitability.
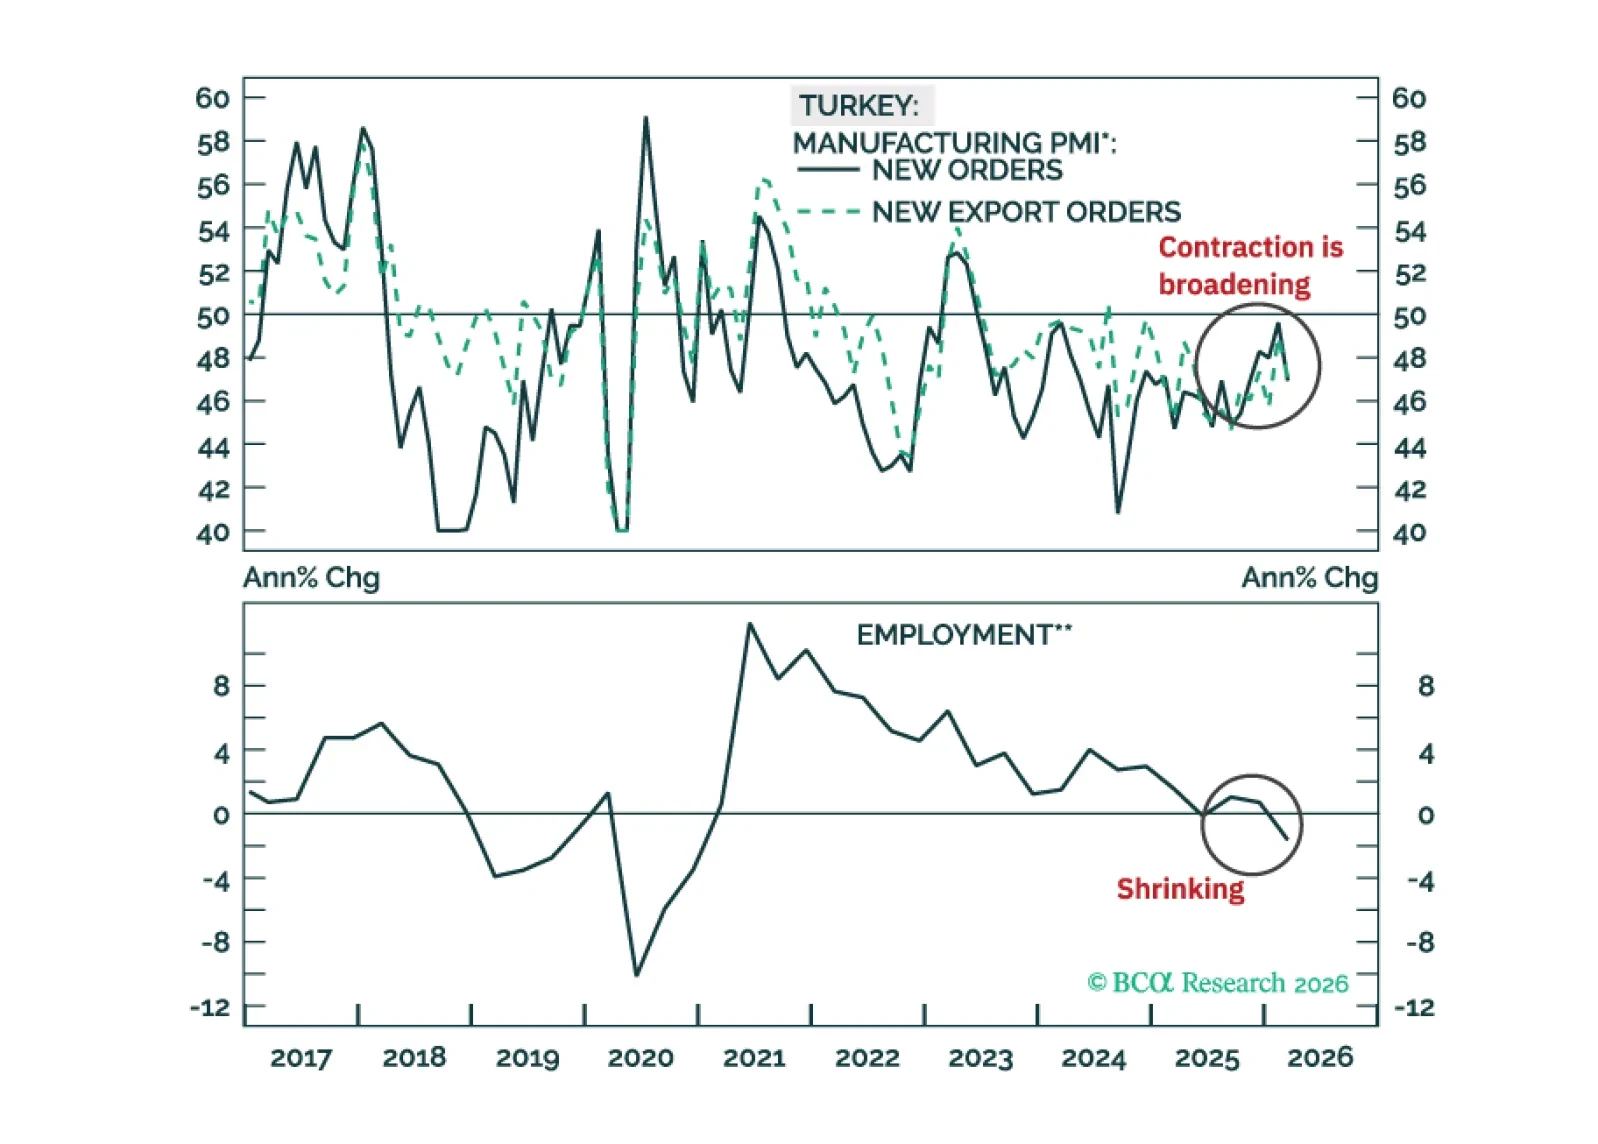
The Turkish financial markets will struggle in the very near term, but beyond that, the cyclical disinflation process will resume. Fixed-income investors should put Turkish 2-year local currencybonds on a ‘buy’ watch list.
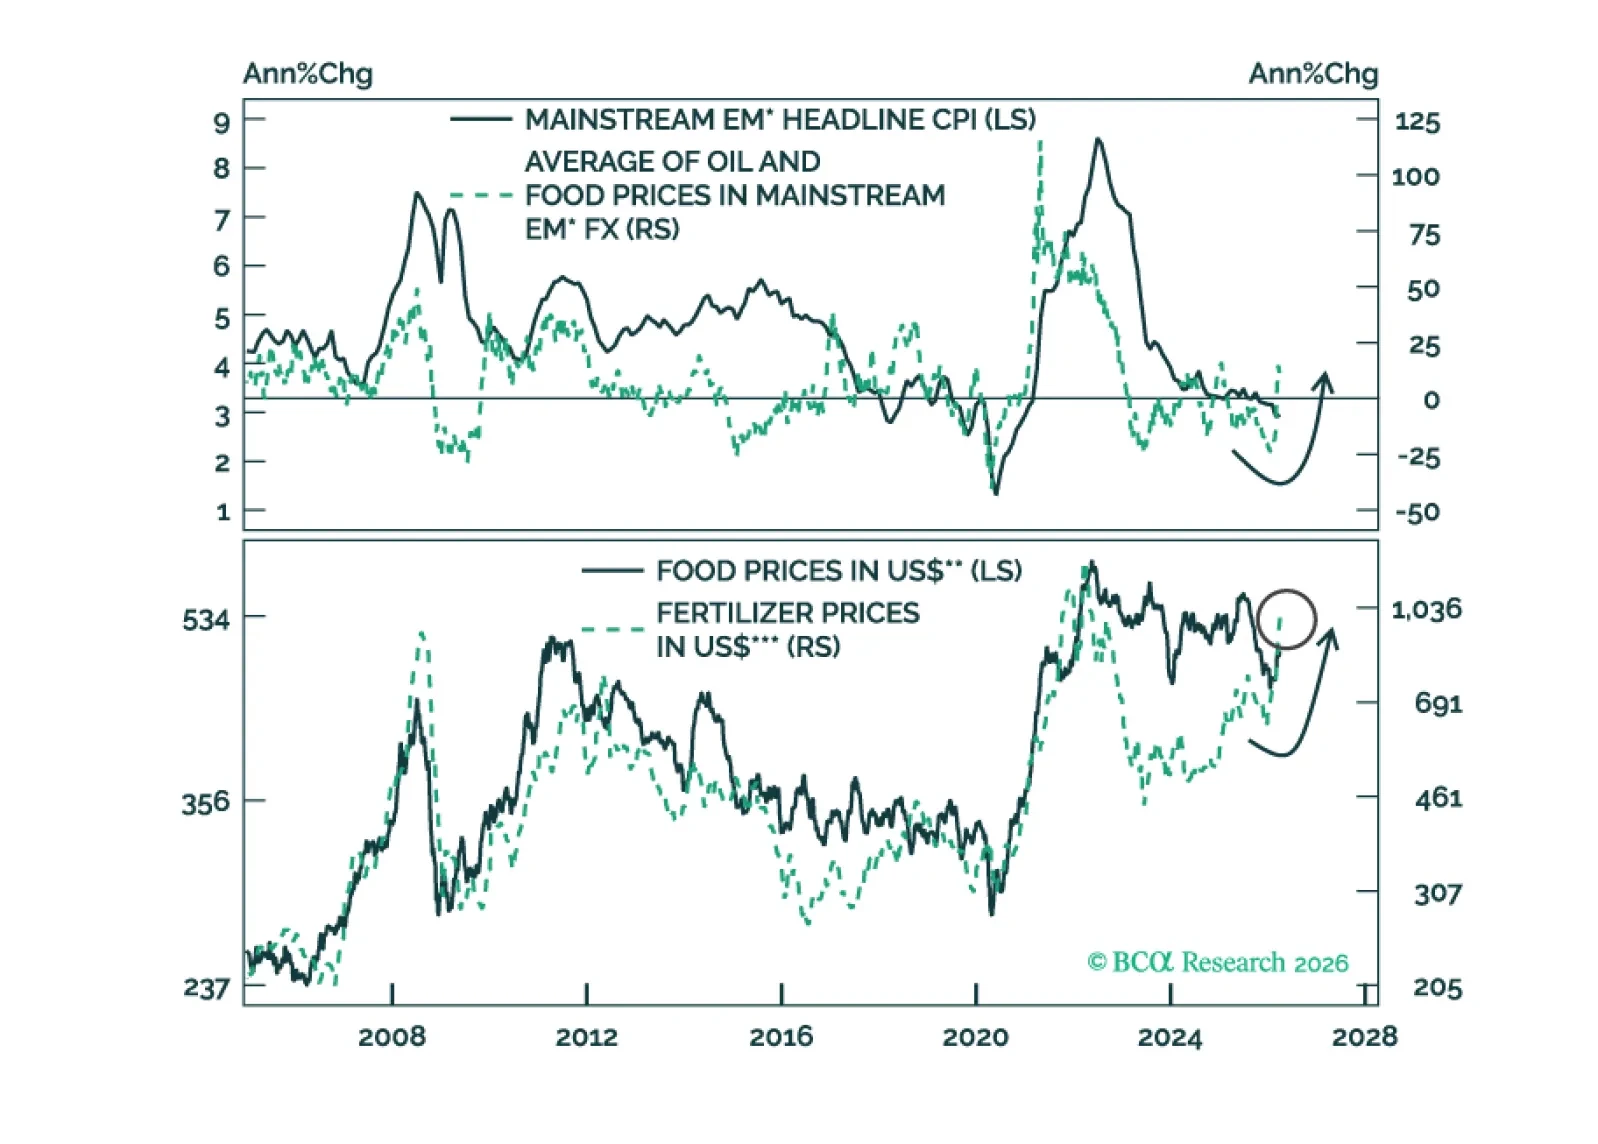
The global risk-off phase will persist. It is too early to buy local-currency bonds in Mainstream EM, but it is not too late to sell EM sovereign and corporate credit (USD bonds).
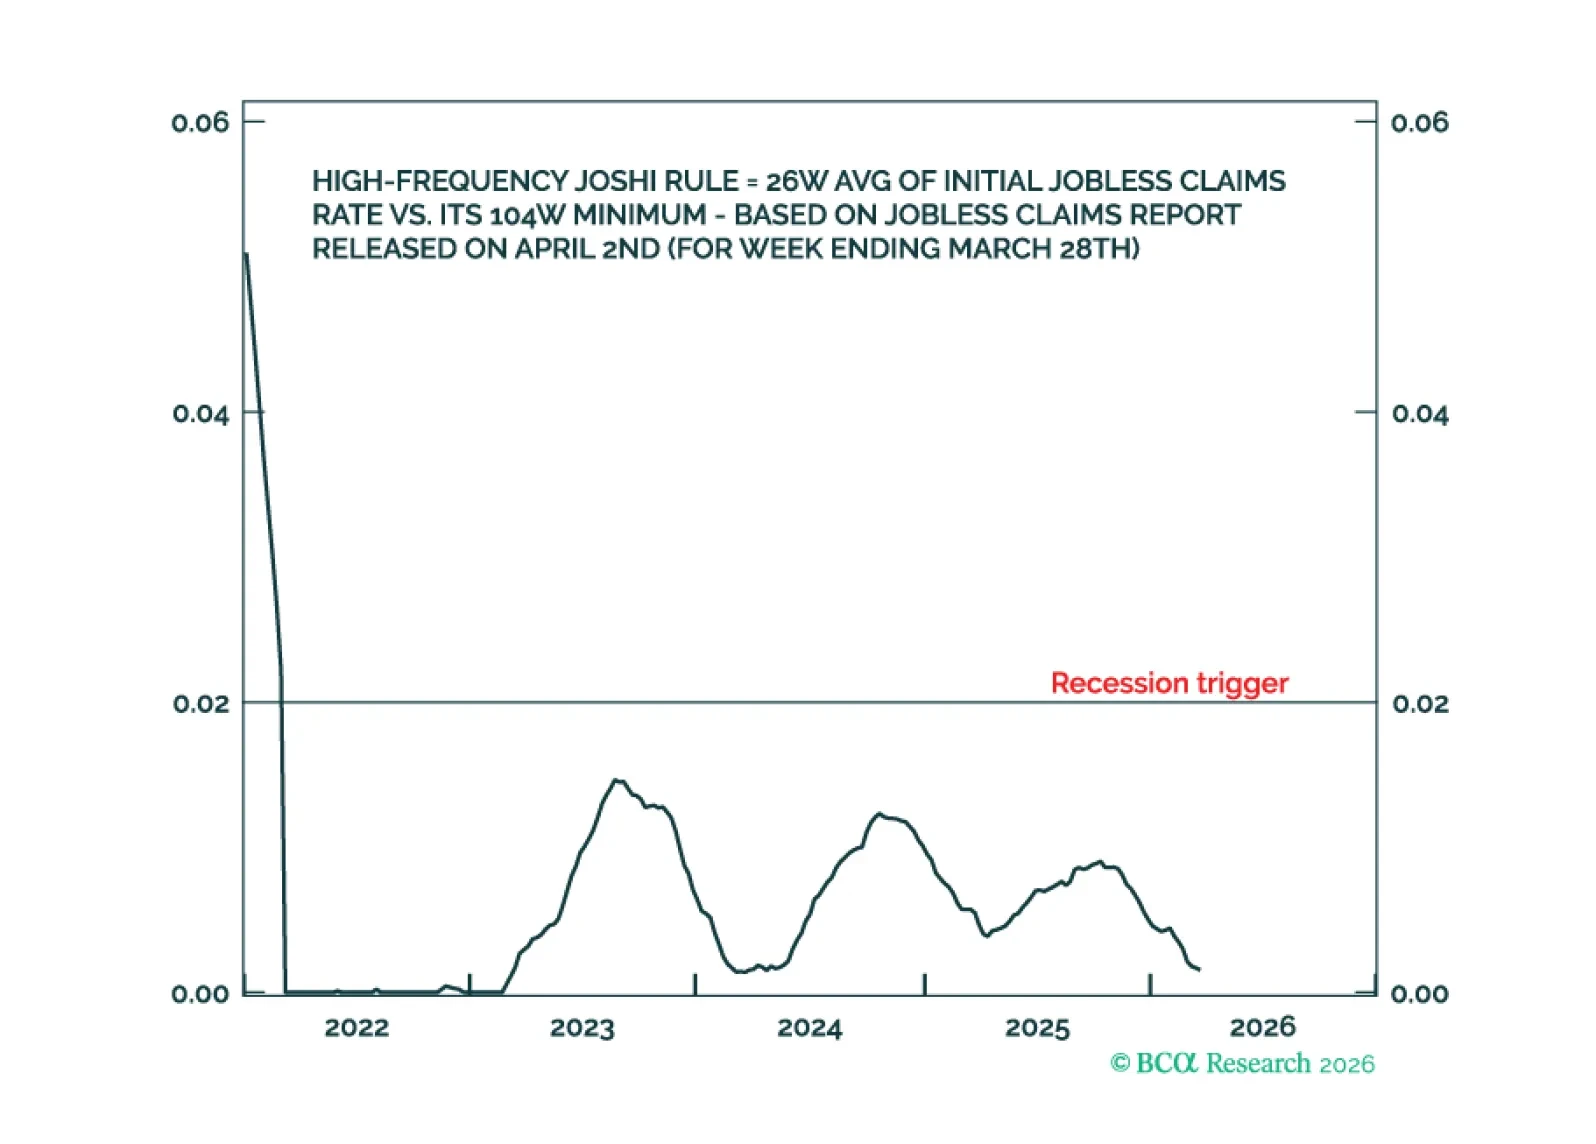
While the Middle East conflict’s inflationary impact is likely to persist, US recession risk is contained whereas non-US recession risk is more elevated. We discuss what this means for investment strategy. Plus, a new tactical trade is to underweight Utilities.