 CoreMacro
Find out more
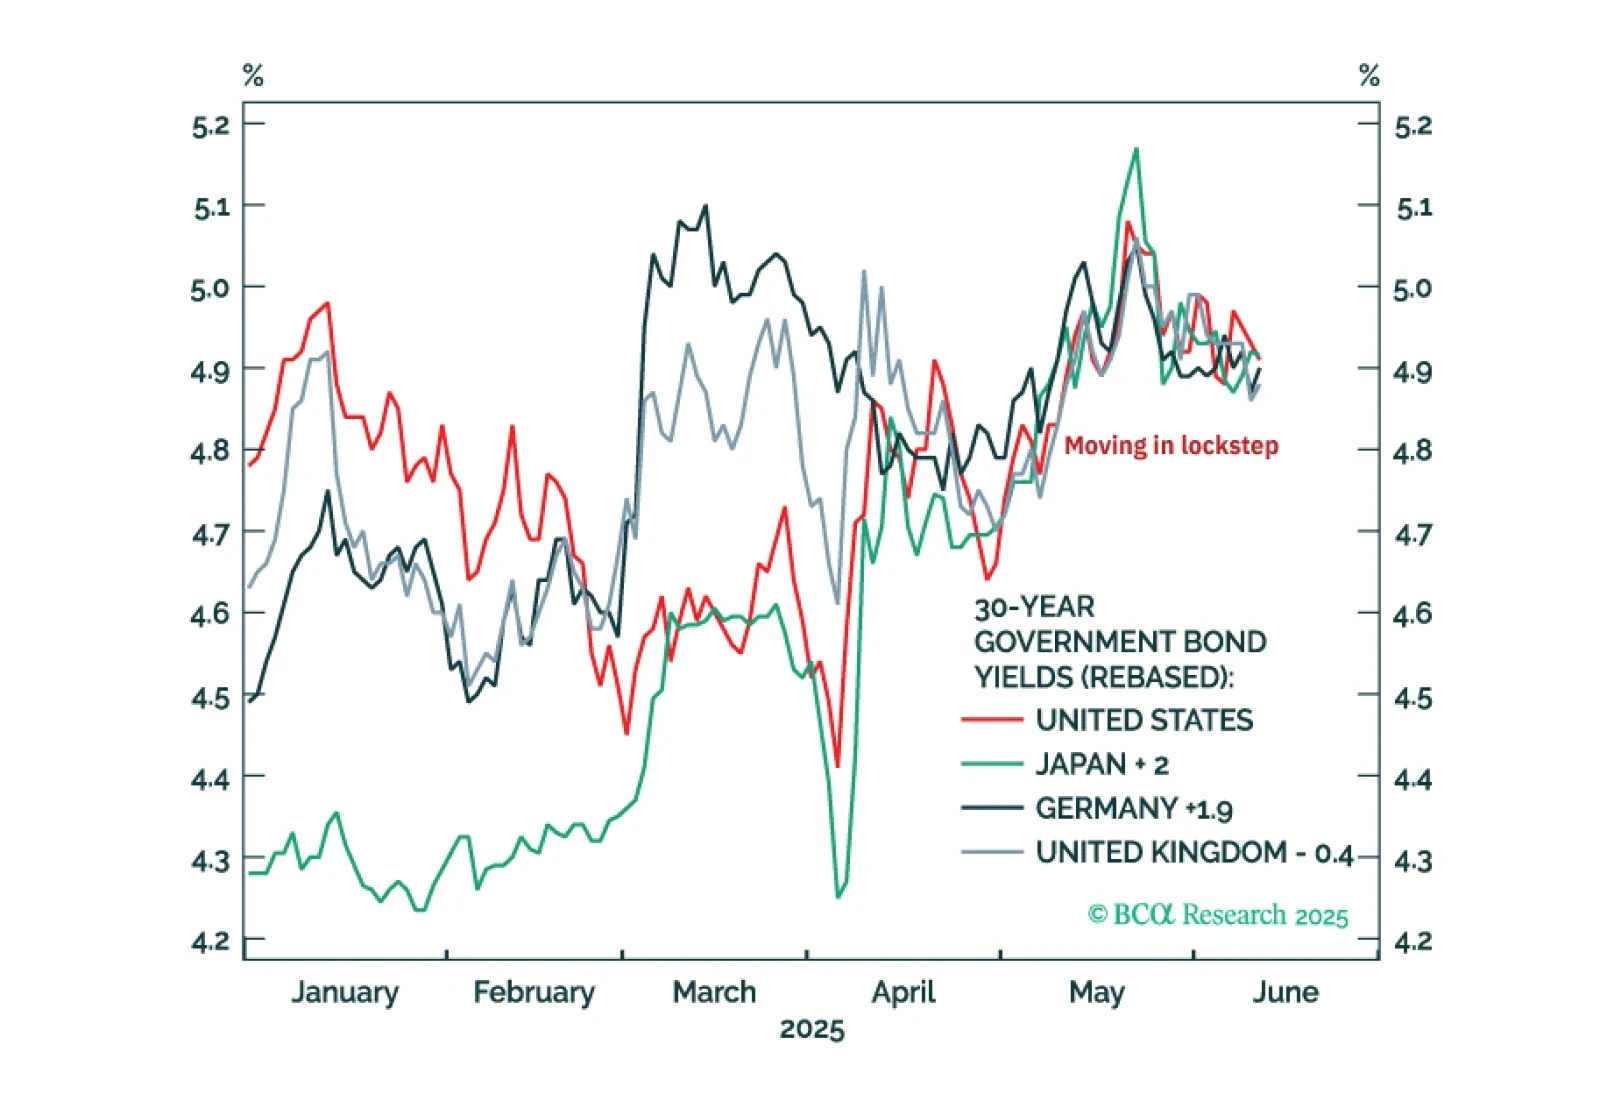
The perfectly synchronised moves in US, Japanese, German, and UK 30-year bond yields through the past two months are odd… and irrational. These irrational moves present compelling investment opportunities.
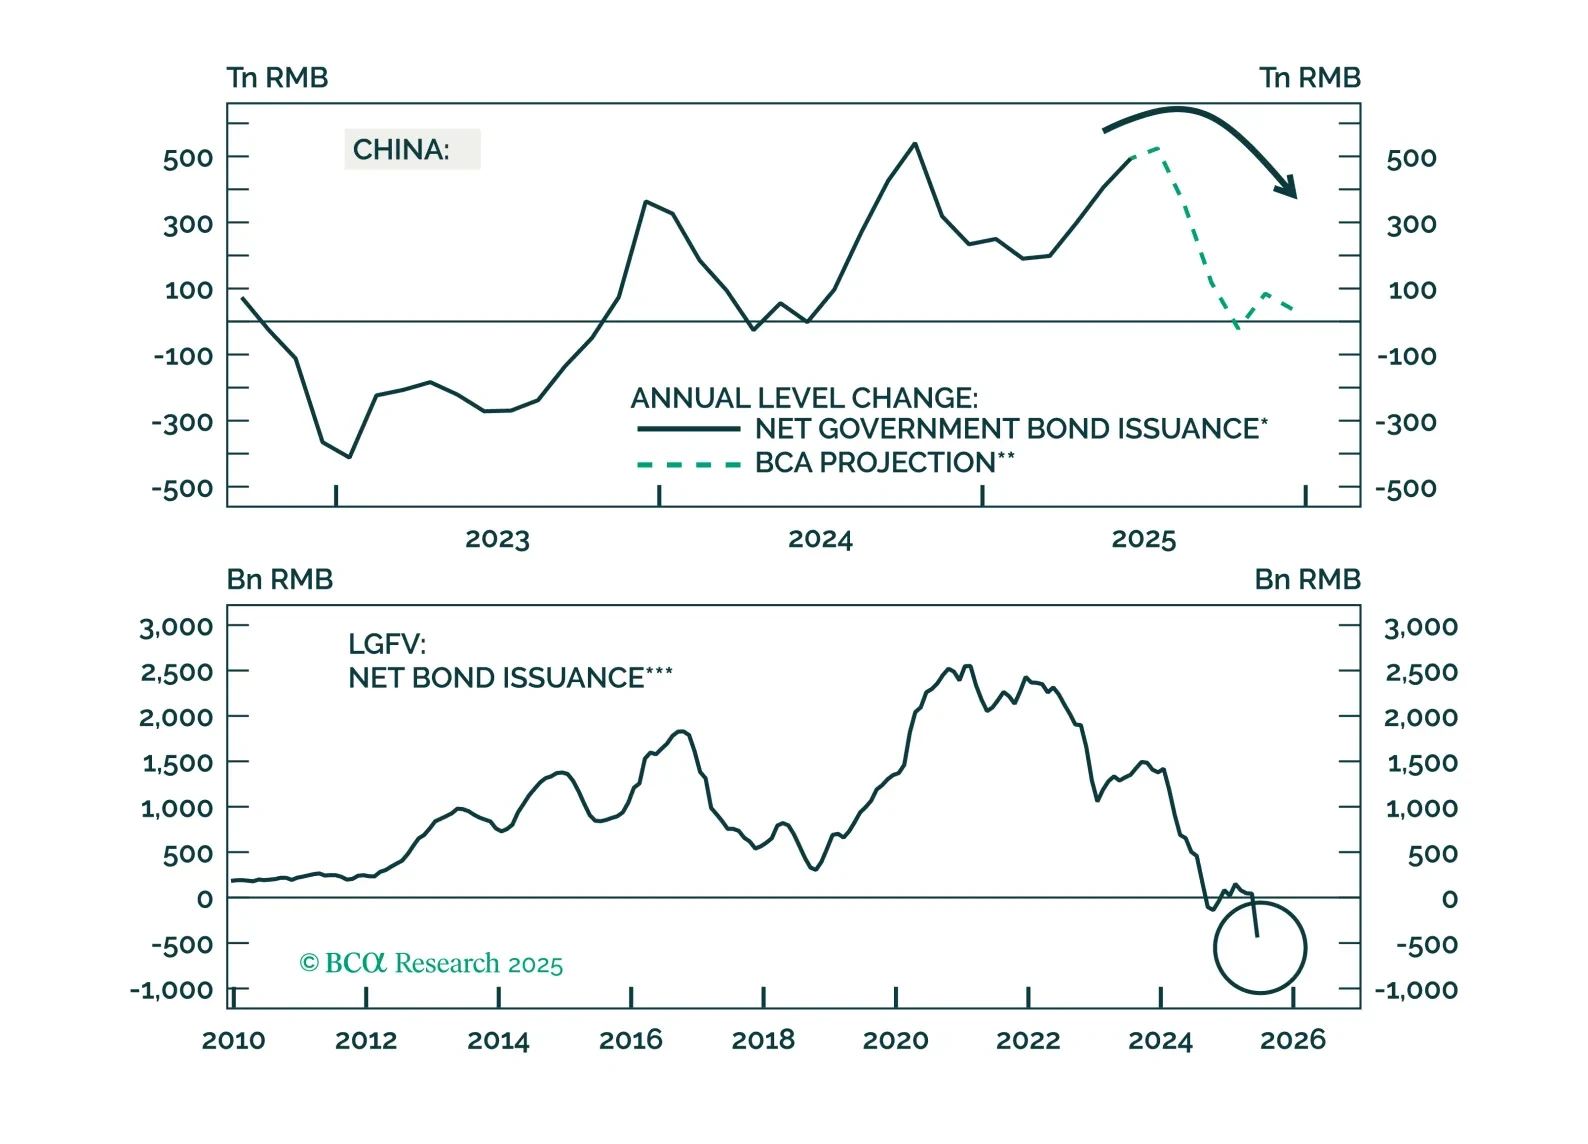
The London Sino-US trade talks offered hope of de-escalation, but Chinese equities remain under pressure from deflationary headwinds and lack a clear macro catalyst to trend higher.
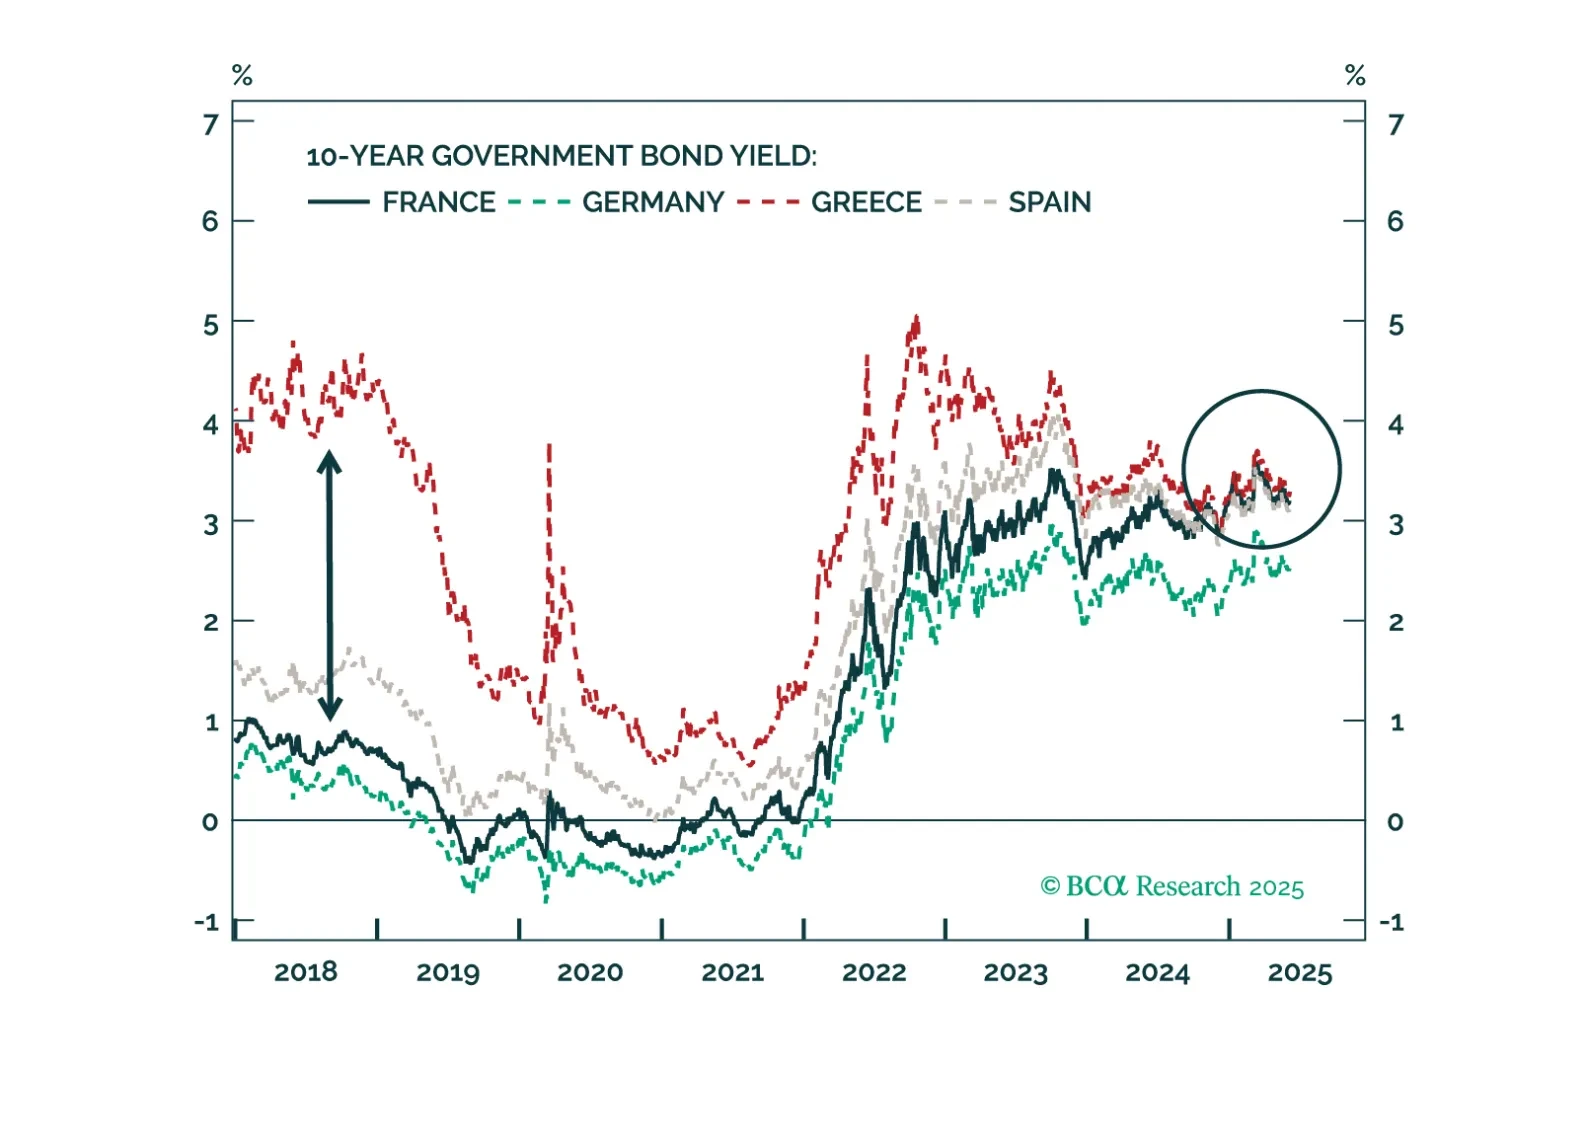

The US economy has held up better so far this year than we had expected. For the time being, investors should remain modestly underweight equities. A more aggressive underweight would be justified only once the “whites of the recession’s eyes” are visible.
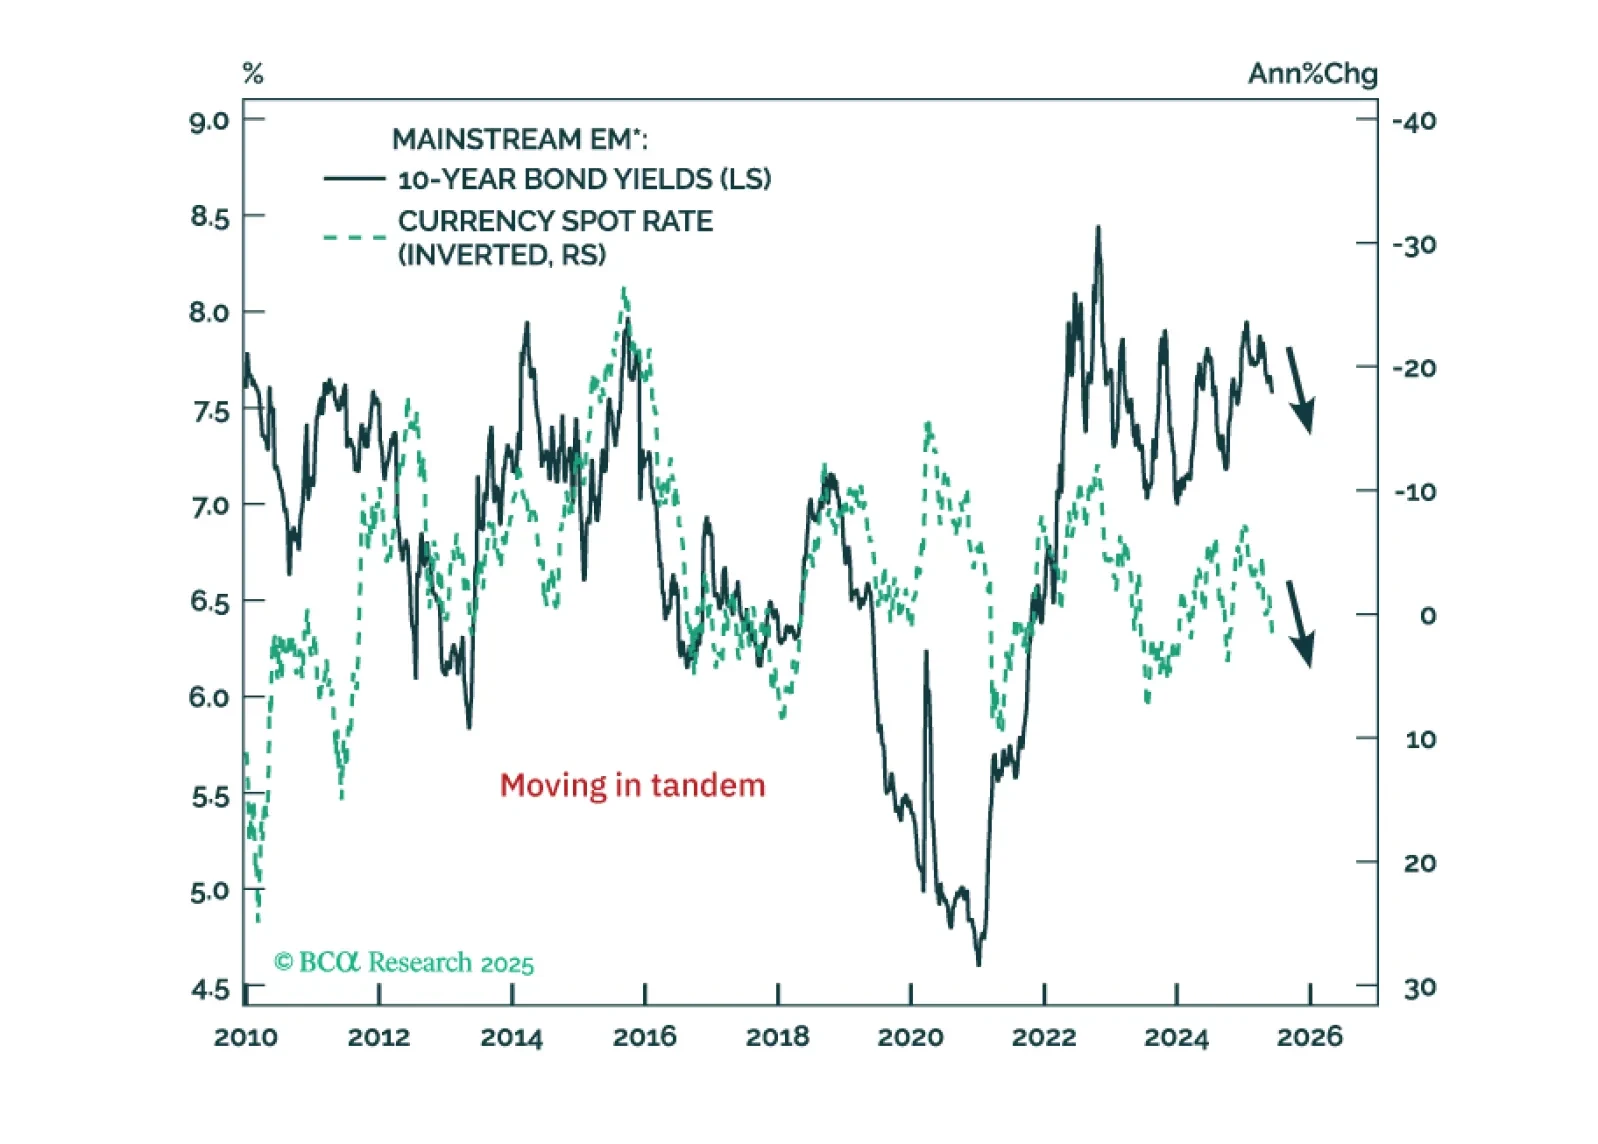
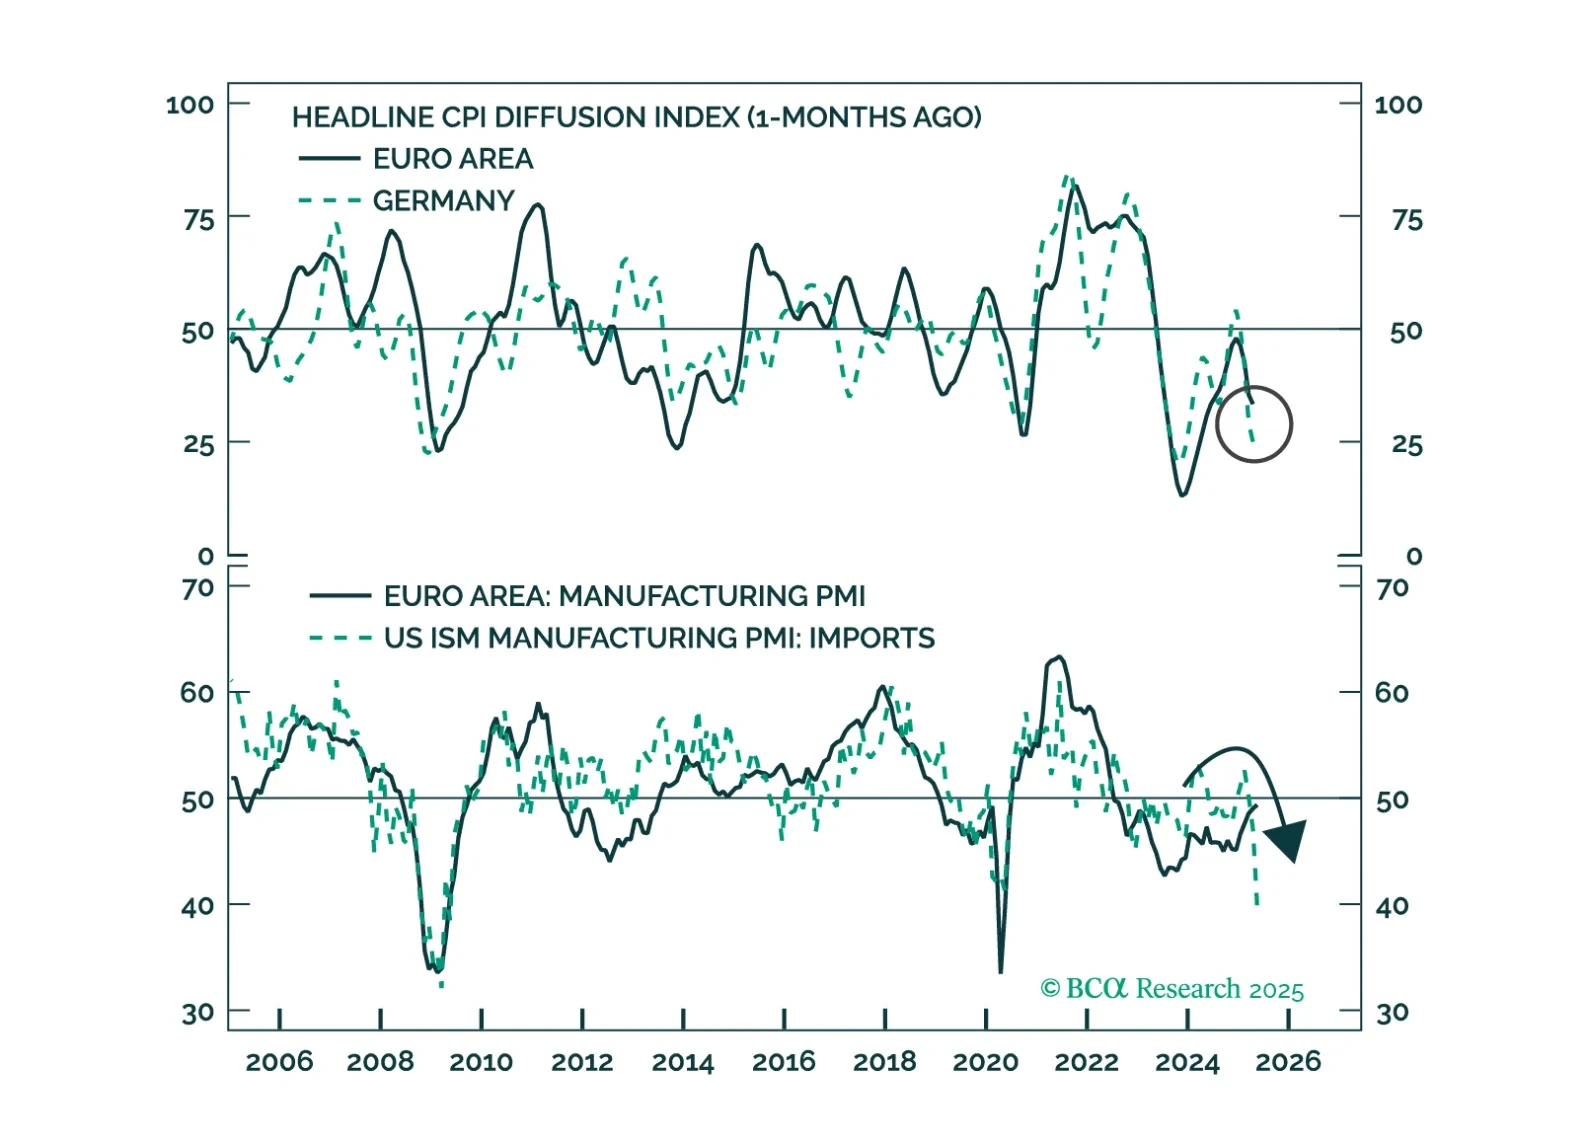
The ECB is changing its tone, but don’t call it a pivot. Slower cuts, sticky disinflation, and a soft growth patch shift the opportunity set. We break down the tactical bond trades and why EUR/USD dips are still for buying.
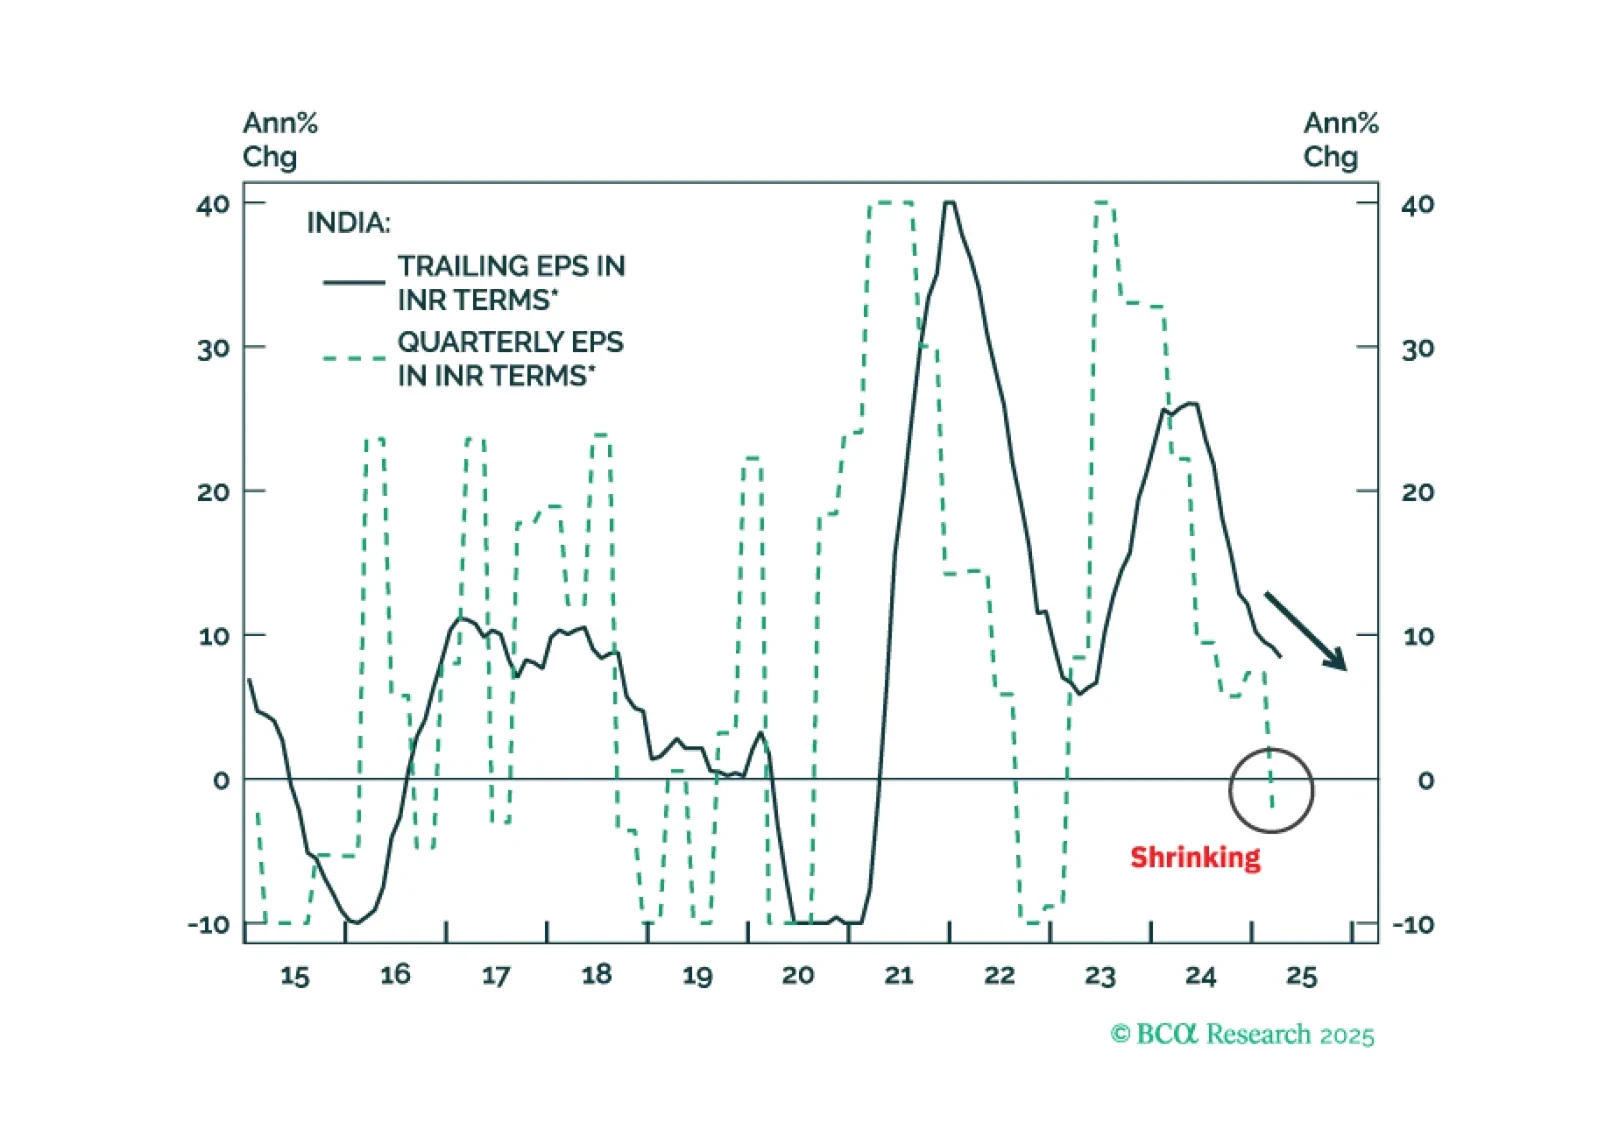
India's IT service exports have been booming and will continue to do so despite wider AI usage. Indian IT stocks, however, will not benefit from it as the expanding Global Capability Centers (GCCs) in India compete with the nation’s IT companies, driving the latter's profitability down.
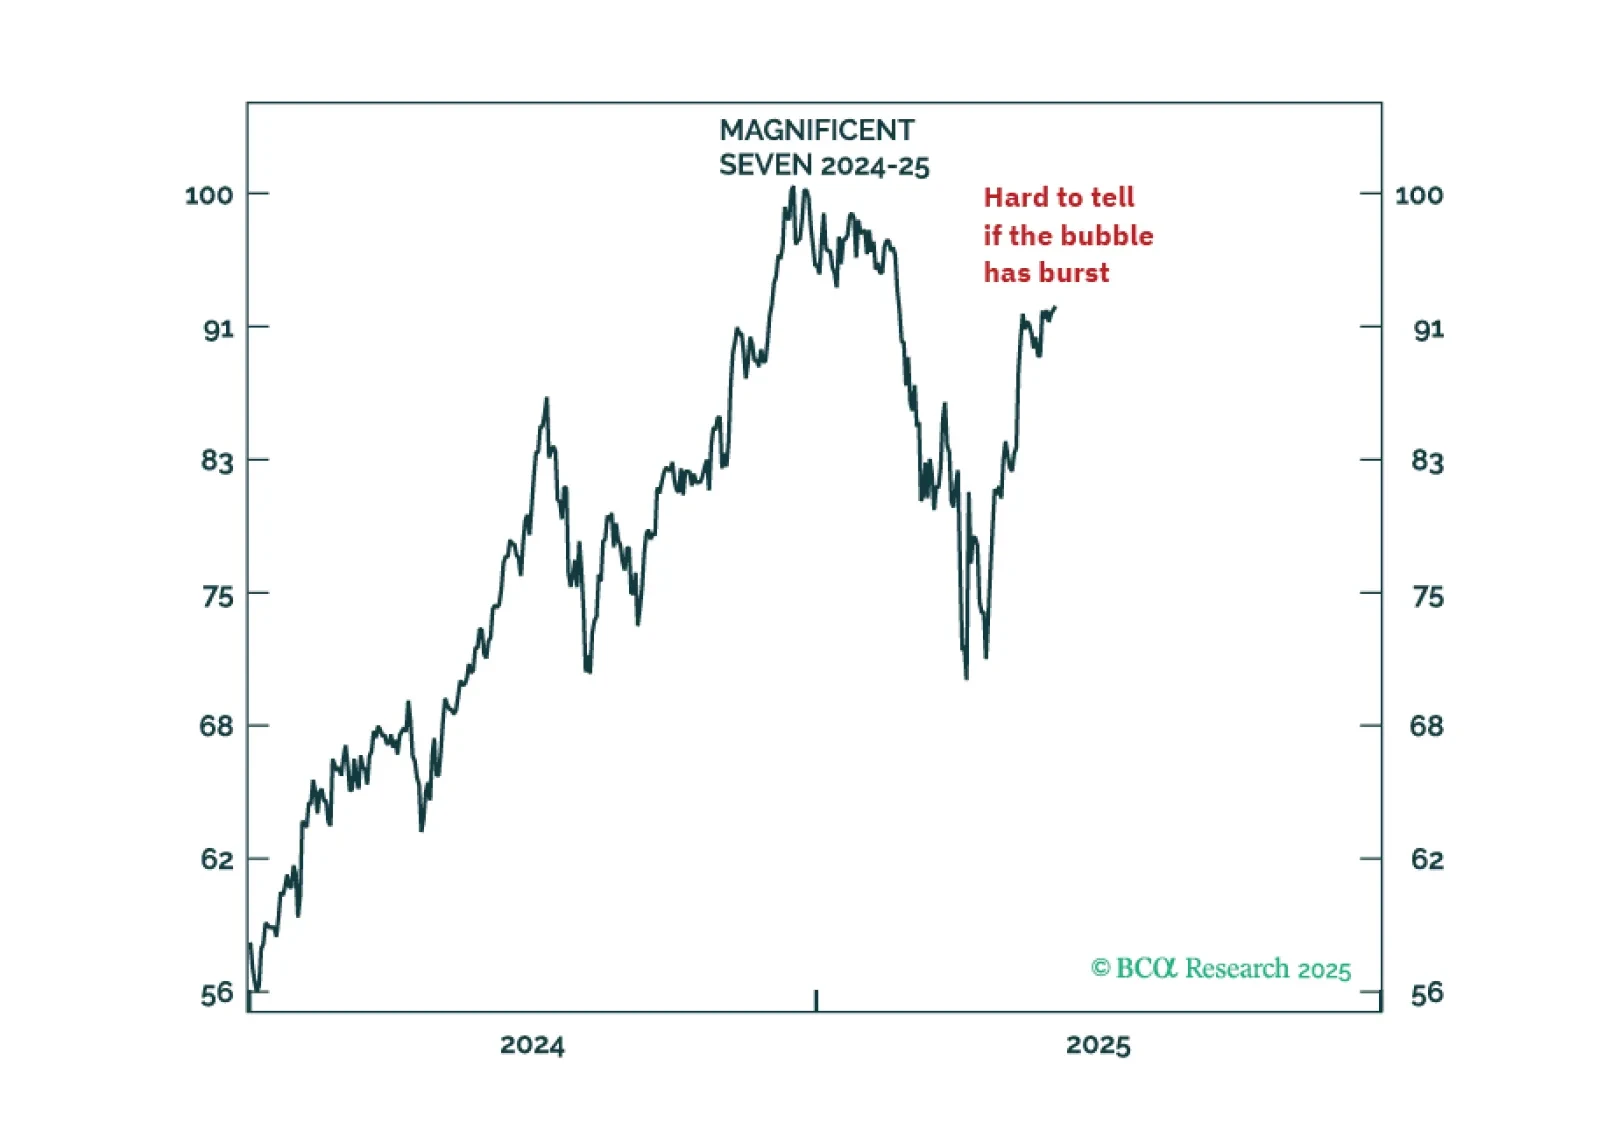
I am a structural disbeliever in the US superstar stocks because these winners of the previous technology, Web 2.0, are unlikely all to be the winners of the latest technology, AI. But I would suspend my disbelief if the Magnificent-7 index reaches a new high and the bursting AI-bubble configuration is broken. Plus, a new recommendation is to overweight Global Healthcare (IXJ).
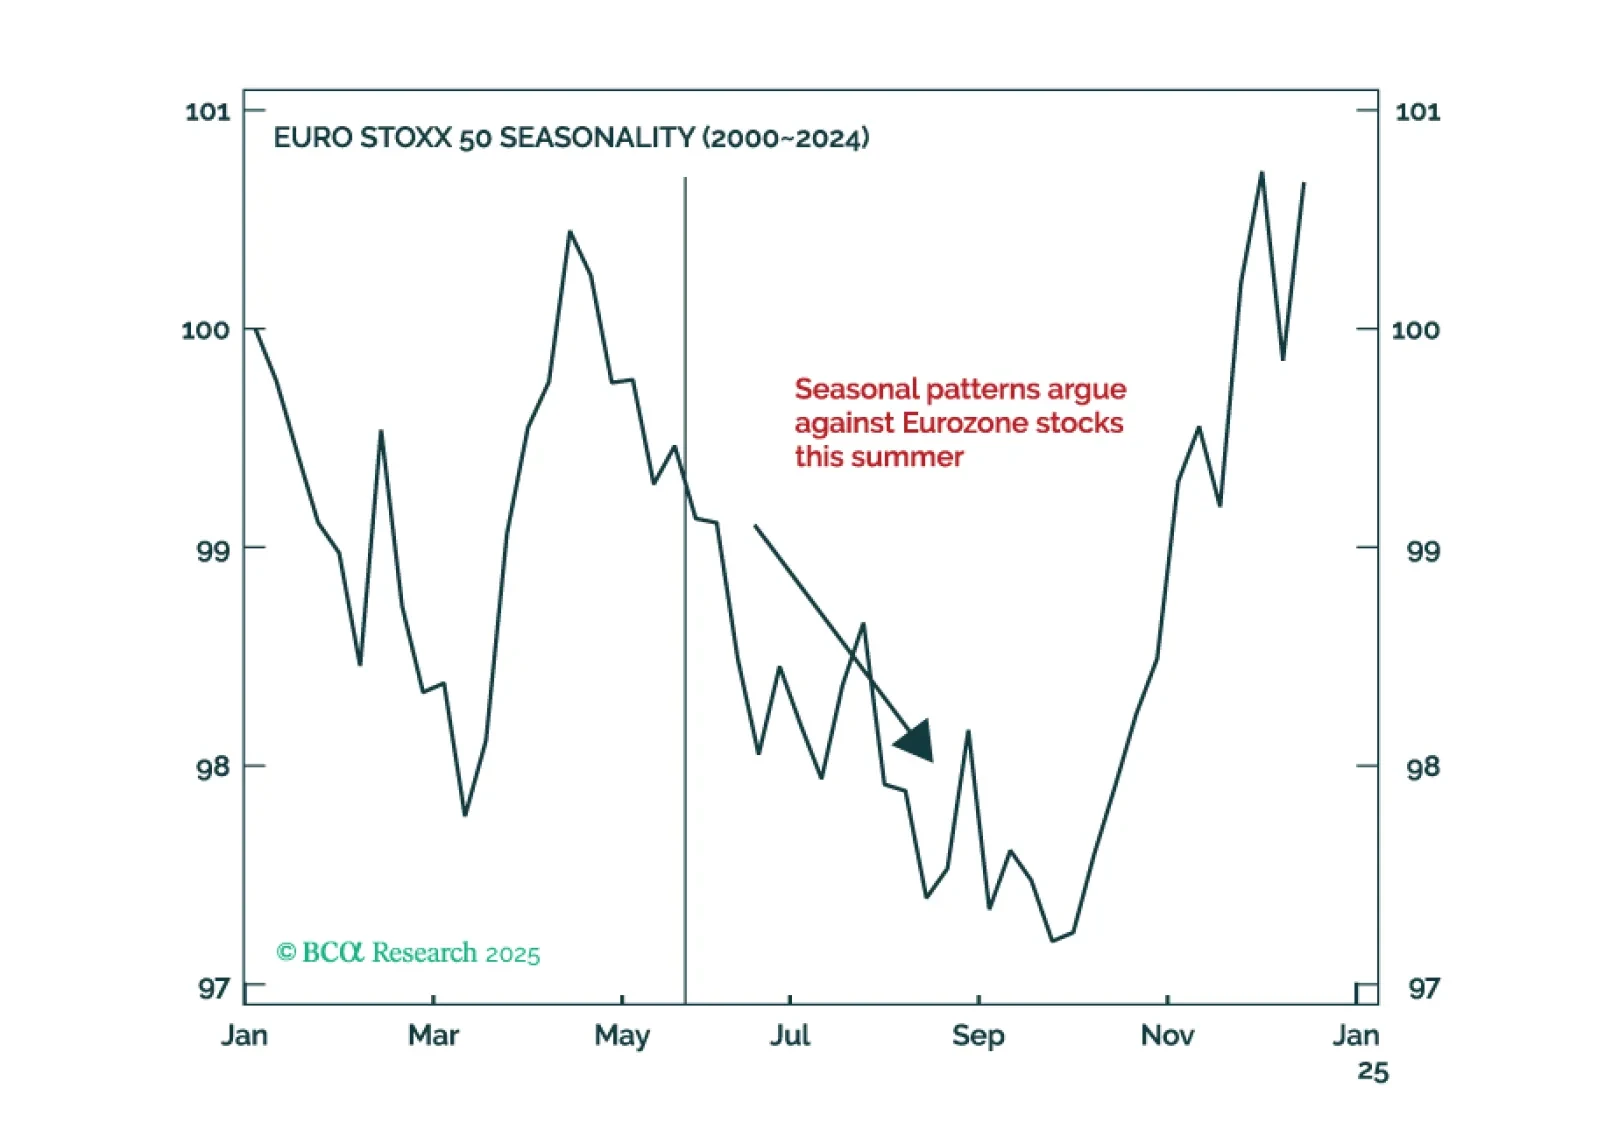

After considering some of the most common bullish arguments, we stand by our recession view and reiterate our defensive asset allocation recommendations.