 CoreMacro
Find out more
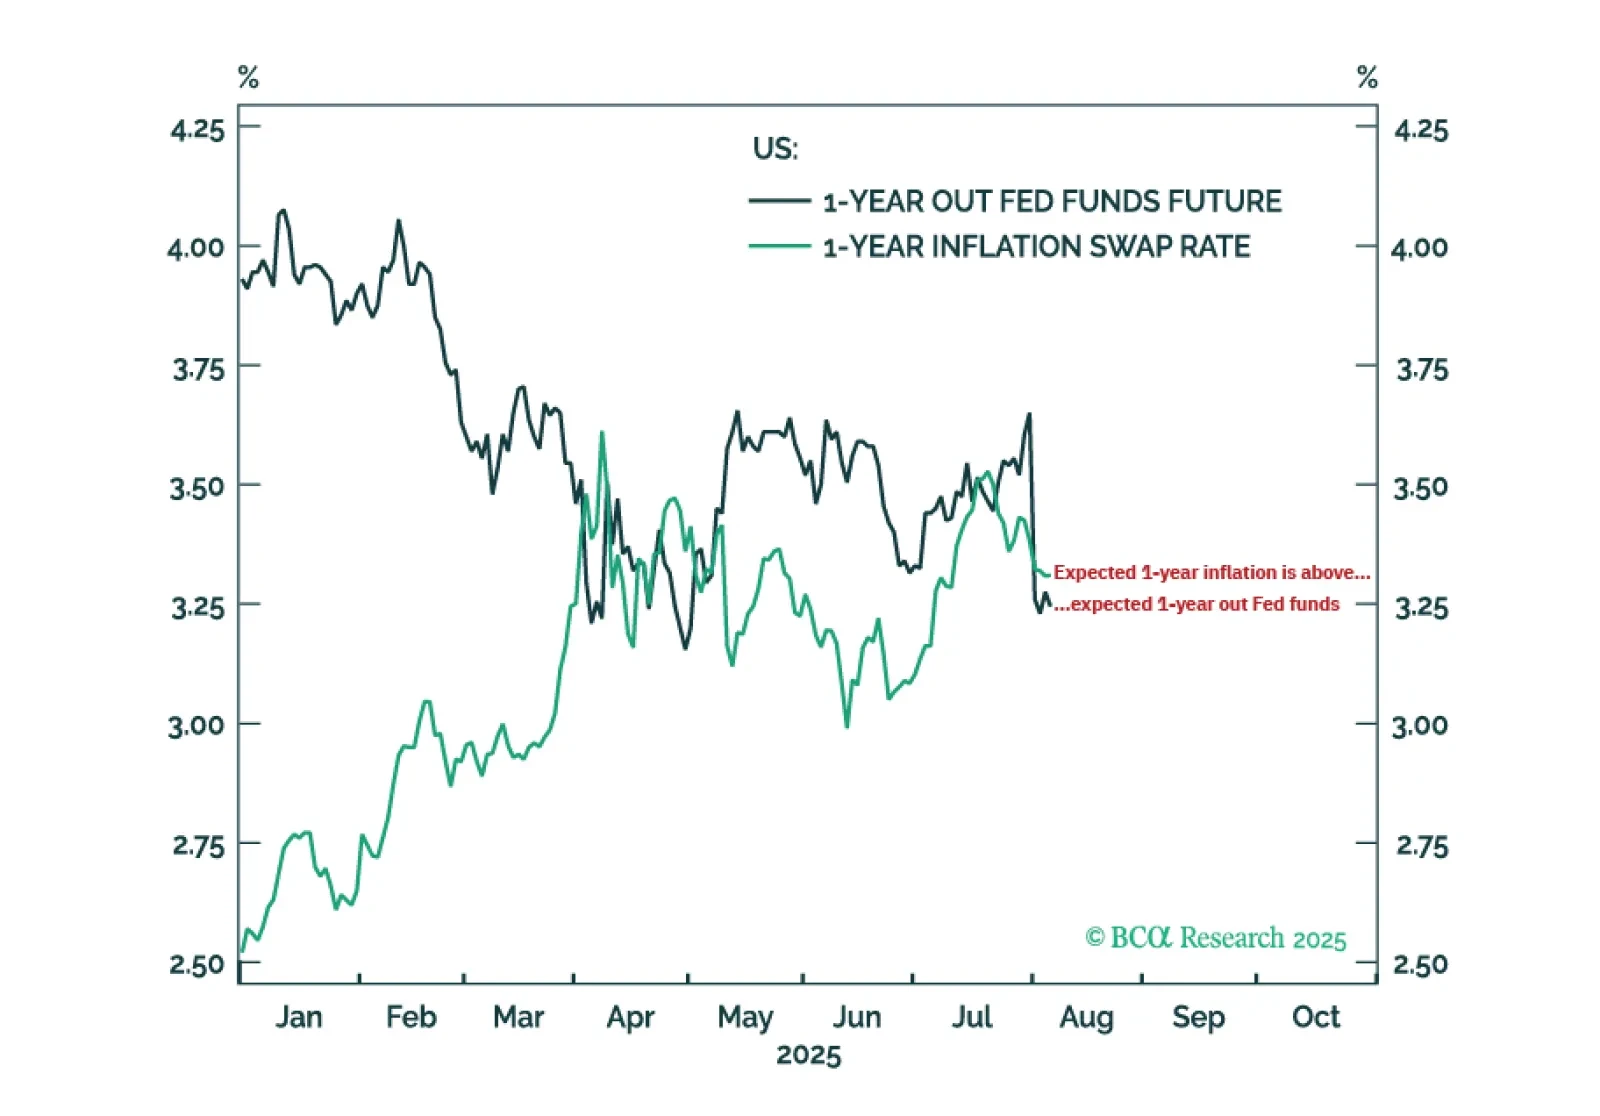
Expectations for US inflation at 3.3 percent are inconsistent with expectations for the Fed to slash rates, so one of these expectations is likely wrong. We describe how to play this mispricing. Plus, a new position is to go overweight global consumer discretionary (RXI).
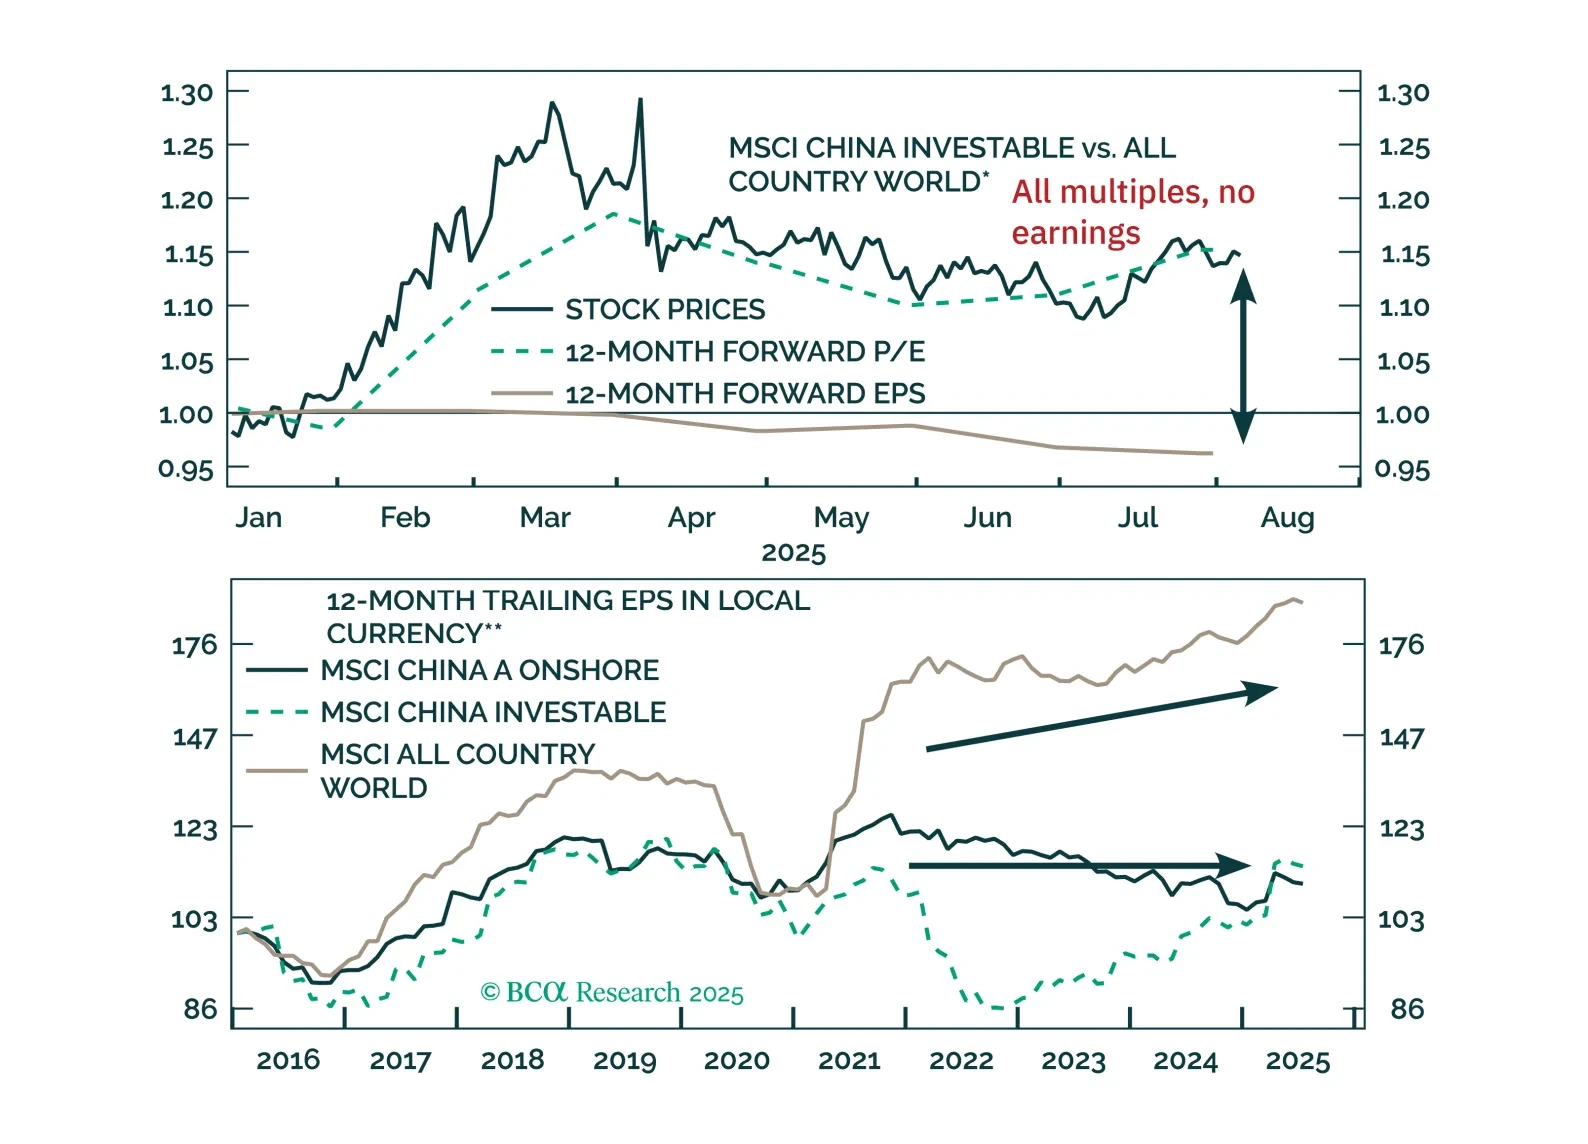
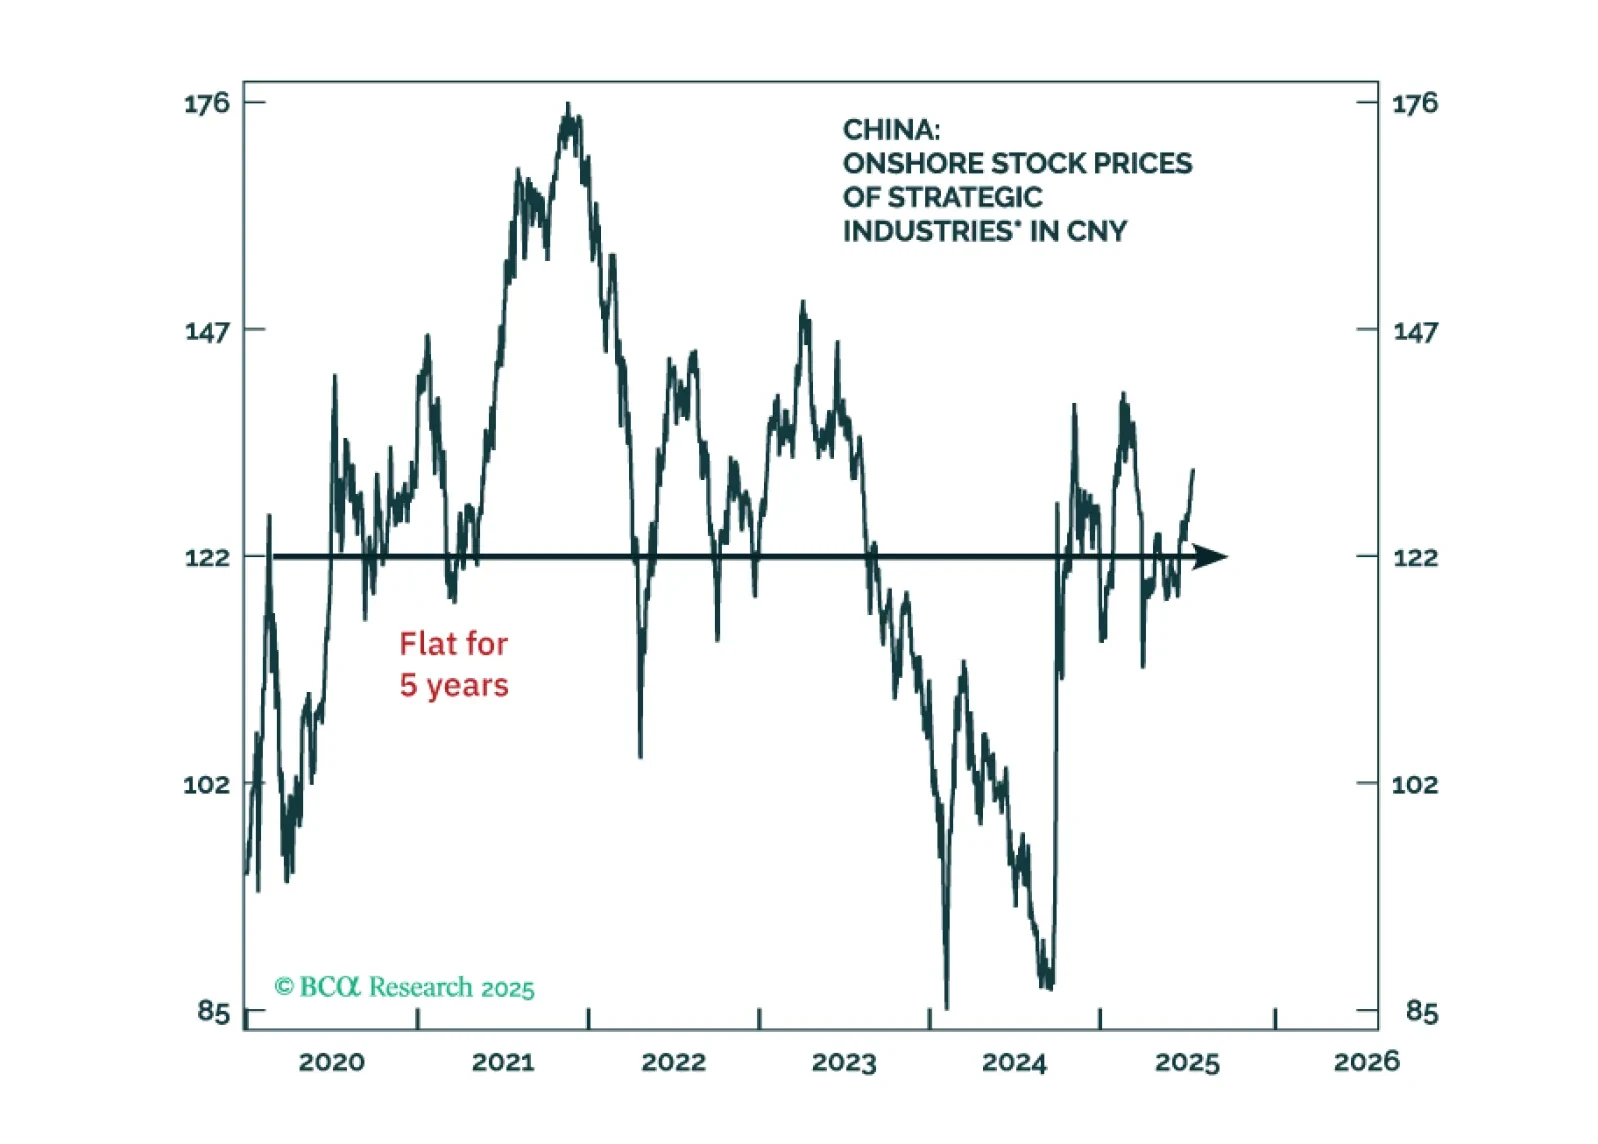
Chinese stock prices have significantly decoupled from the country’s business cycle, with the full impact of US tariffs yet to be realized. The valuation-driven equity gains without a cyclical economic recovery will be vulnerable to a reversal.

We maintain our 12-month US recession probability at 60%. However, until the “whites of the recession’s eyes” are more clearly visible, we would refrain from moving to a fully defensive stance.
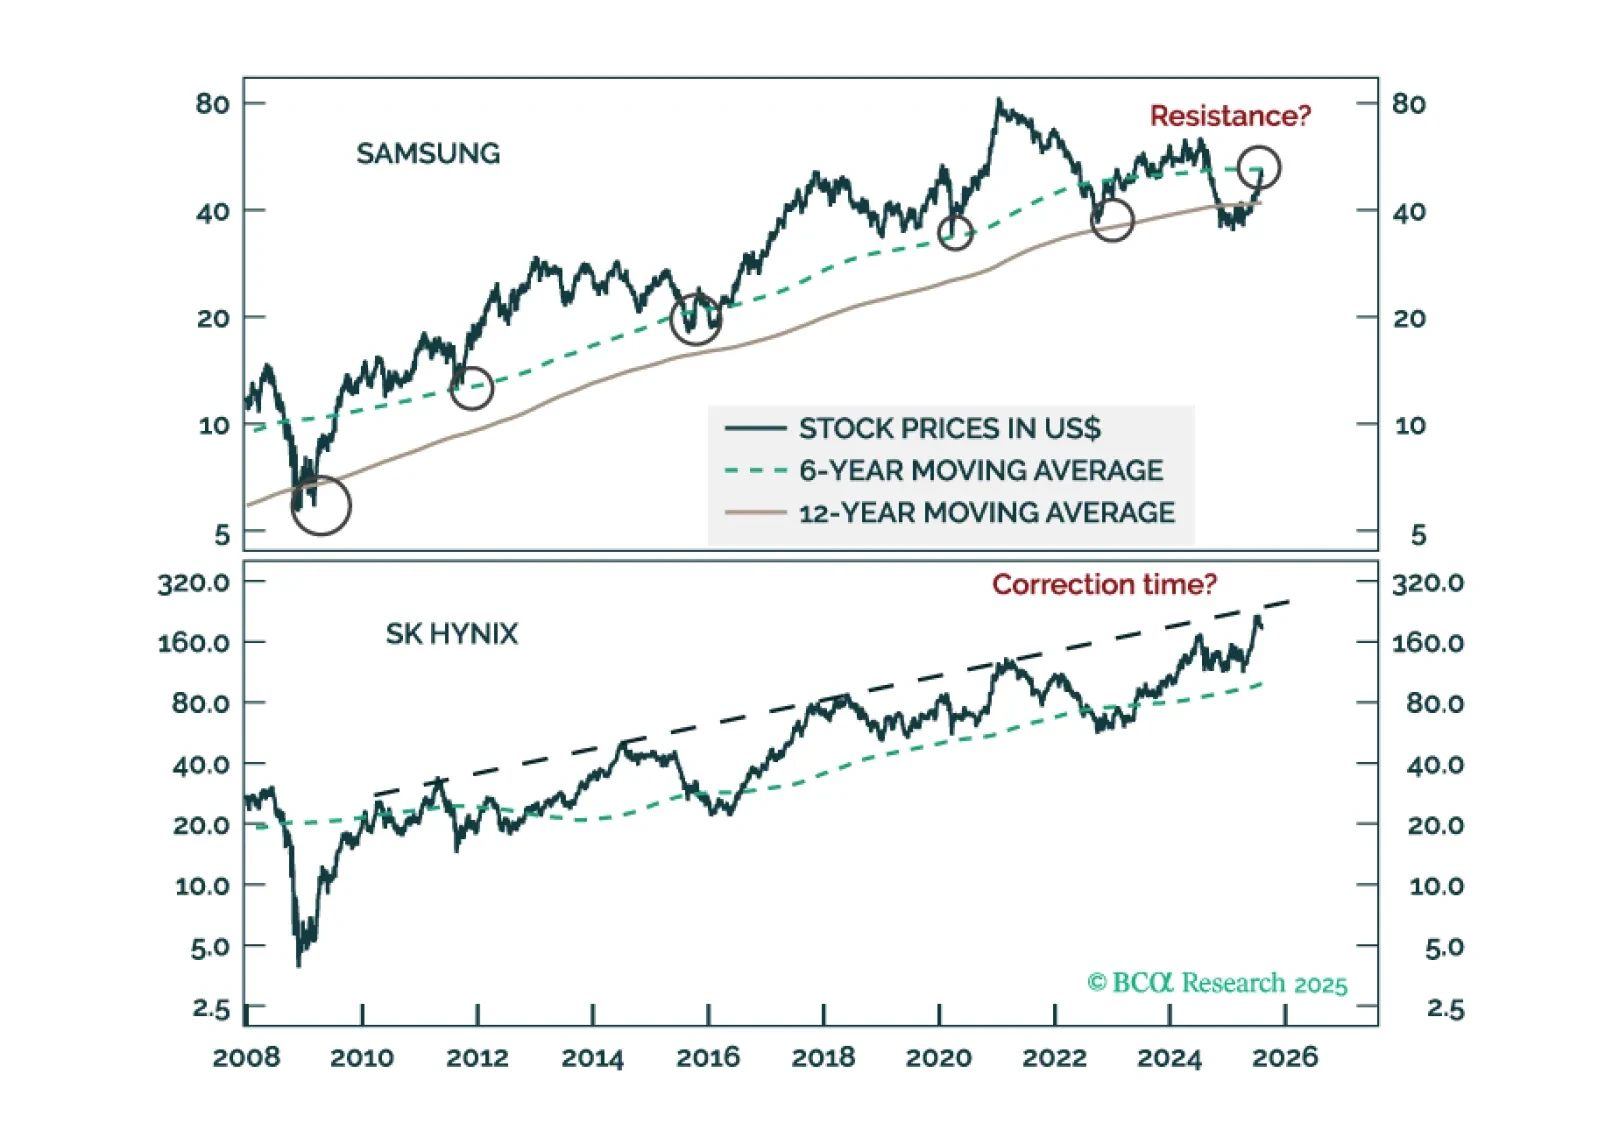
A deflationary shock from shrinking exports will ripple throughout the Korean economy. We are downgrading the KOSPI from overweight to neutral and reiterating a long position in 10-year domestic bonds, currency unhedged.
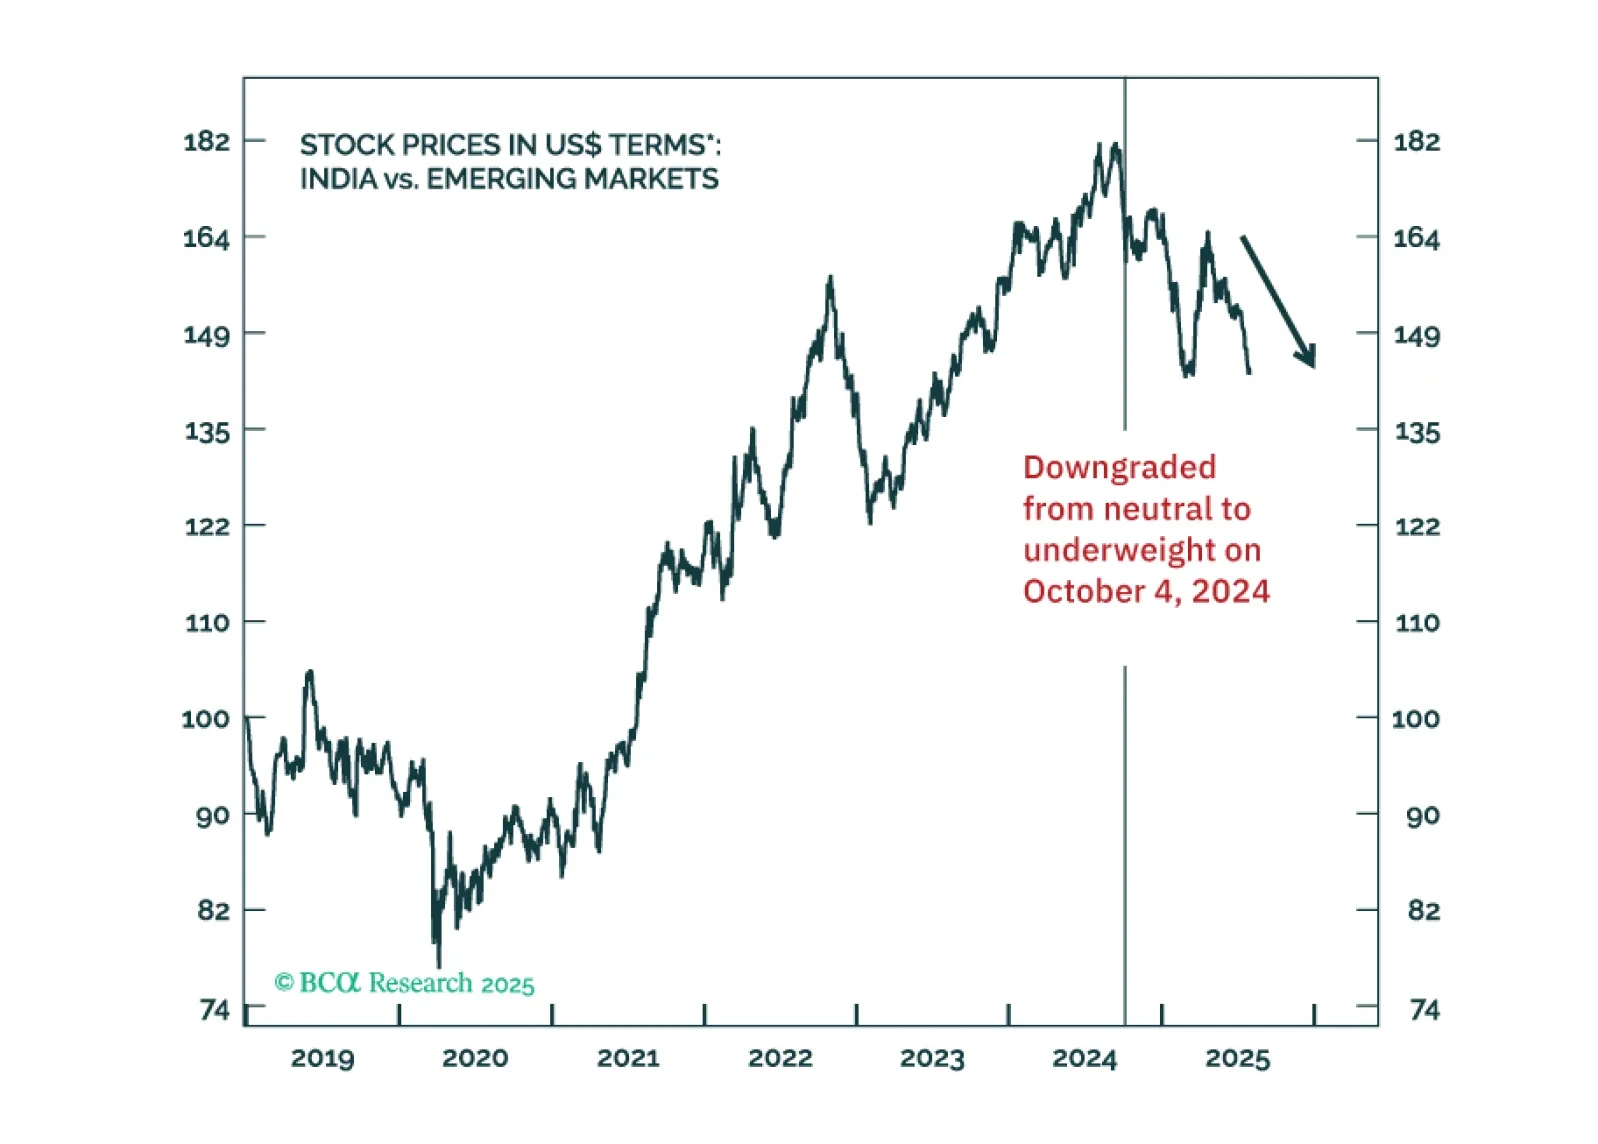
A high US tariff and the lingering uncertainties on the US-India trade deal will hurt investors sentiment. This and contracting corporate profits will push share prices lower. Stay underweight Indian stocks.
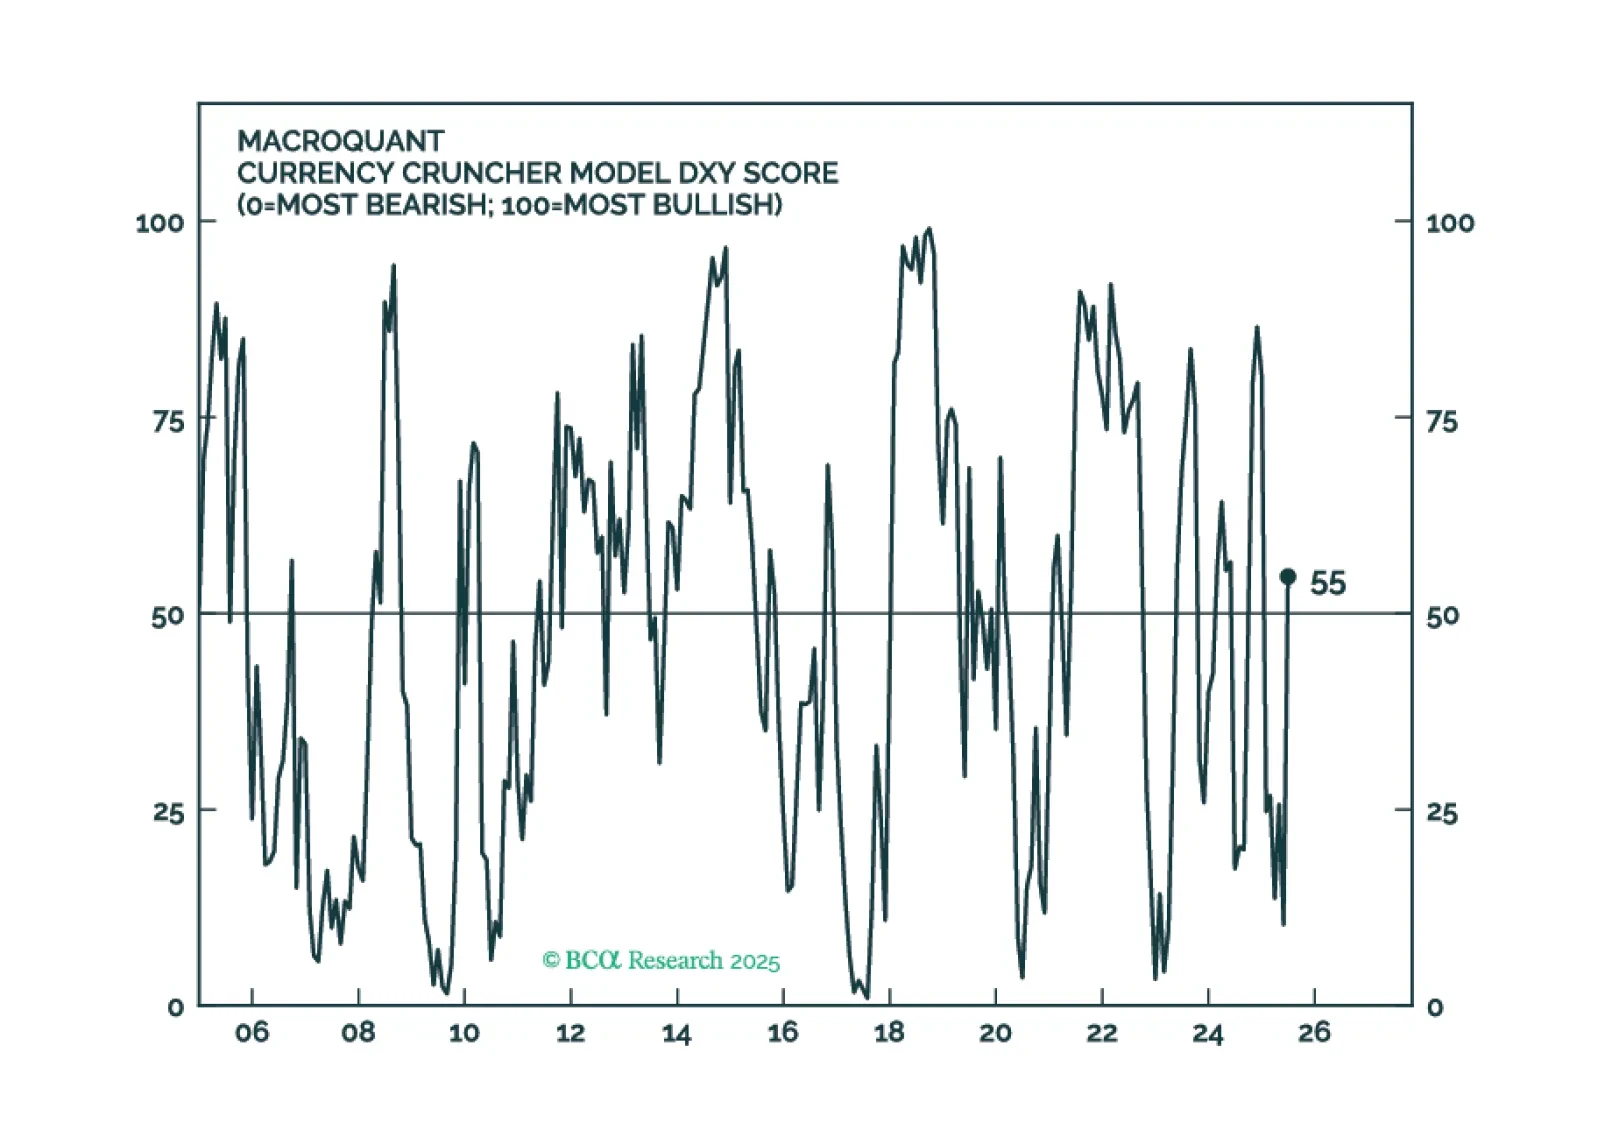
MacroQuant is recommending that equity investors keep their finger near the eject button but avoid pressing it for now. The model is warming up to the dollar again and sees scope for oil prices to rise.
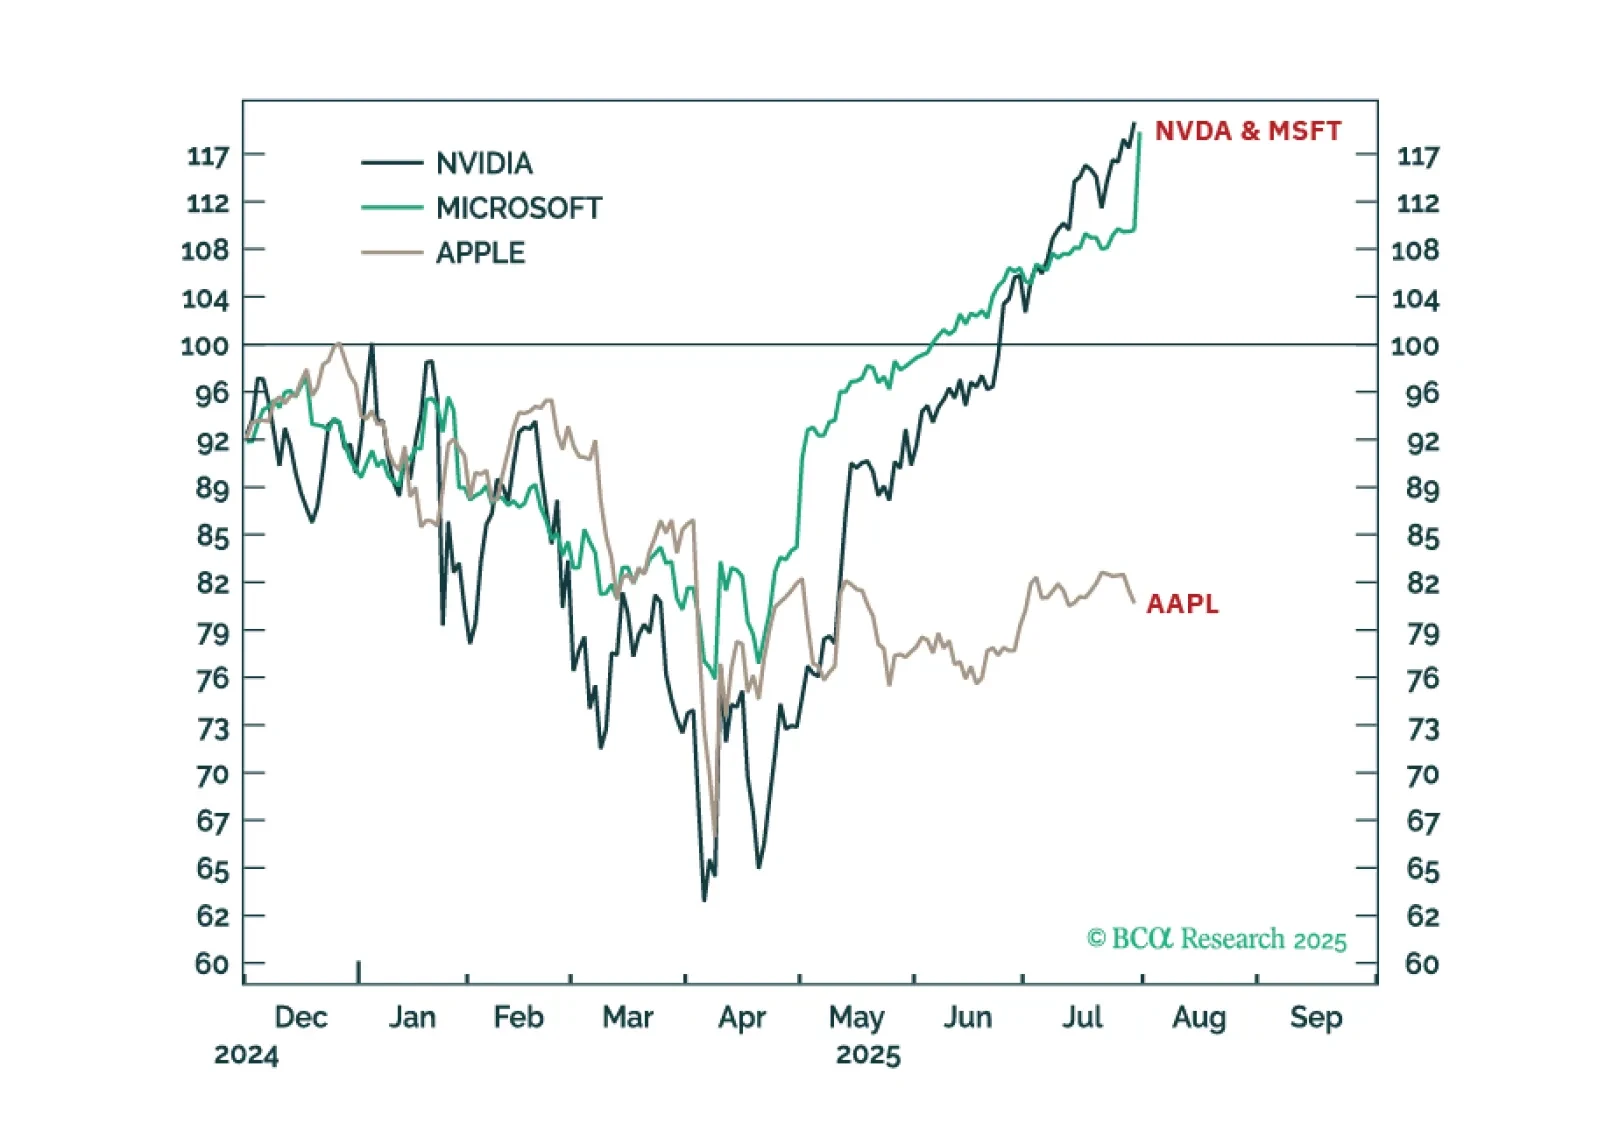
Microsoft has gone up in a worryingly near-perfect straight line with dimension 1.098. Take August off before making a big commitment to stocks. Plus: a new tactical trade is to go long USD/HUF.
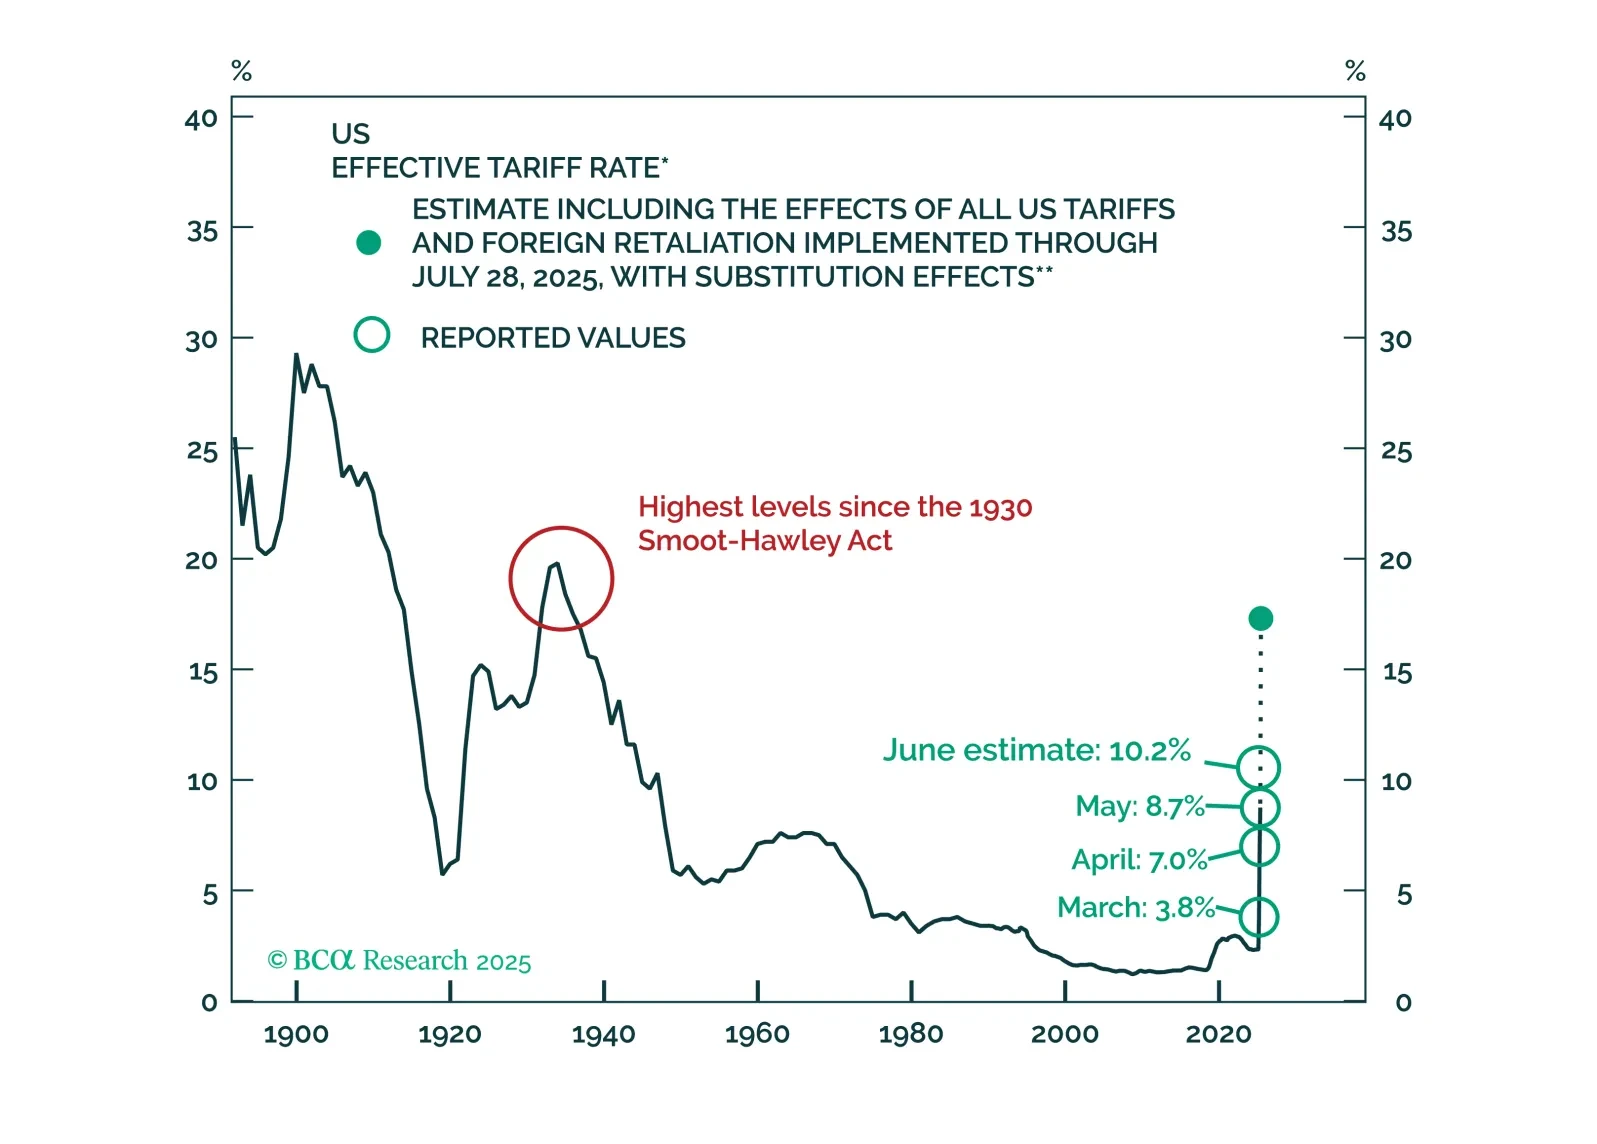
We will only move to a fully defensive stance if the “whites of the recession’s eyes” appear. So far, they have not. We will be increasingly looking to our MacroQuant model for guidance on when the next turning point in markets may come.
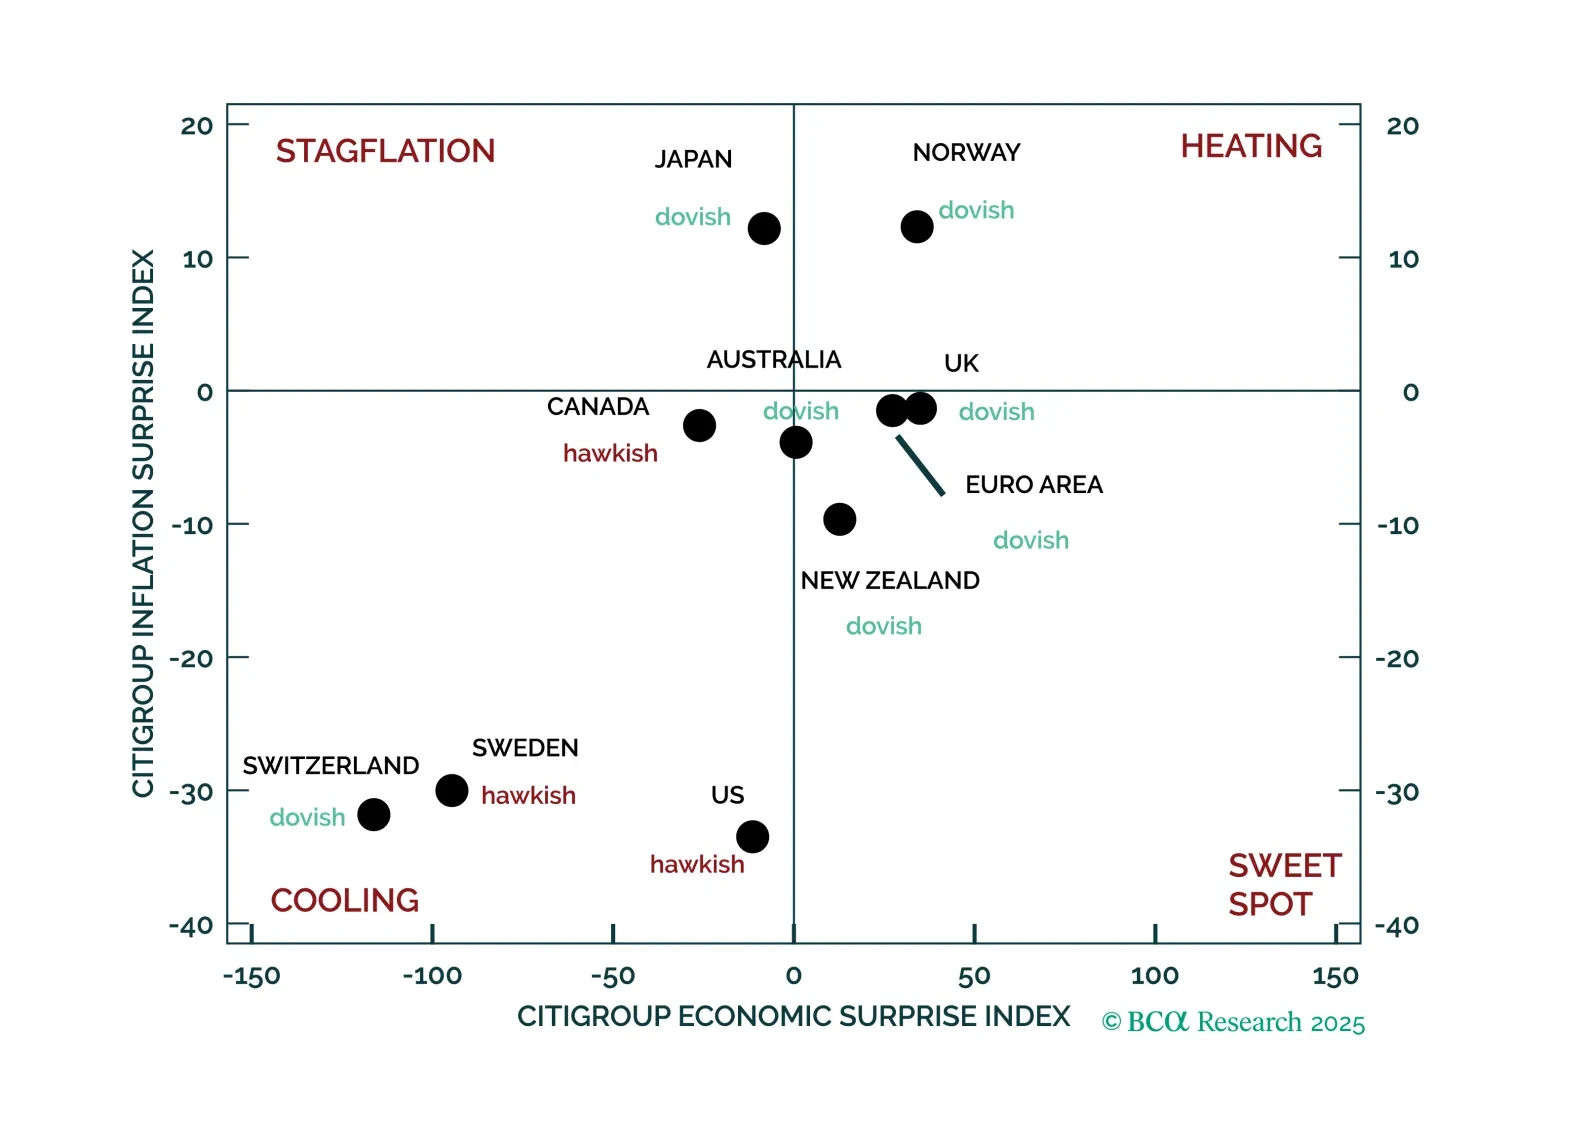
We apply a systematic approach to investing based on economic, inflation, and monetary policy surprises to the foreign exchange market. The signals from this framework are broadly consistent with the tactical views of our FX strategists, which anticipate a pause in the USD’s decline and a partial reversal of the recent euro strength.