 CoreMacro
| Global
Global macro research on the forces driving the world economy, with calls across stocks, bonds, and currencies.
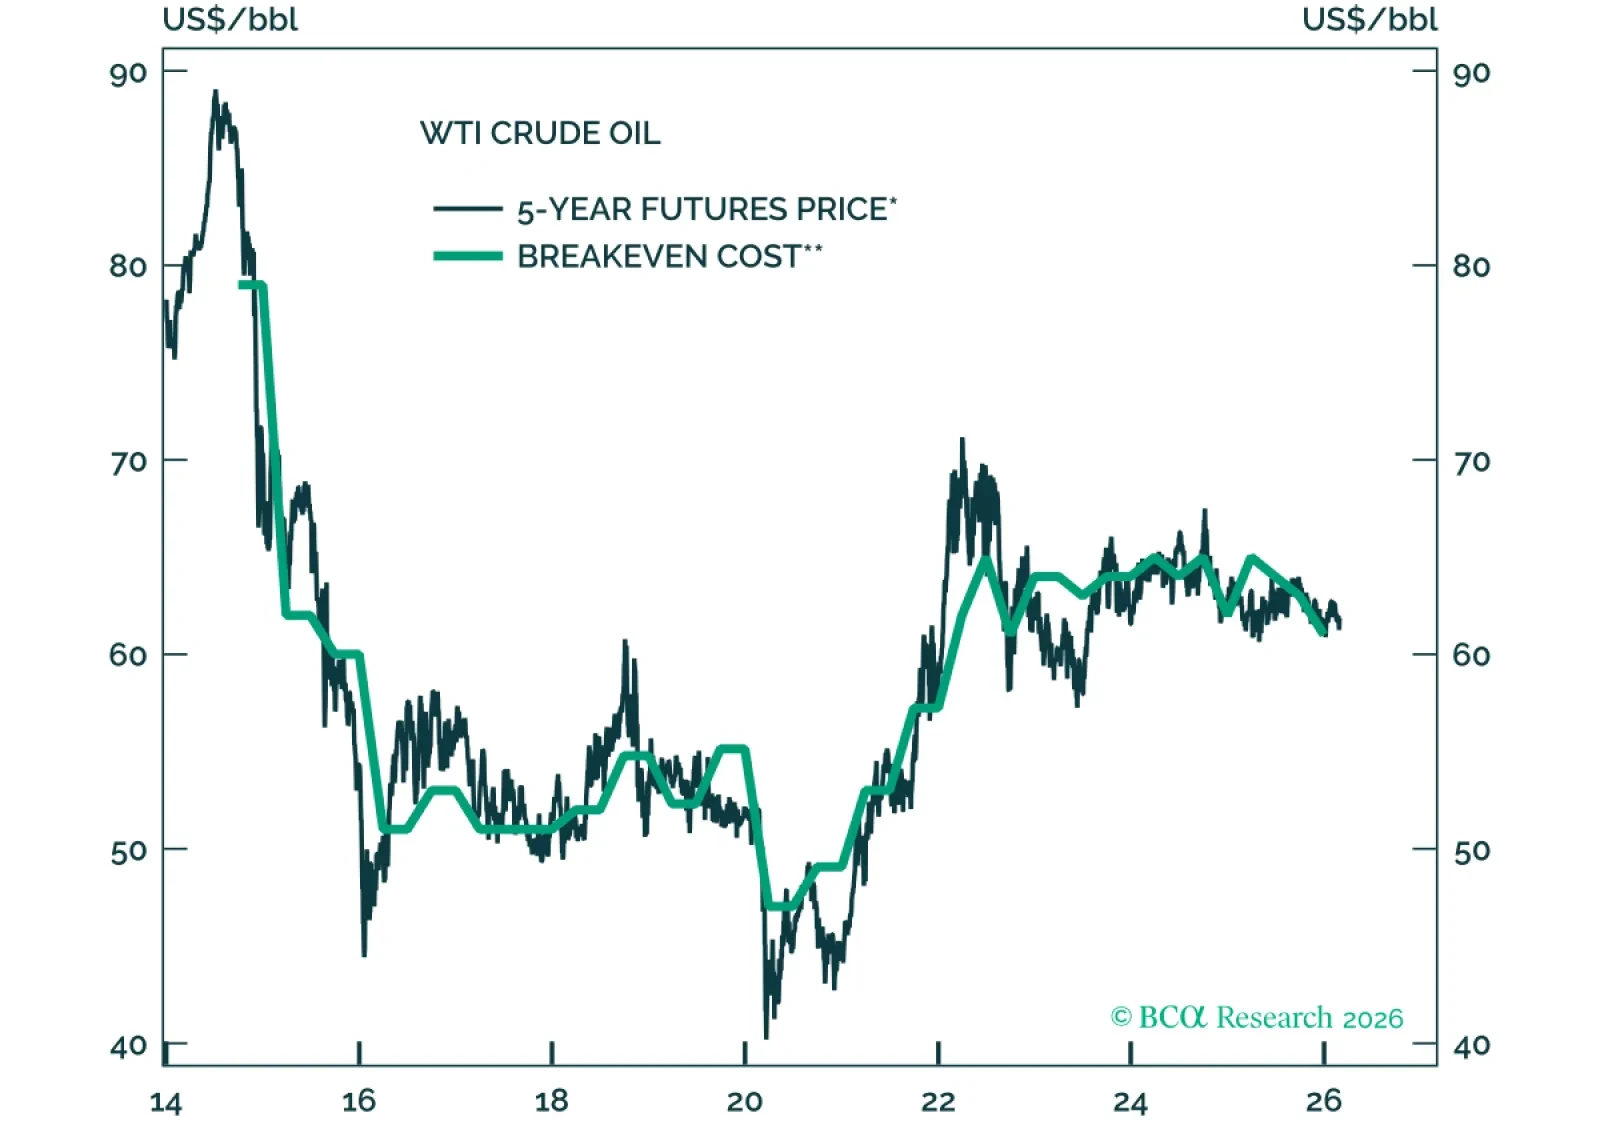
Since 1970, every US recession excluding the pandemic downturn was preceded by a sharp rise in oil prices. As I write this, WTI is trading at $71/bbl, up 24% year-to-date and up 19% relative to the Q4 2025 average. That said, today’s oil price is still only 8% higher than the average for all of 2025. If oil prices stay broadly where they are, the impact on the US economy should be limited.
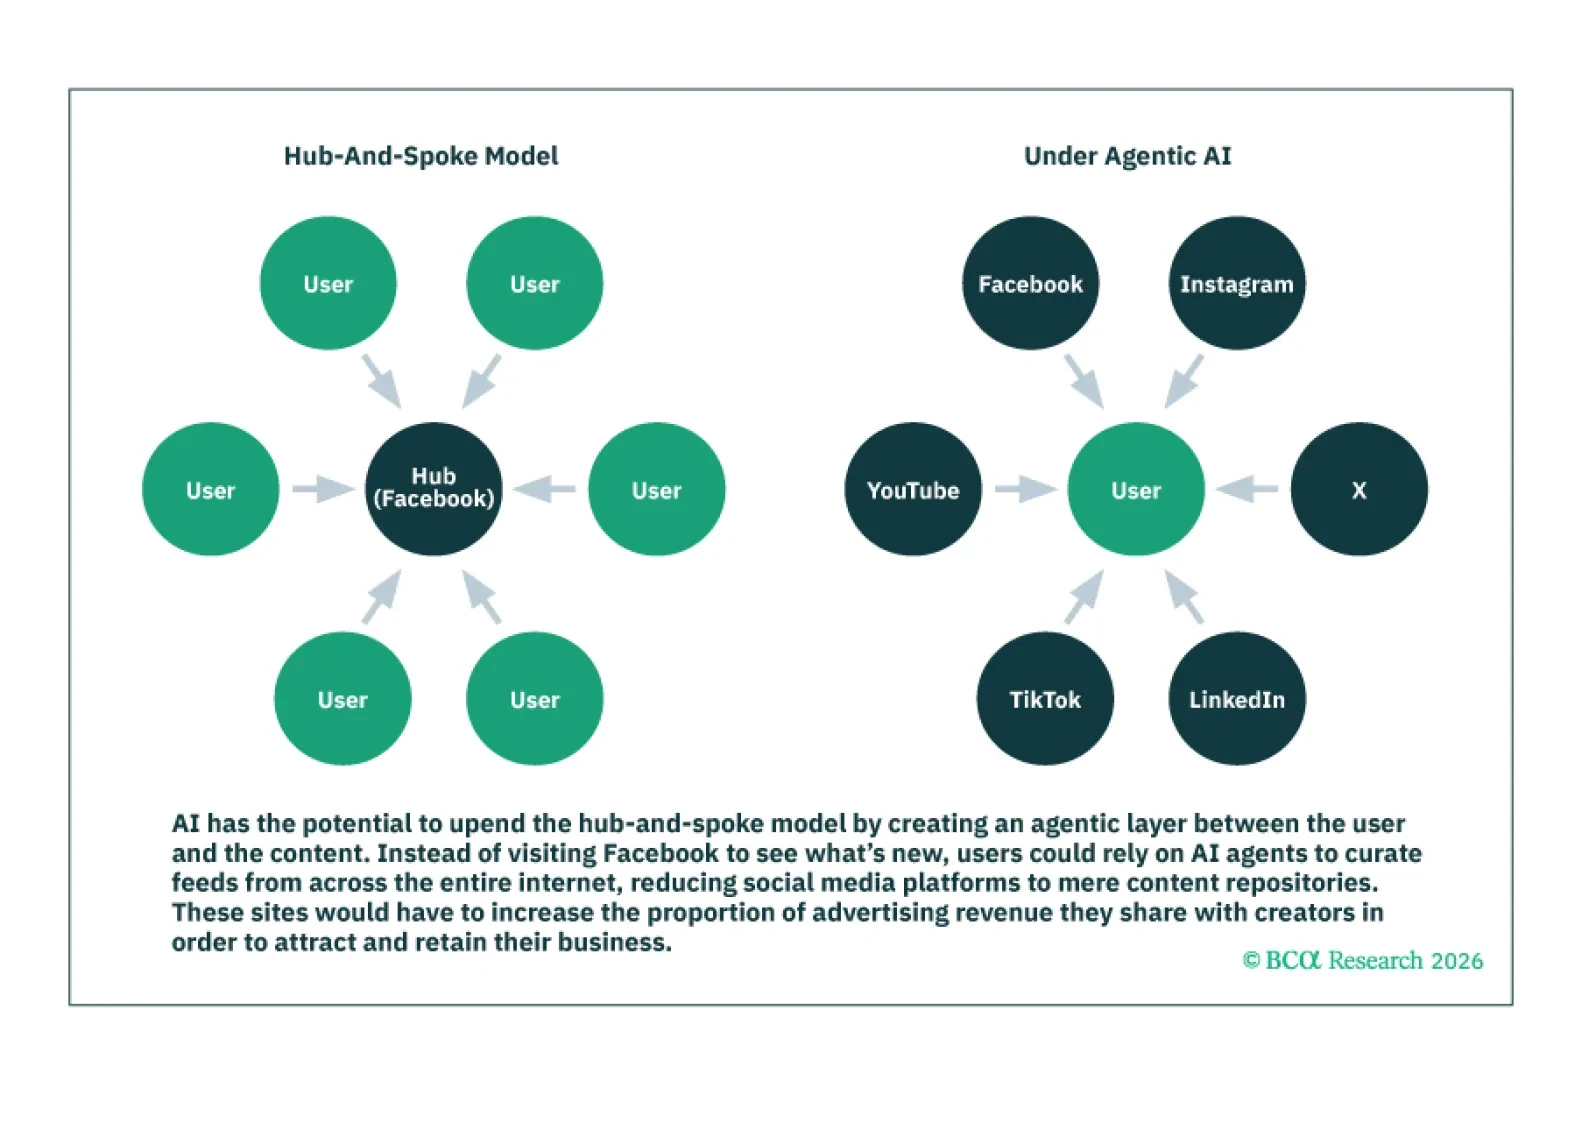
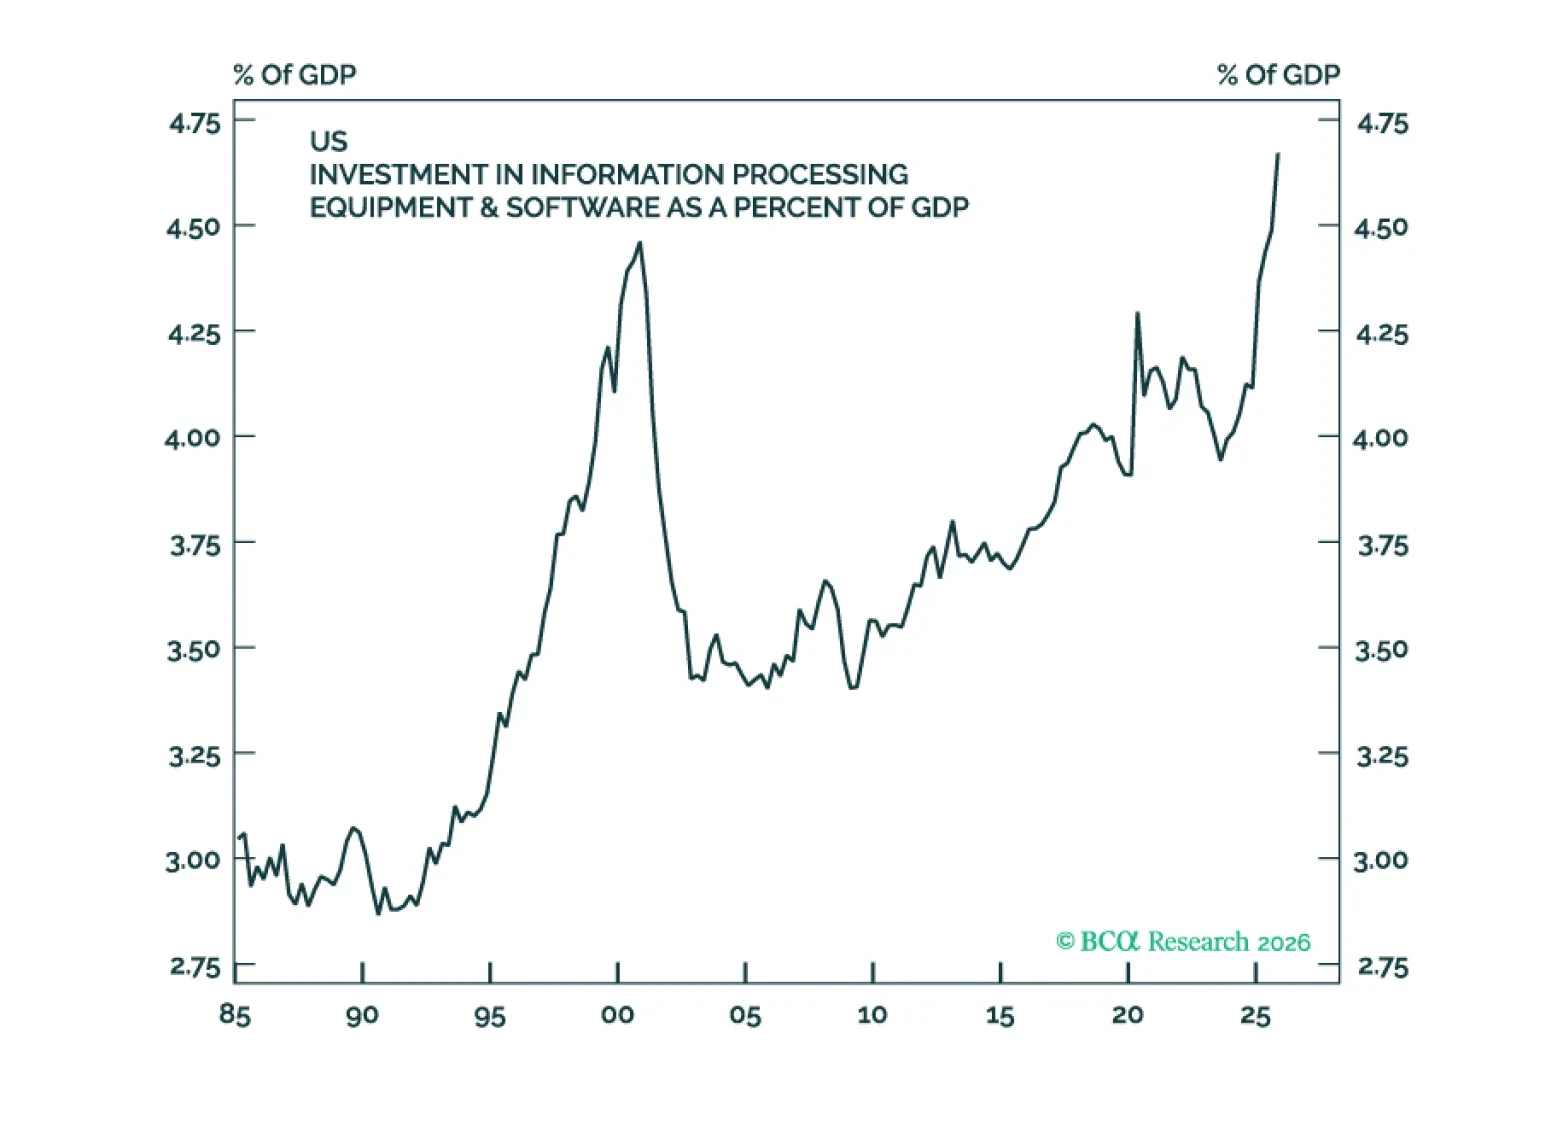
Fourth quarter US GDP growth clocked in at 1.4%, well below consensus expectations of 2.8%. We are not too troubled by the miss. The government shutdown weighed on the economy, with government spending subtracting 0.9 percentage points from growth. Real private final domestic demand – a clean measure of GDP growth that excludes government expenditure, net exports, and inventories – rose by a respectable 2.4%.
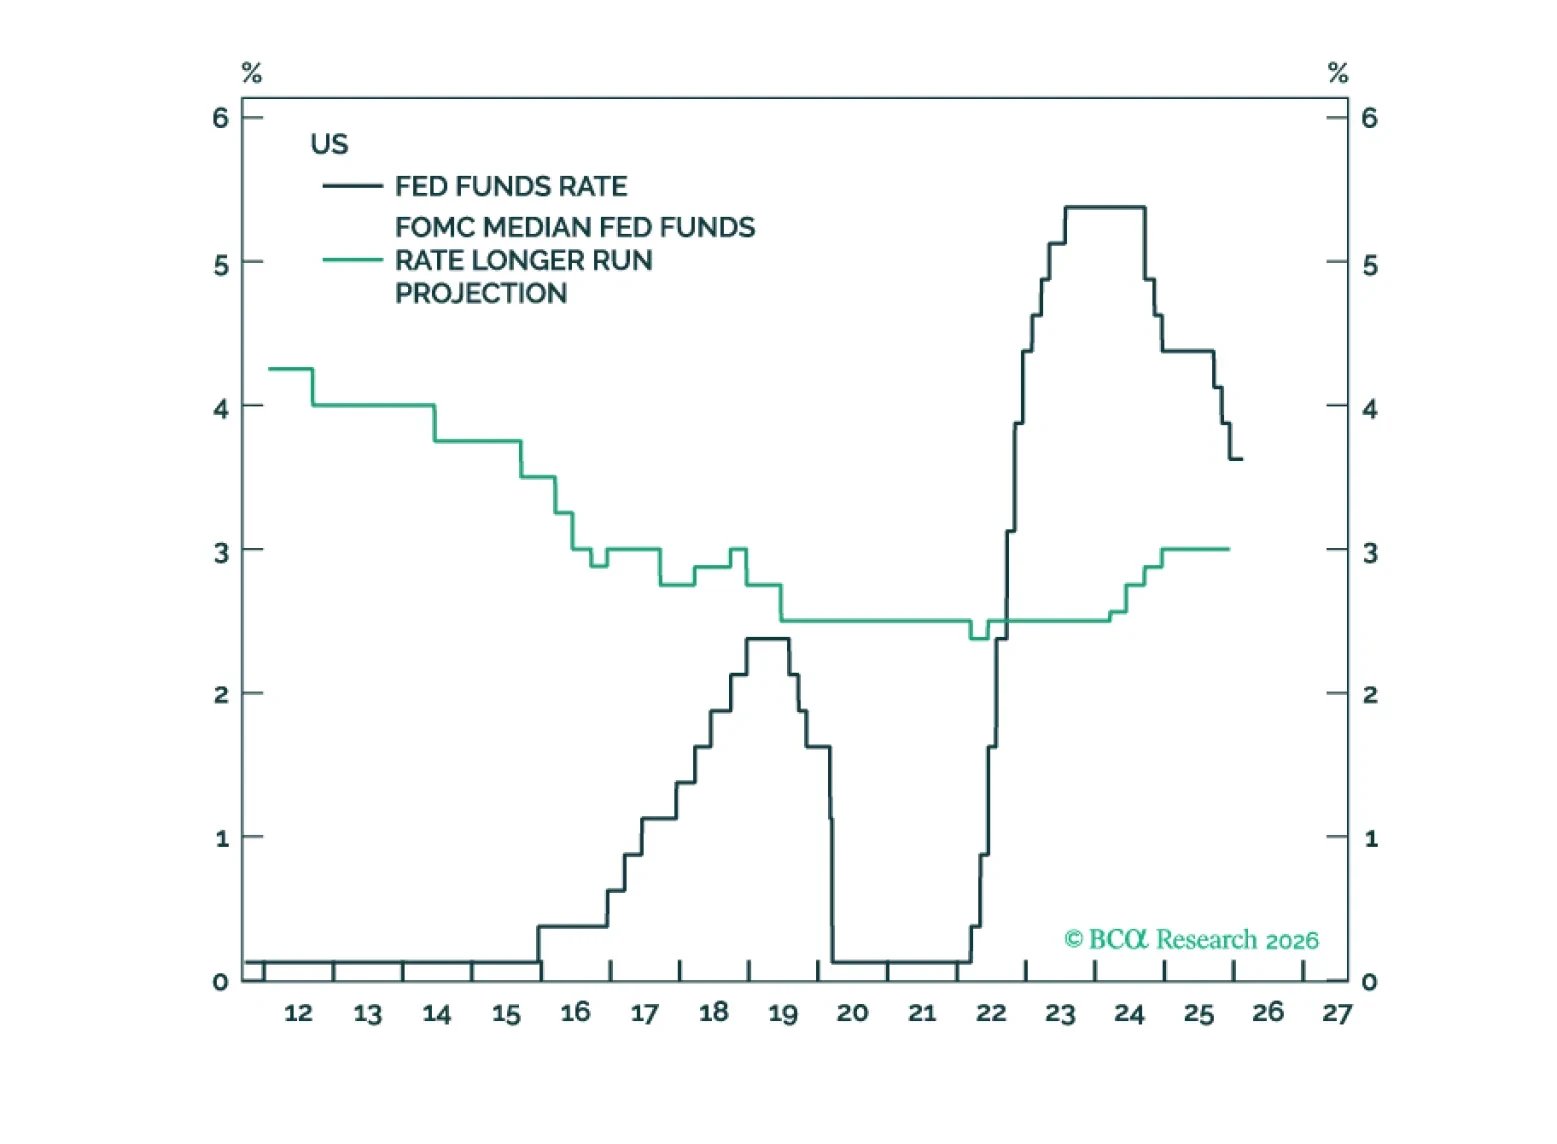
The neutral rate in the US is being propped up by a variety of forces that are at risk of reversing. These include the AI capex boom, large budget deficits, and the extraordinarily high level of household wealth. As such, interest rates are likely to surprise to the downside over the next few years.
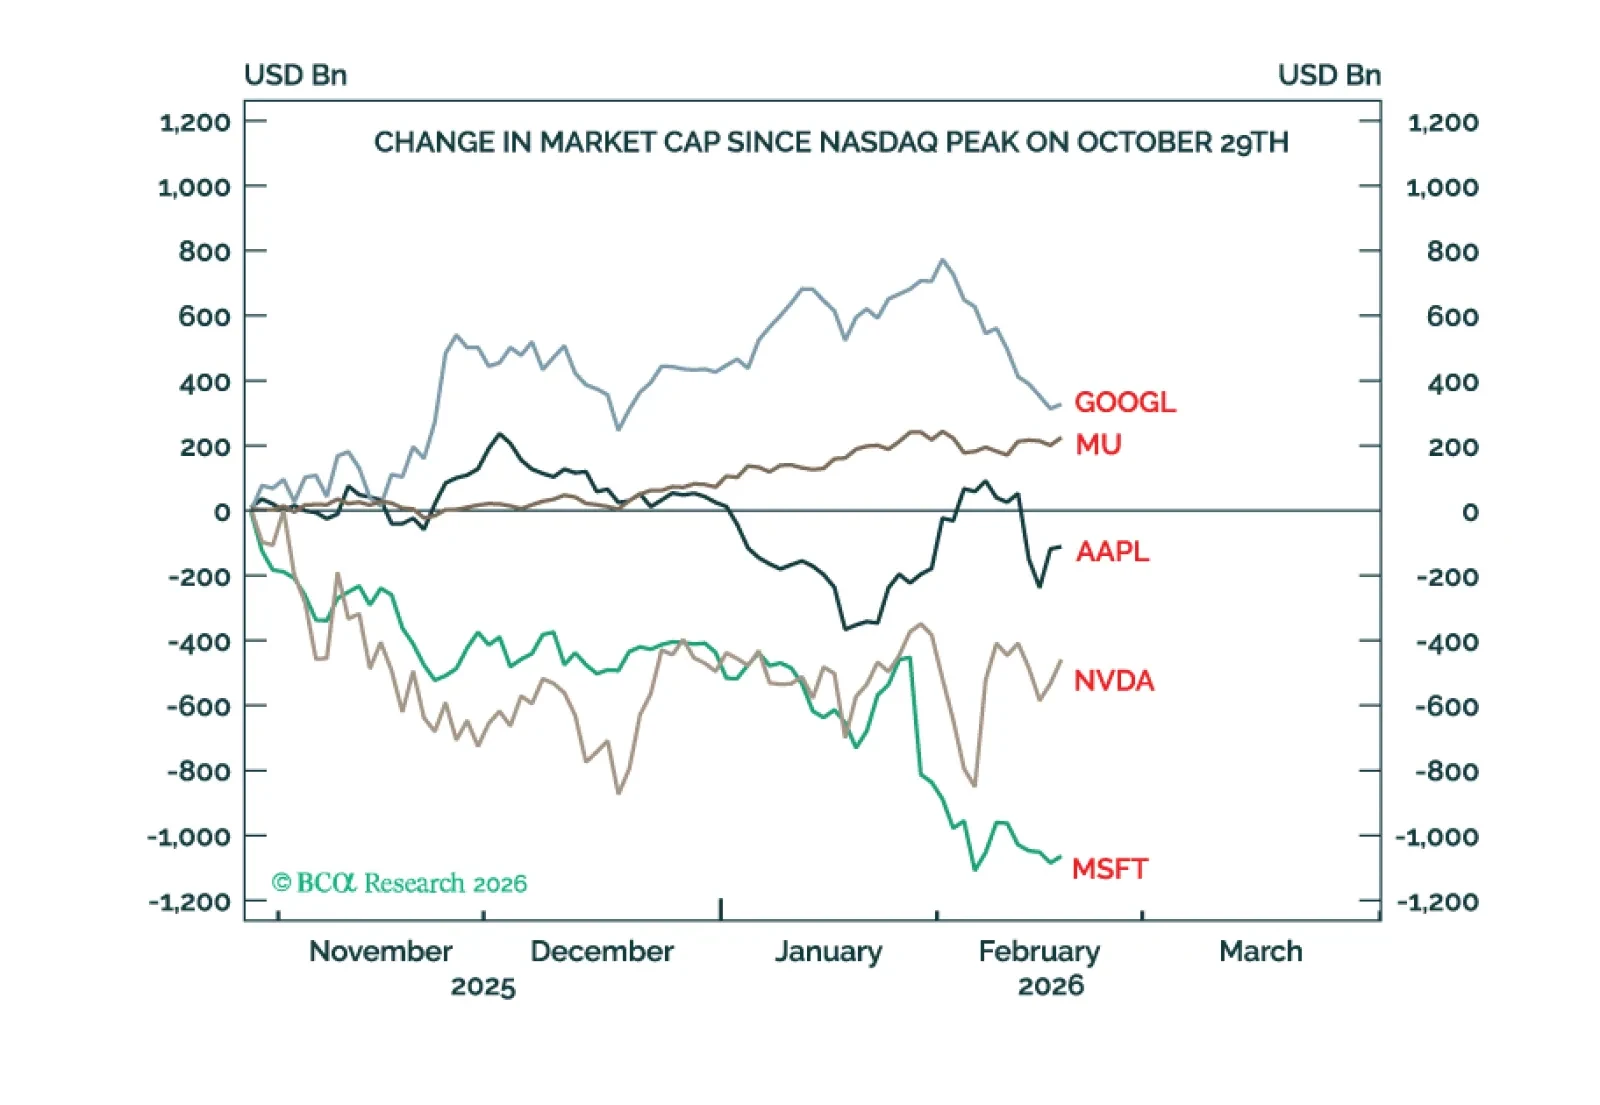
Tech has starkly underperformed other equity sectors and the tech-heavy US market has underperformed non-US markets, but global stocks are up and have comfortably outperformed bonds. This pattern of performances is likely to continue through the rest of 2026. Plus, two new tactical trades are: long coffee; and long ETH.
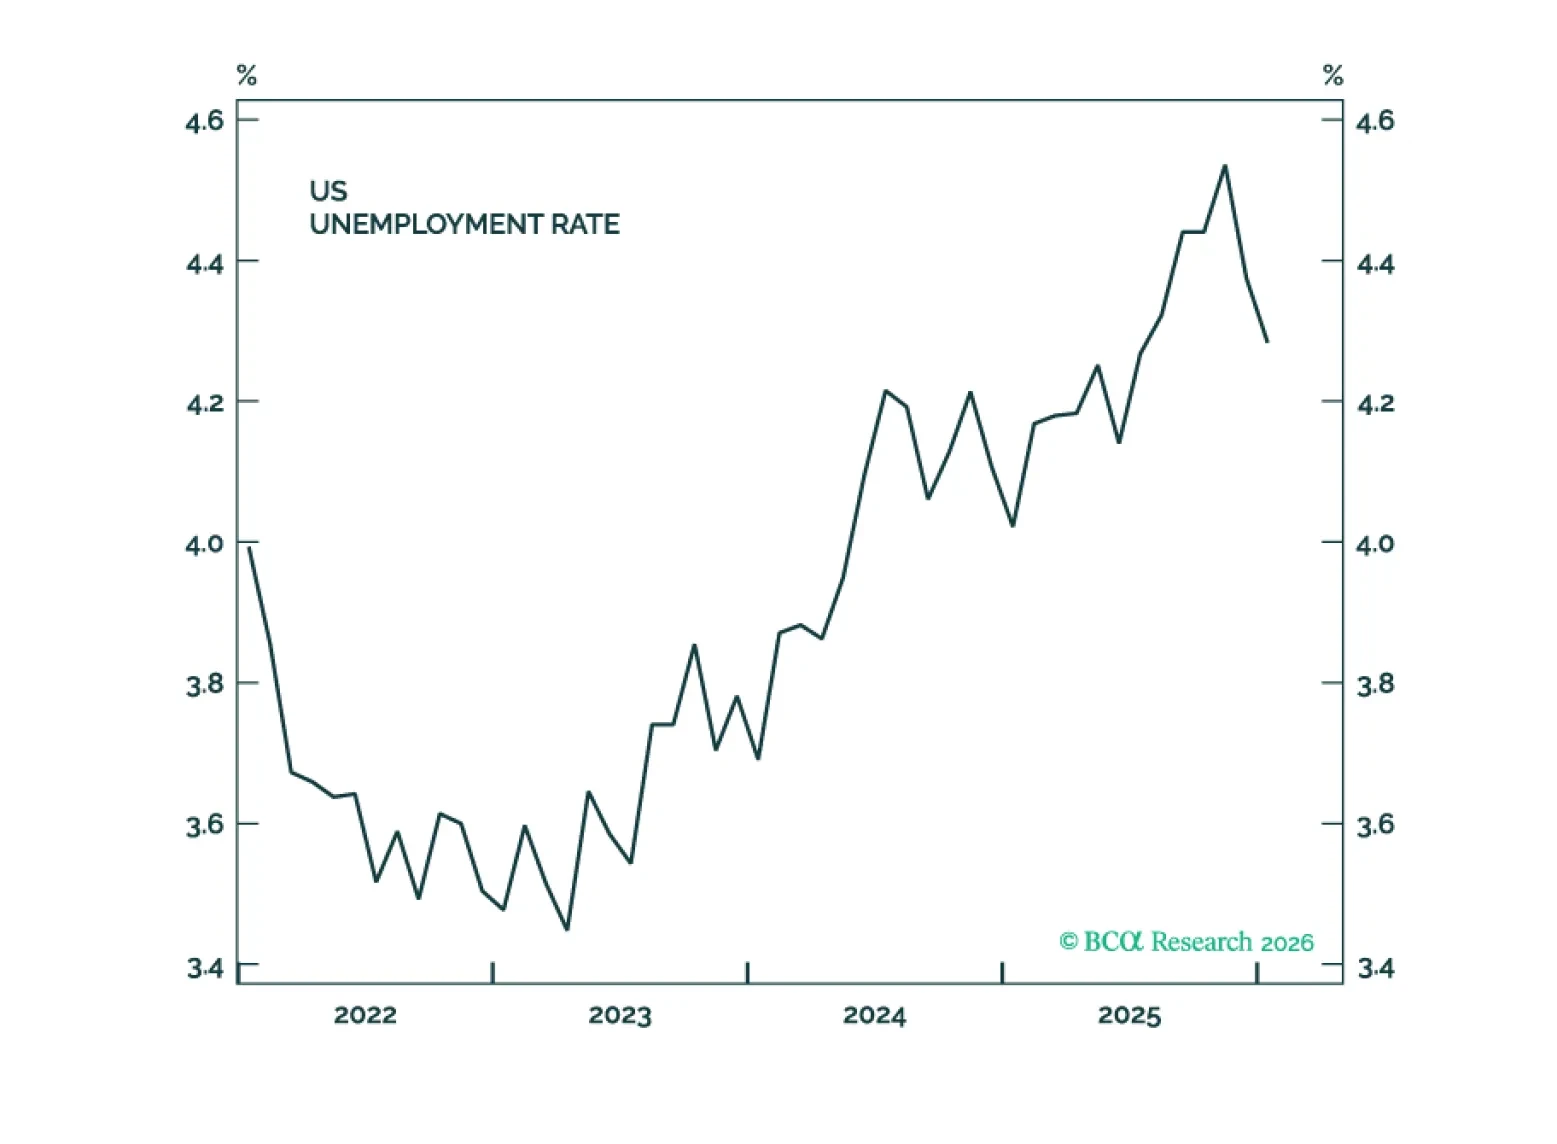
The January jobs report was unambiguously strong. Although the 172K gain in private payrolls will almost certainly be revised down, the message from the "ratios" was reassuring: The unemployment rate fell for a second straight month, the labor force participation rate increased, the share of workers who are involuntarily part-time declined, and the prime-age employment-to-population ratio rose back to its all-time high. Unlike the payroll survey, the household survey from which ratios are calculated is subject to minimal revisions.
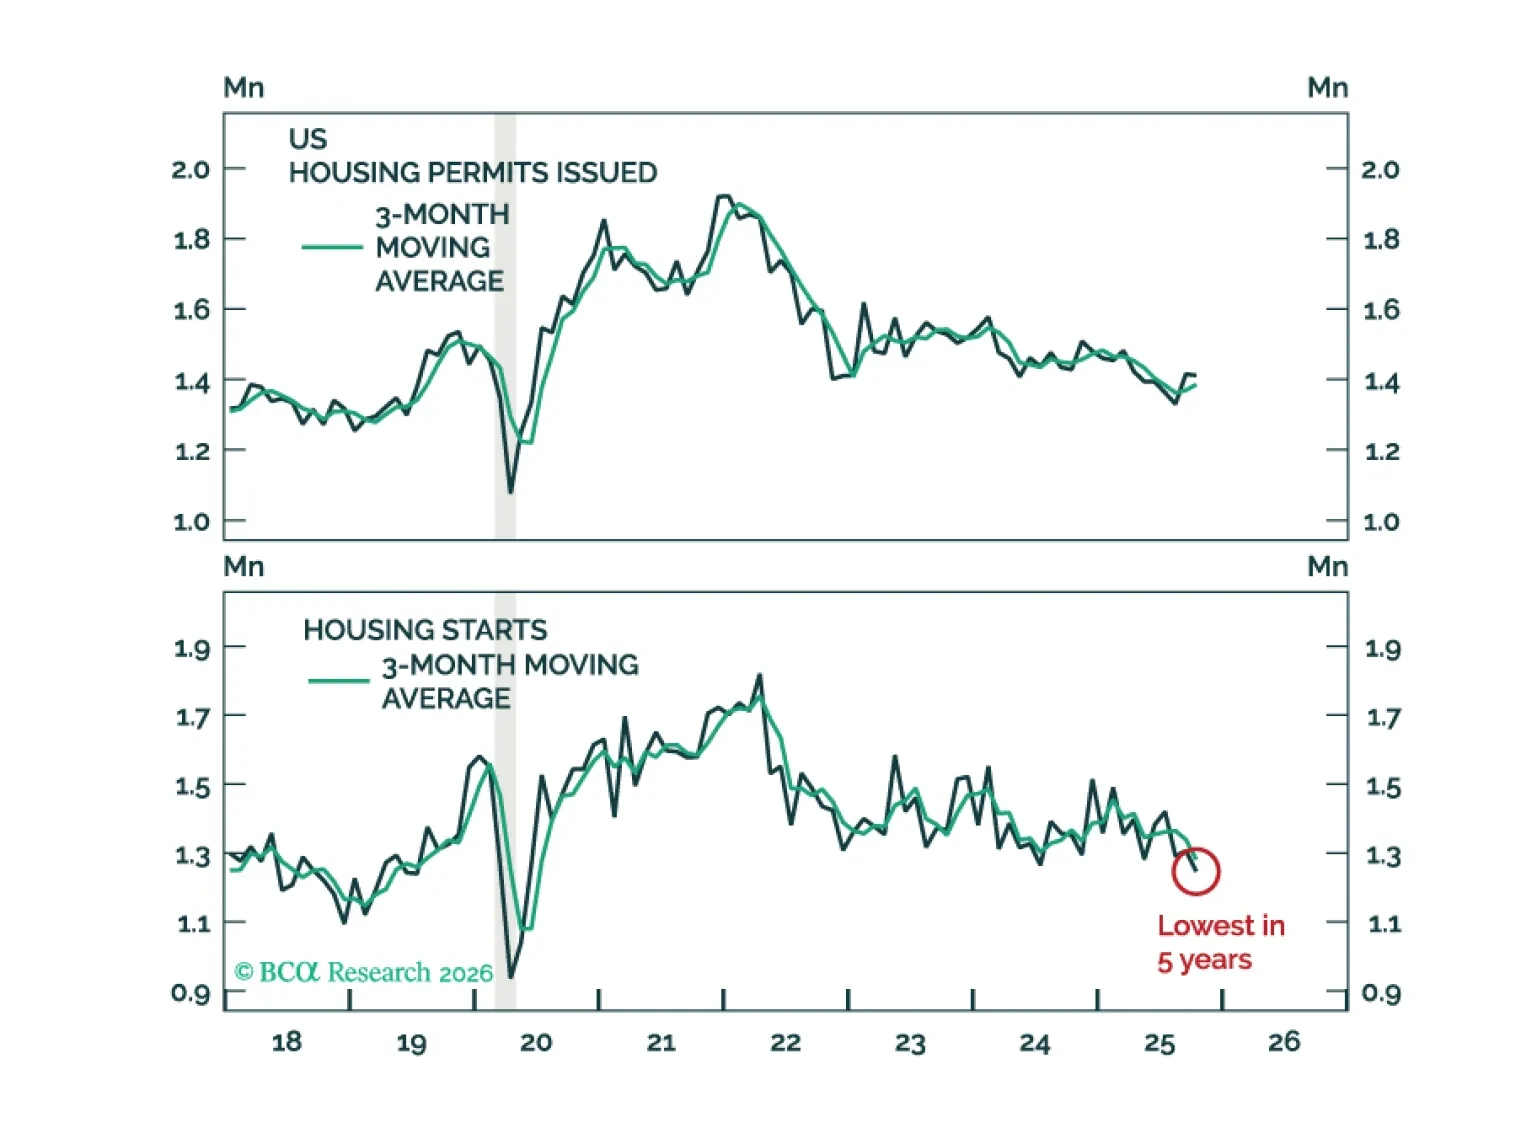
The US residential real estate market remains soft. While the decline in mortgage rates is a positive, it is too early to bet on housing becoming the engine of growth for the US economy this year.