 FICC
One macro framework for rates, FX, credit, and commodities, helping investors connect cross-market signals and position with clarity and conviction.
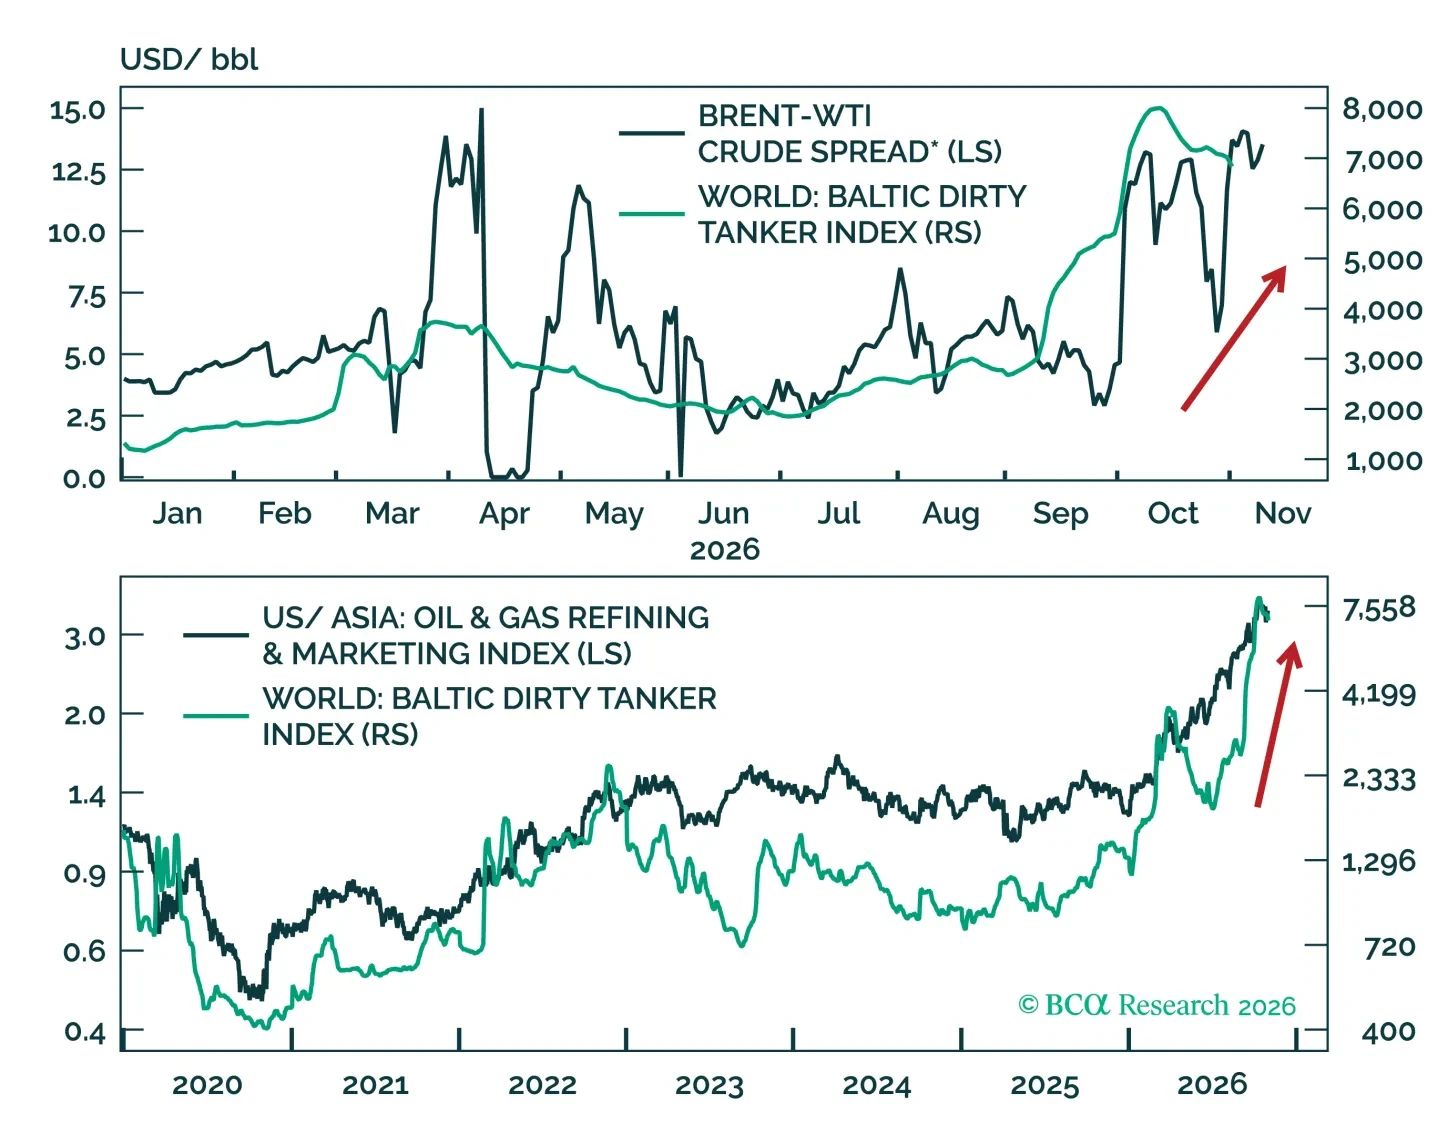
Commodities have diverged sharply in recent months. We explain why energy prices are likely to stay elevated after the US midterms, why gold’s slide should prove limited, and how we are positioning for the months ahead.
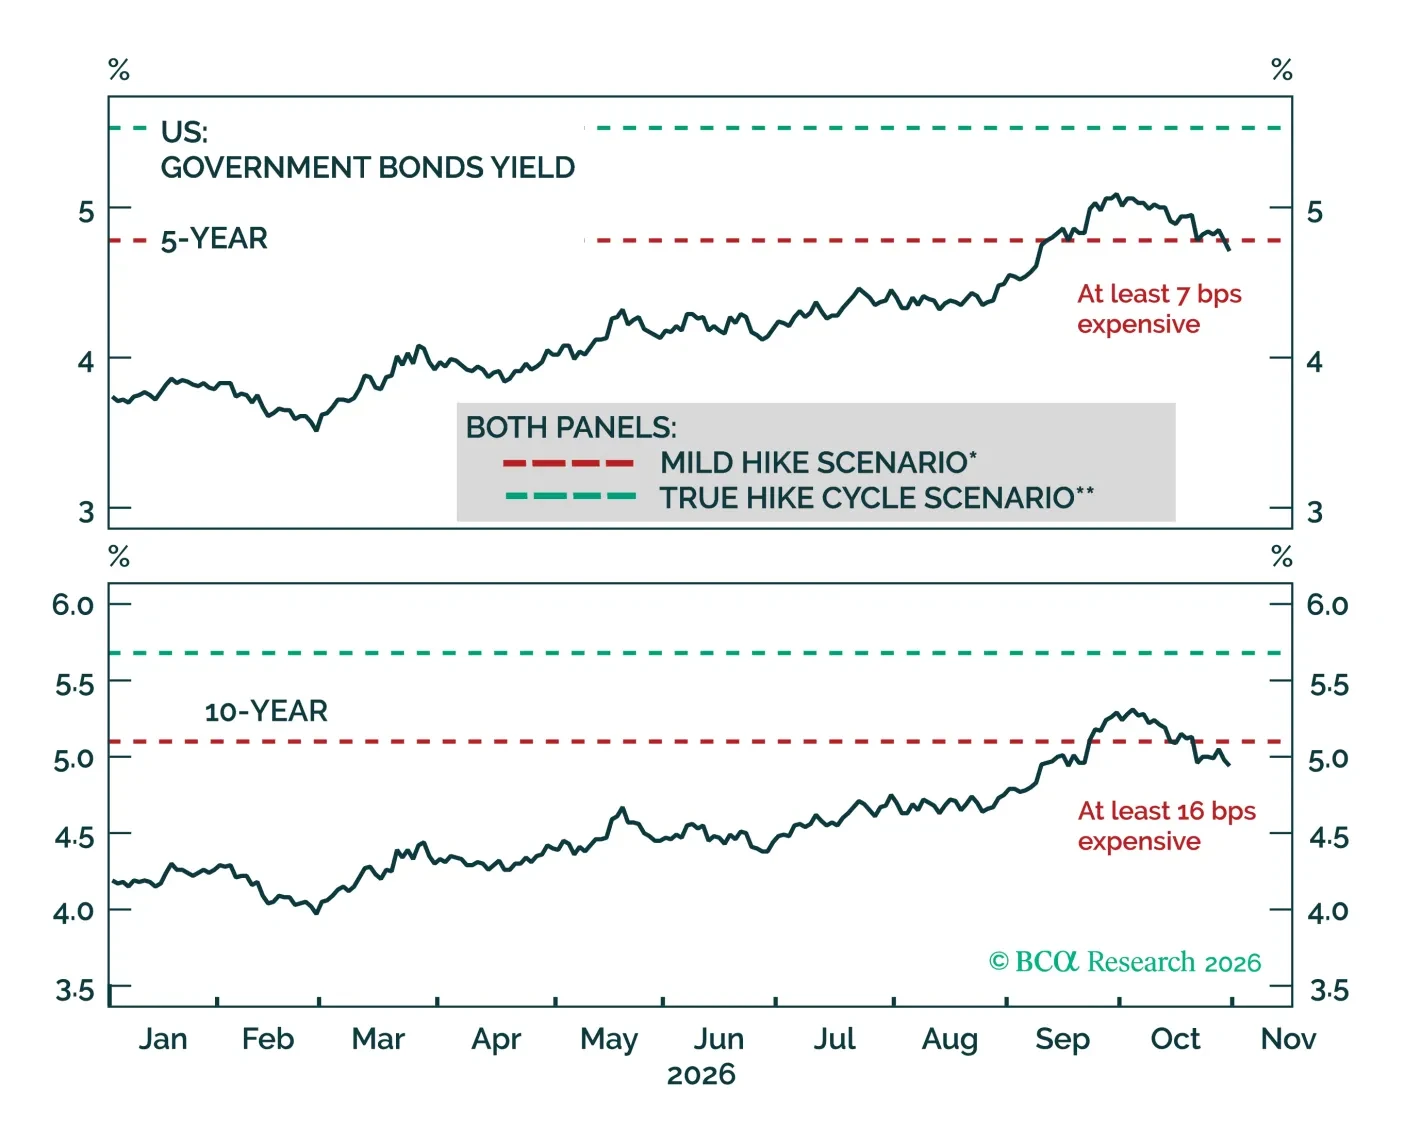
US Treasury yields have fallen below our fair value estimate as investors rotated out of AI equities and into fixed income. We lay out why near-term inflation risks argue for a rebound, and the tactical trades we initiate to position for it.
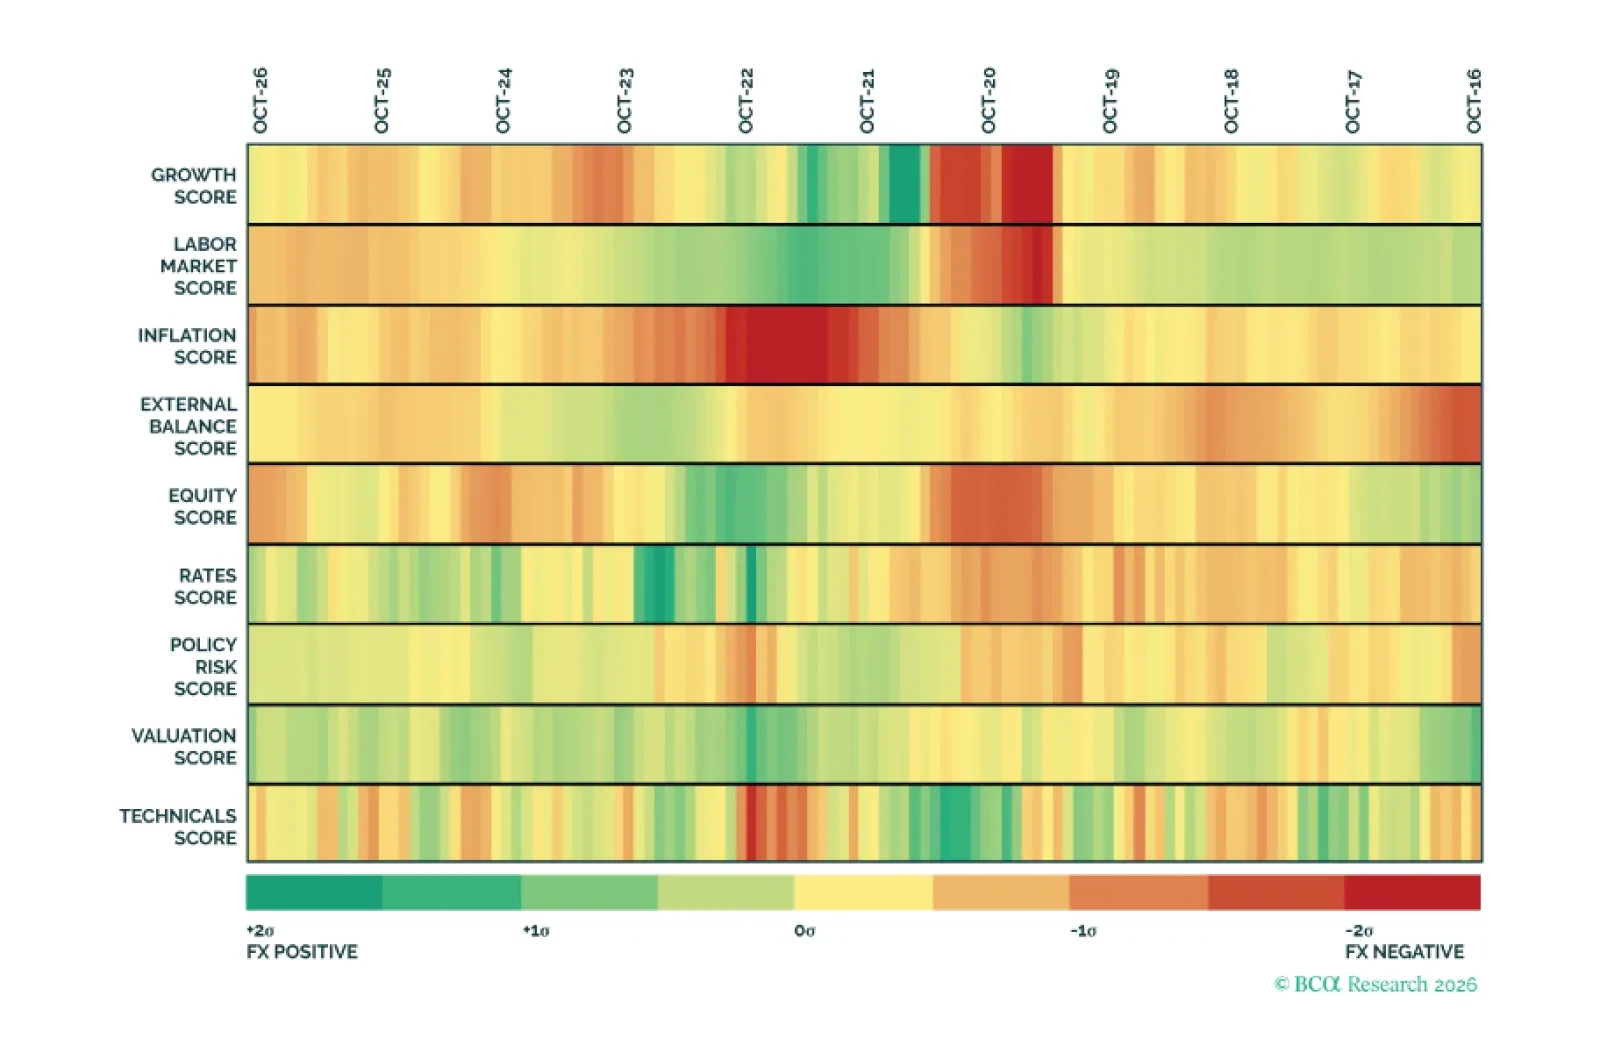
GBP offers attractive carry today, but the market’s aggressive rate hike pricing is likely to turn into a headwind within 12 months. Our latest Currency Chartpack examines the valuation, growth, rate, and policy drivers of the pound, showing why the long-term outlook is less rosy than near-term data implies.
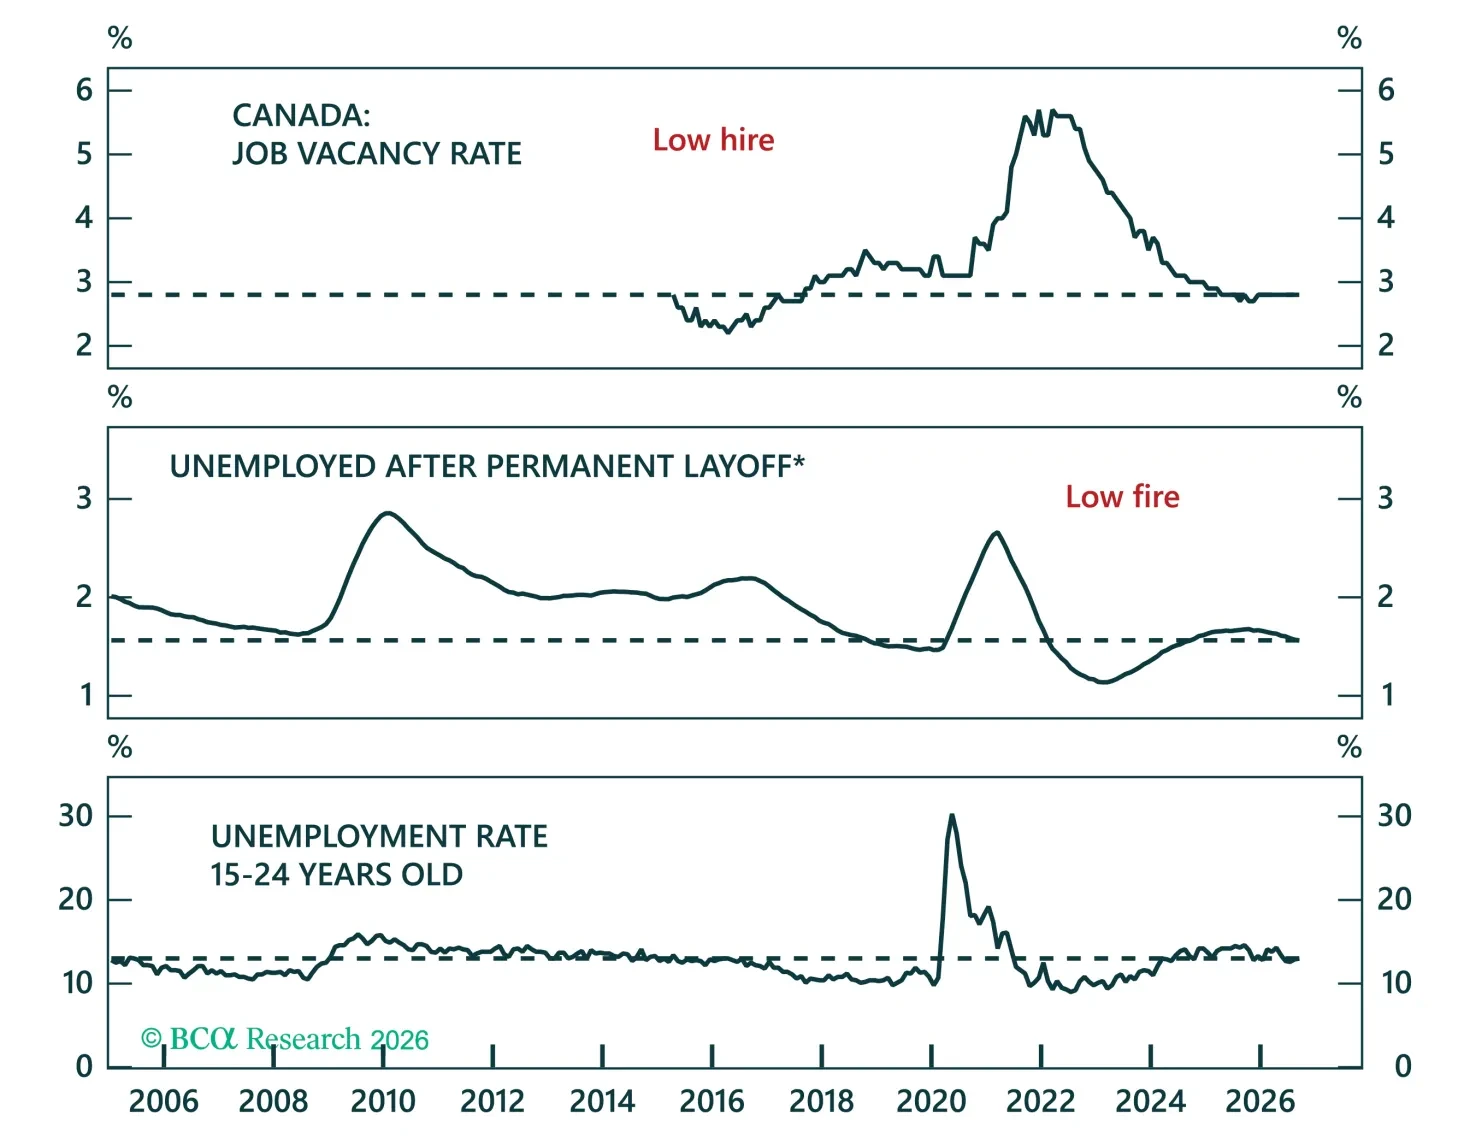
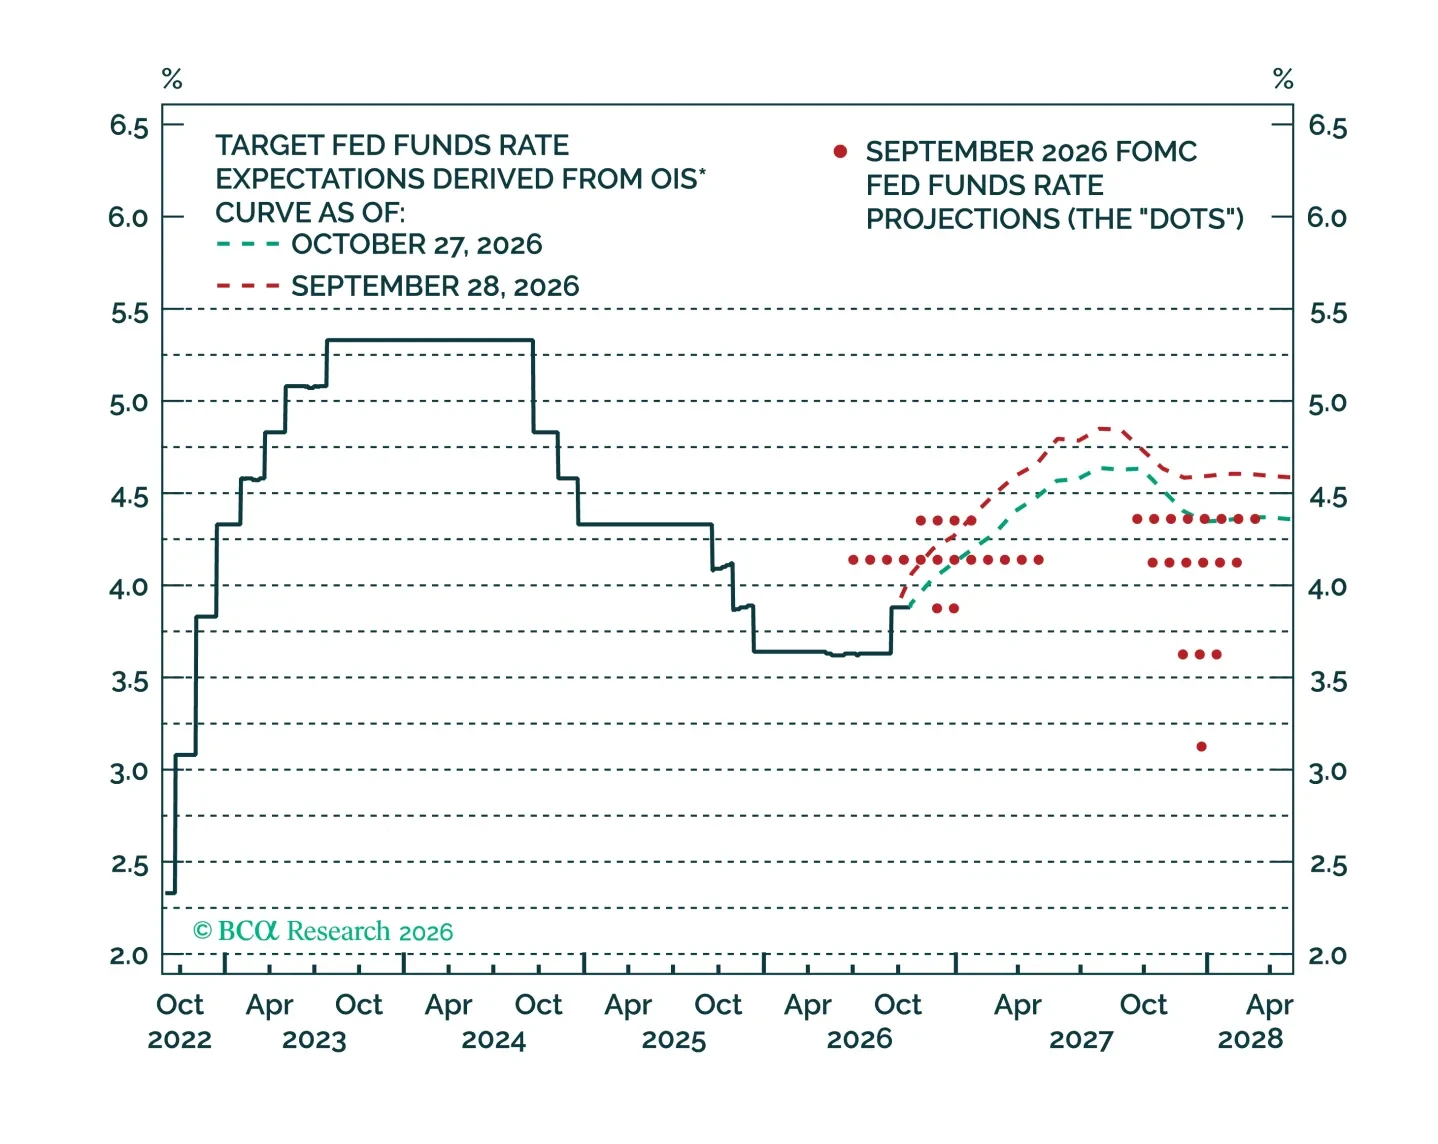
The Fed will hike rates at a pace of 25 bps per quarter until either falling inflation or tighter financial conditions cause it to stop.
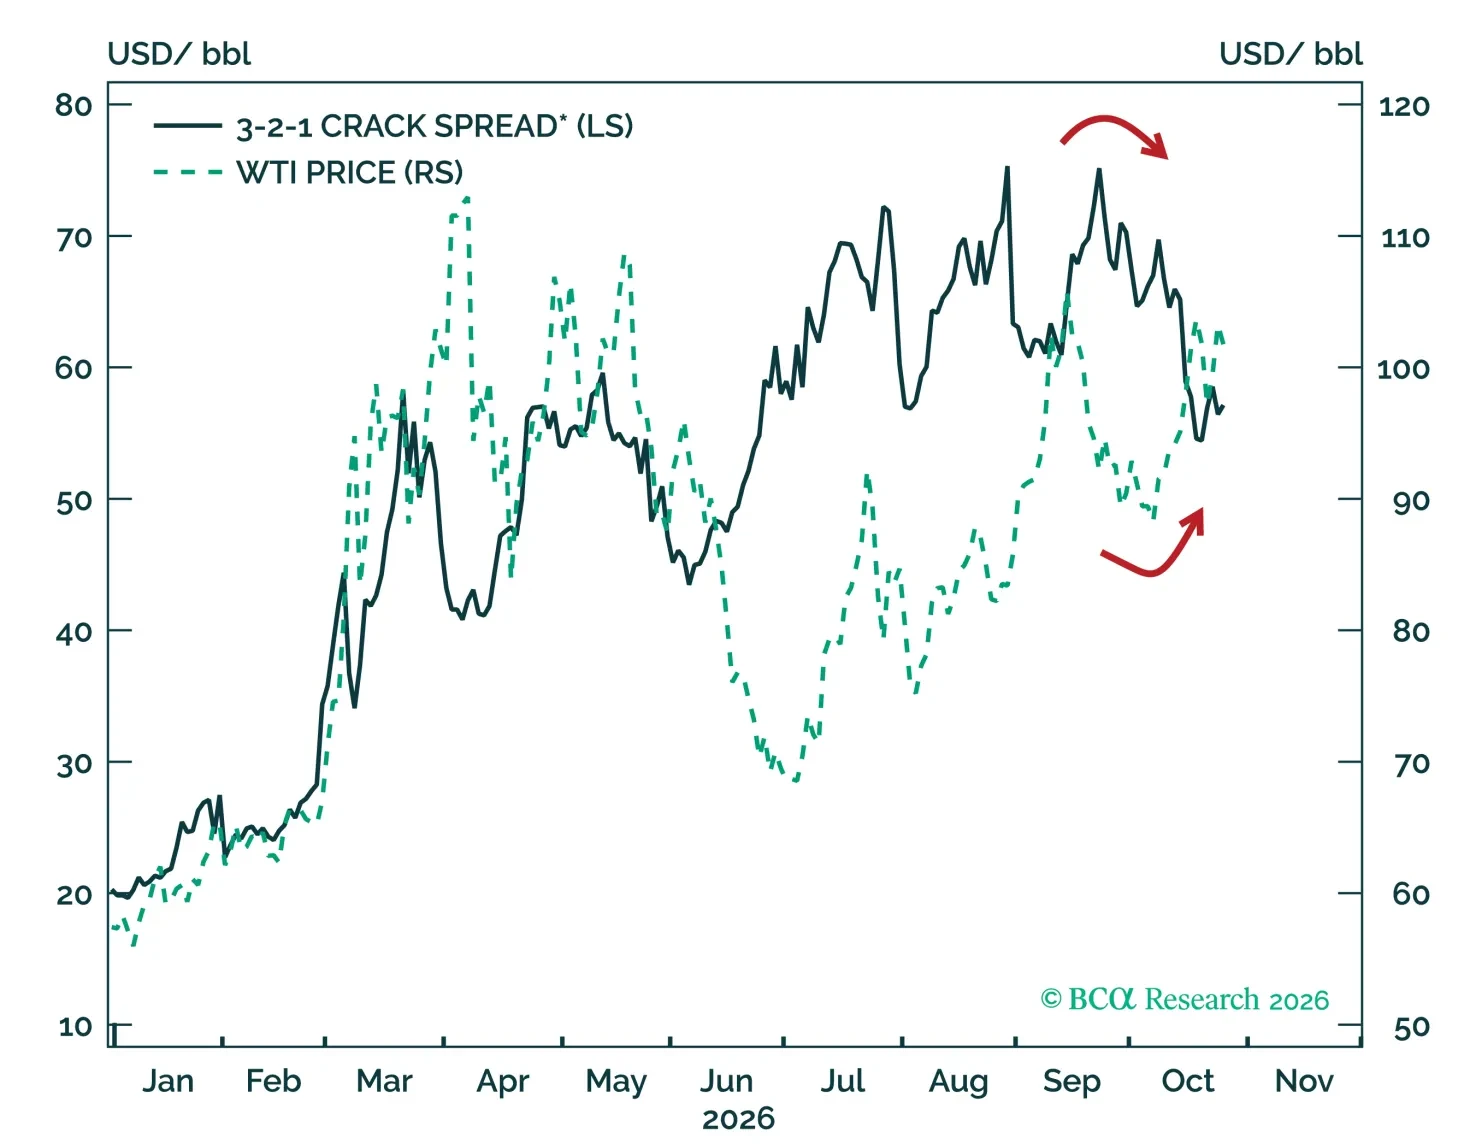
Crude has led the latest rally, leaving refined product prices behind and crack spreads narrower. We explain why the spread compression is unlikely to continue and why product prices will follow crude.
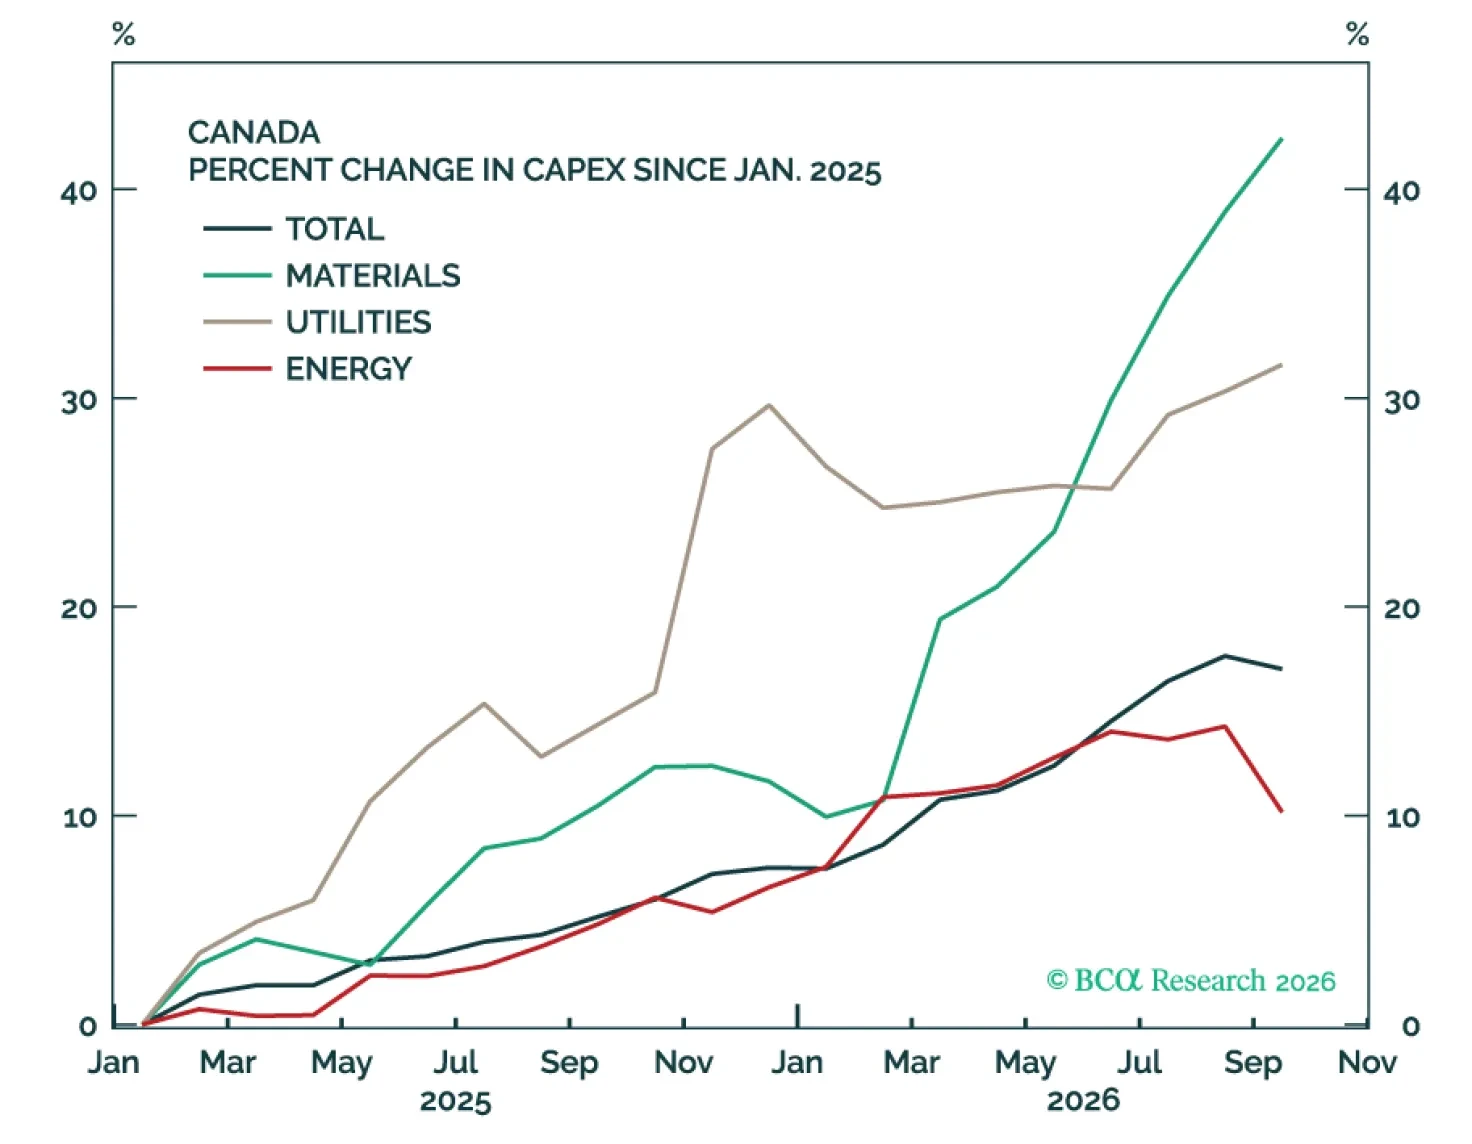
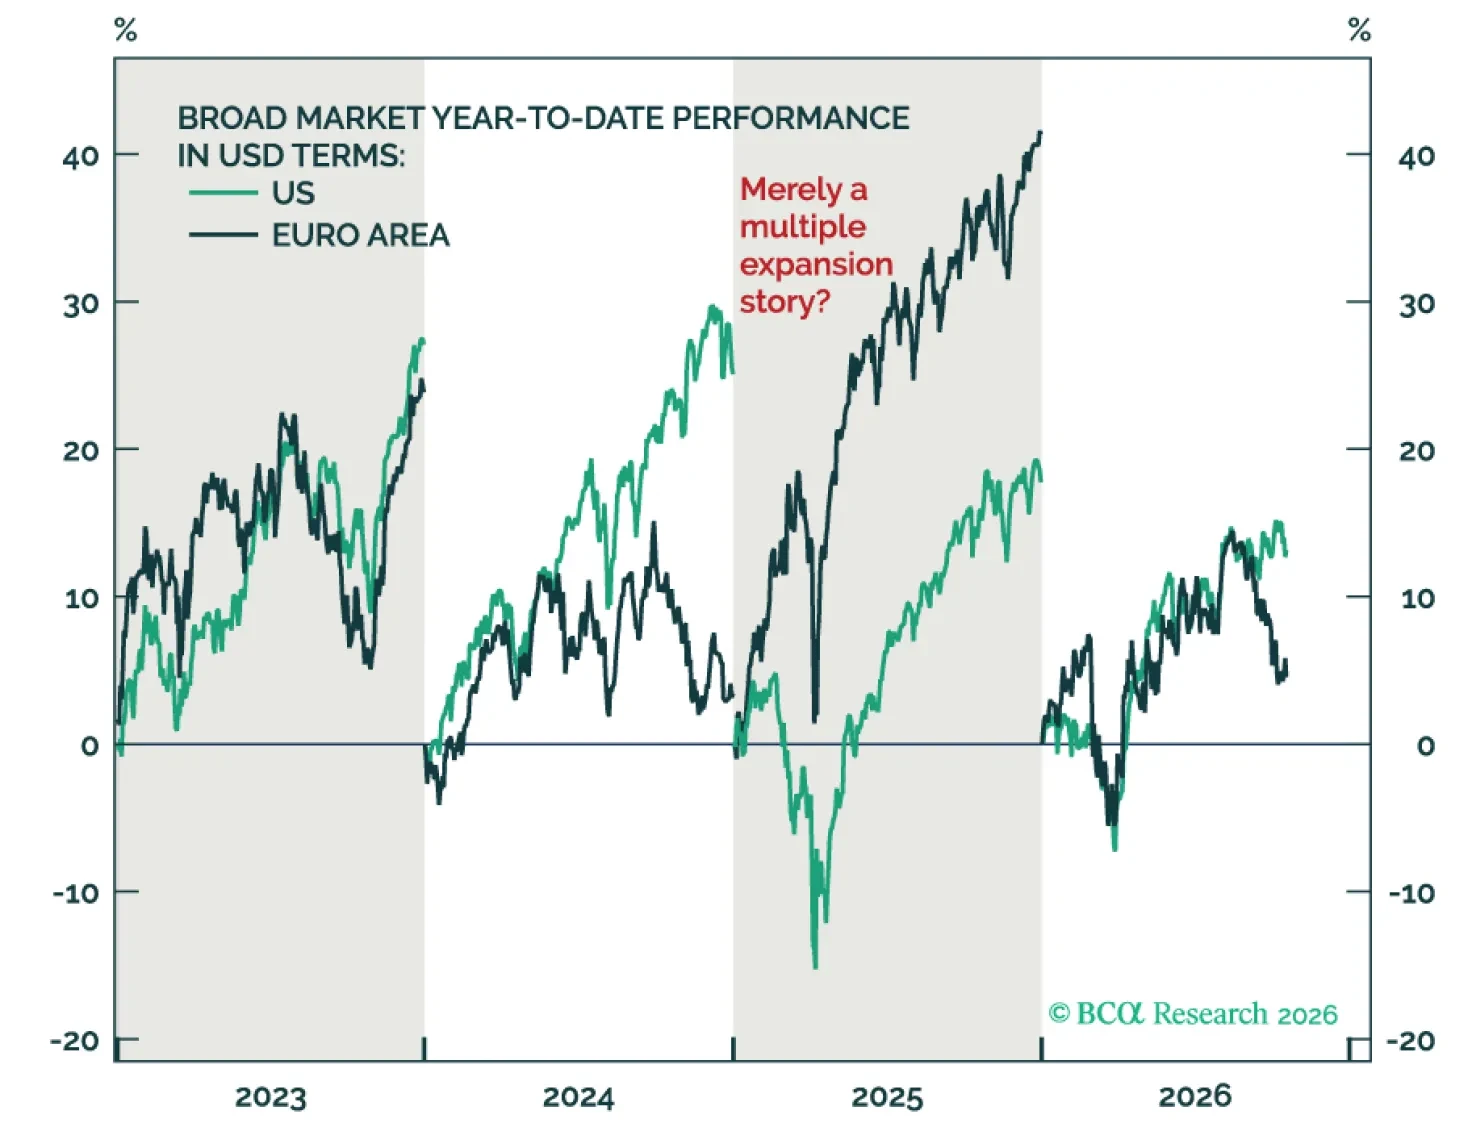
Europe has 99 problems, but the paucity of bearish views about the Old Continent is not one of them! And yet, somewhat shockingly, European assets have outperformed US assets over the past two years. Sure, markets make mistakes. But the macro graveyards are littered with investors who thought they were smarter than the markets. In this report, we suggest that Europe is on a cusp of significant structural reforms that will unlock value in its services sector. And that while many of the challenges are real, they’re either well understood or priced in.
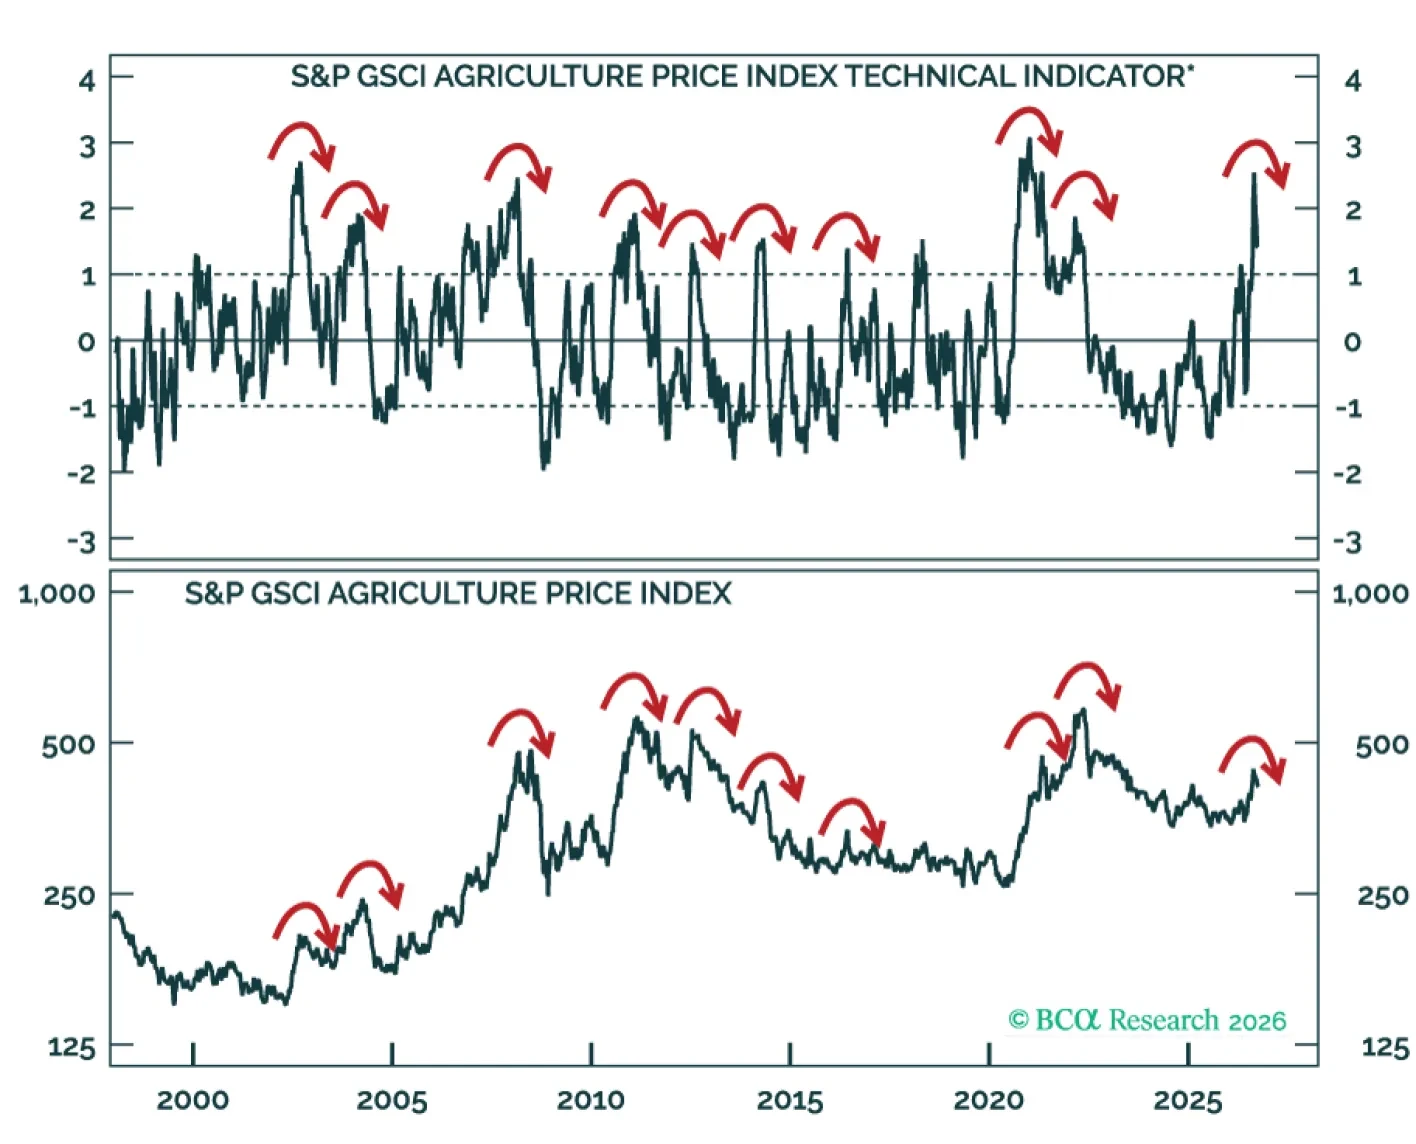
Ags have tumbled from overbought highs, and further near-term weakness is likely. But a “super” El Niño and an ongoing energy shock are setting the stage for the next rally.
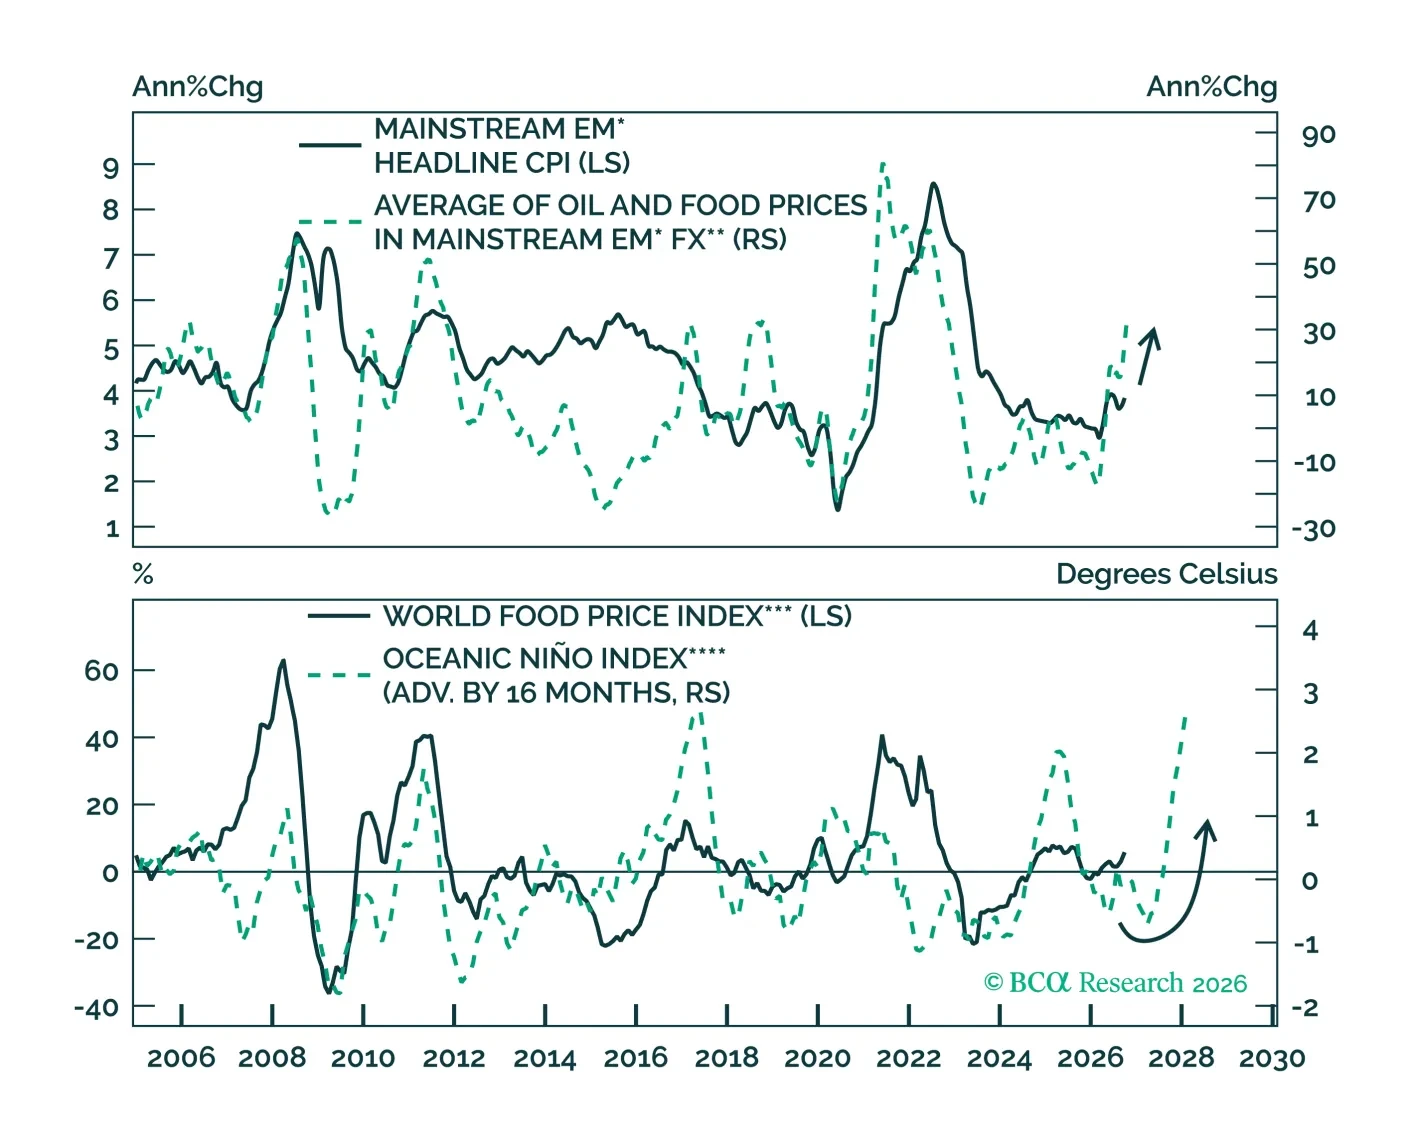
EM local bonds face near-term turbulence from rising inflation, global risk aversion, and currency weakness. Use the sell-off to build exposure: medium- and longer-term fundamentals remain favorable.