Latest from BCA Research
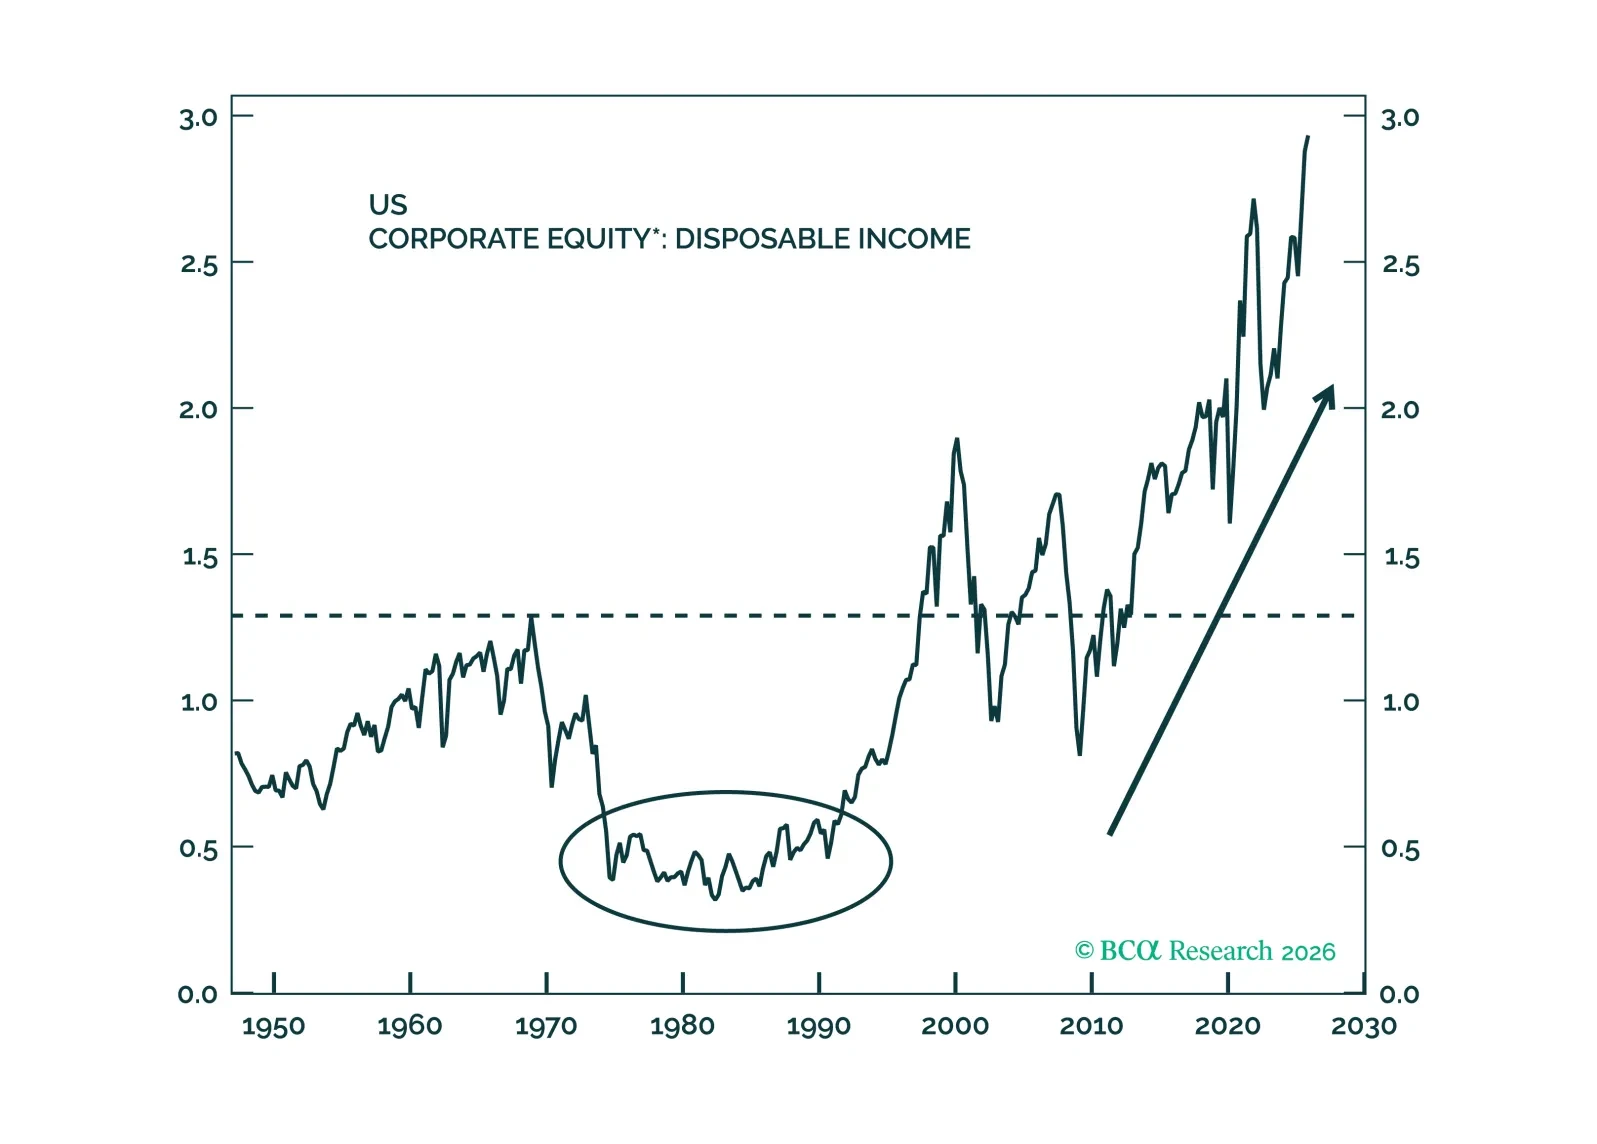
Although the multi-decade surge in the value of households’ equity holdings has made US activity more vulnerable to a stock selloff, the latest income, spending and employment data suggest that consumption growth can carry on at a 2% inflation-adjusted pace.
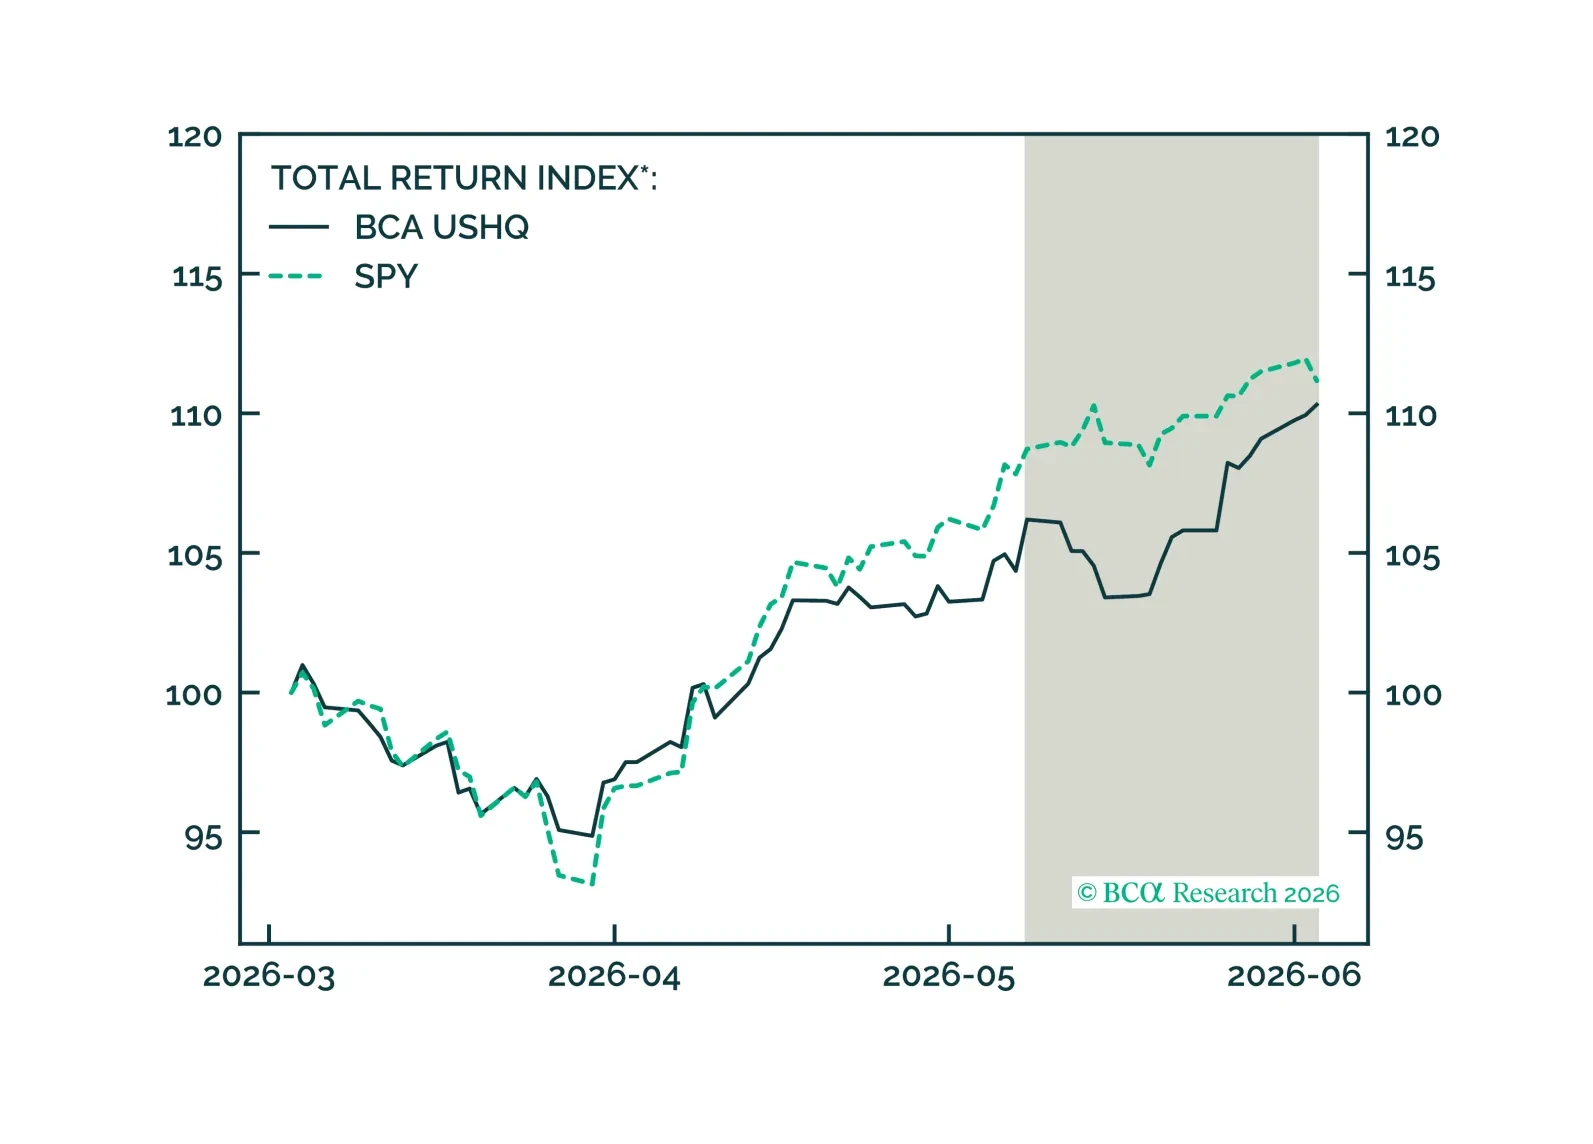
The US High Quality (USHQ) portfolio outperformed its benchmark through May, returning 3.88%, while its SPY benchmark returned 2.25%. On a trailing three-month basis, the USHQ portfolio’s performance was weaker than the benchmark, with USHQ underperforming by approx. 86bps.
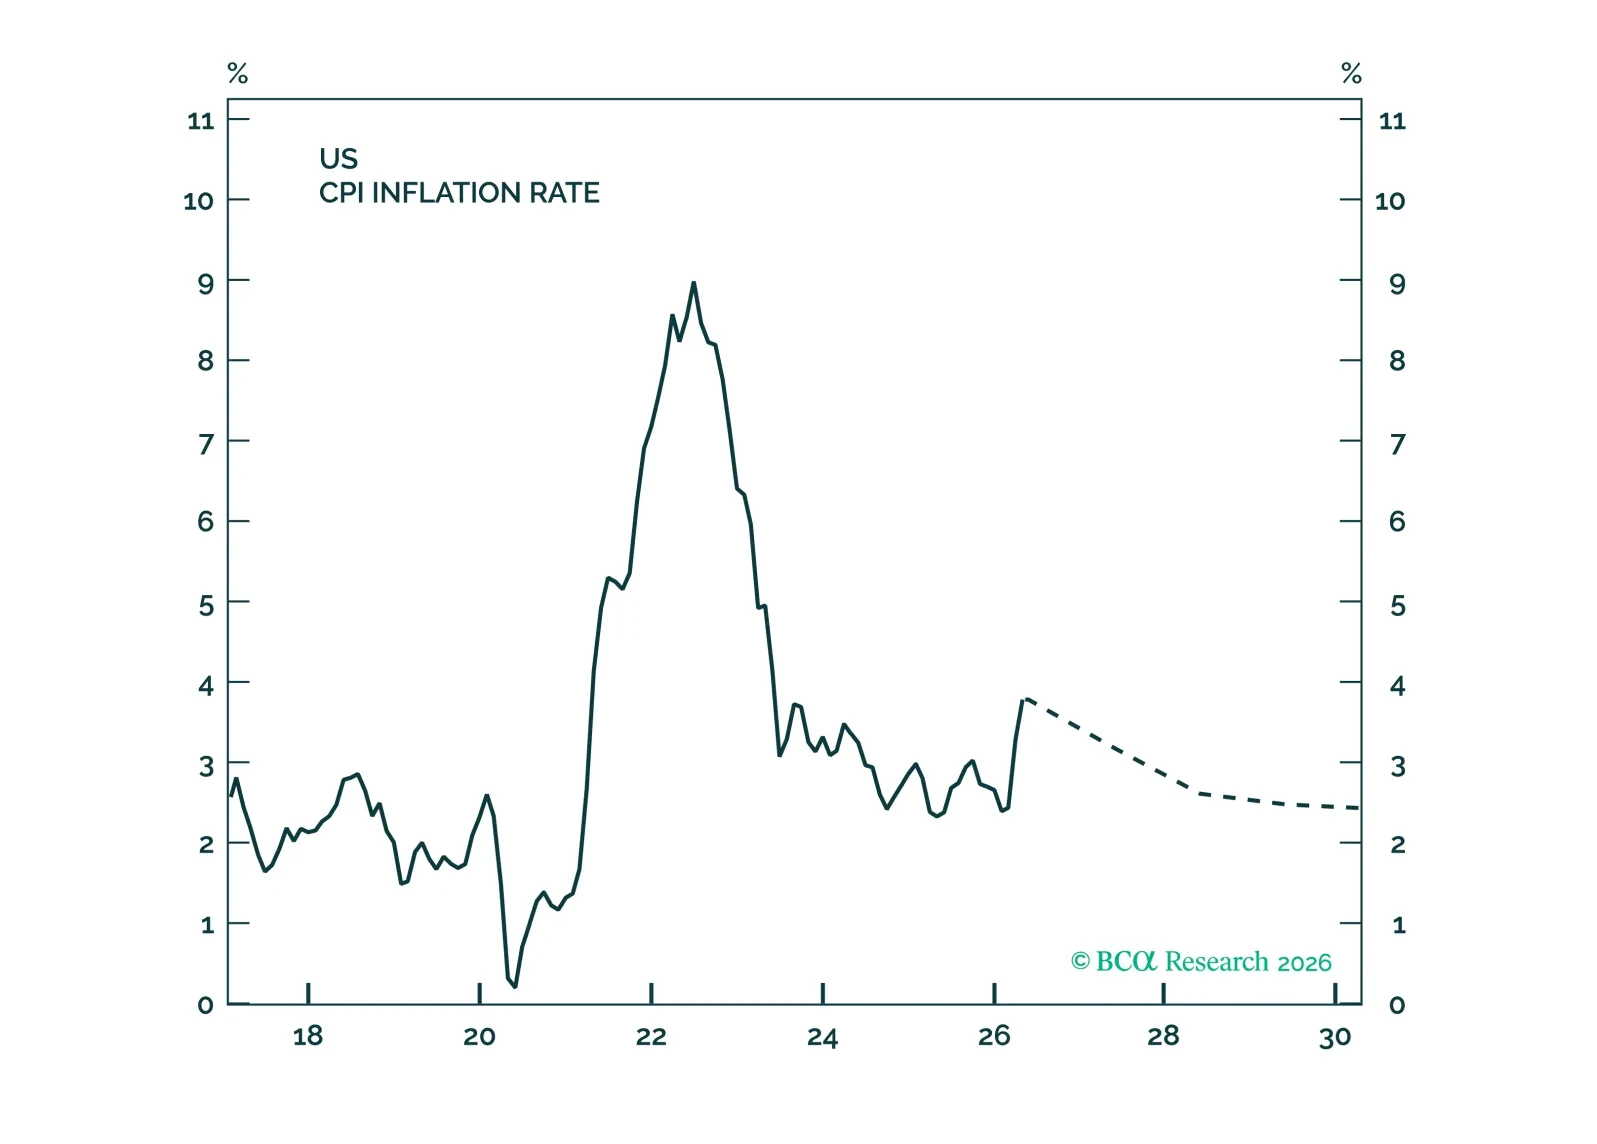
The AI boom will increase inflation in the near term and could also raise it over the long term. The Fed’s reluctance to hike rates is understandable, but it risks amplifying what may already be a brewing stock market bubble.
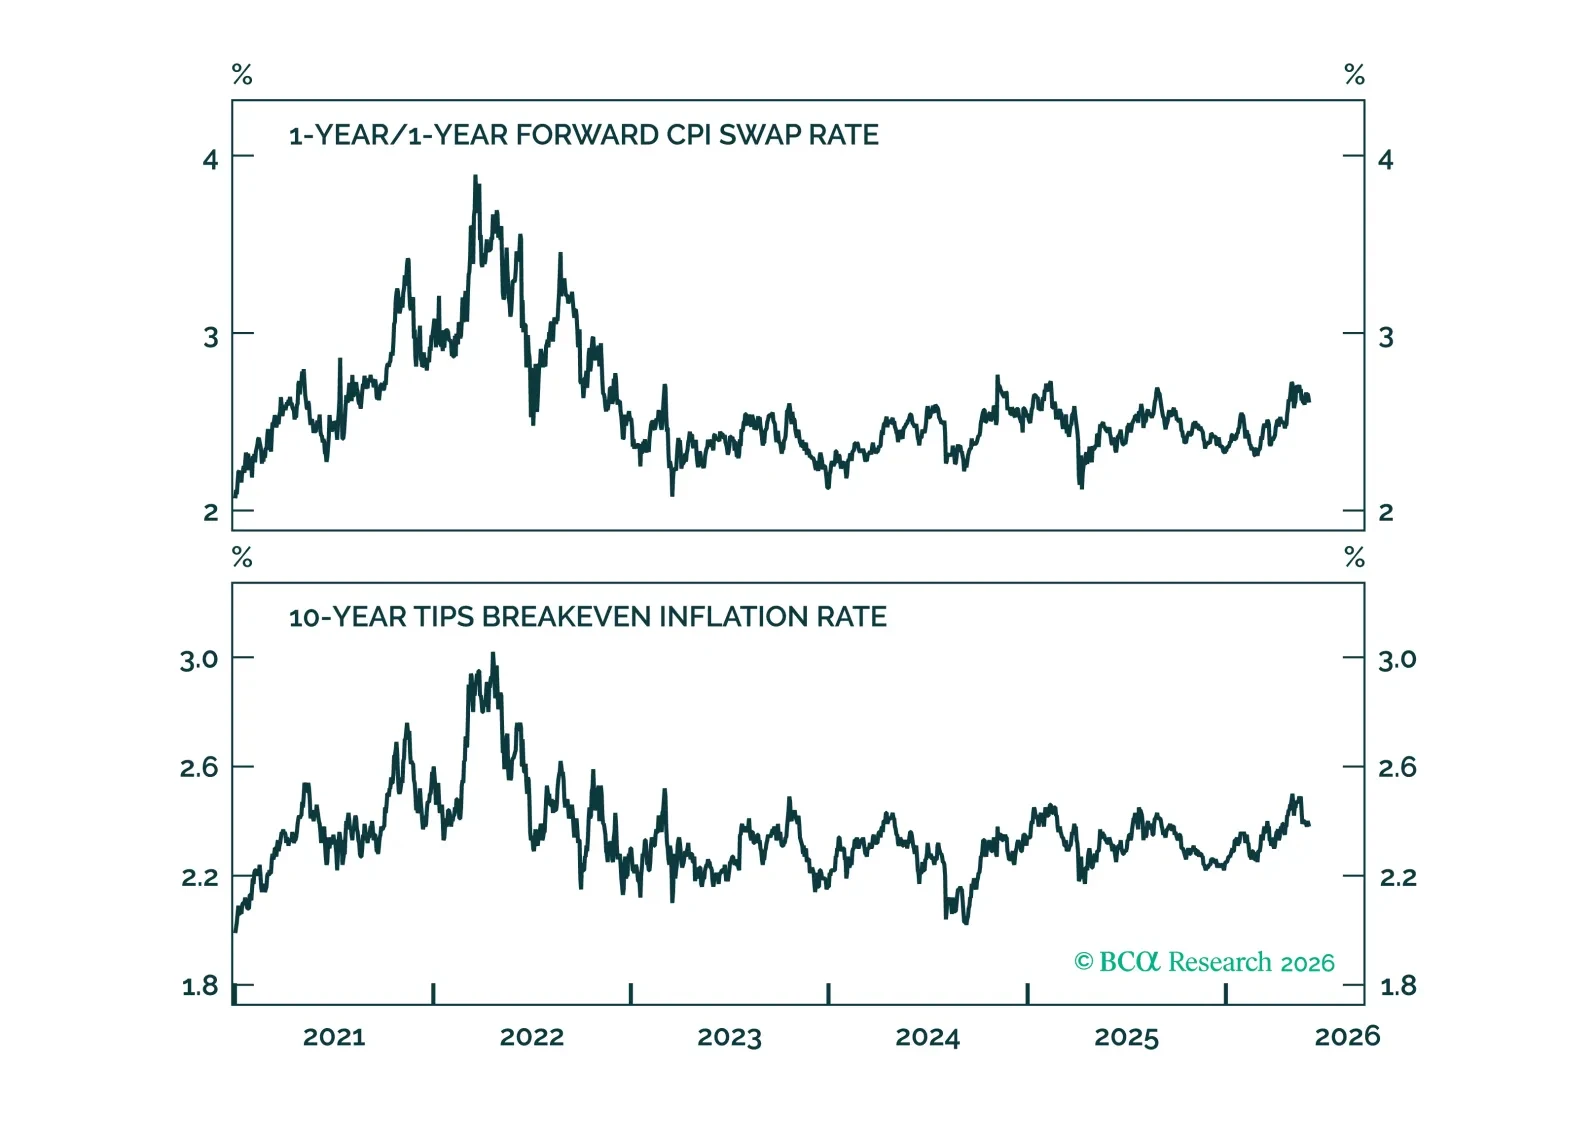
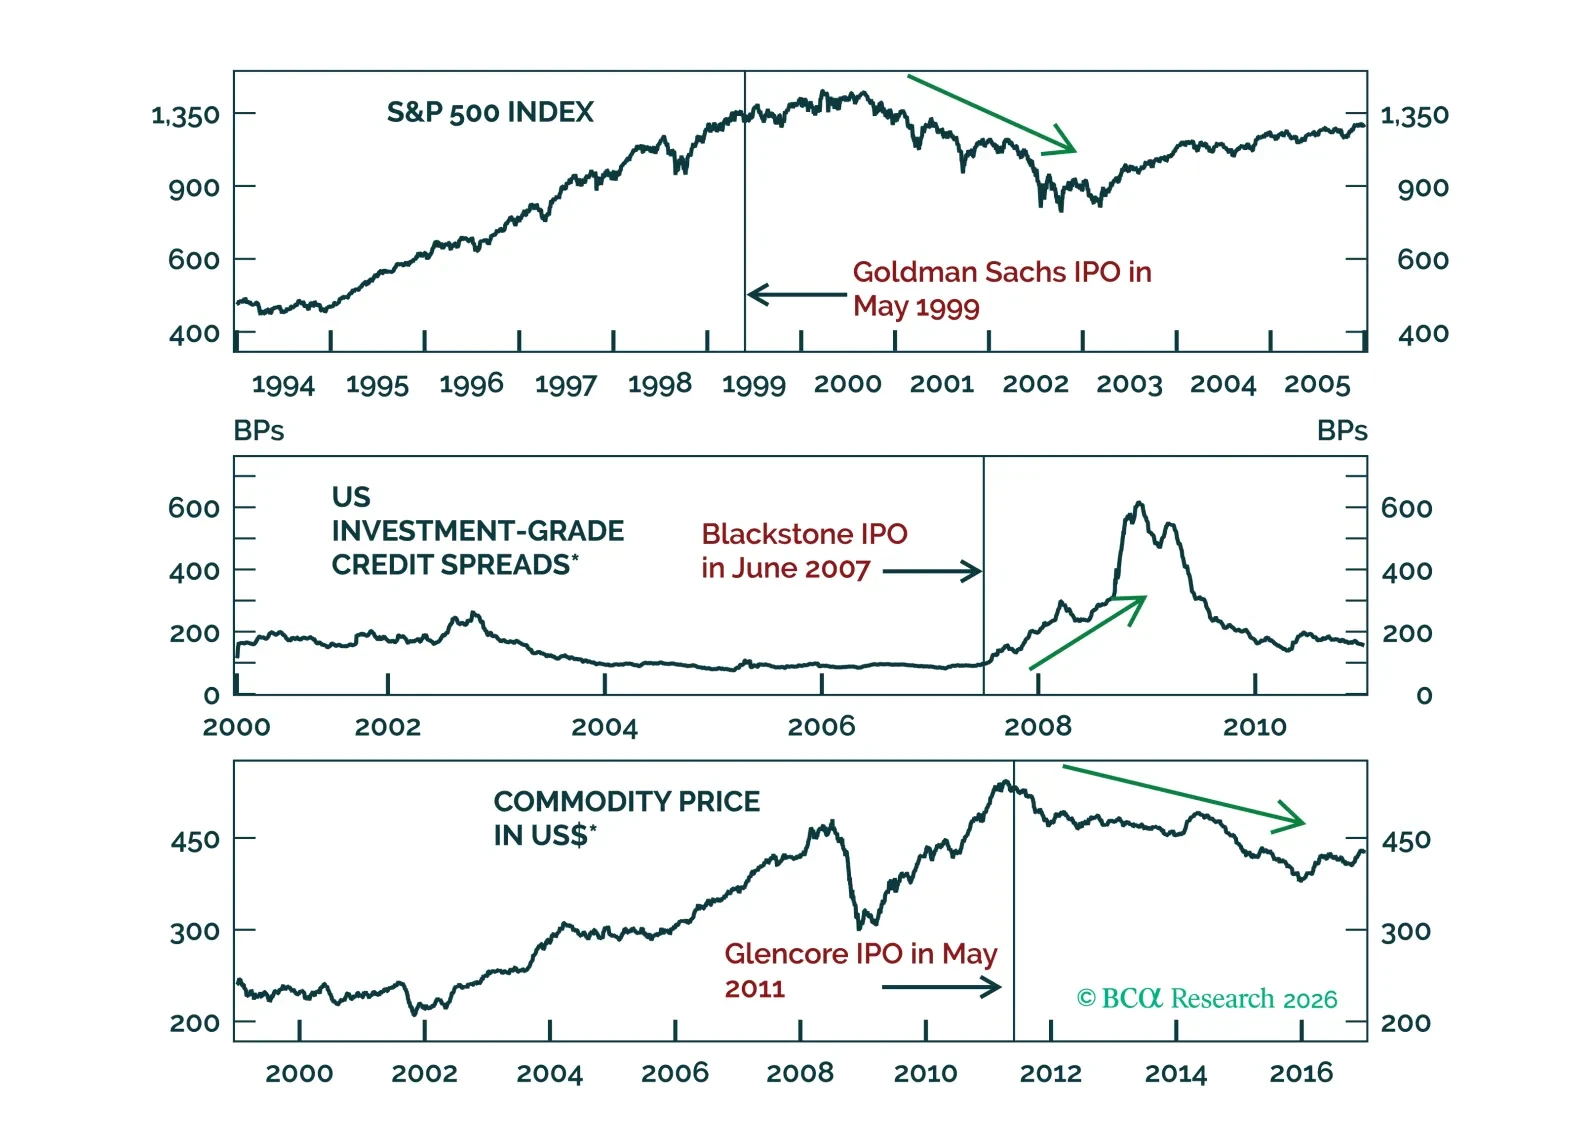
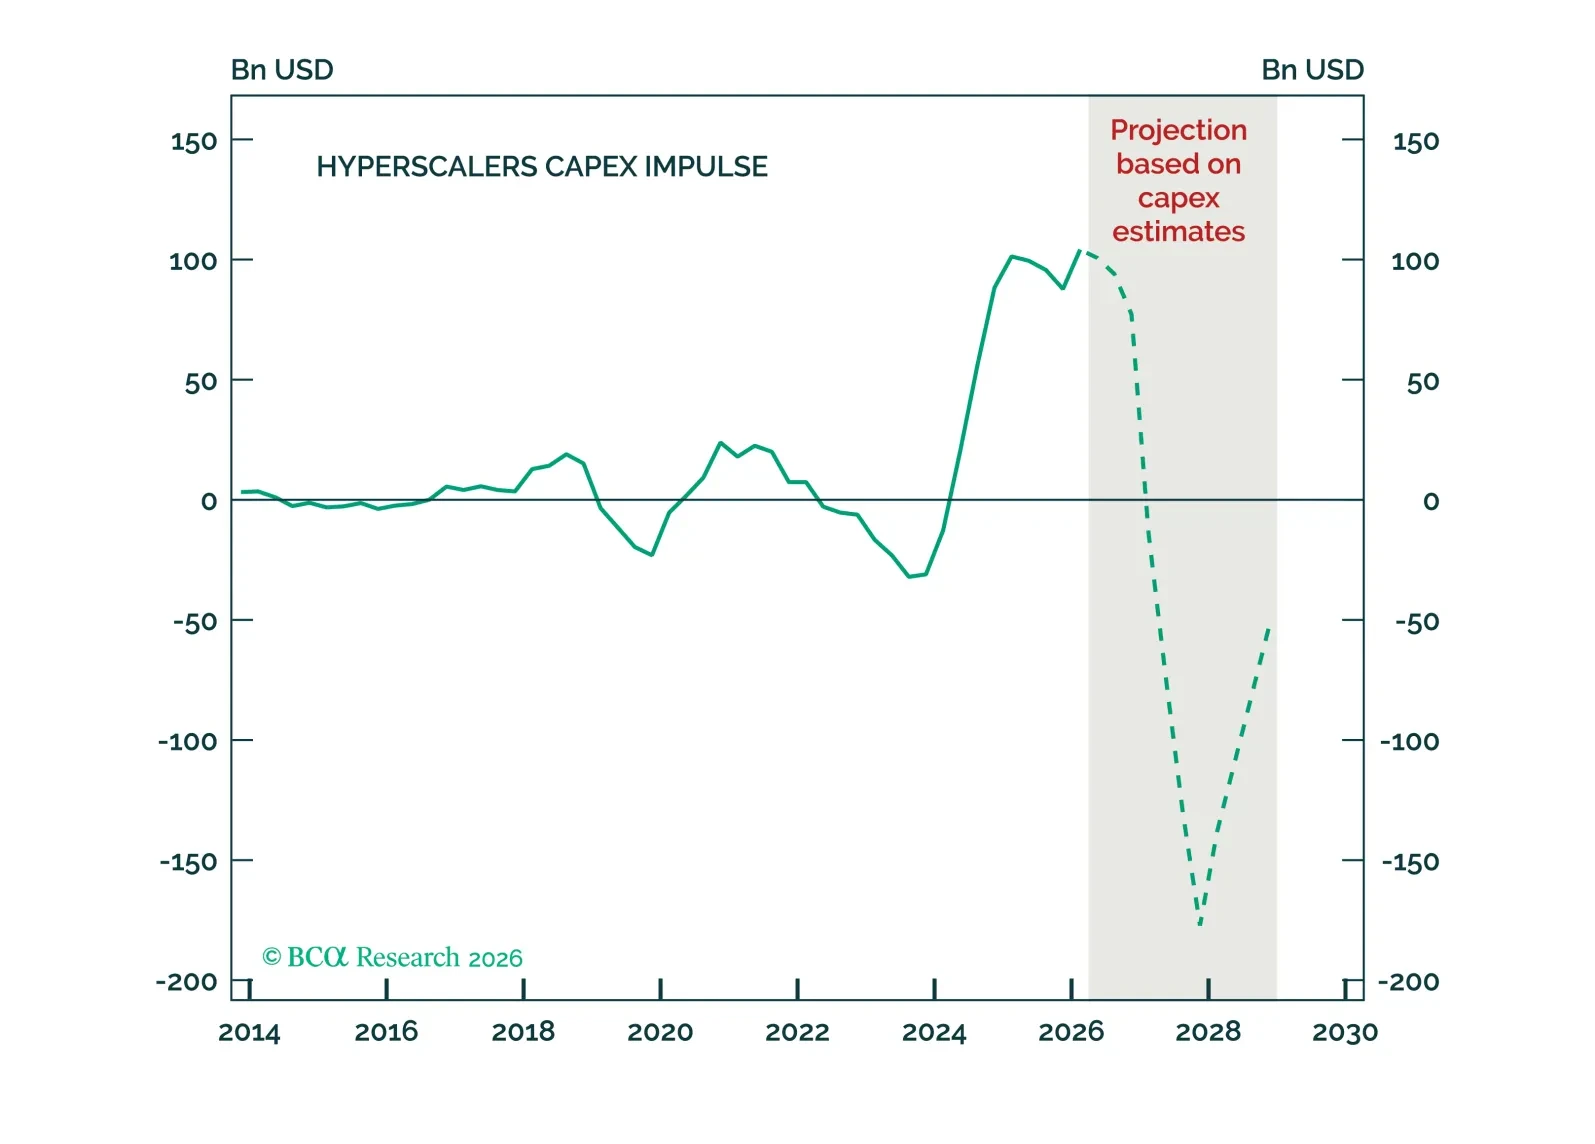
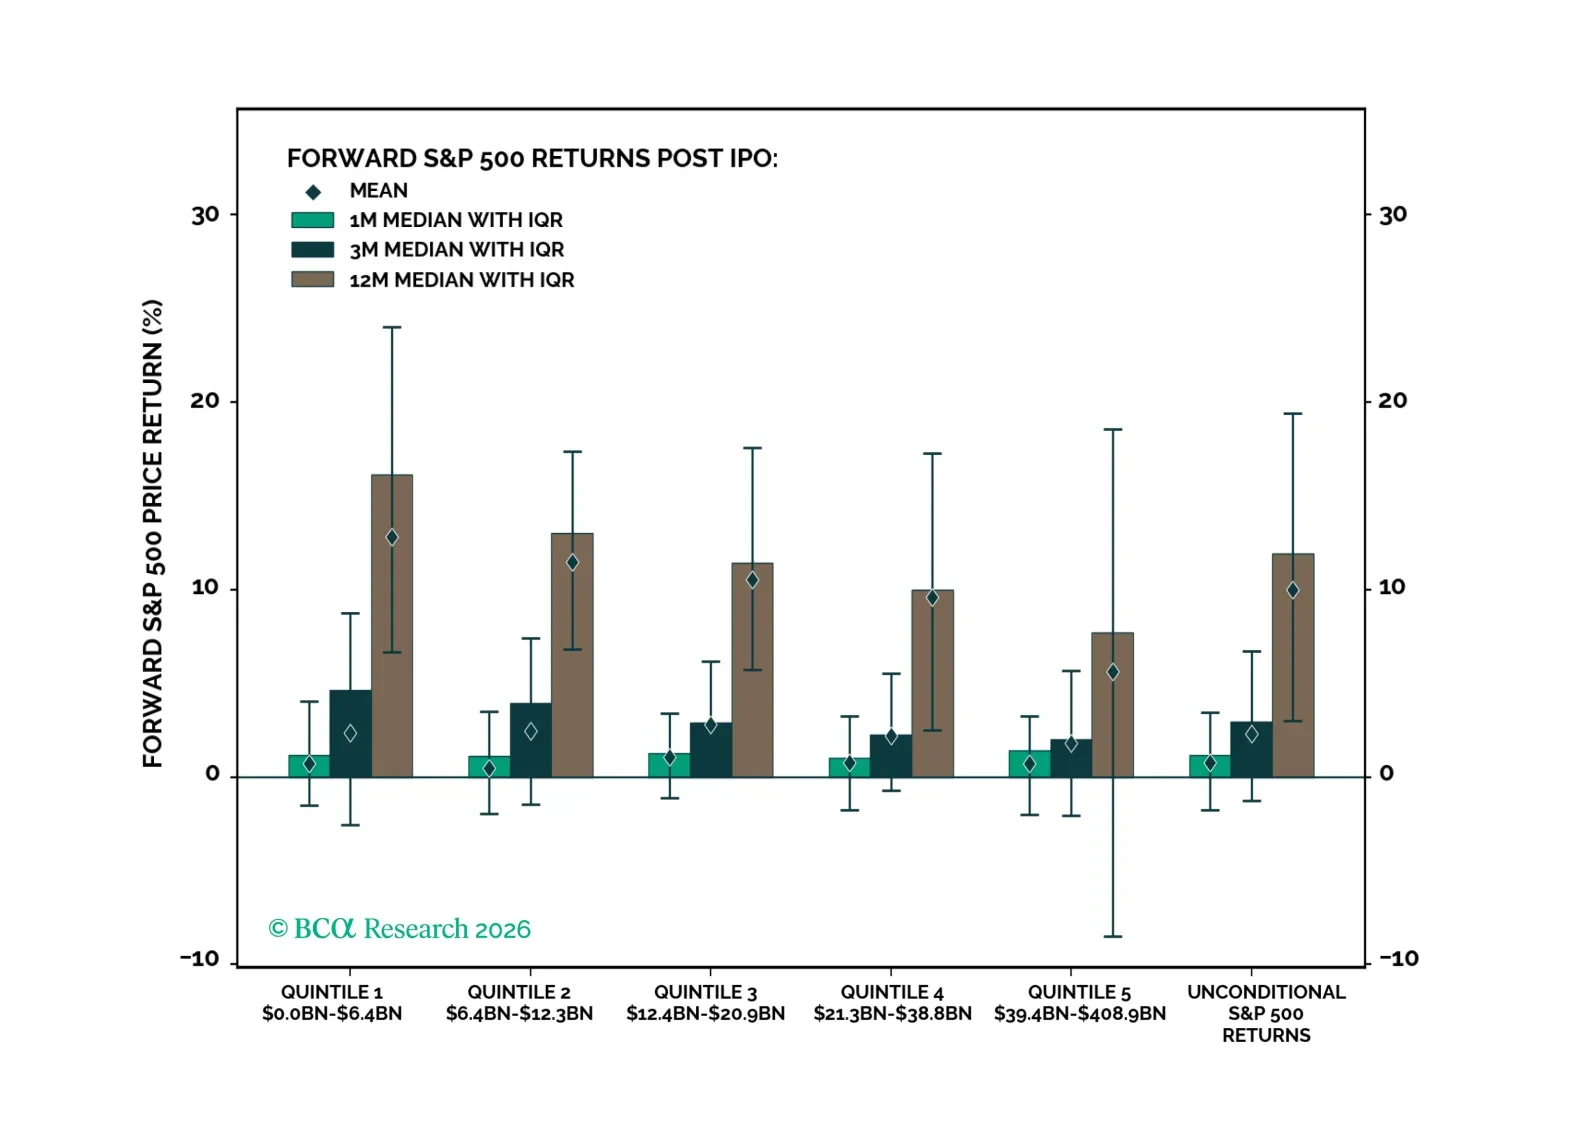
Bears will fold like lawn chairs this summer as traffic returns to Hormuz, allowing markets to overcome seasonal malaise. But we are starting to see how the expansion ends. A macro brew of global central bank tightening due to stickier-than-expected inflation, negative second derivative in AI capex, and surging supply of equities due to Monster IPOs. Expect a blow-off rally until midterms, uncertainty after, calamity in 2027.
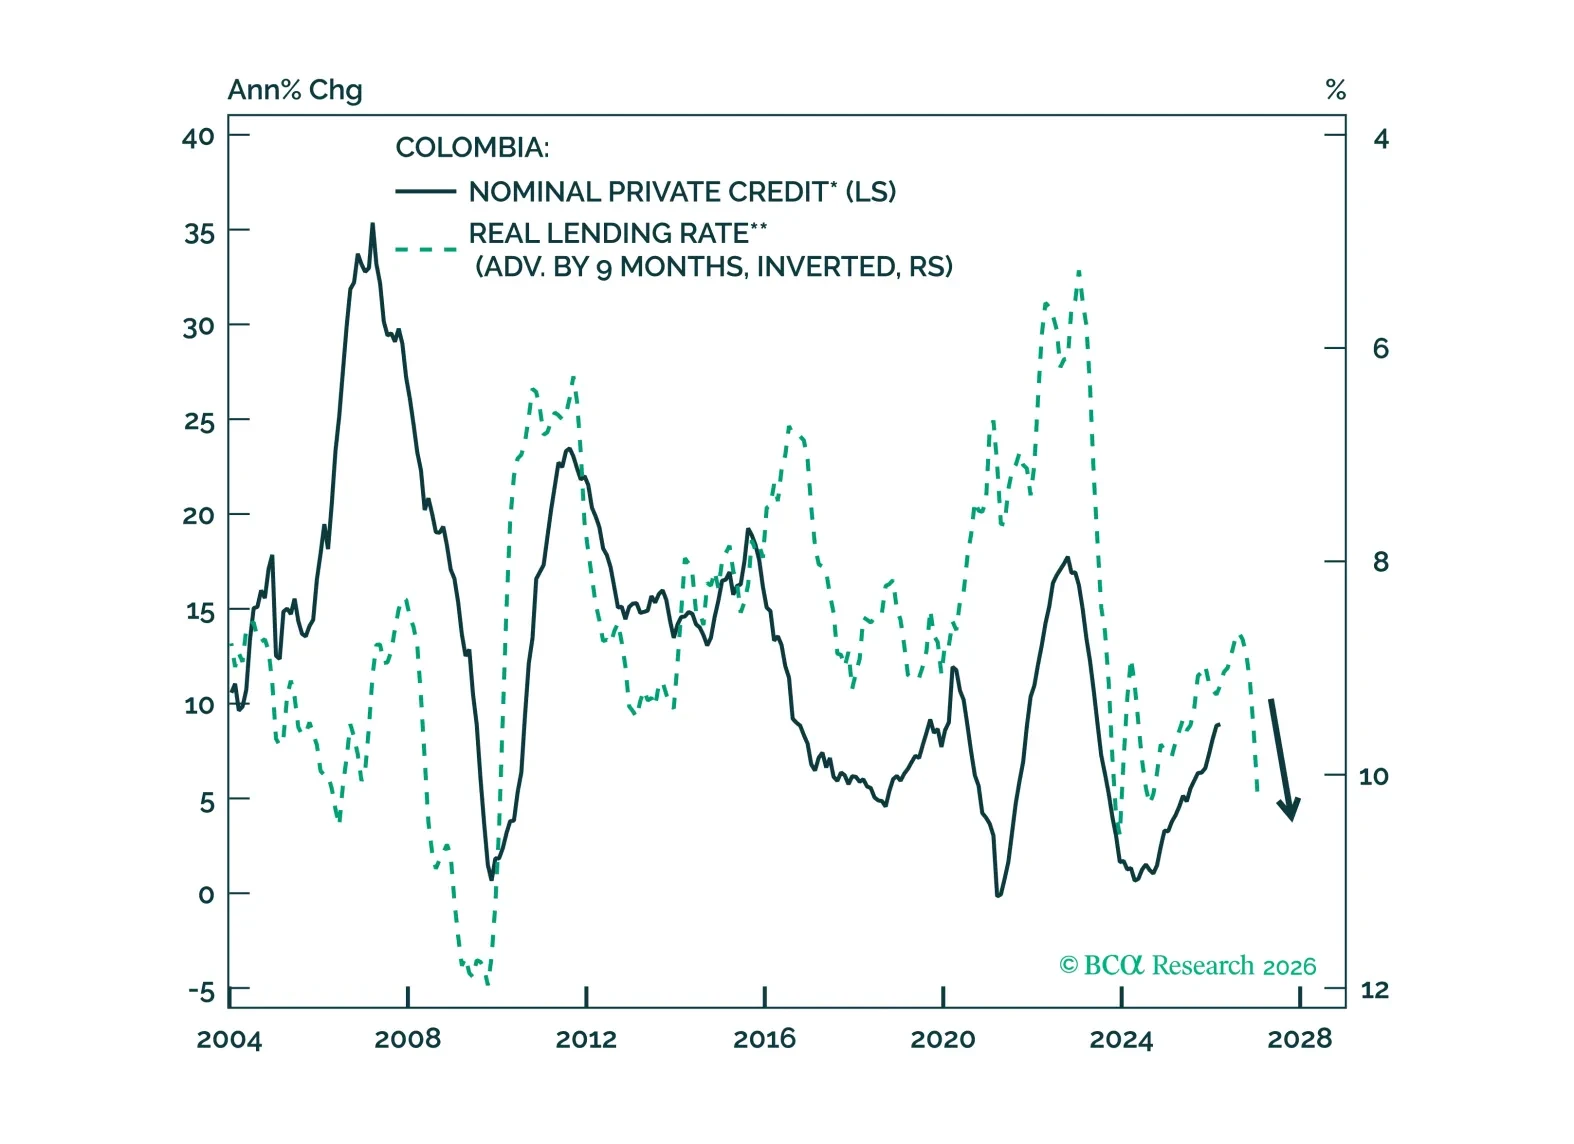
The rally in Colombia’s financial markets has a short shelf life. The election will bring a right-wing government, but it cannot fix inflation, fiscal arithmetic, or balance-of-payments vulnerabilities. Use the near-term rally to downgrade Colombian fixed income and equities.
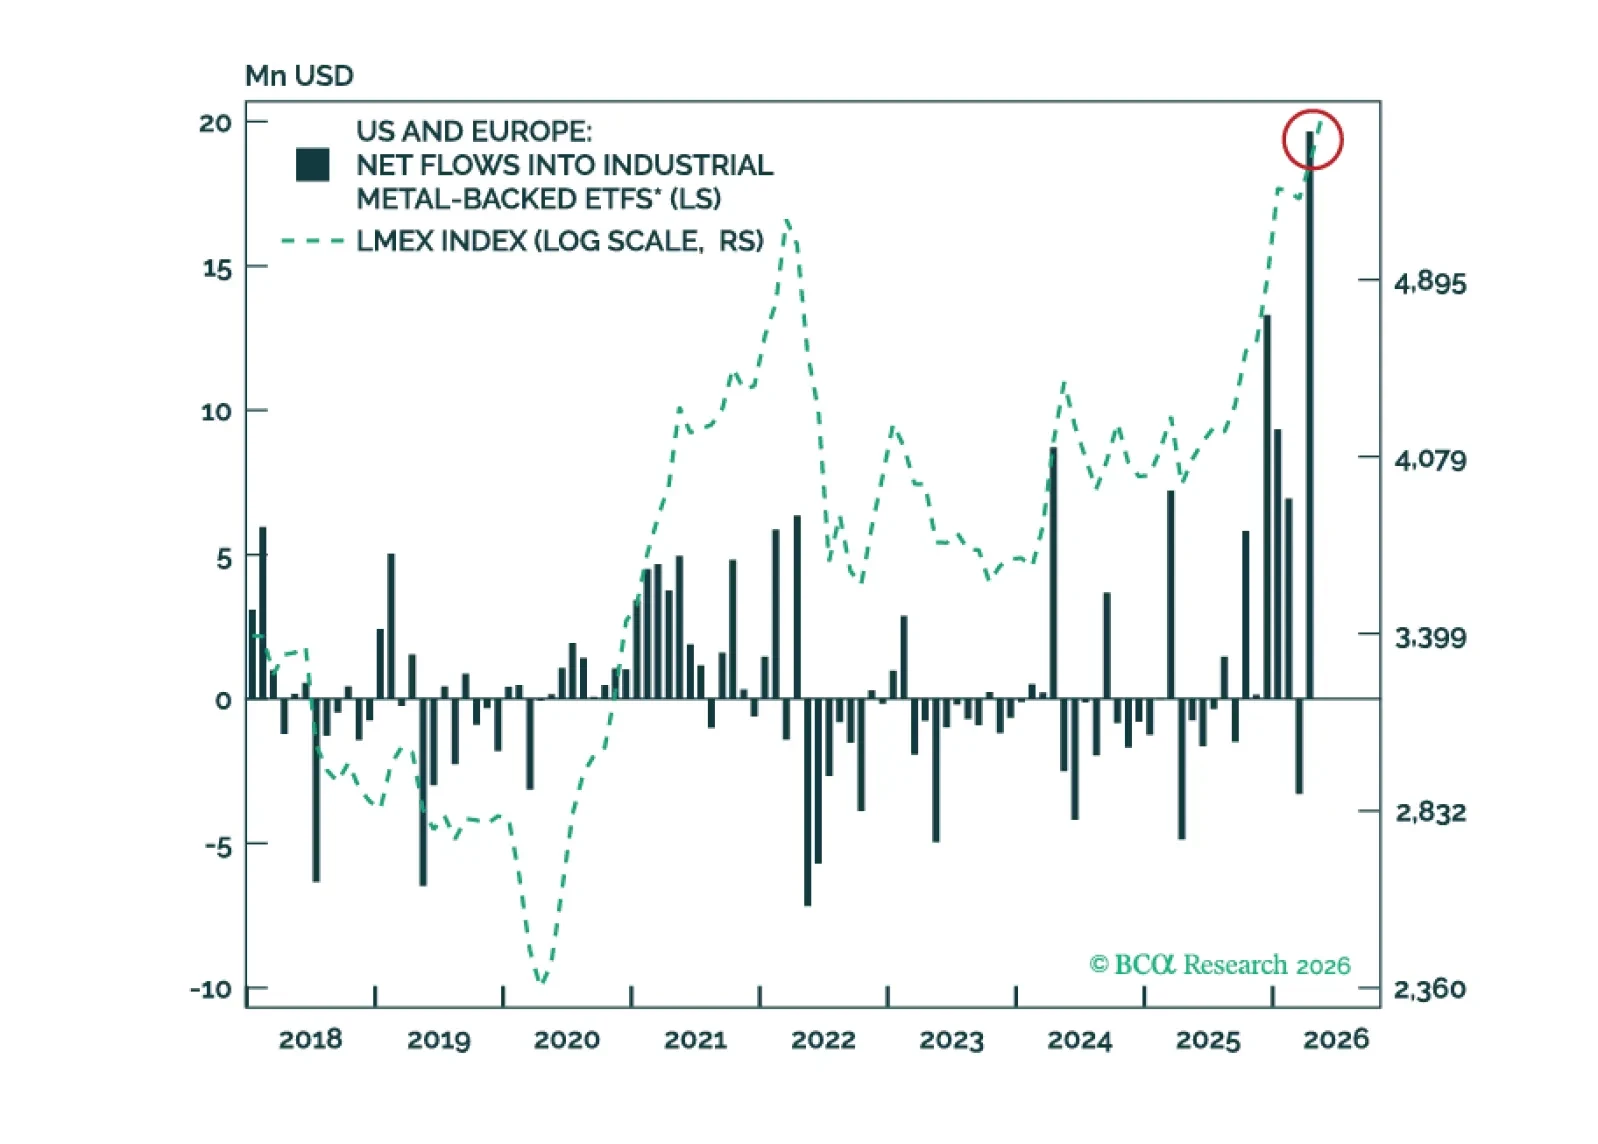
Copper prices are surging again after a brief pullback in the first quarter. What is driving the renewed strength, and can it persist?