 GeoMacro
A blend of geopolitics and macro, synthesizing the new and old macro to generate alpha and identify the beta through probability-weighted market views.
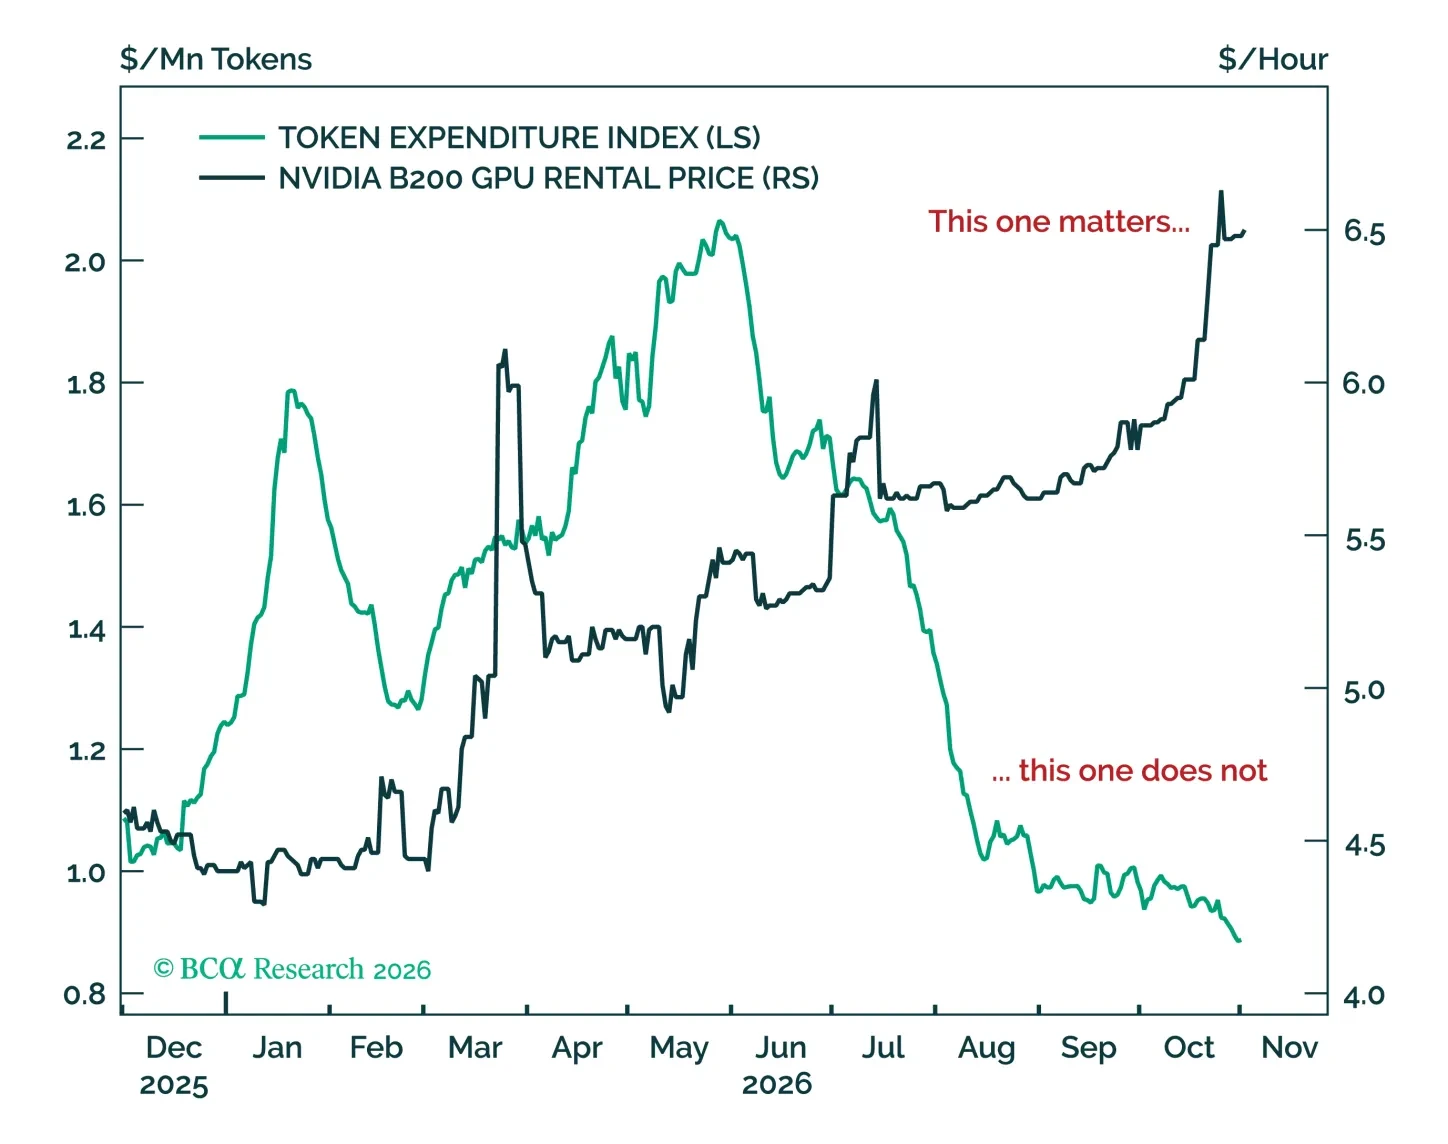
October has been a bad month for equities — particularly AI/tech ones — and a great month for oil. We do not think that the AI supercycle is ending, it has more room to go. Token price decline is a sign of a price war between LLMs, not a decline in demand. In fact, that price war is what is driving datacenter profitability, which is what the bull market is actually based on. As such, what matters on a tactical time horizon is whether Trump capitulates on Iran. If he does not, the market will have to correct. We take the bullish side and expect oil prices to decline imminently, forcing a short squeeze and powering equities higher.
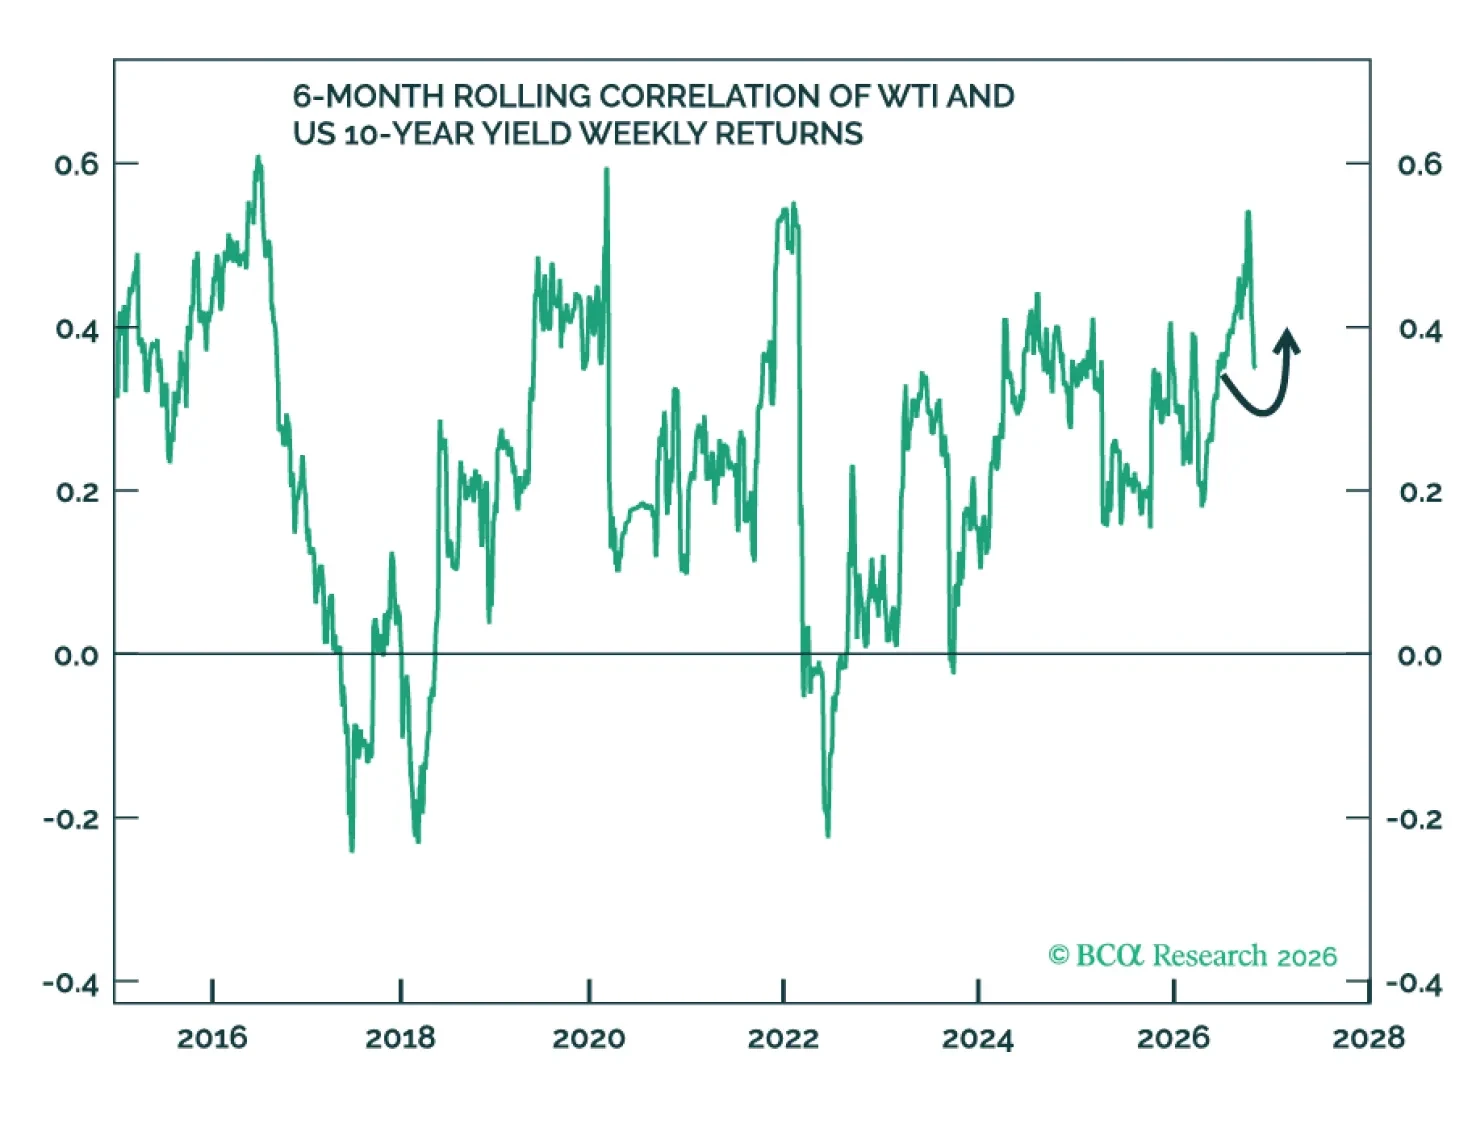
Democrats look to be clinching a Senate victory in the final day of the campaign, but Iran, not the Senate, poses the real risk.
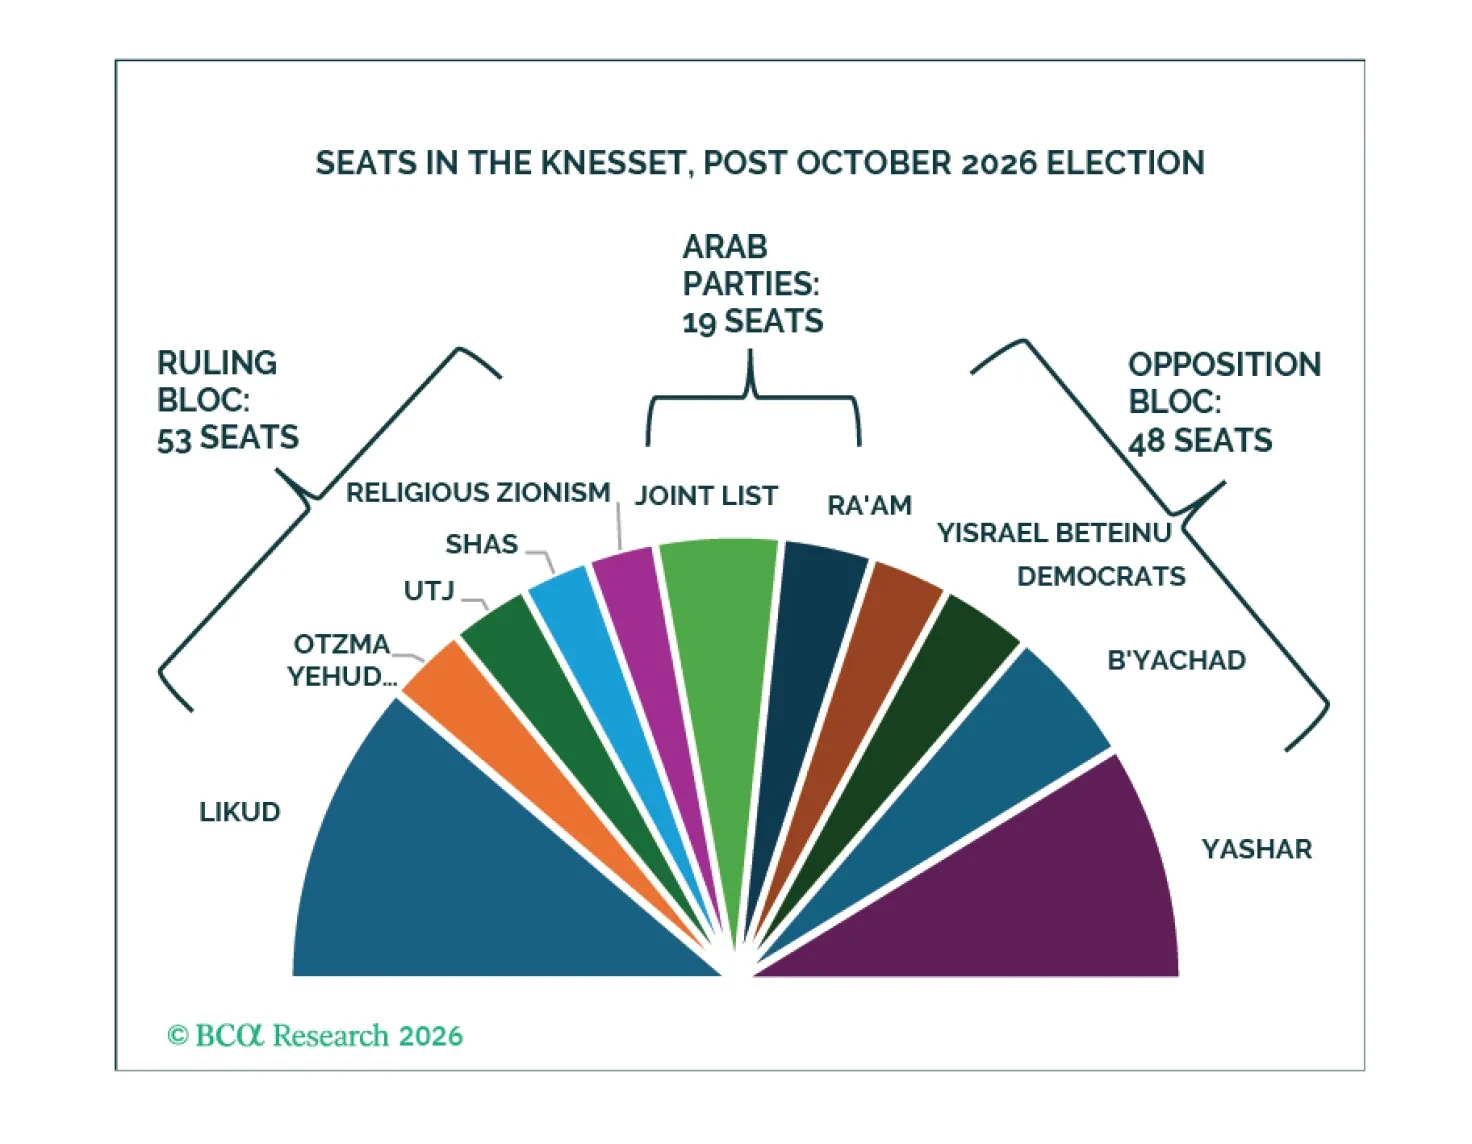
Another Netanyahu-led government would raise the risk of Israeli escalation and a major oil supply shock, while an opposition victory would reduce, but not eliminate, this risk due to its greater coordination with and deference to the US.
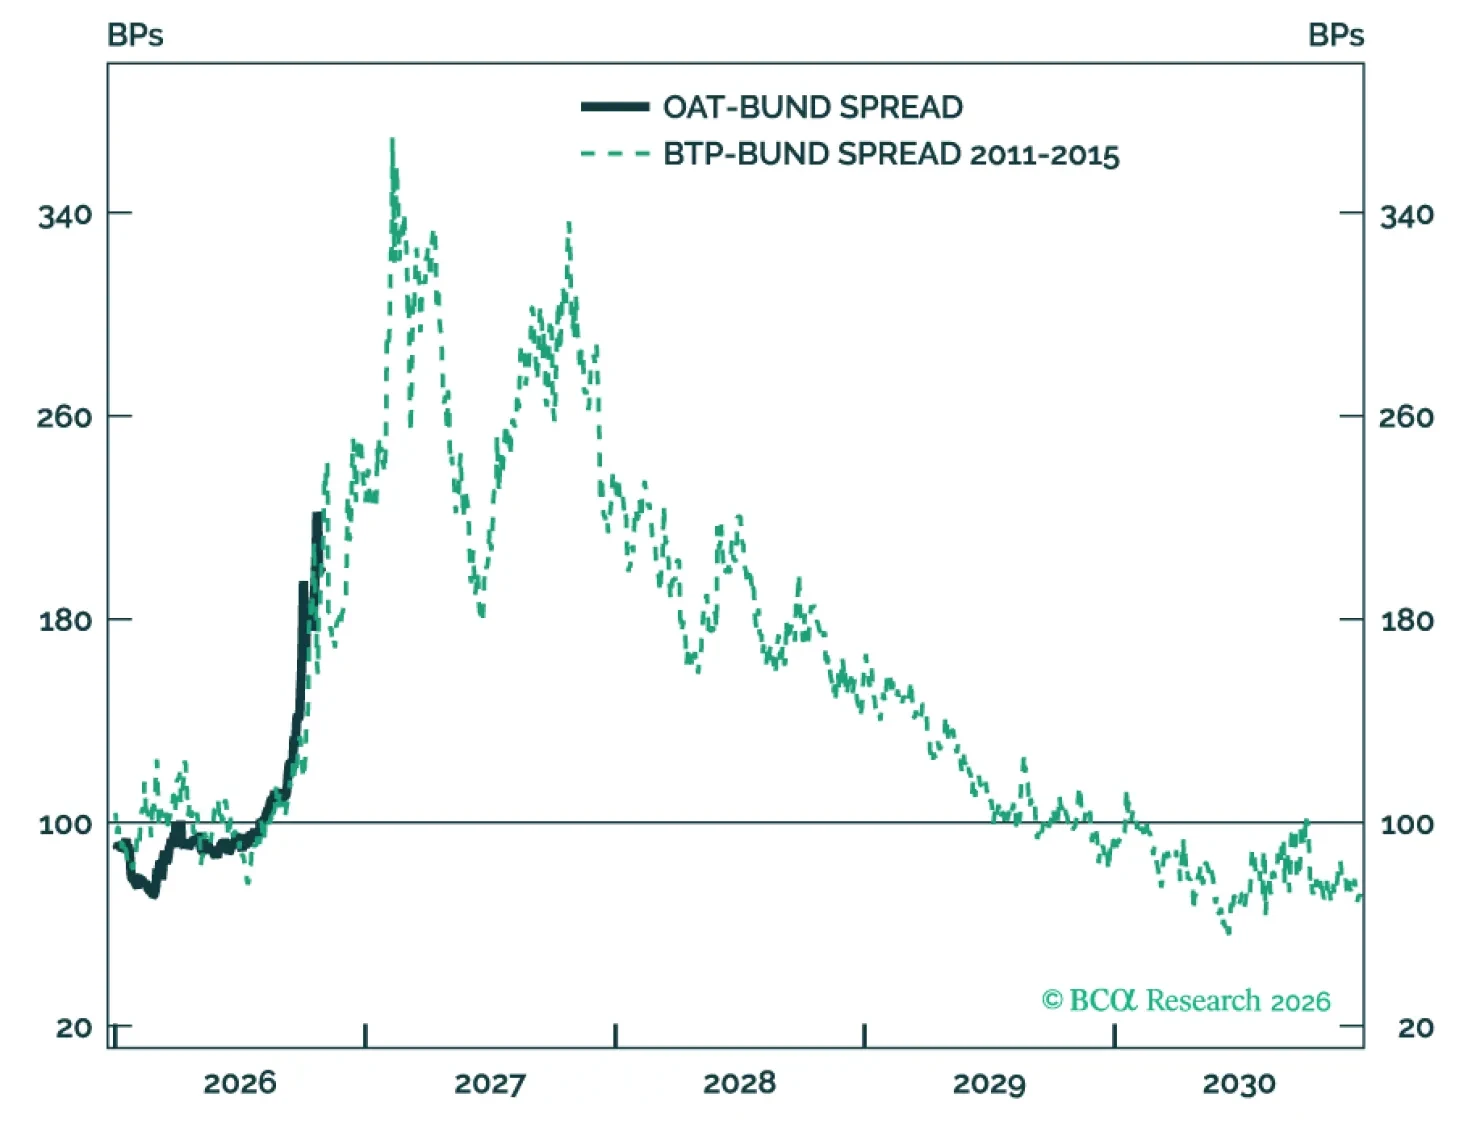
France’s fiscal mess is far from over, but the bond vigilantes may have gotten ahead of themselves. We book profits on short OATs, eyeing another opportunity in early 2027 as election risks resurface. Meanwhile, French equities are too cheap to ignore. We tactically buy on depressed valuations.
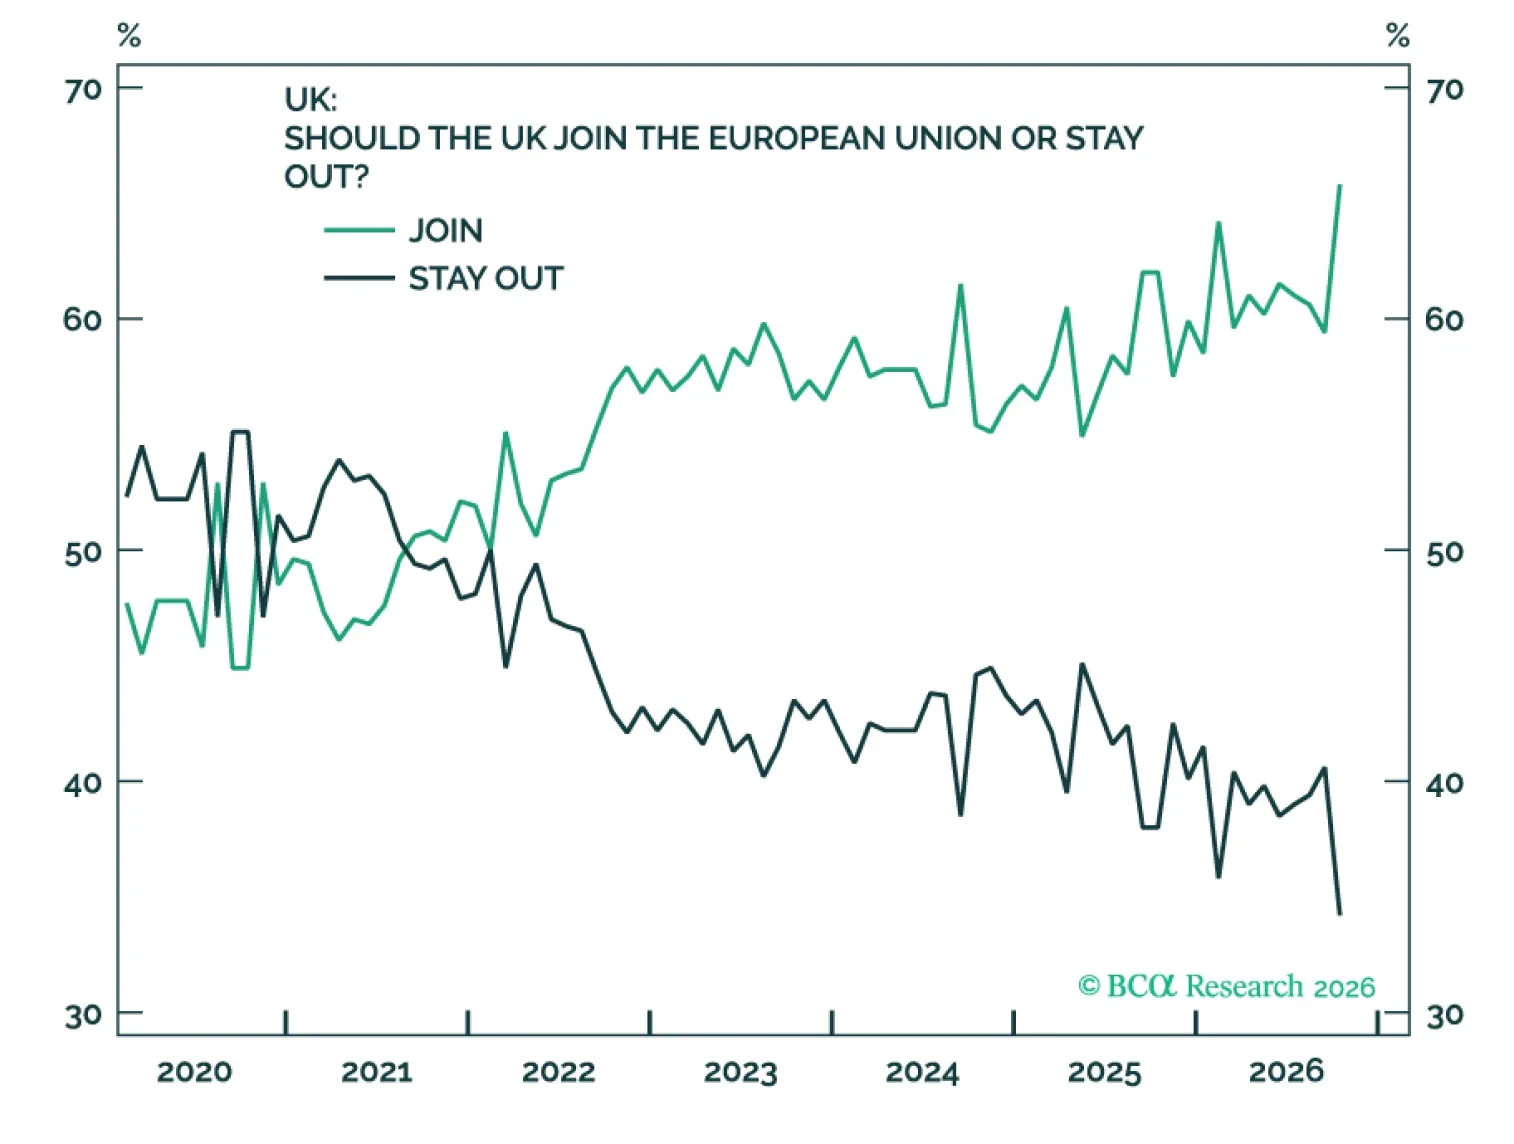
The UK faces many challenges but secessionism can be contained.
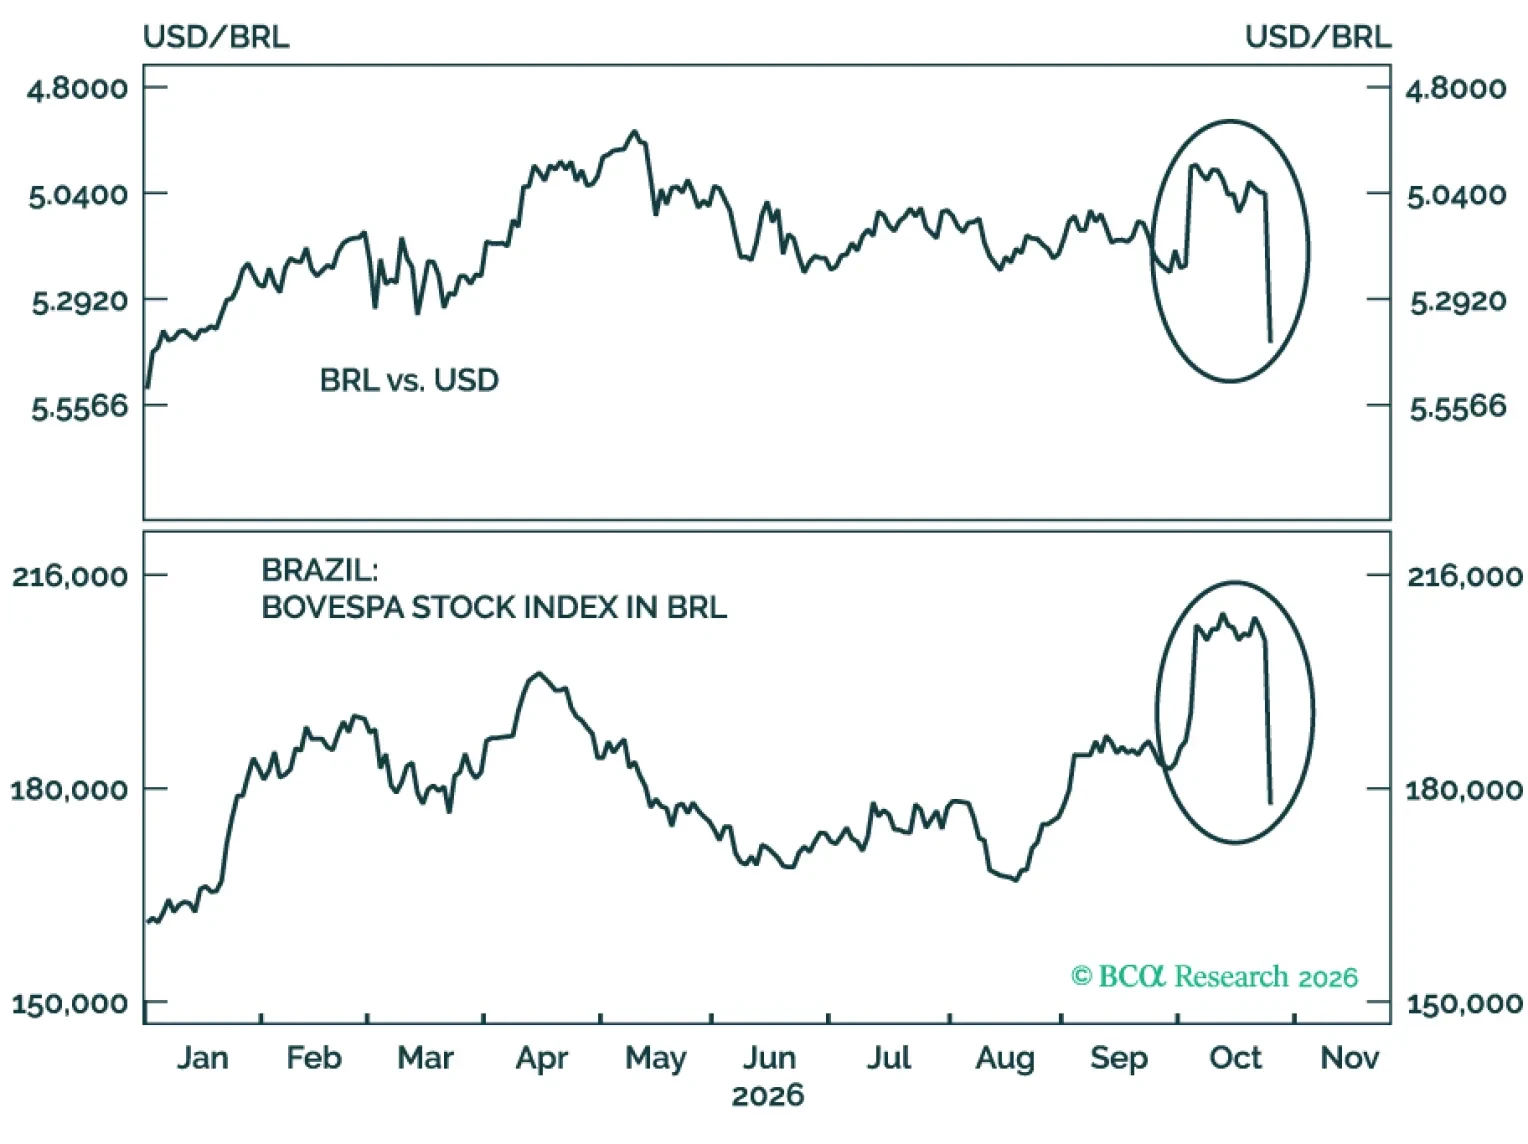
Brazil’s elections have turned into a game of roulette for investors. Bulls and bears were each wrong-footed between the first and second rounds of elections. We are downgrading Brazilian equities, local bonds, and sovereign credit to underweight within their respective EM portfolios.
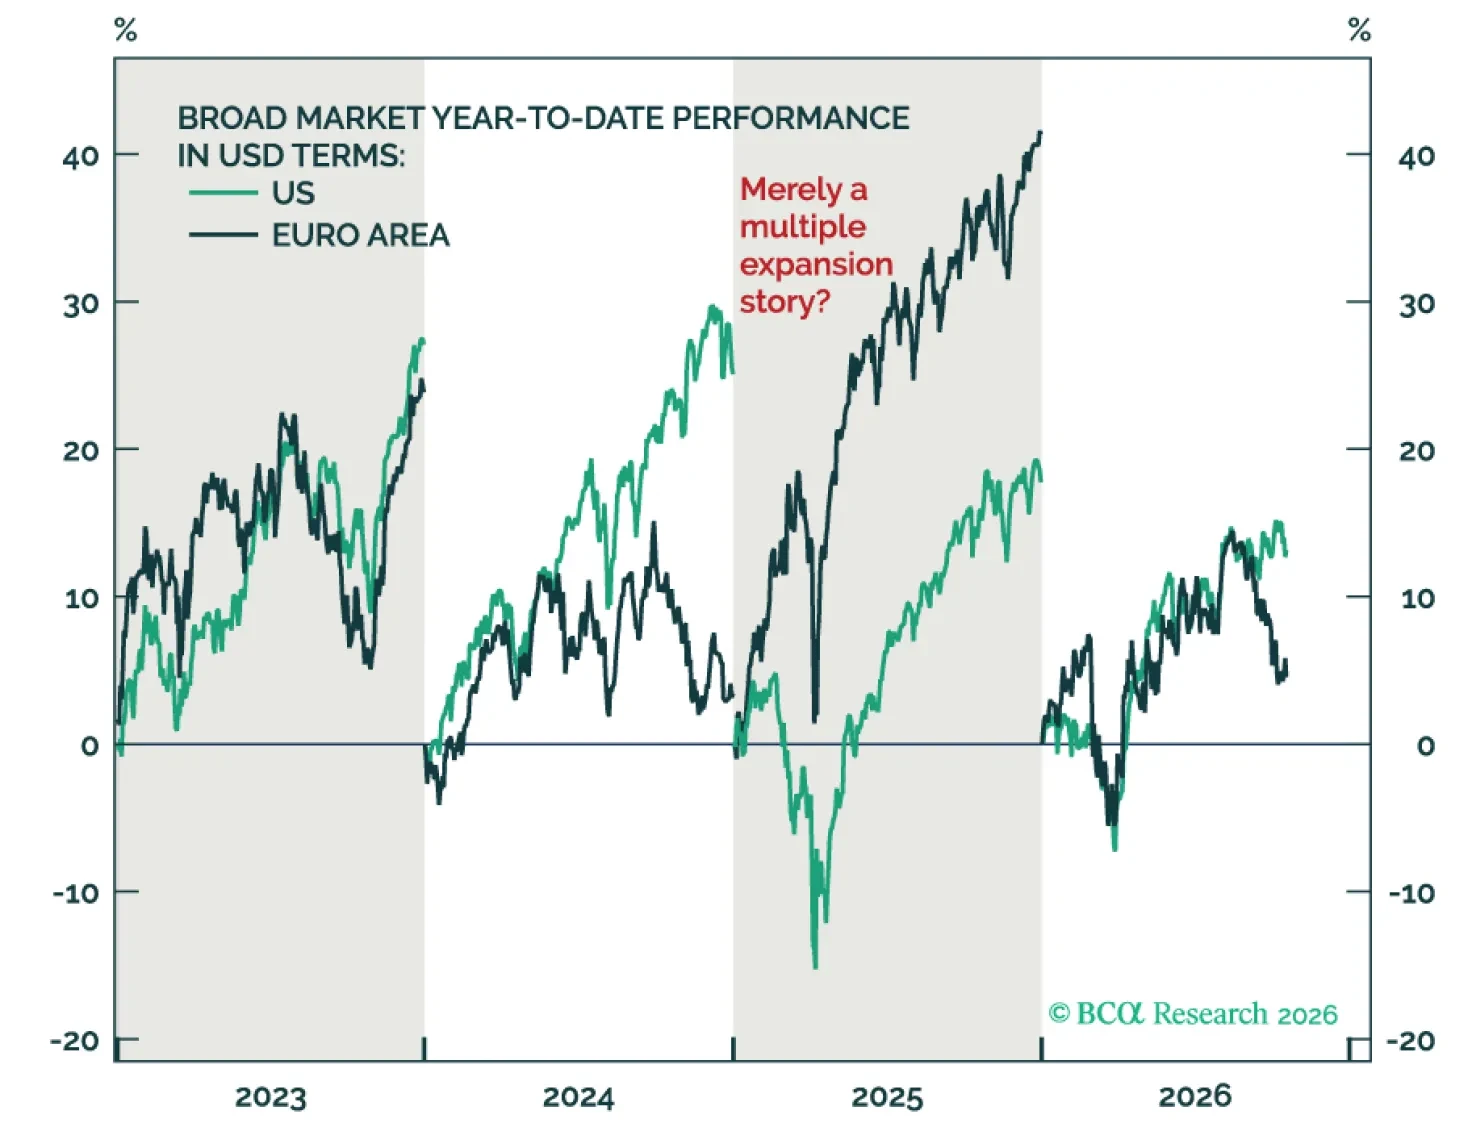
Europe has 99 problems, but the paucity of bearish views about the Old Continent is not one of them! And yet, somewhat shockingly, European assets have outperformed US assets over the past two years. Sure, markets make mistakes. But the macro graveyards are littered with investors who thought they were smarter than the markets. In this report, we suggest that Europe is on a cusp of significant structural reforms that will unlock value in its services sector. And that while many of the challenges are real, they’re either well understood or priced in.
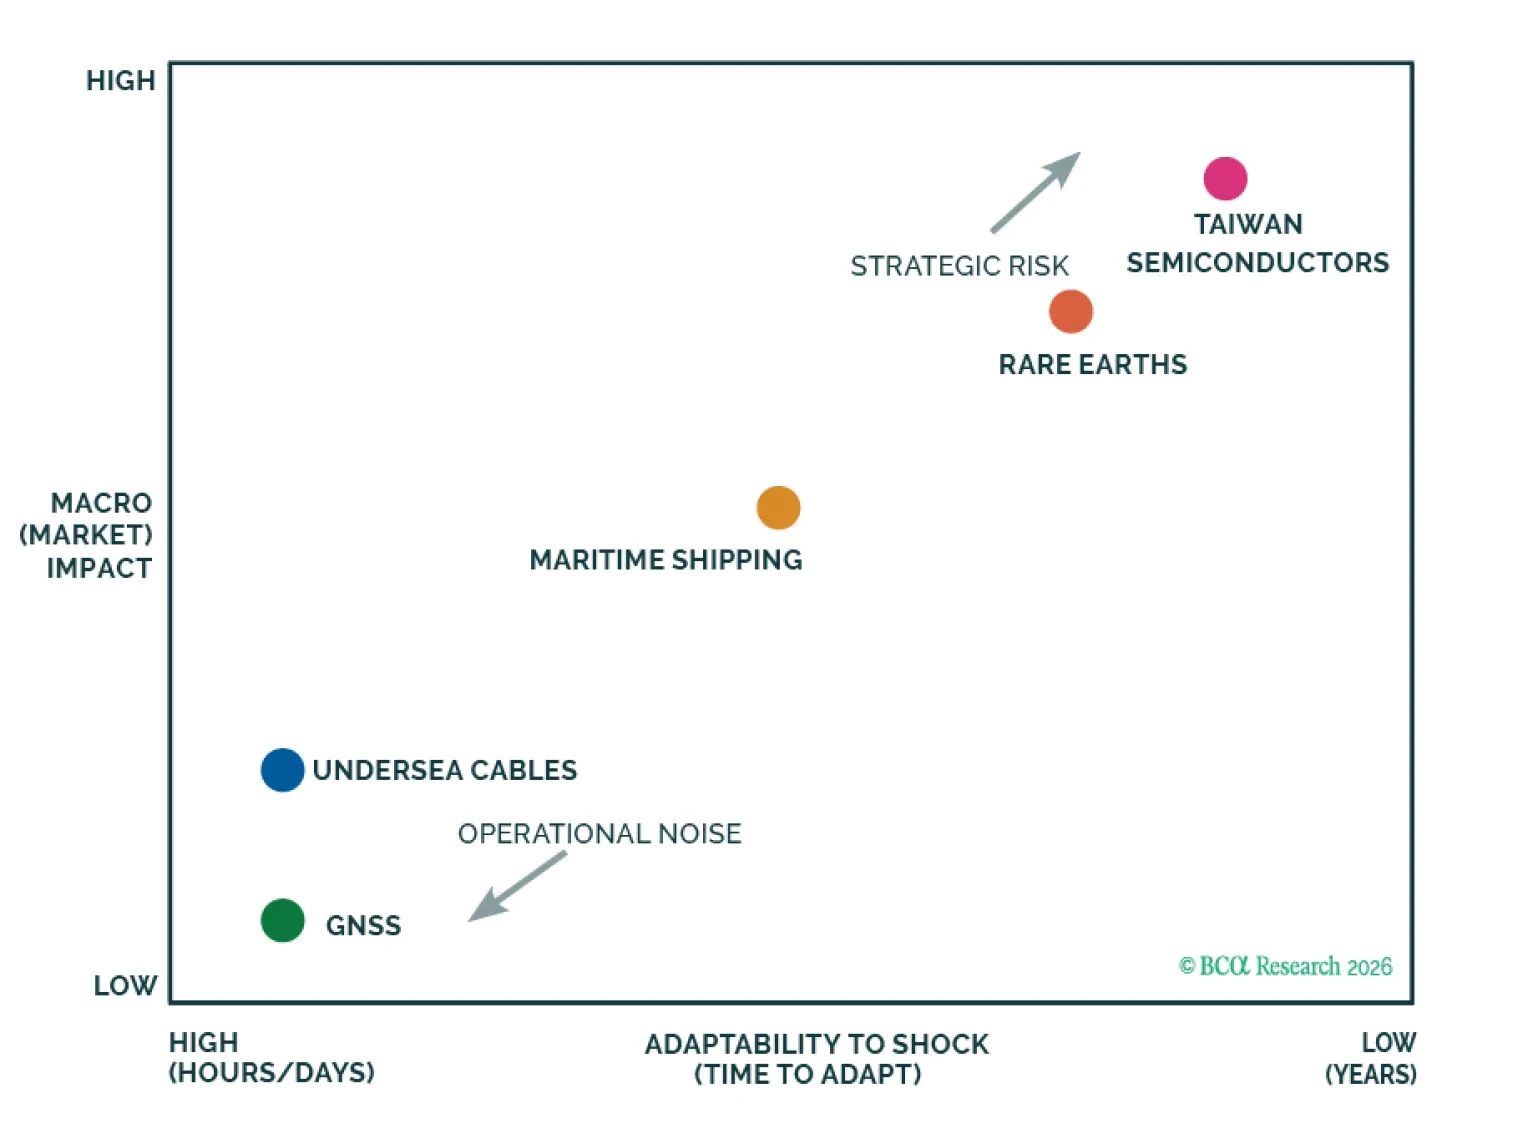
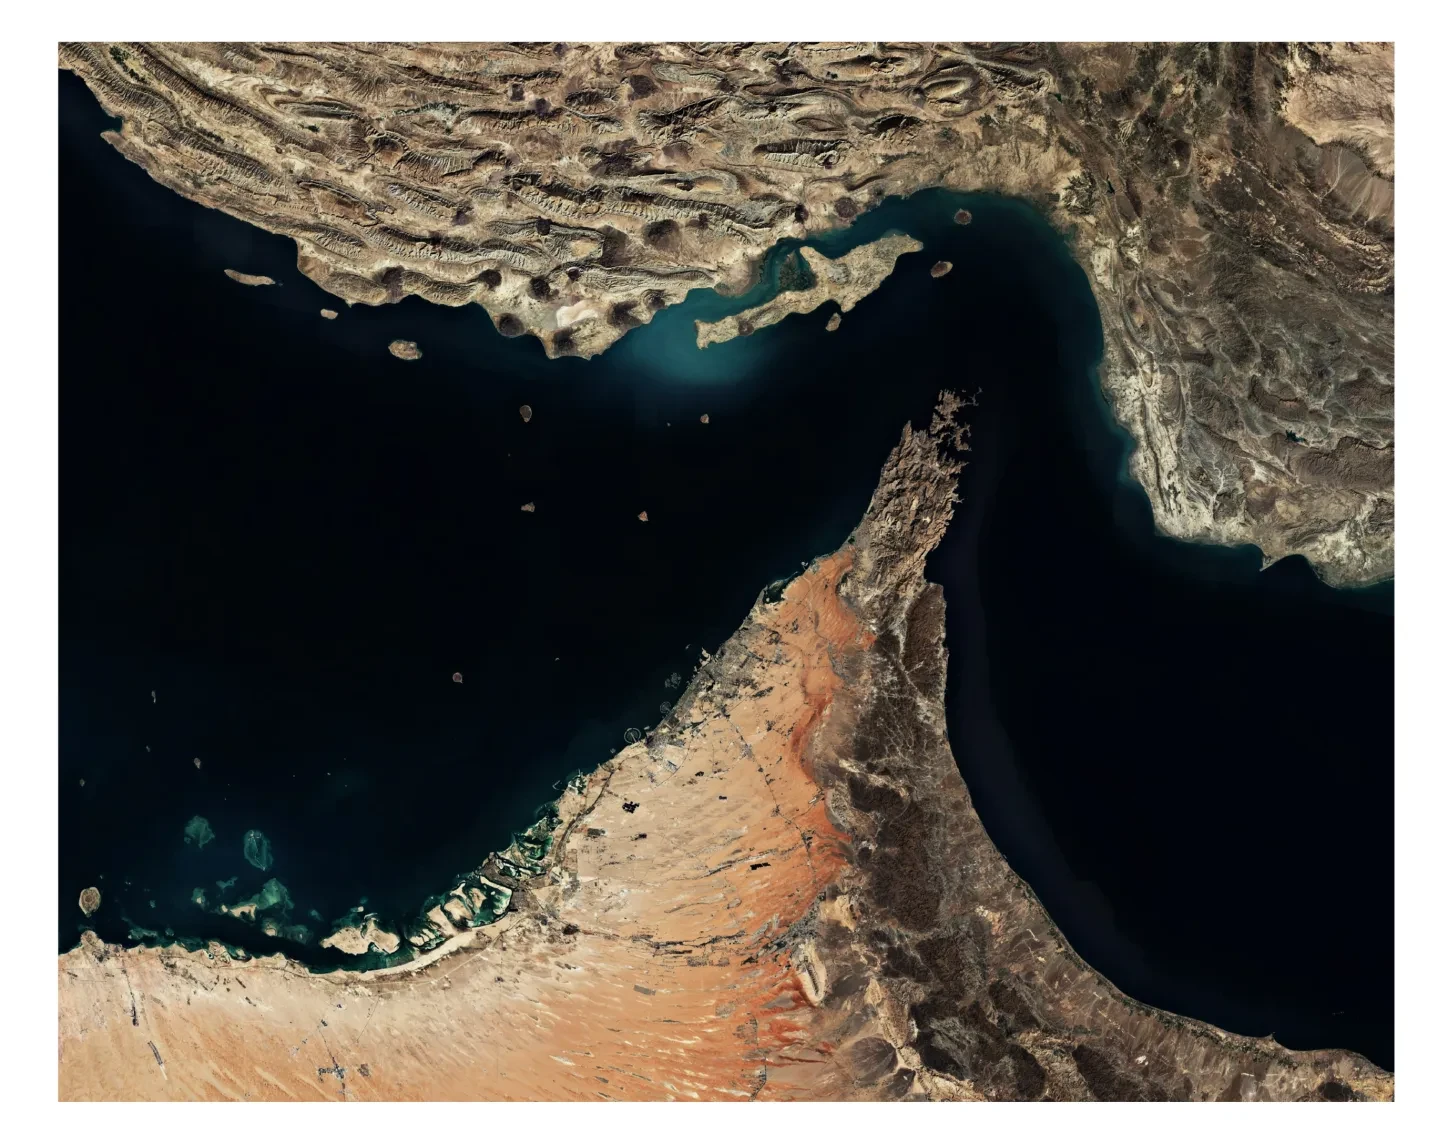
Iran is effectively trying to create an “October surprise,” an adage that refers to a pre-election crisis that alters the trajectory of polling and the eventual outcome. It is likely to be successful, with oil prices likely to face upward momentum from here. The intention would be to ensure that oil prices do not see any significant decline from now until November 3.
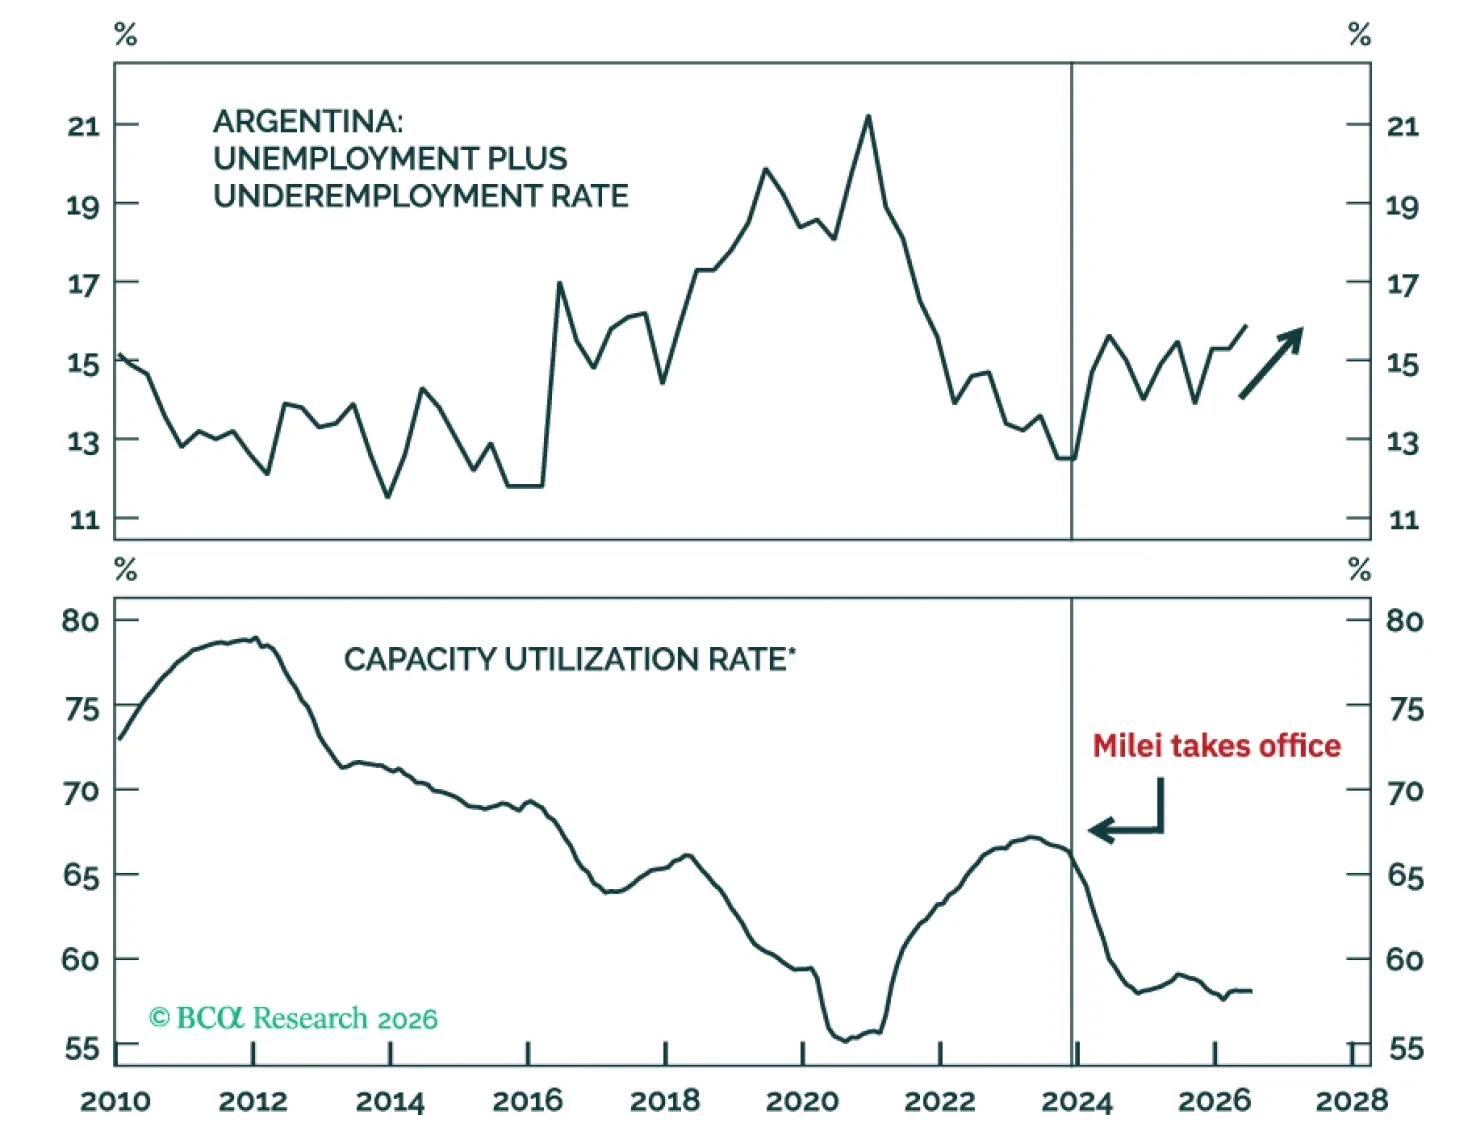
If President Milei does not ease policy immediately to contain the disinflationary squeeze, he is likely to lose next year's election. This means neoliberal structural reforms will suffer a setback in subsequent years. Close long positions in Argentine assets.