 CoreMacro
Find out more
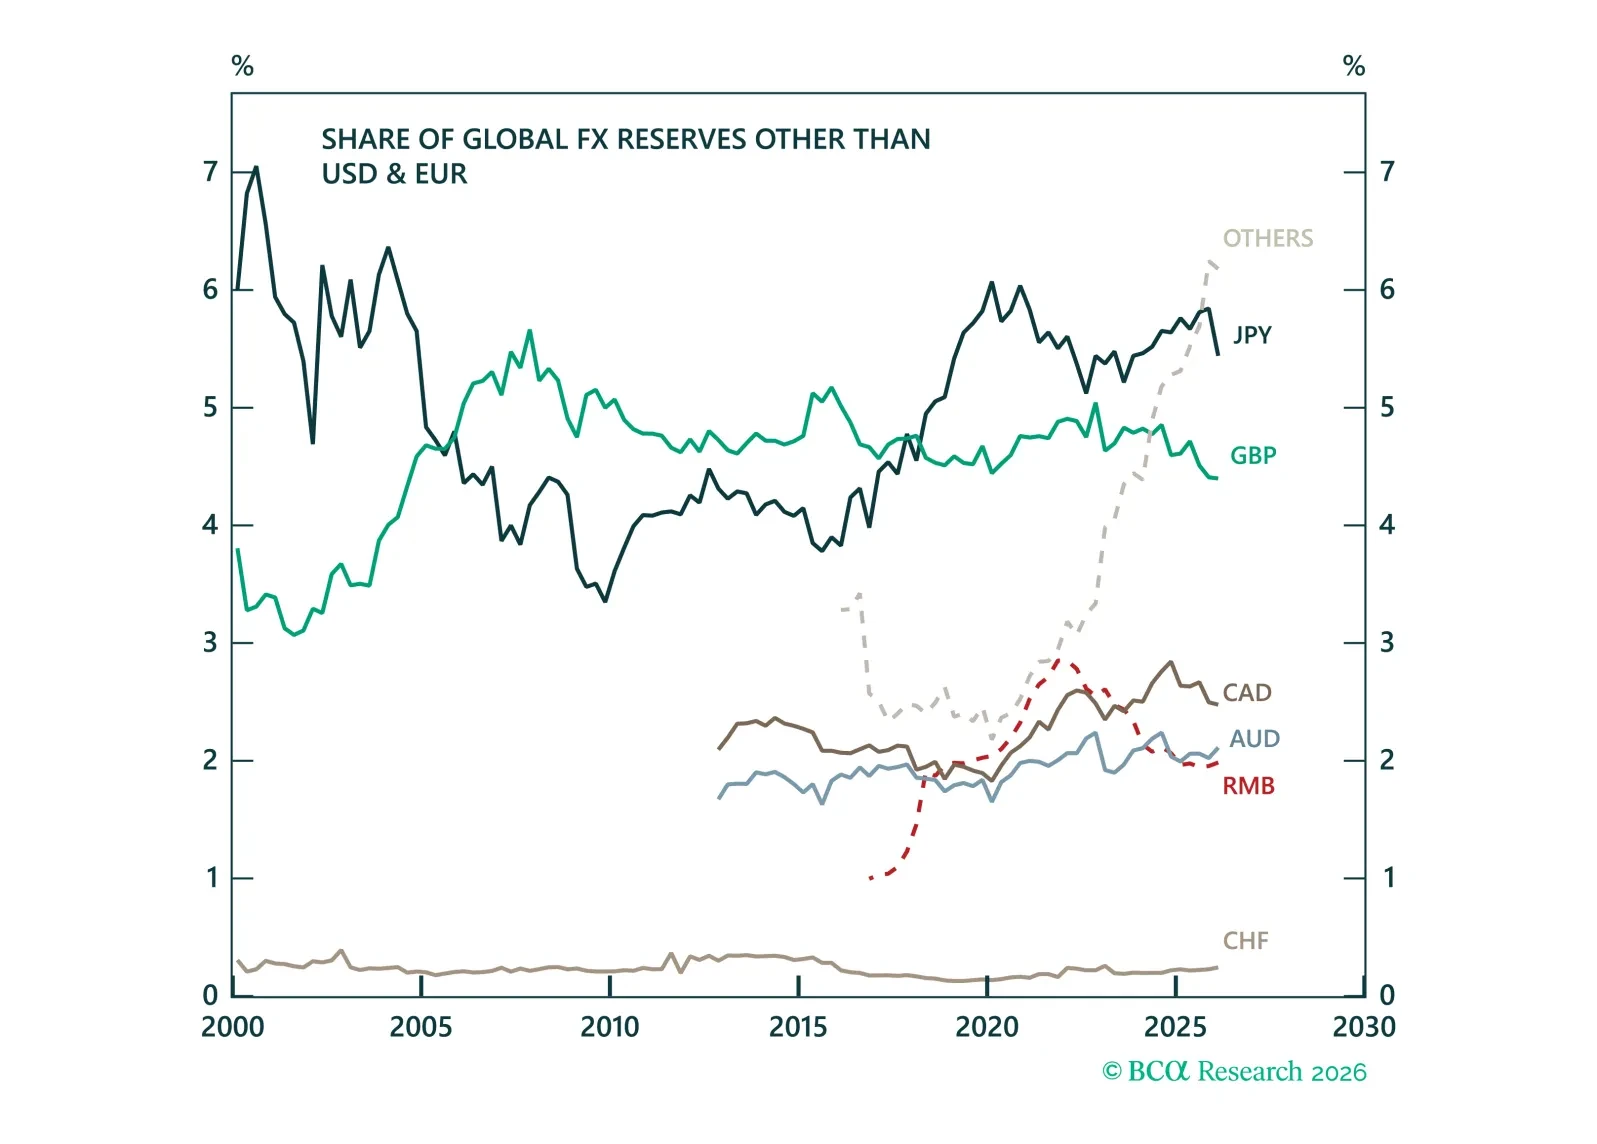
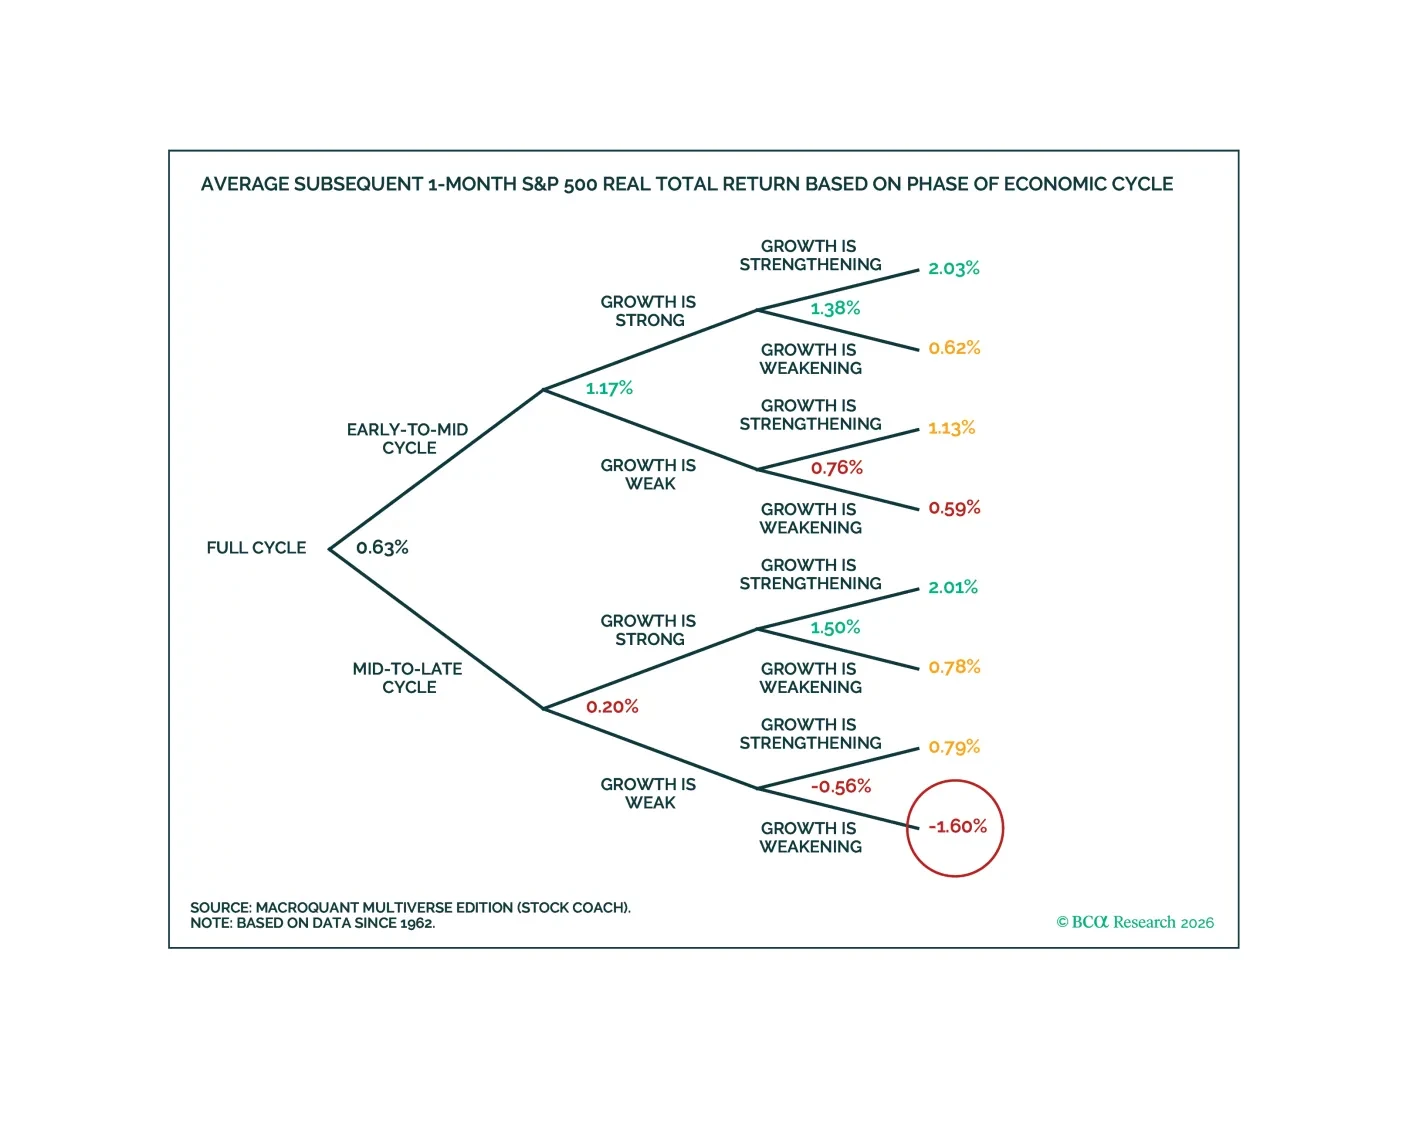
MacroQuant recommends underweighting equities and adopting a benchmark duration stance in fixed-income portfolios. The model is very positive on the US dollar, bearish on gold, neutral on copper, and bullish on oil.
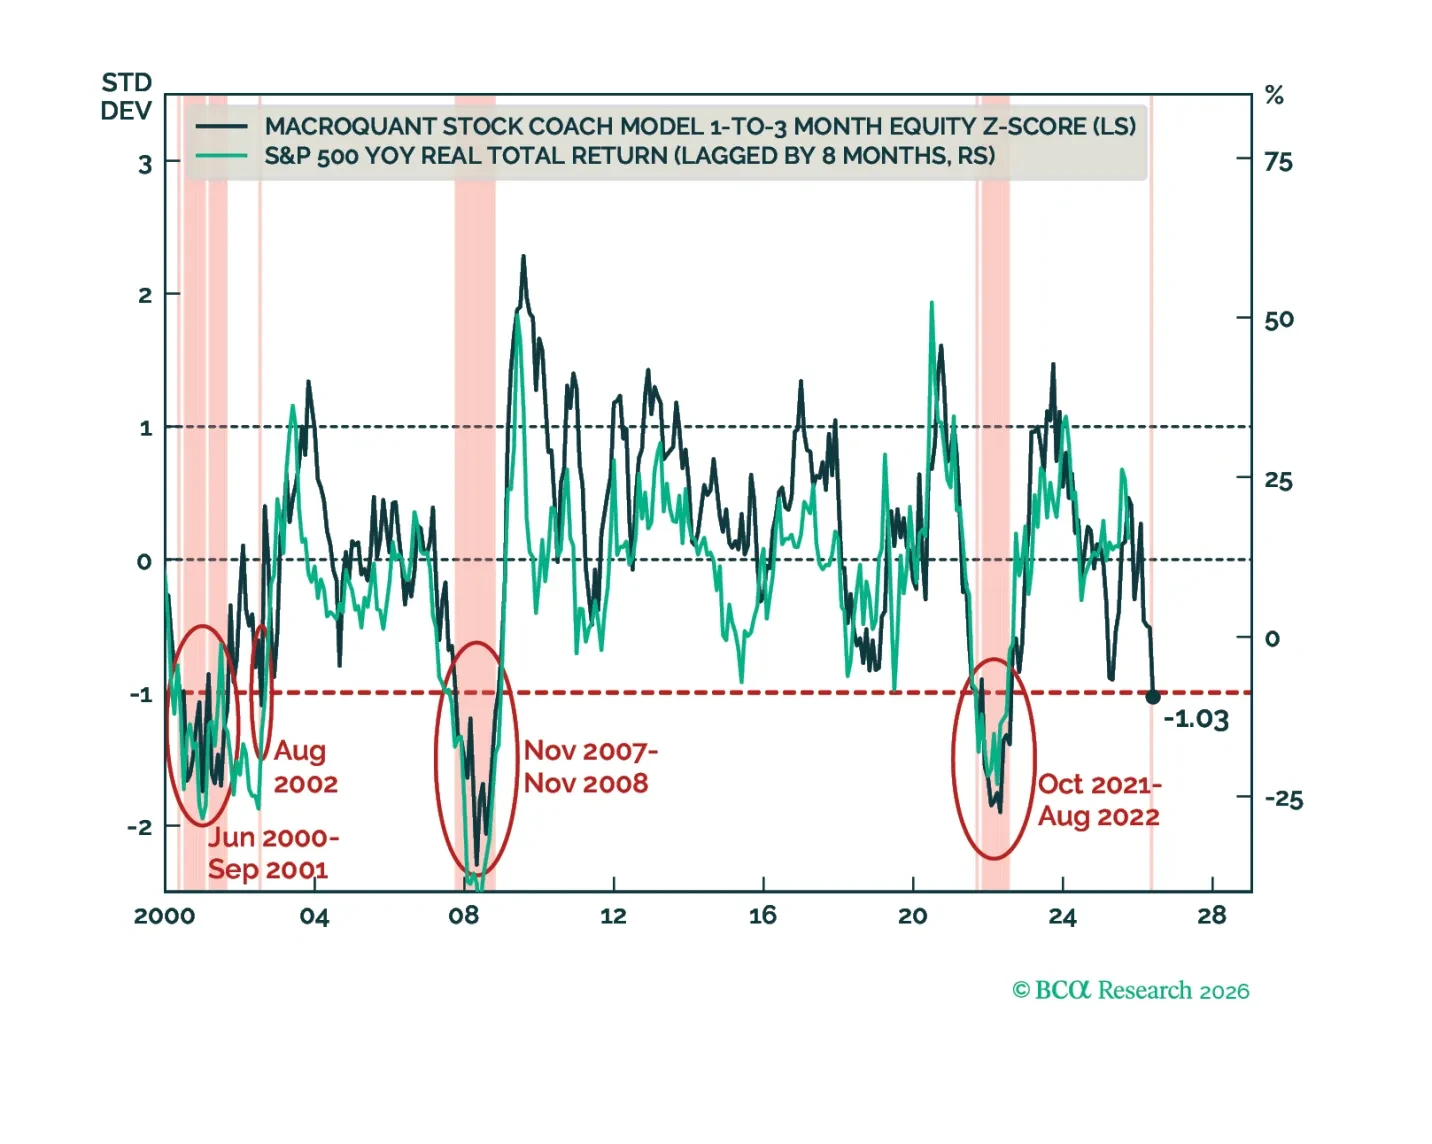
The equity bull market is getting long in the tooth. Bonds should perform well once economic growth begins to slow. The dollar will strengthen over the coming months before resuming its downtrend. While crude has likely found a near-term floor, we favor metals over energy in the long run.
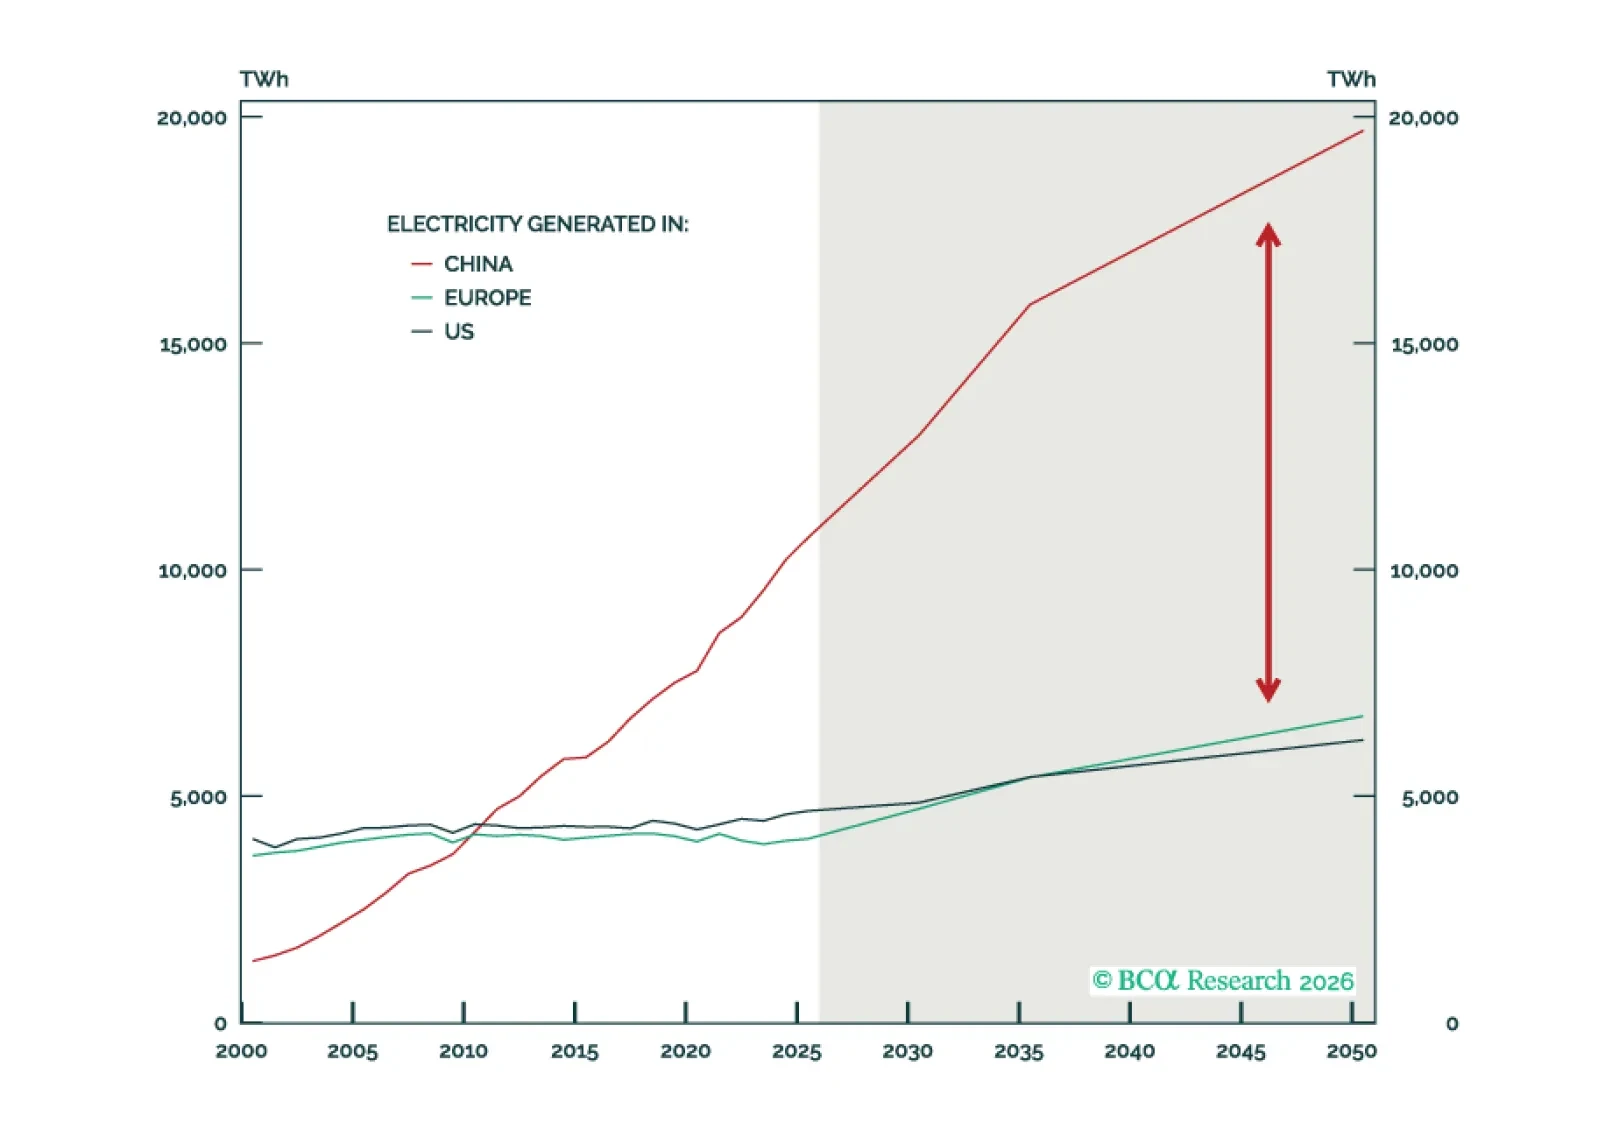
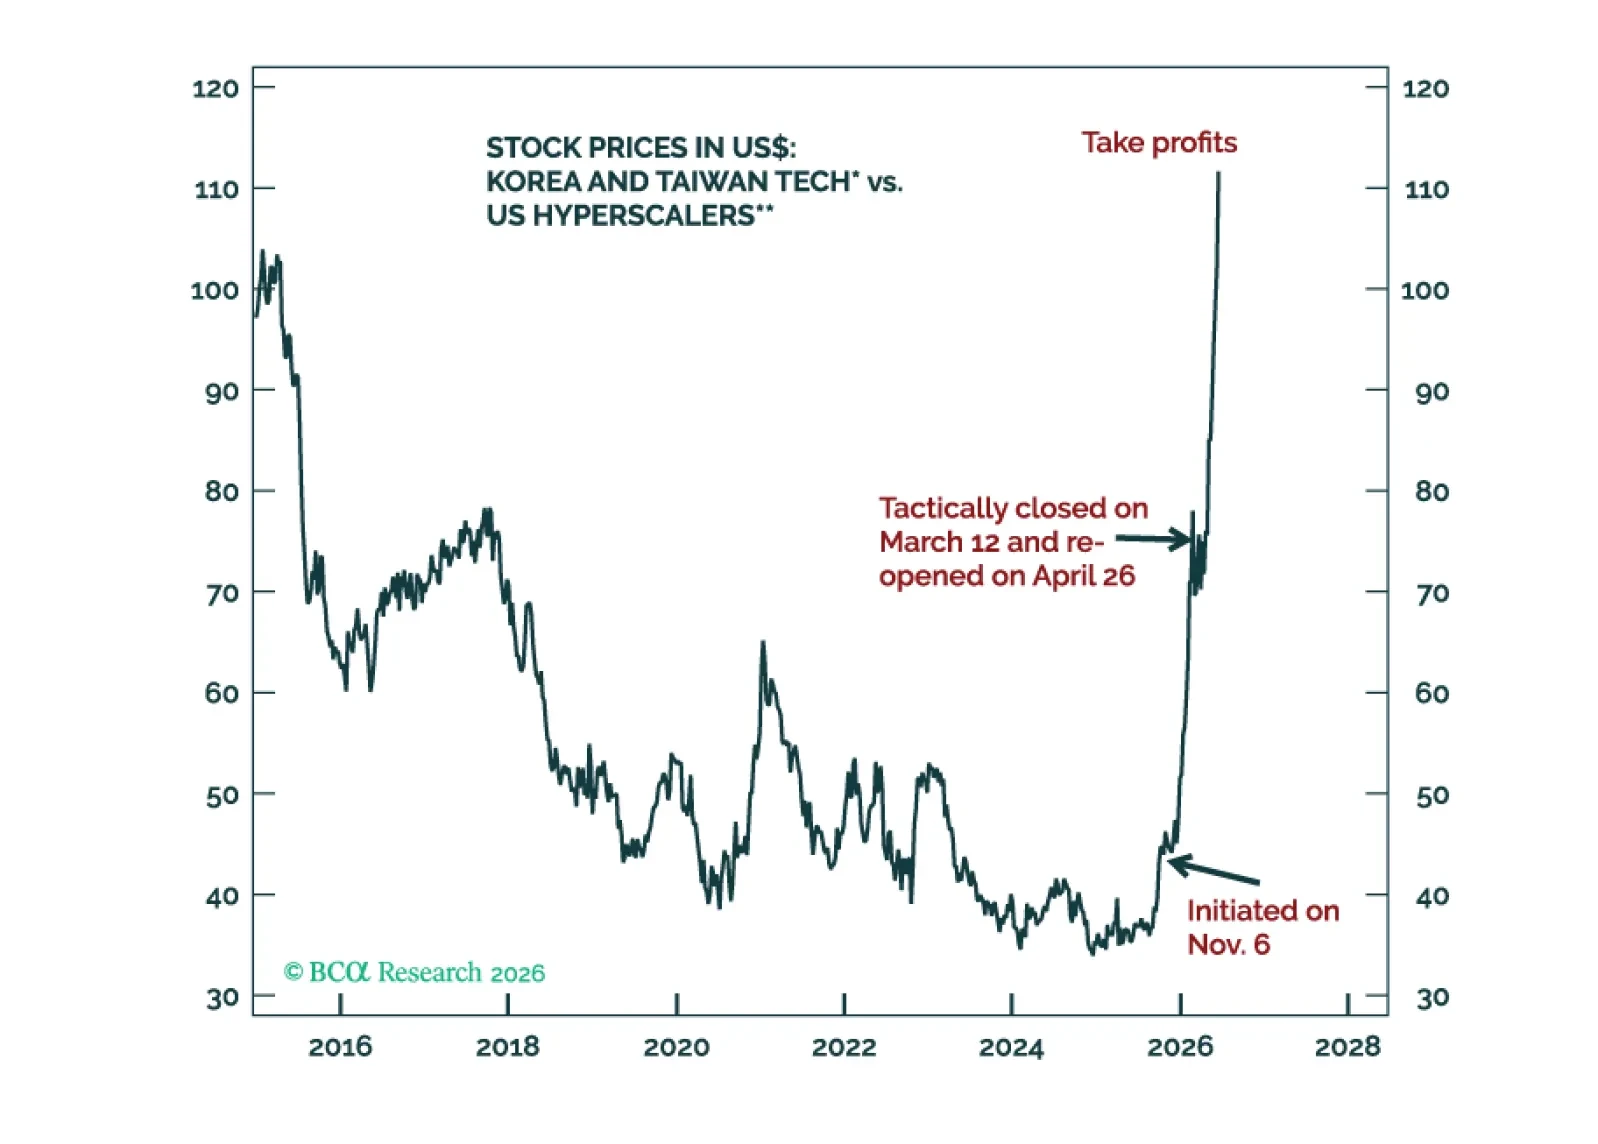
Korea’s recent equity market tantrum is a warning signal for global risk assets. We are booking profits on the long Asian semiconductor stocks / short US hyperscalers trade and downgrading Korea from overweight to neutral in an EM equity portfolio.
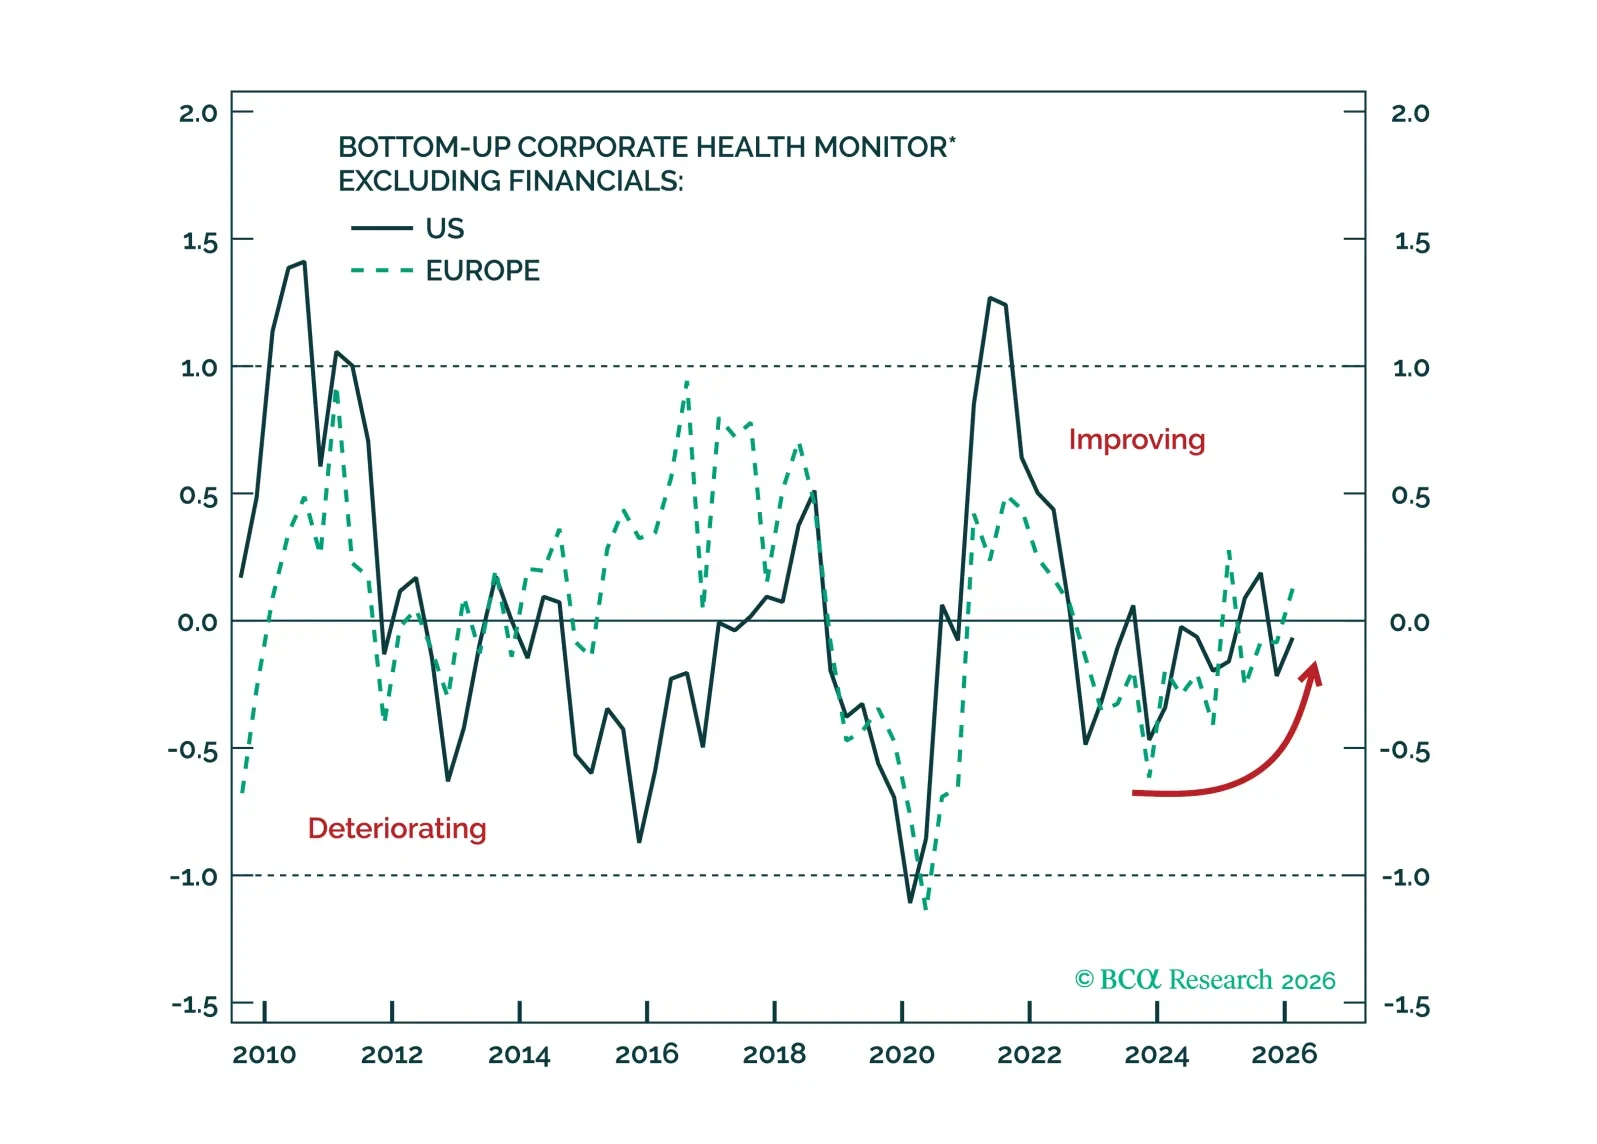
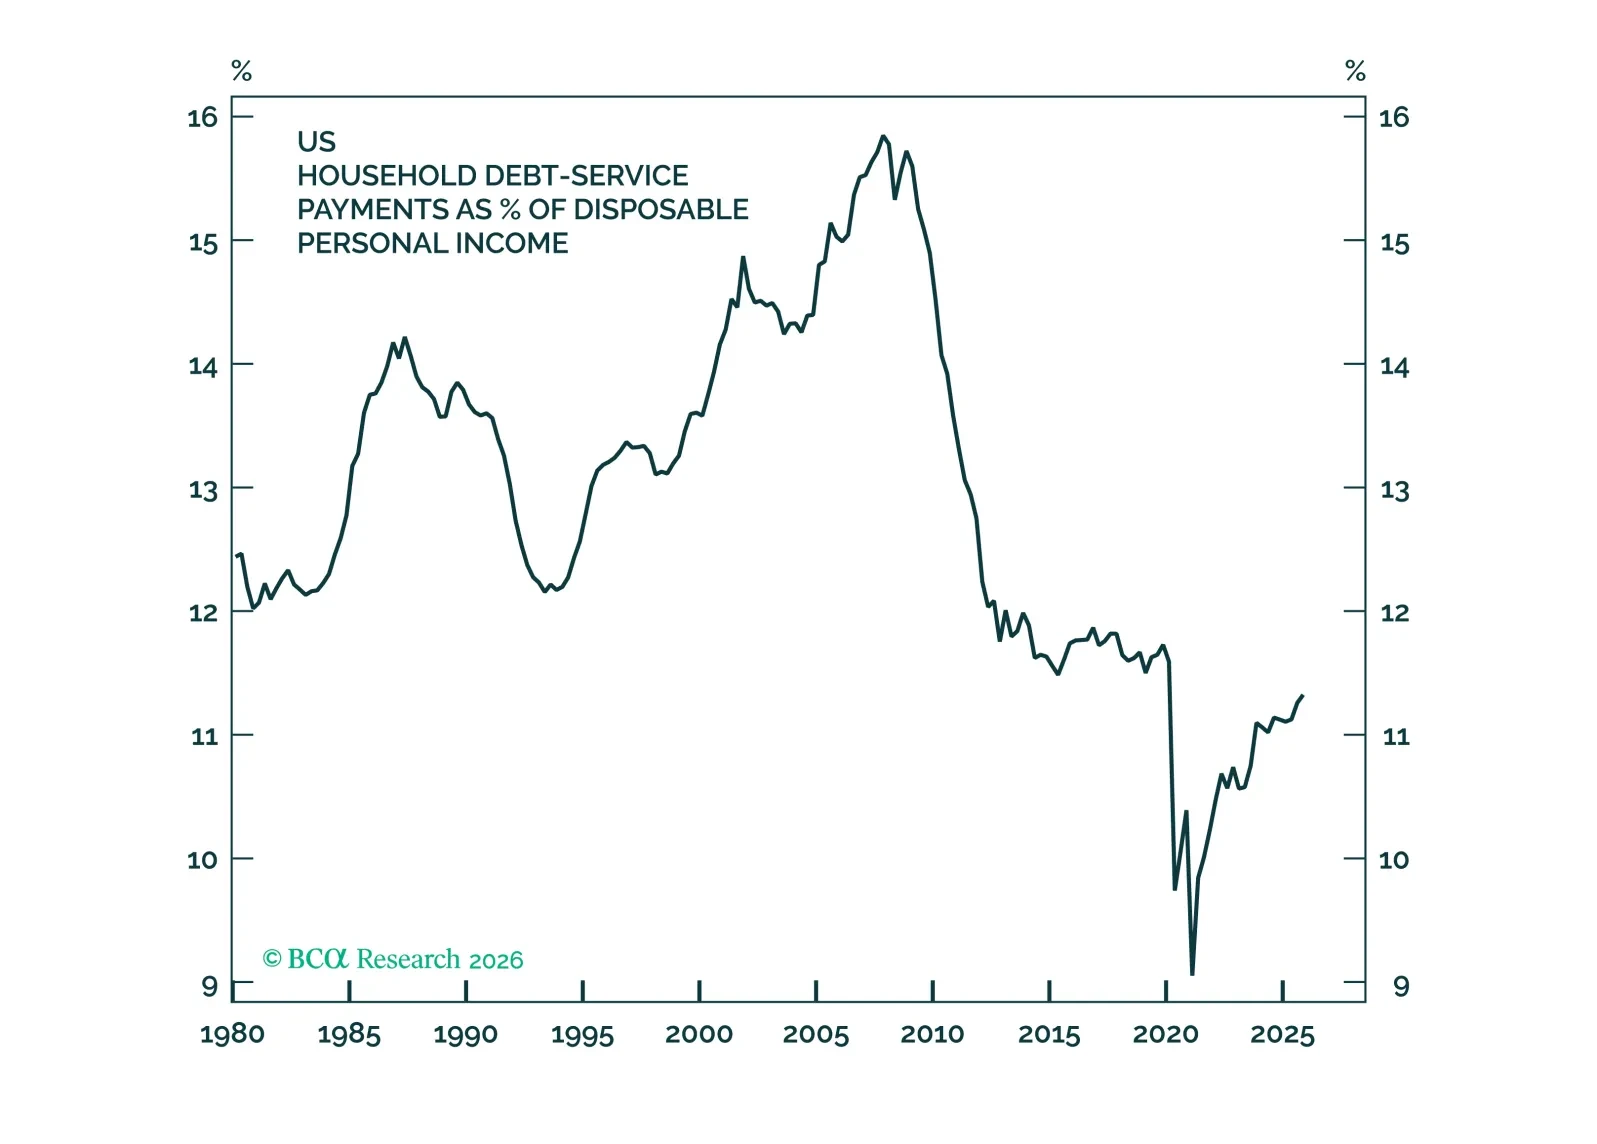
The most vulnerable households have whittled down their real debt balances while achieving significant real wealth gains. The combination has made consumption more resilient to income hiccups than in past cycles.
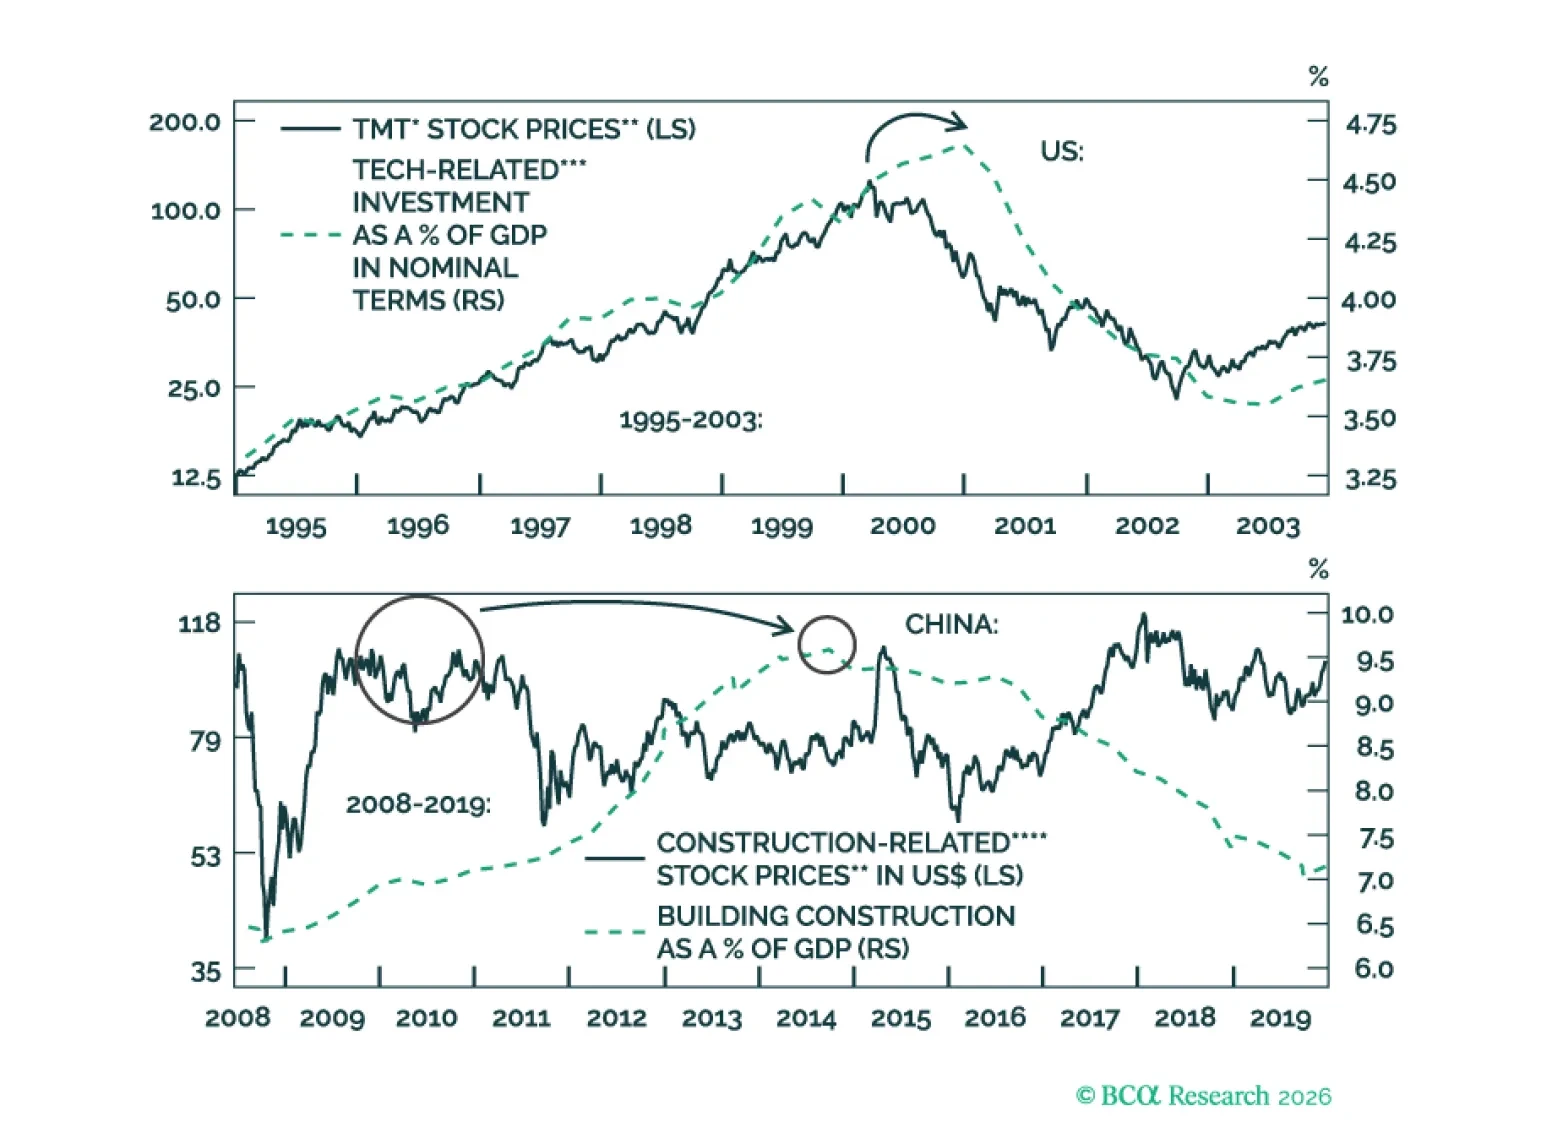
AI is transformative, yet tech stocks may not produce positive returns. Market cycles have not disappeared. Greed and fear will still produce large share price fluctuations. Meanwhile, US inflation is the key near-term risk. Global non-tech capex aspirations also look overstated.
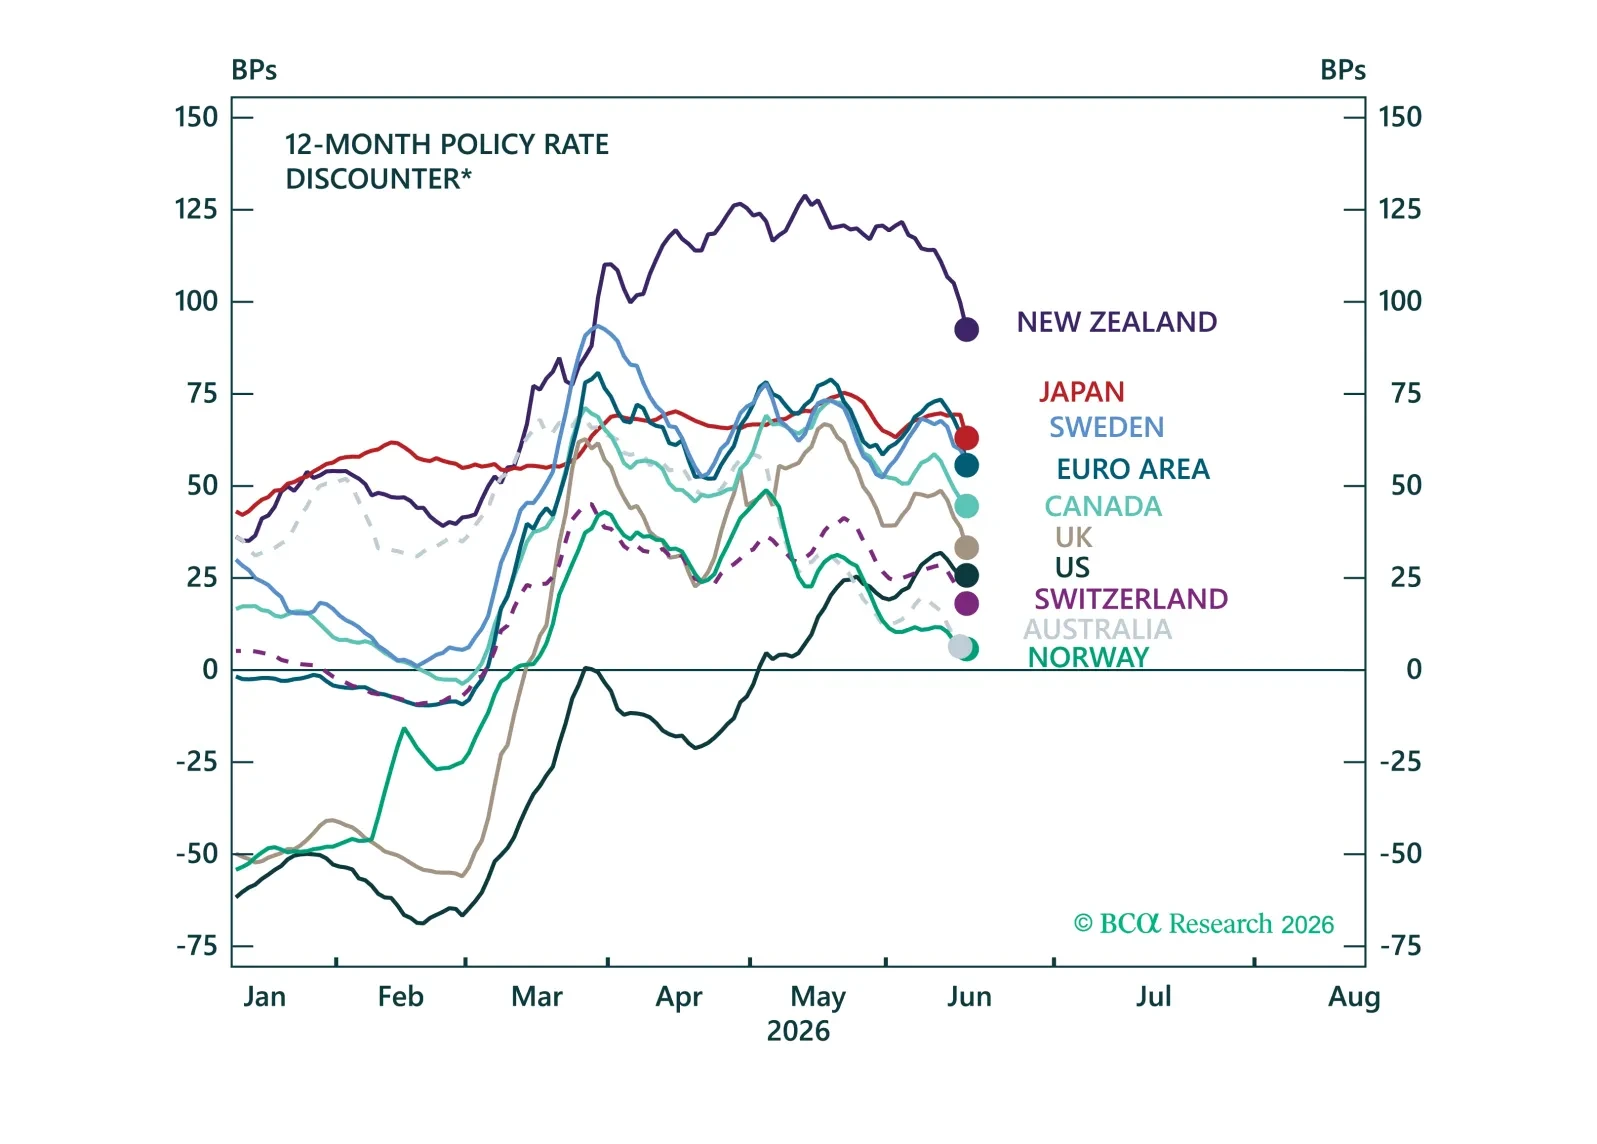
We react to DM central bank meetings this week and highlight the opportunities emerging across global fixed income and currency markets.
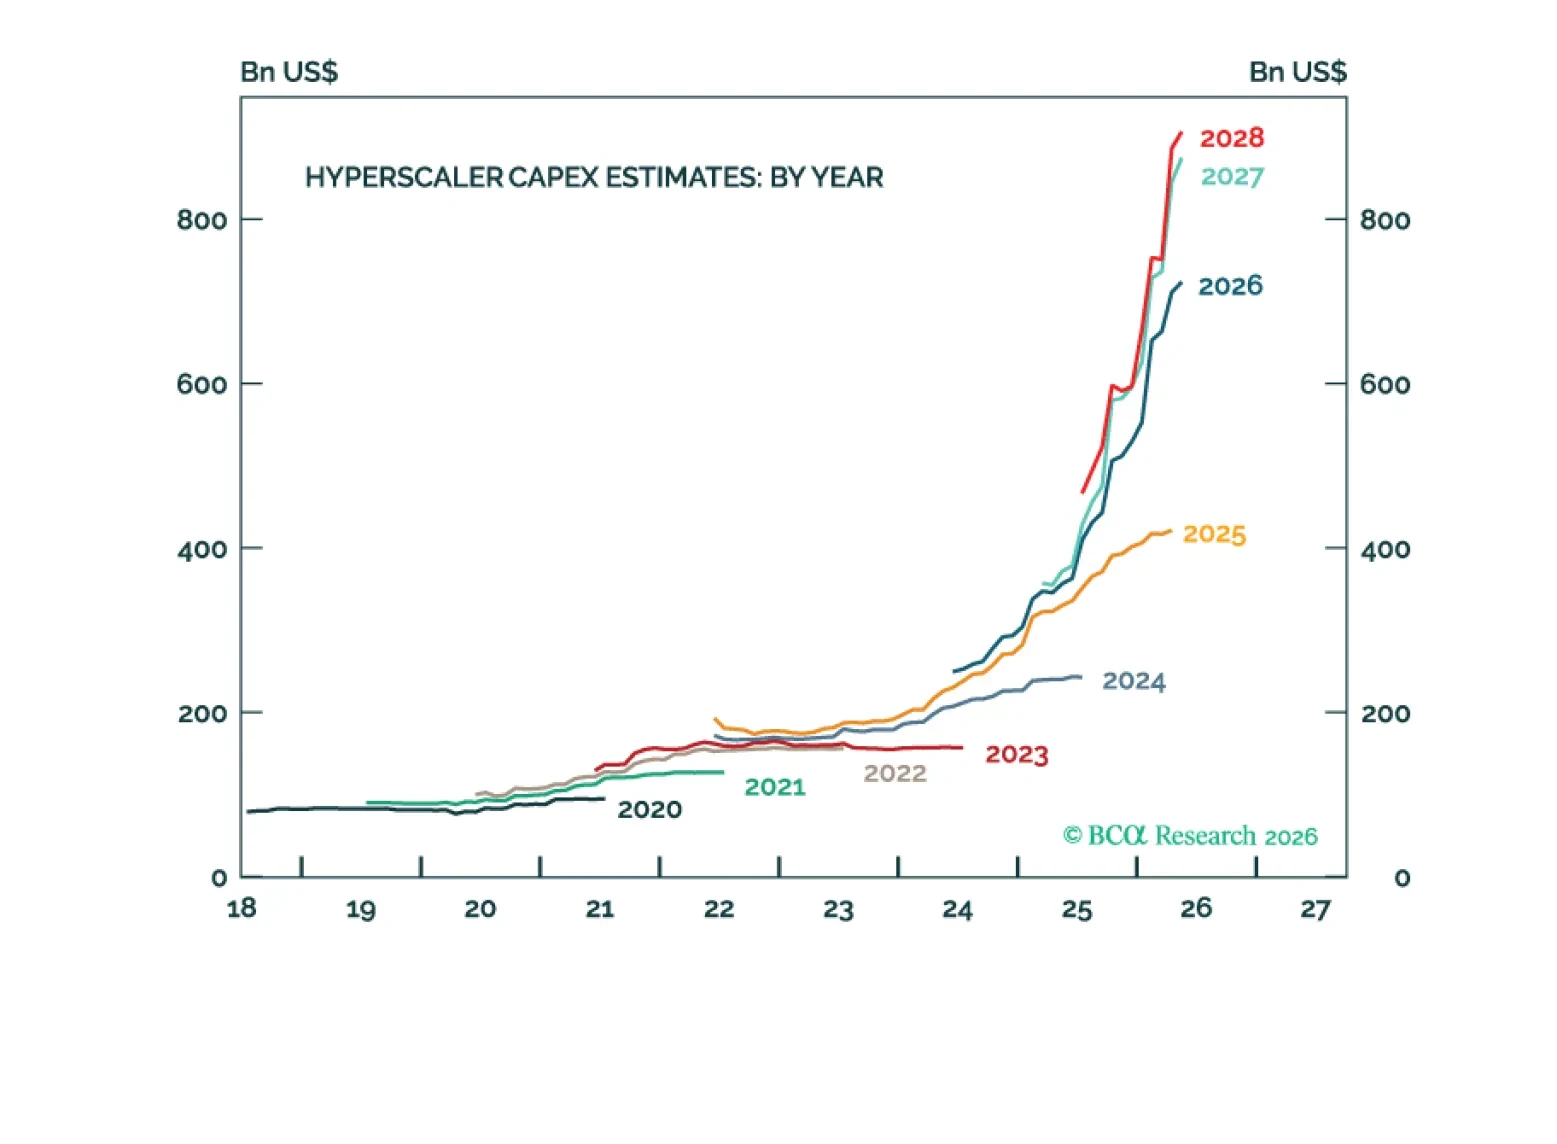
A surefire way to make money is to buy stocks in industries experiencing shortages. AI supply-chain bottlenecks will persist for the next few years but markets will price in relief before then.