 CoreMacro
Find out more
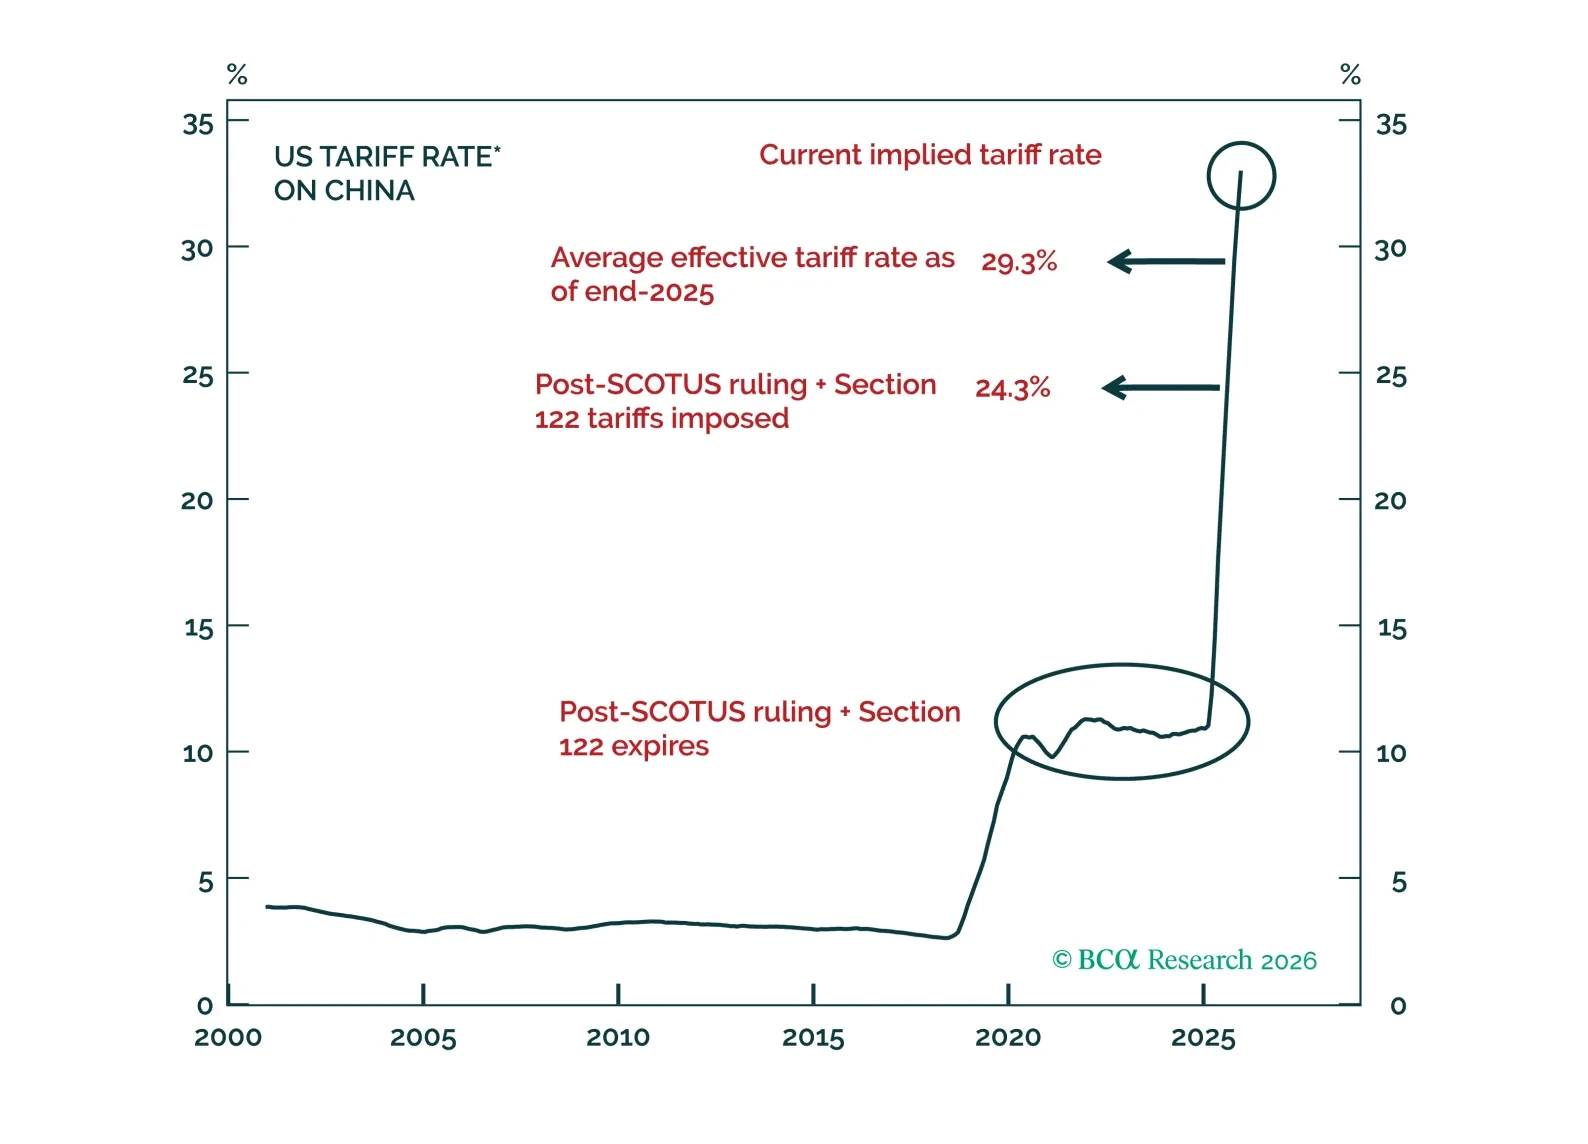
This report examines the implications for Chinese exports and global trade in light of the US Supreme Court’s ruling on tariffs.
Fourth quarter US GDP growth clocked in at 1.4%, well below consensus expectations of 2.8%. We are not too troubled by the miss. The government shutdown weighed on the economy, with government spending subtracting 0.9 percentage points from growth. Real private final domestic demand – a clean measure of GDP growth that excludes government expenditure, net exports, and inventories – rose by a respectable 2.4%.
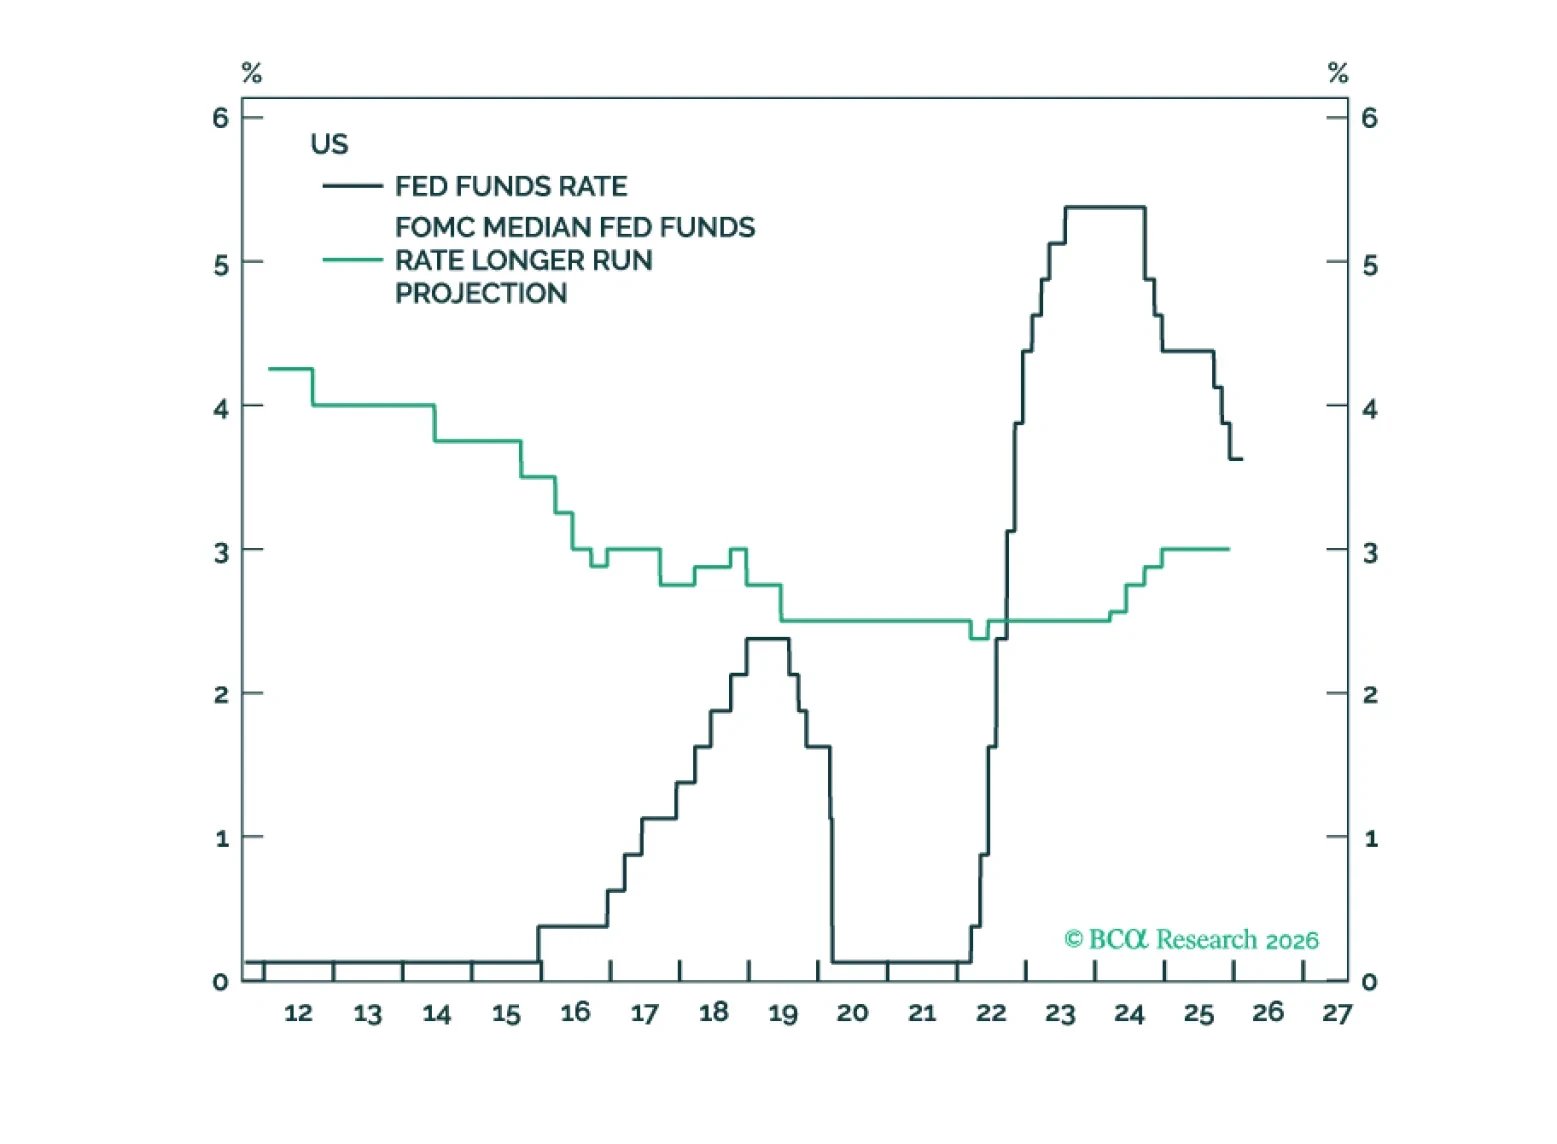
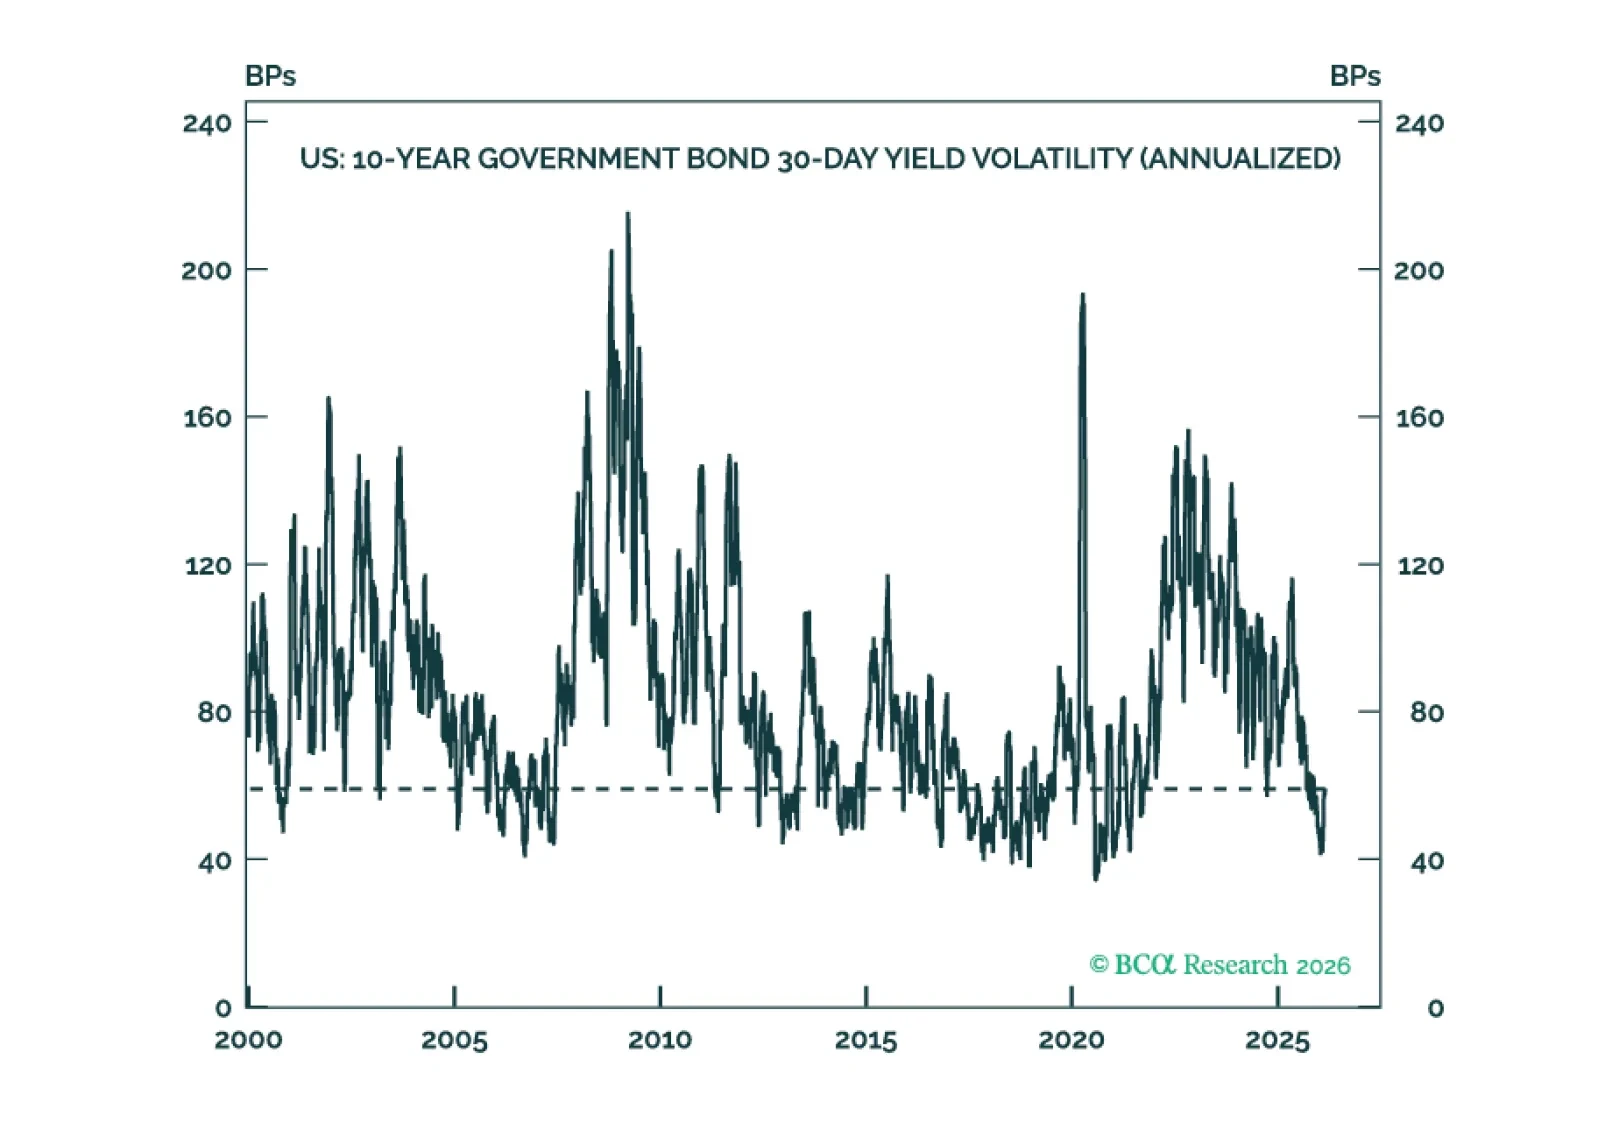
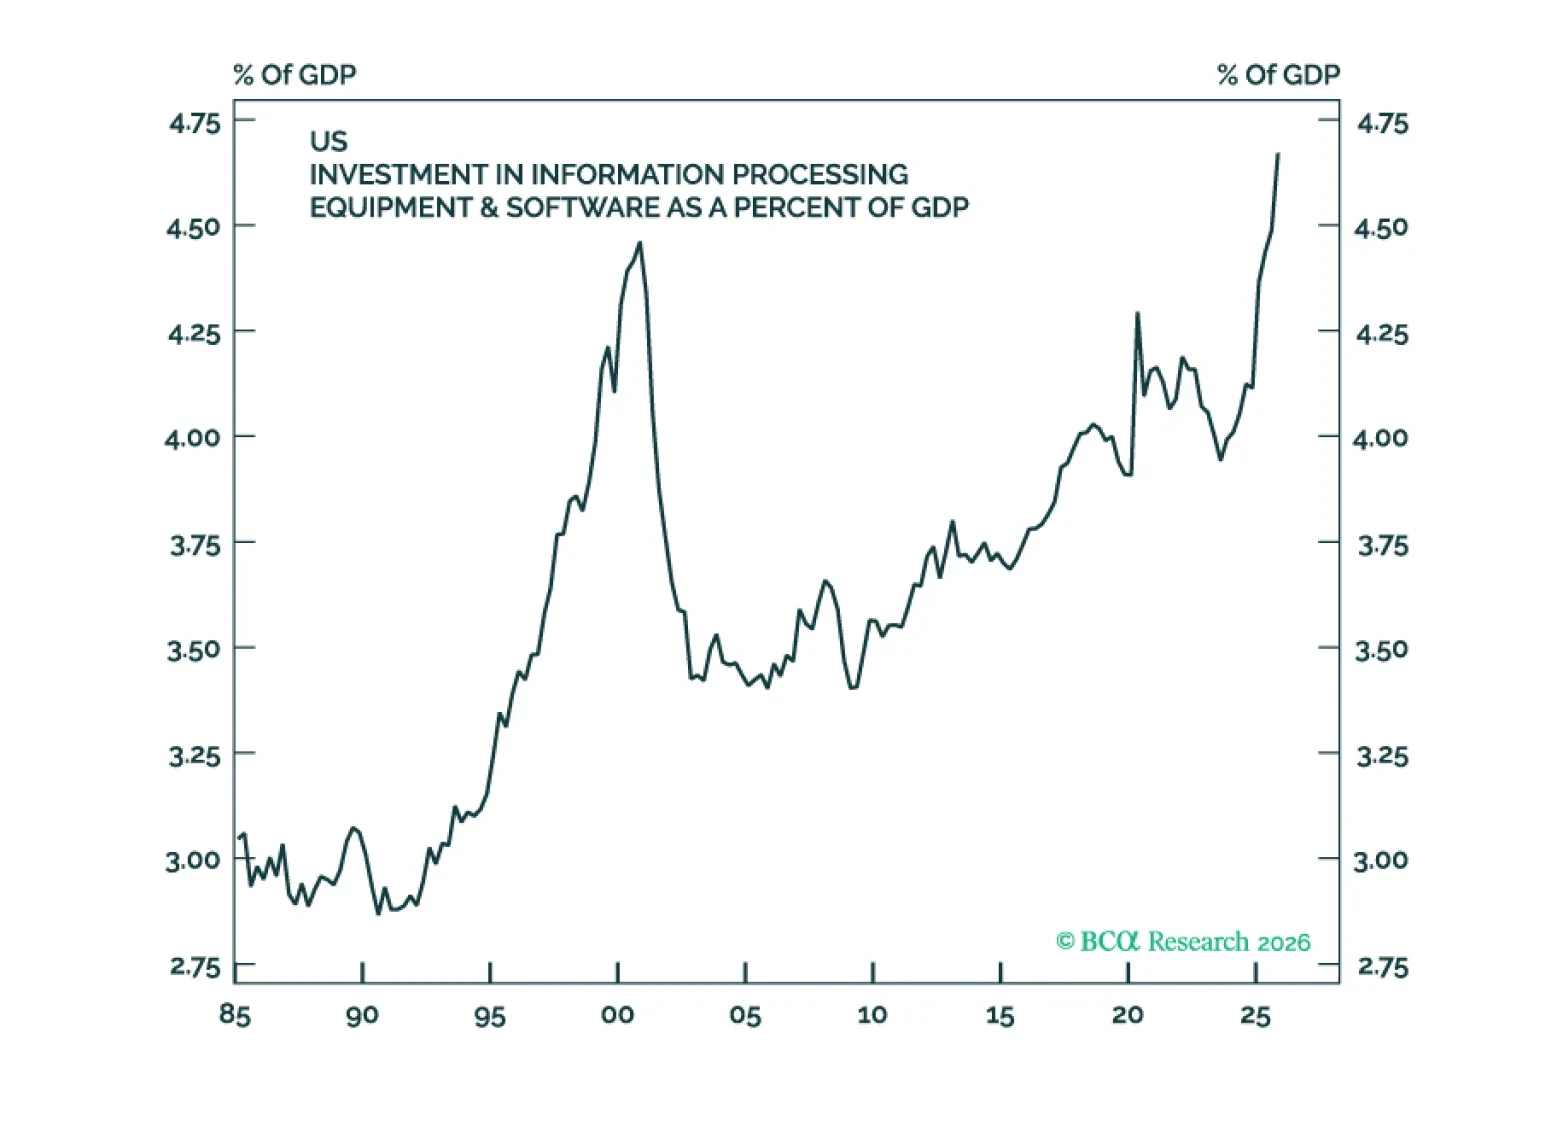
The neutral rate in the US is being propped up by a variety of forces that are at risk of reversing. These include the AI capex boom, large budget deficits, and the extraordinarily high level of household wealth. As such, interest rates are likely to surprise to the downside over the next few years.
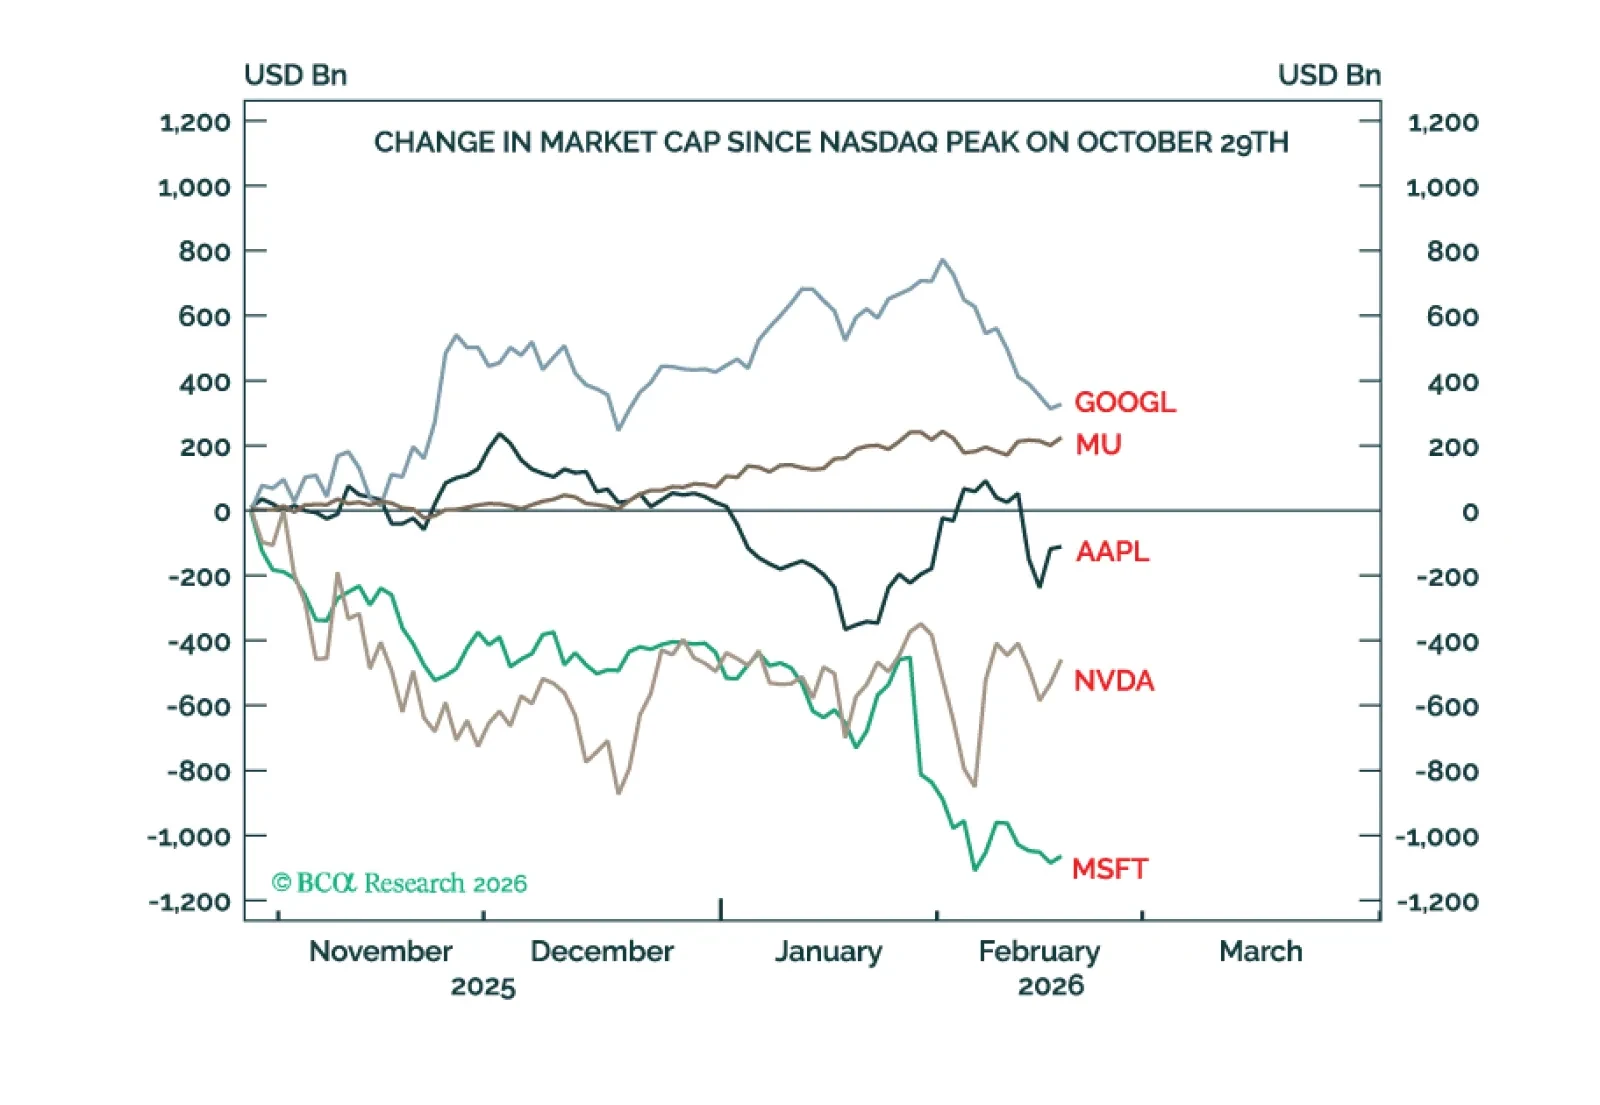
Tech has starkly underperformed other equity sectors and the tech-heavy US market has underperformed non-US markets, but global stocks are up and have comfortably outperformed bonds. This pattern of performances is likely to continue through the rest of 2026. Plus, two new tactical trades are: long coffee; and long ETH.
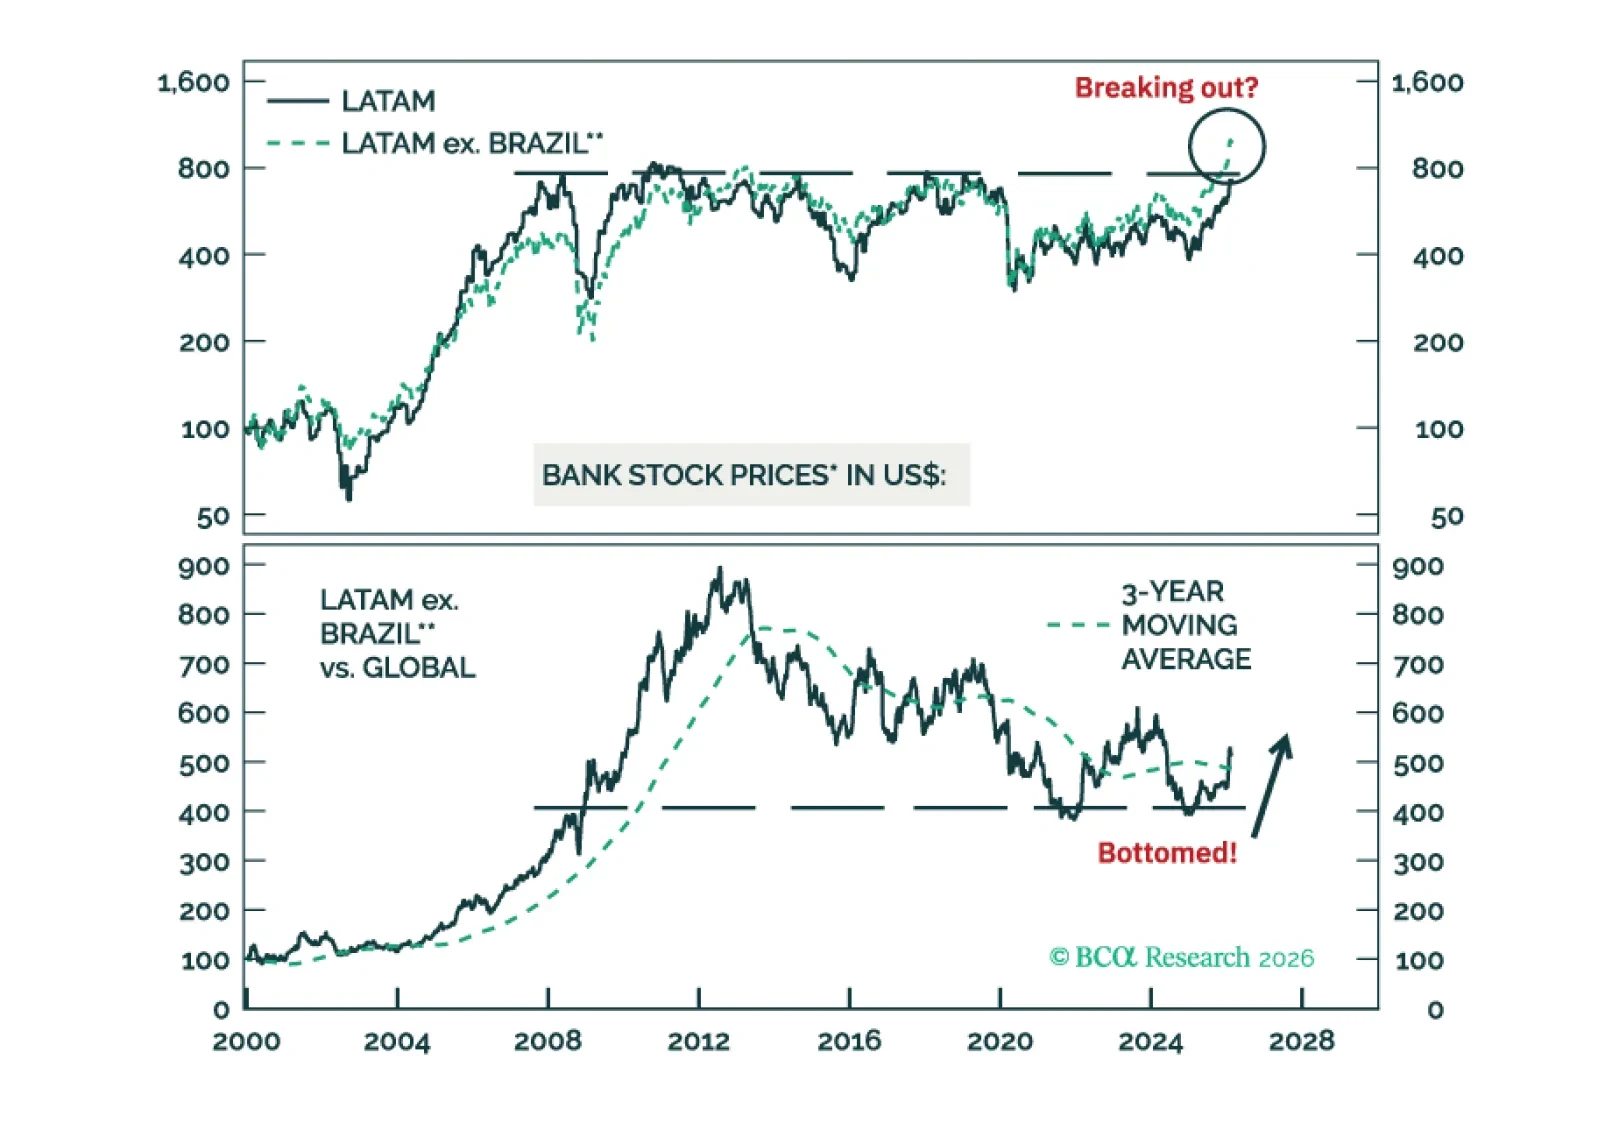
Go long LATAM ex. Brazil banks / short global bank stocks. Brazilian bank equities will underperform due to poor and worsening macro fundamentals.
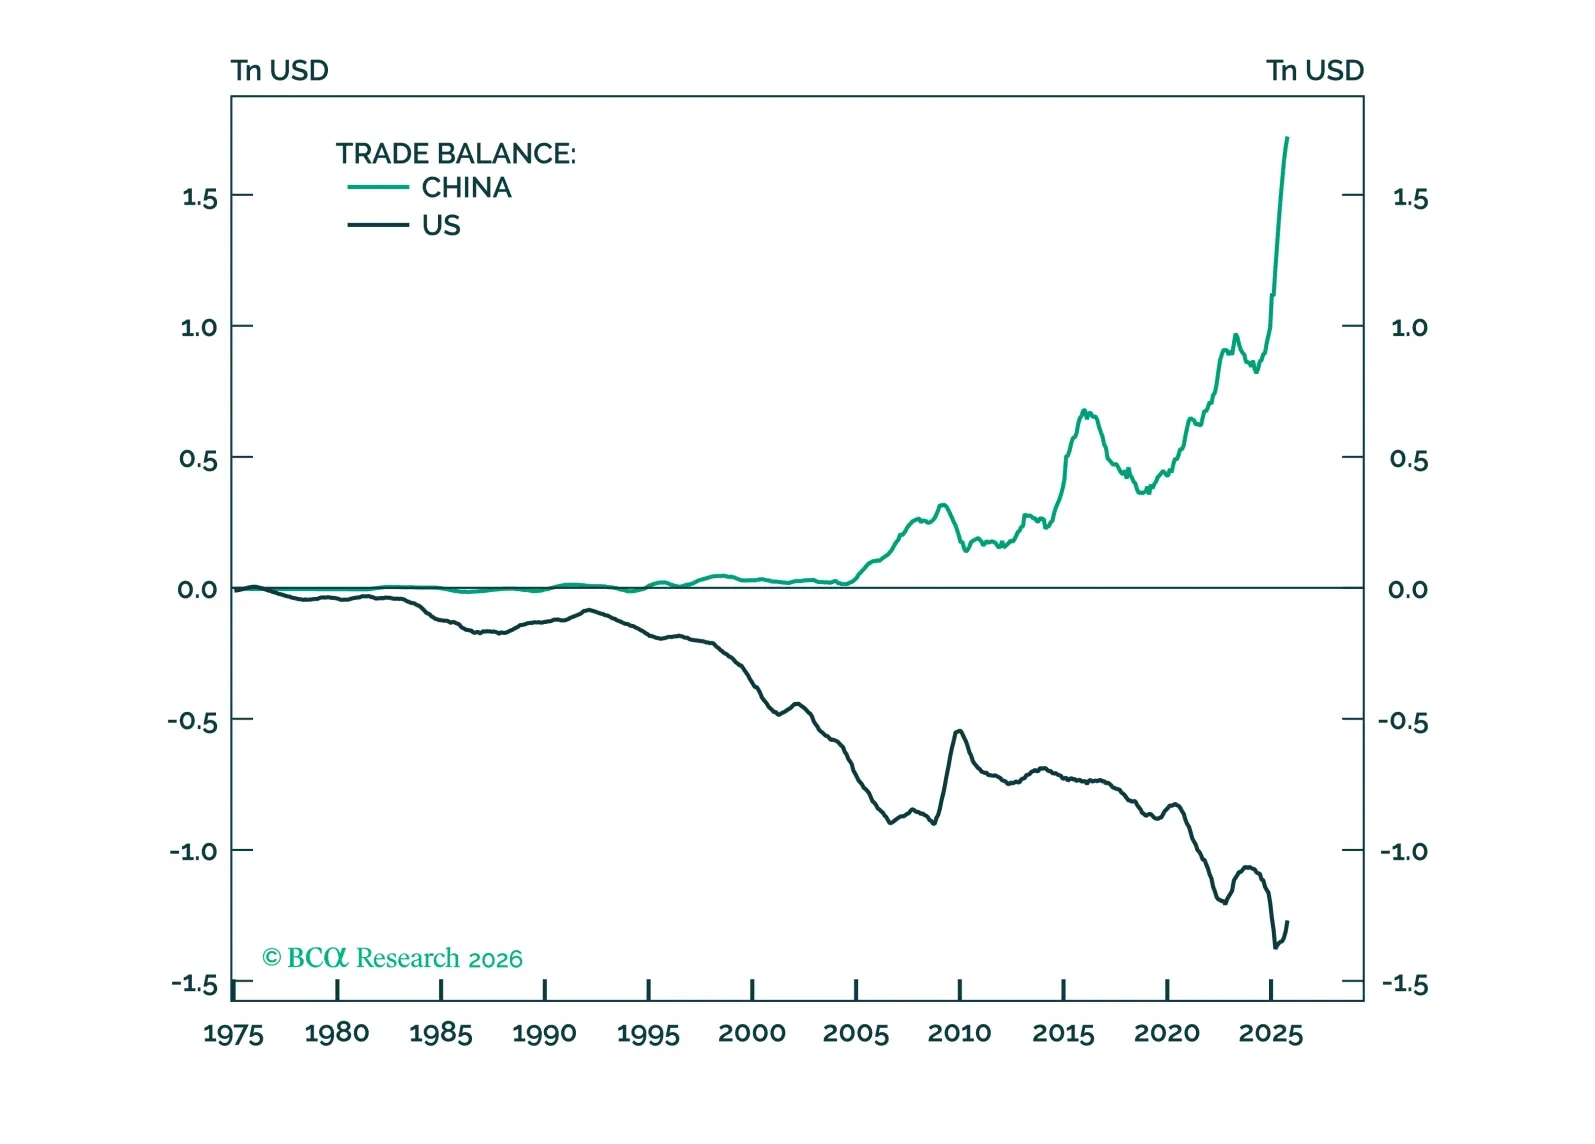
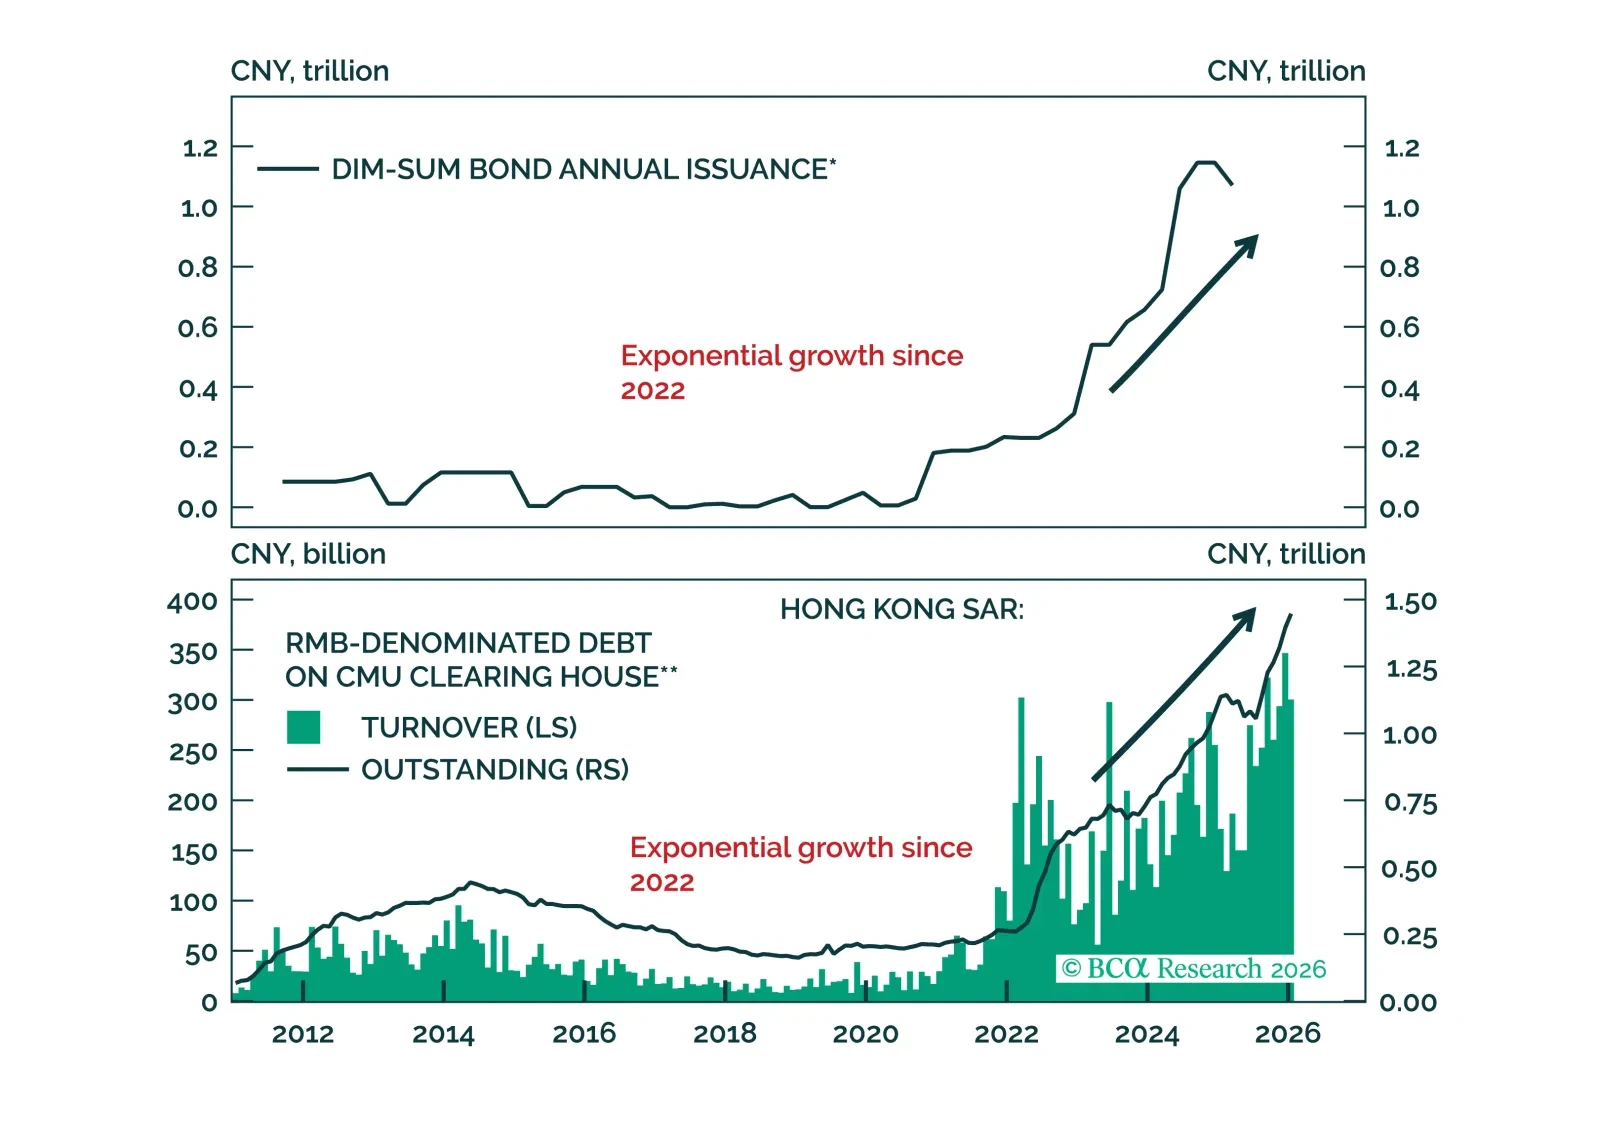
The CNY is undervalued and highly competitive. This gives China room to let the currency appreciate while remaining an export-driven powerhouse, gradually shifting from export intensity toward stronger domestic consumption. This achieves two objectives. First, it narrows the capital account deficit and strengthens the CNY’s role as a global anchor. Second, it enhances Beijing’s geopolitical autonomy by reducing reliance on foreign final demand.
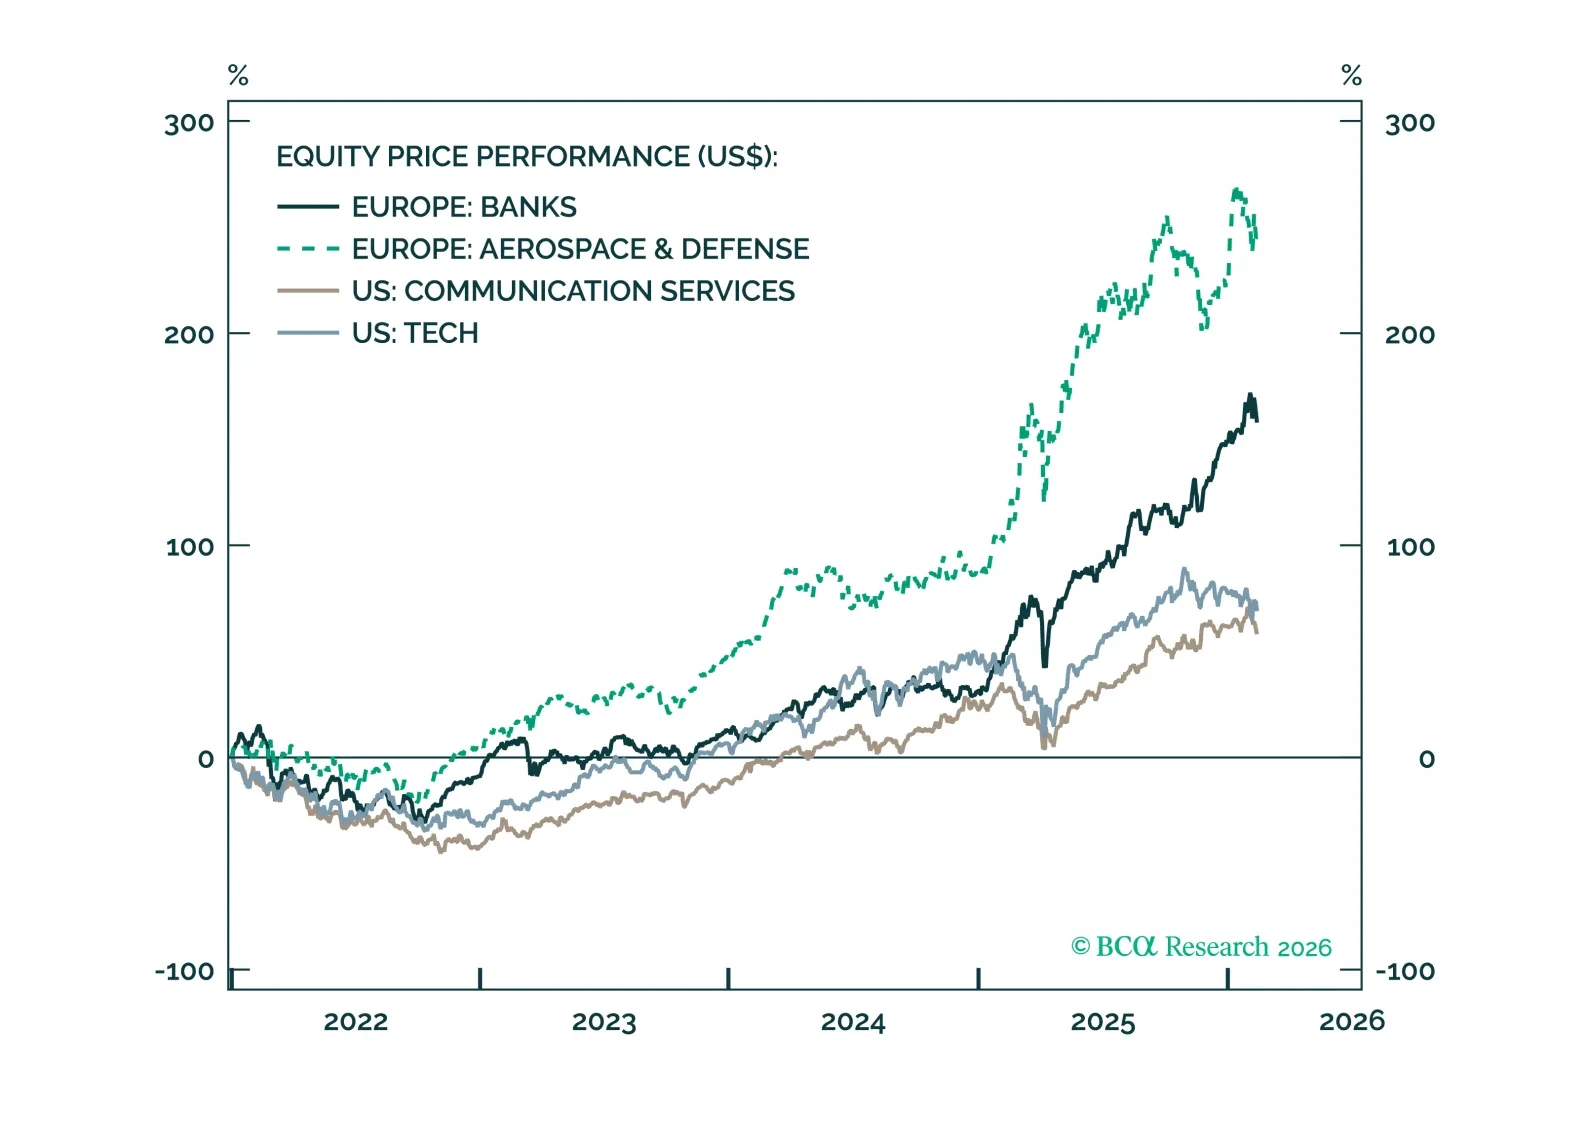
The near-term outlook is less supportive for European banks and defense equities. We downgrade banks to neutral and continue to expect defense stocks to trade in a “sell the rumor, buy the news” pattern.