Latest from BCA Research
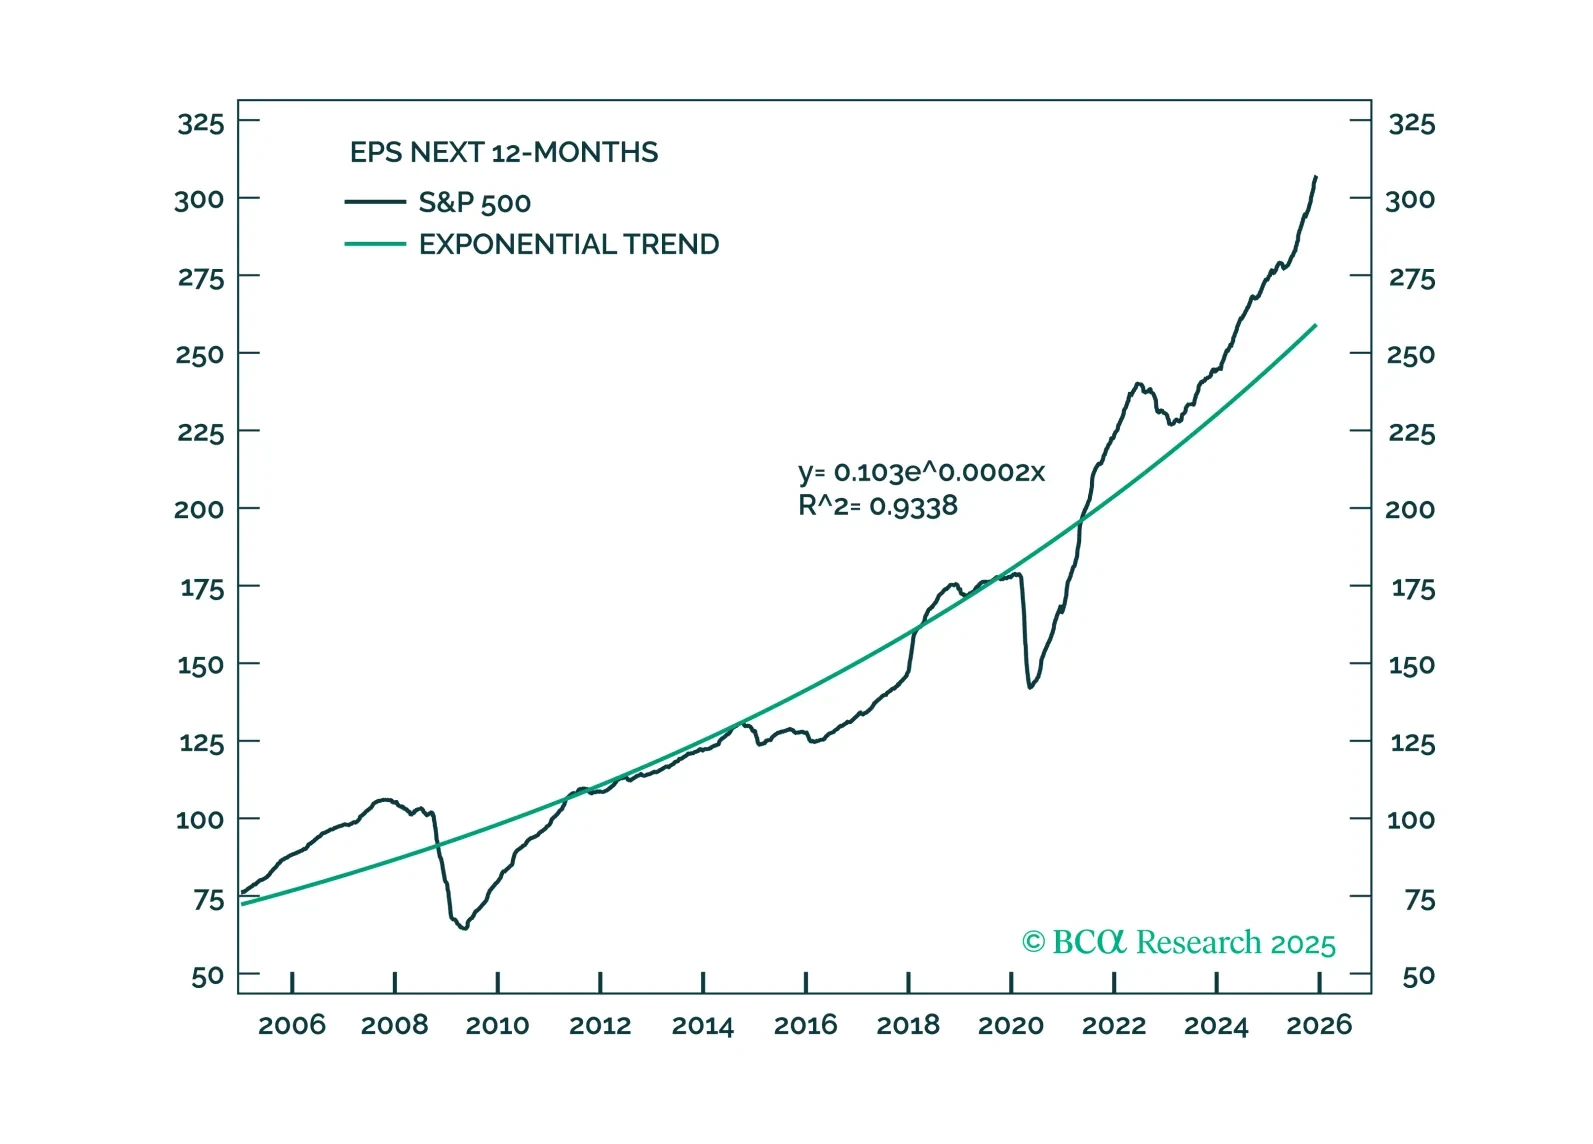
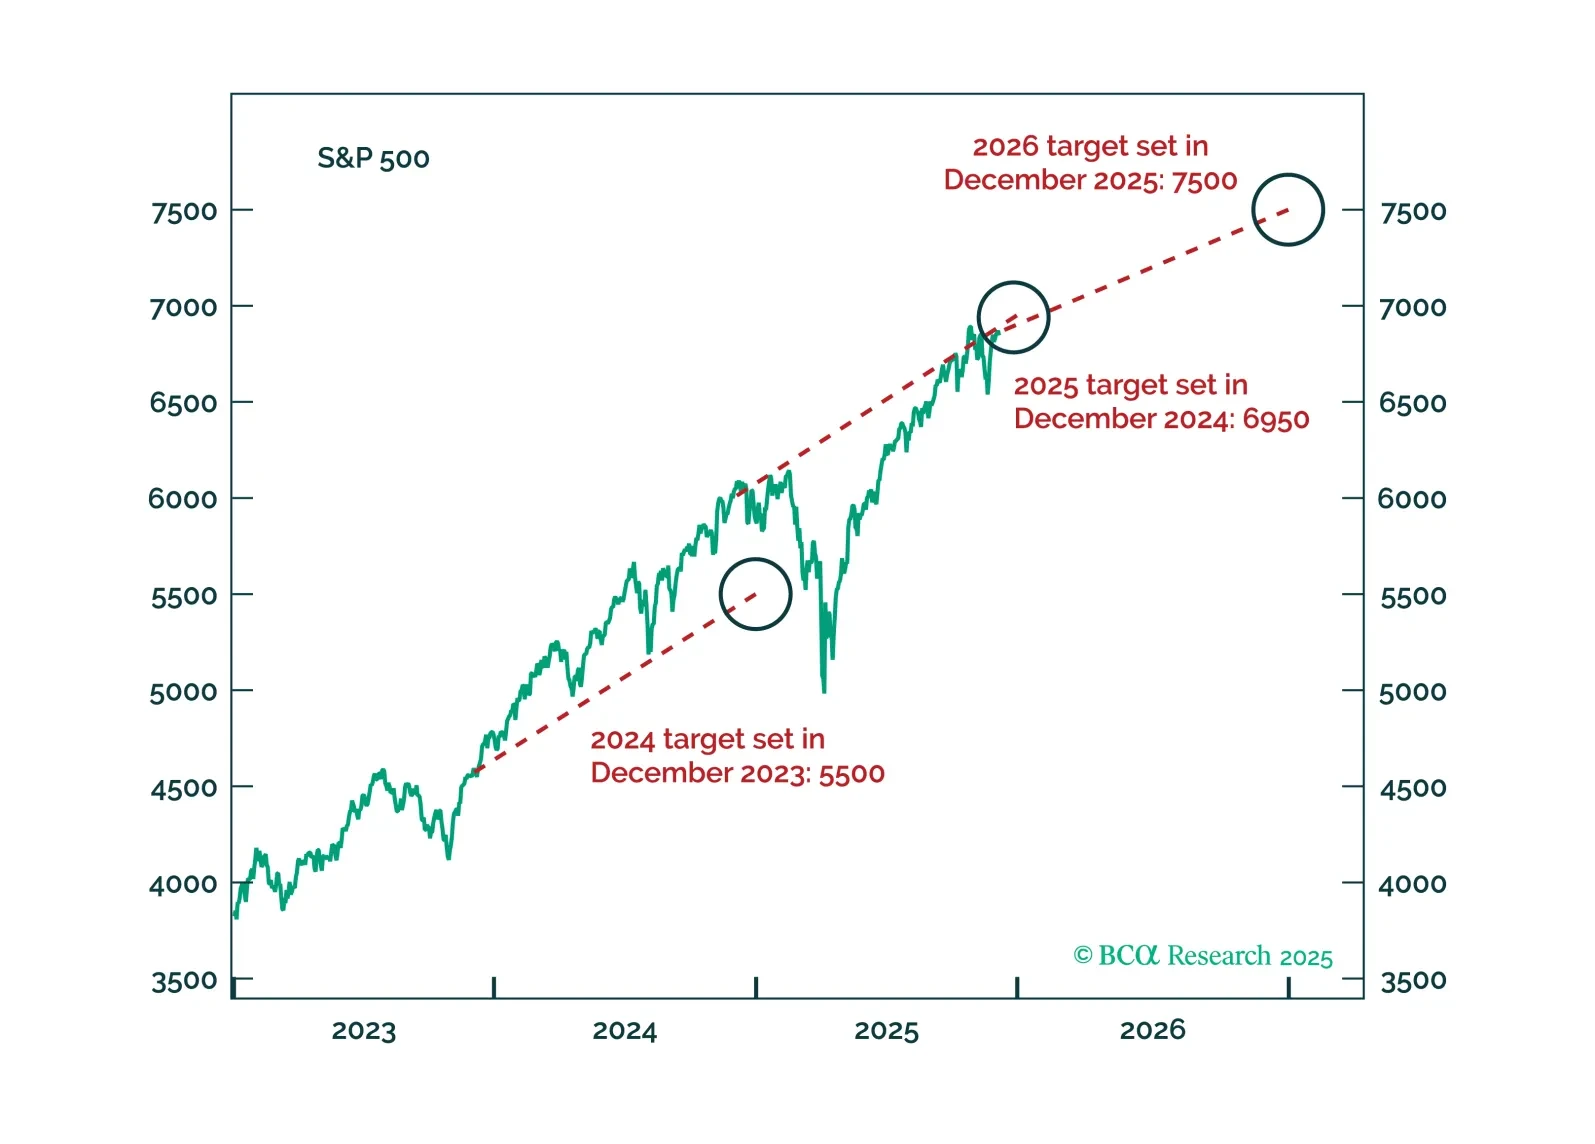
We had a good year in 2025. For two years now, we have been unabashedly bullish, proving that the GeoMacro framework works.
Washington’s new strategy sheds liberal idealism for hard-edged multipolar realism: spheres of influence accepted, allies chided, Asia red lines firm, Latin America elevated, and AI-plus-digital assets crowned as national-security sinews. The result is a world steadied by US offshore balancing – an unexpectedly bullish backdrop for emerging markets in the years ahead.
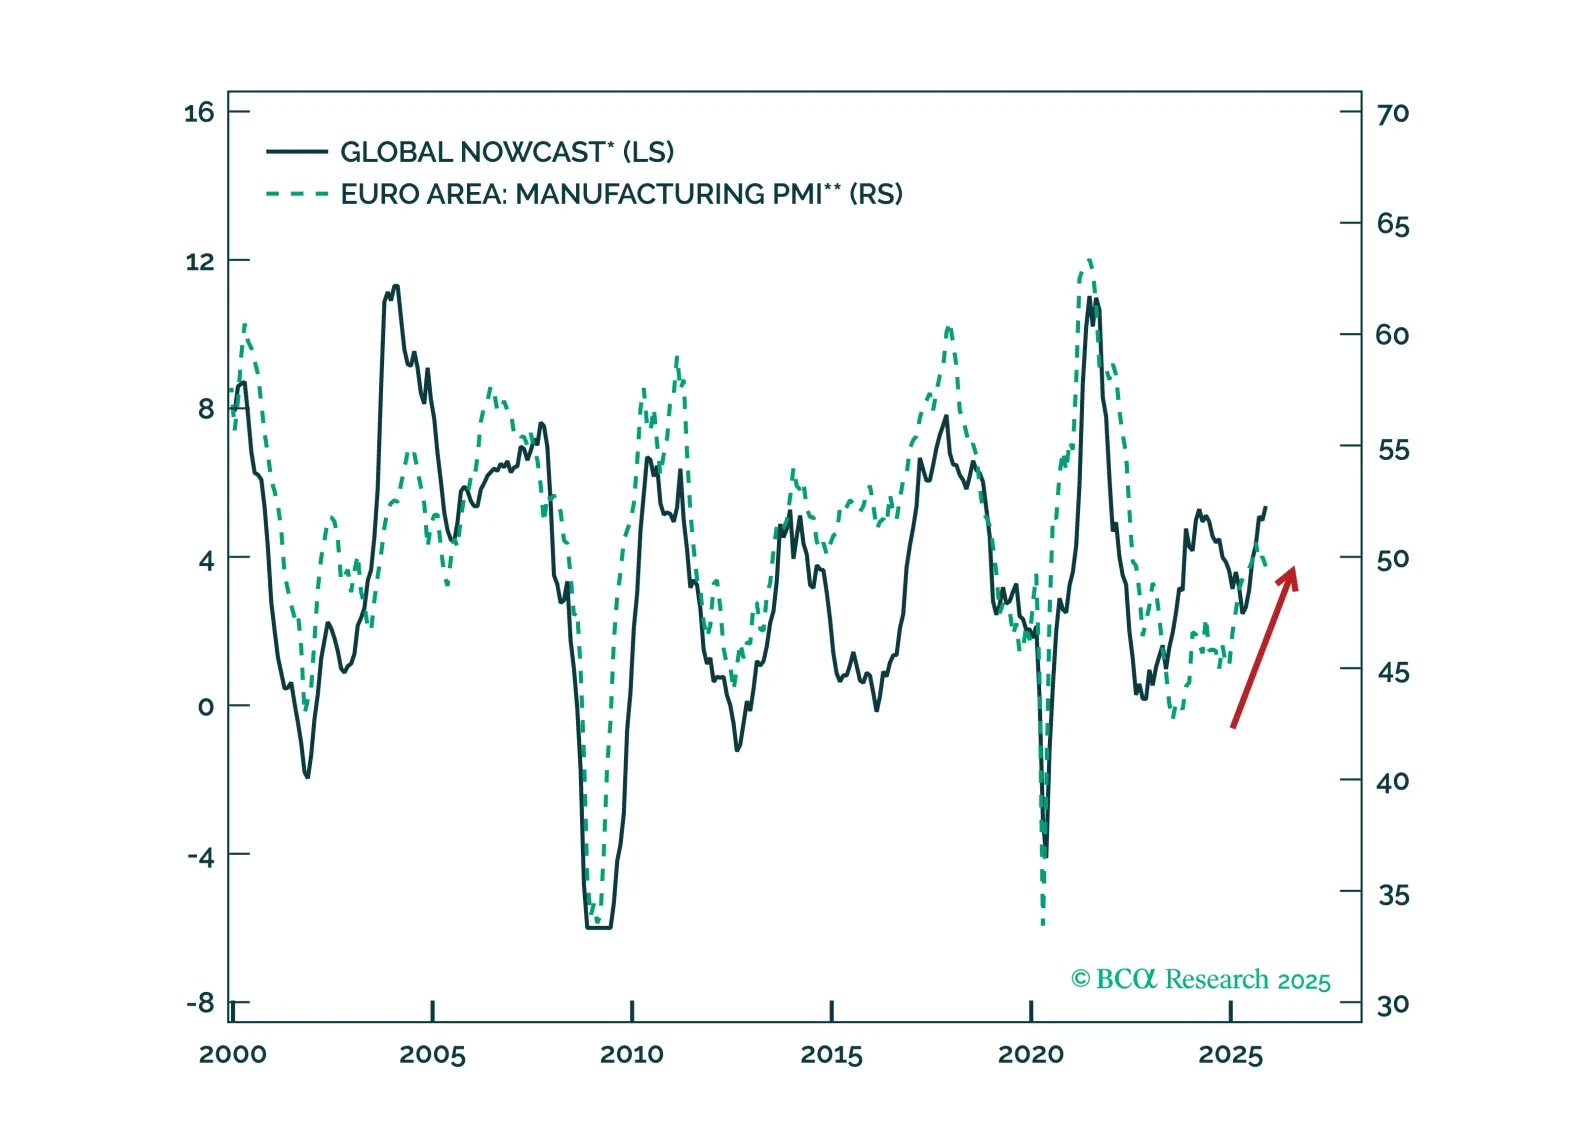
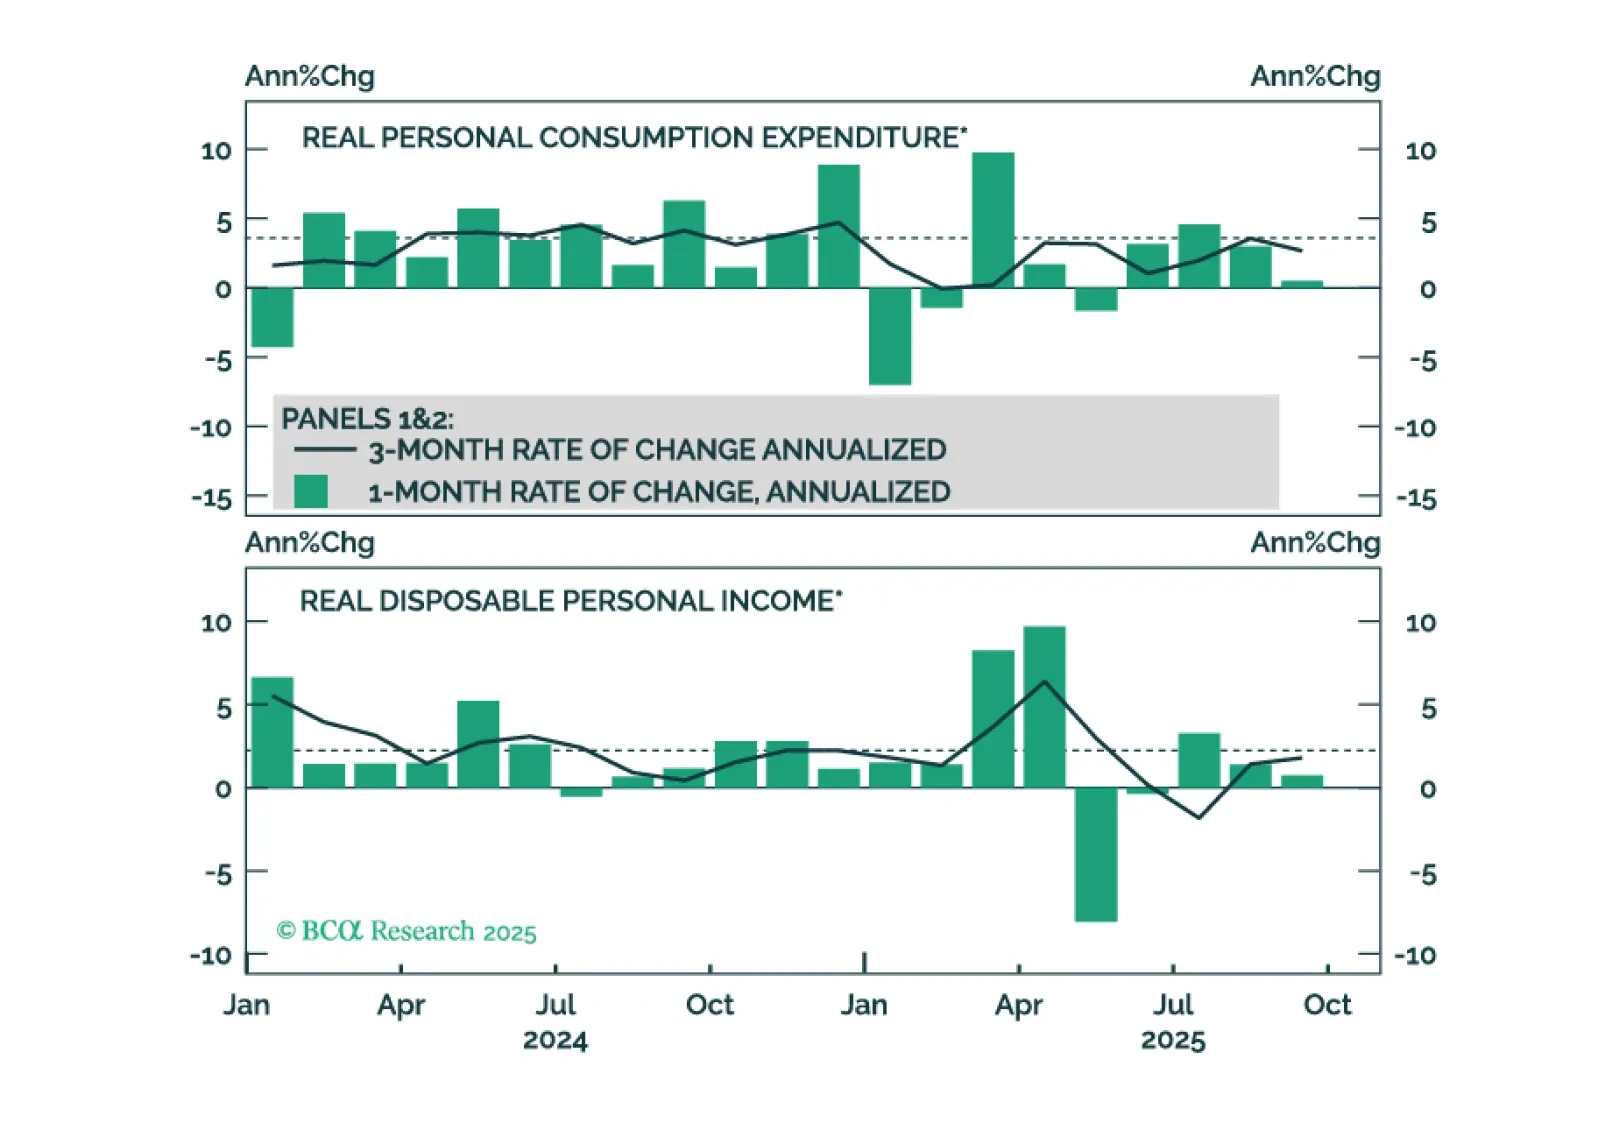
September’s weak consumer spending data challenge the K-shaped recovery narrative and suggest that spending will slow to match already-weak employment growth.
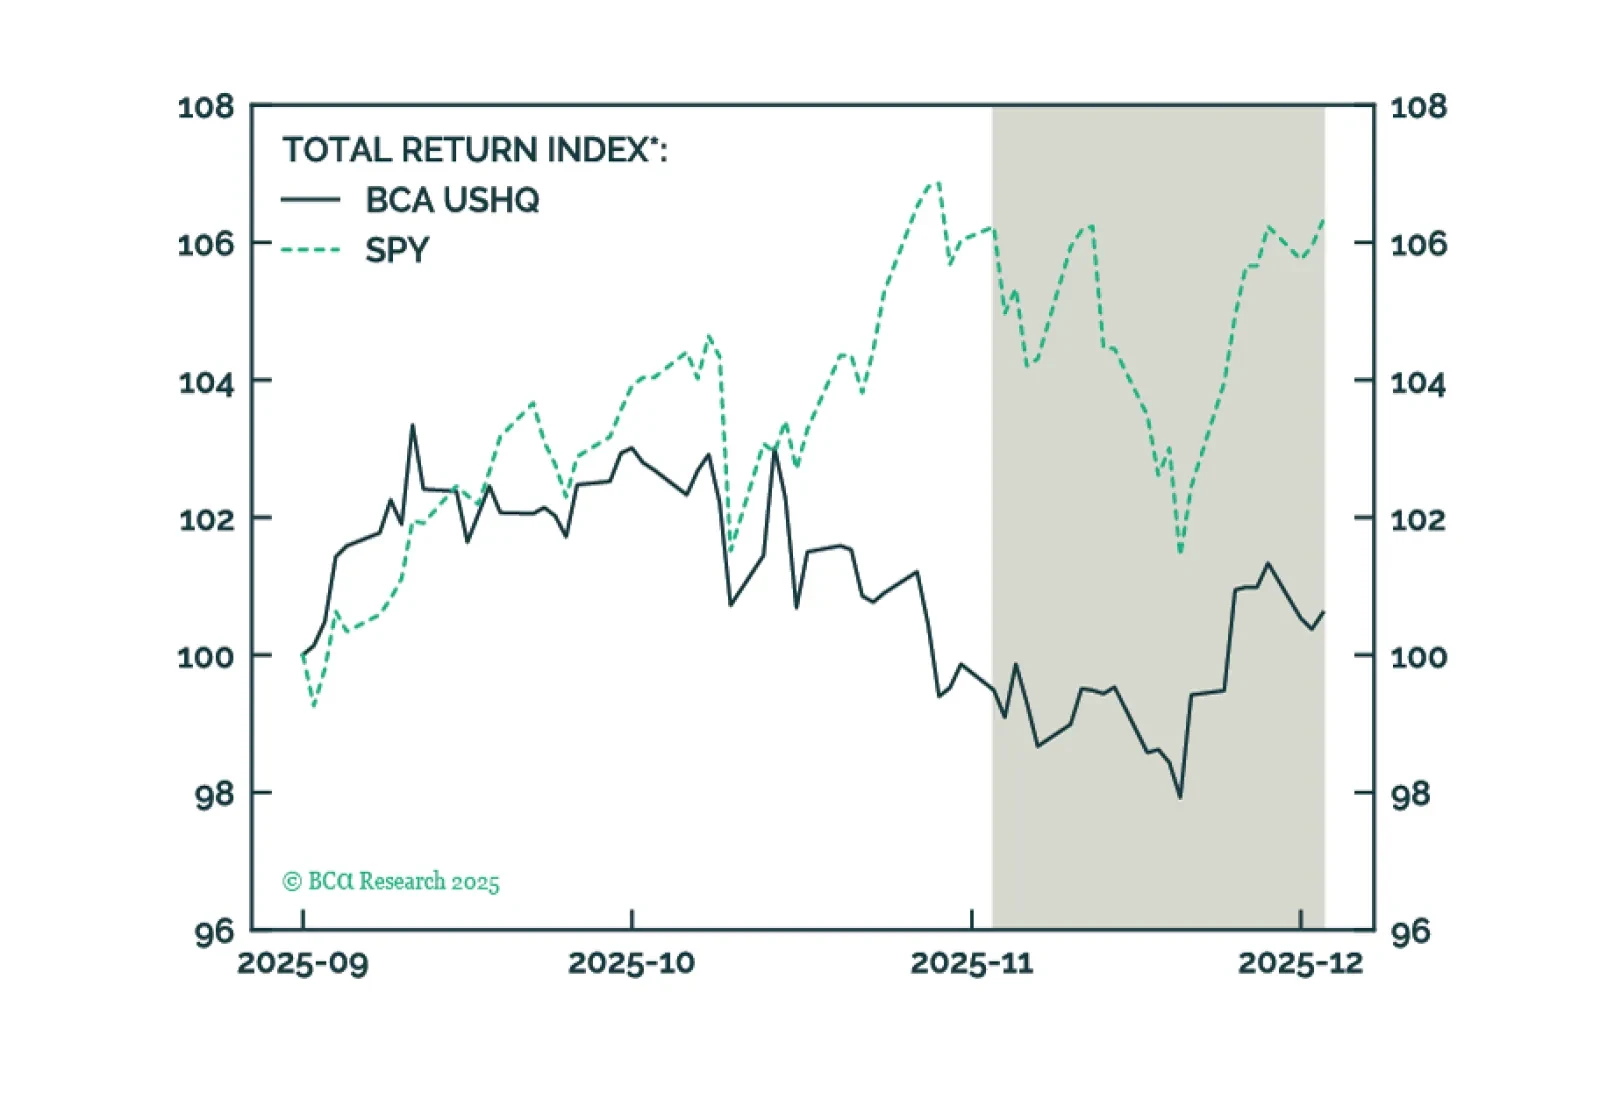
The US High Quality portfolio outperformed its benchmark through November, returning 1.13%, whilst its SPY benchmark returned 0.08%. Our US High Quality SMID portfolio experienced a decline in performance this month. The portfolio returned -2.27%, underperforming its MSCI US Small and Mid Cap benchmark by 357bps.
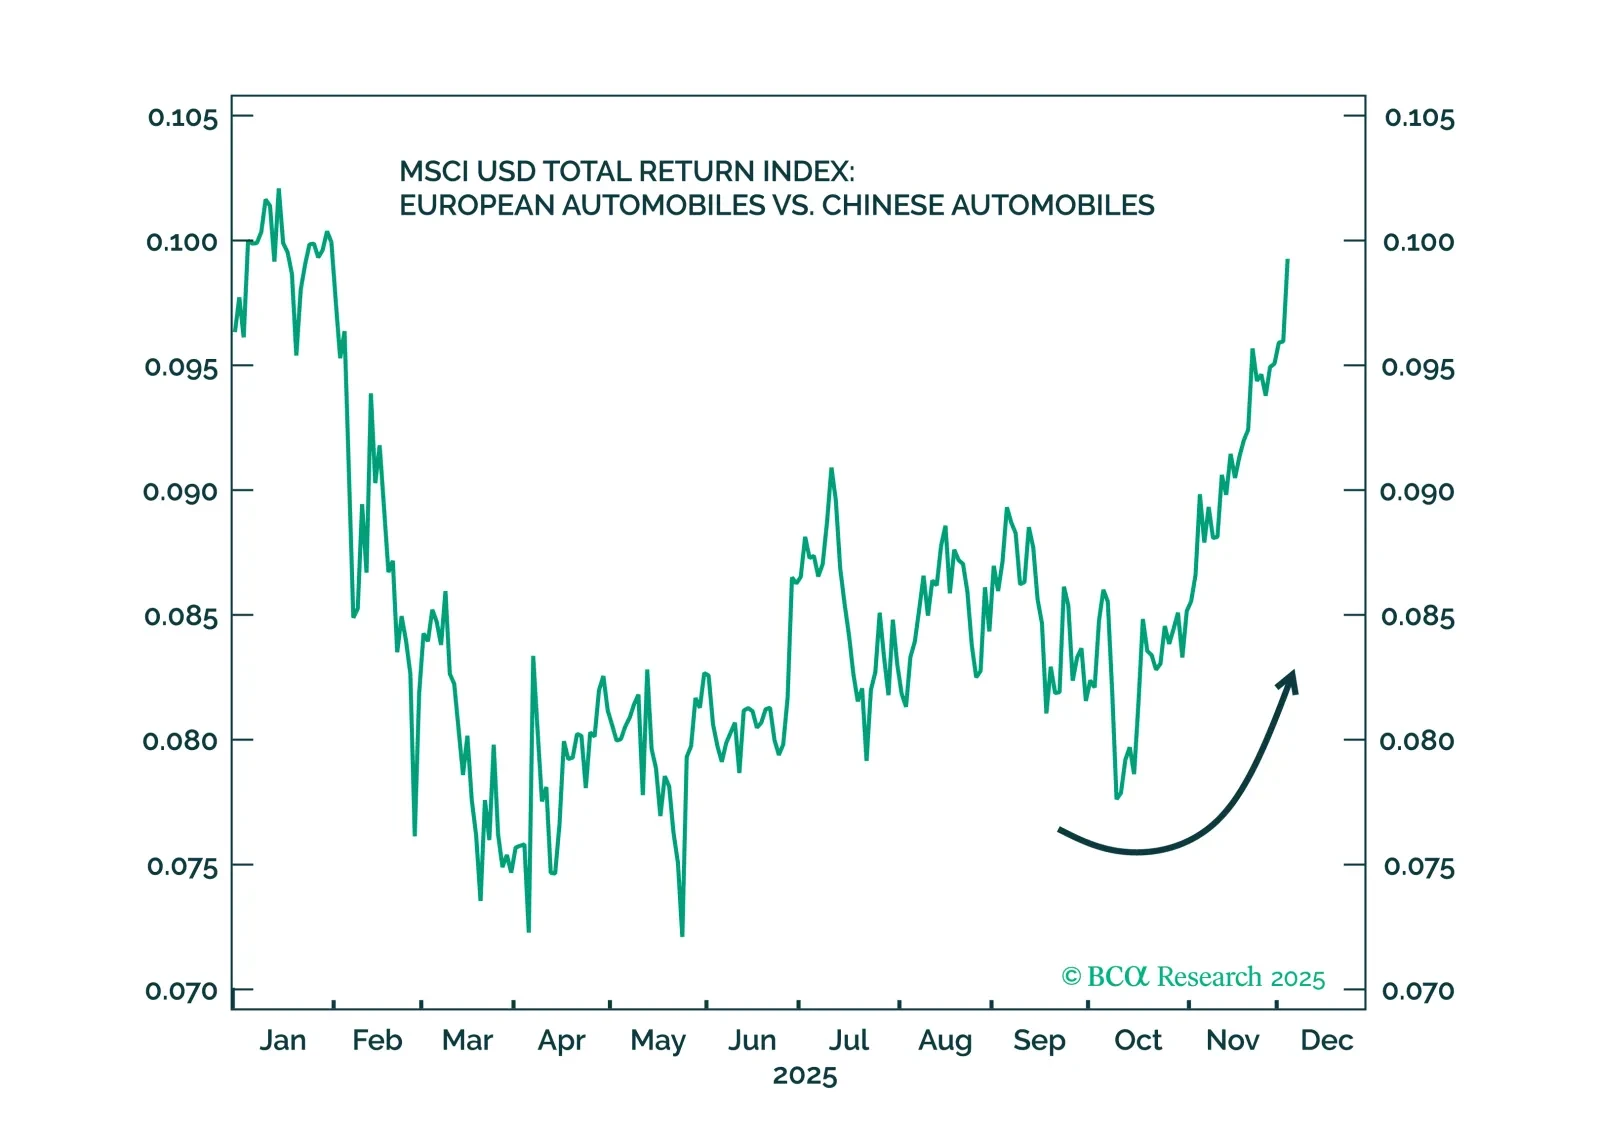
We got Trump's tariff shock and backtracking correct and predicted Israel's attack on Iran. But we missed the China rally — and there is still no Ukraine ceasefire.
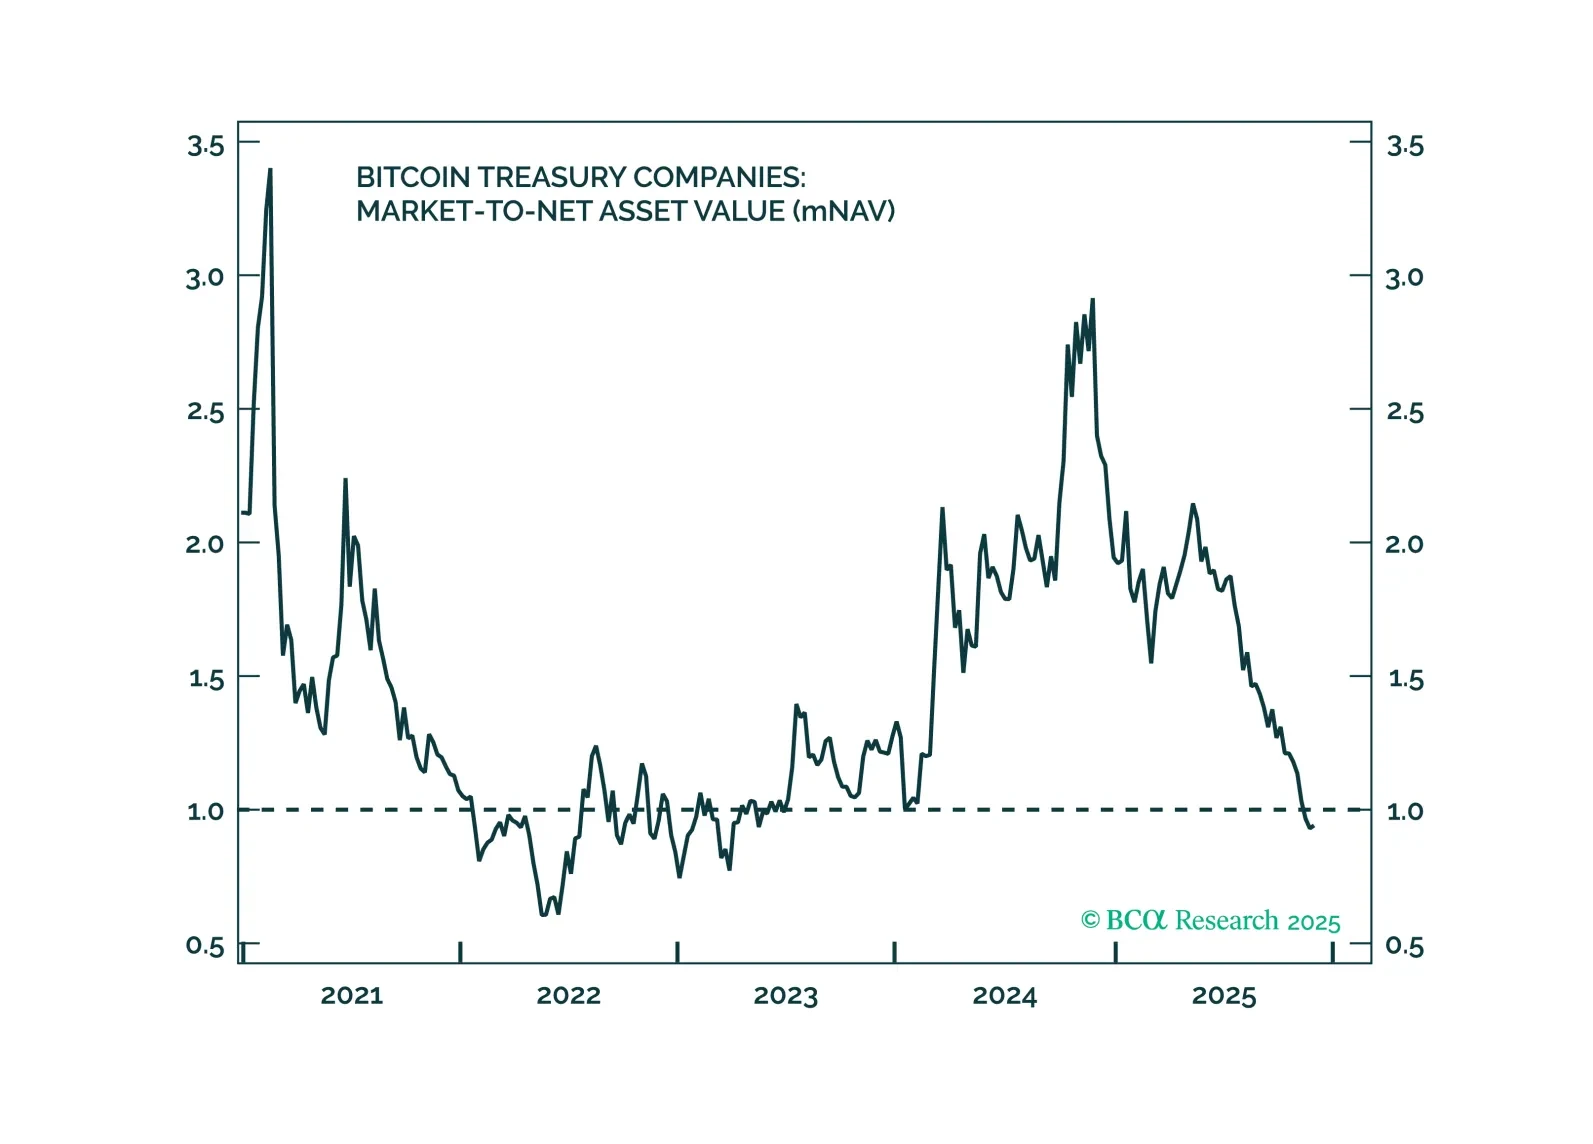
Bitcoin’s recent volatility masks a deeper story – the widest disconnect from traditional macro drivers since 2022. With sentiment now deeply negative and institutional demand still building, the conditions for a realignment with fundamentals are falling into place.