Latest from BCA Research
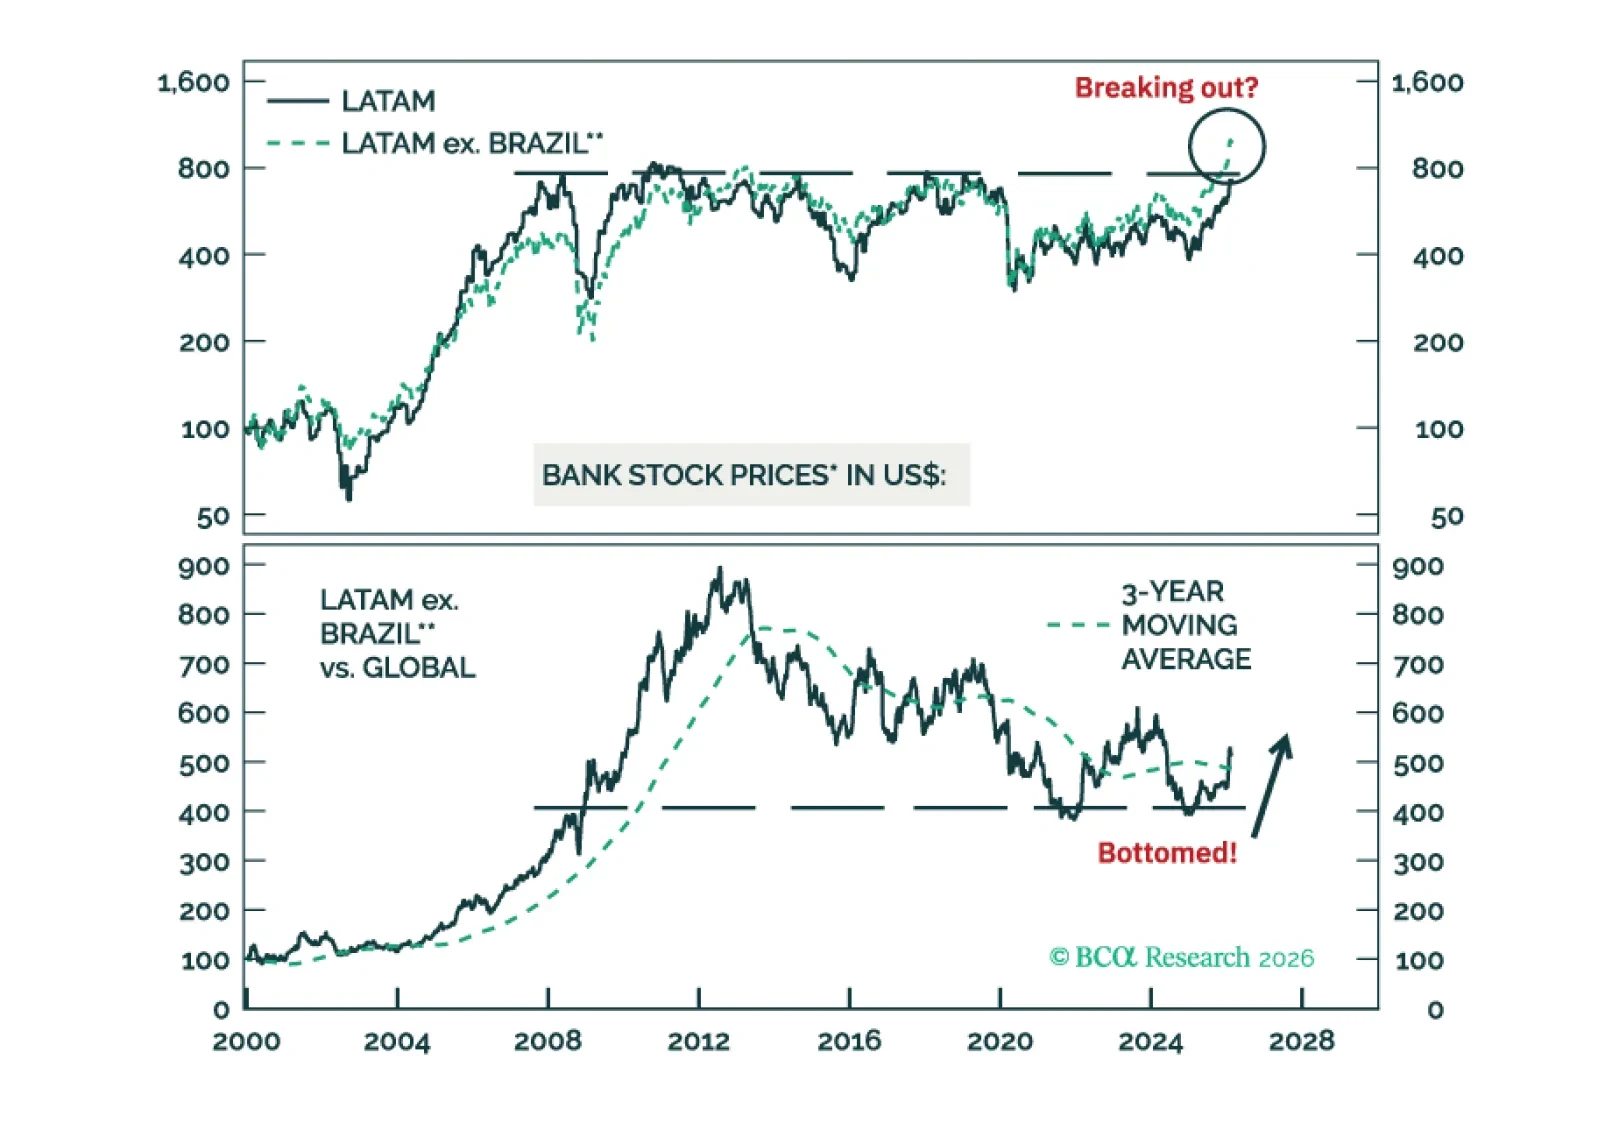
Go long LATAM ex. Brazil banks / short global bank stocks. Brazilian bank equities will underperform due to poor and worsening macro fundamentals.
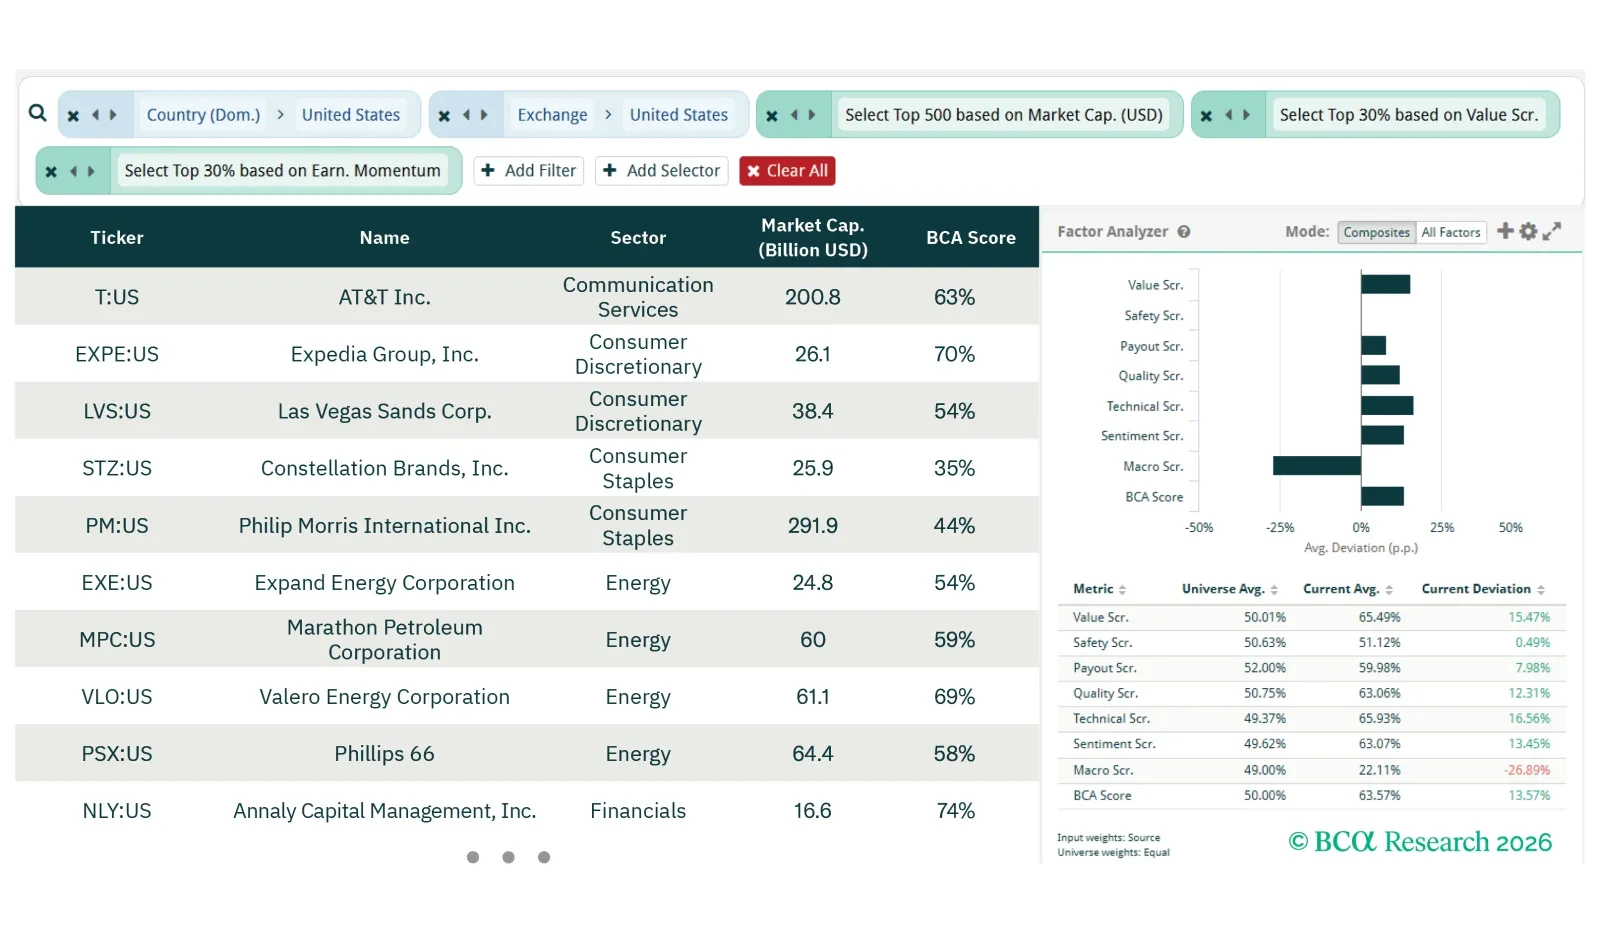
For this screener report, we explore opportunities in laggards with earnings momentum, Japanese semiconductors and US rate-sensitive stocks.
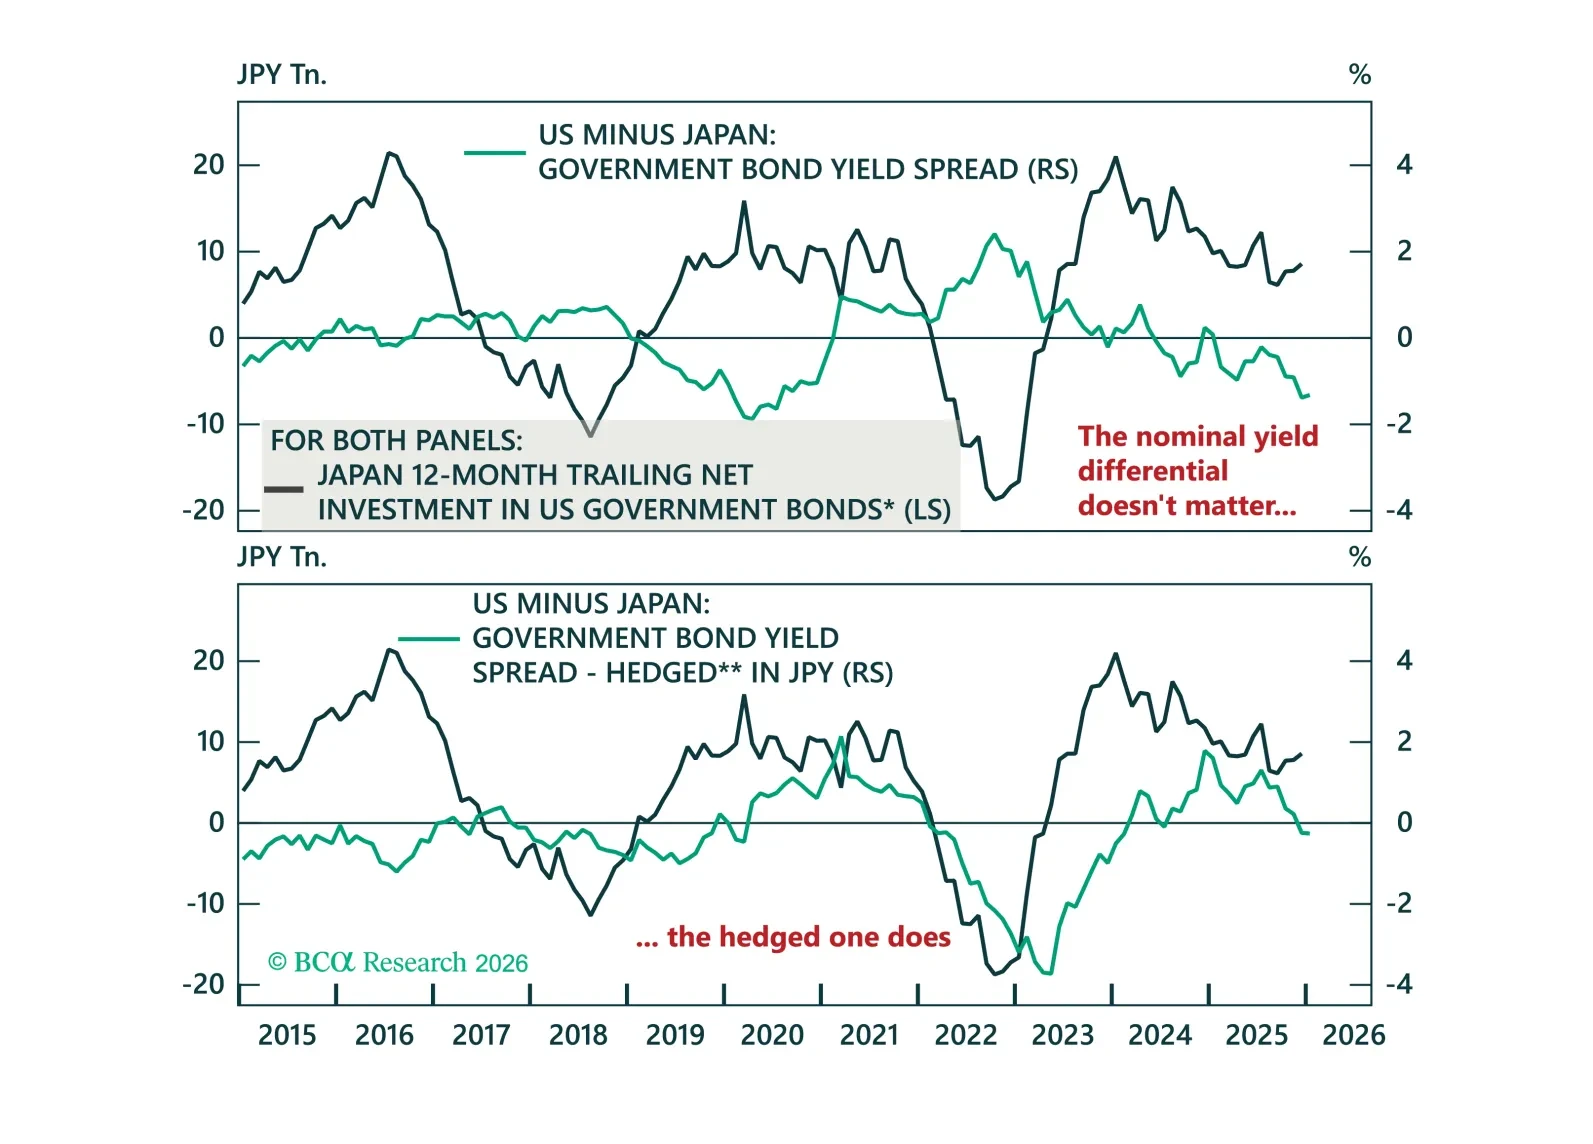
We spent last week meeting investors in Switzerland. This Strategy Insight revisits the most prominent topics we discussed, including repatriation fears, SNB intervention, and Dutch pension reform.
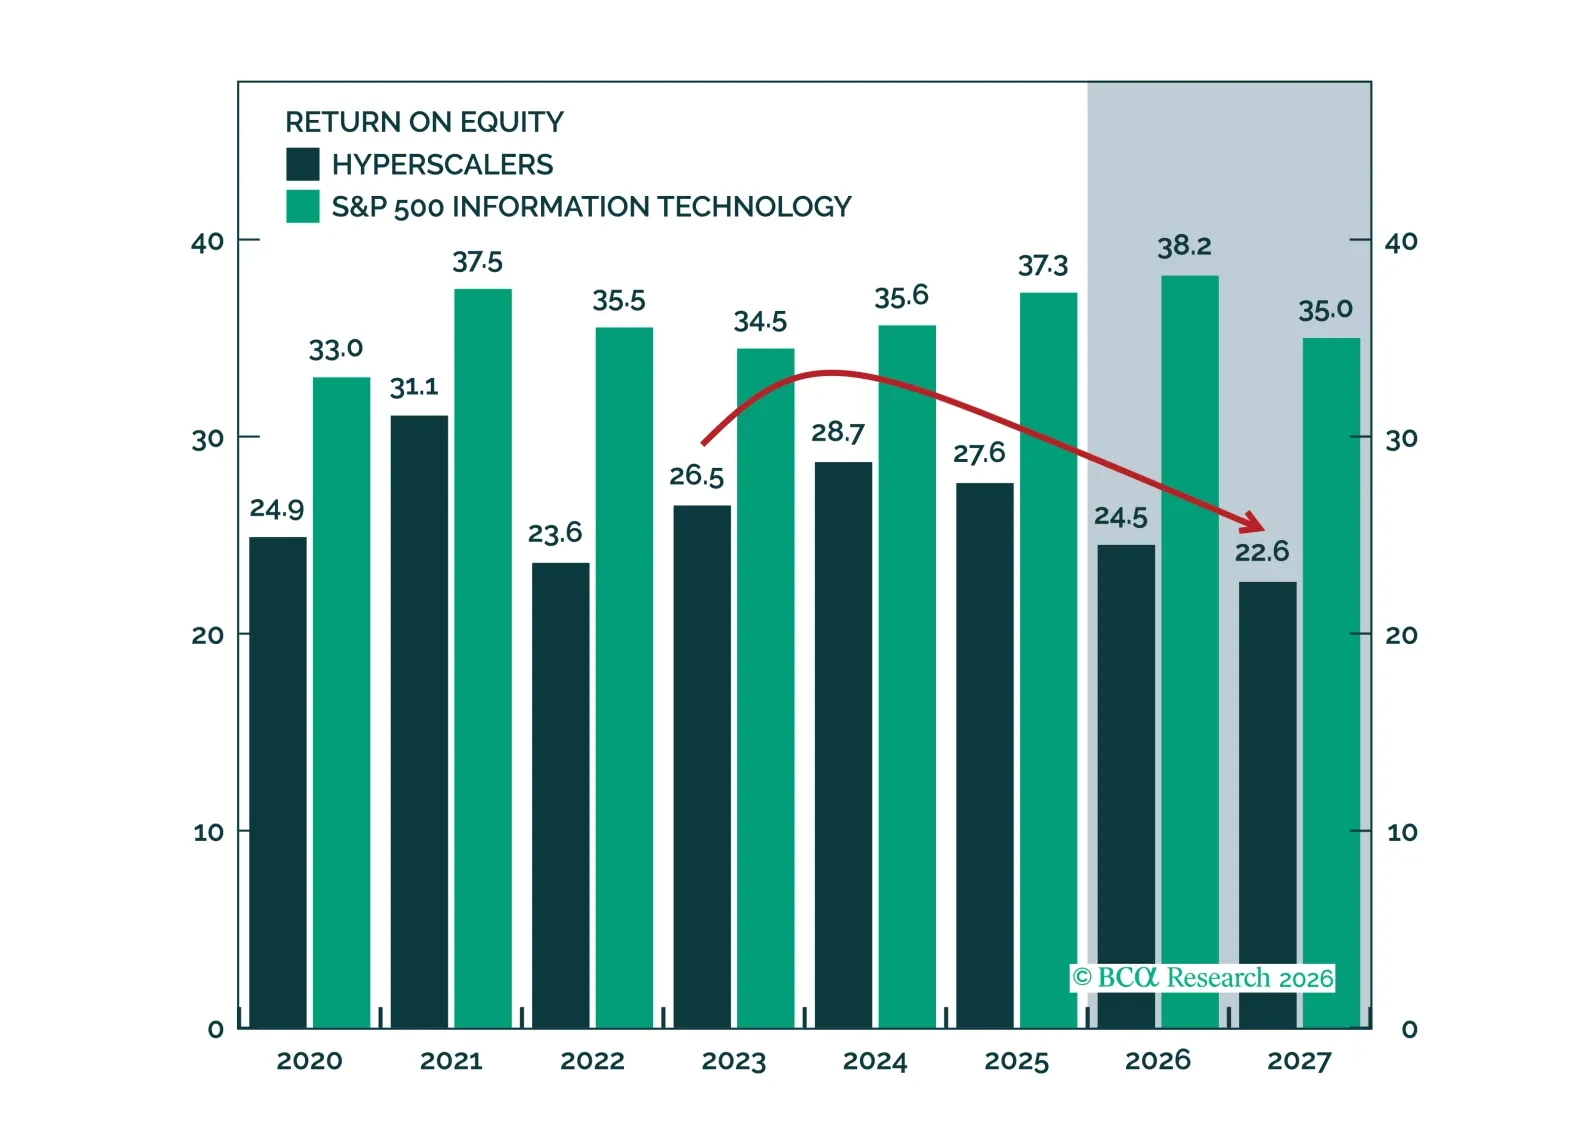
The capex debate is better framed not as boom versus bubble, but as around capacity, leverage, and cash conversion. ROEs have compressed, but revenue growth and margin expansion offer a credible path back. Spenders likely have time to make good on their investments, though the market’s leash may be shorter than anticipated.
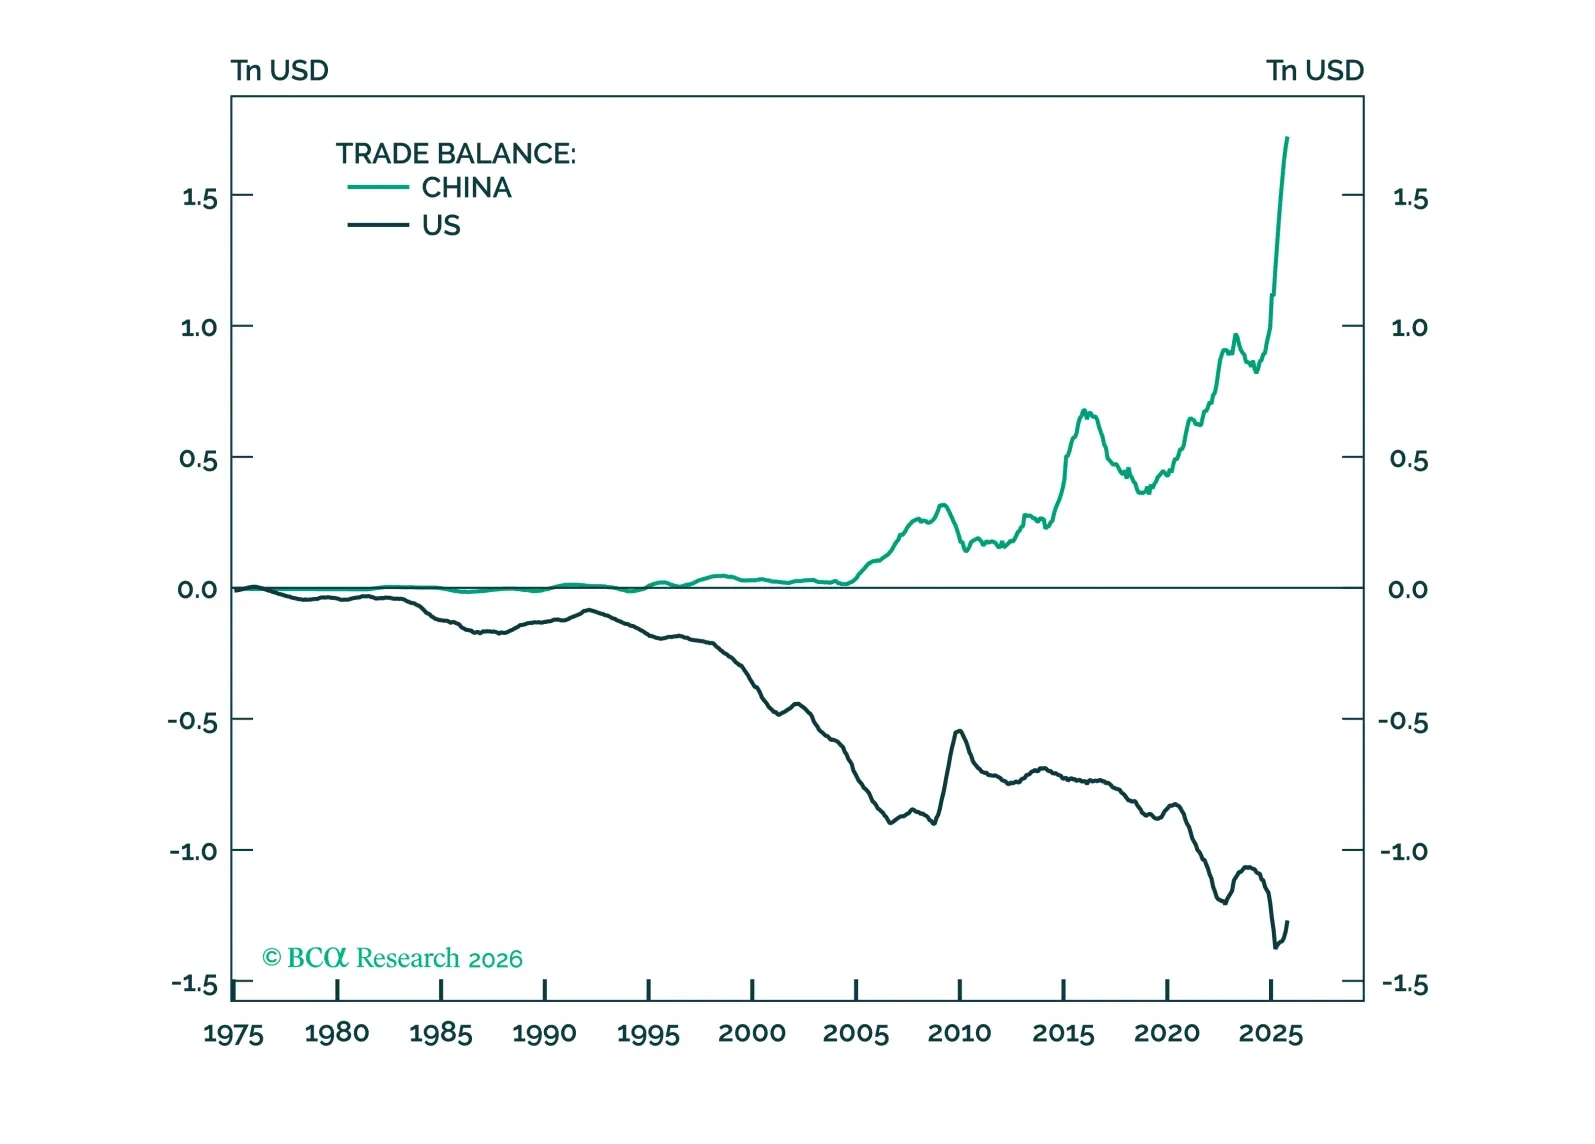
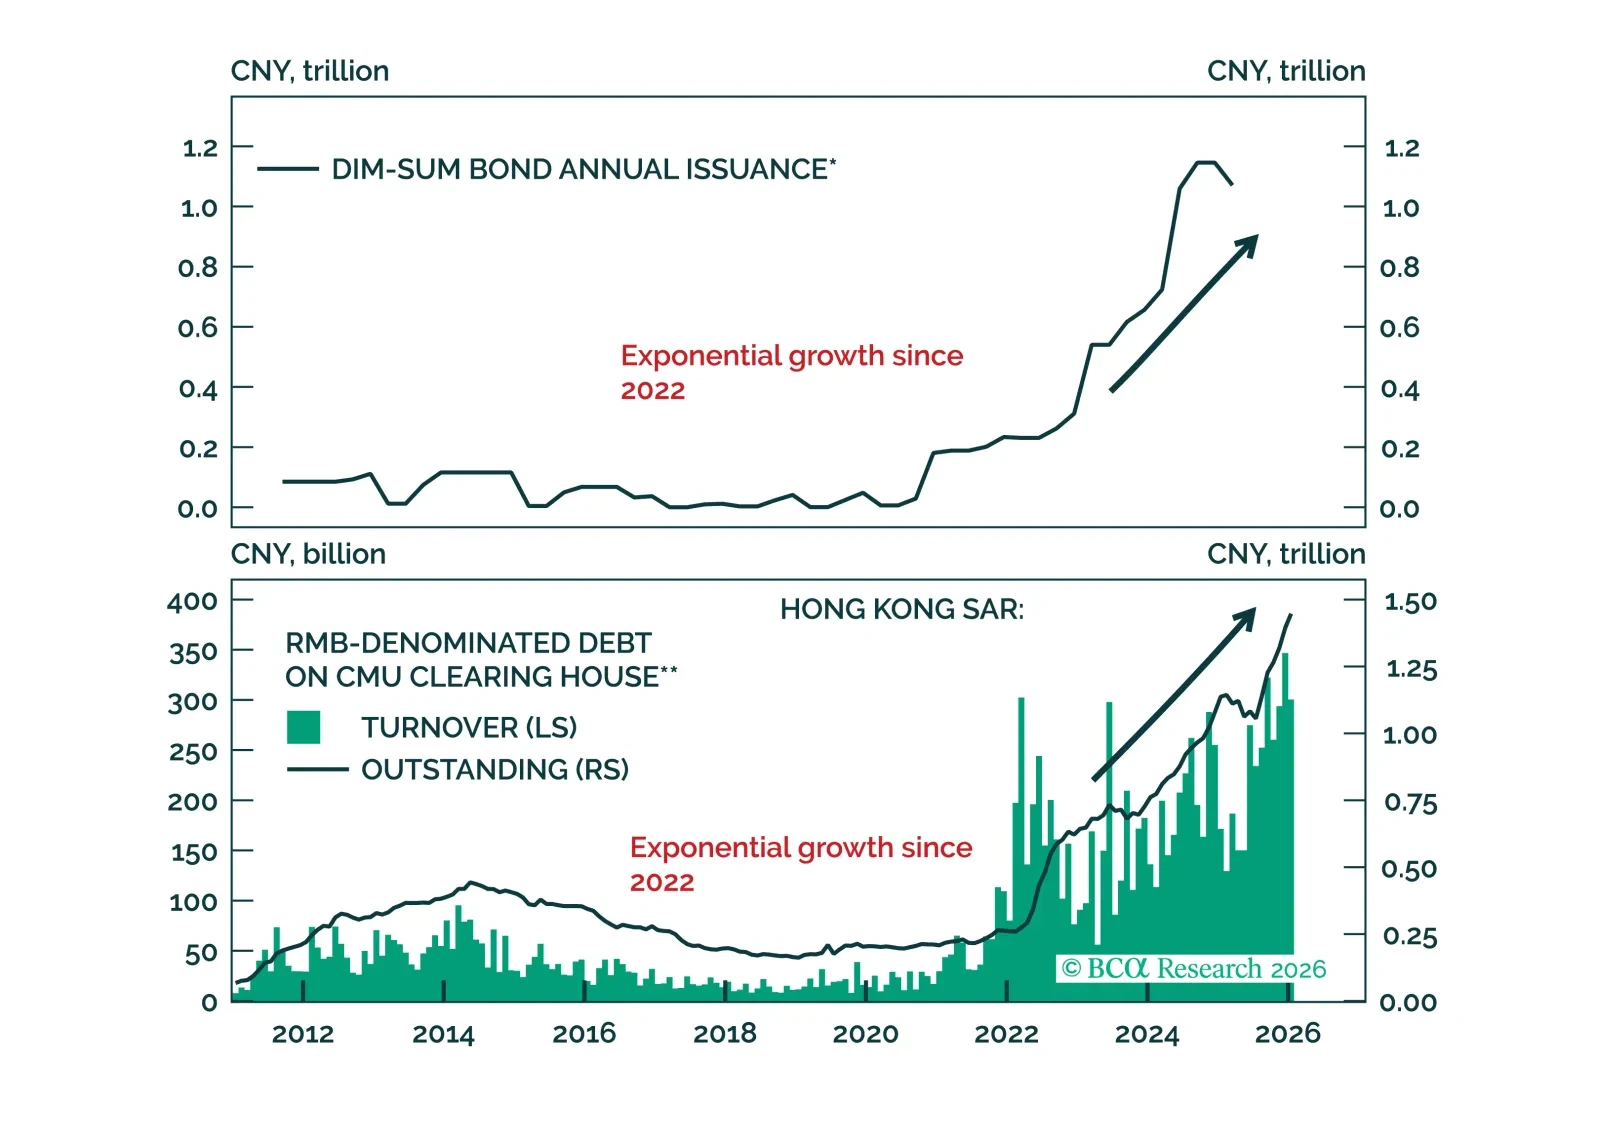
The CNY is undervalued and highly competitive. This gives China room to let the currency appreciate while remaining an export-driven powerhouse, gradually shifting from export intensity toward stronger domestic consumption. This achieves two objectives. First, it narrows the capital account deficit and strengthens the CNY’s role as a global anchor. Second, it enhances Beijing’s geopolitical autonomy by reducing reliance on foreign final demand.
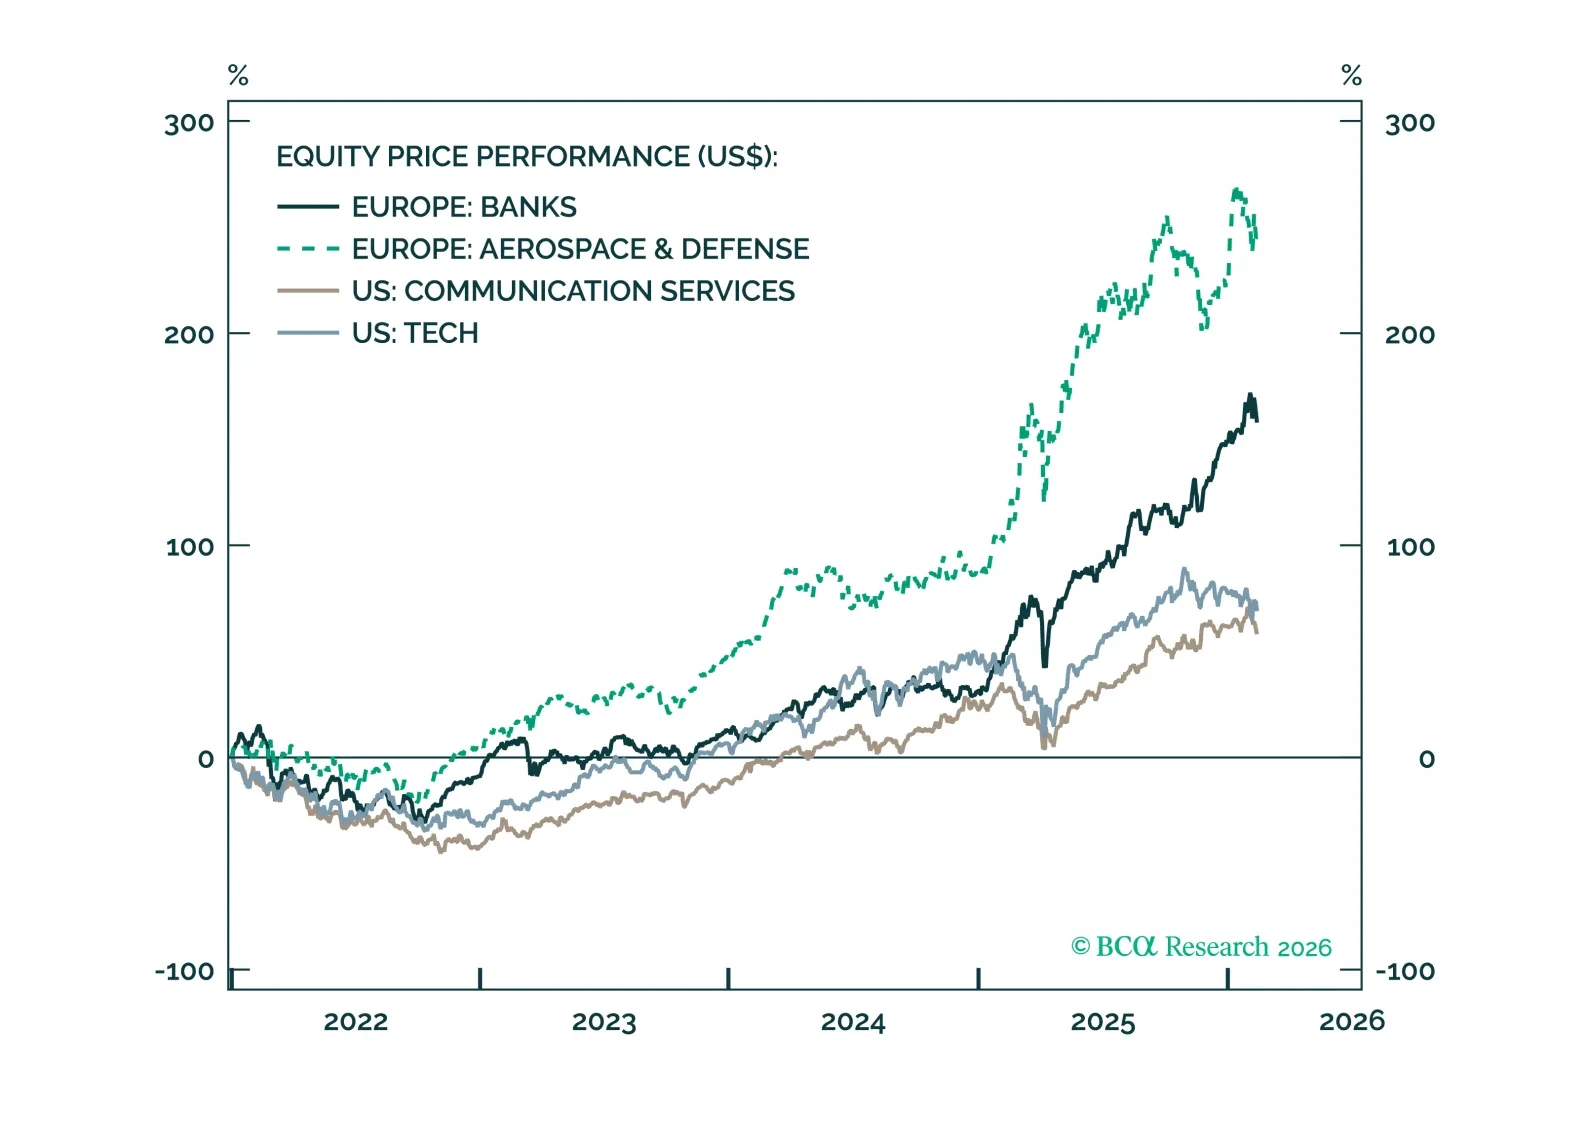
The near-term outlook is less supportive for European banks and defense equities. We downgrade banks to neutral and continue to expect defense stocks to trade in a “sell the rumor, buy the news” pattern.
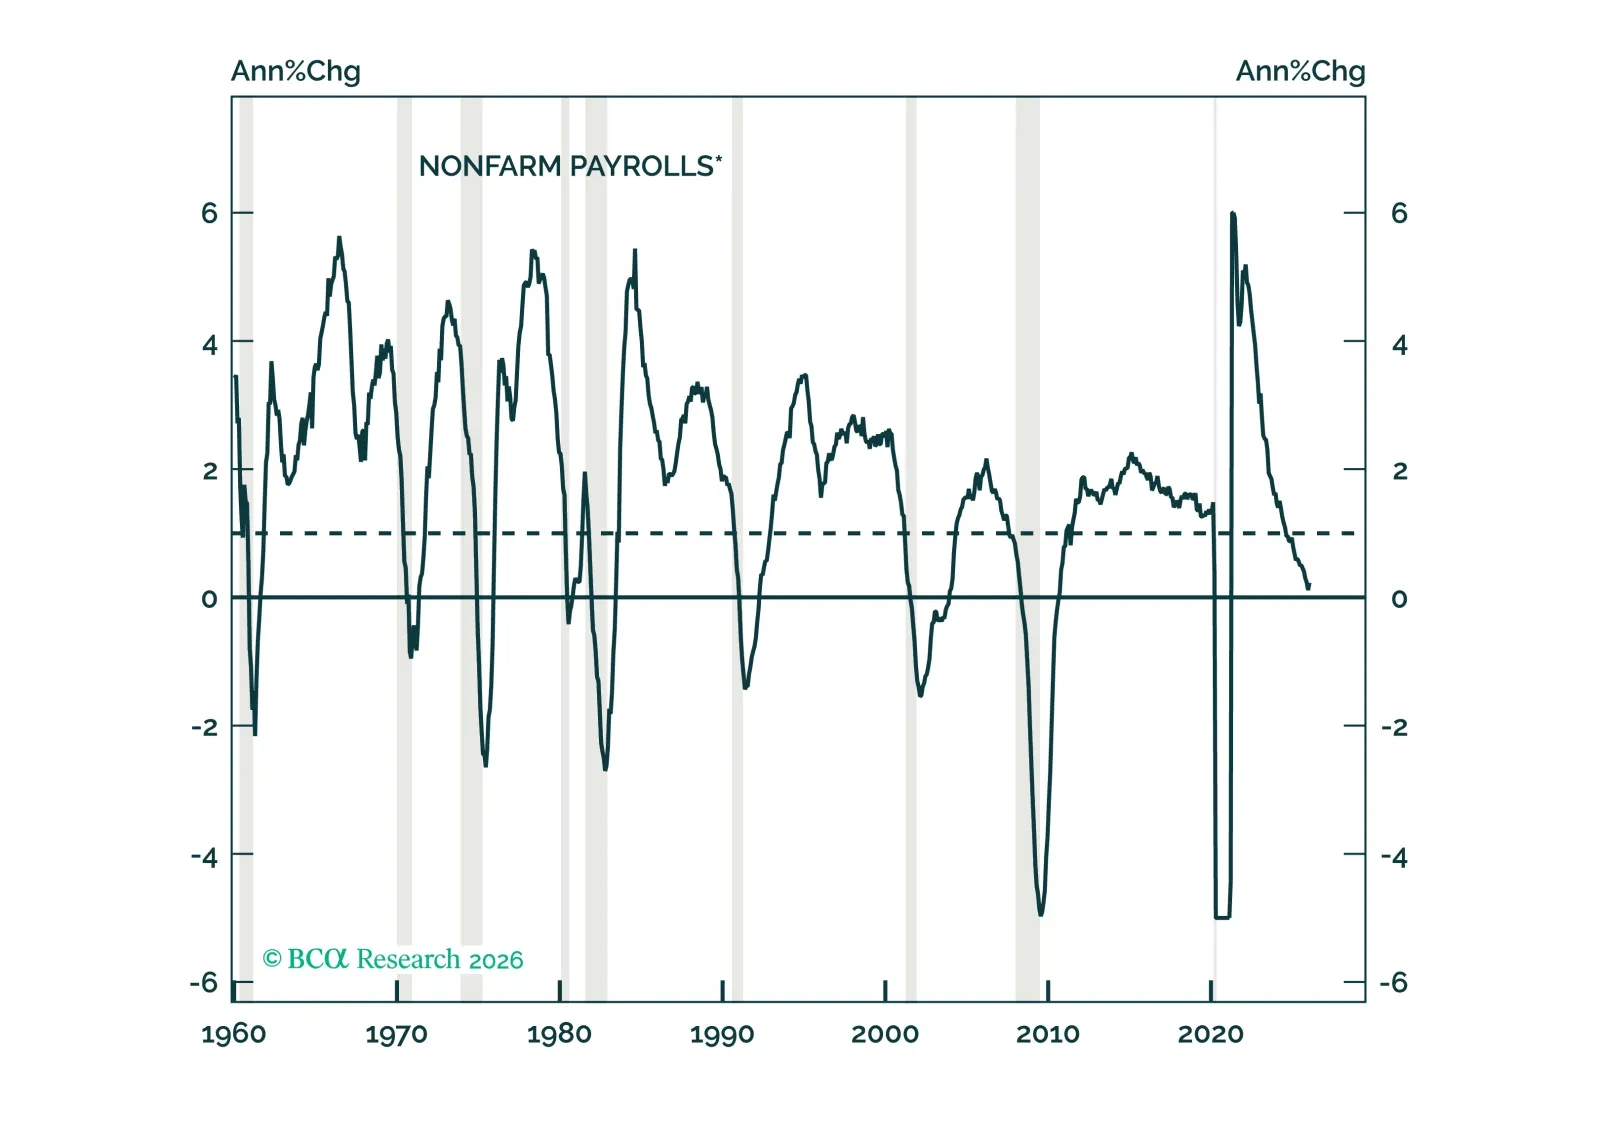
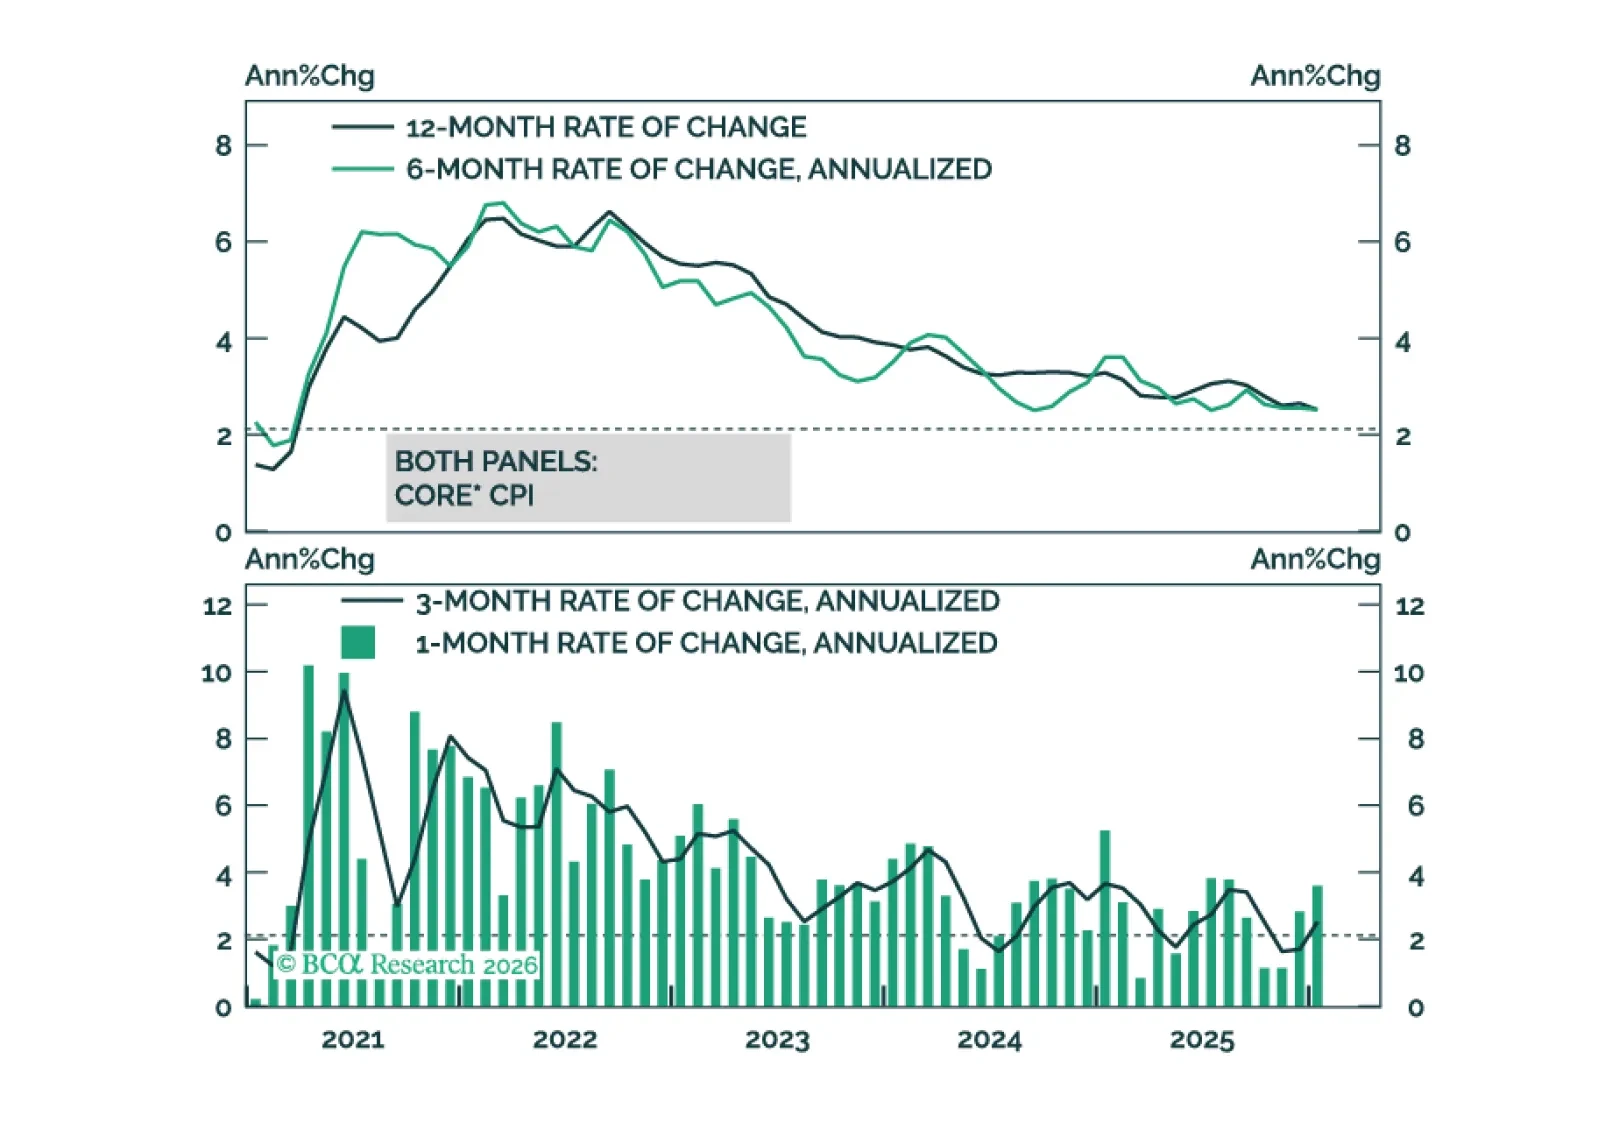
The annual benchmark payrolls revisions revealed that the labor market has been weaker for longer than initially reported. The probability that a crack in consumption is just around the corner is much reduced and we have therefore dialed back our recession expectations. Though our asset allocation recommendations remain neutral across the board, we are more optimistic than we were at the beginning of the year.