Latest from BCA Research
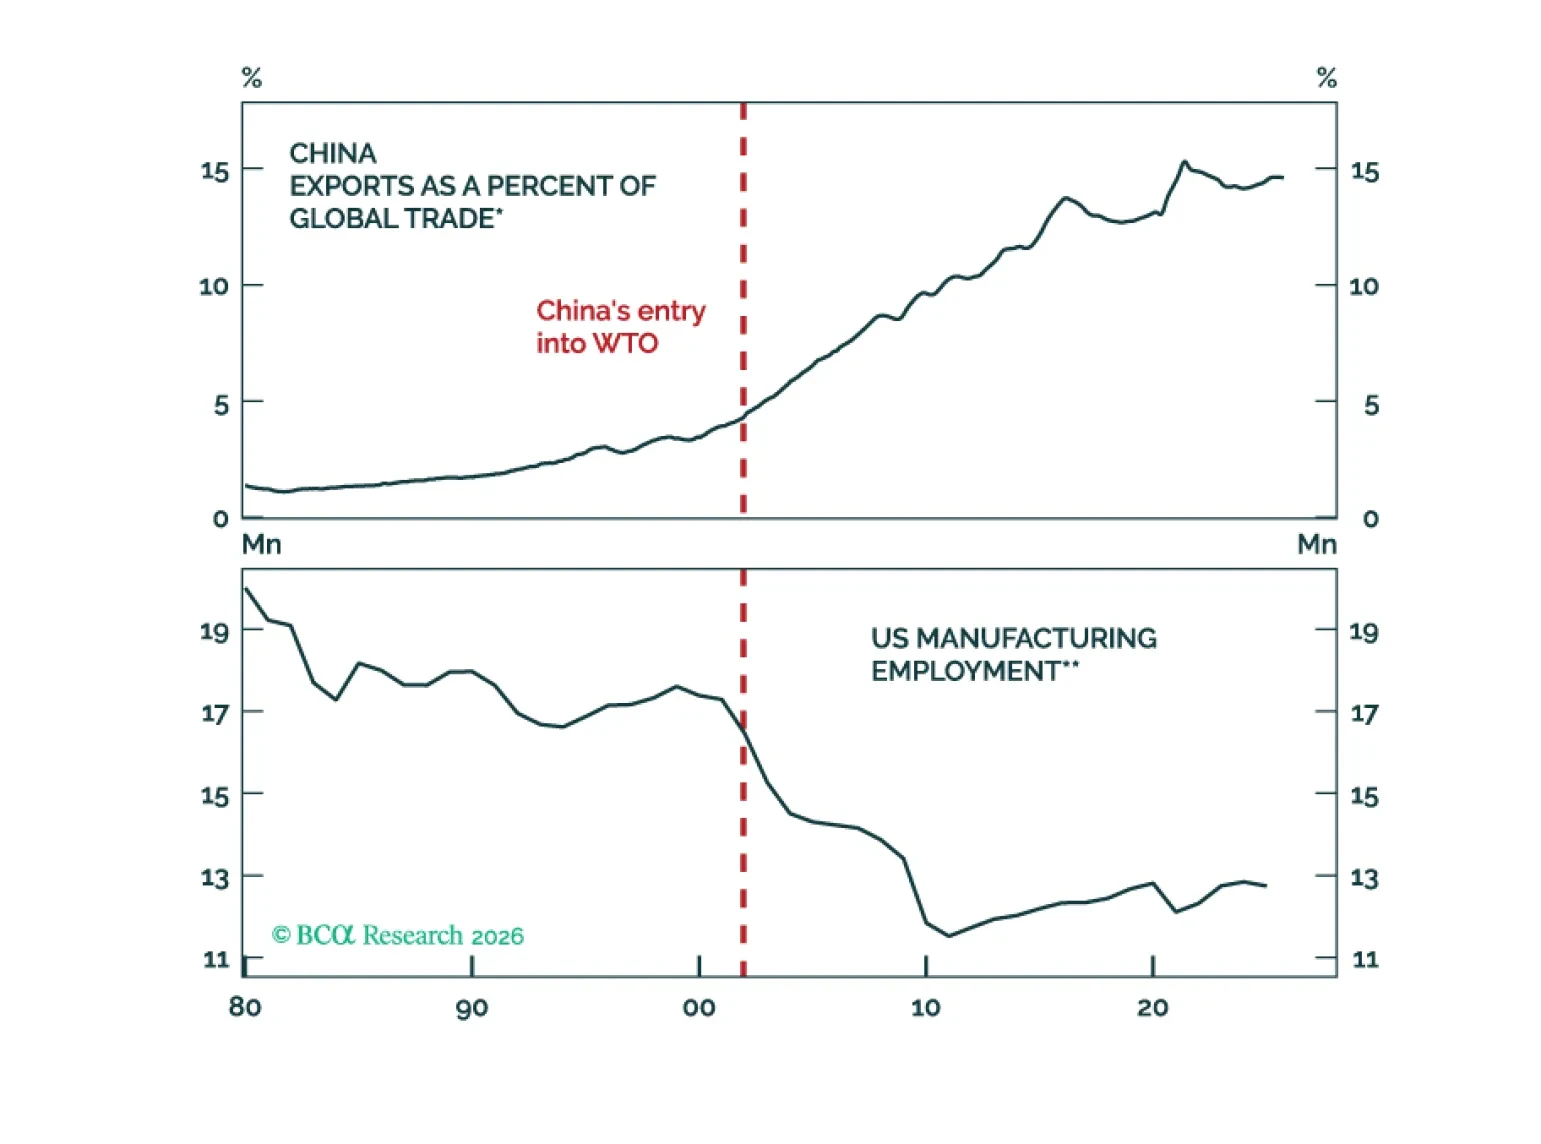
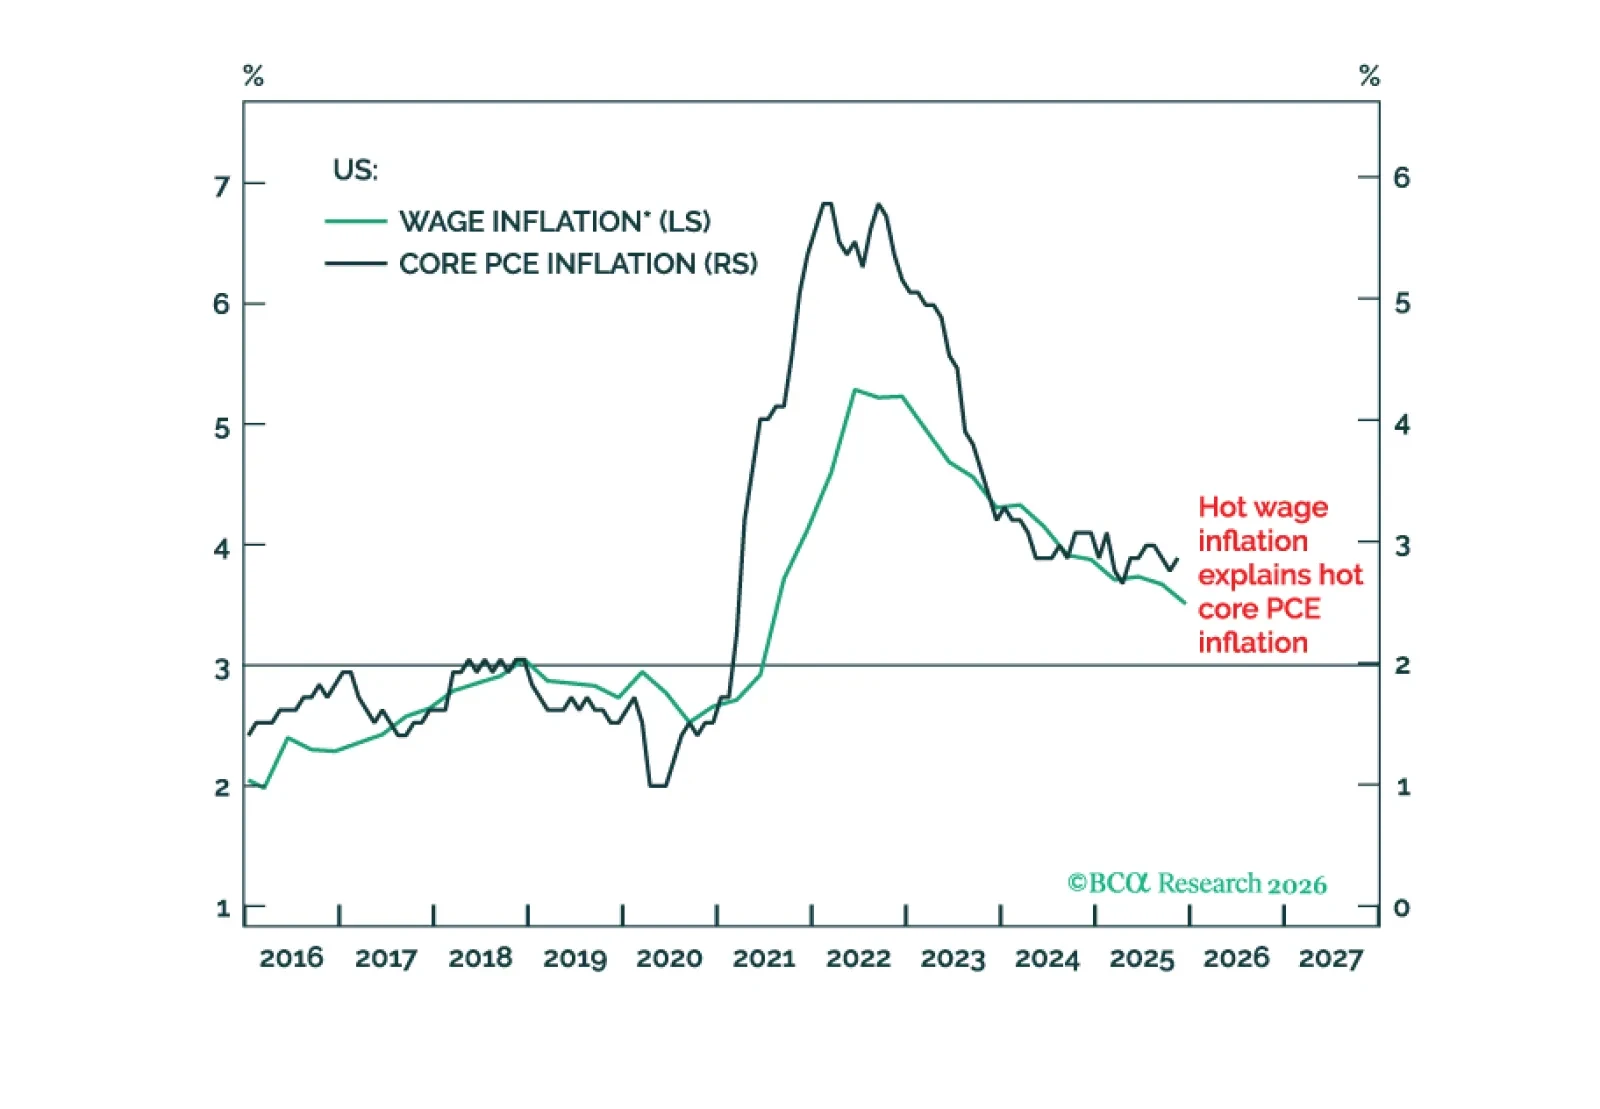
The Warsh Fed will run the US economy hot. This is bad for T-bonds and the dollar, but good for stocks. Plus, a new tactical trade is overweight Consumer Discretionary (RXI) versus Industrials (EXI).
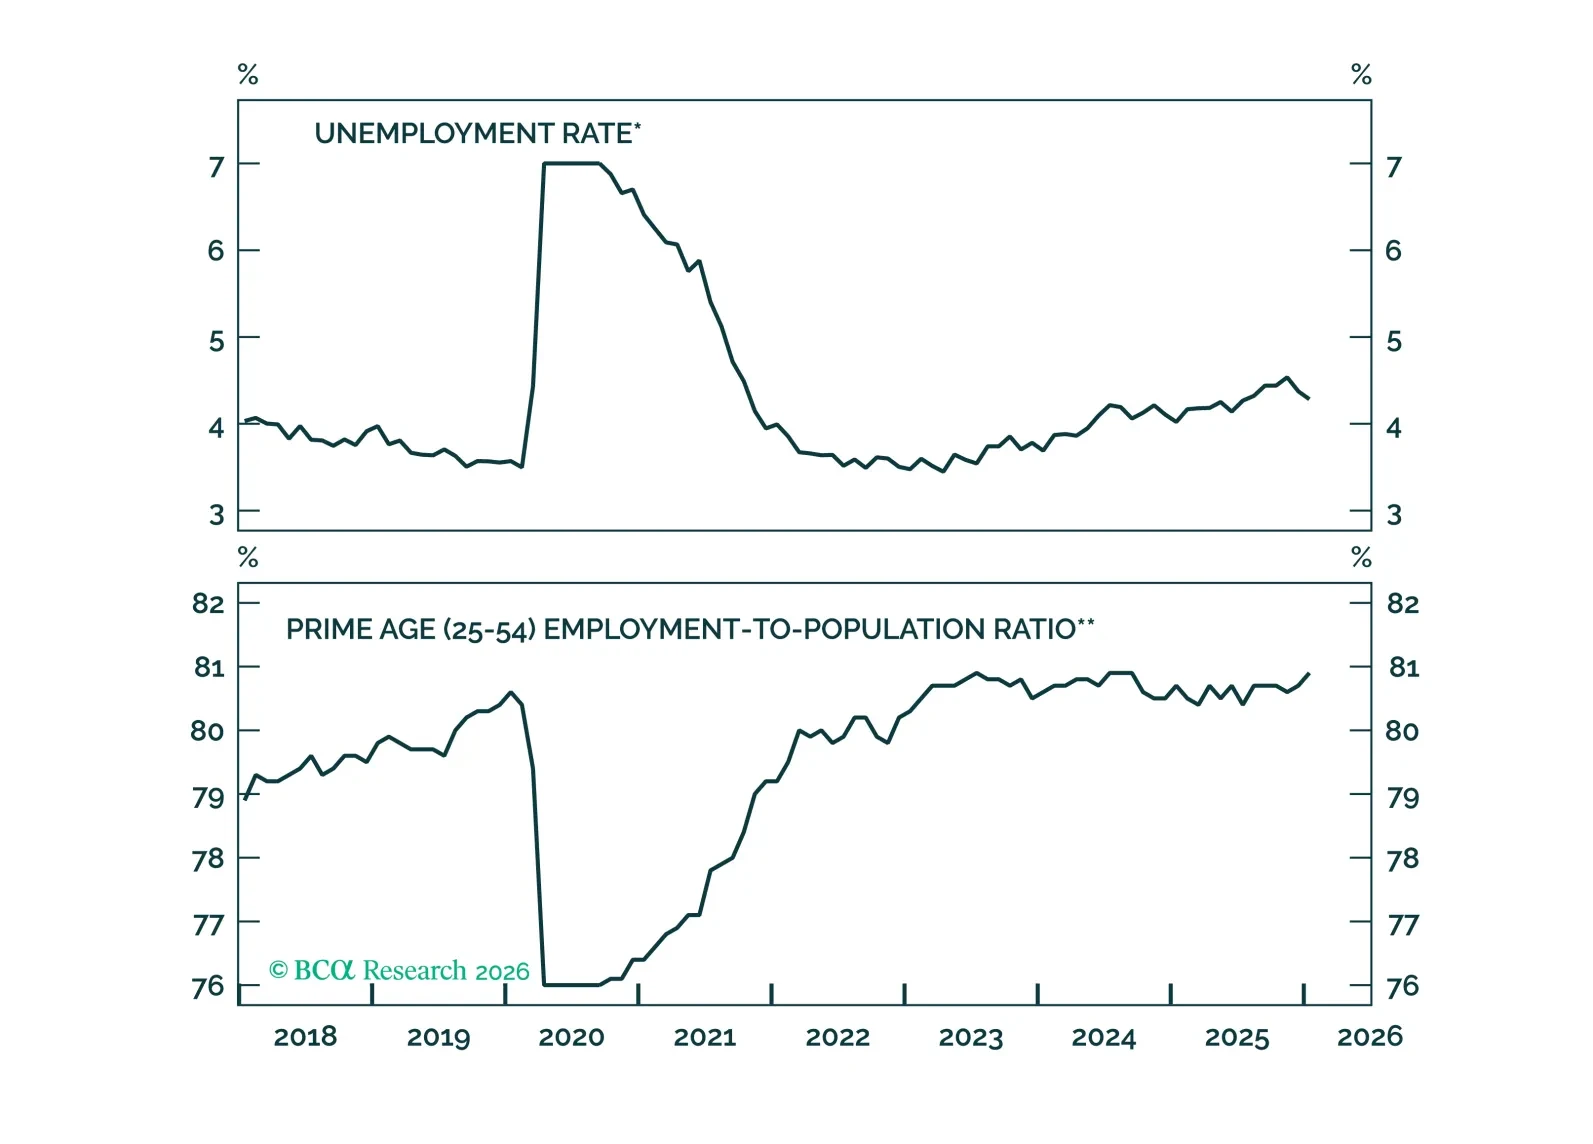
The January jobs report was unambiguously strong. Although the 172K gain in private payrolls will almost certainly be revised down, the message from the "ratios" was reassuring: The unemployment rate fell for a second straight month, the labor force participation rate increased, the share of workers who are involuntarily part-time declined, and the prime-age employment-to-population ratio rose back to its all-time high. Unlike the payroll survey, the household survey from which ratios are calculated is subject to minimal revisions.

President Donald Trump’s political capital is moderate, as he frontloaded his most disruptive policies within the first year.
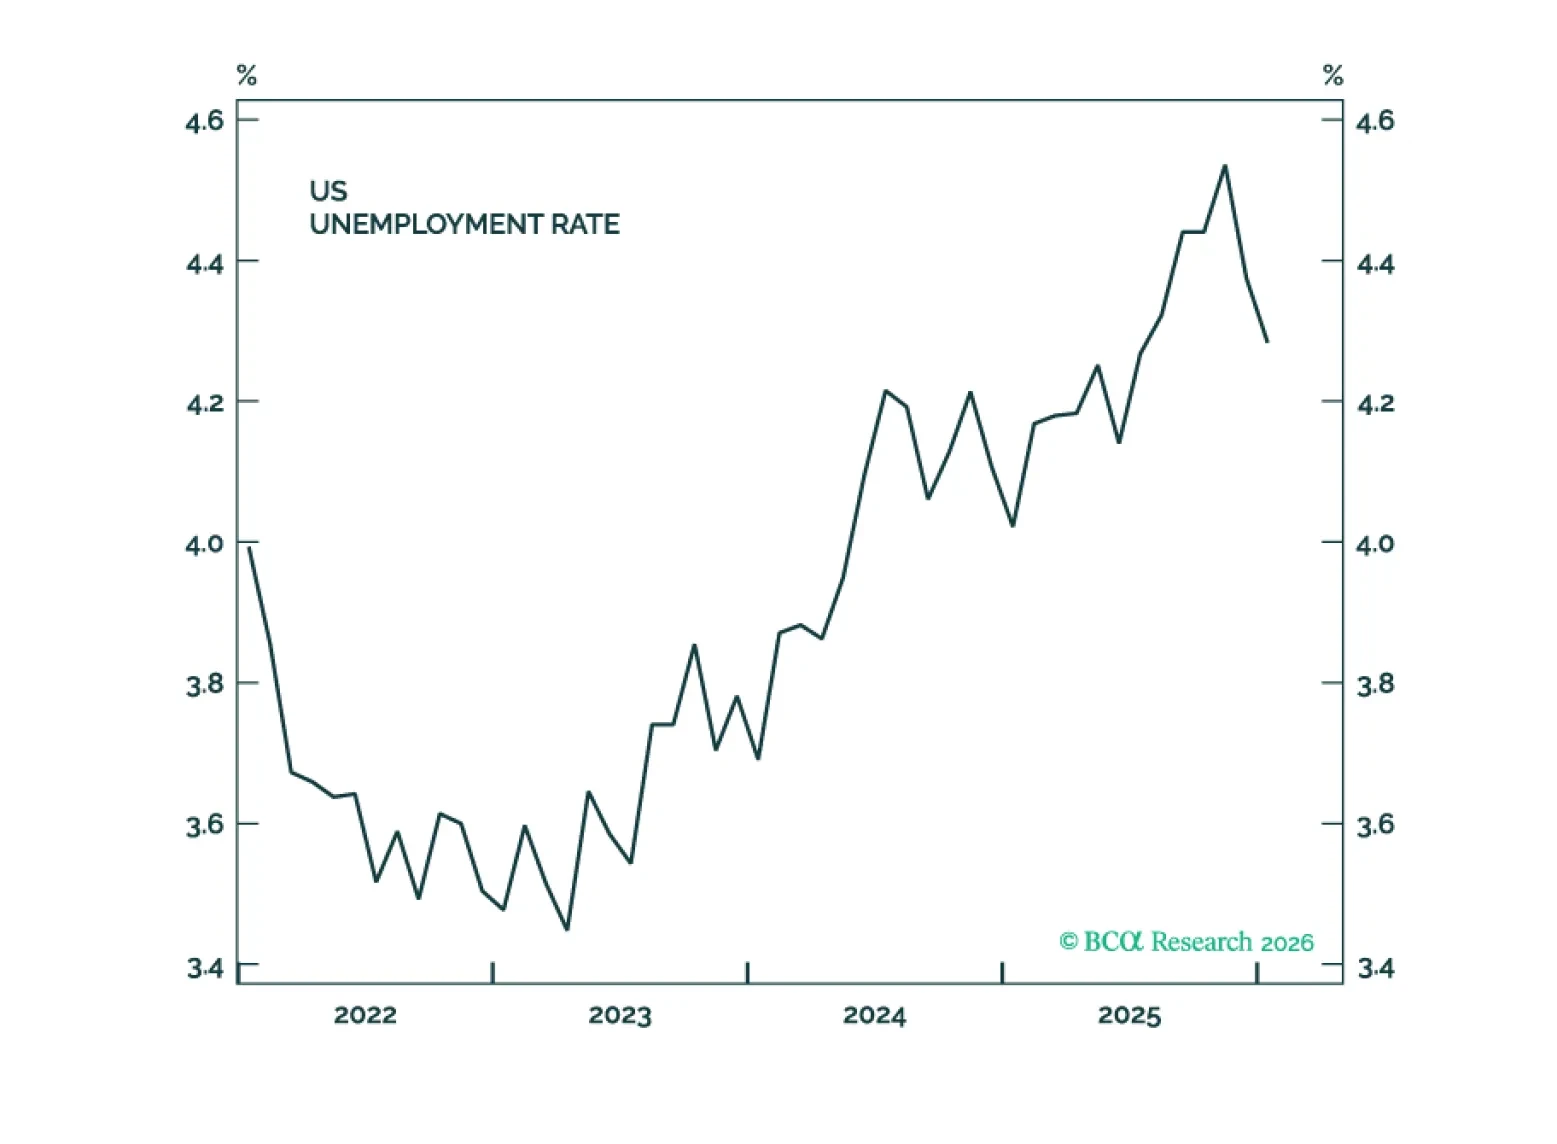
The labor market tightened in January, significantly lowering the odds of a H1 2026 rate cut. Rate cuts driven by lower inflation are still likely in H2 2026.
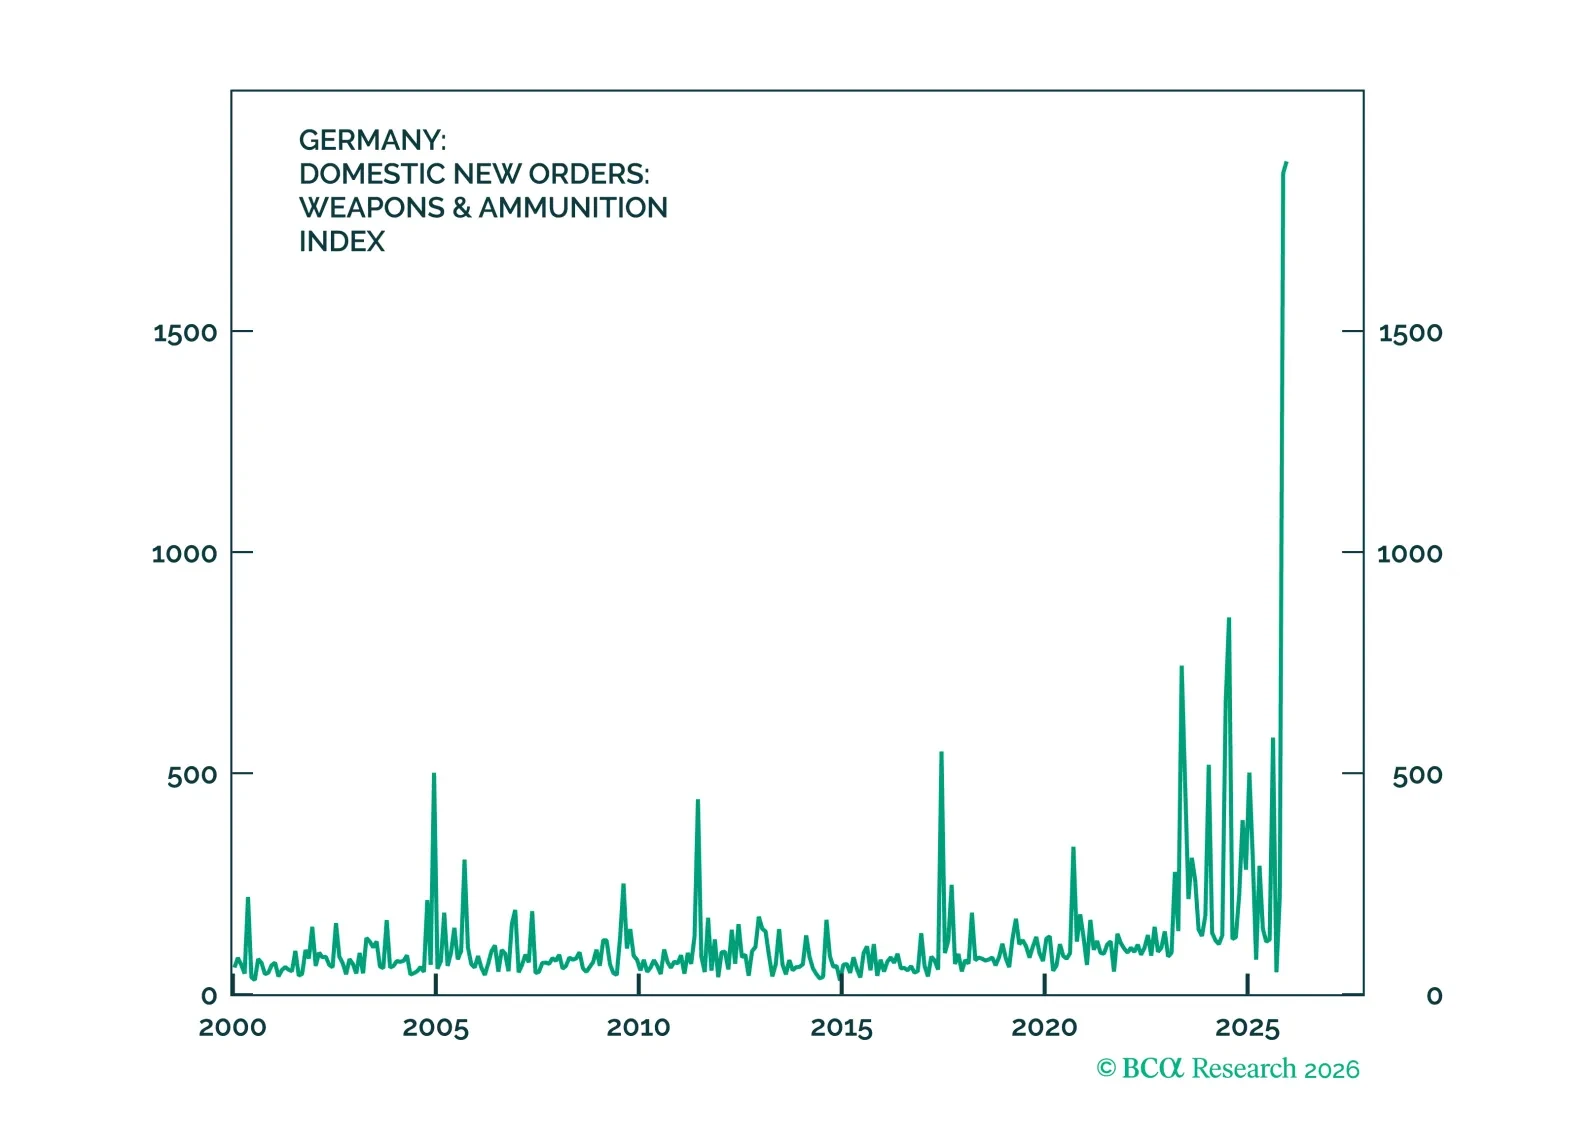
Beyond the imminent SCOTUS ruling, we revisit our bullish Europe thesis – with the Chart of the Month suggesting that Germany is so back – as well as our bearish USD view. Also, a few charts on oil and geopolitics.
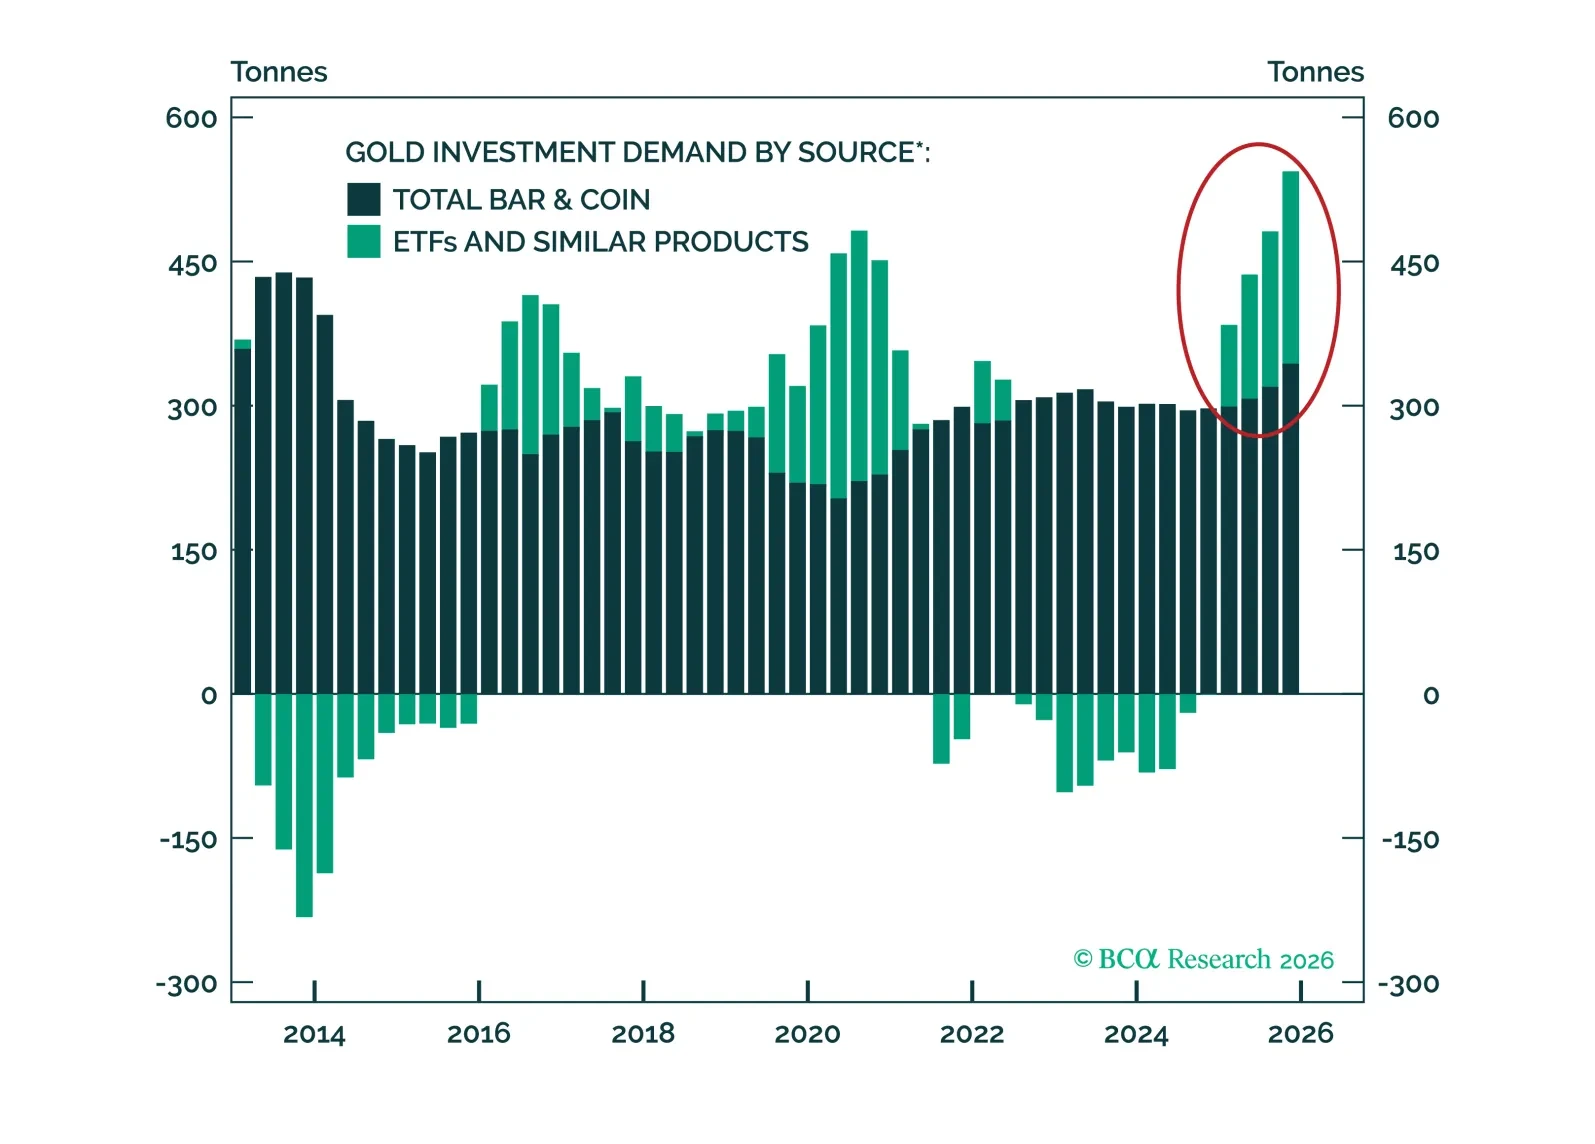
This report flags near-term risks for gold. Yet we remain optimistic about the prospects for its long-term bull market.
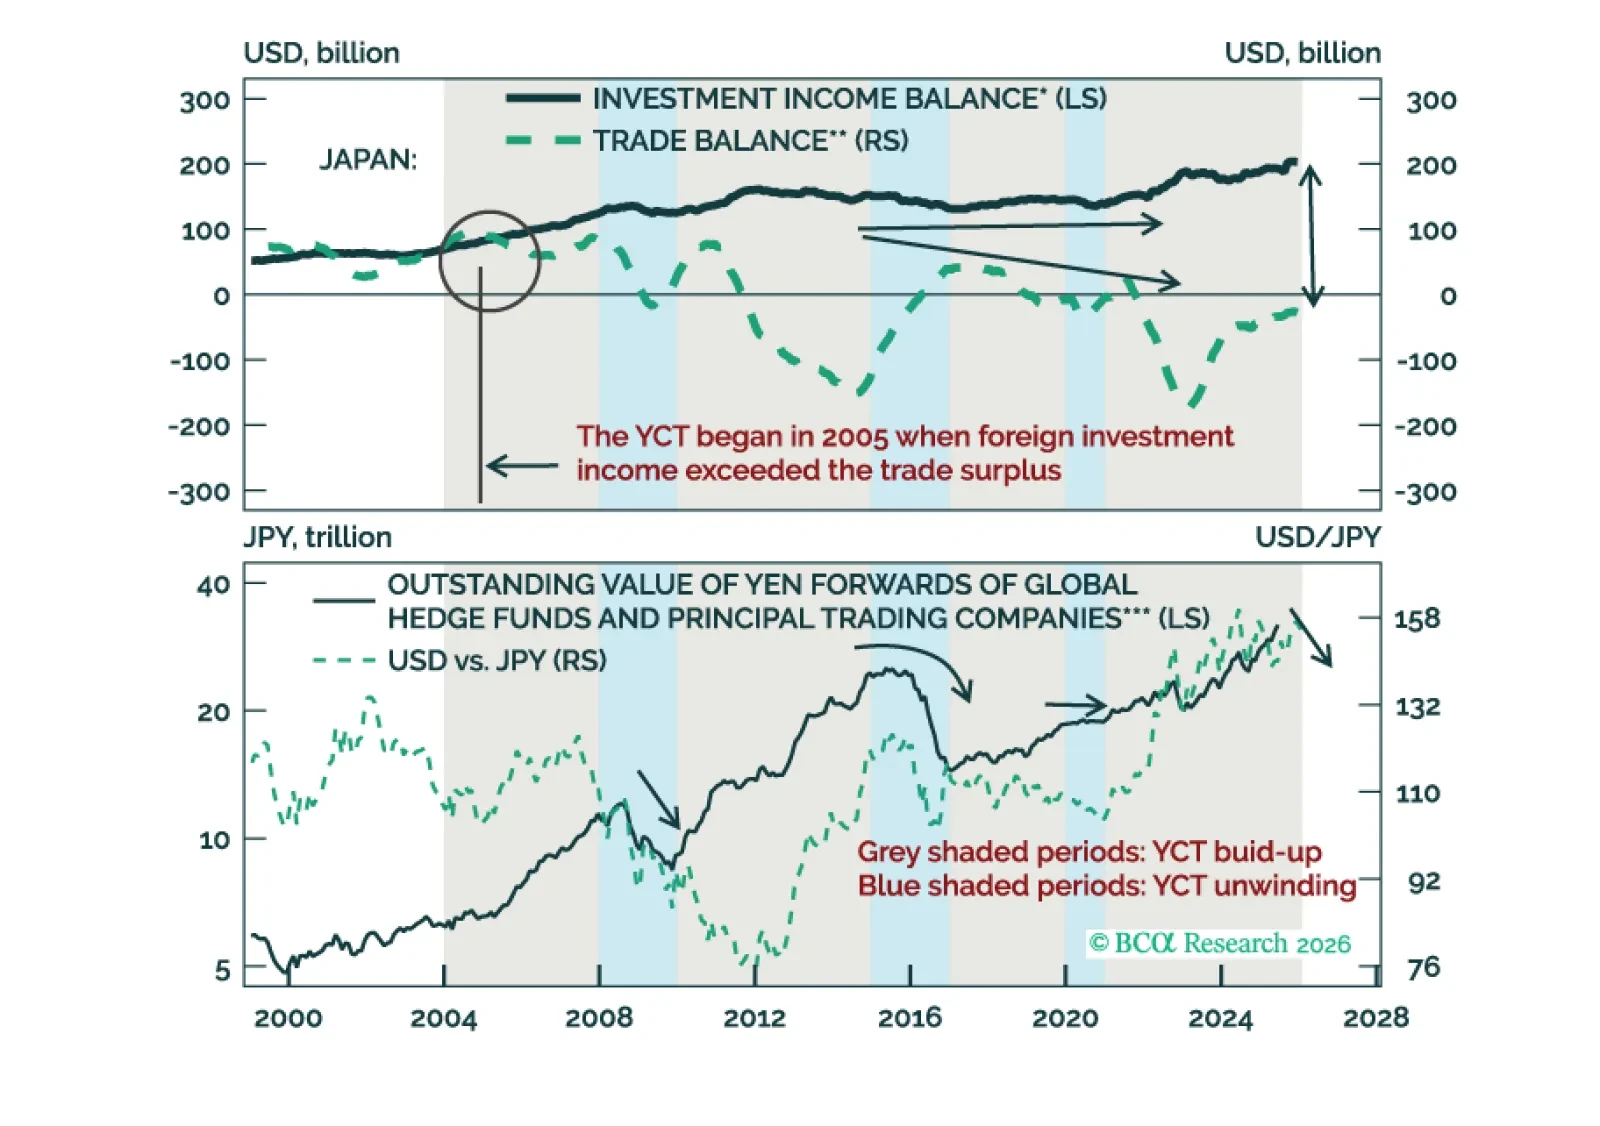
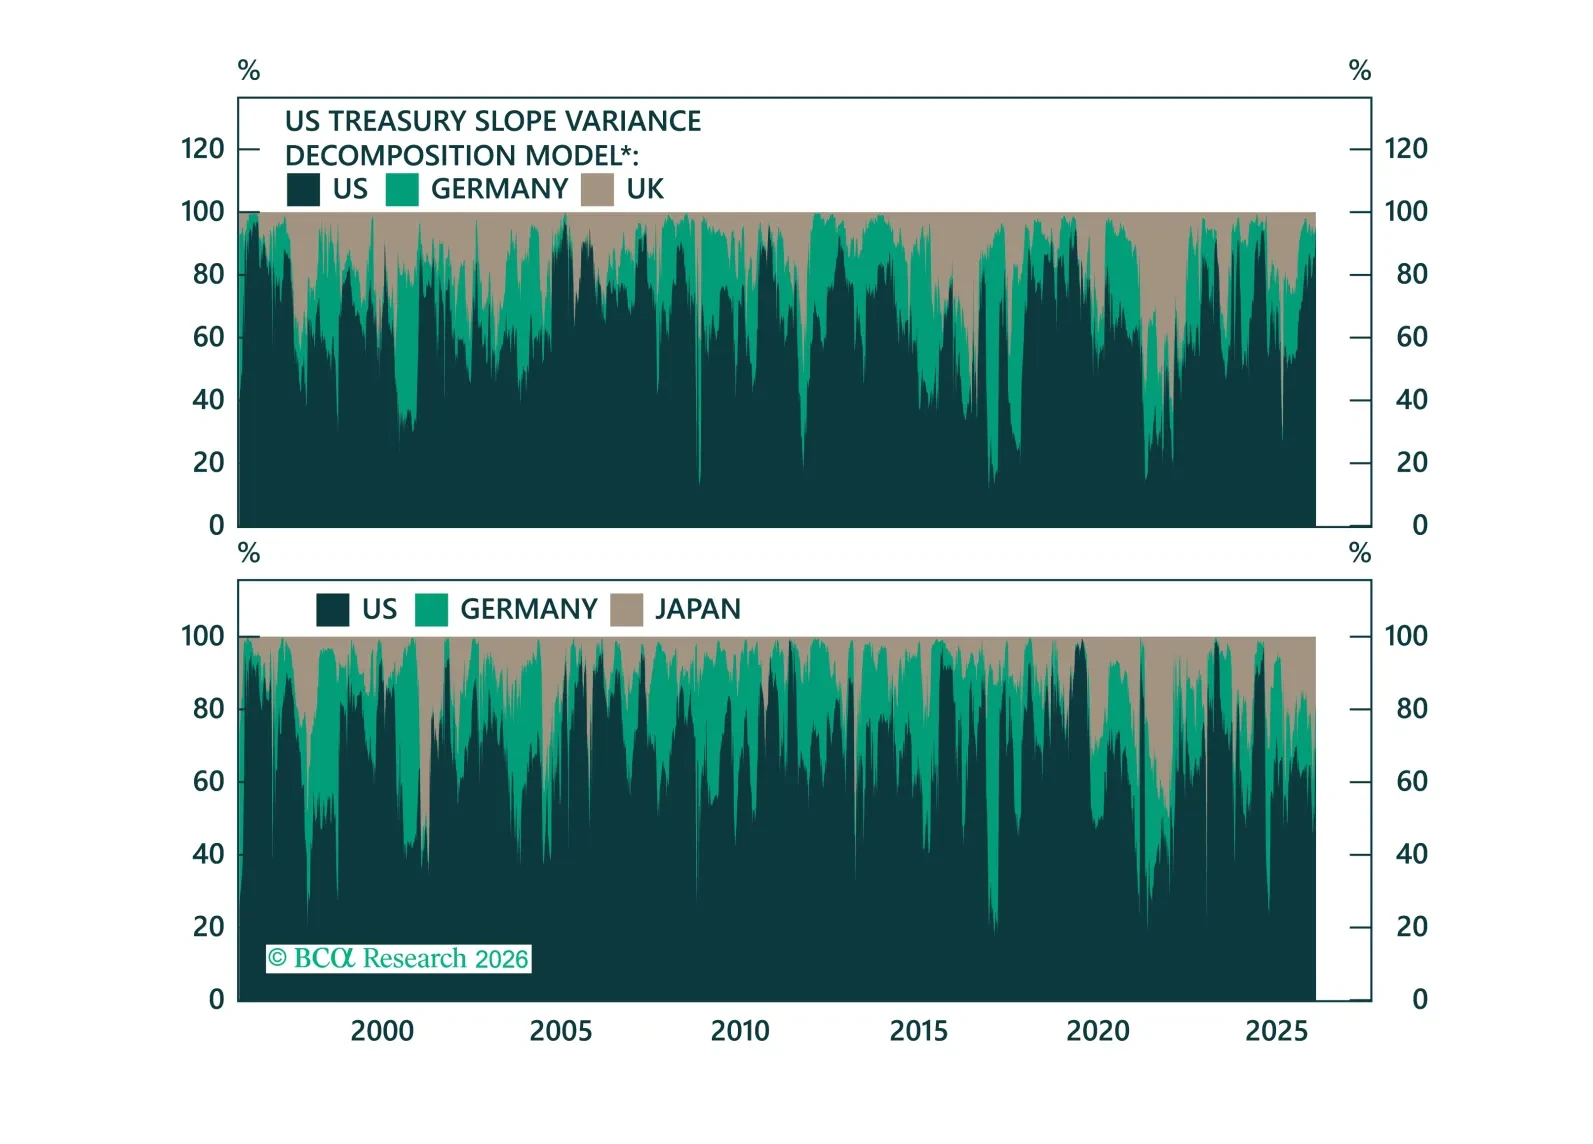
What’s driving government bond yields, and how do different bond markets impact each other? In today's Strategy Insight, we decompose yield moves into global drivers and idiosyncratic local drivers.
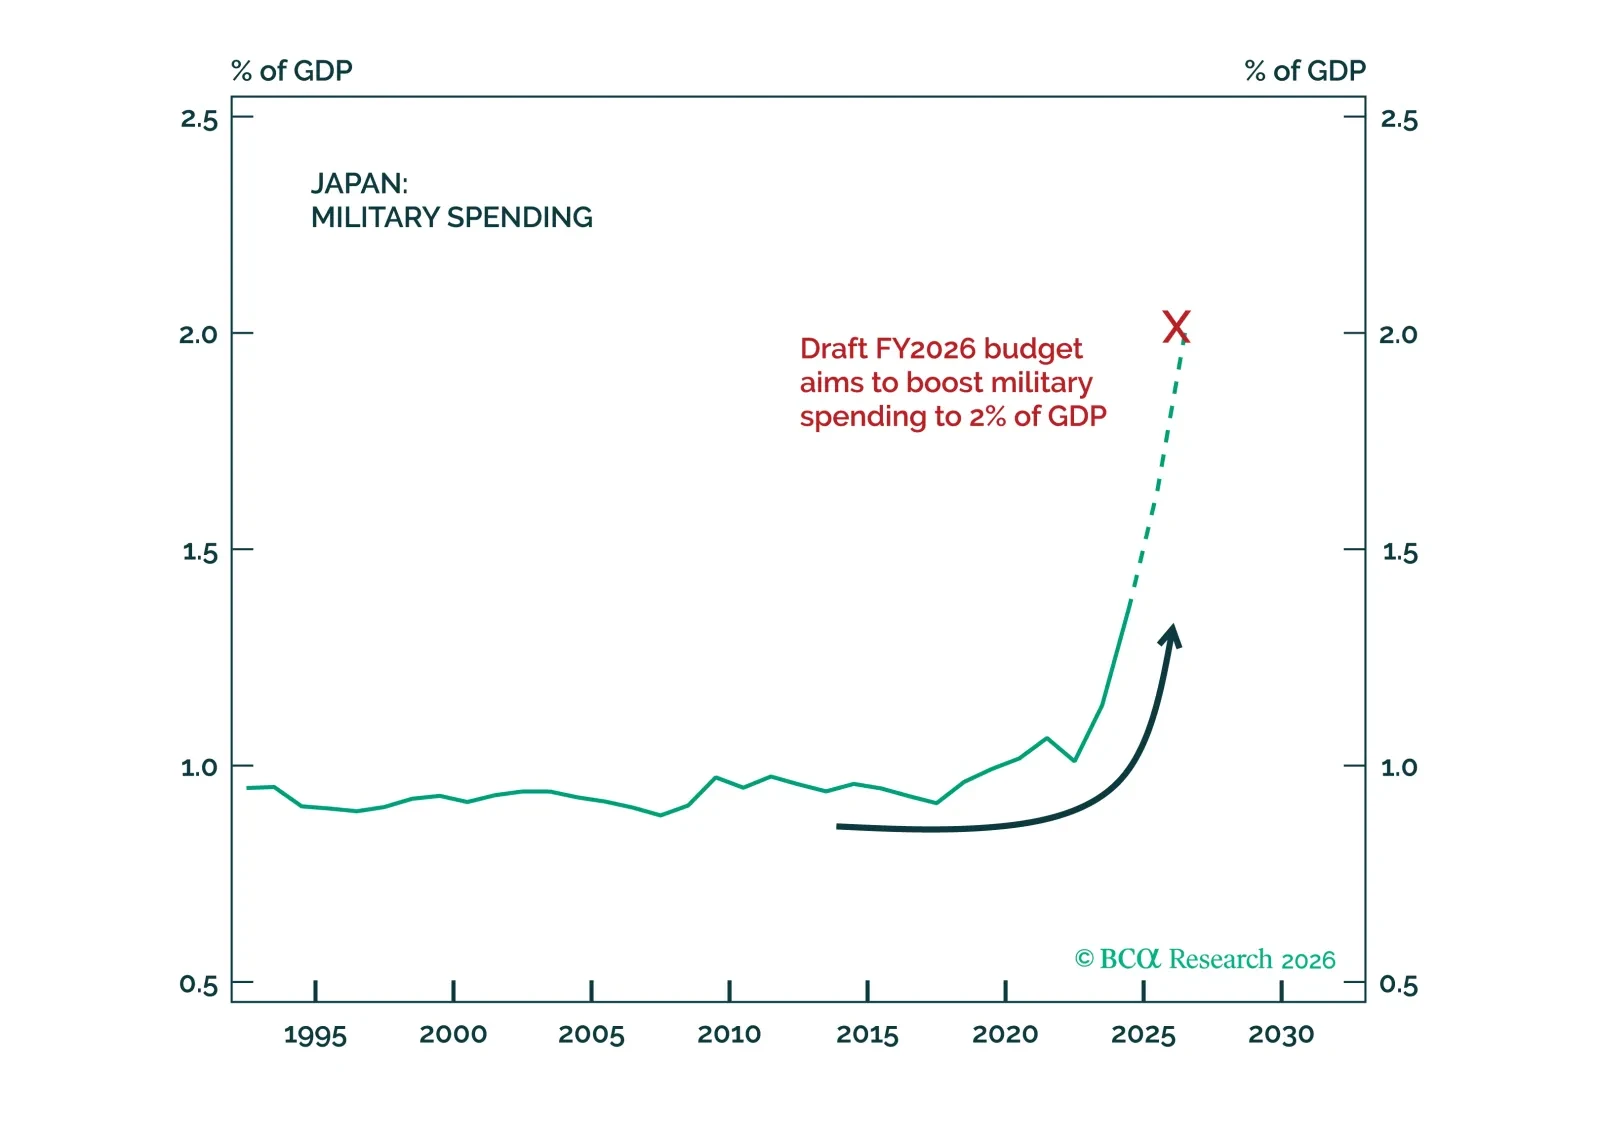
Ignore Japan's constitutional debate. Rearmament will accelerate anyway. Tech, defense stocks, and industrials will benefit. The threat to JGBs is real but will probably be contained.