Latest from BCA Research
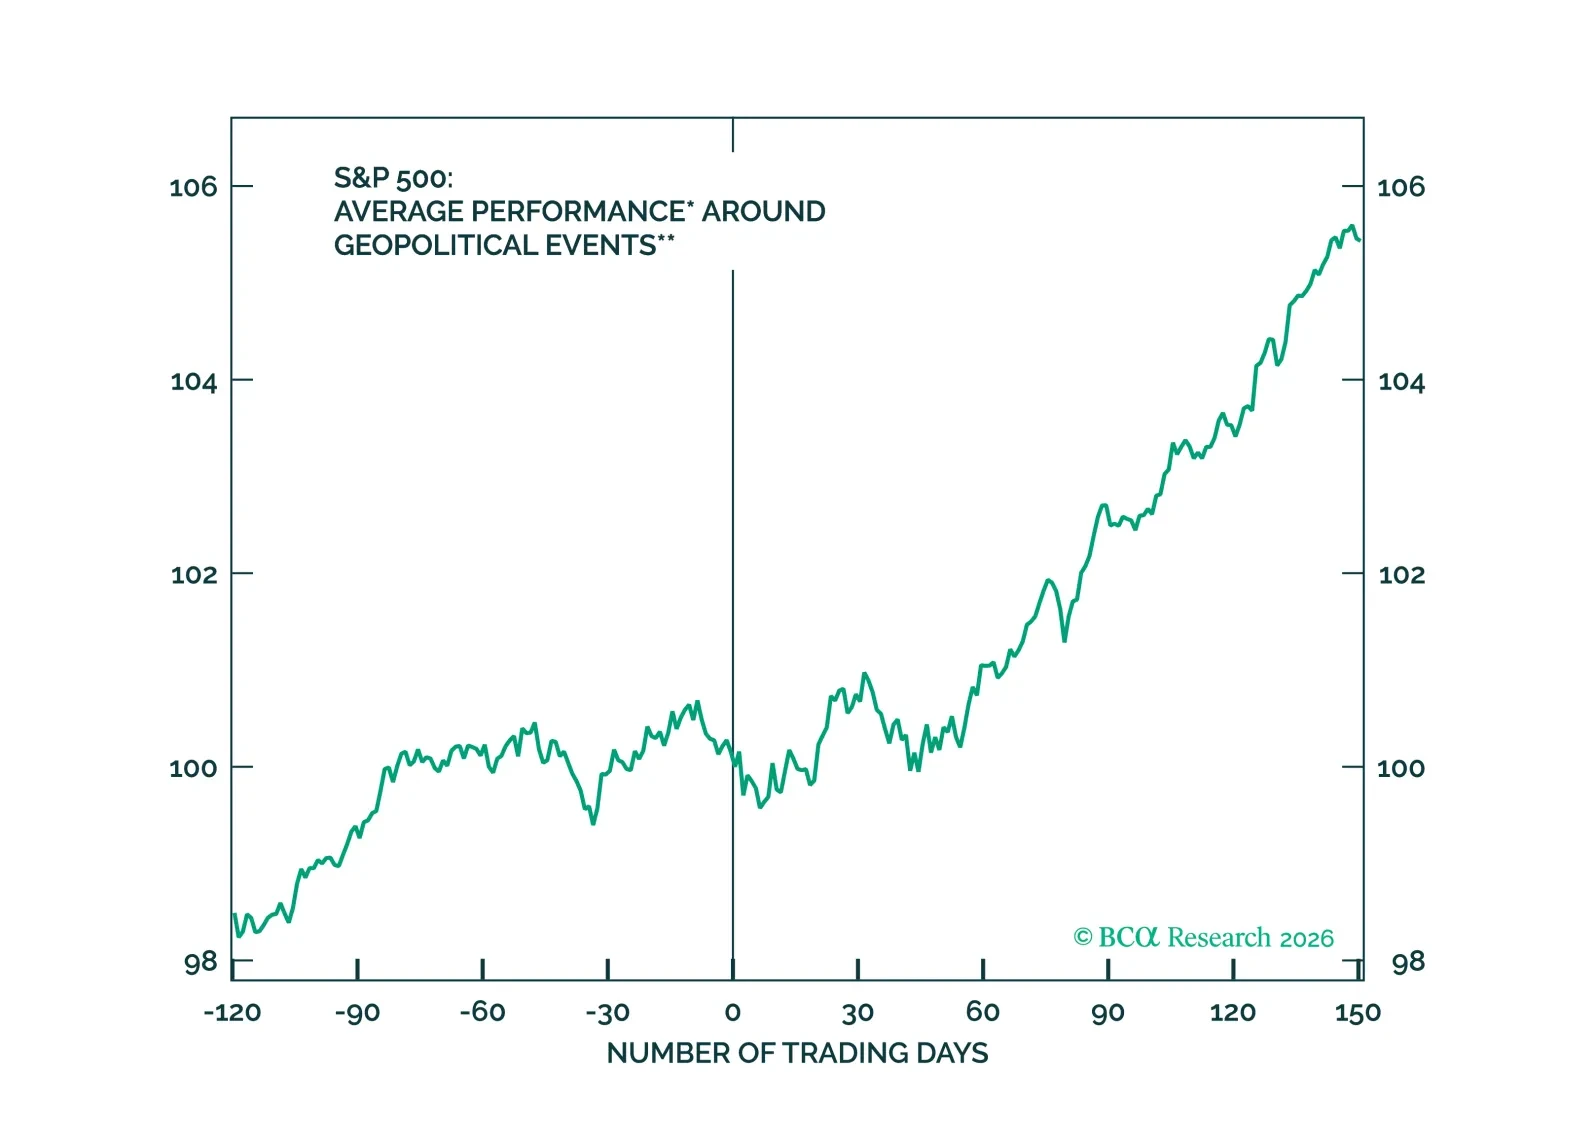
In the short term, there is plenty to be worried about in macro beyond the Middle East. The market was on thin ice before the Iran conflict. In the long term, the base case scenario remains bullish, but the war in the Middle East needs to be brief.
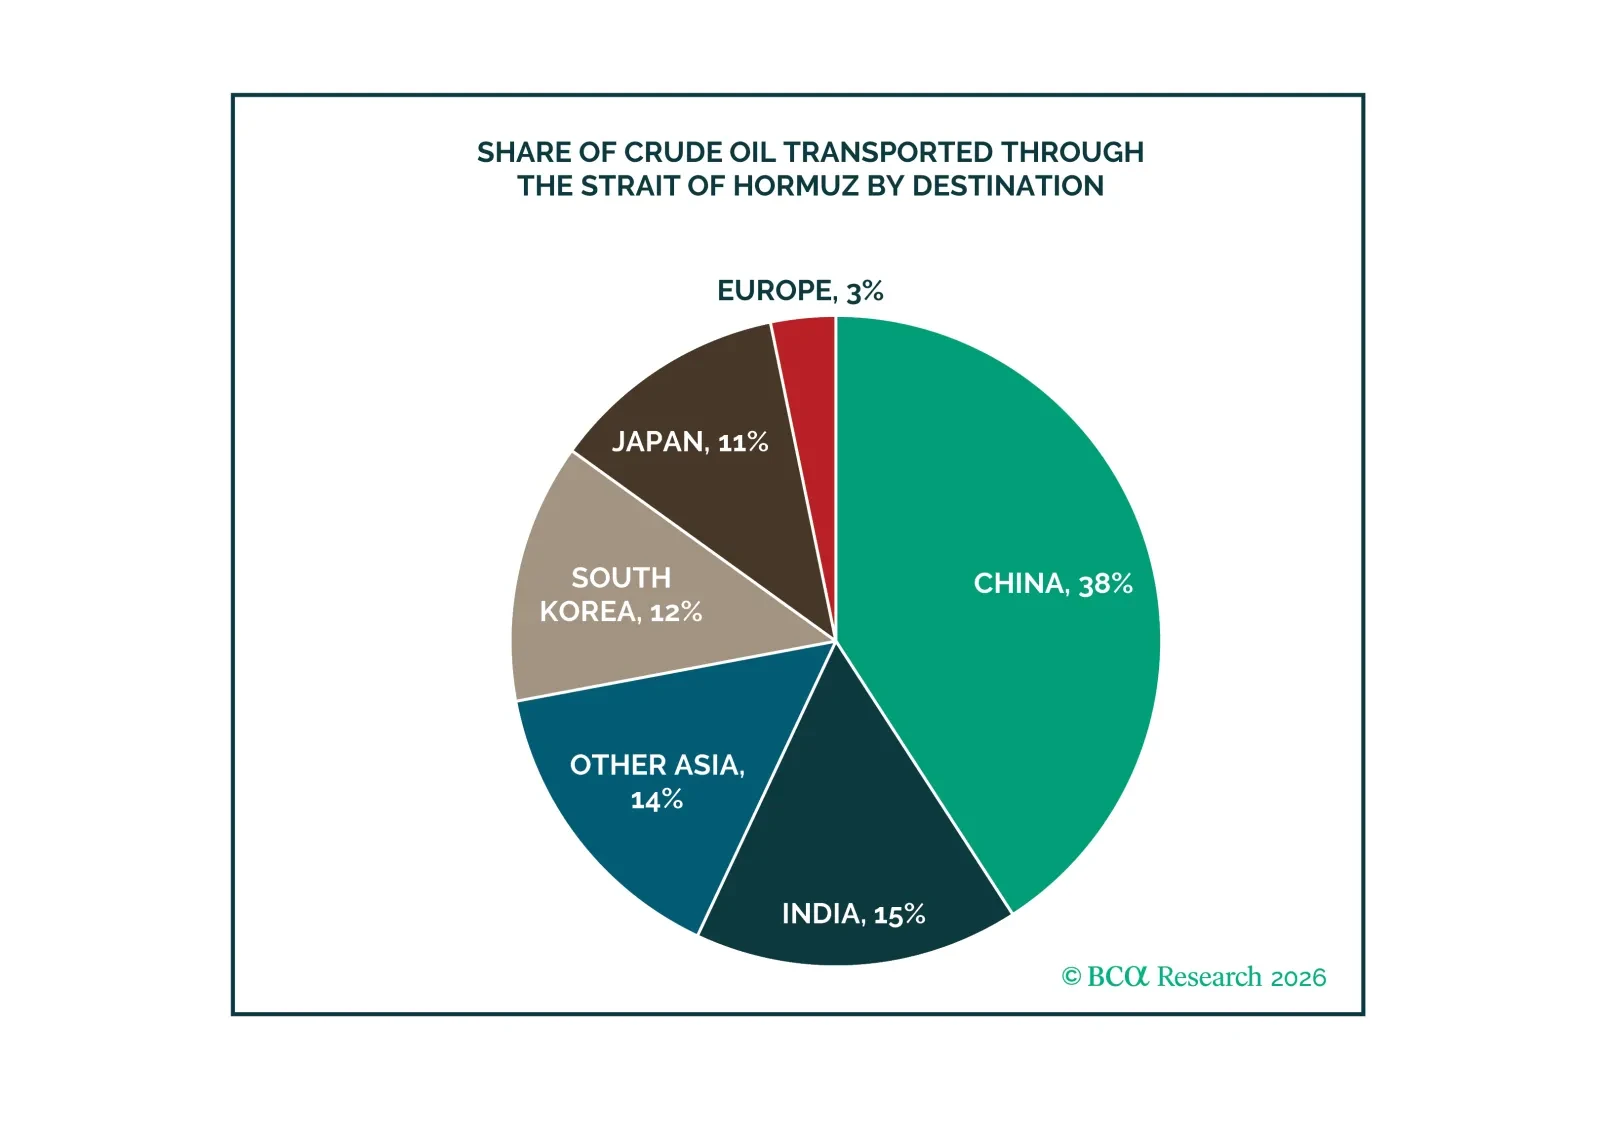
The war in Iran is disrupting global oil and LNG flows and remains a threat to regional energy infrastructure. Energy price risks remain skewed to the upside over the near term.
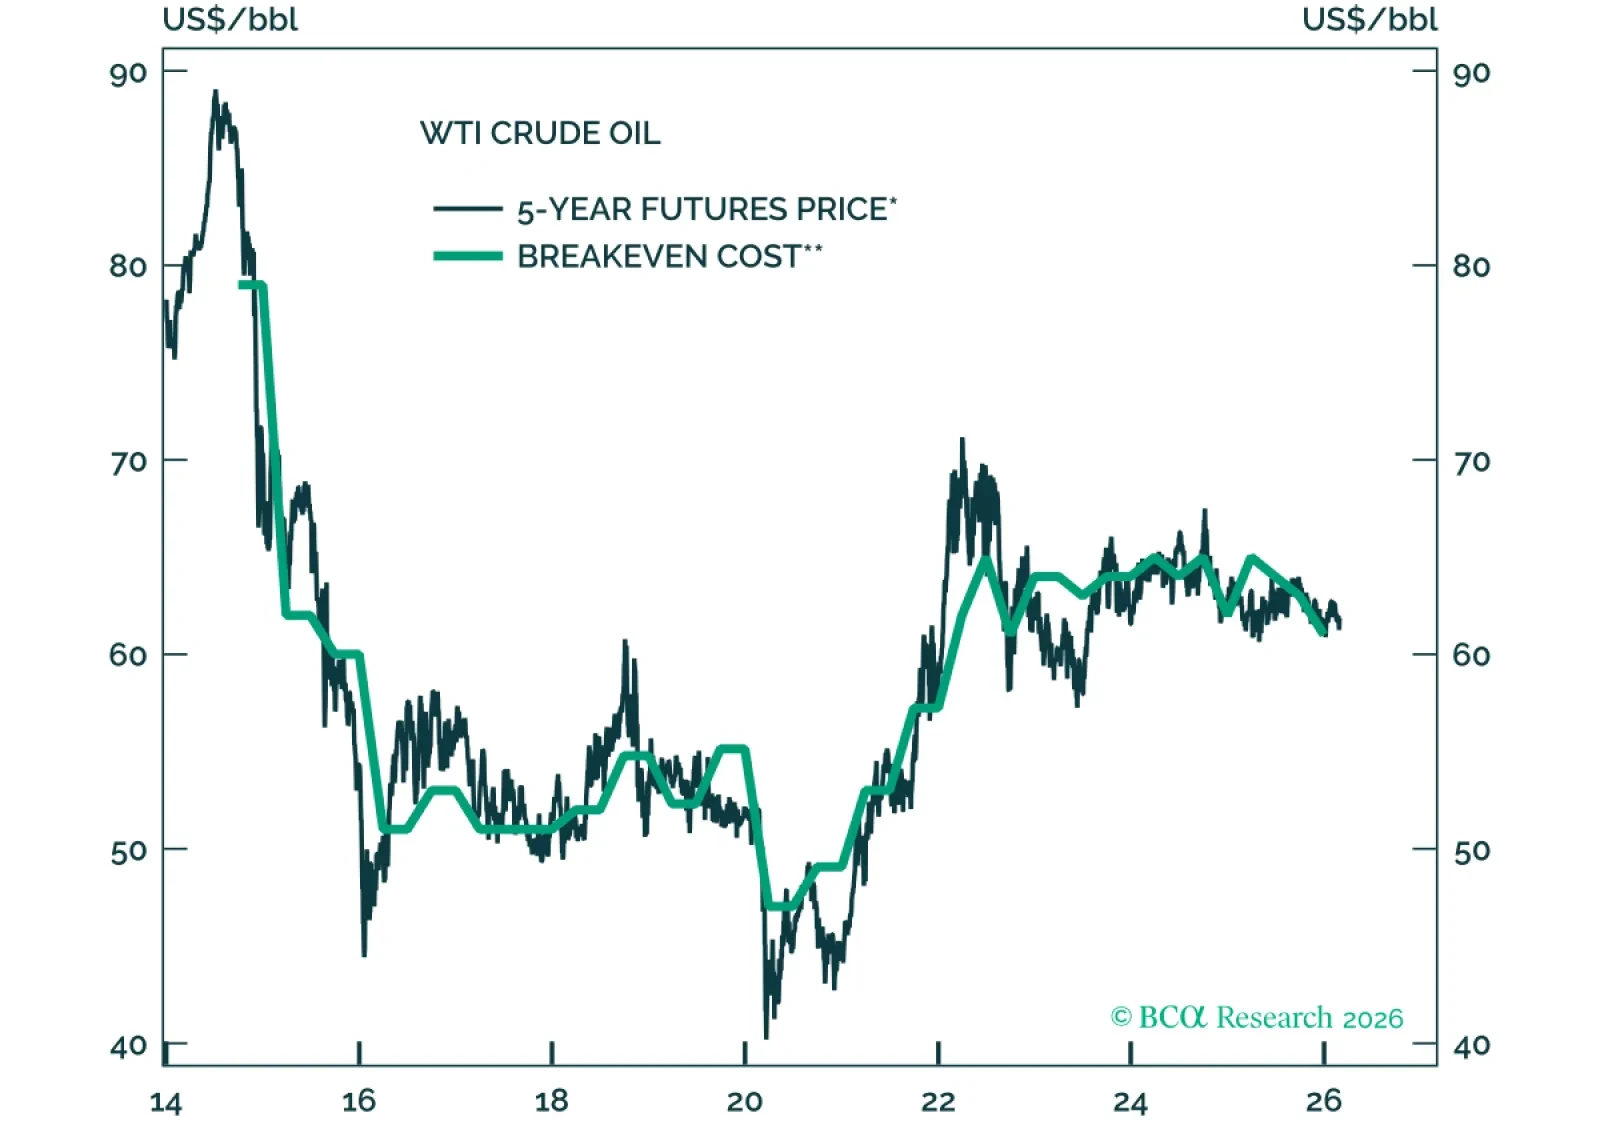
Since 1970, every US recession excluding the pandemic downturn was preceded by a sharp rise in oil prices. As I write this, WTI is trading at $71/bbl, up 24% year-to-date and up 19% relative to the Q4 2025 average. That said, today’s oil price is still only 8% higher than the average for all of 2025. If oil prices stay broadly where they are, the impact on the US economy should be limited.
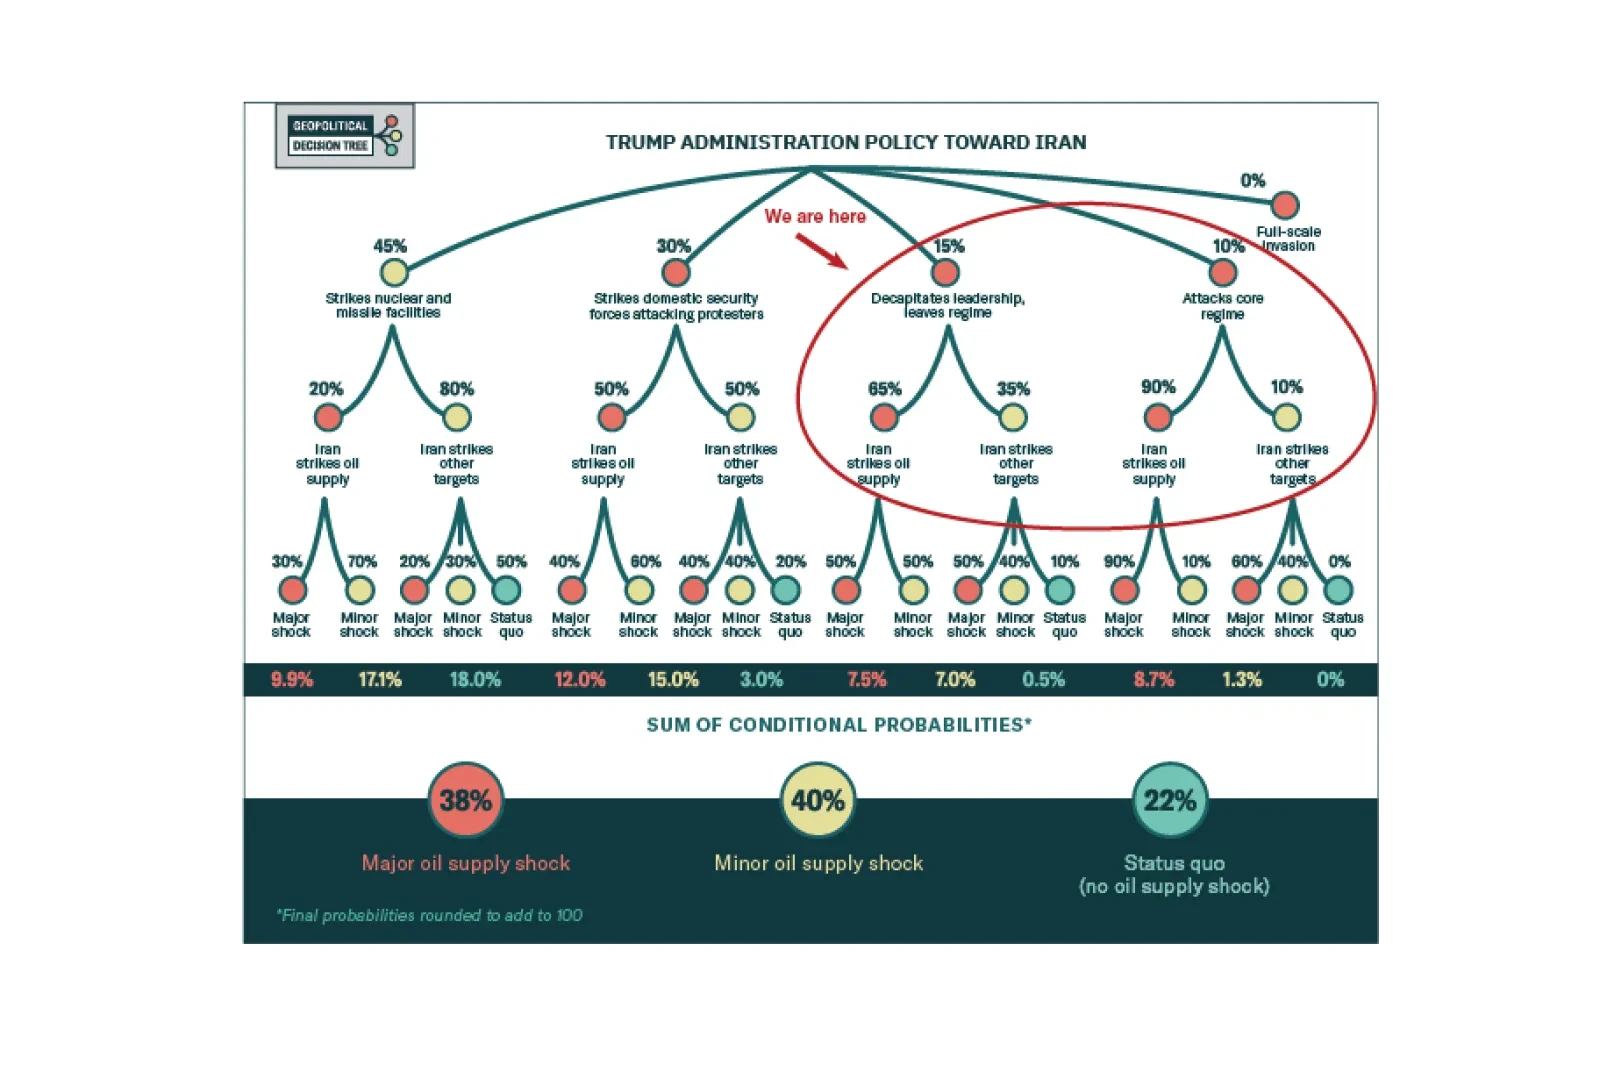
It is too soon to sell the rip in oil or buy the dip in stocks. Stick with risk-off trades for now.
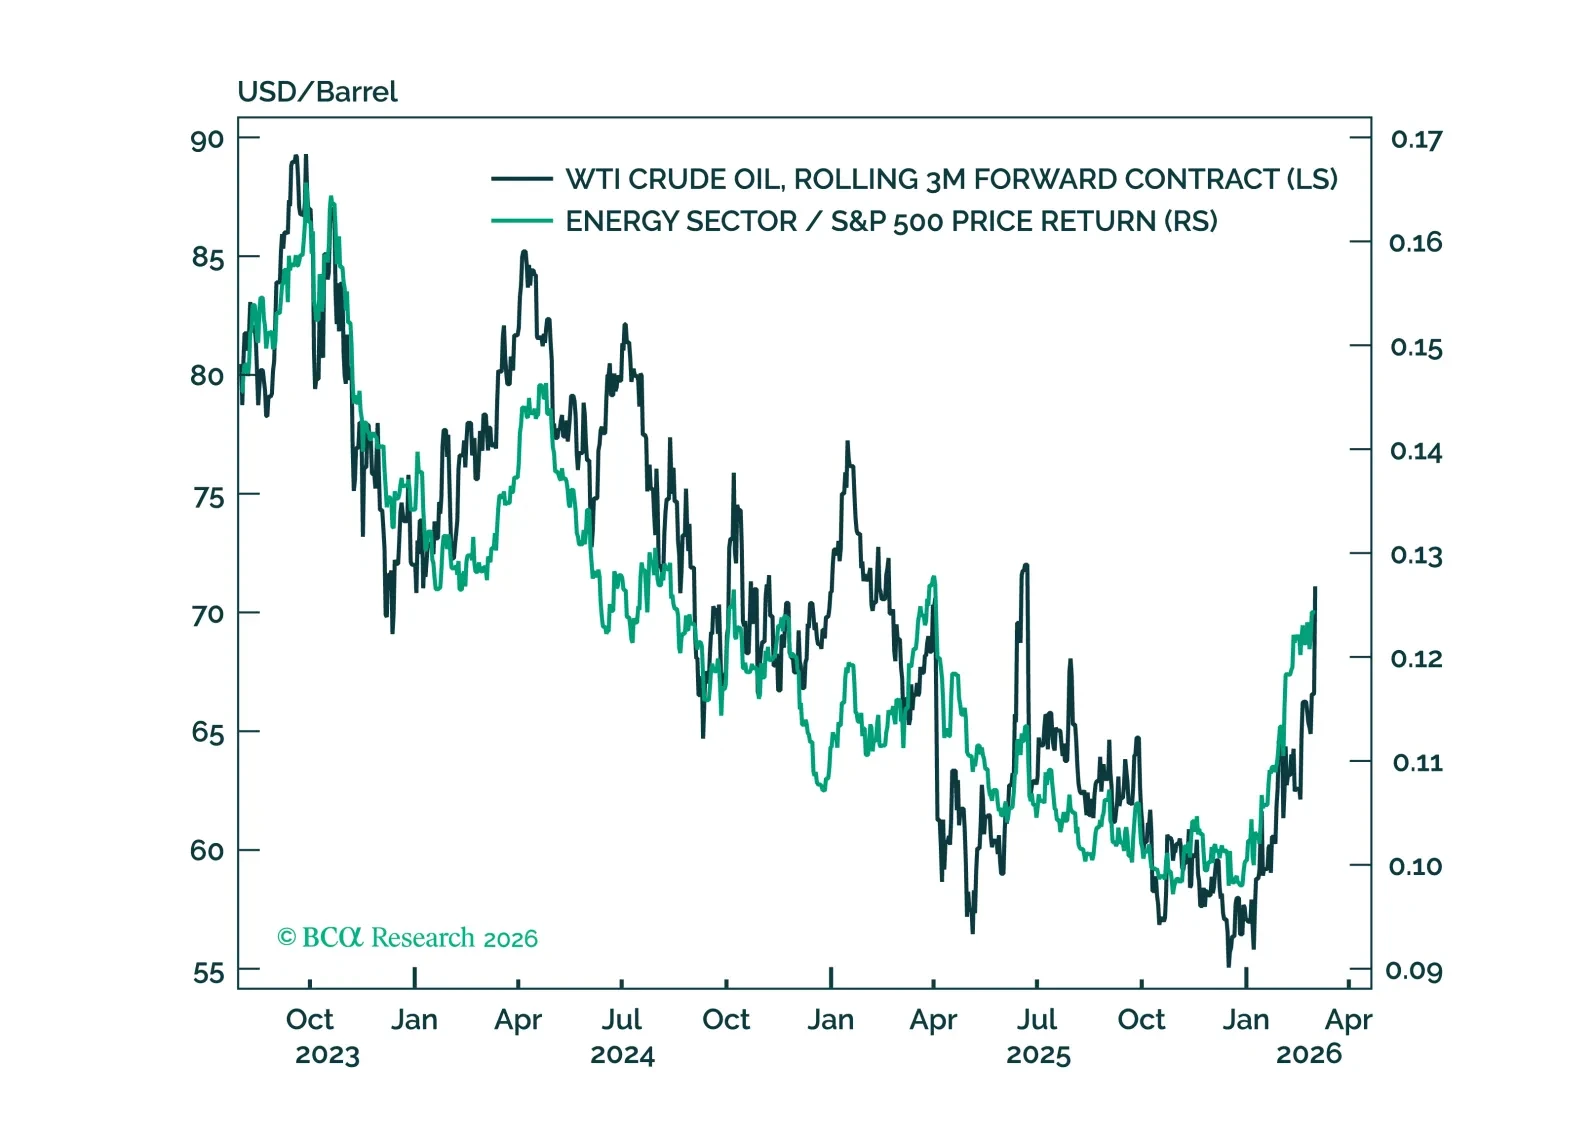
Middle East hostilities have triggered risk-off moves and pushed oil prices higher. Previous geopolitically driven oil price disruptions suggest that speed, persistence and equity market vulnerability relate to the degree of the market sell off. At the other end of the spectrum, energy stocks should benefit, but have already rallied significantly.

India is seeing net capital outflows for the first time in a generation. The central bank is selling foreign reserves to defend the rupee, which is draining banking system liquidity. The latter risks derailing the nascent credit revival. Indian stock prices remain vulnerable.
Since our Saturday missive, there have been several developments in the ongoing conflict between Iran and the US-Israel coalition.
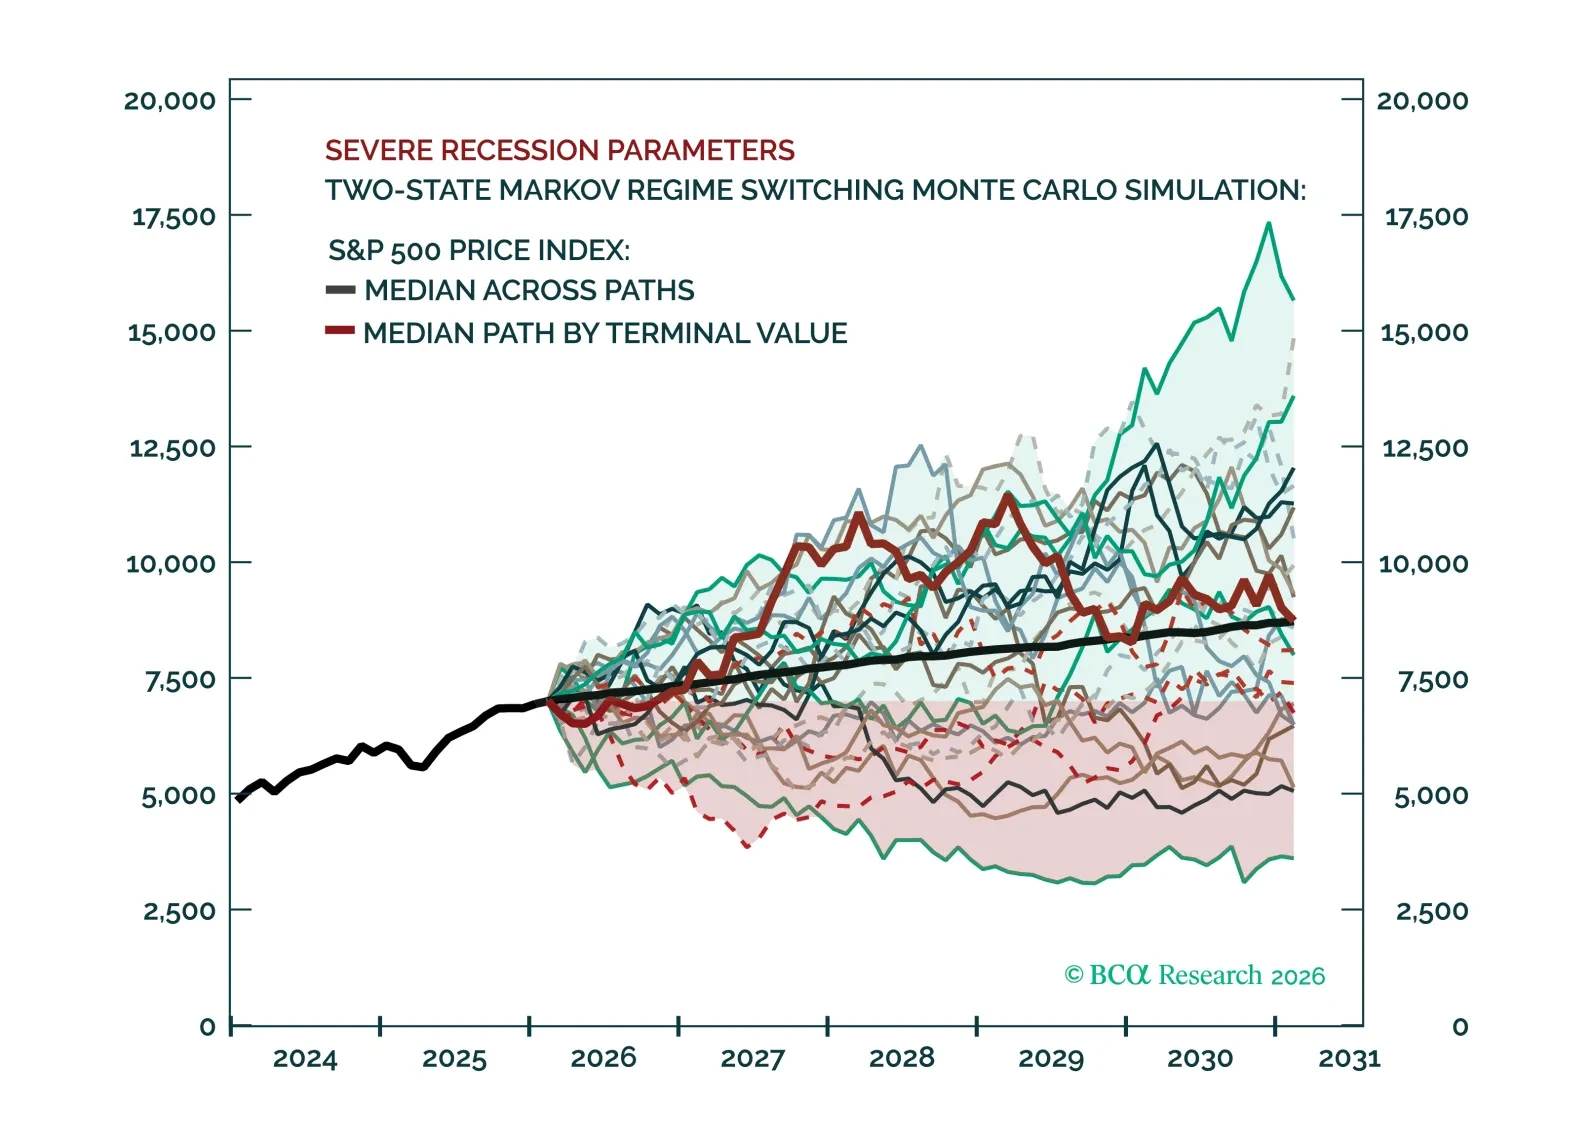
Recessions are inevitable but unpredictable. While earnings drive long‑term equity performance through the cycle, around turning points fundamentals follow a predictable sequence: multiples contract first, then prices, then earnings. Recessions can shift sector leadership, but simulations show that medium‑term index‑level upside remains intact unless future downturns are materially more severe than in history.
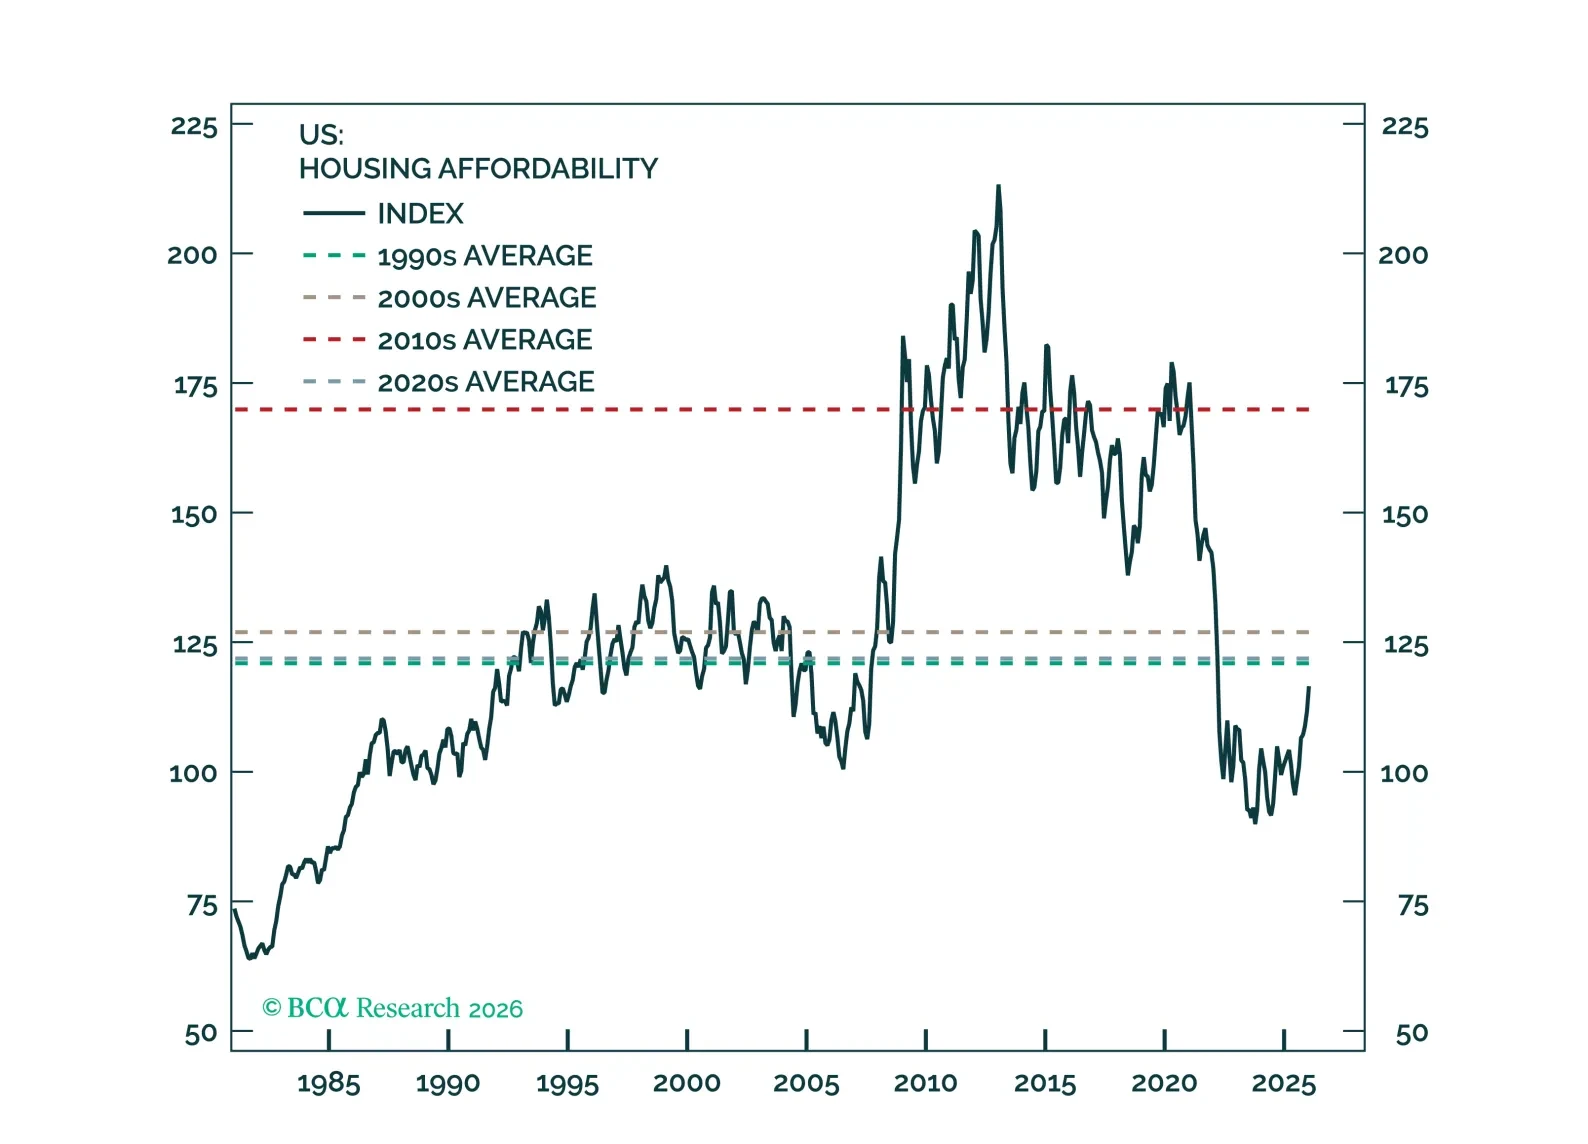
Fears of widespread job losses due to AI are overstated. For investors, the key is that white-collar anxiety is accelerating a red-hot blue-collar economy via lower yields. Upgrade Private Real Estate to overweight.
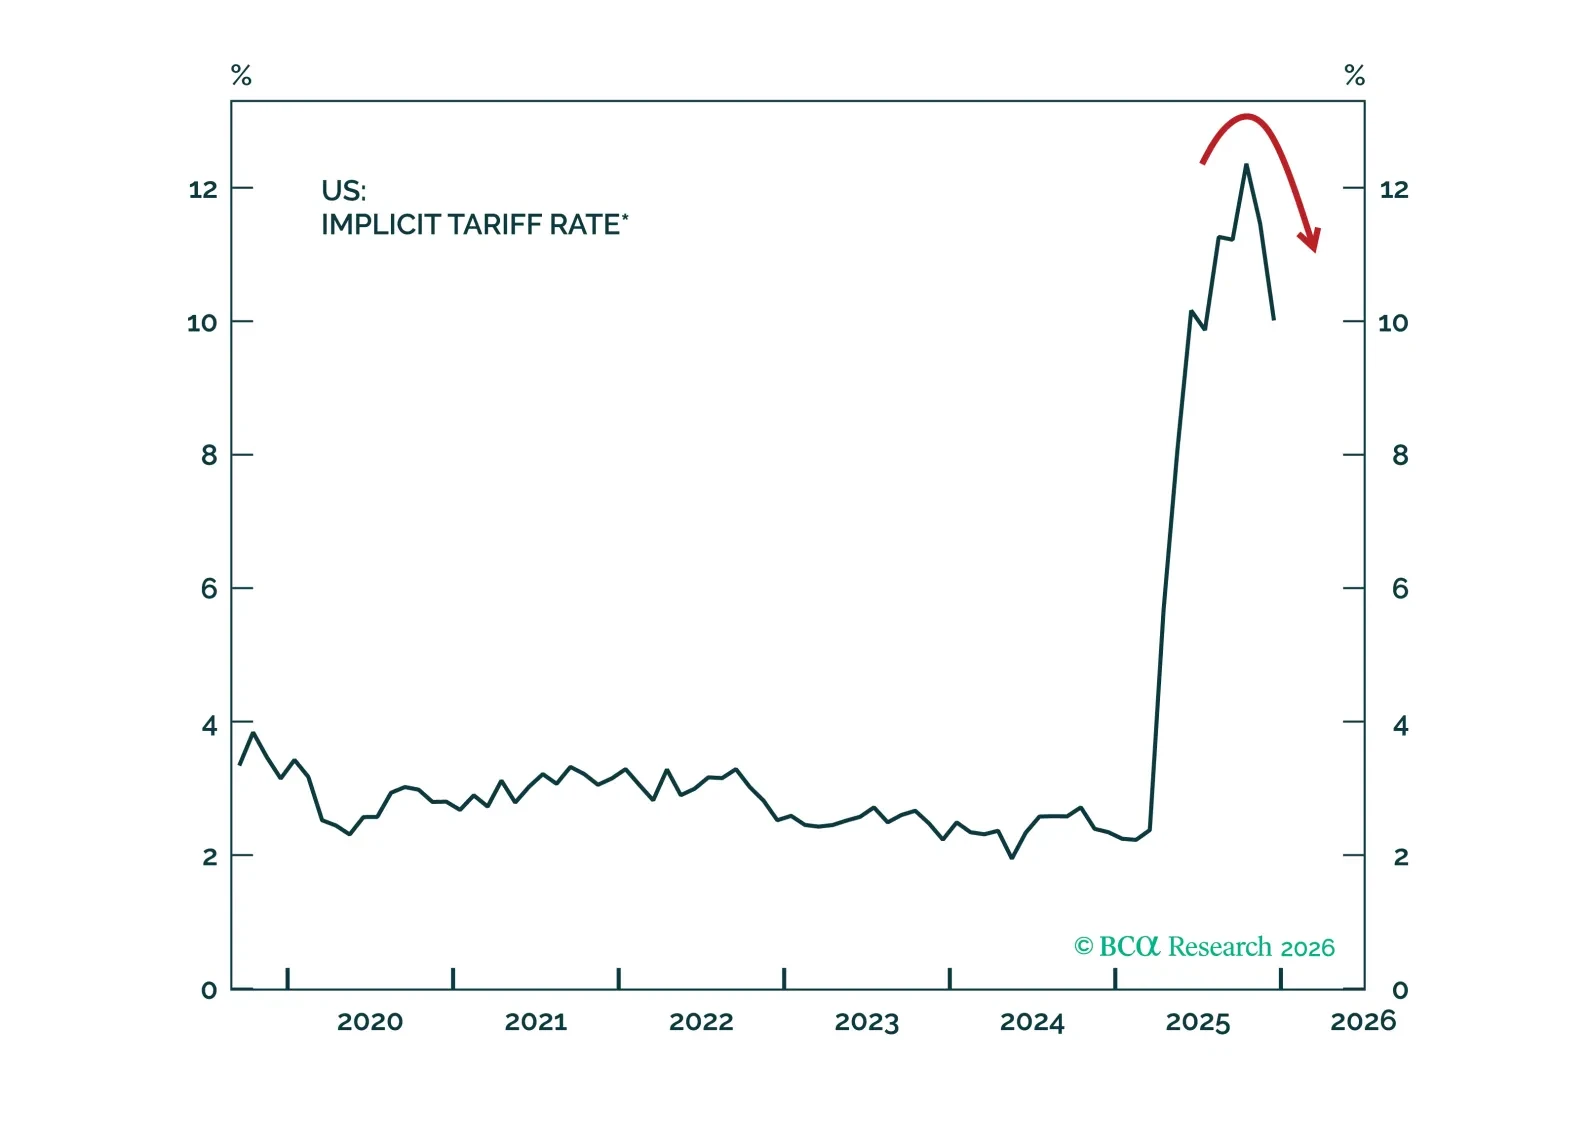
The Section 122 tariffs under the US Trade Act of 1974 are more favorable to Europe; the trade-weighted tariff rate falls to 10.45%, from 11.74% pre-ruling. This positive development does not change our overall views on Europe, as we expected lower tariffs ahead of the US midterms.