Skip to main content

Latest from BCA Research
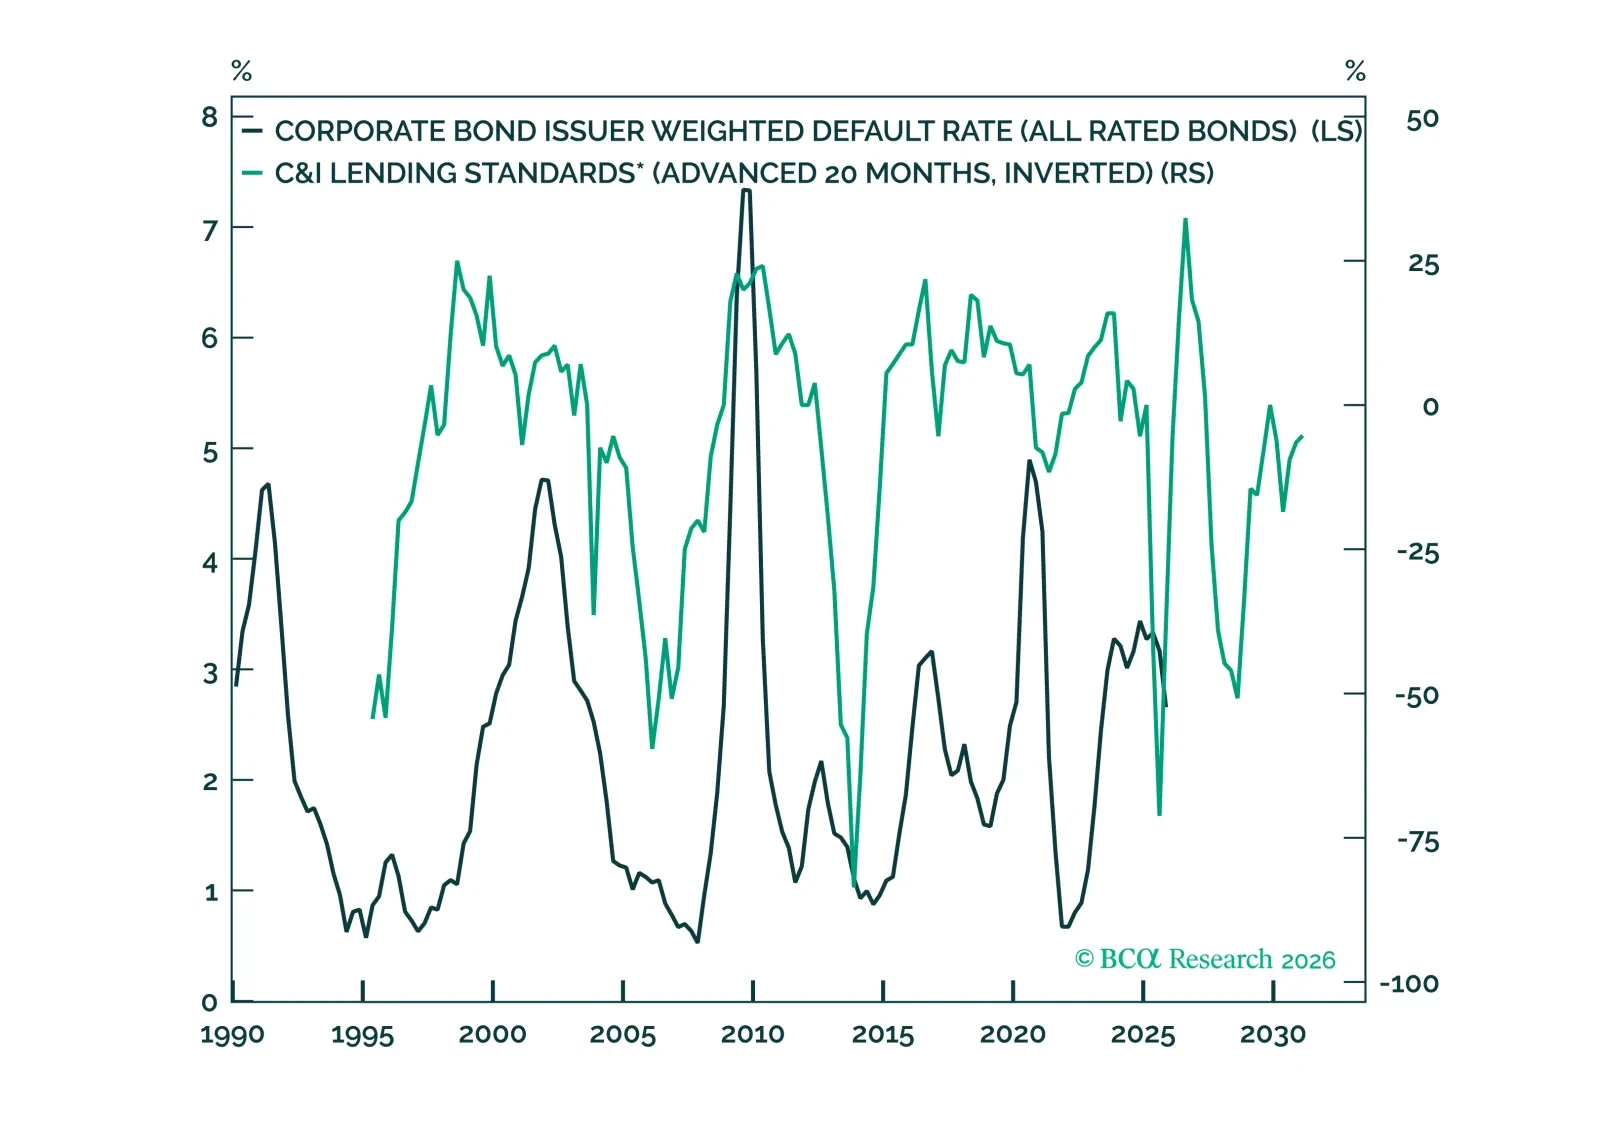
The turmoil in private credit is a wild card, but our traditional suite of credit cycle indicators does not point to an imminent spread-widening episode. We reiterate our benchmark weightings on Treasuries, investment-grade and high-yield corporate bonds.
The fog of war is the thickest at the dawn of kinetic action. However, BCA’s GeoMacro Strategy has trade recommendations to manage and thus we send this missive despite the significant uncertainty.
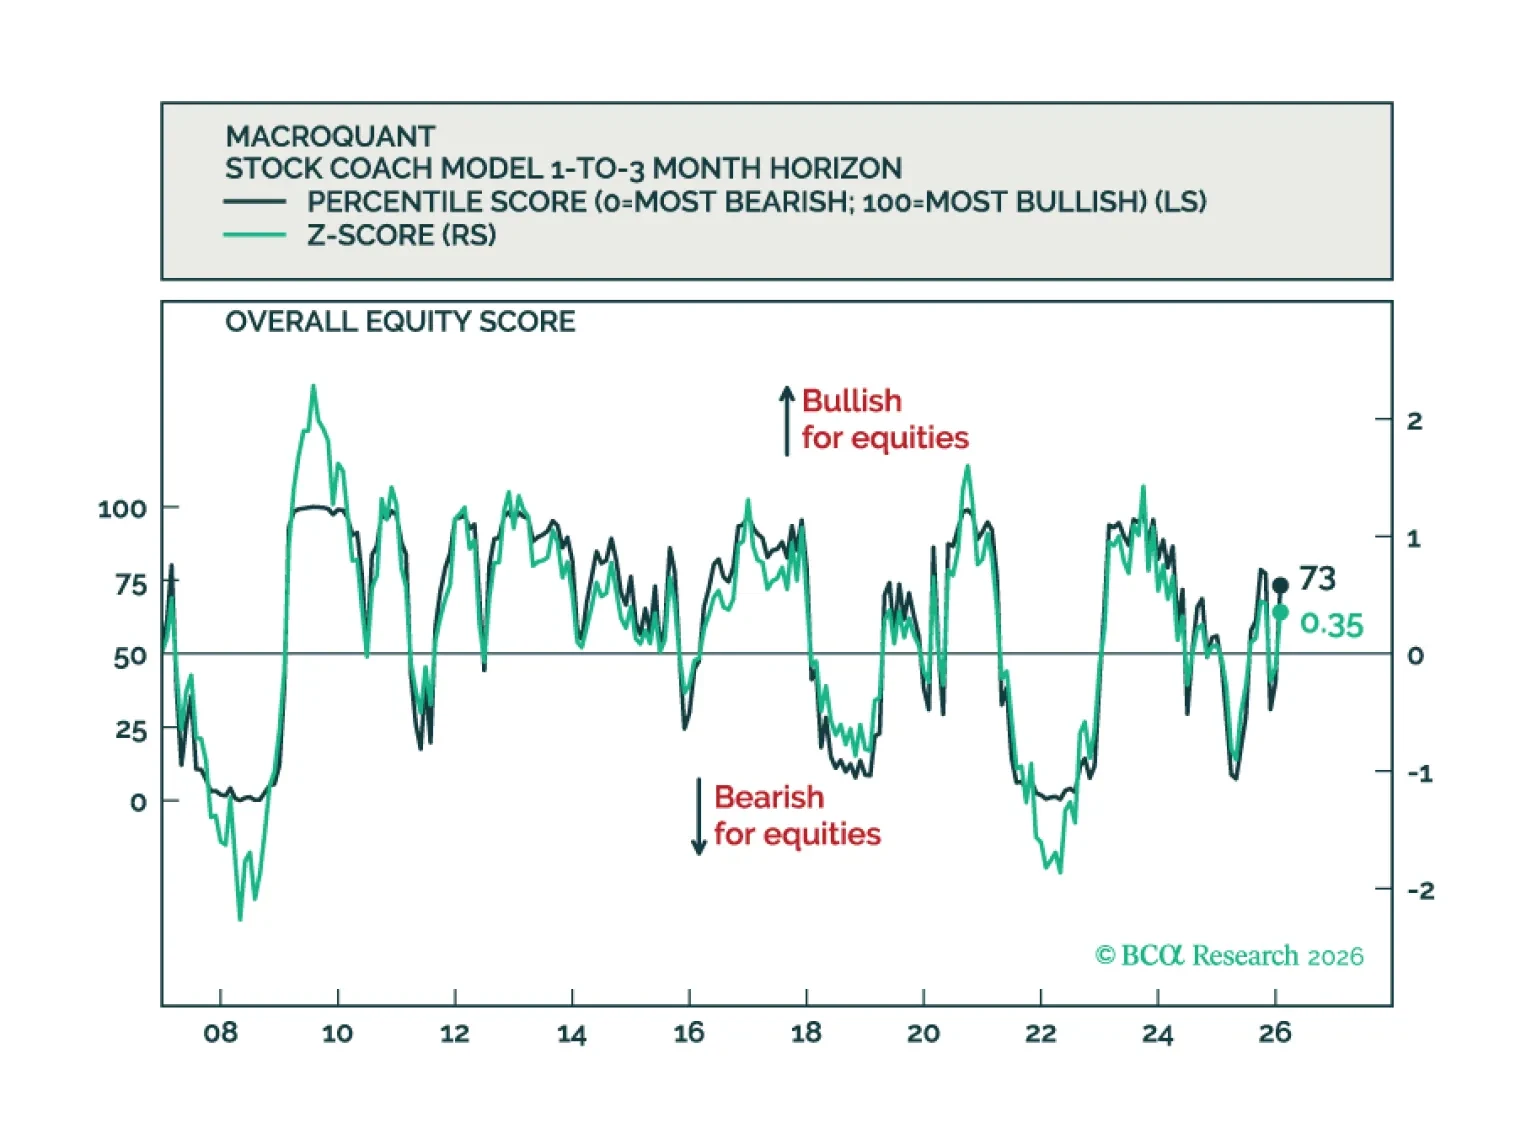
MacroQuant recommends a modest overweight position in equities, favors an above-benchmark duration stance in fixed-income portfolios, remains bearish on the US dollar, has downgraded oil to neutral, and is bullish on copper and gold.
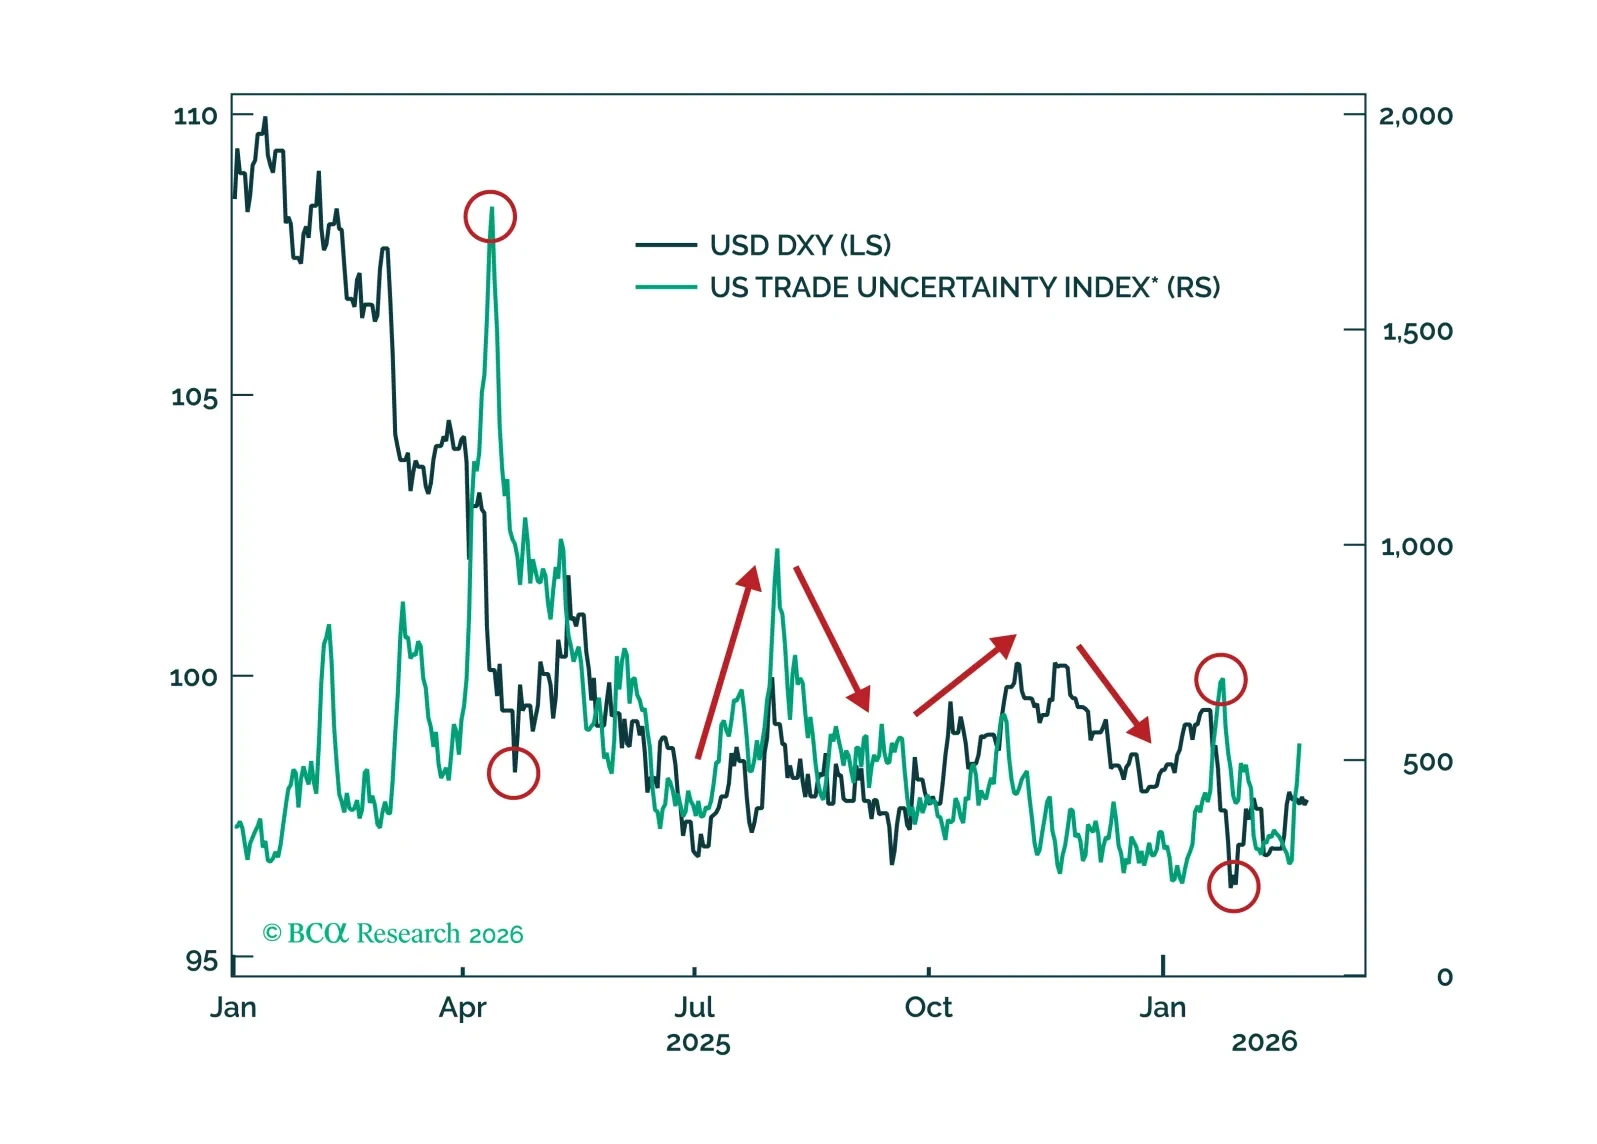
Policy risks are set to fade just as markets underestimate hawkish Fed repricing and crowd into short-USD positions, setting the stage for a tactical dollar rebound into the election cycle. Go long USD/CHF to capture the rate differential and receding policy uncertainty.
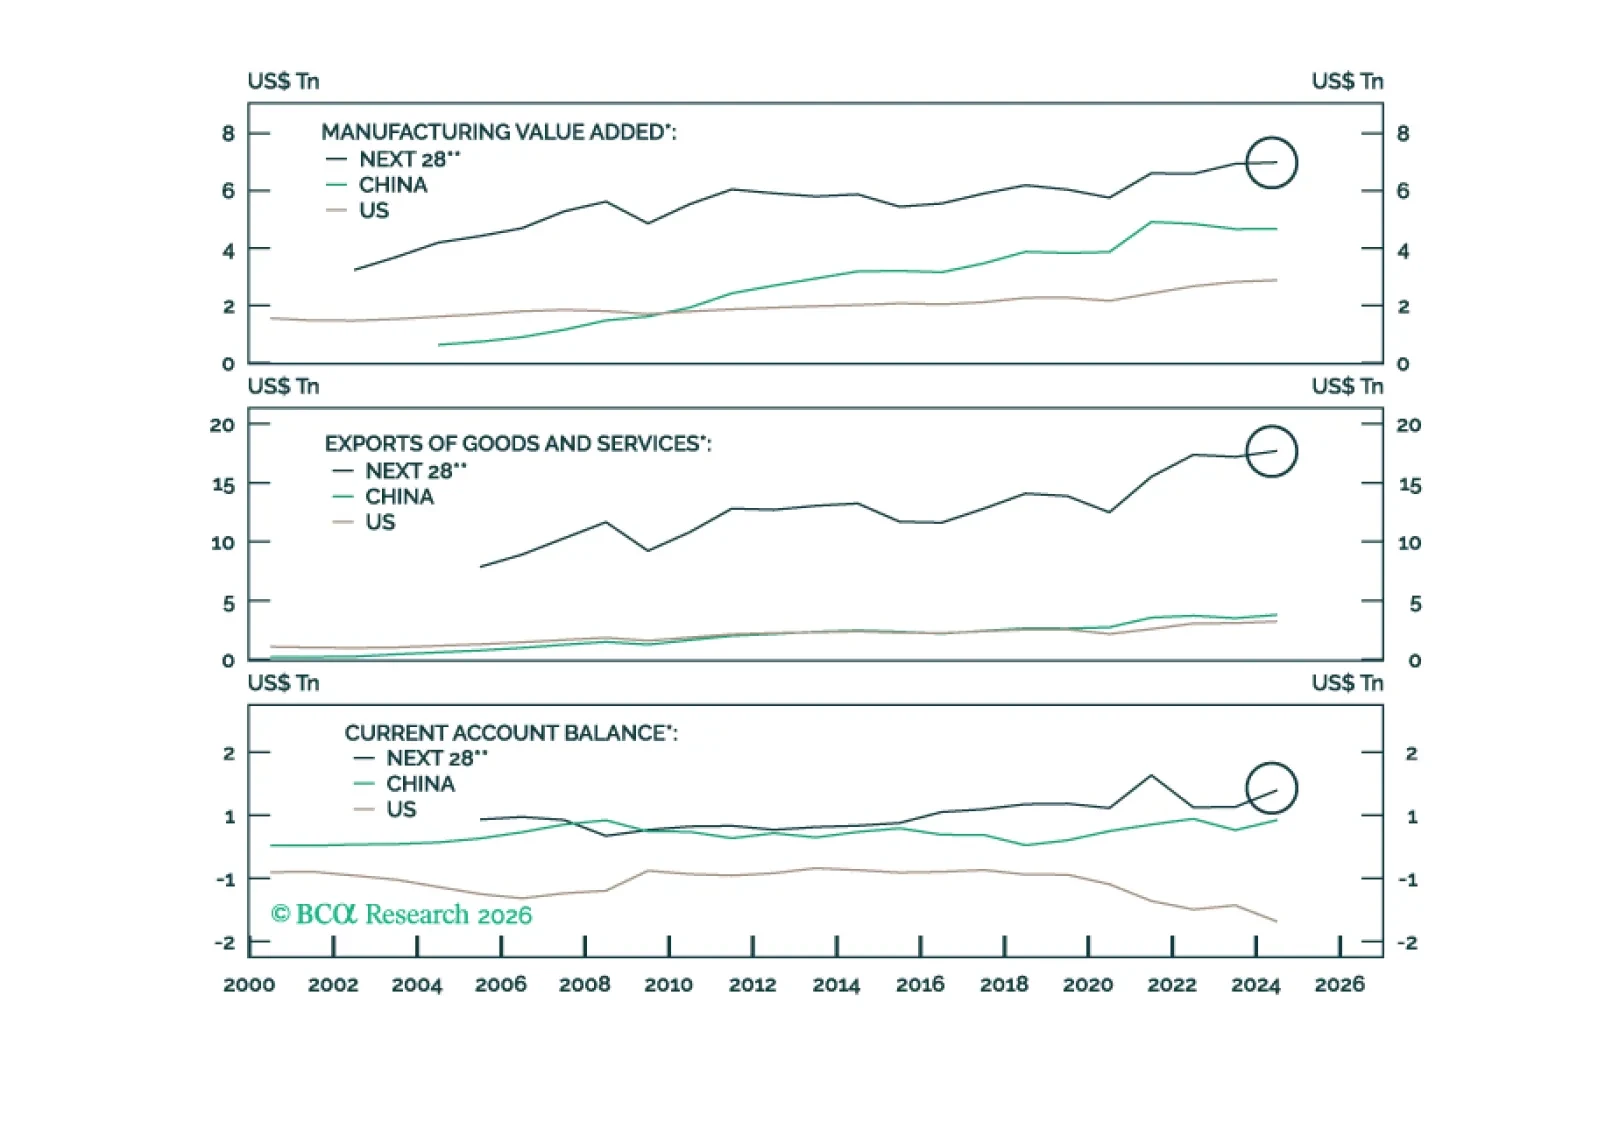
Bank Credit Analyst In Section II, Jesse ranks middle economic powers across hard and soft power dimensions and recommends investing in their defense and industrial sectors.
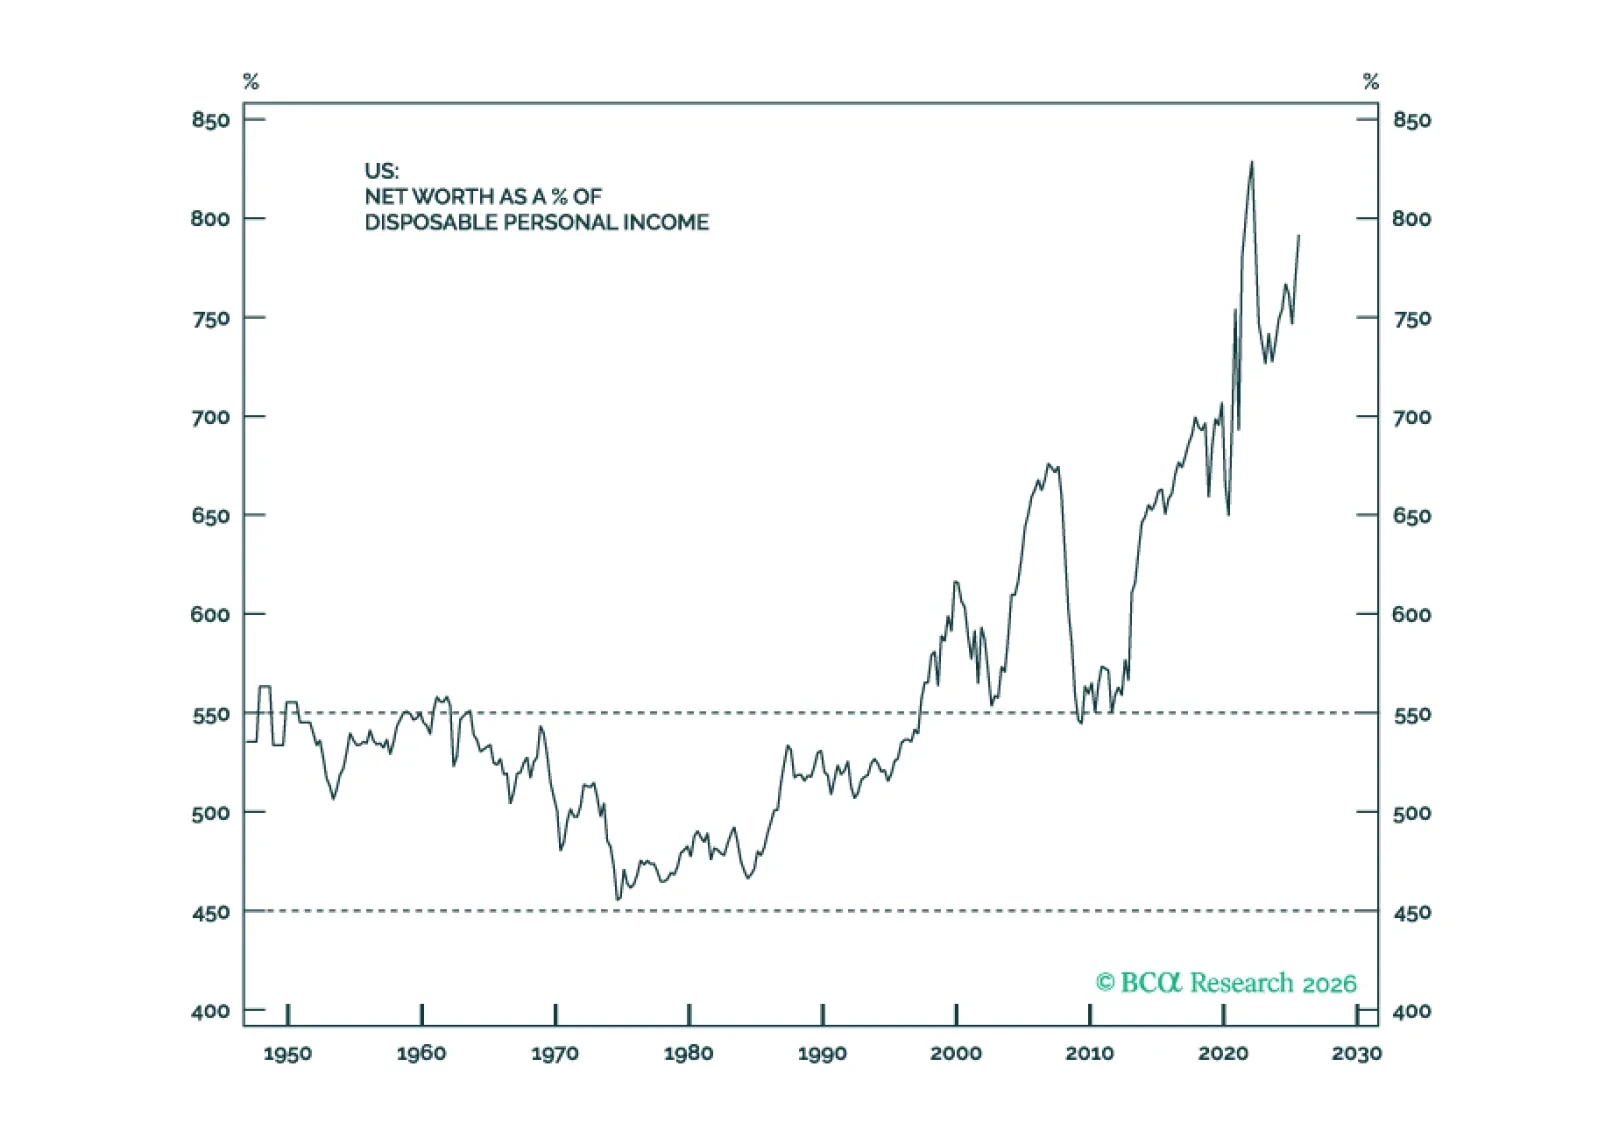
Bank Credit Analyst In Section I, Doug recommends cutting US equity exposure in favor of Europe as reduced recession odds make it unlikely that the US will draw safe-haven capital flows. In Section II, Jesse ranks middle economic powers across hard and soft power dimensions and recommends investing in their defense and industrial sectors.
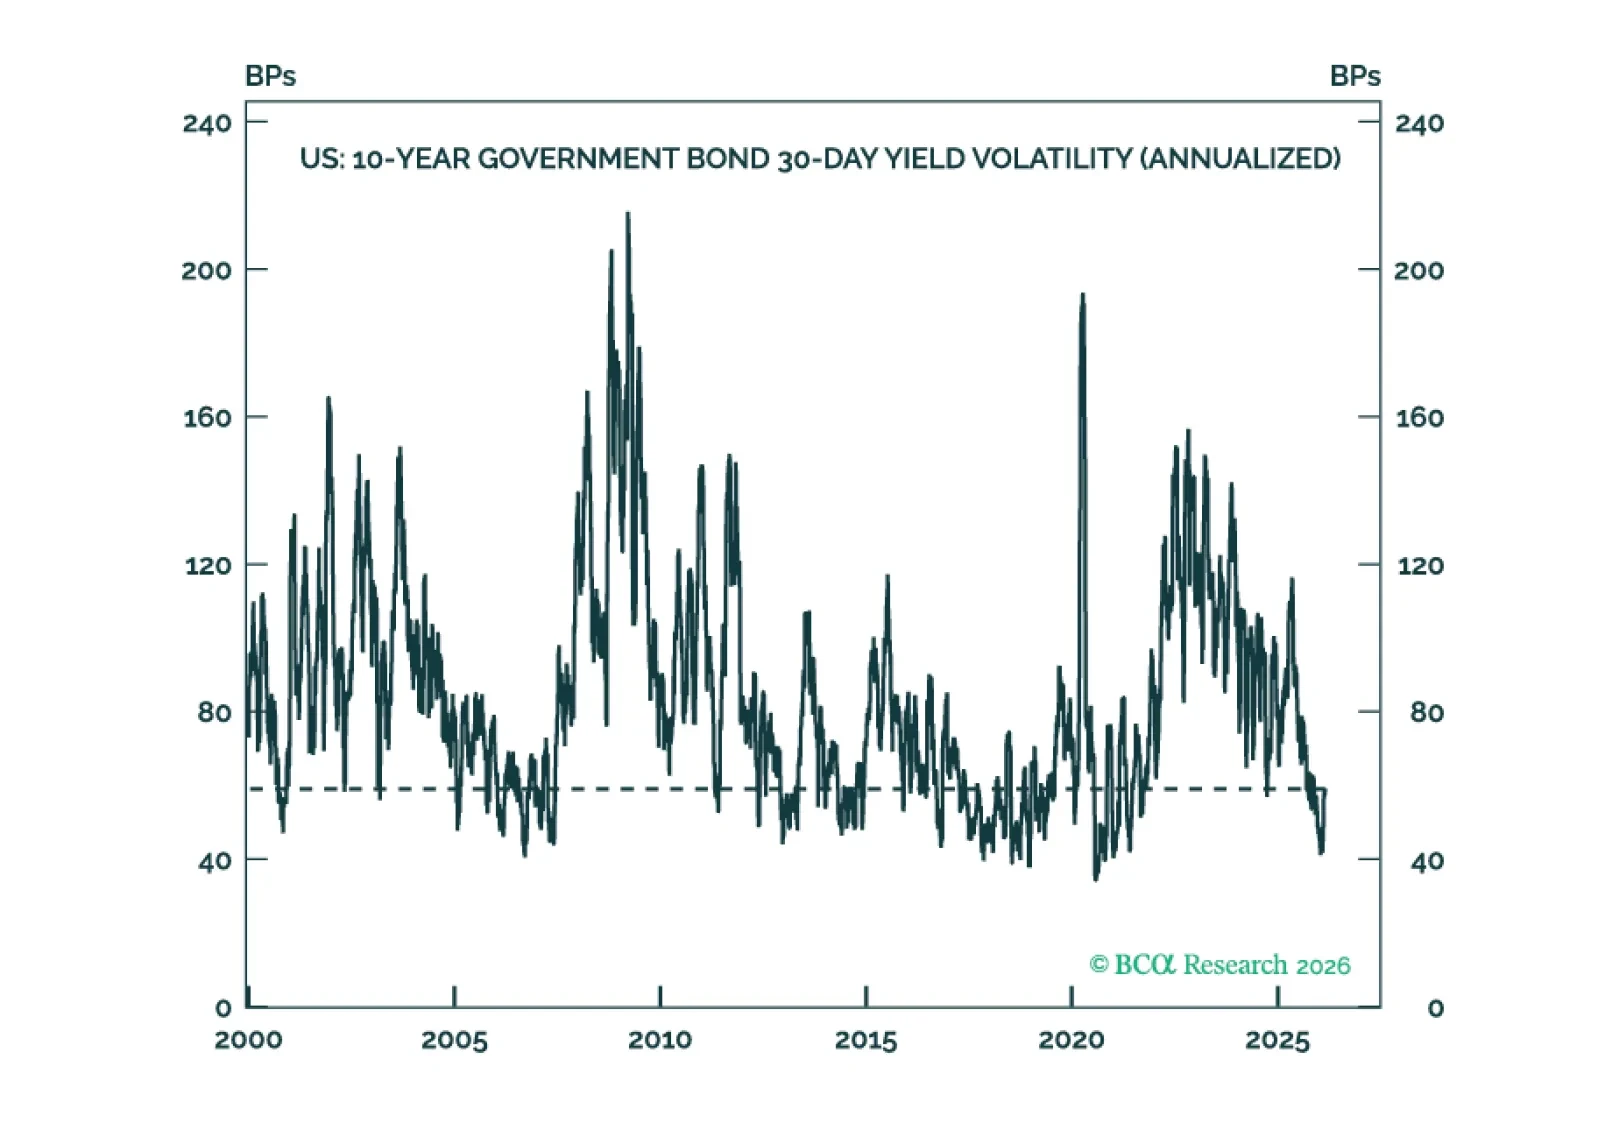
Special Report Interest rate volatility is very low across developed market fixed income. Investors should maximize the carry in their portfolios to outperform in a low rate vol environment.
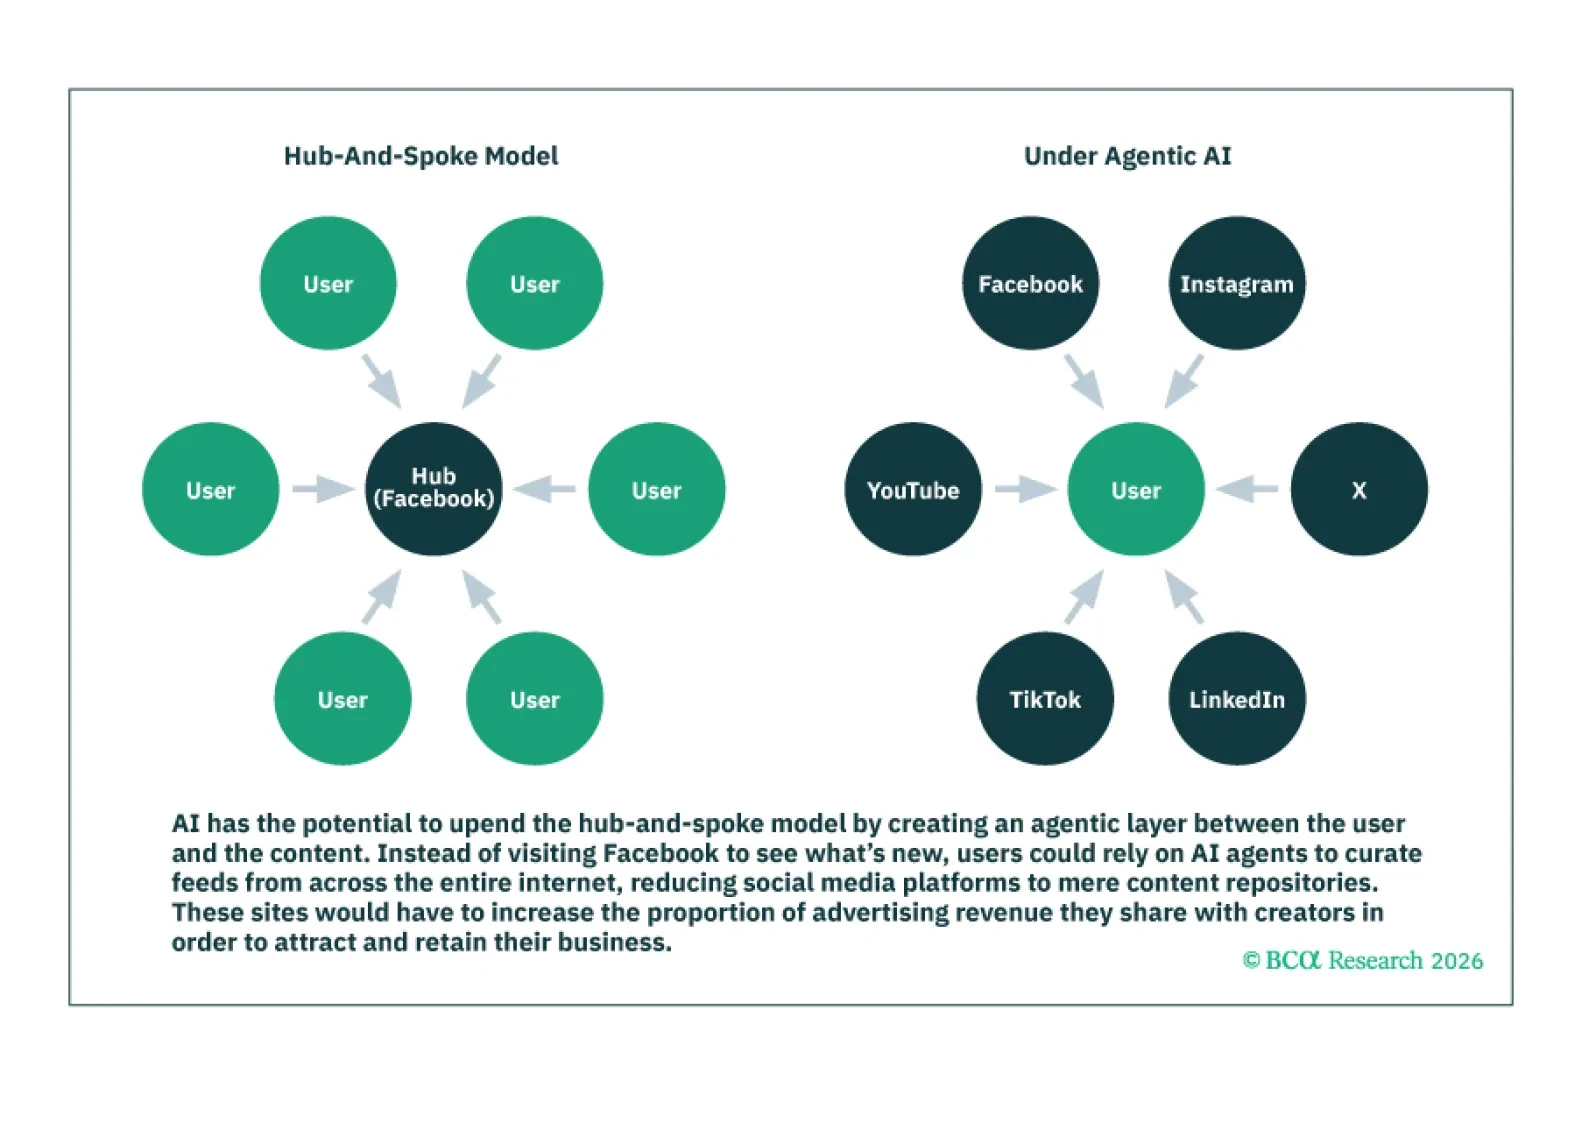
Special Report Tech companies have historically generated profits from three main sources: 1) economies of scale; 2) network effects; and 3) proprietary technologies. AI threatens to undercut all three sources.
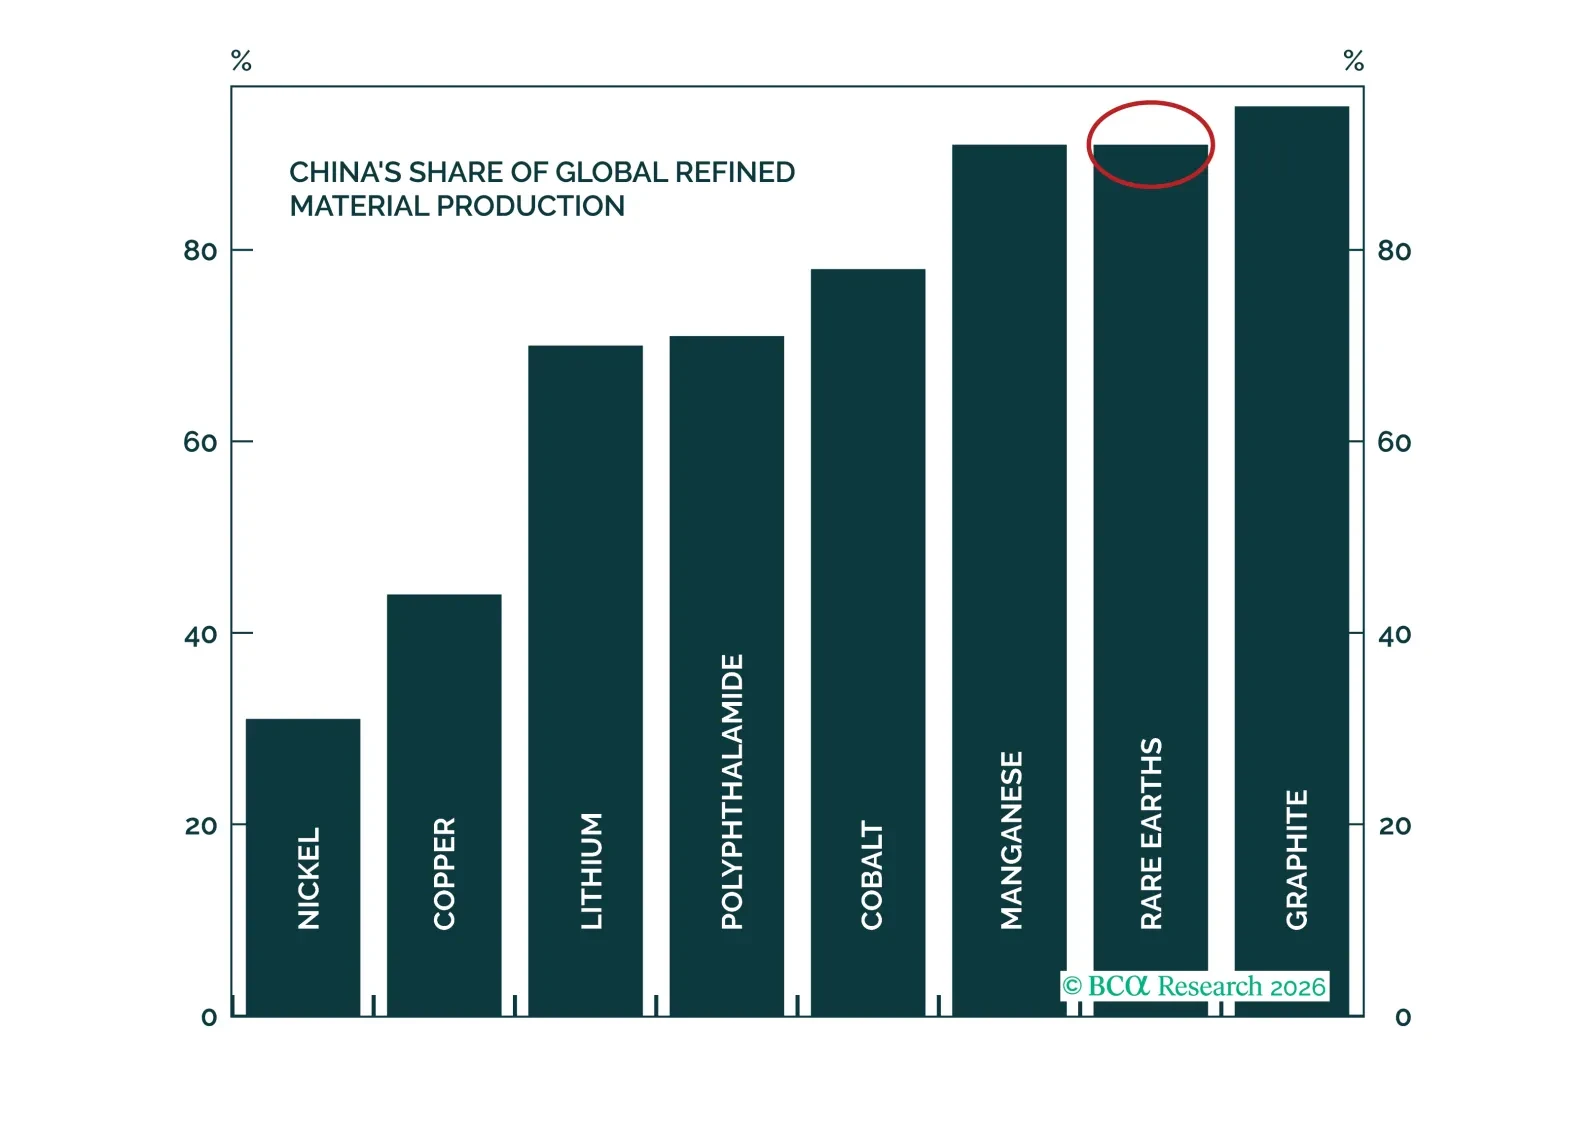
Special Report The global drive to build a resilient ex-China rare earth supply chain is accelerating. It has emerged as a strategic priority and is backed by both public and private sector investment in many countries. In this Special Report, we argue that rare earth adjacent plays present a more attractive opportunity for investors looking to gain exposure to the rare earth capex cycle than a pure-play strategy.
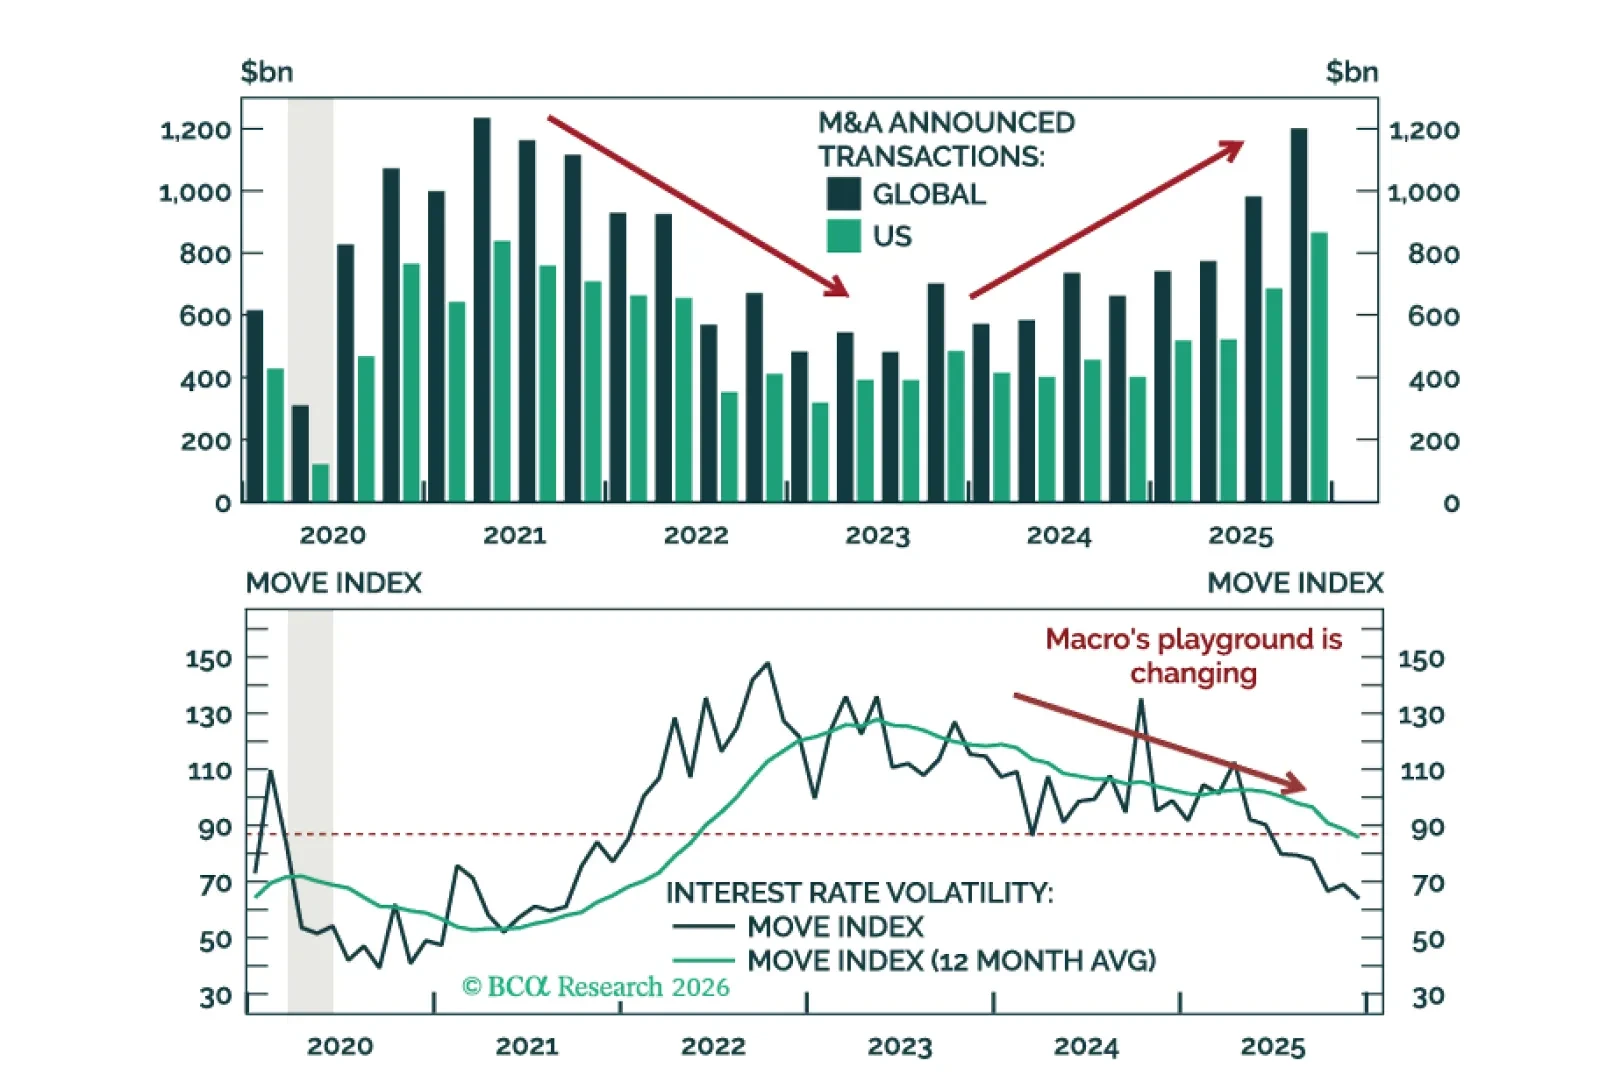
M&A activity finally reaccelerated in Q4 2025—it’s just the start. Macro Hedge Funds have outperformed with top-decile performance from Discretionary Macro—but that’s towards the end. We move Macro from overweight to underweight and Event Driven from neutral to overweight.