Latest from BCA Research
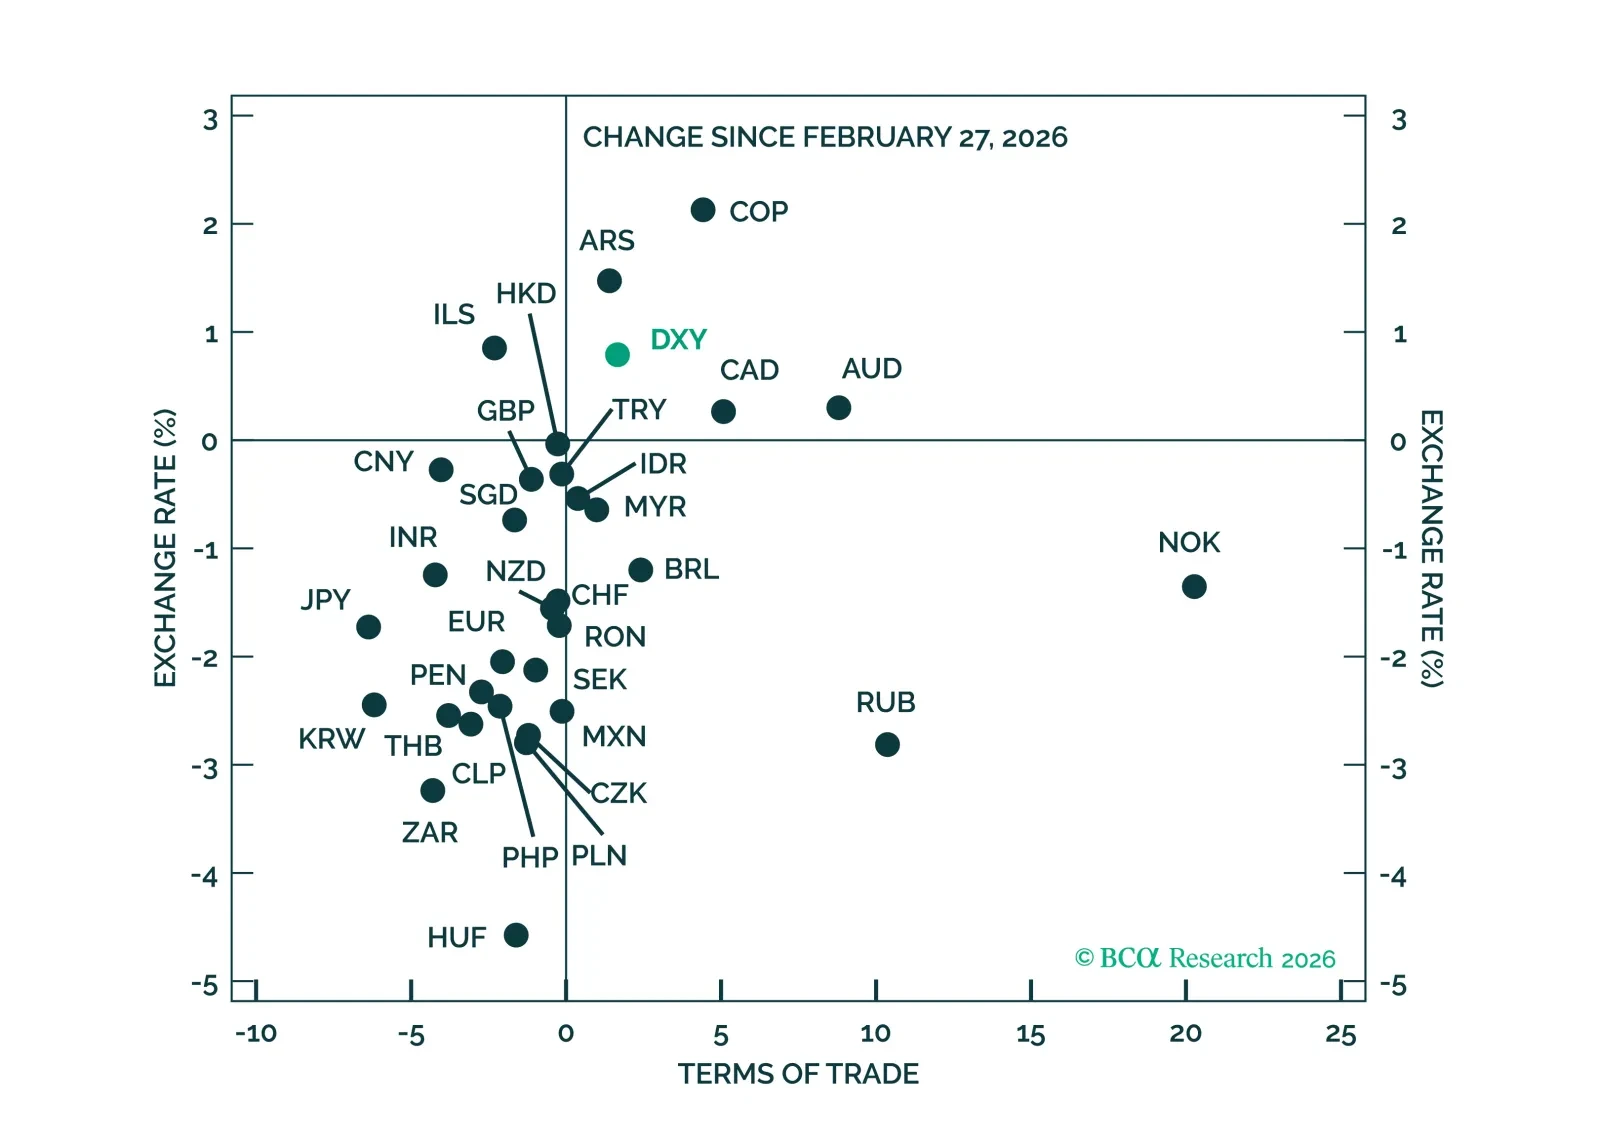
The Iran war remains a terms-of-trade shock rather than a classic flight to safety – for now. As oil risks skew higher, policy repricing and growth differentials should continue to favor a tactical rebound in the USD.
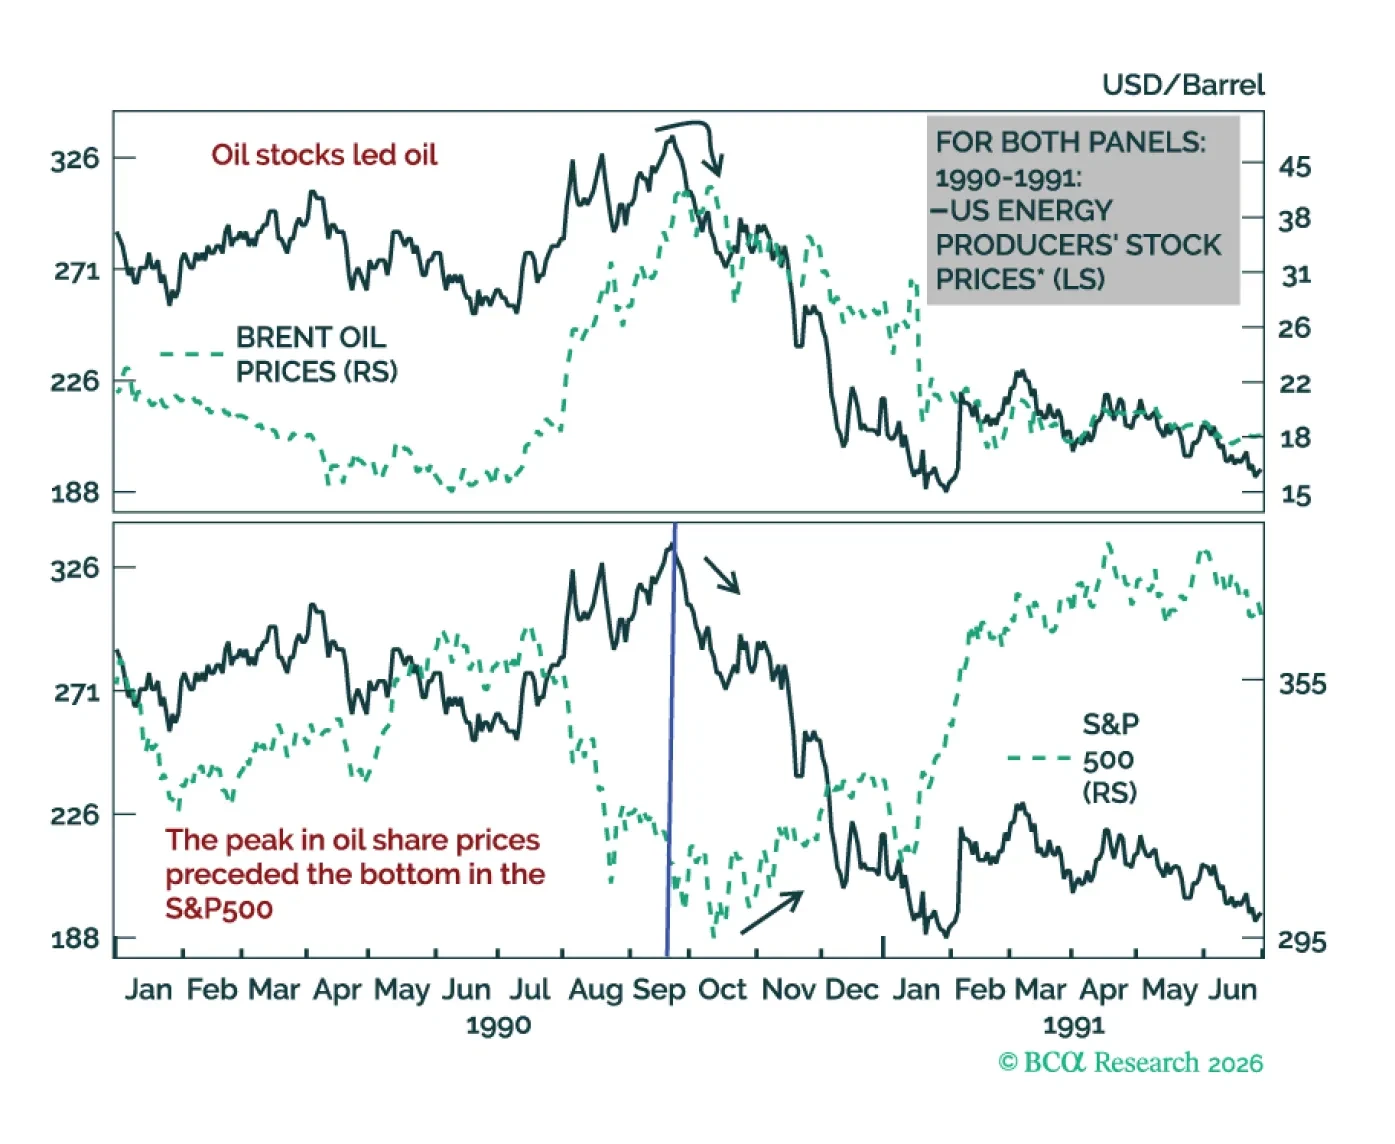
Oil prices will likely rise in the near term, irrespective of developments in the Strait of Hormuz. Given that global share prices have become correlated with crude prices, global stocks will continue selling off. Go short the EM equity index and take profits on our open trades that have benefited from the global risk-on environment.
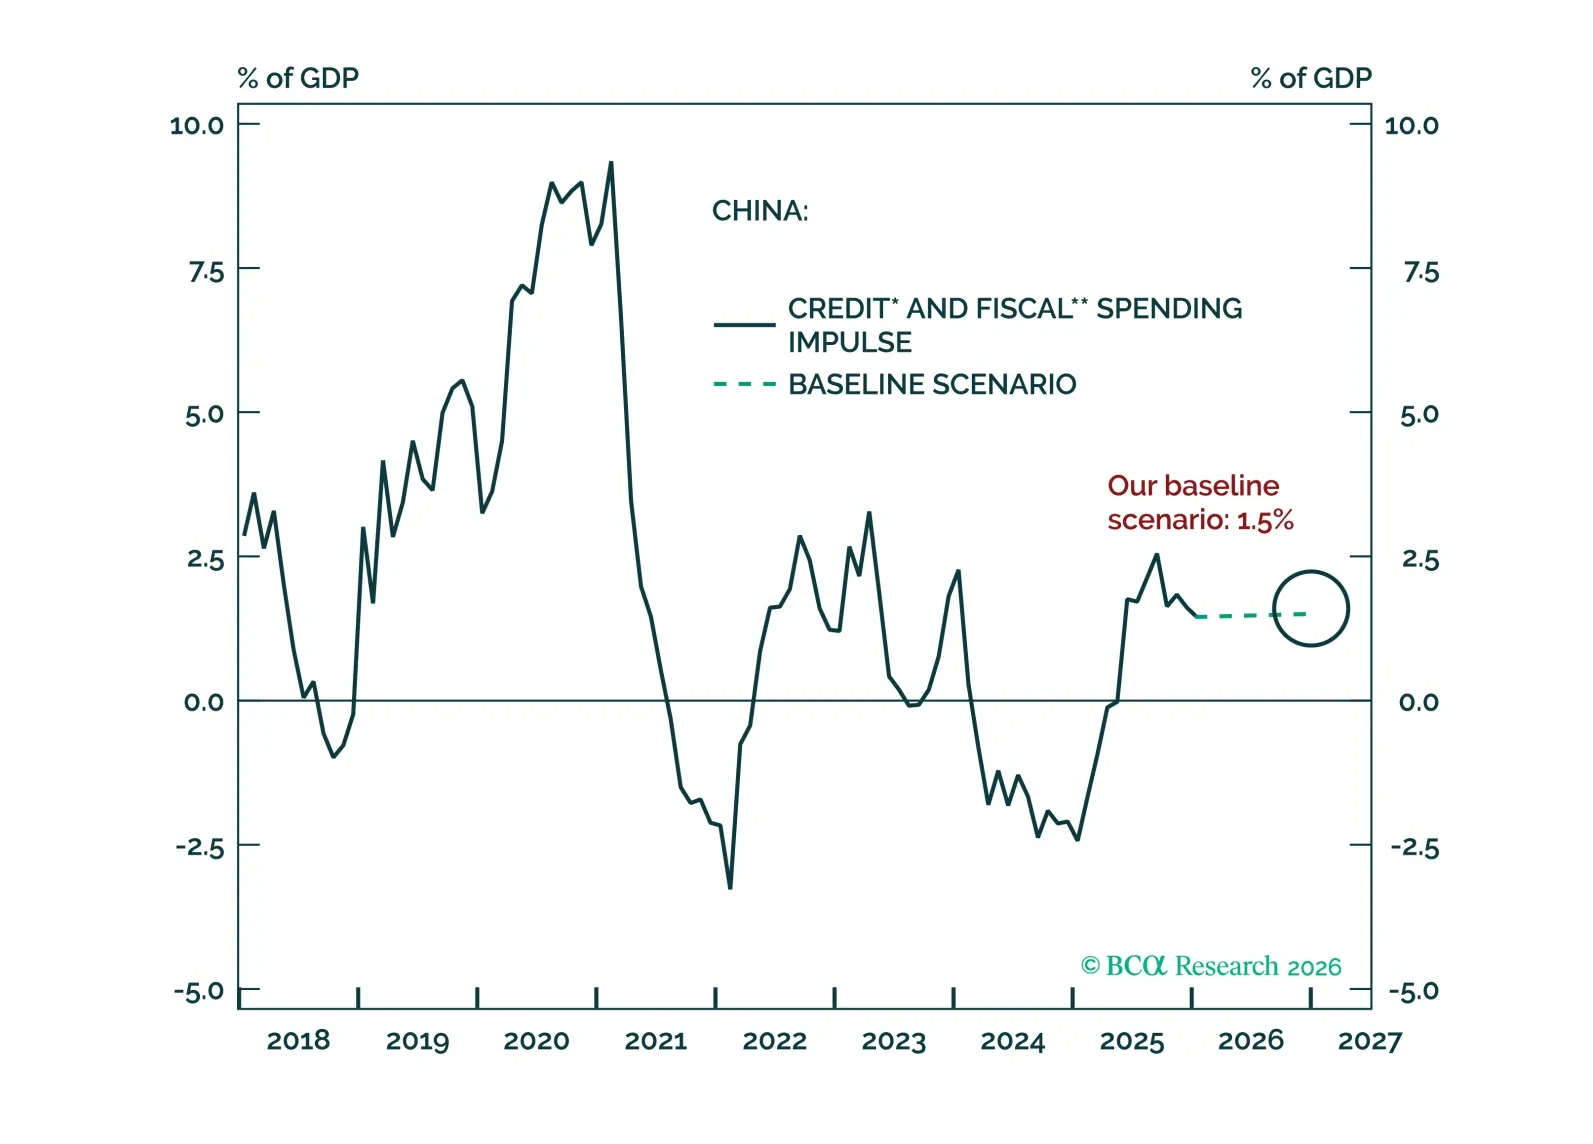
This report unpacks this year’s uneventful NPC, reading the tea leaves of key messages and offering insights on the impact of rising oil prices on China.
Drone and ballistic missile attacks were slowing, as of March 11. Air traffic in the region was also slowly recovering, as the pace of attacks declined. Warning, however: Reports from US CENTCOM and the IDF claim that Iran still has around 40% to 50% of its stockpile of missiles and launchers. Attacks are continuing, even though at a reduced tempo.
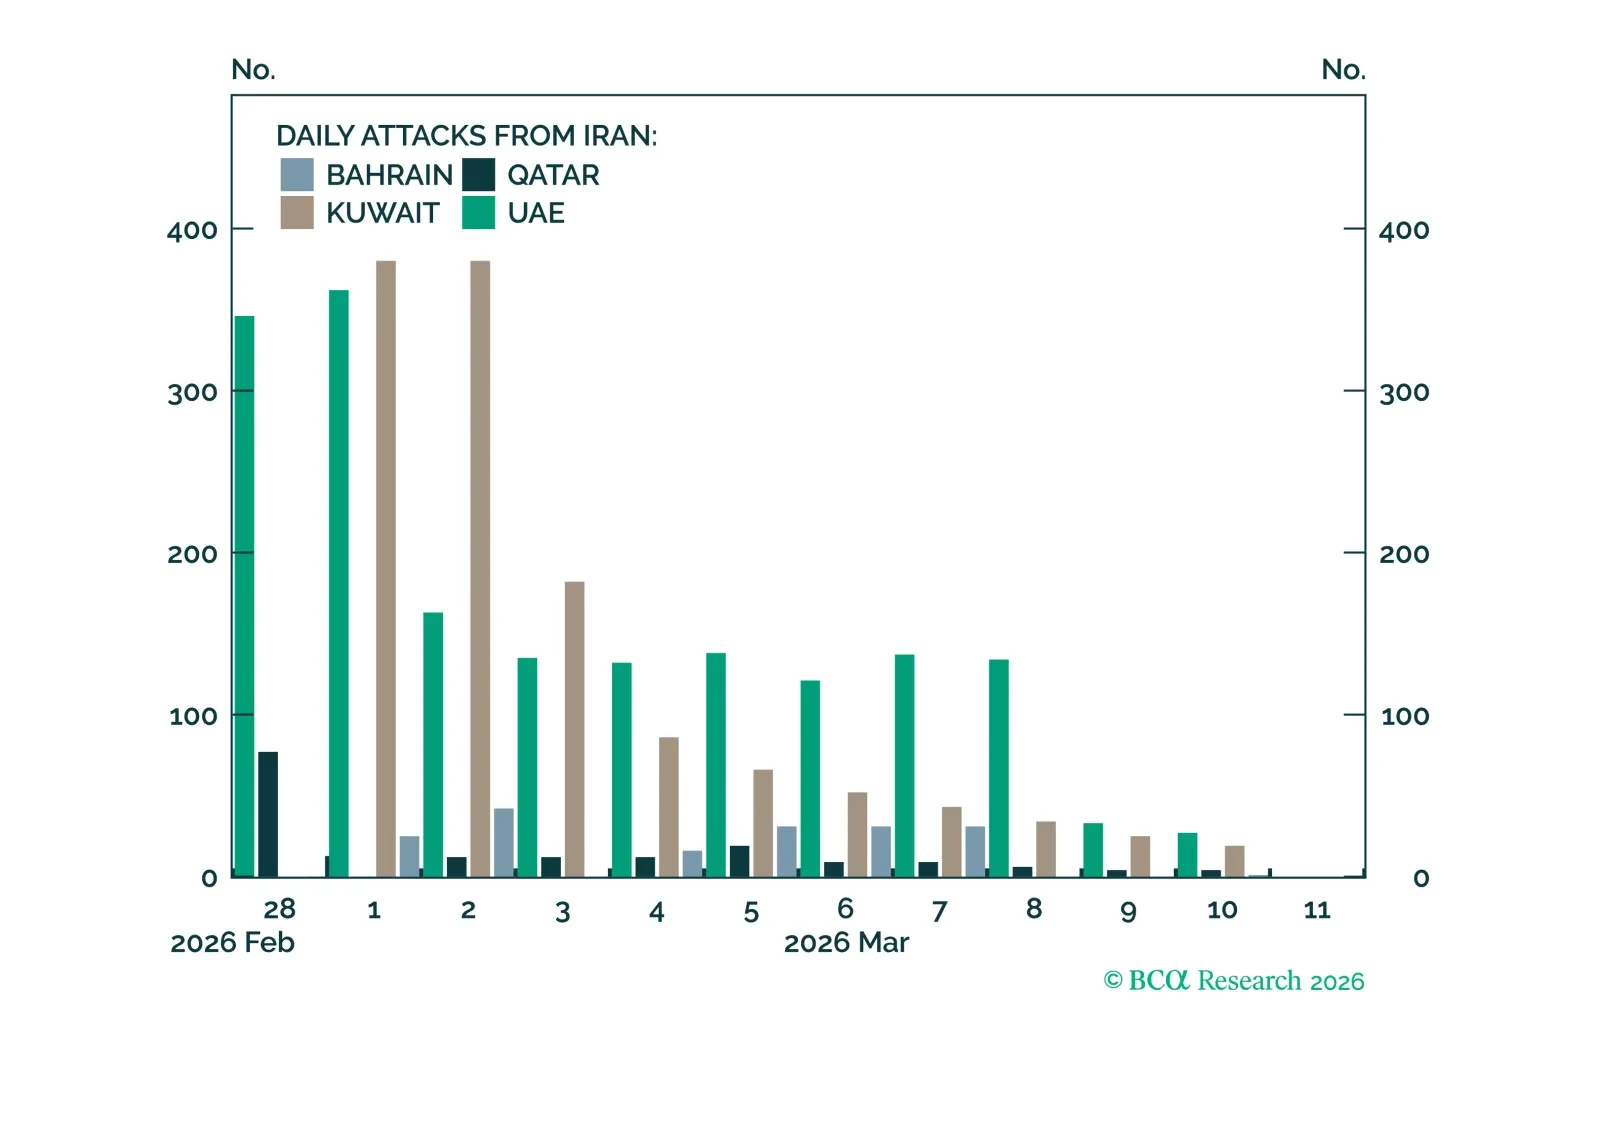
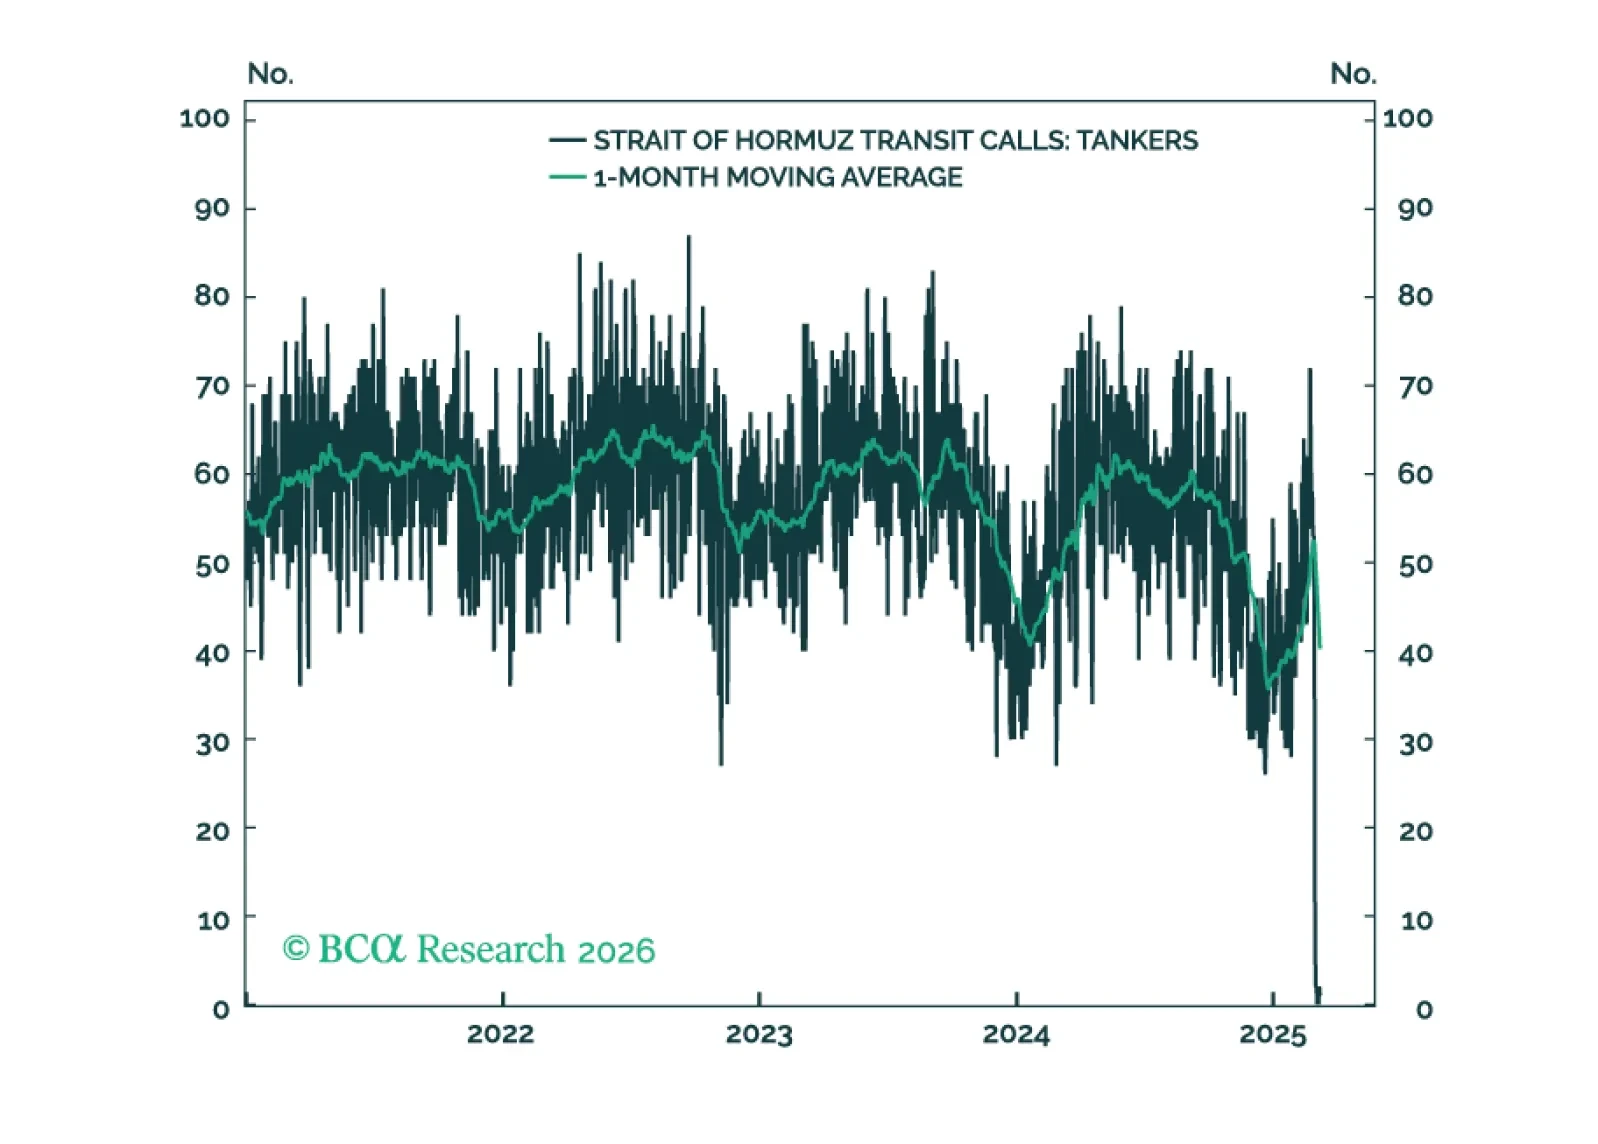
With all eyes on the Strait of Hormuz, BCA Research has created a dashboard of data for your convenience.
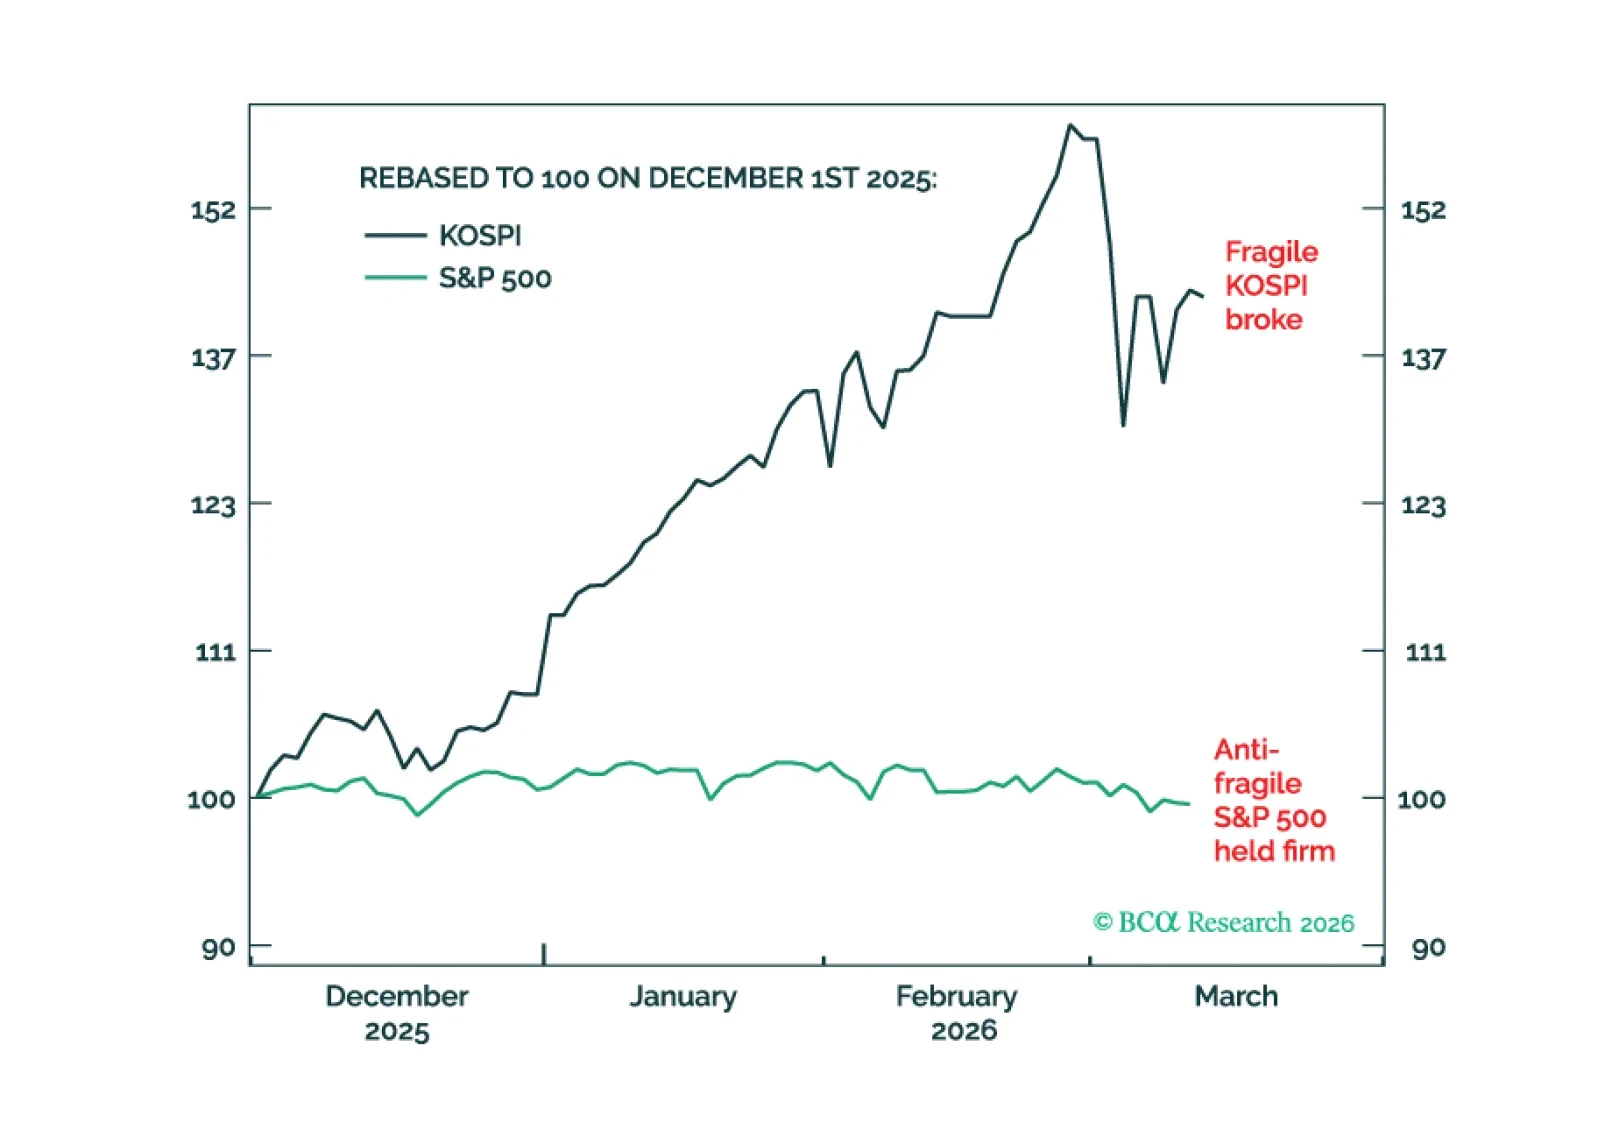
In the ongoing Middle East crisis, anti-fragile markets will remain relatively resilient while fragile markets will break. We describe how to draw the distinction. Plus, a new trade is a 50:50 combination of long USD/MXN and overweight Consumer Discretionary.
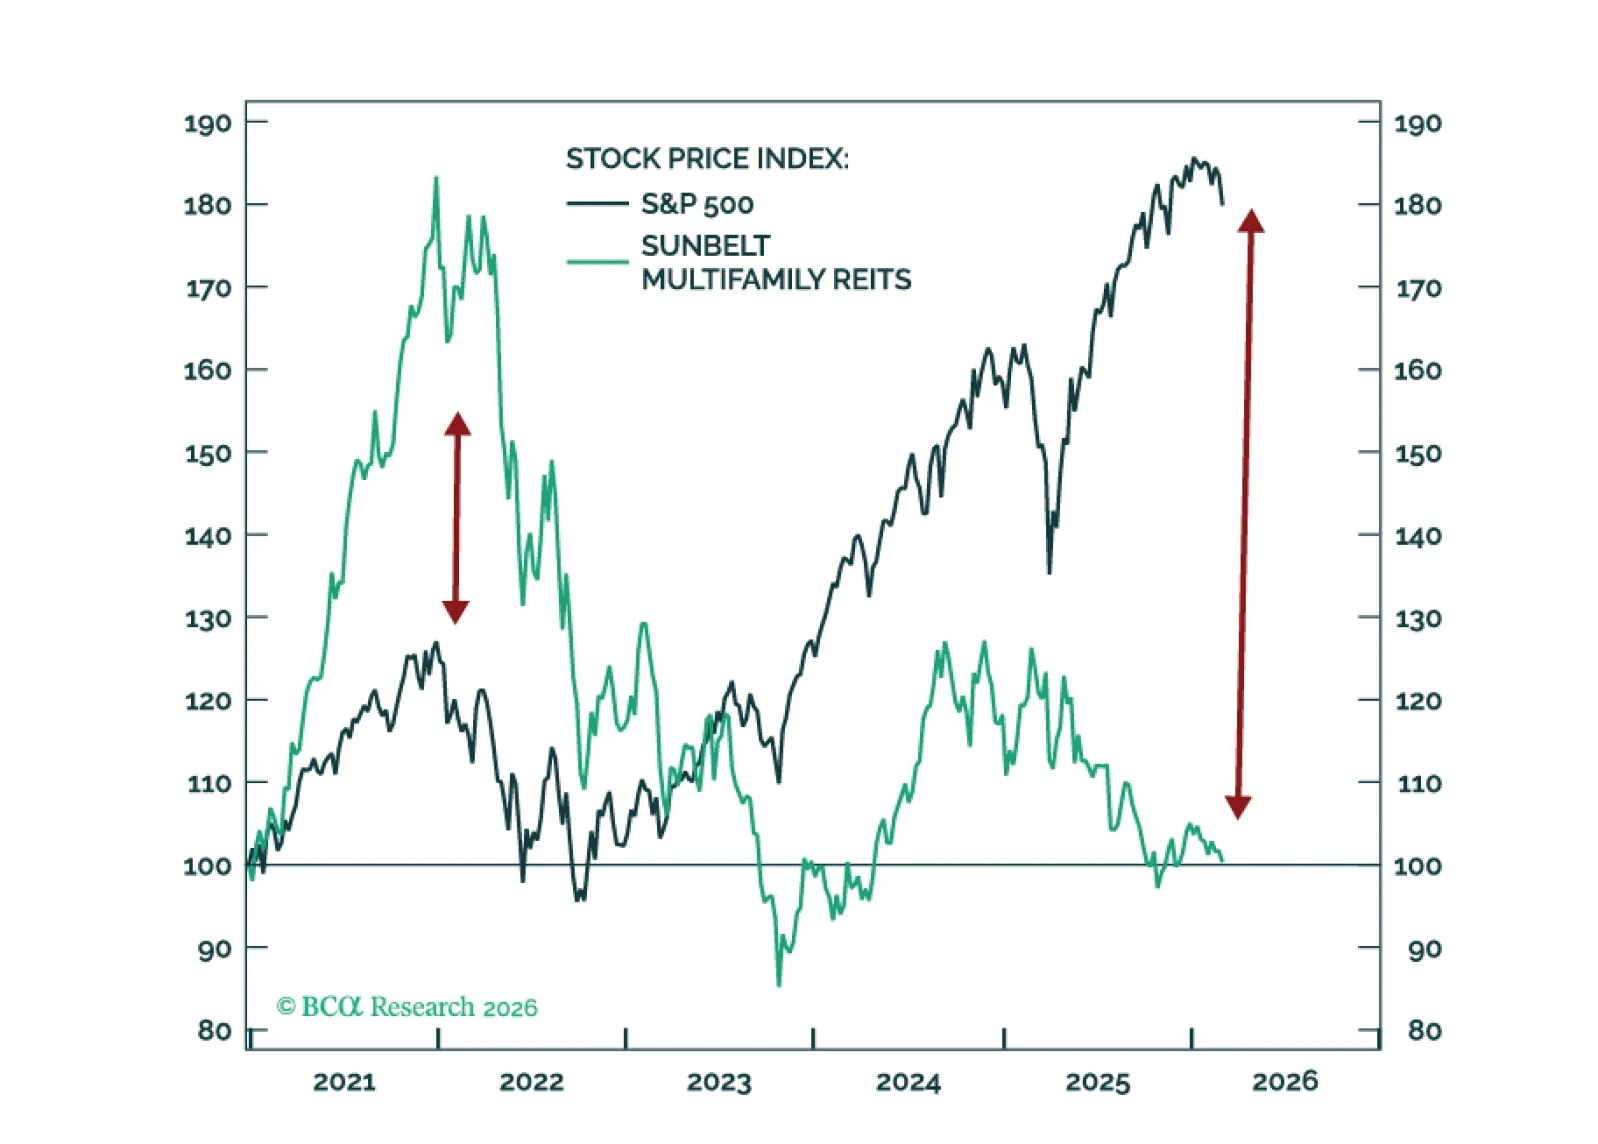
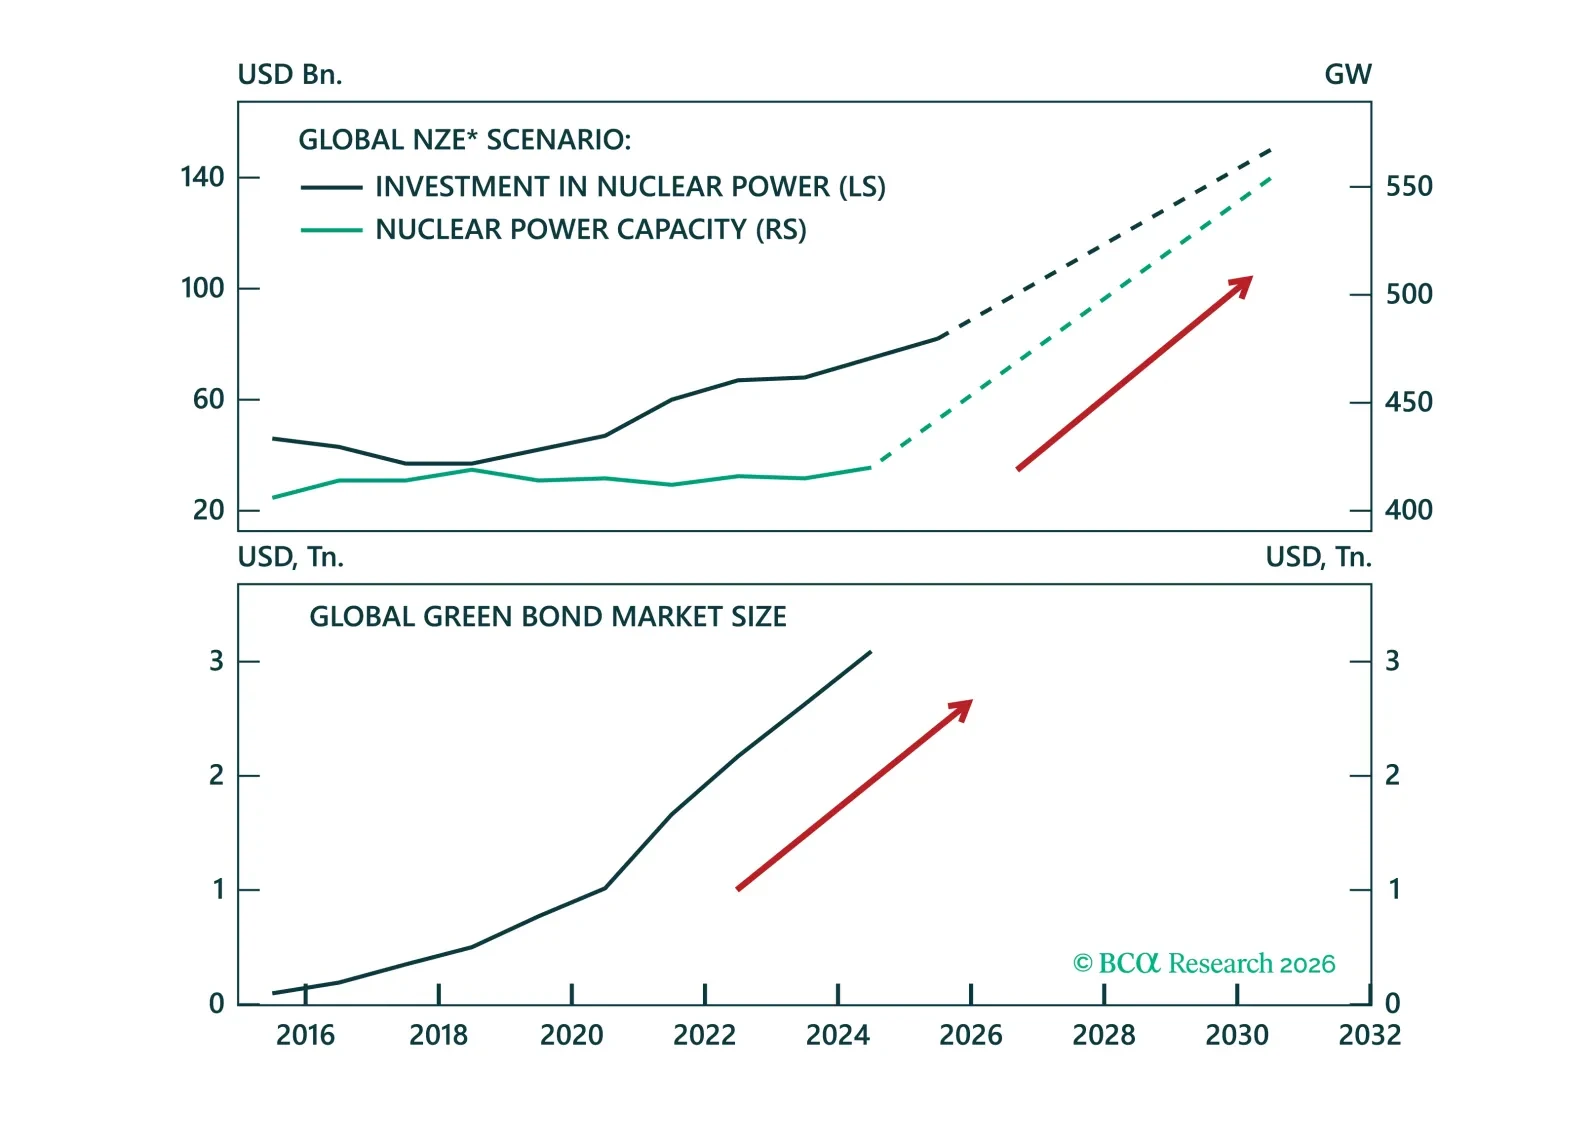

The recent oil price shock reinforces our view that inflation will surprise to the upside during the next few months but fall rapidly in H2 2026.

China's slowdown coincides with at least a minor global oil shock – a combination we have long feared.