GeoMacro
Find out more
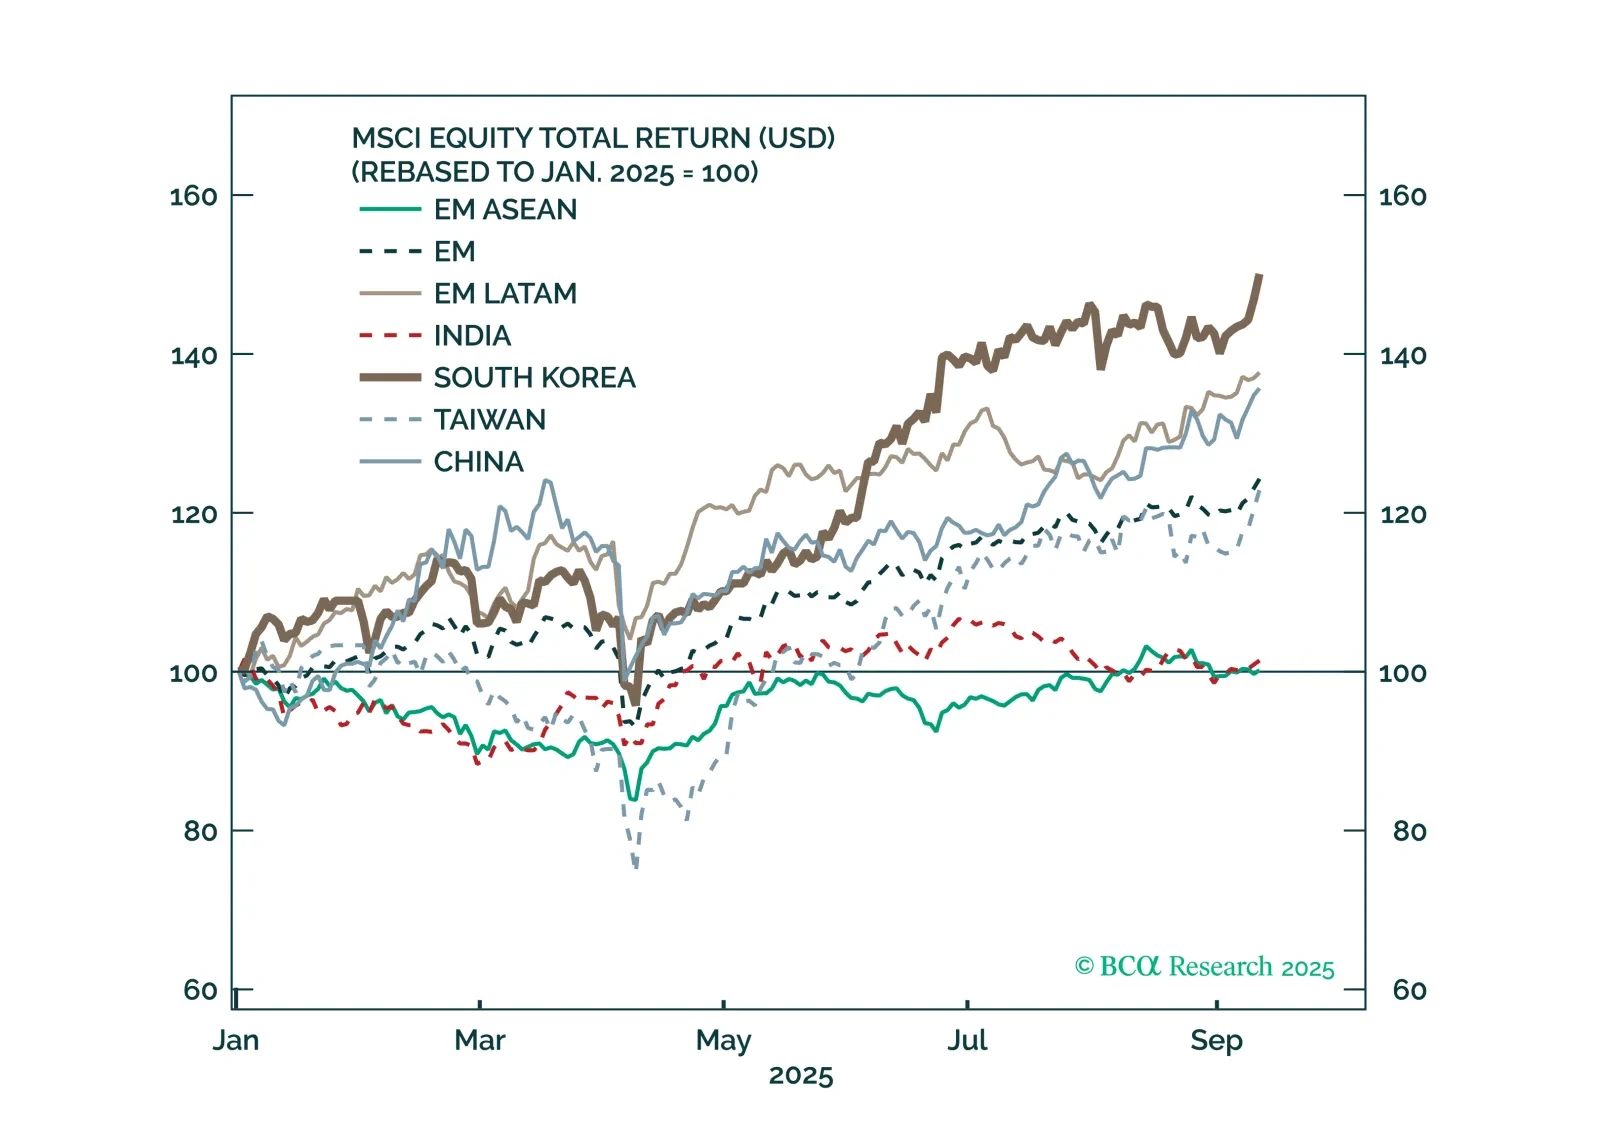
Political instability across Asia is colliding with the trade war fallout, forcing Southeast Asian economies to ease monetary and fiscal policy, while pushing the Bank of Japan in the opposite direction.
Russia’s recalcitrance will probably trigger a near-term global stock market correction by prompting larger sanctions and derailing US-China talks. But Israel’s actions do not raise our odds of a major oil shock.
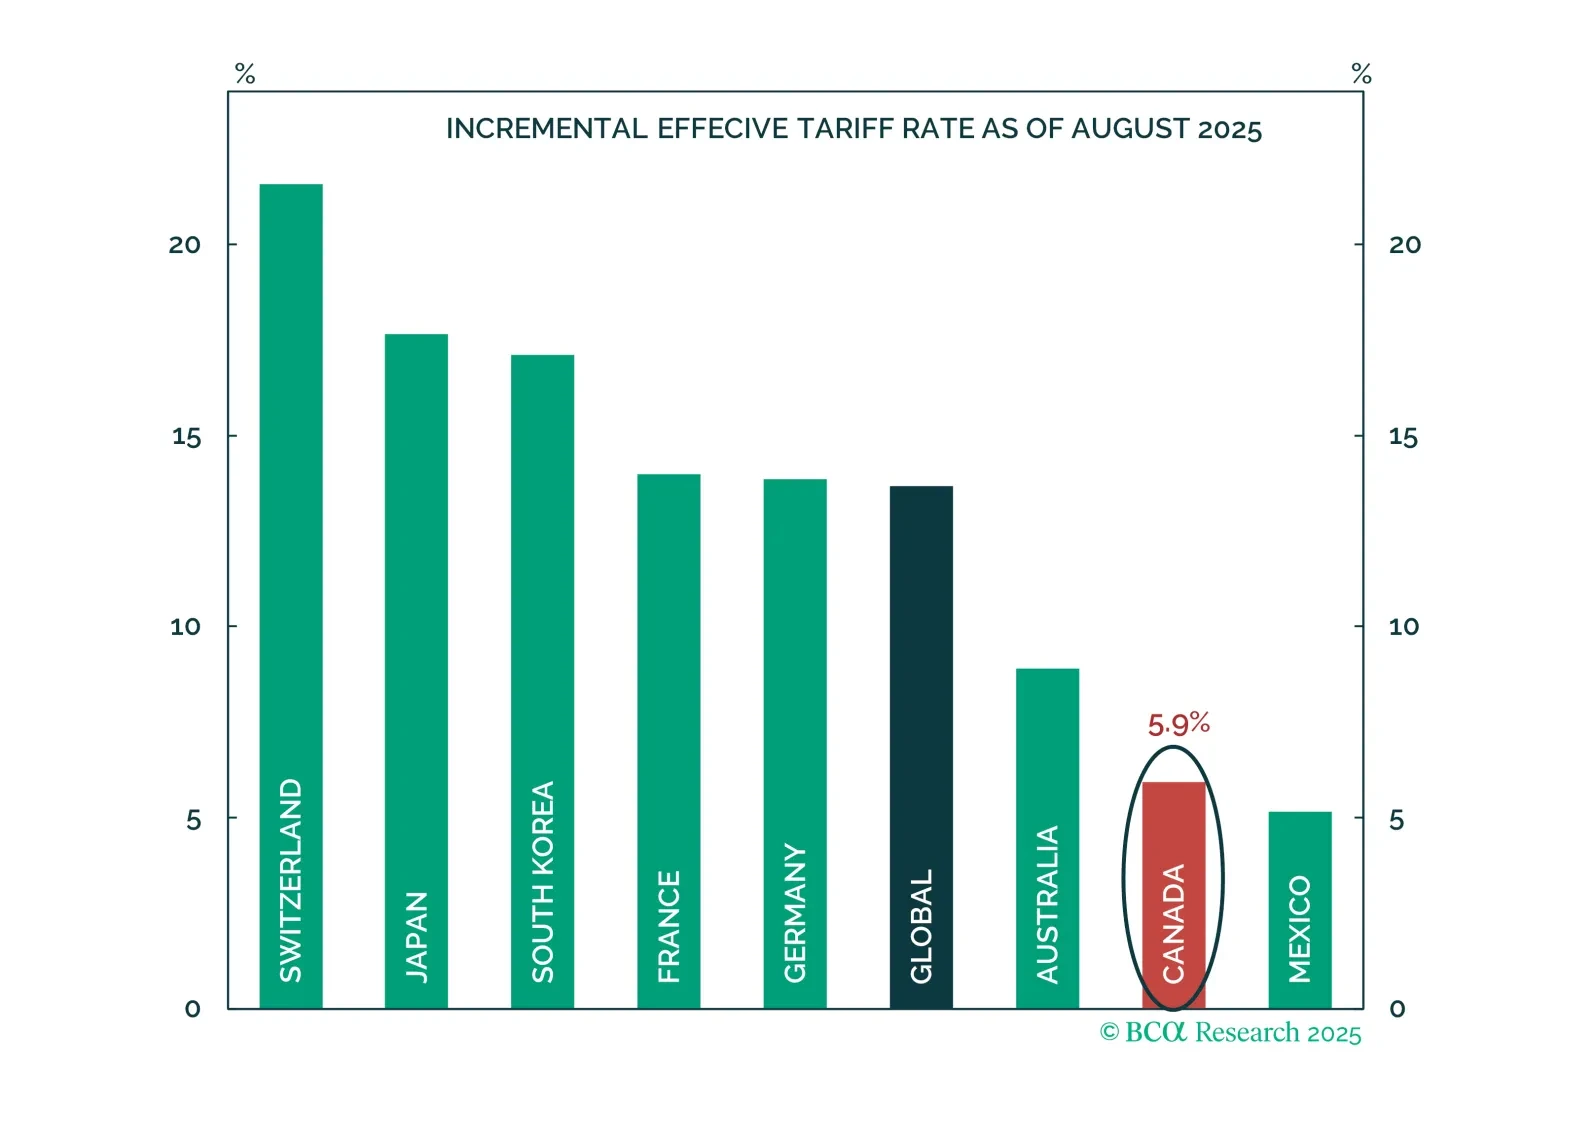
The equity bull market continues, as we have been expecting. The bears are over-indexed on the unorthodox policies of the Trump administration, failing to understand that those policies are negative for the USD, which is itself positive for stocks. Yes, a recession could befall the markets over the next two quarters. However, households are extremely de-levered. As such, as long as borrowing rates continue to fall, consumption could be held up by the transition from the cash-driven economy to a leverage-driven one.
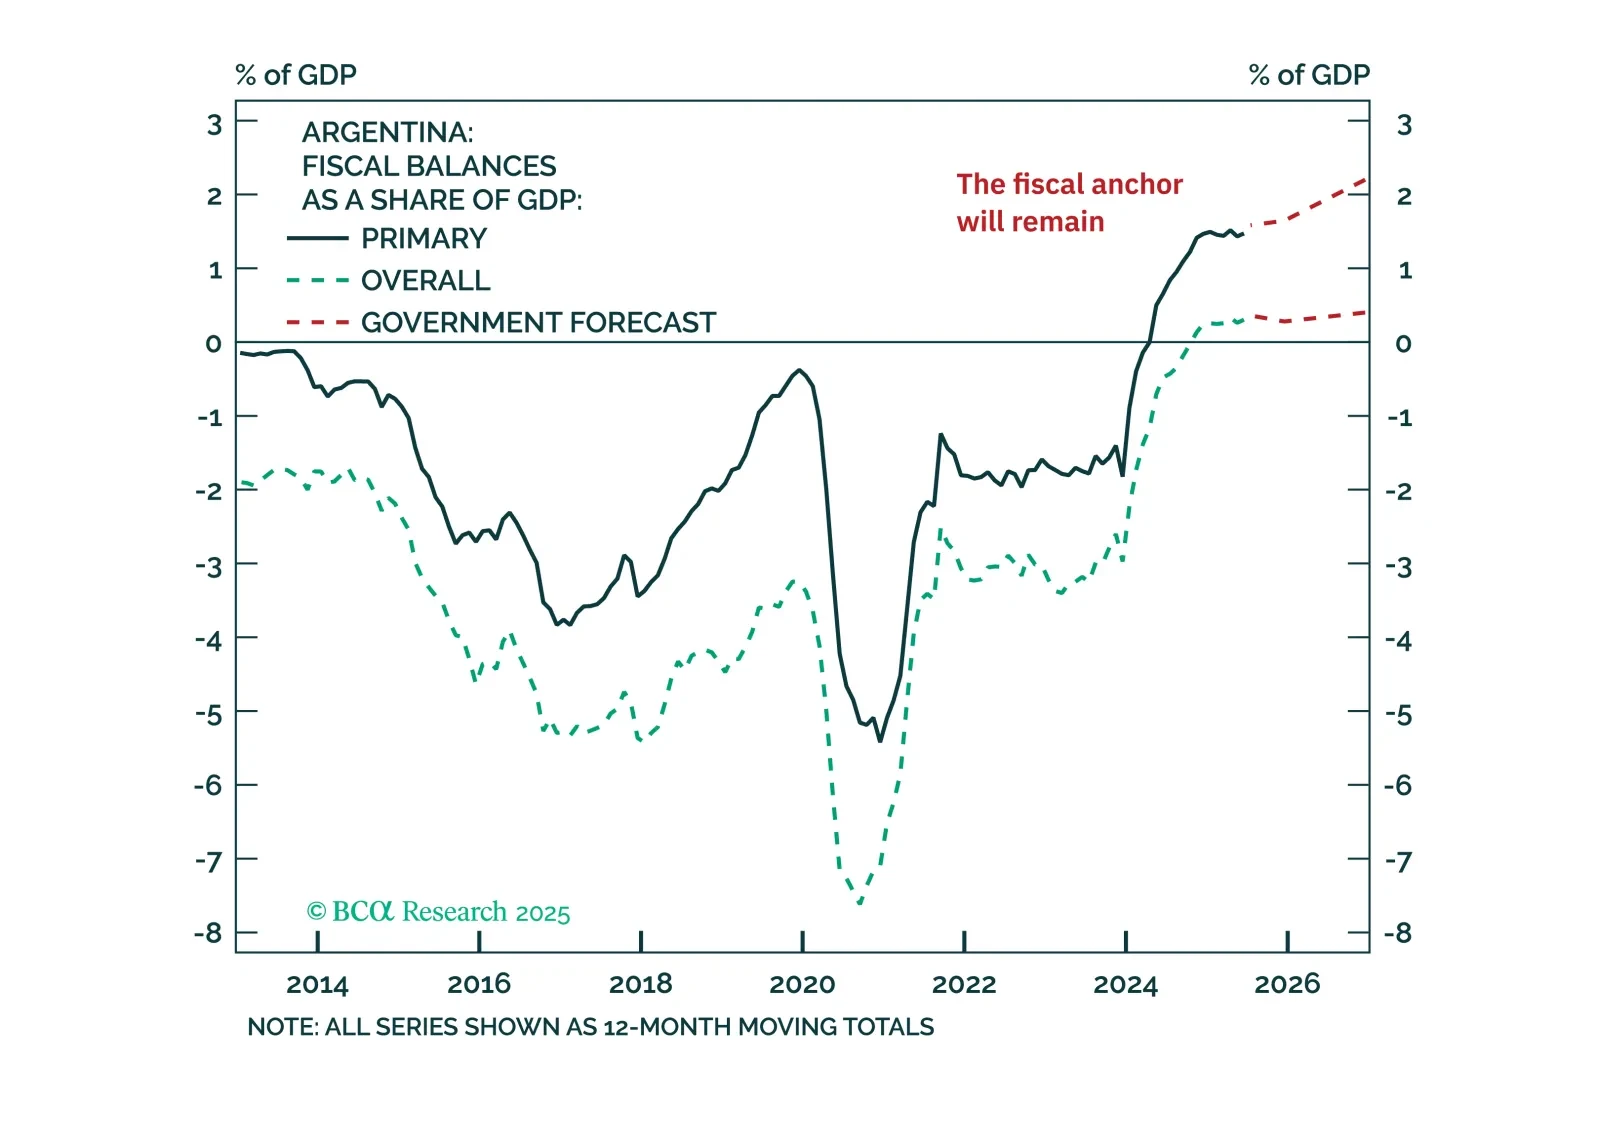
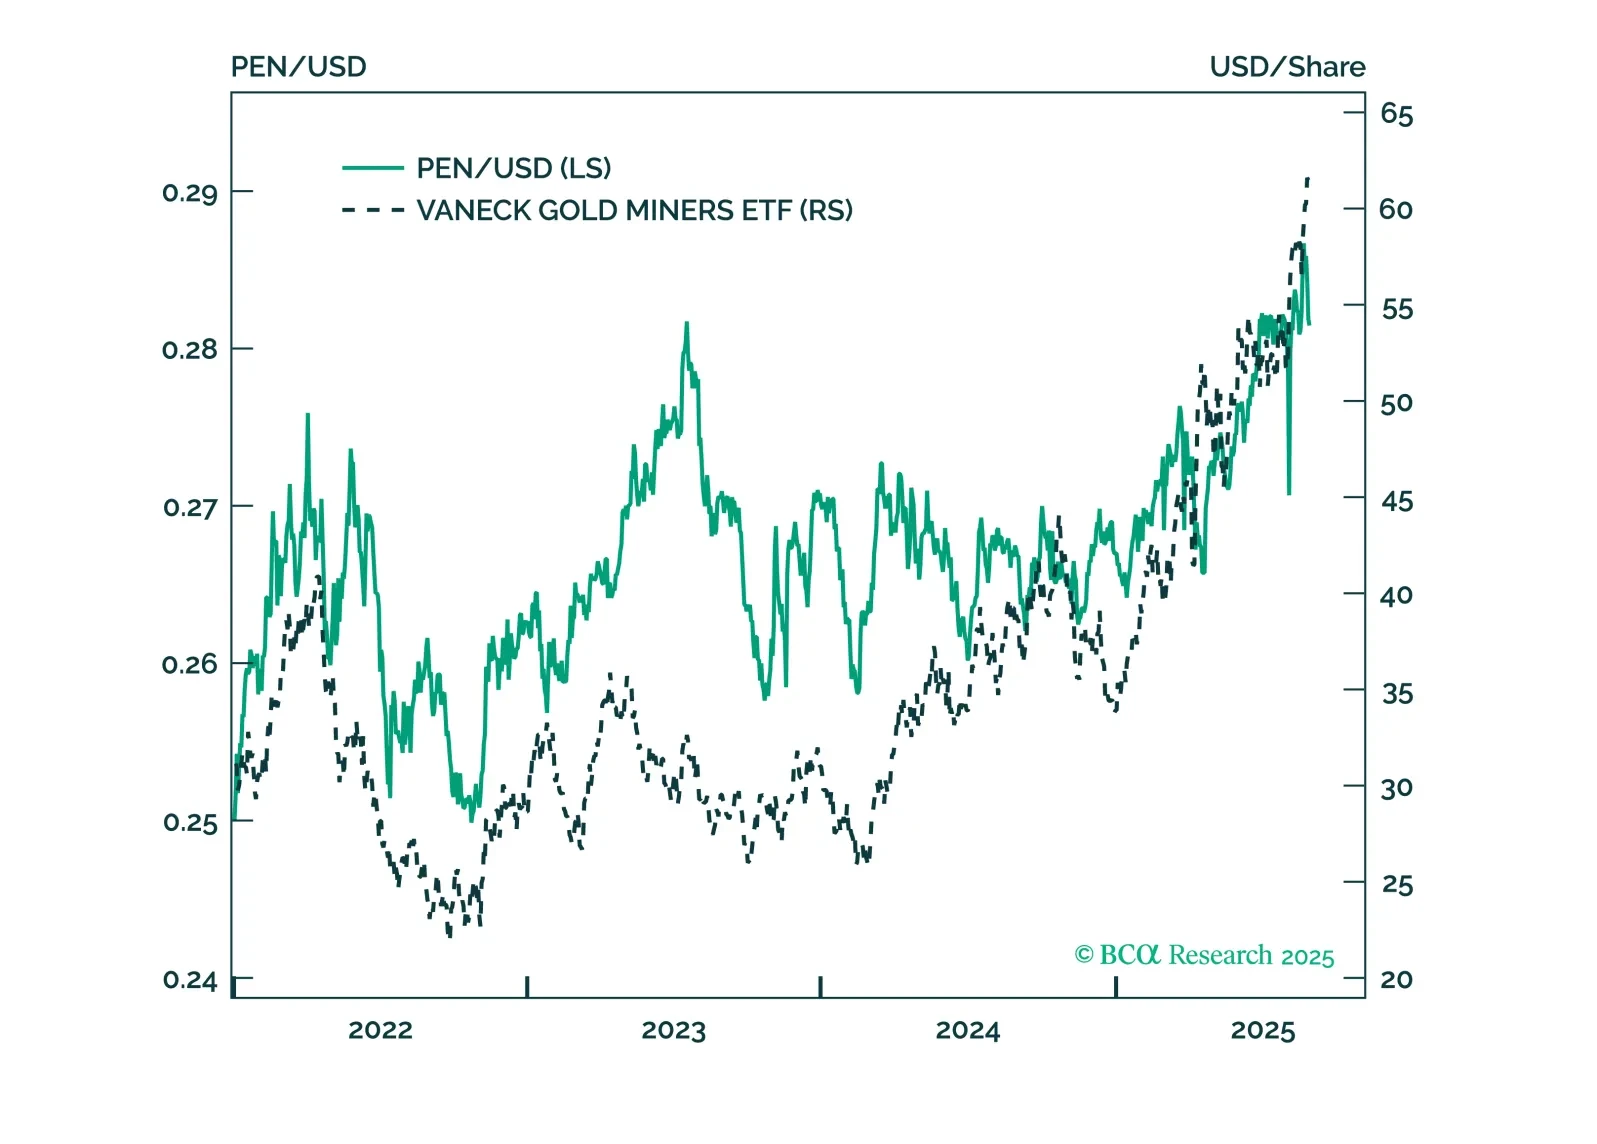
The Buenos Aires election results are a setback for the government's political momentum, but not the endgame. Our long-term bullish view remains in place, but short-term investors should stay on the sidelines in the near run.
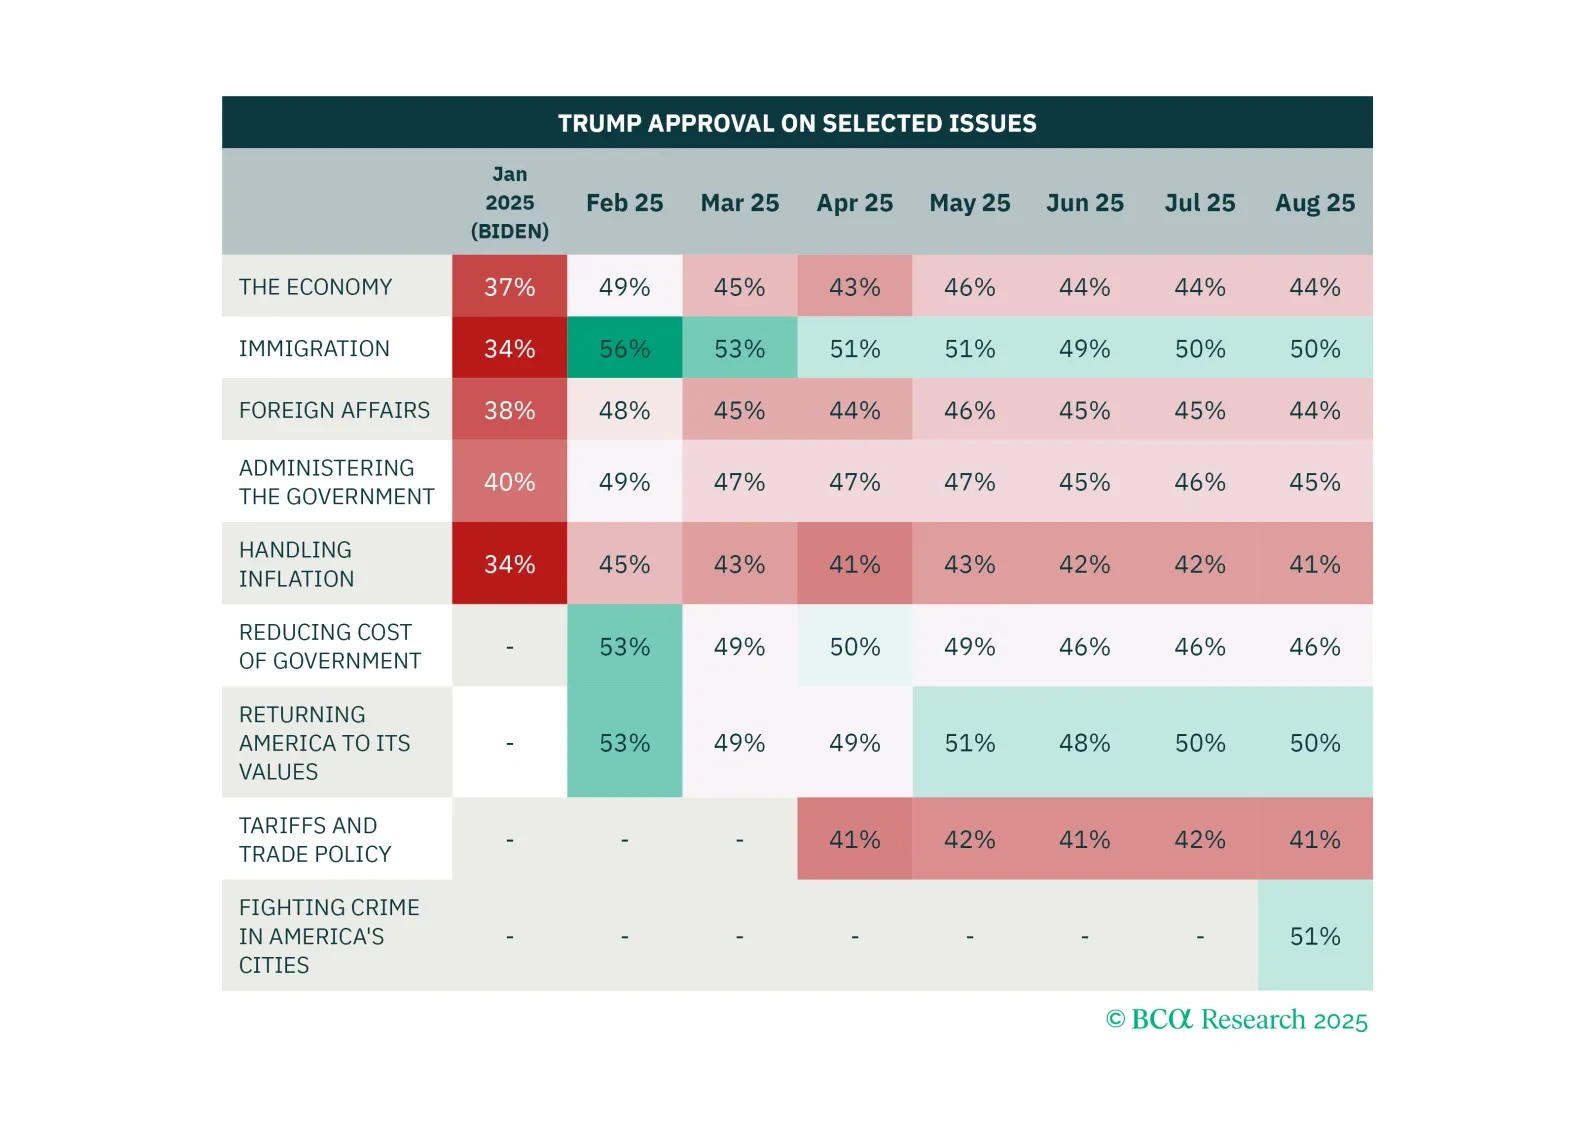
Several clients have asked the GeoMacro team what we expect the Trump administration to focus on over the next 12 months. These will be critical 12 months as the midterm electoral campaign will be in full swing following Labor Day next year.
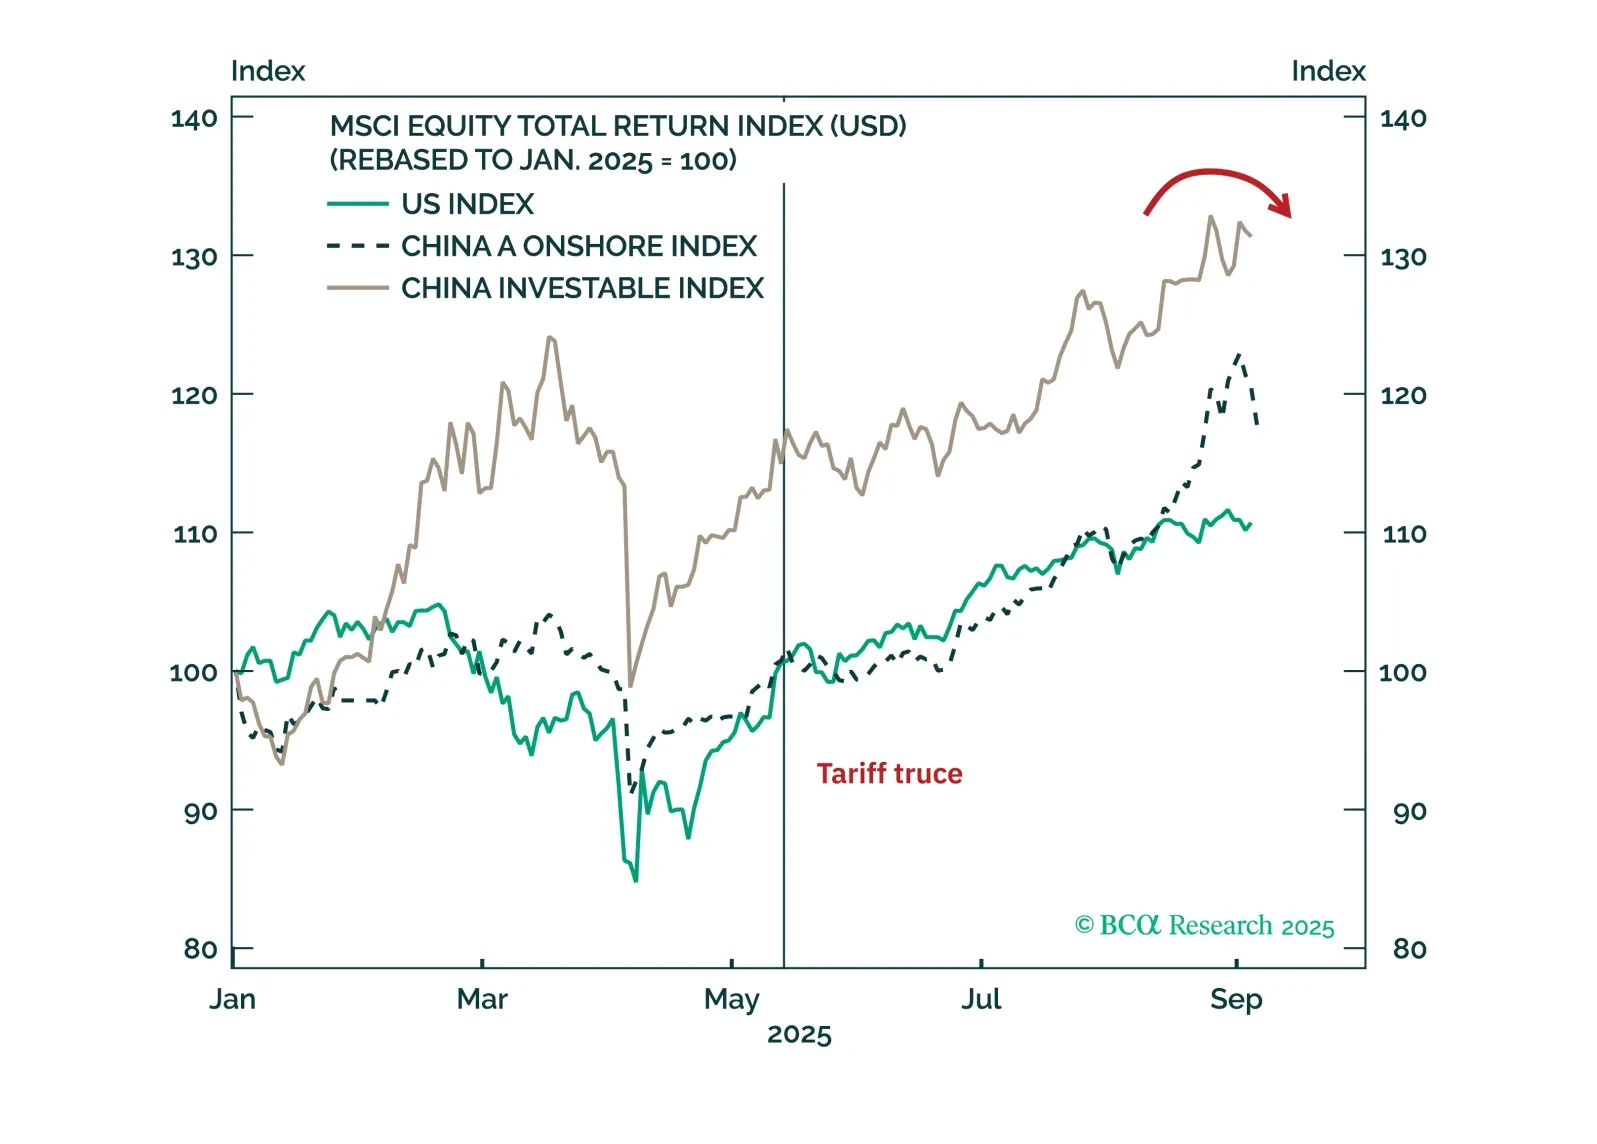
Investors will be disappointed if they buy into the China rally and then Russia escalates the war in Ukraine.
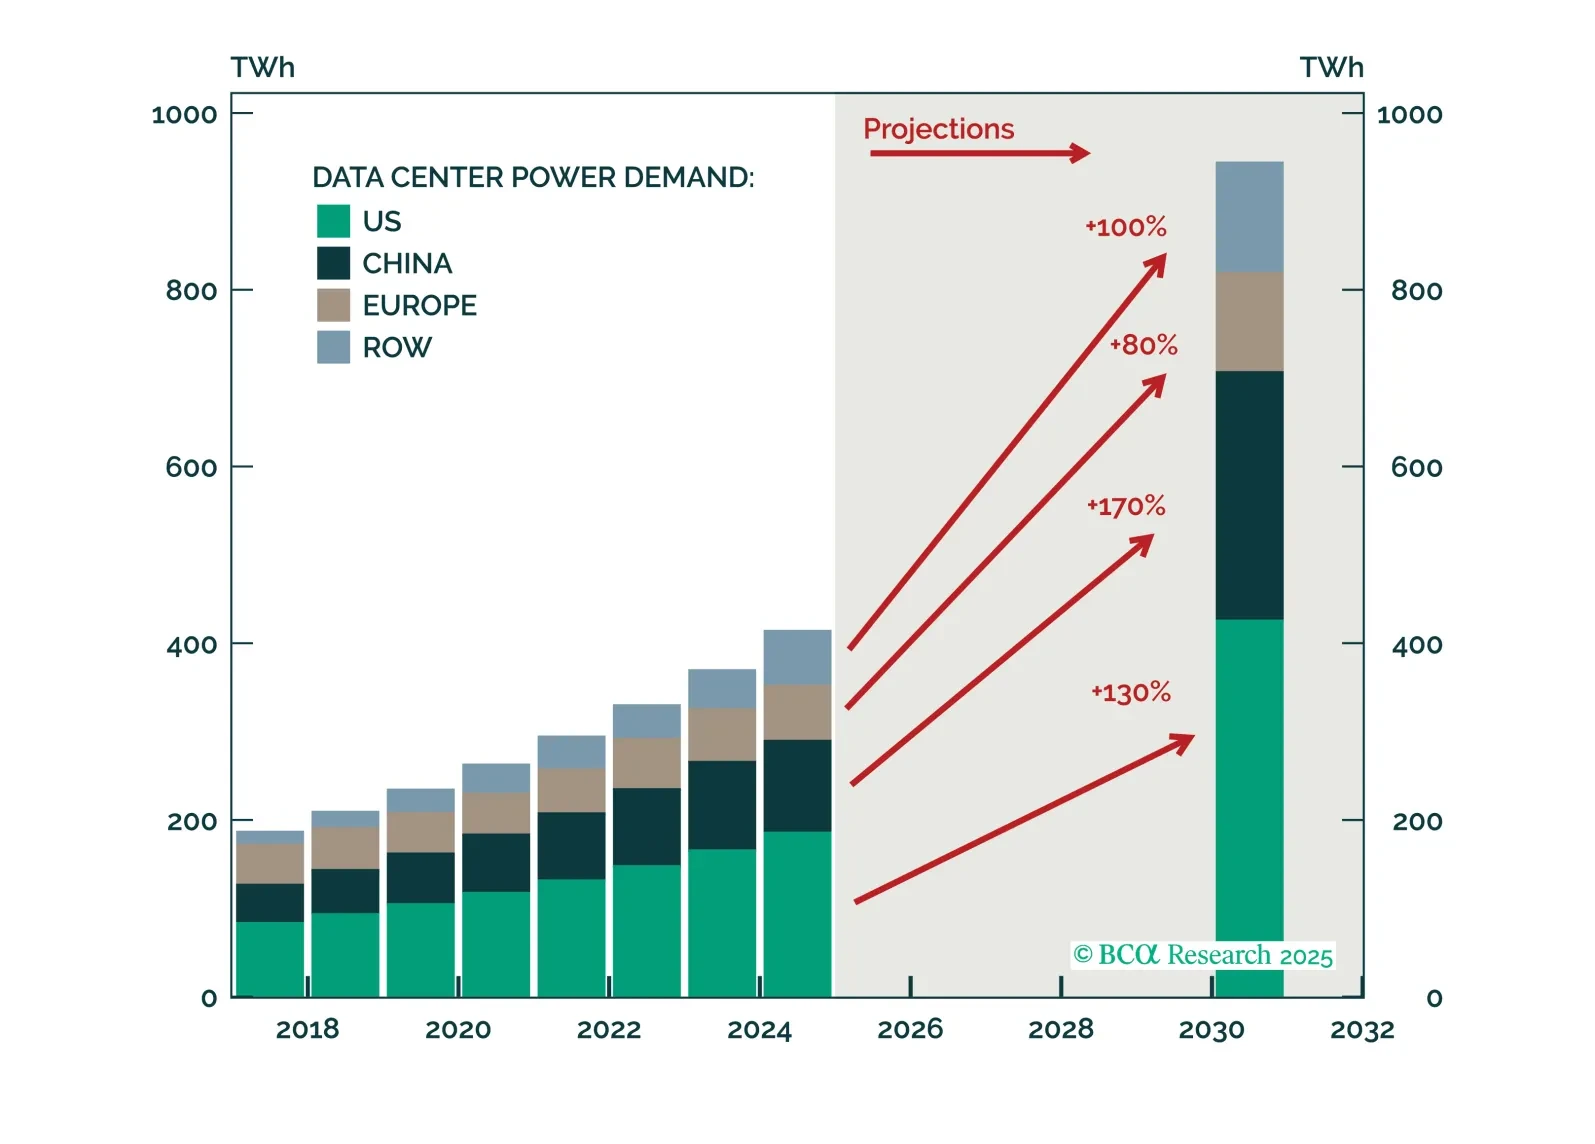
Renewables’ role in power-hungry data centers is overstated. Natural gas will fill clean electricity’s data center supply shortfall, particularly in the US and Europe.
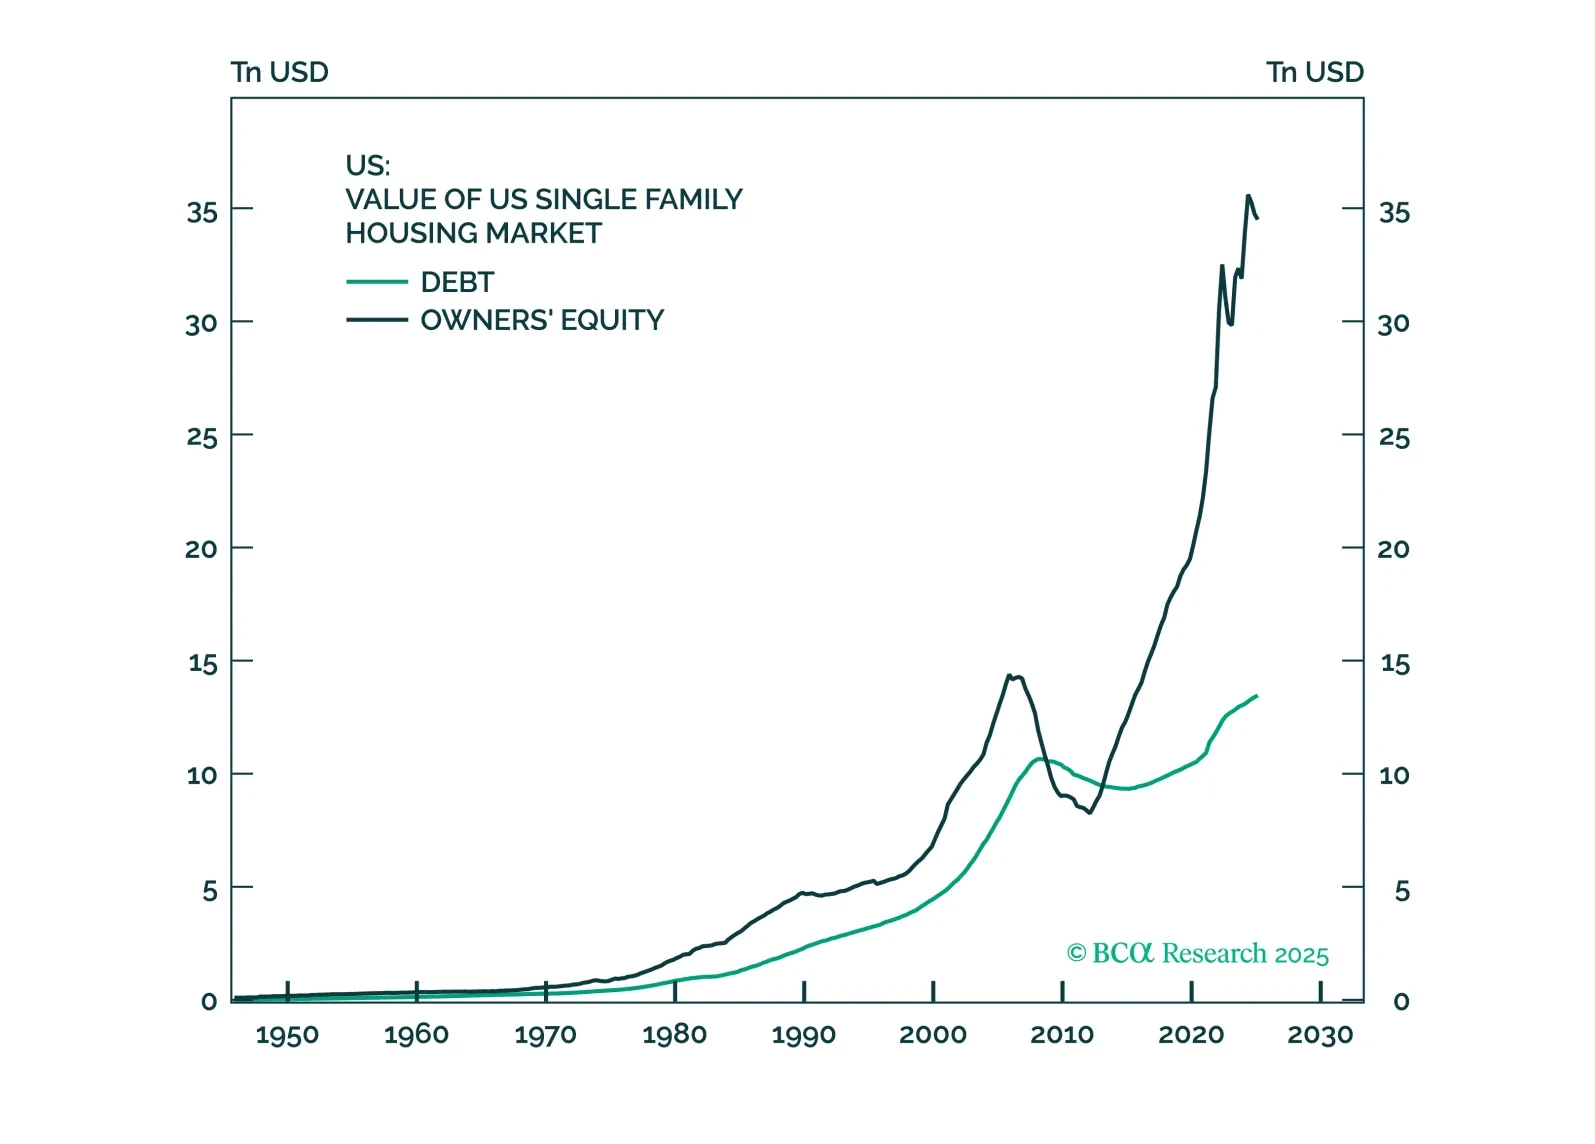
In the Alpha report, we maintain our bullishness on the equity market. We are optimistic that the cash-fueled cycle will evolve into a leverage-driven one, with the AI capex cycle acting as the "bridge" between the two. Our view is easily falsifiable. If the 10-year yield starts moving against us, we will pull the plug on the cycle. One reason to fret is that tariff revenue has now become critical to the equity bull market. Without it, bonds could riot.
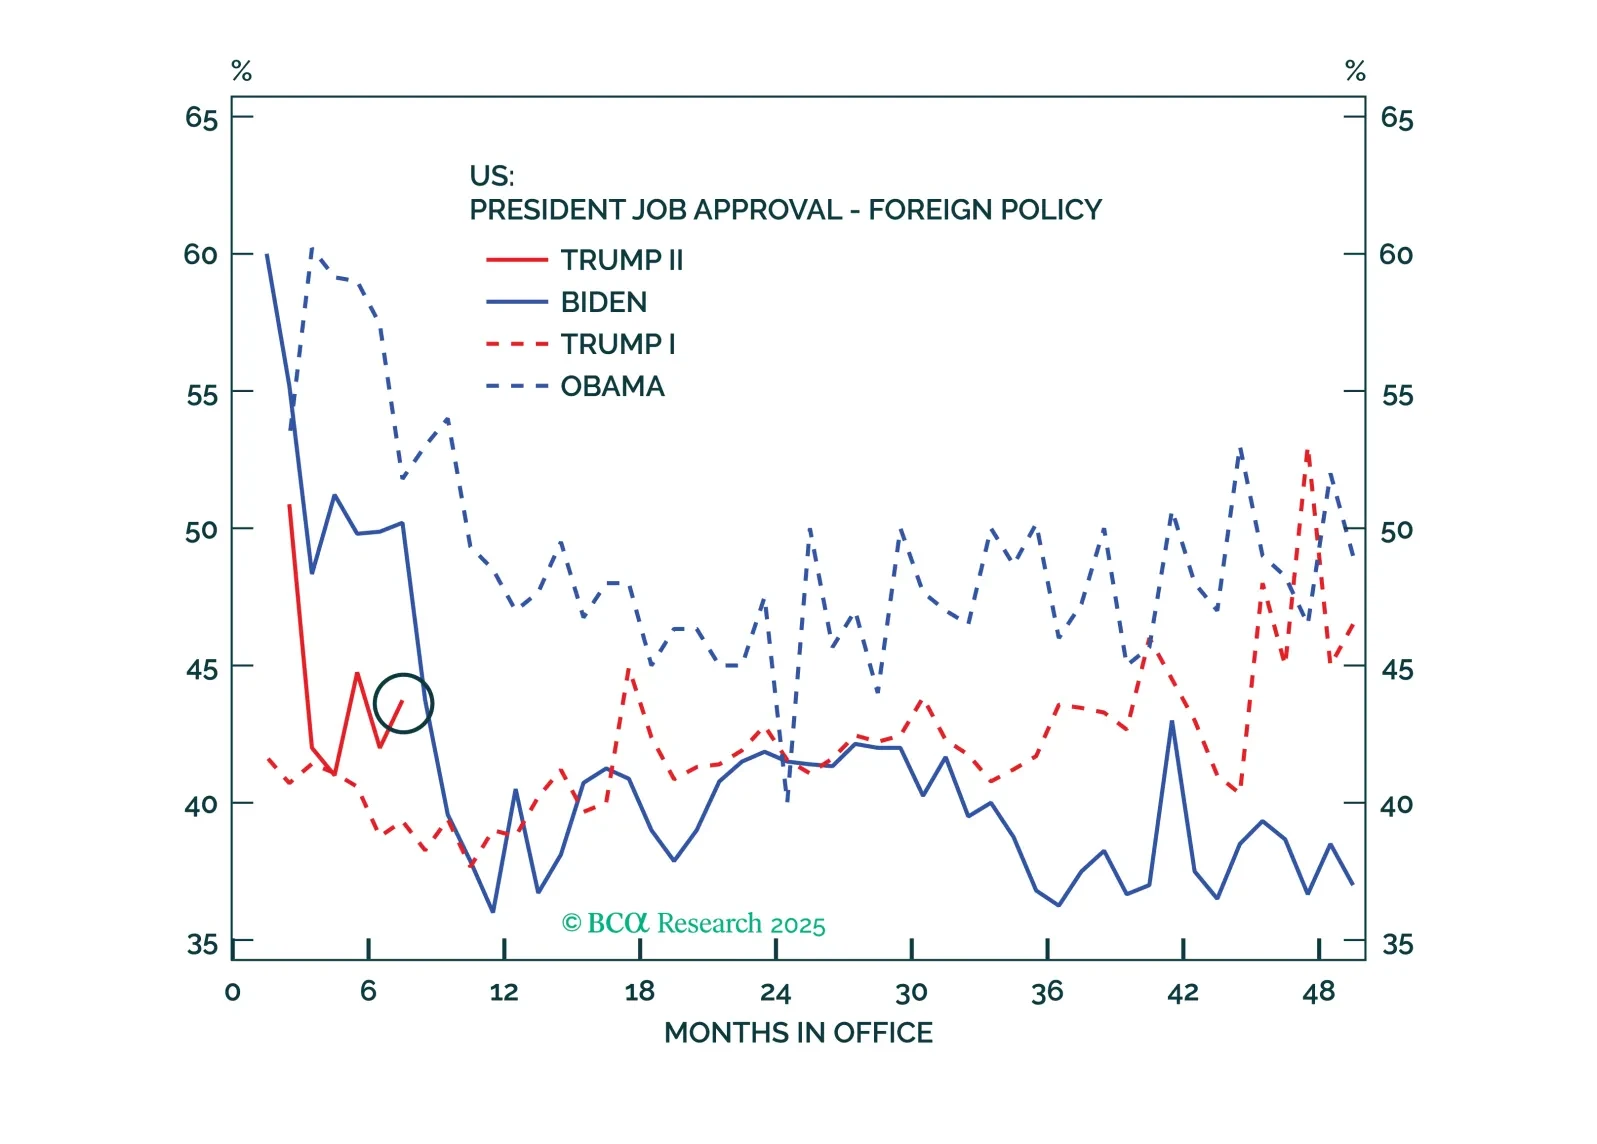
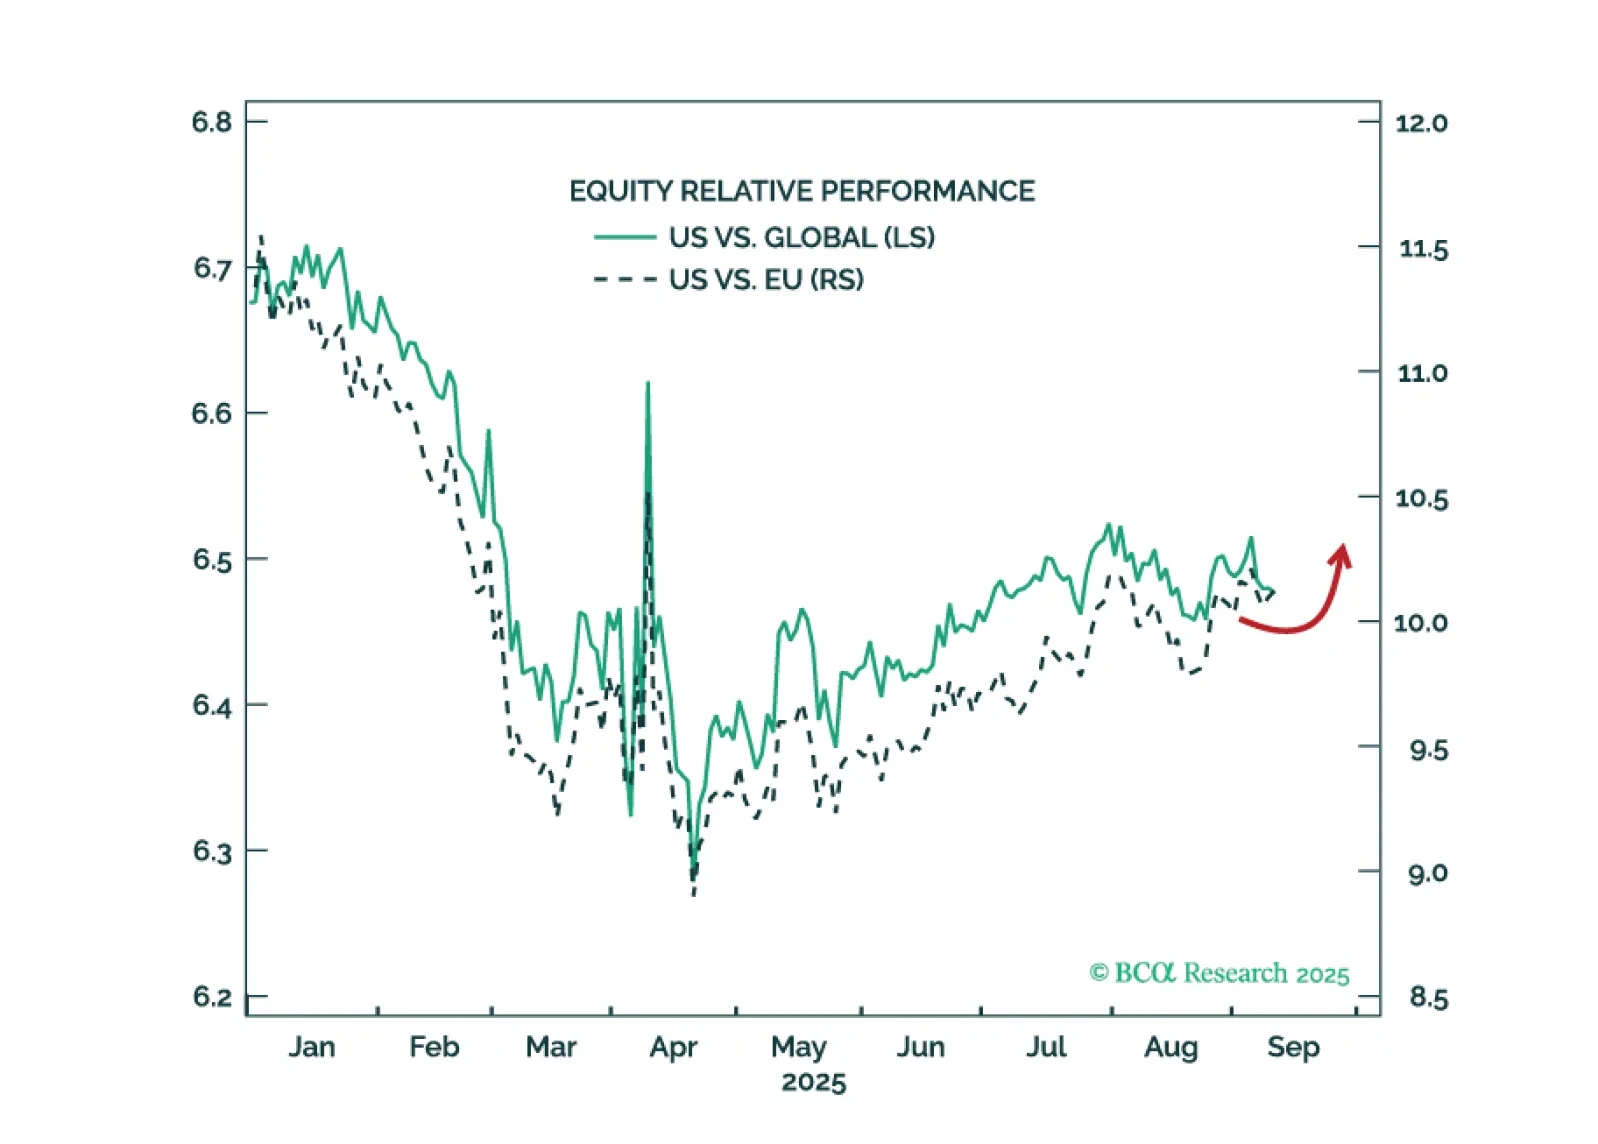
Trump, the Fed, the Russo-China bloc, Venezuela, and France are all seeing developments that imply some contrarian tactical views: Long USD, overweight US versus Europe, overweight Europe versus China, and short oil.