 GeoMacro
Find out more
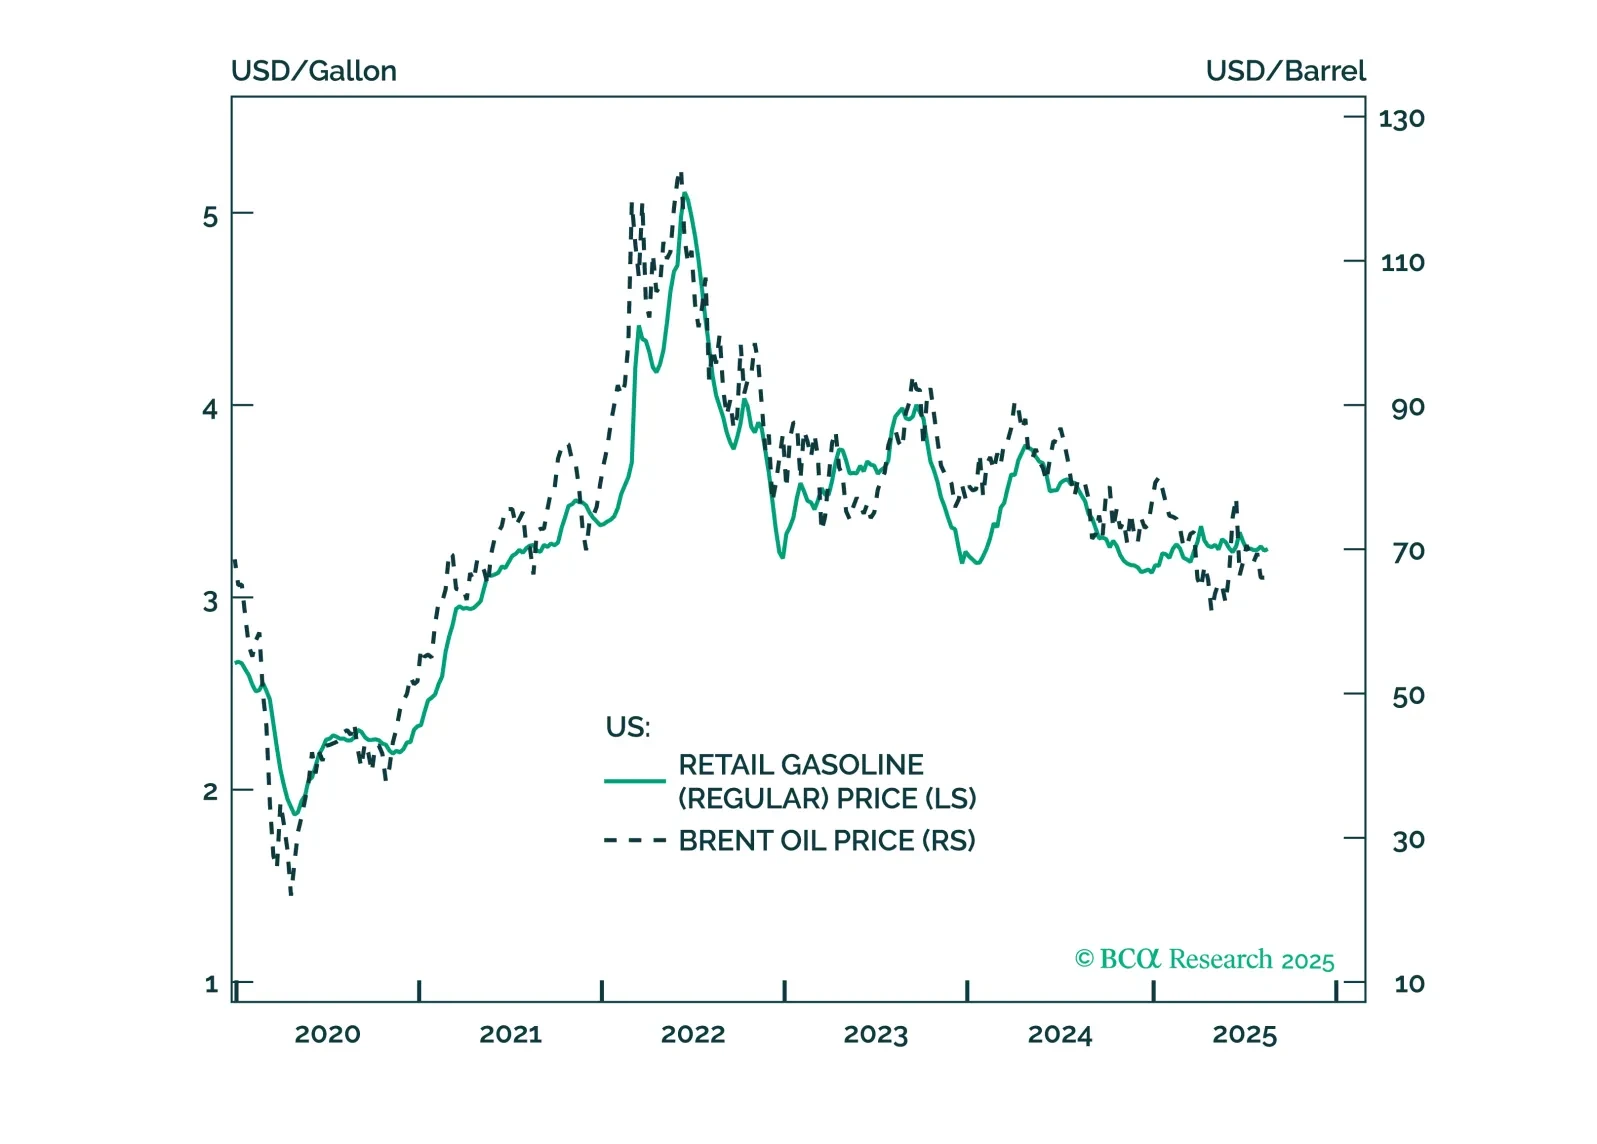
The media is missing the big picture: the war is already contained. The falling oil price confirms that. We fully expect cold feet and volatility incidents in the very near term but there is only a 5% chance of Russia triggering a larger war with NATO – and that is what really matters.
President Donald Trump and his counterpart President Vladimir Putin have met at an air force base in Alaska. The backdrop? America’s shiny F-22 Raptors ominously gleaming on the tarmac, a clear show of force by the US. A reminder that President Trump may be quite friendly with Putin, but that he will not hesitate to impose pain on Moscow if the Kremlin keeps dragging out the conflict in Ukraine.
Trump’s political capital is near its peak. But near-term optimism will give way to a new round of volatility. Contrary to expectations, the USD may benefit.
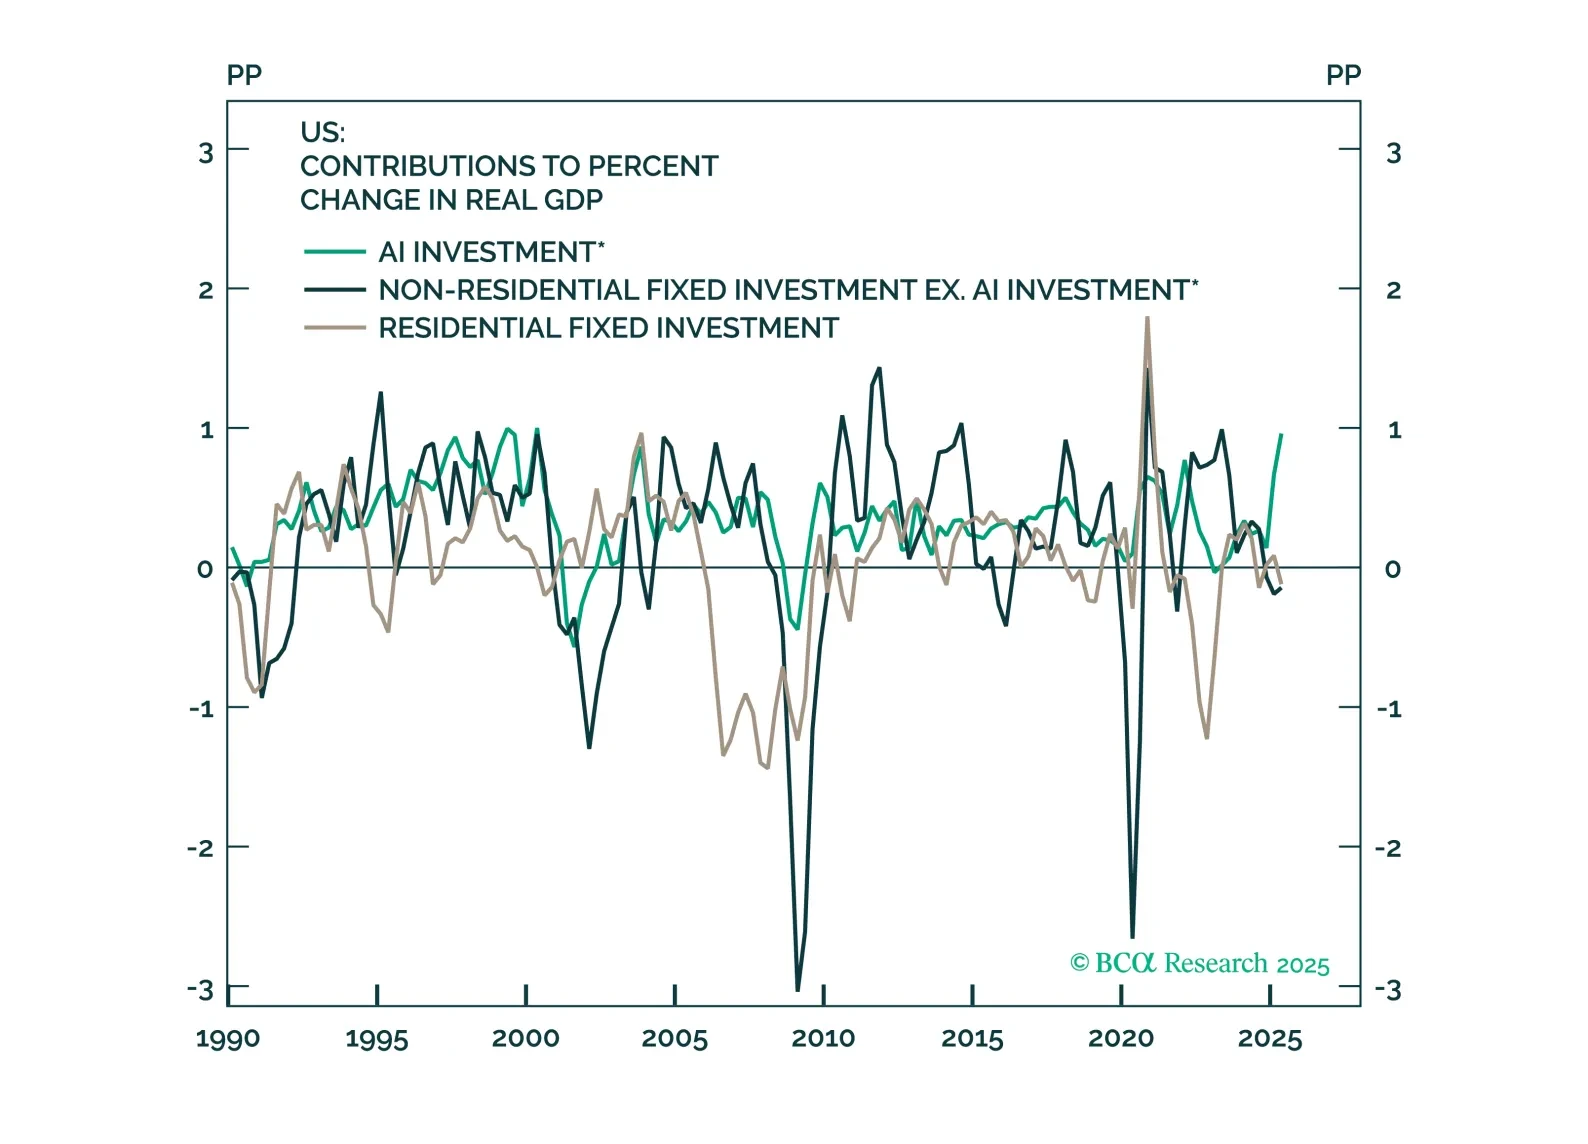
This is the first time that our chartpack does not include any charts on the trade war. Did we just curse our equity overweight? Right as the inflation print comes out and causes agita to the market? Sure, maybe. The tactical ins and outs are not that interesting to us. Far more interesting is the fact that the Fed is going to have to cut regardless of what "widget inflation" does. With no more fiscal backstop fueling the economy via wanton transfer payments to households, the inflation-fiscal gravy train is over. As such, the Fed will cut more than the market thinks, particularly given the political pressure from the Trump White House.

Taiwan’s failed recall election reduces 12-month geopolitical risk for Taiwanese and Chinese equities on the margin. We are reviewing our long European industrials / short Chinese industrials trade.
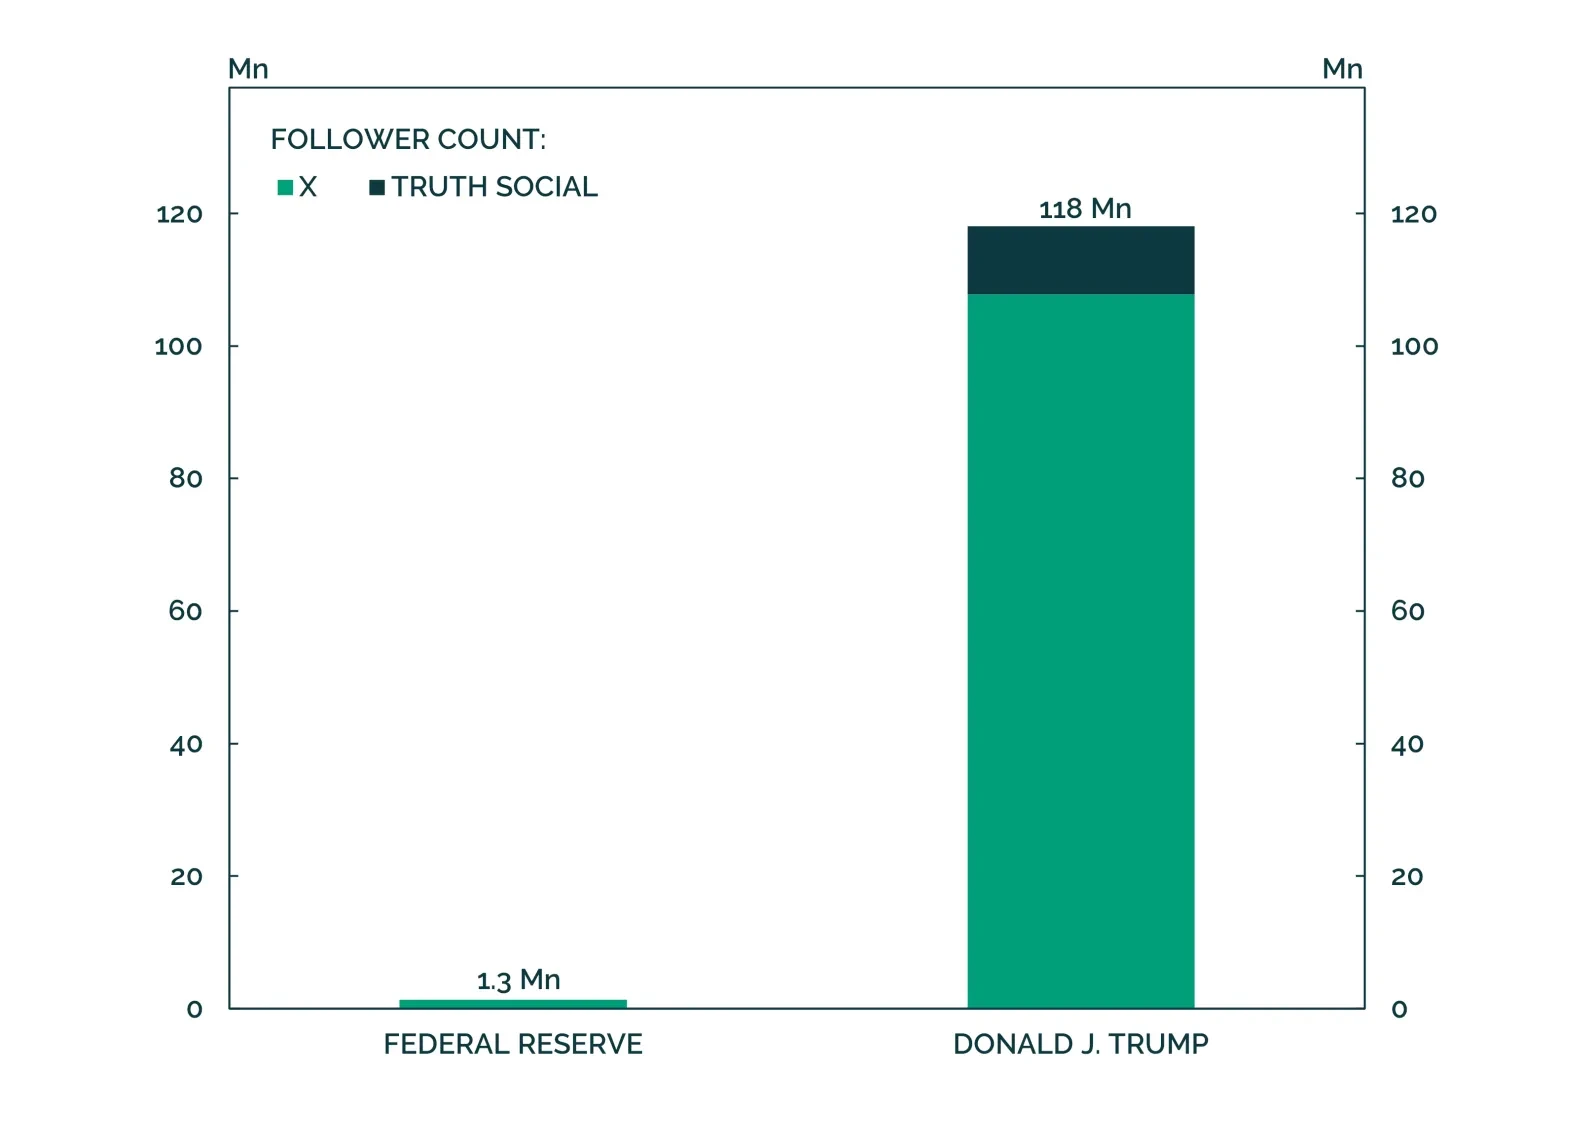
Markets have ripped in July, ignoring underwhelming payrolls and retail sales figures. This was our bet, so we don't think this is a mistake. The economy is transitioning from one catalyzed by cash to one led by lower borrowing rates. The combination of a growth slowdown tempered fiscal policy, and an uber-dovish Fed is good for bonds and equities, which has not yet been priced by markets.
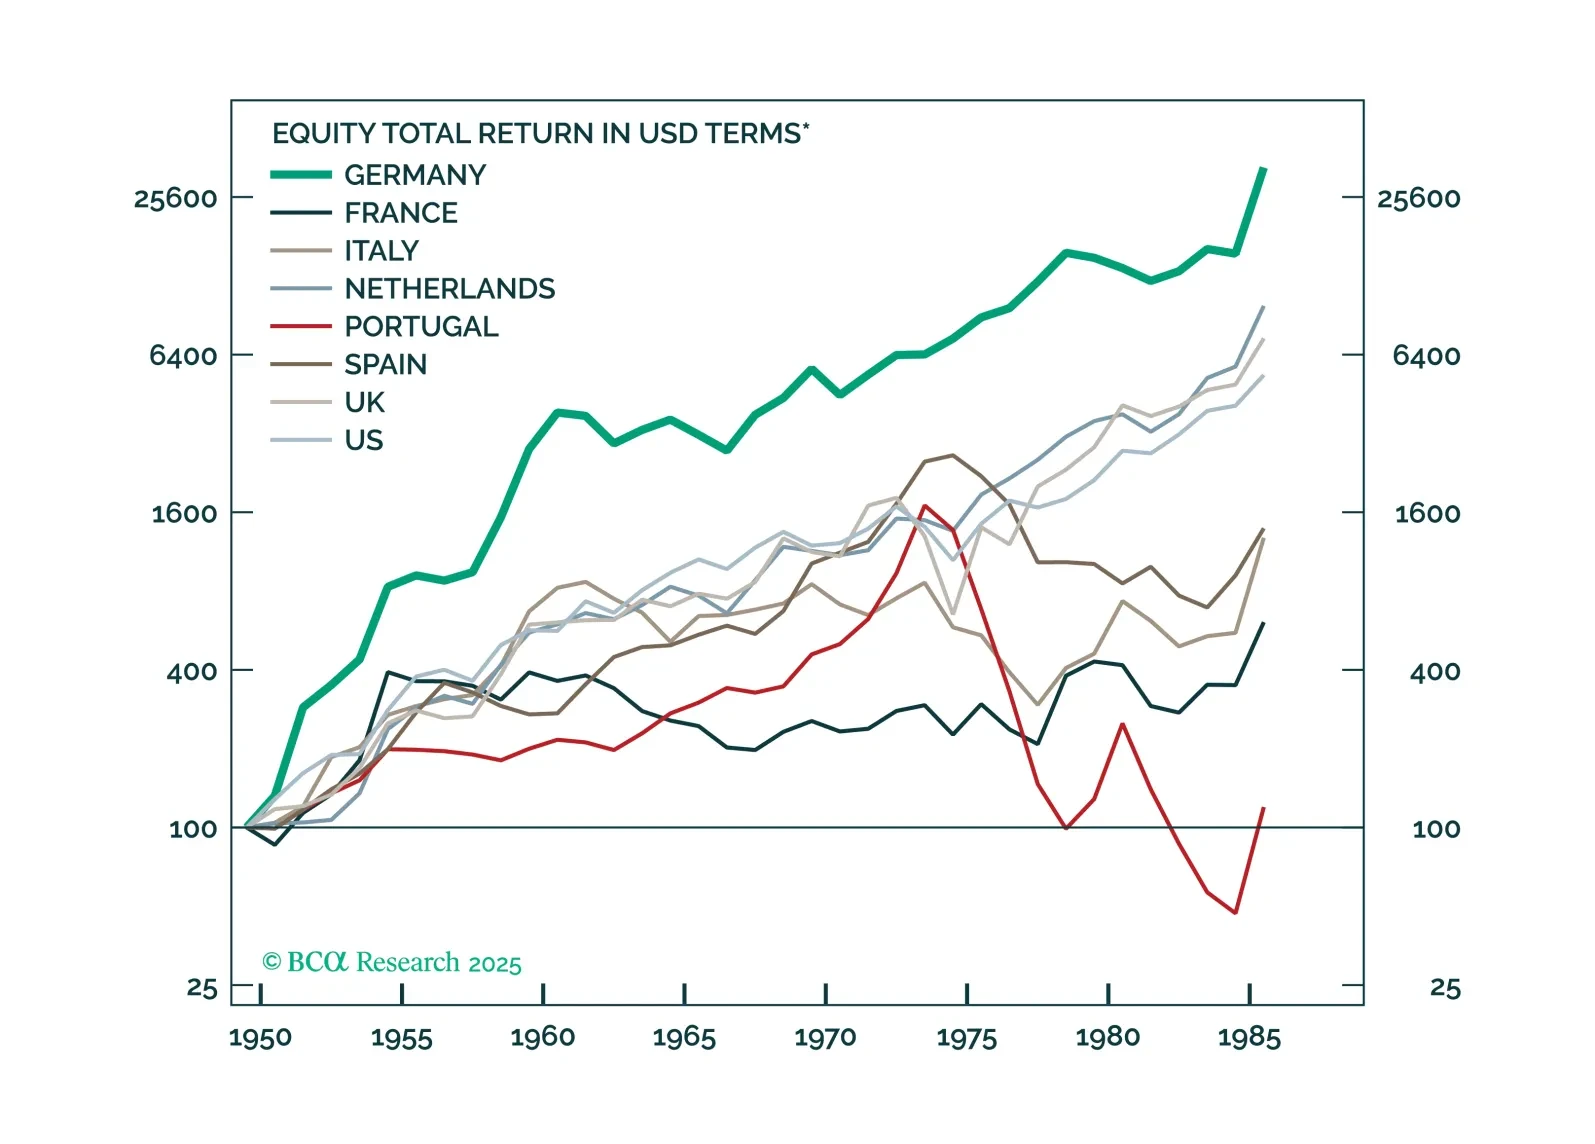
In our Beta report, we introduce a new framework for thinking about long-term investing in a multipolar world: The Garrison State. Investors need to shed their outdated view that geopolitical risks are... a risk. History teaches us that pressure makes diamonds. And geopolitical pressure makes Garrison States, which tend to outperform precisely because by definition, the bevy of risks that surrounds them is existential.
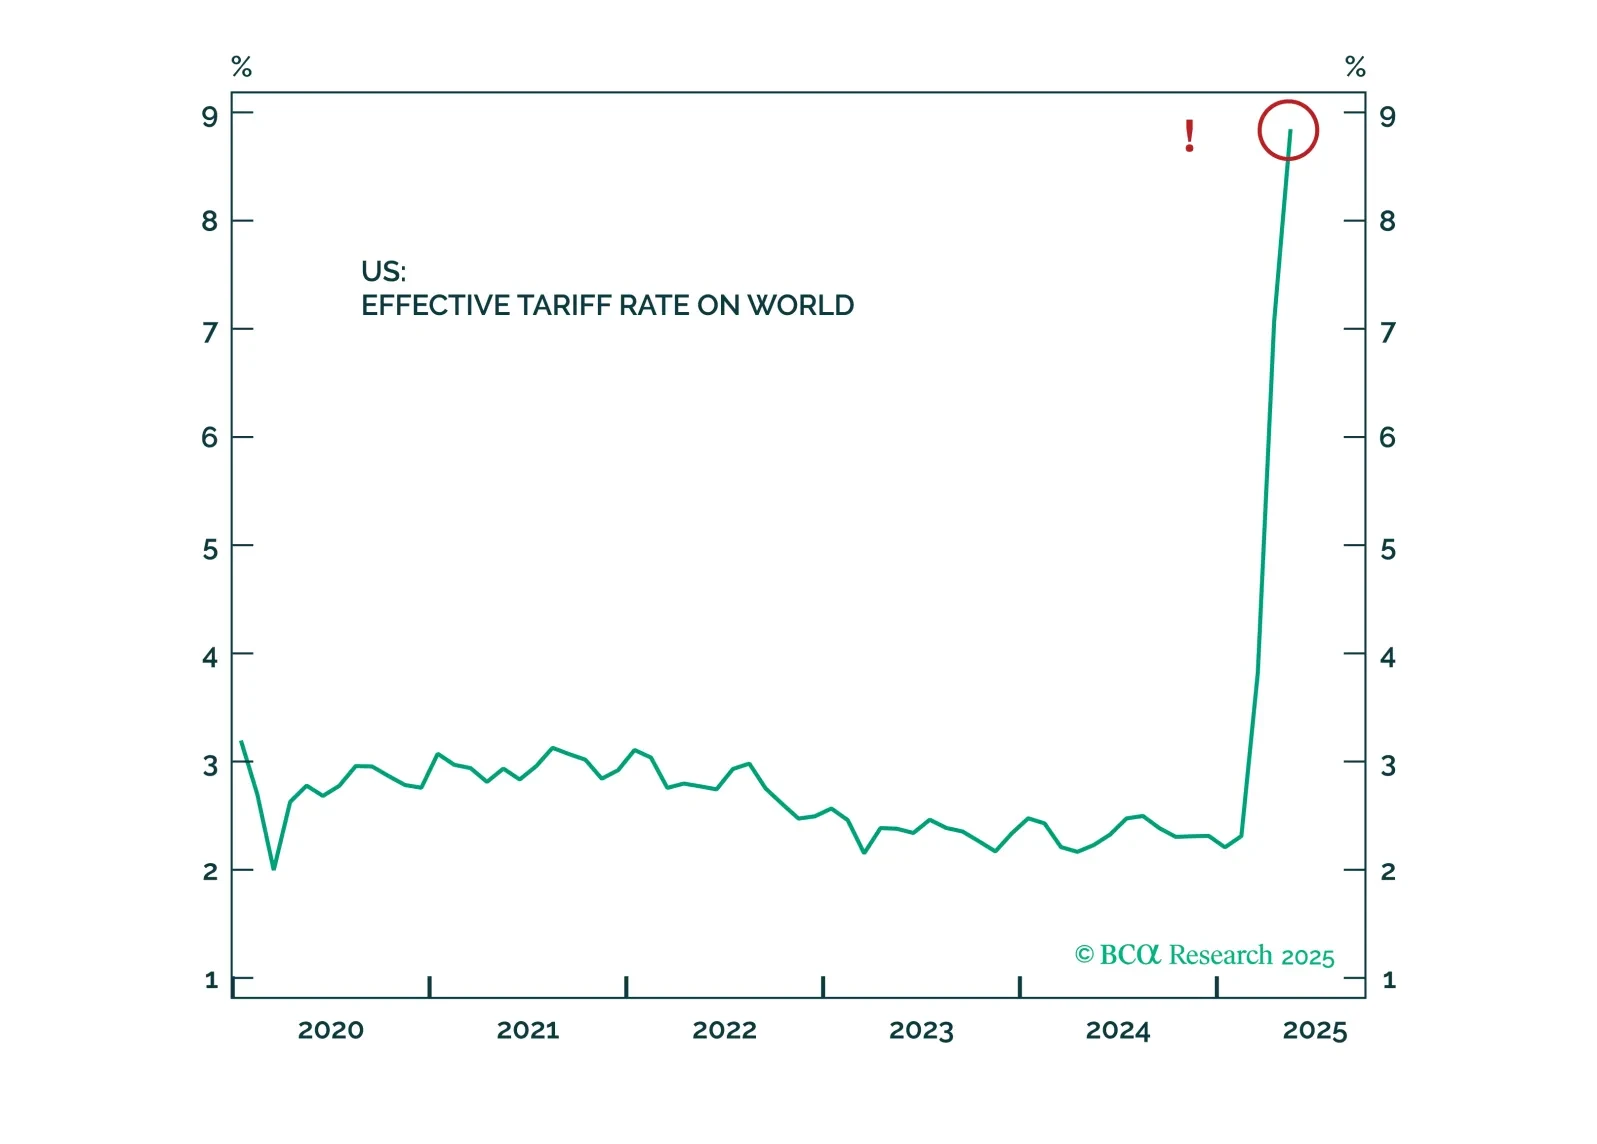
Investors should stick to a defensive stance in the very near term as the Russia-Ukraine conflict and persistent trade tensions cause market volatility.
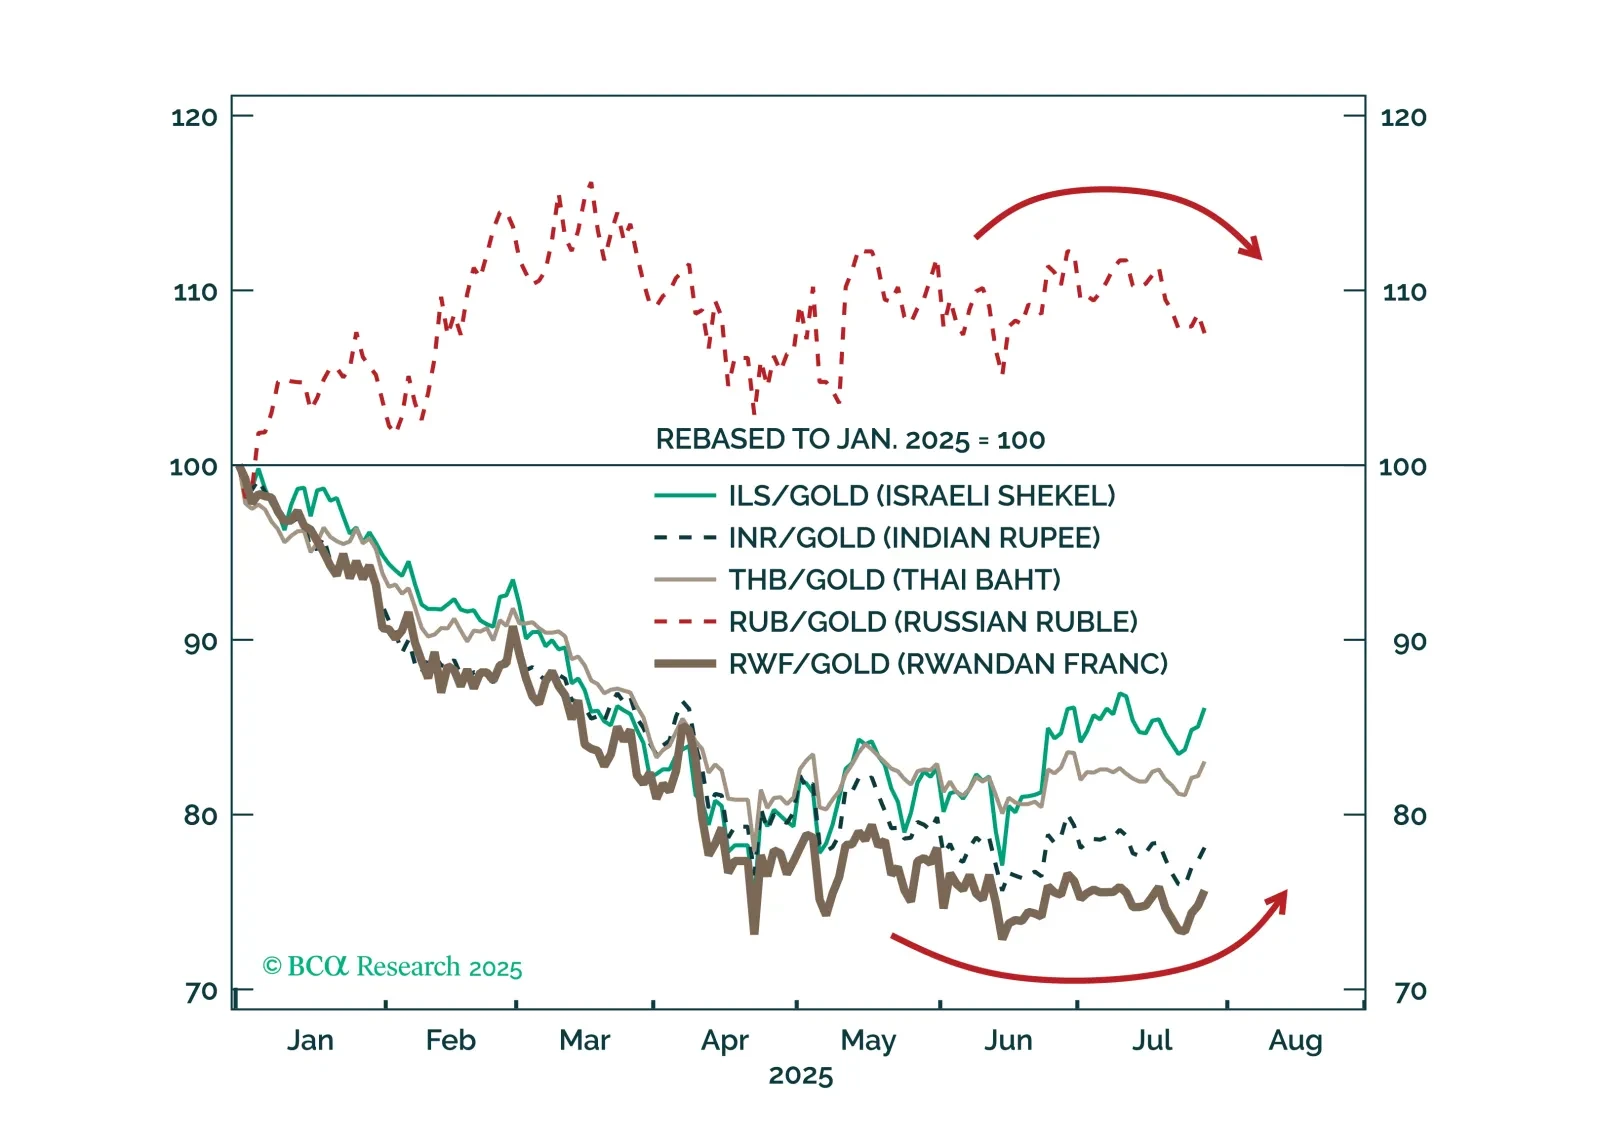
Russia poses an immediate risk to global financial markets, and then perhaps a buying opportunity. Trump is pivoting to ceasefires and trade deals, but Russia could trigger a new tariff shock first.
