 GeoMacro
A blend of geopolitics and macro, synthesizing the new and old macro to generate alpha and identify the beta through probability-weighted market views.
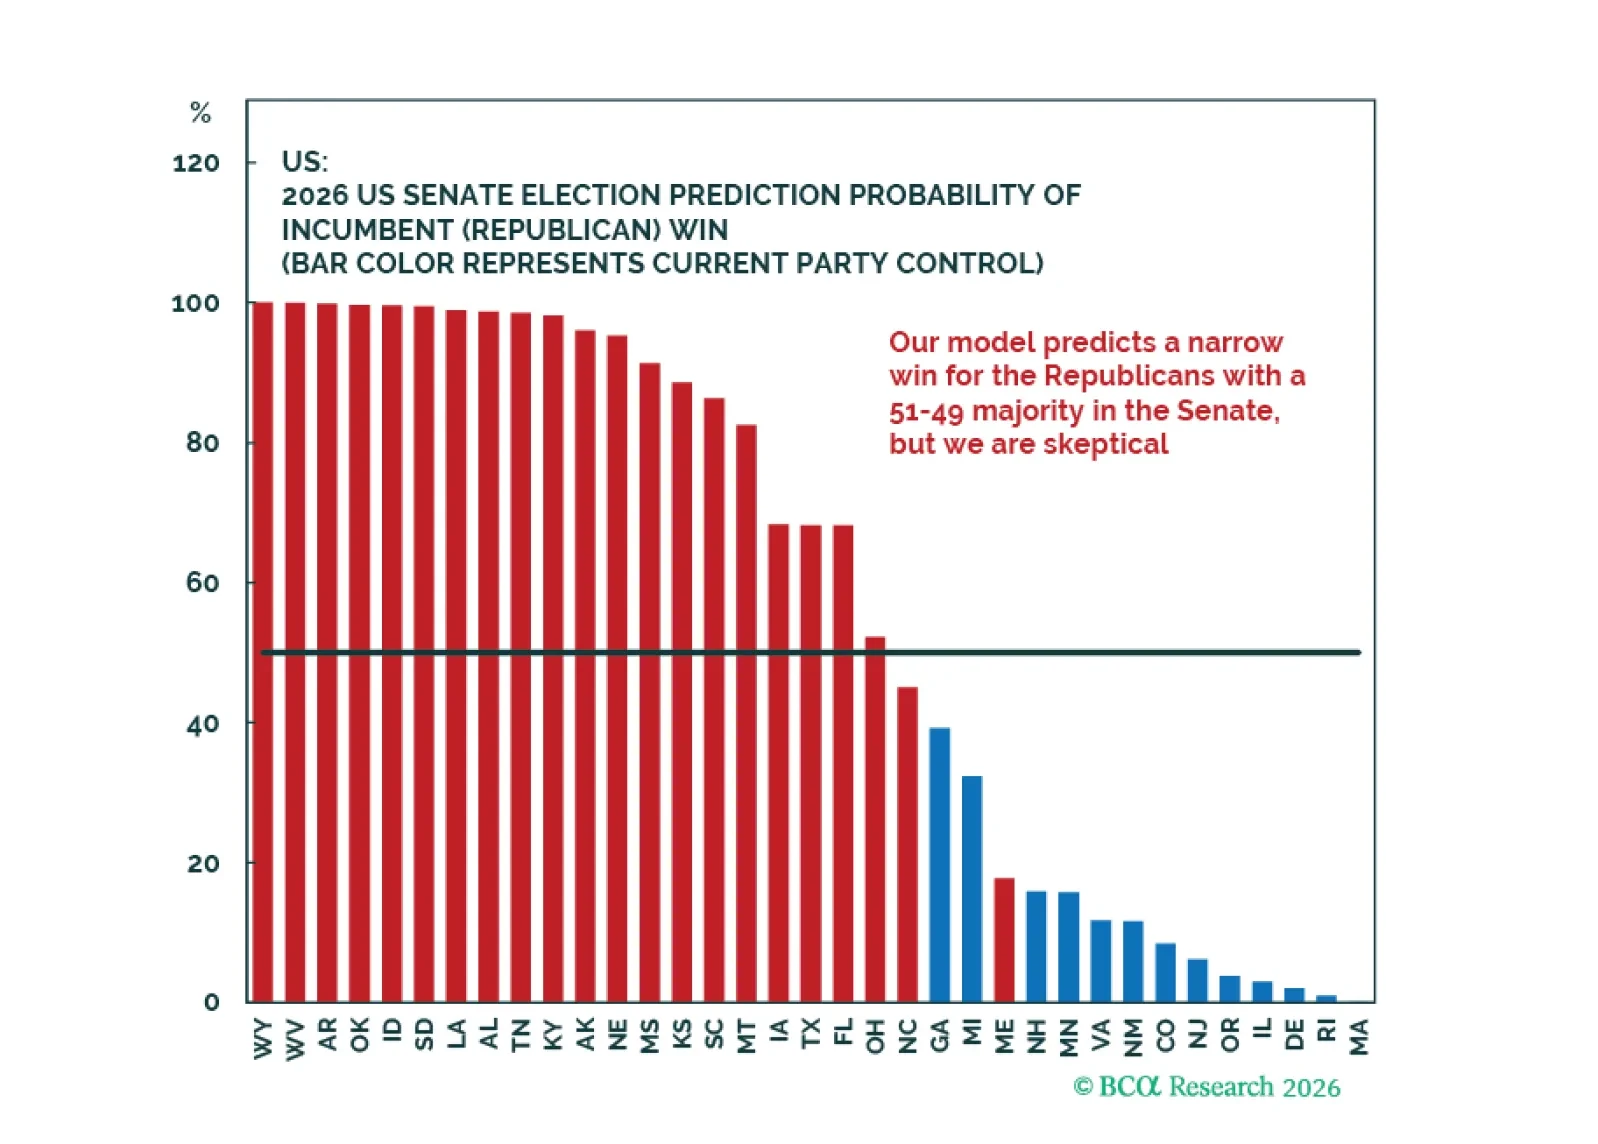
Midterms matter but geopolitics are the main risk this year. Markets will eventually refocus on geopolitical and inflation risks, raising Fed rate hike odds and supporting US dollar and stocks over global counterparts this year.
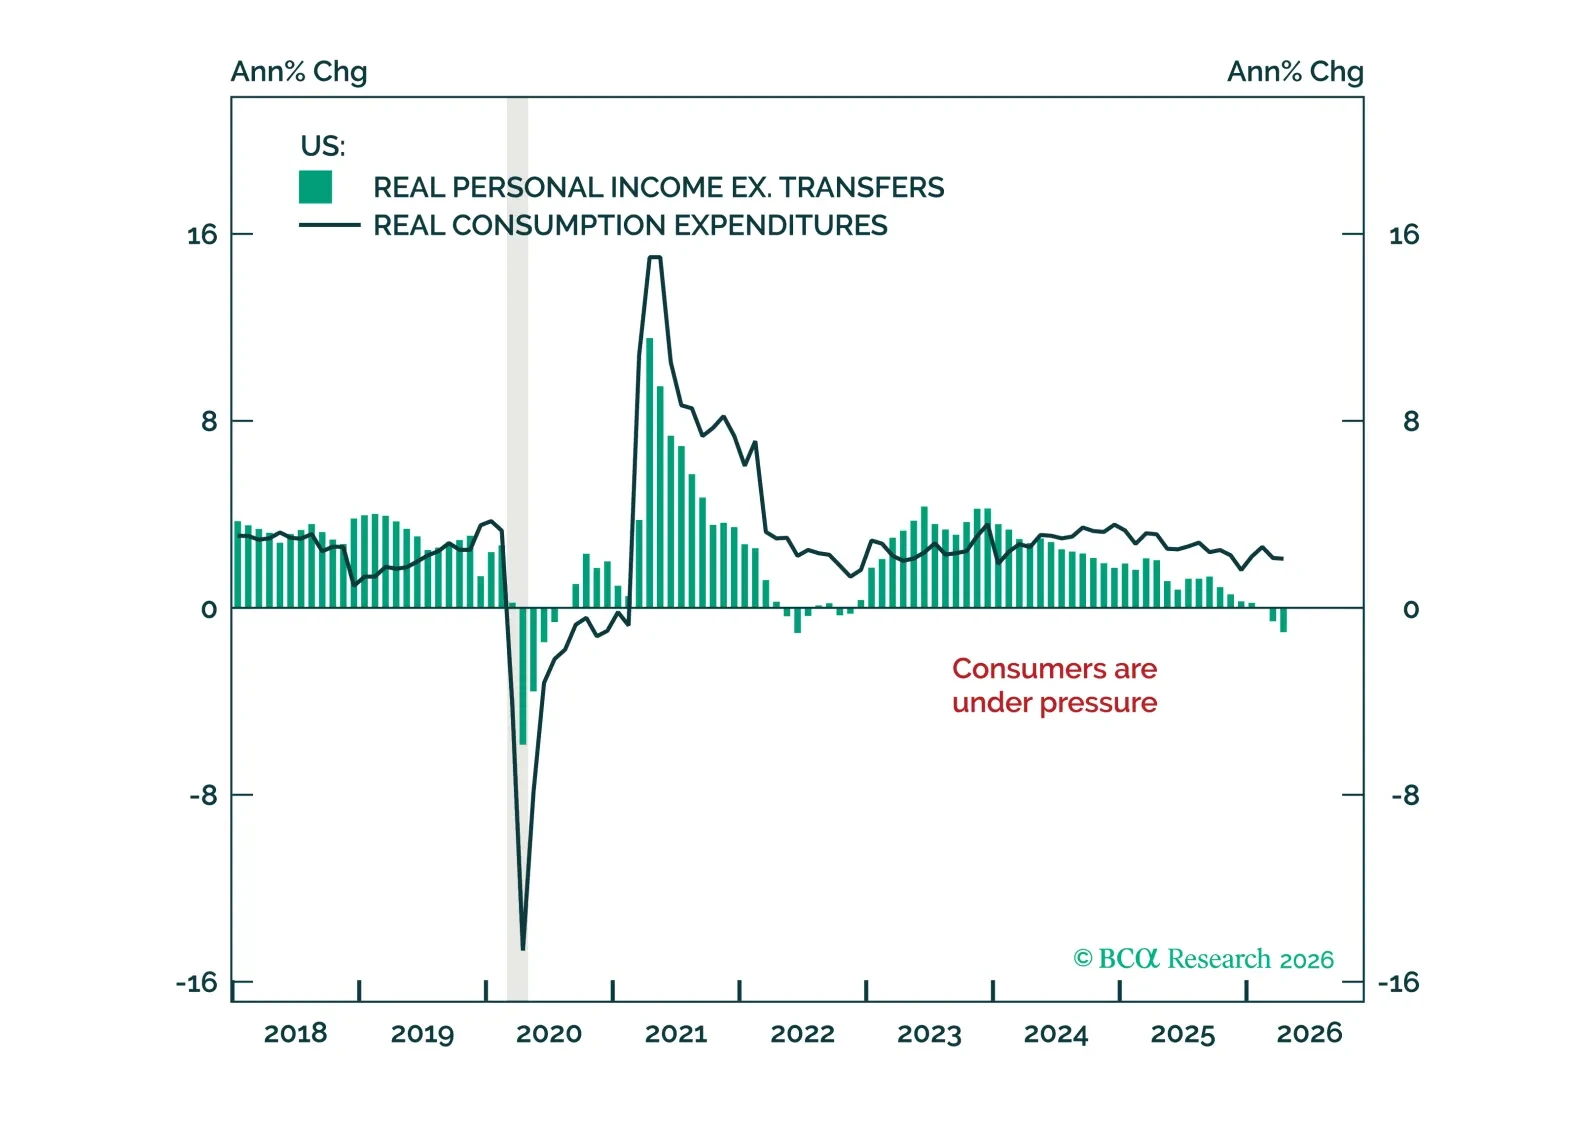
For the first time since… 2022… the GeoMacro team is starting to contemplate the end of the cycle in a serious way.
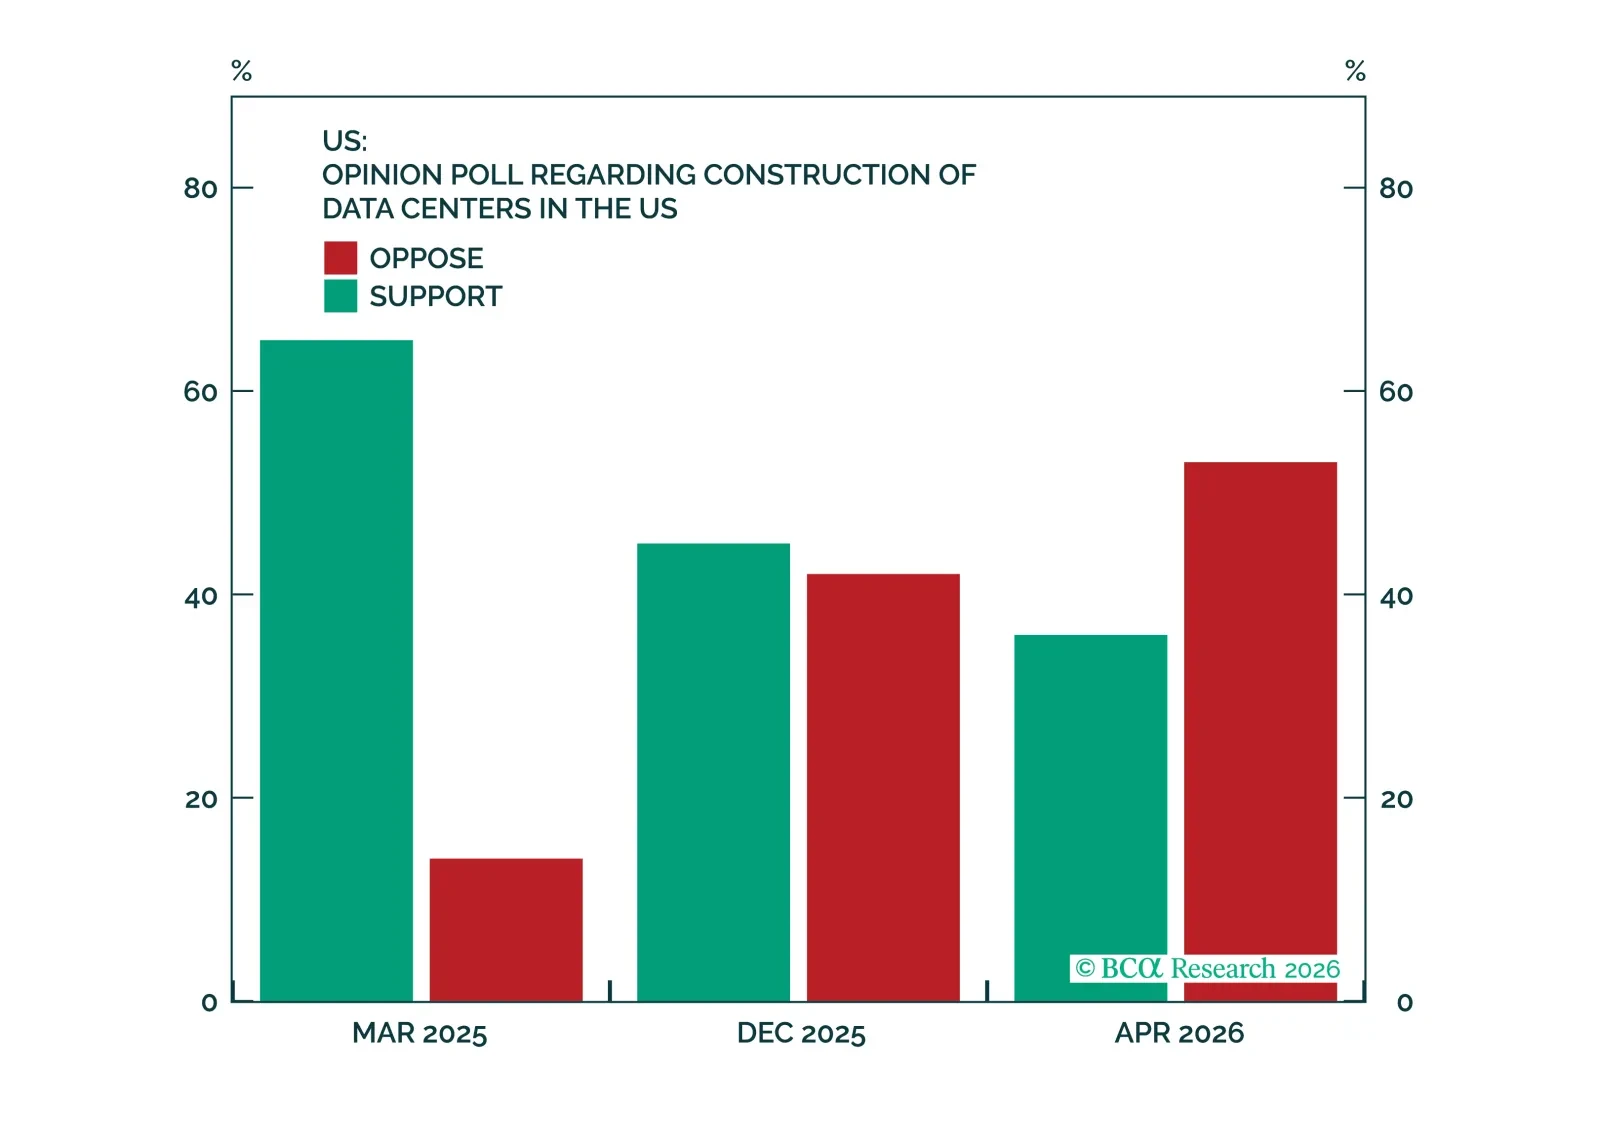
The populist backlash against AI could result in bipartisan regulation in 2027, but is especially likely to prompt tax hikes from 2029.
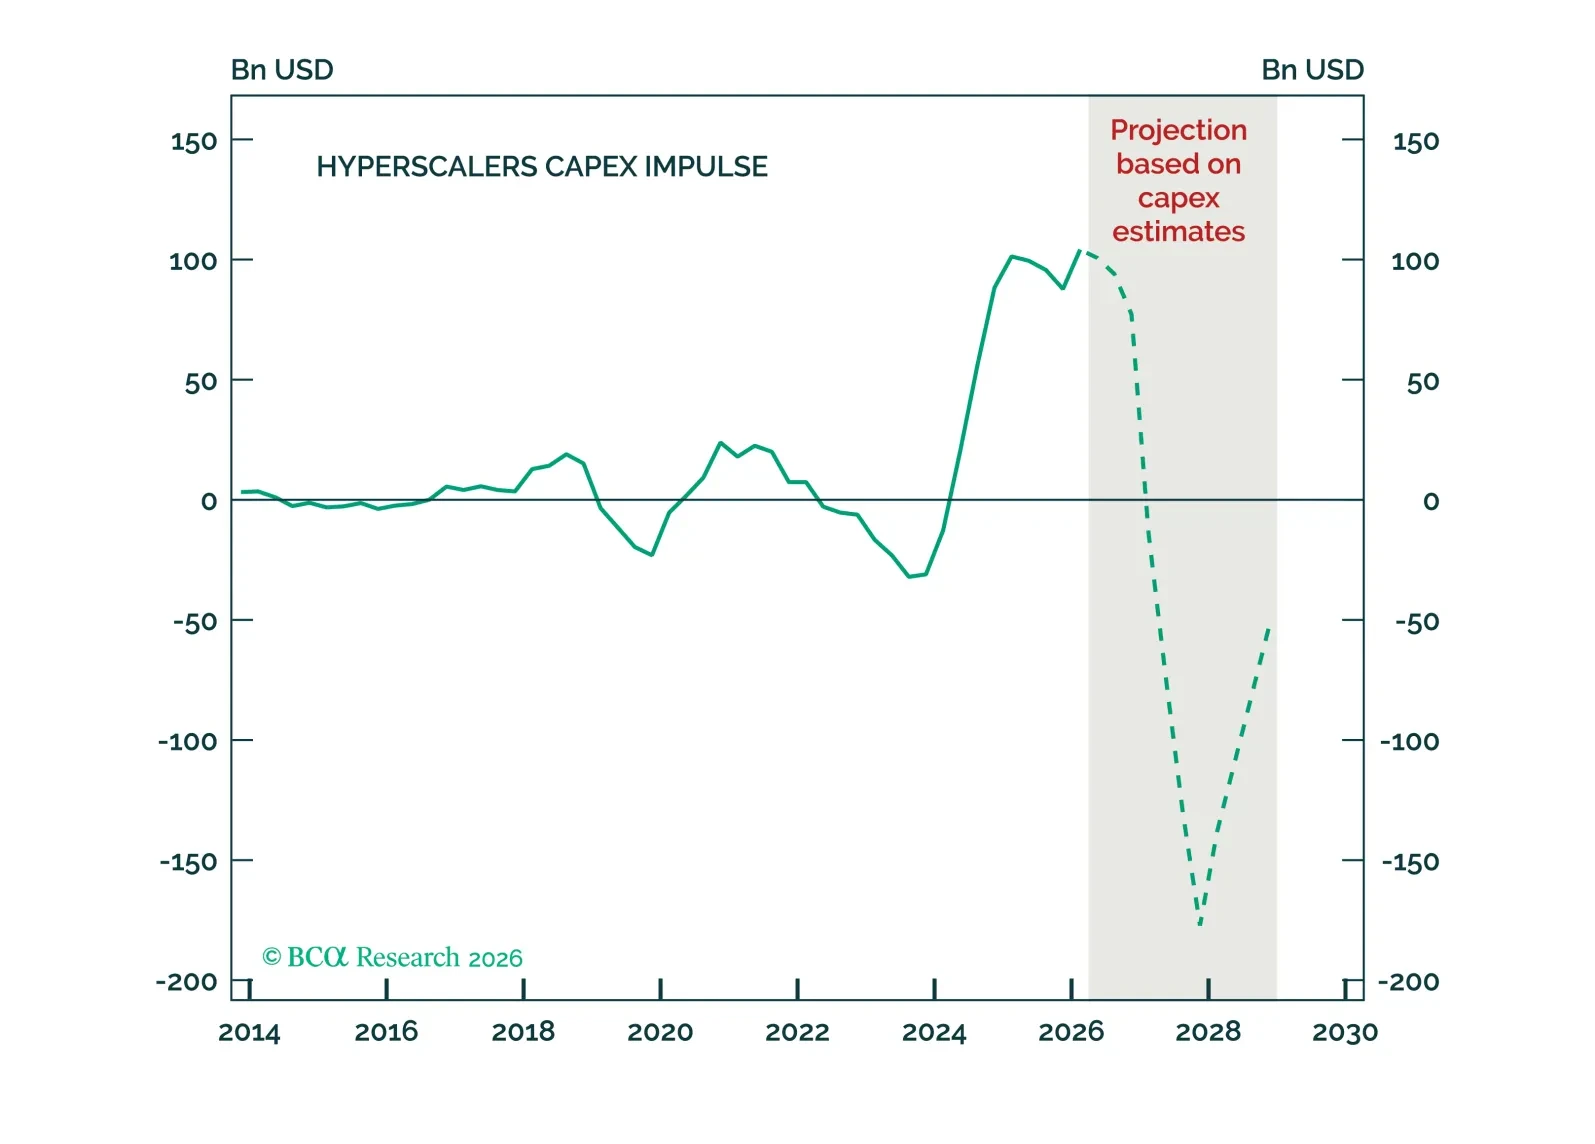
Bears will fold like lawn chairs this summer as traffic returns to Hormuz, allowing markets to overcome seasonal malaise. But we are starting to see how the expansion ends. A macro brew of global central bank tightening due to stickier-than-expected inflation, negative second derivative in AI capex, and surging supply of equities due to Monster IPOs. Expect a blow-off rally until midterms, uncertainty after, calamity in 2027.
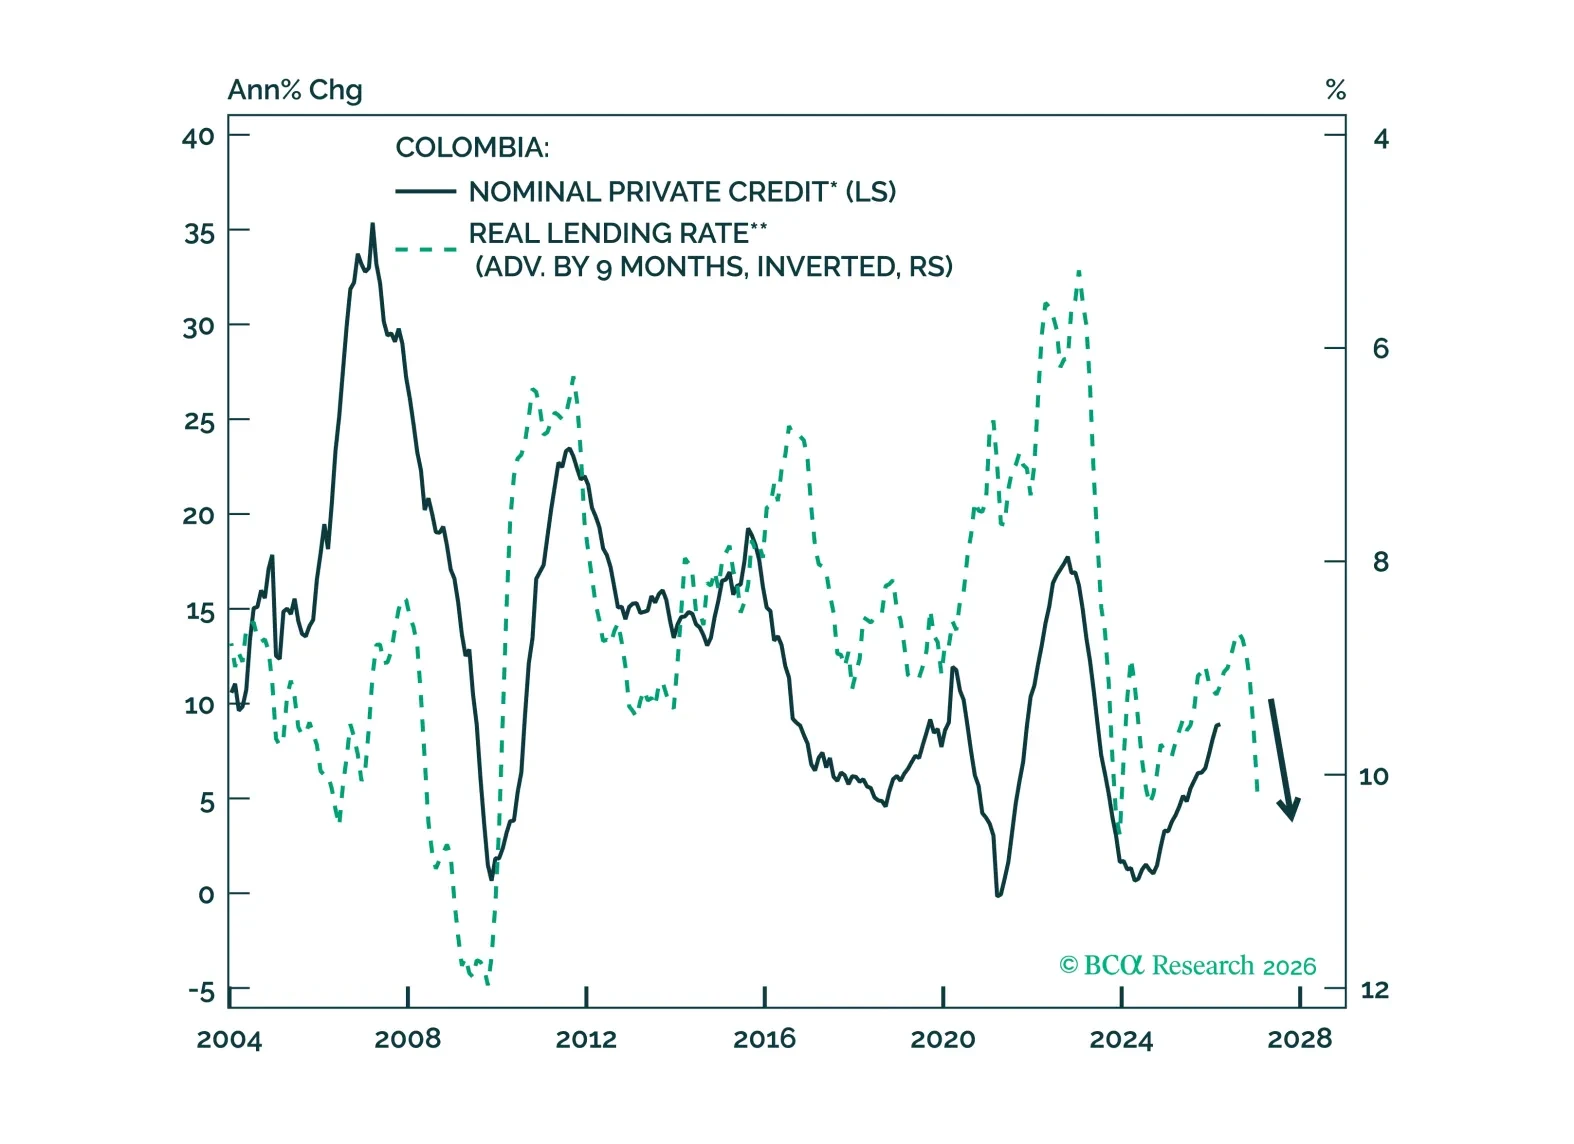
The rally in Colombia’s financial markets has a short shelf life. The election will bring a right-wing government, but it cannot fix inflation, fiscal arithmetic, or balance-of-payments vulnerabilities. Use the near-term rally to downgrade Colombian fixed income and equities.
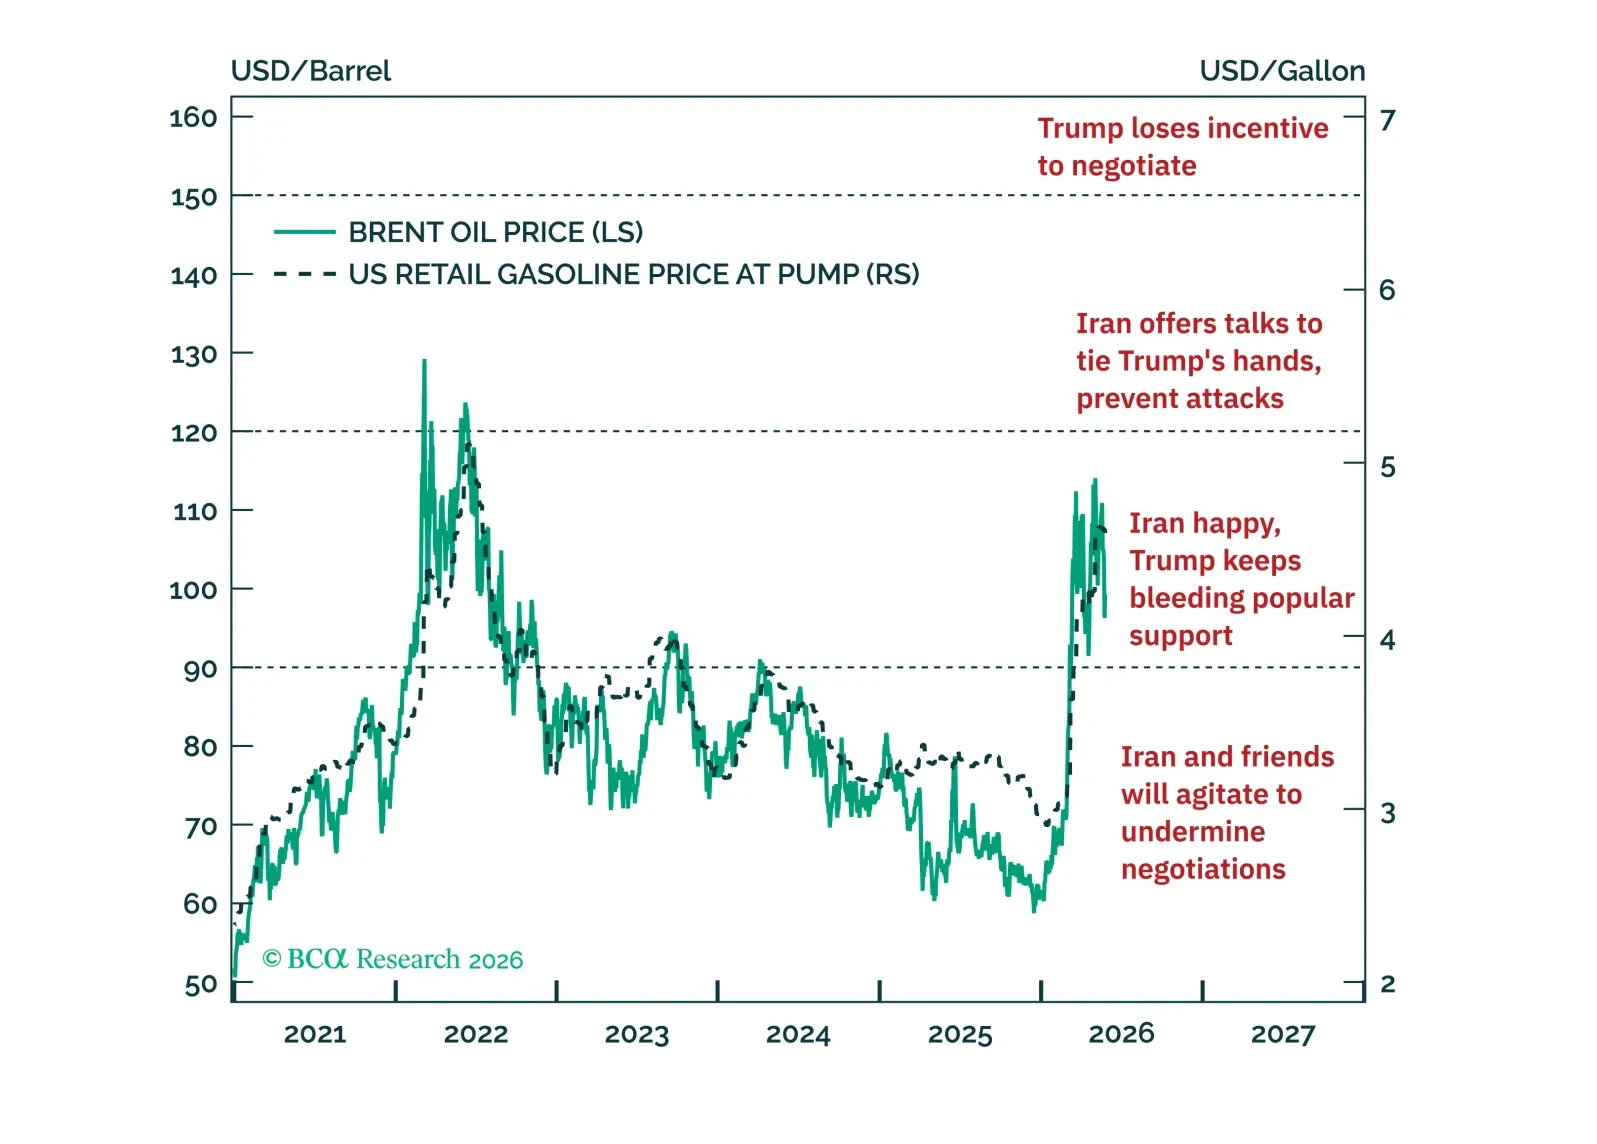
The odds of a near-term US-Iran deal have gone up slightly, but the odds of a Russian provocation that divides NATO have also gone up.
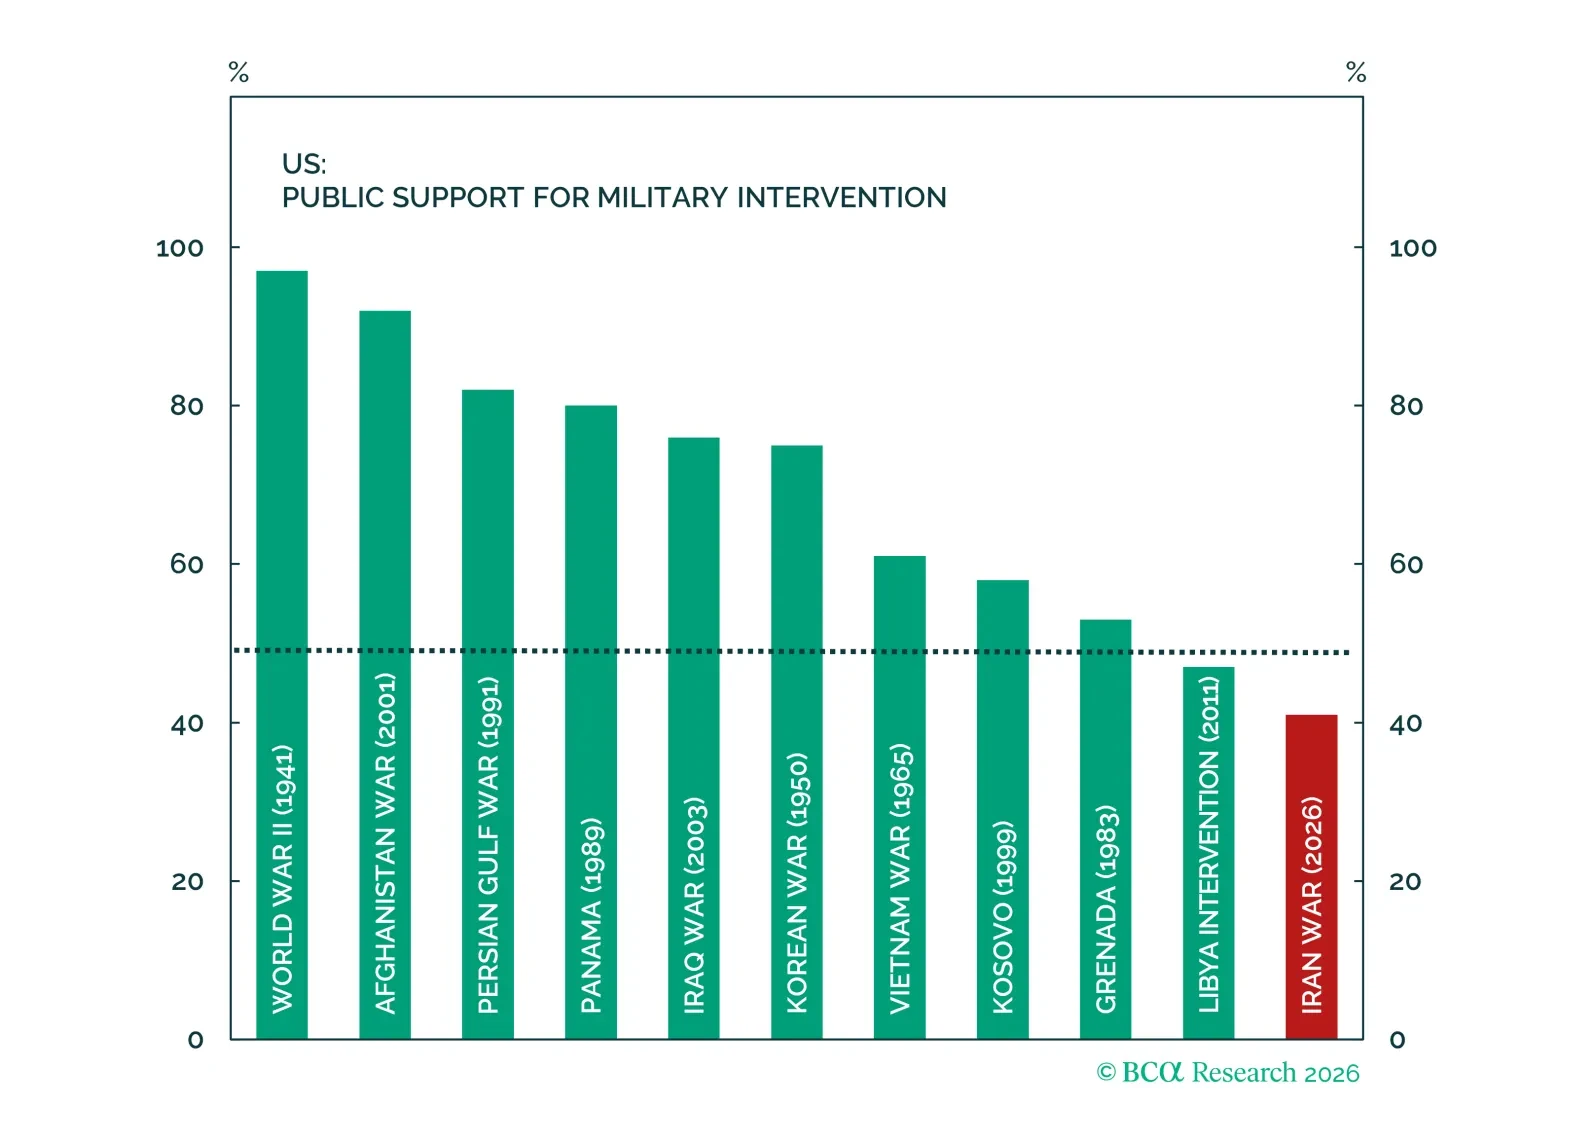
I spent the last week in London, speaking to a wide array of BCA Research clients. Throughout the early part of the week, well connected friends and sources in the Middle East warned me that a renewed US attack on Iran was imminent (by Friday, May 22, after the market close, bien sûr). Several clients with hefty AUM’s – and thus an impressive geopolitical consulting budget – in London confirmed that the US attack was all but assured.
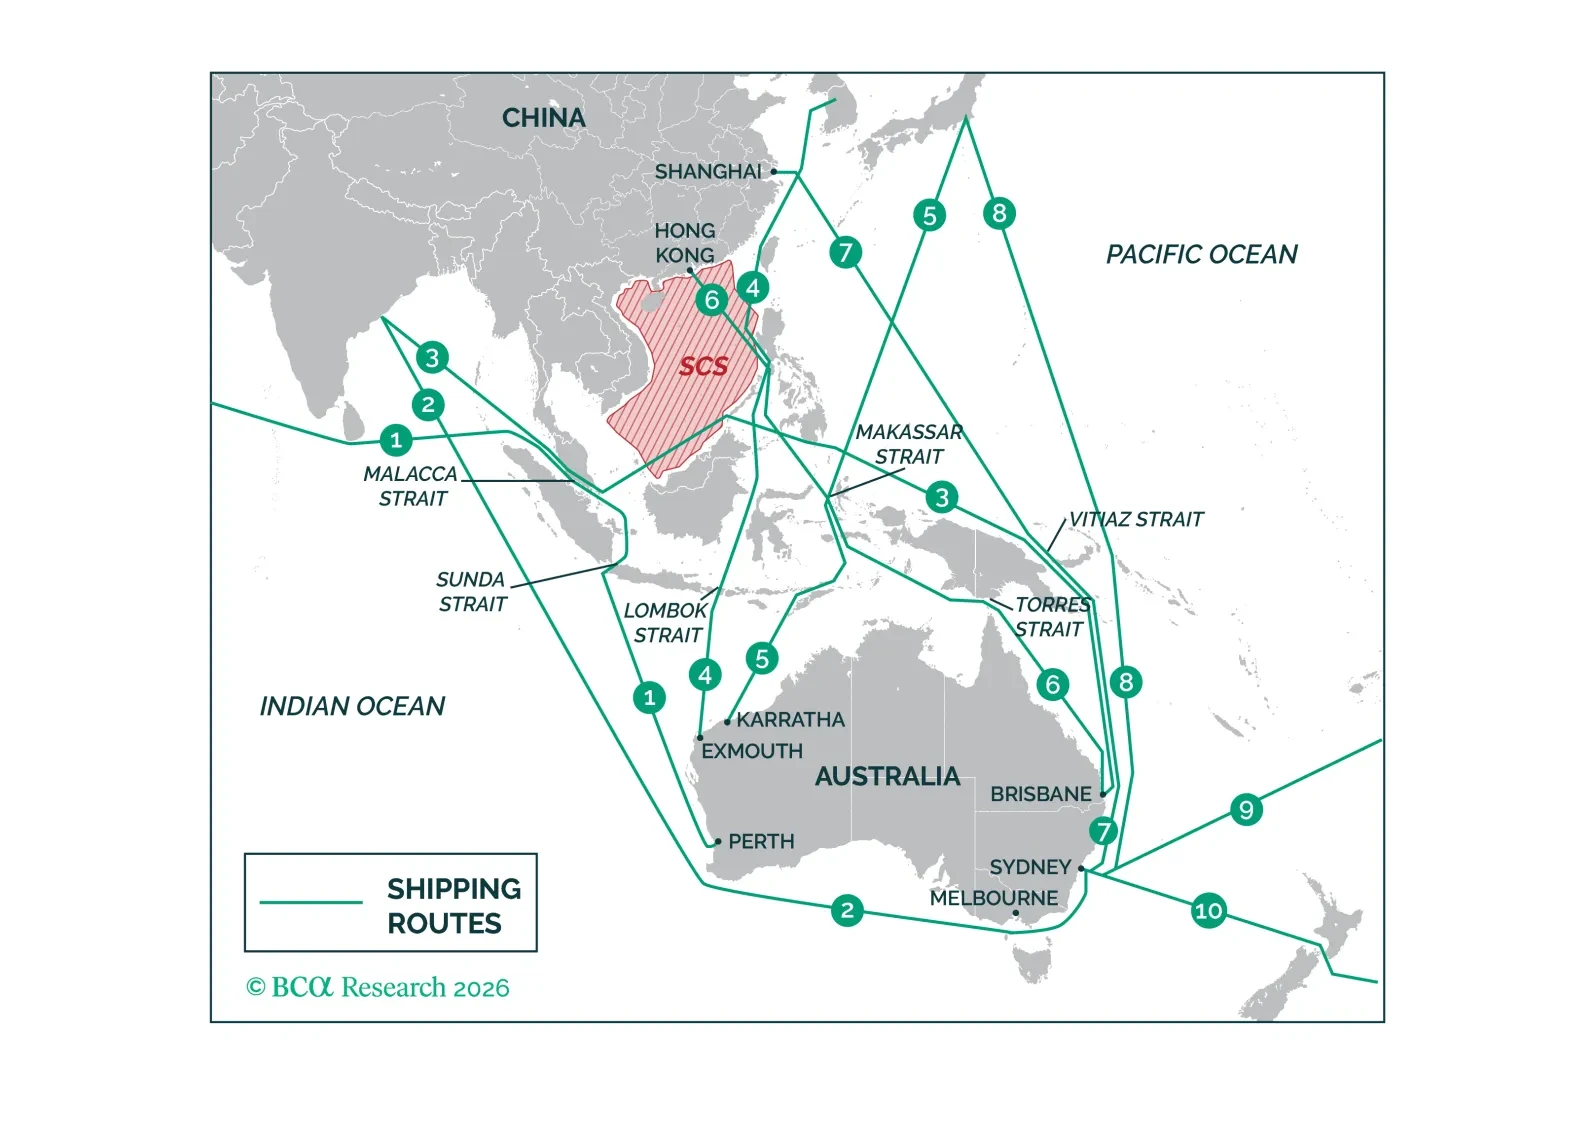
In this month’s Beta Report, we assess what that structural tension means for investors under two distinct scenarios. In our base case – a multipolar world order – Australia's position turns out to be more advantageous than it appears. The great power capital expenditure race generates demand for precisely what Australia produces. In the tail risk – a hard bipolar rupture – the calculus inverts, and the same commodity dependencies that long appeared as structural strengths begin to look like structural liabilities.
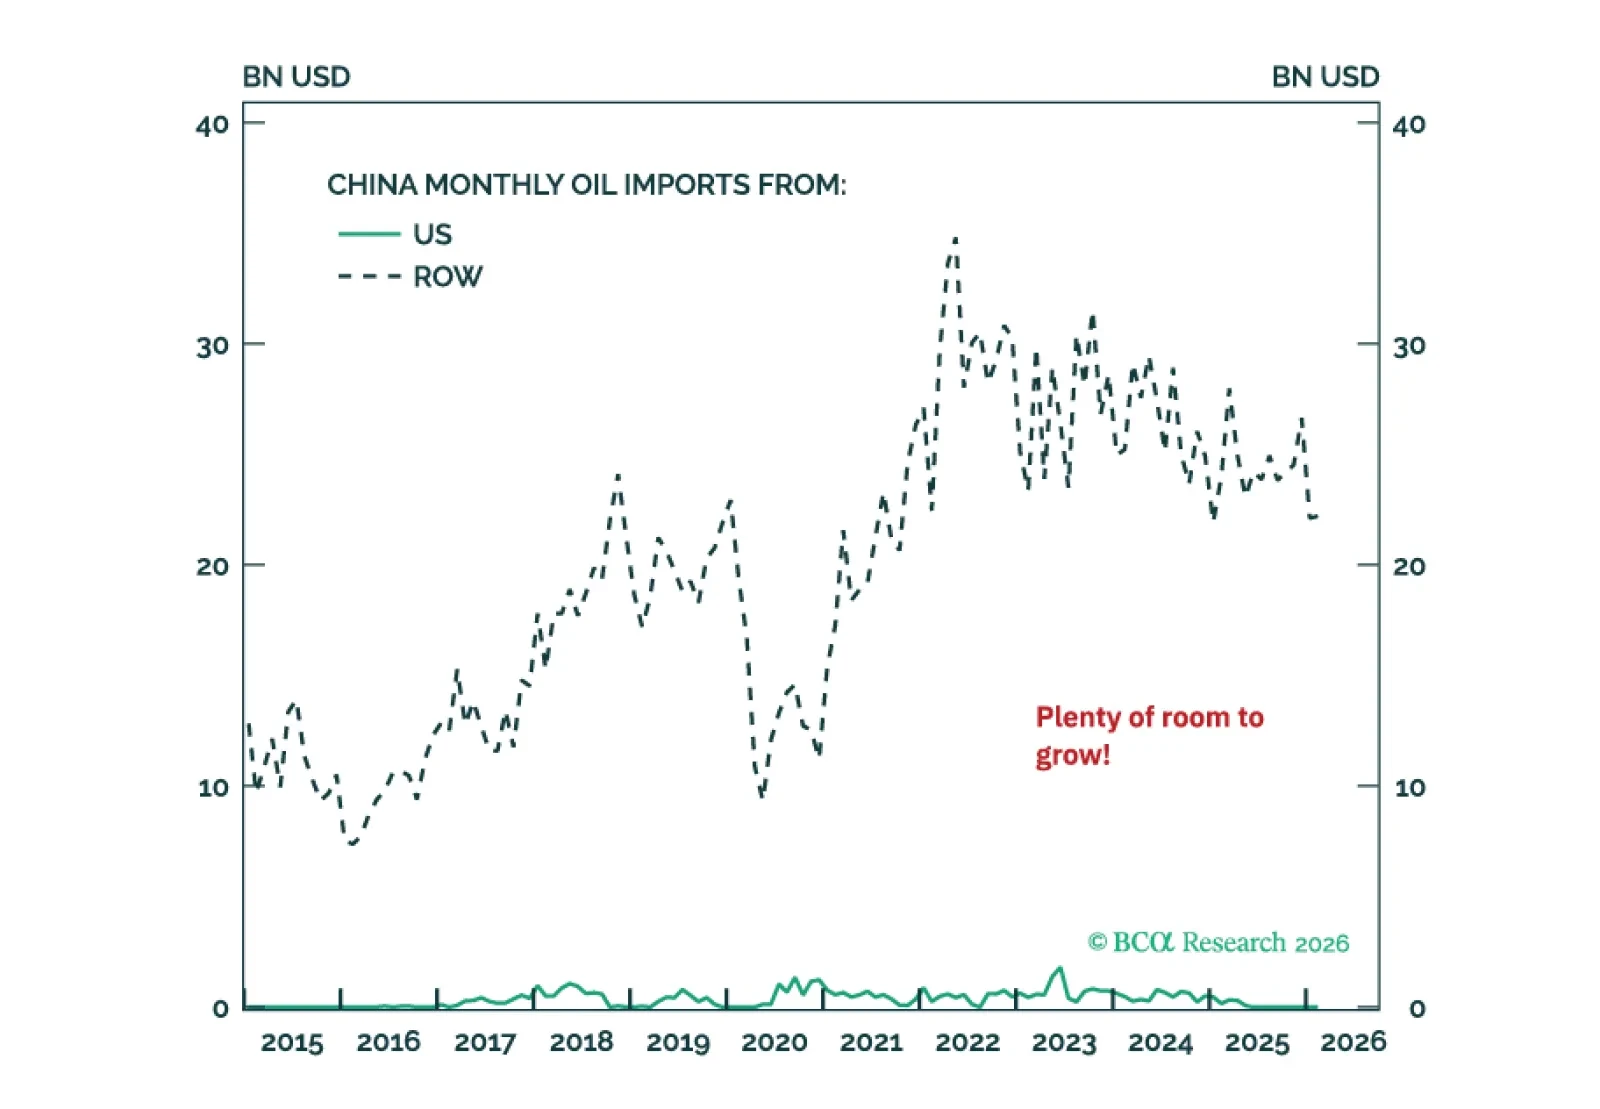
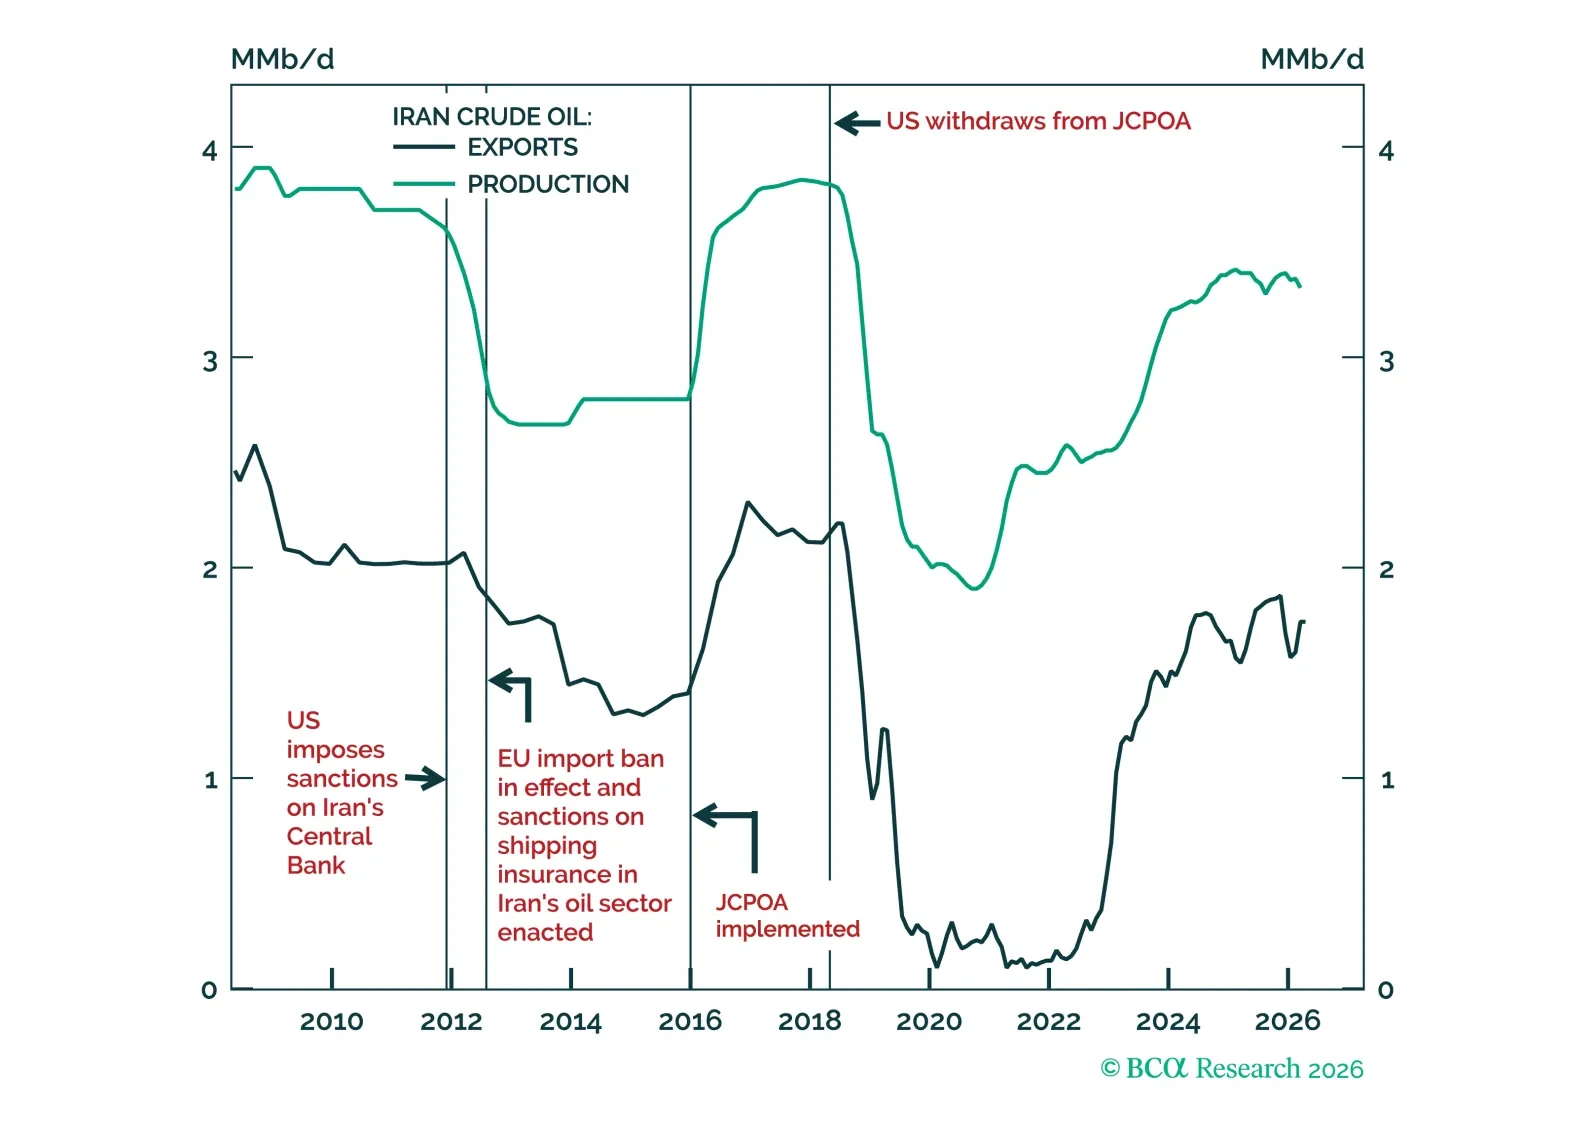
Hopes for an imminent Middle East de-escalation have capped oil prices in recent weeks, but that restraint may soon fade.