Skip to main content
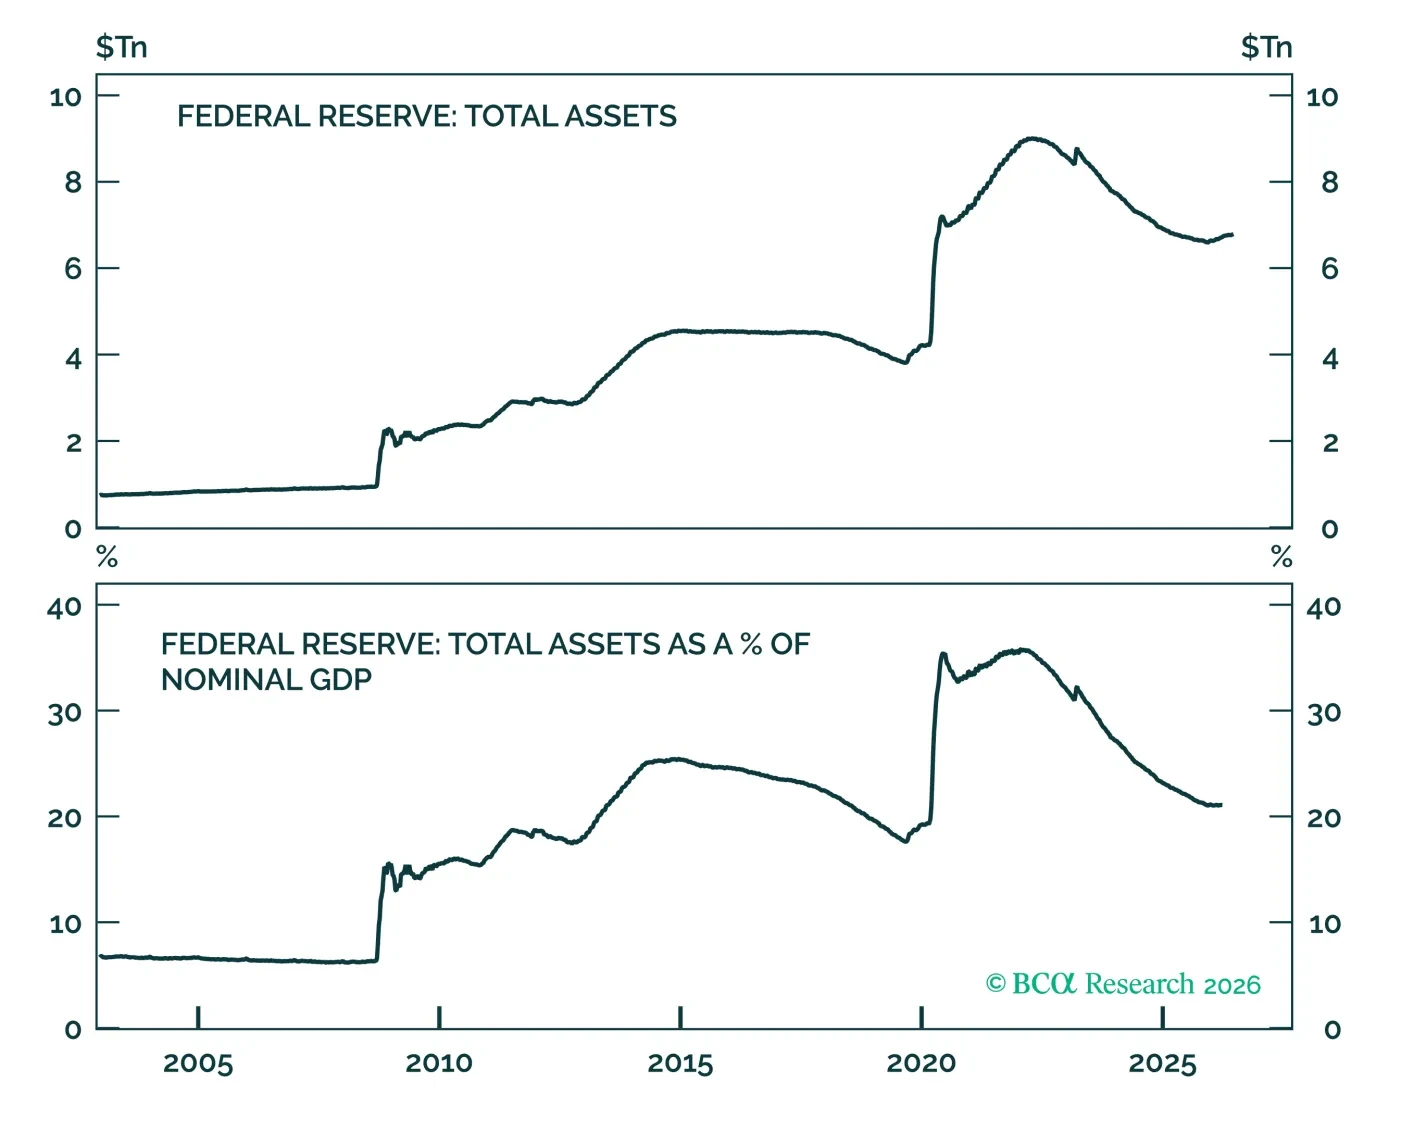
Special Report We discuss what recommendations to expect from the Fed’s balance sheet task force. We conclude that any future balance sheet consolidation will be smaller than many anticipate.
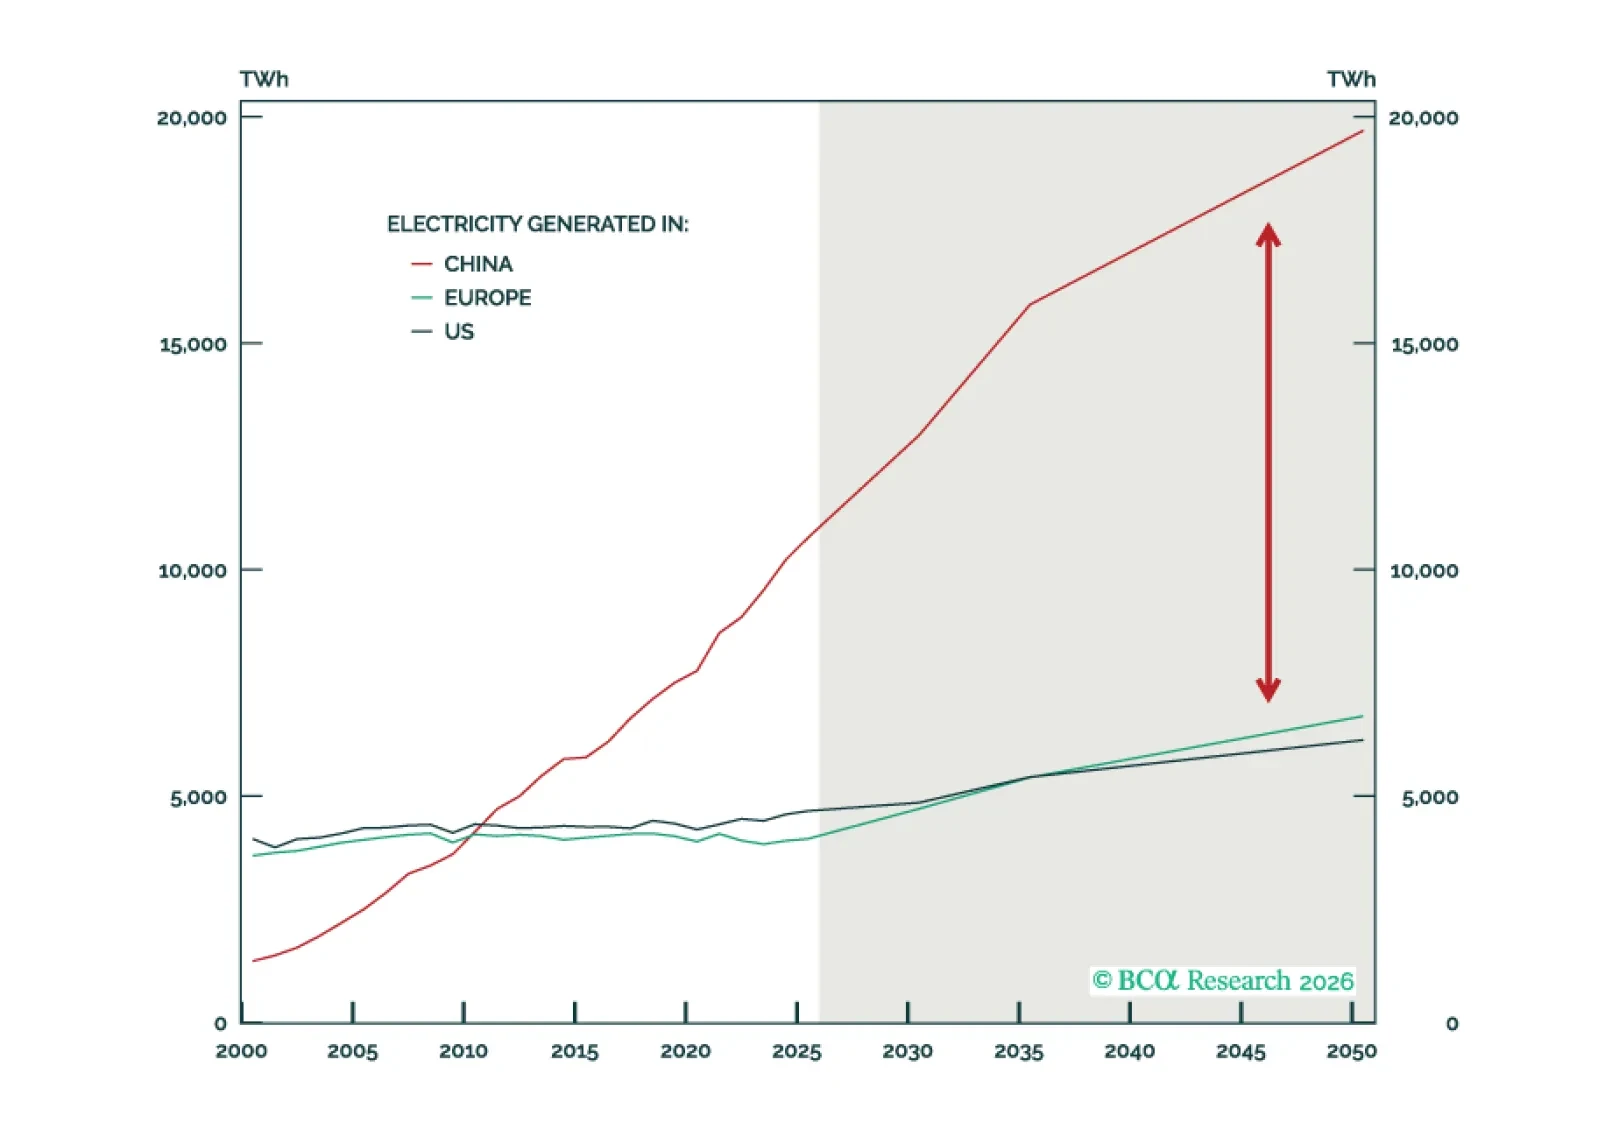
Special Report China holds a structural advantage in this "Age of Electricity" by operating the world's largest electricity system. However, this advantage has inherent limits, and the US remains competitive despite its challenges.
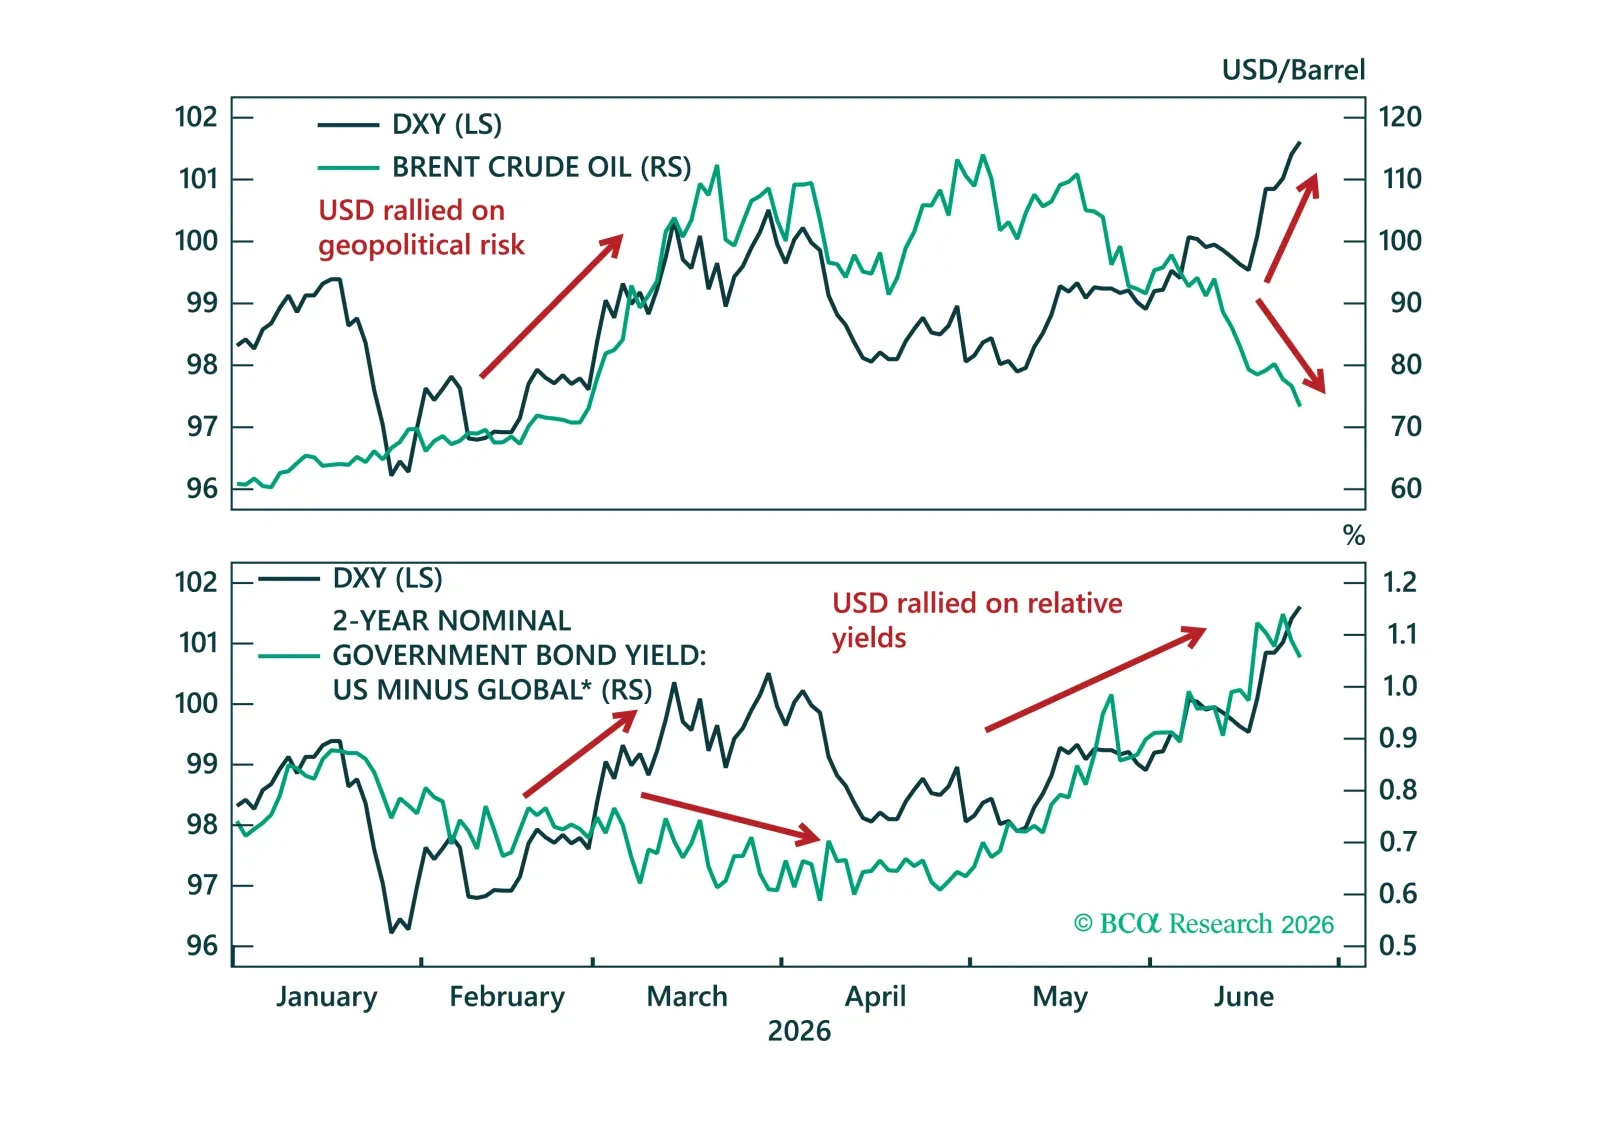
The dollar has had a strong run but its key supports from Fed repricing, positioning, and terms of trade are starting to fade. We close our tactical long USD positions and turn to short USD/JPY, where intervention risk makes yen shorts look increasingly dangerous.
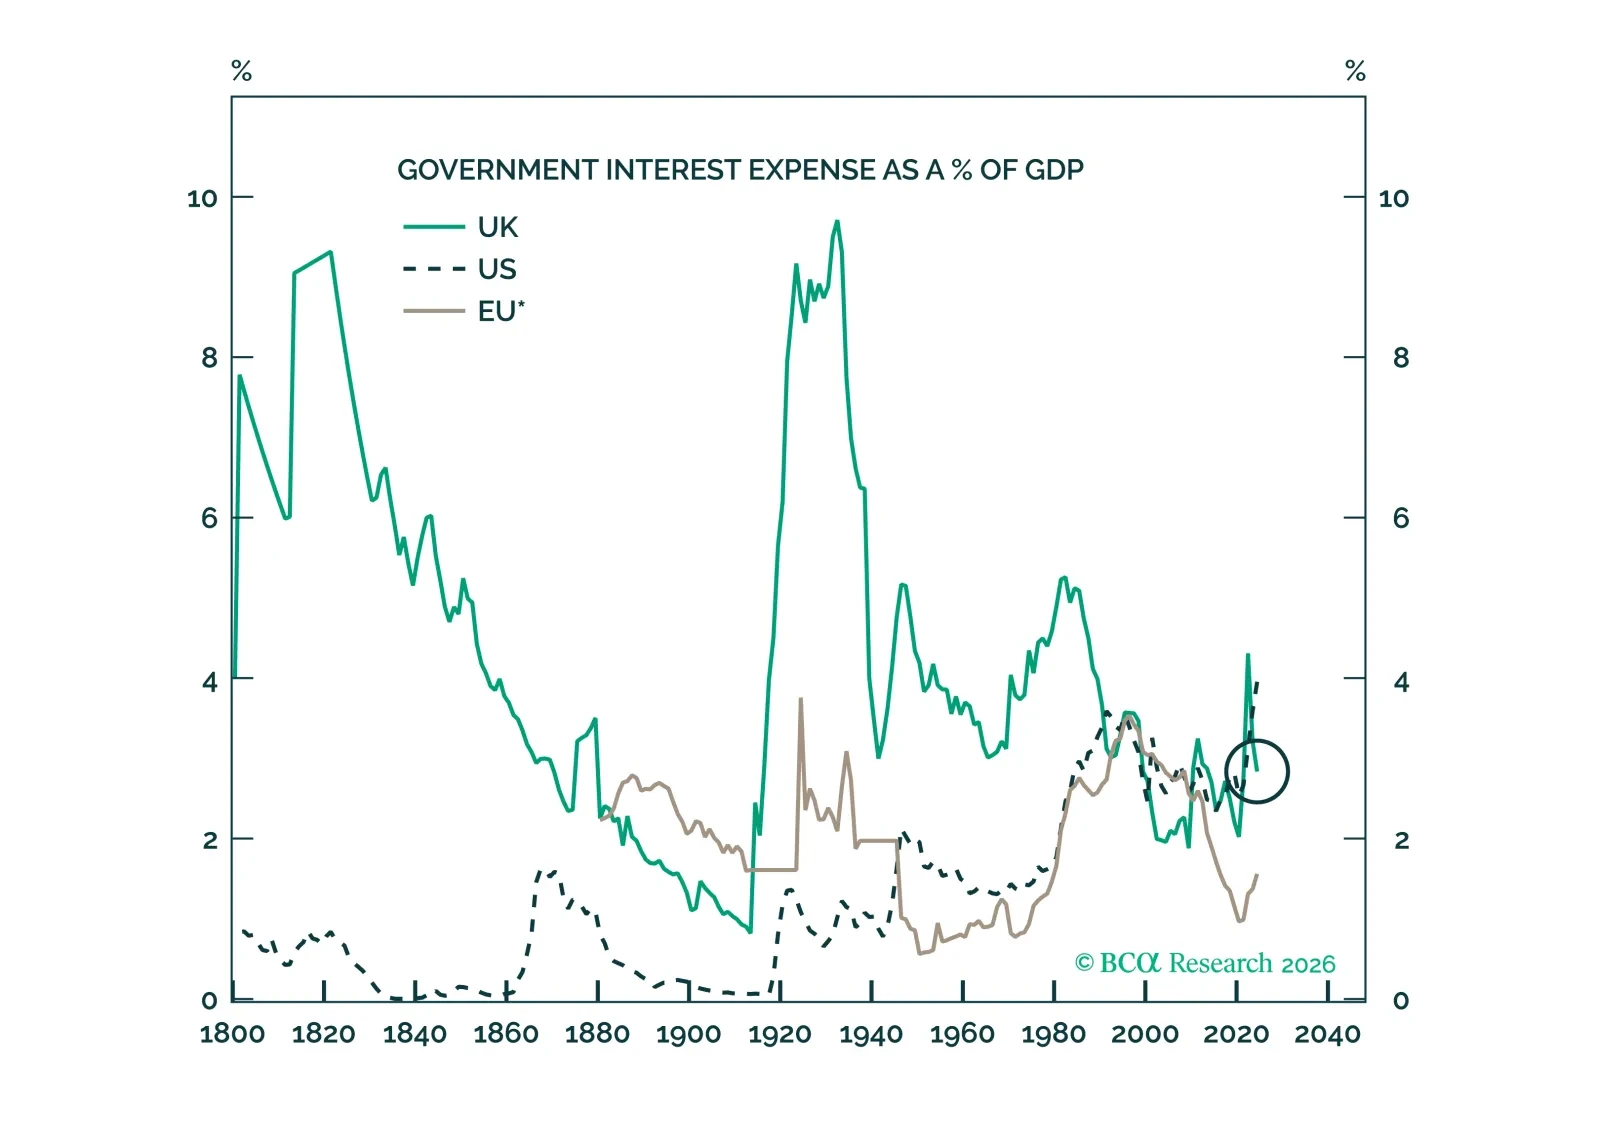
Stay overweight gilts despite renewed political turmoil in the UK.
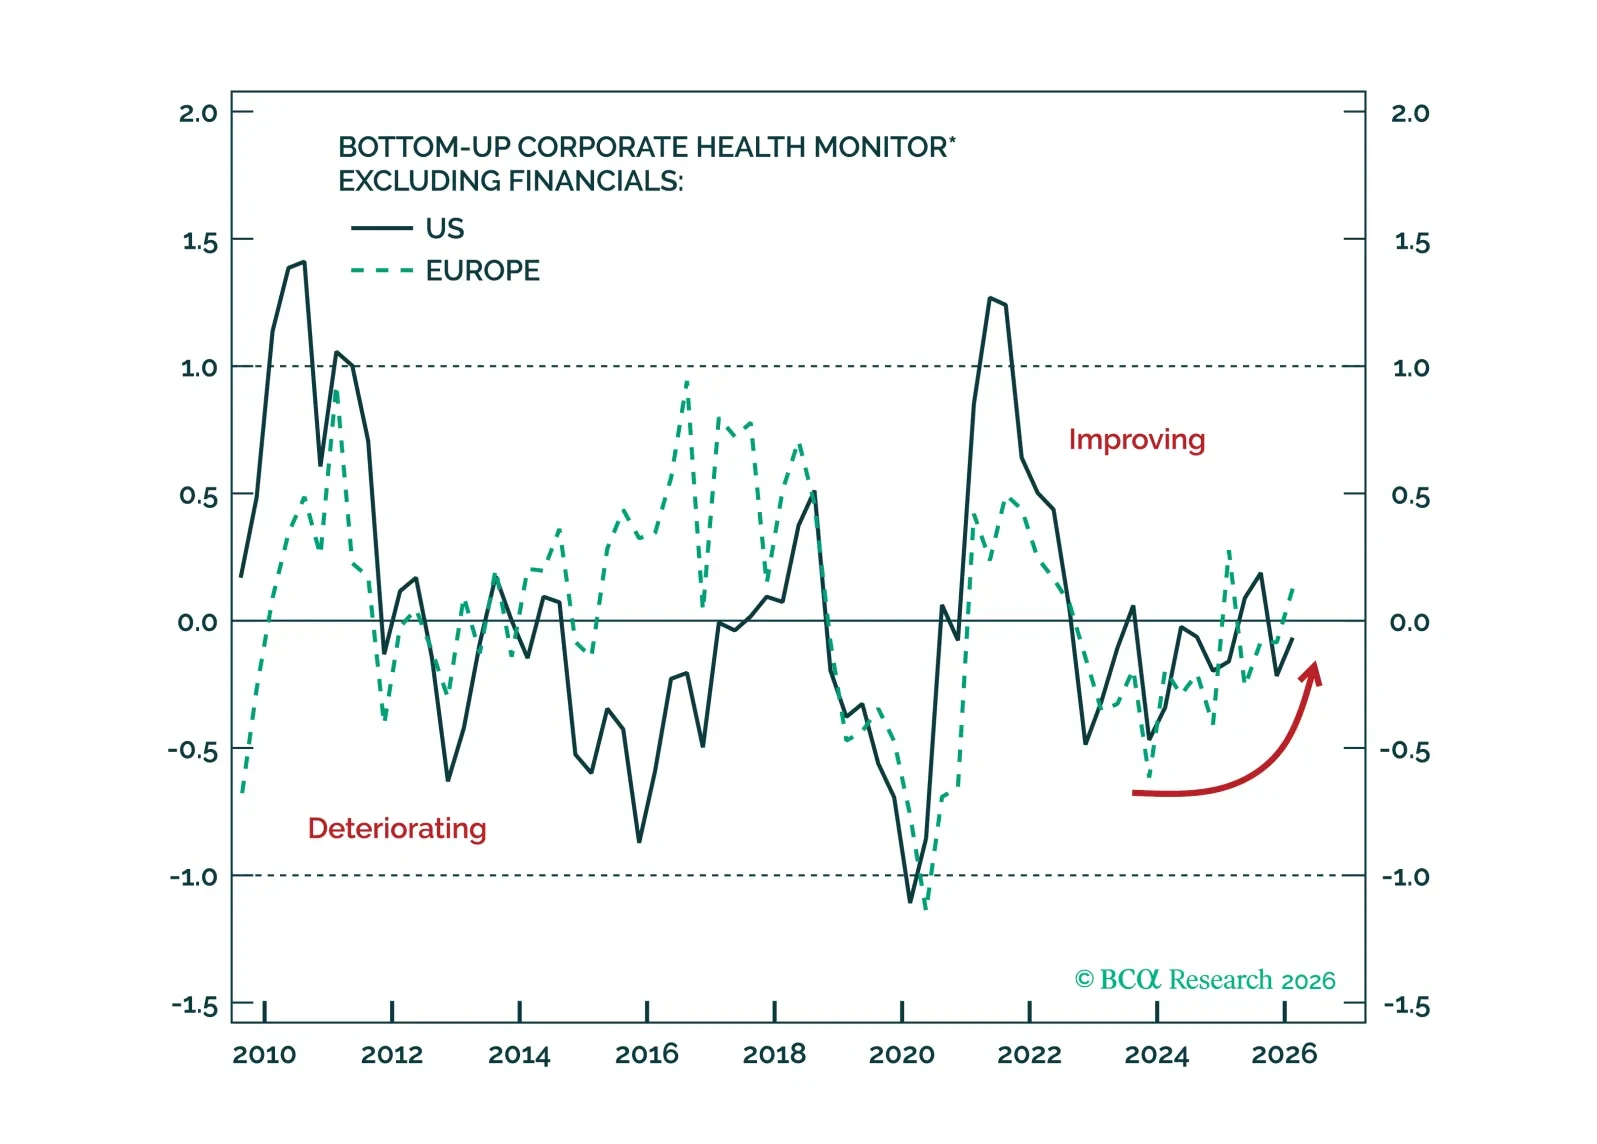
Special Report Corporate health remains supportive of tight credit spreads in both the US and Europe, but a growing divide is emerging beneath the surface. Investment-grade issuers continue to strengthen, while lower-rated borrowers face mounting pressures. Credit markets are pricing resilience, leaving investors vulnerable should corporate fundamentals begin to deteriorate.
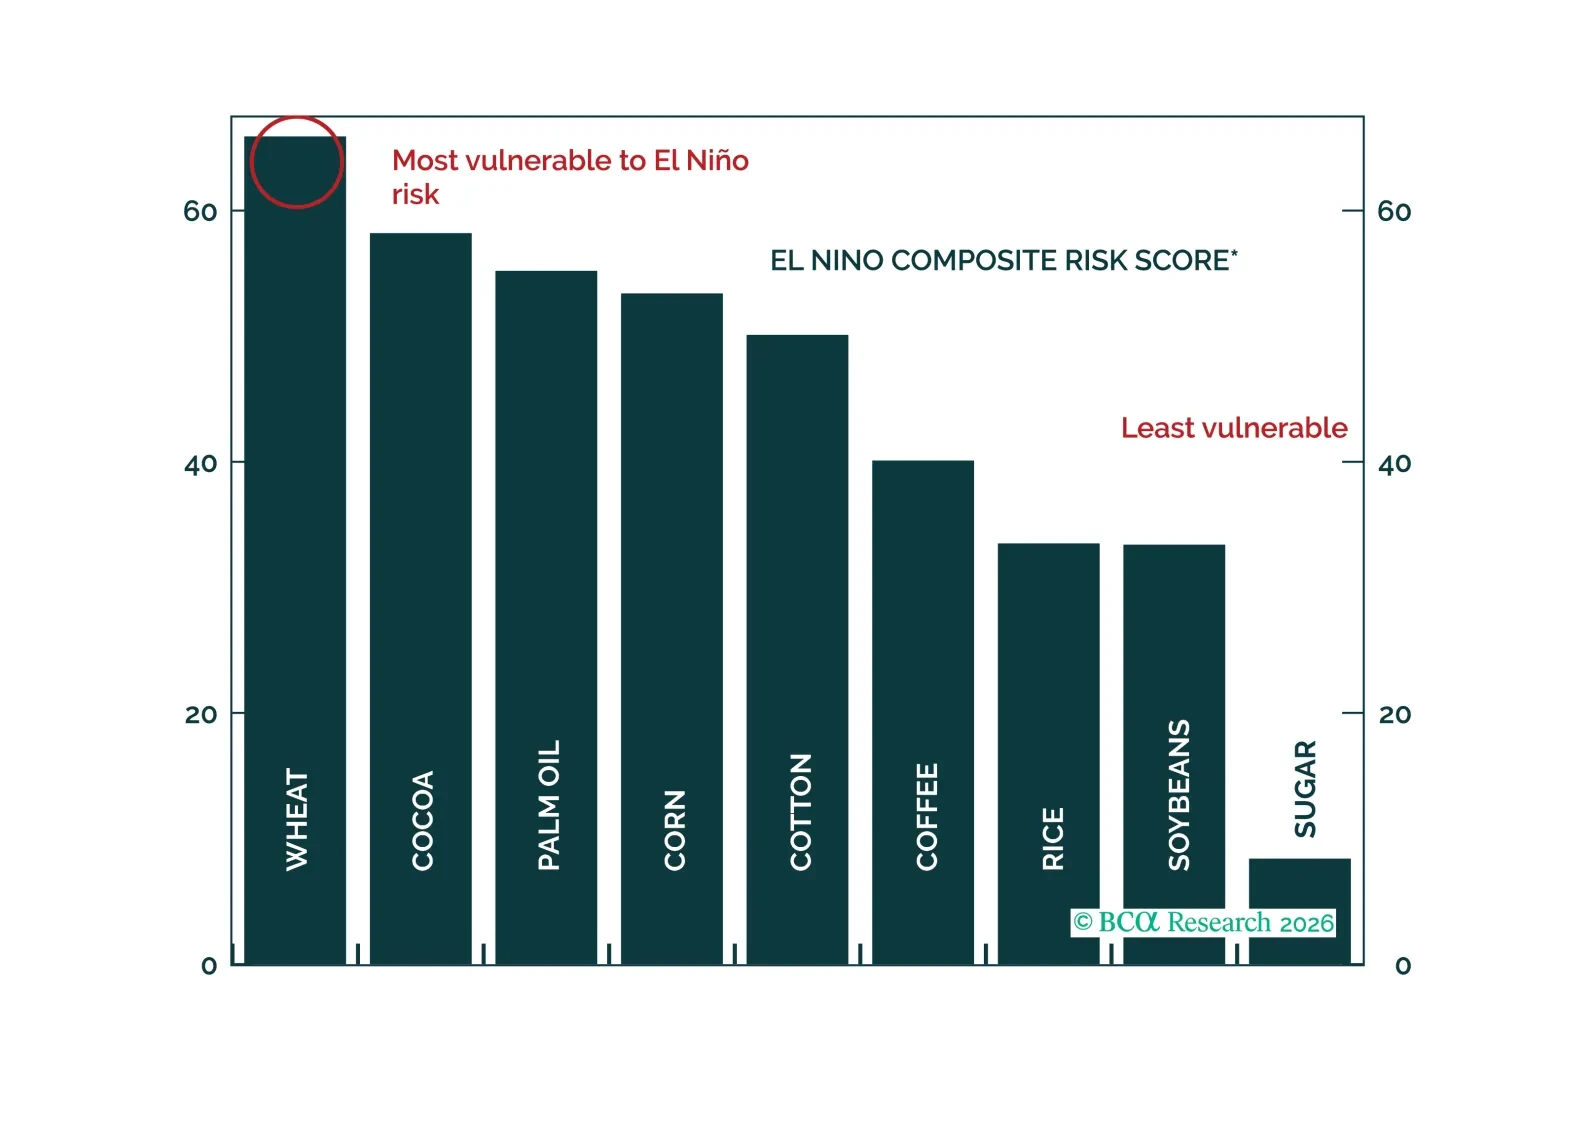
Special Report The risk of a “super El Niño” represents a meaningful threat to agricultural markets. Wheat, cocoa, and palm oil appear particularly vulnerable to El Niño-related supply disruptions. A rise in food prices could also generate political — and potentially geopolitical — reverberations across frontier and emerging markets, where food prices are far more relevant than in developed economies.
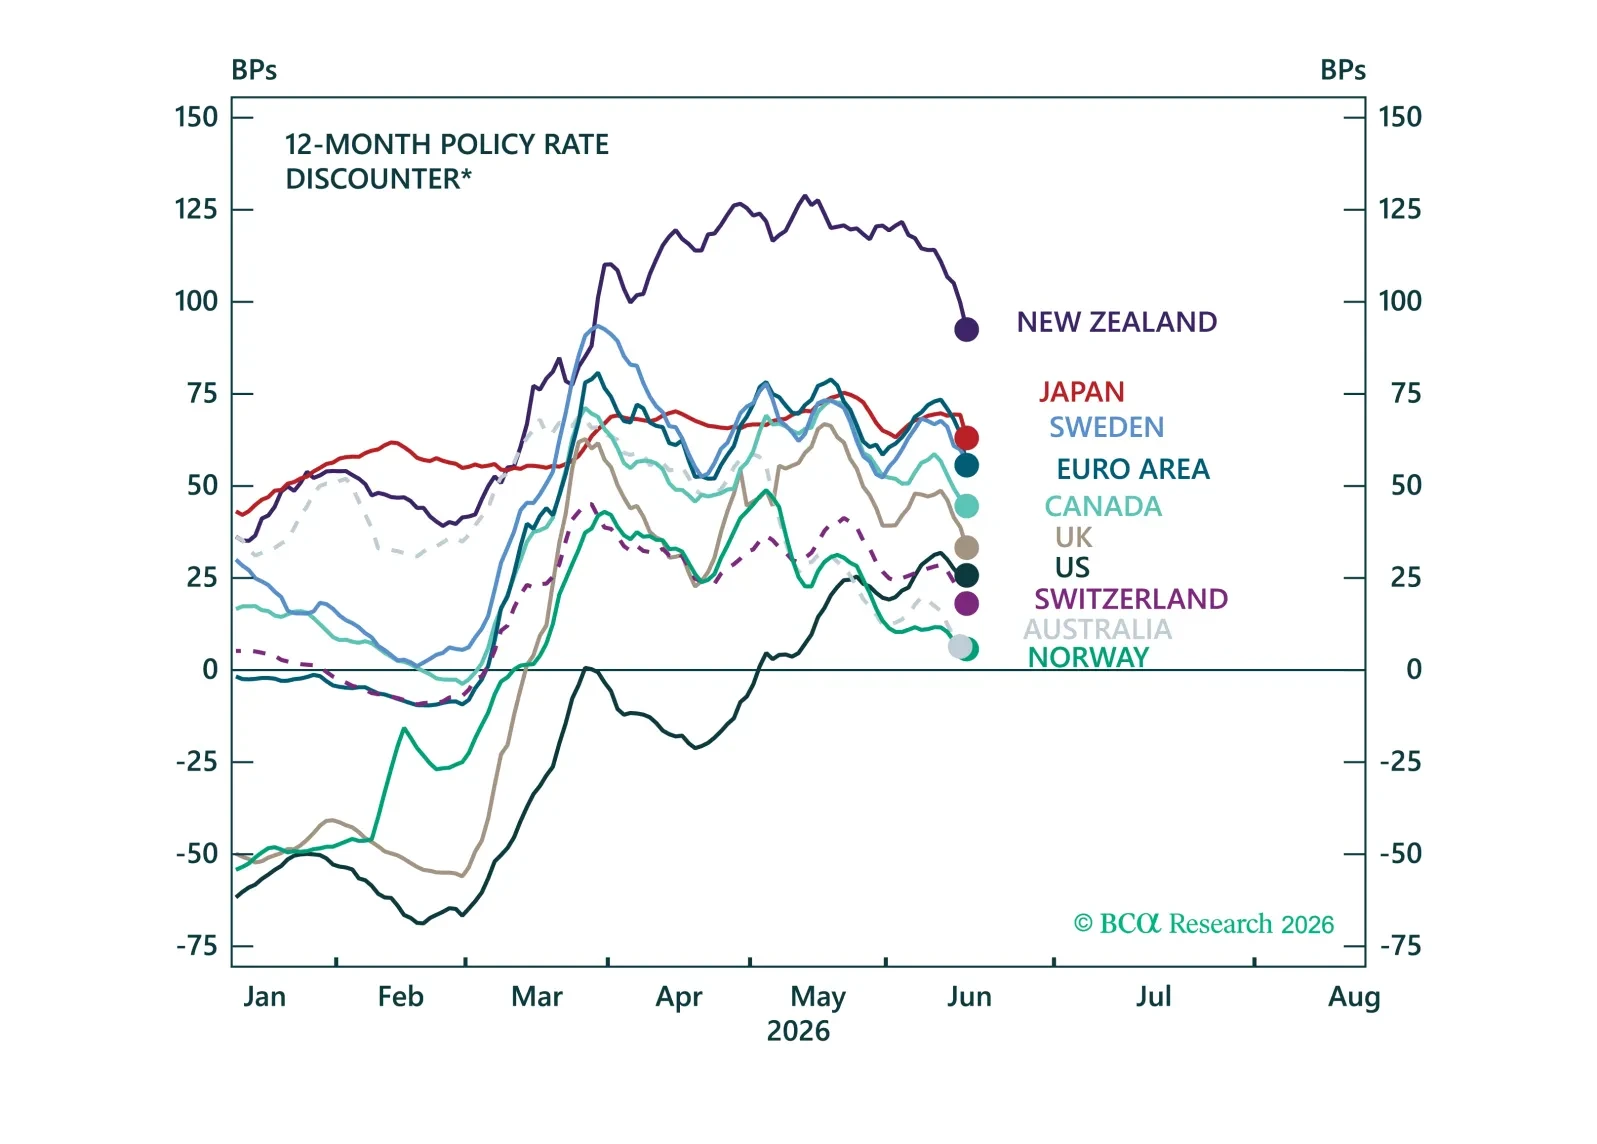
We react to DM central bank meetings this week and highlight the opportunities emerging across global fixed income and currency markets.
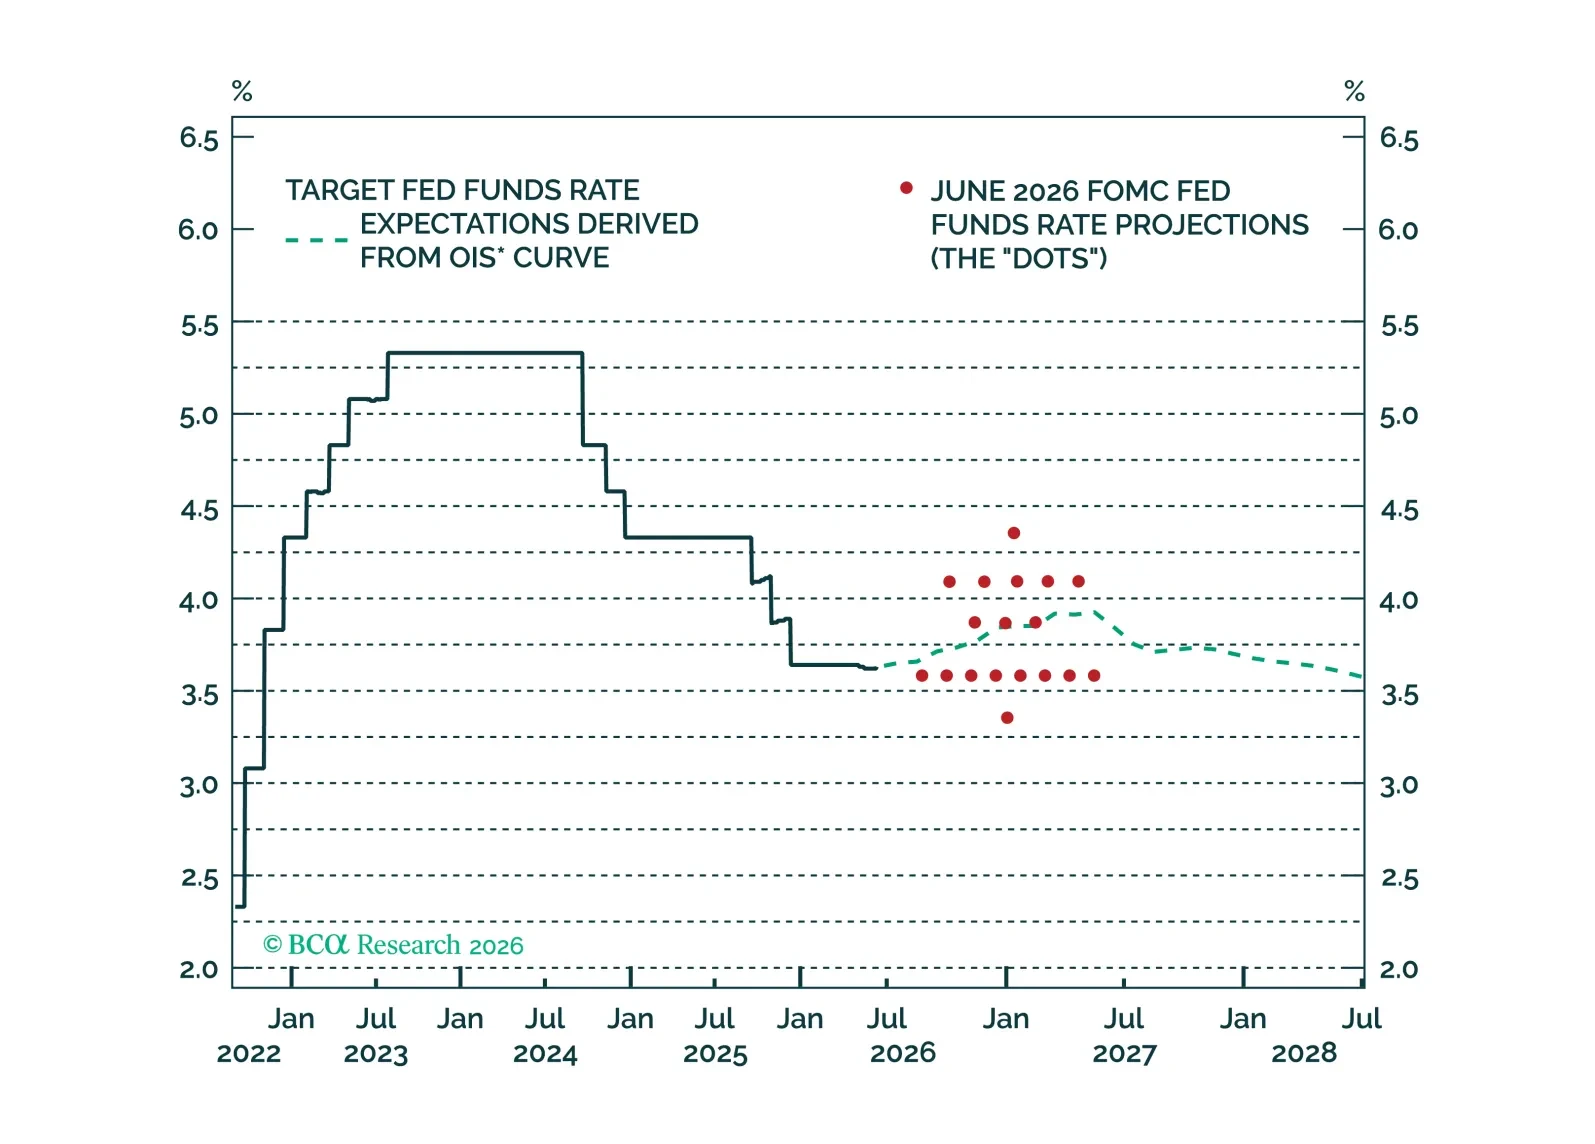
Kevin Warsh announced an ambitious reform agenda for the Federal Reserve. We discuss the potential impact and the current outlook for interest rates.
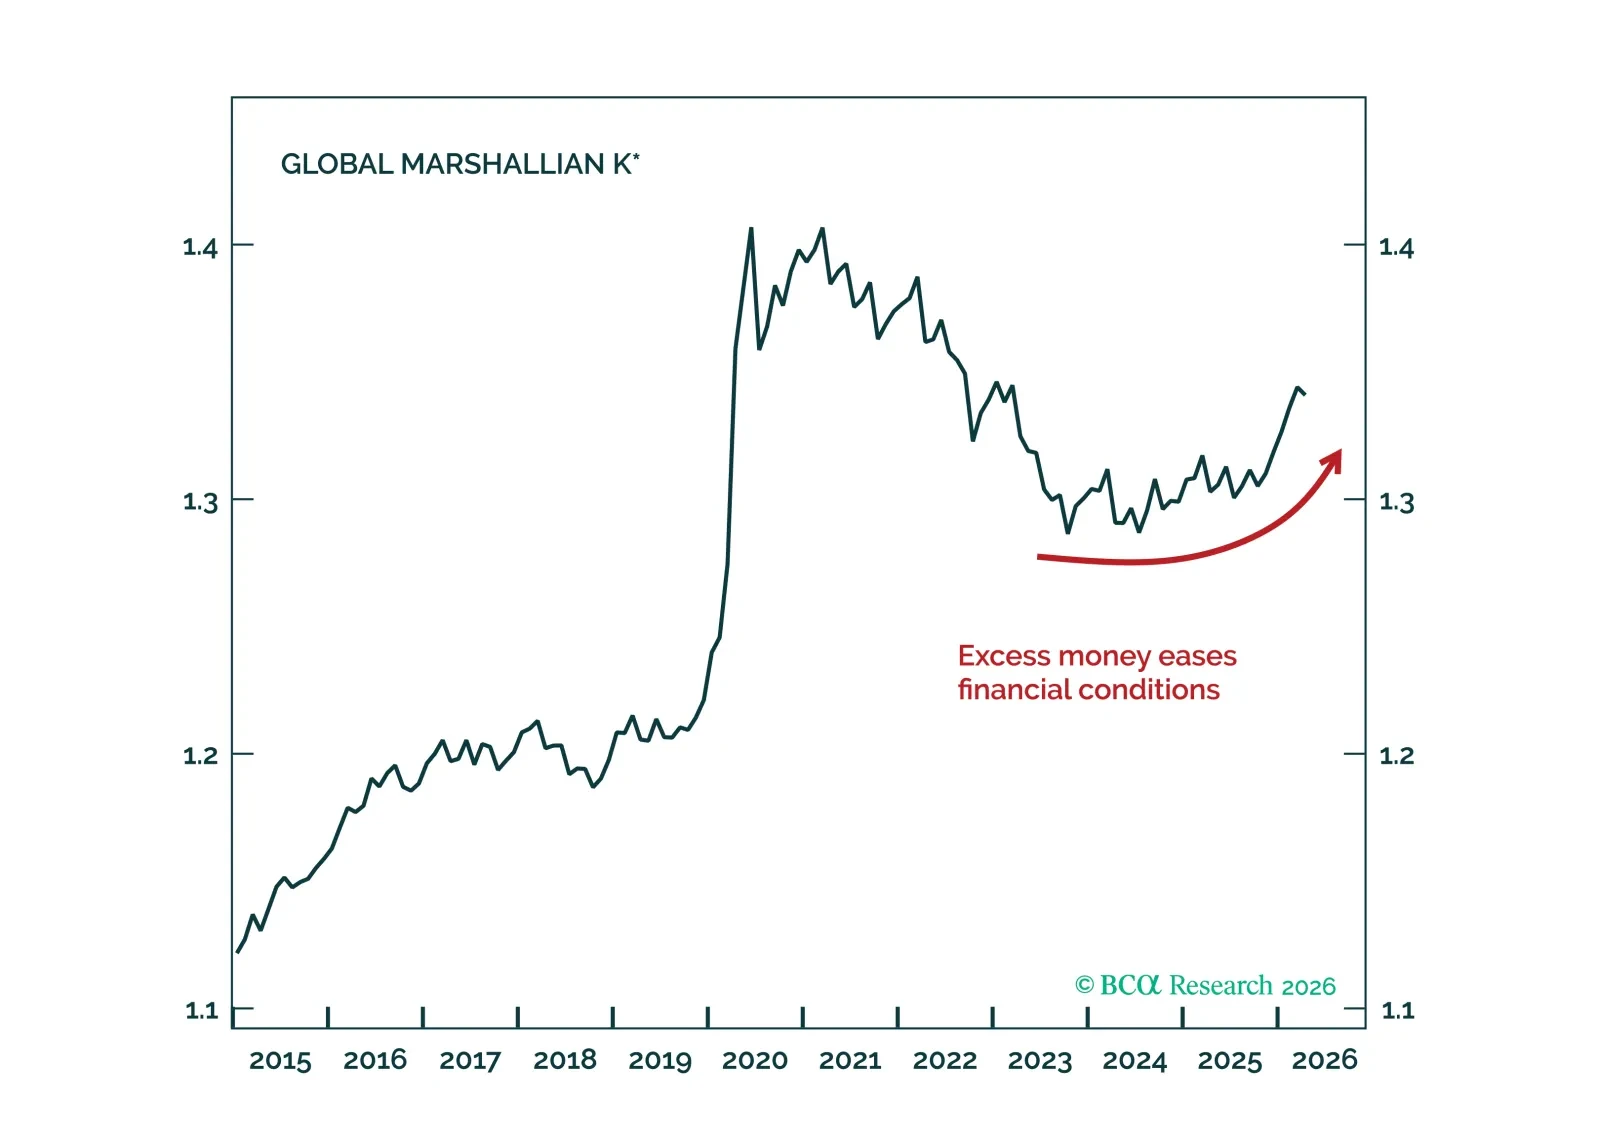
Special Report Markets keep buying the dip because liquidity remains plentiful. That buffer lasts through 2026; the bigger question is what happens when it thins in 2027.
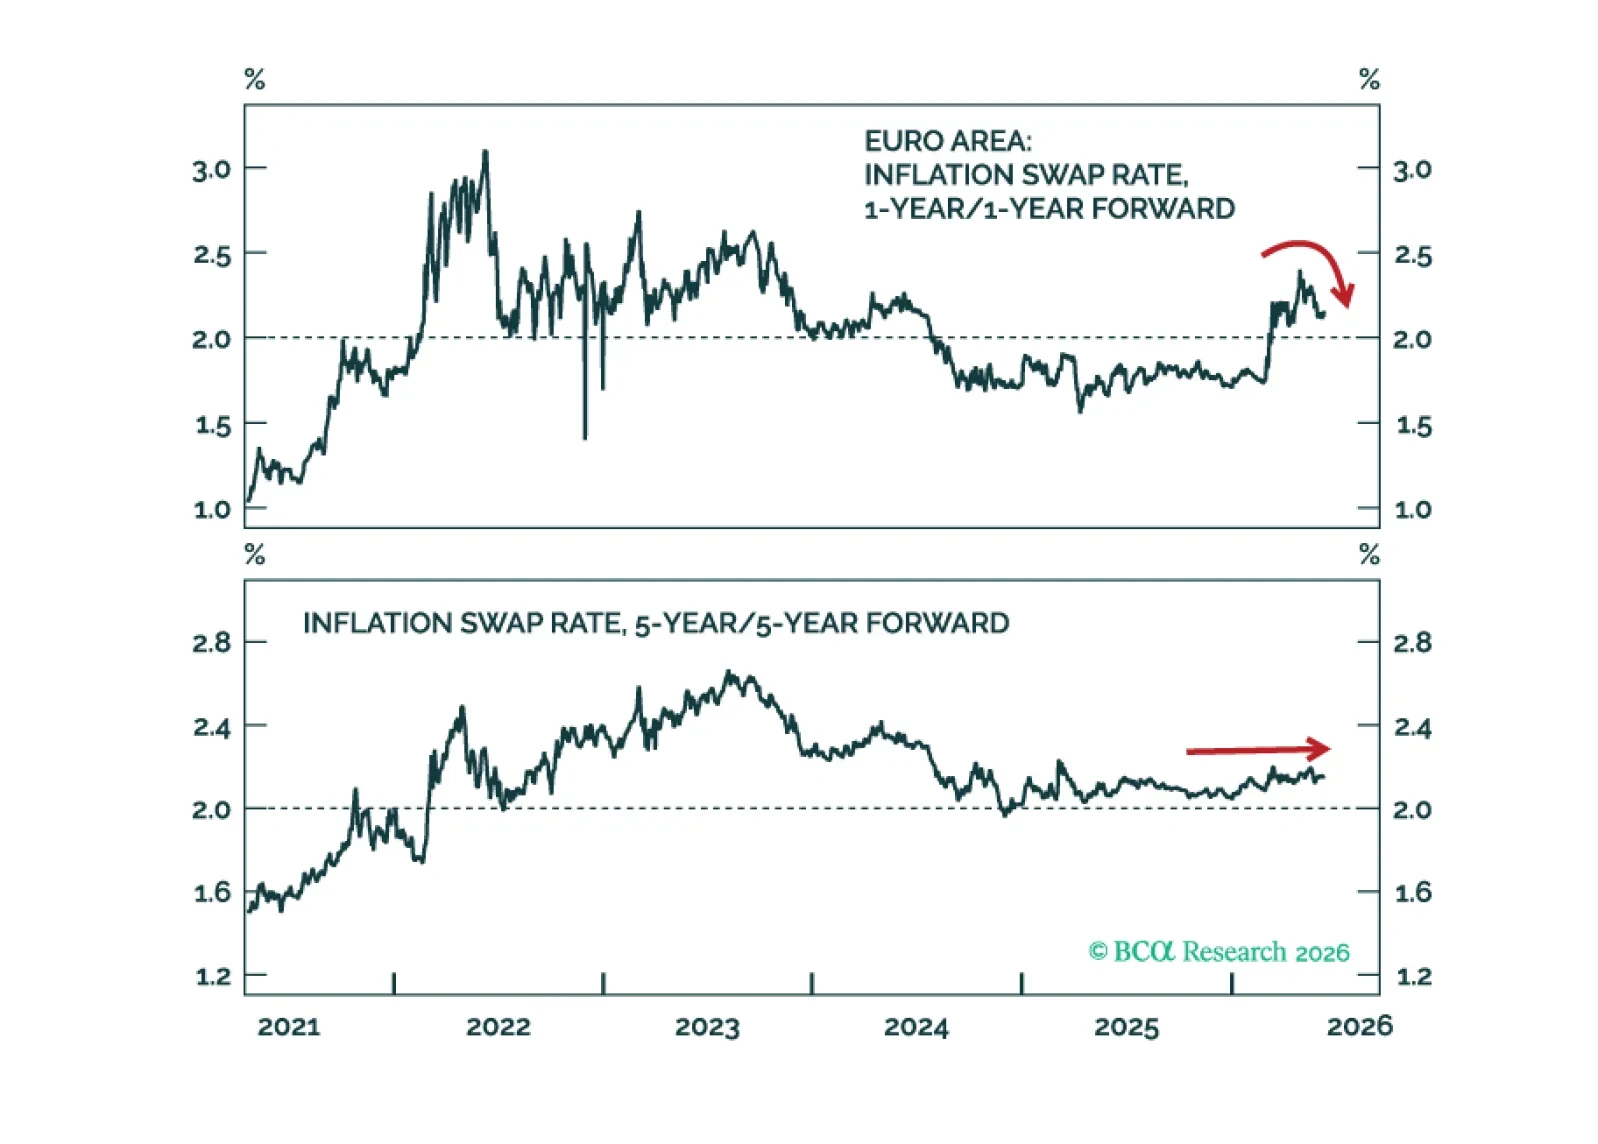
Today’s ECB rate hike is not the beginning of a hiking cycle. Growth concerns will soon move to the forefront of ECB policy decisions, preventing further tightening.