FICC
Find out more
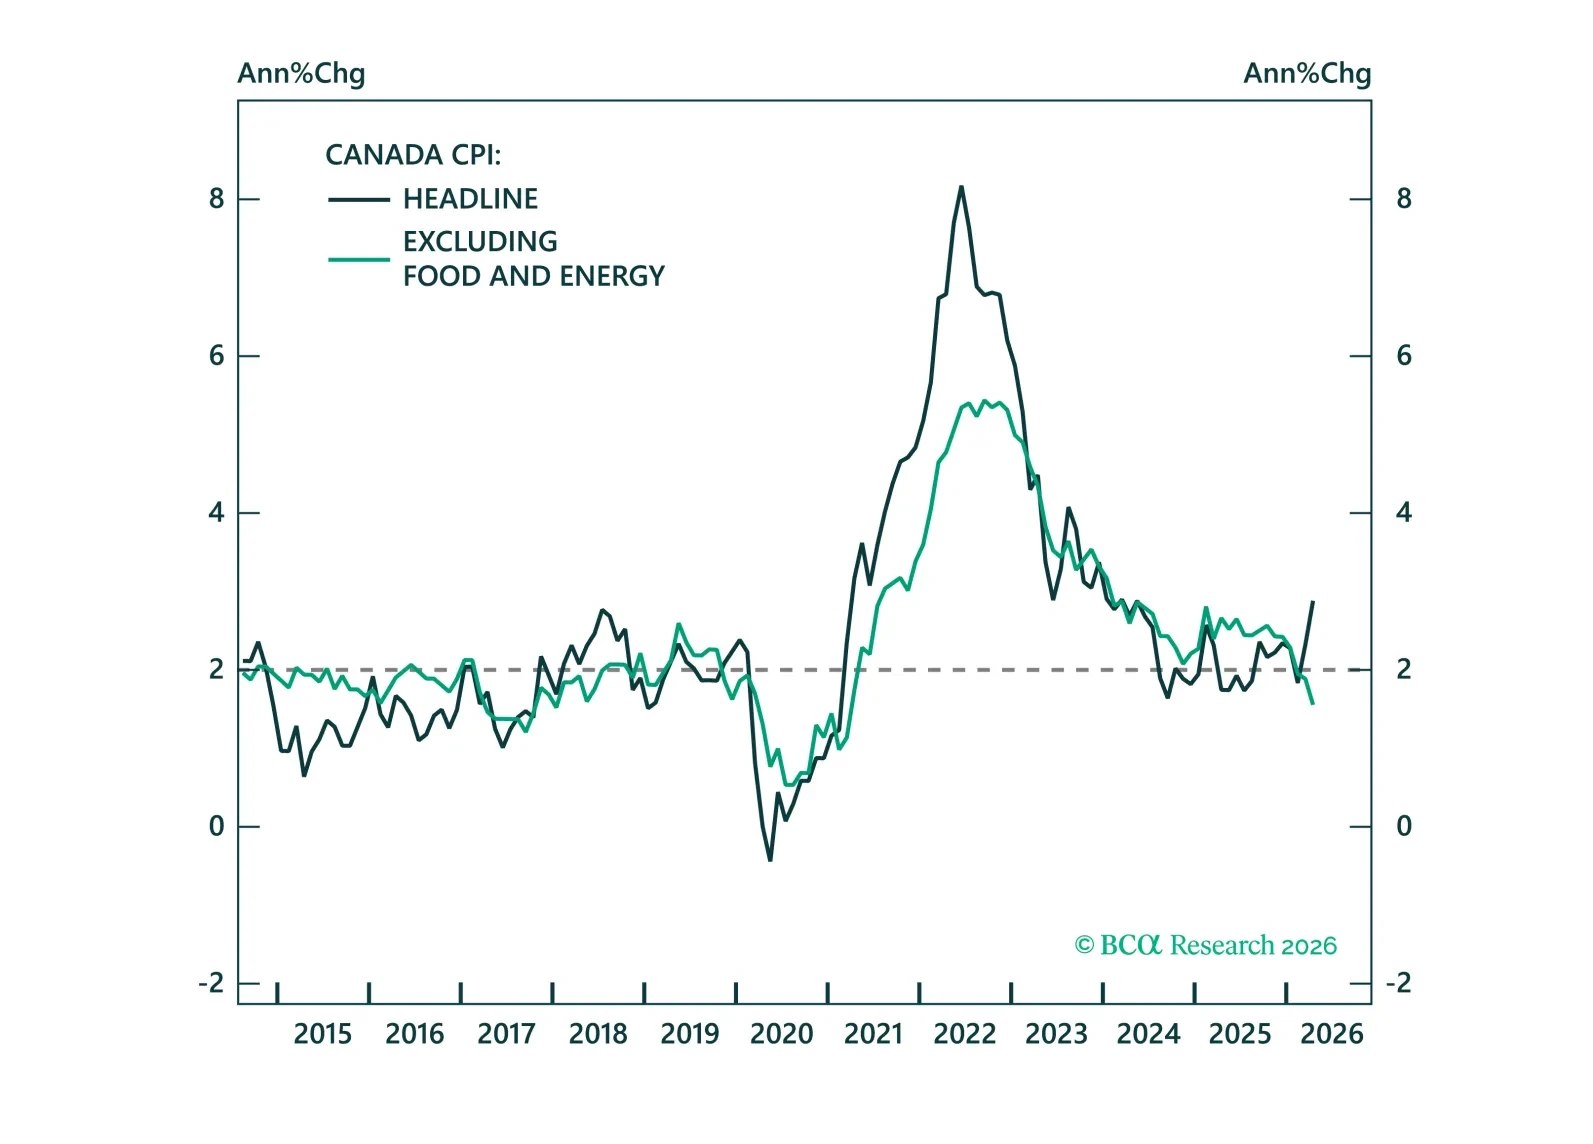
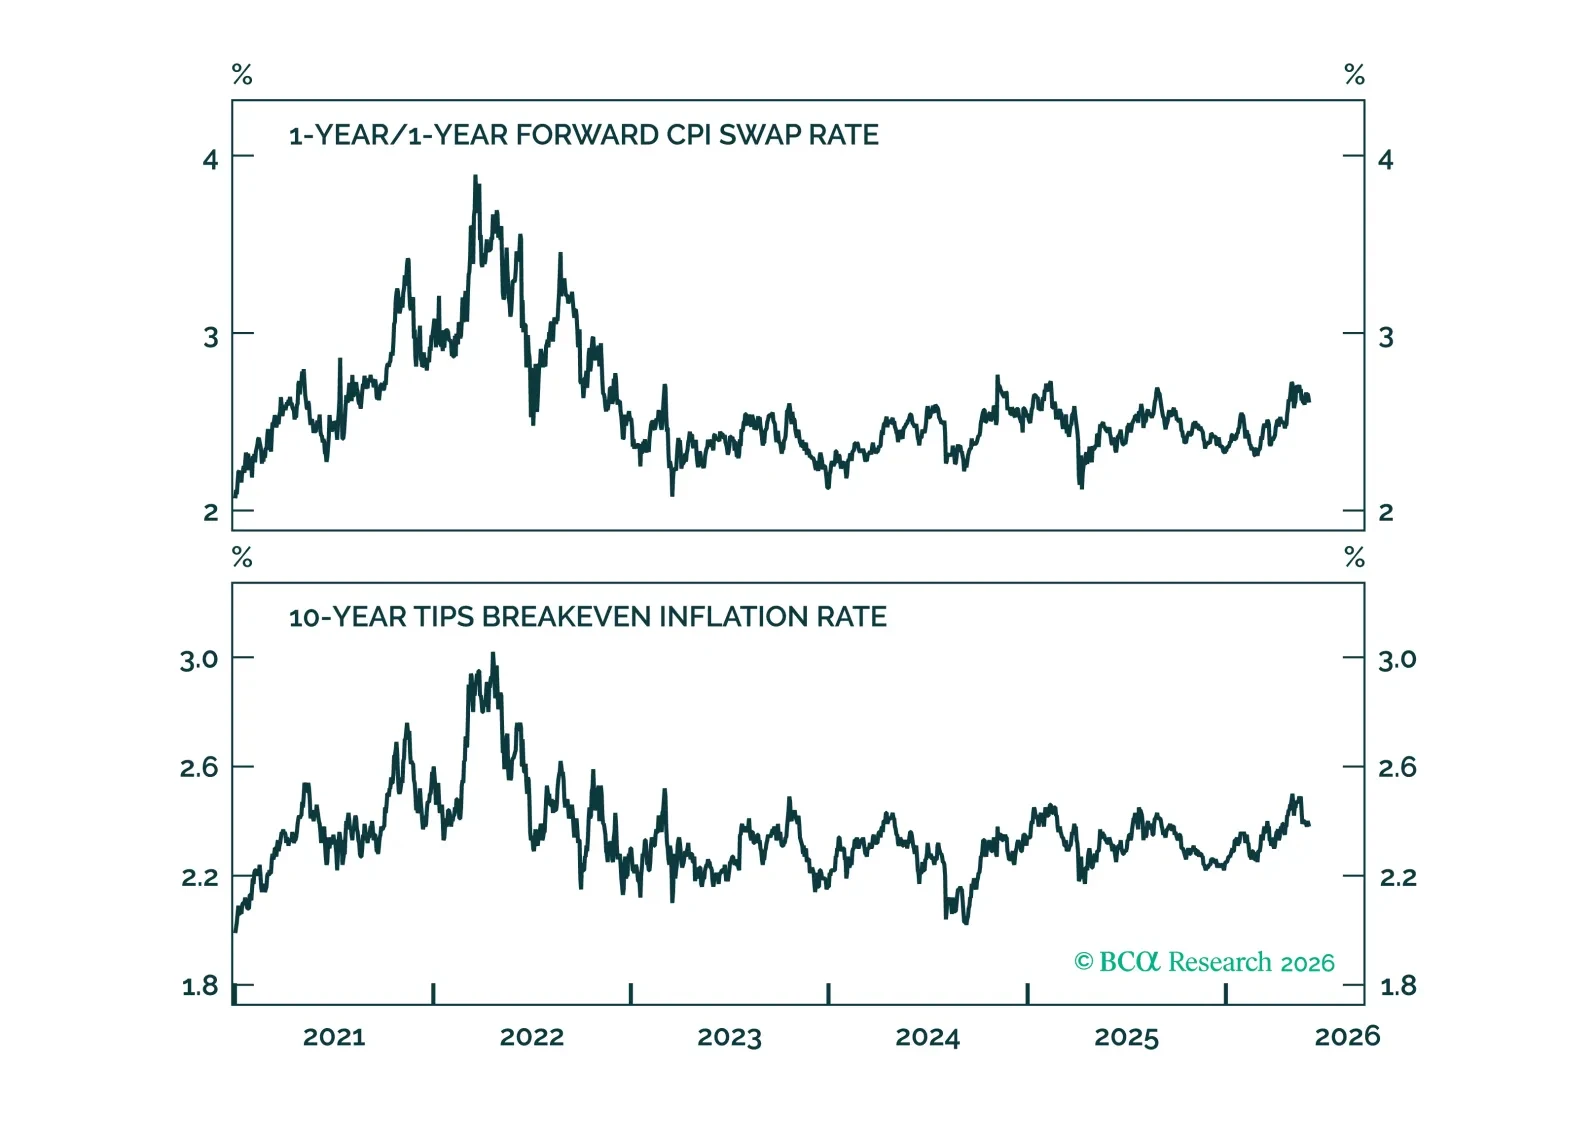
The Bank of Canada left rates unchanged and emphasized inflation risks from higher oil prices. We discuss why inflation and labor market data argue against the tightening currently priced.
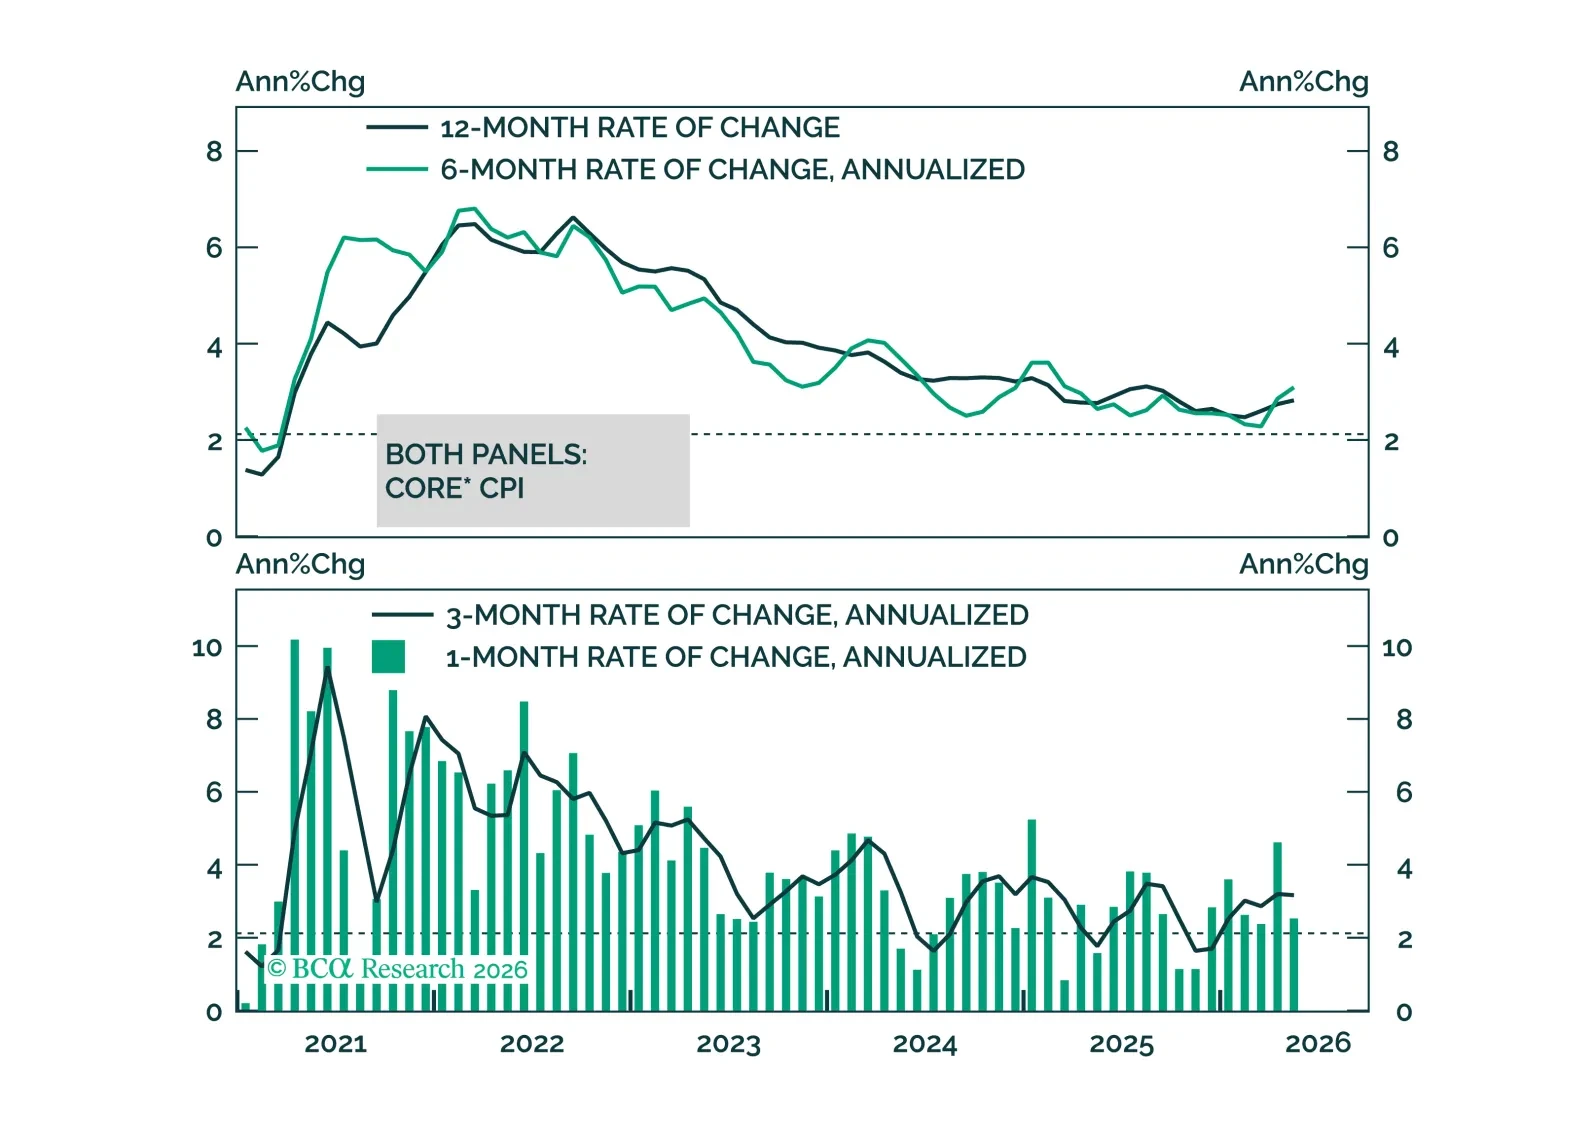
May CPI data show no evidence of passthrough from energy prices to core inflation. This will keep the Fed on hold for the time being.
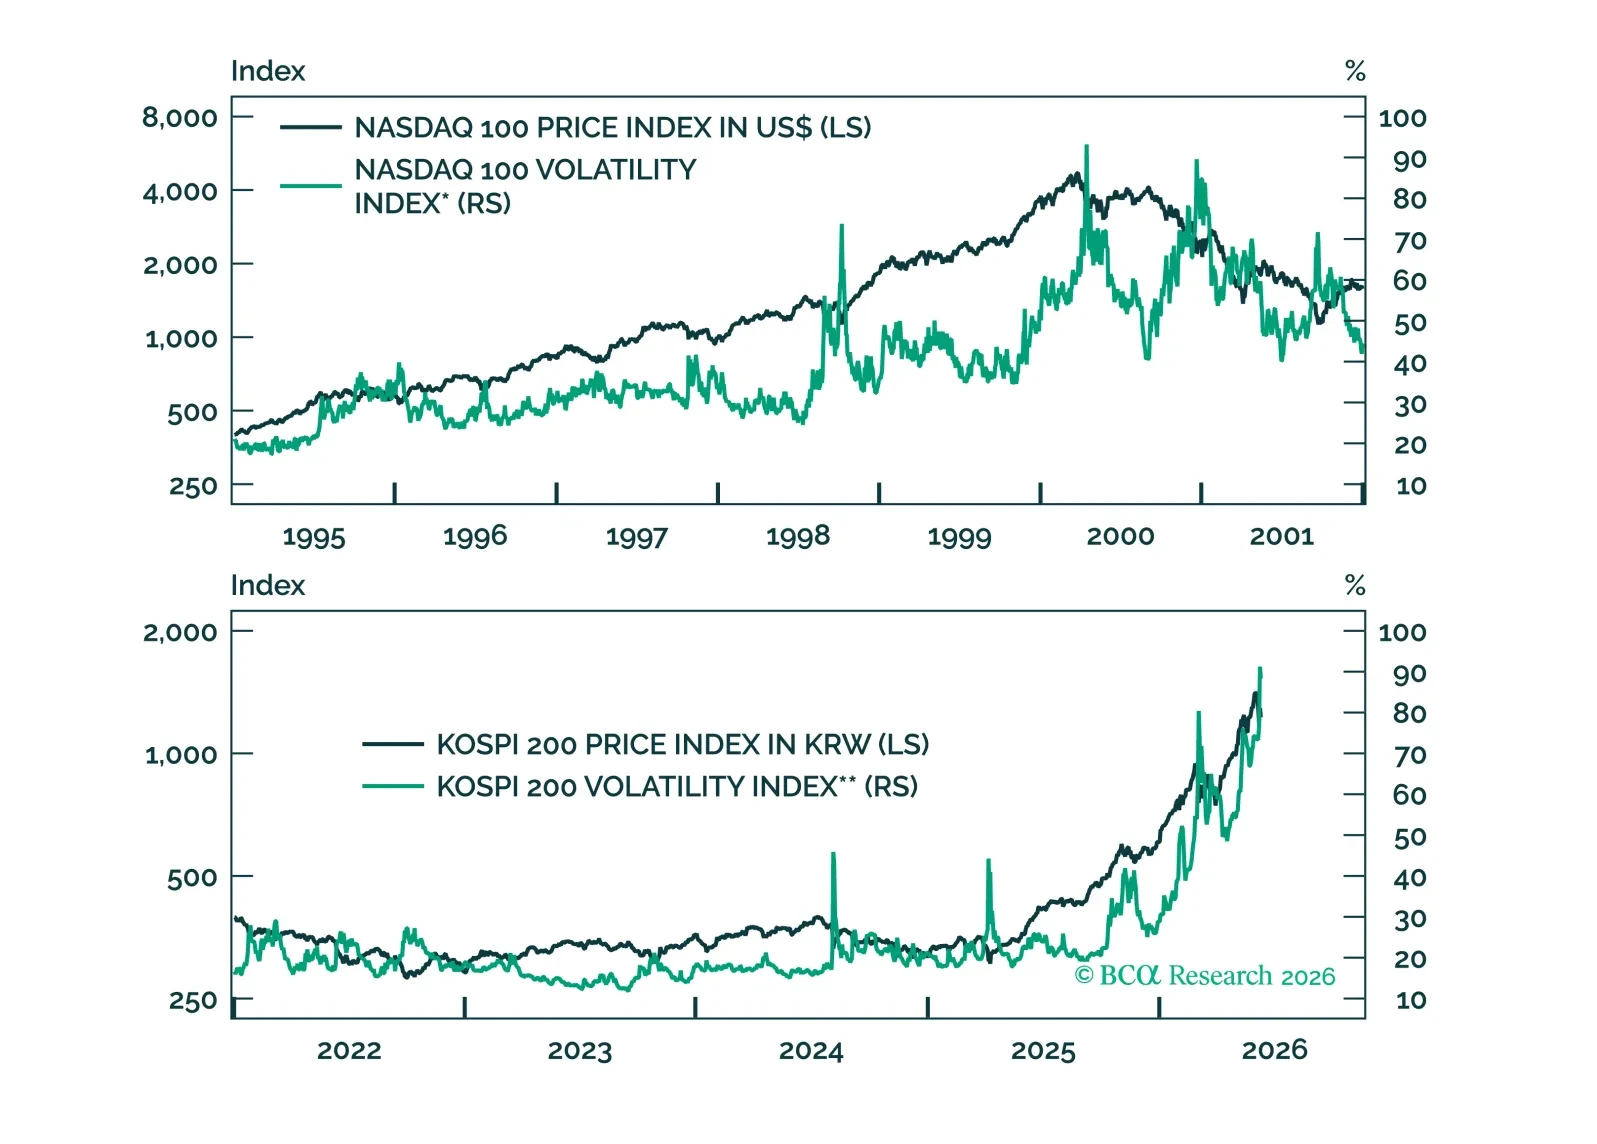
Rising volatility in Korean markets captures a late-cycle surge in which euphoria and drawdown risk are rising together. While KOSPI momentum remains intact, the bigger opportunity may be emerging in the increasingly mispriced KRW, which could rally meaningfully as portfolio flow headwinds fade.
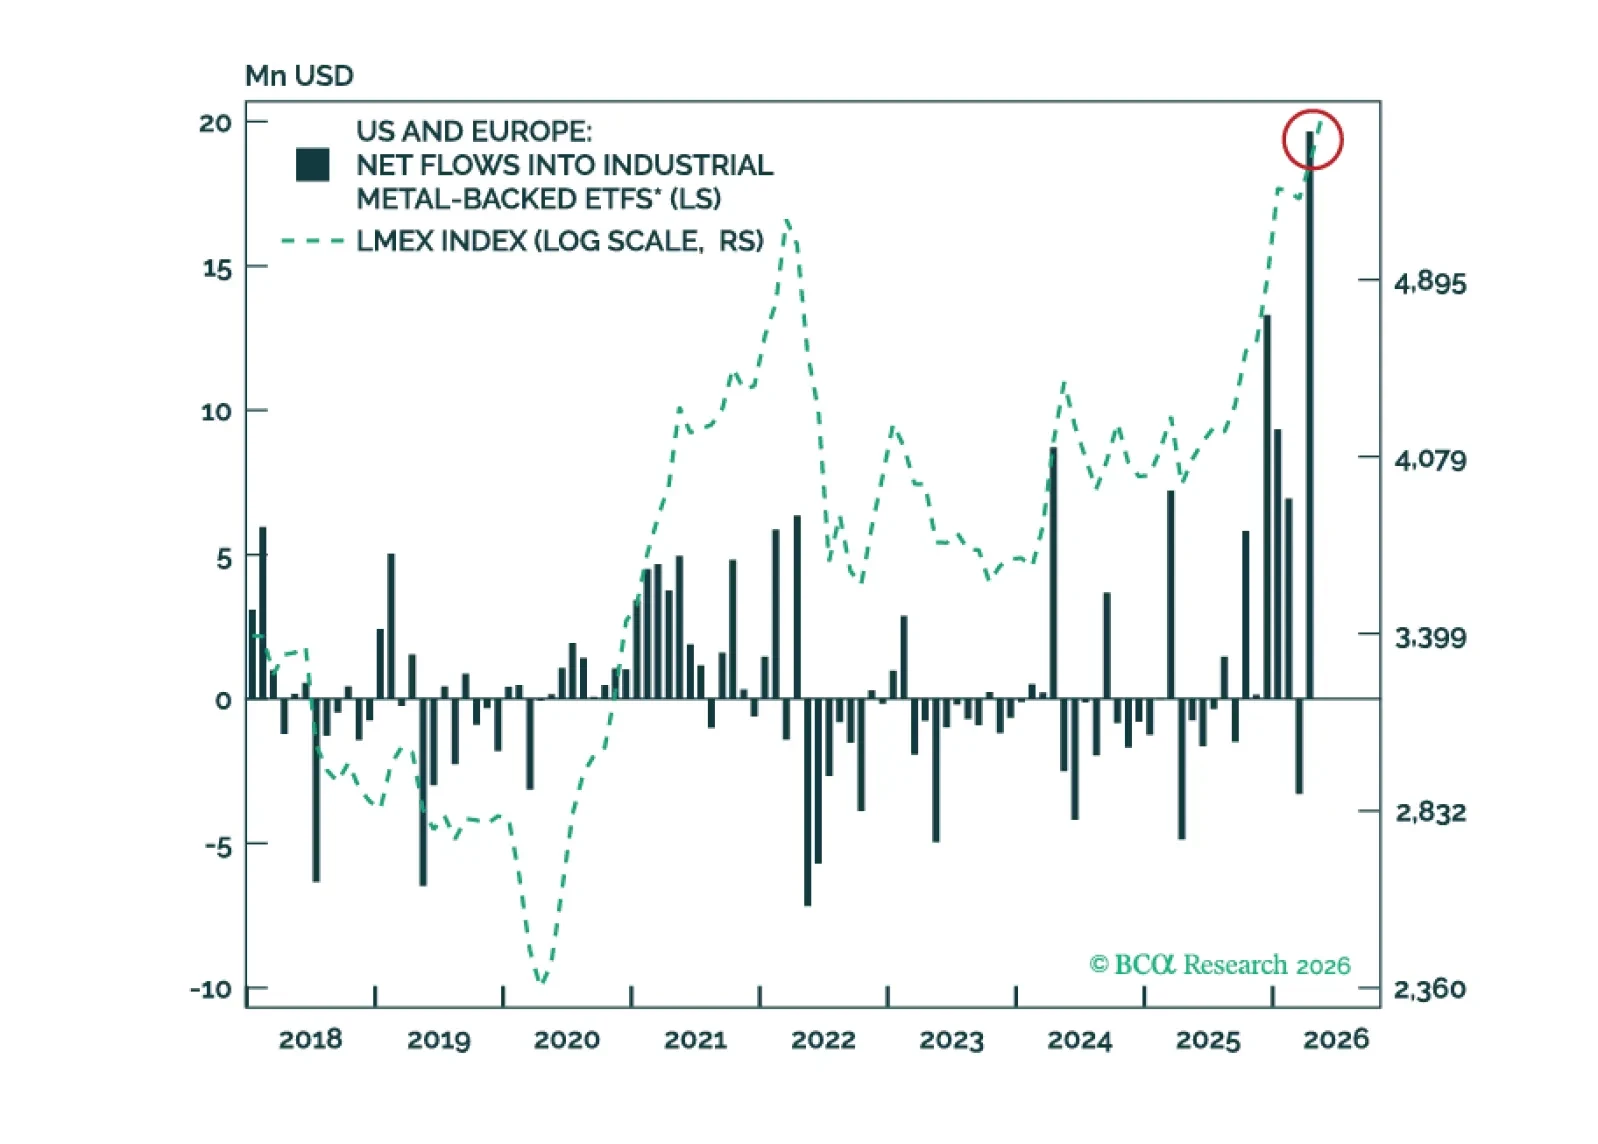
Copper prices are surging again after a brief pullback in the first quarter. What is driving the renewed strength, and can it persist?
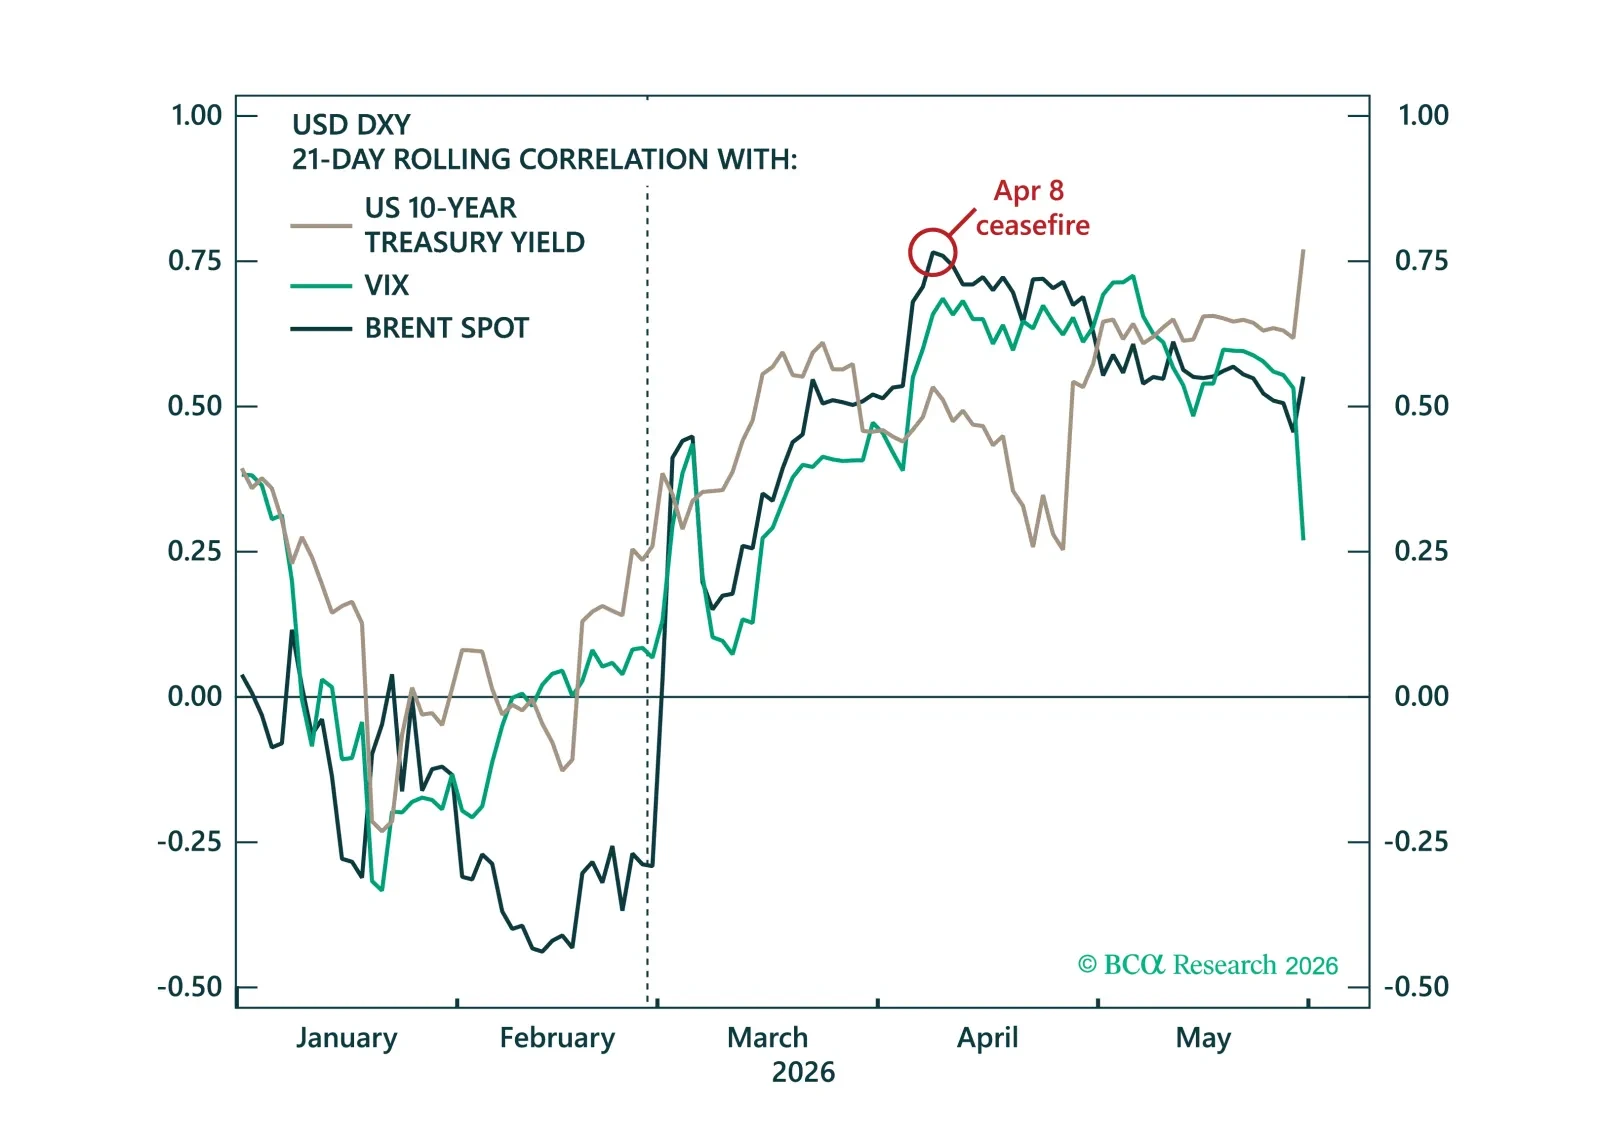
The dollar's muted response to the Iran conflict has led many to question its safe-haven appeal. We argue the opposite – the dollar's defensive properties have returned, while improving growth and rate dynamics should underpin further USD strength in the months ahead.
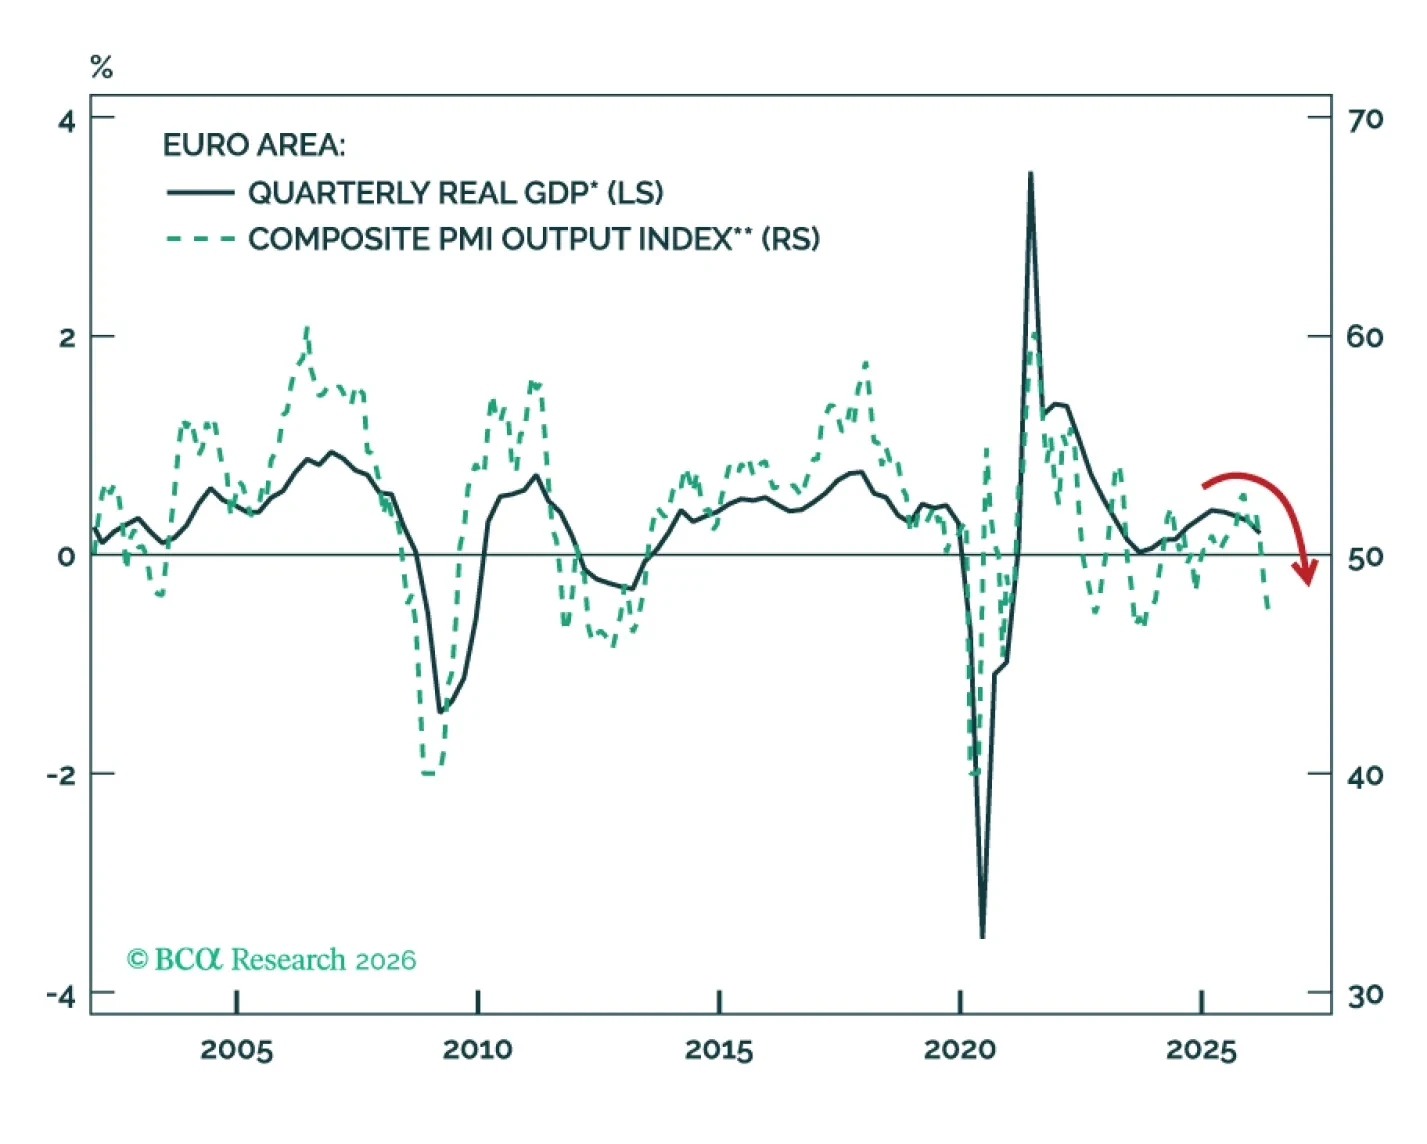
Europe is sliding from stagflation toward recession as prolonged disruptions in the Strait of Hormuz weaken growth, labor markets, and supply chains while keeping inflation elevated. Even if a US-Iran deal is reached, limited fiscal support and rising food inflation leave the Euro Area increasingly vulnerable to a deeper economic downturn.
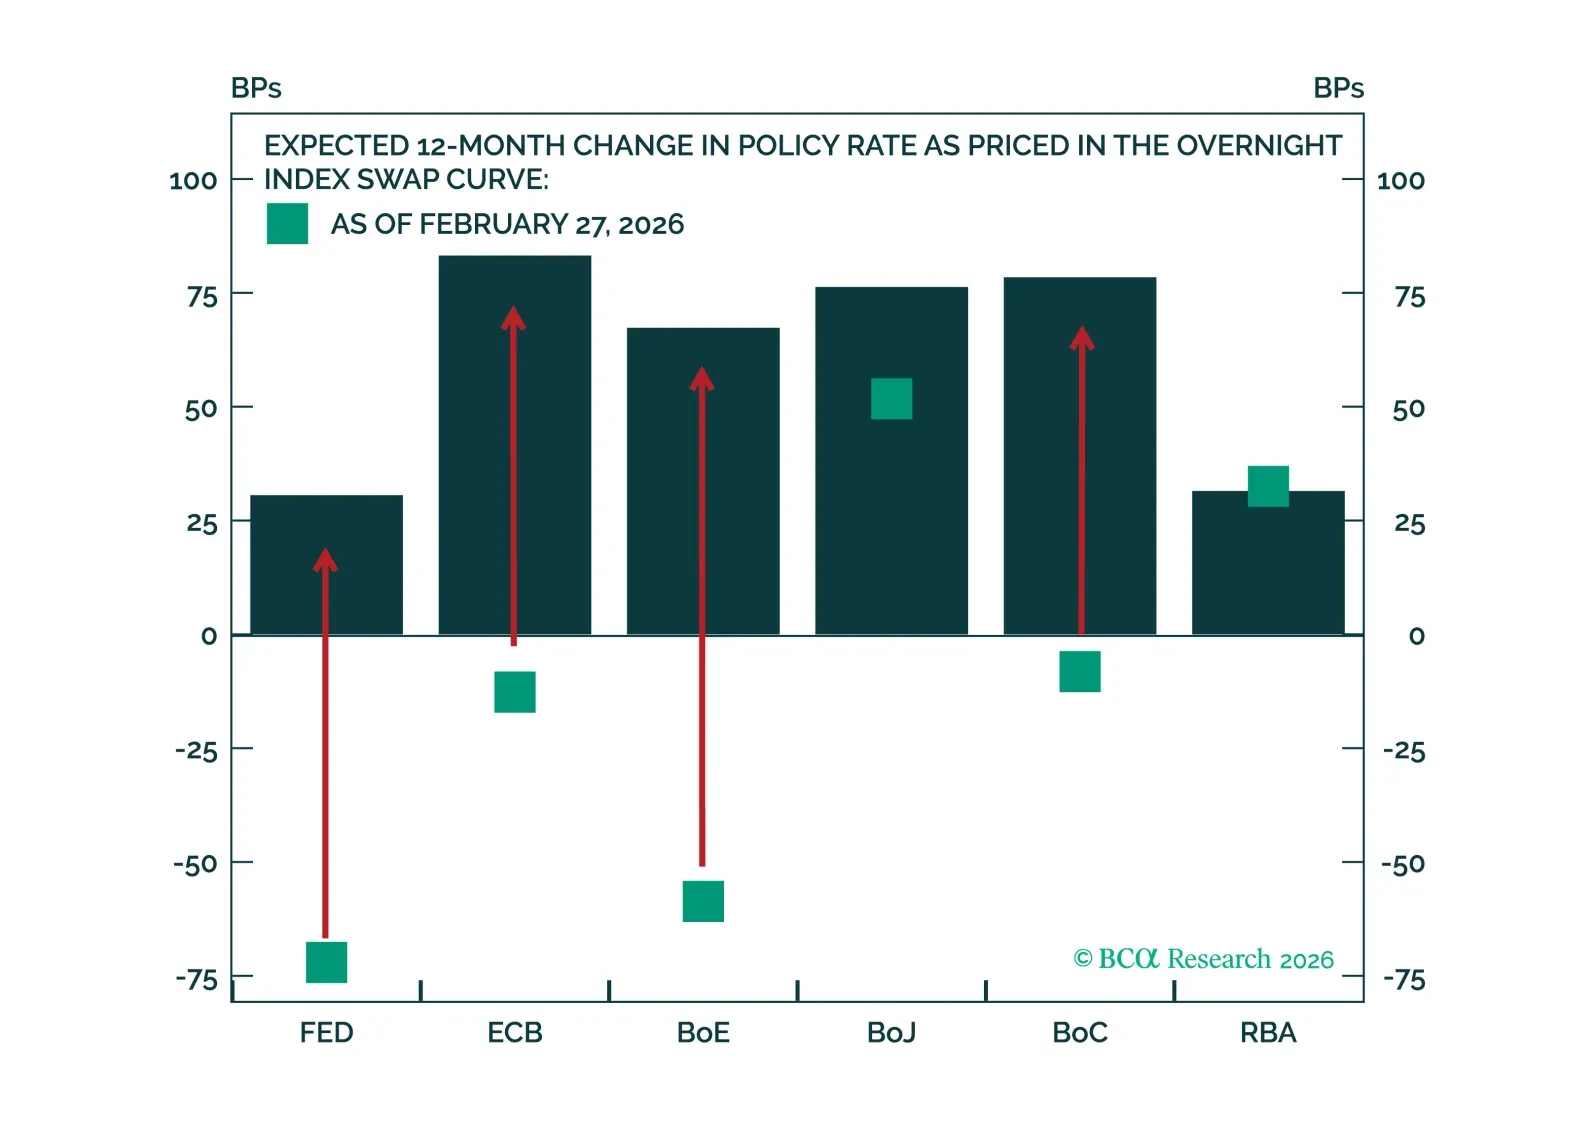
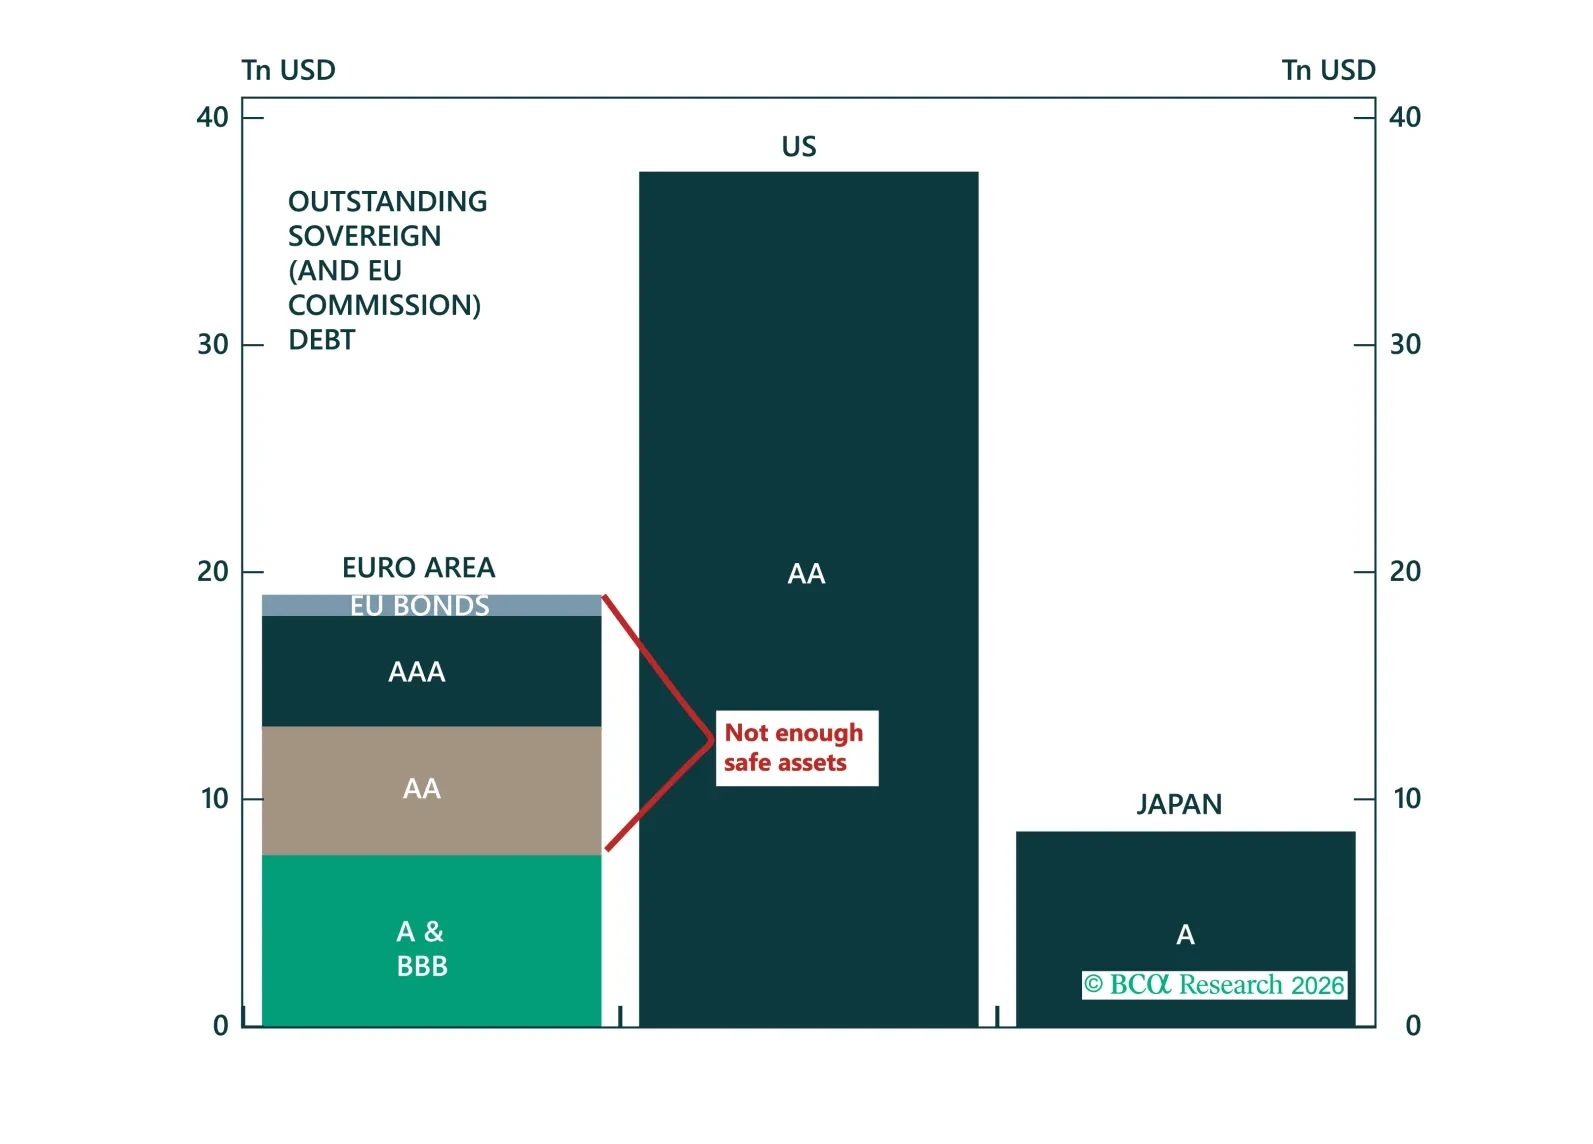
Downgrade global and US portfolio duration from “above benchmark” to “at benchmark” as the risk of hawkish monetary policy surprises is rising.
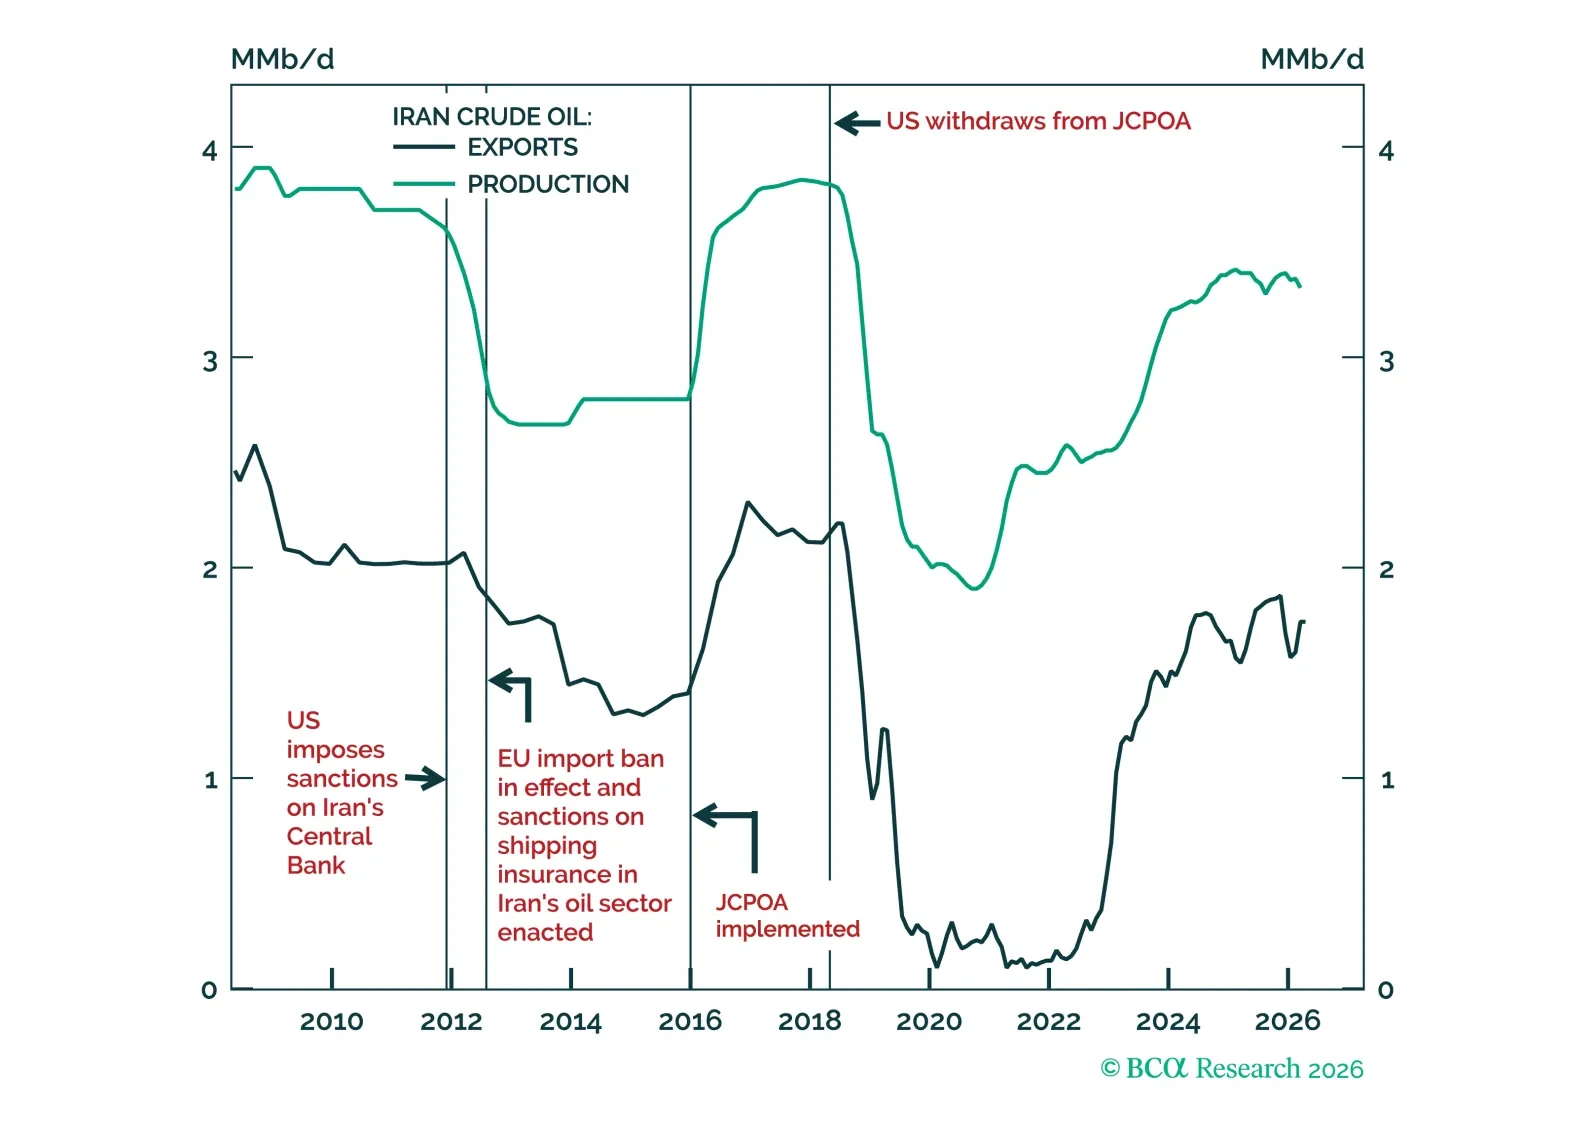
Hopes for an imminent Middle East de-escalation have capped oil prices in recent weeks, but that restraint may soon fade.