 FICC
Find out more
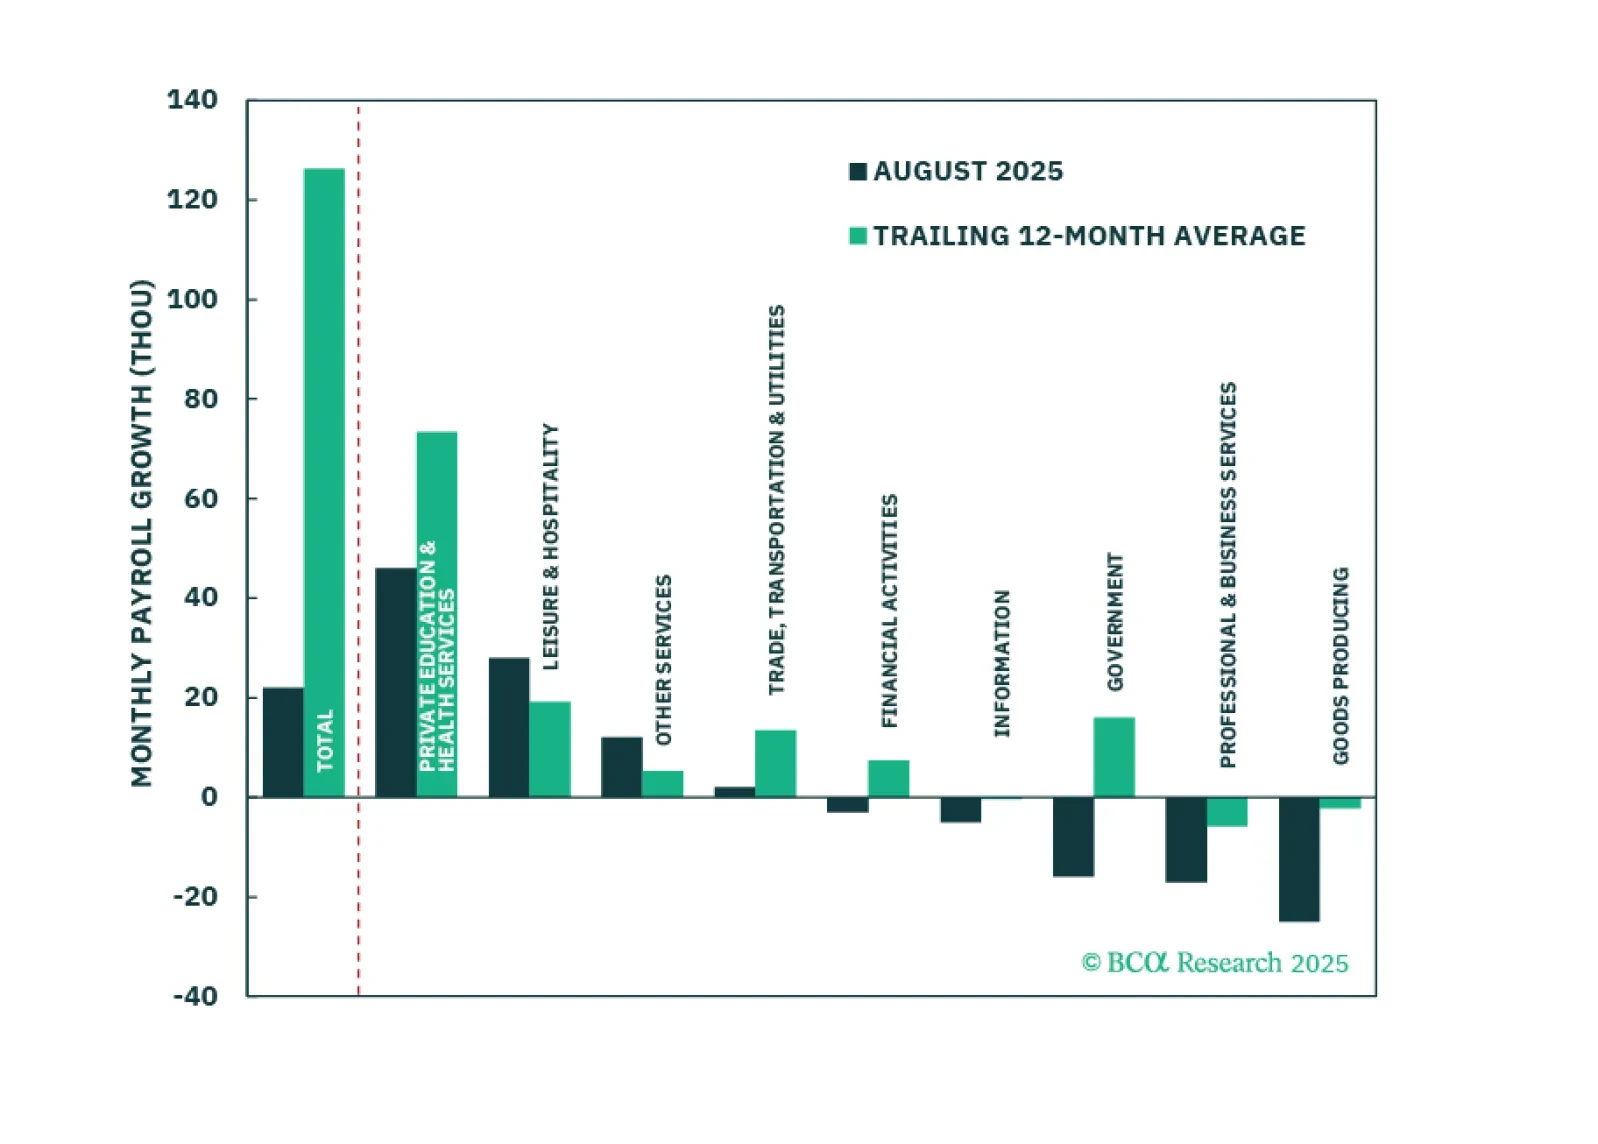
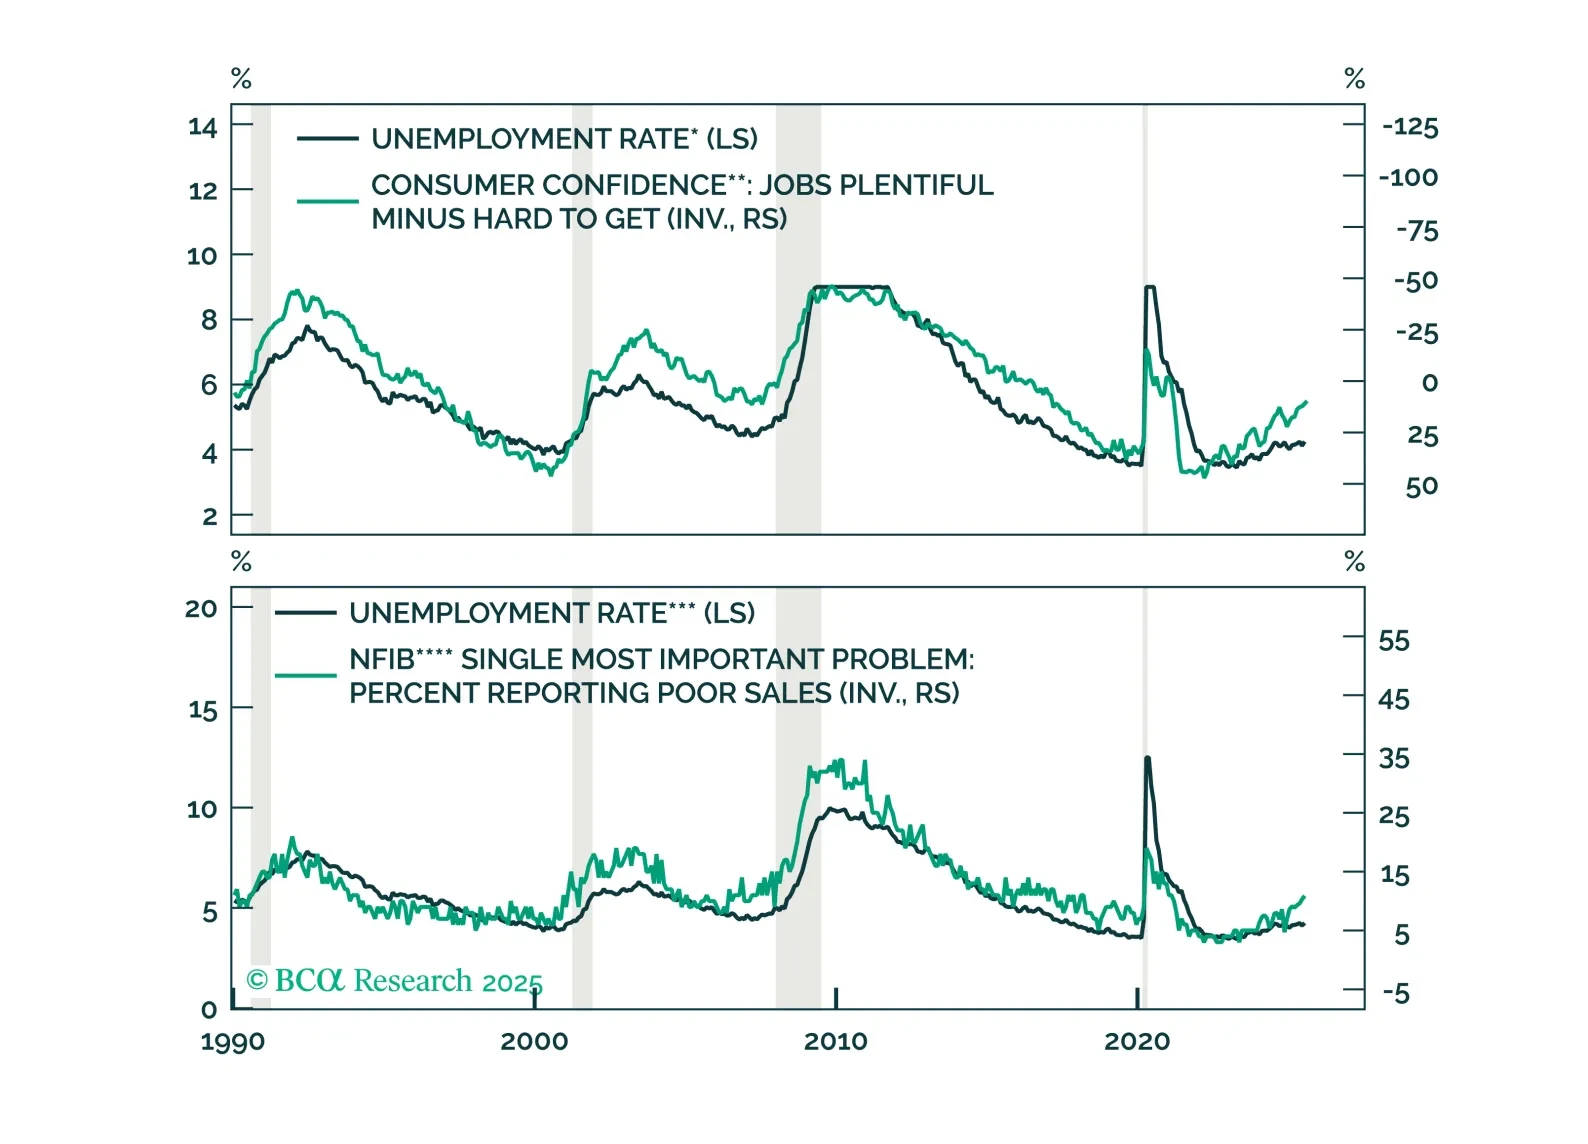
The August employment report showed a modest increase in labor market slack, enough to cement a 25-basis-point rate cut this month.
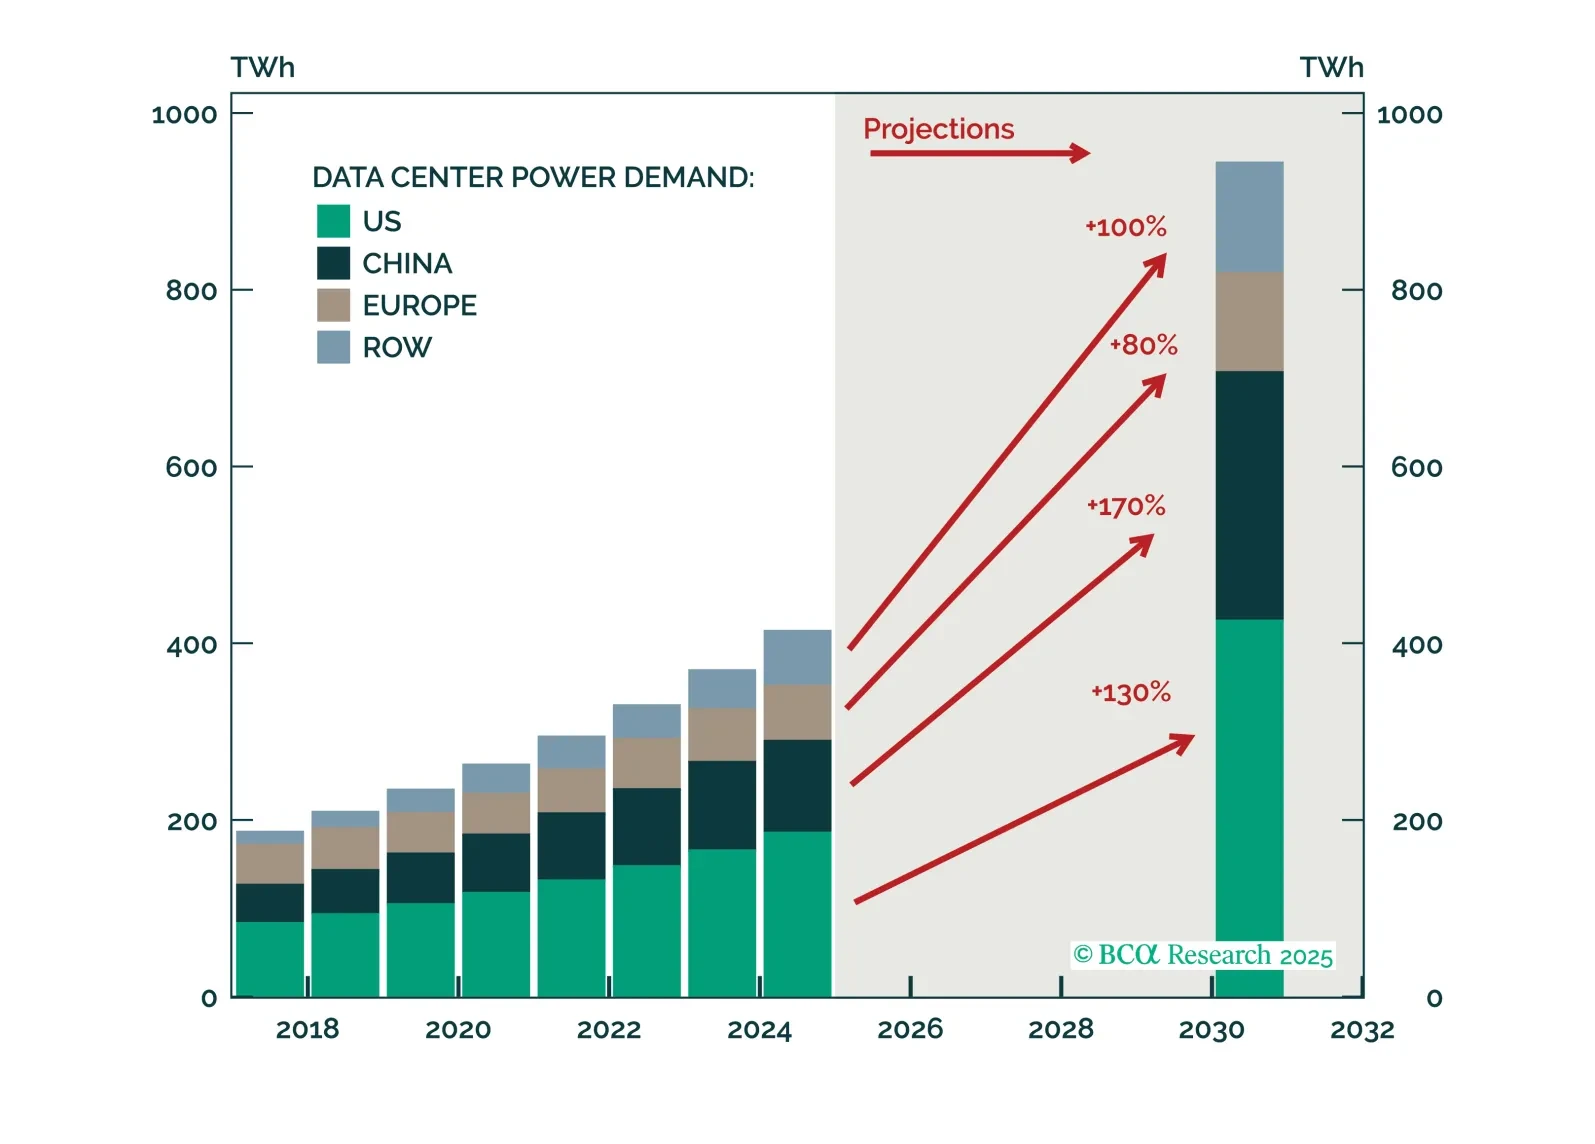
Renewables’ role in power-hungry data centers is overstated. Natural gas will fill clean electricity’s data center supply shortfall, particularly in the US and Europe.
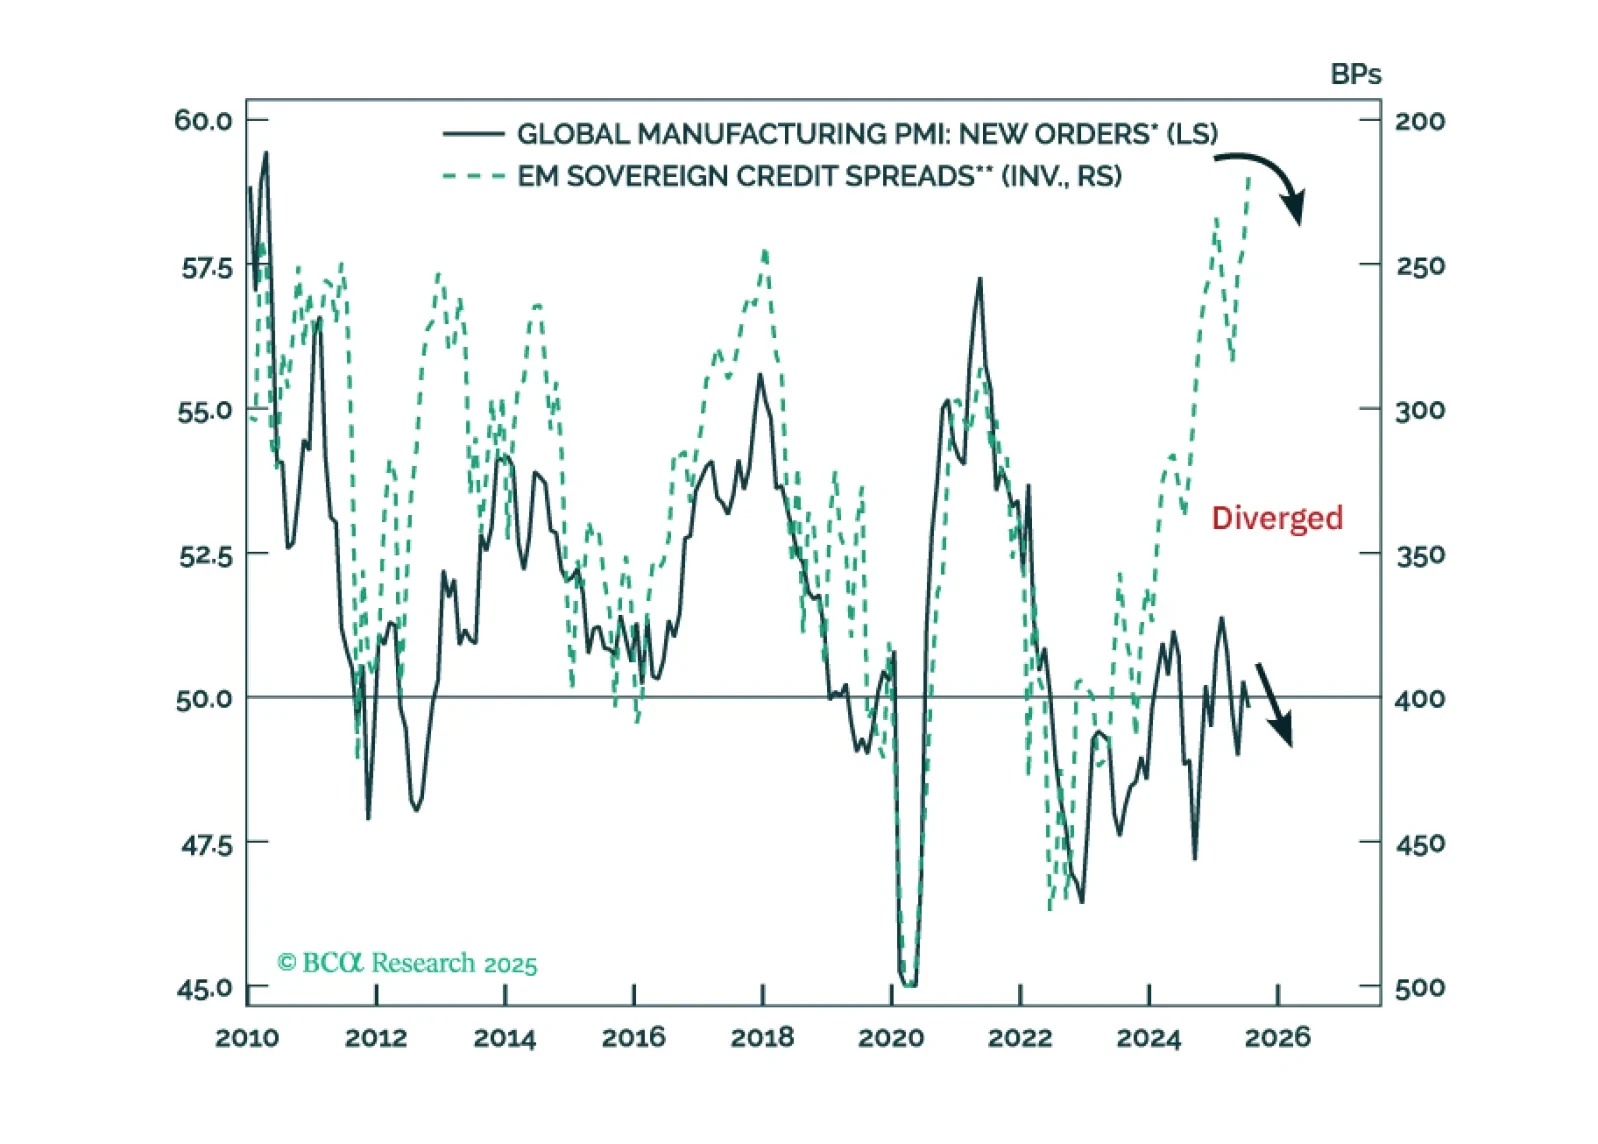
EM sovereign and corporate credit spreads are set to widen. Within a global credit portfolio, maintain a neutral allocation to EM credit markets versus US corporate credit. Favor EM local currency bonds over EM USD bonds.
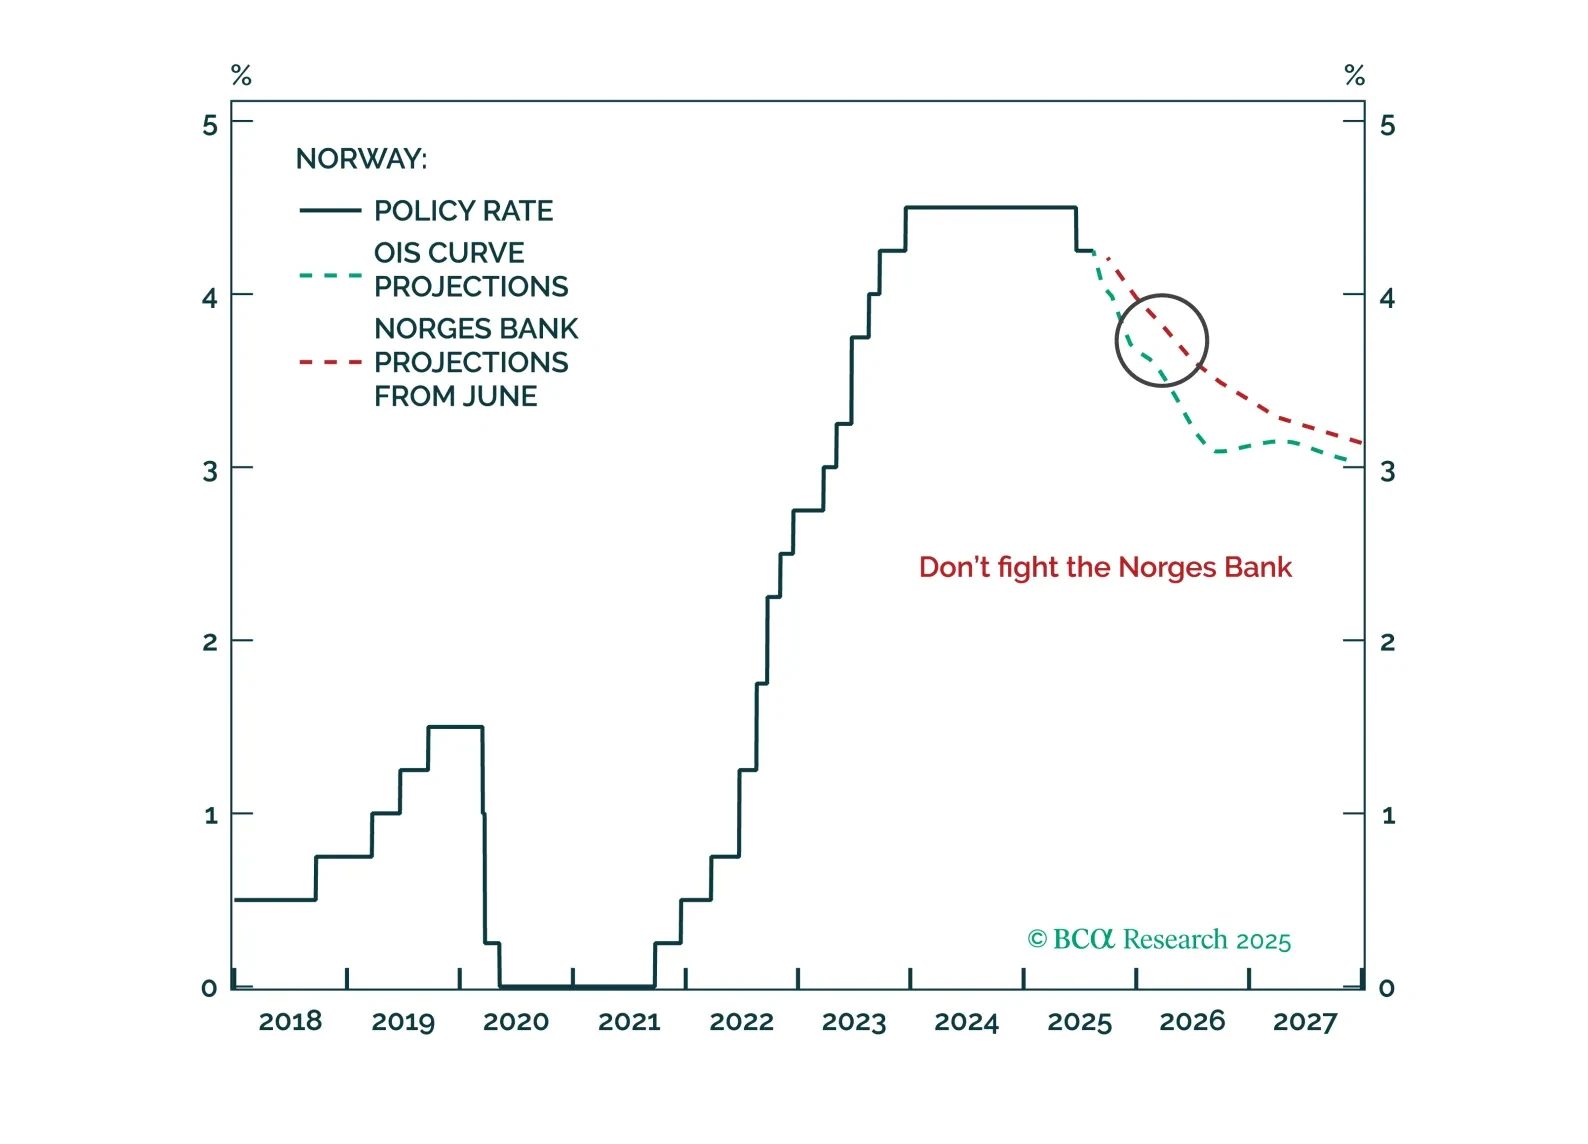
The Norges Bank will cut rates only once until year-end as the NOK weakens and inflation hovers around 3%. Expect aggressive easing next year as the economic recovery is delayed by weakness in the energy sector and the labor market deteriorates.
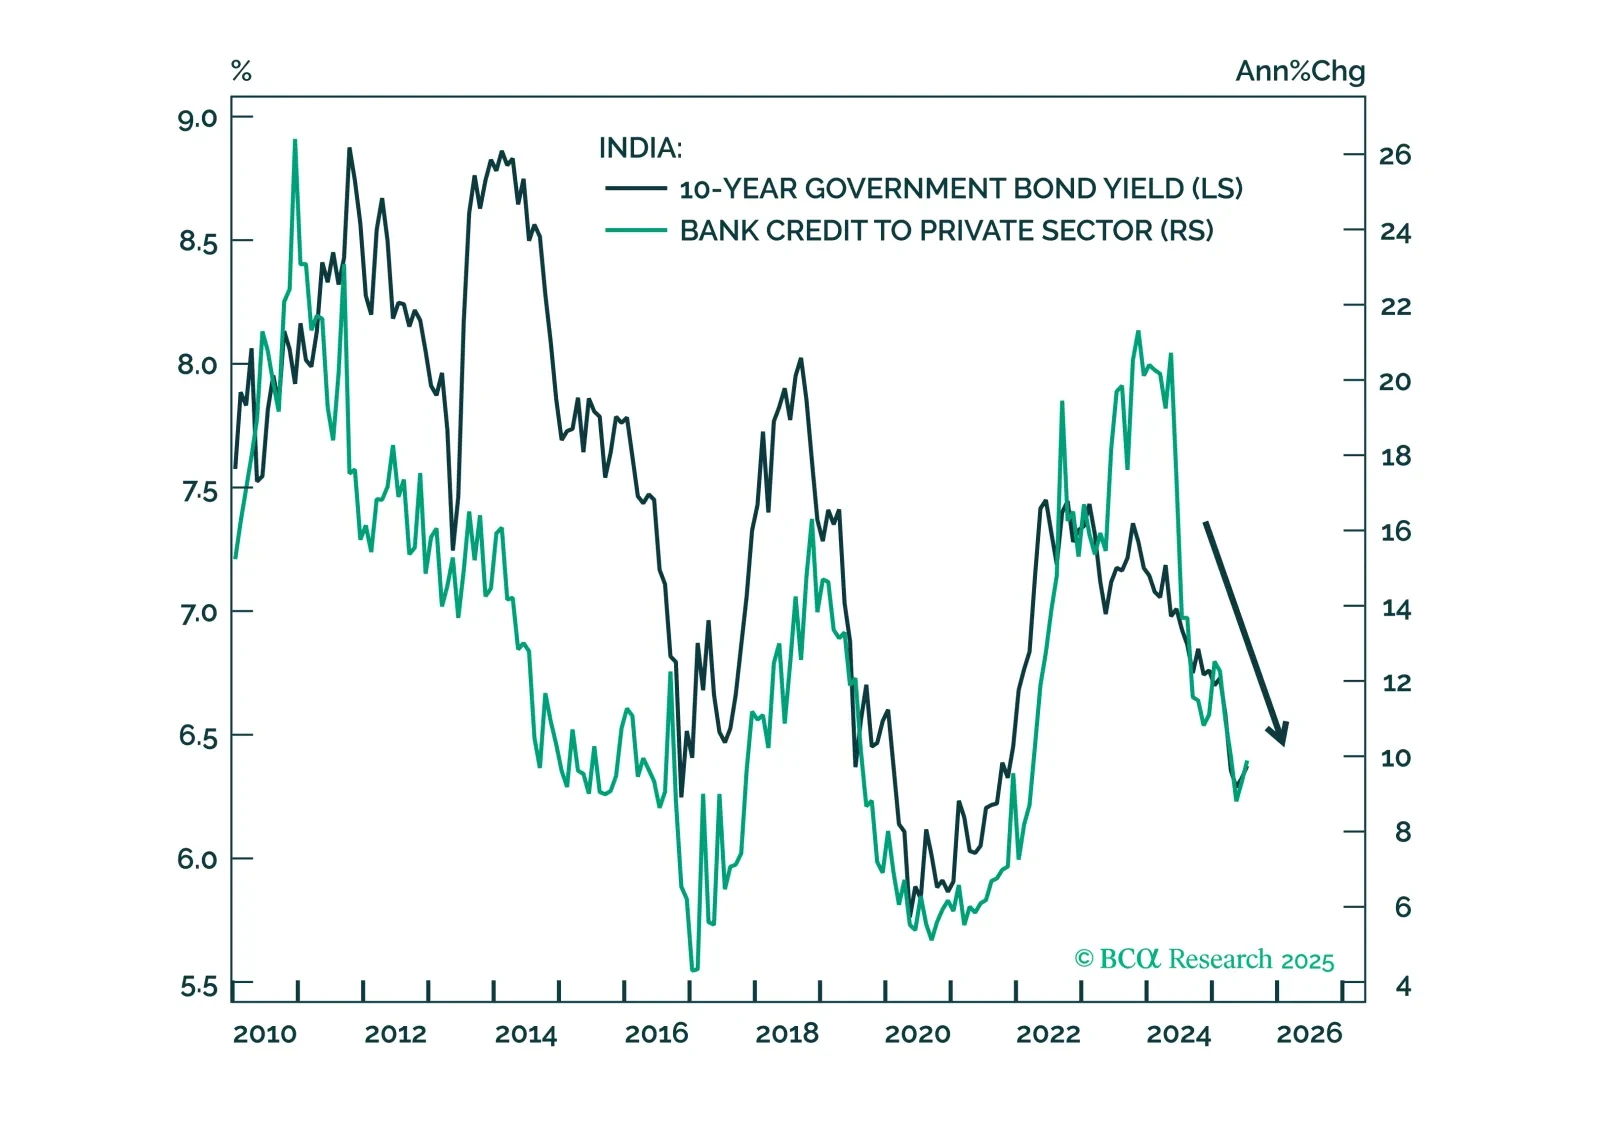
The Indian rupee remains vulnerable to further depreciation amid slowing growth, tight domestic policy, and fragile capital flows. Trade risks and a weakening external balance will likely keep INR underperforming EM Asia peers.

The cost of tariffs is falling on the US consumer, not foreign exporters or US firms.

In a widely anticipated move, the RBA resumed cutting rates. However, with housing, consumption, and PMIs improving, we see little scope for the RBA to ease beyond market expectations.