FICC
Find out more
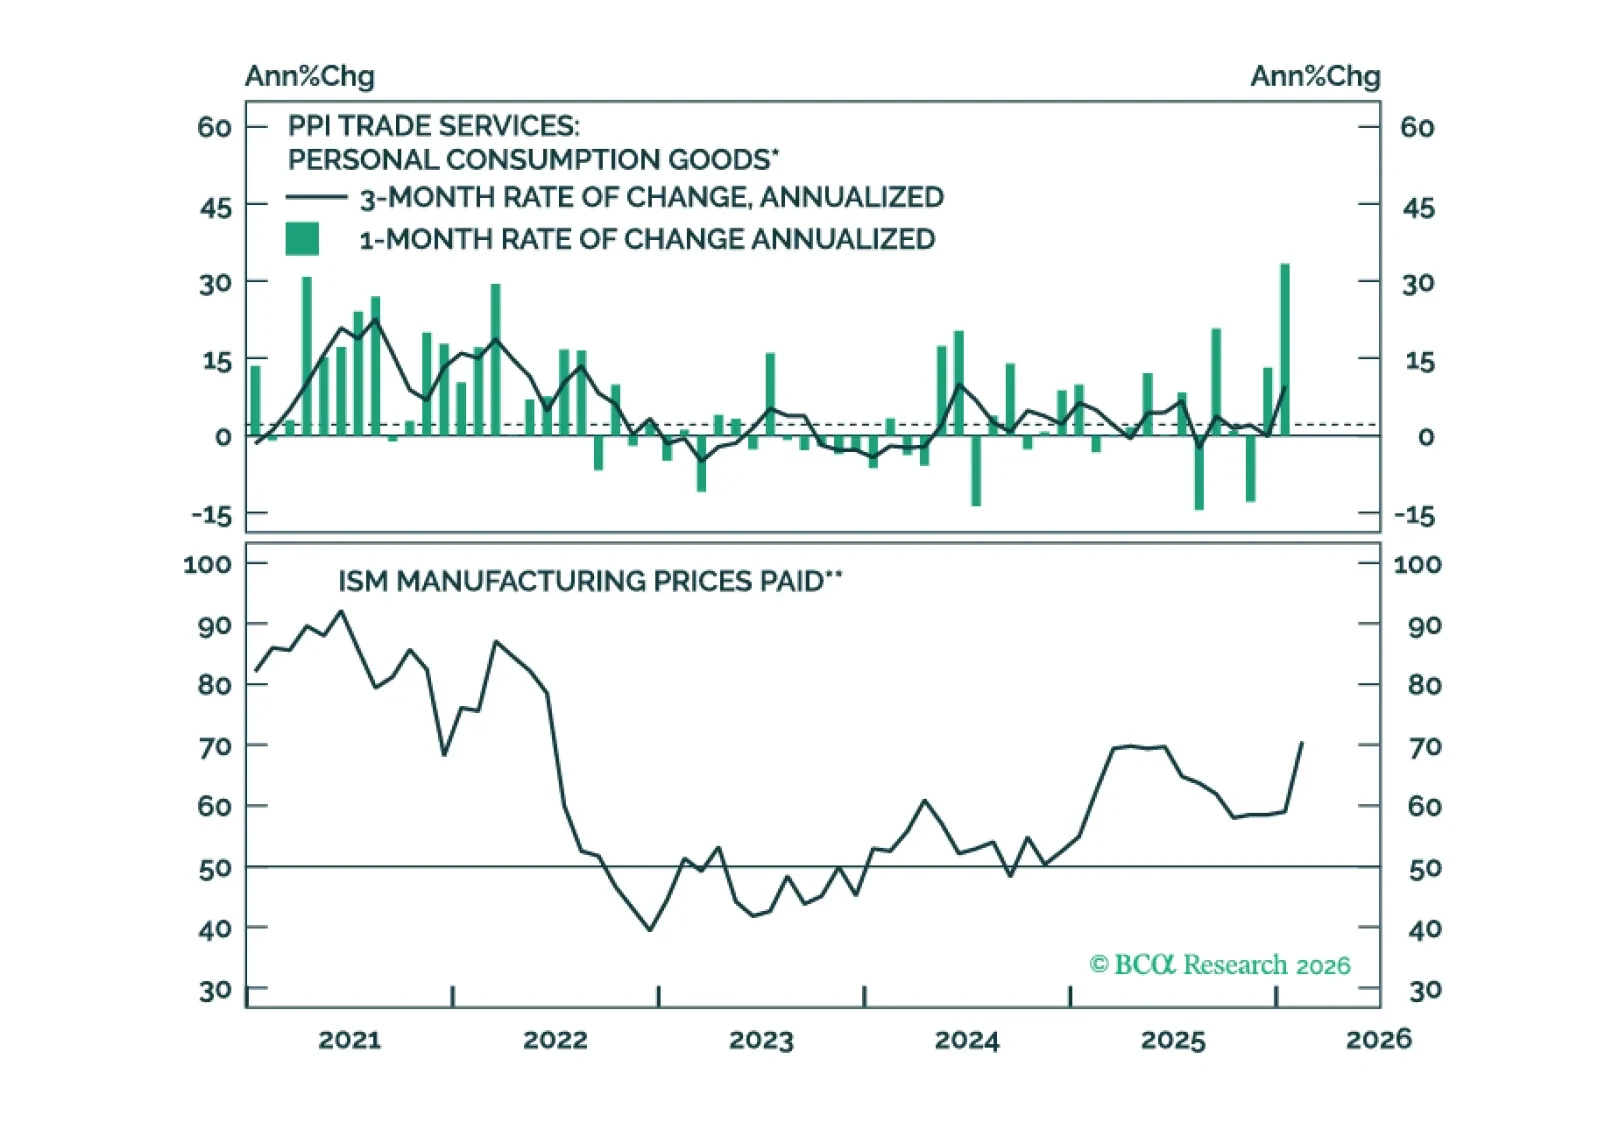
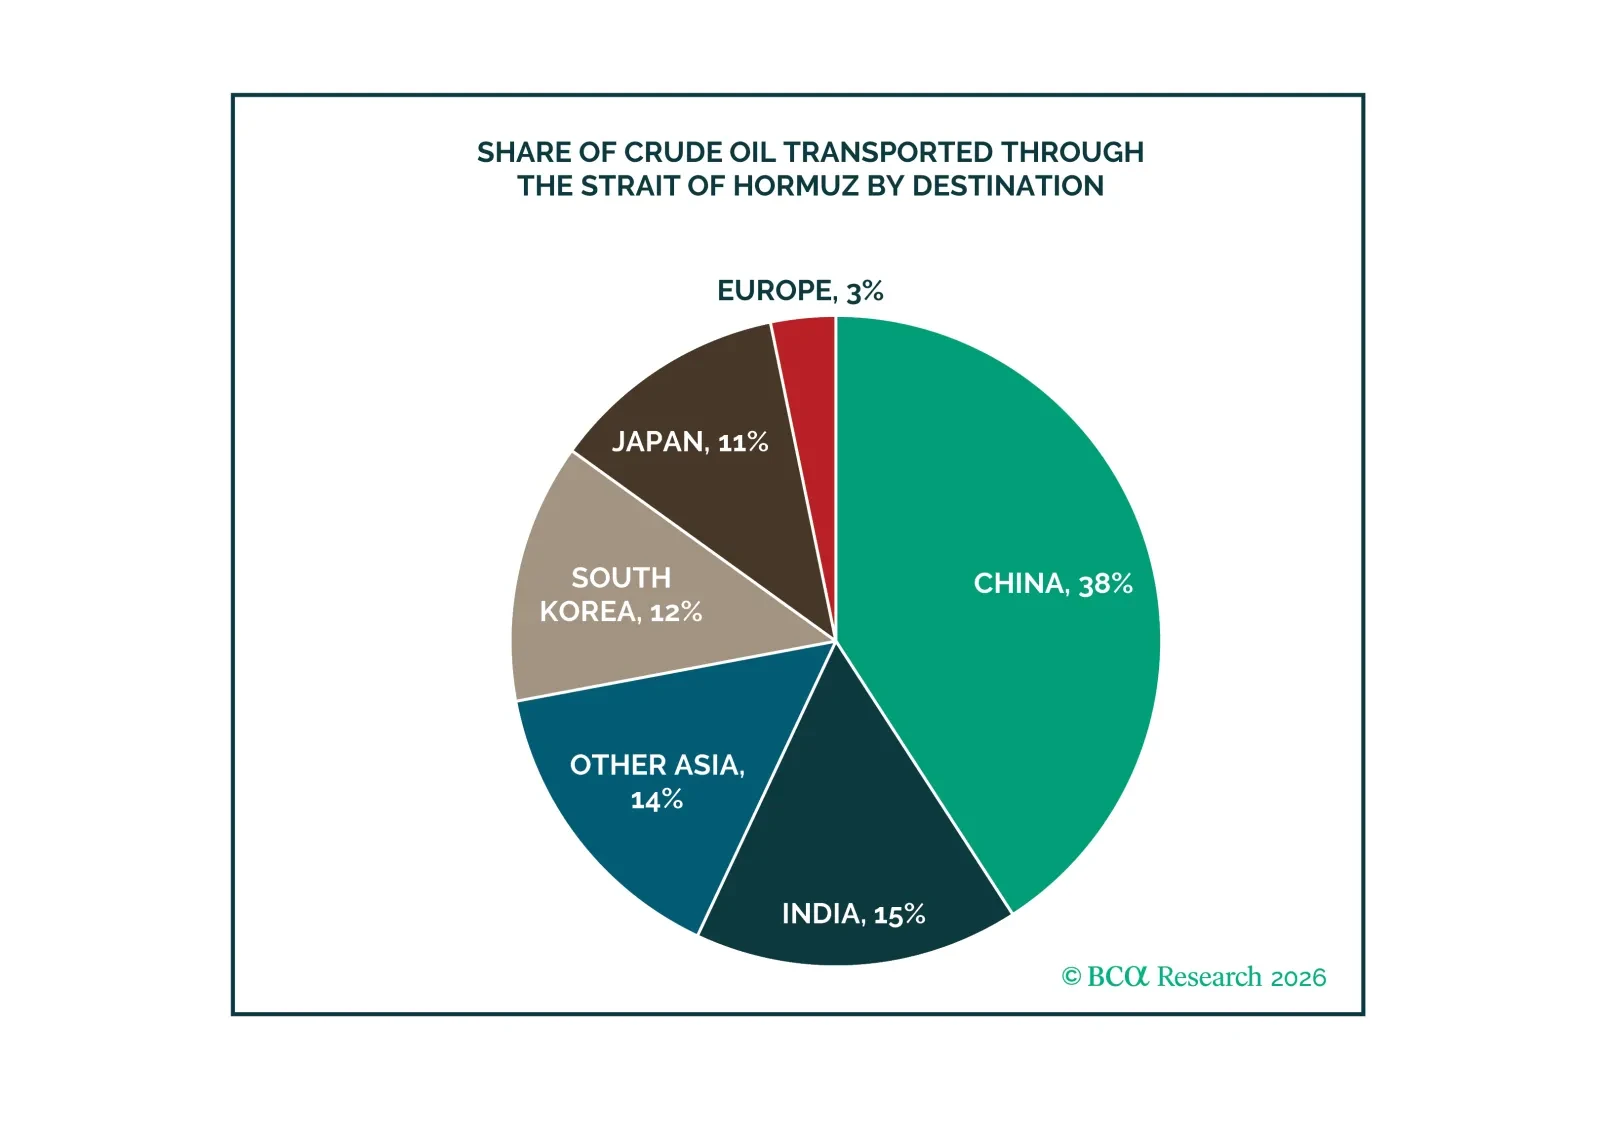
The war in Iran is disrupting global oil and LNG flows and remains a threat to regional energy infrastructure. Energy price risks remain skewed to the upside over the near term.
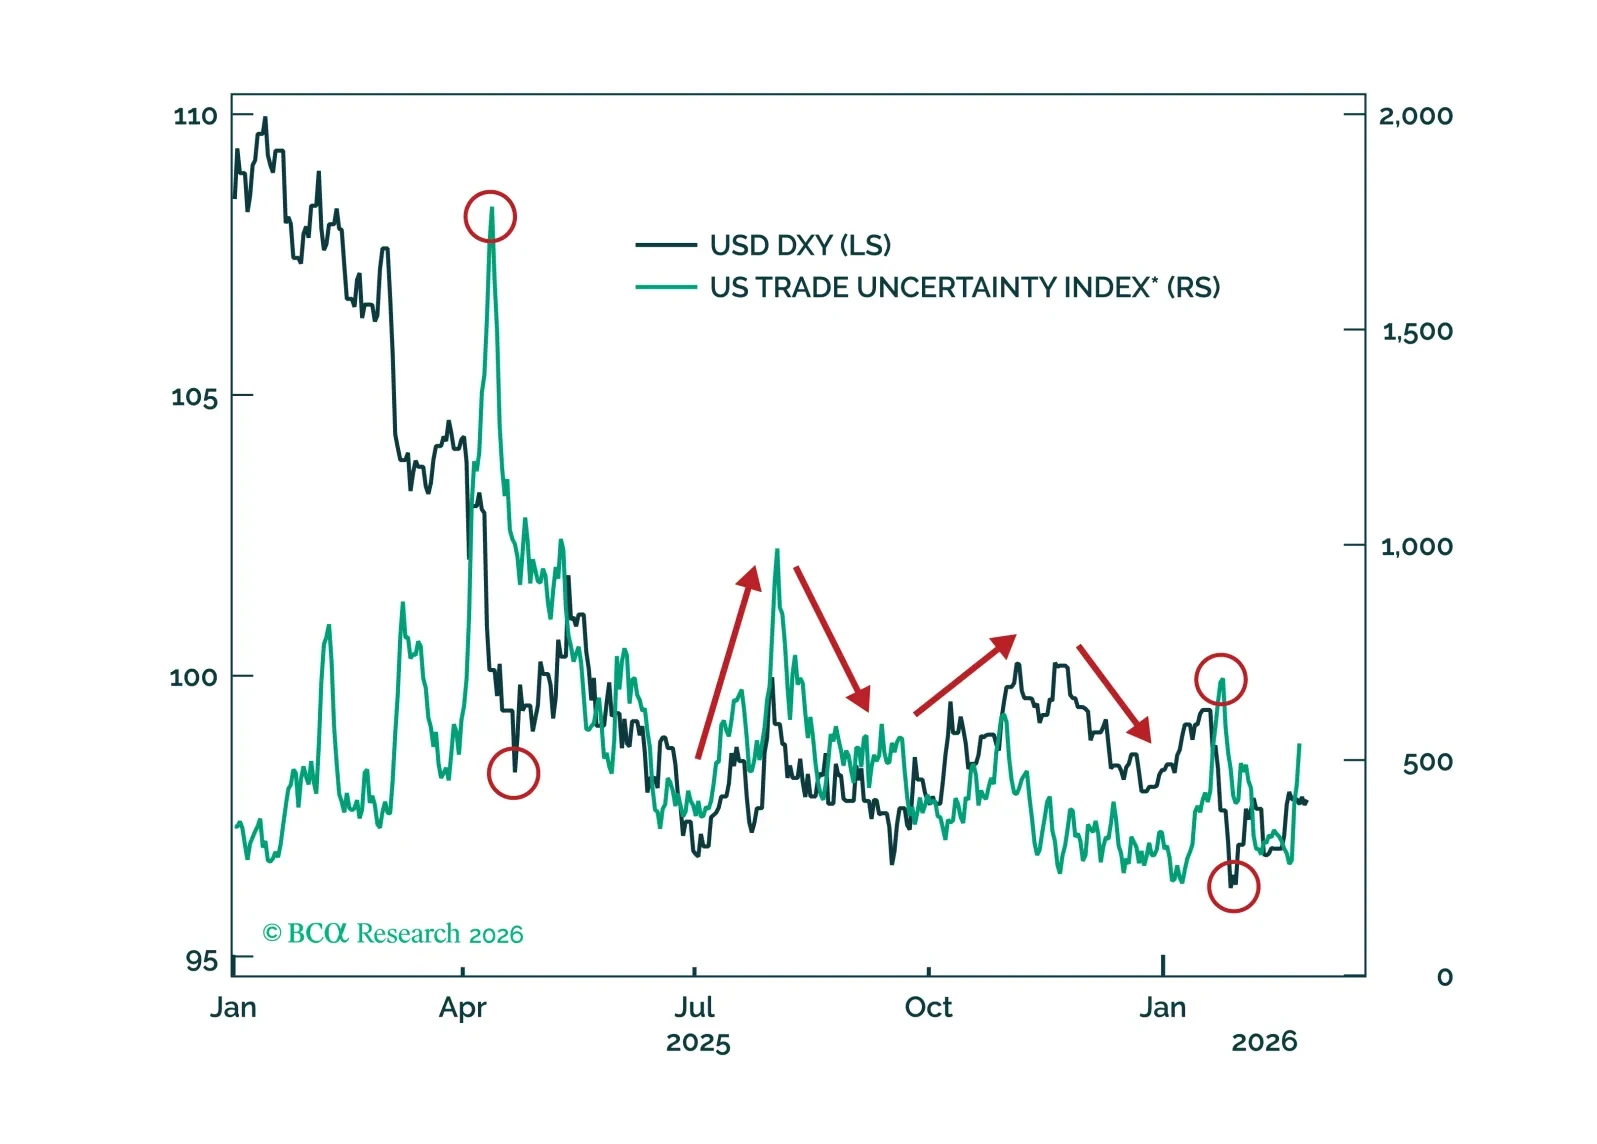
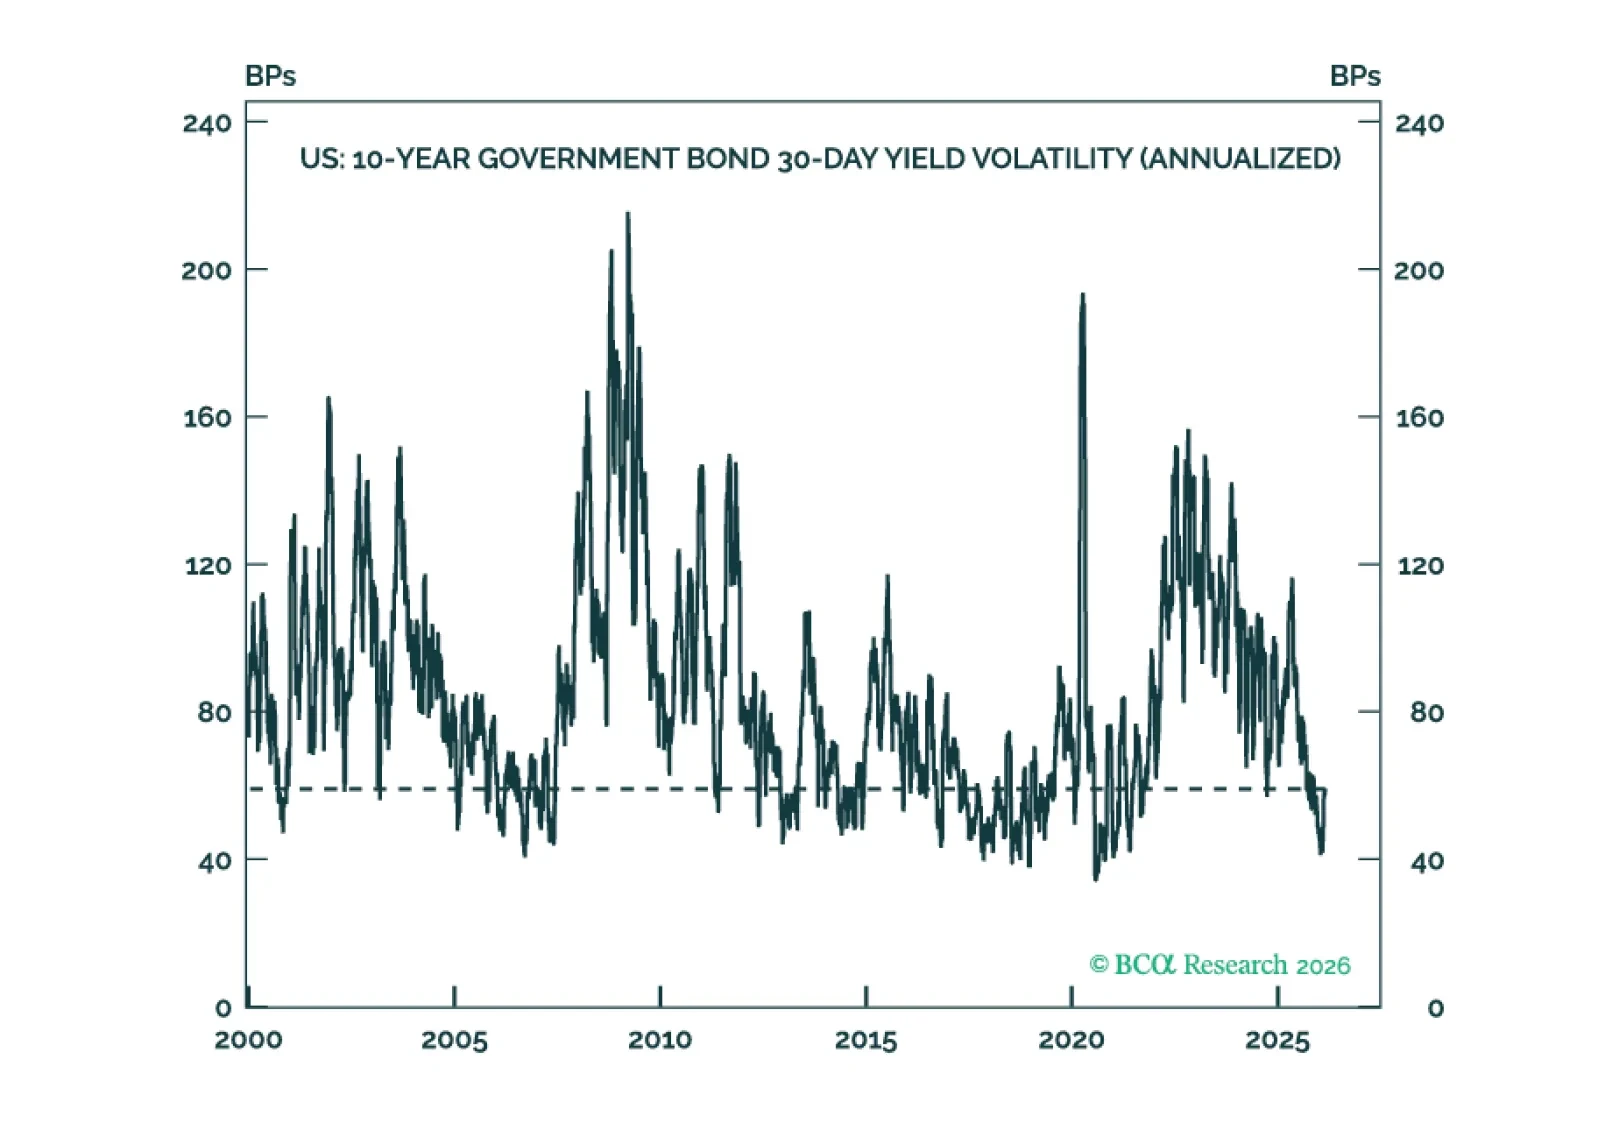
Policy risks are set to fade just as markets underestimate hawkish Fed repricing and crowd into short-USD positions, setting the stage for a tactical dollar rebound into the election cycle. Go long USD/CHF to capture the rate differential and receding policy uncertainty.
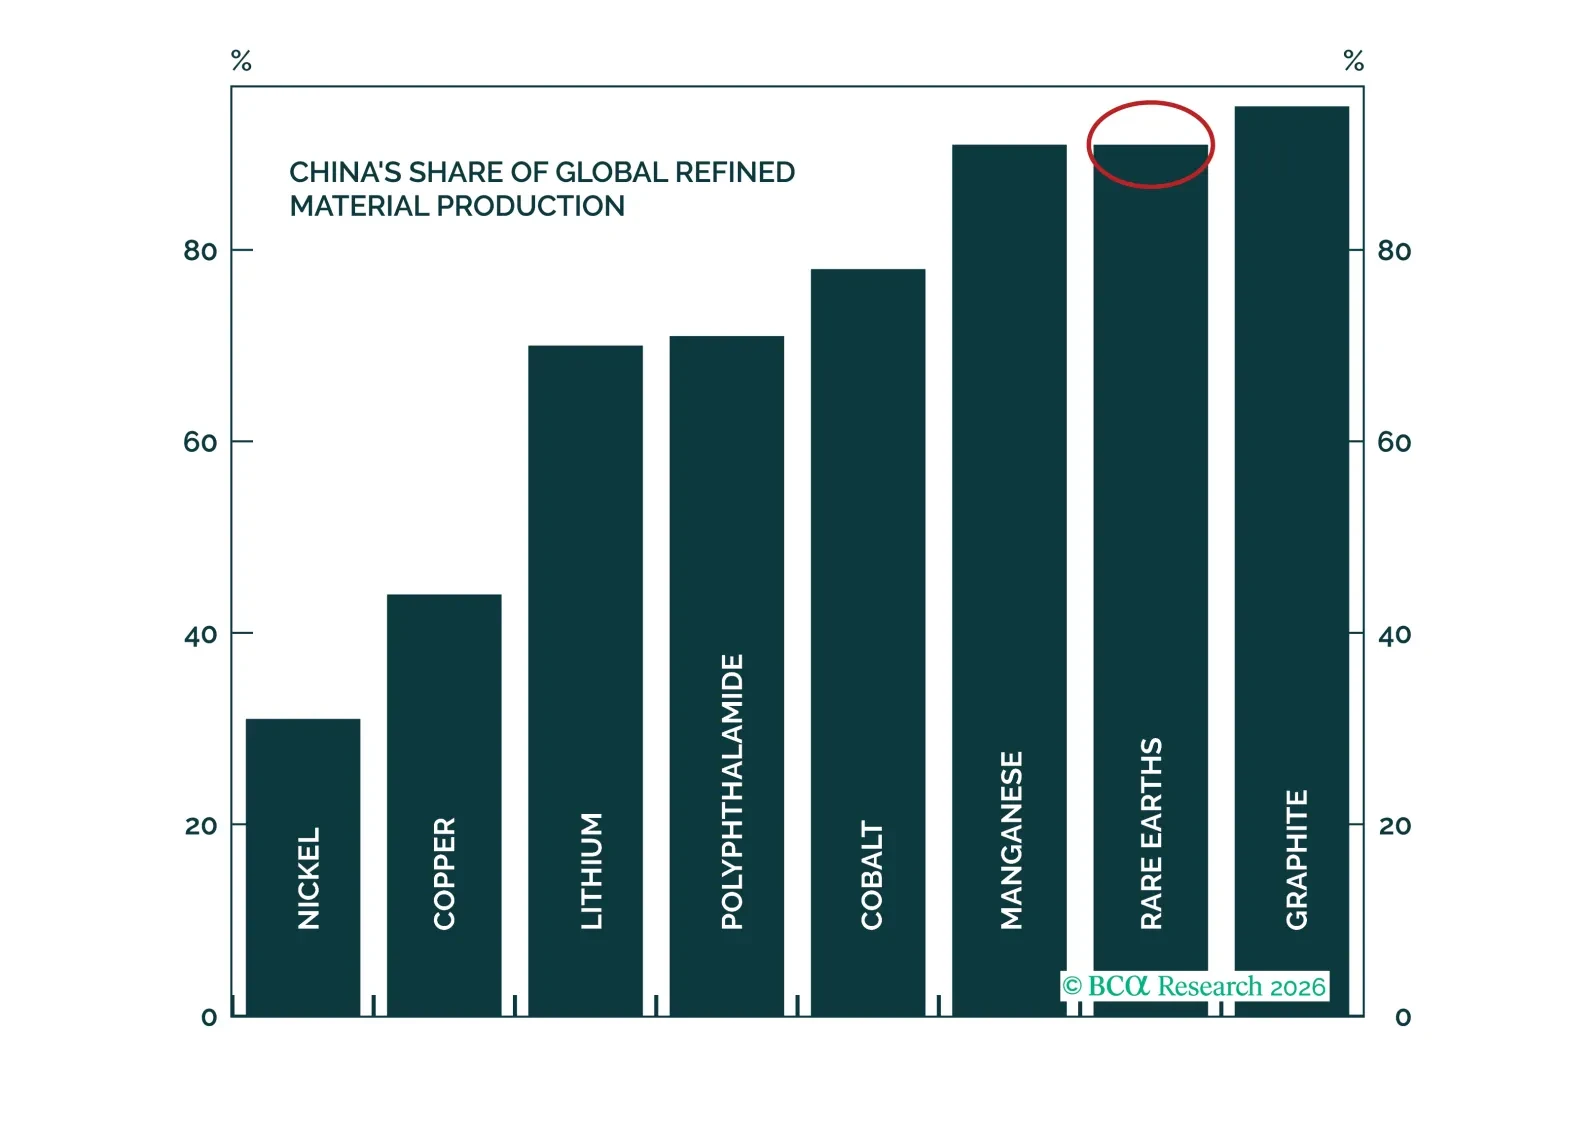
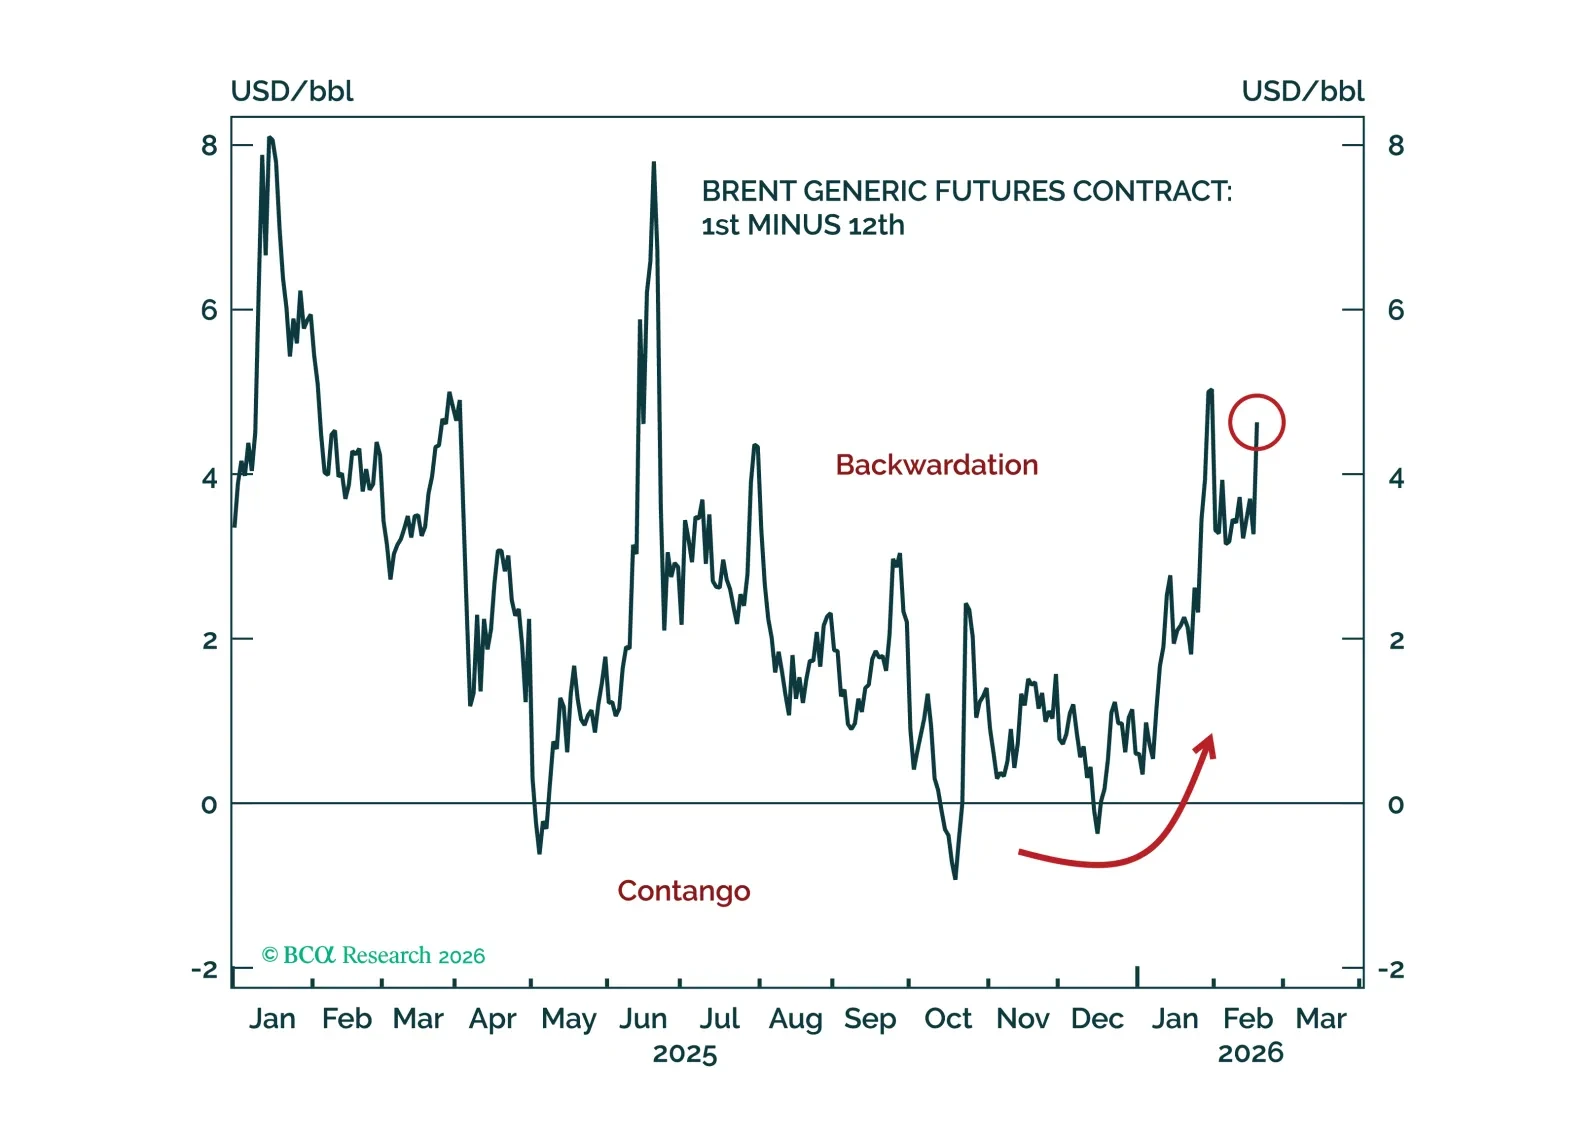
Oil price risks remain skewed to the upside over the near term as geopolitical risks continue to dominate. Nevertheless, we ultimately expect bearish fundamentals to reassert themselves over a six-to-12-month timeframe and drive oil prices lower.
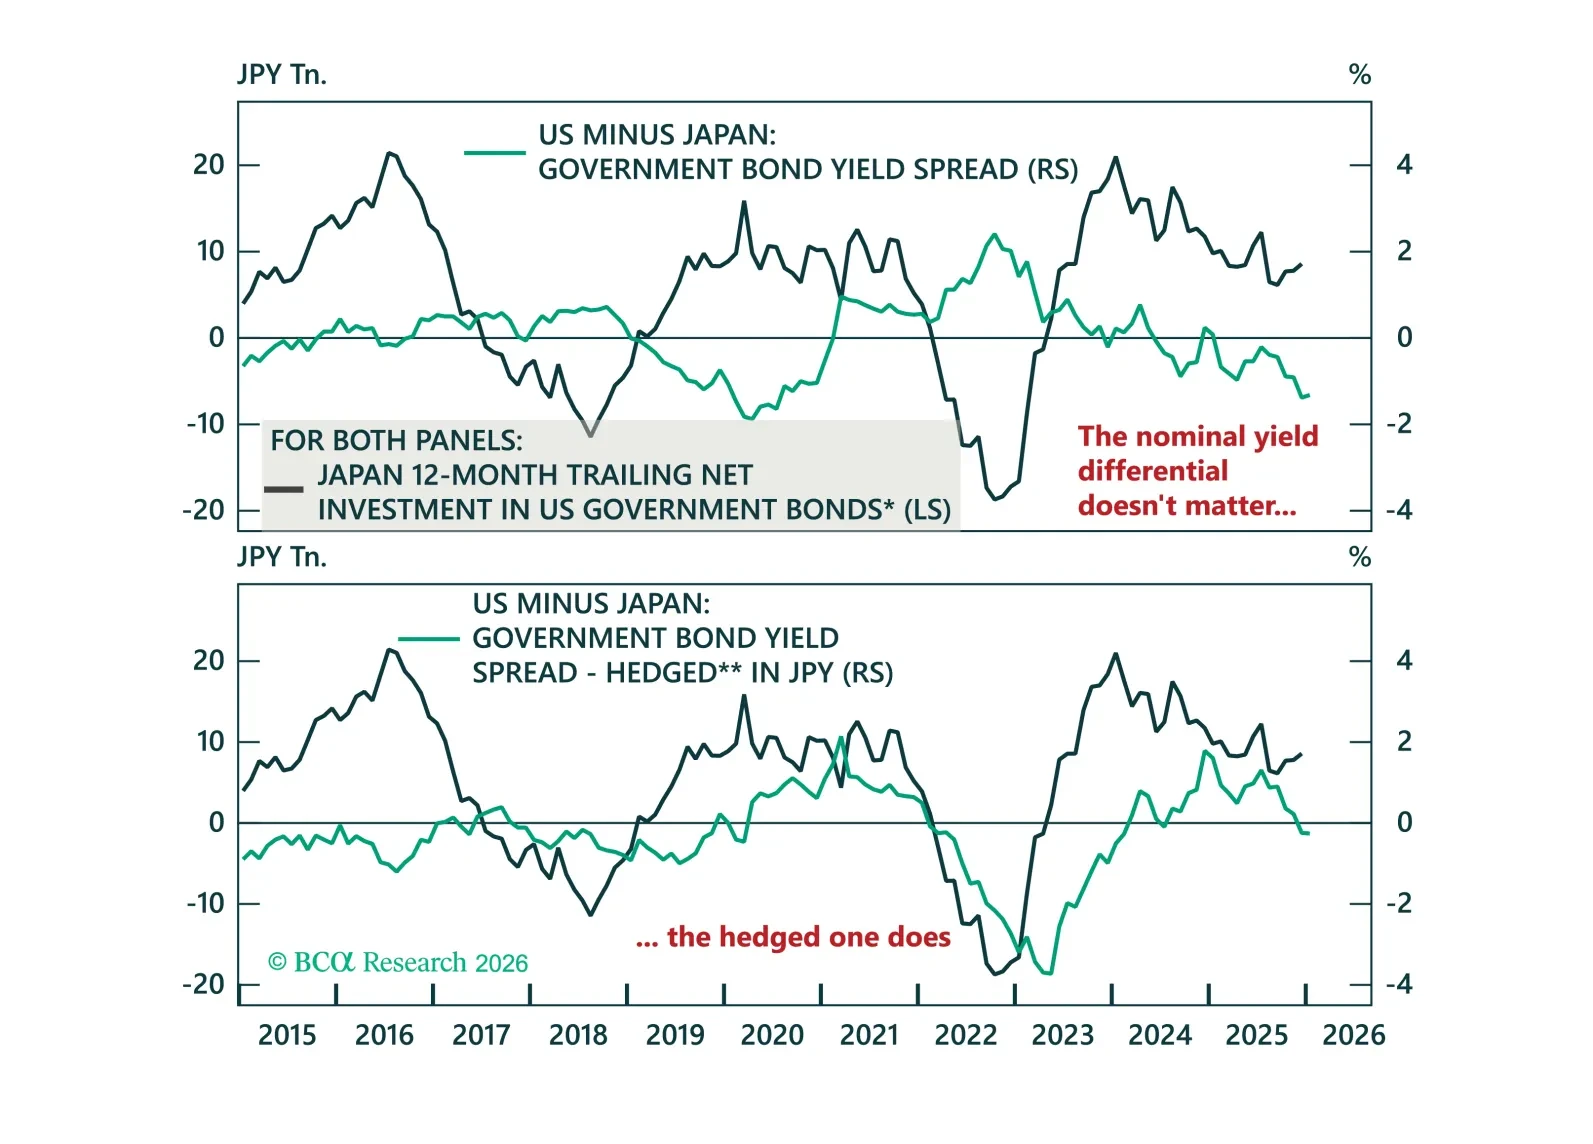
We spent last week meeting investors in Switzerland. This Strategy Insight revisits the most prominent topics we discussed, including repatriation fears, SNB intervention, and Dutch pension reform.
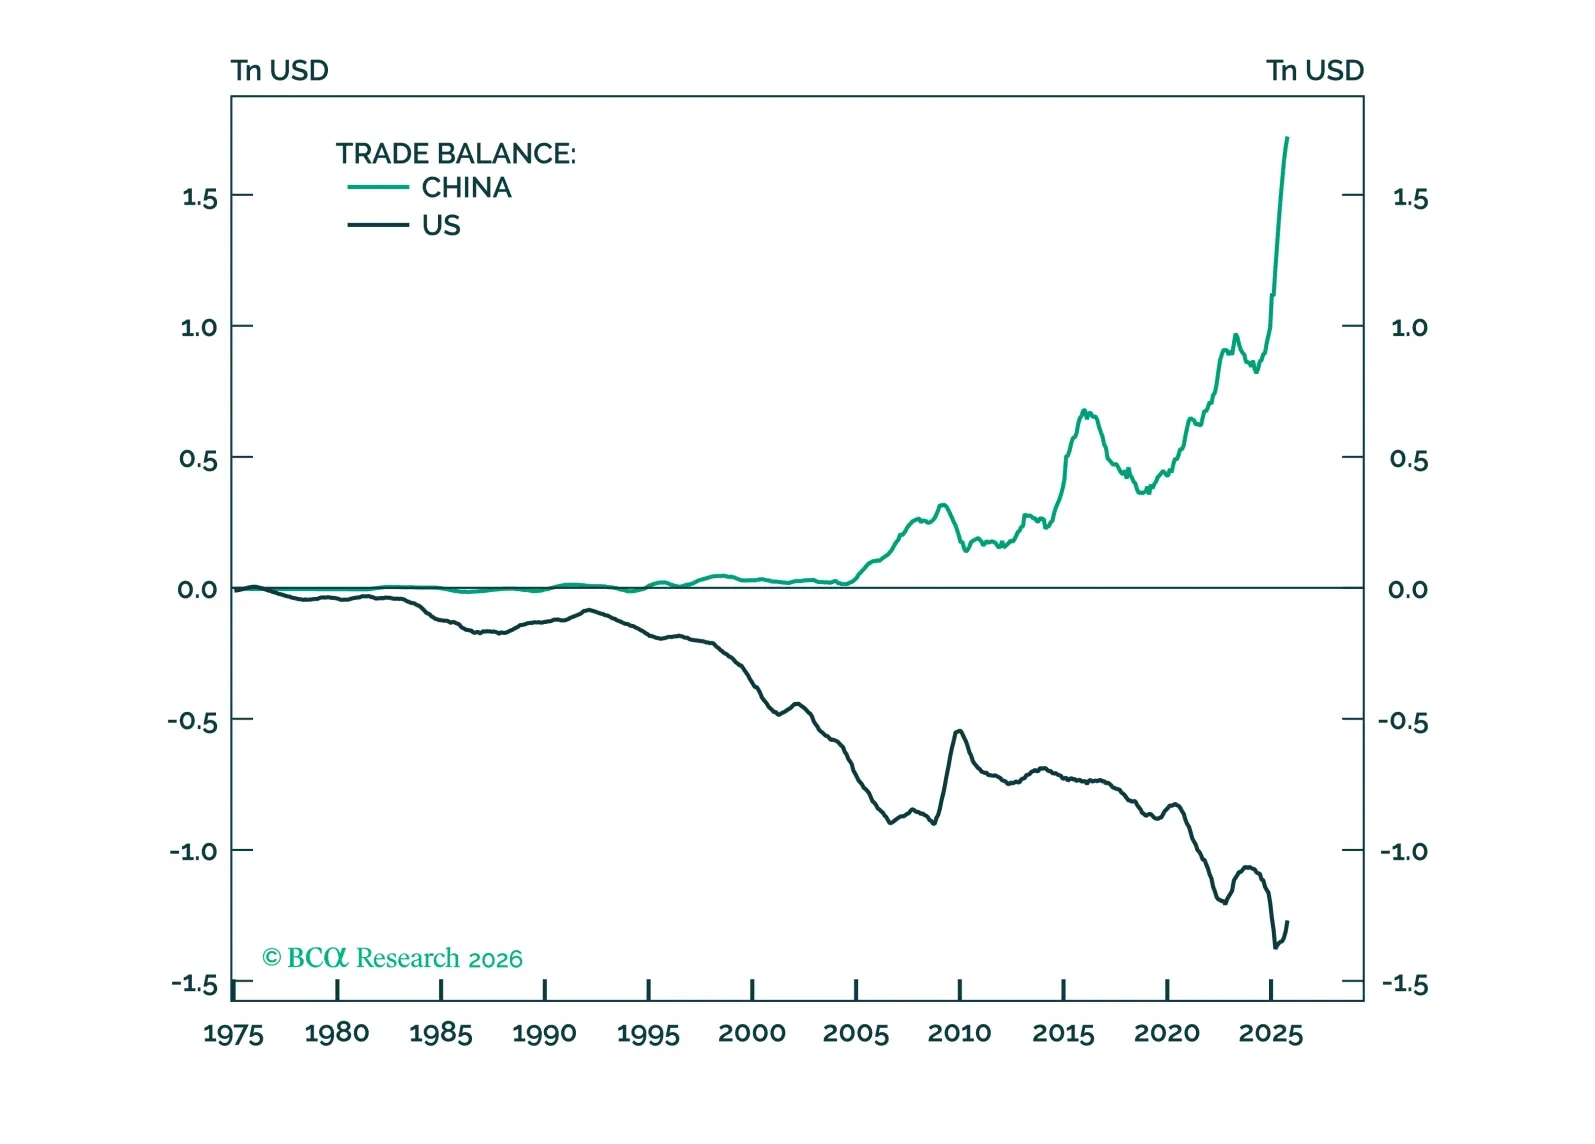
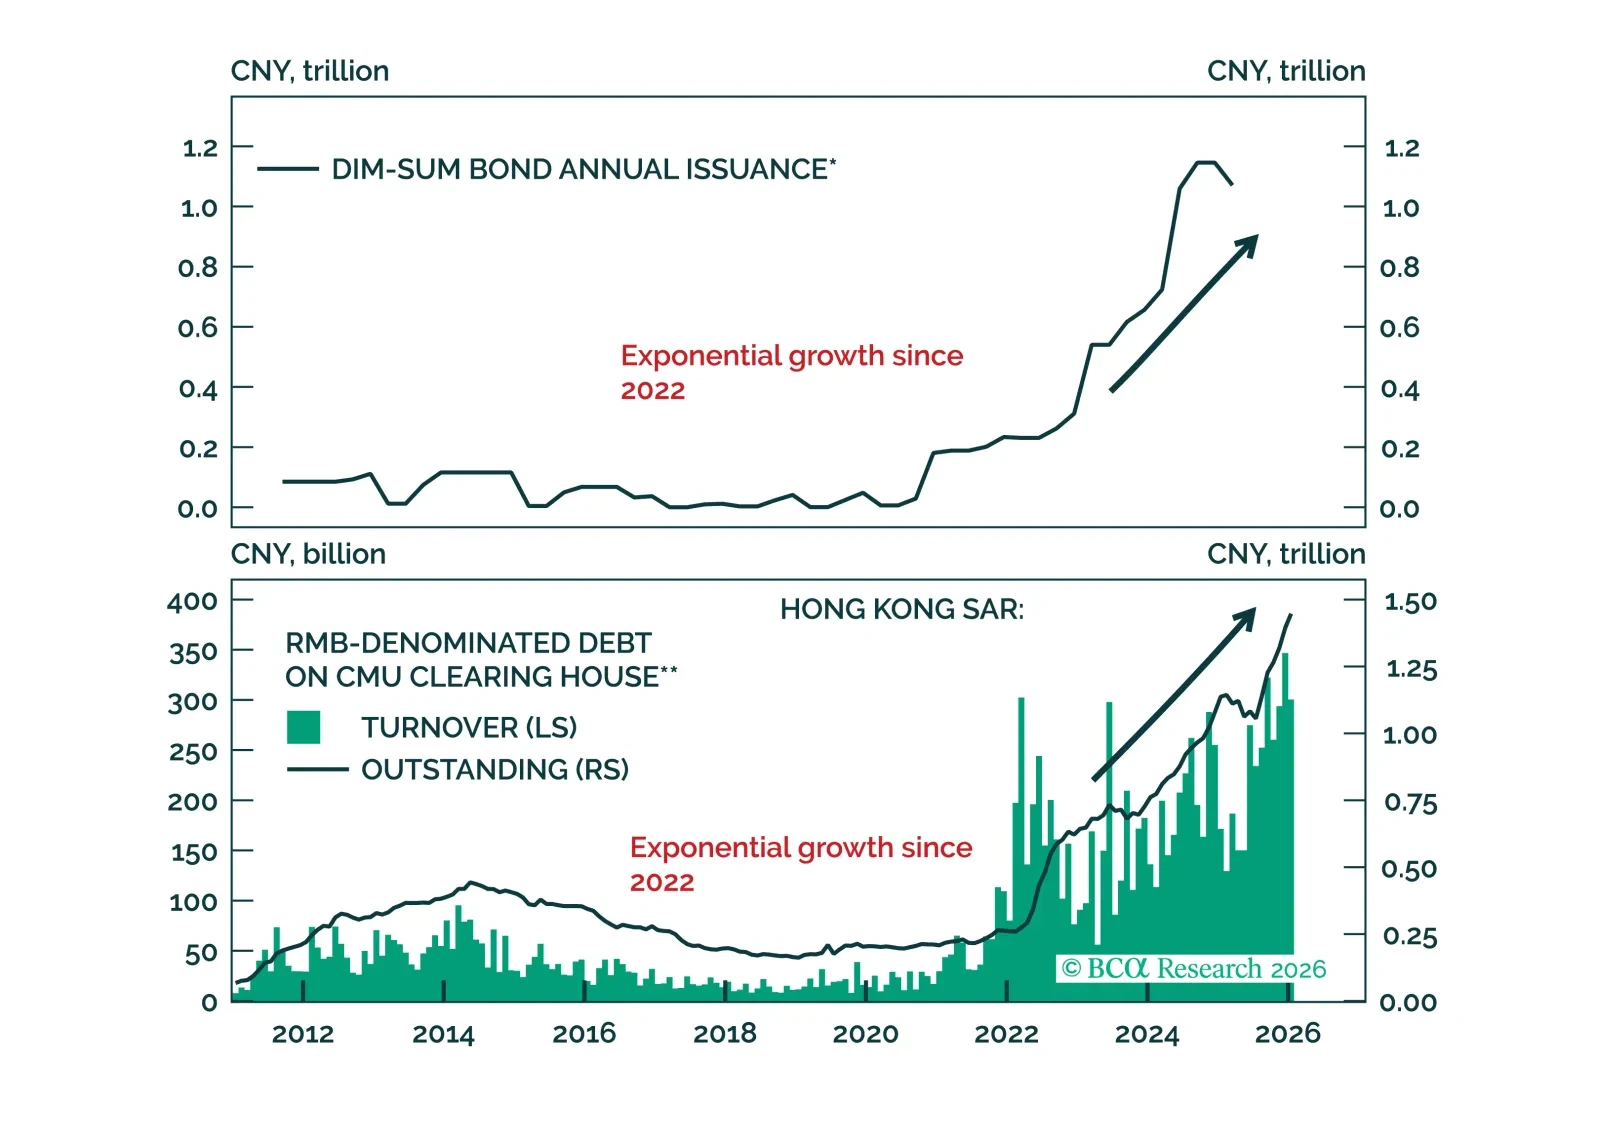
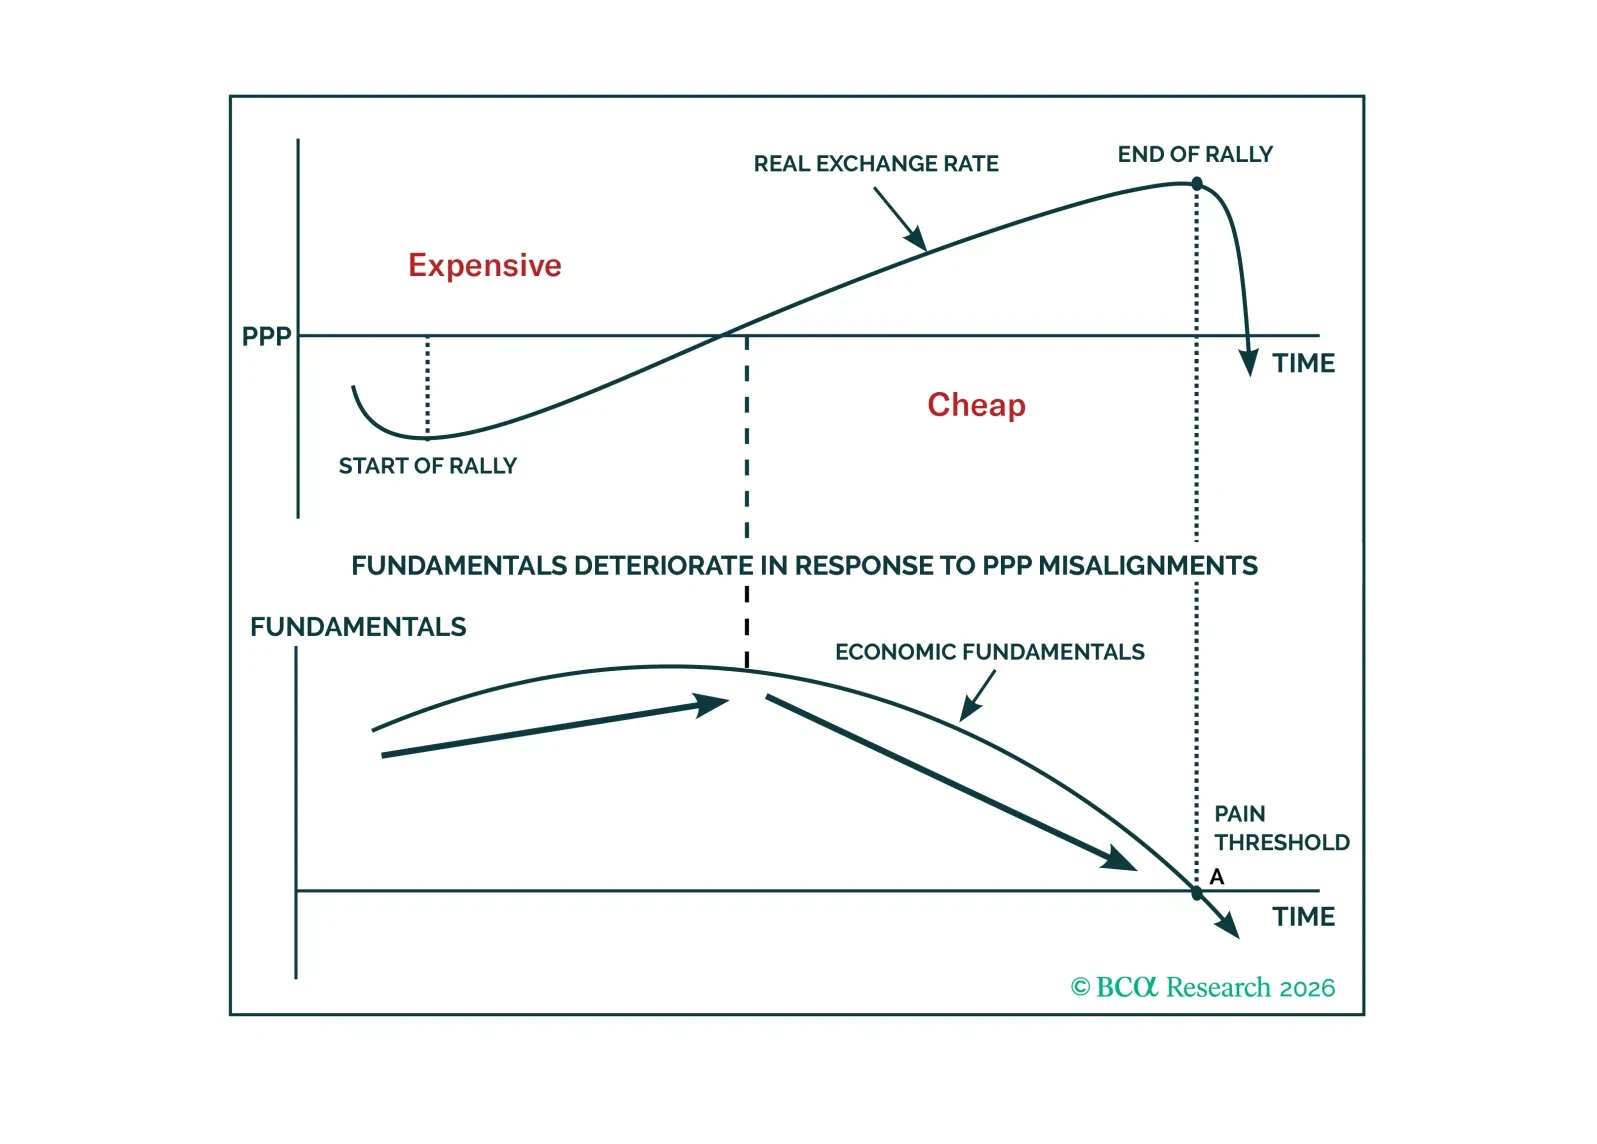
The CNY is undervalued and highly competitive. This gives China room to let the currency appreciate while remaining an export-driven powerhouse, gradually shifting from export intensity toward stronger domestic consumption. This achieves two objectives. First, it narrows the capital account deficit and strengthens the CNY’s role as a global anchor. Second, it enhances Beijing’s geopolitical autonomy by reducing reliance on foreign final demand.