 CoreMacro
Find out more
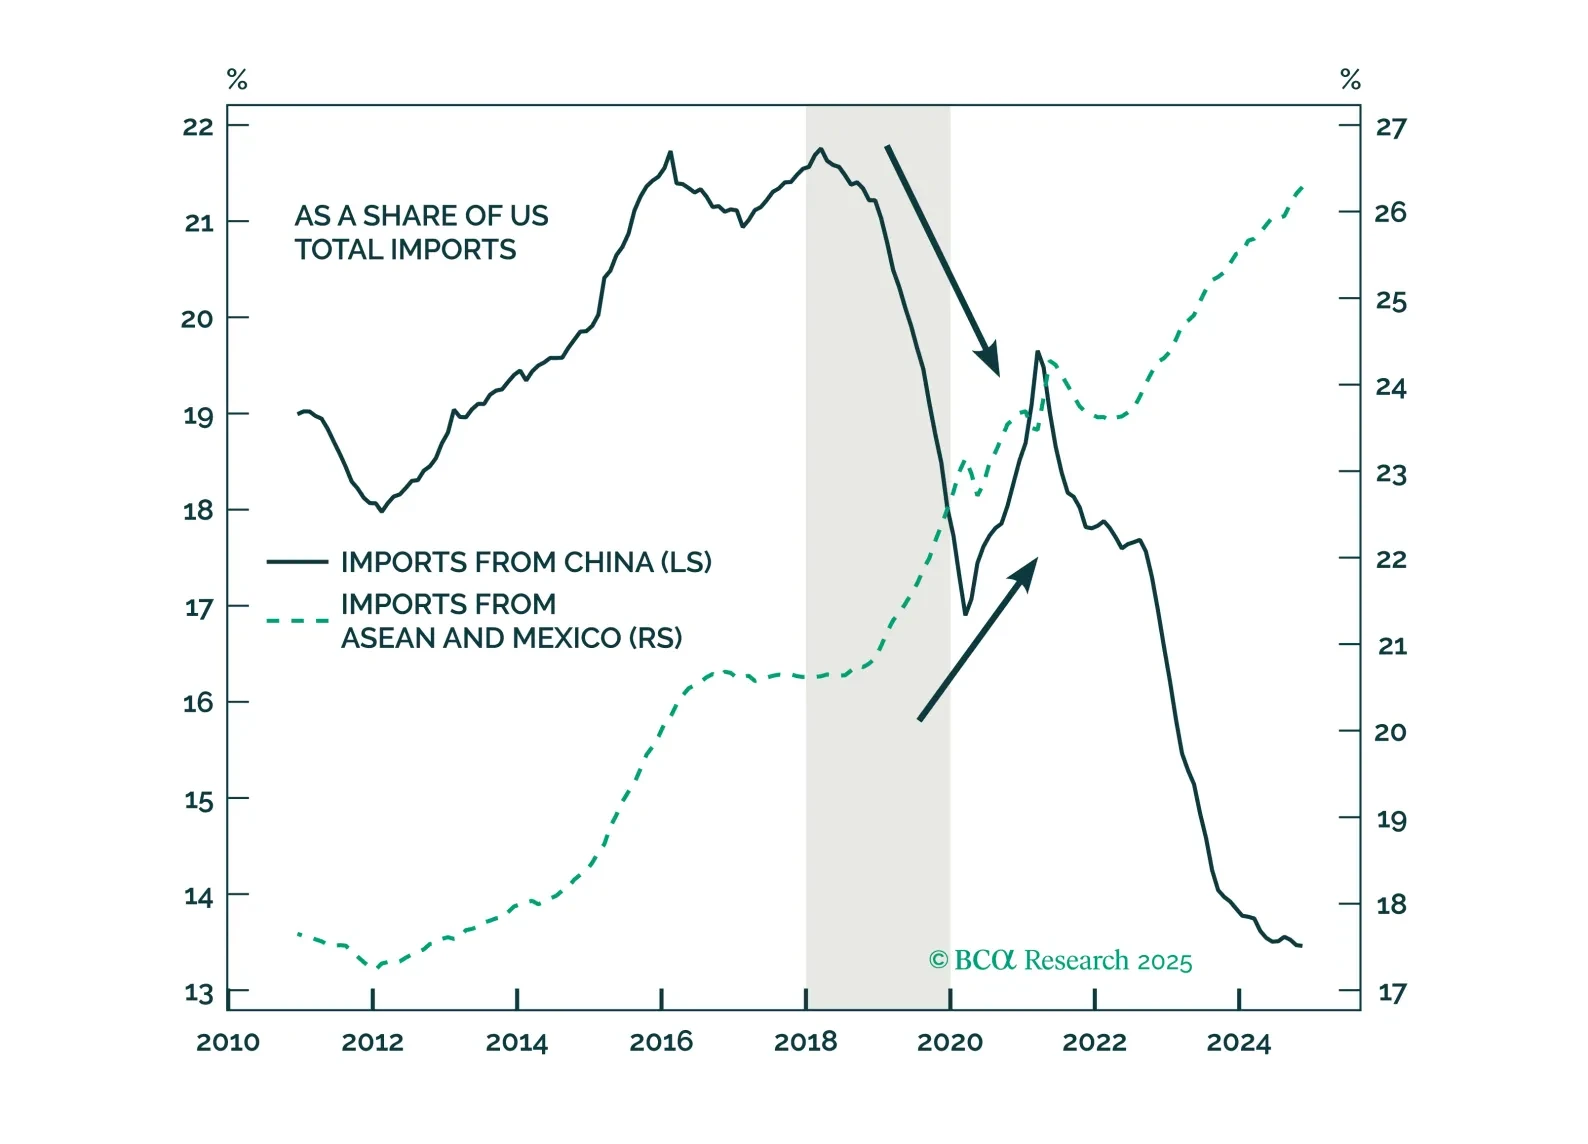
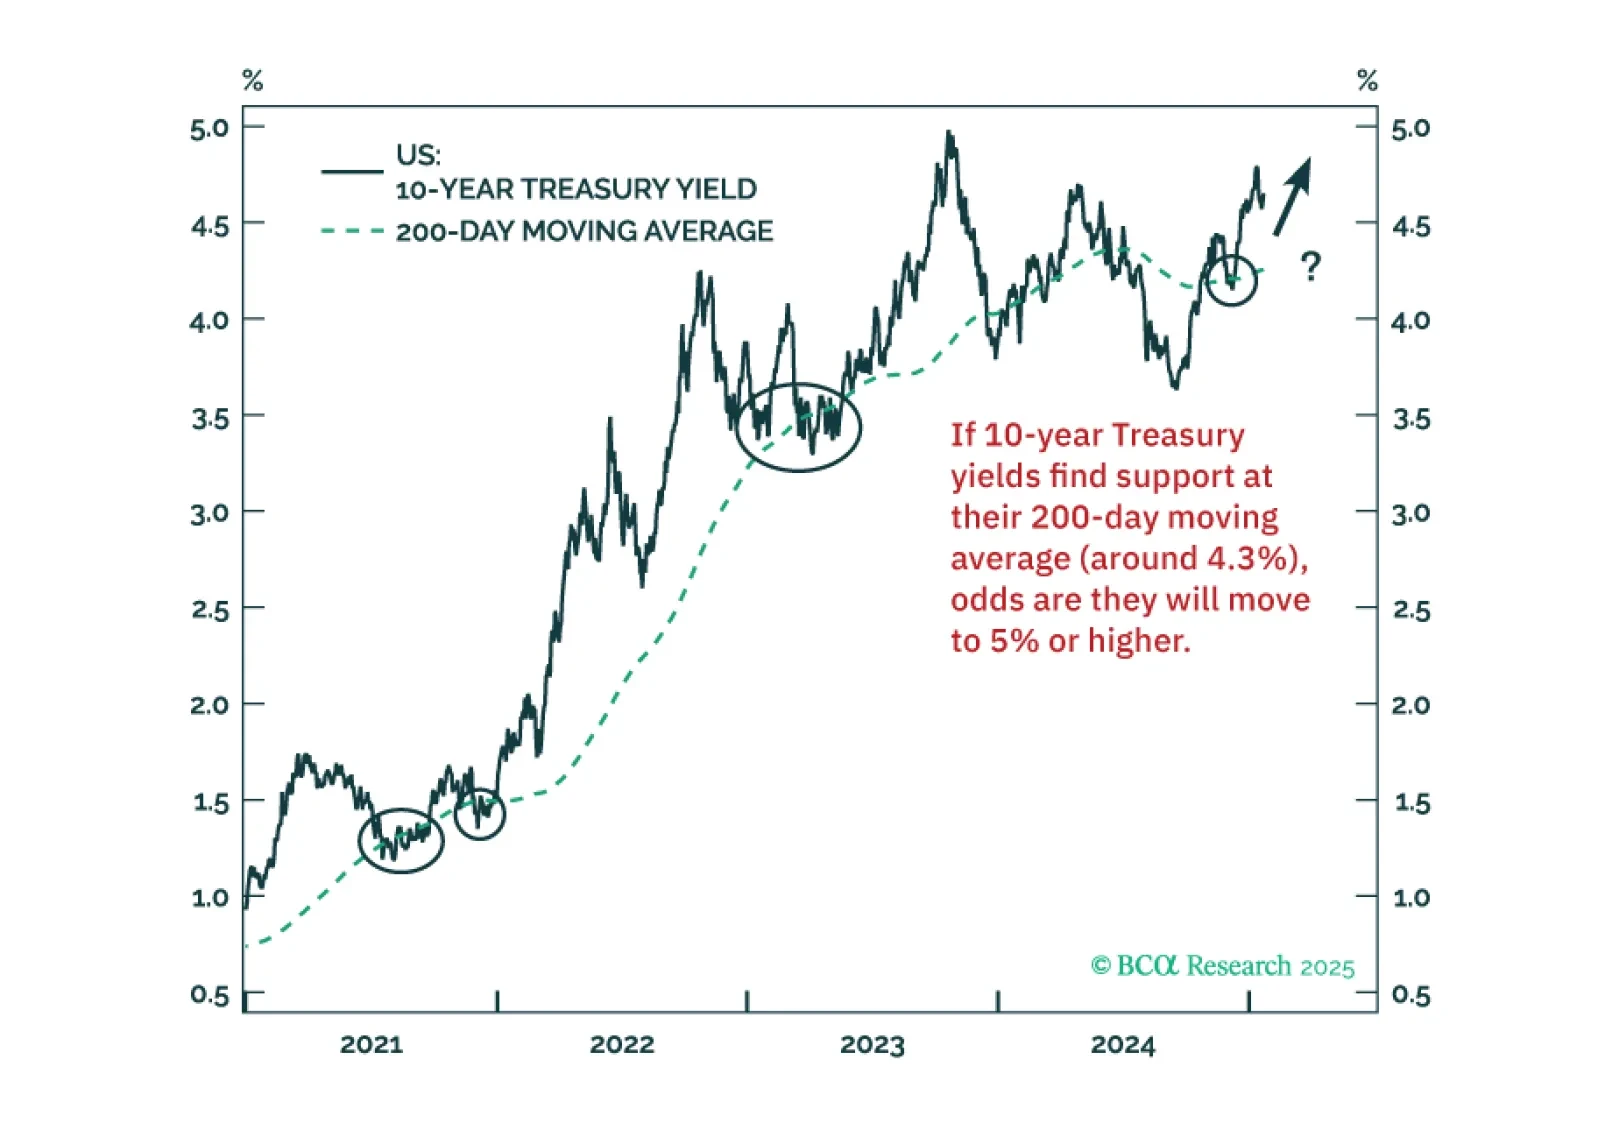
Last week, I visited clients in Europe. My recent report on Bessenomics – the name we gave to US Treasury Secretary Scott Bessent's policy mix – was often the focal point of the discussions. We will continue discussing Bessenomics, its progress, and its investment implications in forthcoming reports. In the meantime, we are sending my chart pack used during this trip as a Charts That Matter publication – a chart-based report. It covers the following areas: China, Bessenomics, US fixed income, global currencies, EM credit markets, the global ex-US business cycle, EM and US equities, and an EM local bond relative value matrix. In my opinion, the most important variable in global financial markets are US long-term Treasury yields. If they hold above their 200-day moving average, odds are that new highs lie ahead. My hunch is that 10-year yields will break above 5%. When and as this happens, global risk assets will sell off considerably.
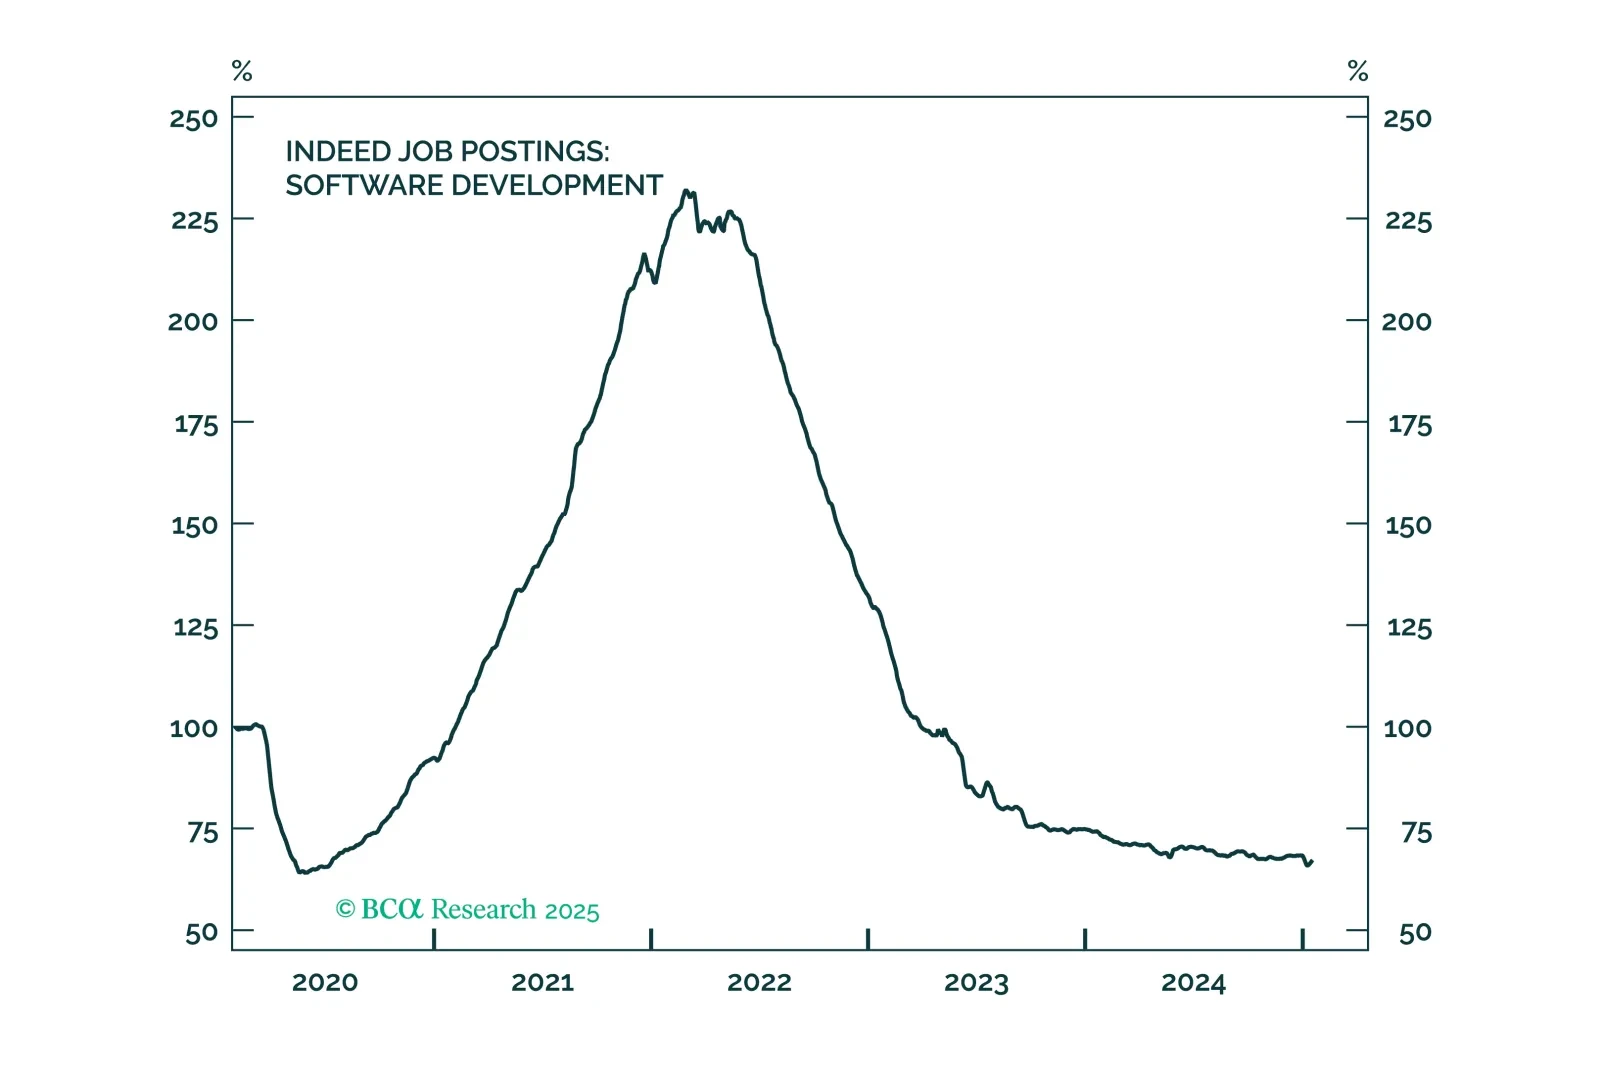
We were stopped out of our defensive asset allocation recommendations last Thursday, when the S&P 500 closed above 6,100, but our reading of the labor market tea leaves still supports a bearish fundamental view.
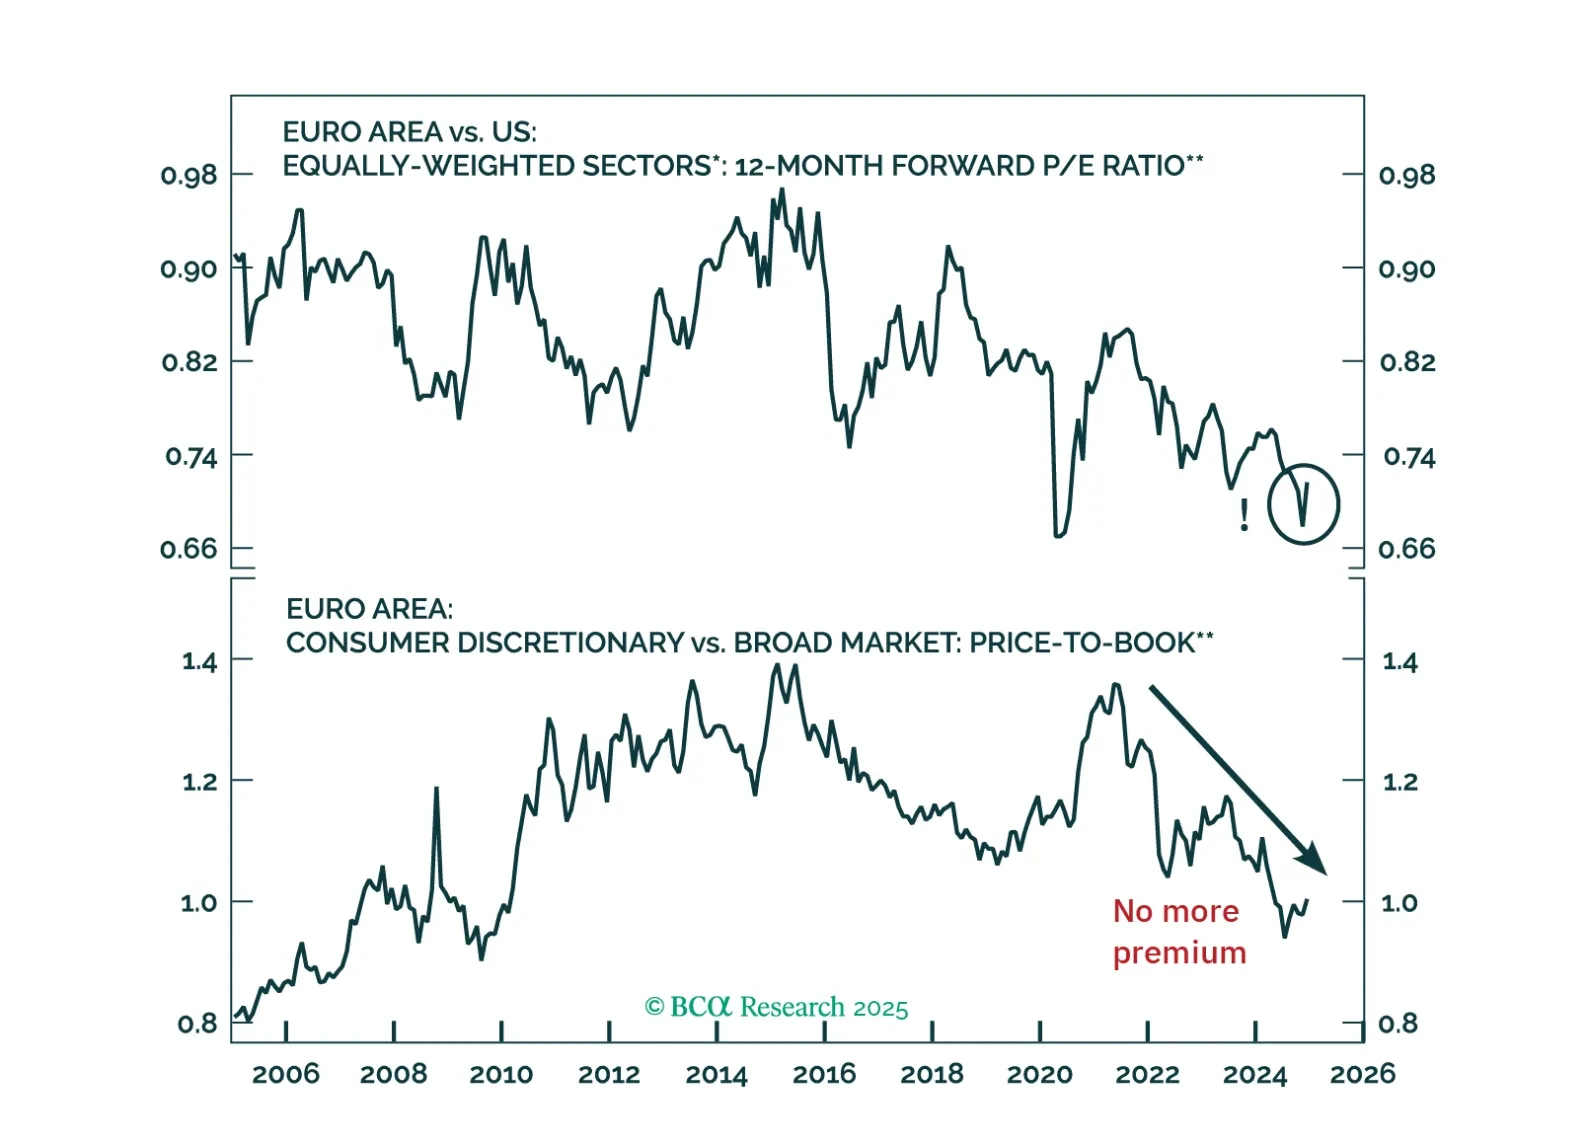
Global risk assets are engulfed in a wave of euphoria, which is pulling Europe higher along the way. However, risks still abound. How should investors adjust their allocation to Europe under these highly uncertain conditions?
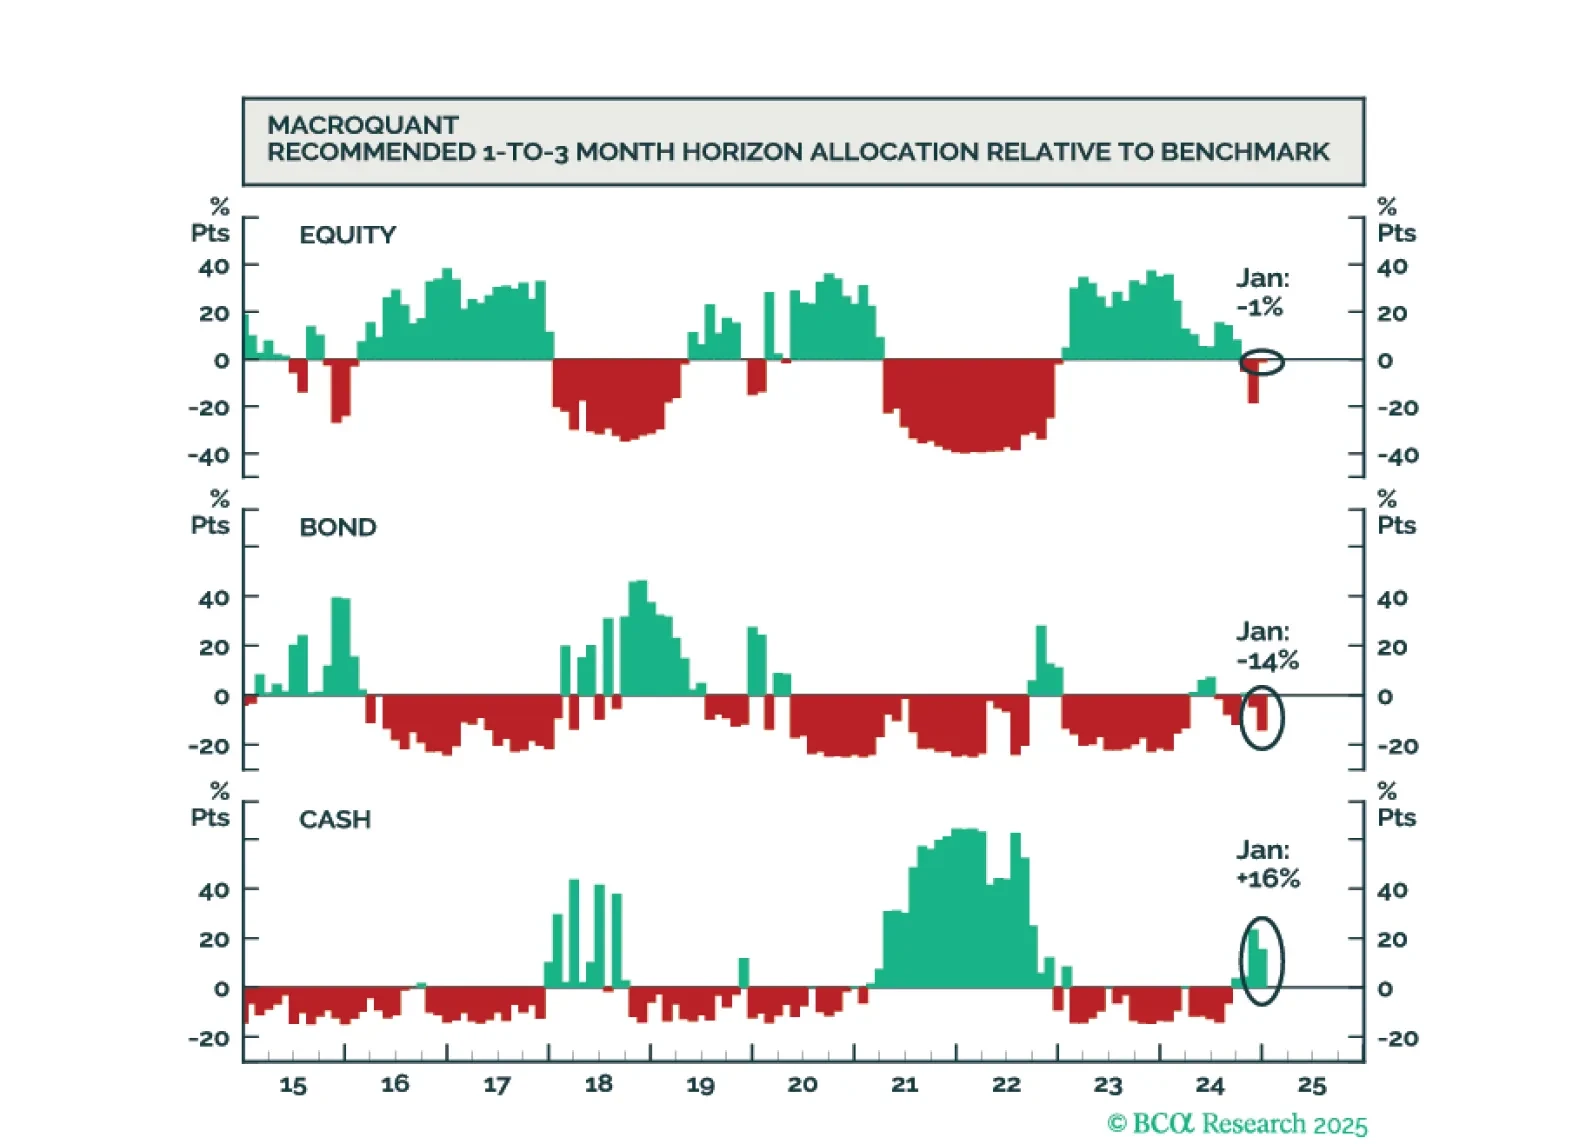
While the US economy could remain upright on the tightrope for a while longer, it will inevitably fall, leading to a major bear market in stocks. We will be looking to our MacroQuant model for guidance on when to turn fully defensive. We are not there yet.
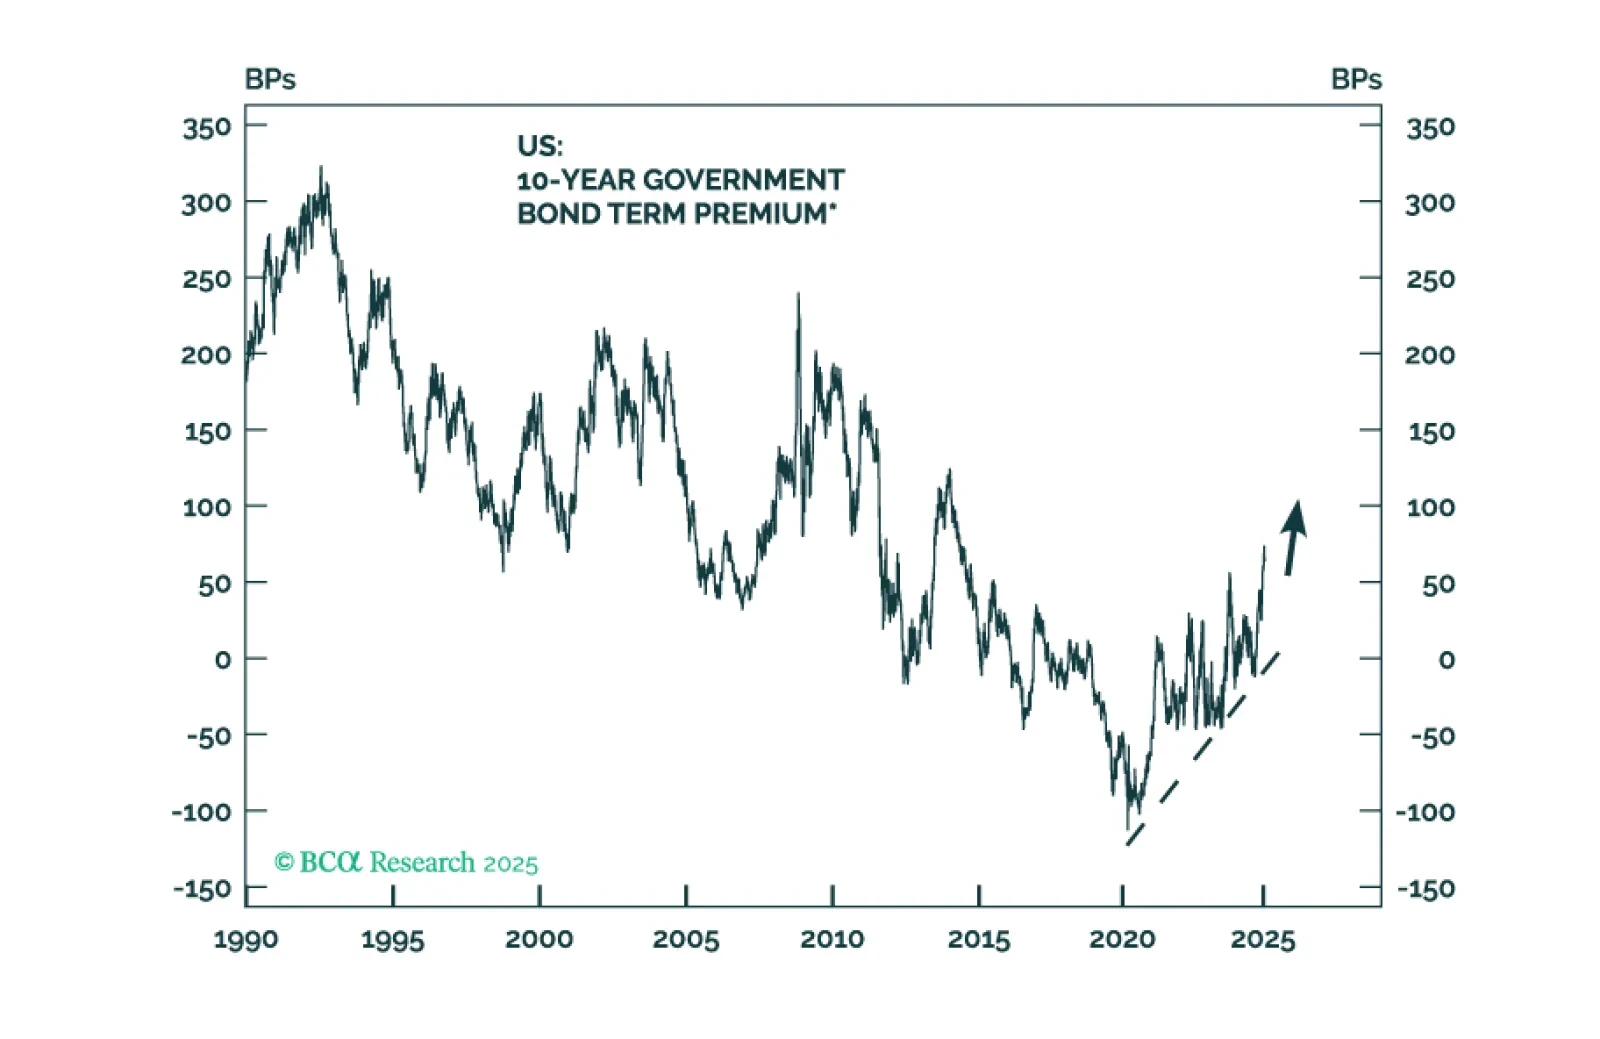
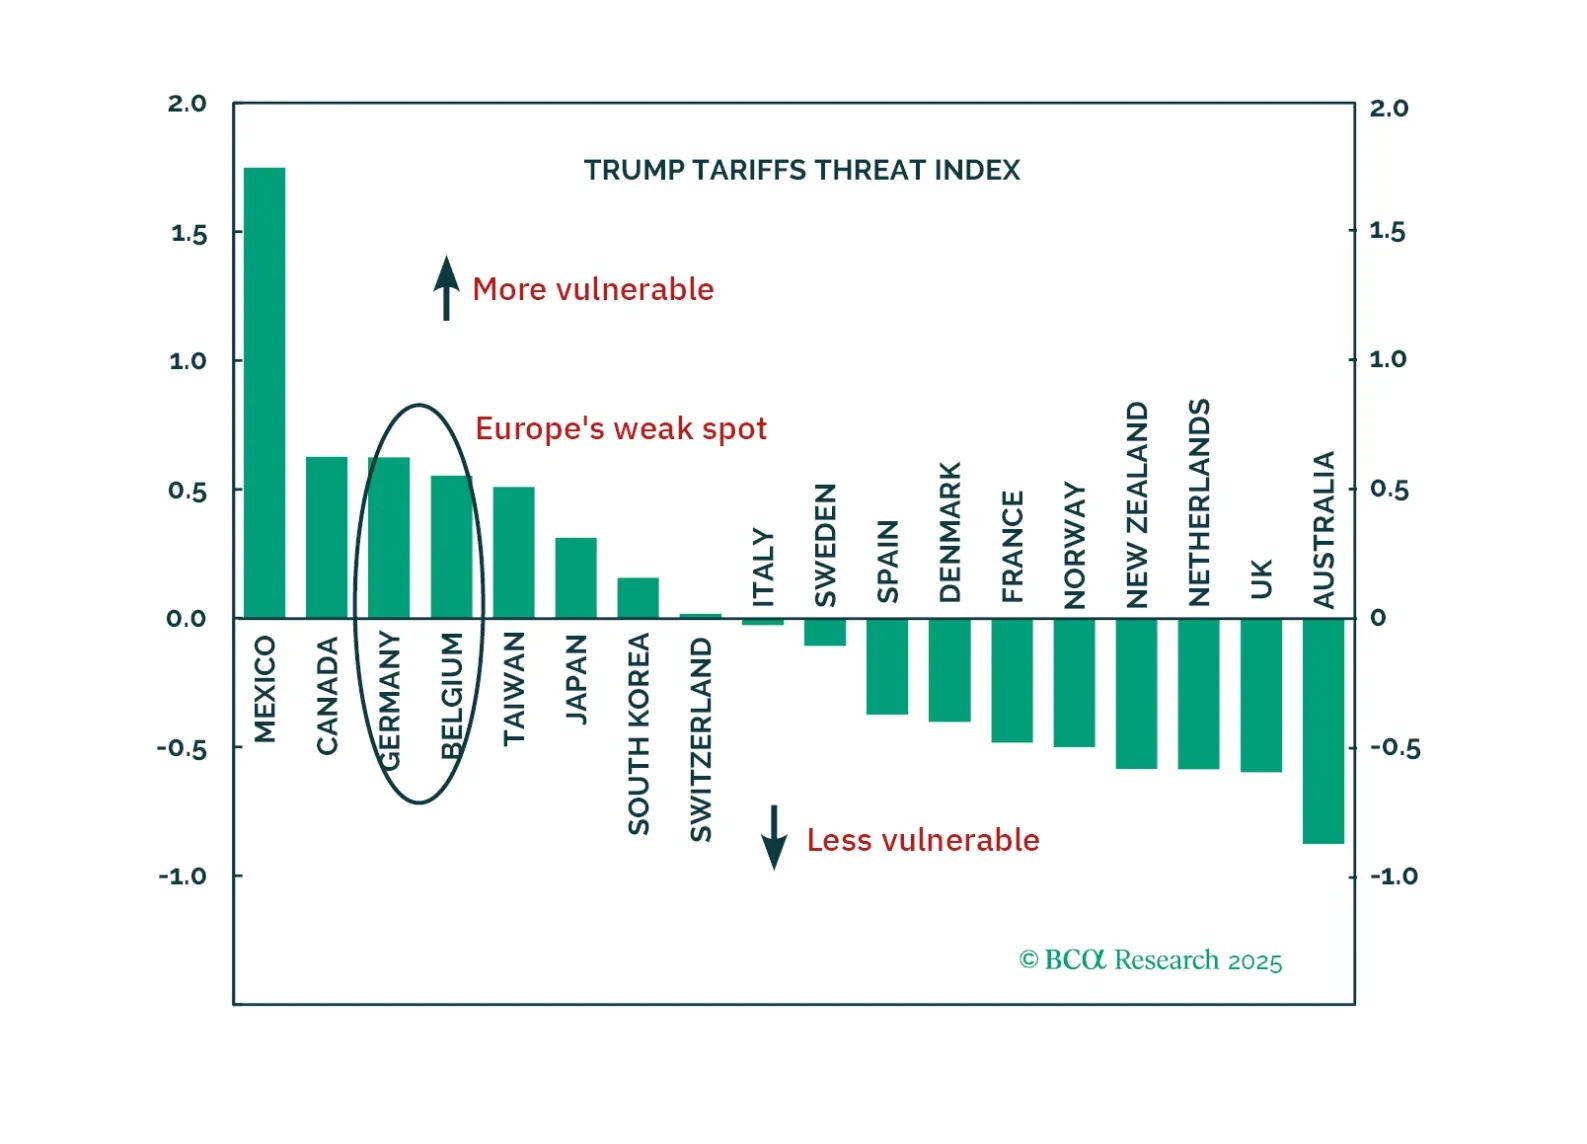
President Trump is about to be inaugurated. Investors often assume all his policies will hurt Europe, but the reality is more nuanced.
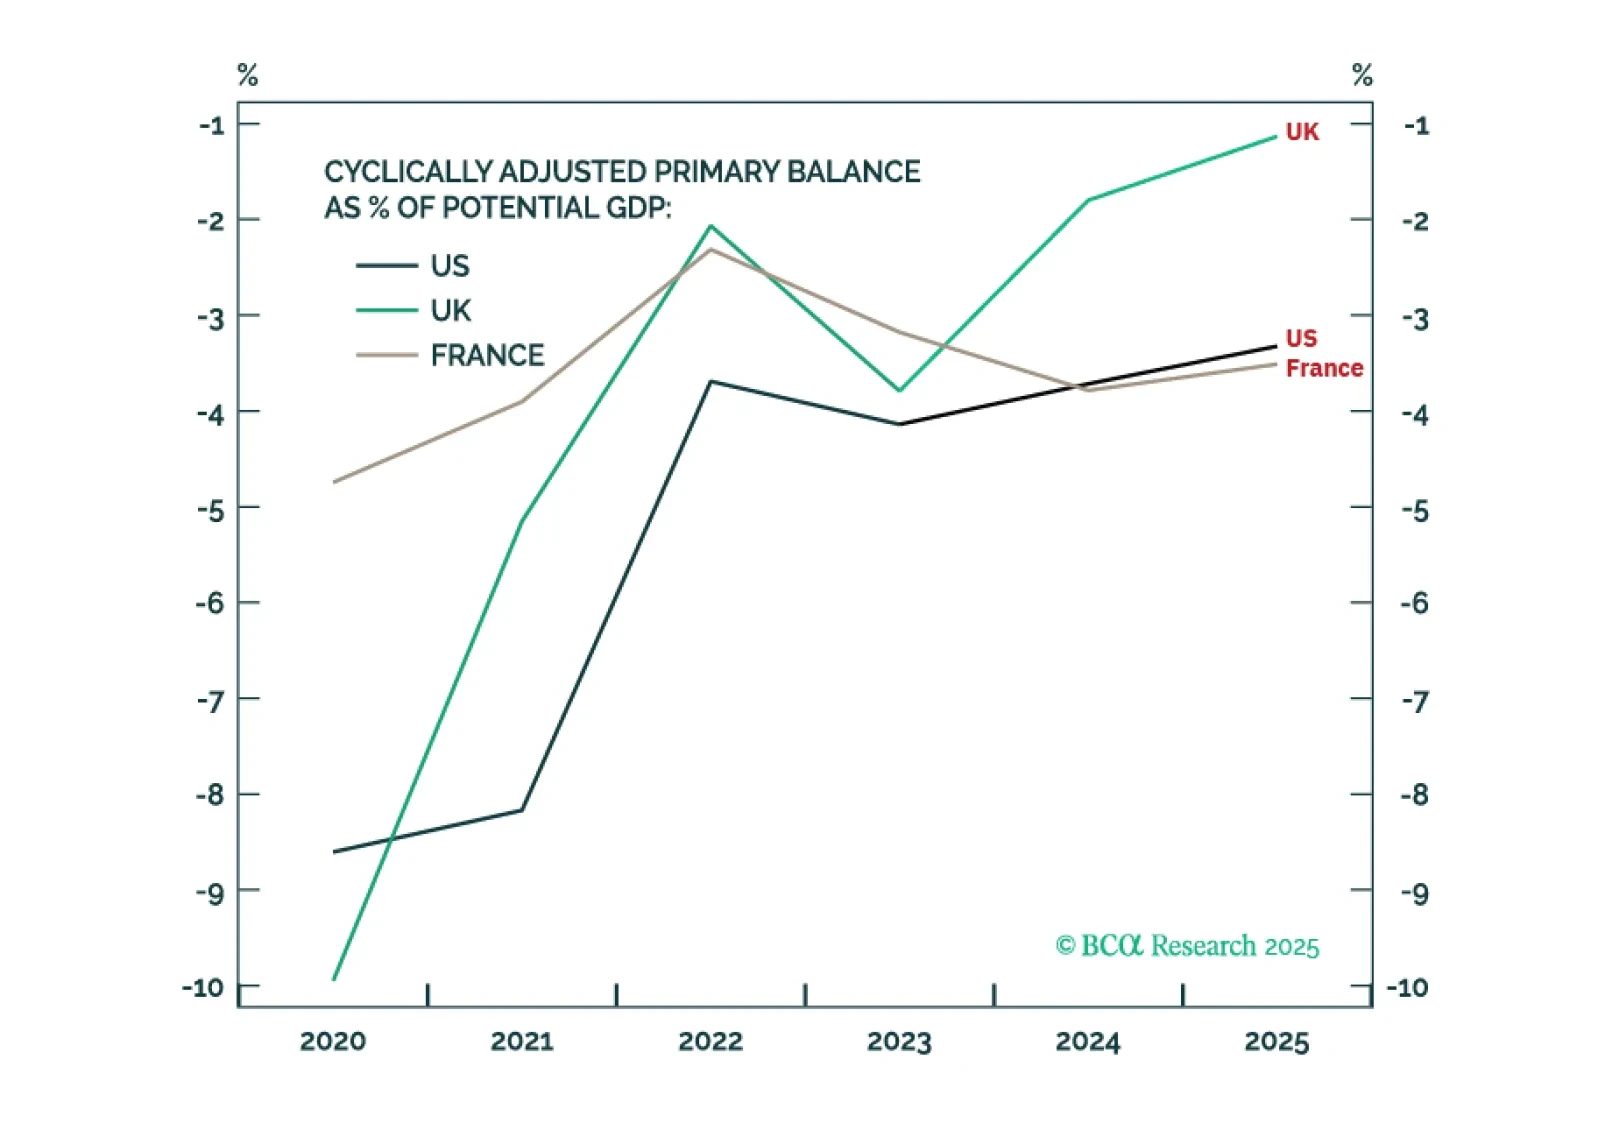
Political instability combined with the maths of debt sustainability is much more concerning in France than in either the UK or the US. Go long UK gilts versus French OATs and go tactically long GBP/USD.
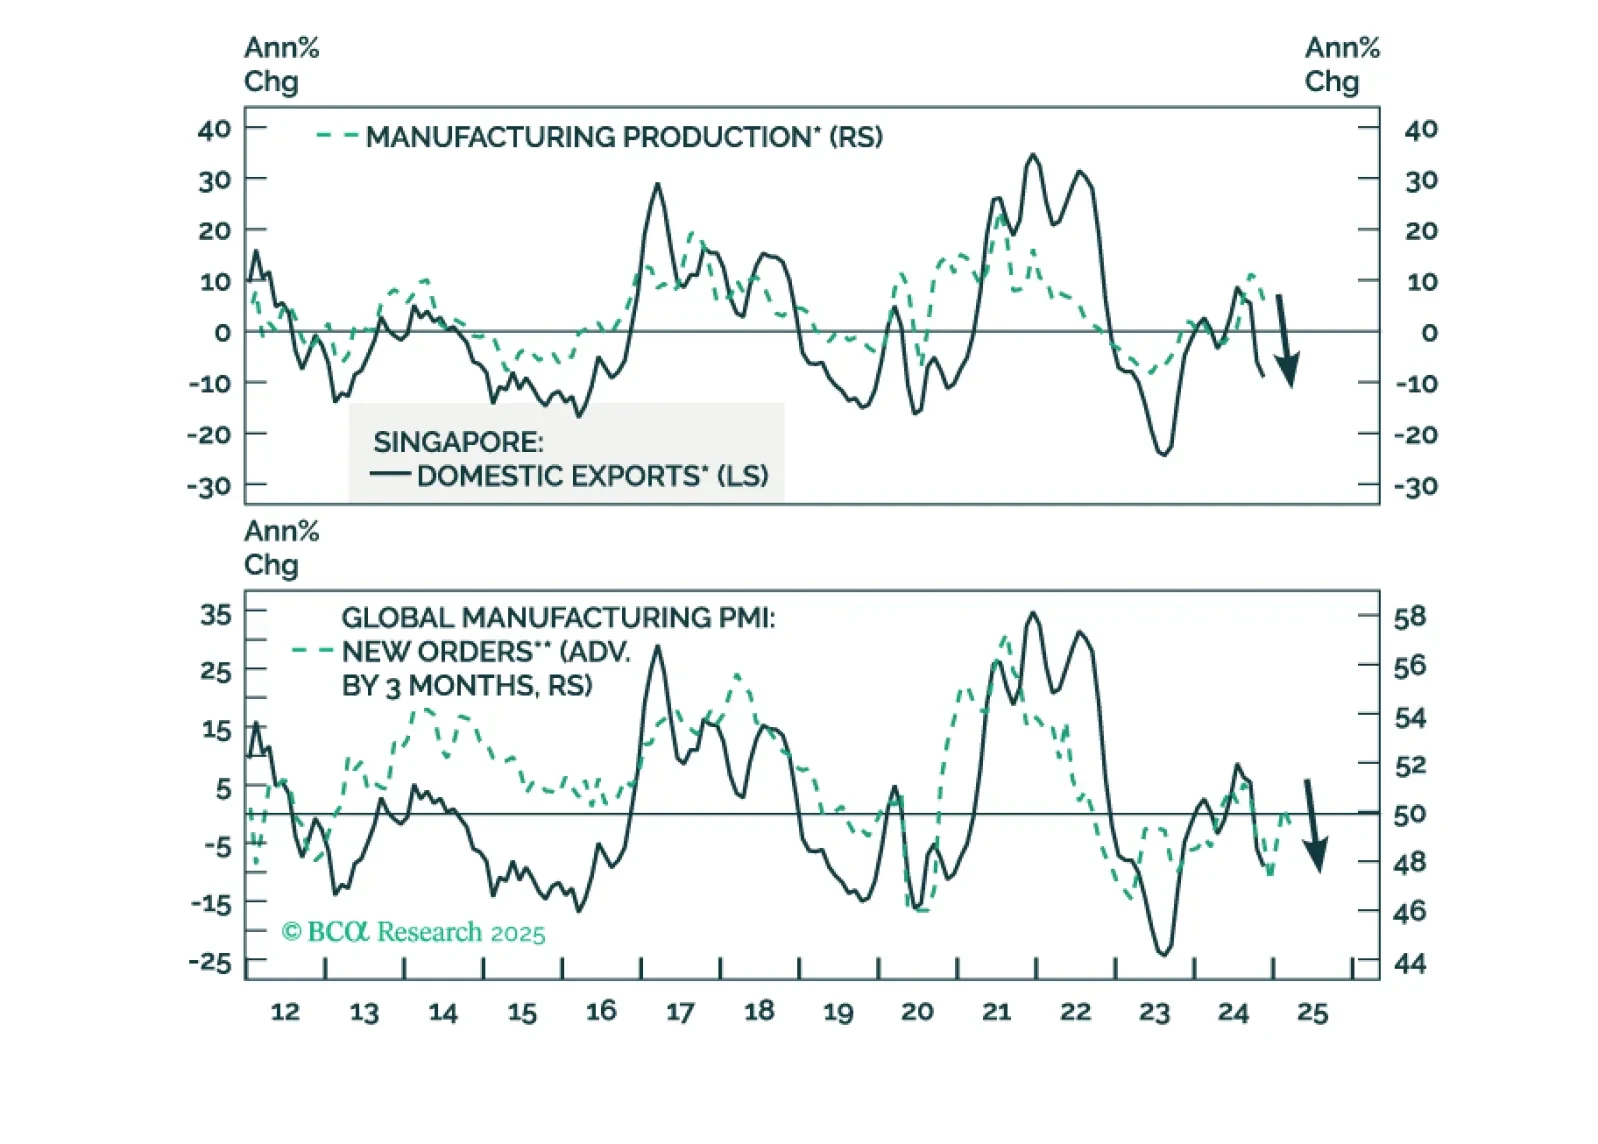
Can Singapore stocks continue the bull run into 2025? What does the city-state’s manufacturing and export outlook foretell? Is the Singapore dollar still competitive? See our analysis and investment recommendations in today’s report.
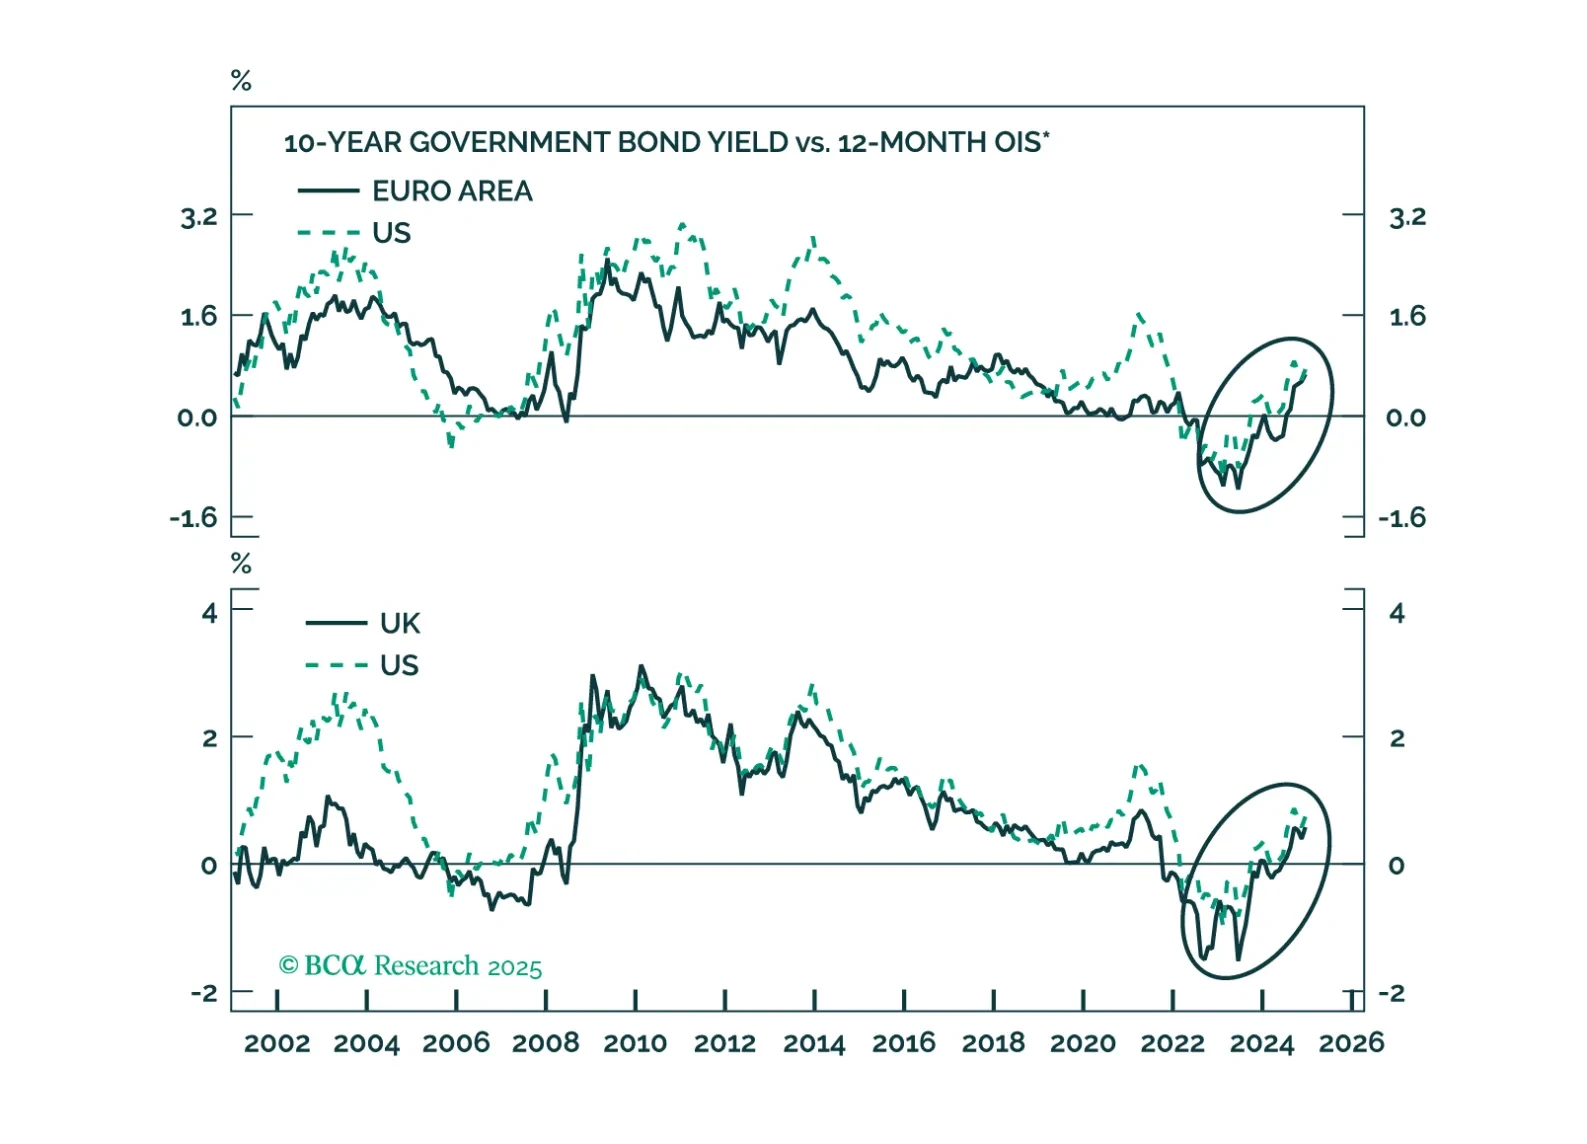
UK and German bonds are victims of the global bond market riots. Will European yields continue to move higher and will the euro and the pound find a floor anytime soon?